
Australia Solar Power Market Size, Share, Trends and Forecast by Type, Deployment, and Region, 2026-2034
Australia Solar Power Market Size, Share, Trends & Forecast (2026-2034)
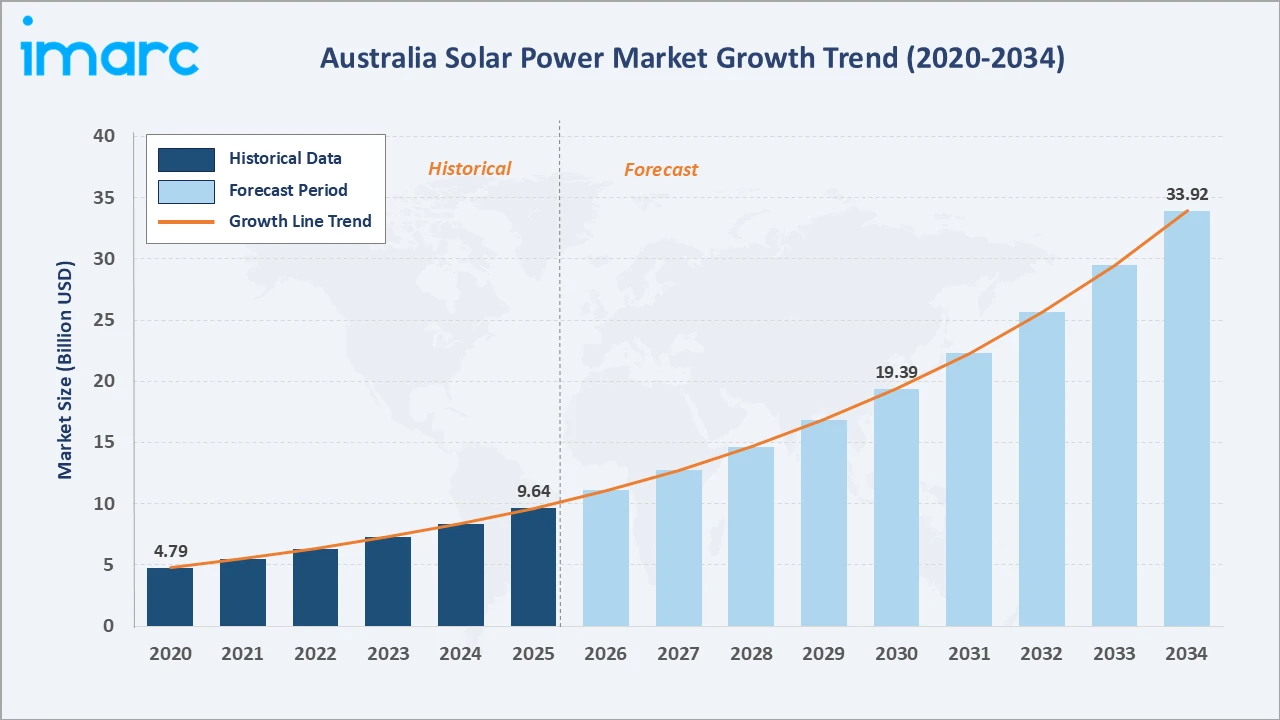
The Australia solar power market grew from USD 9.64 Billion in 2025 to USD 11.09 Billion in 2026 and is projected to reach USD 33.92 Billion by 2034, growing at a CAGR of 15.00% during 2026-2034. The australia solar power market is driven by strong government renewable energy targets, continuous decline in solar PV module costs, and increasing deployment across residential, commercial, and utility sectors. The australia solar pv inverter market and australia solar panel market are witnessing rapid expansion, supported by rising electricity prices and growing energy independence motivations.
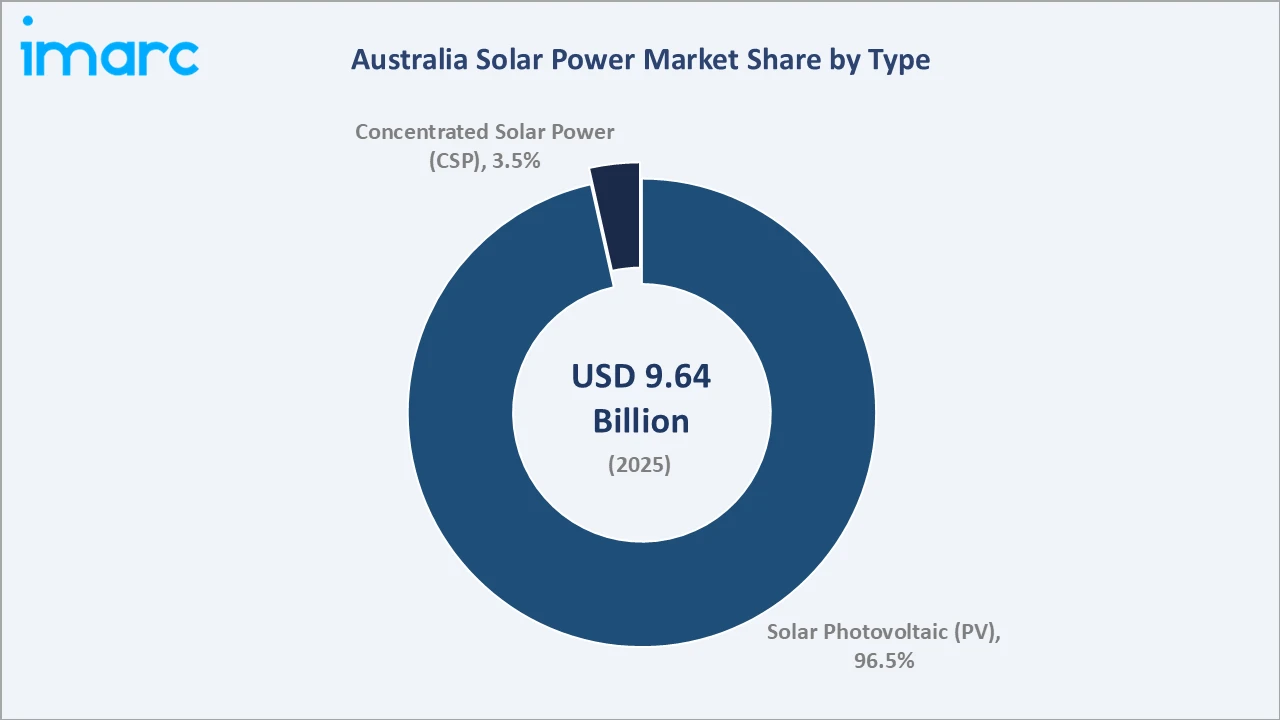
Solar PV dominates at 96.5% of the type segment in 2025, while Utility leads the deployment segment at 68.7%. ACT & New South Wales commands the largest regional share at 33.5% of the overall market. The solar industry Australia continues to expand as one of the fastest-growing renewable energy markets globally, with the australia solar power equipment market benefiting from strong private and public investment.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 9.64 Billion |
|
Market Size (2026 |
USD 11.09 Billion |
|
Forecast Market Size (2034) |
USD 33.92 Billion |
|
CAGR (2026-2034) |
15.00% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Solar Photovoltaic (PV) (96.5%, 2025) |
|
Dominant Deployment |
Utility (68.7%, 2025) |
|
Leading Region |
ACT & New South Wales (33.5%, 2025) |
The australia solar power market size expanded from USD 4.79 Billion in 2020 to USD 9.64 Billion in 2025 and is estimated to reach USD 11.09 Billion in 2026. The market is further projected to grow to USD 19.39 Billion by 2030 and USD 33.92 Billion by 2034, driven by Australia's ambitious net-zero commitments, government incentive programs, falling technology costs, and strong investor interest in utility-scale and distributed solar projects across the solar industry Australia.
To get more information on this market, Request Sample
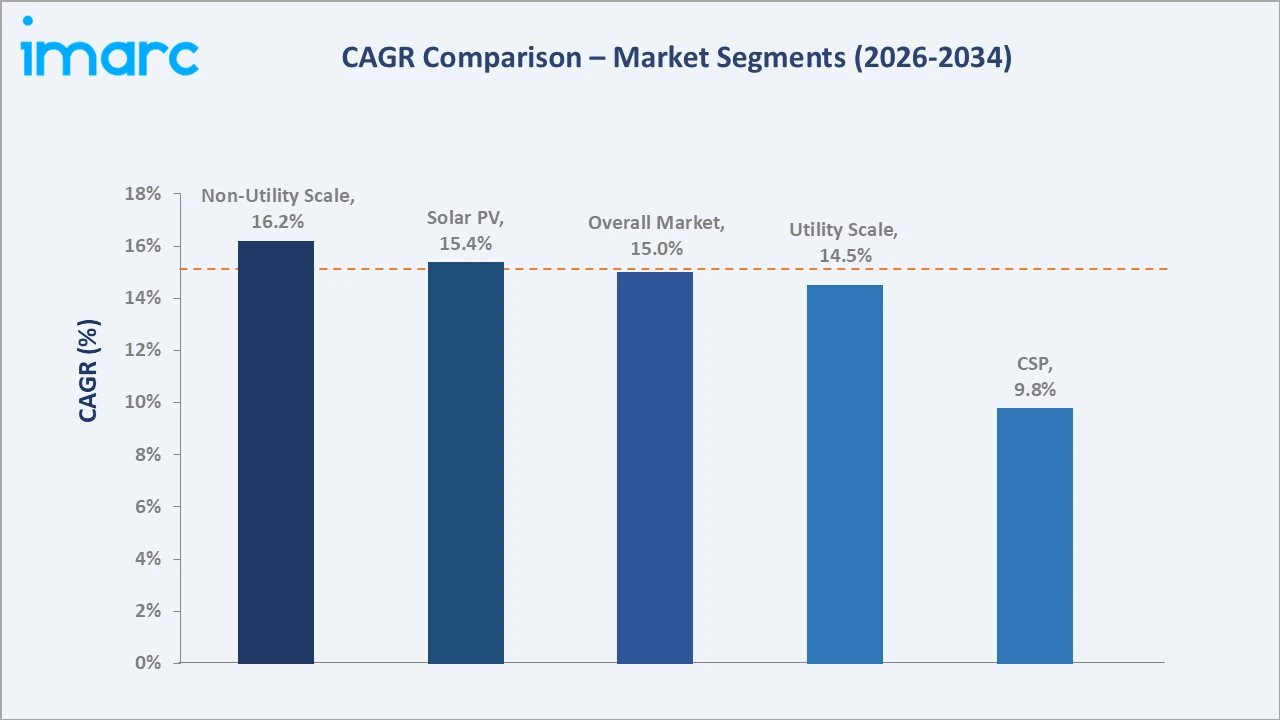
Solar PV leads with a CAGR of ~15.4% during 2026–2034, driven by continued cost competitiveness and mass adoption. CSP grows at ~9.8% CAGR. The Utility deployment segment expands at ~14.5% CAGR supported by large-scale solar farm development. Non-Utility grows at ~16.2% CAGR driven by residential rooftop and commercial solar adoption across the australia solar panel market.
Executive Summary
The Australia solar power market expanded from USD 9.64 Billion in 2025 to an estimated USD 11.09 Billion in 2026, positioning it as one of the fastest-growing renewable energy markets in the Asia-Pacific region. The market is underpinned by strong solar irradiance across the continent, a well-established policy framework supporting renewable energy deployment, and declining solar PV technology costs, which collectively support sustained high-CAGR growth across all market segments. The market is projected to reach USD 33.92 Billion by 2034, registering a CAGR of 15.00% during 2026–2034. Solar PV at 96.5% leads through cost efficiency and widespread deployment. Utility at 68.7% reflects large-scale project dominance. ACT & New South Wales leads regionally at 33.5%, driven by strong policy support and high solar adoption rates across the australia solar power equipment market.
Key Market Insights
| Insight | Data |
|---|---|
| Dominant Type | Solar Photovoltaic (PV) – 96.5% share (2025) |
| Dominant Deployment | Utility – 68.7% market share (2025) |
| Leading Region | ACT & New South Wales – 33.5% share (2025) |
| Key Opportunity | Utility-scale solar farm development, battery storage integration, green hydrogen synergies, and rooftop solar expansion in the australia solar panel market |
Key Analytical Observations Supporting the Above Data:
- Solar PV at 96.5%: The Solar PV segment dominates due to its superior cost-competitiveness, technological maturity, and scalability across residential, commercial, and utility applications. Continuous advances in module efficiency and the rapidly growing australia solar pv inverter market further strengthen this segment's dominance across all deployment scales.
- Utility Deployment at 68.7%: The Utility segment leads due to economies of scale in large solar project development, long-term power purchase agreements, and alignment with Australia's national renewable energy targets. Government-backed renewable energy auctions continue to support utility project pipelines within the australia solar power market.
- ACT & NSW at 33.5%: ACT & New South Wales leads regionally due to high population density, strong policy frameworks, elevated electricity prices motivating solar adoption, and a high concentration of commercial and industrial solar installations within the australia solar power equipment market.
Australia Solar Power Market Overview
The australia solar power market represents one of the most commercially advanced solar markets globally, characterized by high per-capita solar installations, exceptional solar irradiance across most of the continent, and a diversified ecosystem spanning rooftop residential, commercial, and utility-scale segments. Australia's solar resource advantage enables one of the world's most favorable environments for low-cost solar energy generation across the australia solar panel market.
The australia solar power equipment market integrates global module manufacturers, domestic EPC contractors, grid operators, financiers, and technology providers. Macroeconomic drivers include rising electricity prices, decarbonization commitments, and growing corporate renewable energy procurement. The expanding australia solar pv inverter market further strengthens the ecosystem through improved grid integration and energy management capabilities.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
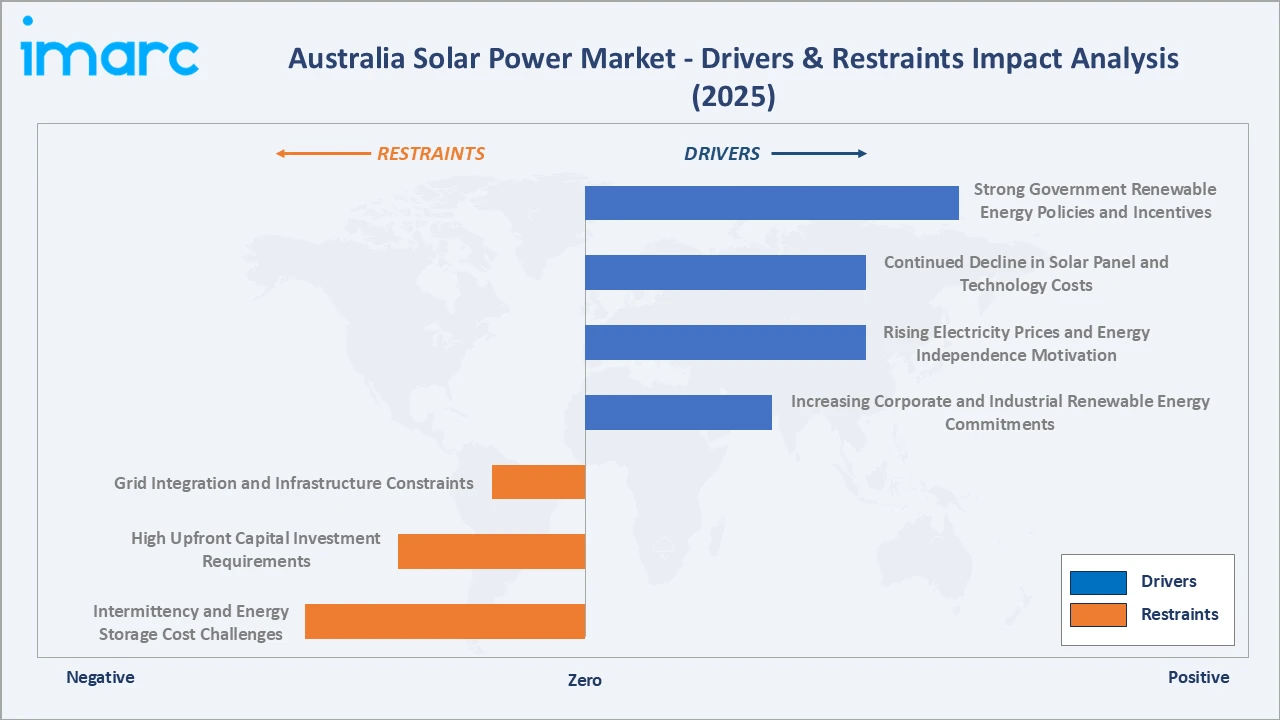
- Strong Government Renewable Energy Policies and Incentives: Government renewable energy policies and incentive programs are primary market drivers, reducing the effective cost of solar installations for end users and creating regulatory certainty for project developers. Policy support mechanisms drive adoption across residential, commercial, and utility segments, accelerating overall market expansion across the australia solar power market and reinforcing the competitive position of the solar industry Australia in the regional renewable energy landscape.
- Continued Decline in Solar Panel and Technology Costs: Continuous decline in solar PV module, inverter, and balance-of-system component costs is making solar energy progressively more competitive against conventional electricity generation. Cost reductions enable new customer segments and deployment contexts, driving adoption across the australia solar panel market and supporting sustained high-growth rates. The australia solar pv inverter market similarly benefits from technology cost reductions, improving the overall system economics of solar installations.
- Rising Electricity Prices and Energy Independence Motivation: Persistently elevated electricity tariffs are compelling residential and commercial consumers to adopt solar PV systems as a cost-saving measure. Shortened payback periods and energy independence motivations strengthen the investment case for solar adoption across all consumer segments. This dynamic sustains consistent demand for the australia solar power equipment market independent of policy incentives.
- Increasing Corporate and Industrial Renewable Energy Commitments: Corporate power purchase agreements and sustainability commitments are generating substantial demand for utility-scale and commercial solar projects. Large energy users procuring solar energy to meet decarbonization targets and reduce operating costs create a durable structural demand driver for the australia solar power market, supporting long-term project pipelines and investment certainty.
Market Restraints
- Grid Integration and Infrastructure Constraints: Integrating large volumes of intermittent solar energy into existing grid infrastructure presents technical and economic challenges. Transmission network limitations, grid stability requirements, and the need for complementary storage or firming capacity increase overall system costs, creating barriers to expanding solar penetration in regions with constrained grid infrastructure.
- High Upfront Capital Investment Requirements: Despite declining technology costs, the initial capital investment for solar installations remains significant, particularly for utility-scale projects. Access to project financing, permitting timelines, and construction cost pressures can constrain project development pipelines, slowing overall market growth relative to available solar resource potential.
- Intermittency and Energy Storage Cost Challenges: The inherent intermittency of solar generation requires complementary storage or backup capacity, adding to overall system costs. Achieving cost-effective solar-plus-storage solutions at scale remains challenging, limiting the commercial viability of fully self-sufficient solar installations and constraining market penetration in certain segments and regions.
Market Opportunities
- Green Hydrogen Production Synergies: Australia's abundant solar resources create substantial opportunity for green hydrogen production, with solar power providing low-cost renewable electricity for large-scale electrolysis operations. Developing solar-to-hydrogen projects in high-irradiance regions represents a significant emerging demand driver for utility-scale solar within the australia solar power market.
- Battery Storage Integration and Virtual Power Plants: Combining solar PV with battery storage systems creates new value propositions for residential and commercial customers, enabling greater self-sufficiency and participation in demand response programs. This integration opportunity expands the addressable market and increases average system value across the australia solar panel market.
Market Challenges
- Skilled Workforce Constraints in Rapid Expansion: Rapid market growth is creating pressures on workforce availability across installation, engineering, and project management functions. Workforce development capacity must scale alongside market growth to sustain deployment rates and maintain installation quality standards across the australia solar power market.
- Supply Chain Disruptions and Equipment Cost Volatility: Global supply chain dynamics and logistical challenges can introduce pricing uncertainty and project timeline risks for solar equipment procurement. Cost volatility can affect project economics and development decisions, creating operational challenges for developers and installers across all segments of the australia solar power equipment market.
Emerging Market Trends
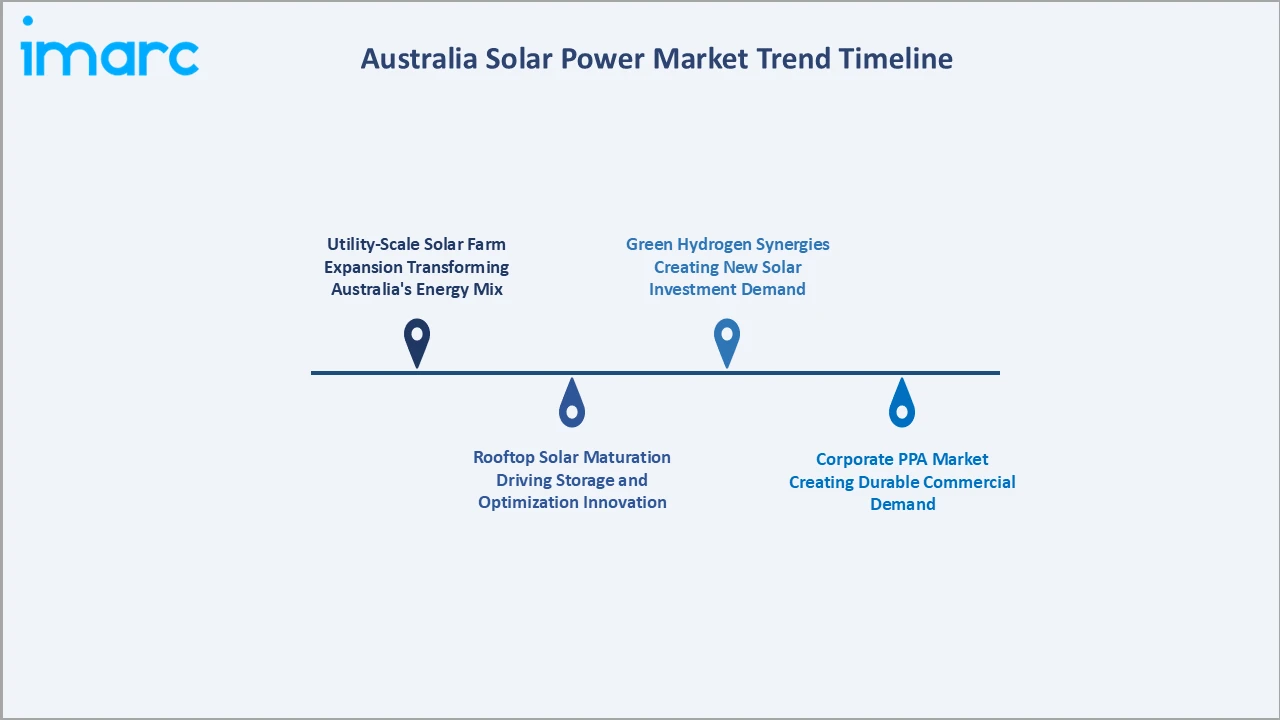
1. Utility-Scale Solar Farm Expansion Transforming Australia's Energy Mix
Utility-scale solar farms are fundamentally reshaping Australia's electricity generation mix, with large-scale projects delivering significant capacity additions. Falling costs, government auction programs, and long-term power purchase agreement availability support continued utility project development, creating structural demand for solar equipment and driving growth across the australia solar power equipment market through the forecast period.
2. Rooftop Solar Maturation Driving Storage and Optimization Innovation
Australia's high rooftop solar penetration in metropolitan areas is driving innovation in inverter technology, smart energy management systems, and battery storage integration. The maturing residential australia solar panel market is creating demand for next-generation optimization tools, virtual power plant participation, and advanced monitoring capabilities within the australia solar pv inverter market.
3. Corporate PPA Market Creating Durable Commercial Demand
Corporate power purchase agreements are establishing a significant new demand channel for utility-scale solar, enabling project developers to secure bankable revenue streams independent of government incentive reliance. Growing corporate sustainability commitments are supporting long-term solar PPA market growth and contributing to market maturation across the australia solar power market.
4. Green Hydrogen Synergies Creating New Solar Investment Demand
The convergence of Australia's solar resource advantage with global green hydrogen demand is creating investment opportunities for large-scale solar projects designed to power electrolysis facilities. This emerging trend supports development of solar installations in remote high-irradiance regions, expanding the geographic scope and total addressable market of the solar industry Australia beyond traditional grid-connected markets.
Industry Value Chain Analysis
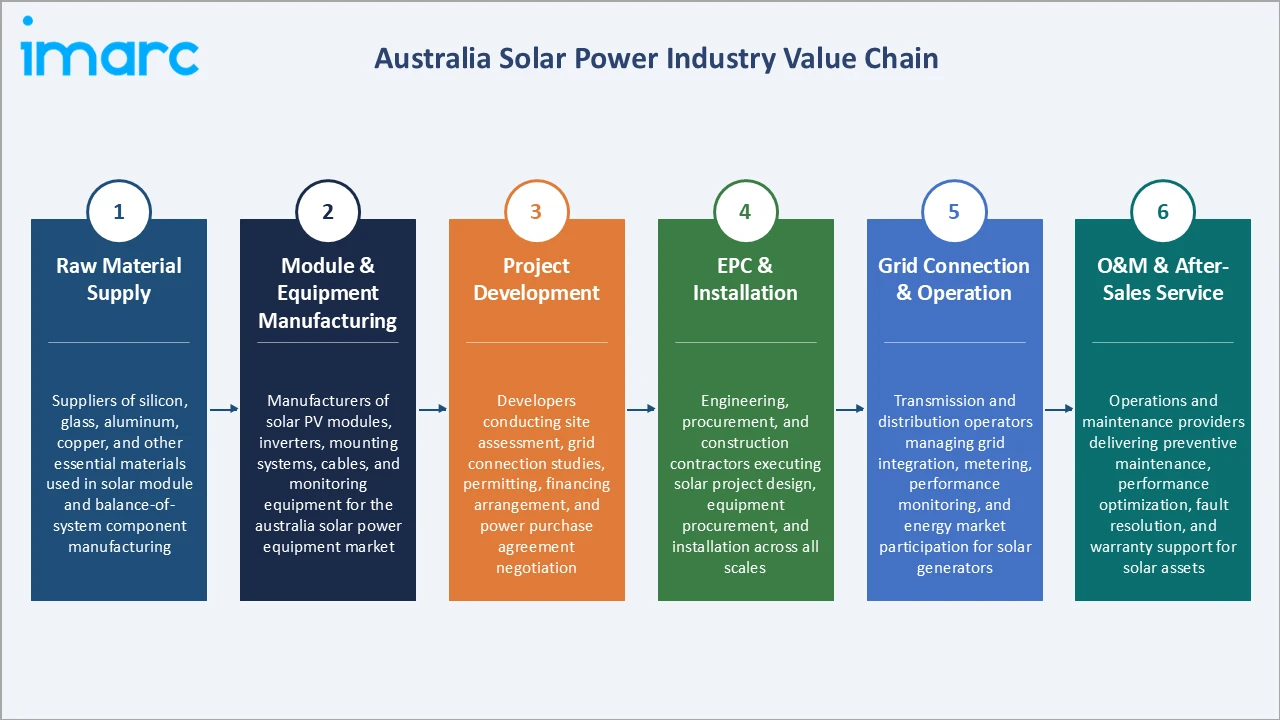
The Australia solar power market value chain integrates globally distributed raw material suppliers, manufacturing operations, project development services, engineering and construction contractors, grid connection operators, and ongoing asset management providers. Each stage creates distinct value contribution and presents specific investment and optimization opportunities for market participants across the solar industry Australia.
| Stage | Description |
|---|---|
| Raw Material Supply | Suppliers of silicon, glass, aluminum, copper, and other essential materials used in solar module and balance-of-system component manufacturing |
| Module & Equipment Manufacturing | Manufacturers of solar PV modules, inverters, mounting systems, cables, and monitoring equipment for the australia solar power equipment market |
| Project Development | Developers conducting site assessment, grid connection studies, permitting, financing arrangement, and power purchase agreement negotiation |
| EPC & Installation | Engineering, procurement, and construction contractors executing solar project design, equipment procurement, and installation across all scales |
| Grid Connection & Operation | Transmission and distribution operators managing grid integration, metering, performance monitoring, and energy market participation for solar generators |
| O&M & After-Sales Service | Operations and maintenance providers delivering preventive maintenance, performance optimization, fault resolution, and warranty support for solar assets |
The project development stage represents the australia solar power value chain's most strategically critical function, where site selection, grid connection security, and commercial agreement terms determine overall project viability and investor returns.
Technology Landscape in the Australia Solar Power Industry
Crystalline Silicon Solar Cell Technology
Crystalline silicon remains the dominant technology in the australia solar panel market, with monocrystalline PERC and TOPCon cell architectures achieving efficiency improvements. Ongoing advancements in cell design and manufacturing processes continue to reduce cost per watt, supporting the competitive position of solar PV across all deployment segments.
Solar Inverter and Power Electronics Innovation
Advanced string inverters, microinverters, and power optimizers are transforming system performance across the australia solar pv inverter market. Next-generation inverter products with integrated monitoring, smart grid communication capabilities, and battery storage interfaces enable sophisticated energy management for residential and commercial solar installations.
Battery Energy Storage Integration
Battery storage integration with solar PV systems is creating new value propositions across residential, commercial, and utility segments. Solar-plus-storage solutions enable self-consumption optimization, time-of-use arbitrage, and grid services participation, expanding the addressable market and increasing average system value across the australia solar power equipment market.
Concentrated Solar Power and Emerging Technologies
CSP technology with integrated thermal storage provides dispatchable renewable generation that complements intermittent solar PV production. Emerging technologies including bifacial solar panels, agrivoltaic systems, and floating solar installations are expanding deployment contexts and potential applications across the australia solar power market.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Type | Solar Photovoltaic (PV) | 96.5% | 2025 |
| Deployment | Utility | 68.7% | 2025 |
| Region | ACT & New South Wales | 33.5% | 2025 |

By Type
Solar Photovoltaic (PV) leads the australia solar power market at 96.5% in 2025 and grows at a CAGR of ~15.4% during 2026-2034. The Solar PV segment encompasses the full spectrum of solar deployment from small residential rooftop systems to large utility-scale solar farms, reflecting the technology's versatility, scalability, and cost competitiveness across all customer categories and application contexts within the australia solar panel market.
To access detailed market analysis, Request Sample
Concentrated Solar Power (CSP) at 3.5% grows at a CAGR of ~9.8% during 2026-2034, representing a strategically important segment offering dispatchable renewable generation through thermal storage integration. CSP projects operate primarily in high-direct-normal-irradiance regions, delivering reliable solar generation capacity that can be dispatched independent of instantaneous sunlight availability, complementing the broader solar industry Australia.
By Deployment
Utility deployment leads the australia solar power market at 68.7% in 2025 and grows at a CAGR of ~14.5% during 2026-2034. The Utility segment encompasses large-scale solar farms connected directly to the high-voltage transmission grid, benefiting from economies of scale, long-term PPA availability, and government renewable energy auction programs supporting the australia solar power equipment market through the forecast period.
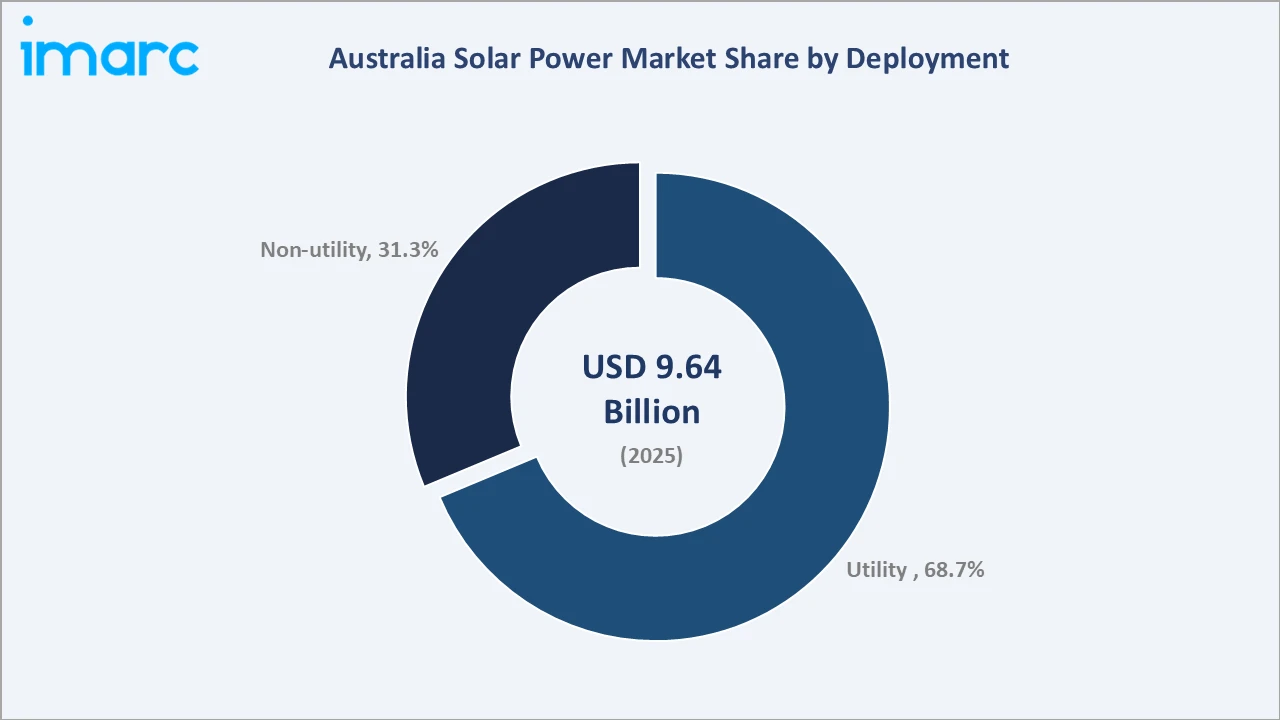
Non-Utility deployment at 31.3% grows at the fastest CAGR of ~16.2% during 2026-2034, encompassing residential rooftop, commercial and industrial, and community solar installations. Growth is driven by high electricity price sensitivity, government incentive programs, and increasing consumer preference for energy self-sufficiency across the solar industry Australia.
Regional Market Insights
| Region | Share (2025) | Key Australia Solar Power Market Drivers & Characteristics |
|---|---|---|
| ACT & New South Wales | 33.5% | High population density, strong policy support, elevated electricity prices, and high concentration of commercial and industrial solar installations. |
| Queensland | 26.8% | Exceptional solar irradiance, significant land availability for utility-scale farms, strong state renewable energy targets, and growing residential adoption. |
| Victoria & Tasmania | 21.7% | Strong state renewable energy policies, growing rooftop solar penetration, increasing utility-scale project development, and industrial renewable energy procurement. |
| Western Australia | 12.6% | Isolated grid enabling higher solar penetration, remote community solar projects, growing mining industry renewable energy adoption, and strong solar resources. |
| NT & South Australia | 5.4% | Emerging utility-scale developments, remote community solar electrification, and early-stage growth in industrial renewable energy projects across the region. |
ACT & New South Wales leads at 33.5%, reflecting the ACT's 100% renewable energy commitment, a large commercial solar market in the greater Sydney region, and concentration of corporate PPA procurement activity. Queensland at 26.8% benefits from Australia's strongest solar irradiance resources and significant utility-scale solar farm development in inland regions of the australia solar power market.
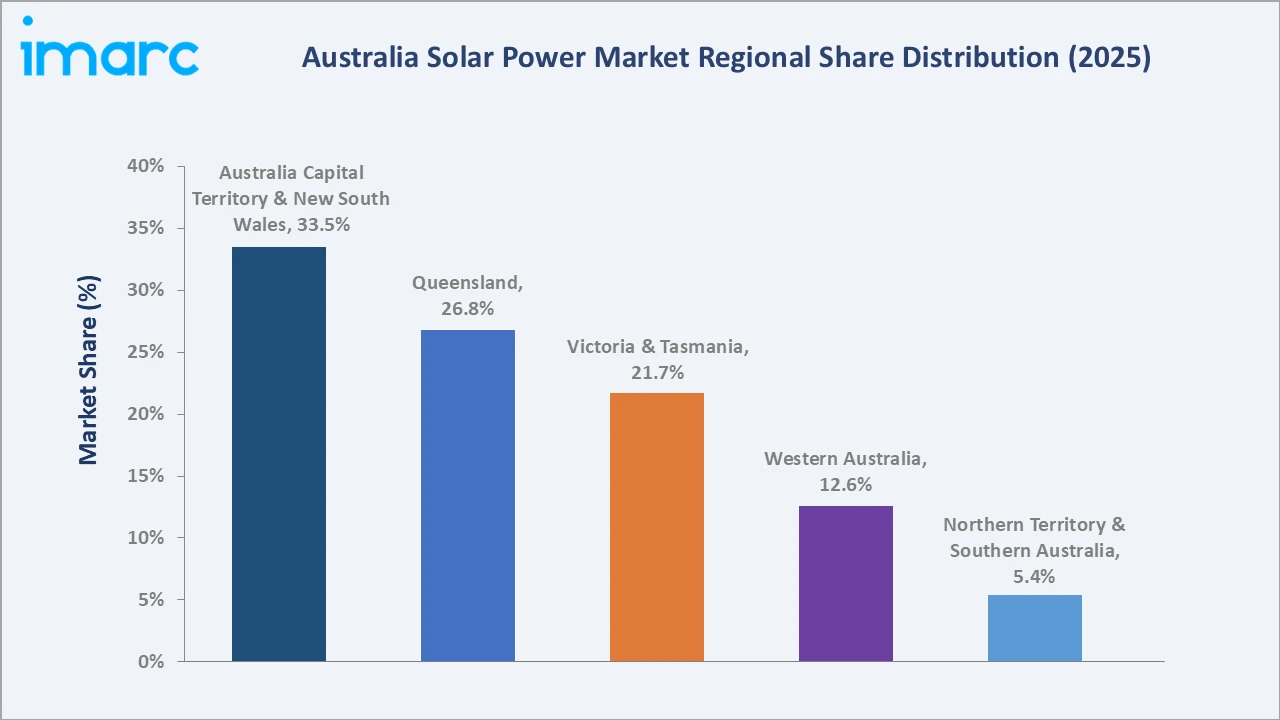
Victoria & Tasmania at 21.7% reflects state government renewable energy targets and growing commercial and industrial solar adoption. Western Australia at 12.6% leverages its isolated grid structure, which enables higher solar penetration ratios than interconnected grid regions within the solar industry Australia. NT & South Australia at 5.4% represents the earliest stage of development, with significant long-term growth potential.
Competitive Landscape
The australia solar power market competitive landscape encompasses integrated energy companies, global solar equipment manufacturers, specialized project developers, and technology innovators. Competition is intensifying across all segments as falling costs attract new participants and established energy companies expand solar portfolios to meet corporate decarbonization targets within the australia solar power equipment market.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| AGL Energy Limited | Utility solar farms, retail solar & storage products | Market Leader | Large-scale solar project development and vertically integrated energy retail |
| Origin Energy Limited | Utility solar generation | Strong Challenger | Commercial and industrial solar PPA expertise with integrated energy retail |
| Acciona Energy Australia | Large-scale solar farms | Strong Challenger | International renewable project development expertise and utility execution |
| Trina Solar Limited | High-efficiency solar panels | Innovator | Advanced solar cell technology, bifacial module leadership and R&D capability |
The competitive landscape's most significant dynamic is the growing participation of large integrated energy companies deploying capital into solar generation assets, creating competitive pressure on specialized solar developers while bringing substantial financing capacity to project development across the australia solar power market.
Key Company Profiles
AGL Energy Limited
AGL Energy Limited is one of Australia's largest integrated energy companies with a growing renewable energy portfolio spanning solar generation, energy storage, and retail energy services. The company is actively expanding its solar generation capacity through utility-scale project development and commercial renewable energy agreements.
- Key Offerings: Utility-scale solar farms, residential and commercial solar products, battery storage systems, and renewable energy retail services across the australia solar power market.
- Recent Developments: In October 2026, AGL Energy partnered with Bega Group to deliver a 1.23 MW rooftop solar installation at its food manufacturing facility in Wetherill Park, Western Sydney. The project will include more than 2,400 solar panels and is expected to reduce emissions associated with electricity consumption at the site by 9% in its first year. Under a 15-year Power Purchase Agreement (PPA), AGL will build, own and operate the solar system without requiring upfront capital investment from Bega Group.
- Strategic Focus: Expanding renewable generation capacity through utility-scale solar development, transitioning from conventional generation assets, and growing retail solar and storage customer base across the solar industry Australia.
Origin Energy Limited
Origin Energy Limited is a leading Australian integrated energy company with increasing focus on solar power generation and commercial renewable energy solutions. The company leverages its extensive customer relationships and energy retail infrastructure to deliver solar and storage solutions across the australia solar power market.
- Key Offerings: Utility solar generation, commercial and industrial solar PPA solutions, residential solar and battery packages, and renewable energy certificate services.
- Recent Developments: In August 2026, Origin Energy Limited and Coles Group extended their renewable electricity partnership for another three years. The agreement targets the installation of 15 MW of solar capacity across 75 Coles sites, alongside 15 MWh of battery storage. The initiative aims to reduce emissions, improve energy resilience and support Australia's transition to a lower-carbon electricity system. The partnership will also expand trials of battery systems that combine backup power with electricity market participation and peak-demand management.
- Strategic Focus: Growing renewable energy generation assets, expanding commercial solar PPA market share, and integrating solar with battery storage to deliver enhanced energy solutions within the australia solar panel market.
Acciona Energy Australia
Acciona Energy Australia is a subsidiary of a leading international renewable energy group, specializing in large-scale solar and wind project development. The company brings international renewable energy project expertise and substantial financial capacity to the australia solar power equipment market, enabling delivery of major utility-scale solar projects.
- Key Offerings: Large-scale utility solar farms, renewable project development services, EPC contracting, and long-term operations and maintenance for solar generation assets.
- Recent Developments: In December 2025, ACCIONA Energía announced the completion of commissioning and the start of commercial operations at its Aldoga Solar Farm in Queensland, Australia. The 480 MWp solar photovoltaic project is expected to generate enough clean electricity to meet the annual consumption of approximately 185,000 households and avoid around 934,000 tonnes of CO₂ emissions annually. Under a 15-year Power Purchase Agreement, the entire renewable electricity output will be supplied to Stanwell Corporation, supporting Queensland’s clean energy transition.
- Strategic Focus: Delivering utility-scale solar projects through integrated development and construction capabilities, leveraging international renewable energy expertise to secure and execute major Australian renewable energy tenders.
Market Concentration Analysis
The australia solar power market exhibits a moderately fragmented competitive structure across project development and equipment supply segments, with multiple international and domestic participants competing on technology, price, and execution capability. Concentration varies by segment, with utility-scale project development showing higher concentration among well-capitalized energy companies, while residential and commercial installation markets remain fragmented across a large number of certified installers operating throughout Australian states and territories.
Market concentration is evolving through two opposing dynamics: consolidation in utility-scale development where capital requirements and competitive tendering favor larger participants, while distributed solar installation markets remain fragmented with relatively low barriers to certified entry. Equipment supply concentration at the module and inverter manufacturing level is moderately high, with a concentrated group of global manufacturers supplying the majority of product volumes deployed across the australia solar power market.
Investment & Growth Opportunities
Highest Growth Segments
Non-Utility deployment (~16.2% CAGR through residential and C&I solar growth), Solar PV segment (~15.4% CAGR through continued cost reductions and mass adoption), Utility-scale solar (~14.5% CAGR through large solar farm development), Overall Market (15.0% CAGR reflecting broad sector momentum), and CSP (~9.8% CAGR through dispatchable renewable applications) represent the australia solar power market's highest-growth investment segments through 2034.
Emerging Investment Opportunities
Australia's green hydrogen development pipeline represents the most transformational emerging opportunity in the australia solar power market. Solar-to-hydrogen projects require large-scale solar generation in high-irradiance locations, creating investment demand for remote utility-scale solar farm development beyond traditional grid-connected markets. Solar-plus-storage systems are also growing rapidly within the Non-Utility segment, driven by residential and commercial demand for energy independence across the australia solar panel market.
Investment Themes
- Utility-scale solar farm development targeting green hydrogen production facilities, creating demand in remote high-irradiance regions: Australia's strongest solar resource areas represent the most commercially viable locations for hydrogen-enabling large-scale solar, supporting the solar industry Australia's expansion beyond traditional grid-connected markets.
- Solar-plus-storage virtual power plant platform investment for Australia's distributed solar segment: High rooftop solar penetration creates significant opportunity for aggregated battery storage platforms, delivering grid services while creating recurring revenue streams from residential and commercial customers across the australia solar power equipment market.
Future Market Outlook (2026-2034)
The australia solar power market is projected to grow from USD 9.64 Billion in 2025 to USD 11.09 Billion in 2026, reaching USD 33.92 Billion by 2034, at a CAGR of 15.00% during 2026-2034. The market's anchor value of USD 19.39 Billion in 2030 represents the solar industry Australia at a structural inflection point, where solar power becomes the dominant new electricity generation technology across all Australian states and territories.
Three structural forces define australia solar power market growth through 2034 Australia's commitment to net-zero emissions creating long-term policy certainty for solar investment; continuing technology cost reductions enabling new deployment contexts and customer segments across the australia solar panel market and australia solar pv inverter market; and growing corporate and industrial renewable energy procurement creating demand certainty independent of government incentive program dependency.
Research Methodology
Primary Research
Primary research comprised structured interviews with australia solar power market stakeholders, including solar project developers, EPC contractors, equipment distributors, grid operators, policy specialists, and institutional investors. Consumer surveys covering residential and commercial solar adopters across major Australian states supplemented stakeholder interview findings, providing demand-side perspectives on adoption drivers and market barriers.
Secondary Research
Secondary research encompassed national energy market operator data, renewable energy regulator statistics, company annual reports, government energy department publications, investor presentations, industry association reports, and academic publications. Over 60 secondary sources were reviewed and cross-referenced to develop comprehensive market intelligence for the australia solar power market.
Forecasting Models
Market revenue forecasts were developed using a capacity-to-revenue model: installed solar capacity by year and segment multiplied by utilization factors and average realized energy prices by deployment type, aggregated to total market revenue. Policy scenario analysis and technology cost trajectory modeling informed key forecast assumptions through 2034.
Australia Solar Power Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Solar Photovoltaic (PV), Concentrated Solar Power (CSP) |
| Deployments Covered | Utlility, Non-utility |
| Regions Covered | Australia Capital Territory & New South Wales, Victoria & Tasmania, Queensland, Northern Territory & Southern Australia, Western Australia |
| Companies Covered | AGL Energy Limited, Origin Energy Limited, Acciona Energy Australia, Trina Solar Limited, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Australia solar power market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Australia solar power market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Australia solar power industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Australia Solar Power Market Report
The australia solar power market size is estimated at USD 11.09 Billion in 2026, driven by government renewable energy targets, falling solar costs, and strong residential and utility adoption.
The australia solar power market grows at 15.00% CAGR during 2026-2034, reaching USD 33.92 Billion by 2034, supported by policy frameworks, technology cost reductions, and corporate renewable procurement.
Solar PV leads at 96.5% growing at ~15.4% CAGR, driven by cost competitiveness and scalability across residential, commercial, and utility segments of the australia solar panel market.
Utility deployment leads at 68.7% growing at ~14.5% CAGR, supported by large-scale solar farm development and government renewable energy auction programs.
ACT & New South Wales leads at 33.5% through high population density, strong policy support, and elevated electricity prices driving solar adoption.
Leading companies include AGL Energy Limited, Origin Energy Limited, Acciona Energy Australia and Trina Solar Limited, among others.
Key drivers include government renewable energy policies, declining solar technology costs, rising electricity prices, and increasing corporate renewable commitments across the solar industry Australia.
The australia solar pv inverter market is expanding rapidly, with advanced inverter technologies supporting grid integration and battery storage system compatibility through 2034.
The australia solar panel market is projected to grow at ~15.4% CAGR, driven by both utility-scale and distributed solar deployment with high-efficiency module adoption accelerating.
Key opportunities in the australia solar power equipment market include battery storage integration, smart inverter technology, agrivoltaic systems, and green hydrogen enabling solar projects.
Australia ranks among global leaders in per-capita solar installations with one of the world's highest rooftop solar penetration rates and a rapidly growing utility-scale solar sector.
The solar industry Australia plays a central role in the national energy transition, with solar power targeted to supply a majority of Australia's electricity generation needs by 2034.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade