
Aptamers Market Size, Share, Trends and Forecast by Type, Application, and Region, 2026-2034
Global Aptamers Market Size, Share, Trends & Forecast (2026-2034)
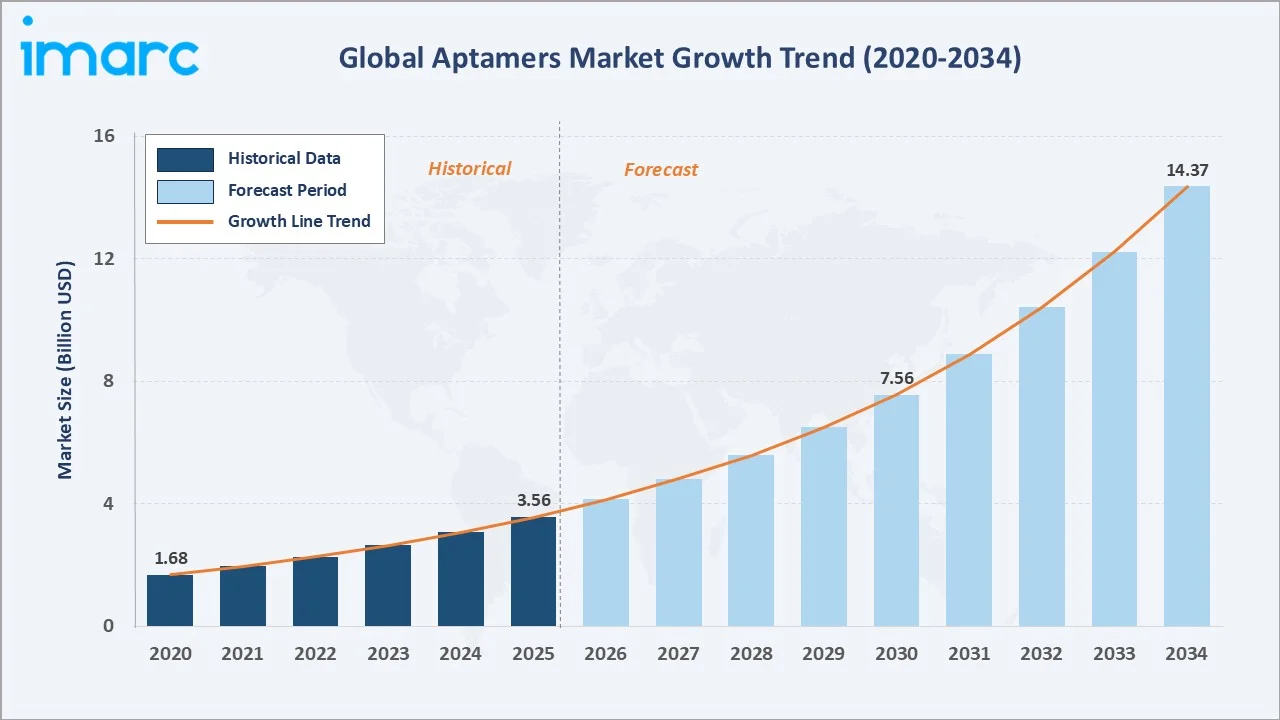
The global aptamers market grew from USD 3.56 Billion in 2025 to USD 4.14 Billion in 2026 and is projected to reach USD 14.37 Billion by 2034, growing at a CAGR of 16.26% during 2026-2034. The market is driven by biotechnology advancements, personalized medicine demand, and antibody cost advantages.
Expanding diagnostic, therapeutic, and research applications further support the aptamers market size. Nucleic acid dominates at 77.2%, reflecting its stability and ease of synthesis. Diagnostics leads applications at 36.8%. North America commands 40.7% of the global market share, backed by strong biotechnology research infrastructure.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 3.56 Billion |
|
Market Size (2026) |
USD 4.14 Billion |
|
Forecast Market Size (2034) |
USD 14.37 Billion |
|
CAGR (2026-2034) |
16.26% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Nucleic Acid (77.2%, 2025) |
|
Dominant Application |
Diagnostics (36.8%, 2025) |
|
Leading Region |
North America (40.7%, 2025) |
The global aptamers market increased from USD 1.68 Billion in 2020 to USD 3.56 Billion in 2025 and is estimated to reach USD 4.14 Billion in 2026. The market is further expected to grow to USD 7.56 Billion by 2030 and USD 14.37 Billion by 2034.
To get more information on this market, Request Sample
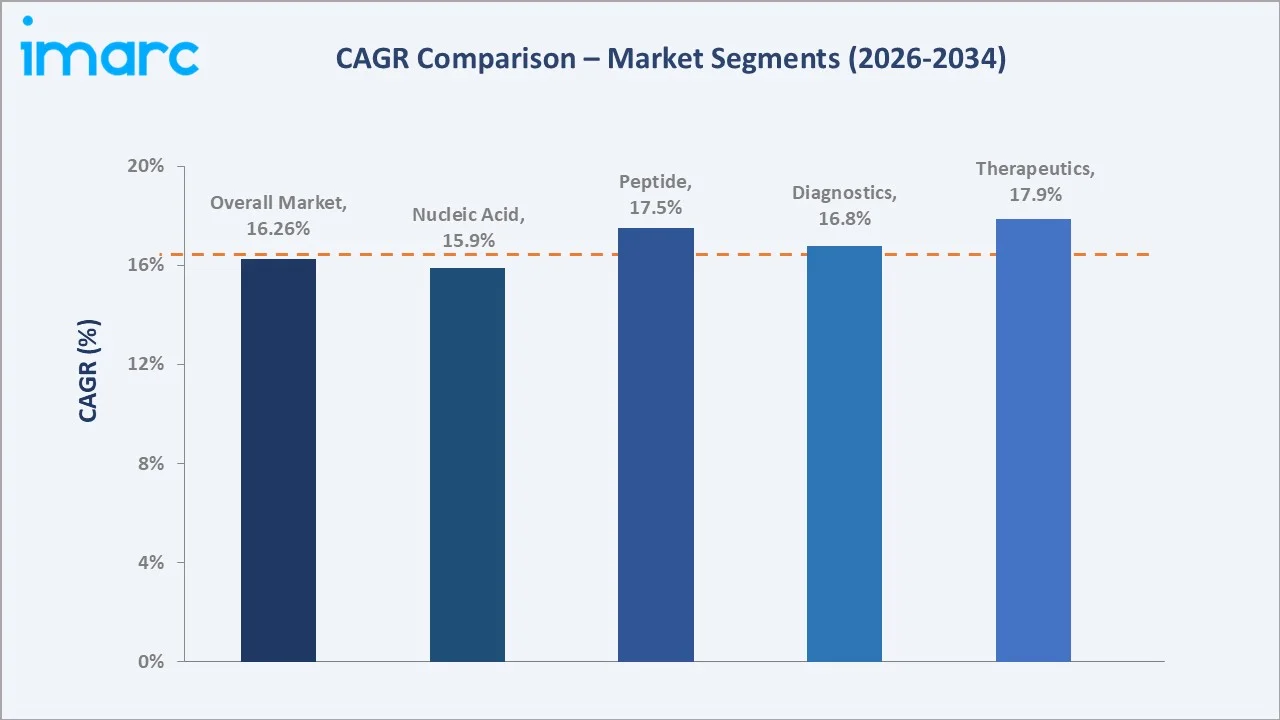
Therapeutics grows fastest at ~17.9% CAGR, supported by approved aptamer drugs such as avacincaptad pegol and expanding oncology pipelines. Peptide aptamers grow at ~17.5% CAGR as protein-scaffold binders gain traction in intracellular targeting, drug target validation, and early-stage therapeutic discovery programs.
Executive Summary
The global aptamers market expanded from USD 3.56 Billion in 2025 to an estimated USD 4.14 Billion in 2026. Aptamers, synthetic oligonucleotide or peptide binders, are increasingly replacing antibodies in assays, therapeutics, and research tools due to their stability, specificity, and animal-free production.
Key aptamers market trends include AI-driven design, aptamer-based proteomics, and targeted radiopharmaceuticals. The market is projected to reach USD 14.37 Billion by 2034. Nucleic acid at 77.2% leads through superior stability. Diagnostics at 36.8% reflects biomarker detection demand. North America leads regionally at 40.7%.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Nucleic Acid - 77.2% share (2025) |
|
Dominant Application |
Diagnostics - 36.8% market share (2025) |
|
Leading Region |
North America - 40.7% share (2025) |
|
Market Opportunity |
Point-of-care aptamer biosensors; aptamer-drug conjugates and targeted radiopharmaceuticals; AI-driven aptamer design; aptamer-based proteomics platforms |
Key Analytical Observations Supporting the Above Data:
- Nucleic Acid at 77.2%: DNA and RNA aptamers dominate due to superior stability, high specificity, and ease of chemical synthesis. Their adaptability across diagnostics, therapeutics, and research makes them the preferred choice for developers. Continuous improvements in synthesis chemistry and modification technologies further strengthen the segment's leadership position. Their compatibility with established oligonucleotide manufacturing infrastructure also supports scalable commercial supply.
- Diagnostics at 36.8%: Diagnostics leads as aptamers offer high binding affinity, easy modification, and faster development timelines for laboratory and point-of-care tests across oncology, infectious diseases, and personalized medicine. Growing demand for rapid and decentralized testing further reinforces the segment's leadership. Aptamer-based assays also offer longer shelf life and lower batch variability than antibody-based tests.
- North America at 40.7%: North America dominates due to advanced biotechnology infrastructure, supportive regulatory frameworks, and substantial public and private R&D investment, with the United States accounting for over 87.50% of the regional market. Early commercialization of aptamer-based products also supports regional leadership. Strong collaboration between universities, biotechnology firms, and pharmaceutical companies further accelerates innovation.
Global Aptamers Market Overview
Aptamers are short single-stranded DNA, RNA, or peptide molecules selected through Systematic Evolution of Ligands by Exponential Enrichment (SELEX) to bind specific targets. Often called chemical antibodies, they combine antibody-like affinity with synthetic reproducibility, low immunogenicity, long shelf life, and flexible chemical modification.
The aptamers ecosystem integrates oligonucleotide suppliers, aptamer developers, pharmaceutical and diagnostic licensees, contract research organizations, and regulators. Macroeconomic factors include rising chronic disease burden, aging populations, growing healthcare R&D spending, and increasing public funding for precision medicine research worldwide.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
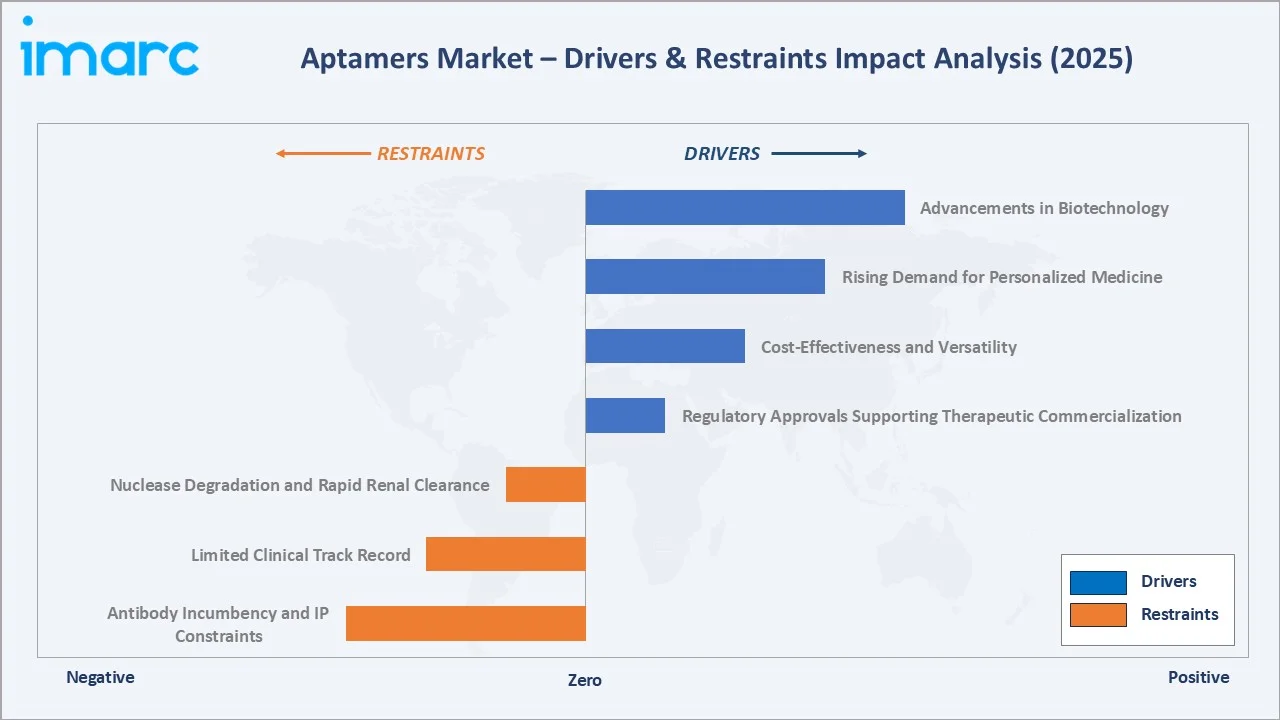
- Advancements in Biotechnology: Improved SELEX methods, high-throughput screening, and chemical modifications are enhancing aptamer specificity and stability. In November 2024, a genetic medicines client of Aptamer Group advanced Optimer delivery vehicles to the final commercial development stage. These innovations allow aptamers to compete with antibodies in performance while offering faster, more reproducible development. As a result, adoption is widening across diagnostics, therapeutic development, and disease monitoring.
- Rising Demand for Personalized Medicine: Aptamers precisely target biomarkers, aligning with individualized treatment in oncology, genetic disorders, and autoimmune diseases. Growing demand for accurate companion diagnostics and targeted therapies is expanding aptamer adoption across clinical and research settings. Aptamers can be rapidly customized against patient-specific biomarkers, supporting precise therapy selection. This alignment with individualized care is encouraging pharmaceutical and diagnostic companies to integrate aptamers into their development pipelines.
- Cost-Effectiveness and Versatility: Aptamers are chemically synthesized at scale without animal-derived materials, lowering production costs and batch variability. Their long shelf life and use in biosensors, drug delivery, and molecular imaging make them attractive antibody alternatives. Scalable synthesis also shortens lead times and reduces cold-chain dependence during storage and transport. These economic benefits particularly attract high-volume diagnostic manufacturers and cost-sensitive healthcare systems in emerging markets.
- Regulatory Approvals Supporting Therapeutic Commercialization: In September 2025, Japan granted conditional approval to Astellas' IZERVAY (avacincaptad pegol), a synthetic C5-inhibiting aptamer, as the country's first geographic atrophy treatment. Such approvals validate aptamer therapeutics commercially. IZERVAY recorded US sales of USD 110 Million during April-June 2025, demonstrating real-world commercial demand. Successful approvals are strengthening investor confidence and encouraging pharmaceutical companies to advance aptamer candidates into late-stage development.
Market Restraints
- Nuclease Degradation and Rapid Renal Clearance: Unmodified aptamers are rapidly degraded by nucleases and filtered by kidneys due to their small size. Required modifications such as PEGylation and backbone substitution add cost and development complexity. These modifications can also alter binding properties, requiring additional optimization rounds and validation studies. Consequently, development timelines lengthen and costs rise, limiting the pace at which aptamer therapeutics progress toward clinical use.
- Limited Clinical Track Record: Only a few aptamer therapeutics have reached approval, limiting clinical confidence among pharmaceutical partners. Many programs remain dependent on out-licensing, slowing late-stage development and commercial scale-up. Smaller developers often face funding constraints while seeking partners, delaying trial initiation. This limited track record also makes regulators and payers cautious, slowing broader acceptance of aptamer-based drugs in mainstream treatment protocols.
- Antibody Incumbency and IP Constraints: Well-established antibody workflows, validated reagents, and clinician familiarity slow aptamer substitution. Fragmented SELEX-related patents and freedom-to-operate concerns further raise barriers for new entrants. Diagnostic and research laboratories often hesitate to revalidate established assays with new binders. This inertia restricts aptamer penetration in mature application areas, despite clear technical and economic advantages over antibodies.
Market Opportunities
- Point-of-Care Aptamer Biosensors: Aptamer stability at ambient temperature suits low-cost rapid tests for resource-limited settings. In March 2025, Kiffik Biomedical and Rubix LS partnered on a rapid colorectal cancer test combining interstitial fluid collection with aptamer detection. Growing emphasis on decentralized testing and early disease detection is increasing demand for such formats. Developers combining aptamers with portable readers and smartphone connectivity can capture significant value in near-patient testing.
- Aptamer-Drug Conjugates and Radiopharmaceuticals: Aptamers are emerging as precise delivery vehicles for cytotoxic payloads and radioligands. Their small size enables tissue penetration and fast clearance, creating opportunities in targeted oncology therapeutics. Partnerships with large pharmaceutical companies can accelerate clinical validation and provide developers with milestone and royalty revenue.
Market Challenges
- SELEX Selection Variability: SELEX outcomes vary with target conformation, buffer conditions, and library design, often yielding binders that underperform in complex biological samples. Improving reproducibility and real-world validation remains a key technical challenge. Inconsistent performance between laboratory conditions and clinical samples can erode end-user confidence. Developers must invest in rigorous validation, standardized protocols, and advanced selection techniques to ensure reliable, reproducible binders.
- GMP Manufacturing Scale-Up: Producing heavily modified oligonucleotides at therapeutic scale requires specialized GMP capacity and costly reagents. Limited supplier capacity and quality control demands affect timelines and margins for aptamer developers. Smaller companies often depend on a limited number of contract manufacturers, creating supply risk. Building dedicated capacity or securing long-term manufacturing agreements is therefore essential for commercial-scale aptamer programs.
Emerging Market Trends
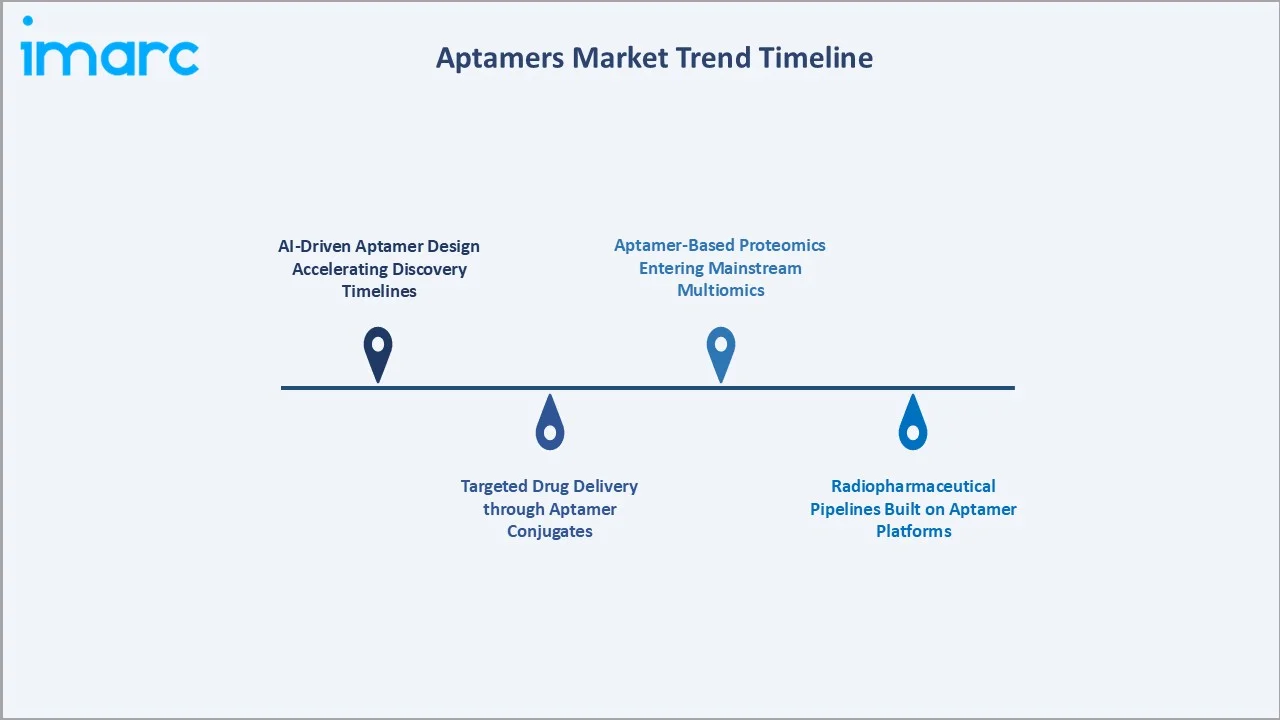
1. AI-Driven Aptamer Design Accelerating Discovery Timelines
Machine learning and artificial intelligence are increasingly being applied to aptamer discovery and optimization, enabling researchers to predict target binding, identify promising sequences, and reduce the number of experimental screening cycles. The integration of AI with computational modeling and oligonucleotide expertise is expected to improve development efficiency and accelerate the identification of therapeutic aptamers.
2. Aptamer-Based Proteomics Entering Mainstream Multiomics
Aptamer-based proteomic technologies are gaining traction in large-scale protein profiling and multiomics research due to their ability to analyze thousands of proteins using relatively small biological samples. Increasing integration of aptamer-based platforms with sequencing and other high-throughput technologies is expanding their applications in biomarker discovery, disease research, drug development, and precision medicine.
3. Targeted Drug Delivery through Aptamer Conjugates
Aptamers are increasingly being engineered as targeted drug-delivery vehicles because of their ability to selectively recognize specific cellular targets. Aptamer–drug conjugates and other aptamer-based delivery systems are being investigated for directing therapeutic payloads toward cancer cells and other disease-associated cells, with the potential to improve treatment specificity while reducing exposure to healthy tissues.
4. Radiopharmaceutical Pipelines Built on Aptamer Platforms
Aptamer-based radioconjugates are emerging as a potential platform for targeted radiopharmaceutical development. Their selective binding properties can enable the delivery of radioactive payloads to specific disease-associated targets, supporting applications in targeted radiotherapy and molecular imaging. Ongoing preclinical research and pipeline development are expected to further evaluate their targeting efficiency, safety, and therapeutic potential.
Industry Value Chain Analysis
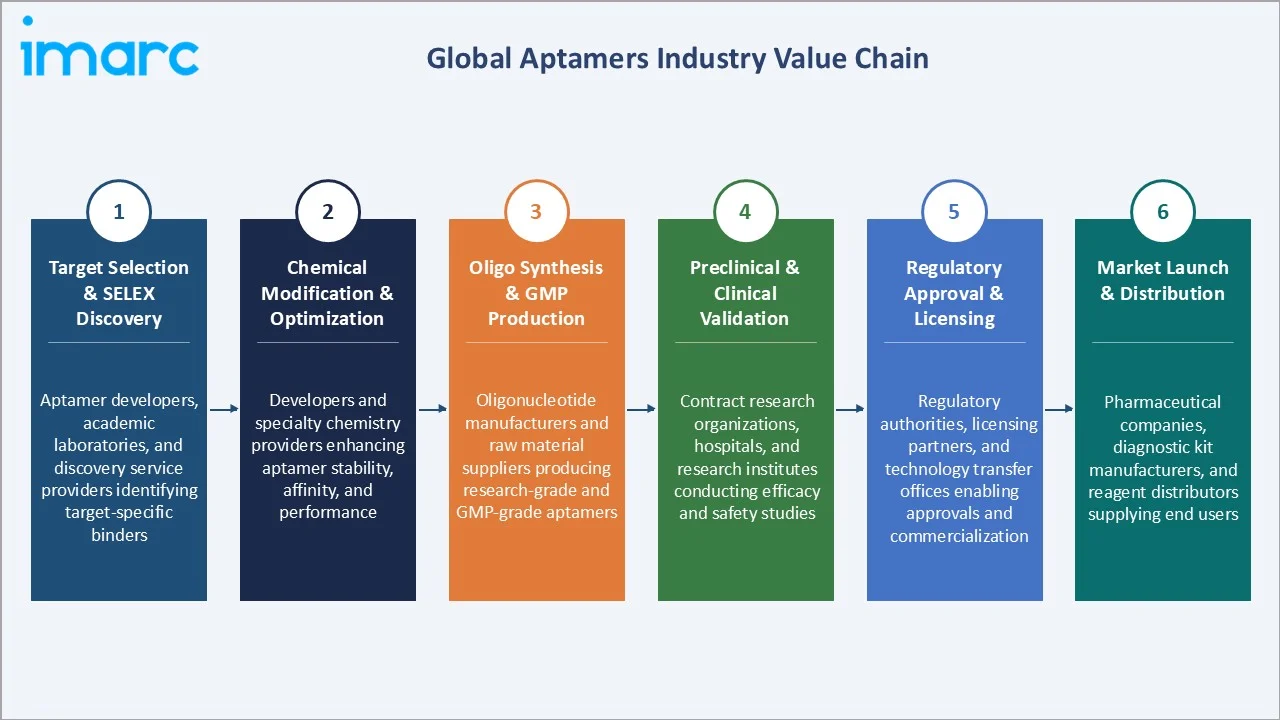
The aptamers value chain spans molecular discovery to clinical and commercial deployment. Value is concentrated in proprietary selection platforms and chemical modification know-how, while revenue increasingly flows through licensing, royalties, and supply agreements with pharmaceutical and diagnostic partners worldwide.
|
Stage |
Key Participants |
|
Target Selection & SELEX Discovery |
Aptamer developers, academic laboratories, and discovery service providers identifying target-specific binders |
|
Chemical Modification & Optimization |
Developers and specialty chemistry providers enhancing aptamer stability, affinity, and performance |
|
Oligo Synthesis & GMP Production |
Oligonucleotide manufacturers and raw material suppliers producing research-grade and GMP-grade aptamers |
|
Preclinical & Clinical Validation |
Contract research organizations, hospitals, and research institutes conducting efficacy and safety studies |
|
Regulatory Approval & Licensing |
Regulatory authorities, licensing partners, and technology transfer offices enabling approvals and commercialization |
|
Market Launch & Distribution |
Pharmaceutical companies, diagnostic kit manufacturers, and reagent distributors supplying end users |
Chemical modification and optimization is the most value-critical stage, as it determines in vivo stability, pharmacokinetics, and patentability. Developers owning proprietary modification chemistries command stronger licensing terms and clearly differentiate their platforms from generic SELEX providers globally.
Technology Landscape in the Global Aptamers Industry
SELEX and Cell-SELEX Platforms
SELEX remains the core discovery method, iteratively enriching binders from large random libraries. Cell-SELEX selects aptamers against live cell surfaces, capturing native protein conformations. Capillary electrophoresis and microfluidic SELEX shorten selection cycles, reduce reagent use, and improve overall binder quality.
Chemical Modification and Stabilization
Modified bases, 2'-fluoro and 2'-O-methyl sugars, PEGylation, and mirror-image L-RNA chemistry extend aptamer half-life and resist nucleases. Slow off-rate modified aptamers enhance binding for proteomics, while TME Pharma's L-RNA aptamers avoid enzymatic degradation in vivo.
Aptamer-Based Biosensors and Proteomics
Aptamers integrate into electrochemical, optical, and lateral flow biosensors for rapid, low-cost detection. Aptamer-based proteomics platforms such as SomaScan measure thousands of proteins simultaneously, supporting biomarker discovery, drug development, clinical research, and population-scale health studies across academic and commercial settings.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Nucleic Acid |
77.2% |
2025 |
|
Application |
Diagnostics |
36.8% |
2025 |
|
Region |
North America |
40.7% |
2025 |

By Type
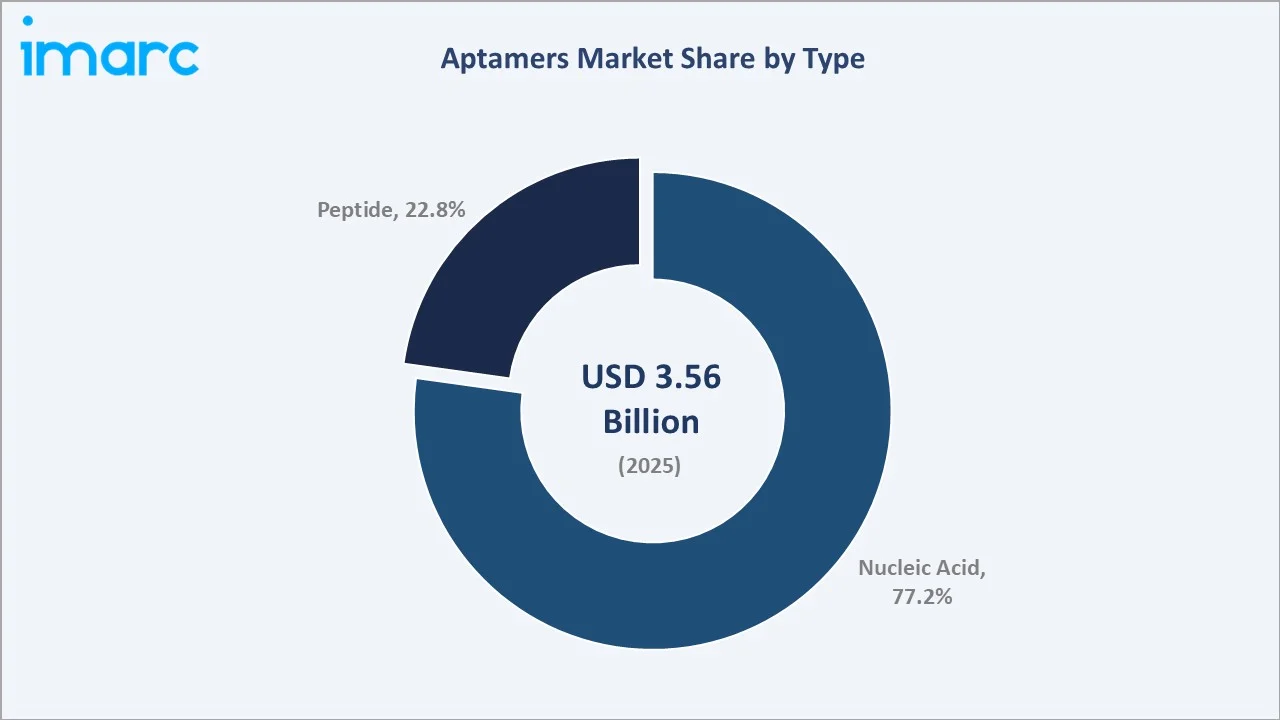
Nucleic acid leads at 77.2% (2025). DNA and RNA aptamers offer superior stability, specificity, and ease of synthesis, enabling broad use in diagnostics and therapeutics. Continuous advances in nucleic acid chemistry and mass production capabilities continue to reinforce the segment's dominant aptamers market share.
To access detailed market analysis, Request Sample
Peptide at 22.8% grows fastest at ~17.5% CAGR. Peptide aptamers, displayed on stable protein scaffolds, disrupt intracellular protein interactions and support drug target validation, creating growing demand across academic research, pharmaceutical discovery, and emerging therapeutic development programs.
By Application
Diagnostics leads at 36.8% (2025). Aptamers bind biomarkers with high affinity and are easily synthesized and modified, supporting laboratory and point-of-care tests in oncology, infectious diseases, and cardiovascular care, while offering cost-effectiveness and faster development than antibody-based assays.
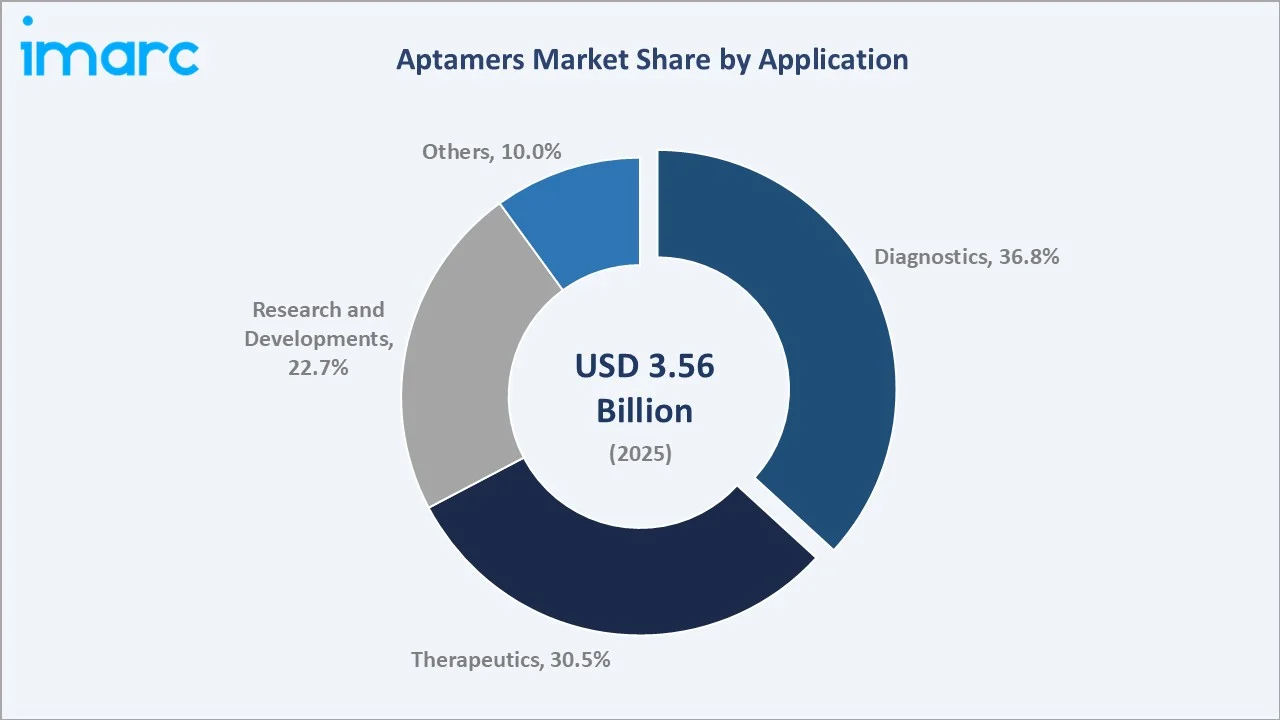
Therapeutics at 30.5% grows fastest at ~17.9% CAGR through approved ophthalmic aptamers and oncology pipelines. Research and developments holds 22.7%, driven by drug discovery tools, while others at 10.0% cover food safety, environmental testing, and bioprocessing applications.
Regional Market Insights
|
Region |
Share (2025) |
Key Global Aptamers Market Drivers & Characteristics |
|
North America |
40.7% |
Driven by advanced biotechnology infrastructure, strong R&D investment, and supportive regulatory frameworks across the United States and Canada. |
|
Asia-Pacific |
27.8% |
Supported by expanding healthcare access, rising diagnostic demand, and growing biomedical research funding across major economies. |
|
Europe |
21.0% |
Reflects an aging population, strong academic research, and demand for early and precise diagnostics and personalized care. |
|
Latin America |
6.0% |
Rising chronic disease burden and improving healthcare infrastructure are gradually supporting aptamer adoption. |
|
Middle East and Africa |
4.5% |
Growing healthcare investment and diagnostic infrastructure development are creating emerging demand for aptamer-based tools. |
North America's 40.7% leadership reflects the United States' strong biotechnology base, where cardiovascular disease causes close to 2,500 deaths daily. Asia-Pacific's 27.8% reflects rising HIV and infectious disease diagnostics demand, with Mizoram recording India's highest HIV prevalence at 2.73% in 2025.
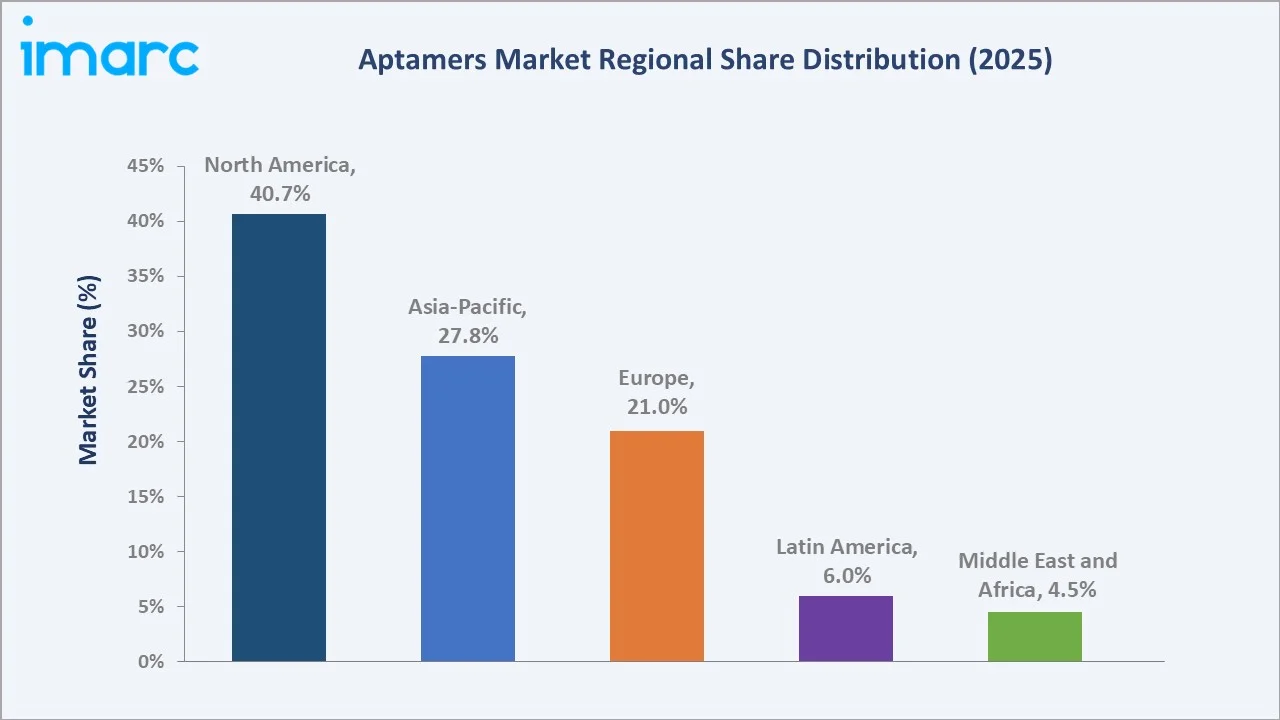
Europe's 21.0% reflects its aging population, with those aged 60 and above in the WHO European region expected to reach 247 million by 2030. Latin America at 6.0% and Middle East and Africa at 4.5% grow through rising cancer burden and healthcare infrastructure investment.
Competitive Landscape
Aptamers market analysis shows a moderately fragmented landscape combining platform developers, therapeutic biotechs, and oligonucleotide suppliers. Competition centers on proprietary selection and modification chemistries, licensing partnerships, and portfolio expansion across diagnostics, therapeutics, and research applications worldwide.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
SomaLogic Operating Co., Inc. |
SOMAmer, SomaScan Assay, SomaSignal Tests |
Market Leader |
Pioneer of modified aptamer-based proteomics, now part of Illumina's multiomics portfolio with broad global customer reach. |
|
Aptamer Group |
Optimer binders, Optimer-Fc |
Innovator |
Develops synthetic Optimer binders for research, diagnostics, bioprocessing, and targeted therapeutics through licensing and royalty-based models. |
|
Kaneka Eurogentec S.A. |
Custom and GMP oligonucleotides |
Strong Challenger |
Provides research-grade and GMP oligonucleotide synthesis supporting aptamer development, scale-up, and clinical supply. |
|
Aptagen, LLC |
Apta-Index, custom SELEX services |
Niche Player |
Offers custom aptamer discovery services and an online aptamer database widely used by academic and industrial researchers. |
Key players include SomaLogic Operating Co., Inc., Aptamer Group, Kaneka Eurogentec S.A., Aptagen, LLC, and others.
Key Company Profiles
SomaLogic Operating Co., Inc.
SomaLogic Operating Co., Inc. is a leader in data-driven proteomics, using modified aptamers to measure thousands of proteins from small biological samples. It operates as part of Illumina following its acquisition from Standard BioTools in January 2026.
- Key Brands: SomaScan Assay, SomaSignal Tests, SomaScan Proteomics Services, among others.
- Recent Developments: In January 2026, Illumina completed its acquisition of SomaLogic for USD 350 Million in cash, plus up to USD 75 Million in milestones and royalties, combining SomaScan with Illumina's NGS ecosystem and DRAGEN software. The acquisition strengthens customer access to proteomic insights at scale, supporting faster drug discovery and multiomics research.
- Strategic Focus: Scaling aptamer-based proteomics for drug discovery and multiomics research through integration with high-throughput sequencing workflows. The company is expanding customer access to its technologies and service offerings through Illumina's global commercial reach. It also leverages DRAGEN software and Illumina Connected Multiomics to deliver richer datasets for pharmaceutical and academic customers.
Aptamer Group
Aptamer Group, headquartered in York, United Kingdom, develops next-generation synthetic Optimer binders for research, diagnostics, bioprocessing, and therapeutic applications, serving pharmaceutical, diagnostic, and life science customers through fee-for-service and licensing arrangements.
- Key Brands: Optimer binders, Optimer-Fc, Optimer delivery vehicles.
- Recent Developments: In March 2026, Aptamer Group plc launched a targeted radiopharmaceutical programme with Radiopharmium Ltd, identifying three strategic therapeutic targets for Optimer radioconjugates.
- Strategic Focus: Increasing higher-margin licensing income, including enzyme-modulating Optimer licenses with Twist Bioscience and Alphazyme. The company is also building a proprietary radiotherapy pipeline alongside a partnered program with a top-3 global pharmaceutical company. It aims to deliver in vivo data by the end of 2026, strengthening its therapeutic partnering position.
Market Concentration Analysis
The global aptamers market shows moderate concentration in proteomics, where SomaLogic holds a dominant platform position, and high fragmentation in custom discovery services. Numerous small developers and academic spin-offs compete on selection chemistry, target coverage, turnaround time, and pricing.
Concentration is evolving through two opposing forces: consolidation by large life science companies acquiring aptamer platforms, and continuous entry of specialized startups leveraging AI-driven design and novel modification chemistries to address unmet needs across diagnostics and therapeutics.
Investment & Growth Opportunities
Highest Growth Segments
Therapeutics (~17.9% CAGR through approved ophthalmic aptamers and oncology pipelines), peptide aptamers (~17.5% CAGR through intracellular targeting), and diagnostics (~16.8% CAGR through point-of-care testing) represent the highest-growth investment vectors in the global aptamers market through 2034.
Emerging Investment Opportunities
Aptamer-drug conjugates and radioconjugates represent the most promising emerging opportunity. Aptamers' small size, rapid clearance, and precise targeting suit radioligand delivery, positioning developers for high-value pharmaceutical partnerships offering upfront payments, milestones, and long-term royalty income.
Investment Themes
- Platform licensing models creating recurring revenue: Developers shifting from fee-for-service discovery to royalty-bearing licenses with pharmaceutical and reagent companies offer scalable, higher-margin business models with improved long-term revenue visibility. Recent licensing deals with reagent and enzyme companies demonstrate the commercial viability of this approach.
- AI-enabled aptamer discovery and GMP oligonucleotide capacity: Investment in computational design tools and modified oligonucleotide manufacturing addresses key bottlenecks in selection speed and therapeutic-scale supply, creating defensible positions across the aptamers value chain. Investors backing such capabilities can benefit from rising outsourcing demand among developers.
Future Market Outlook (2026-2034)
The global aptamers market is projected to grow from USD 3.56 Billion in 2025 to USD 4.14 Billion in 2026, reaching USD 14.37 Billion by 2034, registering a CAGR of 16.26% during 2026-2034. The market's anchor value of USD 7.56 Billion in 2030 represents a structural inflection.
Three structural forces define aptamers market trends through 2034: expanding therapeutic approvals validating clinical utility; integration of aptamer proteomics into multiomics research; and AI-enabled design shortening discovery timelines while broadening diagnostic and point-of-care applications across developed and emerging healthcare markets.
Research Methodology
Primary Research
Primary research comprised structured interviews with aptamer developers, oligonucleotide manufacturers, pharmaceutical licensing executives, diagnostic kit makers, CRO managers, academic researchers, and procurement heads across North America, Asia-Pacific, Europe, Latin America, and Middle East and Africa.
Secondary Research
Secondary research encompassed company annual reports, investor presentations, regulatory approvals, clinical trial registries, patent databases, peer-reviewed journals, government health statistics, and industry association publications, supporting a comprehensive aptamers market analysis. Over 50 secondary sources were reviewed.
Forecasting Models
Market revenue forecasts were developed using bottom-up and top-down approaches: application-level demand across diagnostics, therapeutics, and research multiplied by average product and service values, validated against company revenues, regional healthcare expenditure, and expert interview inputs.
Aptamers Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Nucleic Acid, Peptide |
| Applications Covered | Diagnostics, Therapeutics, Research and Developments, Others |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Countries Covered | United States, Canada, Germany, France, United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico |
| Companies Covered | SomaLogic Operating Co., Inc., Aptamer Group, Kaneka Eurogentec S.A., Aptagen, LLC, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the aptamers market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the global aptamers market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the aptamers industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Aptamers Market Report
Global aptamers market size is estimated at USD 4.14 Billion in 2026, driven by biotechnology advancements, rising personalized medicine demand, and cost advantages over antibodies. Growing adoption across diagnostics, therapeutics, and research applications further supports market expansion worldwide.
Global aptamers market grows at 16.26% CAGR during 2026-2034, reaching USD 14.37 Billion by 2034. Overall growth is sustained by therapeutic approvals, aptamer-based proteomics adoption, AI-enabled discovery, and expanding point-of-care diagnostic applications across developed and emerging markets.
Nucleic acid leads at 77.2% through superior stability, specificity, and ease of synthesis, enabling broad use across diagnostic assays, therapeutic development, and research tools, supported by continuous advances in nucleic acid chemistry and scalable production.
Diagnostics leads at 36.8% through high-affinity biomarker detection, easy modification, and faster development timelines for laboratory and point-of-care tests in oncology, infectious diseases, cardiovascular care, and personalized medicine.
North America leads at 40.7% through advanced biotechnology infrastructure, supportive regulation, and substantial public and private R&D investment, with the United States accounting for over 87.50% of the regional market, supported by early commercialization.
Leading companies include SomaLogic Operating Co., Inc., Aptamer Group, Kaneka Eurogentec S.A., Aptagen, LLC, and others.
Global aptamers market is projected to reach approximately USD 7.56 Billion by 2030, supported by growing therapeutic pipelines, aptamer-based proteomics integration into multiomics research, wider diagnostic adoption, and increasing licensing partnerships between aptamer developers and pharmaceutical companies.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade