
Asia Pacific Copper Pipes and Tubes Market Size, Share, Trends and Forecast by Finish Type, Outer Diameter, End User, and Country, 2026-2034
Asia Pacific Copper Pipes and Tubes Market Size, Share, Trends & Forecast (2026-2034)
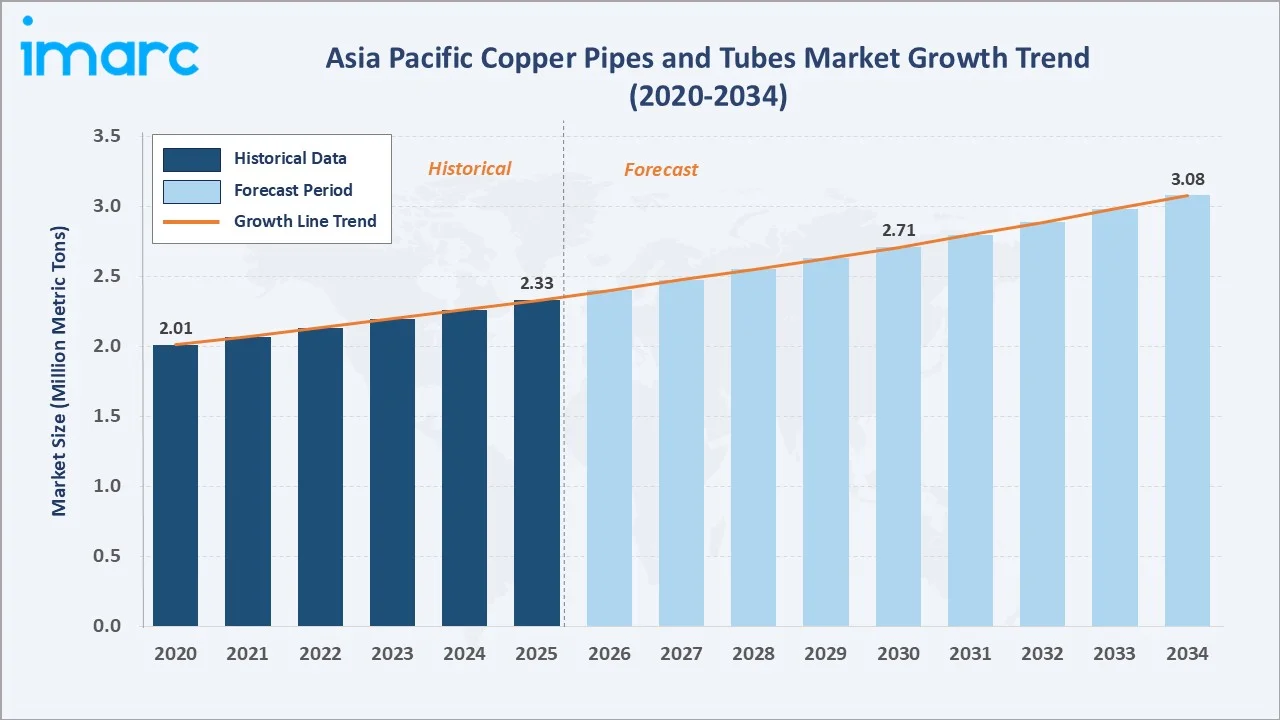
The Asia Pacific copper pipes and tubes market reached a volume of 2.33 Million Metric Tons in 2025 and is projected to reach 3.08 Million Metric Tons by 2034, exhibiting a CAGR of 3.03% during 2026-2034. Rising HVAC and refrigeration installations, expanding industrial heat exchanger applications, and copper's superior thermal conductivity are the primary drivers shaping market growth.
LWC grooved leads the finish type category at 34.7%, HVAC dominates the end user segment at 42.6%, and China holds 38.9% country share.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
2.33 Million Metric Tons |
|
Forecast Market Size (2034) |
3.08 Million Metric Tons |
|
CAGR (2026-2034) |
3.03% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Country |
China (38.9%, 2025) |
|
Second Largest Country |
Japan (16.7%, 2025) |
|
Leading Finish Type |
LWC Grooved (34.7%, 2025) |
|
Leading End User |
HVAC (42.6%, 2025) |
The Asia Pacific copper pipes and tubes market expanded from 2.01 Million Metric Tons in 2020 to 2.33 Million Metric Tons in 2025, supported by steady recovery in construction activity and rising penetration of energy-efficient cooling systems across the region. Anchored at 2.71 Million Metric Tons in 2030, the forecast to 3.08 Million Metric Tons by 2034 is underpinned by accelerating industrial heat exchanger demand, expanding electrical infrastructure investment, and continued urbanization.
To get more information on this market, Request Sample
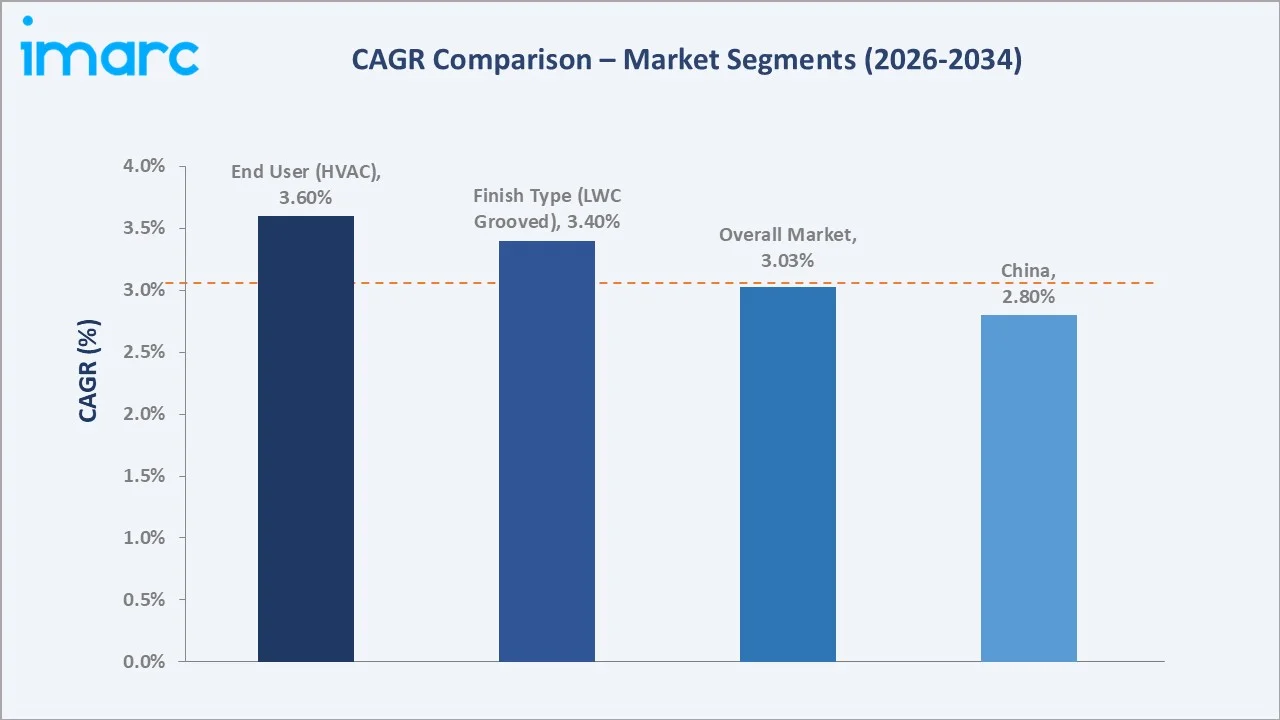
CAGR trajectories across finish type and end user sub-segments show HVAC and LWC grooved expanding faster than the overall 3.03% market CAGR. India and Indonesia emerge as the fastest-growing markets on the back of rising construction and cooling-equipment penetration.
Executive Summary
The Asia Pacific copper pipes and tubes market is on a steady growth trajectory, rising from 2.01 Million Metric Tons in 2020 to 3.08 Million Metric Tons by 2034. The industry has evolved from domestic, construction-linked demand toward a diversified base spanning HVAC, industrial heat exchange, plumbing, and electrical applications. Improving manufacturing scale among regional producers continues to reshape supply patterns across the region.
LWC grooved leads the finish type segment at 34.7% in 2025, favored for its heat-transfer efficiency in air-conditioning coils, while HVAC accounts for 42.6% of end user demand, driven by widespread use of copper tubes in residential, commercial, and industrial cooling systems. China holds 38.9% market share, supported by its large-scale extrusion and drawing capacity and deep integration with domestic air-conditioning manufacturing.
Key Market Insights
|
Insight |
Data |
|
Leading Finish Type |
LWC Grooved - 34.7% share (2025) |
|
Second Largest Finish Type |
Straight Length - 27.6% share (2025) |
|
Leading End User |
HVAC - 42.6% share (2025) |
|
Second Largest End User |
Industrial Heat Exchanger - 22.8% share (2025) |
|
Leading Country |
China - 38.9% share (2025) |
|
Second Largest Country |
Japan - 16.7% share (2025) |
|
Top Companies |
Golden Dragon Precise Copper Tube Group Inc., Hailiang Group, Wieland Group, Mueller Industries, Inc., KME Group S.p.A. |
Key analytical Observations Expanding On the Data Above:
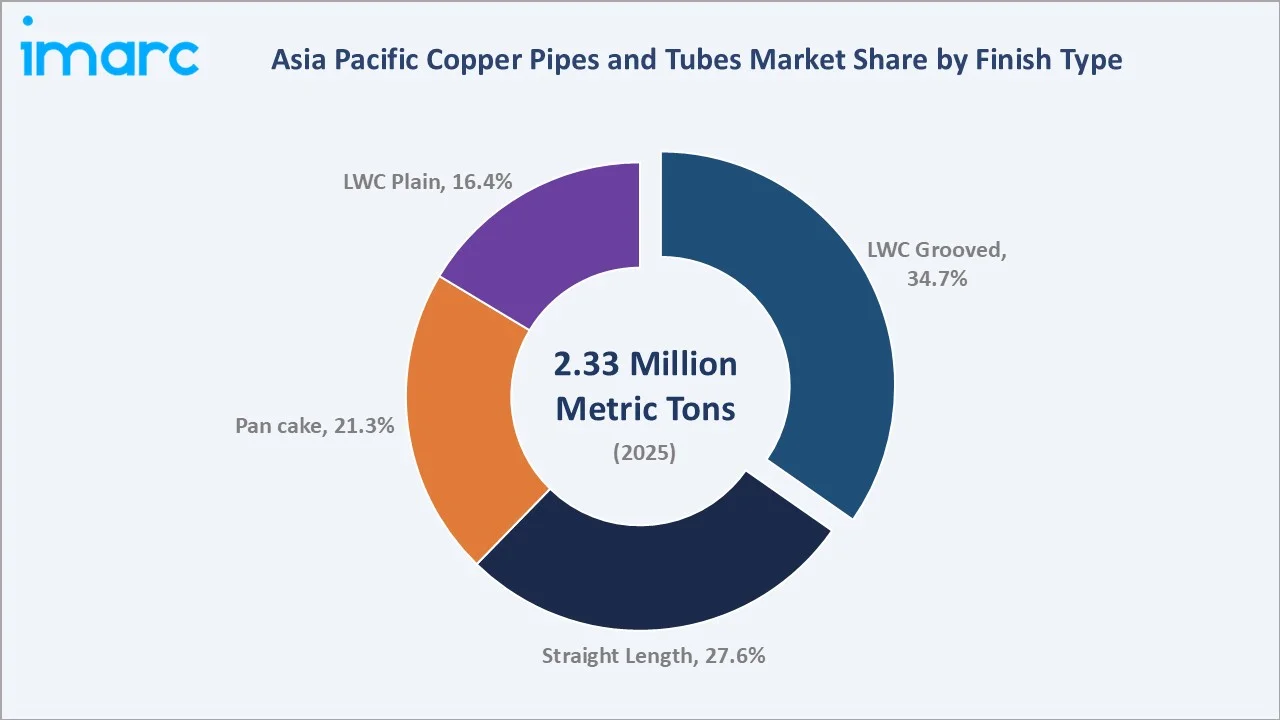
- LWC grooved dominance at 34.7% reflects the finish type's superior heat-exchange efficiency in split and packaged air-conditioning coils, making it the preferred choice among regional HVAC OEMs.
- Straight length at 27.6% remains essential for plumbing and long-run industrial piping, where dimensional stability and ease of installation are priorities.
- HVAC dominance at 42.6% is reinforced by rising residential cooling penetration and stricter minimum energy performance standards across major Asia Pacific economies.
- Industrial heat exchanger demand at 22.8% is expanding alongside growth in process industries, data center cooling, and power generation infrastructure.
- China share at 38.9% is anchored by its dominant position in global copper tube extrusion capacity and dense downstream HVAC and refrigeration manufacturing base.
Asia Pacific Copper Pipes and Tubes Market Overview
Copper pipes and tubes refer to seamless and welded tubular copper products used to transport fluids and refrigerants and to transfer heat across HVAC, plumbing, industrial, and electrical applications. Their corrosion resistance, thermal conductivity, and durability make them a preferred material across a wide range of infrastructure and cooling systems.
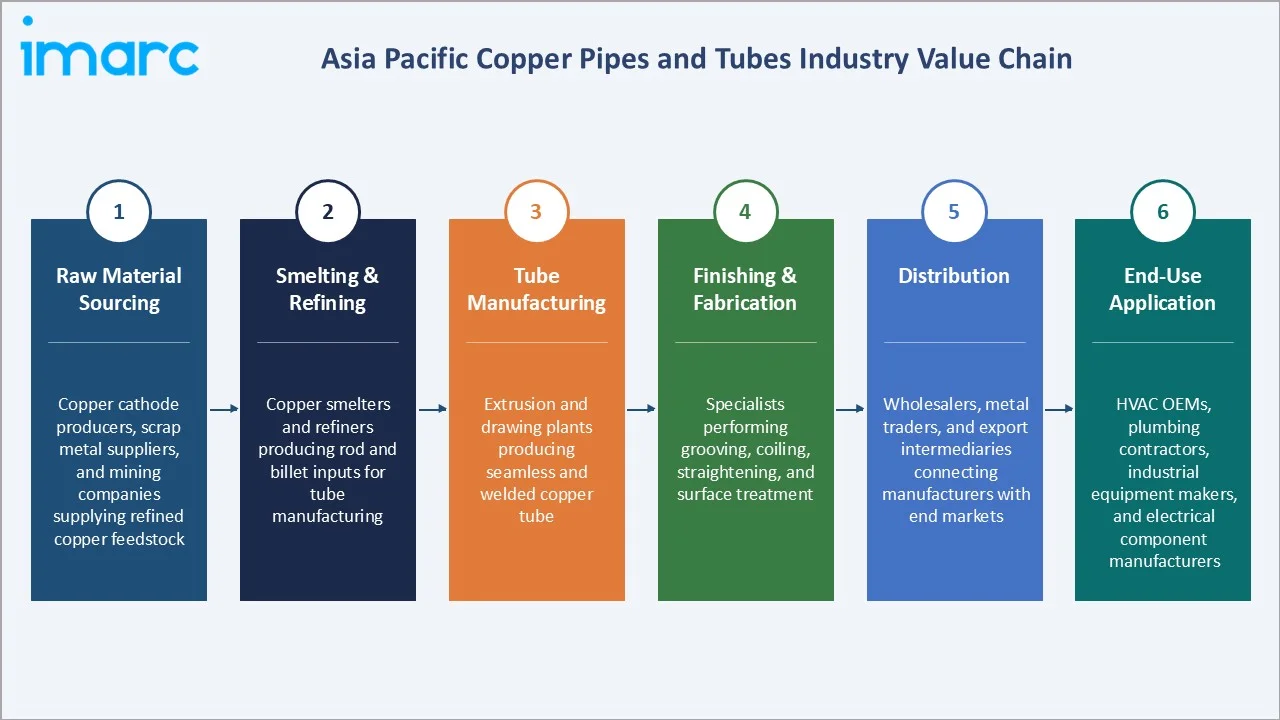
The Asia Pacific ecosystem integrates copper cathode and scrap suppliers, tube extrusion and drawing manufacturers, finishing specialists, distributors, and end-use industries such as air-conditioning OEMs, industrial equipment makers, and construction contractors. Trade flows, copper price movements, and evolving efficiency regulations continue to shape ecosystem dynamics.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
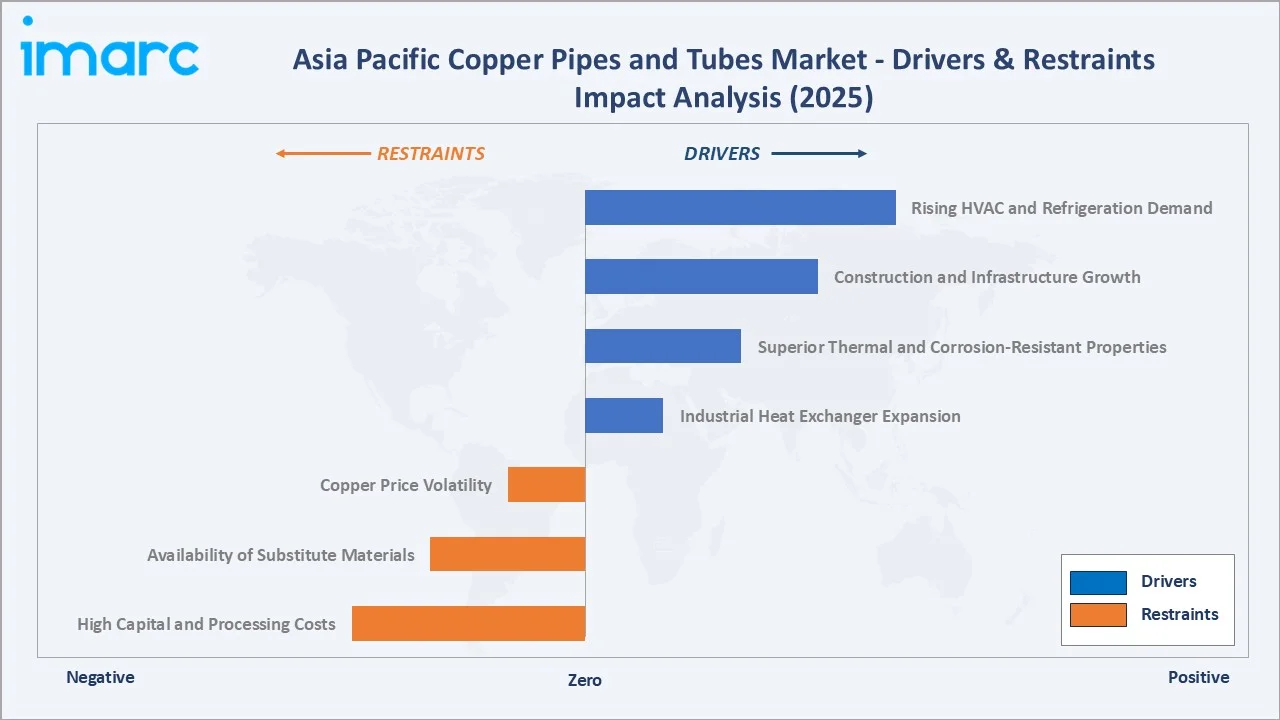
- Rising HVAC and Refrigeration Demand: Expanding residential and commercial air-conditioning installation across Asia Pacific is the single largest driver of copper tube consumption, given copper's superior thermal conductivity and reliability in refrigerant circuits.
- Construction and Infrastructure Growth: Sustained investment in residential, commercial, and industrial construction across China, India, and Southeast Asia continues to lift demand for copper plumbing and building-services tubing. As per IMARC Group, the India construction market size was valued at USD 685.0 Billion in 2025.
- Superior Thermal and Corrosion-Resistant Properties: Copper's combination of high thermal conductivity, corrosion resistance, and long service life keeps it the preferred material over aluminum and plastic substitutes in critical heat-exchange applications.
- Industrial Heat Exchanger Expansion: Growing deployment of heat exchangers across power generation, chemical processing, automotive, and industrial manufacturing is supporting demand for copper pipes and tubes, particularly in applications requiring efficient heat transfer and durability.
Market Restraints
- Copper Price Volatility: Fluctuations in benchmark copper prices directly affect tube manufacturing costs and downstream pricing, creating margin pressure for fabricators and uncertainty for long-cycle projects.
- Availability of Substitute Materials: Aluminum, PEX, and PVC piping offer lower-cost alternatives in select plumbing and refrigeration applications, constraining copper's addressable share in price-sensitive segments.
- High Capital and Processing Costs: Copper tube extrusion and drawing require significant capital investment in specialized machinery, creating a barrier for smaller fabricators seeking to scale production.
Market Opportunities
- Smart HVAC and IoT-Enabled Systems: Growing integration of connected sensors and smart controls into HVAC systems is creating opportunities for tube manufacturers to supply precision-engineered components.
- Renewable Energy and Electrification: Expanding solar thermal, heat pump, and EV charging infrastructure is opening new application areas for copper tube and busbar products beyond traditional HVAC and plumbing.
Market Challenges
- Environmental and Recycling Compliance: Tightening regulations around emissions and scrap sourcing are raising compliance costs for manufacturers, particularly smaller producers with limited recycling infrastructure.
- Skilled Labor and Technical Capacity: Precision tube manufacturing requires specialized expertise, and talent shortages in some emerging markets can constrain capacity expansion plans.
Emerging Market Trends
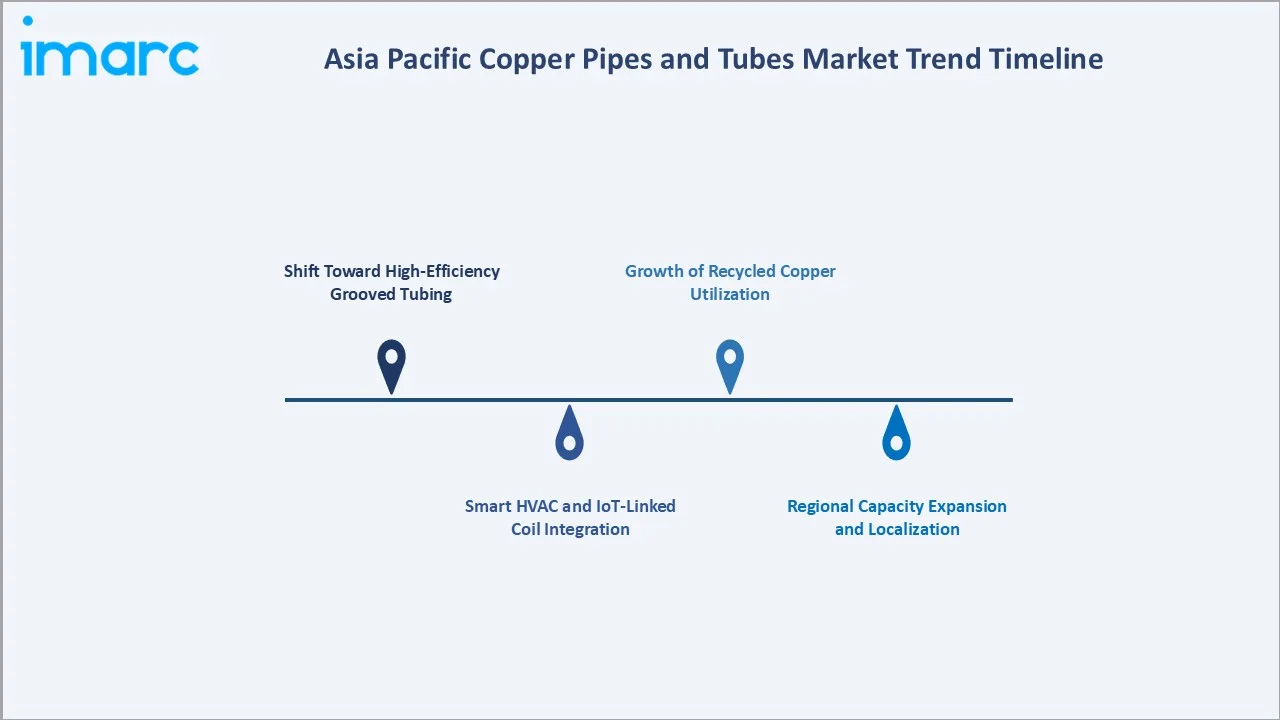
1. Shift Toward High-Efficiency Grooved Tubing
Regional HVAC OEMs are increasingly specifying inner-grooved copper tubes to meet tightening minimum energy performance standards. The transition is accelerating investment in advanced grooving and finishing technology among leading regional manufacturers.
2. Smart HVAC and IoT-Linked Coil Integration
Manufacturers are engineering copper coils and tube assemblies compatible with sensor-enabled, connected HVAC systems, enabling real-time performance monitoring and predictive maintenance across commercial installations.
3. Growth of Recycled Copper Utilization
Growing emphasis on circular manufacturing is increasing the use of recycled copper scrap in tube production. Its high recyclability supports sustainability-focused sourcing strategies and helps regional manufacturers reduce dependence on primary copper.
4. Regional Capacity Expansion and Localization
Leading manufacturers are expanding extrusion and drawing capacity within China, India, and Southeast Asia to reduce logistics costs and serve growing domestic HVAC and construction demand closer to end markets.
Industry Value Chain Analysis
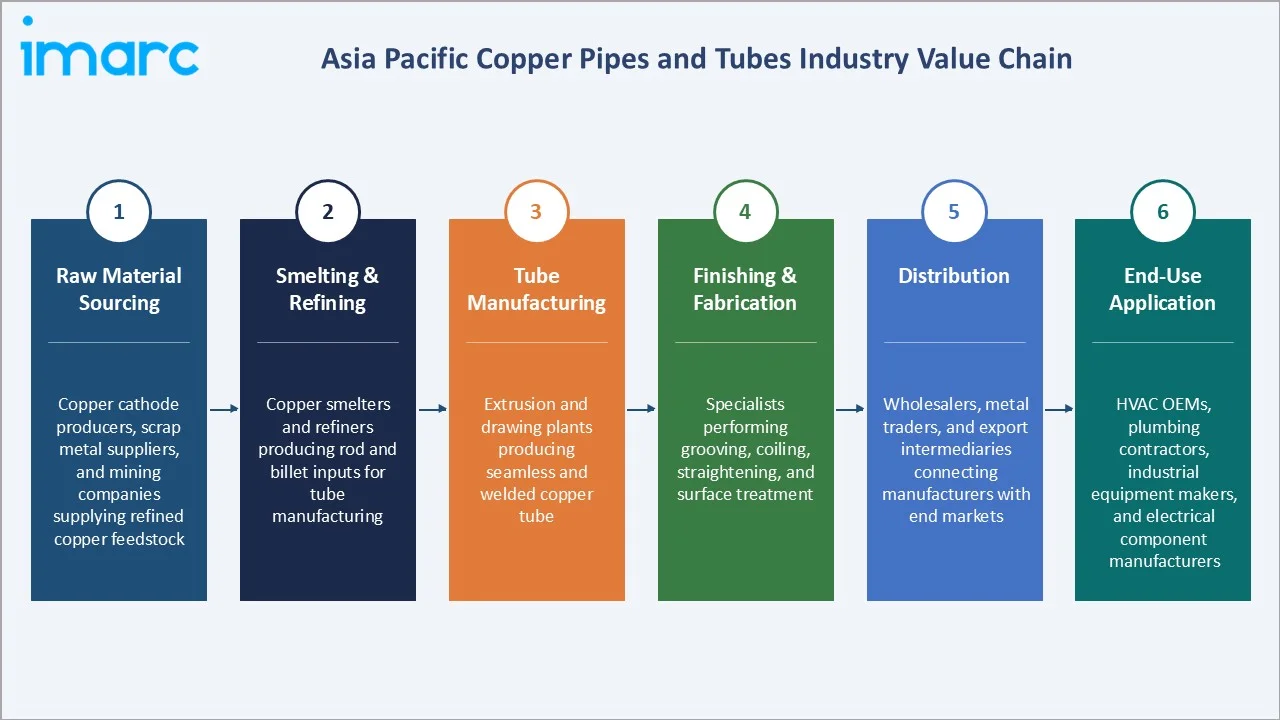
The Asia Pacific copper pipes and tubes value chain spans six stages, from raw material sourcing through end-use application. Manufacturing, finishing, and distribution capture significant value-add, while raw material sourcing and recycling infrastructure increasingly determine competitive position amid copper price volatility.
|
Stage |
Key Players / Examples |
|
Raw Material Sourcing |
Copper cathode producers, scrap metal suppliers, and mining companies supplying refined copper feedstock |
|
Smelting & Refining |
Copper smelters and refiners producing rod and billet inputs for tube manufacturing |
|
Tube Manufacturing |
Extrusion and drawing plants producing seamless and welded copper tube |
|
Finishing & Fabrication |
Specialists performing grooving, coiling, straightening, and surface treatment |
|
Distribution |
Wholesalers, metal traders, and export intermediaries connecting manufacturers with end markets |
|
End-Use Application |
HVAC OEMs, plumbing contractors, industrial equipment makers, and electrical component manufacturers |
Vertically integrated manufacturers, particularly those with in-house smelting and finishing capabilities, are positioned to capture greater value than fabricators reliant on externally sourced rod and billet.
Technology Landscape in the Asia Pacific Copper Pipes and Tubes Industry
Advanced Extrusion and Drawing Technology
Manufacturers are adopting high-speed continuous casting and rolling lines that improve dimensional consistency and reduce energy consumption per ton of finished tube, supporting cost efficiency and quality at scale.
Materials Innovation and Alloy Development
Ongoing development of copper alloy formulations is improving corrosion resistance and mechanical strength, extending service life in demanding industrial heat exchanger and specialty applications.
Smart Connectivity in HVAC Systems
Integration of copper tube assemblies with sensor-enabled, connected HVAC equipment is enabling real-time performance monitoring and predictive maintenance for commercial building operators.
Automation in Manufacturing
Increasing deployment of automated finishing, inspection, and packaging systems is helping regional manufacturers improve throughput and maintain consistent quality across high-volume tube production.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Finish Type |
LWC Grooved |
34.7% |
2025 |
|
Outer Diameter |
3/8, 1/2, 5/8 Inch |
🔒 |
2025 |
|
End User |
HVAC |
42.6% |
2025 |
|
Country |
China |
38.9% |
2025 |

By Finish Type
LWC grooved commands a 34.7% share in 2025, driven by its superior heat-transfer performance in air-conditioning and refrigeration coils, deep integration with HVAC OEM production lines, and expanding demand from energy-efficiency-focused installations. The segment benefits from established manufacturing scale among leading regional producers and continued specification by major appliance makers.
To access detailed market analysis, Request Sample
Straight length, at 27.6% share, remains the standard choice for plumbing, industrial piping, and long-run installations, prized for its dimensional stability and ease of on-site handling.
By End User
HVAC leads the end user segment with a 42.6% share in 2025, supported by rising residential and commercial cooling penetration, stricter energy-efficiency codes, and copper's continued preference over aluminum in refrigerant-carrying components. The segment's growth outlook remains closely tied to construction cycles and air-conditioner replacement demand across the region.
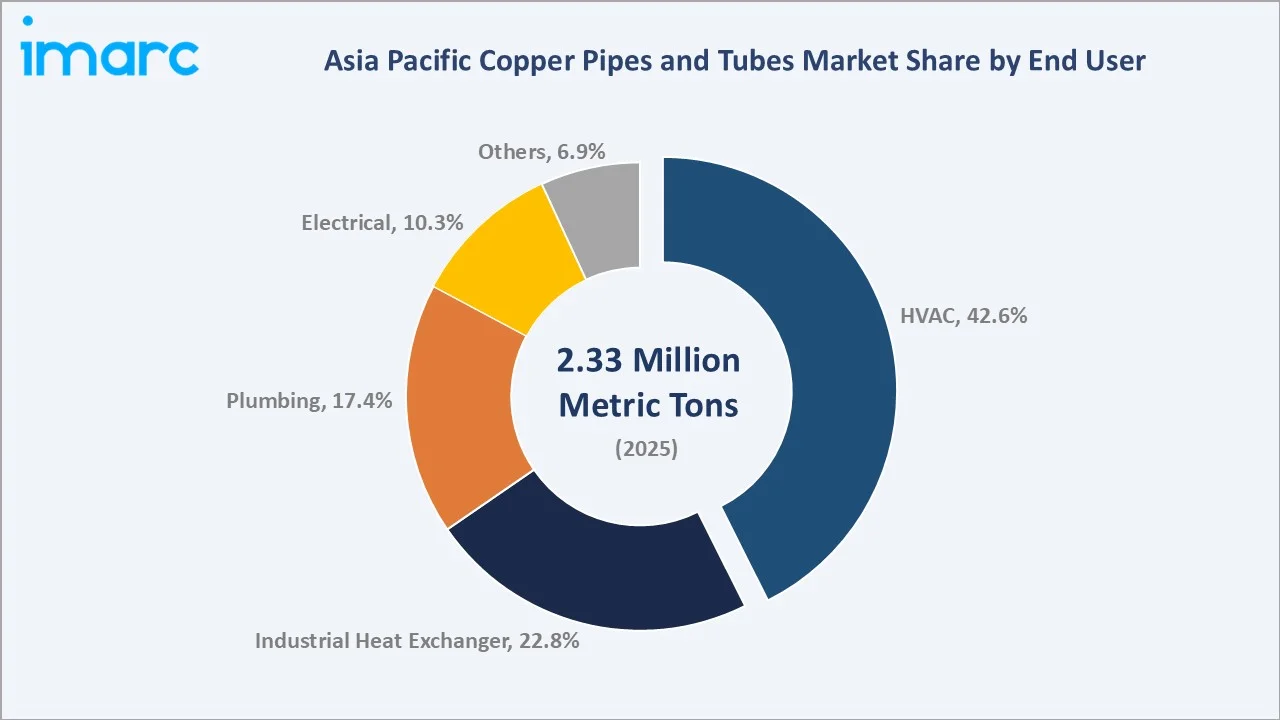
Industrial heat exchanger accounts for 22.8% of demand, driven by process industry and power generation cooling requirements.
Regional Market Insights
|
Country |
Share (2025) |
Key Growth Drivers |
|
China |
38.9% |
Large-scale manufacturing base, strong domestic HVAC production, and extensive export infrastructure |
|
Japan |
16.7% |
Mature construction sector, high-specification industrial applications, and established replacement demand |
|
India |
14.8% |
Rapid urbanization, expanding construction activity, and rising air-conditioner penetration |
|
South Korea |
9.8% |
Advanced manufacturing capability and strong electronics and industrial end-use base |
|
Australia |
8.2% |
Steady construction and renovation activity, and growing adoption of energy-efficient cooling systems |
|
Indonesia |
6.4% |
Expanding middle-class housing demand and growing industrial investment |
|
Others |
5.2% |
Gradual infrastructure development and rising regional trade integration |
China at 38.9% in 2025 leads the market, supported by its dominant copper tube extrusion capacity, dense HVAC manufacturing base, and integration with both domestic and export-oriented supply chains. Sustained investment in production efficiency and continued urban construction activity support the country's leadership across the forecast period.
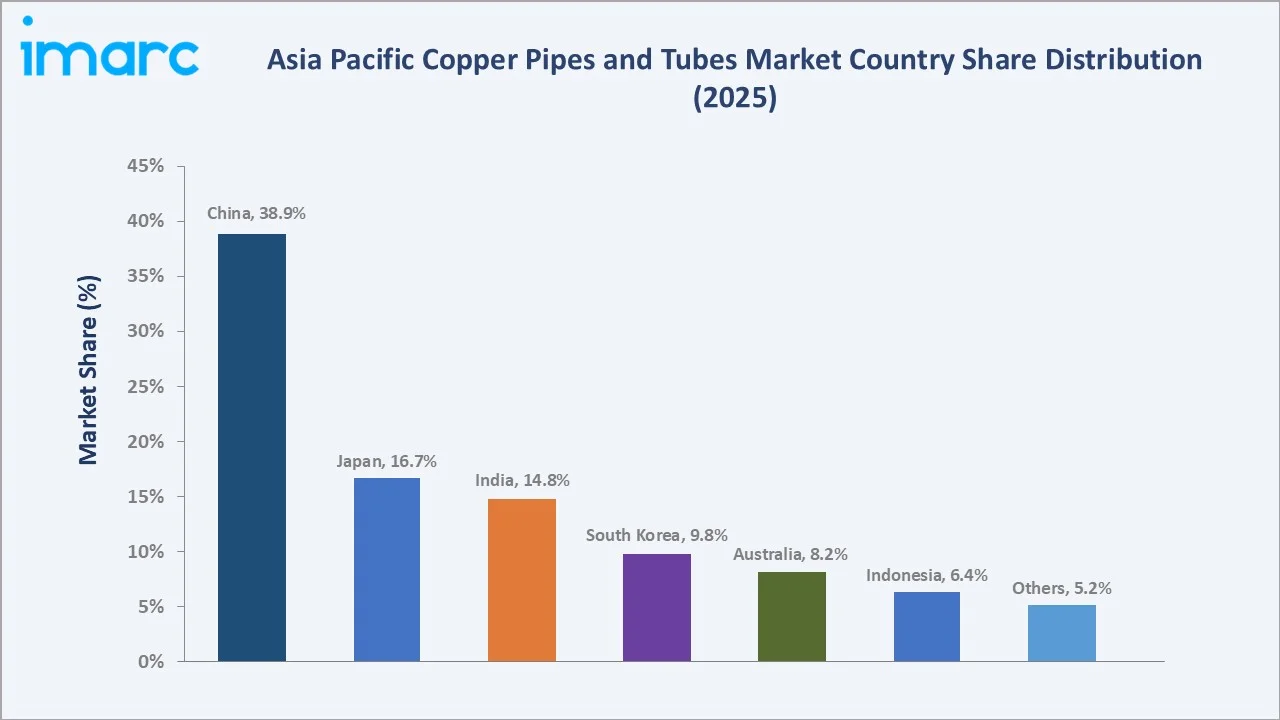
India at 14.8% is the fastest-growing market, fueled by expanding construction activity, rising air-conditioner ownership, and increasing local manufacturing investment.
Competitive Landscape
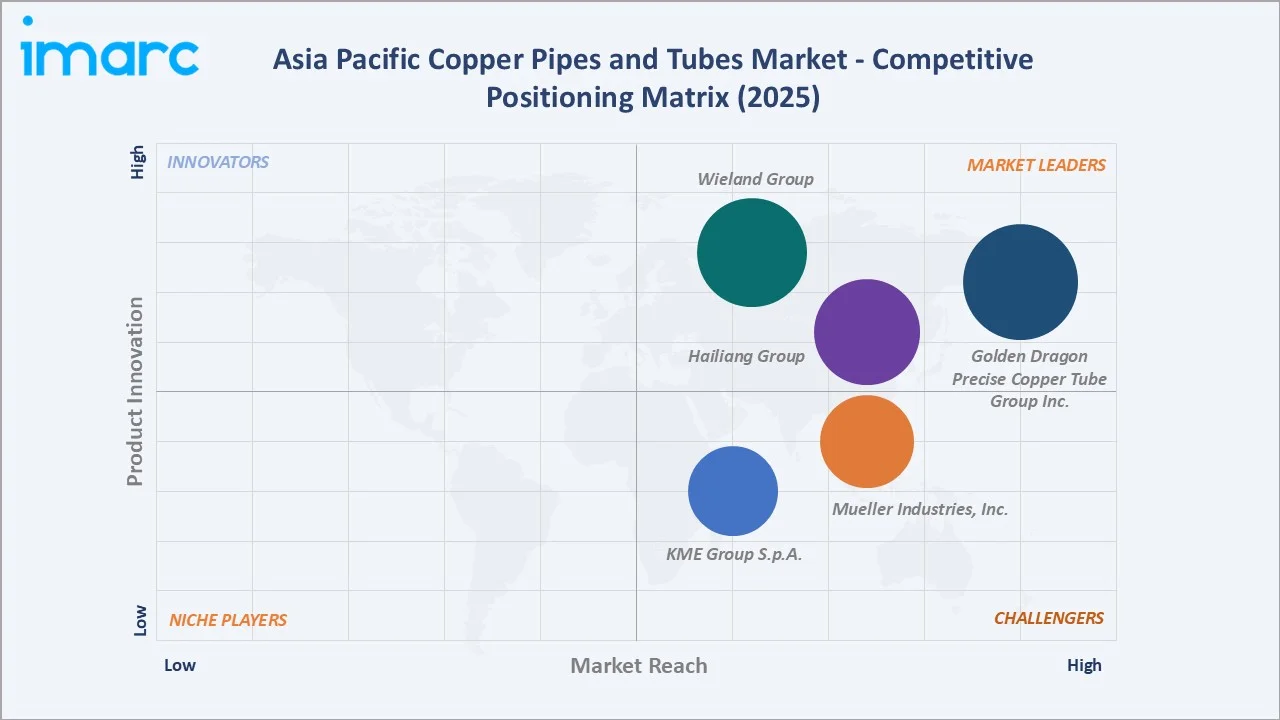
The Asia Pacific copper pipes and tubes market is moderately fragmented, with large-scale Chinese producers leading volume output while global manufacturers compete on technical specification, alloy innovation, and regional distribution reach. Manufacturing scale, vertical integration, and energy-efficiency-focused product development form the key competitive differentiators across the industry.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
|
Golden Dragon Precise Copper Tube Group Inc. |
GD Copper |
Leader |
Large-scale precision copper tube manufacturing with expanding international production footprint |
|
Hailiang Group |
Hailiang |
Leader |
High-volume copper and copper alloy tube production with diversified regional manufacturing bases |
|
Wieland Group |
Wieland Copper Products |
Leader |
Advanced copper and copper alloy solutions with strong technical and engineering focus |
|
Mueller Industries, Inc. |
Mueller Streamline |
Challenger |
Diversified copper tube and fittings manufacturing with established global distribution |
|
KME Group S.p.A. |
KME |
Challenger |
Specialized copper semi-finished products with focus on industrial applications |
Key players include Golden Dragon Precise Copper Tube Group Inc., Hailiang Group, Wieland Group, Mueller Industries, Inc., and KME Group S.p.A., among others.
Key Company Profiles
Golden Dragon Precise Copper Tube Group Inc.
Golden Dragon Precise Copper Tube Group Inc. is a China-based manufacturer of precision copper tube products, with production bases across China. The firm manufactures copper tubes for applications across the air-conditioning, refrigeration, plumbing, and industrial sectors.
- Product Portfolio: Smooth and inner-grooved copper tubes, capillary tubes, and copper tube fittings serving air-conditioning, refrigeration, and industrial applications.
- Recent Developments: The company has continued to invest in expanding its manufacturing capacity and strengthening its international production and distribution network.
- Strategic Focus: Strengthening global manufacturing scale and expanding international distribution reach.
Hailiang Group
Hailiang Group is a China-headquartered manufacturer of copper and copper alloy products, with a diversified manufacturing base serving HVAC, plumbing, and industrial markets.
- Product Portfolio: Copper and copper alloy tubes, fittings, bars, and coated pipes serving HVAC, water reticulation, and industrial applications.
- Recent Developments: The company has continued to expand its manufacturing footprint and raw material sourcing capabilities to support long-term supply security.
- Strategic Focus: Expanding integrated manufacturing capabilities and strengthening its international production footprint.
Wieland Group
Wieland Group is a Germany-headquartered manufacturer of copper and copper alloy semi-finished products, with an established presence across the global copper processing industry.
- Product Portfolio: Copper and copper alloy tubes, rods, strips, and engineered components serving HVAC, industrial, and specialty applications.
- Recent Developments: The company has continued to invest in its manufacturing and technical service capabilities to support customers across its core end markets.
- Strategic Focus: Deepening product innovation and strengthening regional technical support capabilities.
Market Concentration Analysis
The Asia Pacific copper pipes and tubes market is moderately concentrated, with large-scale manufacturers accounting for a significant share of regional production capacity, supported by extensive extrusion and drawing infrastructure and deep integration with domestic HVAC manufacturing.
Barriers to entry include high capital requirements for tube manufacturing equipment, the need for consistent access to refined copper feedstock, and the technical expertise required to meet HVAC OEM specification standards, favoring established, well-capitalized manufacturers.
Consolidation is gradually advancing as leading producers expand overseas manufacturing footprints and smaller fabricators seek partnerships or acquisition to access scale and technical capability, reinforcing the position of leading players across the region.
Investment & Growth Opportunities
Fastest-Growing Segments
HVAC remains the fastest-growing end user segment, supported by rising cooling penetration and tightening energy-efficiency standards. LWC grooved is similarly outpacing overall market growth as HVAC OEMs increasingly specify higher-efficiency coil designs.
Emerging Markets
India is the fastest-growing market, anchored by rapid urbanization, expanding construction activity, and rising air-conditioner penetration. Indonesia is also emerging as a significant growth market, supported by expanding housing demand and industrial investment.
Venture & Investment Trends
Investment is concentrated in capacity expansion for grooved tube production, overseas manufacturing facilities that reduce logistics costs, and upstream copper sourcing and recycling infrastructure that supports supply chain resilience.
Future Market Outlook (2026-2034)
The Asia Pacific copper pipes and tubes market is forecast to expand from 2.33 Million Metric Tons in 2025 to 3.08 Million Metric Tons by 2034 at a CAGR of 3.03%, adding approximately 0.75 Million Metric Tons in incremental volume over the forecast period.
Three forces will shape the market through 2034: continued growth in HVAC and refrigeration installations; expanding industrial heat exchanger and electrification-linked demand; and ongoing capacity expansion among leading regional producers.
By 2034, the market is expected to be defined by higher-efficiency grooved tube adoption, deeper integration with smart HVAC systems, and growing utilization of recycled copper feedstock across the region's manufacturing base.
Research Methodology
Primary Research
Primary research included structured interviews with tube manufacturing executives, HVAC OEM procurement leads, copper distributors, and industry association representatives, validating market sizing and regional demand patterns.
Secondary Research
Secondary sources included industry association publications, national statistical agencies, company annual reports, trade and customs data, and regulatory filings related to energy-efficiency standards across Asia Pacific economies.
Forecasting Models
Market forecasts used top-down and bottom-up models combining historical volume trends, end-use growth rates, regional construction and HVAC installation data, and copper price scenario analysis.
Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million Metric Tons |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Finish Types Covered | LWC Grooved, Straight Length, Pan cake, LWC Plain |
| Outer Diameters Covered | 3/8, 1/2, 5/8 Inch, 3/4, 7/8, 1 Inch, Above 1 inch |
| End Users Covered | HVAC, Industrial Heat Exchanger, Plumbing, Electrical, Others |
| Countries Covered | China, Japan, India, South Korea, Australia, Indonesia, Others |
| Companies Covered | Golden Dragon Precise Copper Tube Group Inc., Hailiang Group, Wieland Group, Mueller Industries, Inc., KME Group S.p.A., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Frequently Asked Questions About the Asia Pacific Copper Pipes and Tubes Market Report
The market reached a volume of 2.33 Million Metric Tons in 2025, driven by rising HVAC installations, industrial heat exchanger demand, and continued preference for copper's thermal performance.
The market is projected to grow at a CAGR of 3.03% from 2026-2034, reaching 3.08 Million Metric Tons, supported by expanding HVAC and industrial applications.
LWC grooved leads at 34.7% in 2025, driven by its superior heat-transfer efficiency in air-conditioning and refrigeration coil applications across the region.
HVAC dominates the end user segment at 42.6% in 2025, fueled by rising cooling penetration, stricter energy-efficiency standards, and copper's continued preference over aluminum in refrigerant-carrying components.
China commands 38.9% share in 2025, supported by extensive extrusion and drawing capacity and deep integration with domestic HVAC manufacturing.
India, with 14.8% share in 2025, is the fastest-growing market, driven by urbanization and rising air-conditioner penetration.
Leading players include Golden Dragon Precise Copper Tube Group Inc., Hailiang Group, Wieland Group, Mueller Industries, Inc., and KME Group S.p.A., among others.
Advances in high-speed extrusion, alloy innovation, and smart HVAC integration are enabling higher-efficiency, precision-engineered copper tube products.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade