
Asia Pacific Tire Market Size, Share, Trends and Forecast by Radial/Bias Tires, End-Use, Vehicle Type, Size, Distribution Channel, and Country, 2026-2034
Asia Pacific Tire Market Size, Share, Trends & Forecast (2026-2034)
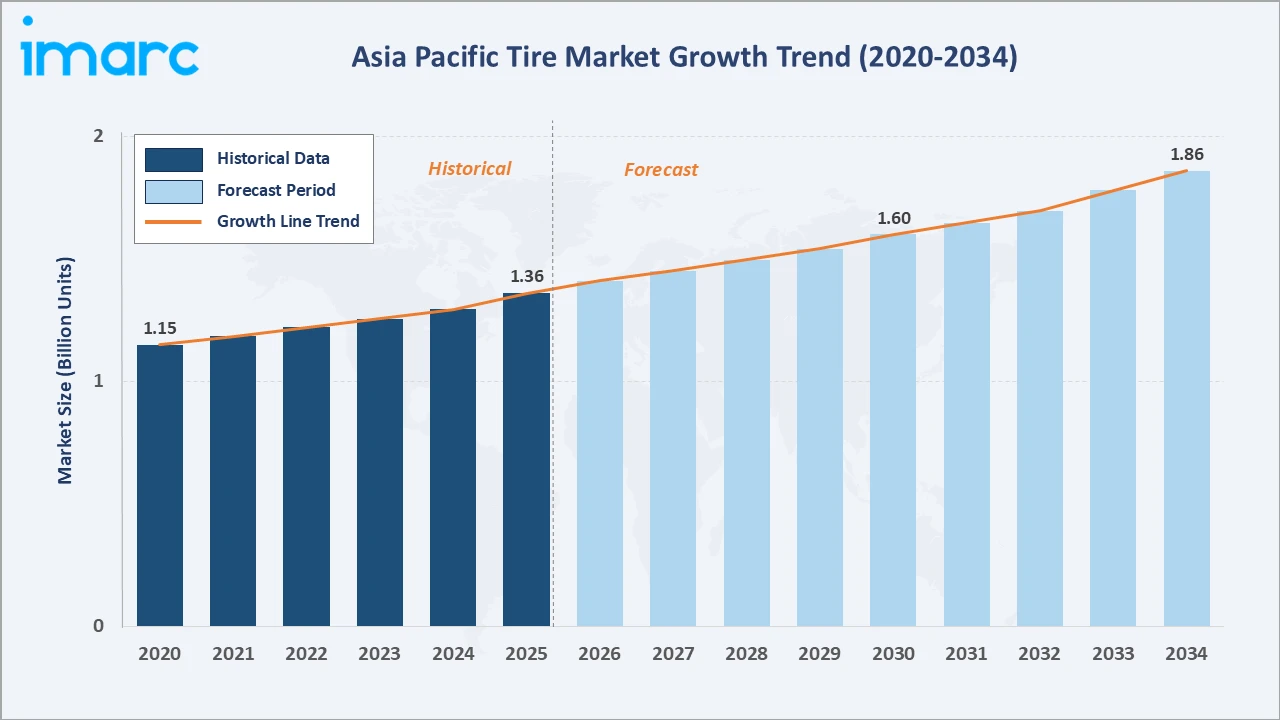
The Asia Pacific tire market stood at 1.36 Billion Units in 2025, growing to an estimated 1.41 Billion Units in 2026, and is projected to reach 1.86 Billion Units by 2034, registering a CAGR of 3.35% during 2026-2034. The market is driven by rapid vehicle population growth, expanding highway infrastructure, and surging demand for replacement tires across both developed and emerging APAC economies. Rising electric vehicle adoption is further creating a high-value speciality tire segment, while the shift to online tire retail is broadening consumer access.
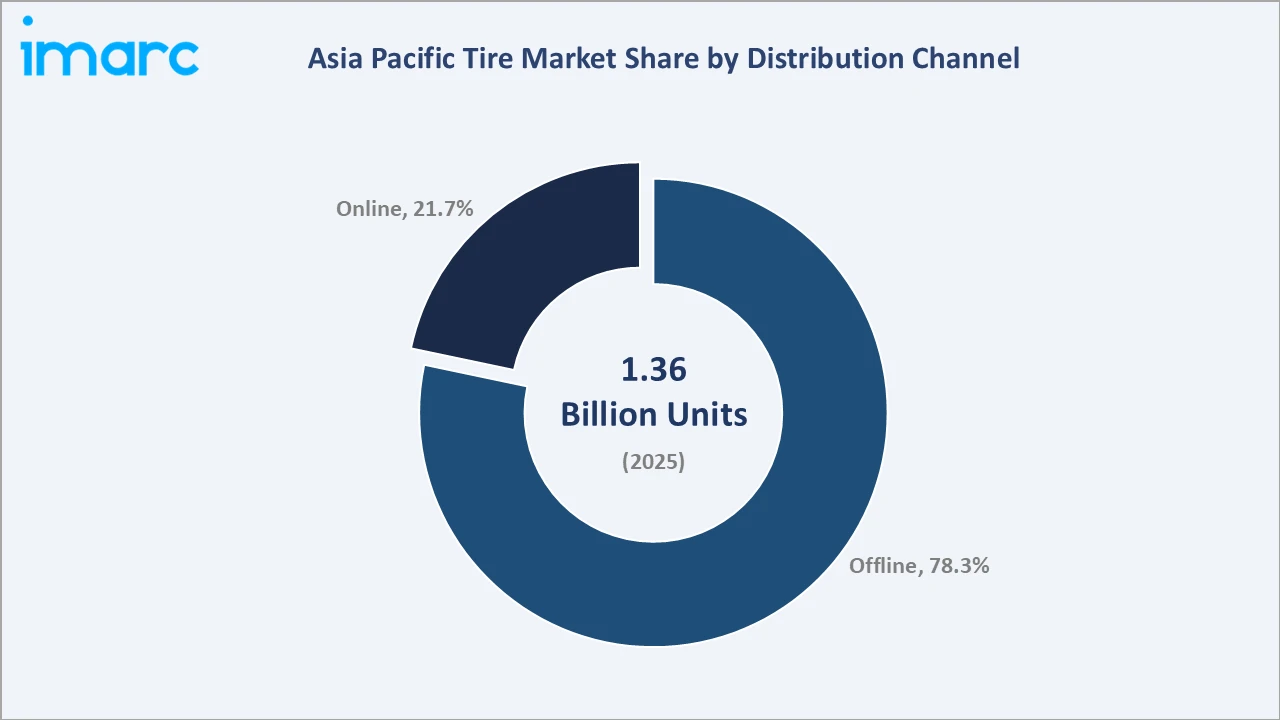
Offline channels dominate at 78.3% while the replacement end-use segment leads at 61.8%. China commands 32.6% of regional market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
1.36 Billion Units |
|
Market Size (2026) |
1.41 Billion Units |
|
Forecast Market Size (2034) |
1.86 Billion Units |
|
CAGR (2026-2034) |
3.35% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Distribution Channel |
Offline (78.3%, 2025) |
|
Dominant End-Use |
Replacement (61.8%, 2025) |
|
Leading Country |
China (32.6%, 2025) |
The Asia Pacific tire market size increased from 1.15 Billion Units in 2020 to 1.36 Billion Units in 2025 and is estimated to reach 1.41 Billion Units in 2026. The market is further expected to grow to 1.60 Billion Units by 2030 and 1.86 Billion Units by 2034. Asia Pacific tire market is commercially significant among global tire markets, combining the world's largest vehicle base in China, the fastest-growing vehicle market in India, and a dense cluster of premium and EV-focused markets in Japan, South Korea, and Australia.
To get more information on this market, Request Sample
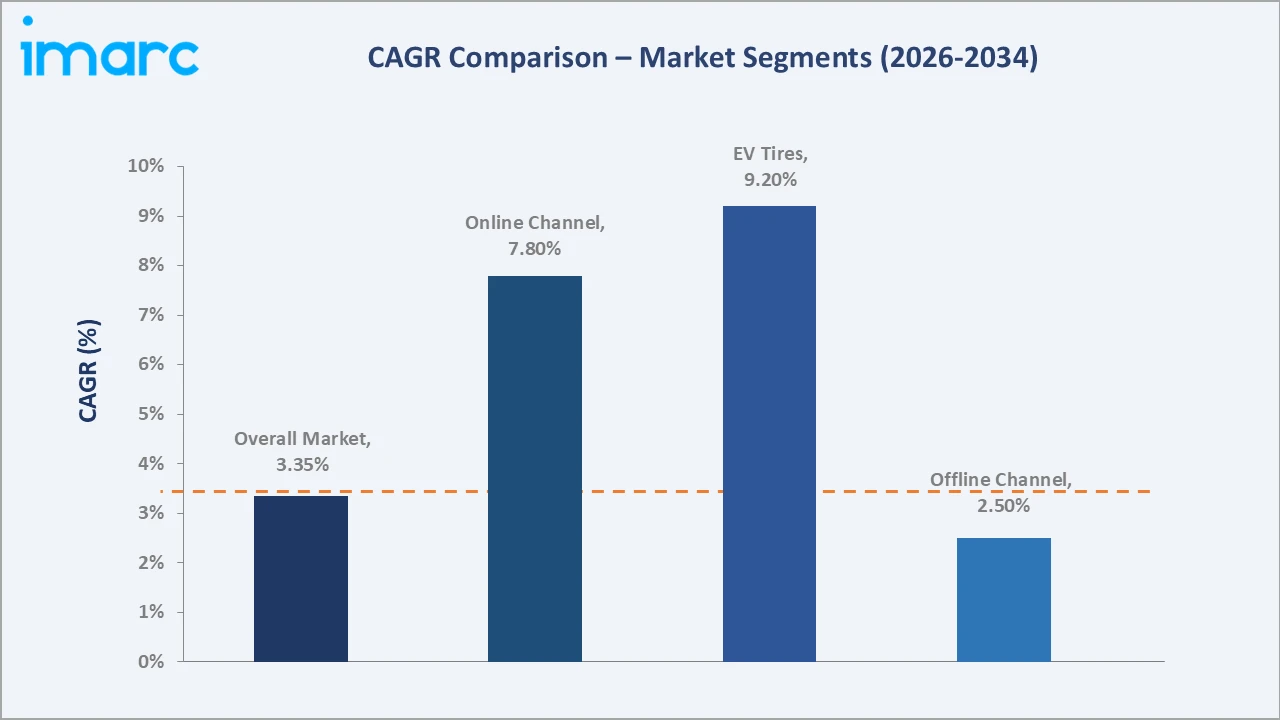
The online channel is growing fastest at ~7.8% CAGR through digital platform expansion in China and India, specialist platforms, and home-delivery tire fitting services reaching semi-urban consumers. EV tires are growing at ~9.2% CAGR as EV vehicle fleets in China, South Korea, and India demand performance-optimized, weight-tolerant, and energy-efficient tire solutions from global manufacturers.
Executive Summary
The Asia Pacific tire market expanded from 1.36 Billion Units in 2025 to an estimated 1.41 Billion Units in 2026, driven by rising vehicle ownership, highway infrastructure expansion, and growing replacement demand across China, India, Japan, Indonesia, and South Korea. The market's commercial scale is underpinned by the world's largest concentrated vehicle base, supported by sustained government investment in road networks and rising consumer spending on mobility.
The market is projected to reach 1.86 Billion Units by 2034, registering a CAGR of 3.35%. The offline distribution channel leads at 78.3%, reflecting the dominance of established dealer and workshop networks. The replacement segment leads at 61.8%, driven by fleet expansion and rising per-vehicle mileage.
Key Market Insights
|
Insight |
Data |
|
Leading Distribution Channel |
Offline – 78.3% share (2025) |
|
Leading End-Use Segment |
Replacement – 61.8% share (2025) |
|
Leading Region |
China – 32.6% share (2025) |
|
Market Opportunity |
Increasing vehicle base, government investment, rising consumer spending, e-commerce demand, smart sensor tires |
Key Analytical Observations Supporting the Above Data:
- Offline at 78.3%: The offline channel dominates due to the continued preference for in-person tire consultation, fitting, and inspection services across APAC markets. Established tire workshop networks and dealer chains maintain strong consumer trust. The dominance of offline channels is further supported by the technical nature of tire replacement, where consumers and fleet operators prefer professional fitting, balancing, and alignment services.
- Replacement at 61.8%: The replacement segment leads driven by the rapid expansion of the in-use vehicle fleet across APAC, rising per-vehicle mileage from highway development, and the regulatory push for periodic tire safety replacement. As consumer safety awareness increases, planned tire replacement cycles are shortening, particularly in India and Southeast Asia.
- China at 32.6%: China leads regionally through the world's largest vehicle market, a deeply established domestic tire manufacturing ecosystem, and surging EV adoption creating demand for high-performance low-rolling-resistance tires. The build-out of expressways and urban road infrastructure in Tier-2 and Tier-3 Chinese cities is sustaining above-national tire replacement demand cycles.
Asia Pacific Tire Market Overview
Asia Pacific tire market is positioned at the intersection of the world's highest vehicle density market (China), the world's fastest-growing vehicle market (India), and some of the most technically demanding vehicle markets globally (Japan, South Korea, Australia). The market's commercial structure encompasses OEM tire supply to automotive assembly plants, the high-volume replacement tire market, and the rapidly emerging EV-specific tire segment.
Asia Pacific tire ecosystem integrates global manufacturers with regional and domestic producers, creating a tiered competitive structure. Macroeconomic factors include rising urbanization and incomes, government highway investment, growing EV fleets, and increasing regulatory standards for tire fuel efficiency and safety across the region.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
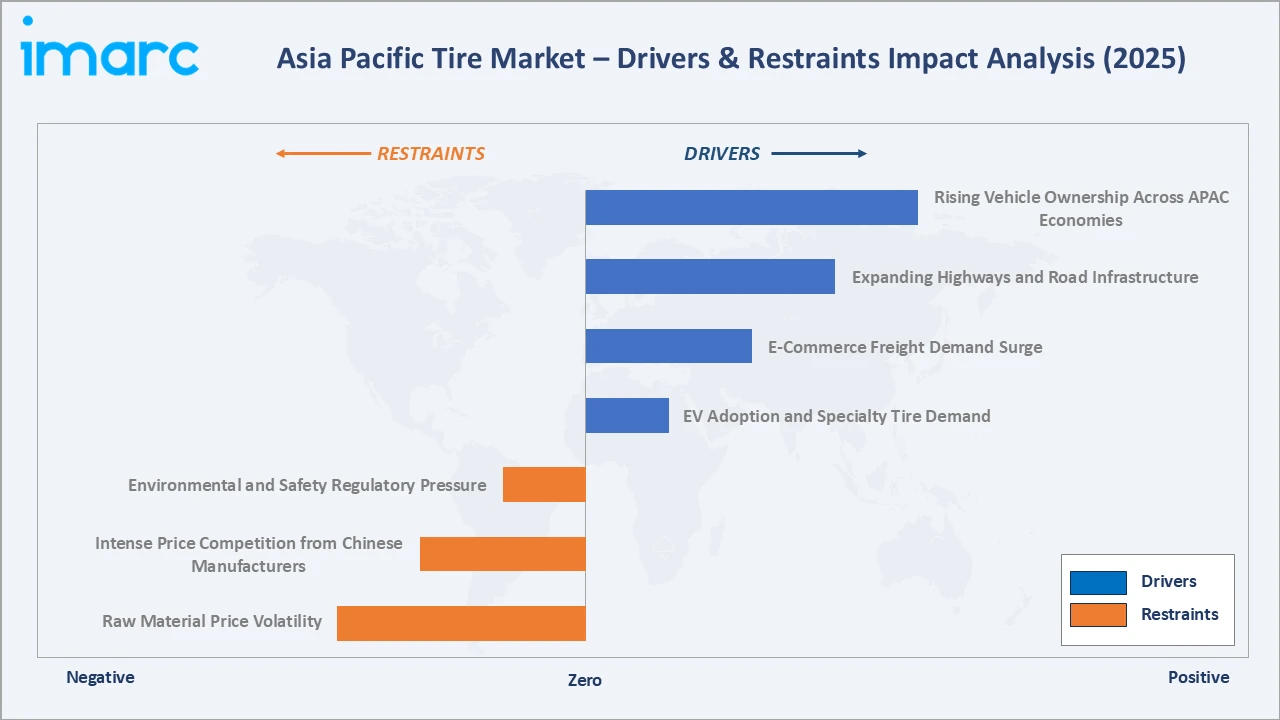
- Rising Vehicle Ownership Across APAC Economies: Rising vehicle ownership across China, India, Indonesia, and Vietnam is the primary structural driver of APAC tire demand, creating both OEM and replacement volume. India's passenger vehicle sales surpassed 4.2 million units in FY2025, sustaining tire demand across price segments. This expansion directly increases the in-use vehicle fleet, which is the primary base for replacement tire demand. Urbanization and rising incomes across ASEAN economies are accelerating first-vehicle ownership, adding millions of new tire consumers annually.
- Expanding Highways and Road Infrastructure: Government investments in highway and road infrastructure across China, India, Thailand, and Vietnam are directly supporting tire demand by increasing per-vehicle mileage and accelerating replacement cycles. India's National Highway development program and China's ongoing expressway expansion are creating above-national average tire consumption in high-mileage commercial vehicle segments. Road infrastructure development also supports logistics fleet growth, driving commercial vehicle tire demand across medium and heavy trucks.
- E-Commerce Freight Demand Surge: The explosive growth of e-commerce across China, India, Southeast Asia, and Australia is driving sustained demand for commercial vehicle tires through rapid logistics fleet expansion. Last-mile delivery vehicle growth has created a distinct urban commercial tire segment. This is particularly significant for light commercial vehicle tires, where e-commerce logistics operators are running high-mileage urban delivery cycles that compress replacement intervals.
- EV Adoption and Specialty Tire Demand: Growing electric vehicle adoption across China, South Korea, Japan, and India is creating demand for EV-optimized tires that handle higher vehicle weight, deliver low rolling resistance, and support regenerative braking. This specialty segment commands significant price premiums over standard radial tires, supporting revenue value growth above volume growth.
Market Restraints
- Raw Material Price Volatility: Natural rubber price volatility, driven by weather events and supply disruptions in Thailand, Indonesia, and Malaysia, directly impacts tire manufacturing costs and margin stability. Synthetic rubber and carbon black price movements linked to crude oil cycles add further cost unpredictability. These raw material cost pressures are particularly challenging for mid-tier regional tire manufacturers with limited hedging capability, constraining their ability to compete on price while maintaining product quality.
- Intense Price Competition from Chinese Manufacturers: China's large-scale domestic tire manufacturers have created significant pricing pressure across Southeast Asian and South Asian markets, competing aggressively on price in the replacement segment. This price compression limits revenue growth for premium global brands in the mid-range replacement segment and reduces margin for regional manufacturers. The competitive pricing pressure from Chinese-manufactured tires is particularly intense in Indonesia, Thailand, and India's commercial vehicle replacement segment.
- Environmental and Safety Regulatory Pressure: Increasingly stringent fuel-efficiency labeling requirements, rolling resistance standards, and end-of-life tire disposal regulations across Japan, South Korea, Australia, and China are increasing compliance costs for manufacturers. Meeting evolving European and domestic eco-design standards requires continuous product reformulation investment. End-of-life tire disposal regulations are also creating infrastructure and compliance cost pressures across the value chain.
Market Opportunities
- EV Tire Specialization and Premium Positioning: The accelerating EV fleet across China and South Korea represents the region's highest-margin tire growth opportunity. EV-specific tires with embedded sensors, self-sealing technology, and airless design are commanding significant premiums, enabling manufacturers to shift market mix toward higher-value products. Investment in EV tire manufacturing and R&D capacity in APAC creates durable competitive advantage as EV penetration rises.
- Online Tire Retail and Fitting Service Integration: The expansion of online tire retail, particularly in China through Tuhu, and emerging platforms in India and Southeast Asia, is creating new distribution models that reach consumers beyond traditional dealer networks. Integrated online-to-offline tire fitting services, where consumers purchase online and schedule professional fitting locally, are reducing barriers to online tire purchase and driving incremental replacement demand in semi-urban and tier-2 markets.
Market Challenges
- Technological Obsolescence in Smart Tire Innovation: Rapid innovation in smart tire technology embedded sensors, airless structures, and AI-based tire performance analytics is creating product lifecycle pressure for manufacturers. Continuous R&D investment is required to remain competitive in premium and OEM segments as vehicle manufacturers integrate tire performance monitoring into connected vehicle systems. The high investment required for smart tire development is challenging for smaller regional producers.
- Managing Multi-Market Regulatory Complexity: Operating across the APAC region requires compliance with diverse and often diverging national tire safety, labeling, and environmental standards across 10+ major country markets. Regulatory fragmentation increases product variation costs, approval timelines, and certification expenditure for manufacturers serving the region from centralized production facilities.
Emerging Market Trends
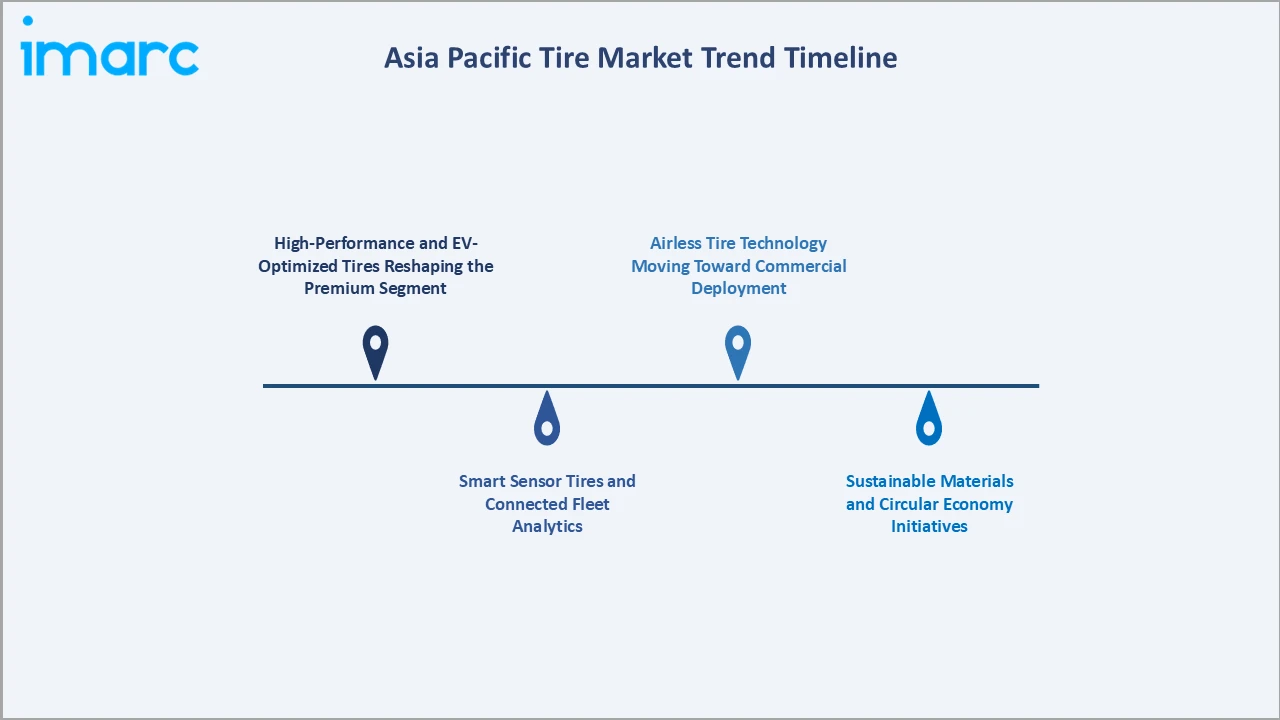
1. High-Performance and EV-Optimized Tires Reshaping the Premium Segment
Rising EV adoption across China, South Korea, and Japan is accelerating demand for tires engineered for heavier EV weight, high torque, and regenerative braking. Premium OEMs are specifying EV-specific tires, and global manufacturers are launching dedicated EV tire product lines. This trend is driving value growth above unit volume growth and reshaping manufacturer R&D priorities toward EV-compatible solutions.
2. Smart Sensor Tires and Connected Fleet Analytics
The integration of pressure, temperature, and wear sensors into tires is enabling real-time fleet tire performance monitoring, reducing blowout risk, and optimizing replacement cycles for commercial fleets. Fleet operators in logistics, public transport, and ride-hailing are early adopters, creating a technology-led B2B replacement demand.
3. Sustainable Materials and Circular Economy Initiatives
Global manufacturers are accelerating the use of bio-based rubber, recycled carbon black, and steel cord recycling to meet sustainability targets and respond to tightening eco-design regulations. Michelin's commitment to 100% sustainable materials by 2050 and Goodyear's 70% sustainable material EDS tire are APAC-relevant benchmarks. Circular economy tire initiatives retreading, recycling, and materials recovery are also gaining commercial scale, particularly in commercial vehicle segments.
4. Airless Tire Technology Moving Toward Commercial Deployment
Airless or non-pneumatic tire development, advanced by Michelin, Goodyear, and Bridgestone, is progressing toward low-speed commercial and industrial applications. APAC's large two-wheeler market and industrial vehicle base represent natural early adoption opportunities for puncture-proof airless solutions. While full passenger car commercialization remains a medium-term prospect, airless tire technology is beginning to influence product development investments and create competitive differentiation in the APAC industrial tire segment.
Industry Value Chain Analysis
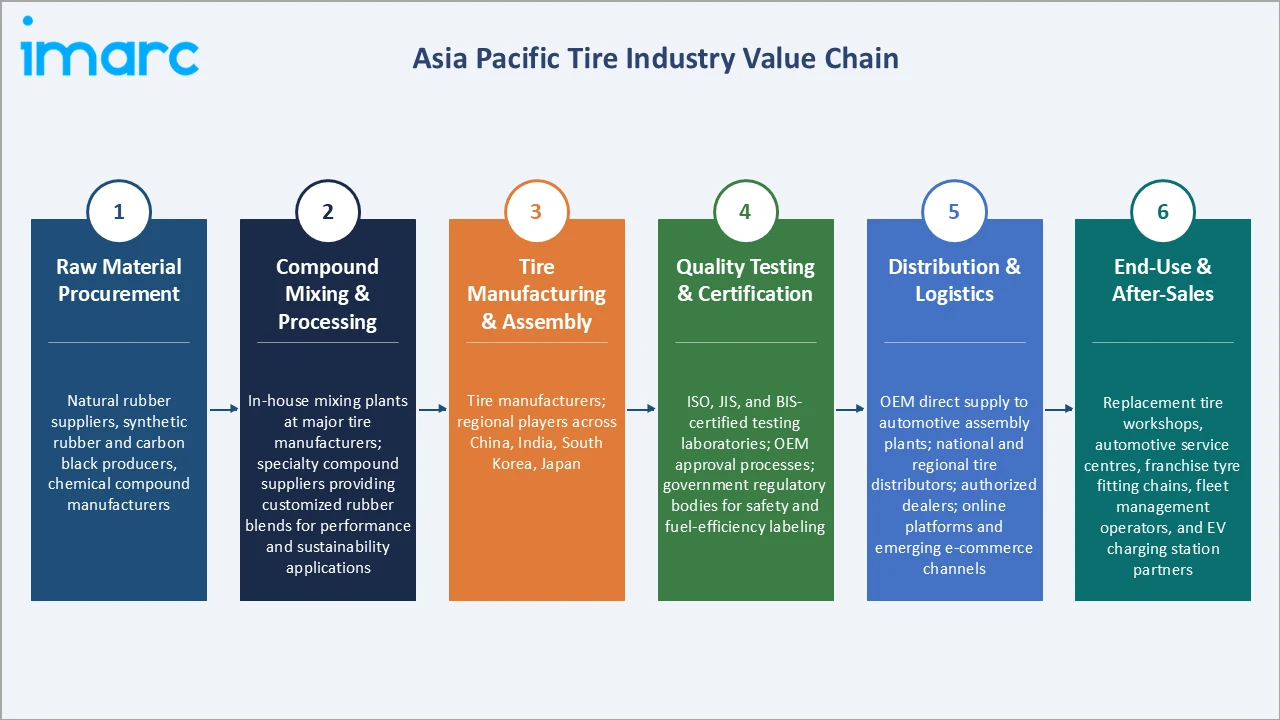
Asia Pacific tire value chain encompasses natural rubber cultivation concentrated in Thailand, Indonesia, and Malaysia through compound mixing, tire manufacturing, quality testing, and distribution across a highly diverse multi-country regional market.
|
Stage |
Key Participants |
|
Raw Material Procurement |
Natural rubber suppliers, synthetic rubber and carbon black producers, chemical compound manufacturers |
|
Compound Mixing & Processing |
In-house mixing plants at major tire manufacturers; specialty compound suppliers providing customized rubber blends for performance and sustainability applications |
|
Tire Manufacturing & Assembly |
Tire manufacturers; regional players across China, India, South Korea, Japan |
|
Quality Testing & Certification |
ISO, JIS, and BIS-certified testing laboratories; OEM approval processes; government regulatory bodies for safety and fuel-efficiency labeling |
|
Distribution & Logistics |
OEM direct supply to automotive assembly plants; national and regional tire distributors; authorized dealers; online platforms and emerging e-commerce channels |
|
End-Use & After-Sales |
Replacement tire workshops, automotive service centres, franchise tyre fitting chains, fleet management operators, and EV charging station partners |
The distribution and logistics stage is the most commercially consequential for market reach, where tire brands operating across APAC's fragmented multi-country market structure must balance centralized manufacturing efficiency with localized distribution to serve diverse terrain, vehicle, and regulatory requirements across 10+ country markets.
Technology Landscape in the Asia Pacific Tire Industry
Radial and High-Performance Tire Technology
Radial tire technology dominates the APAC replacement and OEM segments through superior fuel efficiency, ride comfort, and tread life relative to bias tires. Ultra-high-performance (UHP) radial tires are growing fastest in passenger and premium segments as vehicle performance and consumer expectations rise. Low rolling resistance technology embedded in radial construction is also gaining regulatory mandated adoption across Japan, South Korea, and China.
Smart Tire Sensors and Connected Technology
Embedded tire pressure monitoring systems (TPMS) are now mandatory across Japan, South Korea, China, and increasingly across Southeast Asia, creating a connected tire sensor baseline. Advanced smart tire platforms incorporating wear monitoring, road surface detection, and predictive analytics are transitioning from commercial fleet to consumer passenger application.
Sustainable Material and Airless Tire Innovation
Bio-based rubber, recycled carbon black, and sustainable cord materials are gaining share in tire compound formulations driven by OEM sustainability specifications and regulatory pressures. Michelin, Goodyear, and Bridgestone are the leading innovation drivers, with commercial sustainable material tire products already available across APAC markets. Airless tire development remains a medium-term commercial horizon, with low-speed industrial and urban delivery vehicle applications providing the near-term entry pathway.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Radial/Bias Tires | Radial | 🔒 | 2025 |
| End-Use | Replacement | 61.8% | 2025 |
| Vehicle Type | Passenger Cars | 🔒 | 2025 |
| Size | 🔒 | 🔒 | 2025 |
| Distribution Channel | Offline | 78.3% | 2025 |
| Country | China | 32.6% | 2025 |

By Distribution Channel
Offline channels lead at 78.3% (2025). The offline segment encompasses the established tire workshop, authorized dealer, and automotive service centre networks that serve the dominant share of APAC tire replacement consumers. Professional fitting, balancing, and alignment services bundled with tire purchase sustain the structural preference for offline tire purchase across all major APAC markets.
To access detailed market analysis, Request Sample
Online channels at 21.7% are growing fastest at ~7.8% CAGR through dedicated tire e-commerce platforms. China's Tuhu platform, which generated over RMB 30 billion in GMV in 2023, exemplifies the online-to-offline tire retail integration model that is expanding rapidly across China, India, and Southeast Asia.
By End-Use
Replacement dominates at 61.8% (2025). The replacement segment is the largest and most commercially resilient segment, driven by the APAC region's expanding in-use vehicle fleet and rising per-vehicle mileage from infrastructure development. Fleet replacement cycles particularly for commercial vehicles and two-wheelers create predictable and recurring tire demand.
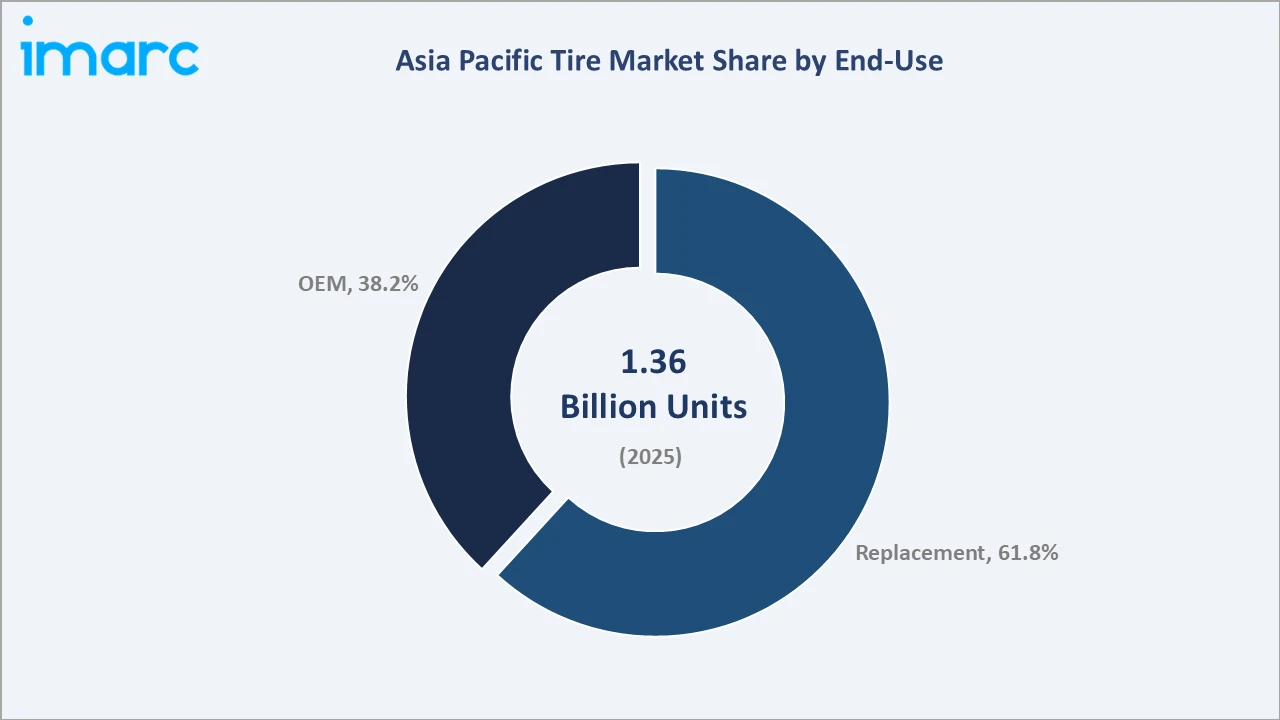
OEM at 38.2% reflects the strong automotive assembly base across China, Japan, South Korea, India, Thailand, and Indonesia. OEM tire supply requires precision fitment specifications and long-term manufacturer certification, creating durable supplier relationships between global tire majors and automotive OEMs.
Regional Market Insights
|
Country |
Market Share (2025) |
Key Growth Drivers |
|
China |
32.6% |
World's largest vehicle market; domestic tire giant GITI and Zhongce; EV rollout and smart tire demand |
|
India |
22.8% |
Rapid two-wheeler and passenger car growth; highway expansion; rising replacement demand |
|
Japan |
11.4% |
Premium and performance tire demand; Bridgestone and Yokohama home market; innovation in run-flat and EV tires |
|
Indonesia |
8.7% |
Growing middle-class vehicle ownership; manufacturing hub for export-oriented tire production |
|
South Korea |
6.9% |
Hankook and Kumho home market; EV-focused tire R&D; global OEM supply partnerships |
|
Thailand |
5.2% |
ASEAN automotive production hub; natural rubber availability; export-focused manufacturing |
|
Australia |
4.6% |
High per-vehicle spending; premium replacement and all-terrain tire demand for diverse terrain |
|
Malaysia |
3.8% |
Growing automotive production; natural rubber producer; regional distribution centre |
|
Pakistan |
2.1% |
Expanding domestic vehicle industry; low penetration supporting high growth potential |
|
Other Regions |
1.9% |
Vietnam, Philippines, New Zealand and other emerging APAC economies supporting growth in base demand |
China's 32.6% market leadership reflects the world's largest vehicle market, a dense domestic tire manufacturing ecosystem, and accelerating EV tire demand. India's 22.8% reflects Asia's fastest-growing vehicle market, a rapidly expanding highway network, and significant unmet two-wheeler and commercial vehicle tire demand. Japan's 11.4% reflects a mature premium replacement market and the home base of Bridgestone and Yokohama.
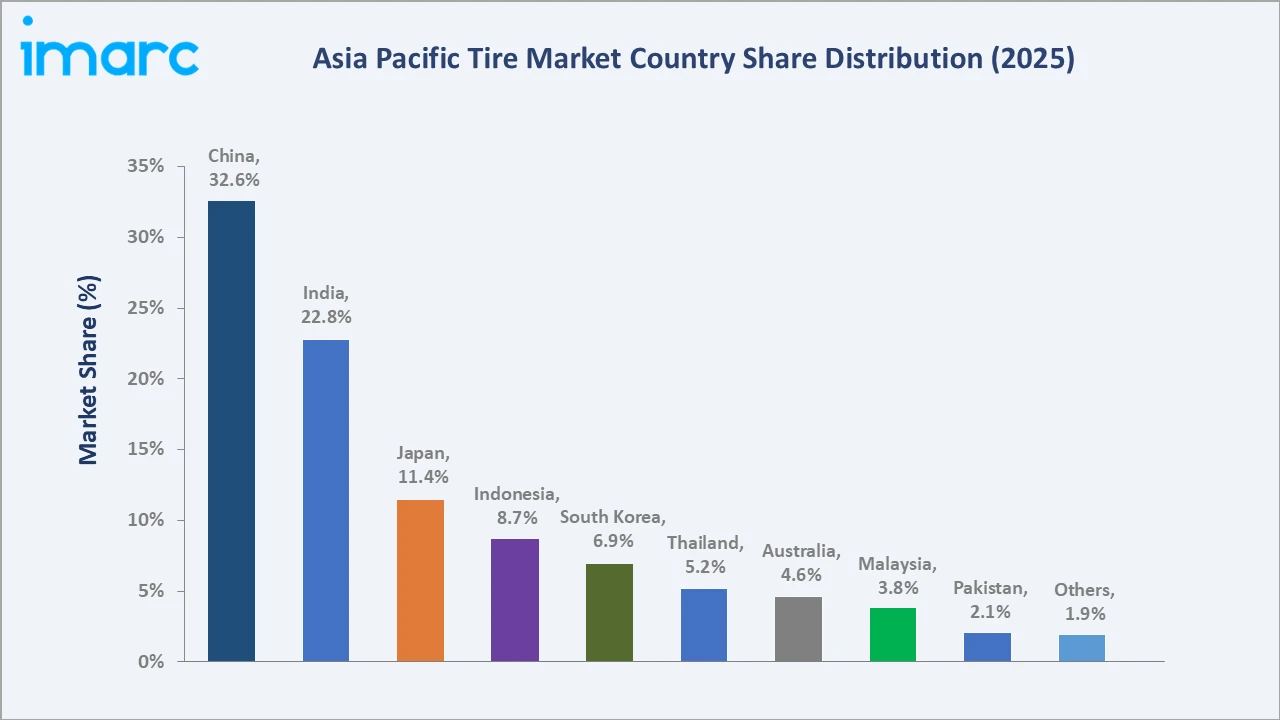
Indonesia's 8.7% reflects a fast-growing consumer vehicle market and a significant natural rubber producer advantage. South Korea's 6.9% reflects Hankook and Kumho's domestic OEM and global export activities. Thailand's 5.2% reflects ASEAN's automotive production hub status and natural rubber proximity. Australia's 4.6% reflects high per-vehicle spending on premium replacement and all-terrain tires.
Competitive Landscape
Asia Pacific tire market competitive landscape is defined by the dominance of global tire majors alongside strong APAC-rooted players. Competition is intensifying through EV tire specialization, online distribution disruption, and sustainability differentiation.
| Company | Key Brands | Market Position | Core Strength |
|---|---|---|---|
| Michelin | Michelin, BFGoodrich, Uniroyal | Market Leader | Global leader in sustainable and fuel-efficient tire innovation across all vehicle segments |
| Bridgestone Corporation | Bridgestone, Firestone | Market Leader | Largest global tire manufacturer with extensive APAC production and OEM supply network |
| Continental AG | Continental, General Tire, Barum | Innovator | Advanced smart tire technology and EV-optimized tire solutions with integrated sensor systems |
| The Goodyear Tire & Rubber Company | Goodyear, Dunlop, Kelly | Strong Challenger | Broad brand portfolio serving both OEM and high-volume replacement channels across APAC |
Key players include Michelin, Bridgestone Corporation, Continental AG, The Goodyear Tire & Rubber Company, and others.
Key Company Profiles
Michelin
Michelin is the world's leading tire manufacturer and the benchmark for sustainable innovation, fuel-efficiency technology, and premium tire engineering, with a strong and growing APAC presence across all vehicle segments.
- Key Brands: Michelin, BFGoodrich, Uniroyal.
- Recent Developments: In March 2026, Michelin opened a 2,000 sq. ft. Michelin Tire Service store in Navi Mumbai with NX Sanghi Tyres, reinforcing its India retail expansion strategy. Michelin has committed to producing tires from 100% sustainable materials by 2050.
- Strategic Focus: Maintaining global technology leadership through sustainable material innovation, EV-optimized tire development, and premium brand positioning across APAC passenger, commercial, and specialty segments.
Bridgestone Corporation
Bridgestone Corporation is the world's largest tire manufacturer by revenue, with deep APAC roots across Japan, China, India, Thailand, and Australia, serving OEM and replacement markets across all vehicle categories.
- Key Brands: Bridgestone, Firestone, Dayton.
- Strategic Focus: Premiumization in key APAC markets, EV tire technology investment, and strategic portfolio streamlining toward high-margin passenger and specialty tire segments.
Market Concentration Analysis
The Asia Pacific tire market exhibits a moderately fragmented structure, with the top five operators accounting for approximately 40-45% of organized market revenue across the region. Concentration is highest in the premium passenger and EV tire segments, where global leaders command dominant share through superior technology, OEM relationships, and brand positioning.
Market concentration is evolving through two dynamics: global leaders expanding APAC production capacity to capture growing demand, while domestic Chinese manufacturers are improving quality positioning and expanding into Southeast Asia, gradually narrowing the quality gap with global brands in the mid-range replacement segment.
Investment & Growth Opportunities
Highest Growth Segments
Replacement specialization (~3.8% CAGR through EV fleet expansion), online distribution platforms (~7.8% CAGR from digital retail adoption), offline distribution platforms (~2.5% CAGR from fleet analytics adoption), and OEM (~2.7% CAGR) represent the highest-growth investment vectors in Asia Pacific tires through 2034.
Emerging Investment Opportunities
India's two-wheeler tire market, with over 200 million in-use two-wheelers and growing, represents one of APAC's most commercially underdeveloped high-volume segments. Southeast Asia's emerging electric two-wheeler fleet, combined with regulatory push for safer and more fuel-efficient tires, is creating a first-mover window for EV-compatible two-wheeler tire investment. APAC's commercial vehicle replacement segment is also growing as logistics and ride-hailing fleet expansion accelerates replacement cycles.
Investment Themes
- EV tire manufacturing capacity in China, India, and South Korea: targeting OEM supply partnerships with regional EV manufacturers and capturing growing independent replacement demand as EV fleet penetration accelerates.
- Online-to-offline tire retail platform investment: replicating and adapting the China Tuhu model to India and Southeast Asian markets, creating scalable digital acquisition with local fitting service integration that addresses the dominant consumer preference for professional tire installation.
Future Market Outlook (2026-2034)
The Asia Pacific tire market is projected to grow from 1.36 Billion Units in 2025 to 1.41 Billion Units in 2026, reaching 1.86 Billion Units by 2034, registering a CAGR of 3.35% during 2026-2034. The market's anchor value of 1.60 Billion Units in 2030 represents the APAC tire market at a structural transition point, where EV tires are becoming mainstream, online distribution is capturing significant share, and sustainability-mandated product reformulation is reshaping manufacturing economics.
Three structural forces define APAC tire market growth through 2034: the continued expansion of the region's vehicle fleet, particularly in India, Indonesia, and Vietnam, creating the fastest-growing new vehicle tire consumer base; EV fleet growth across China, South Korea, and Japan driving a product mix shift toward higher-value specialty tires; and digital retail maturation creating geographic tire market democratization beyond established dealer networks.
Research Methodology
Primary Research
Primary research comprised structured interviews with Asia Pacific tire industry stakeholders, including OEM procurement directors, regional distributor executives, tire retail chain managers, fleet operators from logistics and transport sectors, and EV manufacturer supply chain teams across China, India, Japan, South Korea, Indonesia, and Australia.
Secondary Research
Secondary research encompassed APAC vehicle production and sales data, tire import-export statistics across key country markets, company annual reports and investor presentations, government infrastructure investment data, and regulatory filings. Over 60 secondary sources were reviewed, including national automotive associations and trade publications.
Forecasting Models
Market volume forecasts were developed using a vehicle fleet expansion model: APAC in-use vehicle stock by country and vehicle type, multiplied by estimated tire sets per vehicle per year (replacement frequency), plus OEM new vehicle production tire demand, aggregated at country level and summed to regional total.
Asia Pacific Tire Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion Units |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Radial/Bias Tires Covered | Radial, Bias |
| End-Uses Covered | OEM, Replacement |
| Vehicle Types Covered | Passenger Cars, Light Commercial Vehicles, Medium and Heavy Commercial Vehicles, Two-Wheelers, Off-The-Road (OTR), Three- Wheelers |
| Sizes Covered |
|
| Distribution Channels Covered | Offline, online |
| Countries Covered | China, India, Japan, Australia, South Korea, Thailand, Indonesia, Malaysia, Pakistan, Others |
| Companies Covered | Michelin, Bridgestone Corporation, Continental AG, The Goodyear Tire & Rubber Company, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Asia Pacific tire market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Asia Pacific tire market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Asia Pacific tire industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Asia Pacific Tire Market Report
Asia Pacific tire market size is estimated at 1.41 Billion Units in 2026, driven by rising vehicle ownership, highway infrastructure expansion, and growing replacement demand across China, India, and Southeast Asia. EV fleet growth and online distribution expansion are further supporting market momentum.
Asia Pacific tire market grows at 3.35% CAGR during 2026-2034, reaching 1.86 Billion Units by 2034. Growth is sustained by APAC's expanding vehicle fleet, rising EV penetration, growing highway mileage, and the structural shift of the replacement market toward higher-frequency shorter-interval replacement cycles.
Offline channels lead at 78.3% through the established tire workshop and dealer network dominance. Consumer preference for professional fitting, balancing, and alignment services sustains offline channel structural leadership across all major APAC markets.
Replacement leads at 61.8% through the APAC region's rapidly expanding in-use vehicle fleet and rising per-vehicle mileage driven by highway infrastructure development. Fleet replacement cycles for commercial vehicles and two-wheelers sustain consistent above-market replacement demand.
China leads at 32.6% through the world's largest vehicle market, a dense domestic tire manufacturing ecosystem, and accelerating EV tire demand from the world's largest EV fleet. Government highway infrastructure investment and the Tuhu-led online tire retail expansion are further supporting China's market leadership.
Leading companies include Michelin, Bridgestone Corporation, Continental AG, The Goodyear Tire & Rubber Company, and others.
Asia Pacific tire market is projected to reach approximately 1.60 Billion Units by 2030, with EV tire premiumization, online distribution platform growth, and commercial vehicle fleet expansion driving market value growth above volume growth from a 1.41 Billion Unit base in 2026.
Three priority investment opportunities: EV tire manufacturing capacity investment in China, India, and South Korea targeting OEM partnerships and replacement demand; online-to-offline tire retail platform development in India and Southeast Asia; and sustainable material tire R&D investment targeting regulatory-mandated eco-design compliance and premium brand differentiation across APAC.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade