Australia Chocolate Market Size, Share, Trends and Forecast by Product Type, Product Form, Application, Pricing, Distribution, and Region, 2026-2034
Australia Chocolate Market Size, Share, Trends & Forecast (2026-2034)
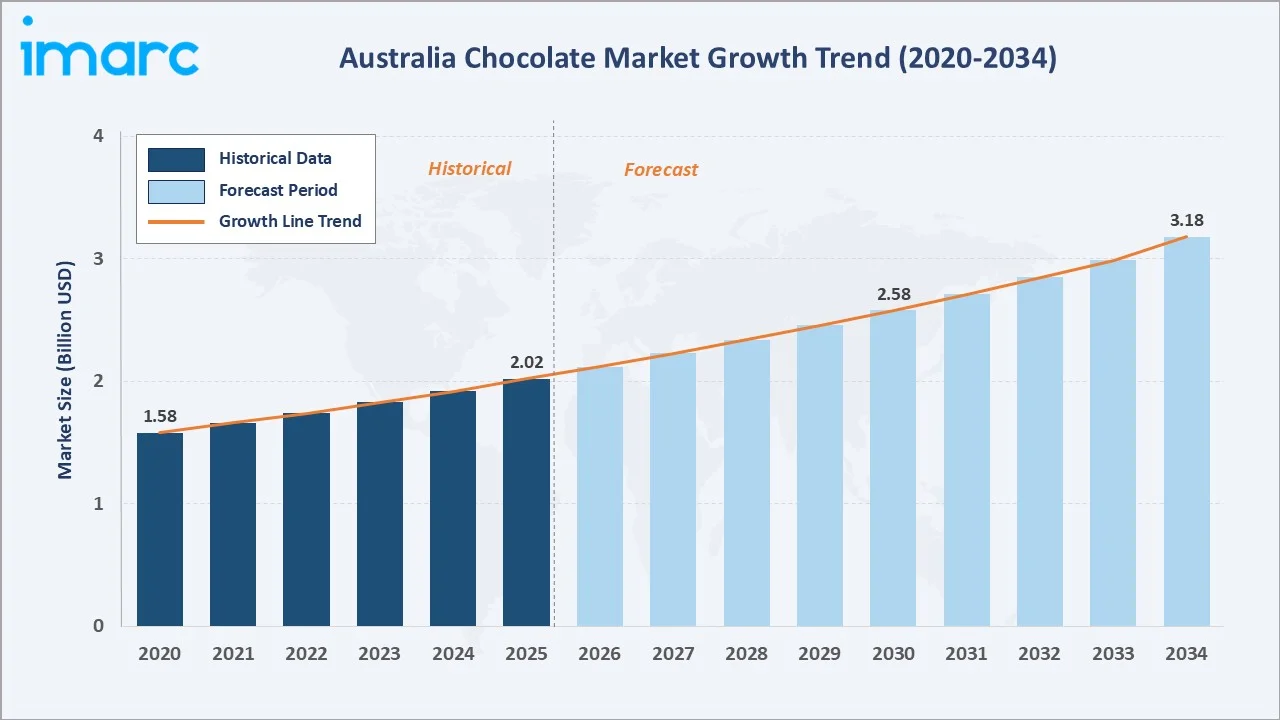
The Australia chocolate market reached USD 2.02 Billion in 2025 and is projected to reach USD 3.18 Billion by 2034, exhibiting a robust CAGR of 5.02% during 2026-2034. Australia’s chocolate sector is one of the most dynamic and per-capita-intensive confectionery markets in the Asia-Pacific region, driven by deeply embedded gifting traditions, a sophisticated food culture that embraces premium and artisan chocolate, and the progressive health-conscious shift toward dark chocolate’s functional benefits. The average Australian consumes approximately 5.5 kilograms of chocolate annually, highlighting the country’s strong consumer appetite for chocolate products. Food products lead application at 74.0%, everyday chocolate dominates pricing at 61.0%, and Australia Capital Territory & New South Wales command the largest regional share at 34.0%.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 2.02 Billion |
|
Forecast Market Size (2034) |
USD 3.18 Billion |
|
CAGR (2026-2034) |
5.02% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Application |
Food Products – 74.0% (2025) |
|
Dominant Pricing |
Everyday Chocolate – 61.0% (2025) |
|
Leading Region |
Australia Capital Territory & New South Wales – 34.0% (2025) |
The Australia chocolate market grew from USD 1.58 Billion in 2020 to USD 2.02 Billion in 2025, driven by the resilience of chocolate as a comfort food during COVID-19 lockdowns, accelerated online grocery and gourmet food delivery adoption, and the premiumization of the category through the expansion of bean-to-bar artisan producers and international premium brands. The market is projected to reach USD 2.58 Billion by 2030 and USD 3.18 Billion by 2034.
To get more information on this market, Request Sample
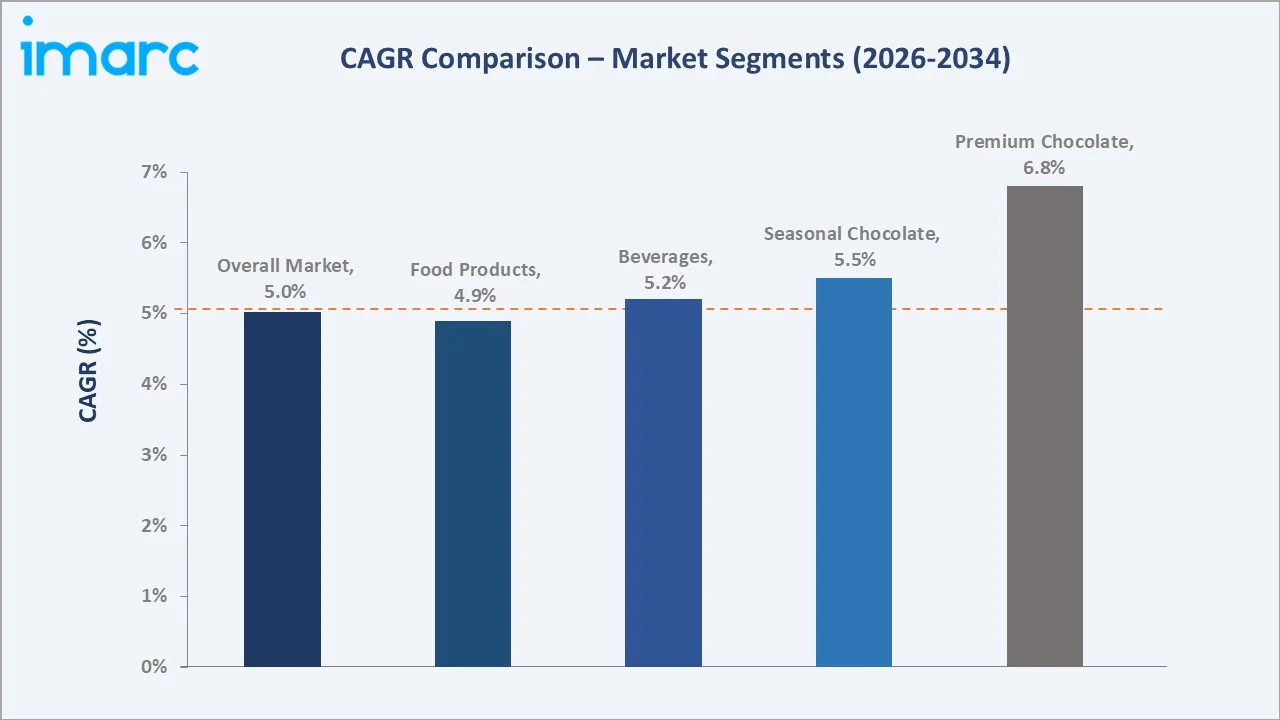
Premium chocolate grows fastest at ~6.80% CAGR through artisan, single-origin, and functional dark chocolate driving trade-up. Seasonal chocolate grows at ~5.50% CAGR through Easter, Christmas, and Valentine’s gifting market expansion. Beverages application grows at ~5.20% CAGR through hot chocolate, chocolate milk, and functional cacao beverages. Food products grow at ~4.90% CAGR as bakery, desserts, and confectionery sectors expand chocolate ingredient use.
Executive Summary
The Australia chocolate industry analysis represents one of the Asia-Pacific region’s most mature, high-value, and innovation-driven confectionery categories, where the combination of Australia’s high per-capita disposable income, a deeply embedded chocolate gifting culture across Easter, Christmas, Valentine’s Day, Mother’s Day, and Father’s Day, and a rapidly evolving consumer palate toward premium, dark, and functional chocolate formats creates structural demand resilience and premiumization upside that distinguishes Australia from lower-income Asian markets growing primarily on volume.
Food products’ 74.0% application dominance reflects chocolate’s foundational role as a baking and confectionery ingredient across Australia’s large retail bakery sector, foodservice chocolate dessert menus, and industrial food manufacturing for chocolate-coated biscuits, pralines, and snack bars. Everyday chocolate’s 61.0% pricing leadership reflects the enduring volume dominance of mainstream confectionery brands that occupy Australia’s supermarket confectionery aisles as habitual purchase categories with deep household penetration and weekly basket inclusion rates. Australia Capital Territory & New South Wales’s 34.0% regional share reflects the economic weight of Australia’s most populous state, the financial services and professional workforce density of Sydney that drives premium chocolate gift spending, and the ACT’s Canberra government sector’s above-average household income driving premium brand adoption.
Key Market Insights
|
Insight |
Data |
|
Dominant Application |
Food Products – 74.0% share (2025) |
|
Dominant Pricing |
Everyday Chocolate – 61.0% share (2025) |
|
Leading Region |
Australia Capital Territory & New South Wales – 34.0% share (2025) |
|
Market Opportunity |
Functional chocolate with added protein, adaptogens, and probiotics; sugar-free and keto-friendly chocolate for health-conscious consumers; sustainable and Fairtrade chocolate premiumization; Indigenous ingredient chocolate for tourism and export |
Key Analytical Observations:
- Food Products at 74.0% (2025): Chocolate’s food products application in Australia encompasses four major sub-segments that collectively sustain the category’s overwhelming volume majority. The food products segment’s dominance is further reinforced by Australia’s expanding meal kit delivery market incorporating chocolate dessert components, and private-label chocolate product ranges expanding chocolate ingredient accessibility for home baking.
- Everyday Chocolate at 61.0% (2025): Everyday chocolate encompasses all mainstream-priced chocolate products sold at AUD 1-6 per standard unit in supermarket confectionery aisles, convenience stores, and petrol stations. Everyday chocolate faces the principal margin pressure from Australia’s cocoa price escalation, creating manufacturer cost pressures that translate into retail price inflation that has modestly compressed volume growth while sustaining value growth.
- Australia Capital Territory & New South Wales at 34.0% (2025): Australia Capital Territory & New South Wales lead the market due to high population concentration, high disposable incomes, urban retail penetration, and demand for premium and specialty chocolates. The presence of major supermarkets, specialty stores, cafés, and gifting occasions further supports regional consumption.
Australia Chocolate Market Overview
The Australia chocolate market encompasses milk, dark, white, filled, and premium chocolate products sold through supermarkets, convenience stores, specialty retailers, cafés, and online channels. Demand is supported by high per-capita consumption, gifting occasions, premiumization, and product innovation. The market also includes growing segments such as organic, low-sugar, vegan, and sustainably sourced chocolates catering to evolving consumer preferences. Macroeconomic factors include rising disposable incomes, urbanization, strong household consumption, tourism, and well-developed retail and e-commerce channels. Growth in the Australia vegan chocolate market reflects increasing demand for plant-based, premium, and healthier options.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
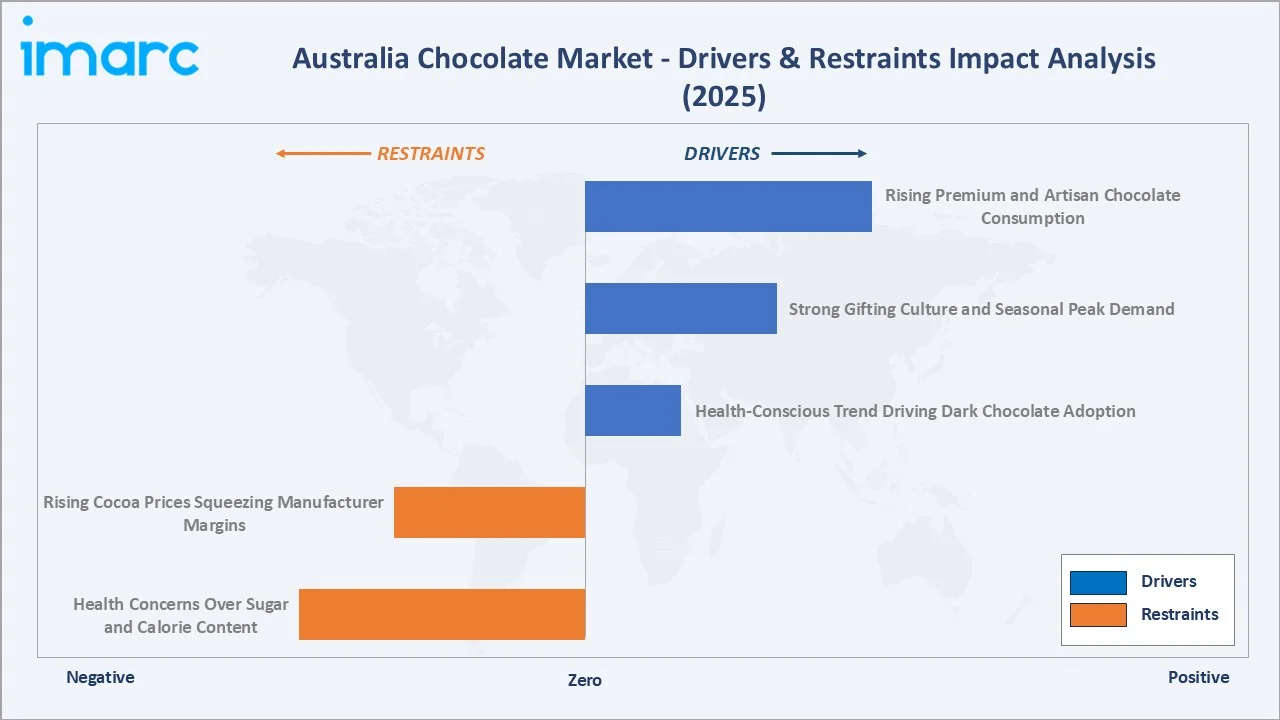
- Rising Premium and Artisan Chocolate Consumption: Australia’s chocolate market is experiencing a structural premiumization wave driven by the convergence of elevated consumer food sophistication, increasing disposable income concentration in the professional and knowledge worker demographic, and the “craft chocolate” movement’s Australia-specific expression through bean-to-bar producers and specialty retail. The artisan chocolate sector represents Australia’s fastest-growing chocolate manufacturing segment, significantly outpacing the mainstream confectionery category.
- Strong Gifting Culture and Seasonal Peak Demand: Australia’s calendar of chocolate gifting occasions creates structural demand peaks that sustain premium chocolate producers’ revenue through predictable high-volume, high-margin occasions. Australia’s corporate gifting market for chocolate creates a B2B premium chocolate demand stream.
- Health-Conscious Trend Driving Dark Chocolate Adoption: In 2023, 24.9% of Australians followed a specific diet or eating pattern, while 5.3% identified as vegetarian or vegan. Australia’s highly health-aware consumer market is paradoxically driving chocolate consumption growth through the repositioning of dark chocolate as a health-beneficial indulgence. Dark chocolate's clinically documented cardiovascular benefits, antioxidant content, mood-enhancing properties, and cognitive function support create a health narrative that Australian consumers increasingly leverage to justify premium dark chocolate purchases without guilt.
Market Restraints
- Rising Cocoa Prices Squeezing Manufacturer Margins: Increasing Cocoa bean and Cocoa ingredient prices are rising production costs for chocolate manufacturers and putting pressure on profit margins. Producers may respond by increasing retail prices, reducing pack sizes, or reformulating products, which can affect consumer demand. Persistent raw material inflation can therefore restrain growth in the Australia chocolate market, particularly in price-sensitive mass-market segments.
- Health Concerns Over Sugar and Calorie Content: Growing awareness of high sugar, calorie, and fat intake is encouraging Australian consumers to moderate traditional chocolate consumption. Increasing focus on weight management and healthier eating can reduce demand for conventional high-sugar products. This is pressuring manufacturers to develop reduced-sugar, portion-controlled, dark, and functional chocolate alternatives to sustain market growth.
Market Opportunities
- Functional and Fortified Chocolate Innovation: Growing consumer interest in health-oriented indulgence is creating opportunities for functional and fortified chocolate products in Australia. Manufacturers can incorporate ingredients such as protein, fiber, vitamins, minerals, probiotics, and plant-based functional compounds to enhance nutritional value. This allows brands to target wellness-focused consumers while maintaining chocolate’s indulgent appeal. The trend also supports premium pricing and differentiation across snacks, sports nutrition, and better-for-you confectionery segments.
- Indigenous Australian Ingredient Chocolate as Export and Tourism Product: Using native Australian ingredients such as wattle seed, macadamia, lemon myrtle, and native fruits in chocolate creates opportunities for distinctive premium products. These formulations can appeal to tourists and international consumers seeking authentic Australian flavors and provenance. Premium positioning can support higher margins, while export channels can expand the global reach of Australian specialty chocolate brands.
Market Challenges
- Intense Competition and Private-Label Expansion: The market faces strong competition among multinational brands, domestic producers, premium chocolatiers, and supermarket private labels. Price competition can pressure margins, while smaller brands must invest in differentiation, branding, and innovation to maintain visibility.
- Climate and Temperature-Sensitive Distribution: Australia’s warm climate creates challenges for chocolate storage and transportation because products are sensitive to high temperatures. Manufacturers and retailers require effective temperature-controlled logistics and warehousing to prevent melting, blooming, and quality deterioration.
Emerging Market Trends
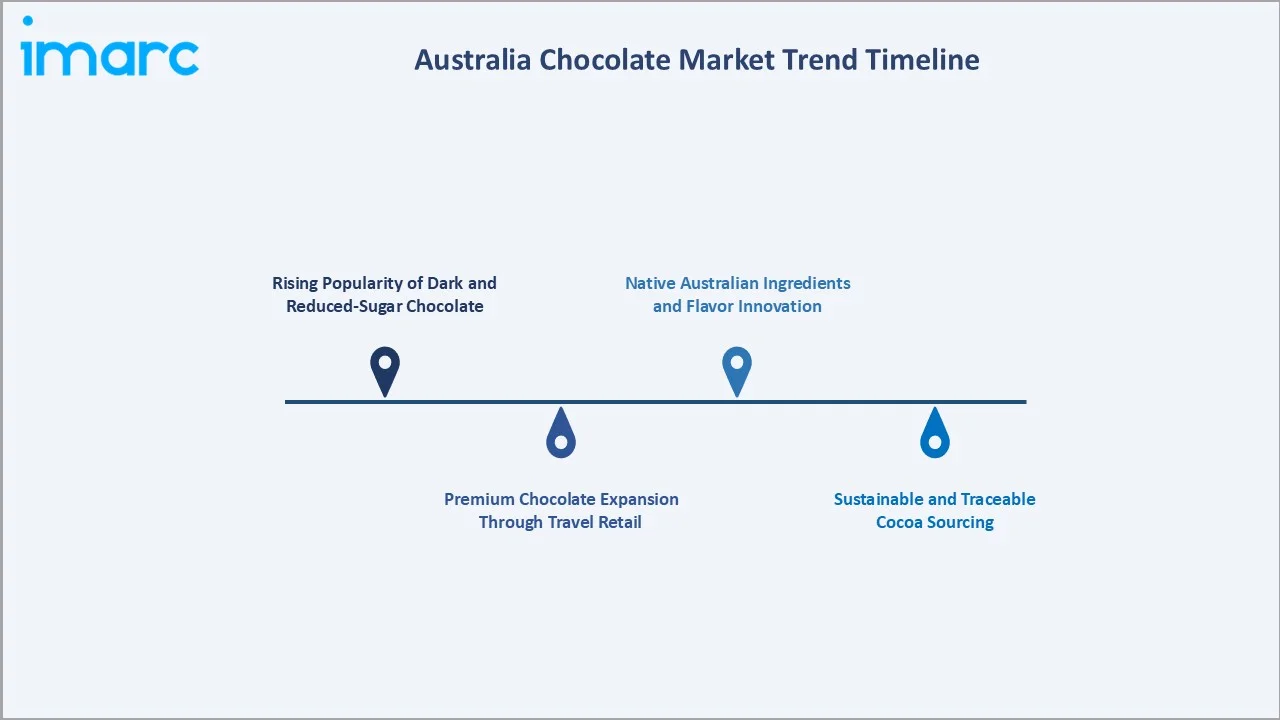
1. Rising Popularity of Dark and Reduced-Sugar Chocolate
Health-conscious consumers are showing greater interest in dark chocolate, reduced-sugar formulations, and portion-controlled products. Higher cocoa-content products are increasingly positioned as premium alternatives to conventional confectionery. Manufacturers are also exploring natural sweeteners and reformulation technologies to reduce added sugar. Maintaining taste and texture remains central to successful product development. This trend is expanding into the better-for-you chocolate category.
2. Premium Chocolate Expansion Through Travel Retail
In July 2026, Läderach entered the Australian market by opening a chocolaterie at Sydney Airport (Kingsford Smith Airport). Located in the airport’s airside area, the launch strengthens the Swiss chocolatier’s international expansion and introduces its premium chocolate offerings to Australian consumers and international travelers. This launch highlights the growing trend of premium international chocolate brands entering high-traffic travel retail locations. Airports provide access to both domestic and international consumers, supporting brand visibility, premium gifting, and impulse purchases.
3. Sustainable and Traceable Cocoa Sourcing
Sustainability is becoming increasingly important in cocoa procurement and chocolate branding. Companies are emphasizing responsibly sourced cocoa, supply-chain traceability, recyclable packaging, and ethical sourcing practices. Consumers are becoming more attentive to the environmental and social impacts associated with chocolate production. Certifications and transparent sourcing claims can strengthen brand differentiation. This trend is influencing both premium and mainstream chocolate portfolios.
4. Native Australian Ingredients and Flavor Innovation
Chocolate manufacturers are increasingly experimenting with native ingredients such as wattleseed, macadamia, lemon myrtle, finger lime, and native berries. These ingredients create distinctive flavor combinations and strengthen Australian product identity. Such offerings can attract consumers seeking novel and locally inspired experiences. They also provide opportunities in premium gifting and tourism channels. Flavor innovation is therefore becoming an important differentiation strategy.
Industry Value Chain Analysis
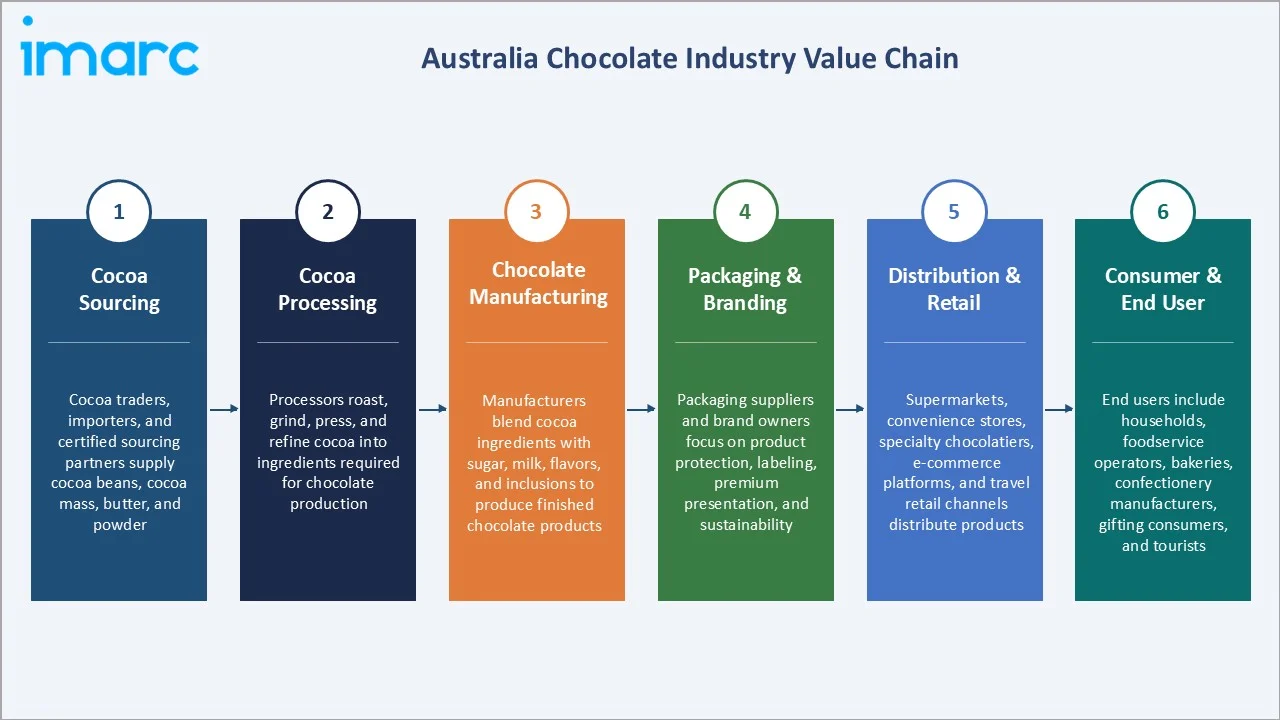
Australia chocolate value chain integrates cocoa sourcing from Pacific and African origins, domestic and international chocolate manufacturing, quality and sustainability certification, brand-differentiated packaging, multi-channel retail distribution, and consumer engagement, creating a complex supply chain that simultaneously manages commodity risk, sustainability obligation, and consumer experience delivery.
|
Stage |
Key Participants |
|
Cocoa Sourcing |
Cocoa traders, importers, and certified sourcing partners supply cocoa beans, cocoa mass, butter, and powder. |
|
Cocoa Processing |
Processors roast, grind, press, and refine cocoa into ingredients required for chocolate production. |
|
Chocolate Manufacturing |
Manufacturers blend cocoa ingredients with sugar, milk, flavors, and inclusions to produce finished chocolate products. |
|
Packaging & Branding |
Packaging suppliers and brand owners focus on product protection, labeling, premium presentation, and sustainability. |
|
Distribution & Retail |
Supermarkets, convenience stores, specialty chocolatiers, e-commerce platforms, and travel retail channels distribute products. |
|
Consumer & End User |
End users include households, foodservice operators, bakeries, confectionery manufacturers, gifting consumers, and tourists. |
Chocolate manufacturing is the most value-added stage in the Australia chocolate market, as it transforms cocoa ingredients into differentiated products through formulation, flavor innovation, and premiumization. Manufacturers can generate higher margins through artisanal, functional, vegan, dark, and specialty chocolate offerings.
Technology Landscape in the Australia Chocolate Industry
Advanced Tempering and Conching Technology
Modern tempering systems precisely control chocolate temperature to achieve the desired gloss, texture, snap, and shelf stability. Advanced conching equipment improves flavor development and creates smoother chocolate by controlling mixing, aeration, and temperature. Automated systems enable manufacturers to maintain consistent quality across production batches. Energy-efficient equipment can also reduce processing time and operating costs. These technologies are important for both mass-market and premium chocolate production.
Automated Molding and Enrobing Technology
Automated molding systems enable high-speed production of chocolate bars, pralines, blocks, and filled products with consistent shapes and weights. Enrobing technology applies uniform chocolate coatings to biscuits, nuts, confectionery, and snack products. Integrated cooling tunnels improve product setting and production efficiency. Automation reduces manual handling and improves manufacturing consistency. Flexible production lines also enable manufacturers to introduce new formats and seasonal products.
Sustainable and Smart Packaging Technology
Packaging innovation is increasingly focused on recyclable, lightweight, paper-based, and reduced-plastic solutions for chocolate products. Improved barrier technologies help protect chocolate from moisture, oxygen, heat, and flavor deterioration while reducing packaging material use. Digital printing enables customized, seasonal, and premium packaging designs. Smart labeling can also provide consumers with sourcing and product information. These technologies support sustainability goals while strengthening brand differentiation.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Type |
🔒 |
🔒 |
2025 |
|
Product Form |
🔒 |
🔒 |
2025 |
|
Application |
Food Products |
74.0% |
2025 |
|
Pricing |
Everyday Chocolate |
61.0% |
2025 |
|
Distribution |
🔒 |
🔒 |
2025 |
|
Region |
Australia Capital Territory & New South Wales |
34.0% |
2025 |

By Application
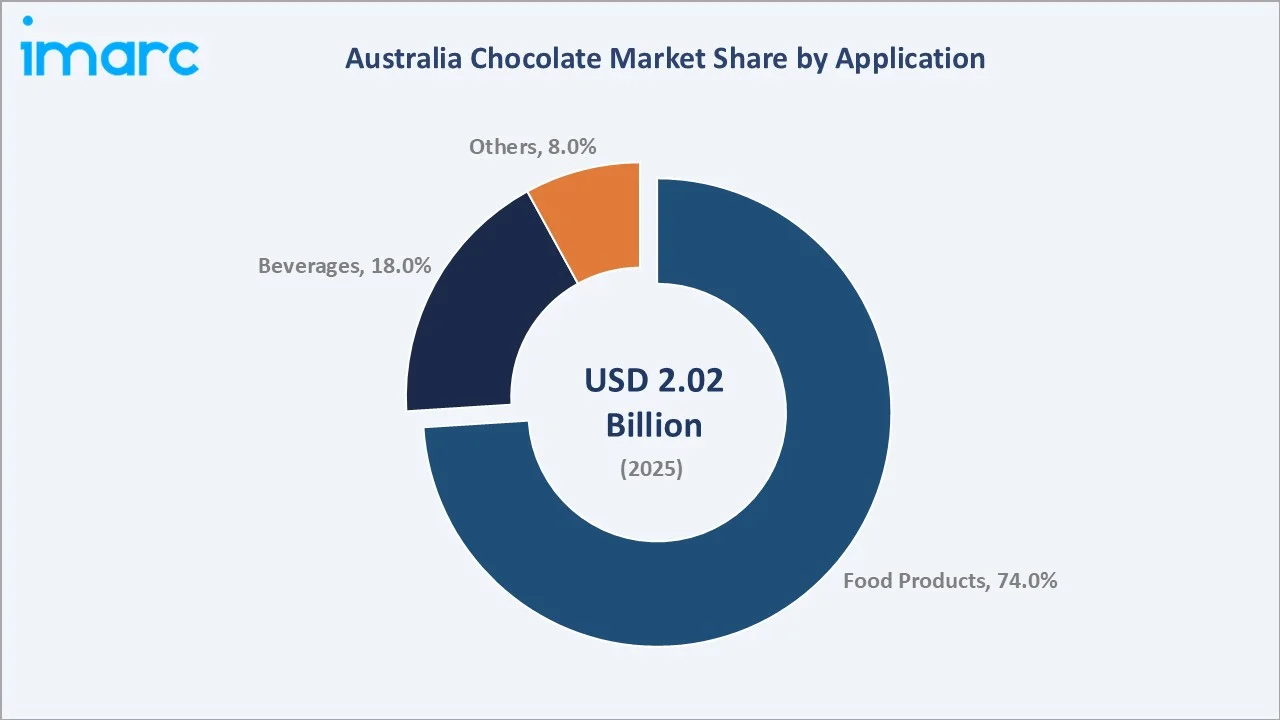
Food products lead at 74.0% (2025) through chocolate’s essential role as a baking and confectionery ingredient, with a dominant share reflecting chocolate’s pervasiveness across bakery, sugar confectionery, and dessert applications.
To access detailed market analysis, Request Sample
Beverages at 18.0% are growing at ~5.20% CAGR through café hot chocolate premiumization and functional chocolate beverages. Others at 8.0% encompass cosmetic applications, chocolate liqueurs, and specialty foodservice formats.
By Pricing
Everyday chocolate leads at 61.0% (2025) through Cadbury, KitKat, and Mars’ mass-market dominance in supermarket confectionery.
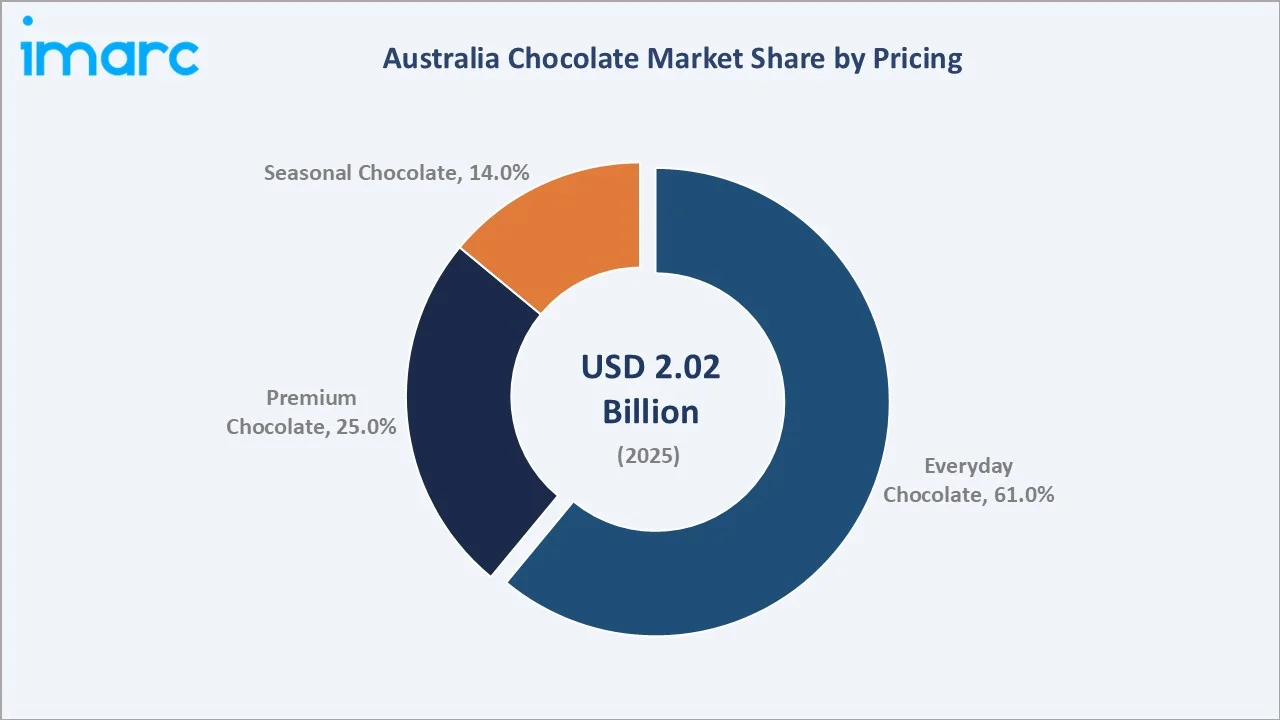
Premium chocolate at 25.0% grows fastest at ~6.80% CAGR through artisan, dark, and single-origin chocolate trade-up. Seasonal chocolate at 14.0% grows at ~5.50% CAGR through the progressive expansion of Australia’s gifting calendar value and per-occasion spending.
Regional Market Insights
|
Region |
Share (2025) |
Key Chocolate Market Drivers & Characteristics |
|
Australia Capital Territory & New South Wales |
34.0% |
Leads due to high population concentration, strong disposable incomes, premium chocolate demand, and extensive retail networks. |
|
Victoria & Tasmania |
25.0% |
Supported by a strong café culture, specialty chocolatiers, tourism, and growing demand for premium and artisanal products. |
|
Queensland |
21.0% |
Driven by population growth, tourism, expanding retail channels, and demand for confectionery and gifting products. |
|
Western Australia |
13.0% |
Benefits from high household spending, urban consumption, specialty retail, and increasing premium chocolate preferences. |
|
Northern Territory & Southern Australia |
7.0% |
Demand is supported by tourism, supermarkets, local specialty producers, and steady household chocolate consumption. |
The Australia Capital Territory & New South Wales region leads with a 34.0% share in 2025, supported by high population density, high disposable incomes, and extensive retail penetration. Victoria & Tasmania account for 25.0%, driven by café culture, specialty chocolatiers, tourism, and premium chocolate consumption. Queensland holds 21.0%, supported by population growth, tourism, gifting demand, and expanding supermarket networks.
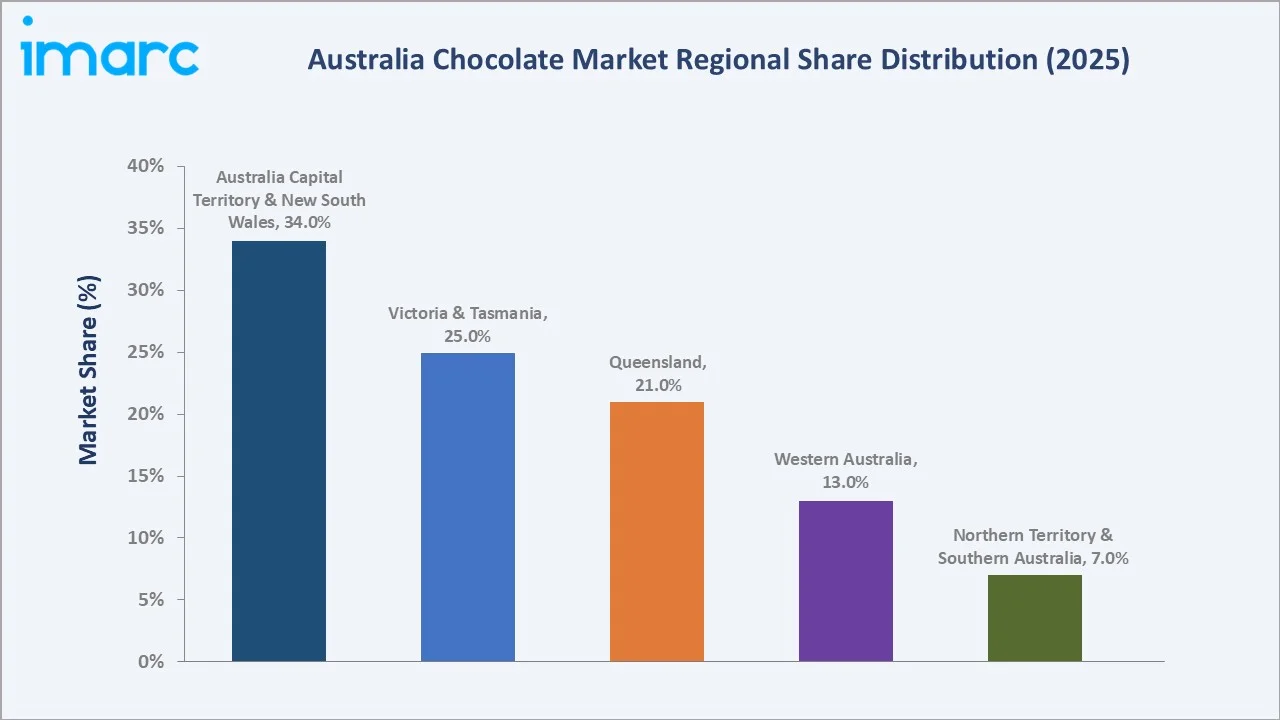
Western Australia represents 13.0%, benefiting from high household spending and growing demand for premium and specialty chocolates. Northern Territory & Southern Australia account for 7.0%, supported by tourism, local retail channels, and steady household consumption.
Competitive Landscape
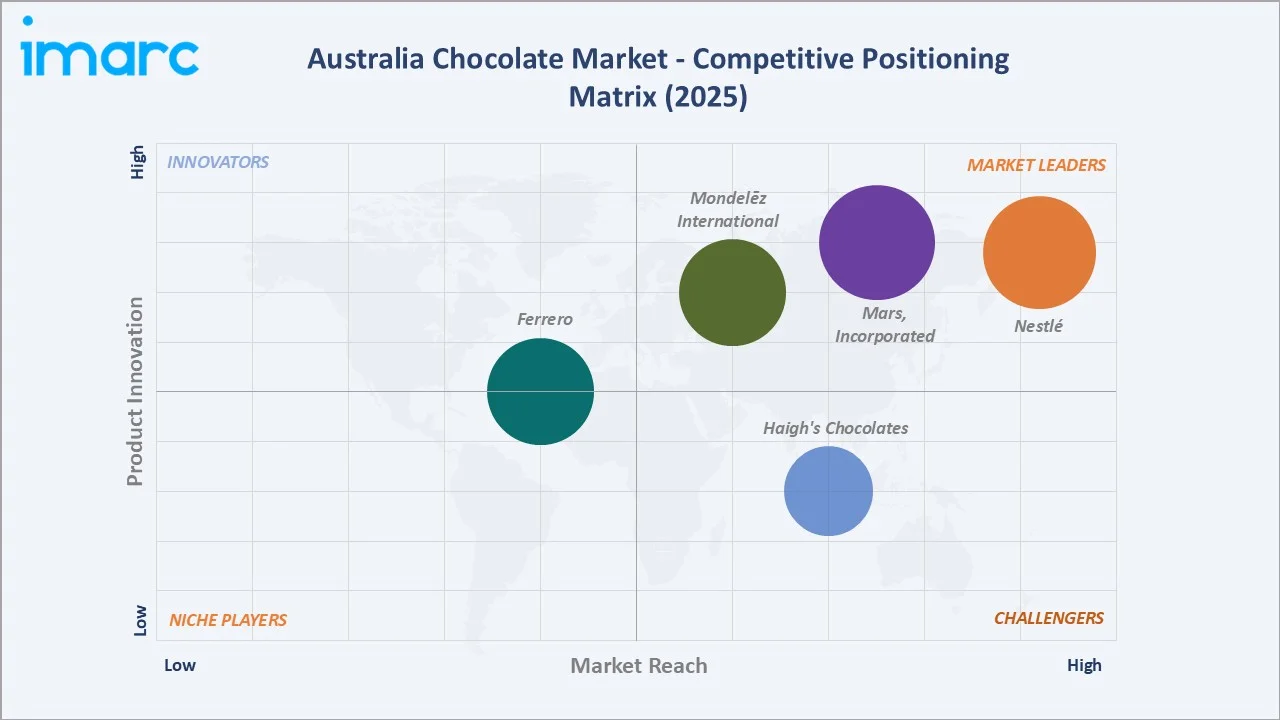
The Australia chocolate market is moderately consolidated, with multinational confectionery companies competing alongside established domestic brands, artisanal chocolatiers, and private-label producers. Competition is driven by brand recognition, product innovation, premiumization, pricing, distribution reach, and growing demand for sustainable, vegan, and better-for-you chocolates.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
Mondelēz International |
CADBURY, CADBURY DAIRY MILK, CÔTE D'OR, MILKA, TOBLERONE |
Market Leader |
Mondelēz International dominates the Australian chocolate market. It owns iconic household brands like Cadbury, Toblerone, and others. |
|
Nestlé |
KitKat, Smarties, Aero, Milkybar, Baci Perugina |
Market Leader |
Nestlé Australia operates manufacturing facilities locally while heavily focusing on sustainable cocoa sourcing and reducing plastic packaging. |
|
Mars, Incorporated |
M&M'S, MARS, BOUNTY, CELEBRATIONS, GALAXY, MILKY WAY, SNICKERS |
Market Leader |
Mars, Incorporated plays a dominant role in the country's chocolate market by manufacturing, innovating, and distributing iconic sweets. |
|
Ferrero |
Kinder, Ferrero Rocher |
Established Player |
Ferrero is a major player in the Australian chocolate and confectionery market, acting as one of the top-selling brand families and a significant local manufacturer. |
|
Haigh's Chocolates |
Haigh's Chocolates |
Challenger |
Haigh's Chocolates holds a significant role in the Australian chocolate industry as the country's oldest family-owned, bean-to-bar chocolate maker. |
Australia chocolate competitive landscape is defined by the coexistence of three distinct competitive tiers: the multinational volume leaders competing on distribution breadth, marketing spend, and supermarket category management; the premium specialist segment competing on quality, provenance, and retail experience; and the artisan innovators competing on authenticity, indigenous ingredients, and tourism-integrated direct retail.
Key Company Profiles
Mondelēz International
Mondelēz International is one of Australia’s largest food manufacturers, with local heritage supporting research, manufacturing, marketing, and distribution activities. Within the Australia chocolate market, Mondelēz has a strong presence through Cadbury, including Cadbury Dairy Milk and other products. Australia is one of Cadbury’s top global markets, while local manufacturing, established retail distribution, product innovation, and strong brand recognition reinforce Mondelēz’s position in the Australian chocolate industry.
- Key Brands: CADBURY, CADBURY DAIRY MILK, CÔTE D'OR, MILKA, TOBLERONE.
- Strategic Focus: Strengthening Cadbury through product innovation, premium indulgence, local manufacturing, and broad distribution capabilities. Recent initiatives include new Cadbury product launches and investment in its highly automated distribution center to improve supply-chain efficiency.
Nestlé
Nestlé operates across multiple food and beverage categories and is supported by manufacturing, distribution, and retail capabilities throughout Australia. Within the Australia chocolate market, Nestlé offers a broad confectionery portfolio through brands such as KITKAT, AERO, SMARTIES, MILKYBAR, and others. Its established brand portfolio, broad retail availability, product innovation, and presence across mainstream and premium chocolate categories support its competitive position in the Australian market.
- Key Brands: KitKat, Smarties, Aero, Milkybar, Baci Perugina.
- Strategic Focus: Focuses on product innovation, premiumization, local manufacturing, and sustainable chocolate production, particularly through its KitKat portfolio. Nestlé also emphasizes sustainable cocoa sourcing and packaging innovation, alongside frequent product launches and brand collaborations to respond to evolving Australian consumer preferences.
Market Concentration Analysis
The Australia chocolate market is moderately consolidated, with a few large multinational companies holding strong positions alongside domestic brands and artisanal chocolatiers. Leading players benefit from established brand portfolios, extensive retail distribution, large-scale manufacturing, and strong marketing capabilities. Competition is also increasing from premium, organic, vegan, and specialty chocolate producers targeting niche consumer segments. Private-label products further intensify price competition across supermarkets and mass retail channels. Product innovation, sustainable sourcing, premiumization, and flavor differentiation are becoming key competitive strategies. Overall, the market combines strong brand concentration at the top with a diverse base of smaller specialty producers.
Investment & Growth Opportunities
Highest Growth Segments
Premium chocolate (~6.80% CAGR) and seasonal chocolate (~5.50% CAGR) represent Australia’s highest-growth chocolate market investment opportunities through 2034, driven by artisan trade-up, dark chocolate health positioning, and gifting occasion premiumization, respectively.
Investment Themes
- Functional Chocolate Platform: Investment in a functional chocolate platform can support products fortified with protein, fiber, vitamins, minerals, probiotics, and other wellness-oriented ingredients. This creates opportunities to target health-conscious consumers, premium snacking occasions, and better-for-you confectionery segments in Australia.
- Indigenous Ingredient Chocolate Export Development: Investment in chocolates featuring native Australian ingredients such as wattleseed, macadamia, lemon myrtle, and finger lime can create distinctive premium export products. Strong provenance and unique flavor profiles can support tourism demand, gifting, and international positioning of Australian specialty chocolate brands.
Future Market Outlook (2026-2034)
The Australia chocolate market is projected to grow from USD 2.02 Billion in 2025 to USD 3.18 Billion by 2034, delivering a robust 5.02% CAGR that positions Australia’s chocolate sector as one of the Asia-Pacific region’s most valuable and structurally resilient confectionery growth markets, sustained by three mutually reinforcing structural forces whose combined momentum creates a compound growth trajectory of compelling consistency. The midpoint anchor of USD 2.58 Billion in 2030 confirms the structural stability of Australia’s chocolate demand growth across economic cycles.
First, Australia’s premiumization imperative, where the chocolate market’s value growth consistently outpaces volume growth as consumers trade up from everyday mainstream chocolate to premium, artisan, and functional formats, will intensify through 2034 as four concurrent premium drivers compound simultaneously. Second, Australia’s seasonal chocolate market’s progressive value expansion, where per-occasion gift spending increases, the number of culturally recognized gifting occasions grows through Australia’s multicultural population, and experiential chocolate creates new seasonal revenue streams, will sustain the seasonal segment’s growth through the forecast period. Third, Australia’s retail channel transformation, through e-commerce growth, specialty food retail expansion, and DTC subscription models, creates structurally higher average selling prices for chocolate distribution outside the mass supermarket channel’s price competition dynamics.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with Australian chocolate producers, including production directors, category buyers at confectionery procurement, specialty food retailers, Australian chocolate industry associations, and premium chocolate consumer focus groups across Sydney, Melbourne, Brisbane, and Perth.
Secondary Research
Secondary research encompassed government publications, industry reports, trade databases, company annual reports, regulatory sources, and industry associations. The analysis also assessed consumer preferences, chocolate consumption trends, product innovations, retail developments, cocoa sourcing, and competitive dynamics across Australia.
Forecasting Models
Forecasting models developed using historical Australia chocolate market data (2020-2025), Australian household disposable income trajectory, premium confectionery category growth rate benchmarking against UK and European market precedents, e-commerce food retail growth trajectory aligned to digital commerce data, cocoa price scenario modeling, artisan chocolate producer capacity expansion pipeline, Easter and seasonal chocolate retail sales trend extrapolation, and rating policy impact on product reformulation timeline.
Australia Chocolate Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | White Chocolate, Milk Chocolate, Dark Chocolate, Others |
| Product Forms Covered | Molded, Countlines, Others |
| Applications Covered |
|
| Pricings Covered | Everyday Chocolate, Premium Chocolate, Seasonal Chocolate |
| Distributions Covered | Direct Sales (B2B), Supermarkets and Hypermarkets, Convenience Stores, Online Stores, Others |
| Regions Covered | Australian Capital Territory & New South Wales, Victoria & Tasmania, Queensland, Northern Territory & South Australia, Western Australia |
| Companies Covered | Mondelēz International, Nestlé, Mars, Incorporated, Ferrero, Haigh's Chocolates, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Australia chocolate market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Australia chocolate market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Australia chocolate industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Australia Chocolate Market Report
The Australia chocolate market reached USD 2.02 Billion in 2025, driven by high per-capita chocolate consumption, strong demand for premium and artisanal products, and extensive retail availability. Growing interest in dark, vegan, functional, and sustainably sourced chocolates further supported market expansion.
The market grows at a 5.02% CAGR, reaching USD 3.18 Billion by 2034, supported by premiumization, product innovation, expanding vegan and functional chocolate segments, and rising demand for sustainable and specialty products.
Food products lead at 74.0% (2025) through chocolate’s foundational role in bakery, sugar confectionery, and dessert applications across Australia’s cafés and restaurants.
Everyday chocolate leads at 61.0% (2025) through Cadbury, KitKat, and Mars’ supermarket confectionery dominance as habitual weekly basket inclusions.
Australia Capital Territory & New South Wales lead at 34.0% through Australia’s most populous state and highest financial services income concentration in Sydney’s CBD, driving premium chocolate spend.
Leading companies include Mondelēz International, Nestlé, Mars, Incorporated, Ferrero, and Haigh's Chocolates, among others.
The market is projected to reach USD 2.58 Billion by 2030, driven by rising demand for premium, artisanal, vegan, dark, and functional chocolates. Expanding retail channels, product innovation, gifting occasions, and growing preference for sustainably sourced products are also supporting market growth.
Top investment opportunities include a functional chocolate platform, indigenous botanical chocolate export, bean-to-bar Pacific-origin chocolate, a premium chocolate subscription DTC, and a corporate gifting premium platform.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade