
Australia Environmental Consulting Services Market Size, Share, Trends and Forecast by Service, Medium Technology, Vertical, and Region, 2026-2034
Australia Environmental Consulting Services Market Size, Share, Trends & Forecast (2026-2034)
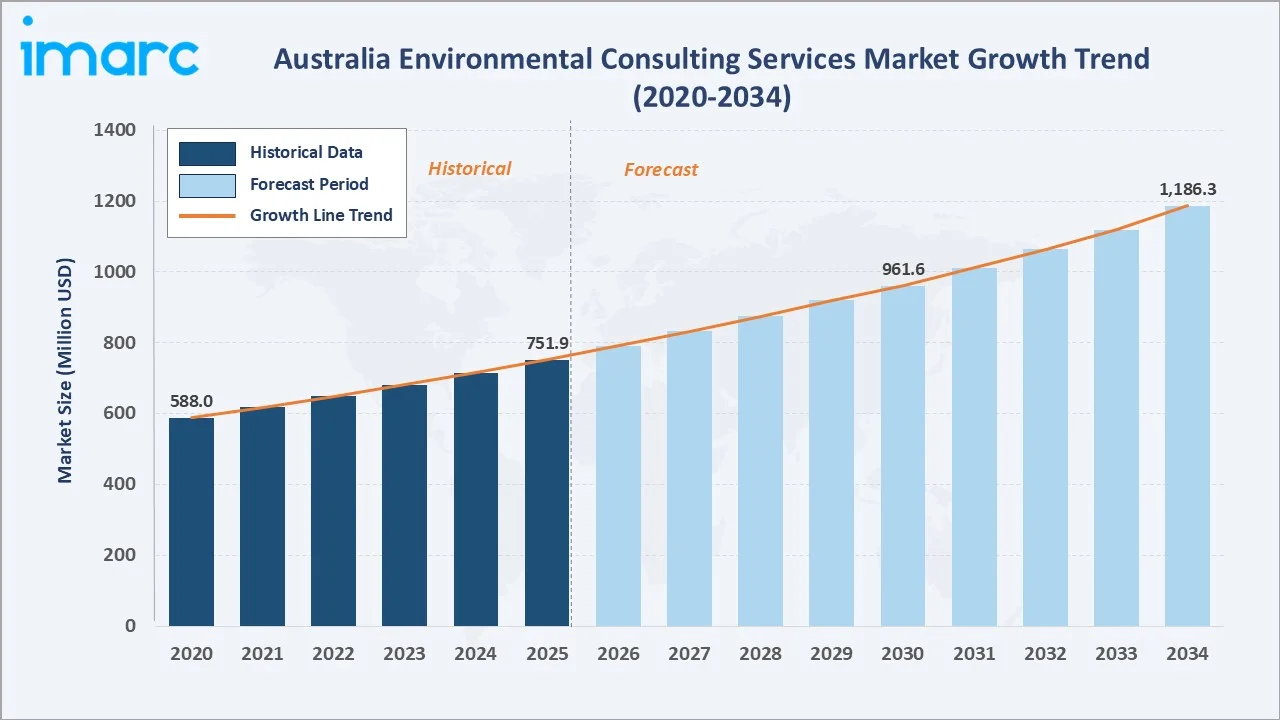
The Australia environmental consulting services market grew from USD 751.9 Million in 2025 to USD 789.8 Million in 2026 and is projected to reach USD 1,186.3 Million by 2034, growing at a CAGR of 5.04% during 2026-2034. The market is driven by tightening environmental regulations, Australia's commitment to a 62-70% reduction in emissions below 2005 levels by 2035, and surging demand for environmental impact assessments across the renewable energy, infrastructure, and resource sectors. Water management leads at 58.6% by medium, energy and utilities dominate at 28.7% by vertical, and the Australia Capital Territory and New South Wales command the largest regional share at 31.5% in 2025.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 751.9 Million |
|
Market Size (2026) |
USD 789.8 Million |
|
Forecast Market Size (2034) |
USD 1,186.3 Million |
|
CAGR (2026-2034) |
5.04% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Medium |
Water Management (58.6%, 2025) |
|
Dominant Vertical |
Energy and Utilities (28.7%, 2025) |
|
Leading Region |
ACT & NSW (31.5%, 2025) |
The Australia environmental consulting services market grew from USD 588.0 Million in 2020 to USD 751.9 Million in 2025, and further to USD 789.8 Million in 2026, reflecting sustained demand from infrastructure development, renewable energy project assessments, corporate ESG reporting, and government-driven environmental compliance programs. The market is projected to reach USD 961.6 Million by 2030 before reaching USD 1,186.3 Million by 2034.
To get more information on this market, Request Sample
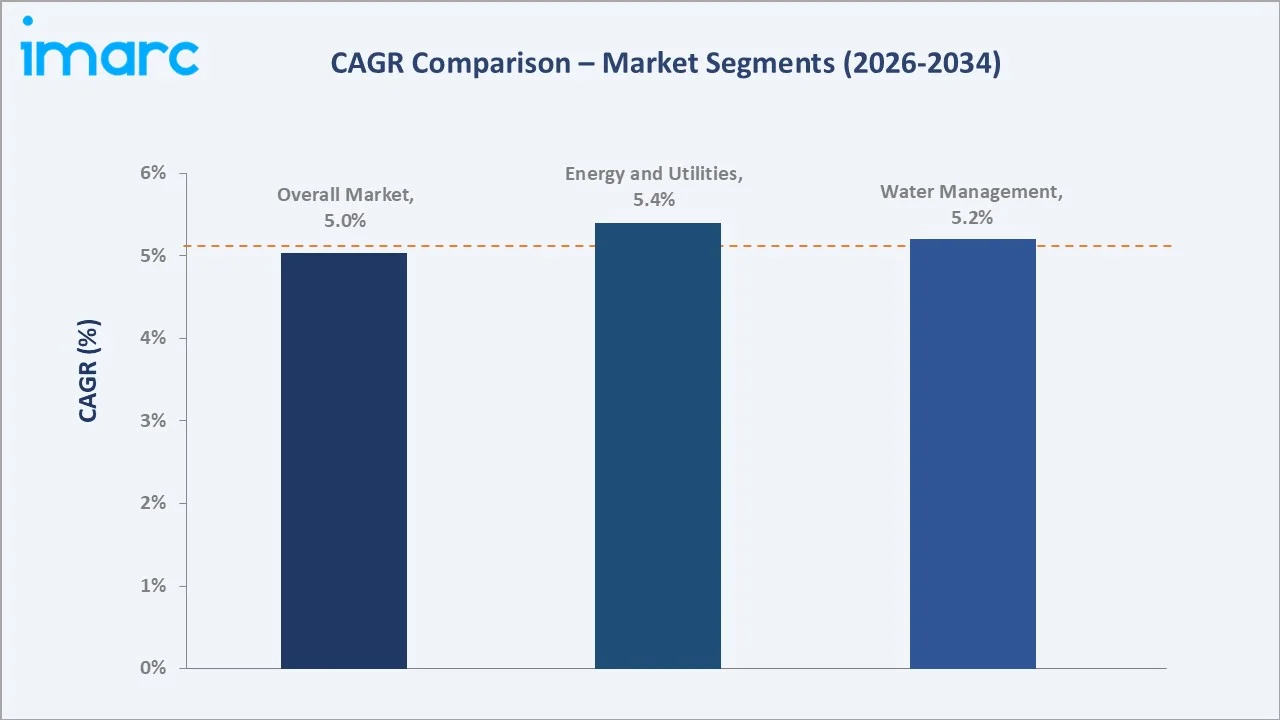
Water management consulting is projected to grow at a 5.2% CAGR, driven by Australia National Water Grid investment and urban water security challenges. The energy and utilities vertical at 5.4% CAGR reflects the environmental assessment and compliance demand from Australia renewable energy transition programs. The overall market CAGR of 5.04% reflects the structural shift toward mandatory environmental disclosure and sustainability integration across all major Australian industries.
Executive Summary
The Australia environmental consulting services market is on a sustained growth trajectory, driven by the convergence of tightening federal and state environmental regulations, Australia's ambitious emissions reduction targets, and growing corporate demand for ESG compliance and sustainability reporting services. The market has expanded consistently, supported by a large-scale infrastructure investment pipeline, the transition of the energy sector away from coal toward renewables, and progressive strengthening of environmental disclosure requirements.
Water management leads at 58.6%, reflecting the primacy of water quality, water security, and wastewater management as Australia most critical environmental challenges across both urban and regional contexts. Energy and utilities at 28.7% is the dominant vertical, driven by the environmental impact assessment requirements of renewable energy projects, including offshore wind, large-scale solar, and pumped hydro installations that are transforming Australia electricity generation landscape. Australia Capital Territory & New South Wales lead regionally at 31.5%, hosting the federal government policy apparatus and the largest concentration of major corporate headquarters that generate demand for compliance, ESG advisory, and environmental management services.
Key Market Insights
|
Insight |
Data |
|
Dominant Medium |
Water Management - 58.6% share (2025) |
|
Dominant Vertical |
Energy and Utilities - 28.7% share (2025) |
|
Leading Region |
Australia Capital Territory & New South Wales - 31.5% (2025) |
|
Key Market Opportunity |
Growing demand for environmental compliance, climate-risk assessment, renewable energy projects, biodiversity management, and sustainable infrastructure development is creating opportunities for environmental consulting firms across Australia. |
Key Analytical Observations Supporting the Above Data:
- Water Management at 58.6%: Water management consulting dominates because water security is Australia most significant and politically prominent environmental challenge, spanning urban water supply security in a drought-prone climate, water quality protection, coastal water management, and industrial wastewater treatment for mining and energy operations.
- Energy and Utilities at 28.7%: Energy and utilities lead verticals because Australia renewable energy transition is generating the largest pipeline of environmental impact assessments in the country's history, with the funding of hundreds of solar, wind, offshore wind, and pumped hydro projects that each require extensive environmental assessment, native vegetation surveys, ecological impact assessment, and ongoing environmental management plans before and during construction.
- Australia Capital Territory & New South Wales at 31.5%: Australia Capital Territory & New South Wales leads because it combines the federal government as a major direct client of environmental consulting services with the largest concentration of ASX-listed corporate headquarters that are subject to sustainability disclosure requirements, and the most active infrastructure development pipeline across roads, rail, and urban development in Sydney and the ACT.
Australia Environmental Consulting Services Market Overview
The Australia environmental consulting services market provides professional advisory, assessment, management, and reporting services that help government agencies, corporations, and project developers understand, manage, and comply with environmental requirements. Core service categories include investment assessment and environmental impact assessment (EIA), environmental permitting and compliance support, project information and environmental management systems, environmental monitoring and testing, site contamination assessment and remediation, ecological and biodiversity assessment, water quality and hydrology services, air quality monitoring, waste management consulting, and ESG and sustainability advisory. The market serves a diverse client base spanning government infrastructure agencies, mining and resources companies, energy generators and utilities, construction and development companies, and ASX-listed corporations with mandatory sustainability reporting obligations.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
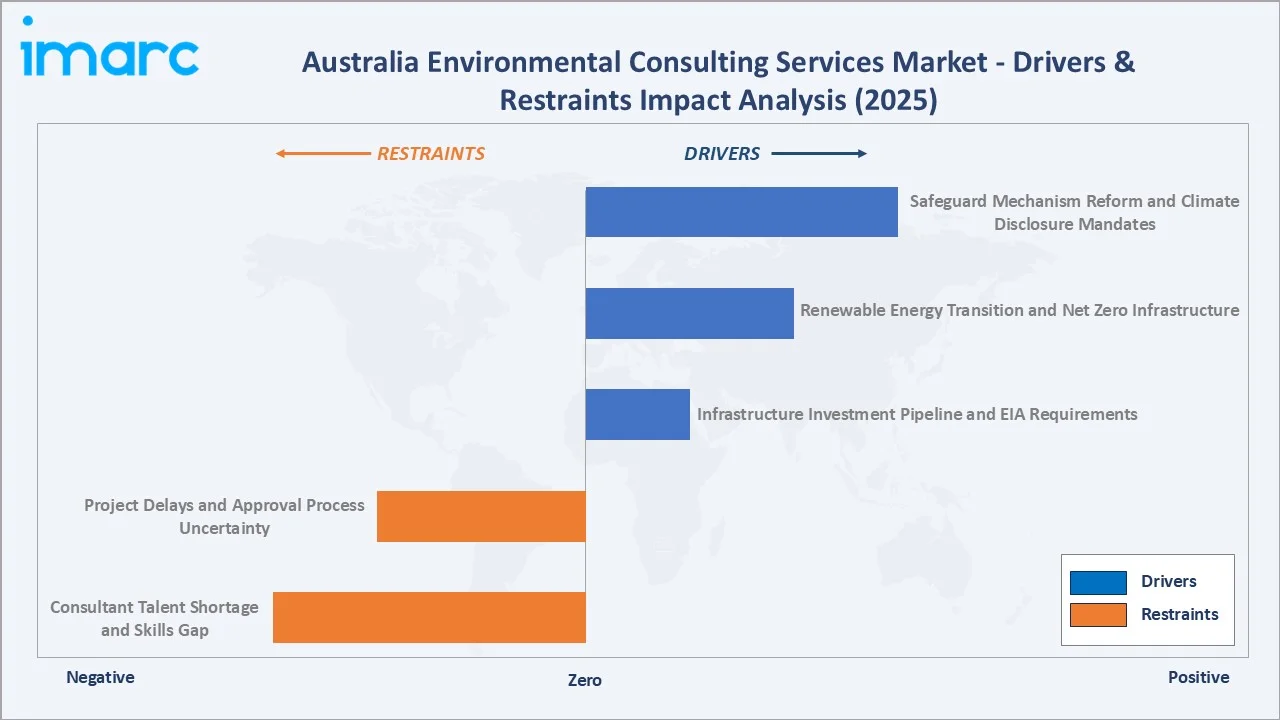
- Safeguard Mechanism Reform and Climate Disclosure Mandates: The reformed Australian Safeguard Mechanism helps achieve emission reduction targets of 43% below 2005 levels by 2030 and net zero by 2050 through declining baselines, creating significant and sustained demand for emissions reporting, abatement strategy, and decarbonization consulting services. Australia's emissions reduction target is driving government policy investment in environmental consulting expertise across multiple agencies and departments.
- Renewable Energy Transition and Net Zero Infrastructure: Australia transition from coal to renewable energy is generating one of the largest environmental impact assessment workloads in the market's history, with planning for an 82% renewable electricity target by 2030. Offshore wind zone assessments, large-scale solar and wind farm EIAs, pumped hydro feasibility studies, and transmission infrastructure environmental assessments are creating sustained multi-year project-based consulting demand that directly benefits major environmental consulting firms across energy transition advisory, ecological impact assessment, and environmental management planning.
- Infrastructure Investment Pipeline and EIA Requirements: Australia large infrastructure investment pipeline, including road, rail, ports, airports, and urban development projects across all states, generates mandatory EIA requirements under both the federal and state planning legislation. Major projects require extensive environmental consulting services for assessment, approval support, and ongoing environmental management.
Market Restraints
- Consultant Talent Shortage and Skills Gap: Australia environmental consulting market faces a significant and well-documented shortage of qualified environmental scientists, hydrogeologists, ecologists, and climate risk specialists, with experienced professionals in strong demand across both the consulting industry and the resource and energy sectors that compete for the same talent pool. This constraint limits the pace of market expansion despite strong demand and drives wage inflation that compresses consulting margins.
- Project Delays and Approval Process Uncertainty: Environmental consulting engagements tied to major project approvals are subject to regulatory timeline uncertainty, legal challenges from environmental groups, and community consultation requirements that can substantially extend project scope and duration. This uncertainty makes revenue forecasting challenging for environmental consulting firms and constrains investment in specialized service line capability development.
Market Opportunities
- Nature Positive Plan and Biodiversity Consulting Demand: Australia Nature Positive Plan and the adoption of the Taskforce on Nature-related Financial Disclosures (TNFD) framework by leading Australian companies are creating significant new demand for biodiversity assessment, ecosystem service valuation, and nature risk management consulting services that represent high-value, specialized engagements beyond traditional regulatory EIA work.
- Digital Environmental Monitoring and AI-Driven Assessment: Growing adoption of remote sensing, satellite-based monitoring, IoT environmental sensor networks, and AI-assisted EIA data analysis is creating new service delivery models that improve the speed and cost-effectiveness of environmental consulting engagements.
Market Challenges
- Competition from In-House Corporate Sustainability Teams: Growing investment by major Australian corporations in in-house sustainability and environmental management functions is partially displacing some categories of environmental consulting work, particularly for routine compliance monitoring and annual reporting that in-house teams increasingly handle without external consultant support.
- Fee Pressure from Government Procurement Frameworks: Government clients, which represent a significant portion of environmental consulting revenue, increasingly use panel contracts, lowest-cost-conforming procurement mechanisms, and fee benchmarking that constrain consulting fee rates and compress margins on publicly funded environmental consulting engagements, particularly for smaller regional projects.
Emerging Market Trends
1. Nature Positive Plan and Biodiversity Advisory Growth
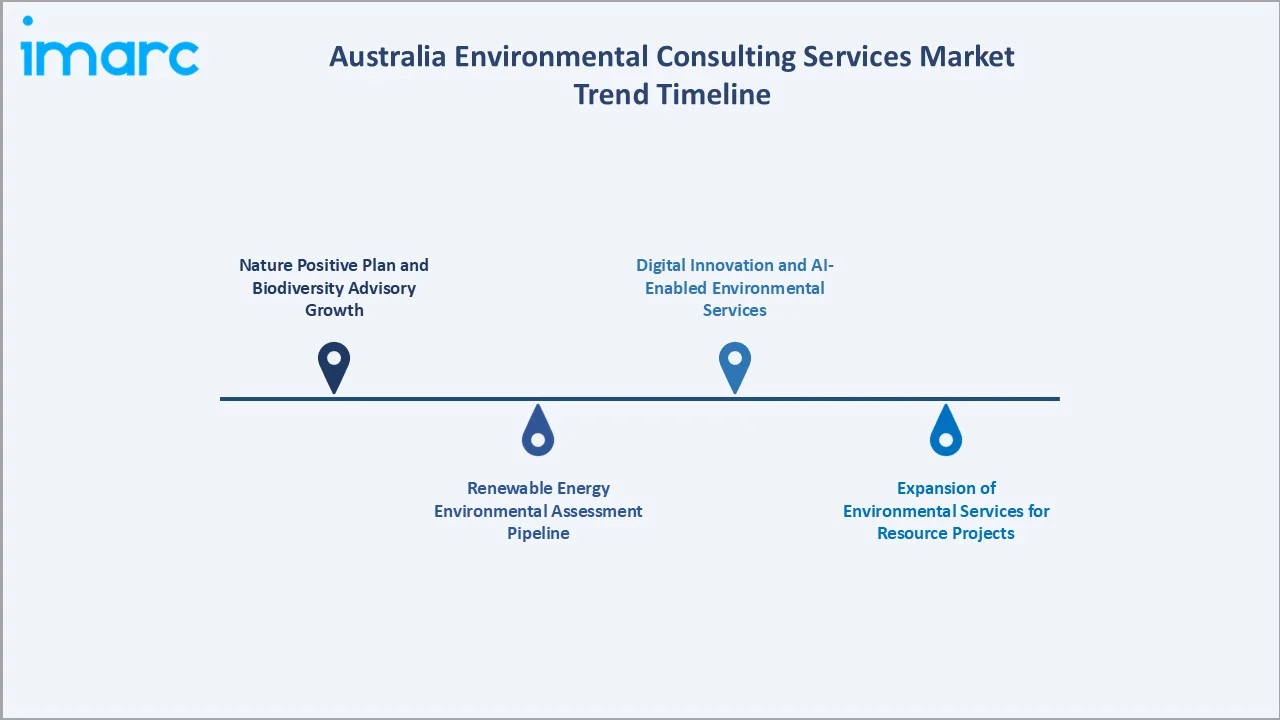
Australia’s Nature Positive Plan commitment to protect 30% of Australia’s land and seas by 2030 is establishing biodiversity and nature risk disclosure as the next major environmental compliance frontier after climate risk. This creates growing demand for ecological assessment, biodiversity offsetting strategy, natural capital valuation, and ecosystem service mapping that represents high-value, specialized environmental consulting work that significantly expands the addressable market beyond traditional compliance work.
2. Renewable Energy Environmental Assessment Pipeline
Australia's transition to 82% renewable electricity by 2030 is generating an unprecedented pipeline of offshore wind, large-scale solar, wind farm, and pumped hydro project environmental assessments. The offshore wind sector alone involves multiple zone declarations, each requiring extensive seabed surveys, marine ecology assessments, fisheries impact studies, and ongoing environmental management programs that represent multi-year consulting engagements for the environmental firms that win assessment mandates.
3. Digital Innovation and AI-Enabled Environmental Services
The adoption of AI, data analytics, remote sensing, and digital monitoring tools is transforming environmental consulting services in Australia. These technologies help consultants improve environmental impact assessments, identify risks, monitor ecosystems, and analyze large datasets more efficiently. Increasing use of digital solutions is also supporting faster decision-making, predictive environmental management, and cost-effective compliance monitoring.
4. Expansion of Environmental Services for Resource Projects
Increasing emphasis on environmental compliance, biodiversity protection, and science-based resource management is encouraging consolidation and capability expansion among consulting firms. In April 2025, APEM Group expanded its Australian operations through the acquisition of AARC Environmental Solutions, a leading provider of environmental and rehabilitation services for the resources sector. AARC delivers science- and data-driven environmental solutions across resources, critical minerals, and development projects in Australia and Asia. The acquisition highlights the growing demand for specialized environmental consulting and rehabilitation services linked to mining, critical minerals, and infrastructure development.
Industry Value Chain Analysis
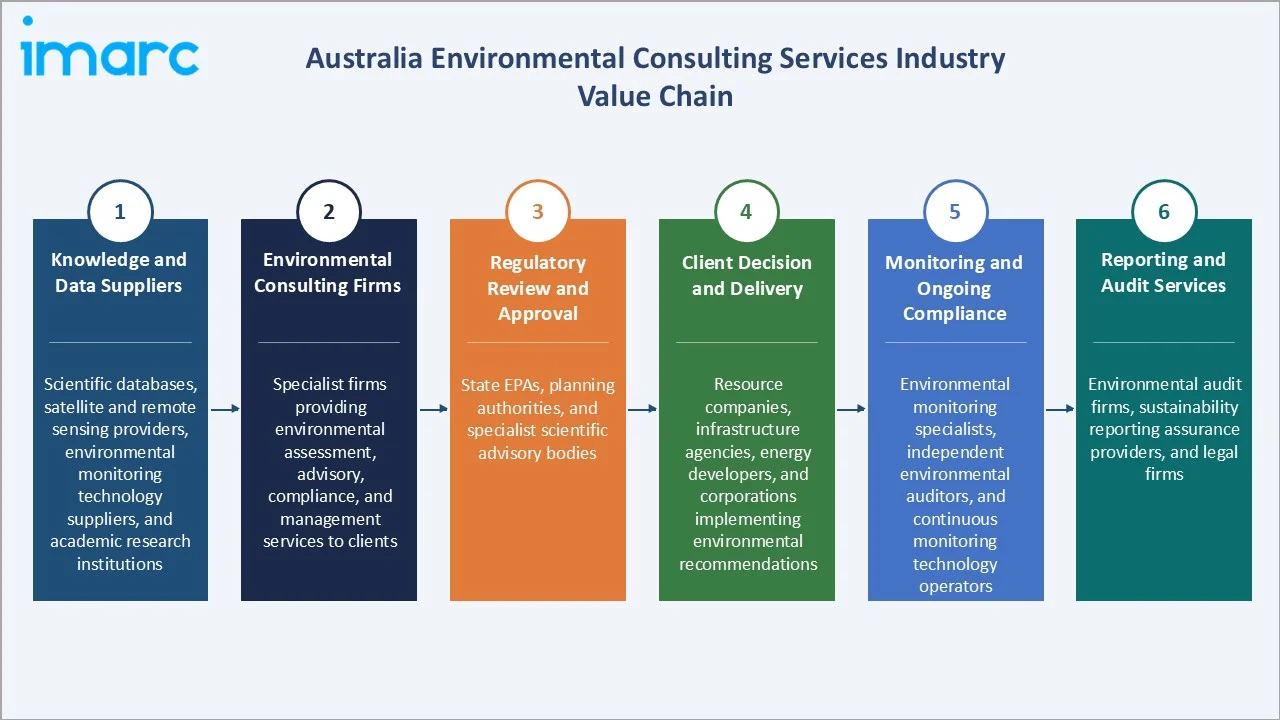
The Australia environmental consulting services value chain spans six integrated stages from knowledge and data provision through reporting and audit. The environmental consulting firm stage captures the highest value addition in the chain, as firms combine scientific expertise, regulatory knowledge, stakeholder engagement capability, and professional indemnity credentials to provide the integrated advisory, assessment, and management services that clients require to navigate complex environmental obligations.
|
Stage |
Key Participants |
|
Knowledge and Data Suppliers |
Scientific databases, satellite and remote sensing providers, environmental monitoring technology suppliers, and academic research institutions. |
|
Environmental Consulting Firms |
Specialist firms providing environmental assessment, advisory, compliance, and management services to clients. |
|
Regulatory Review and Approval |
State EPAs, planning authorities, and specialist scientific advisory bodies. |
|
Client Decision and Delivery |
Resource companies, infrastructure agencies, energy developers, and corporations implementing environmental recommendations. |
|
Monitoring and Ongoing Compliance |
Environmental monitoring specialists, independent environmental auditors, and continuous monitoring technology operators. |
|
Reporting and Audit Services |
Environmental audit firms, sustainability reporting assurance providers, and legal firms. |
The environmental consulting firm stage is the highest value-added stage in the value chain. Firms that combine deep scientific and regulatory expertise with strong stakeholder engagement and professional indemnity credentials command premium fees for complex EIA, contamination, and ESG advisory engagements that clients cannot easily substitute with internal resources or alternative service providers.
Technology Landscape in the Australia Environmental Consulting Services Industry
Remote Sensing and Satellite-Based Environmental Monitoring
Satellite-based multispectral and hyperspectral imaging is transforming ecological assessment and environmental monitoring by enabling rapid, low-cost vegetation mapping, water quality monitoring, land use change detection, and biodiversity habitat assessment at scales that ground-based survey methods cannot achieve cost-effectively. Environmental consultants are incorporating satellite time-series analysis into EIA baseline studies and ongoing environmental monitoring programs for major mining, energy, and infrastructure projects across Australia's geographically dispersed project locations.
Environmental Digital Twins and GIS-Based Decision Tools
Digital twin models of environmental systems, including catchment water quality models, coastal erosion prediction systems, and biodiversity habitat connectivity models, are enabling environmental consultants to provide clients with interactive decision-support tools that improve the quality of environmental management planning and enable real-time scenario testing for complex development decisions. These platforms create higher-value, longer-duration client relationships compared to one-time assessment projects.
ESG Data Management and Reporting Technology Platforms
The growing complexity of Scope 1-3 emissions measurement, supply chain ESG due diligence, and Australian Sustainability Reporting Standards compliance is driving adoption of ESG data management platforms that environmental consultants implement and configure for corporate clients. Sustainability and ESG disclosures remain a priority for many investors, with the market demonstrating that audit readiness, digital capabilities, and nature integration are among client priorities, creating sustainable demand for technology-enabled ESG consulting engagements.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Service |
🔒 |
🔒 |
2025 |
|
Medium |
Water Management |
58.6% |
2025 |
|
Vertical |
Energy and Utilities |
28.7% |
2025 |
|
Region |
Australia Capital Territory & New South Wales |
31.5% |
2025 |

By Medium
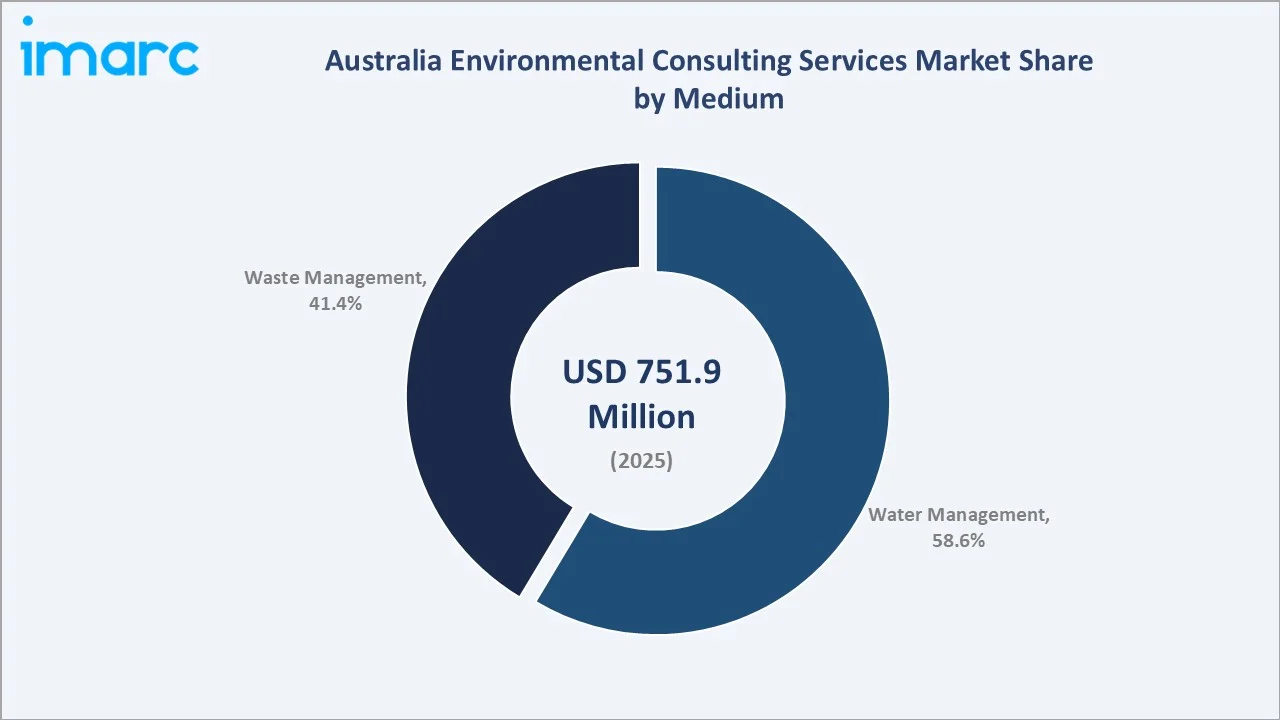
Water management leads at 58.6% in 2025, reflecting the pervasive and politically prominent role of water security, water quality, and water management in Australian environmental policy and project development. Waste management at 41.4% encompasses consulting services for solid waste facility design and planning, hazardous waste management, PFAS and contaminated land remediation, circular economy strategy, and waste-to-energy feasibility assessment.
To access detailed market analysis, Request Sample
By Vertical
Energy and utilities lead at 28.7% in 2025, driven by the environmental assessment and compliance requirements of Australia renewable energy transition. Wind farm, solar farm, offshore wind, pumped hydro, and energy transmission infrastructure projects each require extensive environmental impact assessment, ecological survey, and ongoing environmental management consulting services, creating a multi-year pipeline of consulting work that is driving above-market growth in this vertical.
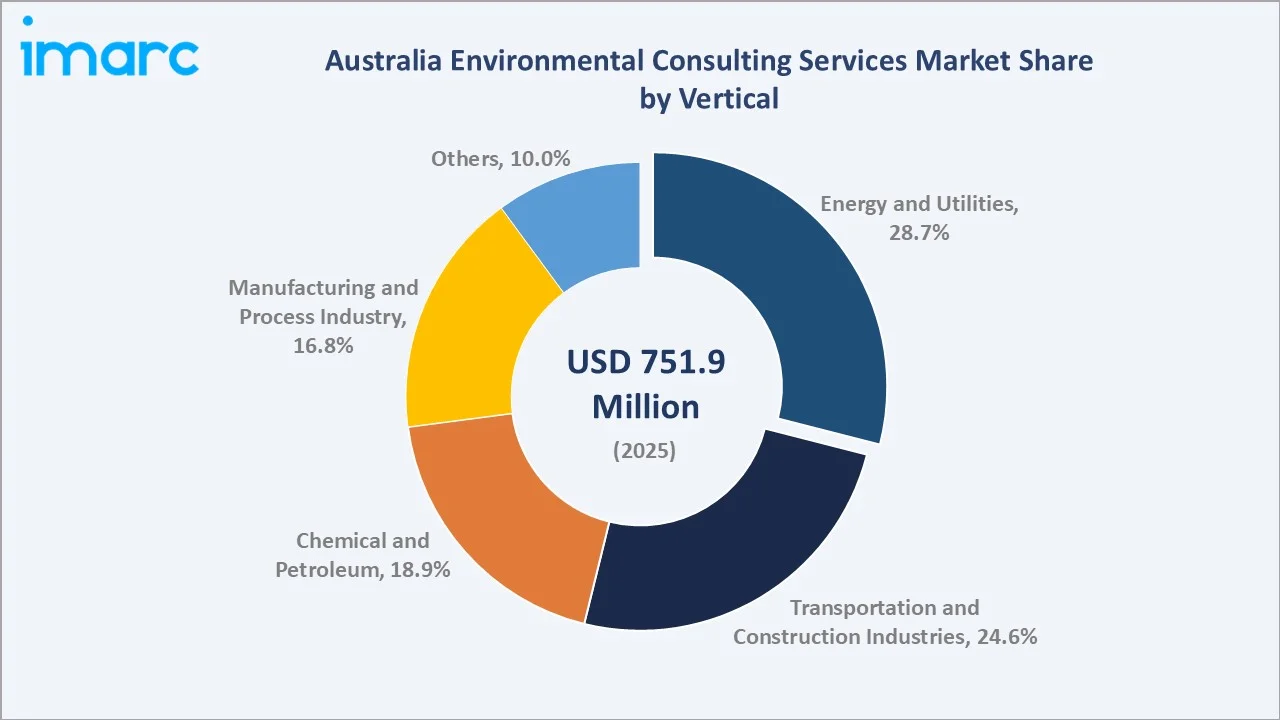
Transportation and construction industries at 24.6% reflect the active Australian infrastructure pipeline, with major road, rail, port, and urban development projects requiring environmental assessment, heritage management, biodiversity offsetting, and construction environmental management plan development. Chemical and petroleum at 18.9% serves the ongoing compliance, operational monitoring, and decommissioning consulting requirements of Australia oil, gas, and chemical industries. Manufacturing and process industry at 16.8% reflects industrial environmental management, air quality, and waste management consulting across Australia manufacturing base.
Regional Market Insights
|
Region |
Share (2025) |
Key Australia Environmental Consulting Services Market Drivers & Characteristics |
|
Australia Capital Territory & New South Wales |
31.5% |
Reflecting the federal government as a major environmental consulting client, the largest concentration of ASX corporate headquarters subject to sustainability disclosure, and the presence of leading firm headquarters that generate significant professional service activity in the region. |
|
Western Australia |
24.8% |
Reflecting the Western Australian resource sector as the most intensive generator of environmental consulting demand in Australia, with mine approvals, marine environment assessments for LNG and offshore operations, rehabilitation planning, and water management for resource projects creating sustained high-value consulting work across major firms. |
|
Queensland |
18.6% |
Reflecting Queensland agriculture, mining, and infrastructure development pipeline, the consulting requirements, major renewable energy project EIA demand particularly for solar and wind farms, and infrastructure environmental assessment requirements. |
|
Victoria & Tasmania |
15.4% |
Reflecting Victoria offshore wind zone assessments representing a major emerging consulting opportunity, urban infrastructure development pipeline, renewable energy project consulting, and a growing demand for ESG and climate risk advisory from major Victorian corporate clients. |
|
Northern Territory & Southern Australia |
9.7% |
Reflecting the Northern Territory resources sector, including gas development and renewable energy for remote communities, South Australia hydrogen economy development generating clean energy project assessments, and the environmental assessment requirements. |
Australia Capital Territory & New South Wales commanding 31.5% of Australia environmental consulting services market reflects the dual role of the federal government as both a direct client and regulatory driver, combined with the concentration of large corporations that generate the highest per-entity environmental consulting demand.
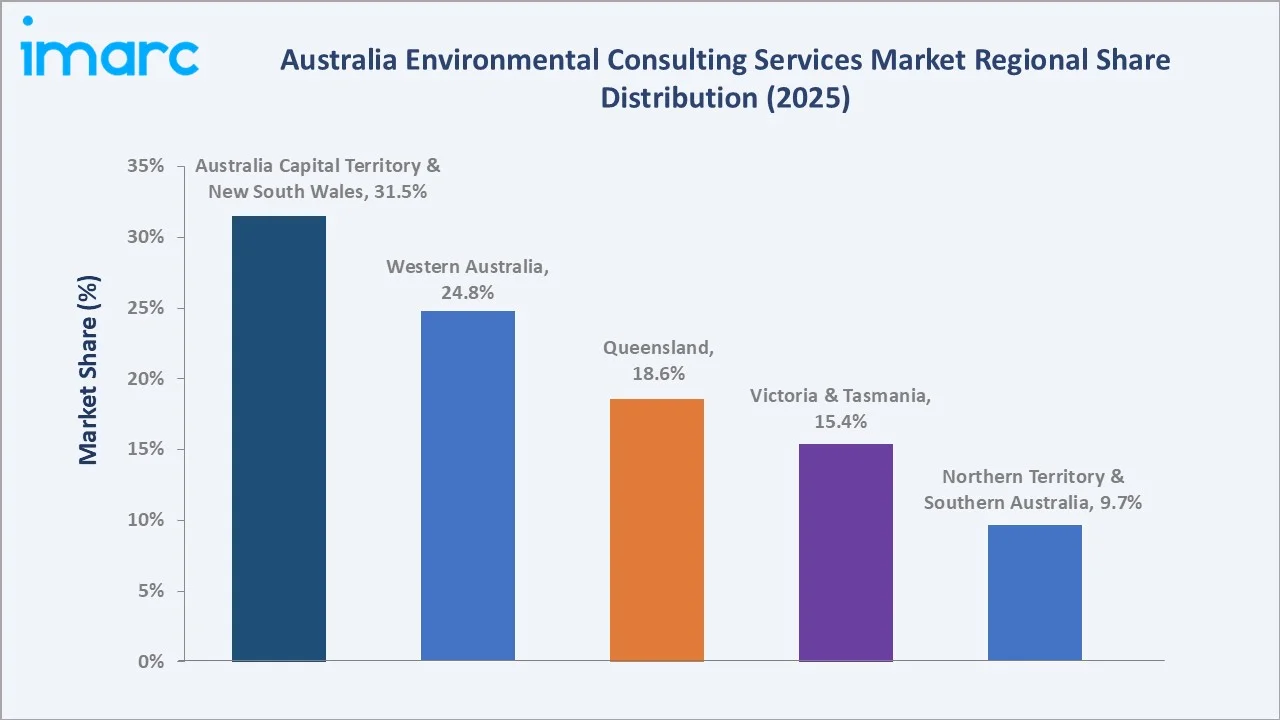
Western Australia at 24.8% reflects the unique intensity of resource sector environmental consulting demand, where iron ore, gold, lithium, LNG, and other resource projects generate some of the largest single-project environmental consulting budgets in Australia. Queensland at 18.6% benefits from the renewable energy and tourism-related environmental consulting pipeline. Victoria and Tasmania at 15.4% are emerging as important growth markets, particularly for offshore wind development environmental assessment, which represents one of the largest new consulting opportunity pipelines in Australia energy sector. Northern Territory & Southern Australia at 9.7%.
Competitive Landscape
The Australia environmental consulting services market is characterized by low market share concentration. The market is led by large global multidisciplinary engineering and consulting firms that bring scale, multi-disciplinary capability, and international best practice to major project mandates, alongside a substantial tier of specialized regional and national firms serving specific sectors or geographic markets.
|
Company |
Key Offerings |
Market Position |
Core Strength |
|
GHD |
Burntfields wildfire risk management solution, Climate and Sustainability, Contamination Assessment and Remediation |
Market Leader |
GHD is a major professional services and engineering company, playing a leading role in delivering integrated environmental consulting services across Australia. |
|
AECOM |
Digital EHS/ESG Solutions, Air Quality Consulting and Engineering, Water, Waste and Natural Resources Management |
Market Leader |
AECOM plays a leading role in Australia's environmental consulting sector, providing comprehensive advisory, planning, and technical services across major infrastructure projects. |
|
Arcadis N.V. |
Environment, Health and Safety Compliance, Ecological and Sustainability, Environmental Permitting and Planning |
Established Player |
Arcadis N.V. plays a major role in Australia’s environmental consulting sector by delivering integrated design, engineering, and sustainability solutions. |
|
Stantec |
Biodiversity Consulting, Climate Change Risk Assessments, Environmental Health, Safety & Compliance, Environmental, Social, and Governance (ESG) Advisory Services |
Established Player |
Stantec plays a major role in Australia’s environmental consulting and sustainable engineering sector, providing comprehensive support across project lifecycles. |
|
Tetra Tech, Inc. |
Environmental Management and Compliance, ESG and Sustainability, Climate Services, Industrial Hygiene Sciences, Geospatial Mapping and Remote Sensing Services |
Innovator |
Tetra Tech, Inc. provides high-end environmental consulting, engineering, and sustainable infrastructure services in Australia through a network of a large number of experts. |
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| GHD | Burntfields wildfire risk management solution, Climate and Sustainability, Contamination Assessment and Remediation | Market Leader | GHD is a major professional services and engineering company, playing a leading role in delivering integrated environmental consulting services across Australia. |
| AECOM | Digital EHS/ESG Solutions, Air Quality Consulting and Engineering, Water, Waste and Natural Resources Management | Market Leader | AECOM plays a leading role in Australia's environmental consulting sector, providing comprehensive advisory, planning, and technical services across major infrastructure projects. |
| Arcadis N.V. | Environment, Health and Safety Compliance, Ecological and Sustainability, Environmental Permitting and Planning | Established Player | Arcadis N.V. plays a major role in Australia’s environmental consulting sector by delivering integrated design, engineering, and sustainability solutions. |
| Stantec | Biodiversity Consulting, Climate Change Risk Assessments, Environmental Health, Safety & Compliance, Environmental, Social, and Governance (ESG) Advisory Services | Established Player | Stantec plays a major role in Australia’s environmental consulting and sustainable engineering sector, providing comprehensive support across project lifecycles. |
| Tetra Tech, Inc. | Environmental Management and Compliance, ESG and Sustainability, Climate Services, Industrial Hygiene Sciences, Geospatial Mapping and Remote Sensing Services | Innovator | Tetra Tech, Inc. provides high-end environmental consulting, engineering, and sustainable infrastructure services in Australia through a network of a large number of experts. |
Competition is intensifying as global environmental consulting firms expand their Australia practices through organic growth and targeted acquisitions, while specialist firms compete on sector-specific expertise and relationship depth with major resource and government clients. Digital innovation capabilities are becoming a critical differentiator for large project mandates as clients seek consultants who can deliver faster, more data-driven environmental assessments.
Key Company Profiles
GHD
GHD is a global professional services company providing engineering, environmental, and advisory solutions across multiple industries. In Australia, the company offers environmental consulting services covering environmental assessment, sustainability, water management, and natural resource management. GHD supports clients in addressing regulatory requirements, environmental risks, and sustainable development objectives. Its multidisciplinary expertise enables the company to serve infrastructure, energy, resources, and government projects across Australia.
- Key Offerings: Burntfields wildfire risk management solution, Climate and Sustainability, Contamination Assessment and Remediation.
- Strategic Focus: Expanding its environmental consulting capabilities through sustainable solutions, digital technologies, and multidisciplinary expertise. The company emphasizes supporting infrastructure, energy, resources, and government projects with environmental risk management, regulatory compliance, and sustainable development services across Australia.
AECOM
AECOM is a global infrastructure consulting and professional services company with a strong presence in Australia. The company provides environmental consulting services covering environmental assessment, sustainability, remediation, climate resilience, and natural resource management. AECOM supports clients across infrastructure, transportation, energy, resources, and government sectors. Its multidisciplinary capabilities help organizations manage environmental risks, meet regulatory requirements, and advance sustainable development projects.
- Key Offerings: Digital EHS/ESG Solutions, Air Quality Consulting and Engineering, Water, Waste and Natural Resources Management.
- Strategic Focus: Focuses on delivering integrated environmental and sustainability solutions to support infrastructure, energy, resources, and government projects across Australia. Its strategic priorities include climate resilience, environmental risk management, digital innovation, regulatory compliance, and sustainable project development.
Market Concentration Analysis
The Australia environmental consulting services market has low market share concentration, with various businesses competing for work across federal and state government, resource, energy, infrastructure, and corporate markets. The market has been gradually consolidating at the higher end through acquisitions, while the base of specialist regional firms remains large and diverse.
Market concentration is expected to remain low but with increasing polarization between large global firms winning major project mandates and specialist smaller firms serving niche markets, as the complexity of regulatory requirements progressively favors large multi-disciplinary practices with the professional indemnity and technical capability to handle the most complex environmental assessment and management assignments.
Investment & Growth Opportunities
Highest Growth Segments
Renewable energy environmental assessment represents the highest near-term volume growth opportunity, driven by the unprecedented pipeline of offshore wind, solar, wind, and pumped hydro project assessments required for Australia 82% renewable electricity target by 2030. Nature Positive consulting represents the highest premium advisory opportunity emerging in the market.
Investment Themes
- Digital Environmental Assessment Platform Development: Investment in AI-assisted EIA analytics, satellite-based environmental monitoring platforms, and digital environmental management systems creates competitive differentiation that supports both faster service delivery and recurring revenue from ongoing monitoring contracts that extend client relationships beyond one-time project assessments.
- Specialist ESG and Sustainability Reporting Capability: The mandatory Australian Sustainability Reporting Standards framework creates structural demand for specialist sustainability reporting advisory, climate scenario analysis, and Scope 3 emissions measurement capability that commands premium fees and creates multi-year ongoing client relationships as companies build annual sustainability reporting competencies.
Future Market Outlook (2026-2034)
The Australia environmental consulting services market stood at USD 751.9 Million in 2025 and is projected to grow from USD 789.8 Million in 2026 to USD 1,186.3 Million by 2034, exhibiting a CAGR of 5.04% during the forecast period. The market is expected to reach an intermediate milestone of approximately USD 961.6 Million by 2030, as mandatory Australian Sustainability Reporting Standards expand to all large entities, the offshore wind zone environmental assessment pipeline ramps to full scale, and Nature Positive Plan biodiversity consulting requirements progressively create new mandatory consulting workstreams for all large project developers.
Three structural forces will define the Australia environmental consulting services market through 2034. First, the progressive mandating of environmental and sustainability disclosure will systematically create new categories of mandatory consulting work for every large Australian business, government agency, and project developer. Second, Australia renewable energy transition will sustain the largest single project-based environmental consulting pipeline in Australia history, with offshore wind zone development alone potentially generating over a decade of marine ecology, fisheries, cultural heritage, and environmental management consulting work across multiple consulting firms. Third, the progressive adoption of digital assessment technology, AI-driven environmental monitoring, and real-time compliance platforms will improve the productivity and margin economics of environmental consulting delivery, enabling firms to handle larger project workloads with the same professional headcount and creating new subscription-based recurring revenue models.
Research Methodology
Primary Research
Primary research comprised structured consultations with environmental consulting firm principals and practice leaders, government environmental agency representatives, corporate sustainability managers at ASX-listed companies, project developers in renewable energy and infrastructure, state EPA staff, and Australian environmental law specialists. These discussions validated market sizing, assessed sector-specific demand dynamics, identified emerging regulatory drivers, and provided competitive intelligence on winning project mandates and consulting fee dynamics across the major Australian state markets.
Secondary Research
Secondary research drew on IMARC Group market data, Australia Environmental Consulting industry analysis, Australian Accounting Standards Board sustainability reporting guidance, AEMO Integrated System Plan publications, environmental policy documents, company investor relations materials, and industry publications. Historical market data spanning 2020 through 2025 was cross-validated across multiple commercial and government data sources.
Forecasting Models
Market forecasts incorporated historical industry growth trend analysis, regulatory requirement expansion modeling, renewable energy project pipeline environmental assessment demand projections, infrastructure investment EIA workload estimates, corporate sustainability advisory demand modeling based on ASX entity disclosure phase-in schedules, contamination assessment and remediation market sizing, and macroeconomic indicators including Australian GDP growth and resource sector investment projections through 2034.
Australia Environmental Consulting Services Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Services Covered | Investment Assessment and Auditing, Permitting and Compliance, Project and Information Management, Monitoring and Testing, Others |
| Medium Technologies Covered | Water Management, Waste Management |
| Verticals Covered | Energy and Utilities, Chemical and Petroleum, Manufacturing and Process Industry, Transportation and Construction Industries, Others |
| Regions Covered | Australia Capital Territory & New South Wales, Victoria & Tasmania, Queensland, Northern Territory & Southern Australia, Western Australia |
| Companies covered | GHD, AECOM, Arcadis N.V., Stantec, Tetra Tech, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Australia environmental consulting services market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Australia environmental consulting services market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Australia environmental consulting services industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Australia Environmental Consulting Services Market Report
The Australia environmental consulting services market reached USD 789.8 Million in 2026, driven by tightening environmental regulations, renewable energy transition project assessments, mandatory sustainability disclosure requirements, and sustained government and corporate demand for environmental compliance consulting.
The market is projected to grow at a CAGR of 5.04% during 2026-2034, supported by mandatory Australian Sustainability Reporting Standards disclosure expansion, Nature Positive Plan biodiversity consulting requirements, offshore wind development environmental assessments, and PFAS contamination assessment and remediation workloads.
The market is projected to reach approximately USD 961.6 Million by 2030, driven by peak renewable energy project assessment activity under Australia's 82% renewable electricity target, mandatory climate disclosure expanding to all large entities, and the offshore wind zone environmental assessment pipeline reaching full scale.
Water management leads with a 58.6% share in 2025, reflecting Australia chronic water security challenges, the primacy of water quality and hydrology consulting in resource sector project assessments, and sustained government investment in water infrastructure that generates ongoing water management consulting demand.
Energy and utilities lead with a 28.7% share in 2025, driven by the unprecedented pipeline of renewable energy project environmental impact assessments generated by Australia transition to 82% renewable electricity by 2030.
Australia Capital Territory & New South Wales lead with a 31.5% share in 2025, reflecting the federal government as a major direct client, the concentration of ASX corporate headquarters facing sustainability disclosure obligations, and the active infrastructure development pipeline in Sydney that generates extensive environmental assessment demand.
Key players include GHD, AECOM, Arcadis N.V., Stantec, and Tetra Tech, Inc., among others.
The market is projected to reach USD 1,186.3 Million by 2034, driven by full mandatory sustainability disclosure, offshore wind development environmental assessment, Nature Positive biodiversity consulting, remediation programs, and digital environmental monitoring platform adoption improving service delivery economics.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade