
Australia Fashion and Apparel Market Size, Share, Trends and Forecast by Type, Distribution Channel, End User, and Region, 2026-2034
Australia Fashion and Apparel Market Size, Share, Trends & Forecast (2026-2034)
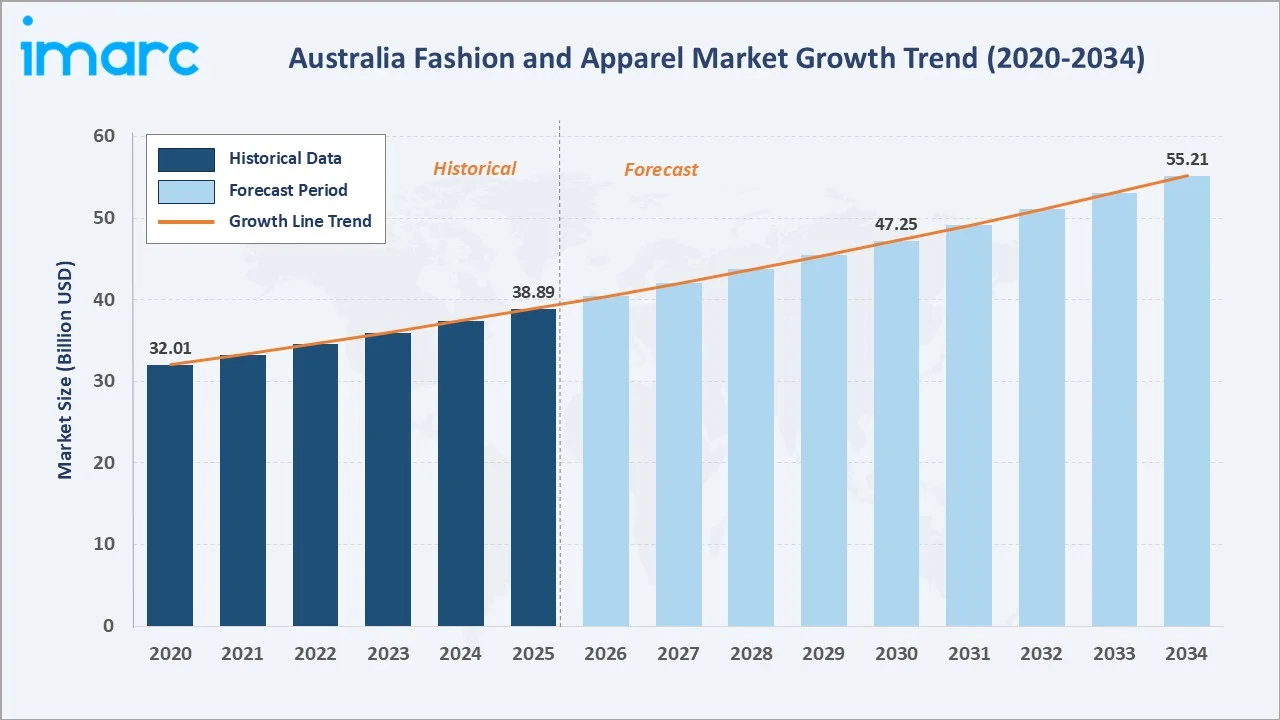
The Australia fashion and apparel market grew from USD 38.89 Billion in 2025 to USD 40.43 Billion in 2026 and is projected to reach USD 55.21 Billion by 2034, exhibiting a CAGR of 3.97% during 2026-2034. Rising fashion consciousness, expanding e-commerce infrastructure, and the increasing demand for sustainable and ethically produced apparel are primary growth drivers.
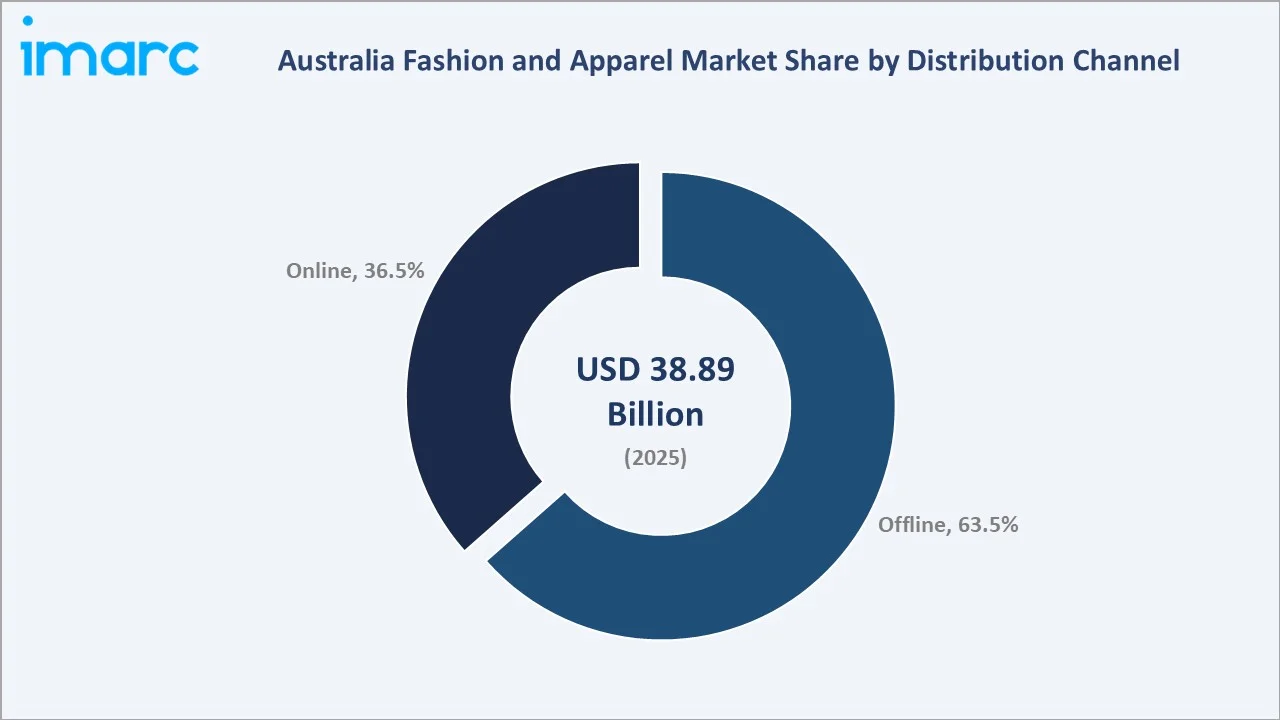
Offline leads distribution channel with a 63.5% share in 2025, while women represent the largest end user segment at 49.6%. Australia Capital Territory & New South Wales commands the highest regional share at 35.7%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 38.89 Billion |
| Market Size (2026) | USD 40.43 Billion |
|
Forecast Market Size (2034) |
USD 55.21 Billion |
|
CAGR (2026-2034) |
3.97% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Australia Capital Territory & New South Wales (35.7%, 2025) |
|
Second Largest Region |
Victoria & Tasmania (25.6%, 2025) |
|
Leading Distribution Channel |
Offline (63.5%, 2025) |
|
Leading End User |
Women (49.6%, 2025) |
The Australia fashion and apparel market expanded from USD 32.01 Billion in 2020 to USD 38.89 Billion in 2025 and an estimated USD 40.43 Billion in 2026, driven by rising fashion consciousness among urban consumers and growing discretionary spending on apparel across all demographic segments. Anchored at USD 47.25 Billion in 2030, the forecast to USD 55.21 Billion by 2034 is supported by accelerating online retail adoption and premiumization trends across women's, men's, and kids' segments.
To get more information on this market, Request Sample
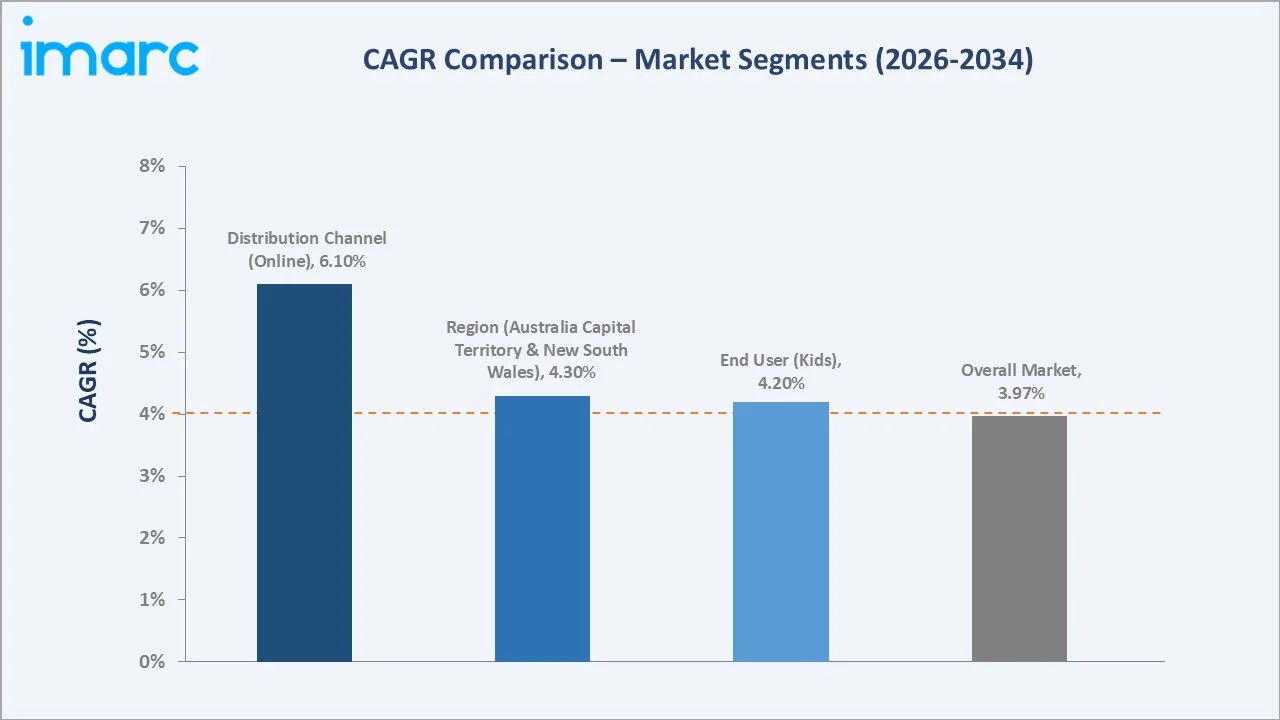
CAGR trajectories across distribution channel and end user sub-segments show online and kids expanding faster than the overall 3.97% market CAGR, driven by digital-native purchasing habits, growing children’s fashion premiumization, and rising participation of younger demographics in fashion spending.
Executive Summary
The Australia fashion and apparel market is on a sustained growth trajectory from USD 32.01 Billion in 2020 to USD 40.43 Billion in 2026 and is projected to reach USD 55.21 Billion by 2034. The market’s expansion is supported by rising consumer spending, evolving fashion preferences, and the growing influence of e-commerce and digital retail channels.
Offline leads distribution channel at 63.5% in 2025, anchored by established department stores, specialty apparel chains, and shopping centers. Women remain the dominant end user at 49.6%, fueled by strong demand for diverse fashion styles, frequent apparel purchases, and evolving consumer preferences. Australia Capital Territory & New South Wales leads regionally at 35.7%, supported by its large population base, strong retail infrastructure, and concentration of fashion and commercial activity.
Key Market Insights
|
Insight |
Data |
|
Leading Distribution Channel |
Offline – 63.5% share (2025) |
|
Second Largest Distribution Channel |
Online – 36.5% share (2025) |
|
Leading End User |
Women – 49.6% share (2025) |
|
Second Largest End User |
Men – 35.8% share (2025) |
|
Leading Region |
Australia Capital Territory & New South Wales – 35.7% share (2025) |
|
Second Largest Region |
Victoria & Tasmania – 25.6% share (2025) |
|
Top Companies |
Inditex, H&M Group, Cotton On Group, Global Fashion Group |
Key Analytical Observations Expanding On the Data Above:
- Offline leadership at 63.5% is underpinned by the continued importance of in-store experiences, fitting rooms, and immediate product access across department stores, standalone brand outlets, and shopping center anchors that serve urban and suburban populations.
- Online at 36.5% is accelerating across all age groups, with mobile commerce, buy-now-pay-later integration, and next-day delivery services reshaping purchasing patterns significantly for fashion categories.
- Women dominance at 49.6% reflects higher fashion engagement, broader product choice across price points, and active participation in both luxury and fast fashion segments, including growing interest in sustainable and capsule wardrobe concepts.
- Men share at 35.8% is supported by growing interest in contemporary fashion, expanding premium and casualwear options, and increasing adoption of athleisure and lifestyle apparel.
- Australia Capital Territory & New South Wales at 35.7% leads regionally due to high concentration of high-income households, major retail precincts, international brand presence, and a dense urban population with strong fashion media influence.
Australia Fashion and Apparel Market Overview
Fashion and apparel refers to a broad industry encompassing the design, production, distribution, and sale of clothing, footwear, accessories, and related lifestyle products. The market is shaped by evolving consumer preferences, changing fashion trends, rising disposable incomes, and the expansion of both physical retail and e-commerce channels across Australia.
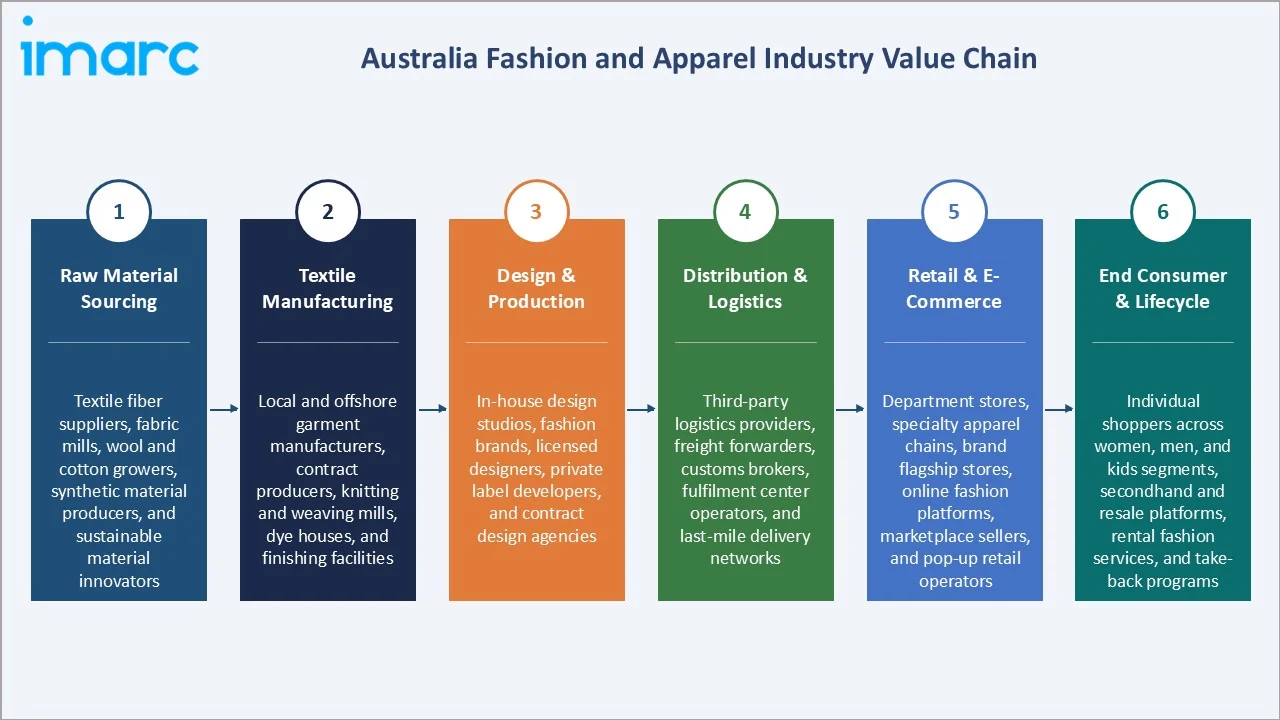
The industry ecosystem integrates raw material suppliers, textile manufacturers, fashion designers and brands, logistics providers, retailers, and digital commerce platforms. Macroeconomic factors including consumer confidence, wage growth, housing costs, and tourism volumes shape discretionary fashion spending cycles across Australian states and territories.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
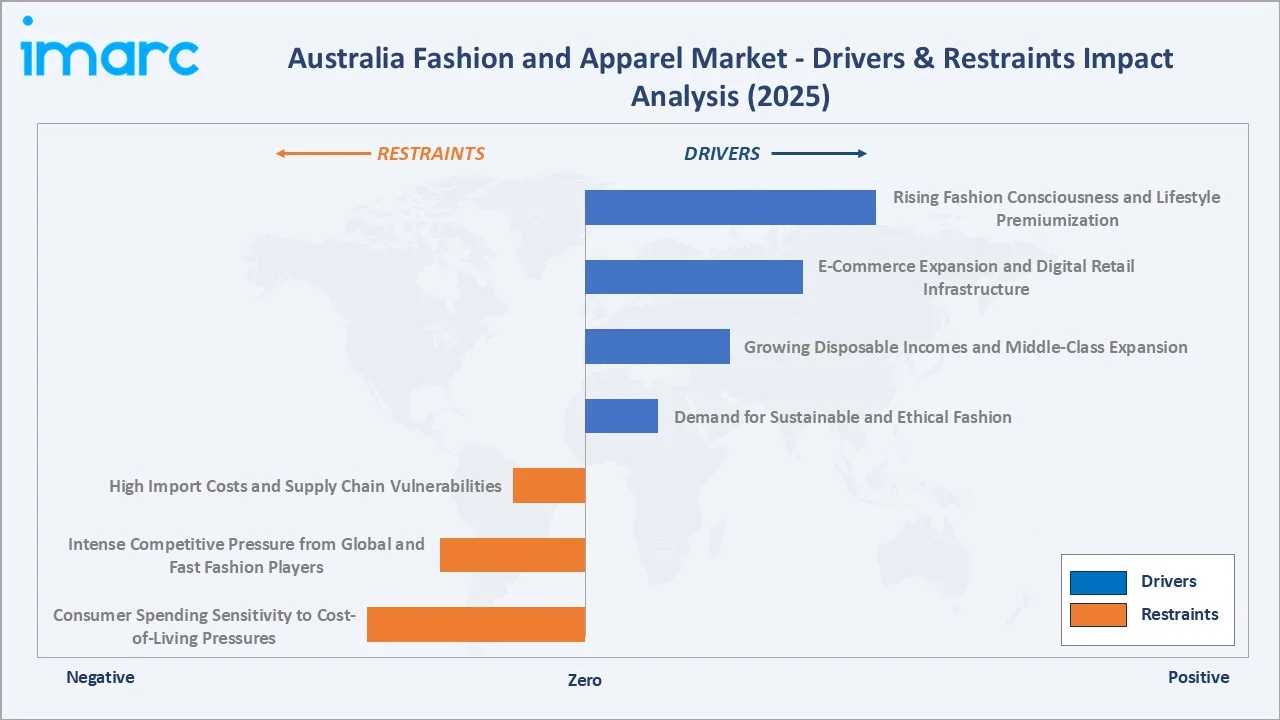
- Rising Fashion Consciousness and Lifestyle Premiumization: Growing consumer interest in fashion as a form of self-expression, social identity, and wellness lifestyle is driving higher frequency of apparel purchases and increased per-unit spend. Urbanization, expanding social media influence, and fashion content consumption are elevating style awareness across all age groups.
- E-Commerce Expansion and Digital Retail Infrastructure: The rapid growth of online fashion retail, supported by advanced logistics, flexible return policies, and buy-now-pay-later platforms, is significantly expanding the market’s accessible consumer base. As per IMARC Group, the Australia buy now pay later market size reached USD 327.1 Million in 2025.
- Growing Disposable Incomes and Middle-Class Expansion: Sustained wage growth, low unemployment rates, and rising household incomes across major Australian cities are translating into higher discretionary spending on apparel, premium brands, and fashion accessories. This trend is particularly evident in tier-1 cities and expanding outer-suburban markets.
- Demand for Sustainable and Ethical Fashion: Increasing consumer awareness of environmental and social impacts of fast fashion is creating demand for sustainable fabrics, ethical production practices, circular fashion initiatives, and transparent supply chains. Brands investing in these credentials are achieving stronger brand equity and repeat purchase rates.
Market Restraints
- High Import Costs and Supply Chain Vulnerabilities: Australia’s heavy reliance on imported apparel, particularly from Asia, exposes the market to currency fluctuations, shipping cost volatility, and supply chain disruptions. These factors increase retailer costs and compress margins, particularly for mid-market brands competing on price.
- Intense Competitive Pressure from Global and Fast Fashion Players: The Australia market faces significant competitive pressure from international fast fashion giants, global e-commerce platforms, and direct-to-consumer brands that offer wide product ranges at aggressive price points, making it challenging for local and mid-sized operators to sustain market share.
- Consumer Spending Sensitivity to Cost-of-Living Pressures: Elevated housing costs, rising interest rates, and inflationary pressures on essential goods have reduced discretionary spending headroom for fashion purchases among middle-income Australian households, creating demand volatility particularly in the mid-price apparel segment.
Market Opportunities
- Sustainable and Circular Fashion Innovation: Growing demand for sustainable apparel, secondhand fashion platforms, rental and subscription clothing models, and take-back programs presents significant commercial opportunities for brands that can credibly deliver on environmental commitments while maintaining style and quality standards.
- Expansion into Regional and Tier-2 Markets: Growing consumer purchasing power in regional cities including Newcastle, Wollongong, Geelong, and the Gold Coast hinterland presents expansion opportunities for brands and retailers willing to invest in tailored assortments, pop-up retail formats, and localized marketing strategies.
Market Challenges
- Managing Inventory and Overstock Risks: Rapidly shifting consumer preferences, shortening fashion seasons, and the growing influence of trend cycles driven by social media create significant inventory management challenges. Overstock and markdowns erode profitability and brand positioning, particularly for mid-tier fashion retailers.
- Digital Disruption and Returns Logistics Costs: High return rates from online fashion purchases, driven by sizing inconsistency, product-image mismatches, and trial purchasing behavior, create significant reverse logistics costs and inventory complications that reduce the net profitability of e-commerce fashion channels.
Emerging Market Trends
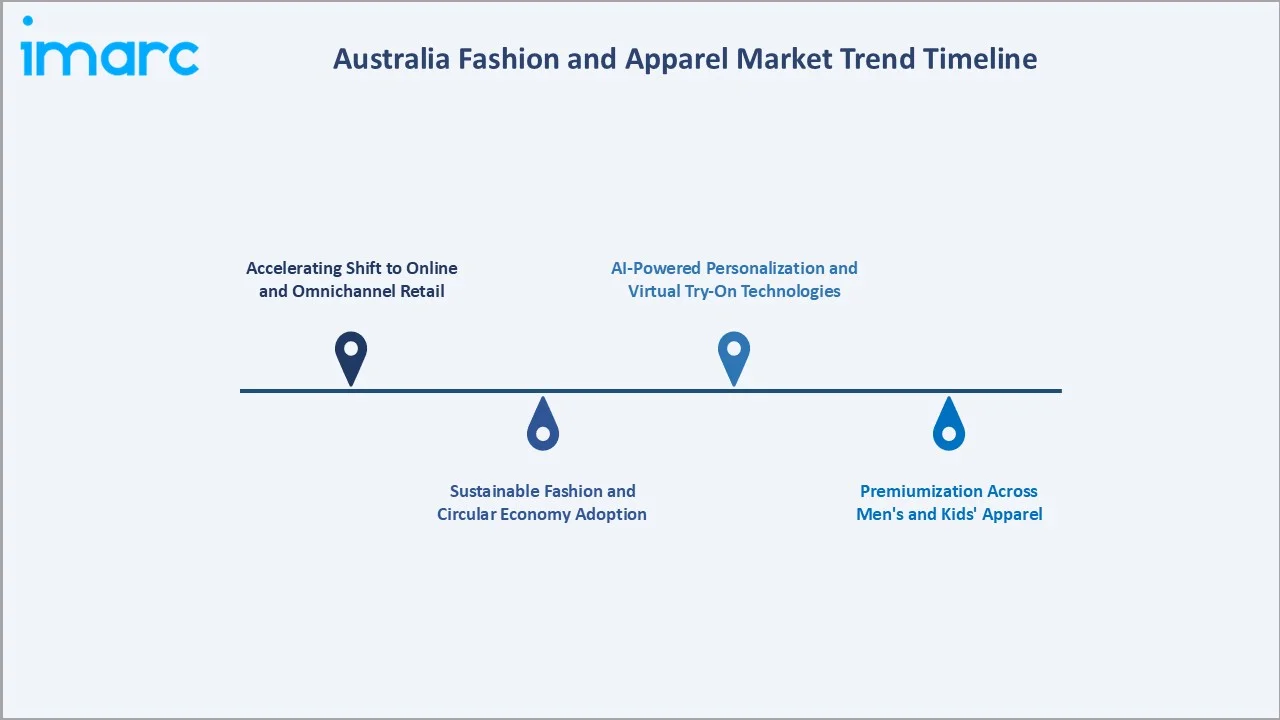
1. Accelerating Shift to Online and Omnichannel Retail
Australian fashion consumers are rapidly migrating toward online channels, with pure-play digital platforms and brand-owned e-commerce stores capturing a growing share of total fashion spend. Omnichannel strategies that seamlessly blend in-store discovery with digital convenience are becoming the preferred model for major apparel retailers seeking to retain customer loyalty and basket size.
2. Sustainable Fashion and Circular Economy Adoption
Consumer demand for sustainability is reshaping product development, sourcing, and marketing strategies across all apparel segments. Growing adoption of recycled materials, ethical sourcing, and resale models is encouraging fashion brands to integrate circular practices across product lifecycles.
3. Premiumization Across Men’s and Kids’ Apparel
The men’s and kids’ apparel segments are experiencing pronounced premiumization trends, as consumers invest in quality basics, performance wear, and branded lifestyle clothing rather than high-volume, low-cost fashion cycles. This shift is supporting margin expansion for brands that articulate quality, durability, and design differentiation.
4. AI-Powered Personalization and Virtual Try-On Technologies
Fashion retailers are deploying AI for size recommendations, style personalization, demand forecasting, and visual search capabilities. Virtual try-on tools powered by augmented reality (AR) are reducing return rates and improving online conversion rates, making digital fashion retail more efficient and consumer-friendly.
Industry Value Chain Analysis
The Australia fashion and apparel value chain spans six interconnected stages from raw material sourcing through end consumer engagement and post-sale lifecycle management. Each stage involves distinct players and creates value through design, quality, accessibility, and consumer experience.
|
Stage |
Key Players / Examples |
|
Raw Material Sourcing |
Textile fiber suppliers, fabric mills, wool and cotton growers, synthetic material producers, and sustainable material innovators supplying inputs to manufacturers and designers |
|
Textile Manufacturing |
Local and offshore garment manufacturers, contract producers, knitting and weaving mills, dye houses, and finishing facilities processing materials into ready-to-cut fabric and components |
|
Design & Production |
In-house design studios, fashion brands, licensed designers, private label developers, and contract design agencies responsible for seasonal collections and product development cycles |
|
Distribution & Logistics |
Third-party logistics providers, freight forwarders, customs brokers, fulfilment center operators, and last-mile delivery networks connecting production to retail points |
|
Retail & E-Commerce |
Department stores, specialty apparel chains, brand flagship stores, online fashion platforms, marketplace sellers, and pop-up retail operators serving end consumers across channels |
|
End Consumer & Lifecycle |
Individual shoppers across women, men, and kids’ segments, secondhand and resale platforms, rental fashion services, and clothing take-back programs supporting circular lifecycle management |
Brands with vertically integrated supply chains, strong direct-to-consumer capabilities, and proprietary digital platforms are positioned to capture higher value at each stage. Integration between design, manufacturing, and retail is increasingly a source of competitive advantage for both global and homegrown Australian fashion labels.
Technology Landscape in the Australia Fashion and Apparel Industry
AI and Machine Learning (ML) in Demand Forecasting
Advanced AI and ML models are being deployed by major Australian fashion retailers to optimize inventory planning, predict seasonal demand patterns, and reduce overstock risks. These systems analyze historical sales data, social media trend signals, and macroeconomic indicators to improve buying decisions and markdown management across product categories.
AR and Virtual Try-On
AR-powered virtual try-on technologies are being integrated into fashion e-commerce platforms and brand apps, allowing consumers to visualize clothing fit and styling before purchase. These tools are demonstrably reducing return rates, improving conversion, and enhancing the online shopping experience across both mid-market and premium fashion brands.
Sustainable Materials and Textile Innovation
Material innovation is a growing technology frontier in Australian fashion, with brands exploring recycled polyester, organic cotton, hemp, lyocell, and bio-based fabrics as alternatives to conventional synthetics and conventional cotton. Textile-to-textile recycling technologies and chemical recycling processes are also gaining traction among sustainability-focused operators.
Omnichannel Commerce Technology
Unified commerce platforms that connect in-store point-of-sale systems, online storefronts, loyalty programs, and inventory management in real time are enabling Australian fashion retailers to deliver seamless omnichannel experiences. Click-and-collect, endless aisle, and ship-from-store capabilities are reducing friction and improving fulfilment efficiency across retail networks.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
🔒 |
🔒 |
2025 |
|
Distribution Channel |
Offline |
63.5% |
2025 |
|
End User |
Women |
49.6% |
2025 |
|
Region |
Australia Capital Territory & New South Wales |
35.7% |
2025 |

By Distribution Channel
Offline commands a 63.5% majority share in 2025, anchored by the continued dominance of department stores, specialty fashion chains, standalone brand stores, and shopping center precincts across major Australian cities and suburban markets.
To access detailed market analysis, Request Sample
Online holds a 36.5% share in 2025 and is the faster-growing distribution channel, supported by the expansion of dedicated online fashion platforms, brand-owned digital stores, and marketplace aggregators.
By End User
Women dominate with a 49.6% share in 2025, driven by higher fashion engagement, broader product range coverage across price tiers, strong demand for occasion wear, casualwear, and activewear, and growing interest in sustainable and capsule wardrobe fashion formats. The segment benefits from a dense ecosystem of both international and local brands competing across all distribution channels.
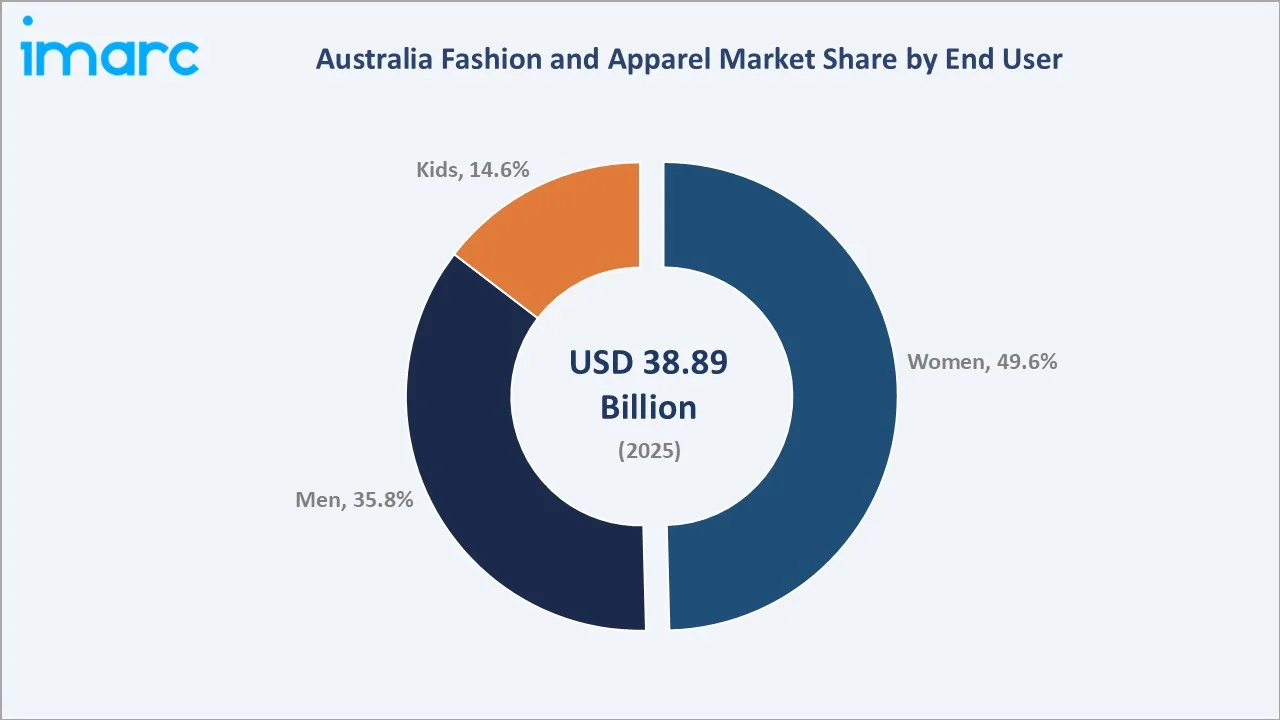
Men at 35.8% are benefiting from the casualization of workwear, growing athleisure adoption, and increasing fashion consciousness among male consumers.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
Australia Capital Territory & New South Wales |
35.7% |
Large urban population, premium retail concentration, high disposable incomes, and strong international brand presence |
|
Victoria & Tasmania |
25.6% |
Fashion-forward consumer culture, robust independent designer ecosystem, high retail density, and growing outer-suburban demand |
|
Queensland |
18.4% |
Population growth, expanding retail infrastructure, tourism-linked fashion spend, and rising tier-2 city purchasing power |
|
Western Australia |
12.3% |
Resource sector income uplift, growing Perth metropolitan retail market, and rising demand for premium lifestyle apparel |
|
Northern Territory & Southern Australia |
8.0% |
Emerging retail development, niche lifestyle fashion demand, and growing participation from regional urban centers |
Australia Capital Territory & New South Wales leads the regional landscape with a 35.7% share in 2025, anchored by Sydney’s status as Australia’s leading retail market and a high-income urban consumer base with strong fashion media influence.
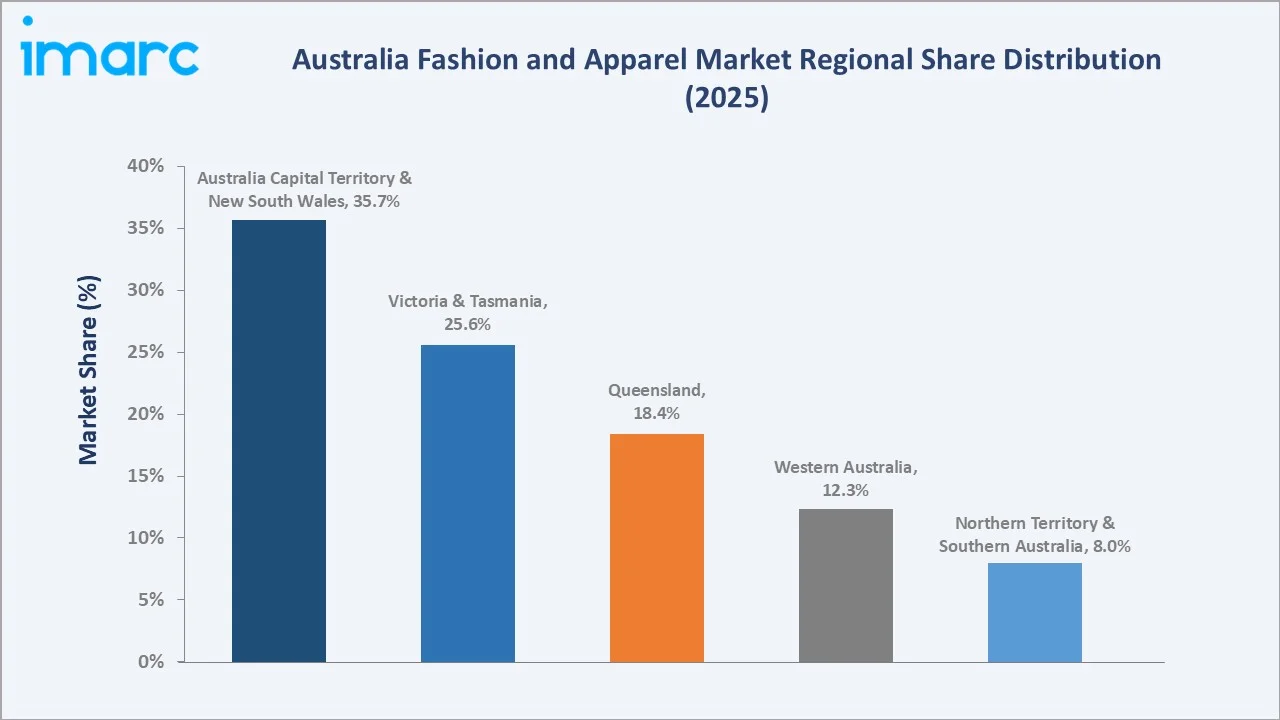
Victoria & Tasmania at 25.6% is the second largest region, supported by Melbourne’s position as Australia’s fashion capital, with a vibrant independent designer scene, strong luxury brand presence, and a highly fashion-conscious consumer culture.
Competitive Landscape
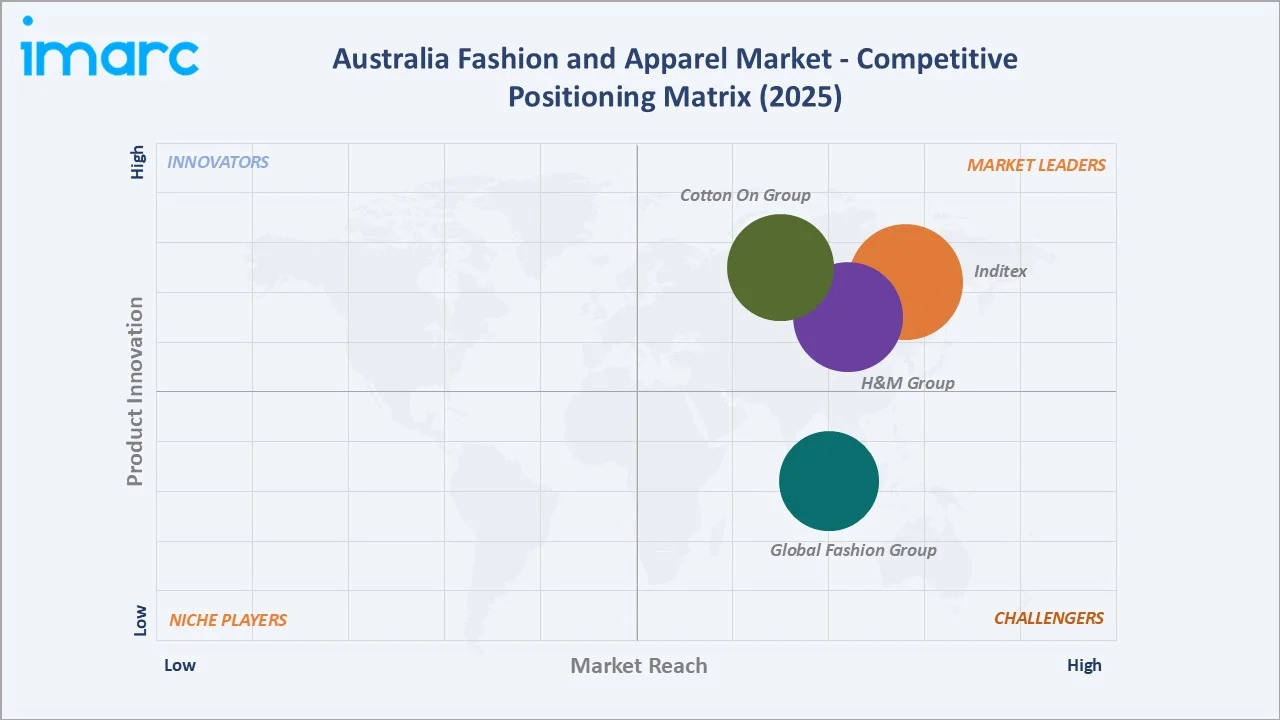
The Australia fashion and apparel market is moderately fragmented, with established international fashion groups holding significant market positions alongside strong domestic operators and fast-growing digital-native brands. Global fast fashion retailers compete on price and trend velocity, while premium and lifestyle brands differentiate on quality, sustainability credentials, and brand heritage.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
|
Inditex |
Zara |
Leader |
Fast-fashion retailer with trend-responsive supply chain and premium high-street positioning across Australian metro markets |
|
H&M Group |
H&M |
Leader |
Value-led global fashion operator expanding sustainable collections and omnichannel retail capabilities in Australia |
|
Cotton On Group |
Cotton On |
Leader |
Australian-origin value fashion operator with extensive domestic store network and growing international e-commerce presence |
|
Global Fashion Group |
The Iconic |
Challenger |
Australia’s leading online fashion platform offering broad brand and product range with strong logistics and returns infrastructure |
Key players include Inditex, H&M Group, Cotton On Group, and Global Fashion Group, among others.
Key Company Profiles
Inditex
Inditex is a Spanish multinational fashion group headquartered in Arteixo, Galicia. It is one of the world’s largest fashion retailers, operating brands including Zara.
- Product Portfolio: Zara, offering women’s, men’s, and kids’ clothing, footwear, and accessories across trend-responsive, high-street premium positioning.
- Recent Developments: Inditex has continued to invest in its Australian store network, digital platforms, and supply chain capabilities to strengthen its competitive position across the market.
- Strategic Focus: Strengthening omnichannel integration between physical stores and digital platforms, expanding sustainable product lines, and leveraging real-time consumer data to optimize inventory and trend responsiveness.
H&M Group
H&M Group is a Swedish multinational clothing retail company, headquartered in Stockholm, Sweden. The group operates multiple fashion brands globally, including H&M, with an established online retail presence complementing its physical footprint.
- Product Portfolio: H&M, offering a broad range of women’s, men’s, and kids’ apparel across value and contemporary price points, with expanding conscious collections featuring sustainable materials.
- Recent Developments: H&M Group has undertaken ongoing store network review and operational adjustments across its Australian business to enhance retail efficiency and improve financial performance.
- Strategic Focus: Advancing circular fashion commitments, deepening digital omnichannel capabilities, and growing the share of sustainable materials across collections to align with evolving Australian consumer preferences.
Cotton On Group
Cotton On Group is an Australian privately owned fashion retail company headquartered in Geelong, Victoria. It operates a diverse portfolio of fashion and lifestyle brands across multiple international markets, serving consumers through physical stores and online channels.
- Product Portfolio: Cotton On, offering casual and lifestyle apparel, accessories, stationery, and footwear across multi-brand retail formats targeting young adults, teens, and kids across value price points.
- Recent Developments: Cotton On Group has continued to expand its retail presence and e-commerce capabilities across domestic and international markets, advancing its multi-brand growth strategy.
- Strategic Focus: Scaling omnichannel retail capabilities, growing international e-commerce revenue, and strengthening sustainable sourcing commitments while maintaining broad domestic store network leadership.
Market Concentration Analysis
The Australia fashion and apparel market is moderately fragmented, with international fashion groups holding significant shares of the accessible premium and value segments, while domestic operators maintain strong positions through established store networks and brand loyalty.
Barriers to entry include high brand-building and marketing costs, competition for prime retail locations, established customer loyalty to leading brands, complex supply chain requirements, and the need for strong omnichannel capabilities to compete effectively in the market.
Consolidation is occurring through selective mergers and acquisitions, brand portfolio rationalization by larger groups, and the exit of weaker mid-tier physical retailers unable to support the costs of omnichannel investment.
Investment & Growth Opportunities
Fastest-Growing Segments
Online is the fastest-growing segment, driven by digital-first consumer behavior, mobile commerce adoption, and continued investment by major fashion operators in direct-to-consumer and marketplace capabilities.
Emerging Markets
Queensland represents a high-growth opportunity market, supported by strong population expansion, significant interstate migration, broadening outer-suburban retail infrastructure, and a rising base of digitally engaged consumers.
Venture & Investment Trends
Investment is flowing into sustainable fashion technology platforms, resale and circular economy operators, AI-powered personalization and size recommendation tools, and direct-to-consumer brand infrastructure. Capital is also being directed toward omnichannel fulfilment technology, returns management optimization, and fashion rental and subscription service models as investors target scalable, differentiated positions within the evolving Australian fashion ecosystem.
Future Market Outlook (2026-2034)
The Australia fashion and apparel market is forecast to expand from USD 38.89 Billion in 2025 to an estimated USD 40.43 Billion in 2026 and is forecast to reach USD 55.21 Billion by 2034, growing at a CAGR of 3.97%, adding approximately USD 16.32 Billion in incremental market value over the forecast period.
Four forces will shape the market through 2034: the continued digital transformation of fashion retail; the mainstreaming of sustainable and circular fashion practices; the premiumization of men’s and kids’ apparel; and the deepening integration of AI and data analytics into product design, supply chain, and consumer engagement. Brands that invest ahead of these structural shifts will be best positioned to capture disproportionate growth.
By 2034, the Australia fashion and apparel market is expected to be defined by mature omnichannel retail models, credible sustainability differentiation, and technology-enabled consumer personalization.
Research Methodology
Primary Research
Primary research included structured interviews with fashion retail executives, brand managers, supply chain specialists, sustainability officers, and consumer behavior researchers across the Australian apparel industry. Findings were used to validate market sizing assumptions, segmentation dynamics, and calibrate forecast models against operator-level growth expectations.
Secondary Research
Secondary sources included publications from the Australian Retailers Association, the Australian Fashion Council, the Australian Bureau of Statistics retail trade data, Australia Post e-commerce industry reports, and publicly available financial disclosures from listed fashion and retail companies operating in the Australian market. International benchmarks and global fashion industry reports were used to contextualize Australian market dynamics.
Forecasting Models
Market forecasts were developed using top-down and bottom-up modeling approaches, combining macroeconomic indicators including GDP growth, consumer confidence, and retail trade indices with bottom-up channel, segment, and regional market sizing. Regression analysis, trend extrapolation, and scenario modelling were applied to produce base-case forecasts with sensitivity analysis for key growth assumptions.
Australia Fashion and Apparel Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Formal Wear, Casual Wear, Sports Wear, Safety Wear, Others |
| Distribution Channels Covered | Online, Offline |
| End Users Covered | Men, Women, Kids |
| Regions Covered | Australia Capital Territory & New South Wales, Victoria & Tasmania, Queensland, Northern Territory & Southern Australia, Western Australia |
| Companies Covered | Inditex, H&M Group, Cotton On Group, Global Fashion Group, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Australia fashion and apparel market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Australia fashion and apparel market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Australia fashion and apparel industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Australia Fashion and Apparel Market Report
The Australia fashion and apparel market size is estimated at USD 40.43 Billion in 2026, supported by rising fashion consciousness, e-commerce expansion, and growing consumer spending on apparel across all key segments.
The market is projected to grow at a CAGR of 3.97% from 2026-2034, reaching USD 55.21 Billion, driven by digital retail growth, sustainability trends, and income-led premiumization.
Offline leads at 63.5% share in 2025, anchored by department stores, specialty chains, and shopping center precincts across major Australian cities and suburban markets.
Women lead with 49.6% share in 2025, driven by broader product range, higher purchase frequency, and strong engagement across both offline and online fashion channels.
Australia Capital Territory & New South Wales commands 35.7% in 2025, led by Sydney’s premium retail concentration, high-income urban consumers, and strong international brand presence.
Key players include Inditex, H&M Group, Cotton On Group, and Global Fashion Group, among others.
Key trends include sustainable and circular fashion adoption, omnichannel retail integration, AI-powered personalization, resale market growth, and premiumization in men’s and kids’ apparel.
Key challenges include high import costs, intense international competition, consumer spending sensitivity to cost-of-living pressures, returns management costs, and fast-changing trend cycles.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade