Australia Identity Verification Market Size, Share, Trends and Forecast by Type, Component, Deployment Mode, Organization Size, Vertical, and Region, 2026-2034
Australia Identity Verification Market Size, Share, Trends & Forecast (2026-2034)
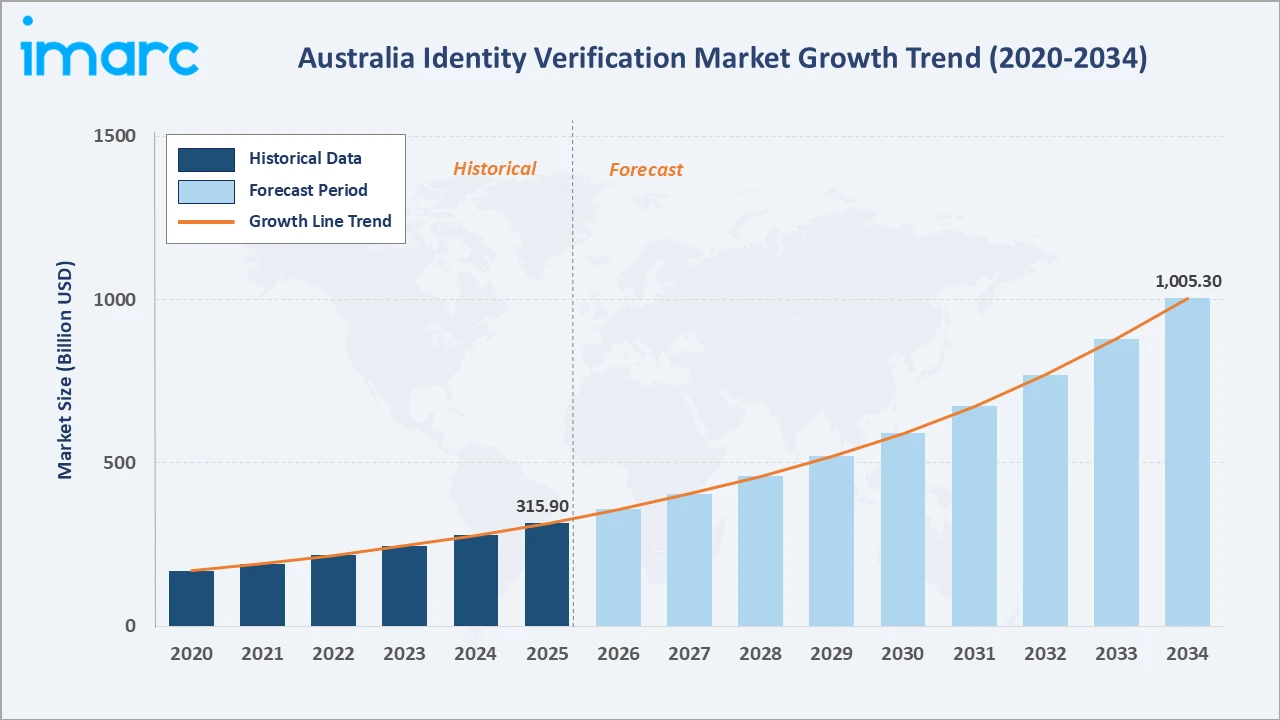
The Australia identity verification market grew from USD 315.9 Million in 2025 to USD 357.9 Million in 2026 and is projected to reach USD 1,005.3 Million by 2034, growing at a CAGR of 13.32% during 2026-2034. Demand is widening as banks, telecommunications providers, government agencies, retailers and digital platforms replace manual document checks with automated, remote and continuously assured identity processes. Rising online account opening, expanding digital payments and growing exposure to synthetic identity fraud are pushing organizations toward layered verification. Advances in facial recognition, liveness detection, document authentication and machine learning are raising accuracy while shortening onboarding times. Supportive regulation, including anti-money laundering obligations, the national digital identity framework and stronger privacy and cyber expectations, is widening mandatory use cases. Structural shifts toward mobile-first service delivery, cross-channel customer journeys and reusable digital credentials are deepening recurring demand for identity verification solutions across the economy.
Supporting growth factors include rising fraud losses, regulatory scrutiny and the migration of services online. Biometrics dominates at 56.4%. Large Enterprises lead at 64.2%. Australia Capital Territory & New South Wales commands 37.2% of the regional market share.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 315.9 Million |
| Market Size (2026) | USD 357.9 Million |
| Forecast Market Size (2034) | USD 1,005.3 Million |
| CAGR (2026-2034) | 13.32% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Dominant Type | Biometrics (56.4%, 2025) |
| Dominant Organization Size | Large Enterprises (64.2%, 2025) |
| Leading Region | Australia Capital Territory & New South Wales (37.2%, 2025) |
The market size increased from USD 169.1 Million in 2020 to USD 315.9 Million in 2025 and is estimated to reach USD 357.9 Million in 2026. The market is further expected to grow to USD 590.2 Million by 2030 and USD 1,005.3 Million by 2034. The Australian market is commercially distinctive because a highly digitized, concentrated financial sector and a government-backed digital identity framework create unusually strong, regulation-led demand for verification.
To get more information on this market, Request Sample
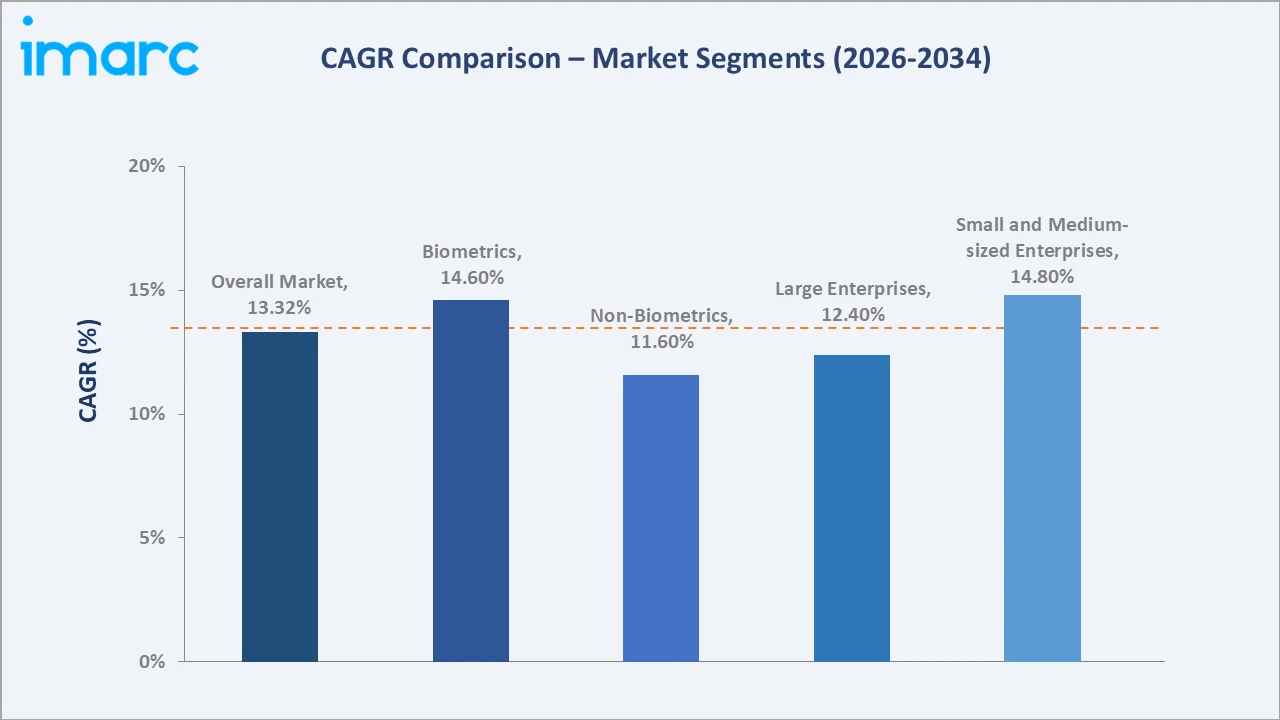
Biometrics at ~14.6% CAGR and Small and Medium-sized Enterprises at ~14.8% CAGR are the fastest-growing sub-segments, supported by mobile facial authentication adoption and by cloud-delivered verification services that lower entry costs for smaller organizations.
Executive Summary
The market expanded from USD 315.9 Million in 2025 to an estimated USD 357.9 Million in 2026, with demand anchored in financial services onboarding, telecommunications SIM registration, government service delivery, online retail and gaming, and workforce and gig-economy screening. The fastest-developing areas are biometric authentication, liveness detection, reusable digital identity credentials and cloud-based verification for smaller organizations, each growing faster than the overall market because they combine stronger fraud protection with lower friction for the user. Compliance obligations around know-your-customer and anti-money laundering controls keep verification spending non-discretionary, while rising deepfake and synthetic identity attacks raise the technical bar. The market is projected to reach USD 1,005.3 Million by 2034. Biometrics at 56.4% leads through accuracy and convenience advantages. Large Enterprises at 64.2% anchor spending through regulated, high-volume onboarding. Australia Capital Territory & New South Wales leads regionally at 37.2%.
Key Market Insights
| Insight | Data |
|---|---|
| Dominant Type | Biometrics - 56.4% share (2025) |
| Dominant Organization Size | Large Enterprises - 64.2% market share (2025) |
| Leading Region | Australia Capital Territory & New South Wales - 37.2% share (2025) |
| Market Opportunity | Digital identity wallets, SME cloud verification, deepfake-resistant liveness, continuous authentication |
Key Analytical Observations Supporting the Above Data:
- Biometrics at 56.4%: Facial and fingerprint matching delivers higher assurance and faster onboarding than knowledge-based checks, and mobile device sensors make capture ubiquitous, so organizations default to biometrics for high-risk and high-volume journeys.
- Large Enterprises at 64.2%: Banks, insurers, telecommunications carriers and government bodies face the strictest compliance duties and the largest onboarding volumes, which concentrates verification spending in enterprises able to fund integrated platforms.
- Australia Capital Territory & New South Wales at 37.2%: Head offices of major banks, federal agencies and a dense technology and fintech community concentrate buyers and vendors, sustaining the highest regional adoption and procurement activity.
Australia Identity Verification Market Overview
The Australia identity verification market covers technologies and services that confirm a person is who they claim to be during onboarding, authentication and ongoing account activity. It spans biometric methods such as facial recognition, fingerprint and voice matching, and non-biometric methods including document verification, database checks, knowledge-based questions and one-time passcodes. Buyers include banks, insurers, telecommunications providers, government agencies, online retailers, gaming operators, healthcare organizations and employers. Vendors range from global identity platforms to domestic specialists integrating with national document and credential databases. Demand is shaped by anti-money laundering rules, privacy law, the national digital identity framework and escalating fraud. Delivery has shifted toward cloud application programming interfaces, software development kits embedded in mobile apps and managed services, allowing identity verification solutions to scale quickly across channels while keeping user friction low.
Market Dynamics
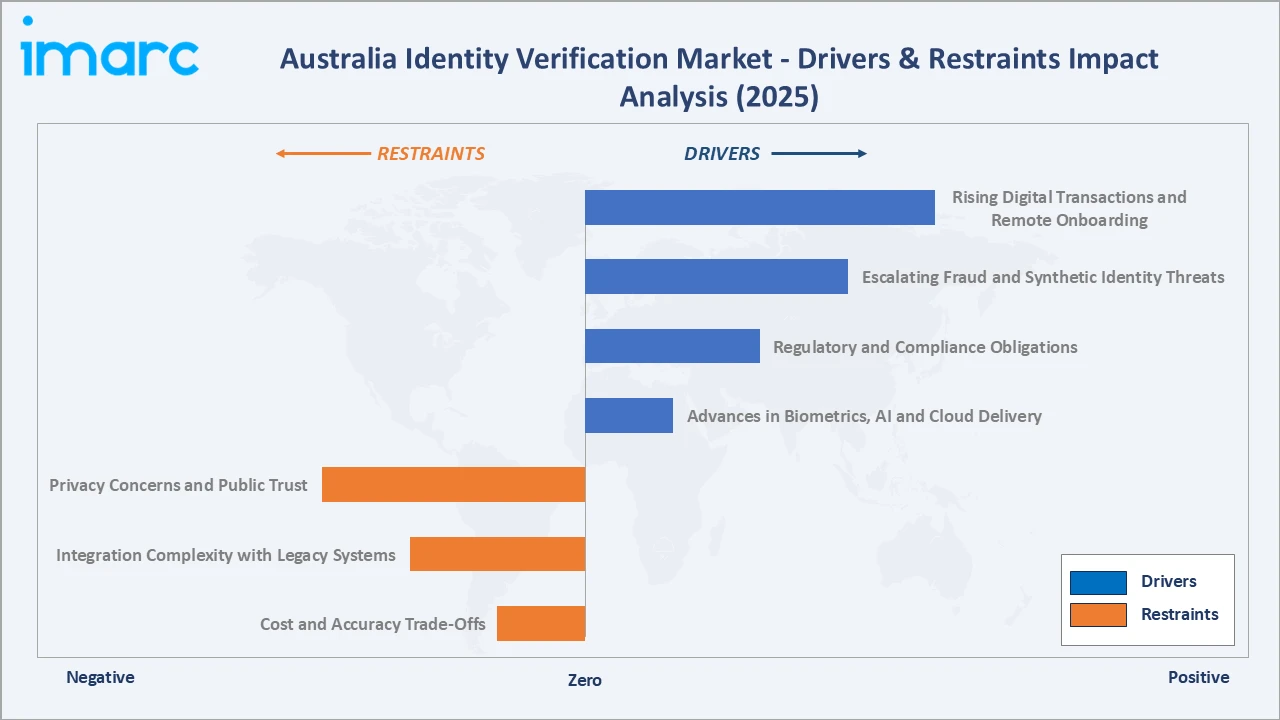
To evaluate market opportunities, Request Sample
Market Drivers
- Rising Digital Transactions and Remote Onboarding: Customers increasingly open accounts, apply for credit, register devices and access public services entirely online, removing the in-person document check that once anchored identity assurance. Each remote journey requires reliable verification at the start and at later risk points, so growth in digital activity converts directly into verification volume. Organizations also use verification to reduce abandonment by making onboarding faster, which links identity performance to revenue. Expansion of mobile banking, buy-now-pay-later, online marketplaces and telehealth keeps adding new use cases across the identity verification market.
- Escalating Fraud and Synthetic Identity Threats: Account takeover, document forgery, synthetic identities and deepfake media are rising in sophistication, and losses create strong pressure on risk and compliance teams to upgrade defenses. Static credentials and knowledge-based questions are increasingly compromised through data breaches, so organizations layer biometrics, liveness detection, device intelligence and behavioral signals. Fraud economics favor investment in prevention because remediation, customer compensation and reputational damage cost more than verification. This pressure sustains spending even when broader technology budgets tighten.
- Regulatory and Compliance Obligations: Anti-money laundering and counter-terrorism financing duties require reporting entities to verify customer identity, and the scope of regulated sectors continues to widen. Privacy and cyber security expectations push organizations toward minimizing stored personal data and adopting privacy-preserving verification. The national digital identity framework and related accreditation schemes create a common trust standard that encourages reuse of verified credentials. Because compliance failure carries penalties and enforcement action, verification is treated as a non-discretionary operating cost.
- Advances in Biometrics, AI and Cloud Delivery: Improved facial recognition accuracy, liveness detection, document forensics and machine learning risk scoring raise pass rates for genuine users while blocking attackers. Cloud-based application programming interfaces and mobile software development kits cut integration time and cost, extending access to mid-sized organizations. Better camera quality on mainstream smartphones, 5G connectivity and on-device processing support smoother capture. These technology gains lower friction and expand the addressable base of buyers for identity verification solutions.
Market Restraints
- Privacy Concerns and Public Trust: Consumers and regulators are sensitive about the collection and storage of biometric and identity documents, particularly after high-profile data breaches. Organizations must justify data collection, limit retention and obtain meaningful consent, which adds design effort and can slow deployment. Public skepticism toward facial recognition and centralized databases can lead to opt-outs, alternative manual channels and political scrutiny. These concerns raise compliance cost and may delay projects that depend on broad biometric adoption.
- Integration Complexity with Legacy Systems: Many large organizations operate fragmented core platforms, onboarding tools and case management systems that were not designed for modern verification services. Integrating new verification layers requires customization, data mapping and testing, which lengthens deployment timelines and increases cost. Inconsistent data quality across internal systems can reduce match rates. Smaller vendors may struggle to meet enterprise integration demands, and switching providers later can be disruptive, which makes buyers cautious.
- Cost and Accuracy Trade-Offs: Advanced biometric and liveness solutions carry per-transaction fees and implementation costs that can be difficult for smaller organizations to justify. Accuracy gaps across lighting conditions, device quality and demographic groups can produce false rejections that frustrate genuine users and require manual review. Balancing stringent fraud controls against customer experience forces ongoing tuning and operating cost. These trade-offs slow adoption among cost-sensitive buyers and prolong procurement decisions.
Market Opportunities
- Reusable Digital Identity and Credential Wallets: Government-backed digital identity and verifiable credential wallets allow people to prove attributes once and share them securely many times. Organizations that integrate with these ecosystems can cut onboarding cost, reduce stored data and improve assurance. Vendors able to orchestrate multiple credential sources, document checks and biometrics within one journey are well placed to capture recurring transaction revenue as reuse grows and trust frameworks mature.
- SME and Mid-Market Cloud Verification: Smaller organizations face the same fraud and compliance pressures as large firms but lack engineering resources. Packaged, pay-as-you-go verification delivered through simple application programming interfaces and no-code tools opens a large underpenetrated base. Vendors that bundle onboarding, screening and monitoring with transparent pricing can scale quickly across fintech, property, legal, gaming and marketplace segments.
- Deepfake-Resistant and Continuous Authentication: As generative media undermines selfie and video checks, demand is rising for injection attack detection, advanced liveness, device binding and continuous behavioral authentication. Solutions that verify not only the initial identity but also ongoing session integrity address a growing gap. Providers investing in adversarial testing and certification can differentiate and command premium pricing in high-risk sectors.
Market Challenges
- Evolving Attack Techniques: Fraudsters adapt quickly, using generative tools, injection attacks and stolen credentials to bypass controls. Vendors must continuously retrain models, update detection and share threat intelligence, which raises research and operating cost. Any publicized bypass can damage confidence in a method and trigger reassessment by buyers and regulators.
- Shortage of Skilled Talent: Building and operating biometric, machine learning and security systems requires scarce specialists in data science, cyber security and compliance. Competition from other technology sectors raises salaries and slows hiring. Organizations without internal capability depend on vendors, which can create concentration and dependency risks.
- Fragmented Standards and Data Sources: Identity data sits across government, financial and commercial databases with varying access rules, formats and quality. Gaining permitted access to authoritative sources can be slow, and differing assurance standards complicate cross-sector reuse. This fragmentation increases integration effort and limits how quickly seamless verification can scale.
Emerging Market Trends
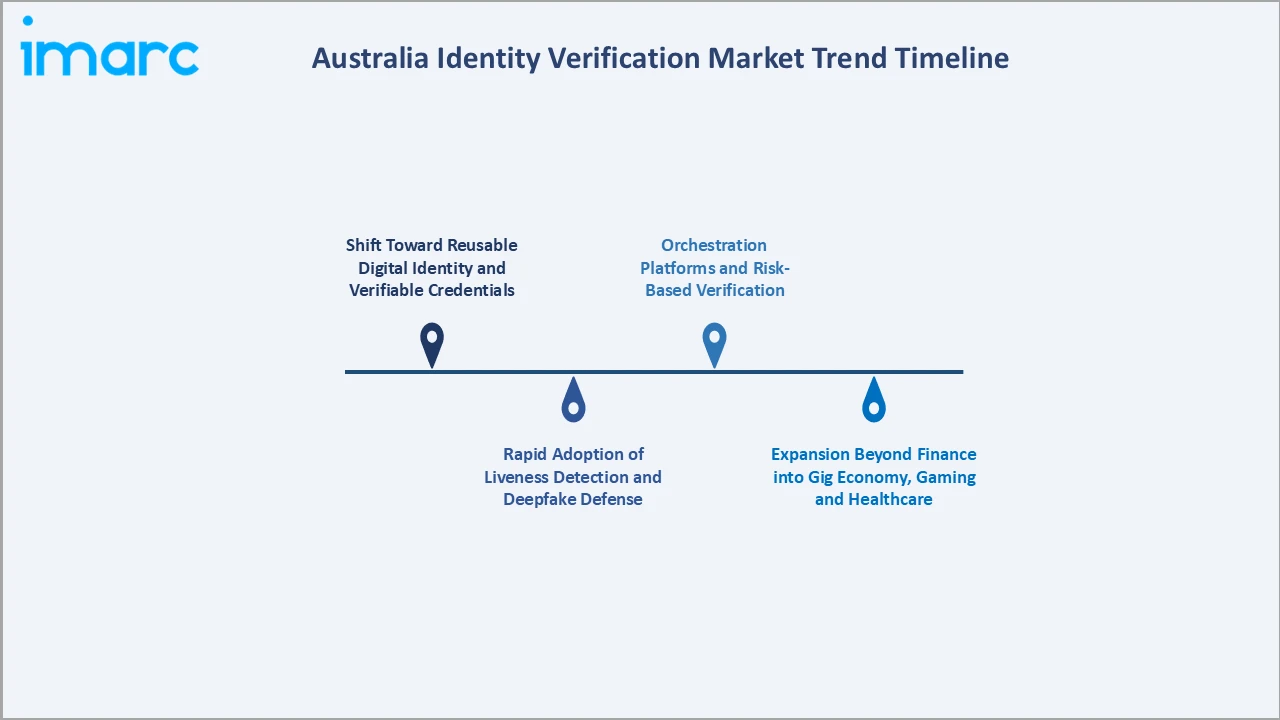
1. Shift Toward Reusable Digital Identity and Verifiable Credentials
Organizations are moving away from repeated document collection toward verified credentials that individuals can store in digital wallets and share selectively. This reduces onboarding time, lowers data storage liability and improves assurance because attributes are cryptographically signed by issuers. Banks, telecommunications providers and government services are piloting and integrating wallet-based flows alongside traditional checks. As accreditation frameworks mature, vendors are adding credential verification, consent management and orchestration layers. The trend is gradually changing identity from a one-time gate into a portable, user-controlled asset that cuts cost per verification.
2. Rapid Adoption of Liveness Detection and Deepfake Defense
Generative media has made simple selfie matching insufficient, so providers are layering active and passive liveness, injection attack detection, device integrity checks and metadata analysis. Buyers increasingly request independent testing and certification against presentation attack standards. Vendors are also using multimodal signals, combining face, voice and behavioral cues, to raise the cost of attack. This arms race is making advanced liveness a baseline requirement in finance, gaming and government use cases and is shifting competition toward detection quality rather than basic matching.
3. Orchestration Platforms and Risk-Based Verification
Instead of applying the same checks to every customer, organizations use orchestration platforms that route each journey through the lightest sufficient set of controls based on real-time risk. Low-risk users pass with minimal friction while higher-risk cases trigger biometrics, document review or manual escalation. Orchestration also lets buyers swap or combine vendors without rebuilding integrations. This approach improves conversion, controls cost and supports continuous improvement through analytics, and it is becoming a central design pattern for enterprise identity architecture.
4. Expansion Beyond Finance into Gig Economy, Gaming and Healthcare
Verification demand is spreading from banks and telecommunications into online marketplaces, gig work platforms, age-restricted services, gaming, property rental and telehealth. These sectors need to confirm identity, age and eligibility at scale while preserving smooth user experience. Regulatory focus on online safety and age assurance is accelerating adoption. Vendors are packaging sector-specific templates, workforce right-to-work checks and age estimation tools, which broadens the customer base and diversifies revenue away from a heavy reliance on financial services.
Industry Value Chain Analysis
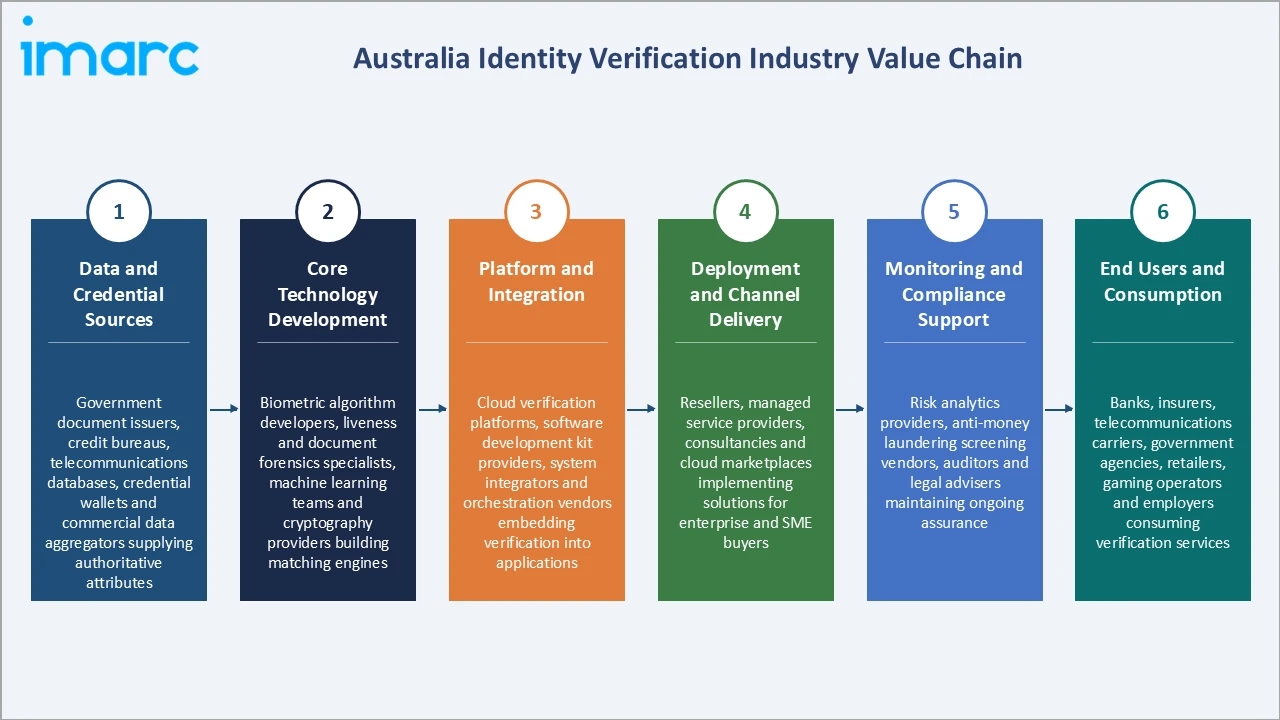
The industry value chain spans data and credential sourcing, technology development, platform integration, deployment and orchestration, ongoing monitoring and compliance support, and end-user consumption. Value accumulates as raw identity signals are converted into trusted, auditable decisions delivered with low friction inside customer journeys.
| Stage | Key Participants |
|---|---|
| Data and Credential Sources | Government document issuers, credit bureaus, telecommunications databases, credential wallets and commercial data aggregators supplying authoritative attributes |
| Core Technology Development | Biometric algorithm developers, liveness and document forensics specialists, machine learning teams and cryptography providers building matching engines |
| Platform and Integration | Cloud verification platforms, software development kit providers, system integrators and orchestration vendors embedding verification into applications |
| Deployment and Channel Delivery | Resellers, managed service providers, consultancies and cloud marketplaces implementing solutions for enterprise and SME buyers |
| Monitoring and Compliance Support | Risk analytics providers, anti-money laundering screening vendors, auditors and legal advisers maintaining ongoing assurance |
| End Users and Consumption | Banks, insurers, telecommunications carriers, government agencies, retailers, gaming operators and employers consuming verification services |
Platform and integration is the most commercially critical stage, because it determines how seamlessly accuracy and compliance are embedded into customer journeys, and therefore drives conversion, switching costs and recurring transaction revenue.
Technology Landscape in the Australia Identity Verification Industry
Facial Recognition and Liveness Detection
Facial matching compares a live capture with a trusted document photo or enrolled template, while liveness detection confirms a real person is present rather than a photo, video or synthetic injection. Deep learning has raised accuracy across lighting conditions and device types, and passive liveness reduces user effort. Providers now test against presentation attack standards and add injection attack defenses to counter deepfakes. Adoption is strongest in banking onboarding, telecommunications and government services, where assurance requirements are high and mobile capture is universal.
Document Authentication and Optical Character Recognition
Document verification uses image analysis, optical character recognition and forensic checks of security features, fonts and data consistency to detect forged or altered licenses and passports. Systems cross-check extracted data against issuer databases and machine-readable zones, and NFC chip reading of passports adds cryptographic assurance. Machine learning models retrain on emerging fraud patterns to maintain detection rates. This layer is foundational because most remote onboarding still begins with a government-issued document, making accuracy and speed central to conversion.
AI-Driven Risk Scoring and Behavioral Analytics
Machine learning models combine device intelligence, network signals, behavioral biometrics and historical patterns to score the risk of each interaction in real time. This allows organizations to apply friction only when needed and to detect account takeover during sessions, not only at entry. Continuous learning improves detection as attackers evolve. Integration with orchestration platforms lets risk scores trigger step-up verification automatically, supporting both fraud reduction and a smoother experience for legitimate customers.
Verifiable Credentials and Privacy-Preserving Cryptography
Verifiable credentials, digital wallets and cryptographic techniques such as selective disclosure and zero-knowledge proofs let individuals prove attributes without revealing full documents. Issuers sign credentials, and verifiers check authenticity instantly, reducing stored personal data and breach exposure. These technologies align with privacy expectations and the national digital identity framework. Adoption is early but accelerating as accredited providers expand, positioning credential verification as a long-term foundation for reusable, low-friction identity assurance across sectors.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Type | Biometrics | 56.4% | 2025 |
| Component | 🔒 | 🔒 | 2025 |
| Deployment Mode | 🔒 | 🔒 | 2025 |
| Vertical | 🔒 | 🔒 | 2025 |
| Organization Size | Large Enterprises | 64.2% | 2025 |
| Region | Australia Capital Territory & New South Wales | 37.2% | 2025 |

By Type
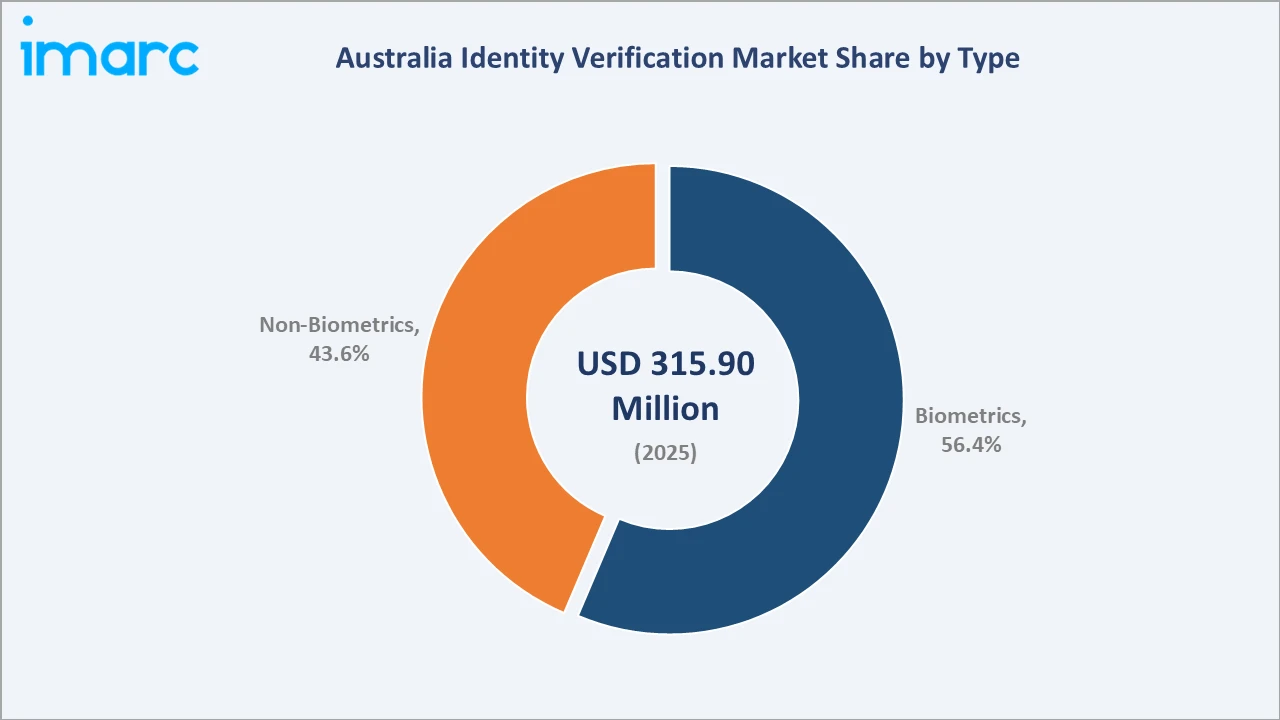
Biometrics leads at 56.4% (2025). The segment benefits from higher assurance than knowledge-based methods, universal smartphone cameras and sensors, and strong fit with remote onboarding. Organizations also favor biometrics because it reduces friction and resists credential theft, supporting steady adoption across regulated and consumer journeys.
To access detailed market analysis, Request Sample
Biometrics is the fastest-growing type at ~14.6% CAGR, as mobile facial authentication, advanced liveness and passkey-style device biometrics spread across finance, government and consumer applications. Falling processing costs and improving accuracy broaden use beyond high-risk journeys into everyday authentication.
By Organization Size
Large Enterprises lead at 64.2% (2025). Banks, insurers, telecommunications carriers and government bodies operate under the strictest compliance duties and process the largest onboarding volumes, so they fund integrated, multi-layered platforms and long-term vendor relationships that concentrate spending in this segment.
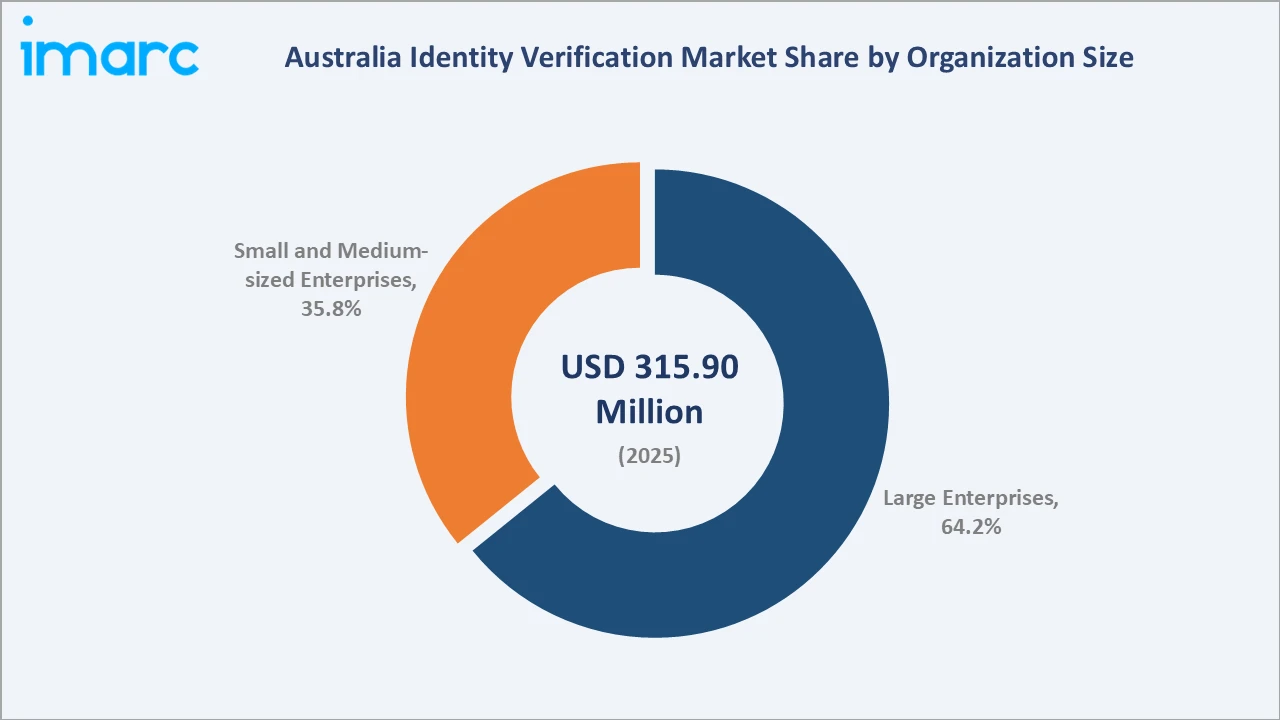
Small and Medium-sized Enterprises are the fastest-growing group at ~14.8% CAGR, as cloud application programming interfaces, pay-as-you-go pricing and no-code tools make verification affordable. Growing compliance reach and fraud exposure among fintechs, marketplaces and service firms further widen adoption.
Regional Market Insights
| Region | Share (2025) | Key Drivers & Characteristics |
|---|---|---|
| Australia Capital Territory & New South Wales | 37.2% | Major bank headquarters, federal agencies, fintech hubs and dense enterprise procurement in Sydney and Canberra |
| Victoria & Tasmania | 26.4% | Melbourne financial services, insurance and technology clusters plus growing state digital service programs |
| Queensland | 17.1% | Expanding population, tourism, gaming and retail sectors driving online onboarding and age verification |
| Western Australia | 12.3% | Resources sector workforce screening, contractor onboarding and growing regional banking digitization |
| Northern Territory & Southern Australia | 7.0% | Government service delivery, remote-access needs and smaller but steadily digitizing enterprise base |
Australia Capital Territory & New South Wales accounts for 37.2% of the market, supported by the concentration of bank headquarters, federal agencies and fintech activity that anchors enterprise identity verification solutions procurement. Victoria & Tasmania holds 26.4%, driven by Melbourne's financial services and insurance base and expanding state digital service programs.
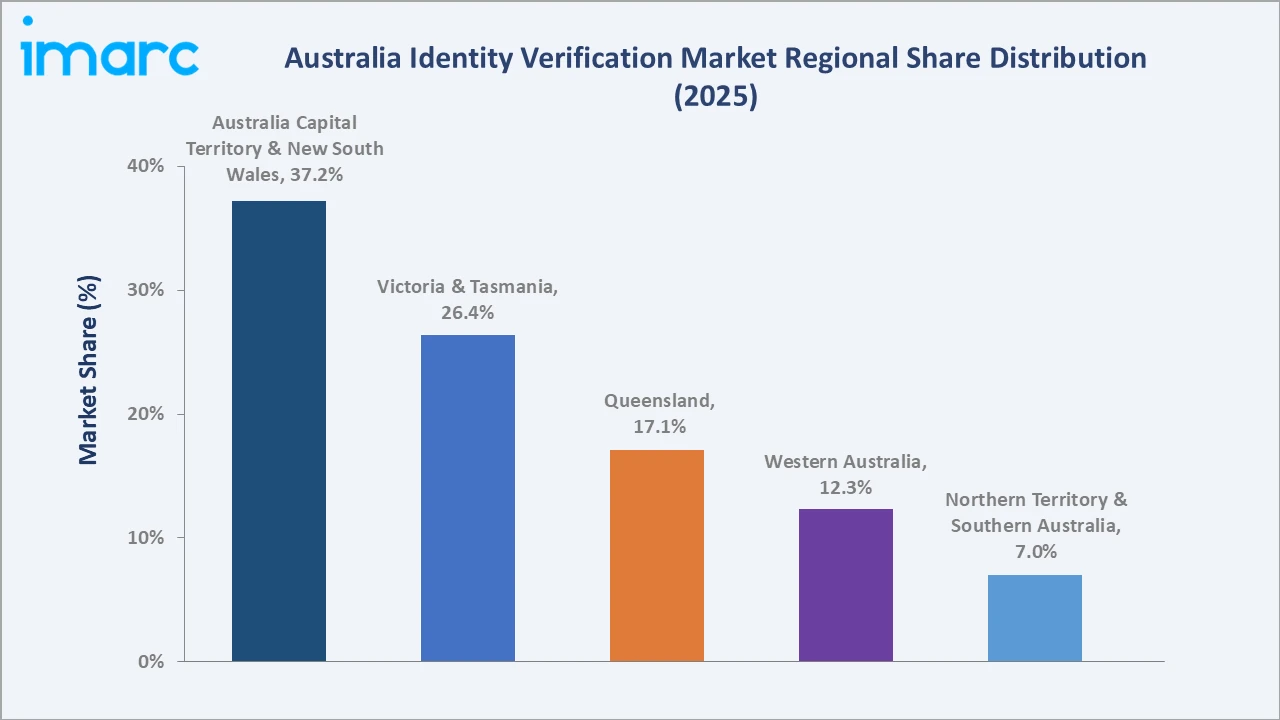
Queensland contributes 17.1% through population growth and online retail, gaming and tourism demand. Western Australia holds 12.3%, shaped by resources workforce screening, while Northern Territory & Southern Australia represents 7.0% with steady growth from government service digitization.
Competitive Landscape
The competitive landscape is moderately fragmented, combining global identity platforms, domestic specialists and credit bureau-linked data providers. Vendors compete on verification accuracy, access to authoritative data sources, accreditation status, integration ease and fraud detection depth, while buyers increasingly favor orchestration and multi-vendor flexibility.
| Company | Key Brands | Market Position | Core Strength |
|---|---|---|---|
| Equifax Pty Ltd | Equifax IDMatrix, Equifax Protect | Market Leader | Bureau data access and widely deployed identity and fraud checks for regulated buyers |
| Experian Australia Pty Ltd | Experian Identity Verification, CrossCore | Strong Challenger | Data-driven fraud orchestration and document verification for banks and lenders |
| GBG (GB Group) Australia | GBG Trust, IDscan, Greenid | Strong Challenger | Domestic electronic verification and global document and biometric identity coverage |
| Entrust Corporation | Onfido Real Identity Platform | Innovator | AI-driven document and biometric verification with strong liveness capability |
| Mastercard Australia Pty Ltd | Mastercard ID, Ekata | Established Player | Network scale, identity signals and digital identity services for financial institutions |
The most commercially significant dynamic is the contest between bureau-linked data providers, which hold authoritative records and regulated customer relationships, and technology-led biometric specialists, which compete on user experience and attack resistance. Buyers increasingly combine both through orchestration platforms, favoring vendors that integrate quickly and support accredited digital identity ecosystems. Consolidation through acquisition of specialist capabilities is giving large players broader portfolios, while open application programming interfaces are lowering switching costs and sharpening competition on accuracy, price per verification and fraud outcomes.
Key Company Profiles
Equifax Pty Ltd
Equifax Pty Ltd is the Australian arm of a global data and analytics group and a leading provider of credit, identity and fraud solutions to banks, lenders, telecommunications carriers and government clients, with strong positioning in electronic identity verification.
- Key Brands: Equifax IDMatrix, Equifax Protect.
- Recent Developments: In 2026, Equifax Australia announced its myVerified Pass digital identity verification solution, targeting a Q4 2026 market launch. The platform will allow consumers to verify their identity through the myEquifax application and securely share selected identity attributes with participating businesses without repeatedly submitting physical identity documents. It incorporates biometric liveness detection, deepfake detection and automated KYC capabilities to streamline customer onboarding and strengthen fraud prevention.
- Strategic Focus: The company is prioritizing cloud migration, deeper integration of bureau data with biometric verification and fraud analytics, and partnerships that extend coverage to digital identity ecosystems while maintaining compliance credentials.
Experian Australia Pty Ltd
Experian Australia Pty Ltd provides credit information, decisioning and identity and fraud solutions to financial institutions, retailers and telecommunications providers, and is a significant participant in Australian identity verification through data-driven risk tools.
- Key Brands: Experian Identity Verification, CrossCore.
- Recent Developments: On 24 June 2026, Experian announced a regional partnership with Resistant AI to introduce AI-powered document fraud detection capabilities across Australia and New Zealand. The solution, Resistant AI Documents, will help banks, lenders and insurers identify fake, manipulated and AI-generated documents, including identity documents and bank statements. The technology will strengthen KYC checks, identity verification and fraud prevention during digital customer onboarding.
- Strategic Focus: Experian is focused on orchestration through CrossCore, expanding data partnerships, strengthening synthetic identity detection and supporting customers with unified fraud and identity decisioning across onboarding and account lifecycle.
GBG (GB Group) Australia
GBG operates an established Australian identity business, including the Greenid electronic verification service widely used by reporting entities, and combines local data coverage with global document and biometric technology.
- Key Brands: GBG Trust, IDscan, Greenid.
- Recent Developments: In 2026, GBG partnered with Realeyes to integrate privacy-preserving biometric face credentials into its GBG Go platform. The solution uses a brief selfie-based verification process to confirm that the same individual remains behind an account during subsequent interactions. Initial capabilities include duplicate-account detection and risk-triggered reverification, supporting continuous identity verification and account takeover prevention.
- Strategic Focus: GBG is concentrating on platform consolidation, expanding biometric and liveness capabilities, strengthening local data sources and supporting digital identity schemes to serve regulated sectors and growing online platforms.
Market Concentration Analysis
The Australia identity verification market is moderately fragmented. Bureau-linked providers such as Equifax and Experian hold the strongest positions through authoritative data access and entrenched relationships with regulated buyers, with the leading provider estimated to hold roughly 15% to 22% of revenue, while many specialists share the remainder across niches such as biometrics, document verification and age assurance.
Two opposing forces are reshaping concentration. Incumbents are consolidating through acquisitions, platform bundling and orchestration, which broadens portfolios and raises integration barriers. At the same time, innovation-led entrants and open application programming interfaces lower switching costs and enable focused vendors to win on deepfake defense, user experience and pricing.
Investment & Growth Opportunities
Highest Growth Segments
Small and Medium-sized Enterprises at ~14.8% CAGR and Biometrics at ~14.6% CAGR are the primary investment vectors through 2034, followed by Large Enterprises at ~12.4% and Non-Biometrics at ~11.6%. These segments grow fastest because demand pull is strongest where fraud exposure and compliance duties rise faster than internal capability, and because cloud delivery and falling per-transaction cost widen the buyer base. Capacity and performance gains from better matching accuracy, passive liveness and orchestration platforms raise conversion and lower operating cost, improving customer economics. Modernization of legacy onboarding journeys, supportive policy through digital identity frameworks and rising private investment accelerate adoption, while structural shifts toward mobile-first service delivery and reusable credentials increase recurring transaction volumes. Capital is therefore concentrating in biometric and SME-oriented platforms, where scalable software margins and recurring revenue support attractive returns through 2034.
Emerging Investment Opportunities
The most dynamic emerging opportunity is deepfake-resistant liveness and reusable digital credential orchestration. It scales fastest across financial services, online marketplaces and age-restricted platforms, where assurance needs are high and verification volumes are large and recurring.
Investment Themes
- Biometric and liveness innovation: Investment in injection attack detection and passive liveness protects conversion and trust, and differentiates vendors as deepfake threats grow.
- SME cloud verification platforms: Packaged, usage-priced services unlock a large underpenetrated buyer base with scalable, recurring software revenue.
- Digital credential and orchestration infrastructure: Platforms that unify credentials, documents and risk signals reduce friction and switching costs, creating durable positions as reuse expands.
Future Market Outlook (2026-2034)
The Australia identity verification market is projected to grow from USD 315.9 Million in 2025 to USD 357.9 Million in 2026, reaching USD 1,005.3 Million by 2034, registering a CAGR of 13.32% during 2026-2034. The market's anchor value of USD 590.2 Million in 2030 reflects durable, compliance-led and fraud-driven demand as digital services, reusable credentials and biometric adoption deepen, with Australia Capital Territory & New South Wales and Victoria & Tasmania sustaining leadership.
Three structural forces define market growth through 2034 tightening regulation and rising fraud that make verification non-discretionary; maturing digital identity and credential ecosystems that enable reuse and lower friction; and continuous advances in biometrics, liveness and AI that raise assurance and widen adoption.
Research Methodology
Primary Research
Primary research included discussions with risk, compliance and technology leaders at Australian banks, telecommunications providers, government agencies and identity vendors, focused on use cases, procurement criteria, accuracy performance and regulatory impact.
Secondary Research
Secondary research drew on regulatory publications, company disclosures, industry association materials and trade press, triangulated to establish type and organization size splits and the regional distribution of identity verification spending in Australia.
Forecasting Models
Forecasting combined verification volume modeling by use case with adoption curves for biometrics and digital credentials, producing yearly values from 2026 to 2034 and segment growth paths reconciled to the overall market CAGR.
Australia Identity Verification Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Biometrics, Non-Biometrics |
| Components Covered | Solutions, Services |
| Deployment Modes Covered | On-premises, Cloud-based |
| Organization Sizes Covered | Small and Medium-sized Enterprises, Large Enterprises |
| Verticals Covered | BFSI, Government and Defense, Healthcare and Life Sciences, Retail and E-Commerce, IT and Telecommunications, Energy and Utilities, Others |
| Regions Covered | Australia Capital Territory & New South Wales, Victoria & Tasmania, Queensland, Northern Territory & Southern Australia, Western Australia |
| Companies Covered | Equifax Pty Ltd, Experian Australia Pty Ltd, GBG (GB Group) Australia, Entrust Corporation, Mastercard Australia Pty Ltd, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Australia identity verification market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Australia identity verification market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Australia identity verification industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Australia Identity Verification Market Report
The market reached USD 315.9 Million in 2025 and an estimated USD 357.9 Million in 2026, supported by remote onboarding growth, rising fraud pressure and expanding regulatory identity obligations.
The market is expected to register a CAGR of 13.32% during 2026-2034, rising from USD 357.9 Million in 2026 to reach USD 1,005.3 Million by 2034.
Biometrics leads the type segment with a 56.4% share in 2025, driven by higher assurance, smartphone-based capture and strong fit with remote onboarding journeys.
Large Enterprises lead the organization size segment with a 64.2% share in 2025, reflecting strict compliance duties and high-volume onboarding at banks, telecommunications carriers and government bodies.
Australia Capital Territory & New South Wales leads with a 37.2% regional share in 2025, supported by bank headquarters, federal agencies and a dense fintech and technology community.
Leading companies include Equifax Pty Ltd, Experian Australia Pty Ltd, GBG (GB Group) Australia, Onfido, Mastercard Australia Pty Ltd, Daon Pty Ltd and IDEMIA Public Security, among others.
The market is projected to reach USD 590.2 Million by 2030, driven by expanding digital services, wider biometric adoption and growth of reusable digital identity credentials.
Small and Medium-sized Enterprises at ~14.8% CAGR and Biometrics at ~14.6% CAGR are the fastest-growing segments, alongside deepfake-resistant liveness and digital credential orchestration platforms.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade