Australia Women Apparel Market Size, Share, Trends and Forecast by Product Type, Season, Distribution Channel, and Region, 2026-2034
Australia Women Apparel Market Size, Share, Trends & Forecast (2026-2034)
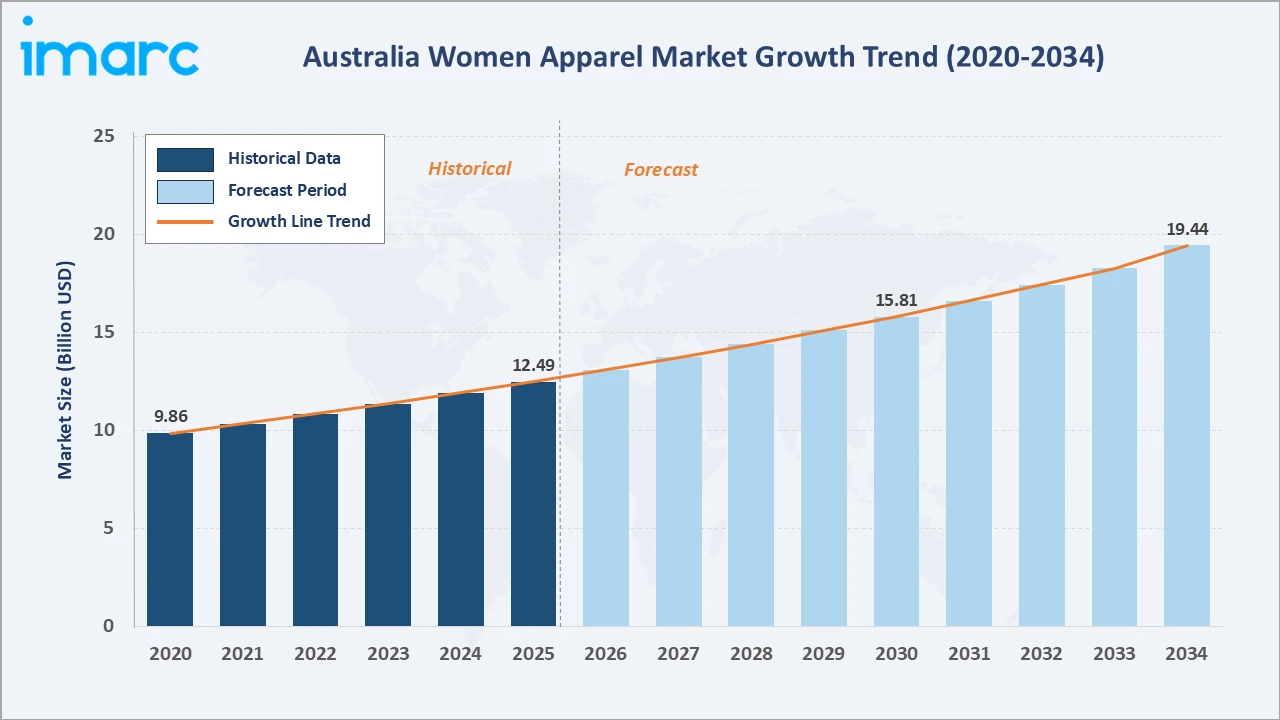
The Australia women apparel market grew from USD 12.49 Billion in 2025 to USD 13.09 Billion in 2026 and is projected to reach USD 19.44 Billion by 2034, exhibiting a CAGR of 4.84% during 2026-2034. Rising female workforce participation, accelerating e-commerce penetration, surging demand for premium and sustainable fashion, and the expanding influence of social media on purchasing behavior are the primary forces shaping market growth.
Tops and dresses lead the product type segment at 35.5%, while all season wear commands 45.7% of the season segment. Australia Capital Territory & New South Wales holds the largest regional share at 32.5%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 12.49 Billion |
|
Market Size (2026) |
USD 13.09 Billion |
|
Forecast Market Size (2034) |
USD 19.44 Billion |
|
CAGR (2026-2034) |
4.84% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Australia Capital Territory & New South Wales (32.5%, 2025) |
|
Second Largest Region |
Victoria & Tasmania (27.5%, 2025) |
|
Leading Product Type |
Tops and Dresses (35.5%, 2025) |
|
Leading Season |
All Season Wear (45.7%, 2025) |
The Australia women apparel market size increased from USD 9.86 Billion in 2020 to USD 12.49 Billion in 2025 and is estimated to reach USD 13.09 Billion in 2026. The market is further expected to grow to USD 15.81 Billion by 2030 and USD 19.44 Billion by 2034. This growth trajectory reflects sustained consumer demand, structural expansion of digital retail channels, and increasing participation of women in Australia's professional workforce across metropolitan and regional centers.
To get more information on this market, Request Sample
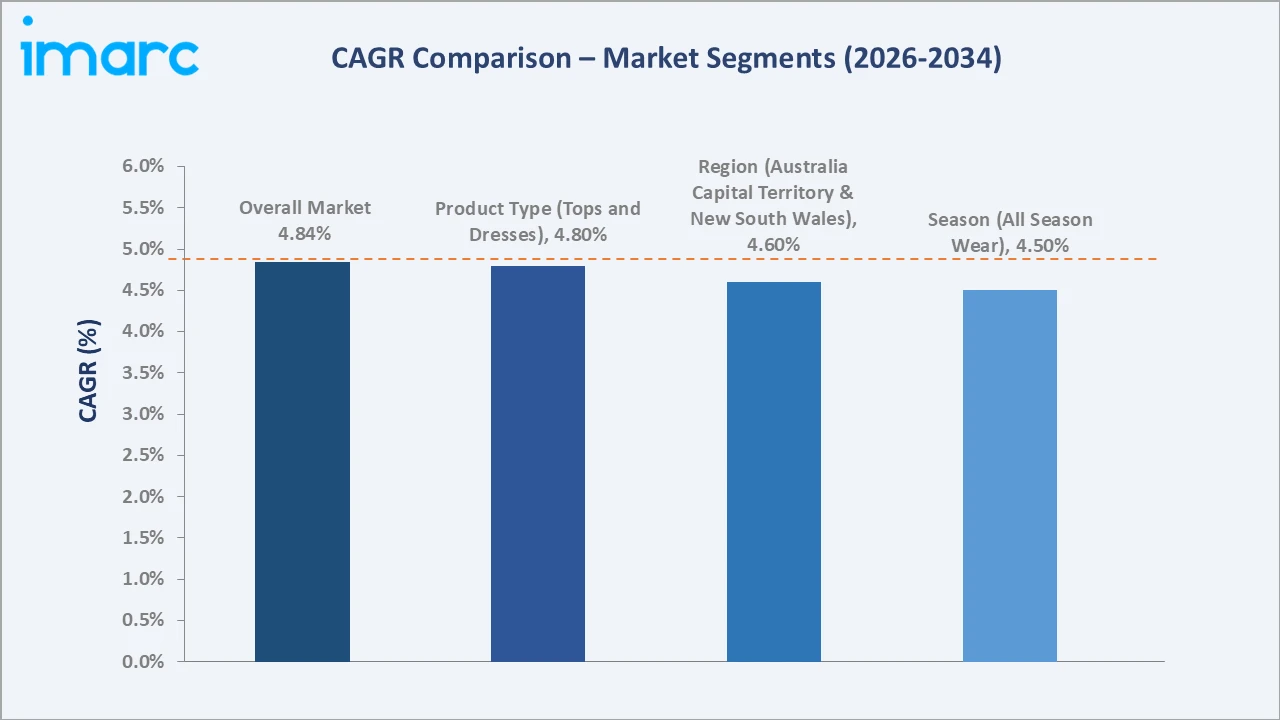
CAGR trajectories across product type, season, and regional sub-segments show ethnic wear and Western Australia expanding faster than the overall 4.84% market CAGR, driven by growing multicultural consumer demand, favorable demographic trends, and expanding digital commerce infrastructure across Australian states.
Executive Summary
The Australia women apparel market expanded from USD 12.49 Billion in 2025 to an estimated USD 13.09 Billion in 2026, positioning it among the fastest-growing apparel markets in the Asia-Pacific region. Rising female workforce participation, growth of digital retail, and increasing consumer investment in premium and sustainable fashion are the key drivers shaping market expansion.
Tops and dresses lead the product type segment at 35.5%, driven by strong demand across formal, casual, and social occasions. All season wear commands 45.7% of the season segment, reflecting Australian consumers' preference for versatile apparel suited to the country's diverse climate zones. Australia Capital Territory & New South Wales holds 32.5% regional share, anchored by Sydney and Canberra's concentrated consumer markets.
Key Market Insights
|
Insight |
Data |
|
Leading Product Type |
Tops and Dresses – 35.5% share (2025) |
|
Second Largest Product Type |
Bottom Wear – 24.7% share (2025) |
|
Leading Season |
All Season Wear – 45.7% share (2025) |
|
Second Largest Season |
Summer Wear – 31.8% share (2025) |
|
Leading Region |
Australia Capital Territory & New South Wales – 32.5% share (2025) |
|
Second Largest Region |
Victoria & Tasmania – 27.5% share (2025) |
|
Top Companies |
Cotton On Group, Myer Holdings Limited, H&M Hennes & Mauritz AB, Industria de Diseño Textil, S.A. |
Key Analytical Observations Expanding On the Data Above:
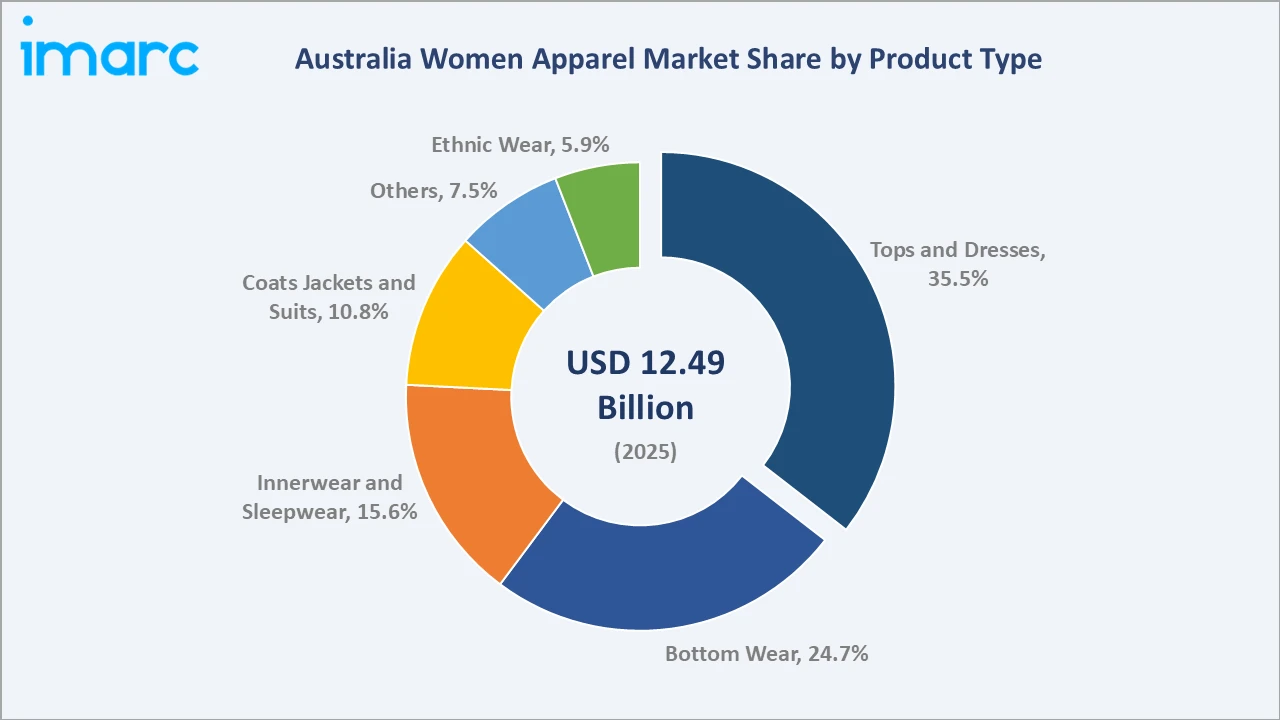
- Tops and dresses dominance at 35.5% reflects broad occasion applicability spanning professional office wear, casual outings, and social events, enabling high purchase frequency and consistent volume turnover across specialty and department store retail channels.
- Bottom wear share at 24.7% is underpinned by consistent consumer demand for denim, tailored trousers, and casual pants across all age groups, with strong performance in both physical and e-commerce retail formats.
- All season wear leadership at 45.7% reflects Australian consumers' preference for versatile, multi-purpose garments that can be styled across the country's varied climate conditions throughout the year.
- Summer wear at 31.8% is supported by Australia's predominantly warm climate, strong domestic tourism activity, and growing demand for lightweight, casual, and activewear-inspired collections across metropolitan consumer markets.
- Australia Capital Territory & New South Wales at 32.5% leads regional share due to its concentrated urban consumer base in Sydney and Canberra, supported by high disposable incomes and well-established retail and digital commerce infrastructure.
Australia Women Apparel Market Overview
Women apparel encompasses a broad range of garments including tops, dresses, bottoms, outerwear, innerwear, and ethnic wear, serving diverse consumer occasions from professional workwear to casual lifestyle and activewear categories. The market spans multiple price tiers from value-oriented basics to premium and luxury collections.
The Australian ecosystem integrates global raw material suppliers, domestic and overseas apparel manufacturers, multi-channel retail networks, and a rapidly growing direct-to-consumer digital commerce segment. Macro drivers including rising female workforce participation, increasing disposable incomes, and growing sustainability awareness are reshaping the market's structure and competitive dynamics.
Market Dynamics
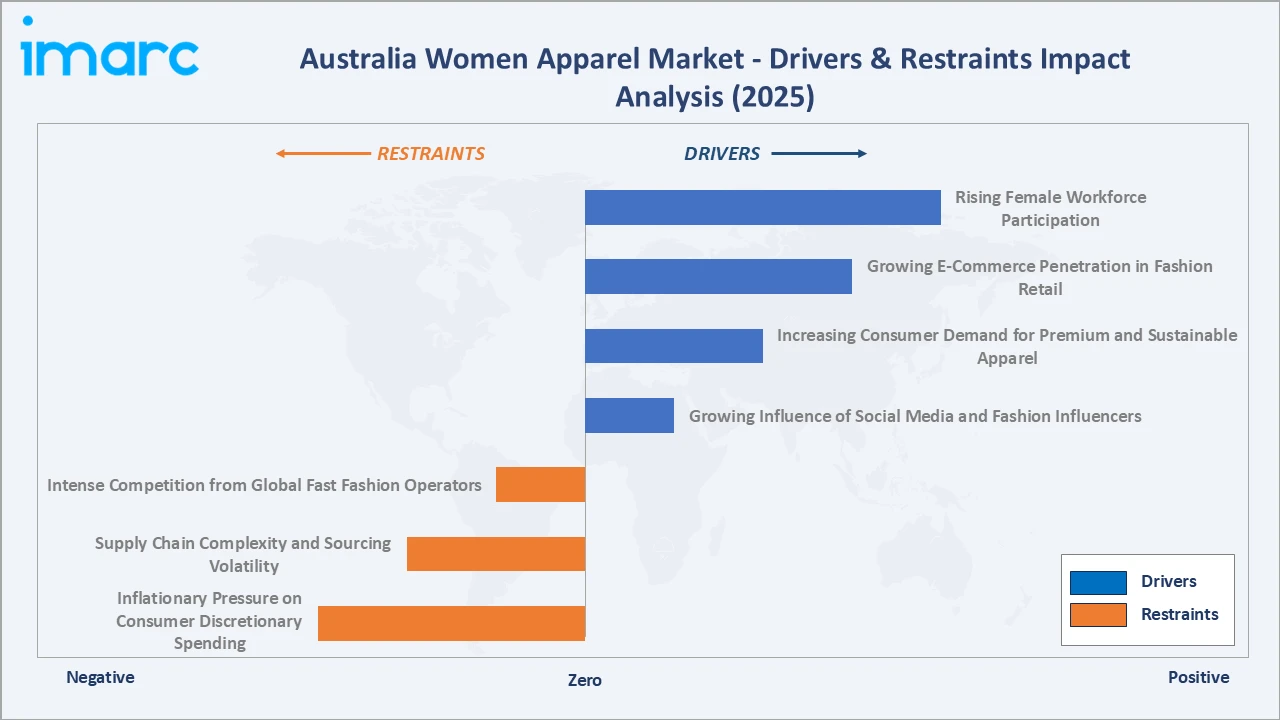
To evaluate market opportunities, Request Sample
Market Drivers
- Rising Female Workforce Participation: Australia's increasing female labor force participation is expanding the consumer base for professional and versatile women's workwear, driving consistent demand for formal, business-casual, and transitional apparel across urban retail markets. The female labor force participation rate in Australia surpassed 62.5% in 2025. This trend contributes to the growth of the Australia fashion and apparel market by encouraging demand for functional and workplace-appropriate clothing.
- Growing E-Commerce Penetration in Fashion Retail: As per IMARC Group, the Australia e-commerce market size was valued at USD 604.1 Billion in 2025. The rapid expansion of online shopping platforms and direct-to-consumer digital channels is widening market access and enabling brands to reach consumers across metropolitan and regional areas more efficiently.
- Increasing Consumer Demand for Premium and Sustainable Apparel: Rising disposable incomes and growing consumer awareness of sustainability are driving demand for higher-quality, ethically sourced women's clothing, creating opportunities for brands investing in responsible supply chains and certified sustainable product ranges.
- Growing Influence of Social Media and Fashion Influencers: Social media platforms are reshaping purchasing behavior, accelerating trend velocity, and driving demand for new seasonal collections among younger female consumer demographics across Australian urban centers.
Market Restraints
- Inflationary Pressure on Consumer Discretionary Spending: Rising cost of living is constraining discretionary apparel spending, prompting consumers to prioritize value-oriented purchases and extending replacement cycles for clothing across non-essential categories.
- Supply Chain Complexity and Sourcing Volatility: Dependence on international manufacturing and complex global sourcing networks exposes market participants to supply disruption risks, lead-time variability, and cost fluctuations that can compress operating margins.
- Intense Competition from Global Fast Fashion Operators: The presence of global fast fashion brands with large-scale sourcing advantages and strong digital marketing capabilities creates significant competitive pressure on domestic Australian women apparel players.
Market Opportunities
- Expansion of Sustainable and Ethical Fashion Collections: Growing consumer preference for certified sustainable, recycled, and ethically sourced apparel creates significant product differentiation and premium pricing opportunities for brands investing in responsible supply chains.
- Multicultural and Inclusive Sizing Market Expansion: Australia's growing multicultural population and increasing demand for inclusive sizing and diverse style offerings present significant market expansion opportunities for brands targeting underserved demographic segments.
Market Challenges
- Inventory Management in Fast-Moving Fashion Cycles: Rapidly changing consumer preferences and trend cycles shorten product life spans and create inventory markdown risk for retailers managing breadth-heavy women apparel assortments across physical and digital channels.
- Talent and Skills Gap in Sustainable Textile Innovation: Growing demand for sustainable textile expertise and digital commerce capabilities is creating skills gaps for manufacturers and retailers investing in product development and supply chain transformation.
Emerging Market Trends
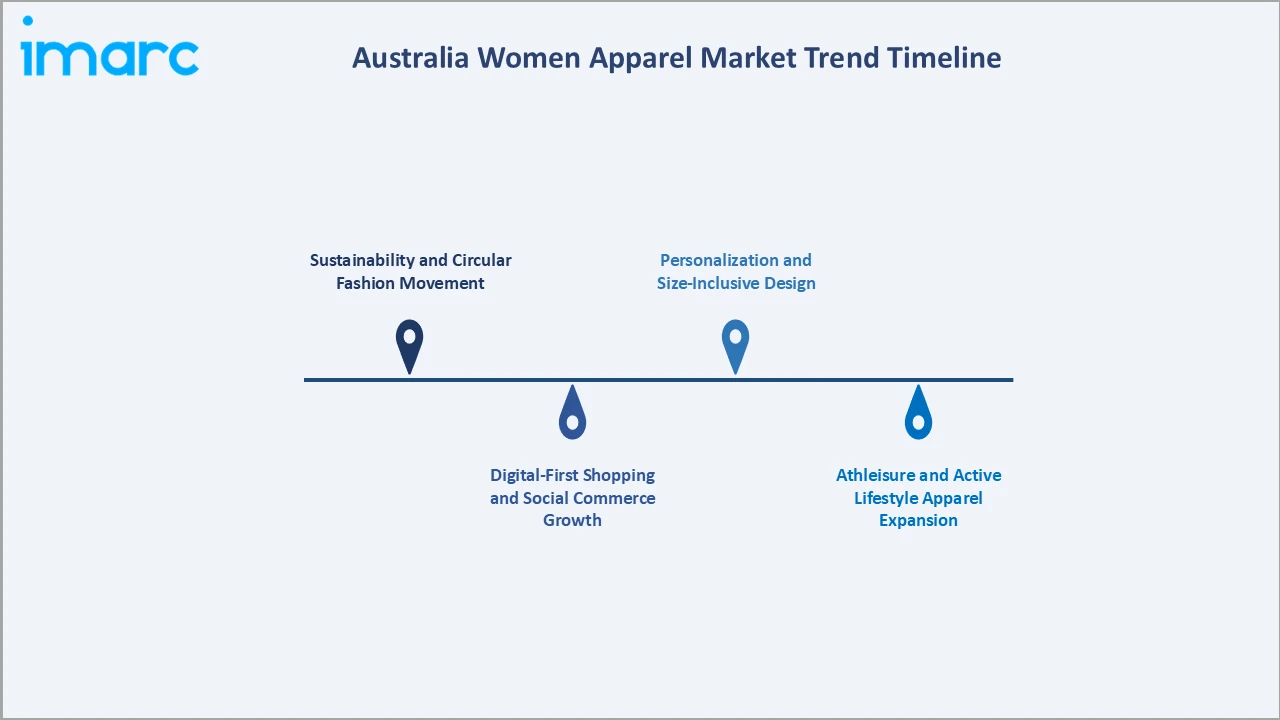
1. Sustainability and Circular Fashion Movement
Growing consumer awareness of textile waste and environmental impact is accelerating adoption of sustainable materials, take-back programs, and circular economy models within the Australia women apparel sector. Several leading retailers have committed to using recycled or sustainably sourced materials across their women's collections, including the growing Australia sleepwear market where bamboo and organic cotton are gaining significant traction, by defined timelines, reshaping sourcing priorities across the supply chain.
2. Digital-First Shopping and Social Commerce Growth
Online and mobile shopping channels are reshaping purchasing journeys, with social commerce platforms enabling seamless product discovery and purchase conversion. Brands are increasingly using personalized recommendations, influencer-led campaigns, and mobile-friendly shopping experiences to improve customer engagement and encourage repeat purchases.
3. Athleisure and Active Lifestyle Apparel Expansion
The blurring of gym wear and everyday fashion is driving strong demand growth in performance-inspired women apparel categories. Consumers are seeking garments that combine technical fabric properties with contemporary styling across casual, outdoor, and professional occasions throughout Australia's active lifestyle market.
4. Personalization and Size-Inclusive Design
Advances in AI-driven sizing tools and digital body measurement technologies are enabling retailers to offer personalized fit recommendations and expand inclusive size ranges, addressing an underserved segment of Australian women consumers and improving conversion rates across digital retail channels.
Industry Value Chain Analysis
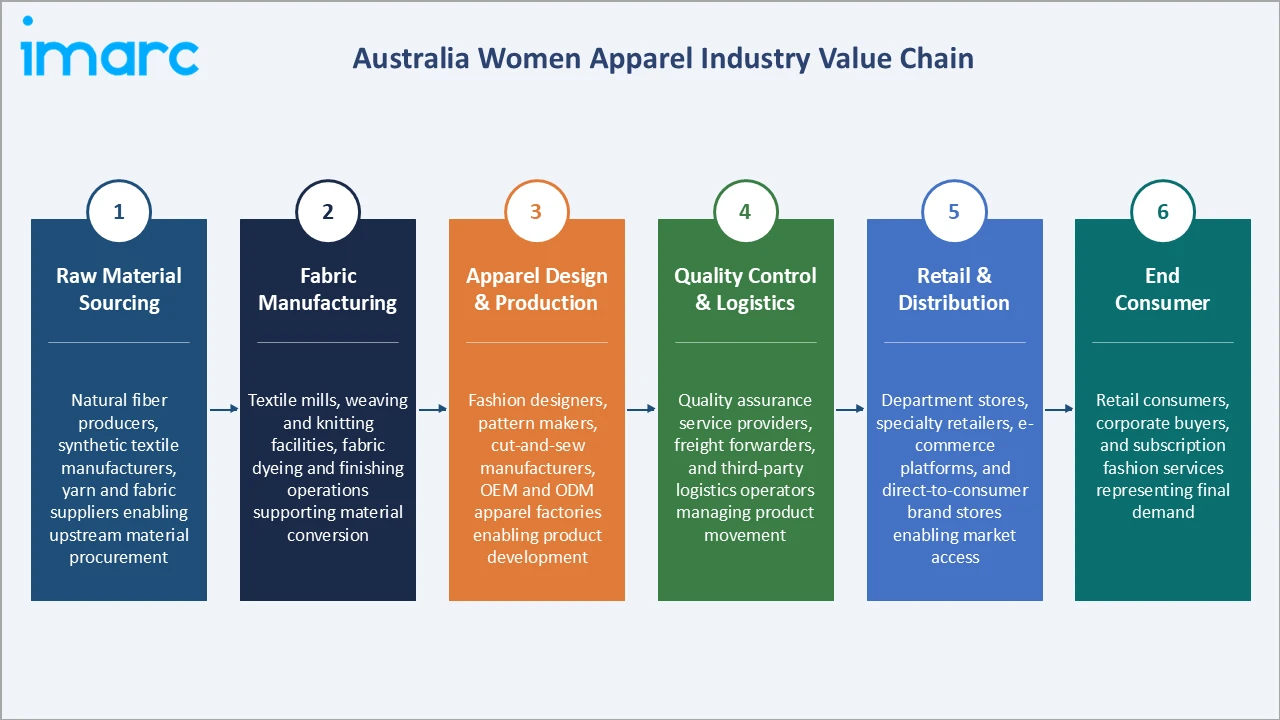
The Australia women apparel value chain spans six stages, from raw material sourcing through end consumer delivery. Design and production, retail distribution, and brand-building stages capture the highest value-add, while sustainability and compliance documentation are increasingly determining competitive position across the market.
| Stage | Key Players / Examples |
|---|---|
| Raw Material Sourcing | Natural fiber producers, synthetic textile manufacturers, yarn and fabric suppliers enabling upstream material procurement |
| Fabric Manufacturing | Textile mills, weaving and knitting facilities, fabric dyeing and finishing operations supporting material conversion |
| Apparel Design & Production | Fashion designers, pattern makers, cut-and-sew manufacturers, OEM and ODM apparel factories enabling product development |
| Quality Control & Logistics | Quality assurance service providers, freight forwarders, and third-party logistics operators managing product movement |
| Retail & Distribution | Department stores, specialty retailers, e-commerce platforms, and direct-to-consumer brand stores enabling market access |
| End Consumer | Retail consumers, corporate buyers, and subscription fashion services representing final demand across market channels |
Vertically integrated retailers controlling design, sourcing, and distribution are positioned to capture greater margin than single-stage operators, while direct-to-consumer digital models are enabling emerging brands to bypass traditional wholesale channels and build stronger consumer relationships.
Technology Landscape in the Australia Women Apparel Industry
Textile Innovation and Sustainable Fabrics
Advanced textile engineering is enabling the development of performance fabrics combining moisture management, UV protection, and stretch recovery across the women's apparel market. Biodegradable fibers, recycled polyester, and organic cotton certifications are gaining traction among brands investing in sustainable product development.
Digital Fashion and E-Commerce Technology
AI-powered recommendation engines, virtual try-on tools, and digital size advisors are improving online shopping conversion and reducing return rates. Augmented reality (AR) integrations in mobile commerce platforms enable consumers to visualize fits before purchase, driving engagement and sales.
Smart Clothing and Wearable Integration
Emerging smart fabric technologies incorporating temperature-regulating fibers and bio-sensing materials are beginning to enter premium women activewear segments, driven by rising consumer interest in health-monitoring wearables and performance apparel.
AI-Driven Personalization and Trend Forecasting
Retailers are deploying machine learning (ML) platforms to analyze consumer behavior, predict seasonal trend adoption, and optimize inventory planning. Trend forecasting algorithms enable brands to reduce overstock and align product development more precisely with evolving consumer preferences in Australia women apparel fashion.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Product Type | Tops and Dresses | 35.5% | 2025 |
| Season | All Season Wear | 45.7% | 2025 |
| Distribution Channel | 🔒 | 🔒 | 2025 |
| Region | Australia Capital Territory & New South Wales | 32.5% | 2025 |

By Product Type
Tops and dresses command the largest segment at 35.5% in 2025, reflecting broad occasion applicability across professional, casual, and social settings. The segment benefits from high purchase frequency, diverse styling options, and consistent demand across all consumer age groups in Australia's urban and suburban retail markets.
To access detailed market analysis, Request Sample
Bottom wear holds 24.7% share, driven by steady consumer demand for denim, tailored trousers, and casual pants across all retail channels.
By Season
All season wear leads at 45.7% in 2025, reflecting Australian consumers' preference for versatile garments that can be styled across the country's varied climatic conditions. The segment benefits from broad applicability across urban professional and casual lifestyle contexts, supporting consistent full-year demand for multi-occasion apparel.
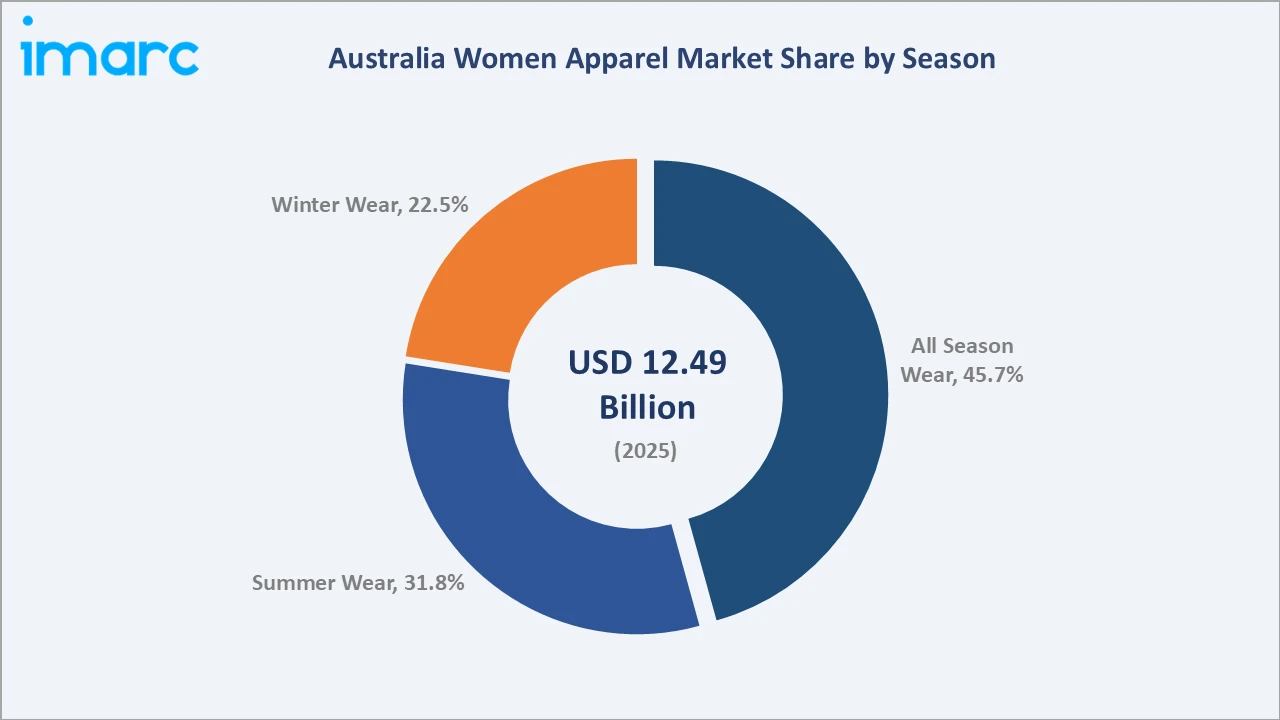
Summer wear at 31.8% is the second-largest season segment, driven by Australia's warm climate and sustained consumer demand for lightweight, casual, and activewear-inspired collections during extended warm periods.
Regional Market Insights
| Region | Share (2025) | Key Growth Drivers |
|---|---|---|
| Australia Capital Territory & New South Wales | 32.5% | Large urban consumer base in Sydney and Canberra, high income levels, strong e-commerce penetration, and diverse demographic demand for professional and lifestyle apparel |
| Victoria & Tasmania | 27.5% | Dense retail network in Melbourne, growing fashion culture, strong multicultural consumer demand, and expanding digital retail channels across metropolitan markets |
| Queensland | 21.5% | Warm climate driving sustained summer apparel demand, growing regional retail expansion, and increasing consumer spending on activewear and casual lifestyle fashion |
| Western Australia | 12.5% | Resource sector-driven consumer income levels, growing urban fashion retail in Perth's metropolitan market, and expanding retail and e-commerce infrastructure |
| Northern Territory & Southern Australia | 6.0% | Emerging retail market expansion, climate-driven seasonal apparel demand, and growing regional economic development supporting consumer spending growth |
Australia Capital Territory & New South Wales leads regional market share at 32.5% in 2025, anchored by Sydney's position as Australia's leading retail market and Canberra's professional consumer demographic supporting consistent demand for formal and workwear apparel categories.
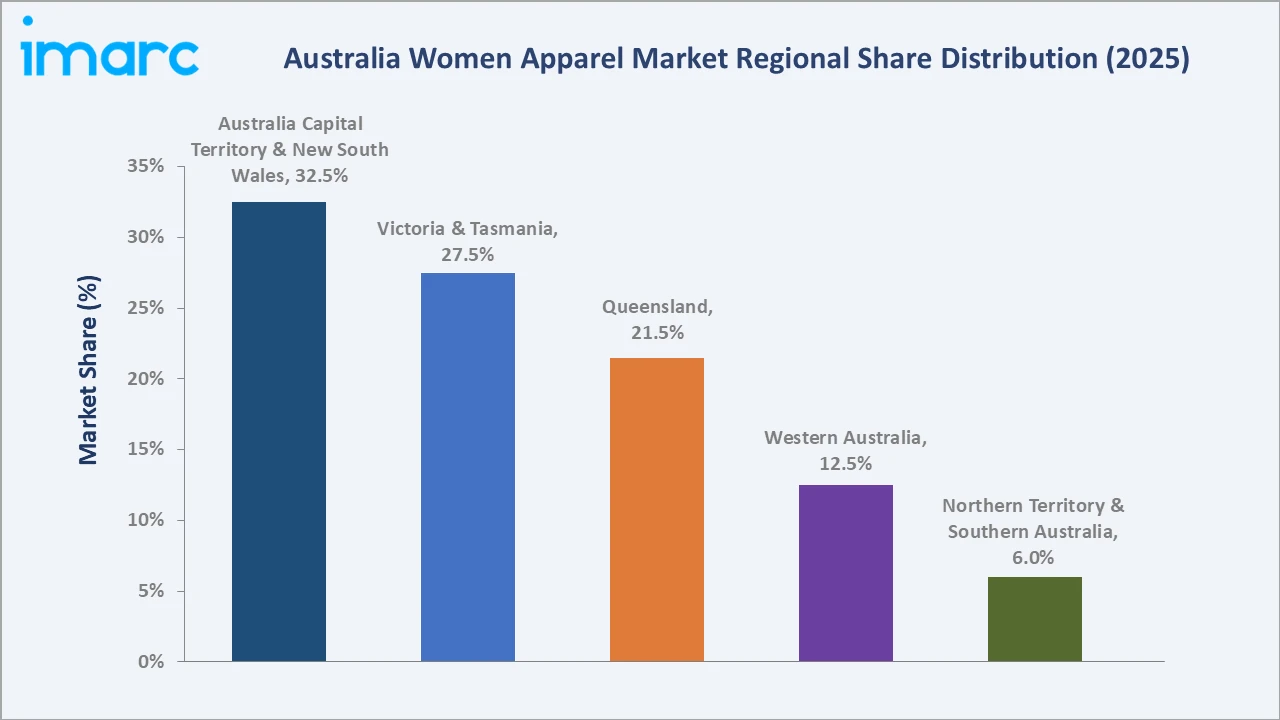
Victoria & Tasmania, with 27.5% share, is supported by Melbourne's vibrant fashion culture and well-established multicultural consumer demand for diverse style offerings across premium and mid-market women apparel brands.
Competitive Landscape
The Australia women apparel market is moderately concentrated, with domestic retail conglomerates, global fast fashion operators, and specialty fashion groups competing across physical retail, e-commerce, and direct-to-consumer channels. Scale, brand recognition, digital capability, and supply chain efficiency form the primary competitive differentiators.
| Company Name | Brand / Key Product | Position | Strategic Focus |
|---|---|---|---|
| Cotton On Group | Cotton On Women, Supré | Leader | Expanding product range and digital retail capabilities with focus on affordable fashion and sustainability |
| Myer Holdings Limited | Myer, Portmans, Dotti, Just Jeans, Jay Jays, Jacqui E | Leader | Enhancing omnichannel retail operations across its enlarged brand portfolio |
| H&M Hennes & Mauritz AB | H&M | Leader | Driving sustainability integration across the supply chain while expanding digital commerce capabilities |
| Industria de Diseño Textil, S.A. | Zara | Challenger | Accelerating supply chain digitalization and expanding online commerce while maintaining strong trend responsiveness across active Australian stores |
Key players include Cotton On Group, Myer Holdings Limited, H&M Hennes & Mauritz AB, and Industria de Diseño Textil, S.A., among others.
Key Company Profiles
Cotton On Group
Cotton On Group is an Australian vertically integrated fashion retailer headquartered in Geelong, Victoria, operating multiple women apparel and lifestyle brands across physical and digital retail channels globally.
- Product Portfolio: Women's casual wear, activewear, intimates, and accessories under Cotton On and Supré brands spanning value and mid-market price tiers.
- Recent Developments: The company continues to expand its women apparel range and invest in digital retail capabilities and sustainable sourcing initiatives across its global operations.
- Strategic Focus: Broadening product range and digital retail presence across domestic and international markets with focus on affordable fashion and sustainability.
Myer Holdings Limited
Myer Holdings Limited is Australia's leading omnichannel retail group, headquartered in Victoria. The firm operates both its department store network and a portfolio of specialty women's fashion chains nationally.
- Product Portfolio: Women apparel across Myer department stores, Portmans, Dotti, Jay Jays, Just Jeans, and Jacqui E brands, spanning premium, contemporary, and casual women's fashion across all price tiers.
- Recent Developments: The company continues to enhance its product offerings, strengthen retail operations, and improve customer experiences across its department stores and digital channels.
- Strategic Focus: Integrating its enlarged brand portfolio, enhancing omnichannel retail capabilities, and leveraging scale across department store and specialty fashion formats to drive revenue growth and improve customer retention nationally.
H&M Hennes & Mauritz AB
H&M Hennes & Mauritz AB is a Swedish multinational clothing retail company with a significant presence in Australia's women apparel segment, operating fashion and lifestyle brands across global markets.
- Product Portfolio: Women's clothing, accessories, and homeware under H&M brand, spanning fast fashion, basics, and premium casual categories across multiple price points.
- Recent Developments: The firm is investing in its sustainability platform and introducing extended women apparel collections targeting professional female consumers in the Australian market.
- Strategic Focus: Driving sustainability integration across the supply chain while expanding digital commerce capabilities and broadening its Australian store and online footprint.
Market Concentration Analysis
The Australia women apparel market exhibits moderate fragmentation, with domestic retail conglomerates, global fast fashion operators, and premium specialty brands each holding meaningful market positions across different consumer segments and price tiers. No single player commands dominant share across all product and channel categories.
Barriers to entry are moderate, including brand equity requirements, supply chain scale advantages, retail real estate access, and growing investment required for effective digital commerce capabilities. These factors favor established players in mid-market and premium segments, while the value tier sees active competition from scale retailers operating large store networks.
Consolidation through strategic acquisitions, brand portfolio expansion, and retail network optimization is enabling established players to strengthen their competitive positions. However, continued competition from online-first brands and international retailers is encouraging market participants to invest in digital capabilities, product differentiation, and customer retention strategies.
Investment & Growth Opportunities
Fastest-Growing Segments
Ethnic wear is the fastest growing product type, supported by sustained demand for culturally inspired clothing across festivals, weddings, and other traditional occasions. Brands are expanding their collections with contemporary designs, versatile silhouettes, and modern styling to appeal to younger consumers and broaden everyday adoption.
Emerging Markets
Queensland and Western Australia are the fastest-growing regional markets, driven by favorable population demographics, growing consumer spending on lifestyle apparel, and expanding retail and digital commerce infrastructure in Brisbane, Gold Coast, and Perth metropolitan areas.
Venture & Investment Trends
Investment is concentrated in sustainable fashion technology platforms, size-inclusive apparel brands, and digital-first direct-to-consumer businesses. Growing consumer interest in ethical sourcing and circular fashion is attracting capital into brands and platforms with differentiated sustainability credentials and transparent supply chains.
Future Market Outlook (2026-2034)
The Australia women apparel market is projected to grow from USD 12.49 Billion in 2025 to USD 13.09 Billion in 2026, reaching USD 19.44 Billion by 2034, registering a CAGR of 4.84% during 2026-2034.
Three forces will shape the market through 2034: sustained growth in female consumer spending across urban and digital channels; increasing integration of sustainability requirements into mainstream retail sourcing; and continued expansion of size-inclusive and culturally diverse apparel offerings targeting underserved consumer demographics.
By 2034, the Australia women apparel market is expected to be characterized by greater digital commerce integration, stronger sustainability standards across supply chains, and continued brand diversification serving the evolving preferences of Australia's multicultural and age-diverse female consumer base.
Research Methodology
Primary Research
Primary research included structured discussions with apparel retailers, fashion buyers, brand managers, and market participants to validate market sizing, segment trends, and regional demand patterns across the Australia women apparel ecosystem.
Secondary Research
Secondary sources included Australian Bureau of Statistics consumer spending data, retail industry publications, trade association reports, and public disclosures from listed retail companies operating in Australia women apparel market.
Forecasting Models
Market forecasts used combined top-down (total consumer expenditure approach) and bottom-up (segment-level build) methodologies, incorporating demographic, macroeconomic, and channel shift assumptions across the 2026–2034 forecast horizon.
Australia Women Apparel Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | Tops and Dresses, Bottom Wear, Innerwear and Sleepwear, Coats, Jackets and Suits, Ethnic Wear, Others |
| Seasons Covered | Summer Wear, Winter Wear, All Season Wear |
| Distribution Channels Covered | Supermarkets and Hypermarkets, Exclusive Stores, Multi-Brand Retail Outlets, Online Stores, Others |
| Regions Covered | Australia Capital Territory & New South Wales, Victoria & Tasmania, Queensland, Northern Territory & Southern Australia, Western Australia |
| Companies Covered | Cotton On Group, Myer Holdings Limited, H&M Hennes & Mauritz AB, Industria de Diseño Textil, S.A., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Australia women apparel market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Australia women apparel market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Australia women apparel industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Australia Women Apparel Market Report
The Australia women apparel market size is estimated at USD 13.09 Billion in 2026, driven by rising female workforce participation, growing e-commerce penetration, and strong consumer demand for versatile and sustainable women's clothing.
The market is projected to grow at a CAGR of 4.84% from 2026-2034, reaching USD 19.44 Billion by 2034, supported by rising consumer spending, digital retail expansion, and growing demand for premium and inclusive fashion.
Tops and dresses dominate the market at 35.5% share in 2025, driven by versatility across formal, casual, and social occasions and consistent consumer demand across all age groups in Australia.
All season wear leads the season segment at 45.7% share in 2025, driven by consumer preference for versatile garments suited to Australia's varied climate conditions and multi-occasion styling requirements throughout the year.
Australia Capital Territory & New South Wales commands 32.5% share in 2025, led by Sydney and Canberra's concentrated urban consumer markets, high income levels, and well-established retail and digital commerce infrastructure.
Western Australia represents the fastest-growing region, driven by favorable demographics, growing consumer spending, and expanding retail and digital commerce infrastructure.
Key players include Cotton On Group, Myer Holdings Limited, H&M Hennes & Mauritz AB, and Industria de Diseño Textil, S.A., among others.
Key drivers include rising female workforce participation, growing e-commerce penetration, increasing consumer demand for premium and sustainable apparel, and the growing influence of social media on fashion purchasing behavior.
Key trends include the sustainability and circular fashion movement, digital-first shopping and social commerce growth, athleisure expansion, and growing demand for personalized and size-inclusive apparel offerings.
Key challenges include inflationary pressure on consumer discretionary spending, supply chain complexity, intense competition from global fast fashion operators, and the growing need for sustainable textile innovation and digital capabilities.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade