
Automotive Display System Market Size, Share, Trends and Forecast by Technology, Display Size, Application, Vehicle Type, Sales Channel, and Region, 2026-2034
Automotive Display System Market Size, Share, Trends & Forecast (2026-2034)
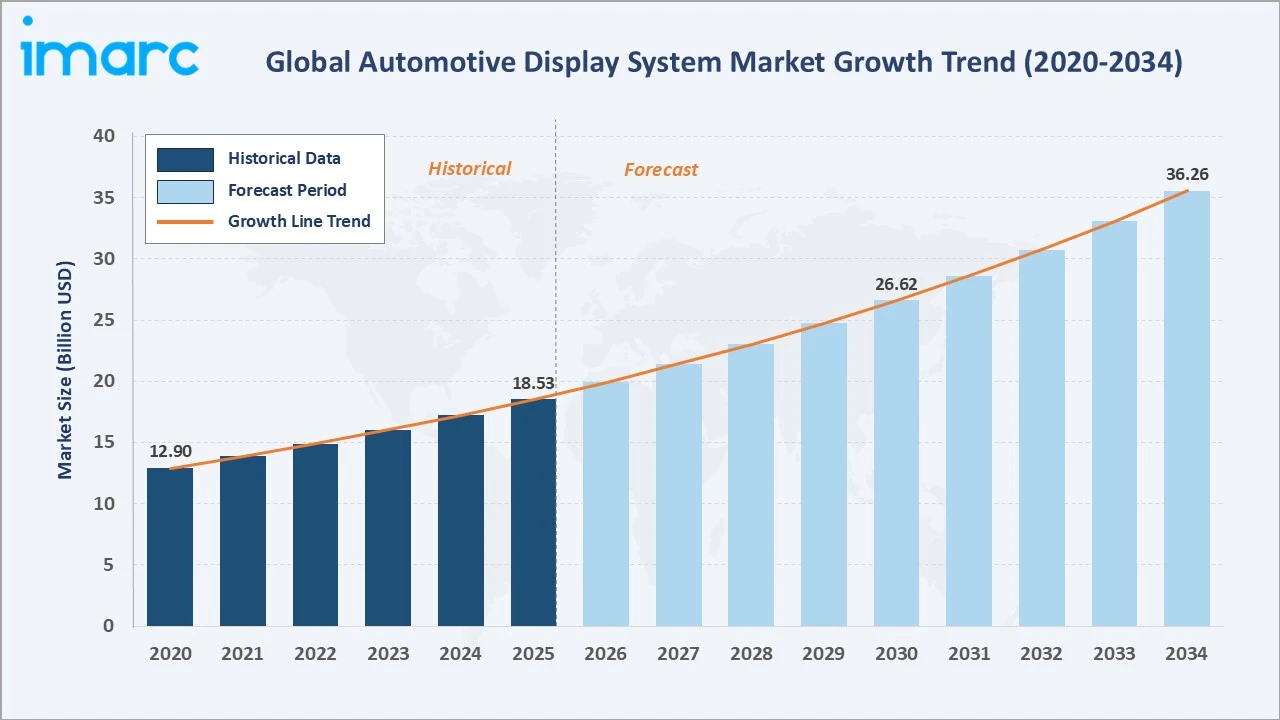
The automotive display system market grew from USD 18.53 Billion in 2025 to USD 19.92 Billion in 2026 and is projected to reach USD 36.26 Billion by 2034, exhibiting a CAGR of 7.51% during 2026-2034. Rising integration of advanced infotainment and digital cockpit technologies is the primary factor shaping market expansion.
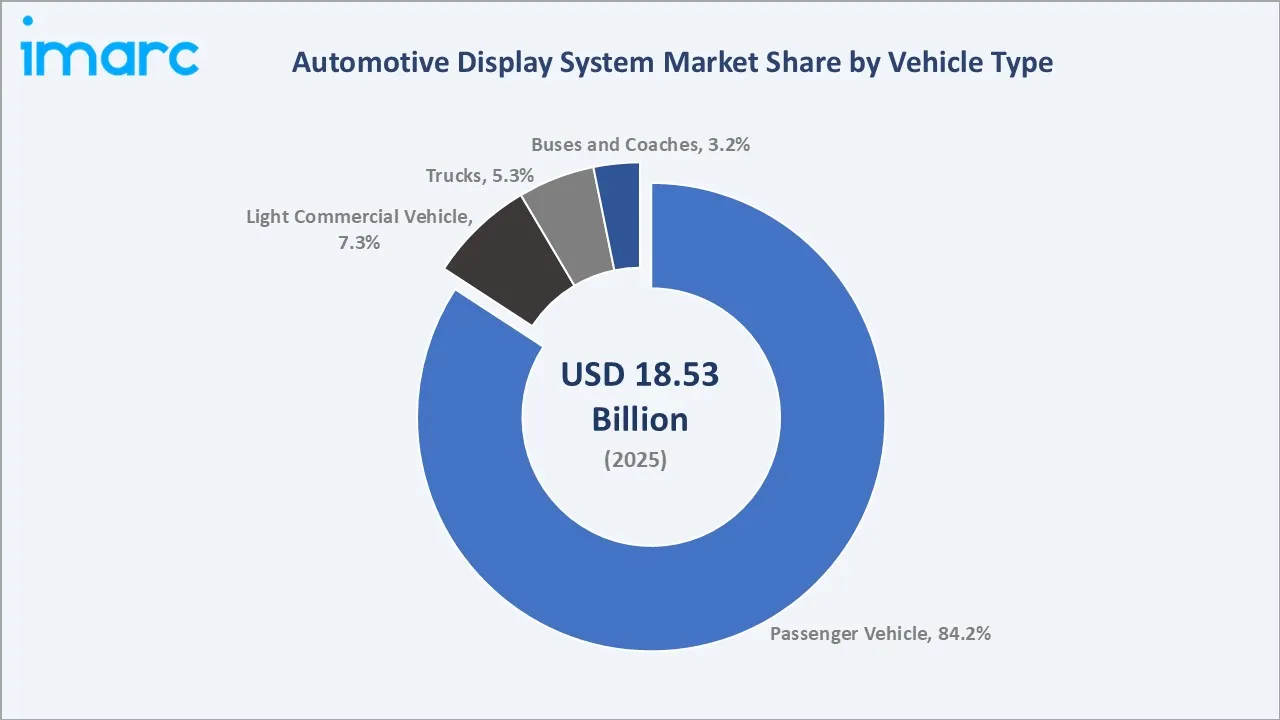
Passenger vehicle commands 84.2% of the vehicle type segment, OEM leads the sales channel with 87.6% share, and Asia-Pacific dominates the regional landscape at 64.5%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 18.53 Billion |
|
Market Size (2026) |
USD 19.92 Billion |
|
Forecast Market Size (2034) |
USD 36.26 Billion |
|
CAGR (2026-2034) |
7.51% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Asia-Pacific (64.5%, 2025) |
|
Second Largest Region |
North America (15.7%, 2025) |
|
Leading Vehicle Type |
Passenger Vehicle (84.2%, 2025) |
|
Leading Sales Channel |
OEM (87.6%, 2025) |
The automotive display system market size increased from USD 12.90 Billion in 2020 to USD 18.53 Billion in 2025 and is estimated to reach USD 19.92 Billion in 2026. The market is further expected to grow to USD 26.62 Billion by 2030 and USD 36.26 Billion by 2034, supported by rising consumer preference for connected vehicle technologies, growing OEM investment in digital cockpit solutions, and regulatory mandates for driver safety displays across major markets.
To get more information on this market, Request Sample
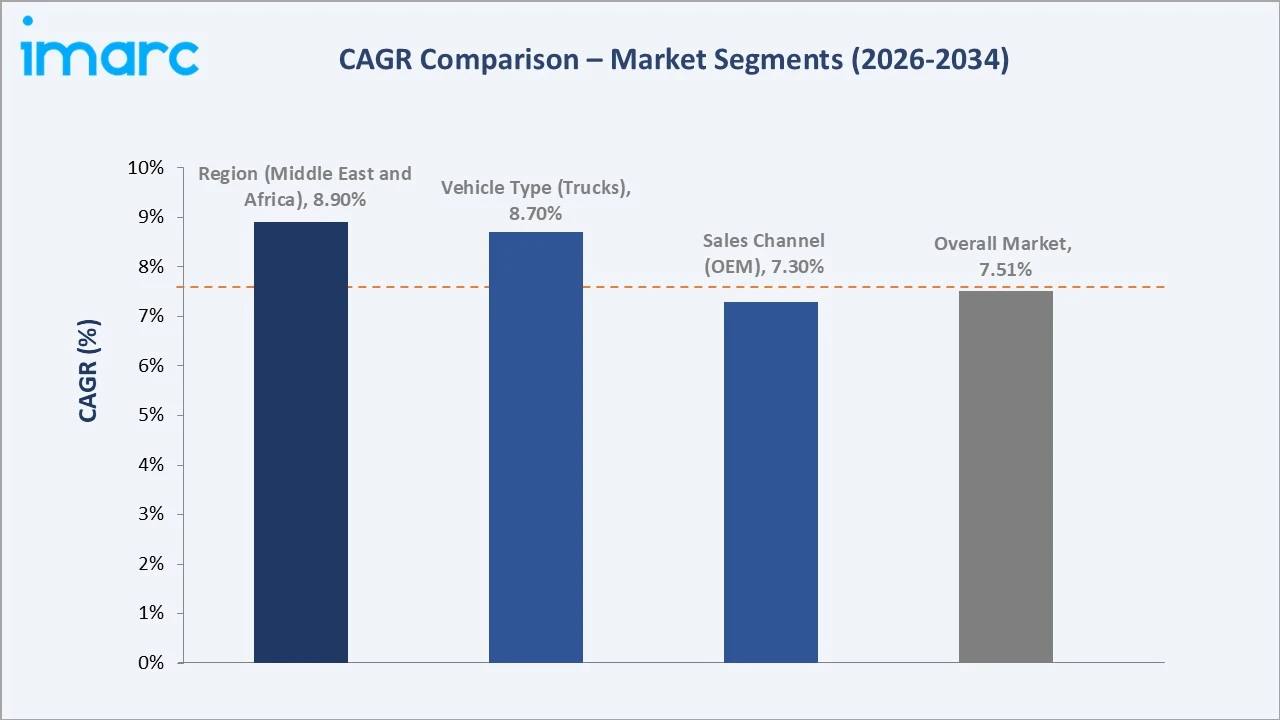
CAGR trajectories across vehicle type and sales channel sub-segments, together with regional patterns, show trucks and Latin America expanding faster than the overall 7.51% market CAGR, driven by rising demand for advanced in-vehicle displays, increasing vehicle digitization, and growing adoption of connected vehicle technologies.
Executive Summary
The automotive display system market expanded from USD 18.53 Billion in 2025 to an estimated USD 19.92 Billion in 2026. The industry has evolved from basic analog instrument clusters to fully integrated, multi-screen digital cockpit experiences spanning digital instrument clusters, center information displays, heads-up display (HUD) units, and rear-seat entertainment screens. Rising consumer expectations for connected in-vehicle experiences, growing EV adoption, and tightening vehicle safety regulations are driving consistent expansion across vehicle categories and geographies.
Passenger vehicle commands 84.2% of the vehicle type segment in 2025, reflecting its dominant share of global vehicle production and the high penetration of touchscreen infotainment and digital cluster systems across mass-market and premium car segments. OEM leads sales channel at 87.6%, as automotive manufacturers prioritize factory-integrated display systems for quality, warranty, and seamless cockpit integration consistency. Asia-Pacific commands 64.5% of the regional share in 2025, anchored by China, Japan, South Korea, and India's combined manufacturing scale and rapidly expanding EV ecosystem.
Key Market Insights
|
Insight |
Data |
|
Leading Vehicle Type |
Passenger Vehicle – 84.2% share (2025) |
|
Second Largest Vehicle Type |
Light Commercial Vehicle – 7.3% share (2025) |
|
Leading Sales Channel |
OEM – 87.6% share (2025) |
|
Second Largest Sales Channel |
Aftermarket – 12.4% share (2025) |
|
Leading Region |
Asia-Pacific – 64.5% share (2025) |
|
Second Largest Region |
North America – 15.7% share (2025) |
|
Top Companies |
Aumovio SE, Robert Bosch GmbH, Denso Corporation, Samsung Electronics Co., Ltd. |
Key Analytical Observations Expanding On the Data Above:
- Passenger vehicle dominance at 84.2% is driven by high consumer appetite for digital infotainment and digital instrument clusters, which are standard across most mid-range and premium passenger car segments globally.
- Light commercial vehicle at 7.3% reflects expanding fleet telematics requirements and operator demand for navigation and communications displays that improve driver productivity and fleet management capabilities.
- OEM leadership at 87.6% is reinforced by automotive manufacturers’ preference for factory-integrated display systems. This approach ensures better compatibility with vehicle electronics, consistent quality, and seamless integration with onboard infotainment and driver assistance functions.
- Aftermarket at 12.4% remains relevant among existing vehicle owners seeking display upgrades, supported by growing availability of compatible aftermarket infotainment systems across a broad range of vehicle makes and models.
- Asia-Pacific at 64.5% reflects the region’s dominant position in global automotive manufacturing, combined with rapidly scaling EV production in China and growing domestic demand for premium in-vehicle technology across Japan, South Korea, and Southeast Asia.
Automotive Display System Market Overview
Automotive display system encompasses the full range of in-vehicle screens used for driver information, infotainment, navigation, and vehicle control, including digital instrument clusters, center information displays, HUDs, and rear-seat entertainment screens.
The ecosystem spans raw material suppliers, display panel manufacturers, software developers, OEM cockpit integrators, and aftermarket distributors, supported by a growing layer of cloud-connected services enabling over-the-air updates and personalization. Macroeconomic trends including electrification, vehicle connectivity, and autonomous driving development are expanding the strategic importance of display systems within broader vehicle architecture planning.
Market Dynamics
To evaluate market opportunities, Request Sample
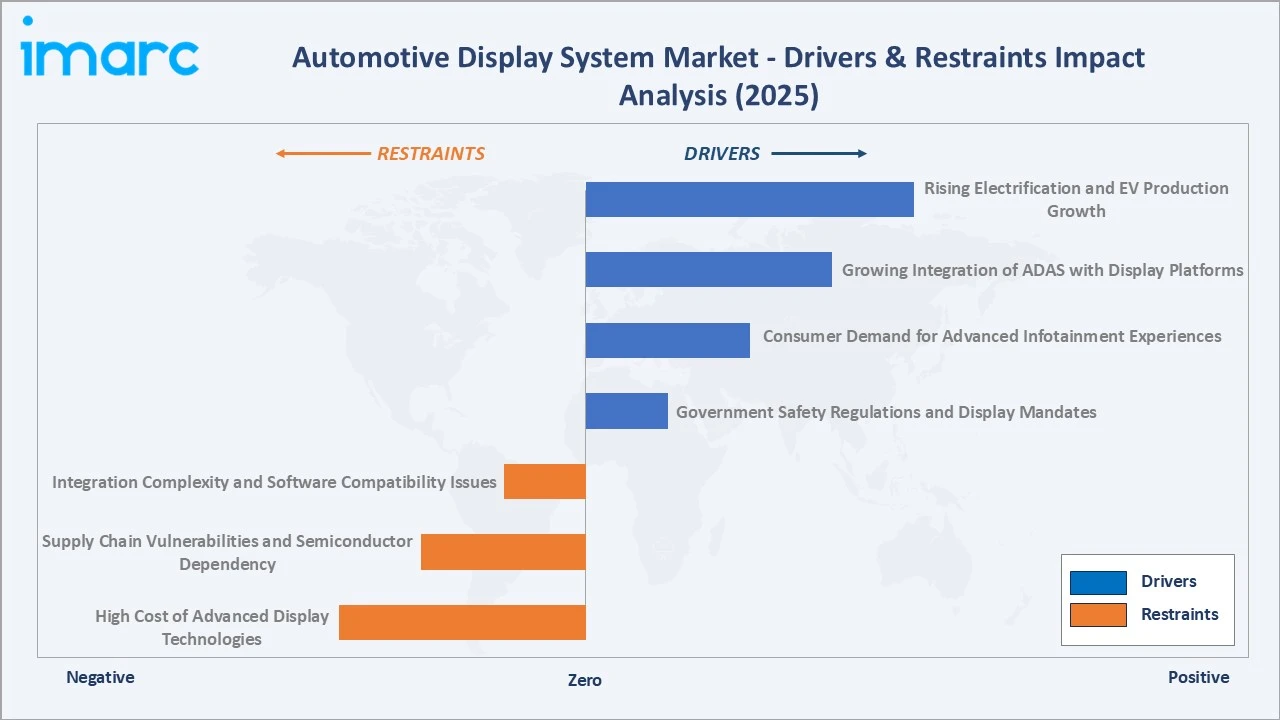
Market Drivers
- Rising Electrification and EV Production Growth: Rapid expansion of EV production is creating consistent demand for advanced display systems, as EV manufacturers prioritize large touchscreen interfaces for battery management, charging status visualization, and energy consumption monitoring. Electric car sales surpassed 17 Million units in 2024, directly expanding the addressable market for premium automotive display integration across passenger and commercial vehicle categories.
- Growing Integration of ADAS with Display Platforms: Increasing regulatory mandates for active safety systems are requiring display units capable of rendering camera feeds, proximity warnings, lane departure alerts, and blind-spot detection overlays in real time, driving higher display specifications and per-unit value across vehicle segments and supporting growth in the automotive display market.
- Consumer Demand for Advanced Infotainment Experiences: Rising consumer expectations for smartphone-like in-vehicle experiences are driving automotive manufacturers to deliver larger, higher-resolution displays with seamless wireless connectivity, voice control, and over-the-air update capability, supporting consistent upgrade cycles across vehicle model generations.
- Government Safety Regulations and Display Mandates: Regulatory requirements for backup cameras, digital speedometers, and driver monitoring systems in key markets are creating minimum display specifications that support baseline demand across mass-market and entry-level vehicle segments.
Market Restraints
- High Cost of Advanced Display Technologies: Premium display technologies including OLED panels, curved screens, and augmented reality heads-up displays (AR-HUDs) carry significantly higher per-unit costs compared to conventional LCD displays, limiting widespread adoption to premium and mid-range vehicle segments and constraining broader market penetration.
- Supply Chain Vulnerabilities and Semiconductor Dependency: Automotive display systems are critically dependent on semiconductor components and specialized display panels sourced from a concentrated set of global suppliers, exposing manufacturers to supply disruptions, pricing pressures, and lead time variability that complicate production planning.
- Integration Complexity and Software Compatibility Issues: Integrating advanced display systems with diverse vehicle architectures, infotainment platforms, and driver assistance technologies increases engineering complexity and validation requirements, potentially extending development cycles and raising implementation costs for automotive manufacturers.
Market Opportunities
- Growth of Aftermarket Display Upgrades in Emerging Markets: Rising vehicle ownership and growing consumer awareness of connected vehicle features in Asia-Pacific, Latin America, and the Middle East are creating expanding aftermarket demand for display system upgrades in existing vehicle fleets.
- Software-Defined Vehicle Architecture Transition: Automotive industry movement toward software-defined vehicle platforms is creating new opportunities for display system providers able to offer over-the-air updateable solutions that can evolve with vehicle software lifecycles beyond the initial point of sale.
Market Challenges
- Managing Display Reliability in Harsh Automotive Environments: Automotive displays must operate reliably across extreme temperature ranges, vibration conditions, and humidity levels, requiring ruggedized designs that add cost and complexity compared to consumer electronics display standards.
- Cybersecurity Risks in Connected Display Systems: Display systems integrated with vehicle networks and external connectivity introduce cybersecurity exposure, requiring display suppliers and OEMs to implement robust security protocols that add development cost and ongoing maintenance obligations.
Emerging Market Trends
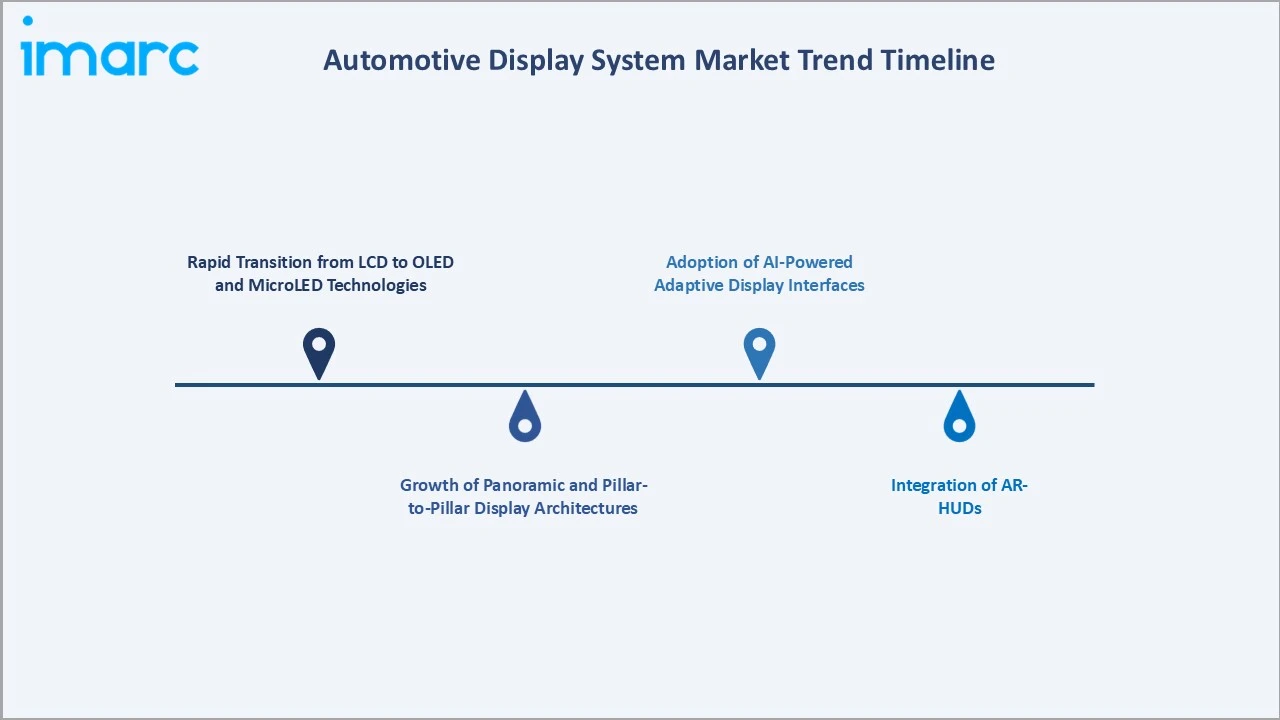
1. Rapid Transition from LCD to OLED and MicroLED Technologies
Automotive display manufacturers are accelerating the transition from conventional LCD panels to OLED and MicroLED displays, which offer superior contrast ratios, faster response times, and thinner form factors suited to curved and flexible cockpit installations. OLED displays eliminate the need for backlighting, enabling deeper blacks and more vibrant color reproduction that enhances readability across varying ambient light conditions in vehicle interiors.
2. Growth of Panoramic and Pillar-to-Pillar Display Architectures
Premium automotive brands are increasingly deploying panoramic display architectures that span the full dashboard width, combining digital instrument clusters, center information displays, and front passenger entertainment into a continuous screen surface. This architectural shift is driving demand for larger display panels, advanced display controllers, and specialized integration solutions that support seamless multi-zone display experiences in the automotive display panel market.
3. Integration of AR-HUDs
AR-HUD adoption is accelerating as automakers project turn-by-turn navigation, speed limit data, and ADAS alerts directly onto the driver’s field of vision on the windshield, reducing the need for the driver to shift gaze from the road. AR-HUD systems represent a high-growth sub-segment of the automotive display market, with growing deployment across premium European and Asian vehicle brands driving increased supplier investment in compact, high-brightness projection technology.
4. Adoption of AI-Powered Adaptive Display Interfaces
Automotive display systems are increasingly incorporating AI and machine learning (ML) algorithms to dynamically adjust content, brightness, and information priority based on driving context, user preferences, and real-time vehicle sensor inputs.
Industry Value Chain Analysis
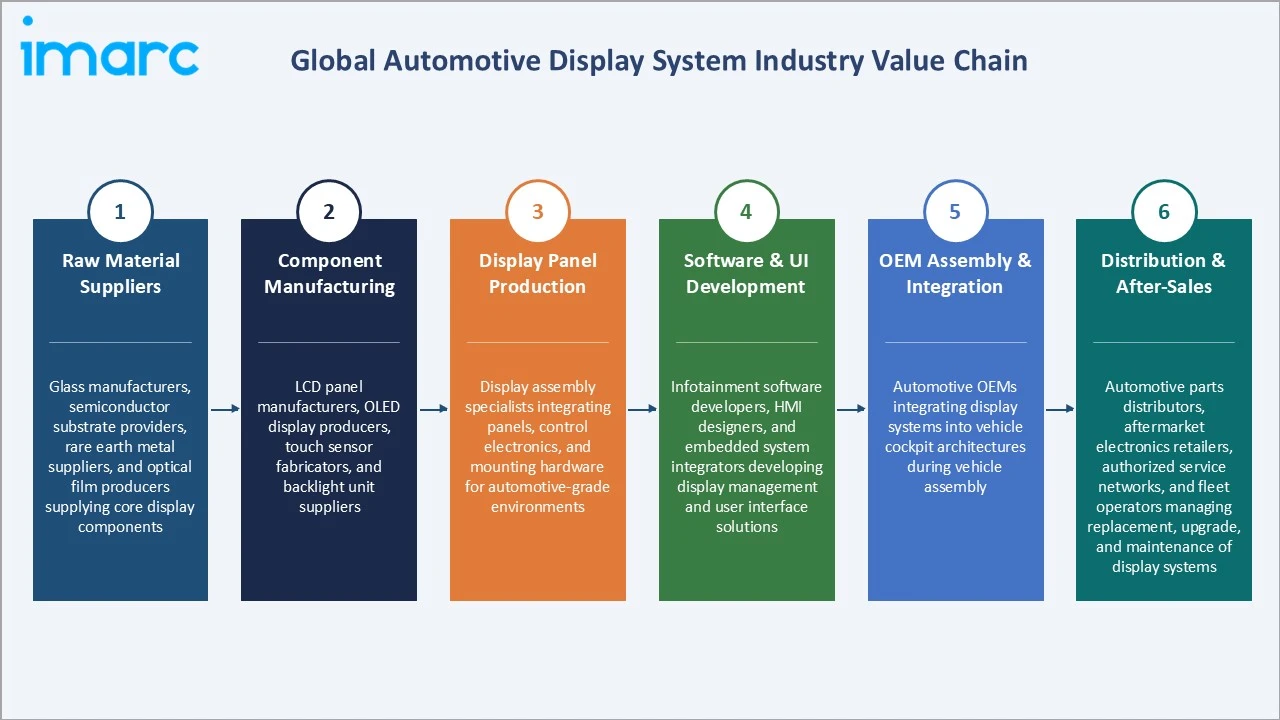
The automotive display system value chain spans six stages, from raw material sourcing through distribution and after-sales service. Display panel production, OEM cockpit integration, and software development capture the highest value-add, while raw material supply and distribution provide foundational infrastructure.
|
Stage |
Key Players / Examples |
|
Raw Material Suppliers |
Glass manufacturers, semiconductor substrate providers, rare earth metal suppliers, and optical film producers supplying core display components |
|
Component Manufacturing |
LCD panel manufacturers, OLED display producers, touch sensor fabricators, and backlight unit suppliers |
|
Display Panel Production |
Display assembly specialists integrating panels, control electronics, and mounting hardware for automotive-grade environments |
|
Software & UI Development |
Infotainment software developers, HMI designers, and embedded system integrators developing display management and user interface solutions |
|
OEM Assembly & Integration |
Automotive OEMs integrating display systems into vehicle cockpit architectures during vehicle assembly |
|
Distribution & After-Sales |
Automotive parts distributors, aftermarket electronics retailers, authorized service networks, and fleet operators managing replacement, upgrade, and maintenance of display systems |
OEM integrators hold a central position in the value chain, controlling vehicle cockpit architecture decisions and supplier selection, which concentrates significant value-capture power at the vehicle assembly stage. Software and UI development is emerging as an increasingly strategic layer, as the shift toward software-defined vehicles elevates the competitive importance of display interface software and over-the-air update capability.
Technology Landscape in the Automotive Display System Industry
Display Panel Technologies
TFT-LCD remains the dominant display technology in volume terms, offering cost-effective performance across mid-range vehicle segments, while OLED adoption is accelerating in premium cockpit applications due to superior contrast, thinner profiles, and flexible form factor capability. MicroLED technology is under active development for automotive applications, offering the brightness levels and longevity required for HUDs and high-ambient-light-readable center information displays, creating opportunities in the automotive multilayer display market.
Embedded Software and Human-Machine Interface Platforms
Dedicated automotive HMI middleware platforms enable display system suppliers to deliver customizable, hardware-agnostic user interface frameworks that automotive OEMs can adapt to brand-specific design languages while leveraging common software architecture across multiple vehicle lines. Voice recognition, gesture control, and haptic feedback are being integrated with display interfaces to reduce driver distraction while supporting richer interaction models.
Connectivity and Over-the-Air Update Infrastructure
Embedded connectivity modules enabling wireless data exchange between display systems and cloud platforms are supporting over-the-air software delivery, real-time map updates, streaming media services, and remote vehicle diagnostics, extending the commercial relationship between OEMs and vehicle owners well beyond the initial purchase.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
| Technology | TFT-LCD |
53.7% |
2025 |
| Display Size | Between 6” to 10” | 🔒 | 2025 |
| Application | Center Stack Display | 42.1% | 2025 |
| Vehicle Type | Passenger Vehicle | 84.2% | 2025 |
| Sales Channel | OEM |
87.6% |
2025 |
|
Region |
Asia-Pacific |
64.5% |
2025 |

By Vehicle Type
Passenger vehicle commands an 84.2% majority share in 2025, reflecting the high volume of passenger car production globally and the broad penetration of touchscreen infotainment systems and digital instrument clusters across mass-market, mid-range, and premium car segments.
To access detailed market analysis, Request Sample
Light commercial vehicle at 7.3% is the second-largest vehicle type segment, driven by expanding fleet telematics demand and the increasing deployment of navigation, communication, and fleet management displays in delivery vehicles and light commercial transport.
By Sales Channel
OEM leads sales channel with 87.6% share in 2025, reflecting the automotive industry’s strong preference for factory-integrated display systems that are calibrated to vehicle specifications, meet OEM quality standards, and are covered under vehicle warranty.
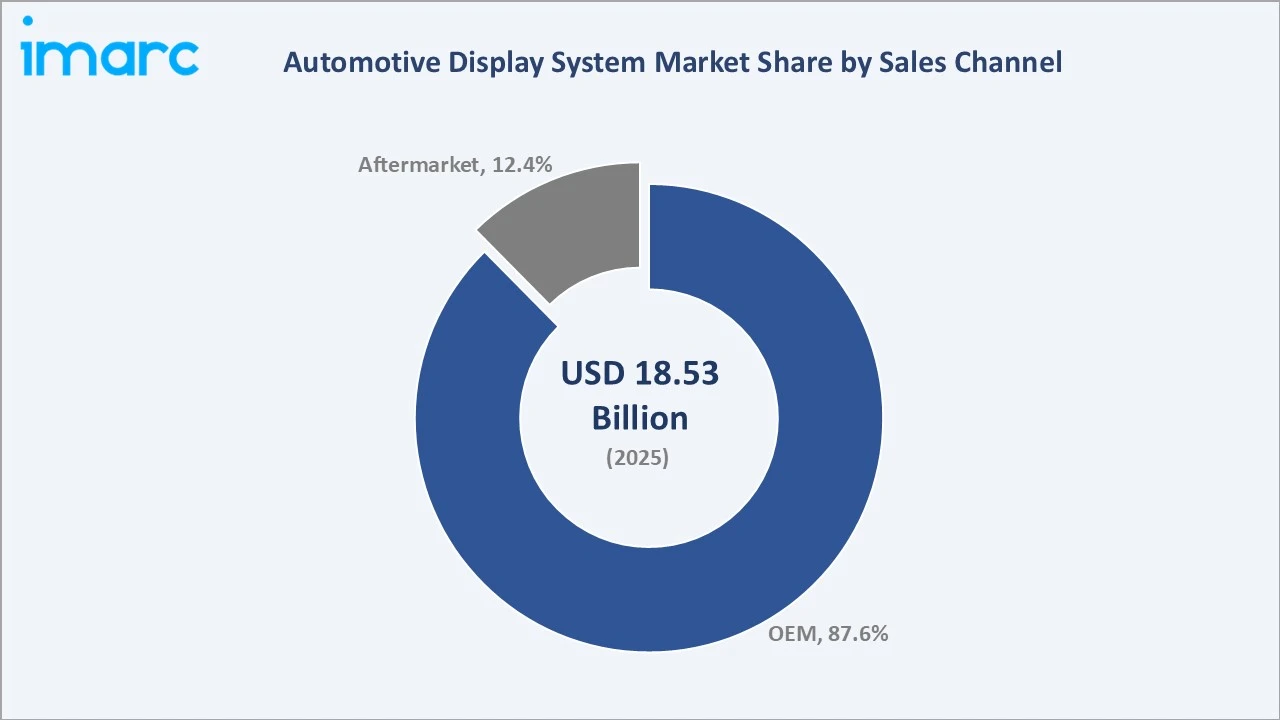
Aftermarket at 12.4% represents a growing segment driven by consumer demand for display upgrades in existing vehicles and the availability of compatible aftermarket infotainment systems for a broad range of vehicle makes and models.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
| Asia-Pacific | 64.5% | Strong automotive manufacturing base, rapidly expanding EV ecosystem, growing domestic demand for connected vehicles, and active adoption of ADAS technologies |
| North America |
15.7% |
High consumer demand for premium infotainment, stringent vehicle safety regulations, advanced technology adoption, and strong OEM manufacturing presence |
| Europe |
13.4% |
Stringent automotive safety standards, growing EV adoption, premium vehicle manufacturing concentration, and regulatory mandates for driver assistance displays |
| Latin America |
3.8% |
Rising vehicle production, growing middle-class demand for advanced in-vehicle technology, and increasing OEM investments in local manufacturing |
| Middle East and Africa |
2.6% |
Rising vehicle imports, increasing consumer preference for feature-rich vehicles, and growing automotive retail infrastructure development |
Asia-Pacific commands 64.5% of the market in 2025, anchored by China’s position as the world’s leading automotive manufacturing and EV production market, complemented by Japan and South Korea’s strong display technology manufacturing capabilities. The region benefits from high vehicle production volumes, a deep automotive supplier base, rapid EV adoption, and growing domestic consumer demand for connected in-vehicle technology.
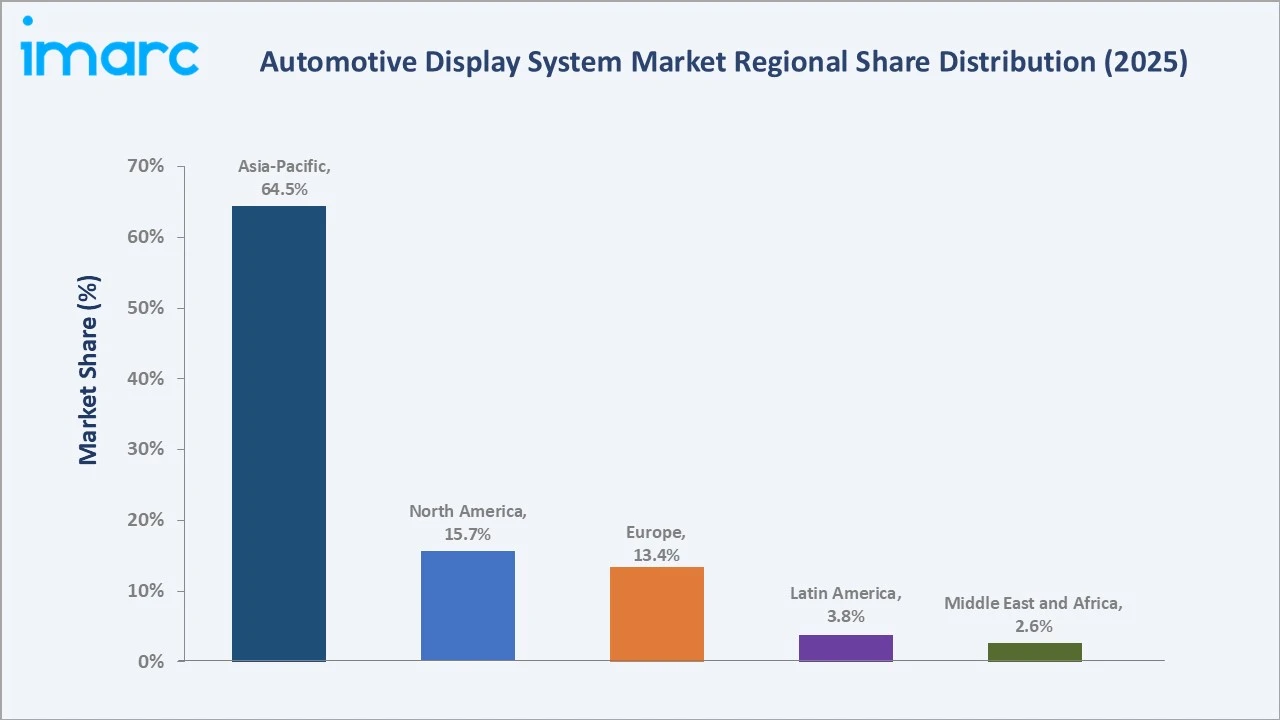
North America at 15.7% is driven by high consumer demand for premium infotainment systems, a robust aftermarket display segment, and significant OEM investment in connected vehicle technologies by domestic and international manufacturers operating in the United States.
Competitive Landscape
The automotive display system market is moderately concentrated, with established Tier-1 automotive suppliers and global electronics manufacturers holding leading positions through integrated display hardware, embedded software, and cockpit systems capabilities. Technology depth in display panel integration, software-defined cockpit platforms, and ADAS display integration form the primary competitive differentiators across the market.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| Aumovio SE | Aumovio | Leader | Expanding digital cockpit display capabilities and deepening integration with ADAS platforms |
| Robert Bosch GmbH | Digital EHS/ESG Solutions, Air Quality Consulting and Engineering, Water, Waste and Natural Resources Management | Leader | Strengthening connected display solutions and expanding software-defined vehicle partnerships |
| Denso Corporation | DENSO FHD LCD Displays | Leader | Growing advanced cluster and HUD product lines through technology partnerships and R&D investment |
| Samsung Electronics Co., Ltd. | HARMAN Automotive | Challenger | Expanding premium infotainment display solutions and growing connected car platform integrations |
Key players include Aumovio SE, Robert Bosch GmbH, Denso Corporation, and Samsung Electronics Co., Ltd., among others.
Key Company Profiles
Aumovio SE
Aumovio SE is an independent automotive technology company, headquartered in Germany. It offers a comprehensive portfolio of automotive display systems, digital cockpit solutions, and instrumentation products used by leading vehicle manufacturers globally.
- Product Portfolio: Broad display system portfolio covering digital instrument clusters, high-resolution center information displays, HUD systems, and integrated cockpit domain controllers for passenger and commercial vehicle applications.
- Recent Developments: Aumovio SE continues to strengthen its product offerings and advance its technology capabilities in line with evolving automotive industry requirements and changing OEM demand patterns.
- Strategic Focus: Integrating next-generation cockpit display technologies with emerging vehicle architectures to support broader adoption across passenger and commercial vehicle platforms.
Robert Bosch GmbH
Robert Bosch GmbH is a leading global technology and services company headquartered in Gerlingen, Germany, providing automotive display solutions, driver information systems, and connected vehicle technologies to OEMs worldwide.
- Product Portfolio: Automotive display solutions spanning instrument clusters, infotainment display systems, HUD units, and integrated cockpit control platforms for a broad range of passenger and commercial vehicle applications.
- Recent Developments: Robert Bosch GmbH continues to advance its automotive display and connected vehicle technology offerings in alignment with market trends and the evolving requirements of global automotive OEM partners.
- Strategic Focus: Advancing software-driven display platform capabilities and broadening vehicle connectivity solutions to serve a widening range of automotive market segments.
Denso Corporation
Denso Corporation is a leading Japanese automotive component manufacturer headquartered in Kariya, Aichi, Japan, producing display systems, instrument clusters, and cockpit electronics for major automotive OEMs in Japan, Asia, and international markets.
- Product Portfolio: Display systems portfolio including digital instrument clusters, multi-information display units, and HUD modules for passenger and commercial vehicle applications.
- Recent Developments: Denso Corporation continues to develop and refine its automotive display and cockpit electronics portfolio in response to growing industry demand for enhanced driver information and advanced vehicle integration capabilities.
- Strategic Focus: Deepening R&D investment in driver information display systems and forging collaborative technology agreements to extend product reach across key automotive markets.
Market Concentration Analysis
The automotive display system market exhibits moderate concentration, with leading Tier-1 automotive technology suppliers, including Aumovio SE, Robert Bosch GmbH, and Denso Corporation, collectively accounting for a substantial portion of global OEM display system supply. The market is characterized by high barriers to entry, including significant capital investment in display manufacturing capability, extensive automotive-grade validation requirements, and the long design win cycles inherent in OEM supply relationships. Consolidation activity is increasing as leading display suppliers acquire software and connectivity capabilities to support the shift toward software-defined cockpit architectures, and as smaller display component suppliers seek scale to absorb growing automotive-grade certification costs.
Investment & Growth Opportunities
Fastest-Growing Segments
Aftermarket is expanding fastest among sales channel categories, driven by rising consumer demand for display upgrades in existing vehicles across Asia-Pacific and emerging markets. Among vehicle types, trucks and light commercial vehicles are the fastest-growing sub-segments, supported by fleet safety regulation expansion and increasing fleet telematics display integration requirements.
Emerging Markets
Latin America and the Middle East and Africa represent the fastest-growing regions in the automotive display system market, supported by rising vehicle production, expanding consumer aspirations for in-vehicle technology, and growing OEM manufacturing investment in both regions. These markets present significant untapped opportunity for display system suppliers able to deliver cost-optimized solutions adapted to regional vehicle mix and consumer preference patterns.
Venture & Investment Trends
Investment activity in the automotive display system market is concentrated in AR-HUD development, OLED panel manufacturing capacity expansion, and software-defined cockpit platform development. Capital is also flowing into AI-enabled display management and personalization software, over-the-air update infrastructure, and transparent display technology development targeting premium vehicle segment applications through the forecast period.
Future Market Outlook (2026-2034)
The automotive display system market is projected to grow from USD 18.53 Billion in 2025 to USD 19.92 Billion in 2026, reaching USD 36.26 Billion by 2034, registering a CAGR of 7.51% during 2026-2034. Four forces will shape the market through 2034: continued transition from LCD to OLED and MicroLED display technologies; deeper integration of display systems with ADAS and vehicle sensor platforms; expansion of software-defined cockpit architectures enabling over-the-air display evolution; and increasing adoption of AR-HUD systems in premium and mass-market vehicle segments.
By 2034, the automotive display system market is expected to be defined by seamless, AI-adaptive multi-display cockpit architectures, with pillar-to-pillar panoramic displays becoming standard equipment across premium and upper-mid-range vehicle segments. Continued regulatory expansion of ADAS mandates and growing EV adoption across all major markets are expected to sustain strong per-vehicle display content growth through the end of the forecast period.
Research Methodology
Primary Research
Primary research included structured interviews with automotive display system suppliers, OEM cockpit engineering teams, automotive technology distributors, and industry analysts, validating market sizing, segment mix, technology adoption patterns, and regional demand dynamics.
Secondary Research
Secondary sources included automotive industry association reports, regulatory agency publications on vehicle safety standards, OEM annual reports and investor presentations, display technology industry publications, and patent and intellectual property filings related to automotive display innovation.
Forecasting Models
Market forecasts used top-down and bottom-up models combining global vehicle production data, average display content per vehicle trends, segment mix evolution estimates, and macroeconomic variables. Scenario analysis addressed regulatory adoption pace, technology transition timing, and EV penetration rate variations across key markets.
Automotive Display System Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Automotive Display System Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Technologies Covered | LCD, TFT-LCD, OLED, Digital Lighting Processing (DLP), Plasma Panels |
| Display Sizes Covered | Less than 5”, Between 6” to 10”, Greater than 10” |
| Applications Covered | Head Up Display, Instrument Cluster, Center Stack Display, Rear Seat Entertainment Display, Rear View Mirror Display, Portable Navigation Device, Others |
| Vehicle Types Covered | Passenger Vehicle (Hatchback, Sedan, Utility Vehicles), Light Commercial Vehicle, Buses & Coaches, Trucks |
| Sales Channels Covered | OEM, Aftermarket |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Countries Covered | United States, Canada, Germany, France, United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico |
| Companies Covered | Aumovio SE, Robert Bosch GmbH, Denso Corporation, Samsung Electronics Co., Ltd., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the automotive display system market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the global automotive display system market.
- The study maps the leading as well as the fastest growing regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the automotive display system industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Automotive Display System Market Report
The automotive display system market size is estimated at USD 19.92 Billion in 2026, driven by rising EV adoption, growing digital cockpit integration, and expanding ADAS display requirements across passenger and commercial vehicle segments.
The market is projected to grow at a CAGR of 7.51% from 2026-2034, reaching USD 36.26 Billion, supported by electrification trends, ADAS mandates, and growing per-vehicle display content value.
Passenger vehicle leads the vehicle type segment at 84.2% in 2025, driven by high consumer demand for advanced infotainment and digital cockpit displays in personal vehicles globally.
OEM dominates sales channel at 87.6% in 2025, reflecting automotive manufacturers’ preference for integrating display systems directly during vehicle production for quality and integration consistency.
Asia-Pacific commands 64.5% share in 2025, led by China, Japan, and South Korea’s strong automotive manufacturing capabilities and rapidly expanding EV production ecosystems.
Leading players include Aumovio SE, Robert Bosch GmbH, Denso Corporation, and Samsung Electronics Co., Ltd., among others.
OLED displays, AR-HUDs, curved and flexible screens, MicroLED panels, and AI-powered adaptive display technologies are the primary innovations driving the automotive display market forward.
EV manufacturers prioritize large touchscreen interfaces for battery management and energy monitoring, increasing average display area per vehicle and driving higher per-vehicle display content value.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade