
Europe Breakfast Cereals Market Size, Share, Trends and Forecast by Category, Product Type, Distribution Channel, and Country, 2026-2034
Europe Breakfast Cereals Market Size, Share, Trends & Forecast (2026-2034)
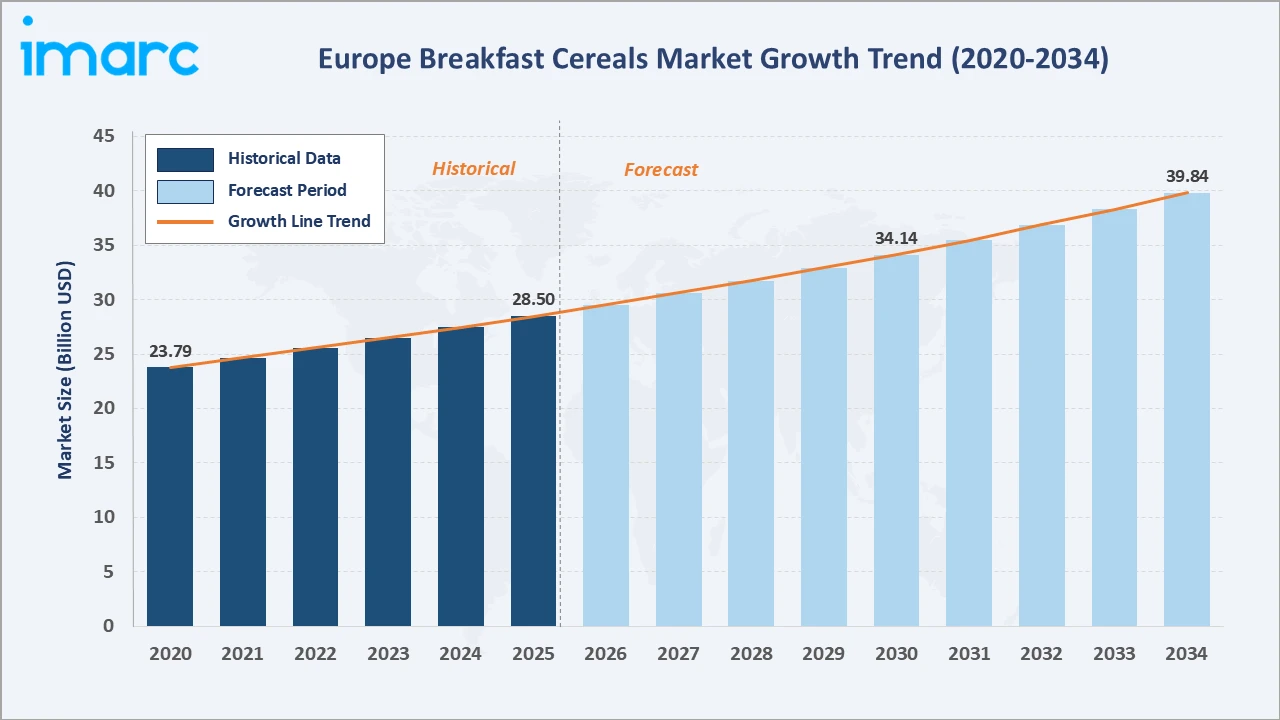
The Europe breakfast cereals market grew from USD 28.50 Billion in 2025 to USD 29.55 Billion in 2026 and is projected to reach USD 39.84 Billion by 2034, growing at a CAGR of 3.68% during 2026-2034 Increasing demand for convenient breakfast options and healthier cereal formulations supports market expansion across the region.
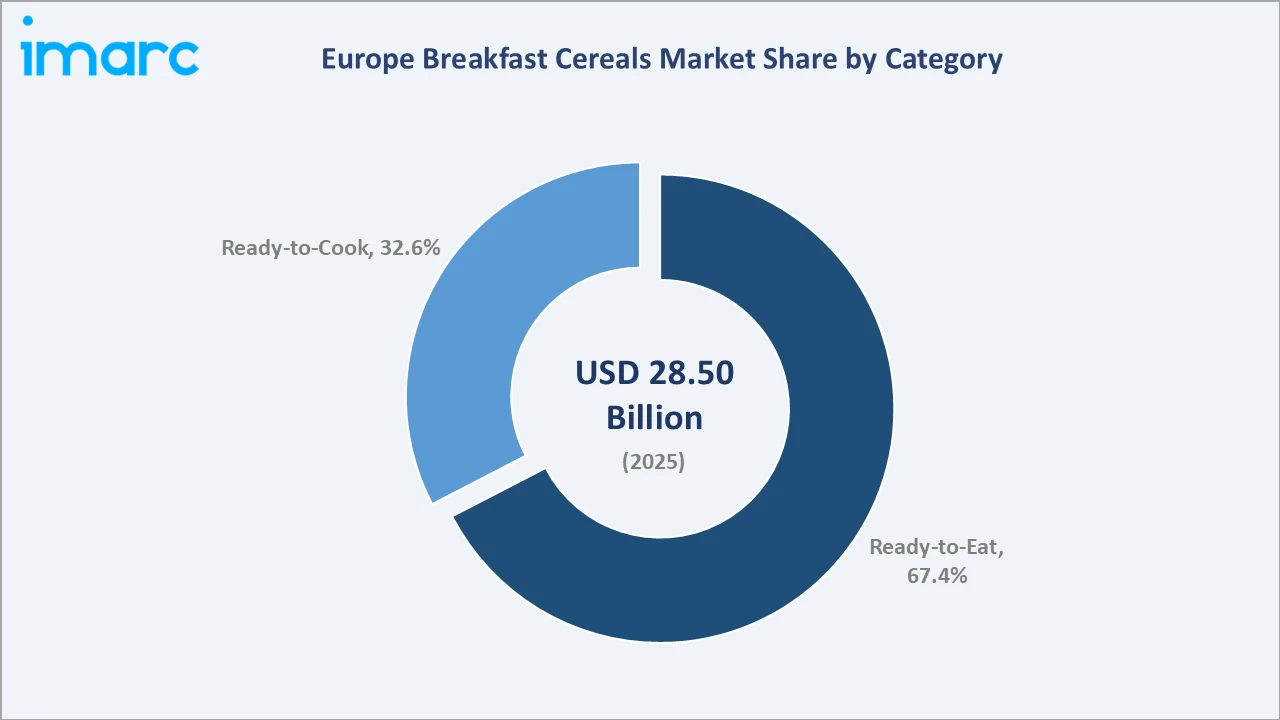
Ready-to-eat leads the category segment at 67.4%, while corn-based breakfast cereals command 42.8% of the product type segment. Germany accounts for 17.8% of the country-wise market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 28.50 Billion |
|
Market Size (2026) |
USD 29.55 Billion |
|
Forecast Market Size (2034) |
USD 39.84 Billion |
|
CAGR (2026-2034) |
3.68% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Country |
Germany (17.8%, 2025) |
|
Second Largest Country |
United Kingdom (16.5%, 2025) |
|
Leading Category |
Ready-to-Eat (67.4%, 2025) |
|
Leading Product Type |
Corn-based Breakfast Cereals (42.8%, 2025) |
The Europe breakfast cereals market size increased from USD 23.79 Billion in 2020 to USD 28.50 Billion in 2025 and is estimated to reach USD 29.55 Billion in 2026. The market is further expected to grow to USD 34.14 Billion by 2030 and USD 39.84 Billion by 2034. This steady growth is anchored by rising health consciousness, busy lifestyles, and a broadening product portfolio spanning fortified, organic, and private-label offerings across all European consumer segments.
To get more information on this market, Request Sample
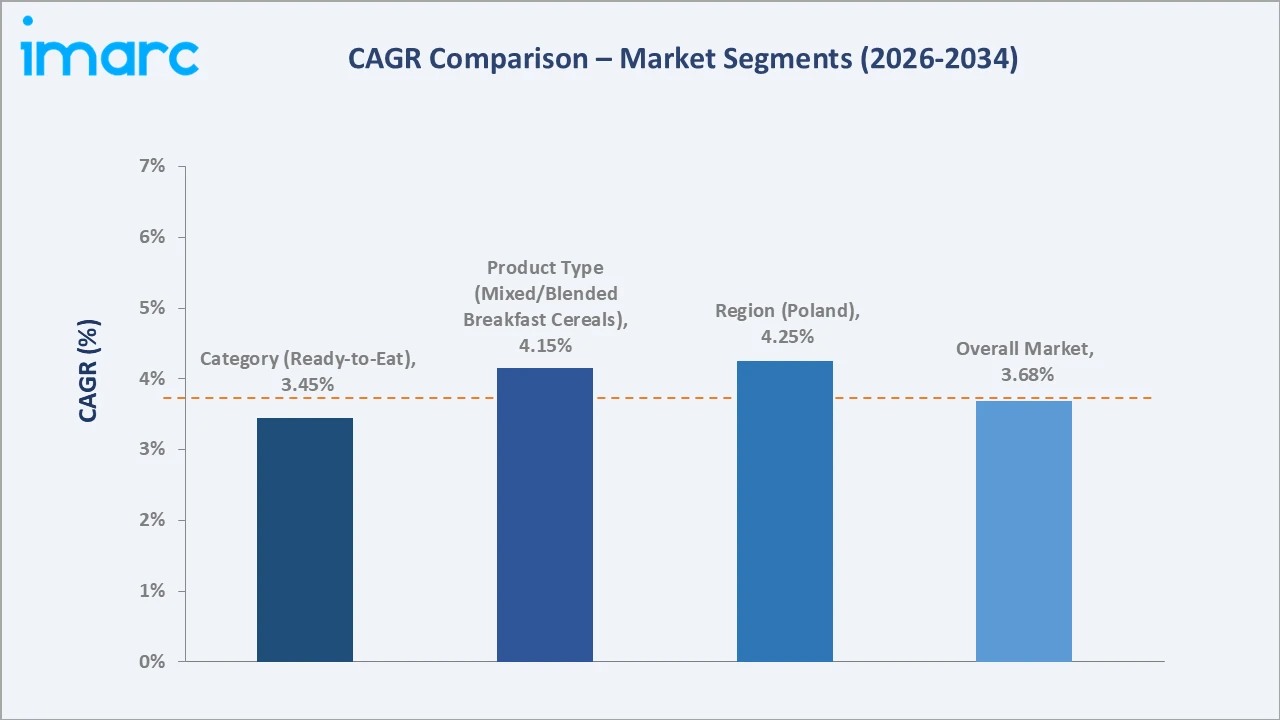
CAGR trajectories across category and product type sub-segments, alongside key country patterns, reveal ready-to-cook and mixed/blended breakfast cereals growing faster than the overall 3.68% market CAGR, driven by increasing consumer interest in warm, customizable, and nutrient-dense breakfast formats.
Executive Summary
The Europe breakfast cereals market expanded from USD 28.50 Billion in 2025 to an estimated USD 29.55 Billion in 2026, positioning it among the largest regional food categories by value in Europe. The market's scale is underpinned by Europe's large consumer base, the established role of breakfast cereals as a convenient daily nutrition solution, and rising consumer demand for health-positioned, fortified, and premium cereal products across all major European markets.
Ready-to-eat leads the category segment at 67.4% in 2025, driven by convenience and wide retail availability, while corn-based breakfast cereals hold the largest product type share at 42.8%, supported by established brand heritage and broad consumer acceptance. Germany commands 17.8% of regional share, supported by strong private-label penetration and high retail density.
Key Market Insights
|
Insight |
Data |
|
Leading Category |
Ready-to-Eat – 67.4% share (2025) |
|
Second Largest Category |
Ready-to-Cook – 32.6% share (2025) |
|
Leading Product Type |
Corn-based Breakfast Cereals – 42.8% share (2025) |
|
Second Largest Product Type |
Mixed/Blended Breakfast Cereals – 36.5% share (2025) |
|
Leading Country |
Germany – 17.8% share (2025) |
|
Second Largest Country |
United Kingdom – 16.5% share (2025) |
|
Top Companies |
Mars, Incorporated, Nestlé S.A., General Mills Inc., PepsiCo Inc. |
Key Analytical Observations Expanding On the Data Above:
- Ready-to-eat dominance at 67.4% is supported by broad retail shelf presence, strong brand loyalty, and the inherent convenience of no-preparation morning consumption, particularly among working adults and families.
- Ready-to-cook share at 32.6% reflects growing appetite for warm, customizable breakfast formats such as porridge and oatmeal, which are perceived as more natural and satiating than cold cereal alternatives.
- Corn-based breakfast cereals leadership at 42.8% is underpinned by decades of consumer familiarity, widespread availability, and the versatility of corn as a base for both mass-market and fortified premium cereal variants.
- Mixed/blended breakfast cereals at 36.5% are gaining relevance as consumers seek nutrient-diverse options combining oats, grains, nuts, and dried fruits in a single product, particularly in the health-conscious millennial segment.
- Germany at 17.8% leads country-level share, anchored by a mature grocery retail sector, robust private-label penetration, and high baseline cereal consumption per household.
Europe Breakfast Cereals Market Overview
Breakfast cereals refer to processed grain-based food products consumed during the morning meal, available in ready-to-eat and ready-to-cook formats. Products span corn flakes, muesli, granola, porridge oats, puffed rice, and mixed-grain blends, catering to diverse nutritional preferences and lifestyles across European households.
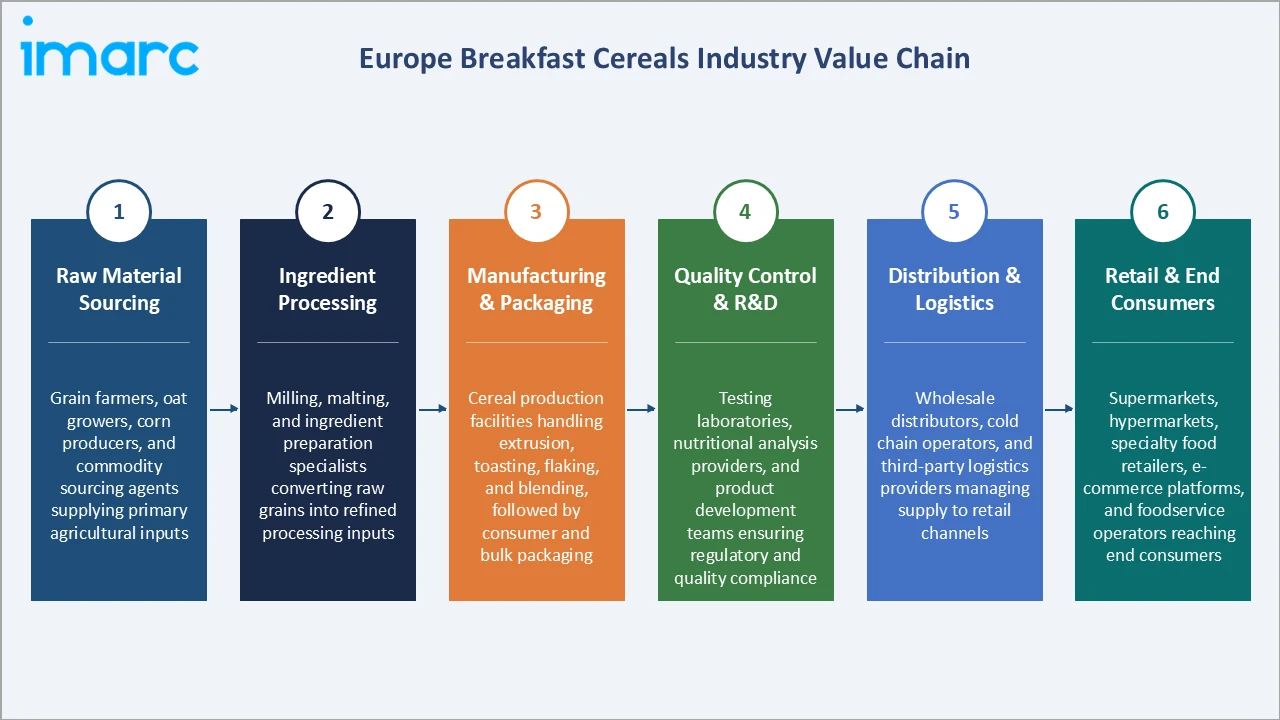
The European ecosystem integrates grain farmers and commodity suppliers, ingredient processors, cereal manufacturers, packaging companies, retail distributors including supermarkets and e-commerce platforms, and end consumers spanning all age groups. Together, these stakeholders enable the development, production, and delivery of a broad range of breakfast cereal products tailored to evolving European dietary trends.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
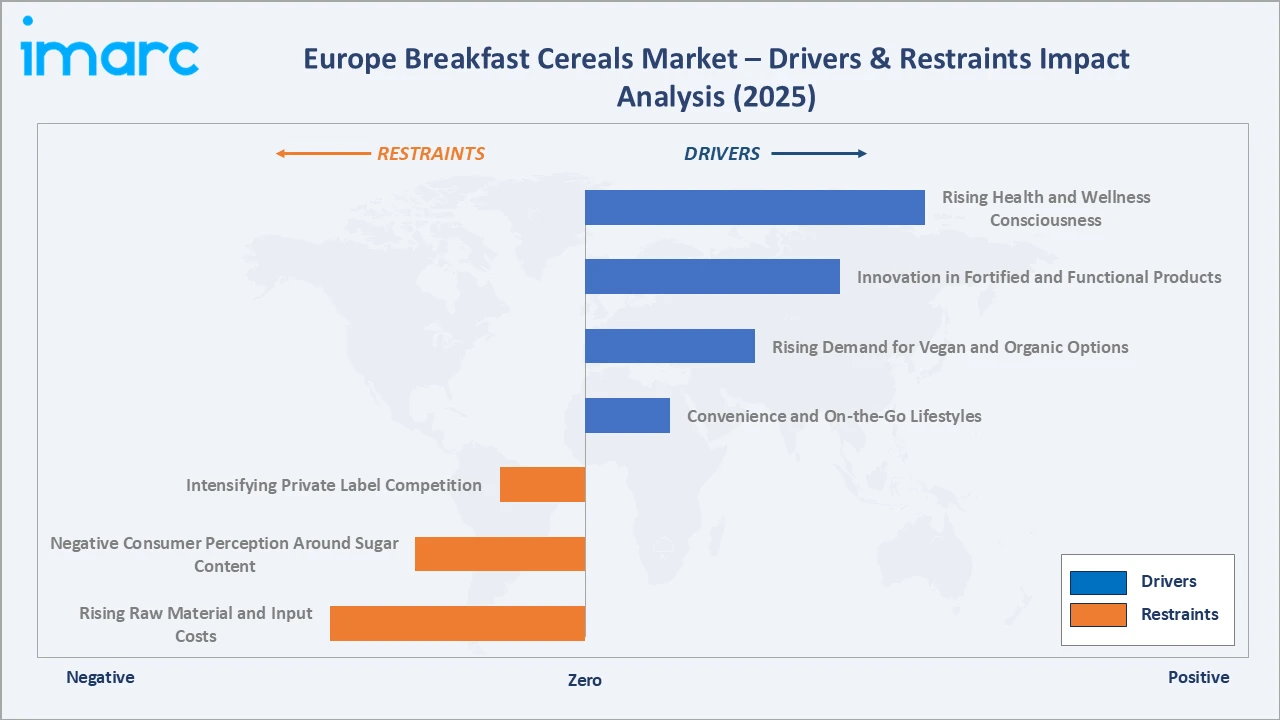
- Rising Health and Wellness Consciousness: Increasing awareness of dietary fiber, whole grains, and micronutrient intake is driving consumers across Europe toward fortified and high-fiber breakfast cereal options as part of balanced daily nutrition routines.
- Innovation in Fortified and Functional Products: Manufacturers are investing in the development of cereals enriched with protein, probiotics, vitamins, and minerals, differentiating products and commanding premium price points across health-focused retail channels in Western Europe.
- Rising Demand for Vegan and Organic Options: As per IMARC Group, the Europe vegan food market size was valued at USD 5.5 Billion in 2025. Growing consumer preference for vegan, plant-based, and organically certified breakfast cereals is expanding product offerings and attracting a broader consumer base, particularly among millennial and Generation Z shoppers.
- Convenience and On-the-Go Lifestyles: Busy urban schedules and a preference for quick, low-preparation breakfast formats are reinforcing demand for ready-to-eat cereal products, which offer a fast and portable morning meal solution for time-pressed European consumers.
Market Restraints
- Rising Raw Material and Input Costs: Volatility in agricultural commodity prices, including grains, oats, and corn, alongside increasing energy and packaging input costs, is creating margin pressure across cereal manufacturers, particularly for mid-tier and smaller regional brands.
- Negative Consumer Perception Around Sugar Content: Heightened scrutiny of added sugar levels in ready-to-eat cereals, amplified by regulatory and media attention, is prompting some consumers to shift away from traditional sugared cereals toward lower-sugar or savory breakfast alternatives.
- Intensifying Private Label Competition: Expanding private-label cereal ranges offered by major European grocery retailers are applying sustained pricing pressure on branded manufacturers, compressing margins and narrowing shelf space for established branded products.
Market Opportunities
- Premiumization of Organic and Specialty Cereal Segments: Growing consumer willingness to pay a premium for organic, non-GMO, and specialty grain cereals is opening significant revenue opportunities for brands that effectively communicate provenance, ingredient quality, and nutritional benefits.
- Expansion of E-Commerce and Direct-to-Consumer Channels: Rising online grocery penetration across Europe is enabling cereal manufacturers to reach health-conscious consumers through digital channels, offering subscription models, personalized nutrition kits, and niche specialty variants not typically stocked in physical retail.
Market Challenges
- Shifting Consumer Preferences Toward Alternative Breakfast Formats: Growing popularity of yogurt, protein bars, smoothies, and other convenient breakfast alternatives is creating competitive substitution pressure for traditional cereal products across multiple European consumer segments.
- Reformulation Complexity and Cost: Meeting evolving clean-label, low-sugar, and high-protein consumer expectations while maintaining taste, texture, and price competitiveness requires significant product reformulation investment that poses challenges for smaller brands with limited R&D resources.
Emerging Market Trends
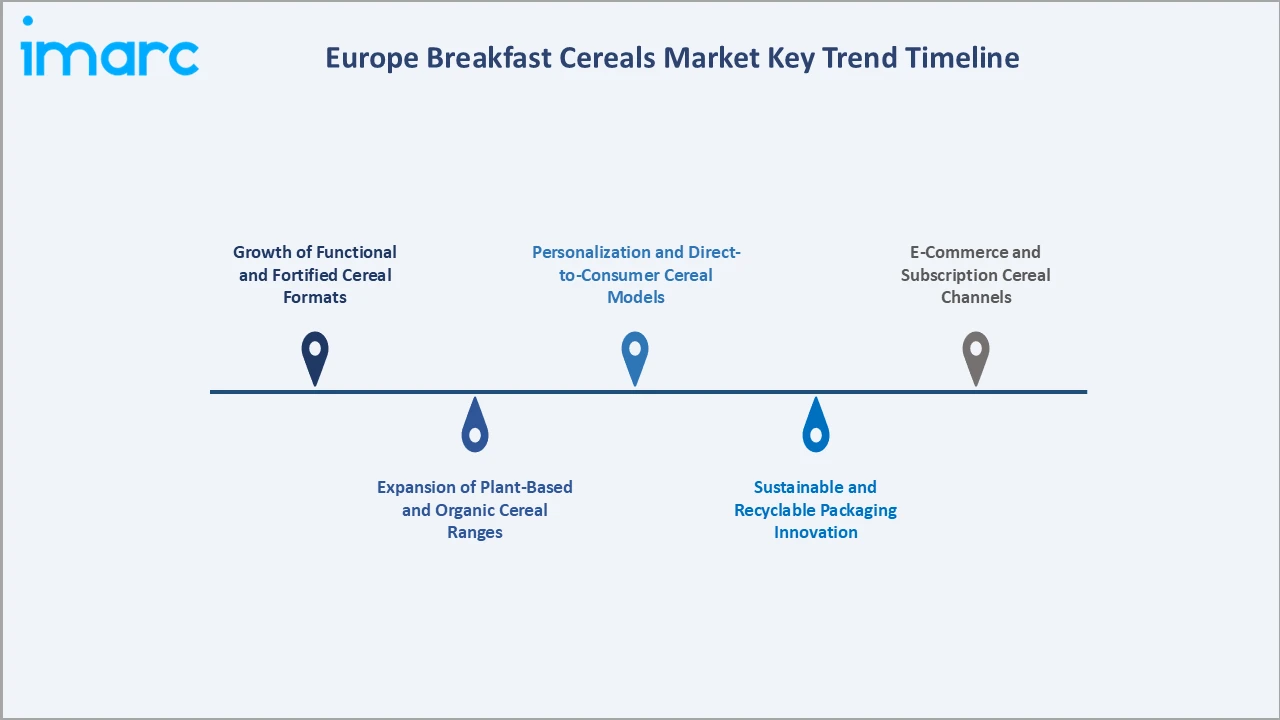
1. Growth of Functional and Fortified Cereal Formats
Cereal manufacturers across Europe are expanding product lines enriched with protein, probiotics, vitamins, and other functional ingredients to meet evolving consumer preferences. This trend is creating opportunities in the Europe oat based cereals market, where oat-based formulations support the development of diverse breakfast products with added nutritional benefits.
2. Expansion of Plant-Based and Organic Cereal Ranges
Rising environmental consciousness and plant-forward dietary shifts are accelerating the development of organic and plant-based cereal lines across European markets. Brands are increasingly sourcing certified organic grains and promoting sustainable agriculture credentials as core differentiators in premium retail positioning.
3. Sustainable and Recyclable Packaging Innovation
Driven by EU regulatory targets and consumer pressure for environmentally responsible packaging, cereal manufacturers are transitioning to recyclable cardboard, paper-based liners, and reduced plastic packaging formats. Sustainability commitments are becoming a meaningful purchase driver for environmentally aware European consumers.
4. Personalization and Direct-to-Consumer Cereal Models
Emerging direct-to-consumer platforms across multiple European countries are enabling consumers to customize cereal mixes based on flavor preferences, dietary requirements, and ingredient choices. These personalized offerings are creating opportunities for cereal brands to strengthen consumer engagement and expand their reach in the France breakfast cereals market.
5. E-Commerce and Subscription Cereal Channels
Online grocery adoption and subscription-based food delivery services are creating new distribution pathways for specialty and premium cereal brands. E-commerce enables smaller brands to achieve broader geographic reach across European markets with lower barriers to entry compared to traditional supermarket shelf placement.
Industry Value Chain Analysis
The Europe breakfast cereals value chain spans six stages, from primary grain and agricultural raw material sourcing through retail and end-consumer delivery. Manufacturing, quality assurance, and retail distribution capture the highest commercial value, while raw material sourcing and ingredient processing form the foundational cost base underpinning the entire production system.
| Stage | Key Players / Examples |
|---|---|
| Raw Material Sourcing | Grain farmers, oat growers, corn producers, and commodity sourcing agents supplying primary agricultural inputs |
| Ingredient Processing | Milling, malting, and ingredient preparation specialists converting raw grains into refined processing inputs |
| Manufacturing & Packaging | Cereal production facilities handling extrusion, toasting, flaking, and blending, followed by consumer and bulk packaging |
| Quality Control & R&D | Testing laboratories, nutritional analysis providers, and product development teams ensuring regulatory and quality compliance |
| Distribution & Logistics | Wholesale distributors, cold chain operators, and third-party logistics providers managing supply to retail channels |
| Retail & Consumer Sales | Supermarkets, hypermarkets, specialty food retailers, e-commerce platforms, and foodservice operators reaching end consumers |
Vertically integrated manufacturers with in-house R&D and proprietary production capabilities are positioned to capture superior margins compared to those reliant on contract manufacturing.
Technology Landscape in the Europe Breakfast Cereals Industry
Advanced Extrusion and Processing Technology
Modern twin-screw extrusion systems enable manufacturers to produce a wider variety of cereal shapes, textures, and formulations with greater energy efficiency. These technologies support the rapid scale-up of new product formats including high-protein and multi-grain extruded cereals.
Clean-Label Formulation and Ingredient Innovation
Investment in natural sweeteners, plant-based protein concentrates, and functional ingredient systems is enabling manufacturers to reformulate existing products and launch clean-label variants meeting consumer and regulatory expectations for simplified, recognizable ingredient lists.
Sustainable Packaging and Material Science
Advances in recyclable mono-material films, paper-based inner liners, and compostable packaging solutions are helping cereal manufacturers address packaging waste concerns and applicable European regulatory requirements. These developments support more sustainable packaging practices and strengthen product differentiation across the breakfast cereals industry.
Automation and Digital Supply Chain Integration
Manufacturers are deploying automated production lines, AI-driven quality inspection systems, and digital supply chain management platforms to reduce production costs, minimize waste, and improve forecast accuracy across complex multi-SKU European cereal portfolios.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Category | Ready-to-Eat | 67.4% | 2025 |
| Product Type | Corn-based Breakfast Cereals | 42.8% | 2025 |
| Distribution Channel | 🔒 | 🔒 | 2025 |
| Country | Germany | 17.8% | 2025 |

By Category
Ready-to-eat commands a 67.4% majority share in 2025, driven by its convenience, broad retail availability, and strong brand legacy among European consumers. The segment benefits from extensive shelf placement, established loyalty among families, and a wide range of product formats spanning corn flakes, muesli, granola, and puffed grain varieties.
To access detailed market analysis, Request Sample
Ready-to-cook at 32.6% in 2025 includes porridge oats, hot oatmeal, and grain-based warm breakfast formats that are gaining traction as consumers associate them with naturalness, satiety, and clean-label nutrition.
By Product Type
Corn-based breakfast cereals lead the product type segment with 42.8% share in 2025, reflecting decades of consumer familiarity, widespread manufacturing infrastructure, and the versatility of corn as a base ingredient for both mass-market and premium fortified cereal products.
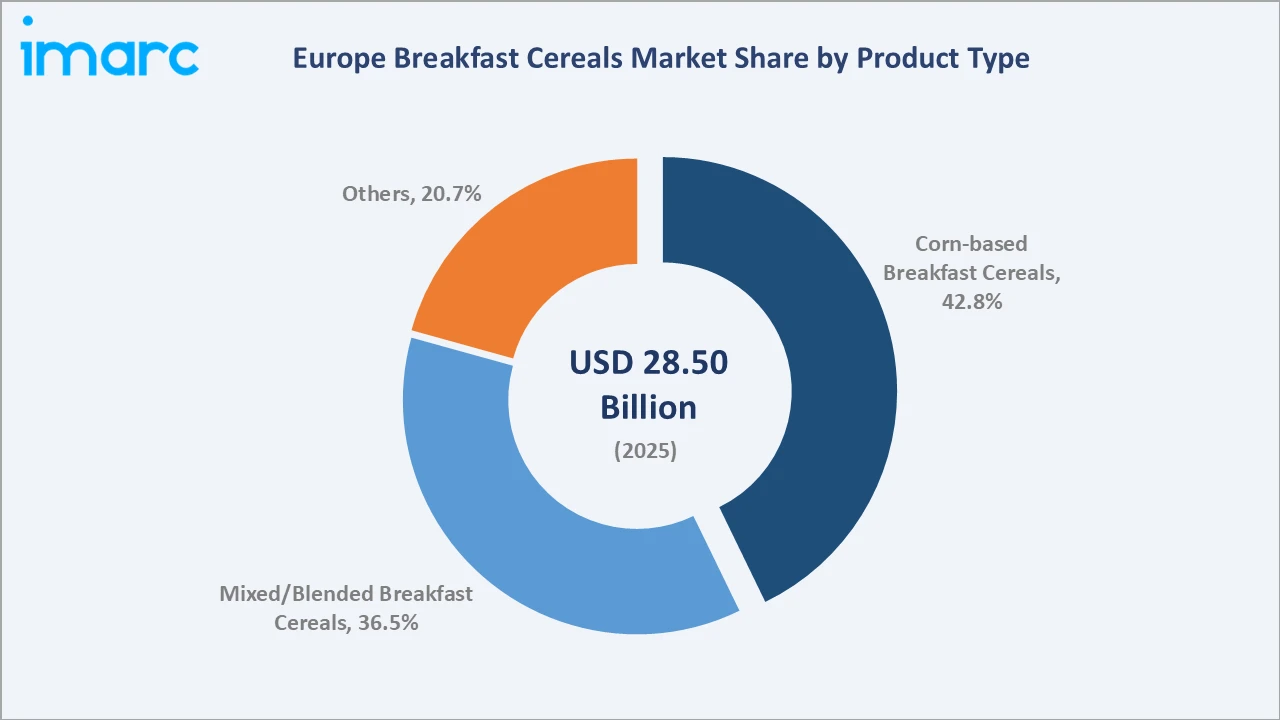
Mixed/blended breakfast cereals hold 36.5% of the product type segment in 2025, driven by rising consumer preference for nutritionally diverse products combining oats, seeds, nuts, and dried fruits. These products resonate strongly with health-conscious adult consumers and are commanding premium pricing within specialty and natural food retail channels.
Regional Market Insights
| Country | Share (2025) | Key Growth Drivers |
|---|---|---|
| Germany | 17.8% | Mature retail infrastructure, high private-label penetration, strong per-household cereal consumption |
| United Kingdom | 16.5% | Deep-rooted breakfast cereal culture, broad product innovation pipeline, strong branded and private-label competition |
| France | 14.7% | Growing health-positioned cereal demand, expanding organic retail segment, high consumer awareness of nutritional labeling |
| Italy | 11.8% | Rising ready-to-eat adoption, expanding convenience food culture, growing urban breakfast cereal consumption |
| Spain | 9.7% | Increasing cereal penetration among younger demographics, growing health and wellness retail presence |
| Poland | 8.2% | Expanding modern retail channels, rising disposable incomes, growing awareness of Western breakfast consumption habits |
| Netherlands | 7.4% | High retail density, established whole-grain and muesli consumption traditions, strong sustainability-focused consumer base |
| Russia | 6.9% | Large population base, expanding urban middle class, increasing retail modernization supporting cereal adoption |
| Switzerland | 4.8% | High-income market with strong demand for premium, organic, and specialty grain breakfast products |
| Others | 2.2% | Remaining European markets with emerging cereal adoption supported by growing retail infrastructure and rising incomes |
Germany accounts for 17.8% of the regional market share in 2025, supported by a well-established grocery retail network, high private-label cereal penetration, and consistent per-capita consumption. Consumers demonstrate steady demand for traditional corn-based cereals as well as premium muesli and organic grain variants, strengthening the position of the Germany breakfast cereals market.
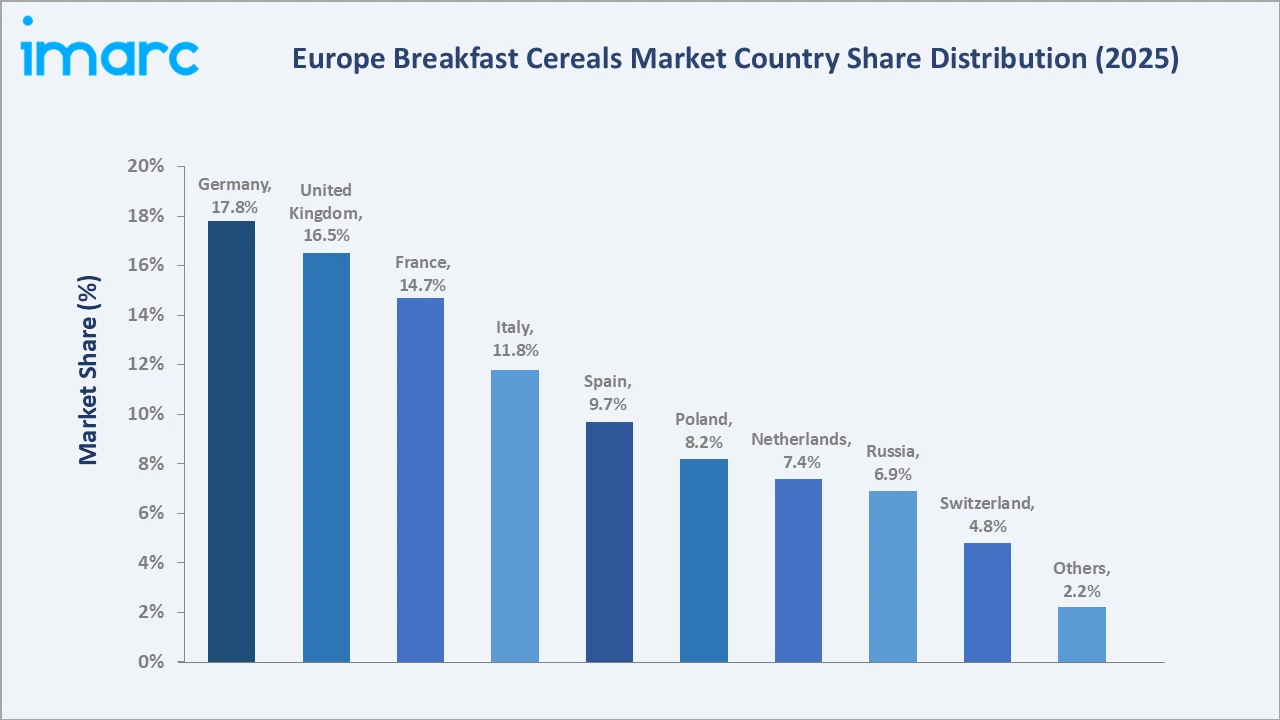
United Kingdom accounts for 16.5% of the market in 2025, supported by established grocery retail networks, widespread cereal consumption, and strong demand for convenient breakfast options.
Competitive Landscape
The Europe breakfast cereals market is moderately concentrated, with global cereal majors and established European heritage brands holding dominant positions across mass-retail channels. Product innovation, brand equity, nutritional reformulation capability, and retail distribution depth form the core competitive differentiators across the industry.
| Company Name | Brand / Key Product | Position | Strategic Focus |
|---|---|---|---|
| Mars, Incorporated | Special K, Corn Flakes, Frosties | Leader | Expanding product portfolios while leveraging established brands and consumer loyalty |
| Nestlé S.A. | Nesquik Cereals | Leader | Developing health-focused cereal innovations while strengthening global market presence |
| General Mills Inc. | Cheerios | Leader | Strengthening whole-grain cereal offerings while expanding health-conscious consumer appeal |
| PepsiCo, Inc. | Quaker Oats, Quaker Granola | Challenger | Expanding oat-based and natural grain products to capture evolving consumer preferences |
Key players include Mars, Incorporated, Nestlé S.A., General Mills Inc., and PepsiCo Inc., among others.
Key Company Profiles
Mars, Incorporated
Mars, Incorporated is a privately held global food and confectionery company with a broad consumer goods portfolio spanning confectionery, petcare, and food segments.
- Product Portfolio: European breakfast cereal portfolio comprising Special K, Corn Flakes, and Frosties, comprising well-established ready-to-eat cereal brands with broad household recognition.
- Recent Developments: The company continues to pursue portfolio integration following recent acquisitions, investing in brand continuity and supply chain optimization across its expanded food and cereal product range in European markets.
- Strategic Focus: Broadening branded cereal reach across European retail channels while nurturing consumer loyalty through trusted, heritage-driven product identities and sustained investment in portfolio depth and market accessibility.
Nestlé S.A.
Nestlé S.A. is a Switzerland-based multinational food and beverage company and one of the largest consumer food groups globally. The company focuses on product innovation, nutritional quality, and brand development to address evolving consumer preferences.
- Product Portfolio: Nesquik Cereals and associated ready-to-eat cereal products, targeting family and children's breakfast segments across European retail channels.
- Recent Developments: The company continues to pursue nutritional improvement programs across its cereal range, focusing on reduced sugar formulations, increased whole-grain content, and responsible packaging transitions within its European operations.
- Strategic Focus: Advancing health-oriented cereal innovation and reinforcing global market reach through collaborative distribution models while aligning product formulations with evolving European consumer nutrition and sustainability expectations.
General Mills Inc.
General Mills Inc. is a United States-based multinational food company with a significant presence in the Europe breakfast cereals market.
- Product Portfolio: Cheerios range of whole-grain ready-to-eat cereals, available across major European retail markets in multiple variants targeting adults and family segments.
- Recent Developments: The company continues to invest in whole-grain cereal reformulation, advancing clean-label initiatives and expanding its nutritionally positioned product range across distribution markets.
- Strategic Focus: Reinforcing whole-grain cereal credentials and widening health-conscious consumer appeal across European markets by continuously evolving product formulations and deepening retailer partnerships through established joint venture distribution.
Market Concentration Analysis
The Europe breakfast cereals market is moderately concentrated, with a small number of large multinational manufacturers and established European heritage brands accounting for the majority of retail sales volumes.
Barriers to entry include significant brand investment requirements, established retailer relationships, complex supply chain infrastructure, and the need for regulatory compliance across multiple European market jurisdictions.
Consolidation trends are gradually reshaping the competitive structure as larger players acquire regional brands and specialty cereal companies to broaden portfolio coverage across health, premium, and private-label adjacent segments. Strategic partnerships between ingredient suppliers and manufacturers are further influencing competitive positioning.
Investment & Growth Opportunities
Fastest-Growing Segments
Ready-to-cook is expanding faster than the overall market, driven by rising demand for warm, fiber-rich, and minimally processed morning formats. Mixed/blended breakfast cereals within the product type segment are also growing above average as consumers seek nutritionally diverse, multi-ingredient breakfast solutions at accessible price points.
Emerging Markets
Poland represents the fastest-growing country, driven by rising disposable incomes, evolving breakfast consumption patterns, and expanding modern grocery retail networks. Growing demand for convenient, affordable, and premium breakfast products is further creating opportunities for cereal manufacturers to expand their presence in the Polish market.
Venture & Investment Trends
Investment activity is concentrated in clean-label reformulation, organic and functional cereal development, and sustainable packaging innovation. Capital is also flowing into e-commerce cereal distribution platforms and direct-to-consumer subscription models that enable brands to build direct consumer relationships beyond traditional grocery retail channels across Europe.
Future Market Outlook (2026-2034)
The Europe breakfast cereals market is projected to grow from USD 28.50 Billion in 2025 to USD 29.55 Billion in 2026, reaching USD 39.84 Billion by 2034, registering a CAGR of 3.68% during 2026-2034.
Four forces will define the market through 2034: continued premiumization within health-positioned and organic cereal segments; accelerating innovation in functional and fortified breakfast formats; expanding e-commerce and direct-to-consumer distribution channels; and growing emphasis on sustainable packaging and clean-label formulations.
By 2034, the Europe breakfast cereals market is expected to be shaped by a more segmented consumer landscape, with distinct demand clusters spanning mass-market value cereals, premium health-positioned formats, and personalized nutrition offerings. Sustainable packaging, clean-label formulation, and science-backed nutritional claims are expected to become standard market entry requirements rather than differentiating factors.
Research Methodology
Primary Research
Primary research included structured interviews with cereal category managers, food manufacturing executives, retail buyers, and nutrition specialists across European markets, validating market sizing, segment mix, and regional demand patterns from industry-facing practitioners.
Secondary Research
Secondary sources included European Commission agricultural and food industry publications, national statistics offices across Germany, the United Kingdom, France, and other key markets, trade association reports, and annual reports and investor presentations from publicly listed cereal and food manufacturing companies.
Forecasting Models
Market forecasts employed top-down and bottom-up modeling approaches combining category-level consumption data, retail sales trends, demographic drivers, and macroeconomic variables. Scenario analysis addressed regulatory evolution, health trend acceleration, and commodity price volatility impacts on cereal market trajectory through 2034.
Europe Breakfast Cereals Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Categories Covered | Ready-to-Cook, Ready-to-Eat |
| Product Types Covered | Corn-based Breakfast Cereals, Mixed/Blended Breakfast Cereals, Others |
| Distribution Channels Covered | Supermarkets and Hypermarkets, Specialty Stores, Online Stores, Others |
| Countries Covered | Germany, United Kingdom, France, Italy, Russia, Spain, Netherlands, Switzerland, Poland, Others |
| Companies Covered | Mars, Incorporated, Nestlé S.A., General Mills Inc., PepsiCo, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Europe breakfast cereals market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Europe breakfast cereals market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the breakfast cereals industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Europe Breakfast Cereals Market Report
The Europe breakfast cereals market size is estimated at USD 29.55 Billion in 2026, driven by rising health consciousness, convenience demand, and broad product innovation across ready-to-eat and ready-to-cook cereal formats.
The market is projected to grow at a CAGR of 3.68% from 2026-2034, reaching USD 39.84 Billion by 2034, supported by premiumization, health-positioned innovation, and expanding demand for organic and convenient breakfast options.
Ready-to-eat represents the largest category segment, commanding 67.4% of the market in 2025, underpinned by zero-preparation convenience, established brand loyalty, and broad shelf availability across European mass retail and grocery channels.
Corn-based breakfast cereals are the largest product type, holding 42.8% of the segment in 2025, driven by deep consumer familiarity, extensive manufacturing infrastructure, and widespread retail shelf presence across all European market tiers.
Germany commands 17.8% share in 2025, led by a mature grocery retail sector, strong private-label penetration, and consistently high per-household cereal consumption volumes.
Leading players include Mars, Incorporated, Nestlé S.A., General Mills Inc., and PepsiCo Inc., among others.
Rising consumer demand for whole-grain, fortified, and reduced-sugar cereal products is accelerating reformulation investment and driving premiumization across European cereal retail channels.
Growing online grocery adoption is enabling specialty and premium cereal brands to reach health-conscious consumers directly, bypassing traditional retail constraints and supporting subscription-based purchasing models.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade