
Europe Carpet Market Size, Share, Trends and Forecast by Material, Price Point, Sales Channel, End User, and Country, 2026-2034
Europe Carpet Market Size, Share, Trends & Forecast (2026-2034)
The Europe carpet market grew from USD 16.96 Billion in 2025 to USD 17.64 Billion in 2026 and is projected to reach USD 22.57 Billion by 2034, exhibiting a CAGR of 3.13% during 2026-2034. Sustained residential renovation activity, commercial real estate expansion, and rising consumer preference for comfort-oriented interior solutions are the primary forces driving market growth across Europe.
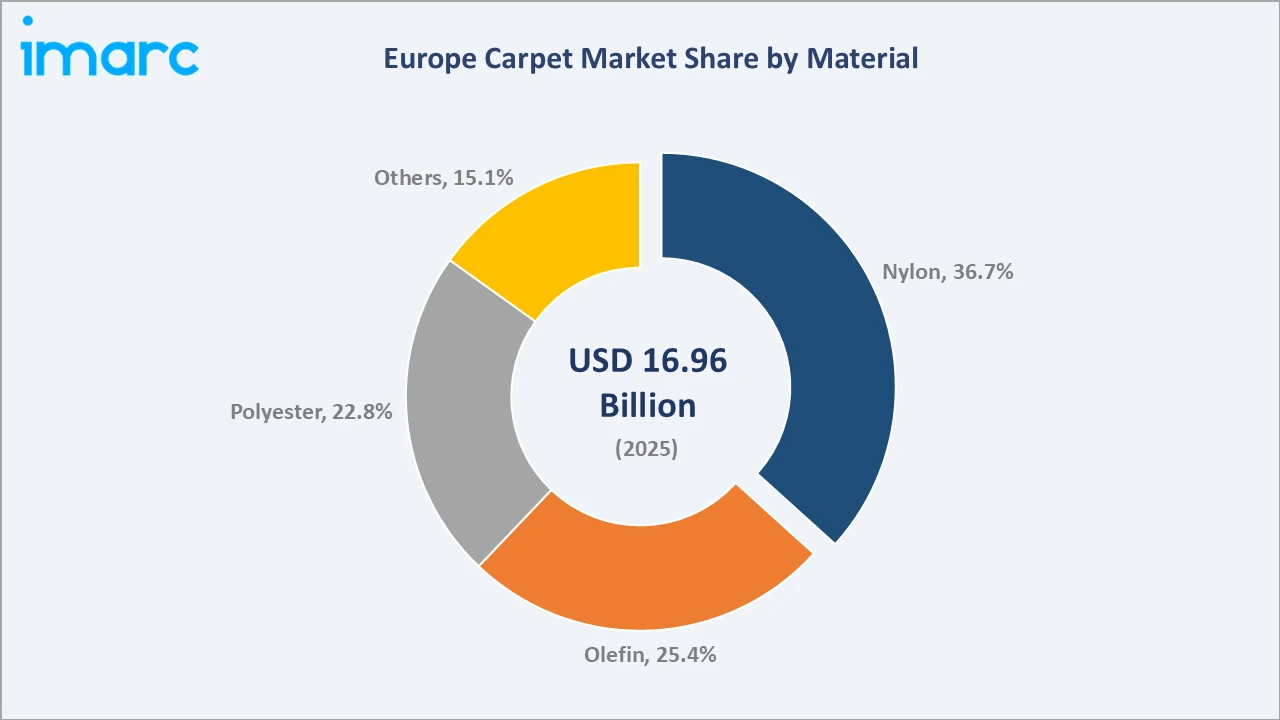
Nylon leads the material segment at 36.7%, while economy commands the price point segment at 61.3%. Germany dominates the market with a 25.8% share in 2025.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 16.96 Billion |
| Market Size (2026) | USD 17.64 Billion |
| Forecast Market Size (2034) | USD 22.57 Billion |
| CAGR (2026-2034) | 3.13% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Largest Country | Germany (25.8%, 2025) |
| Second Largest Country | France (17.6%, 2025) |
| Leading Material | Nylon (36.7%, 2025) |
| Leading Price Point | Economy (61.3%, 2025) |
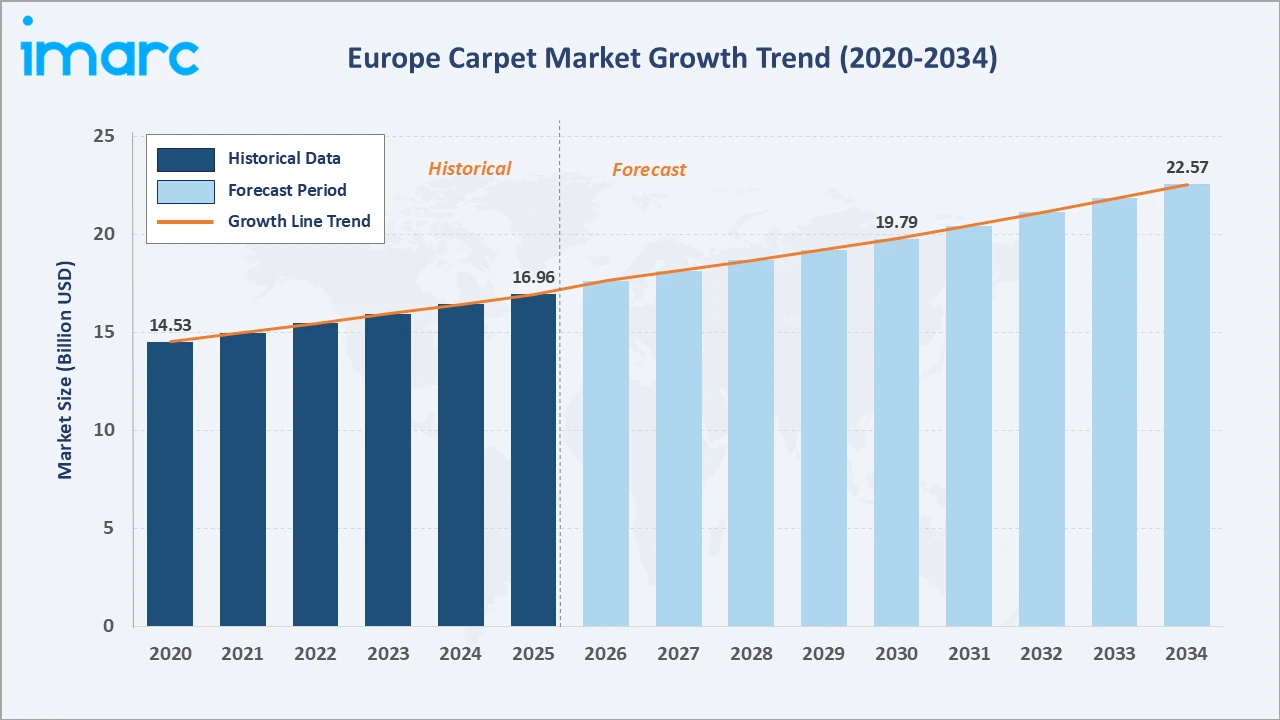
The Europe carpet market size increased from USD 14.53 Billion in 2020 to USD 16.96 Billion in 2025 and is estimated to reach USD 17.64 Billion in 2026. The market is further expected to grow to USD 19.79 Billion by 2030 and USD 22.57 Billion by 2034. The market reflects a commercially mature yet steadily expanding landscape, underpinned by consistent residential demand, a growing premium segment, and increasing commercial specification activity across Western and Central Europe.
To get more information on this market, Request Sample
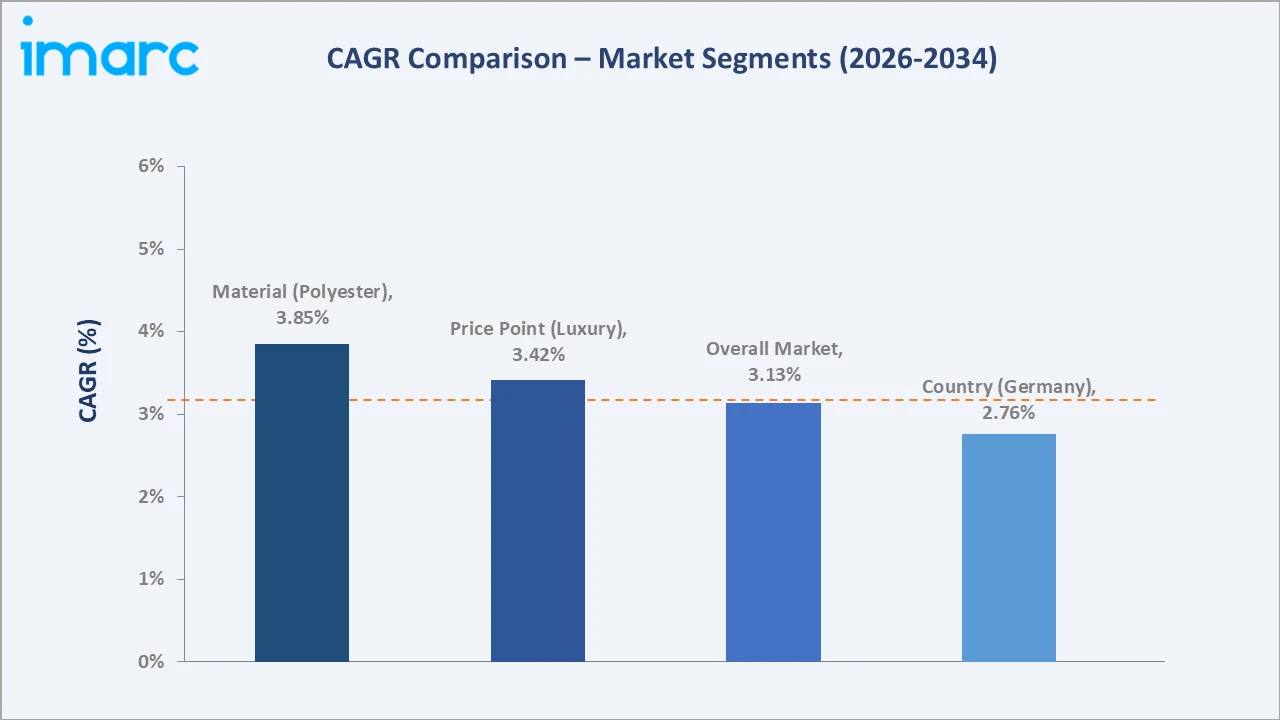
CAGR trajectories across material, price point, and country sub-segments show polyester and luxury expanding faster than the overall 3.13% market CAGR, driven by sustainability trends, premiumization in residential interiors, and expanding boutique hospitality demand across Europe.
Executive Summary
The Europe carpet market expanded from USD 16.96 Billion in 2025 to an estimated USD 17.64 Billion in 2026, driven by consistent residential renovation activity, commercial real estate expansion, and rising demand for comfort-focused interior solutions. Steady improvement in living standards, active home improvement spending across Germany, France, and the United Kingdom, and growing hospitality investment continue to underpin stable demand growth across the region.
Nylon commands 36.7% material share in 2025, favored for its durability, stain resistance, and aesthetic versatility in both residential and commercial applications. Economy leads the price point segment at 61.3%, supported by broad adoption across residential and institutional end-user categories. Germany holds 25.8% market share in 2025, anchored by its large construction and renovation sector.
Key Market Insights
| Insight | Data |
|---|---|
| Leading Material | Nylon – 36.7% share (2025) |
| Second Largest Material | Olefin – 25.4% share (2025) |
| Leading Price Point | Economy – 61.3% share (2025) |
| Second Largest Price Point | Luxury – 38.7% share (2025) |
| Leading Country | Germany – 25.8% share (2025) |
| Second Largest Country | France – 17.6% share (2025) |
| Top Companies | Belysse Group NV, Victoria PLC, Interface, Inc. |
Key Analytical Observations Expanding On the Data Above:
- Nylon dominance at 36.7% reflects its superior durability, abrasion resistance, and stain performance, making it the preferred fiber for high-traffic residential and commercial environments across Europe.
- Olefin at 25.4% is widely adopted in outdoor and contract carpet applications, supported by its moisture resistance, UV stability, and cost-efficient production profile relative to nylon.
- Economy leadership at 61.3% reflects widespread residential demand for functional, affordable floor covering solutions across Europe's diverse national housing markets.
- Luxury at 38.7% is expanding as rising disposable incomes and growing investment in premium residential and hospitality interiors drive upgrades toward designer and natural fiber carpet products.
- Germany at 25.8% leads regional share, anchored by its large construction sector, active renovation market, and the concentration of major carpet manufacturing and distribution infrastructure within the country.
Europe Carpet Market Overview
Carpet refers to a textile floor covering manufactured from woven, tufted, needle-punched, or bonded fibers, including nylon, olefin, polyester, and wool. Carpets provide thermal insulation, acoustic dampening, and aesthetic differentiation across a wide range of interior environments throughout Europe.
Key stakeholders include residential and commercial construction companies, interior designers, facility managers, and hospitality operators. EU standards for fire resistance, indoor air quality, and sustainability labeling increasingly shape product development and procurement decisions across the region.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
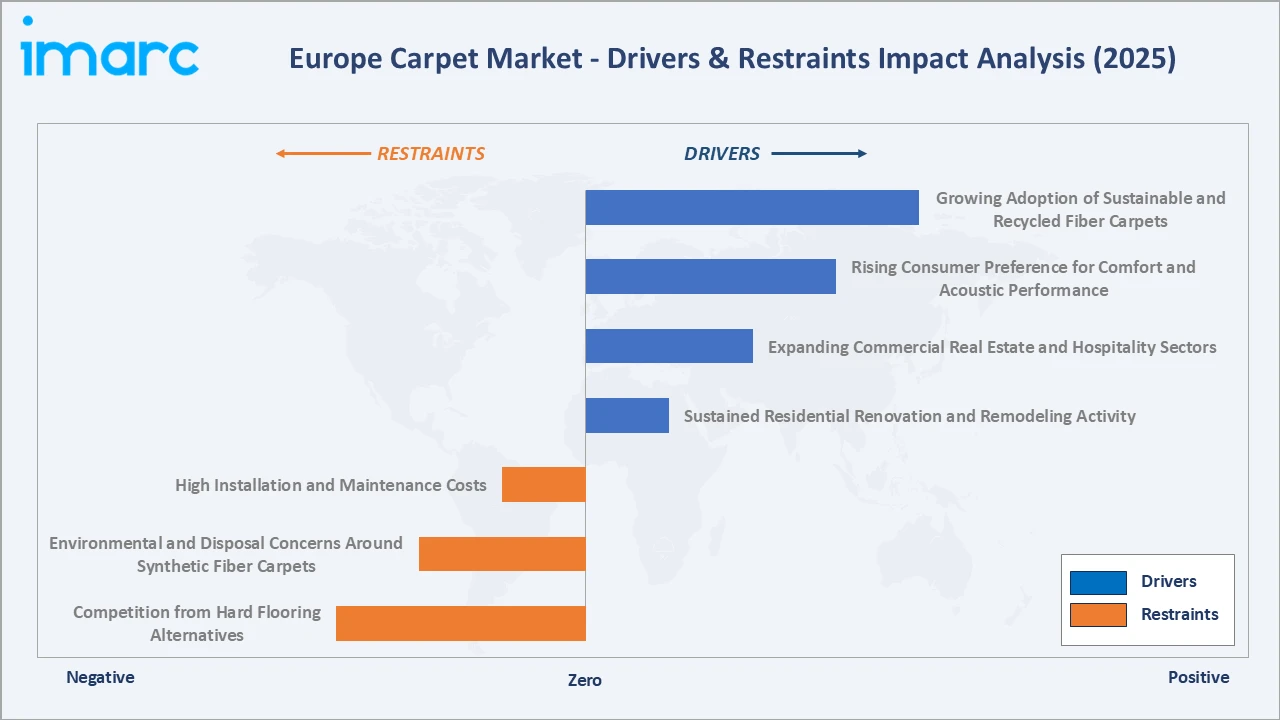
- Sustained Residential Renovation and Remodeling Activity: Ongoing investment in home renovation and remodeling programs across Germany, France, and the United Kingdom is fueling the expansion of the Europe carpet industry. The large stock of aging residential properties across Western Europe sustains a stable replacement demand cycle throughout the residential segment.
- Expanding Commercial Real Estate and Hospitality Sectors: As per IMARC Group, the UK commercial real estate market size reached USD 269.2 Billion in 2025. Continued development of office complexes, hotels, retail spaces, and educational institutions across Europe supports specification-grade carpet procurement. Commercial and hospitality applications prioritize durability and acoustic performance, favoring high-performance nylon and modular carpet tile formats in new build and fit-out projects.
- Rising Consumer Preference for Comfort and Acoustic Performance: Growing awareness of the indoor comfort and noise reduction benefits of carpet flooring is encouraging renewed interest, particularly in markets where hard surface alternatives have gained traction. Carpet's ability to reduce ambient noise levels provides a measurable performance advantage in densely occupied residential and commercial buildings.
- Growing Adoption of Sustainable and Recycled Fiber Carpets: Increasing regulatory pressure and rising consumer environmental awareness are accelerating adoption of carpets incorporating recycled nylon, recycled PET polyester, and bio-based fibers.
Market Restraints
- Competition from Hard Flooring Alternatives: Laminate, luxury vinyl tile, and engineered hardwood flooring continue to gain share in European residential renovation projects, displacing carpet in living areas and corridors where ease of cleaning and contemporary aesthetics are prioritized by homeowners and specifiers.
- Environmental and Disposal Concerns Around Synthetic Fiber Carpets: Growing scrutiny over the environmental impact of synthetic carpets, including end-of-life landfill volumes and energy-intensive production processes, is influencing specification decisions in sustainability-focused commercial and institutional procurement channels across Europe.
- High Installation and Maintenance Costs: Expenses associated with professional installation, periodic deep cleaning, and carpet replacement can discourage price-sensitive consumers and limit carpet adoption in residential and commercial settings across Europe.
Market Opportunities
- Growth in Eco-Certified and Circular Economy Carpet Products: Increasing demand for eco-certified and carbon-neutral carpet products is creating premium market opportunities for manufacturers investing in recycled fiber content, take-back programs, and low-emission production processes across Europe.
- Rising Demand in Healthcare and Education Sectors: Acoustic performance, slip resistance, and thermal comfort requirements in healthcare facilities, schools, and universities are driving carpet specification in these institutional markets, providing a stable demand channel for functional commercial carpet products within the flooring and carpet market across Europe.
Market Challenges
- Raw Material Price Volatility: Fluctuations in crude oil-derived petrochemical feedstocks, which underpin nylon, olefin, and polyester fiber production, expose carpet manufacturers to input cost pressures that are difficult to fully pass through to price-sensitive end users in competitive markets.
- Competitive Pressure from Low-Cost Imports: Increasing volumes of competitively priced carpet imports from Asia and Eastern European manufacturers are compressing margins for established Western European producers, intensifying pressure to differentiate on quality, design, and sustainability credentials.
Emerging Market Trends
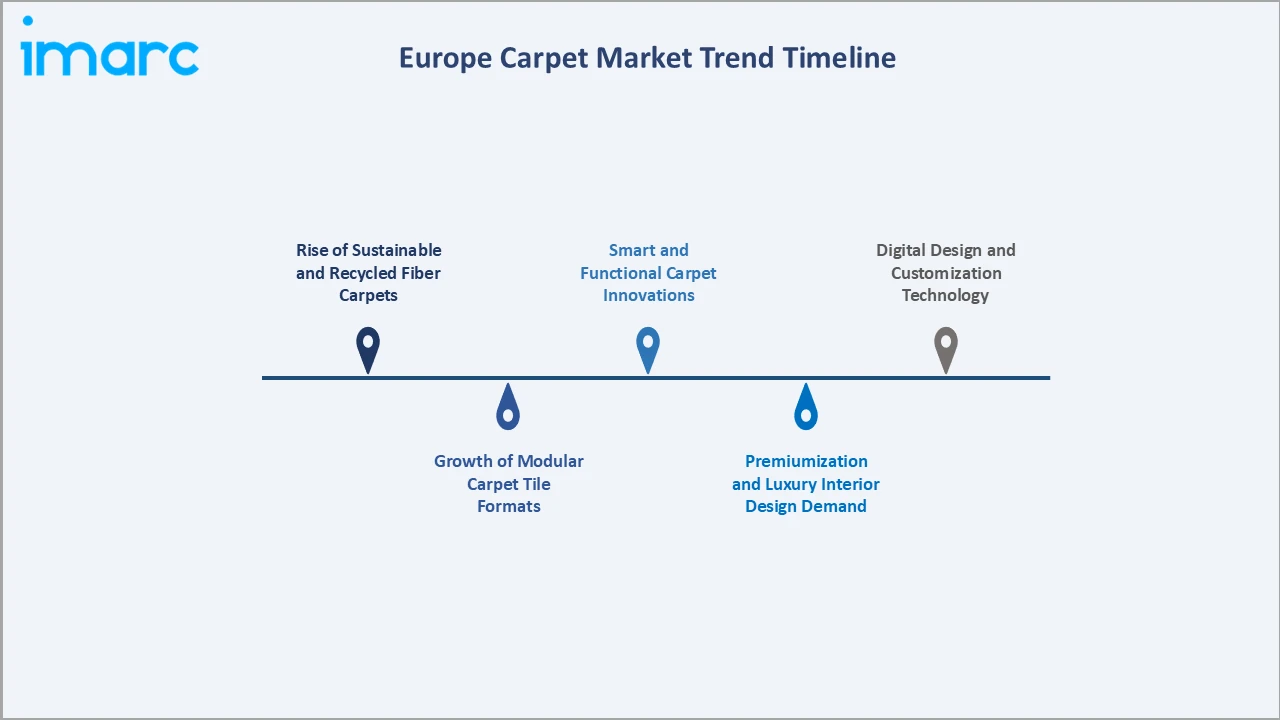
1. Rise of Sustainable and Recycled Fiber Carpets
Manufacturers across Europe are significantly expanding ranges incorporating recycled nylon and recycled PET polyester, responding to regulatory and consumer pressure for sustainable flooring. This trend is encouraging greater investment in recyclable materials, resource-efficient manufacturing, and circular product designs across the European carpet industry.
2. Growth of Modular Carpet Tile Formats
Carpet tiles are gaining share in commercial interiors due to ease of installation, zone-specific replacement capability, and compatibility with underfloor heating and raised floor systems. Design flexibility and reduced waste in large-scale office fit-outs are further supporting adoption across the flooring carpets market, spanning corporate, educational, and hospitality environments throughout Europe.
3. Premiumization and Luxury Interior Design Demand
Rising disposable incomes and growing investment in premium residential and hospitality interiors are driving demand for designer carpets featuring hand-tufted construction, natural fibers, and bespoke pattern capabilities. The luxury carpet segment benefits from increased residential renovation spending and the expansion of boutique hotels and high-end commercial developments.
4. Smart and Functional Carpet Innovations
European carpet manufacturers are introducing products with integrated sensor technology for space utilization monitoring, antimicrobial fiber treatments for healthcare environments, and enhanced moisture management systems for commercial applications. These functional innovations are broadening carpet applications beyond traditional decorative uses across the region.
5. Digital Design and Customization Technology
Adoption of digital tufting, digital weaving, and large-format digital printing technologies is enabling carpet manufacturers to offer rapid design customization at lower minimum order quantities. This is opening new commercial opportunities in boutique hospitality, branded retail environments, and high-end residential projects across Europe.
Industry Value Chain Analysis
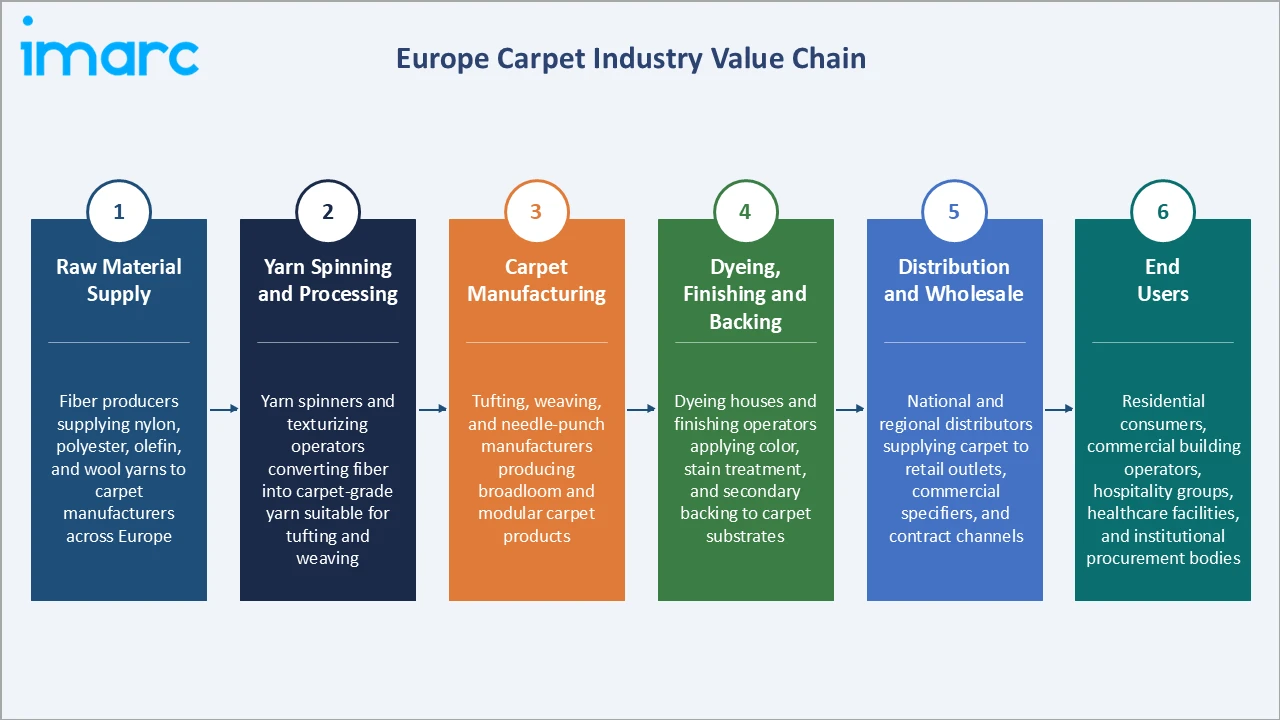
The Europe carpet value chain concentrates value-add at the manufacturing, finishing, and commercial specification stages, with vertically integrated producers capturing margin across fiber processing, carpet production, and branded distribution. Sustainability requirements are reshaping upstream sourcing, with increasing integration between recycled fiber suppliers and carpet manufacturers committed to circular economy product standards.
| Stage | Key Players / Examples |
|---|---|
| Raw Material Supply | Fiber producers supplying nylon, polyester, olefin, and wool yarns to carpet manufacturers across Europe |
| Yarn Spinning and Processing | Yarn spinners and texturizing operators converting fiber into carpet-grade yarn suitable for tufting and weaving |
| Carpet Manufacturing | Tufting, weaving, and needle-punch manufacturers producing broadloom and modular carpet products |
| Dyeing, Finishing and Backing | Dyeing houses and finishing operators applying color, stain treatment, and secondary backing to carpet substrates |
| Distribution and Wholesale | National and regional distributors supplying carpet to retail outlets, commercial specifiers, and contract channels |
| End Users | Residential consumers, commercial building operators, hospitality groups, healthcare facilities, and institutional procurement bodies |
Manufacturers controlling yarn extrusion, backing production, and direct commercial specification channels are positioned to absorb input cost volatility more effectively than single-stage carpet producers reliant on external fiber suppliers and third-party contract distributors competing on price across the Europe market.
Technology Landscape in the Europe Carpet Industry
Tufting Technology
Modern tufting machines capable of high stitch-per-minute rates dominate European carpet manufacturing. Advanced computer-controlled tufting enables high-definition pattern reproduction, variable pile heights, and rapid design changeovers, supporting the trend toward customized commercial and residential carpet products.
Weaving Technology
Wilton and Axminster weaving technologies remain central to premium and designer carpet production in Europe. Computer-controlled Jacquard weaving enables complex pattern reproduction with multiple yarn colors, supporting the luxury residential and hospitality market segments with high design differentiation.
Sustainable Fiber Processing
Closed-loop nylon recycling systems, recycled PET extrusion processes, and bio-based fiber development are advancing sustainability credentials across European carpet manufacturing. Manufacturers are investing in technology partnerships to achieve verified recycled content and reduce production carbon intensity in response to Europe carpet market regulatory & industry shifts, including evolving EU sustainability mandates, Ecolabel certification requirements, and indoor air quality standards shaping procurement across commercial and institutional channels.
Digital Printing and Customization
Large-format digital printing on carpet substrates and software-driven digital tufting are enabling rapid prototyping and small-batch production of customized designs. These technologies reduce sampling lead times and minimum order quantities, supporting boutique commercial projects and bespoke residential specifications across Europe.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Material | Nylon | 36.7% | 2025 |
| Price Point | Economy | 61.3% | 2025 |
| Sales Channel | 🔒 | 🔒 | 2025 |
| End User | 🔒 | 🔒 | 2025 |
| Country | Germany | 25.8% | 2025 |

By Material
Nylon commands 36.7% of the Europe carpet market in 2025, reflecting its superior durability, abrasion resistance, and stain performance across high-traffic residential and commercial environments. Its capacity to retain fiber appearance under sustained footfall makes it the preferred specification in hospitality, office, and retail carpet applications across the region.
To access detailed market analysis, Request Sample
Olefin represents 25.4% market share in 2025, driven by its moisture resistance, UV stability, and cost-effective production profile. It is widely specified in outdoor carpeting, contract applications, and secondary residential spaces where budget efficiency is prioritized.
By Price Point
Economy leads the price point segment at 61.3% in 2025, supported by broad residential demand, institutional procurement, and the large replacement market across Europe's mature housing stock. Functional performance at accessible price points drives consistent volume in this segment throughout the region.
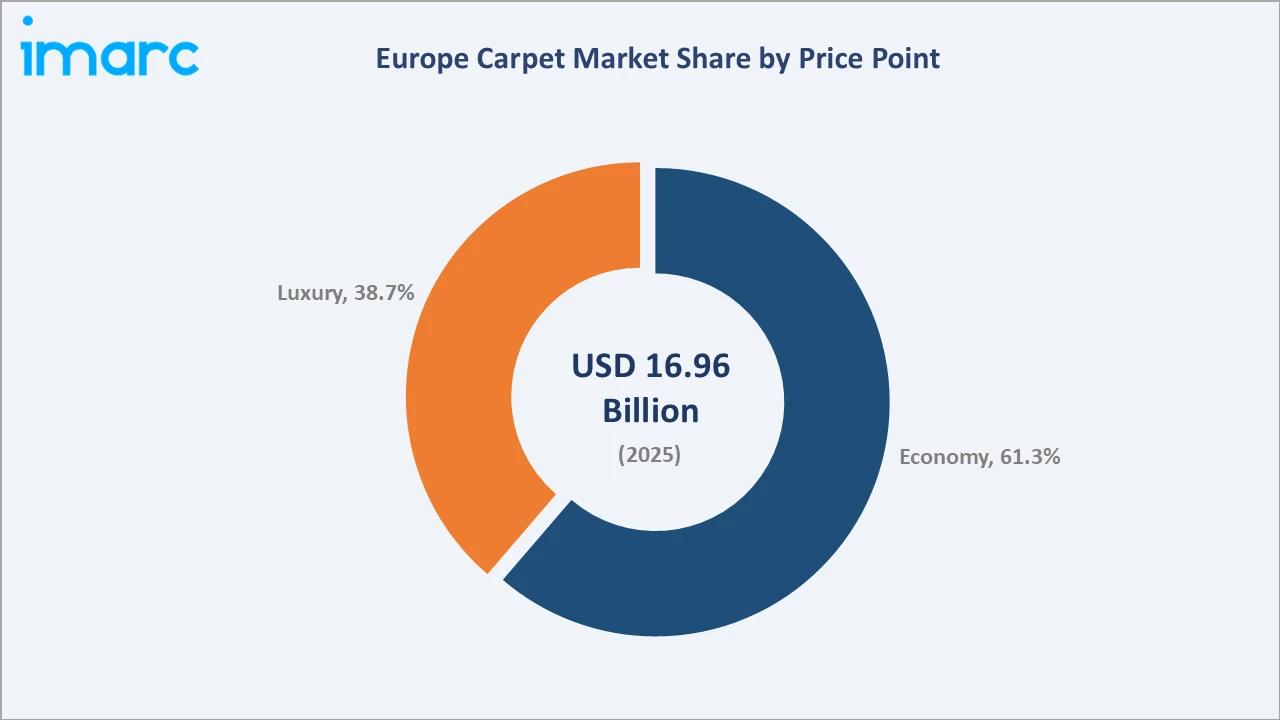
Luxury holds 38.7% share in 2025, supported by growing investment in premium residential interiors, expanding boutique hospitality, and increasing demand for natural fiber and designer carpet products in high-value renovation and fit-out projects.
Regional Market Insights
| Country | Share (2025) | Key Growth Drivers |
|---|---|---|
| Germany | 25.8% | Strong construction and renovation activity, large carpet manufacturing base, high residential improvement spending, and well-developed contractor distribution channel |
| France | 17.6% | Active residential renovation market, growing hospitality sector, expanding interior design industry, and increasing commercial fit-out activity |
| United Kingdom | 16.9% | Deep cultural preference for carpeted interiors, active renovation market, strong residential demand, and broad retail distribution infrastructure |
| Italy | 13.4% | Growing premium and luxury interior market, design-led manufacturing sector, expanding hospitality industry, and increasing commercial specification activity |
| Spain | 9.8% | Growing construction activity, rising tourism and hospitality infrastructure investment, and expanding residential renovation spending |
| Others | 16.5% | Emerging demand in Eastern European markets, growing renovation activity in Benelux and Scandinavian regions, and rising household income supporting interior investment |
Germany at 25.8% in 2025 leads the market, supported by a large construction sector, strong residential renovation market, and the presence of major carpet manufacturing and distribution infrastructure. High household spending on interior improvement and a well-developed contractor channel support consistent demand across residential and commercial segments.
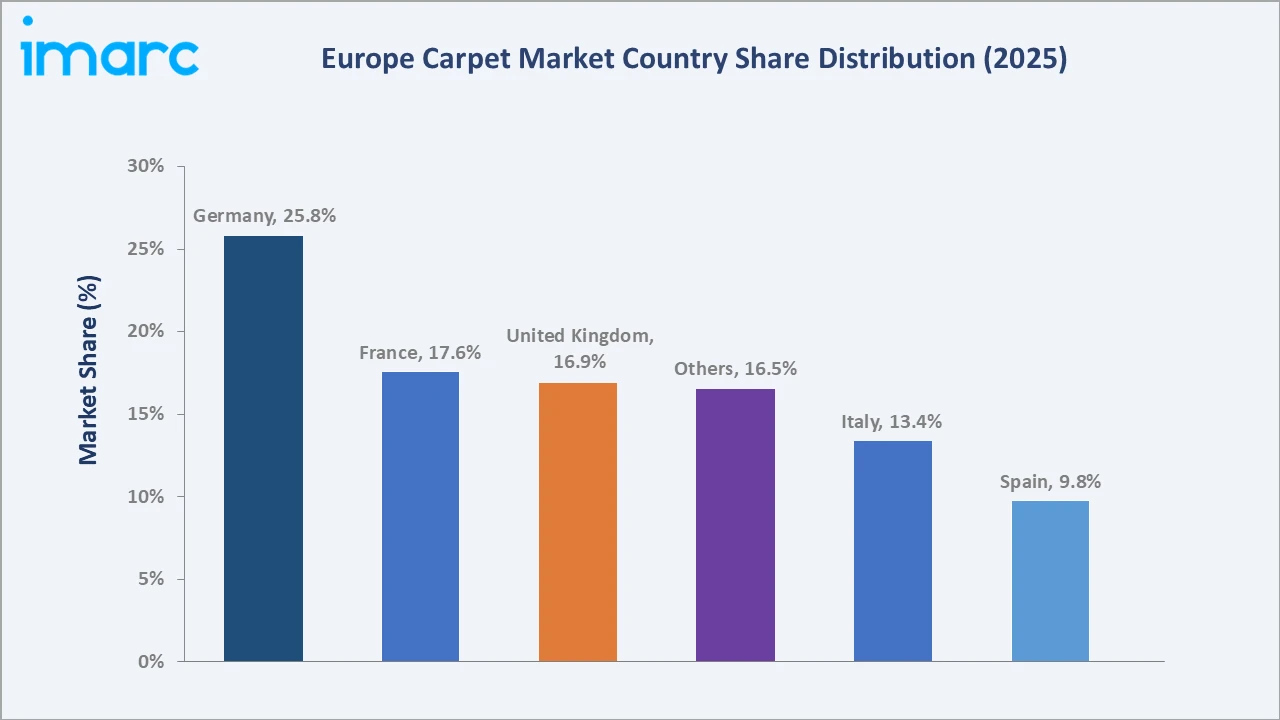
Spain, at 9.8%, is expanding as growing tourism investment drives hospitality sector carpet procurement across the country.
Competitive Landscape
The Europe carpet market is moderately consolidated, with a mix of pan-European carpet specialists, vertically integrated manufacturers, and global flooring groups competing across material, format, and price point segments. Product quality, design capability, sustainability credentials, and distribution network breadth form the key competitive differentiators in the region.
| Company Name | Brand / Key Product | Position | Strategic Focus |
|---|---|---|---|
| Belysse Group NV | Modulyss | Leader | Expanding commercial carpet tile range through design innovation and sustainability-led product development across European commercial specification channels |
| Victoria PLC | Victoria Carpets, Balta | Leader | Strengthening UK and European market position through product innovation, sustainability investment, and a broadened brand portfolio |
| Interface, Inc. | Interface Carpet Tiles | Challenger | Expanding modular carpet tile range in European commercial markets through sustainability differentiation and closed-loop product offerings |
Key players include Belysse Group NV, Victoria PLC, and Interface, Inc., among others.
Key Company Profiles
Belysse Group NV
Belysse Group NV is a Belgium-based manufacturer of commercial carpet tiles and flooring solutions. The firm operates through its Modulyss brand and other commercial-focused labels targeting architects, interior designers, and specification channels across Europe.
- Product Portfolio: Commercial carpet tiles and broadloom carpet for office, hospitality, retail, and institutional applications under the Modulyss brand.
- Recent Developments: The company continues to invest in sustainable fiber development and design innovation under the Modulyss brand, addressing growing commercial market demand for eco-certified carpet tile solutions across Europe.
- Strategic Focus: Strengthening commercial carpet tile position through the Modulyss brand via sustainability-led product development and expanding specification channel reach across European professional and commercial markets.
Victoria PLC
Victoria PLC is a United Kingdom-listed manufacturer and distributor of floor coverings, including carpets, rugs, and hard flooring products. The company operates through a portfolio of manufacturing facilities and brands across the United Kingdom and Europe.
- Product Portfolio: Residential and commercial carpets, rugs, underlay, and hard flooring products under multiple brands including Victoria Carpets and Balta, distributed through retail, commercial, and direct-to-trade channels across Europe.
- Recent Developments: Victoria PLC continues to focus on optimizing manufacturing operations, strengthening distribution networks, and enhancing product offerings to address evolving customer preferences and demand across residential and commercial flooring markets.
- Strategic Focus: Growing United Kingdom and European flooring market position through its broadened brand portfolio, including the addition of the Balta brand, and continued investment in sustainable manufacturing capability.
Interface, Inc.
Interface, Inc. is a United States-based modular carpet tile manufacturer with significant European operations. Headquartered in Atlanta, Georgia, United States, the company operates European manufacturing facilities, marketing products across the region through a specialist commercial channel.
- Product Portfolio: Modular carpet tiles for commercial interior applications, targeting office, hospitality, retail, and education segments through a sustainability-differentiated product range.
- Recent Developments: The company continues to advance circular flooring solutions and sustainable product innovation, strengthening its commercial flooring portfolio for environmentally conscious building and renovation projects.
- Strategic Focus: Expanding European commercial carpet tile market share through closed-loop product offerings, sustainability certification, and design innovation for high-specification commercial fit-out projects.
Market Concentration Analysis
The Europe carpet market is moderately concentrated, with leading European manufacturers, including Belysse Group NV and Victoria PLC, accounting for a significant share of regional production volume. However, the market remains fragmented at the retail and distribution level, with numerous regional manufacturers, importers, and specialty producers serving distinct national markets and customer segments.
Barriers to entry include significant capital investment in tufting and weaving machinery, established customer relationships with retailers and commercial specifiers, the cost of sustainability certification for regulated commercial channels, and the need for broad design ranges to serve diverse European interior preferences. These factors favor established manufacturers with scale, distribution assets, and product development investment.
Consolidation is progressing at a measured pace, with acquisitions by larger flooring groups gradually reducing the number of independent mid-size manufacturers. Sustainability requirements and digital manufacturing investment are further raising barriers, supporting ongoing consolidation toward larger, better-capitalized operators across the region.
Investment & Growth Opportunities
Fastest-Growing Segments
Luxury is the fastest-growing price point segment, driven by rising consumer spending on premium interiors, expanding boutique hospitality, and growing demand for natural fiber and designer products.
Emerging Markets
Spain represents the fastest-growing region, supported by rising residential renovation activity, expanding hospitality infrastructure, and increasing demand for premium flooring solutions.
Venture & Investment Trends
Investment activity is concentrated in sustainable fiber technology, closed-loop recycling infrastructure for end-of-life carpets, digital design and customization capability, and modular carpet tile formats for commercial applications. Strategic capital is also flowing into specialty carpet manufacturers and distributors with strong sustainability positioning and commercial specification relationships.
Future Market Outlook (2026-2034)
The Europe carpet market is projected to grow from USD 16.96 Billion in 2025 to USD 17.64 Billion in 2026, reaching USD 22.57 Billion by 2034, registering a CAGR of 3.13% during 2026-2034.
Four forces will shape the market through 2034 sustained residential renovation and replacement demand across mature Western European housing markets; continued commercial real estate development driving specification-grade carpet procurement; accelerating sustainability requirements reshaping product development and material sourcing strategies; and growing premiumization in residential and hospitality interiors supporting luxury segment expansion.
By 2034, the Europe carpet market is expected to feature a higher proportion of sustainable and certified product offerings, increasing penetration of modular carpet tile formats in commercial applications, and consolidation among mid-size manufacturers around scale, design capability, and sustainability credentials.
Research Methodology
Primary Research
Primary research included structured discussions with carpet manufacturers, distributors, commercial specifiers, interior designers, and industry associations across Europe, validating market sizing, segment mix, and regional demand patterns for the Europe carpet market.
Secondary Research
Secondary sources included European Flooring Manufacturers' Association publications, Eurostat construction and renovation expenditure data, national trade association reports from Germany, France, and the United Kingdom, and public disclosures from listed flooring manufacturers and retailers operating across Europe.
Forecasting Models
Market forecasts used top-down and bottom-up models combining construction activity data, renovation expenditure trends, carpet penetration rates, and historical consumption patterns. Scenario analysis addressed construction cycle volatility, sustainability regulation implementation timelines, and competitive dynamics between carpet and hard surface flooring alternatives.
Europe Carpet Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Materials Covered | Nylon, Olefin, Polyester, Others |
| Price Points Covered | Economy, Luxury |
| Sales Channels Covered | Supermarkets and Hypermarkets, Specialty Stores, Online Stores |
| End Users Covered | Residential, Commercial |
| Countries Covered | Germany, France, United Kingdom, Italy, Spain, Others |
| Companies Covered | Belysse Group NV, Victoria PLC, Interface, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Europe carpet market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Europe carpet market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Europe carpet industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Europe Carpet Market Report
The Europe carpet market size is estimated at USD 17.64 Billion in 2026, driven by residential renovation activity, commercial real estate expansion, and rising consumer preference for comfort-focused interior solutions across the region.
The market is projected to grow at a CAGR of 3.13% from 2026-2034, reaching USD 22.57 Billion by 2034, supported by renovation demand, hospitality sector expansion, and growing premium carpet adoption.
Nylon dominates with 36.7% material share in 2025, favored for its durability, stain resistance, and performance across high-traffic residential and commercial applications.
Economy leads the price point segment at 61.3% in 2025, driven by broad residential demand and institutional procurement across Europe's diverse housing and commercial markets.
Germany leads with 25.8% share in 2025, anchored by its large construction and renovation sector, strong household improvement spending, and concentration of carpet manufacturing infrastructure.
Key players include Belysse Group NV, Victoria PLC, and Interface, Inc., among others.
Key drivers include sustained residential renovation activity, commercial real estate development, growing hospitality sector demand, and rising consumer preference for premium and sustainable carpet products.
Key trends include adoption of recycled fiber carpets, growth of modular carpet tile formats, premiumization in residential and hospitality segments, and digital customization technology across the region.
Key challenges include competition from hard flooring alternatives, raw material price volatility, environmental concerns over synthetic fiber disposal, and competitive pressure from low-cost imports.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade