
Europe Ceiling Fan Market Size, Share, Trends and Forecast by Product Type, Fan Size, Distribution Channel, End Use, and Country, 2026-2034
Europe Ceiling Fan Market Size, Share, Trends & Forecast (2026-2034)
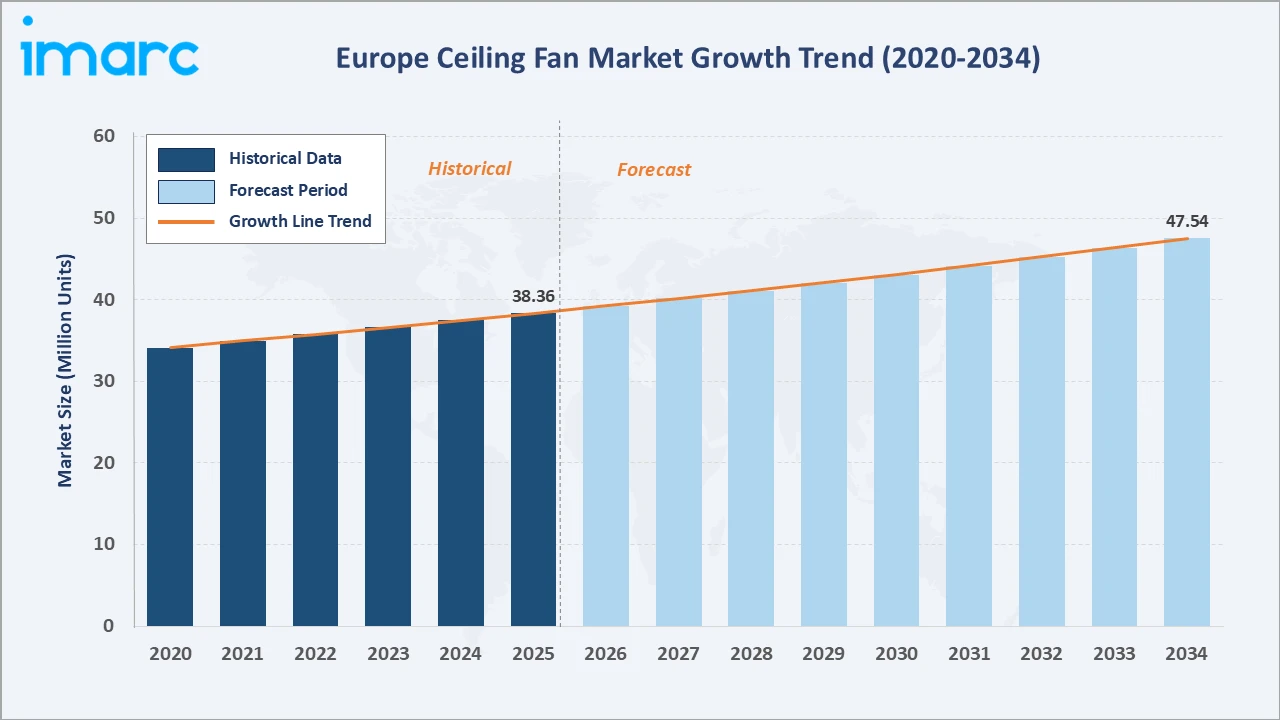
The Europe ceiling fan market grew from 38.36 Million Units in 2025 to 39.26 Million Units in 2026 and will reach 47.54 Million Units by 2034, at a CAGR of 2.34% during 2026-2034. Energy use for cooling in EU households doubled in six years to 80.4 thousand terajoules in 2024.
Hotter summers, energy-efficient DC motors, and smart home integration are reshaping the Europe ceiling fan industry. Standard fans dominate product types at 40.0%. Medium fans lead fan sizes at 45.0%. Germany commands 25.0% of regional market share, supported by large housing stock and strong retail networks.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
38.36 Million Units |
|
Market Size (2026) |
39.26 Million Units |
|
Forecast Market Size (2034) |
47.54 Million Units |
|
CAGR (2026-2034) |
2.34% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product Type |
Standard Fan (40.0%, 2025) |
|
Dominant Fan Size |
Medium (45.0%, 2025) |
|
Leading Country |
Germany (25.0%, 2025) |
The Europe ceiling fan market size increased from 34.17 Million Units in 2020 to 38.36 Million Units in 2025 and is estimated to reach 39.26 Million Units in 2026. It is expected to reach 43.06 Million Units by 2030 and 47.54 Million Units by 2034.
To get more information on this market, Request Sample
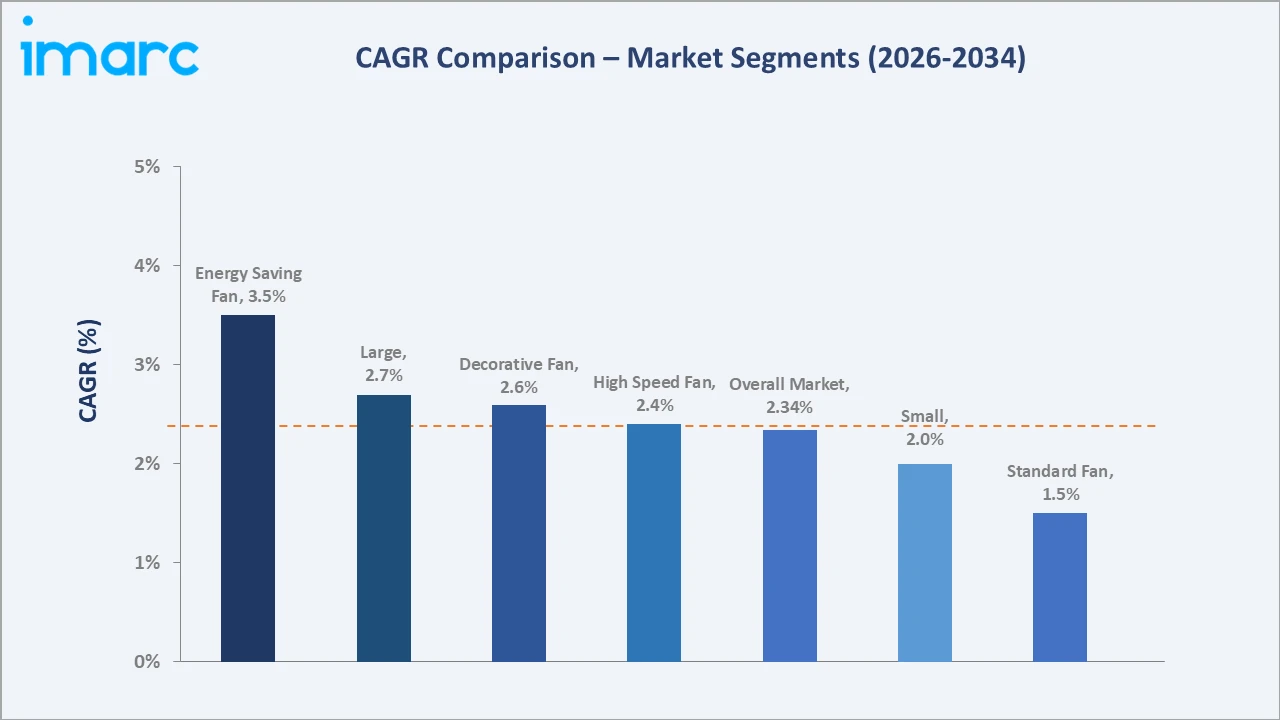
Energy saving fans are expected to grow fastest at ~3.5% CAGR, supported by DC motor technology, lower power consumption, and rising electricity costs. Large fans follow at ~2.7% CAGR as open-plan living spaces, hotels, and commercial buildings adopt high-airflow models for efficient cooling.
Executive Summary
The Europe ceiling fan market expanded from 38.36 Million Units in 2025 to 39.26 Million Units in 2026 and is projected to reach 47.54 Million Units by 2034. Manufacturers are launching DC motor, smart, and designer fans. Standard fans lead at 40.0%, medium fans at 45.0%, and Germany at 25.0%.
Established brands continue to lead premium and specialized segments, while private-label and online sellers compete strongly in standard fans. Rising interest in energy saving models, outdoor fans, and HVLS solutions for commercial spaces signals a shift toward higher-value products across the European market.
Key Market Insights
|
Insight |
Data |
|
Dominant Product Type |
Standard Fan - 40.0% share (2025) |
|
Dominant Fan Size |
Medium - 45.0% market share (2025) |
|
Leading Country |
Germany - 25.0% share (2025) |
|
Market Opportunity |
DC motor energy saving fans; smart and connected fans; outdoor and hospitality installations; HVLS fans for commercial spaces; designer fans |
Key Analytical Observations Supporting the Above Data:
- Standard Fan at 40.0%: Standard fans dominate because they offer reliable airflow at affordable prices, are widely available through DIY stores and online channels, and suit bedrooms, living rooms, and small offices across most European households.
- Medium at 45.0%: Medium-sized fans lead because they fit typical European room sizes, such as bedrooms and living areas of 10 to 25 square meters, offering a good balance of airflow, noise levels, energy use, and price.
- Germany at 25.0%: Germany leads due to its large population and housing stock, strong DIY and electrical retail networks, growing summer heat, and a well-established presence of ceiling fan brands and distributors serving residential and commercial customers.
Europe Ceiling Fan Market Overview
Ceiling fans are mounted on ceilings to circulate air, improving comfort in summer and helping distribute warm air in winter when run in reverse. They are used in homes, offices, hotels, restaurants, shops, gyms, warehouses, and outdoor terraces across Europe.
Ceiling fans are available with AC or DC motors, with or without integrated lighting, and in a wide range of blade sizes, materials, and finishes. Products range from basic models sold in DIY stores to premium designer fans and industrial HVLS fans.
The Europe ceiling fan industry links motor and component suppliers, fan manufacturers, importers, distributors, DIY retailers, online marketplaces, electricians, and end users. Summer temperatures, electricity prices, housing renovation, interior design trends, and EU product rules shape demand across countries and seasons.
Ceiling fans also support European energy efficiency goals by offering low-energy cooling and helping distribute heat in winter. EU product rules on energy efficiency, electrical safety, and waste electronics influence product design, labeling, and recycling requirements across the region.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
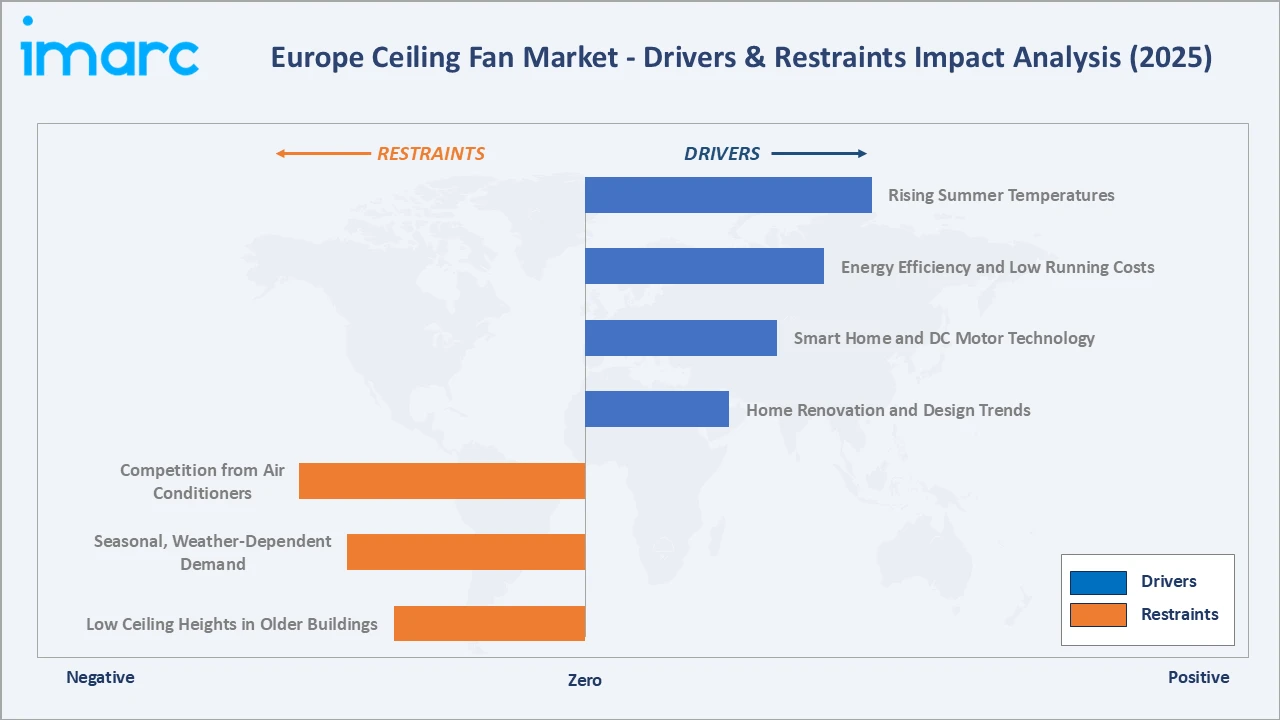
- Rising Summer Temperatures: More frequent and intense heatwaves across Europe are increasing demand for affordable cooling solutions. Many homes lack air conditioning, and ceiling fans provide immediate comfort at low cost, making them a popular choice for bedrooms, living rooms, and home offices.
- Heatwaves in recent summers have caused sharp spikes in demand for cooling products, with retailers in several countries reporting shortages of fans. As climate projections point to more extreme heat, households are increasingly planning cooling purchases before summer begins.
- Energy Efficiency and Low Running Costs: Ceiling fans consume far less electricity than air conditioners, helping households manage high energy bills. Modern DC motor fans use even less power, and running fans in reverse during winter helps distribute heat and reduce heating costs.
- Rising electricity prices across Europe have made running costs a key purchase factor. Ceiling fans allow users to set air conditioning thermostats higher or avoid air conditioning altogether, delivering meaningful energy savings during long summer periods.
- Smart Home and DC Motor Technology: Wi-Fi connected fans, app and voice control, and integration with smart home platforms are attracting tech-savvy buyers. DC motors deliver quieter operation, more speed settings, and better efficiency, encouraging upgrades from older AC motor fans.
- Matter-compatible fans and integration with popular voice assistants allow fans to work with lighting, thermostats, and sensors. Automated schedules and temperature-based control improve comfort while reducing energy use, appealing to younger homeowners and renters.
- Home Renovation and Design Trends: Home improvement spending and interest in stylish interiors are supporting demand for decorative ceiling fans with wooden blades, integrated LED lights, and minimalist designs. Fans are increasingly viewed as design features as well as cooling appliances.
- Interior designers and architects are increasingly specifying ceiling fans in residential and hospitality projects. Wide choices of finishes, blade materials, and lighting options allow fans to complement different interior styles, from Scandinavian minimalism to Mediterranean designs.
Market Restraints
- Competition from Air Conditioners: Falling prices of portable and split air conditioners, along with reversible heat pumps, are attracting consumers seeking stronger cooling. In hotter southern European regions, air conditioning adoption is rising quickly, limiting growth for ceiling fans in some segments.
- Ceiling fan brands are responding by highlighting the lower purchase and running costs of fans and promoting combined use with air conditioners. Using fans alongside air conditioning allows higher thermostat settings, reducing electricity consumption while maintaining comfort.
- Seasonal, Weather-Dependent Demand: Ceiling fan sales are concentrated in late spring and summer and depend heavily on weather conditions. Cooler summers can sharply reduce sales, creating inventory risks for retailers and manufacturers and making demand planning difficult across European markets.
- Retailers and brands are using flexible supply chains, online sales, and pre-season promotions to manage seasonal swings. Promoting year-round benefits such as winter heat distribution also helps smooth demand and reduce dependence on summer weather.
- Low Ceiling Heights in Older Buildings: Many older European apartments have low ceilings or protected structures that limit ceiling fan installation. Installation costs, wiring requirements, and building regulations can discourage buyers, especially renters who cannot easily modify their homes.
- Low-profile and flush-mount fan designs, along with smaller blade spans, are helping address these constraints. Clear installation guidance and partnerships with electricians can also reduce barriers for homeowners and landlords considering ceiling fan installation.
Market Opportunities
- Commercial and HVLS Applications: Warehouses, factories, gyms, airports, and retail spaces are adopting high-volume, low-speed ceiling fans to improve comfort and reduce heating and cooling costs. These large fans offer manufacturers higher-value sales and long-term service opportunities.
- HVLS fans can cover large areas with a small number of units, offering significant energy savings compared with conventional cooling systems. Growing logistics, e-commerce warehousing, and sports facilities across Europe are expanding the market for commercial ceiling fans.
- Outdoor and Hospitality Spaces: Hotels, restaurants, cafés, and homeowners are investing in terraces, patios, and outdoor living areas. Damp- and wet-rated ceiling fans designed for outdoor use create opportunities for premium products in Mediterranean and tourist destinations.
- Outdoor fans with corrosion-resistant finishes and sealed motors can withstand humidity and coastal conditions. Hospitality operators value fans that improve guest comfort on terraces, extending outdoor dining seasons and supporting higher revenues during warm months.
Market Challenges
- Low Consumer Awareness in Northern Europe: In cooler northern and central European countries, ceiling fans are still less common, and many consumers are unaware of their year-round benefits. Manufacturers must invest in education and marketing to expand adoption beyond traditional markets.
- Retailer displays, online content, and installer recommendations can help consumers understand the comfort and energy benefits of ceiling fans. Highlighting winter heat distribution and quiet operation is particularly important in cooler European markets.
- Price Competition from Low-Cost Imports: Low-priced fans sold through online marketplaces create strong price pressure on established brands. Differences in quality, safety, and energy performance can confuse buyers, making it harder for premium manufacturers to justify higher prices.
- Established brands are differentiating through warranties, certified energy performance, safety compliance, and after-sales service. Clear product labeling and enforcement of EU safety rules can also help consumers compare products more effectively.
Emerging Market Trends
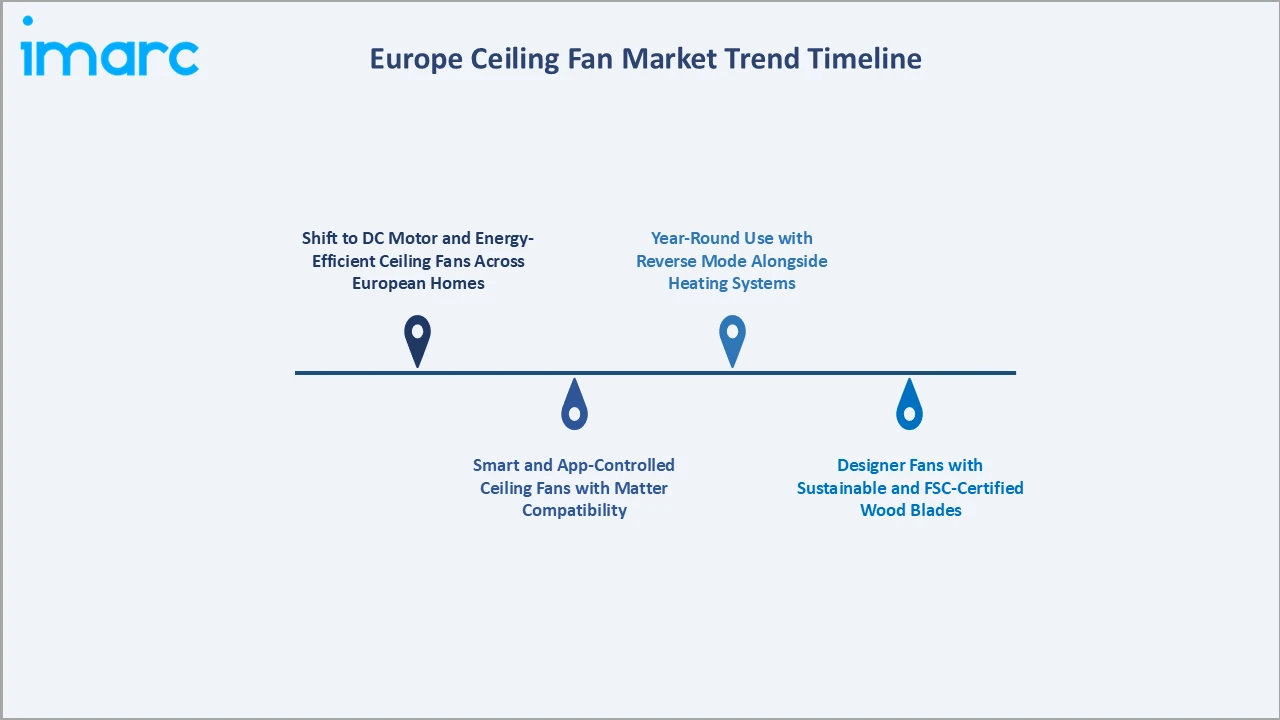
1. Shift to DC Motor and Energy-Efficient Fans
Manufacturers are replacing AC motors with DC motors that use significantly less electricity, run more quietly, and offer more speed settings. Europe ceiling fan market regional breakdown shows strong adoption in Spain, Italy, and France, where long summers make running costs important.
DC motor fans also enable features such as reverse mode, multiple speed settings, and smart control, making them attractive for both new purchases and replacement of older fans.
2. Smart and App-Controlled Ceiling Fans
Connected ceiling fans with app control, voice assistants, timers, and Matter compatibility are gaining popularity. These features allow users to automate comfort settings, combine fans with smart lighting, and monitor energy use, appealing to younger and tech-savvy buyers.
Integration with home energy management systems allows fans to work with heat pumps and solar panels, improving overall household energy efficiency.
3. Designer and Sustainable Materials
Brands are introducing fans with natural and FSC-certified wood blades, recycled materials, and minimalist designs that match modern interiors. Sustainability credentials and design appeal are becoming important purchase factors in the residential ceiling fan market Europe.
Designer collaborations and limited collections are helping brands attract buyers who view fans as statement pieces in modern homes.
4. Year-Round Use with Heating Systems
Consumers and installers are increasingly using ceiling fans in reverse mode during winter to push warm air down from ceilings. Combined with heat pumps and underfloor heating, fans can improve comfort and reduce heating energy use in homes and commercial spaces.
Installers are increasingly recommending ceiling fans as part of energy-efficient renovation packages, supporting demand beyond the summer season.
Industry Value Chain Analysis
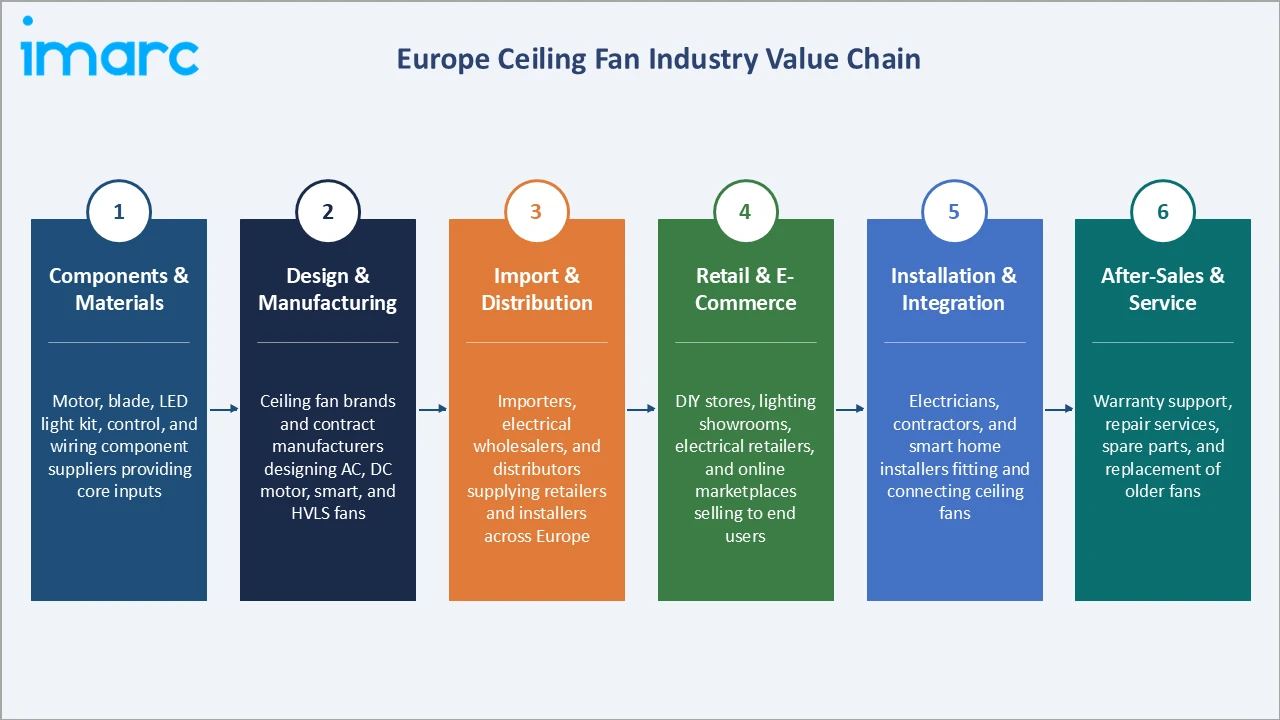
The Europe ceiling fan value chain spans components and materials, design and manufacturing, import and distribution, retail and e-commerce, installation and integration, and after-sales and service. Value is concentrated in design, motor technology, brand strength, and distribution reach, which shape pricing and customer loyalty.
|
Stage |
Key Participants |
|
Components & Materials |
Motor, blade, LED, and control component suppliers |
|
Design & Manufacturing |
Ceiling fan brands and contract manufacturers |
|
Import & Distribution |
Importers, electrical wholesalers, and distributors |
|
Retail & E-Commerce |
DIY stores, lighting shops, and online marketplaces |
|
Installation & Integration |
Electricians and smart home installers |
|
After-Sales & Service |
Warranty, repair, and spare parts providers |
Design and manufacturing is the most consequential stage, as motor efficiency, noise levels, and design quality determine product appeal and pricing. Retail and e-commerce also matter greatly because visibility in DIY stores and online marketplaces drives brand awareness and sales during short peak seasons.
Installation and after-sales service are also gaining importance, as smart fans and DC motor models require correct wiring, setup, and app pairing. Brands that offer long motor warranties and reliable spare parts build stronger trust with consumers and installers.
Technology Landscape in the Europe Ceiling Fan Industry
DC Motors and Aerodynamic Blade Design
Brushless DC motors deliver high efficiency, quiet operation, and precise speed control, while aerodynamic blade designs improve airflow per watt. Together, these technologies allow manufacturers to offer energy saving fans that meet consumer expectations for low running costs and comfort.
Improved motor efficiency also supports compliance with EU energy efficiency requirements and helps brands highlight lower running costs.
Smart Controls and Connectivity
Wi-Fi and Bluetooth modules, remote controls, wall controls, and smart home integration allow users to adjust fan speed, lighting, and schedules from phones or voice assistants. Sensors can also adjust airflow automatically based on room temperature and occupancy.
Smart features are becoming standard in mid-range and premium fans, increasing average selling prices and supporting brand differentiation.
Integrated LED Lighting and Durable Materials
Integrated LED light kits with adjustable color temperatures combine lighting and ventilation in a single fixture. Damp- and wet-rated finishes, marine-grade materials, and sustainable woods extend product life and support installation in outdoor, coastal, and humid environments.
These features expand the range of applications for ceiling fans and support premium pricing in residential and hospitality markets.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Product Type | Standard Fan | 40.0% | 2025 |
| Fan Size | Medium | 45.0% | 2025 |
| Distribution Channel | Offline | 🔒 | 2025 |
| End Use | Residential | 🔒 | 2025 |
| Country | Germany | 25.0% | 2025 |

By Product Type
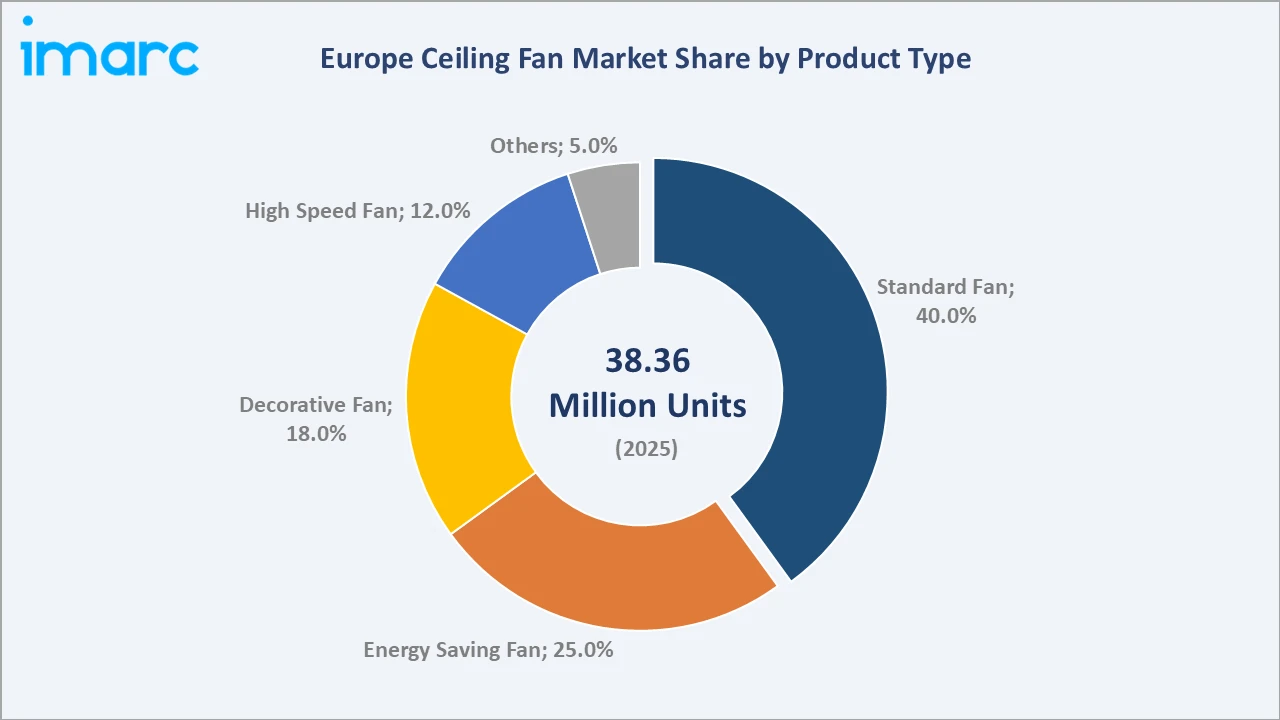
Standard fans lead at 40.0% (2025). Affordable prices, reliable performance, and wide availability in DIY stores and online channels support their leadership. They remain the most common choice for bedrooms, living rooms, and small commercial spaces across European countries.
To access detailed market analysis, Request Sample
Standard fans are often the first ceiling fan purchase for households, offering simple pull-chain, wall, or remote control at accessible prices. Retailers stock these models heavily before summer, supporting their strong presence across European markets.
Energy saving fans at 25.0% grow fastest at ~3.5% CAGR. Decorative fans at 18.0% grow at ~2.6%, high speed fans at 12.0% at ~2.4%, and others at 5.0% at ~2.1%, while standard fans grow more slowly at ~1.5% as buyers upgrade.
By Fan Size
Medium fans lead at 45.0% (2025). They suit typical European bedrooms and living rooms, balancing airflow, noise, energy use, and price. Wide product choice across styles and finishes further supports demand for medium-sized ceiling fans in residential settings.
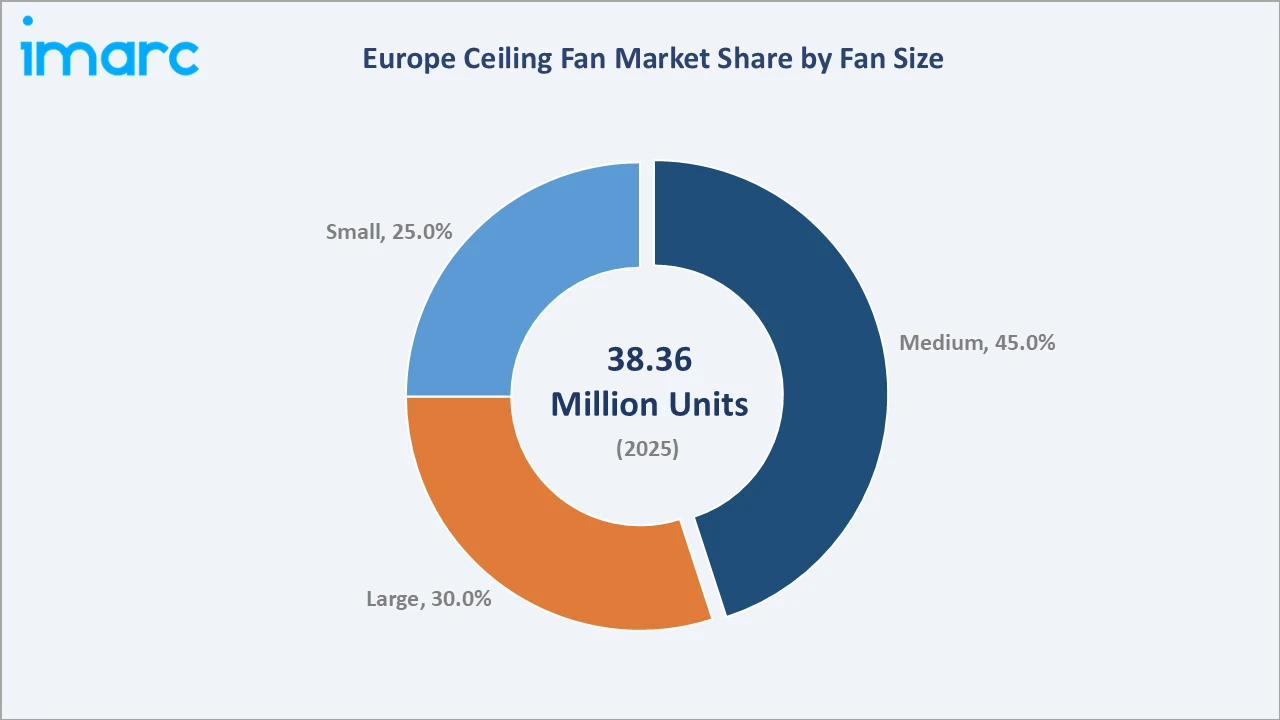
Medium fans also offer the widest range of designs, finishes, and lighting options, making them suitable for both modern and traditional interiors. Their moderate size simplifies installation in apartments and homes with standard ceiling heights.
Large fans at 30.0% grow fastest at ~2.7% CAGR, supported by open-plan homes, hotels, restaurants, and commercial spaces. Small fans at 25.0% grow at ~2.0%, serving compact rooms, apartments, and kitchens, while medium fans grow at ~2.3%.
Regional Market Insights
|
Country |
Share (2025) |
Key Europe Ceiling Fan Market Drivers & Characteristics |
|
Germany |
25.0% |
Large housing stock, strong DIY retail, and rising summer heat. |
|
France |
17.0% |
Heatwaves, home renovation, and growing online sales. |
|
United Kingdom |
16.0% |
Hotter summers and demand for quiet, stylish fans. |
|
Italy |
13.0% |
Long summers, design-led products, and energy savings. |
|
Spain |
10.0% |
Strong cooling demand and established local brands. |
|
Others |
19.0% |
Growing demand in Portugal, Greece, Poland, and Benelux. |
Germany's 25.0% market leadership reflects its large housing stock, strong DIY and electrical retail networks, and increasingly hot summers. France's 17.0% reflects frequent heatwaves, home renovation activity, and growing online sales, while the United Kingdom's 16.0% is supported by rising demand for quiet, stylish cooling.
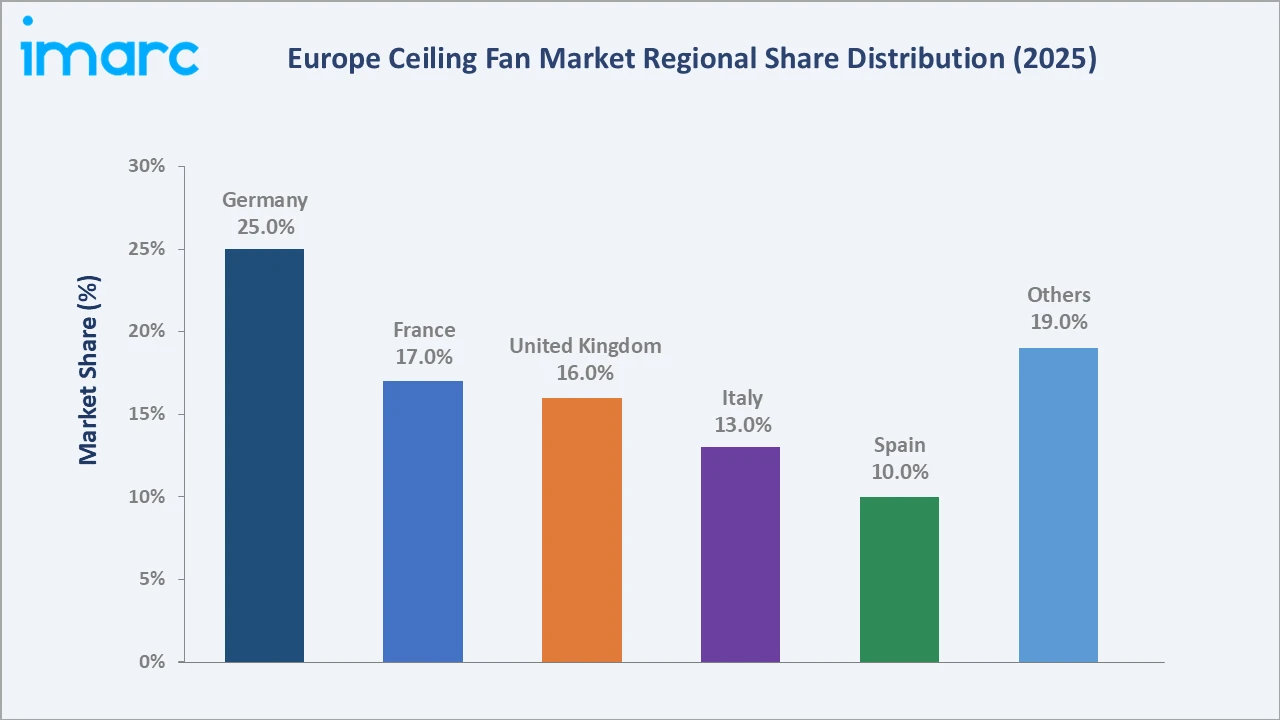
The Europe ceiling fan market regional breakdown shows southern countries growing faster as hotter summers raise cooling needs, while northern and central markets grow steadily through rising awareness, renovation activity, and smart home adoption.
Italy at 13.0% and Spain at 10.0% benefit from long, hot summers and design-led products, with Spain growing fastest at ~2.9% CAGR. Others at 19.0%, including Portugal, Greece, Poland, and Benelux, are expanding with rising temperatures and improving retail availability.
Competitive Landscape
The Europe ceiling fan market includes global ceiling fan brands, European lighting and ventilation specialists, HVLS fan manufacturers, and many private-label suppliers. Competition centers on design, motor efficiency, noise, smart features, price, and retail reach, shaping Europe ceiling fan market share.
Leading brands compete through new collections, smart and DC motor technology, outdoor-rated models, and partnerships with DIY retailers, lighting stores, and online marketplaces. Long warranties, design awards, and after-sales service help brands build loyalty among European consumers.
| Company | Key Brands | Market Position | Core Strength |
|---|---|---|---|
| Hunter Fan Company | Hunter, Casablanca | Market Leader | World's original ceiling fan manufacturer. |
| Faro Barcelona | Faro Barcelona | Market Leader | Designer lighting and DC motor ceiling fans. |
| Delta T, LLC | Haiku, Bison, Mammoth | Strong Challenger | HVLS and premium residential fans. |
| Westinghouse Electric Corporation | Westinghouse | Strong Challenger | Ceiling fans and lighting across Europe. |
| Vortice | Vortice, Nordik, Casals | Strong Challenger | Ventilation and HVLS industrial fans. |
| CasaFan GmbH | Aviatos, Genuino | Innovator | Premium German ceiling fan specialist. |
The most important competitive dynamic is the shift toward DC motor, smart, and designer fans that command higher prices than basic models. Brands are investing in new collections, outdoor-rated products, and online sales channels to differentiate themselves from low-cost imports and private-label products.
Companies are actively expanding showrooms, distributor partnerships, and direct-to-consumer websites. Collaborations with interior designers, architects, and hospitality groups help premium brands secure specifications in new residential, hotel, and commercial projects.
Key Company Profiles
Hunter Fan Company
Hunter Fan Company, founded in 1886, is the world's original ceiling fan manufacturer, offering ceiling fans, lighting, and smart home solutions, and is the number one most installed ceiling fan brand.
- Key Brands: Hunter, Casablanca, HunterSMART.
- Recent Developments: In April 2026, Hunter launched three outdoor cooling products, the DualMount Garage Fan, AirStack, and ZenTech Bladeless, combining high airflow with energy-efficient technology.
- Strategic Focus: Expanding connected comfort through HunterSMART fans and lighting with Matter-enabled control of light and airflow.
Faro Barcelona
Faro Barcelona is a Spanish lighting and ceiling fan designer with over 80 years of experience, offering more than 80 ceiling fan designs with energy-efficient DC motors.
- Key Brands: Faro Barcelona, Faro Lab.
- Recent Developments: In April 2026, Faro Barcelona launched its second US catalogue, expanding its ceiling fan offering with smart controls and FSC-certified wooden blades.
- Strategic Focus: Growing its international presence, with products specified in more than 110 countries and new distribution partnerships in North America.
Delta T, LLC
Delta T, LLC, a Madison Air company, pioneered high-volume, low-speed fans for industrial, commercial, and residential spaces, delivering airflow and energy savings to customers worldwide.
- Key Brands: Haiku, Bison, Mammoth.
- Recent Developments: In May 2026, Delta T, LLC unveiled Bison, a new residential ceiling fan combining powerful airflow with sophisticated design for indoor and outdoor living.
- Strategic Focus: Expanding its residential portfolio by applying industrial HVLS expertise to smart, outdoor-rated home fans such as Mammoth.
Market Concentration Analysis
The Europe ceiling fan market is moderately fragmented, with a few established brands holding strong positions in premium and specialized segments, while many private-label suppliers and online sellers compete in standard and low-priced products.
Spanish and Italian brands hold strong positions in their home markets, supported by local design heritage and established distribution, while global brands compete through technology, smart features, and broad product ranges sold across multiple countries.
Market concentration is relatively higher in HVLS and premium designer fans, where technology, brand strength, and service networks create barriers to entry. Competition remains intense in standard fans sold through DIY stores and online marketplaces, where price is a key purchase factor.
Investment & Growth Opportunities
Highest Growth Segments
Energy saving fans (~3.5% CAGR through DC motor adoption), Spain (~2.9% CAGR through strong cooling demand), large fans (~2.7% CAGR through open-plan and commercial spaces), and decorative fans (~2.6% CAGR through design trends) represent the highest-growth investment areas through 2034.
Emerging Investment Opportunities
Smart DC motor fans, outdoor-rated models, and HVLS fans for commercial and industrial spaces are among the most promising opportunities in the Europe ceiling fan industry. Investment in online sales, installer partnerships, and consumer education in northern Europe also offers attractive returns.
Companies that combine energy efficiency, design appeal, and smart features with strong retail and installer networks are well positioned to capture growth. Expanding into underpenetrated northern European markets also offers long-term opportunities.
Investment Themes
- Energy saving products: DC motor fans meet demand for lower running costs.
- Commercial airflow solutions: HVLS fans serve warehouses, gyms, and retail spaces.
Future Market Outlook (2026-2034)
The Europe ceiling fan market is projected to grow from 38.36 Million Units in 2025 to 39.26 Million Units in 2026, reaching 47.54 Million Units by 2034 at a CAGR of 2.34%. The 2030 value of 43.06 Million Units marks wider adoption of energy saving fans.
Spain and Italy are expected to grow fastest, while Germany, France, and the United Kingdom remain the largest markets.
Three structural forces define Europe ceiling fan industry growth through 2034 rising summer temperatures; demand for energy-efficient cooling; and smart home adoption. Together, these forces support steady growth across product types, fan sizes, and countries, while competition from air conditioners remains a key factor.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry stakeholders, including ceiling fan manufacturers, component suppliers, distributors, retailers, electricians, and industry associations across major European countries.
Secondary Research
Secondary research covered company press releases, annual reports, Eurostat and government data, industry associations, and trade publications. Over 50 credible secondary sources were reviewed, compared, and cross-checked for accuracy and consistency across datasets and countries.
Forecasting Models
Market volume forecasts were developed using a demand-based model: ceiling fan installations by product type, fan size, and country, based on housing stock, replacement cycles, and climate trends, aggregated to total market volume. Assumptions were validated through discussions with industry experts.
Europe Ceiling Fan Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million Units |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | Standard Fan, Decorative Fan, High Speed Fan, Energy Saving Fan, Others |
| Fan Sizes Covered | Small, Medium, Large |
| Distribution Channels Covered | Offline, Online |
| End Uses Covered | Residential, Commercial, Industrial |
| Regions Covered | Germany, France, United Kingdom, Italy, Spain, Others |
| Companies Covered | Hunter Fan Company, Faro Barcelona, Delta T, LLC, Westinghouse Electric Corporation, Vortice, CasaFan GmbH, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Europe Ceiling Fan market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Europe Ceiling Fan market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Europe Ceiling Fan industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Europe Ceiling Fan Market Report
The Europe ceiling fan market size is estimated at 39.26 Million Units in 2026, supported by rising summer temperatures, energy-efficient DC motor fans, and growing smart home adoption across European countries.
The market grows at a 2.34% CAGR during 2026-2034, reaching 47.54 Million Units by 2034, driven by heatwaves, energy savings, and home renovation.
Standard fans lead at 40.0%, owing to affordable prices, reliable performance, and wide availability through DIY stores and online channels.
Medium fans lead at 45.0%, as they suit typical European bedrooms and living rooms while balancing airflow, noise, and energy use.
Germany leads at 25.0%, driven by its large housing stock, strong DIY retail networks, and increasingly hot summers.
Leading companies include Hunter Fan Company, Faro Barcelona, Delta T, LLC, Westinghouse Electric Corporation., Vortice, CasaFan GmbH, among others.
The residential ceiling fan market in Europe is shifting toward quiet DC motor fans, smart controls, integrated LED lighting, and designer finishes that match modern interiors.
The market is projected to reach approximately 43.06 Million Units by 2030, supported by steady growth in energy saving and large fans.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade