
Europe E-Cigarettes Market Size, Share, Trends and Forecast by Product, Flavor, Mode of Operation, Distribution Channel, and Country, 2026-2034
Europe E-Cigarettes Market Size, Share, Trends & Forecast (2026-2034)
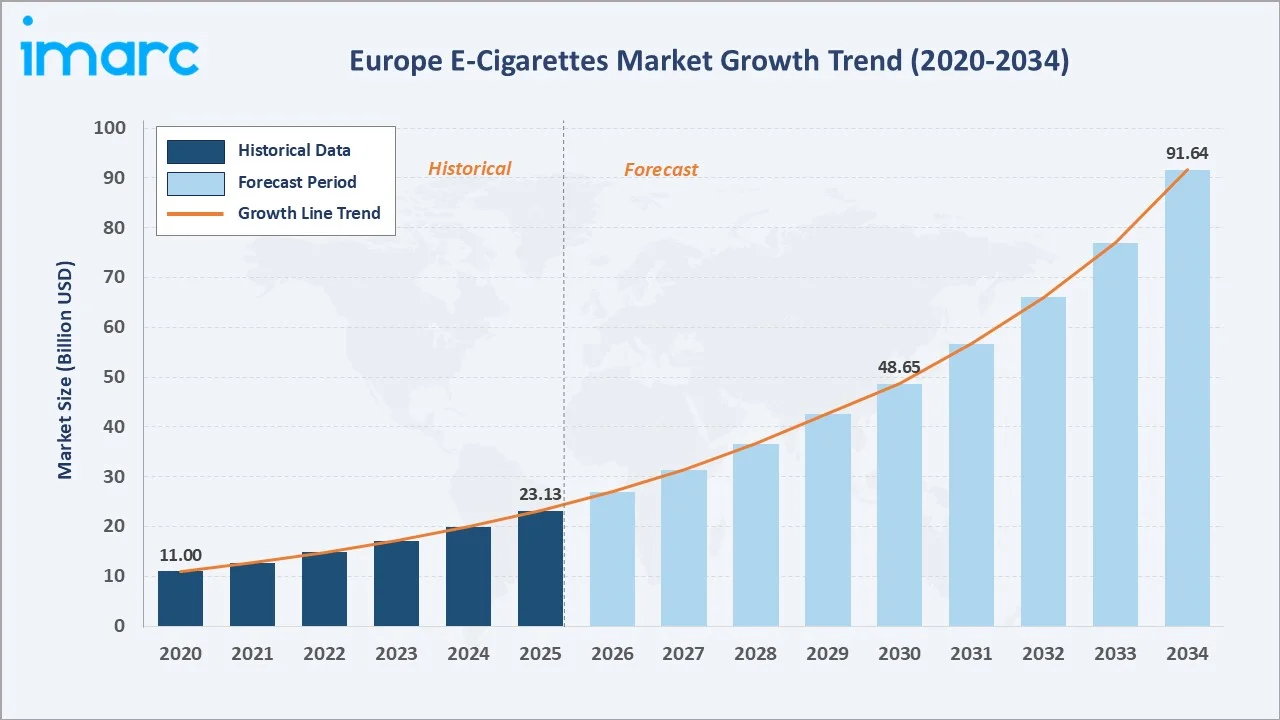
The Europe e-cigarettes market reached USD 23.13 Billion in 2025 and is projected to reach USD 91.64 Billion by 2034, growing at a CAGR of 16.03% during 2026-2034. Europe e-cigarette industry growth is driven by rising tobacco harm reduction awareness, regulatory support for vaping as a cessation tool, and continuous product innovation. Around 44% of European adolescents have experimented with e-cigarettes at least once, while 22% are current users. Moreover, 16% report trying e-cigarettes by the age of 13. This increasing penetration is contributing to the expansion of the Europe e-cigarettes market by broadening product awareness and overall usage rates. Rechargeable e-cigarettes lead the product at 55.8%. Automatic e-cigarettes dominate the mode of operation at 69.8%. The United Kingdom leads regionally at 29.8% (2025).
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 23.13 Billion |
|
Forecast Market Size (2034) |
USD 91.64 Billion |
|
CAGR (2026-2034) |
16.03% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Leading Product |
Rechargeable E-Cigarette (55.8%, 2025) |
|
Leading Mode of Operation |
Automatic E-Cigarette (69.8%, 2025) |
|
Leading Country |
United Kingdom (29.8%, 2025) |
The Europe e-cigarettes market has grown substantially from USD 11.00 Billion in 2020 to USD 23.13 Billion in 2025, driven by the accelerating shift from the traditional Europe cigarette market to next-generation nicotine alternatives. The market is projected to reach USD 48.65 Billion by 2030 and USD 91.64 Billion by 2034.
To get more information on this market, Request Sample
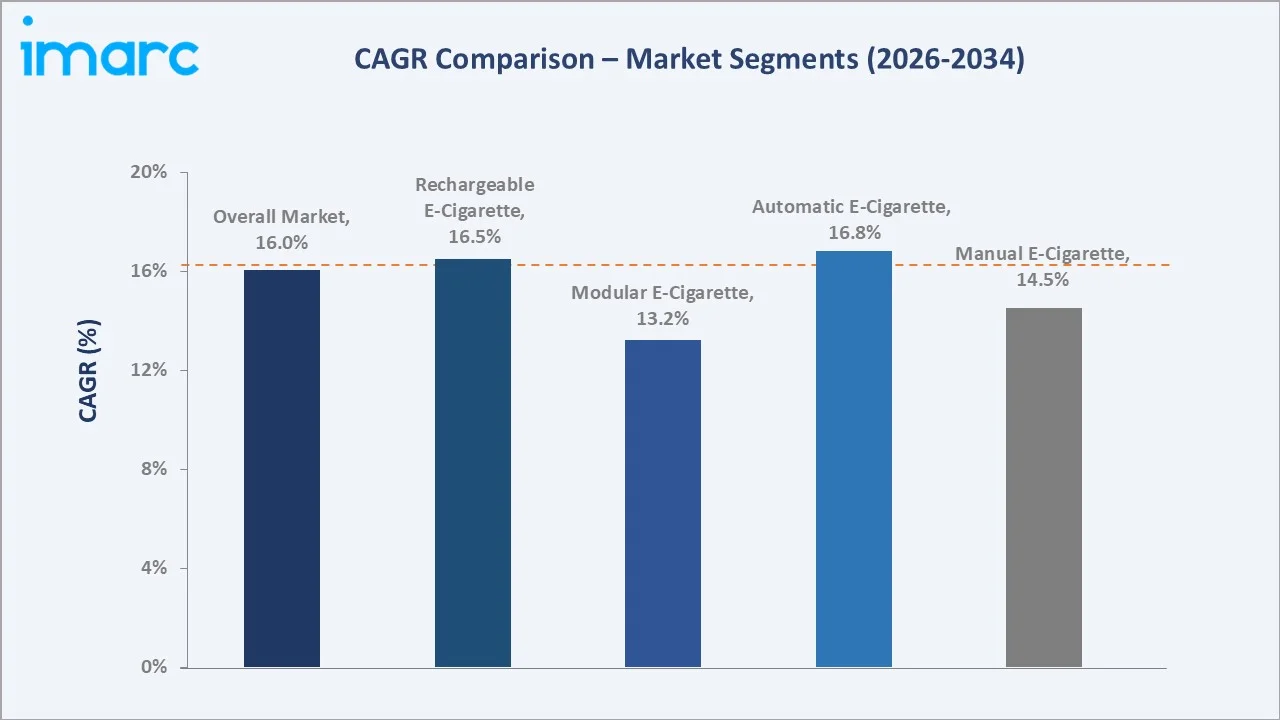
Rechargeable e-cigarettes grow at ~16.5% CAGR through sustained consumer preference for refillable pod systems. Automatic e-cigarettes grow at ~16.8% CAGR through ease-of-use advantages. Modular e-cigarettes grow at ~13.2% CAGR, catering to advanced vapers. The overall 16.03% CAGR reflects the structural transition accelerating from the Europe cigarette market toward regulated vaping products.
Executive Summary
The Europe e-cigarettes market is one of the fastest-growing consumer goods sectors across the continent, driven by deep structural shifts in nicotine consumption behavior. The progressive decline of the traditional Europe tobacco market and Europe cigarette market is directly accelerating the uptake of e-cigarettes as perceived less-harmful alternatives among adult smokers. Rechargeable e-cigarettes lead at 55.8%, automatic e-cigarettes dominate at 69.8%, and the United Kingdom holds the largest country share at 29.8% (2025).
Key Market Insights
|
Insight |
Data |
|
Leading Product Type |
Rechargeable E-Cigarette - 55.8% share (2025) |
|
Leading Mode of Operation |
Automatic E-Cigarette - 69.8% share (2025) |
|
Leading Country |
United Kingdom - 29.8% share (2025) |
|
Market Opportunity |
Nicotine salt pods; heat-not-burn next-gen; emerging EU regulated markets; disposable phase-out alternatives |
Key analytical observations supporting the above data:
- Rechargeable E-Cigarettes at 55.8%: Rechargeable e-cigarettes dominate as they offer the best value-for-money proposition for regular adult vapers; refillable pods, wide flavor selection, and adjustable nicotine strengths align with diverse consumer preferences across the United Kingdom, Germany, and France markets.
- Automatic E-Cigarettes at 69.8%: Automatic (draw-activated) e-cigarettes lead mode of operation share due to superior ease of use, eliminating the manual button press, particularly appealing to adult smokers transitioning from the Europe cigarette market who prefer the most natural inhale-activated vaping experience.
- United Kingdom at 29.8%: The UK leads European e-cigarette adoption due to the most permissive and pro-vaping regulatory environment globally, NHS endorsement for smoking cessation, and the highest smoker-to-vaper conversion rate in Europe. E-cigarette industry growth in Europe is most pronounced in the UK market.
Europe E-Cigarettes Market Overview
The Europe e-cigarettes market encompasses battery-powered nicotine delivery devices that heat liquid nicotine solutions to produce inhalable aerosols without combustion. Product types span rechargeable e-cigarettes (refillable pod systems and tank-based devices), next-generation e-cigarettes (heat-not-burn products using real tobacco sticks), disposable e-cigarettes (single-use pre-filled devices), and modular e-cigarettes (customizable advanced vaping systems). Mode of operation are divided into automatic (draw-activated) and manual (button-activated) devices. The market serves adult smokers transitioning from the Europe cigarette market and Europe tobacco market, recreational vapers, and smoking cessation program participants. Macroeconomic enablers include government harm reduction policies, a growing Europe pure nicotine market through nicotine salts, and continuous product innovation by major tobacco and specialist vape companies.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
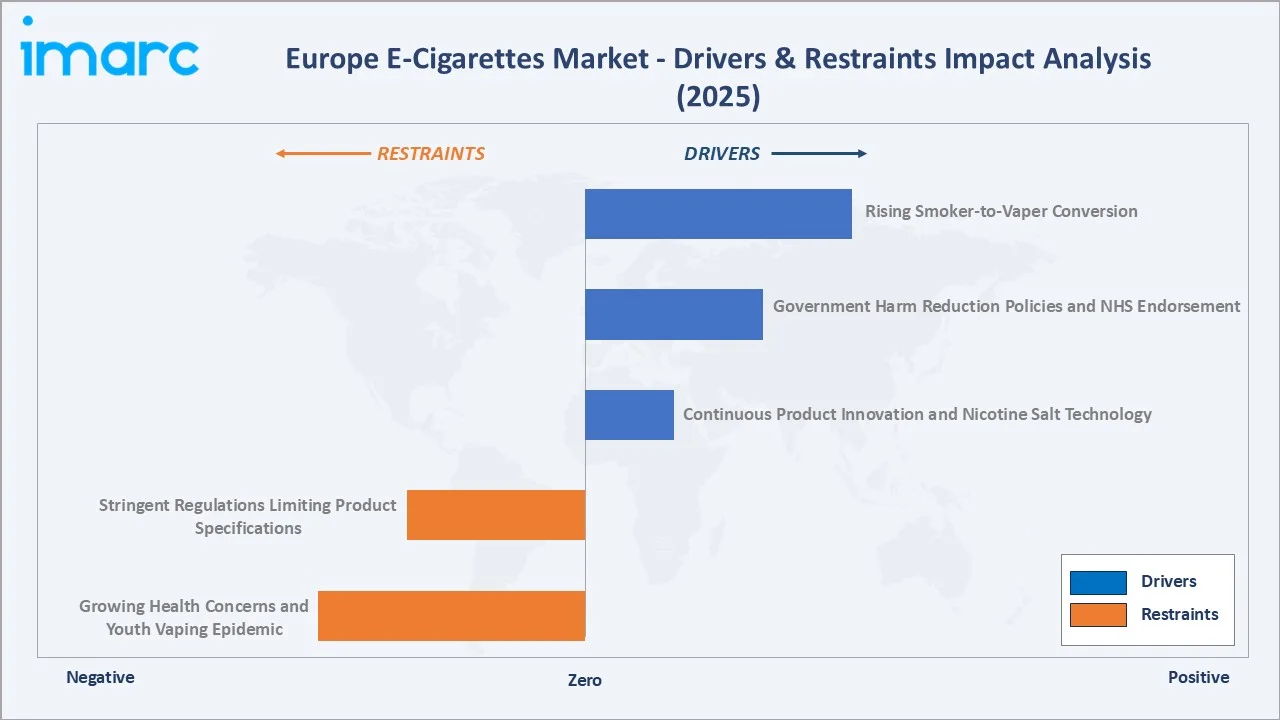
- Rising Smoker-to-Vaper Conversion: The accelerating structural decline of the Europe cigarette market is the primary structural growth driver for e-cigarettes. Tobacco consumption across the European Union is gradually declining; however, it continues to pose a major public health burden. Each year, tobacco use is responsible for more than 500,000 deaths across the EU, including nearly 80,000 deaths linked to exposure to second-hand smoke. As public health authorities actively endorse harm reduction, e-cigarettes are the primary beneficiary of this transition, capturing millions of former combustible cigarette consumers annually.
- Government Harm Reduction Policies and NHS Endorsement: The UK's harm reduction approach, where e-cigarettes are approximately 95% less harmful than combustible cigarettes, provides unprecedented institutional legitimacy. This pro-vaping regulatory posture directly accelerates adoption and reduces consumer hesitancy, particularly among older demographic smokers considering the switch from the Europe tobacco market.
- Continuous Product Innovation and Nicotine Salt Technology: The development of nicotine salt e-liquids, which deliver nicotine more efficiently at lower temperatures, has dramatically improved the vaping experience for former smokers, reducing the behavioral gap between combustible cigarettes and e-cigarettes. This innovation has been central to the growth of the Europe pure nicotine market and the mainstream appeal of rechargeable pod systems, driving e-cigarette industry growth in Europe significantly beyond earlier projections.
Market Restraints
- Stringent Regulations Limiting Product Specifications: Stringent regulations on nicotine strength, e-liquid composition, packaging, labeling, and device specifications are limiting product innovation and reducing the range of e-cigarettes available in Europe. These compliance requirements can also raise development and certification costs, thereby restraining market expansion.
- Growing Health Concerns and Youth Vaping Epidemic: Regulatory scrutiny is intensifying across Europe as youth vaping rates increase, particularly through disposable e-cigarette products. The EU and several member states are implementing or discussing stricter advertising restrictions, flavor bans targeting youth appeal, and minimum age enforcement measures. These regulatory tightening trends increase compliance costs and product reformulation requirements for operators across European markets.
Market Opportunities
- Next-Generation Heat-Not-Burn Product Expansion: Heat-not-burn products represent the fastest-growing product sub-category within the Europe e-cigarettes market. These devices heat real tobacco sticks rather than e-liquid, delivering a combustible tobacco experience with significantly reduced harmful emissions. As adult tobacco consumers in the European tobacco market seek the most authentic combustible alternative, heat-not-burn products offer exceptional growth potential, particularly in Italy, Germany, and Eastern European markets.
- Sustainable and Bio-Nicotine Product Development: The growing Europe pure nicotine market is creating opportunities for bio-derived synthetic nicotine products that bypass traditional tobacco supply chains. Synthetic nicotine e-liquids offer regulatory advantages in some jurisdictions and appeal to health-conscious vapers. Companies investing in sustainable nicotine extraction and tobacco-free nicotine alternatives will be well-positioned to capture premium market segments as consumer awareness of nicotine source transparency grows.
Market Challenges
- Disposable E-Cigarette Environmental and Regulatory Backlash: The explosive growth of single-use disposable e-cigarettes has triggered significant regulatory backlash across Europe due to environmental concerns about lithium battery and plastic waste. The UK banned disposable vapes effective June 2025, and the EU is developing similar measures. Manufacturers must accelerate development of sustainable, refillable alternatives to capture displaced disposable users without regulatory compliance disruption.
- Consumer Education and Misinformation: Widespread public misconceptions about the relative risks of vaping versus combustible cigarettes, driven by misrepresented research and sensationalist media coverage, create consumer hesitancy that limits vaping adoption among the adult smoker population most likely to benefit from switching. Operators must invest heavily in science-based consumer education to correct misinformation and accelerate the structural shift from the Europe cigarette market to regulated vaping alternatives.
Emerging Market Trends
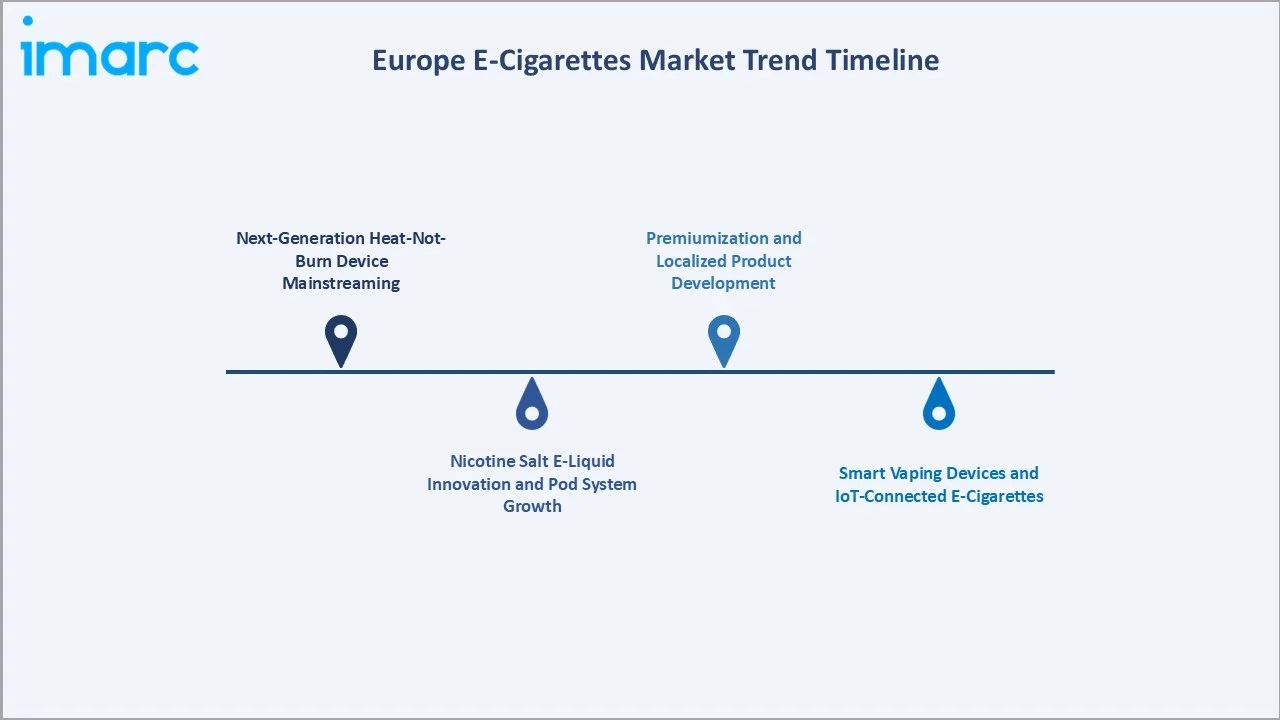
1. Next-Generation Heat-Not-Burn Device Mainstreaming
Heat-not-burn products are transitioning from early adopters to mainstream consumer segments across Italy, Germany, and Eastern Europe. These products appeal strongly to adult smokers who have not responded to conventional e-cigarettes, offering the most closely aligned experience to combustible tobacco. The next-generation e-cigarettes are expected to expand as heat-not-burn product availability, retail distribution, and consumer awareness broaden across all major European markets.
2. Nicotine Salt E-Liquid Innovation and Pod System Growth
Nicotine salt technology, delivering higher nicotine concentrations smoothly at lower power levels, has transformed the rechargeable pod system experience for adult smokers seeking e-cigarette alternatives. This innovation drives the rechargeable e-cigarettes are central to e-cigarette Europe industry growth. As the Europe pure nicotine market evolves, nicotine salt and hybrid salt-freebase formulations are becoming the standard for high-performance pod systems.
3. Premiumization and Localized Product Development
In March 2026, REVIVE marked its official entry into France. The company showcased four product ranges, PURA, CLAIR, AXIS, and RELITE, developed in line with French consumer preferences and regulatory requirements. Featuring a combination of minimalist aesthetics and advanced vaping technology, the launch represents a strategic move to strengthen REVIVE’s presence in one of Europe’s major vaping markets. The launch highlights a growing trend toward premium, market-specific vaping products tailored to local consumer preferences and regulatory requirements. Brands are increasingly differentiating through design, technology, and product customization to strengthen their positioning in competitive European markets.
4. Smart Vaping Devices and IoT-Connected E-Cigarettes
Smart vaping devices integrating Bluetooth connectivity, puff counting, nicotine tracking, and companion mobile applications are emerging at the premium end of the rechargeable and modular e-cigarette segments. These devices enable users to track and gradually reduce nicotine consumption, directly supporting harm reduction and cessation goals. Water-based e-cigarette innovation and similar deep technology investments exemplify the next wave of device differentiation in the European vaping market.
Industry Value Chain Analysis
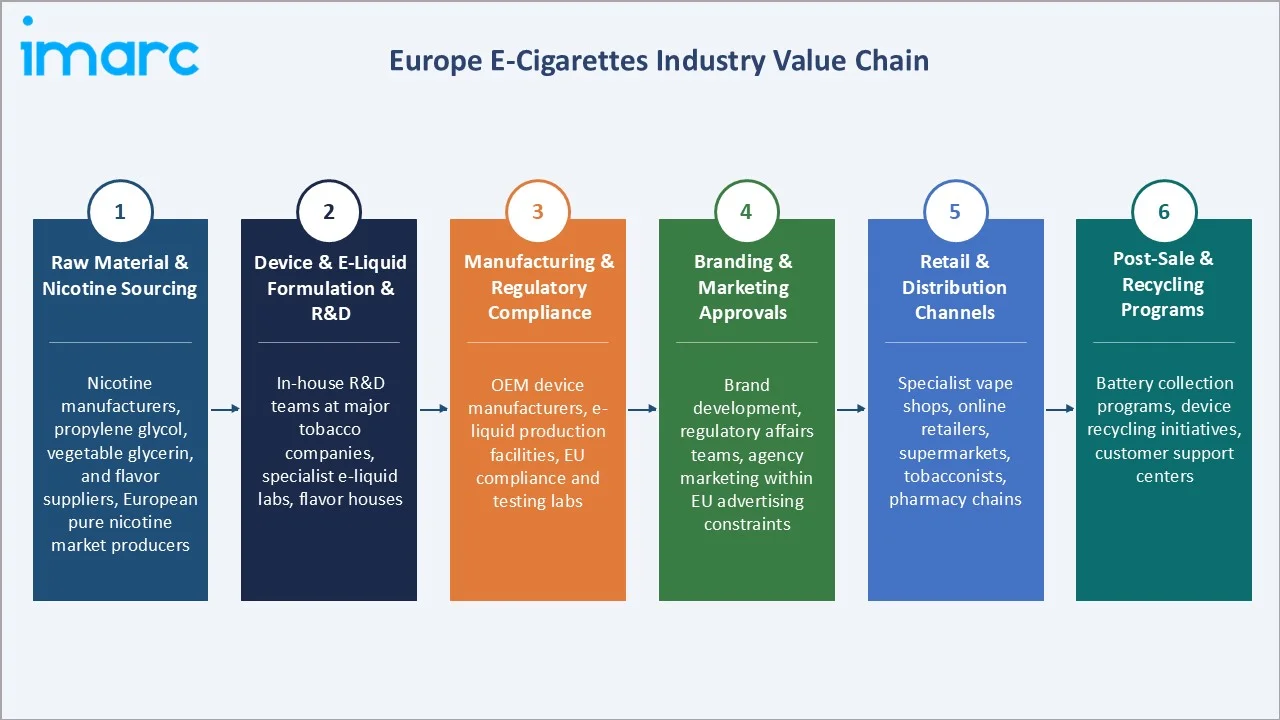
The Europe e-cigarettes market value chain spans nicotine and raw material sourcing, device and e-liquid formulation and R&D, manufacturing and regulatory compliance, branding and marketing approvals, retail and distribution channel management, and post-sale service and device recycling programs.
|
Stage |
Key Participants |
|
Raw Material & Nicotine Sourcing |
Nicotine manufacturers, propylene glycol, vegetable glycerin, and flavor suppliers, European pure nicotine market producers. |
|
Device & E-Liquid Formulation & R&D |
In-house R&D teams at major tobacco companies, specialist e-liquid labs, flavor houses. |
|
Manufacturing & Regulatory Compliance |
OEM device manufacturers, e-liquid production facilities, EU compliance and testing labs. |
|
Branding & Marketing Approvals |
Brand development, regulatory affairs teams, agency marketing within EU advertising constraints. |
|
Retail & Distribution Channels |
Specialist vape shops, online retailers, supermarkets, tobacconists, pharmacy chains. |
|
Post-Sale & Recycling Programs |
Battery collection programs, device recycling initiatives, customer support centers. |
Manufacturing and regulatory compliance represent the most capital-intensive stages, given EU product notification requirements, nicotine concentration testing, and packaging/labeling standards. Raw material sourcing from the Europe pure nicotine market is also strategically significant, as nicotine purity and supply chain traceability increasingly matter to regulators and brand-conscious consumers.
Technology Landscape in the Europe E-Cigarettes Industry
Battery and Heating Element Technology
Advanced lithium-ion and solid-state battery technology determines vaping device performance, portability, and reliability. Next-generation heating elements, including ceramic coil, mesh coil, and induction heating technologies, deliver cleaner aerosol production, extended coil lifespan, and improved flavor consistency. Heat-not-burn device heating chambers represent the most sophisticated engineering in the European vaping market, utilizing precision temperature control to heat tobacco below combustion thresholds.
Nicotine Salt and E-Liquid Formulation Technology
Nicotine salt formulations using benzoic acid or other organic acids allow significantly higher nicotine concentrations to be absorbed more efficiently and comfortably. This technology is the foundation of pod system dominance in the Europe pure nicotine market and has been central to the rechargeable e-cigarette category's market leadership. Water-based e-liquid technology from innovators represents the next frontier, offering cleaner inhalation profiles and novel device design opportunities.
Smart Device Technology and Digital Health Integration
Bluetooth-enabled e-cigarettes with companion apps for puff tracking, nicotine consumption monitoring, and behavioral coaching are emerging as premium product features. These technologies support NHS smoking cessation goals and responsible vaping frameworks. Automatic e-cigarettes benefit particularly from puff-count optimization algorithms that adjust device performance to match individual inhalation patterns, enhancing the ease-of-use advantage that drives the 69.8% automatic mode of operation market share.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product |
Rechargeable E-Cigarette |
55.8% |
2025 |
|
Flavor |
Tobacco |
45.8% |
2025 |
|
Mode of Operation |
Automatic E-Cigarette |
69.8% |
2025 |
|
Distribution Channel |
Specialist E-Cig Shops |
🔒 |
2025 |
|
Country |
United Kingdom |
29.8% |
2025 |

By Product
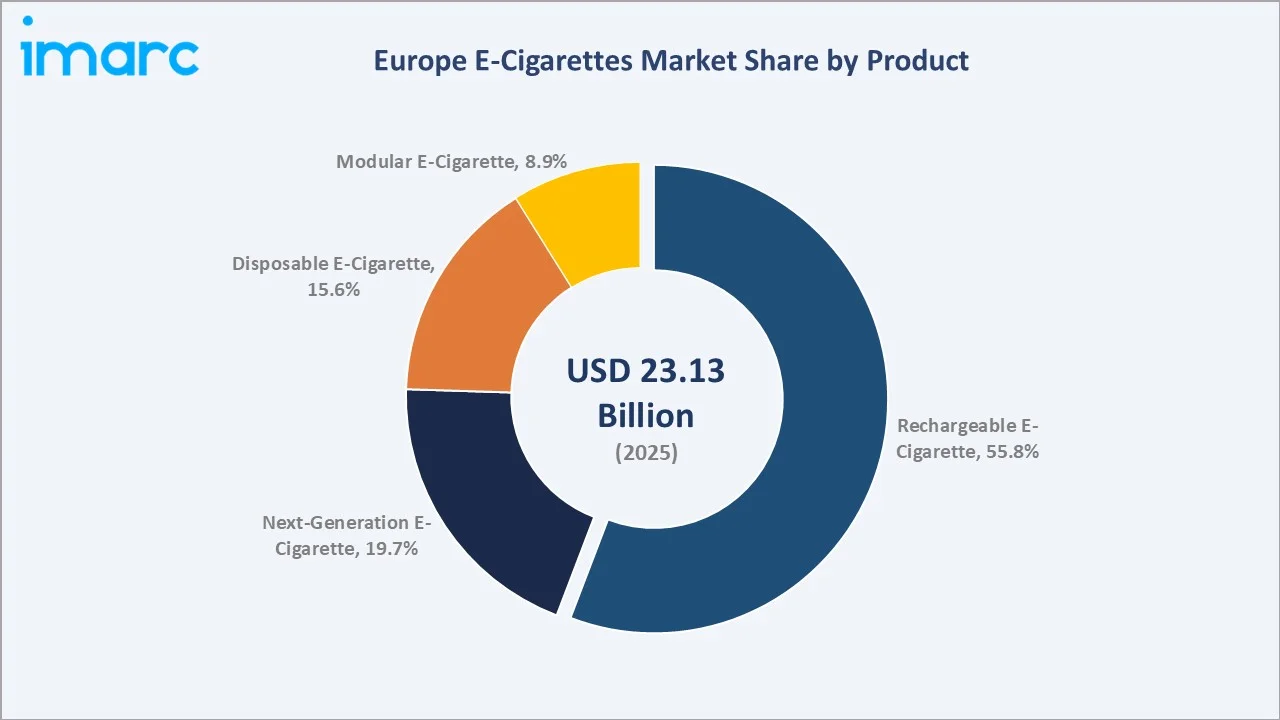
Rechargeable e-cigarettes lead at 55.8% (2025), driven by cost efficiency for regular adult vapers, wide flavor and nicotine strength selection through refillable pod systems, and superior long-term value versus disposables.
To access detailed market analysis, Request Sample
Next-generation e-cigarettes follow at 19.7%, led by heat-not-burn device adoption and growing fastest at a CAGR of ~17.5% through 2034, driven by heat-not-burn device expansion into new European markets and growing adult consumer acceptance. Disposable e-cigarettes account for 15.6%, and modular e-cigarettes for 8.9% of the 2025 market.
By Mode of Operation
Automatic e-cigarettes dominate at 69.8% (2025), driven by their intuitive draw-activated mechanism that most closely replicates the behavioral experience of combustible cigarettes for adult smokers transitioning from the Europe cigarette market. This ease-of-use advantage makes automatic devices the primary gateway product for new-to-vaping adult consumers, supporting e-cigarette Europe industry growth across all major European markets.
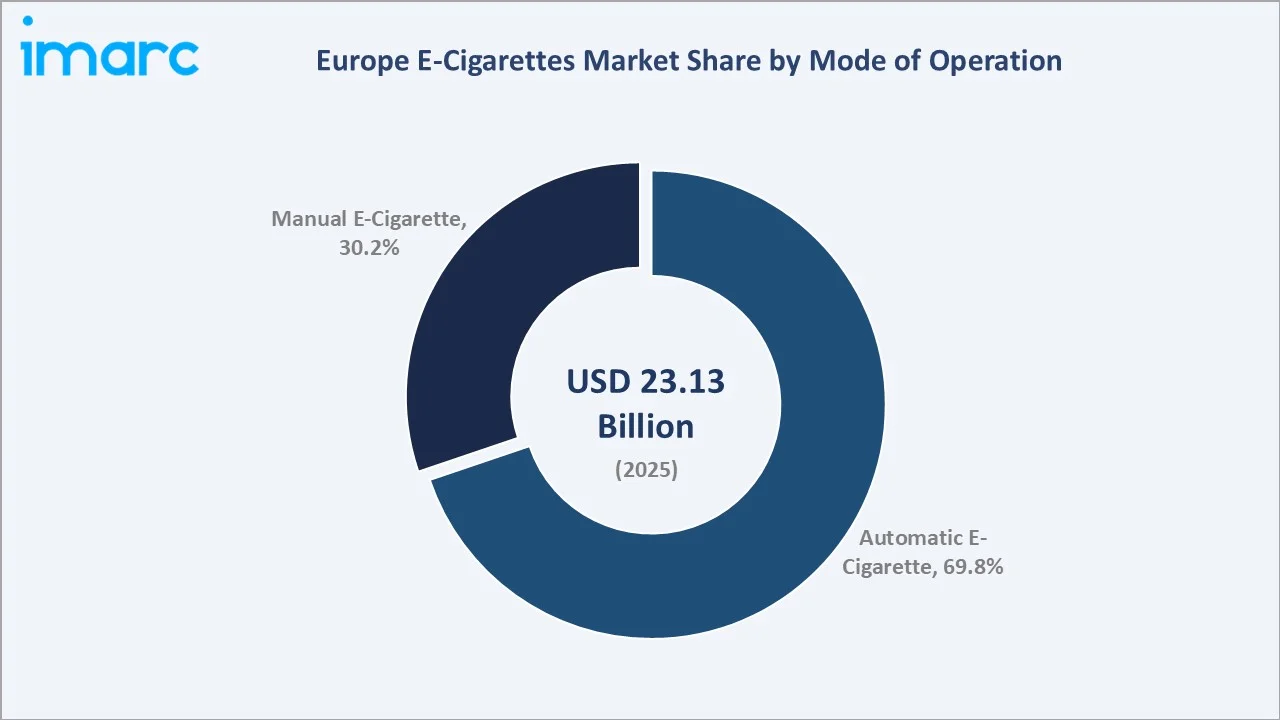
Manual e-cigarettes retain a 30.2% share, favored by experienced vapers who prefer the control of button-activated firing for precise temperature management and vapor production optimization. As the consumer base matures and migrates from entry-level to advanced devices, the manual segment is expected to grow at ~14.5% CAGR through 2034.
Regional Market Insights
|
Country |
Share (2025) |
Key Europe E-Cigarettes Market Drivers & Characteristics |
|
United Kingdom |
29.8% |
Reflecting the most progressive vaping regulatory environment and the highest adult vaping prevalence in Europe. |
|
Germany |
24.7% |
Reflecting a large adult smoker population transitioning to e-cigarettes and advanced specialist vape retail infrastructure. |
|
France |
17.8% |
Reflecting significant ex-smoker vaping culture, strong tobacconist retail channel integration, and declining Europe tobacco market volumes driving e-cigarette adoption. |
|
Italy |
11.6% |
Reflecting strong heat-not-burn device adoption, growing specialist vape retail, significant transition from traditional Europe cigarette market volumes. |
|
Spain |
8.9% |
Reflecting growing e-cigarette awareness, expanding vape retail networks, and increasing adult smoker conversion. |
|
Others |
7.2% |
Reflecting collective growth across Netherlands, Poland, Belgium, Scandinavia, and other European markets with developing e-cigarette regulatory frameworks and growing adult vaper populations. |
The United Kingdom's 29.8% dominance reflects its unique regulatory and cultural position: the most pro-vaping public health framework, NHS funding for stop-smoking services incorporating e-cigarettes, and the highest adult vaping rate in Europe. Germany's 24.7% reflects its position as Europe's largest consumer economy and significant adult smoker base converting to regulated vaping alternatives as the Europe tobacco market declines.
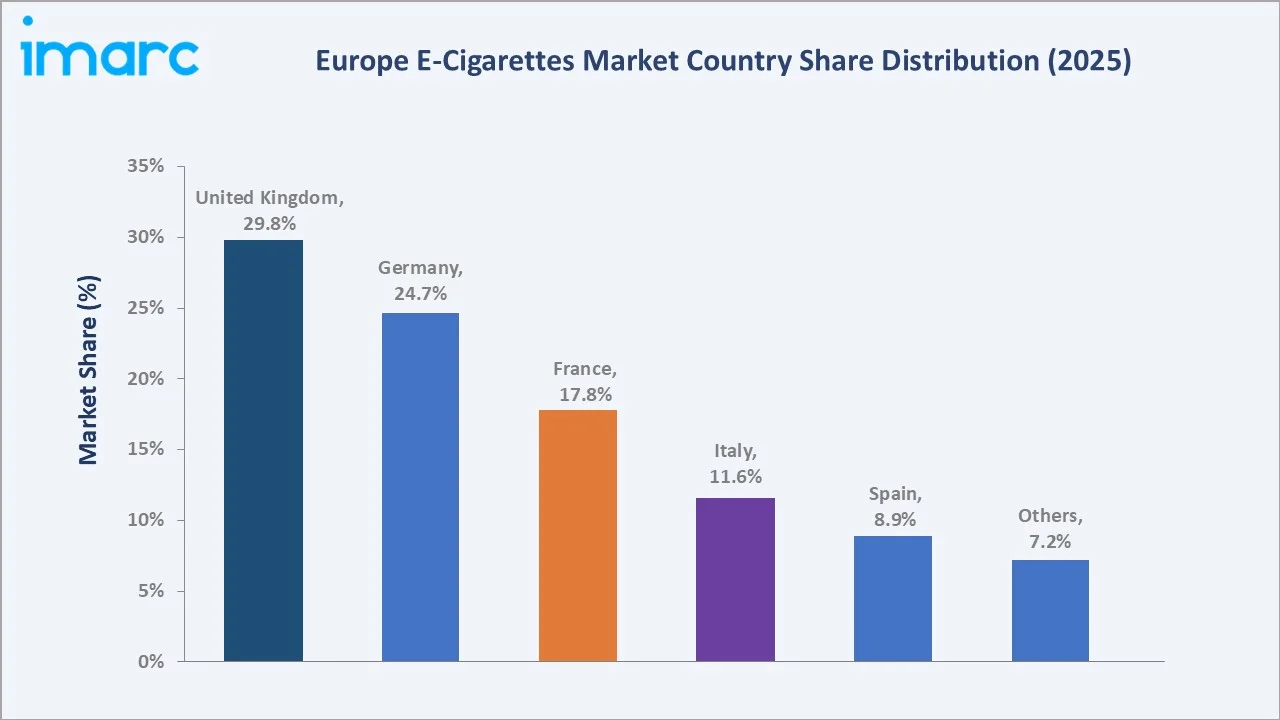
France's 17.8% share reflects deep penetration through tobacconist retail channels and a culturally accepting adult consumer attitude toward vaping. Italy's 11.6% is shaped by particularly strong heat-not-burn device adoption. Spain's 8.9% reflects accelerating market development, with the other segment at 7.2% representing collectively significant growth opportunities across Scandinavia, Poland, Belgium, and the Netherlands.
Competitive Landscape
The Europe e-cigarettes market is moderately concentrated, with tobacco industry majors holding significant shares alongside specialist brands. Competition centers on product innovation, regulatory compliance expertise, distribution network depth, and brand trust. E-cigarette industry growth in Europe is increasingly driven by the major tobacco companies' strategic investments in alternatives to their declining Europe tobacco market and Europe cigarette market core businesses.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
British American Tobacco p.l.c. |
Vuse |
Market Leader |
Drives a major shift toward reduced-risk alternatives in Europe by manufacturing and expanding its flagship Vuse e-cigarette brand. |
|
Philip Morris International |
VEEV, IQOS |
Market Leader |
Philip Morris International sells e-cigarettes and heated tobacco products across Europe as part of its corporate strategy to replace conventional cigarettes with smoke-free alternatives. |
|
Imperial Brands PLC |
blu, Pulze, Zone |
Established Player |
Imperial Brands PLC plays a major role in the European e-cigarette market, focusing primarily on its flagship vaping brand, blu. |
|
Aquioslabs Ltd |
Aquios AQ30 |
Innovator |
Aquioslabs Ltd plays a highly specialized role in the European e-cigarette market as a pioneer and primary technology provider of water-based vaping. |
|
Gamucci |
Vype, VIP |
Established Player |
Gamucci played a pioneering role in the European e-cigarette market as the first major electronic cigarette brand launched in the region. |
The competitive landscape continues to be reshaped by the major tobacco companies' accelerating investment in reduced-risk product alternatives as the Europe tobacco market and Europe cigarette market volumes structurally decline.
Key Company Profiles
British American Tobacco p.l.c.
British American Tobacco is one of the largest tobacco companies and a leading force in the European e-cigarettes market through its Vuse brand. Vuse is the leading e-cigarette brand by market share in multiple European countries, including the UK, Germany, and France. The company has committed to achieving revenue from non-combustible products, reflecting its strategic commitment to transitioning consumers from the declining Europe cigarette market to vaping alternatives.
- Key Brands: Vuse.
- Strategic Focus: Expanding Vuse's pan-European e-cigarette leadership and investing in sustainable device design and closed-loop recycling.
Philip Morris International
Philip Morris International is the pioneer and market leader in heat-not-burn technology through its IQOS device ecosystem, which has transformed the e-cigarette market landscape across Southern and Eastern Europe. IQOS, using HEETS and TEREA tobacco sticks heated without combustion, has achieved exceptional penetration in Italy, Japan, and Eastern European markets where adult tobacco consumers prefer the closest combustible tobacco replication.
- Key Brands: VEEV, IQOS.
- Strategic Focus: Driving IQOS mainstream adoption across Germany, France, and Spain, expanding VEEV rechargeable e-cigarette share, growing Europe pure nicotine market position.
Market Concentration Analysis
The Europe e-cigarettes market is moderately concentrated at the brand level, with British American Tobacco p.l.c., Philip Morris International, Imperial Brands PLC, Aquioslabs Ltd, and Gamucci collectively accounting for an estimated 45-55% of total European e-cigarette market revenue in 2025. These tobacco majors benefit from extensive European distribution infrastructure inherited from their traditional Europe tobacco market and Europe cigarette market operations. Specialist vape brands collectively represent significant market share through specialist vape retail channels. E-cigarette Europe industry growth is expected to drive further consolidation as tobacco companies acquire successful independent vape brands to complement their portfolio strategies.
Investment & Growth Opportunities
Highest Growth Segments
Next-generation e-cigarettes (~17.5% CAGR), automatic rechargeable pod systems (~16.8% CAGR), the growing Europe pure nicotine market through nicotine salt innovations, smart IoT-enabled vaping devices, and sustainable refillable device platforms represent the Europe e-cigarettes market's highest-priority investment vectors through 2034.
Investment Themes
- Heat-Not-Burn Device Expansion: The next-generation e-cigarette segment's ~17.5% CAGR represents Europe's fastest-growing product investment opportunity. Operators with manufacturing capability stand to capture significant revenue as the Italy, Germany, and Eastern European markets scale and as the patent landscape opens opportunities for competitive entries.
- Sustainable Post-Disposable Vaping Solutions: The UK's 2025 disposable e-cigarette ban and parallel EU regulatory actions create immediate market displacement opportunity. Companies delivering refillable, environmentally sustainable rechargeable alternatives at accessible price points will capture a significant share of the UK disposable vape users seeking compliant alternatives, representing a multi-hundred-million-dollar near-term revenue opportunity.
Future Market Outlook (2026-2034)
The Europe e-cigarettes market is projected to grow from USD 23.13 Billion in 2025 to USD 91.64 Billion by 2034, delivering a 16.03% CAGR over the forecast period through accelerating smoker-to-vaper conversion, Next-Generation heat-not-burn expansion, and Europe pure nicotine market innovation. The market's anchor value of USD 48.65 Billion in 2030 represents the inflection point at which e-cigarettes surpass conventional combustible tobacco in total European nicotine market value, marking a historic structural shift in the continent's nicotine consumption landscape.
Three structural forces are expected to define the Europe e-cigarettes market through 2034. First, the continued structural decline of the Europe tobacco market and Europe cigarette market will deliver an increasing flow of adult smoker conversions to regulated vaping alternatives. Second, the disposable e-cigarette regulatory phase-out across Europe will fundamentally reshape product mix dynamics through 2030, accelerating the growth of rechargeable e-cigarettes and next-generation devices as the primary consumer platforms. Third, technological innovation will continuously expand the addressable market for e-cigarettes by improving nicotine delivery efficiency, flavor authenticity, and device reliability, closing the behavioral gap between combustible cigarettes and vaping alternatives.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with senior executives from e-cigarette manufacturers, tobacco companies with vaping divisions, specialist vape retailers, regulatory affairs specialists, public health researchers, e-liquid flavor developers, and industry consultants across the UK, Germany, France, Italy, and Spain. These discussions validated market size estimates, assessed product and mode of operation growth dynamics, evaluated competitive positioning, and gathered qualitative insights on EU regulatory evolution and Europe pure nicotine market product development trends.
Secondary Research
Secondary research encompassed company annual reports, EU compliance filings, European Commission tobacco regulatory publications, national health authority vaping guidance documents, specialist vape industry databases, press releases, trade publication data, and reputed market intelligence publications. These resources were used to analyze market trends, competitive positioning, regulatory developments, and country-level market characteristics across the European e-cigarettes industry.
Forecasting Models
Forecasting models were developed using historical market data (2020-2025), adult smoking prevalence decline trends, regulatory phase-out timelines for disposable e-cigarettes, heat-not-burn device adoption curves, product innovation pipeline analysis, and macroeconomic disposable income indicators. The analysis incorporated both top-down and bottom-up approaches, validated through primary research cross-referencing, to generate reliable market forecasts through 2034.
Europe E-cigarettes Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Products Covered | Modular E-Cigarettes, Rechargeable E-Cigarettes, Next-Generation E-Cigarettes, Disposable E-Cigarettes |
| Flavors Covered | Tobacco, Botanical, Fruit, Sweet, Beverage, Others |
| Mode of Operations Covered | Automatic E-Cigarettes, Manual E-Cigarettes |
| Distribution Channels Covered | Specialist E-Cig Shops, Online, Supermarkets and Hypermarkets, Tobacconist, Others |
| Countries Covered | Germany, France, United Kingdom, Italy, Spain, Others |
| Companies Covered | British American Tobacco p.l.c., Philip Morris International, Imperial Brands PLC, Aquioslabs Ltd, Gamucci, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Europe e-cigarettes market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Europe e-cigarettes market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Europe e-cigarettes industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Europe E-Cigarettes Market Report
The Europe e-cigarettes market reached USD 23.13 Billion in 2025, driven by accelerating adult smoker conversion from the Europe cigarette market, government harm reduction endorsements, product innovation, and structural decline of the Europe tobacco market.
The market is projected to grow at a CAGR of 16.03% during 2026-2034, reaching USD 91.64 Billion by 2034. E-cigarette Europe industry growth is driven by heat-not-burn expansion, rechargeable pod system innovation, nicotine salt technology, and regulatory support for harm reduction across European markets.
Rechargeable e-cigarettes lead at 55.8% (2025) due to cost efficiency for regular adult vapers, broad flavor and nicotine strength selection, and superior value versus disposables.
Automatic e-cigarettes lead at 69.8% (2025) due to their draw-activated mechanism that replicates combustible cigarette behavior for adult smokers transitioning from the Europe cigarette market.
The United Kingdom leads at 29.8% (2025) due to the world's most progressive vaping regulatory environment, NHS endorsement for smoking cessation, and the highest adult vaping prevalence in Europe. E-cigarette Europe industry growth has been most pronounced in the UK market.
Leading companies include British American Tobacco p.l.c., Philip Morris International, Imperial Brands PLC, Aquioslabs Ltd, and Gamucci, among others.
The market is projected to reach approximately USD 48.65 Billion by 2030, representing the structural inflection point where e-cigarettes surpass conventional combustible tobacco in total European nicotine market value, reflecting the historic shift from the Europe tobacco market.
Priority investment opportunities include next-generation heat-not-burn device manufacturing, sustainable rechargeable alternatives to banned disposable e-cigarettes, Europe pure nicotine market nicotine salt R&D, smart IoT-enabled vaping device platforms, and water-based e-liquid technology development.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade