
Europe Sports Betting Market Size, Share, Trends and Forecast by Platform, Betting Type, Sports Type, and Country, 2026-2034
Europe Sports Betting Market Size, Share, Trends & Forecast (2026-2034)
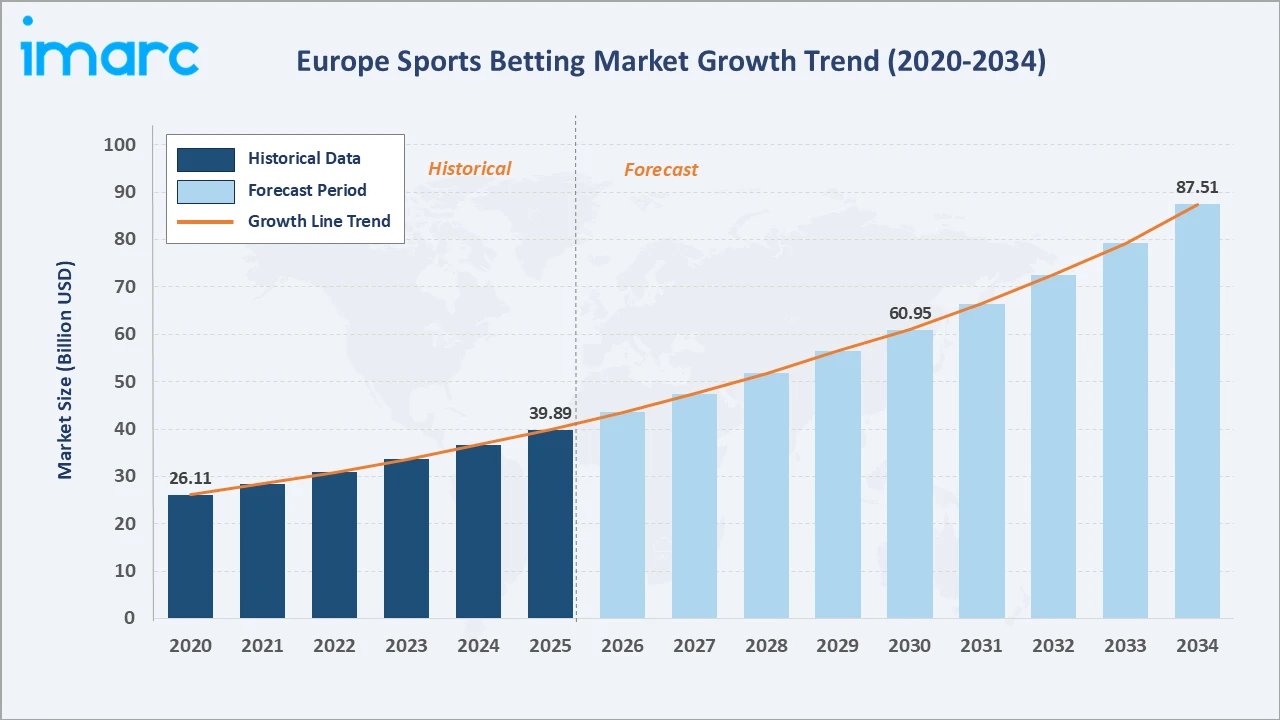
The Europe sports betting market size increased from USD 39.89 Billion in 2025 to USD 44.42 Billion in 2026 and is projected to reach USD 87.51 Billion by 2034, growing at a CAGR of 8.85% during 2026-2034. The market is driven by smartphone penetration, live betting, and expanding European series betting markets. Smartphone adoption in Europe is projected to increase from 83% of mobile connections in 2024 to 91% by 2030. Greater mobile connectivity enables users to place bets conveniently and engage with real-time sports content, supporting higher digital betting activity across the region. Online platforms lead at 78.5%, football leads sports type at 38.5%, and the United Kingdom leads regionally at 25.8% (2025).
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 39.89 Billion |
| Market Size (2026) | USD 44.42 Billion |
|
Forecast Market Size (2034) |
USD 87.51 Billion |
|
CAGR (2026-2034) |
8.85% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Platform |
Online (78.5%, 2025) |
|
Leading Sports Type |
Football (38.5%, 2025) |
|
Leading Country |
United Kingdom (25.8%, 2025) |
The Europe sports betting market expanded from USD 26.11 Billion in 2020 to USD 39.89 Billion in 2025 and an estimated USD 44.42 Billion in 2026, reflecting a robust 8.85% CAGR. The market is projected to reach USD 60.95 Billion by 2030 and USD 87.51 Billion by 2034, driven by progressive regulatory liberalization, the Europe online sports betting market's rapid mobile-first expansion, and growing engagement with European series betting markets.
To get more information on this market, Request Sample
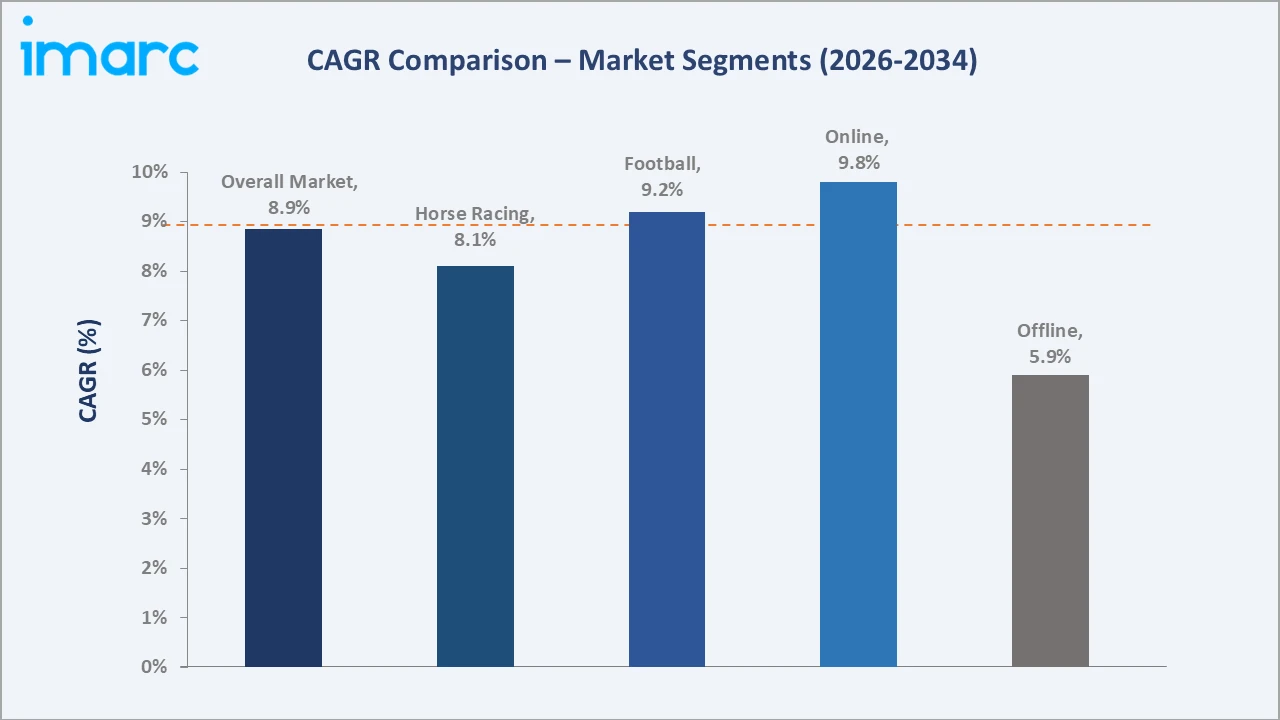
Online platforms lead growth at ~9.8% CAGR through mobile-first sportsbook adoption and live in-play betting. Football betting grows at ~9.2% CAGR through major European series betting markets and major tournament volumes. The overall market CAGR of 8.85% reflects strong, broad-based demand expansion across all European jurisdictions.
Executive Summary
The Europe sports betting market is experiencing sustained double-digit equivalent growth, supported by progressive regulatory liberalization across major European jurisdictions, the explosive growth of the Europe online sports betting market, and deep cultural affinity for football, horse racing, basketball, and baseball wagering. Online platforms lead at 78.5%. Football dominates at 38.5% of sports type share, driven by the core European series betting markets that generate the highest year-round wagering volumes and attract the largest sportsbook promotional budgets. The United Kingdom leads regionally at 25.8%.
Key Market Insights
|
Insight |
Data |
|
Dominant Platform |
Online - 78.5% share (2025) |
|
Leading Sports Type |
Football - 38.5% share (2025) |
|
Leading Country |
United Kingdom - 25.8% share (2025) |
|
Market Opportunity |
Live betting expansion; eSports wagering; emerging regulated markets; AI-odds personalization |
Key Analytical Observations Supporting the Above Data:
- Online at 78.5%: The Europe online sports betting market dominates through mobile sportsbook apps, 24/7 accessibility, live/in-play betting markets, and superior user experience over retail.
- Football at 38.5%: Football leads due to Europe's deep cultural affinity for the sport and the prominence of European series betting markets, which generate sustained year-round wagering volumes amplified by Champions League and European Championship tournaments.
- United Kingdom at 25.8%: The UK leads as Europe's most mature and sophisticated sports betting market, with a well-established regulatory framework under the UKGC, a strong bookmaking heritage, high online penetration, and the world's most actively bet-upon football league, the Premier League.
Europe Sports Betting Market Overview
The Europe sports betting market encompasses all legal wagers placed on sporting events through licensed operators across online (mobile apps, websites) and offline (betting shops, racecourse totes) platforms. Key sports include football, horse racing, basketball, baseball, hockey, and cricket. Betting types span fixed odds wagering, exchange betting, live/in-play betting, pari-mutuel, and eSports betting. The market is shaped by the interplay of national regulatory frameworks, sports media rights valuations, smartphone adoption, and growing demand for real-time in-play wagering. European series betting markets represent the highest-value wagering events. The market is assessed across Germany, France, the United Kingdom, Italy, Spain, and other European nations.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
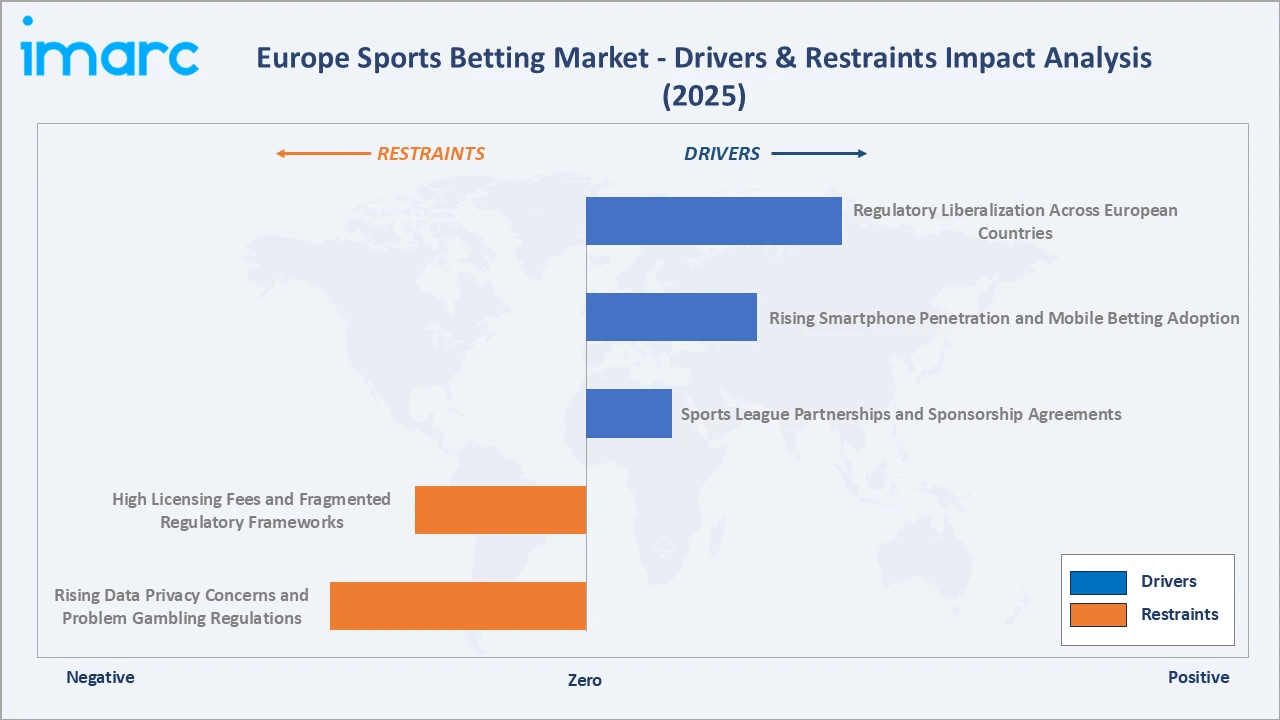
- Regulatory Liberalization Across European Countries: Progressive gambling regulation liberalization is creating transparent, competitive markets that channel consumer demand into licensed Europe online sports betting market operators, generating significant growth.
- Rising Smartphone Penetration and Mobile Betting Adoption: With UK smartphone penetration above 93% and Germany's 109.2 million subscribers in 2024, an increase from 105.4 million subscribers in 2033, mobile-first sportsbook apps have transformed betting accessibility. The Europe online sports betting market benefits directly from consumers' ability to place bets anywhere, at any time, driving wagering frequency and average bet volumes across all demographic segments.
- Sports League Partnerships and Sponsorship Agreements: Escalating partnerships between licensed betting operators and sports leagues, clubs, and broadcasters, including shirt sponsorships, official betting partner designations, and stadium naming rights, are dramatically increasing sports betting brand awareness and consumer acceptance across European markets, particularly for European series betting markets football operations.
Market Restraints
- High Licensing Fees and Fragmented Regulatory Frameworks: European sports betting operators must navigate diverse national licensing requirements, fees, and compliance standards. Multi-market licensing costs, localization requirements, and ongoing compliance reporting create significant operational overhead, particularly for smaller operators seeking to compete across multiple European markets simultaneously.
- Rising Data Privacy Concerns and Problem Gambling Regulations: Stricter GDPR enforcement, evolving data handling requirements for personalized betting services, and tightening responsible gambling mandates, including stake limits, self-exclusion schemes, and advertising restrictions, add compliance complexity and cost.
Market Opportunities
- eSports Betting and Youth Engagement: The Europe esports market growth is creating a rapidly expanding adjacent betting opportunity. eSports events offer diverse betting markets, from match-winner bets to in-game first blood and map winner markets, attracting younger demographics not traditionally engaged with conventional sports betting, representing a major Europe online sports betting market growth vector.
- Emerging Regulated Markets in Eastern and Central Europe: Several Eastern and Central European countries continue to develop or expand regulated sports betting frameworks, presenting significant market entry opportunities for established operators. Poland, Czech Republic, Romania, and Ukraine represent substantial under-penetrated markets where growing football fandom and increasing internet penetration are creating favorable conditions for market development.
Market Challenges
- Advertising Restrictions and Responsible Gambling Mandates: Growing public health concerns about problem gambling are driving advertising watershed rules, stake limits, and mandatory player protection tools across major European markets. UK's consideration of a statutory gambling levy, Italy's advertising ban, and Spain's restrictions on promotional offers create significant marketing constraints that increase customer acquisition costs for Europe online sports betting market operators.
- Match-Fixing and Integrity Risks: Sports integrity concerns and match-fixing risks pose persistent reputational and regulatory challenges for the European sports betting ecosystem. Operators must invest significantly in sports data monitoring, collaboration with sports governing bodies, and suspicious betting alert systems, creating ongoing operational and cost burdens across all European series betting markets.
Emerging Market Trends
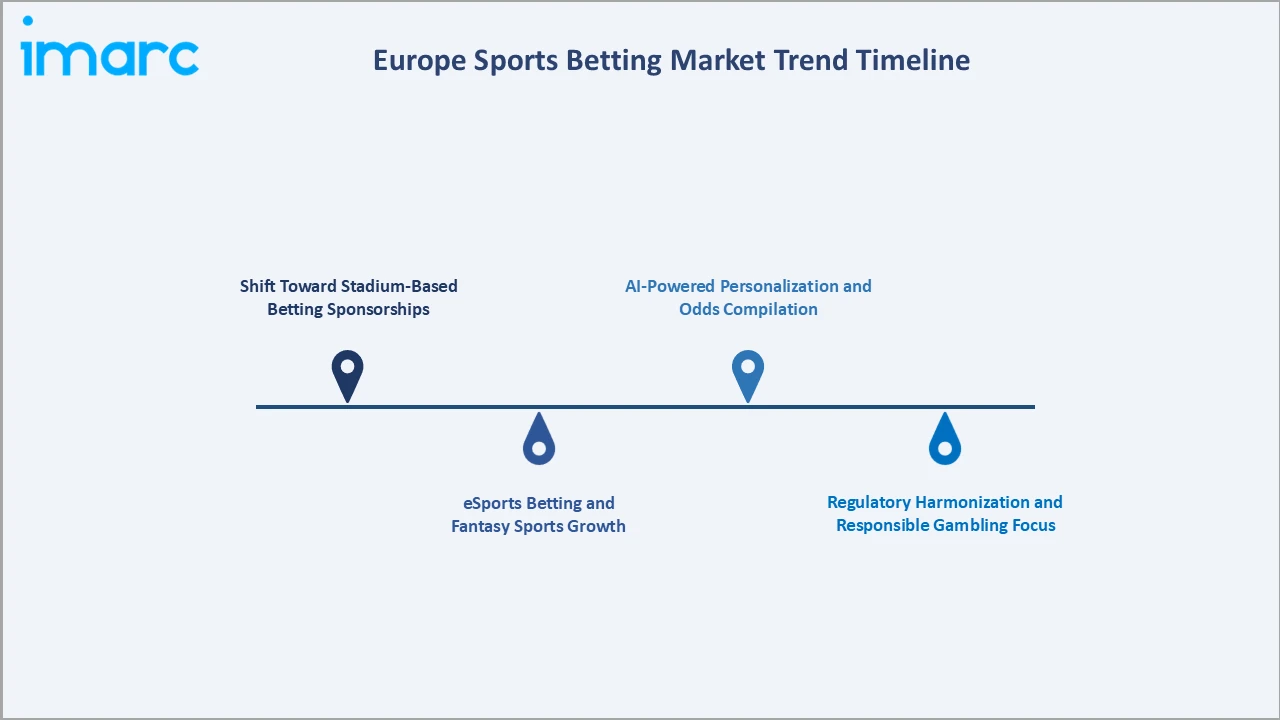
1. Shift Toward Stadium-Based Betting Sponsorships
In August 2026, BoyleSports entered an official betting partnership with Nottingham Forest for the 2026/27 Premier League season. Under the agreement, the bookmaker will gain prominent exposure through LED advertising at the City Ground and across the club’s global broadcast audience, strengthening its presence in English football as gambling brands shift toward stadium-based sponsorship visibility This partnership highlights a growing trend of betting companies increasing visibility through LED boards, stadium branding, and matchday promotions. This approach is becoming more important as restrictions reduce traditional front-of-shirt gambling sponsorship opportunities.
2. eSports Betting and Fantasy Sports Growth
eSports betting is emerging as one of the fastest-growing segments within the European sports wagering ecosystem. The Europe esports market growth creates a significant adjacent wagering opportunity, attracting younger bettors unfamiliar with traditional sports. Fantasy sports platforms are bridging the gap between skill-based engagement and traditional betting, expanding the addressable customer base for Europe online sports betting market operators.
3. AI-Powered Personalization and Odds Compilation
AI and machine learning are transforming odds compilation, risk management, and customer personalization across European sportsbooks. Algorithms analyzing player betting history, preferred sports, and behavioral patterns enable hyper-personalized promotional offers, micro-market creation, and dynamic odds adjustment.
4. Regulatory Harmonization and Responsible Gambling Focus
European regulators are increasingly coordinating on responsible gambling standards, advertising restrictions, and cross-border operator licensing frameworks. In May 2026, Betsuna launched in the UK and Ireland as a new online gambling brand offering sports betting, casino games, and bingo through a single platform. Operated by ProgressPlay Limited, which is licensed by the UK Gambling Commission and the Malta Gaming Authority. Operators investing in robust responsible gambling infrastructure are gaining regulatory goodwill and competitive advantage in securing licenses across multiple European jurisdictions.
Industry Value Chain Analysis
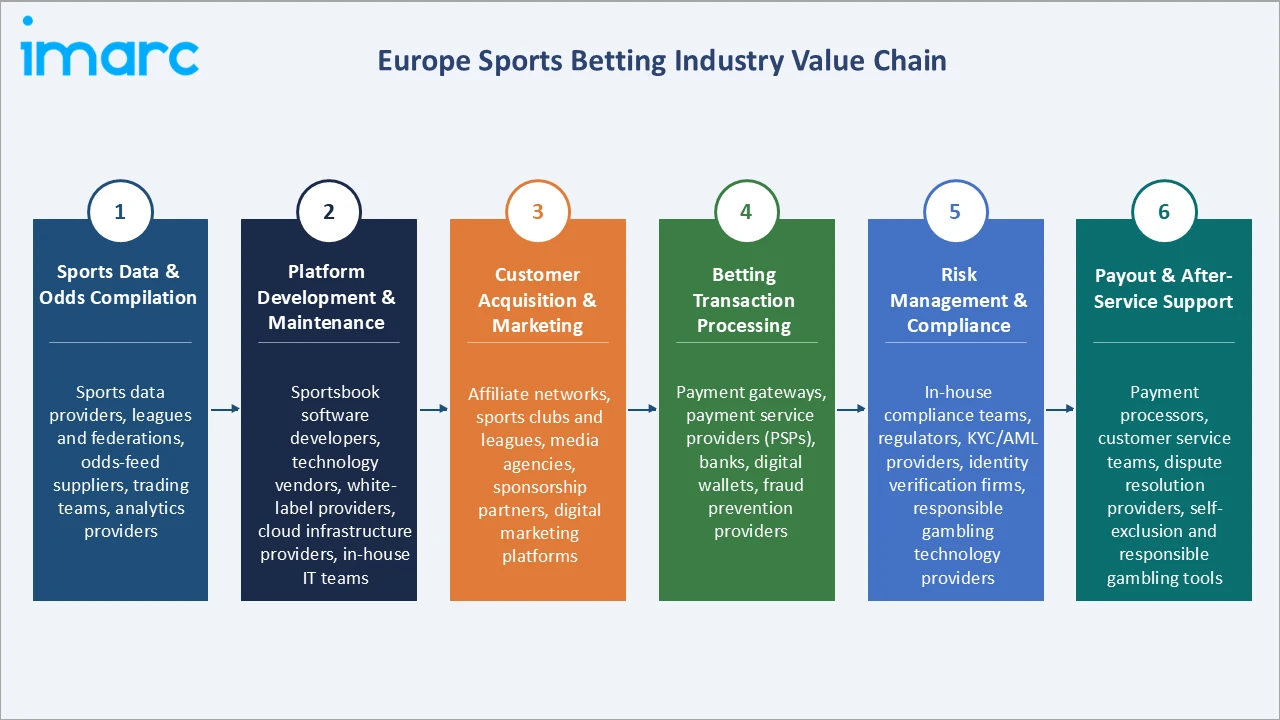
The Europe sports betting market value chain spans sports data and odds compilation, platform development and maintenance, customer acquisition and marketing, betting transaction processing, risk management and regulatory compliance, and payout and after-service support. Each stage is governed by national licensing requirements and increasingly shaped by data integrity and responsible gambling mandates.
|
Stage |
Key Participants |
|
Sports Data & Odds Compilation |
Sports data providers, leagues and federations, odds-feed suppliers, trading teams, analytics providers. |
|
Platform Development & Maintenance |
Sportsbook software developers, technology vendors, white-label providers, cloud infrastructure providers, in-house IT teams. |
|
Customer Acquisition & Marketing |
Affiliate networks, sports clubs and leagues, media agencies, sponsorship partners, digital marketing platforms. |
|
Betting Transaction Processing |
Payment gateways, payment service providers (PSPs), banks, digital wallets, fraud prevention providers. |
|
Risk Management & Compliance |
In-house compliance teams, regulators, KYC/AML providers, identity verification firms, responsible gambling technology providers. |
|
Payout & After-Service Support |
Payment processors, customer service teams, dispute resolution providers, self-exclusion and responsible gambling tools. |
Sports data and odds compilation represent the most strategically critical stage, as real-time data quality directly determines betting product competitiveness and in-play market accuracy. Risk management and regulatory compliance have become increasingly capital-intensive as European regulators tighten player protection and AML requirements across the Europe online sports betting market landscape.
Technology Landscape in the Europe Sports Betting Industry
Real-Time Data and In-Play Betting Technology
Real-time sports data feeds, sophisticated algorithmic odds compilation, and sub-second latency bet acceptance technology are the core technology infrastructure enabling live betting market competitiveness. Market-specific statistical models enable micro-market creation on European football matches at scale.
AI, Machine Learning, and Responsible Gambling Technology
Machine learning models are deployed across customer risk assessment, fraud detection, problem gambling identification, and personalized promotion delivery. AI-powered responsible gambling tools - including behavioral analysis detecting at-risk betting patterns and automatic intervention systems - are increasingly mandated by European regulators. These tools simultaneously fulfill compliance requirements and improve operator sustainability by reducing problem gambling attrition.
Payment Technology and Cryptocurrency Integration
Frictionless payment infrastructure is critical to the competitiveness of Europe online sports betting market. Instant bank transfers, e-wallets, and card processing must deliver sub-second deposit confirmation to optimize betting UX. Cryptocurrency payment integration is emerging across licensed operators in Malta, Gibraltar, and other crypto-friendly jurisdictions. Blockchain-based smart contract bet settlement is being piloted at several frontier operators targeting younger European bettors.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Platform |
Online |
78.5% |
2025 |
|
Betting Type |
🔒 |
🔒 |
2025 |
|
Sports Type |
Football |
38.5% |
2025 |
|
Country |
United Kingdom |
25.8% |
2025 |
By Platform
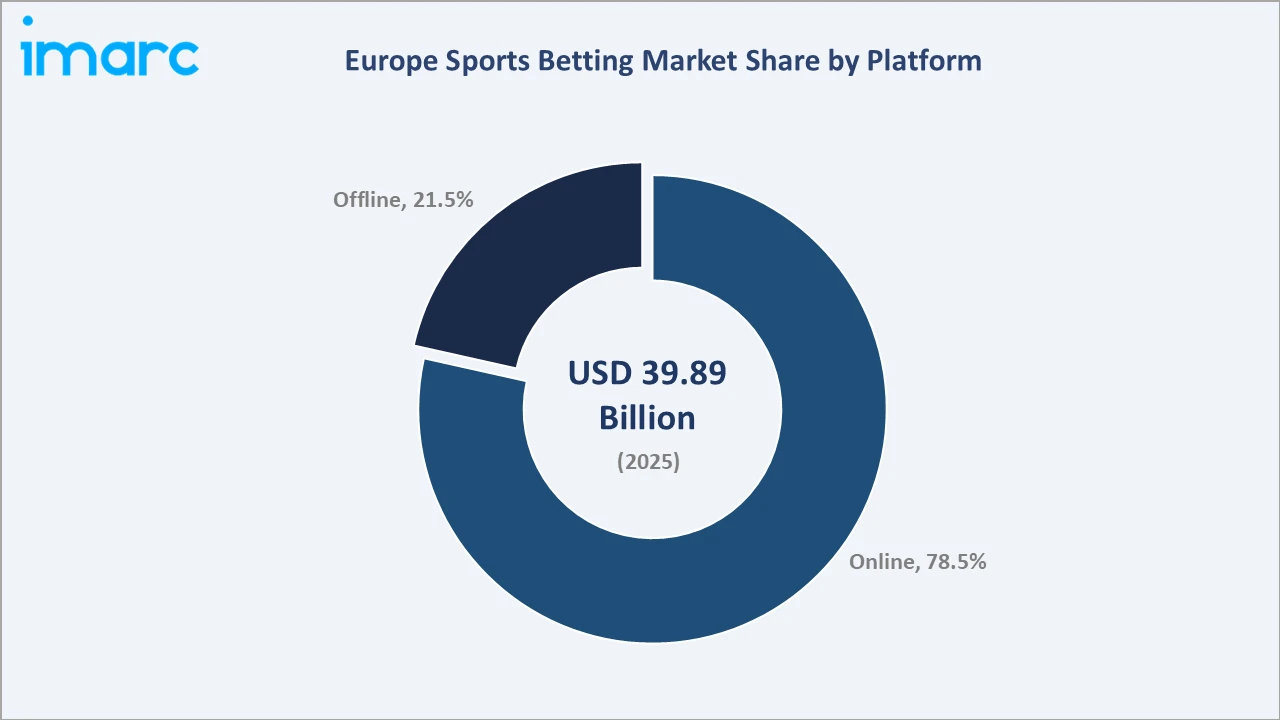
Online platform dominates at 78.5% (2025), driven by smartphone penetration and the structural convenience advantage of 24/7 mobile betting access. The Europe online sports betting market benefits from superior product breadth that offline channels cannot replicate at scale.
To access detailed market analysis, Request Sample
Offline platform retains 21.5% share, anchored by the UK's established bookmaking shop culture, France's PMU horse racing tote network, and Italy's betting shop traditions. The offline segment grows at ~5.9% CAGR, supported by social wagering experiences and demographic segments preferring in-person betting.
By Sports Type
Football leads at 38.5% (2025), driven by the core European series betting markets. These competitions generate Europe's highest betting volumes and attract the largest operator promotional investments. Football grows at ~9.2% CAGR through expanding in-play micro-markets on European series betting markets, growing women's football wagering, and major tournament betting cycles.
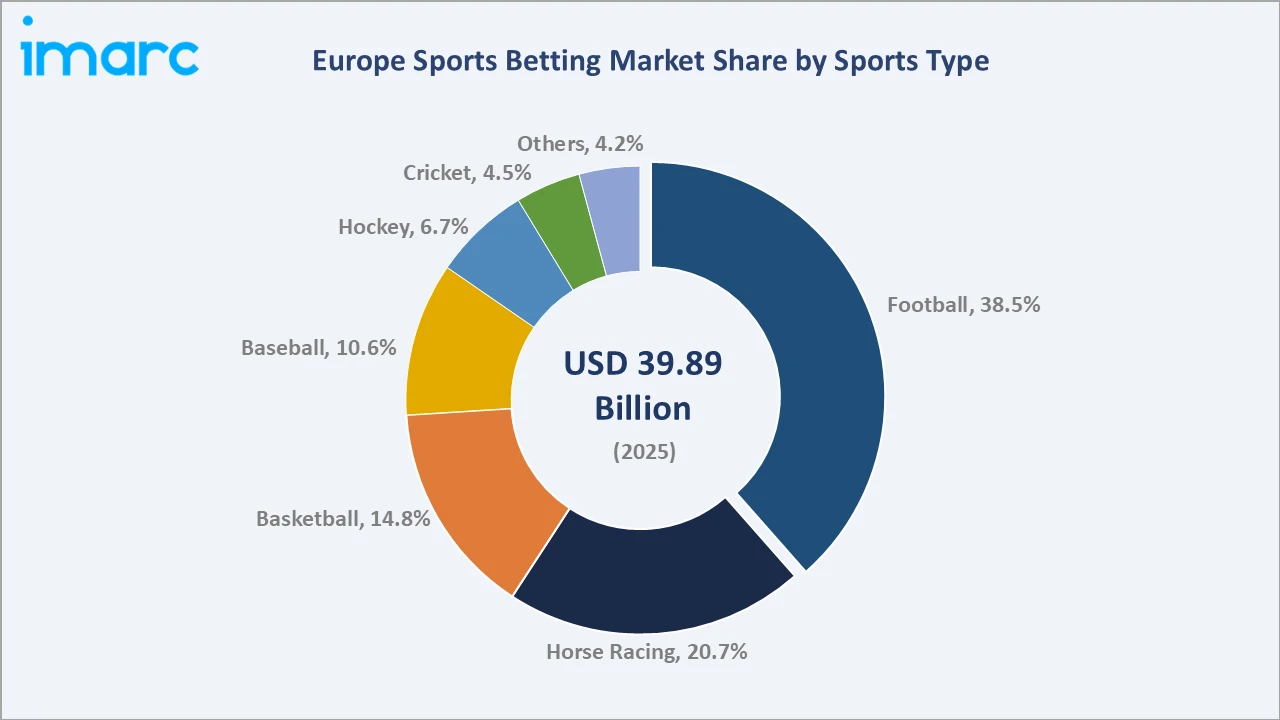
Horse racing follows at 20.7%, growing at ~8.1% CAGR through digital tote modernization and racing streaming integration. Basketball at 14.8%, baseball at 10.6%, hockey at 6.7%, cricket at 4.5%, and others at 4.2%.
Regional Market Insights
|
Country |
Share (2025) |
Key Europe Sports Betting Market Drivers & Characteristics |
|
United Kingdom |
25.8% |
Reflecting the most mature, regulated sports betting market; high online penetration; Premier League and horse racing cultural affinity. |
|
Germany |
21.5% |
Smartphone users driving Europe online sports betting market mobile adoption. |
|
France |
17.8% |
Reflecting a regulated market with strong football, horse racing, and rugby betting culture. |
|
Italy |
14.7% |
Reflecting a regulated market with a strong football betting tradition; growing basketball interest. |
|
Spain |
10.6% |
Reflecting a regulated market with strong La Liga football betting demand; growing basketball wagering; strict advertising restrictions. |
|
Others |
9.6% |
Reflecting diverse emerging and developed betting markets across the Netherlands, Poland, Scandinavia, Belgium, and other European countries with growing regulated football and horse racing betting activity. |
The United Kingdom's 25.8% leadership reflects its structural advantages: the most sophisticated, regulated betting market, Premier League cultural dominance as the most-bet-upon football competition, and deeply embedded bookmaking culture across retail and digital channels. Germany's 21.5% reflects the Europe online sports betting market benefiting from high smartphone penetration.
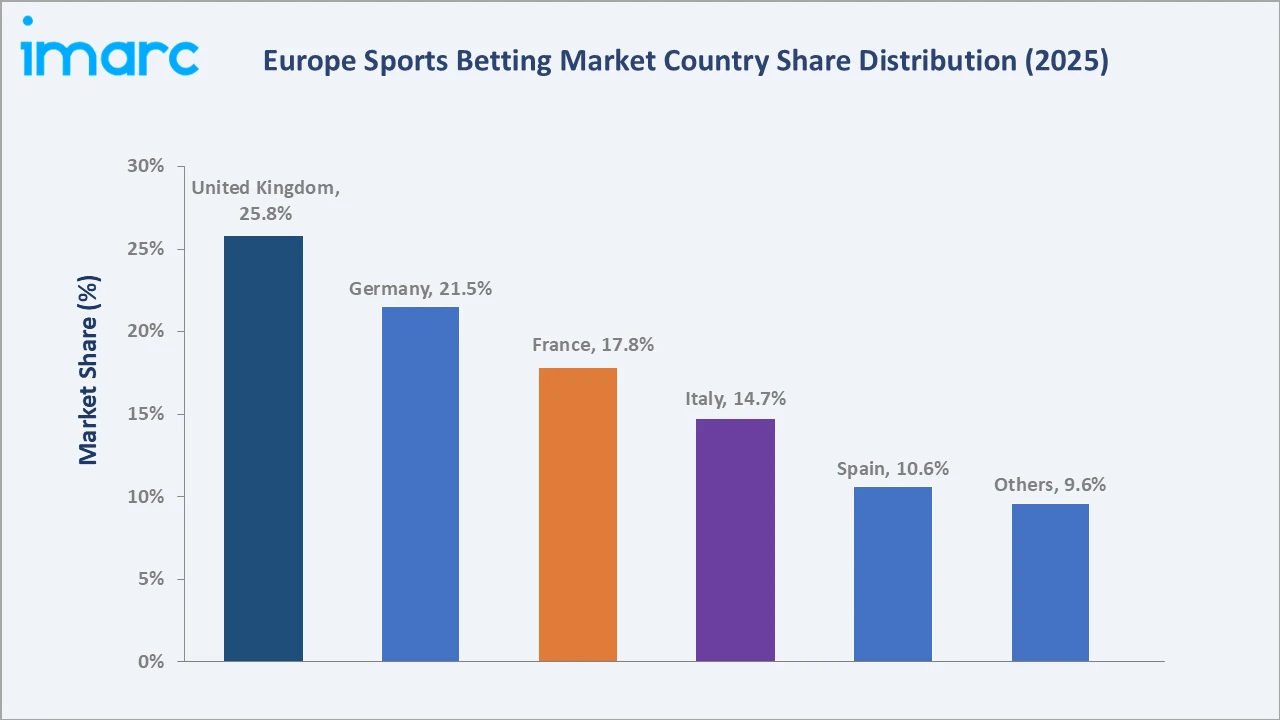
France's 17.8% share reflects a mature dual-channel market combining regulated online sports betting with an extensive horse racing tote network. Italy's 14.7% share is anchored by passionate football betting demand. Spain's 10.6% market is shaped by betting dominance and strict advertising regulation that has consolidated market share among established licensed operators. The Others segment at 9.6% represents significant collective opportunity across emerging regulated markets in Eastern Europe and Scandinavia.
Competitive Landscape
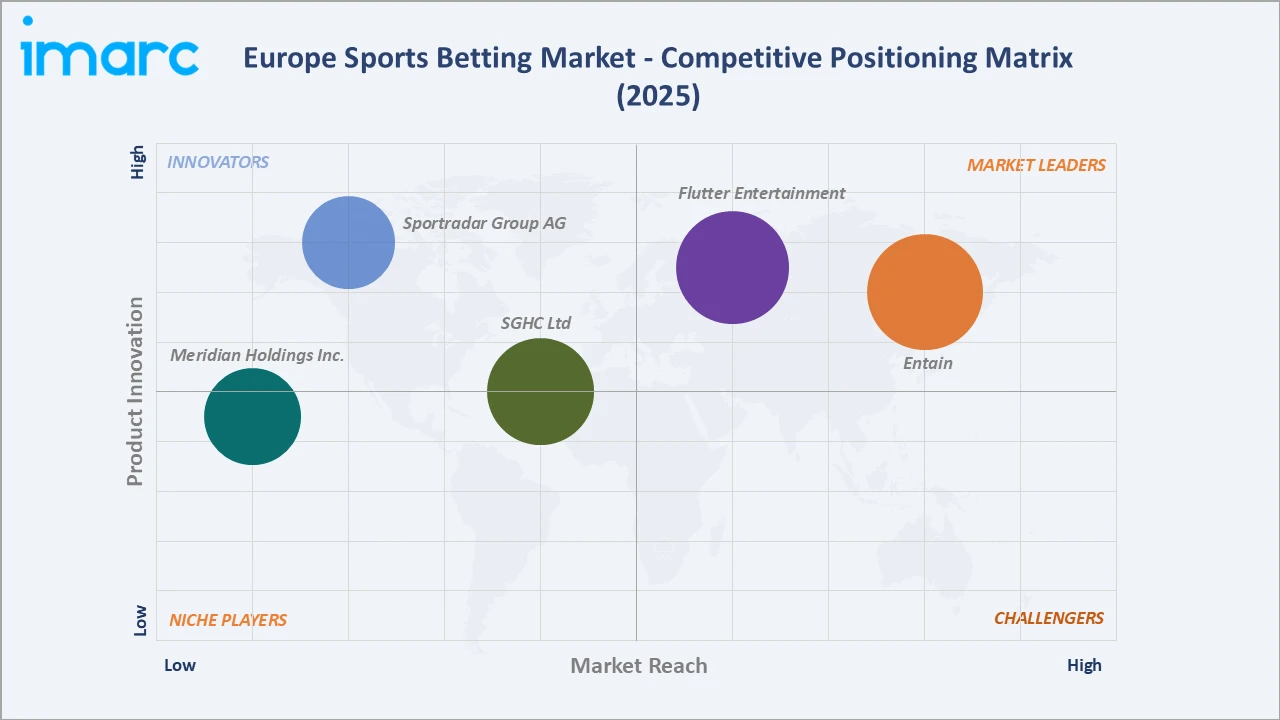
The Europe sports betting market is moderately concentrated, dominated by large multinational operators alongside technology innovators and niche specialists. Competition centers on product breadth, live betting market quality, mobile UX, promotional generosity, brand trust, and regulatory compliance capability across multiple European jurisdictions.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
Flutter Entertainment |
Betfair, Paddy Power, Sky Bet, FanDuel |
Market Leader |
Flutter Entertainment is one of the largest online sports betting and gaming operators, driving the European market through dominant local brands. |
|
Entain |
Coral, Eurobet, STS, BetCity, Crystalbet |
Market Leader |
Entain operates as a major force in the European sports betting and gaming market, focusing exclusively on regulated and regulated territories. |
|
SGHC Ltd |
Betway |
Established Player |
SGHC Ltd (Super Group) acts as the parent holding company for major online gaming and sports betting brands like Betway, driving regulated operations across Europe |
|
Meridian Holdings Inc. |
Meridianbet |
Established Player |
Operates as a prominent B2B and B2C sports betting and gaming technology group in regulated European markets through its brand, Meridianbet. |
|
Sportradar Group AG |
Sportradar |
Innovator |
Sportradar Group AG acts as a vital bridge between European sports leagues and betting operators. |
Competition is intensifying around Europe online sports betting market technology leadership, responsible gambling compliance, and European series betting markets football coverage depth. Global operators are making strategic acquisitions, sports sponsorship investments, and technology platform upgrades to maintain competitive positioning, while data and technology specialists are building critical B2B infrastructure that powers the broader European sports wagering ecosystem.
Key Company Profiles
Flutter Entertainment
Flutter Entertainment is a sports betting and gaming company with a strong presence across several European markets. The company operates a portfolio of established sportsbook and gaming brands, including Paddy Power, Betfair, and others. In the Europe sports betting market, Flutter benefits from broad digital reach, strong brand recognition, advanced betting platforms, and experience in regulated gaming environments.
- Key Brands: Betfair, Paddy Power, Sky Bet, FanDuel.
- Strategic Focus: Strengthening its leadership across major European sports betting markets through locally established brands, advanced sportsbook technology, and product innovation. The company is also emphasizing platform integration, operational efficiencies, strategic acquisitions, and responsible gaming initiatives to drive sustainable growth across regulated European markets.
Entain
Entain is a sports betting and gaming company with a significant presence across Europe through a portfolio of established brands. The company operates across online and retail betting channels, offering sportsbook, casino, and gaming services in multiple regulated markets. In the Europe sports betting market, Entain benefits from strong brand recognition, extensive digital capabilities, broad customer reach, and experience operating within diverse regulatory environments.
- Key Brands: Coral, Eurobet, STS, BetCity, Crystalbet.
- Strategic Focus: Strengthening its position in the Europe sports betting market through digital expansion, product innovation, and a broad portfolio of established local brands. The company emphasizes advanced betting technology, personalized customer experiences, omnichannel integration, and responsible gaming, while continuing to optimize operations across regulated European markets.
Market Concentration Analysis
The Europe sports betting market is moderately concentrated, with the top five operators, Flutter Entertainment, Entain, SGHC Ltd, Meridian Holdings Inc., and Sportradar Group AG, collectively accounting for an estimated 40-55% of the total European licensed sports betting market in 2025. The UK market is the most concentrated, reflecting regulatory barriers to entry and the dominance of established heritage bookmakers. Continental European markets display greater fragmentation, with local and regional operators maintaining significant share alongside global players. The B2B technology layer represents a more concentrated ecosystem where data quality barriers create durable competitive moats. Market consolidation through M&A is expected to continue through 2034, particularly as operators seek multi-market scale to amortize technology and compliance investment.
Investment & Growth Opportunities
Highest Growth Segments
Online platform (~9.8% CAGR est.), eSports betting (~12%+ CAGR est.), live/in-play betting market expansion, emerging regulated Eastern European markets, and AI-powered personalization technology for the Europe online sports betting market represent the sector's highest-priority investment vectors through 2034.
Investment Themes
- eSports Betting Platform Development: The Europe esports market growth creates a compelling adjacent opportunity for betting product development. Specialized eSports odds compilation, CS2/LoL-specific betting market creation, and eSports live betting platforms targeting younger demographics represent differentiated investment themes within the Europe online sports betting market ecosystem.
- Regulated Market Entry in Emerging European Jurisdictions: Several Eastern and Central European countries continue developing regulated sports betting frameworks, creating market entry opportunities for operators with compliance capability and digital product depth. Early-mover advantages in newly regulated markets can be decisive, as licensees benefit from regulatory protection and brand establishment before market saturation.
Future Market Outlook (2026-2034)
The Europe sports betting market is projected to grow from USD 39.89 Billion in 2025 to USD 44.42 Billion in 2026, reaching USD 87.51 Billion by 2034, delivering an 8.85% CAGR over the forecast period through Europe online sports betting market digital expansion, European series betting markets GGR growth, eSports betting mainstreaming, and progressive regulatory liberalization. The market's anchor value of USD 60.95 Billion in 2030 represents the inflection point at which AI-personalized mobile sportsbooks achieve mass-market penetration and newly regulated Eastern European markets contribute meaningfully to the overall European market.
Three structural forces are expected to define the Europe sports betting market through 2034. First, the continued evolution of the Europe online sports betting market toward real-time, AI-powered live betting ecosystems will drive per-customer GGR expansion. Second, European series betting markets will remain the primary GGR engines through 2034 as media rights valuations, tournament cycles, and commercial interest in top-flight European football continue to elevate. Third, emerging regulated markets in Eastern and Central Europe will contribute meaningfully to overall European GGR growth through 2034.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with senior executives from licensed sports betting operators, technology providers, sports data companies, affiliate marketers, regulatory affairs specialists, and industry consultants across the UK, Germany, France, Italy, Spain, and other European markets. These discussions validated market size estimates, assessed platform and sports type growth dynamics, evaluated competitive positioning, and gathered qualitative insights on regulatory developments, live betting technology adoption, and European series betting markets contribution patterns.
Secondary Research
Secondary research encompassed operator annual reports, national gambling authority publications, sports media rights data, European esports market databases, press releases, technology partnership announcements, and reputed market intelligence publications. These resources were used to analyze betting volumes, regulatory developments, competitive positioning, and country-level market characteristics across the European sports betting industry.
Forecasting Models
Forecasting models were developed using a combination of historical data (2020-2025), regulatory expansion timelines, sports calendar event cycles, technology adoption curves for mobile and live betting, eSports market growth projections, and macroeconomic disposable income indicators. The analysis incorporated both top-down and bottom-up approaches, validated through primary research cross-referencing, to generate reliable Europe sports betting market forecasts through 2034.
Europe Sports Betting Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Platforms Covered | Offline, Online |
| Betting Types Covered | Fixed Odds Wagering, Exchange Betting, Live/In Play Betting, Pari-Mutuel, eSports Betting, Others |
| Sports Types Covered | Football, Basketball, Baseball, Horse Racing, Cricket, Hockey, Others |
| Countries Covered | Germany, France, United Kingdom, Italy, Spain, Others |
| Comapnies Covered | Flutter Entertainment, Entain, SGHC Ltd, Meridian Holdings Inc., Sportradar Group AG, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Europe sports betting market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Europe sports betting market.
- The study maps the leading, as well as the fastest-growing, markets. It further enables stakeholders to identify the key country-level markets within the region.
- Porter's five forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Europe sports betting industry and its attractiveness.
- The competitive landscape allows stakeholders to understand their competitive environment and provides insight into the current positions of key players in the market.
Frequently Asked Questions About the Europe Sports Betting Market Report
The Europe sports betting market size is estimated at USD 44.42 Billion in 2026, driven by progressive regulatory liberalization, Europe online sports betting market smartphone-driven digital expansion, and sustained wagering activity across European series betting markets and football competitions.
The market is projected to grow at a CAGR of 8.85% during 2026-2034, reaching USD 87.51 Billion by 2034, driven by live betting expansion, eSports wagering growth, emerging regulated markets, and AI-personalization of the Europe online sports betting market.
Online platforms lead the Europe online sports betting market at 78.5% (2025), driven by smartphone penetration and mobile-first sportsbook apps offering superior in-play betting and live streaming experiences.
Football leads at 38.5% (2025), driven by European series betting markets alongside Champions League and European Championship tournament wagering volumes.
The United Kingdom leads at 25.8% (2025), reflecting the most mature, regulated betting market, Premier League cultural dominance, regulatory framework, and the concentration of leading Europe online sports betting market operator headquarters.
Leading companies include Flutter Entertainment, Entain, SGHC Ltd, Meridian Holdings Inc., Sportradar Group AG, among others.
The market is projected to reach approximately USD 60.95 Billion by 2030, reflecting Europe online sports betting market mobile expansion, AI-powered live betting adoption, European series betting markets growth, and contributions from newly regulated Eastern European markets.
Key Europe online sports betting market trends include live/in-play betting dominance, eSports wagering growth, AI-personalized odds and promotions, responsible gambling technology integration, blockchain payment adoption, and regulatory harmonization across European jurisdictions.
Key drivers include regulatory liberalization, smartphone penetration driving mobile betting adoption, sports league partnership and sponsorship expansion, live betting technology advancement, eSports popularity growth, and sustained wagering engagement with European series betting markets and football competitions.
Priority investment opportunities include eSports betting platform development, emerging regulated Eastern European market entry, AI-driven odds personalization technology, live betting infrastructure investment, European series betting markets data partnerships, and responsible gambling technology development.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade