India Automotive Components Market Size, Share, Trends and Forecast by Vehicle Type, Component, Demand Category, and Region, 2026-2034
India Automotive Components Market Size, Share, Trends & Forecast (2026-2034)
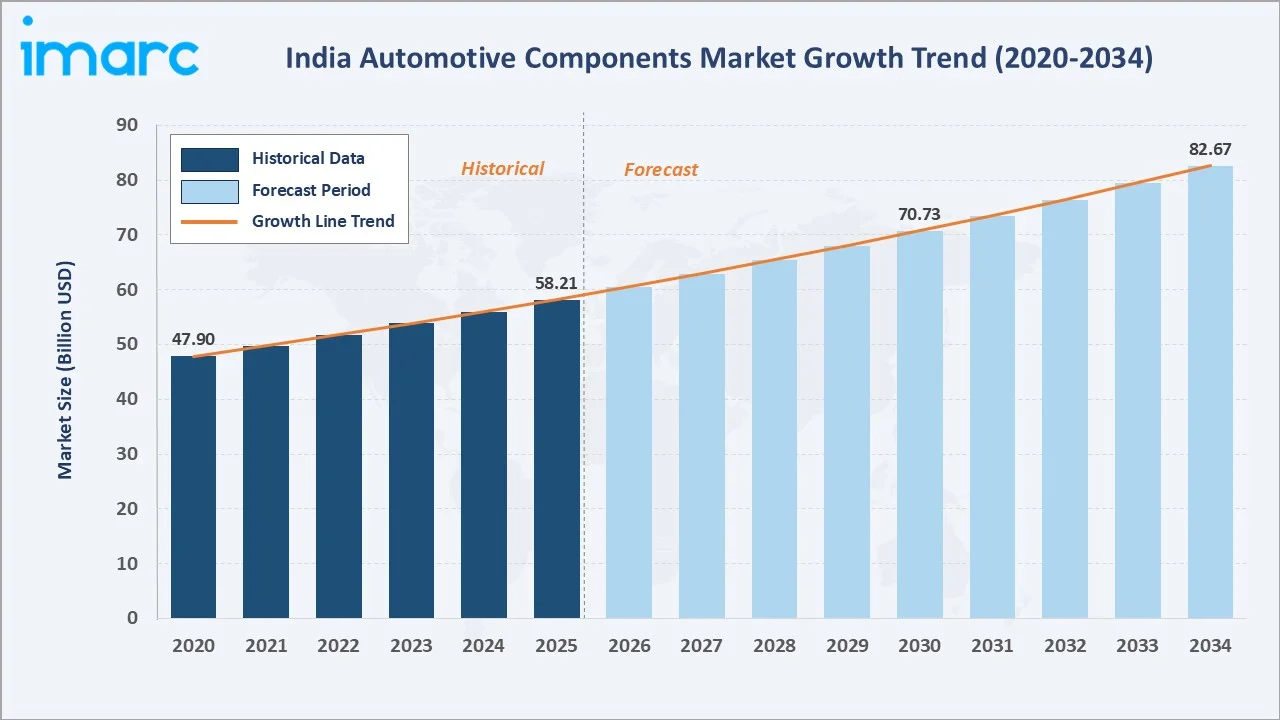
The India automotive components market grew from USD 58.21 Billion in 2025 to USD 60.53 Billion in 2026 and is projected to reach USD 82.67 Billion by 2034 at a CAGR of 3.97% during 2026-2034. Growth is driven by rising domestic vehicle production, government manufacturing incentives, EV component localization, and expanding export competitiveness. India’s automotive industry contributes approximately 7.1% to the country’s GDP, while India ranks as the fourth-largest vehicle producer globally. Passenger cars lead at 35.0% by vehicle type in 2025, OEM demand dominates at 60.0% by demand category, and North India commands the largest regional share at 31.0%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 58.21 Billion |
|
Market Size (2026) |
USD 60.53 Billion |
|
Forecast Market Size (2034) |
USD 82.67 Billion |
|
CAGR (2026-2034) |
3.97% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Vehicle Type |
Passenger Cars (35.0%, 2025) |
|
Dominant Demand Category |
OEM (60.0%, 2025) |
|
Leading Region |
North India (31.0%, 2025) |
The India automotive components market grew from USD 47.90 Billion in 2020 to USD 58.21 Billion in 2025 and is estimated to reach USD 60.53 Billion in 2026, supported by recovering vehicle demand and sustained manufacturing investment. The market is projected to reach USD 70.73 Billion by 2030 before reaching USD 82.67 Billion by 2034.
To get more information on this market, Request Sample
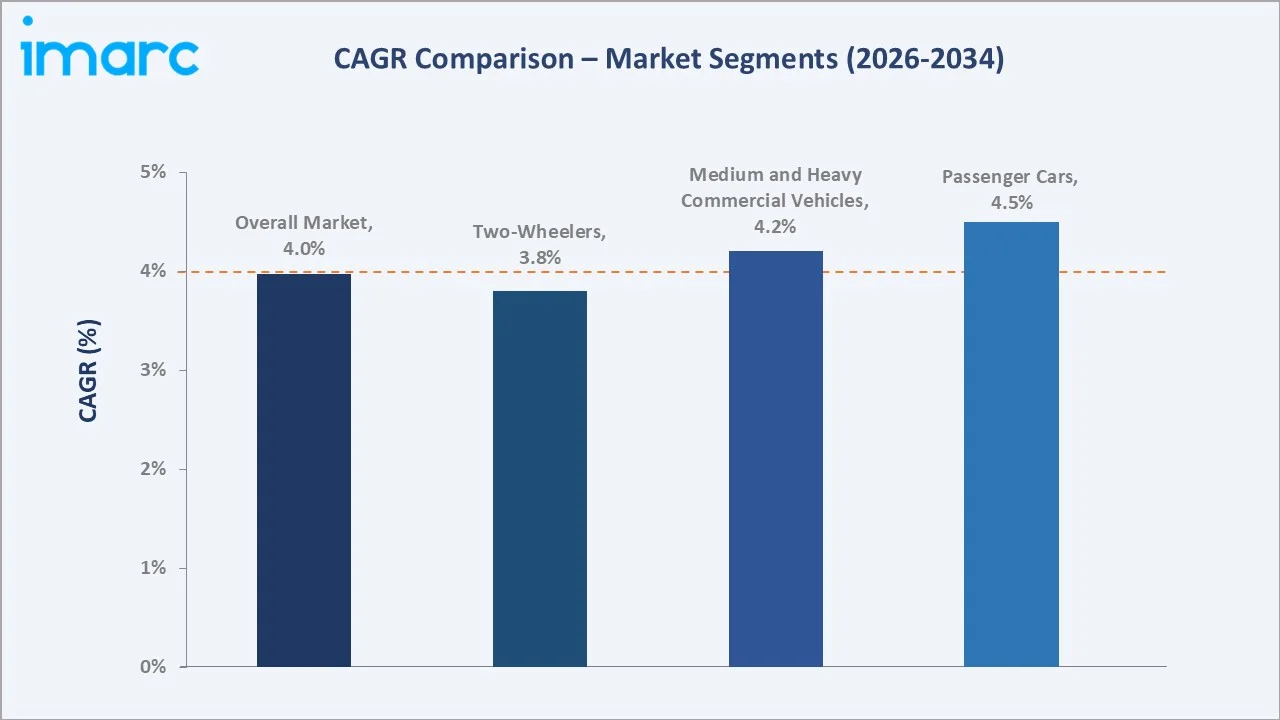
Passenger cars are projected to grow at approximately 4.5% CAGR over the forecast period. Medium and heavy commercial vehicles follow at approximately 4.2% CAGR, supported by infrastructure activity and freight demand. Two-wheelers are projected to grow at approximately 3.8% CAGR, reflecting steady rural and semi-urban mobility demand sustained across the forecast period.
Executive Summary
The India automotive components market is on a sustained growth trajectory, underpinned by a large and diversified vehicle production base, expanding domestic consumption, and growing integration into global automotive supply chains. The market has grown steadily, supported by recovering vehicle demand, government manufacturing incentives, and the accelerating shift toward electric and electronically advanced vehicles, creating demand for new component categories.
Passenger cars account for 35.0%, reflecting the dominance of personal mobility-oriented segments in India's production mix. OEM procurement represents the larger demand channel at 60.0%, driven by the volume requirements of vehicle assembly, while replacement demand at 40.0% is sustained by the large in-use vehicle parc spread across the country. North India holds 31.0%, supported by its dense passenger car manufacturing ecosystem.
Key Market Insights
|
Insight |
Data |
|
Dominant Vehicle Type |
Passenger Cars – 35.0% share (2025) |
|
Dominant Demand Category |
OEM – 60.0% share (2025) |
|
Leading Region |
North India – 31.0% (2025) |
|
Key Market Opportunity |
EV component localization and automotive export expansion offer the largest incremental revenue opportunity through 2034 |
Key Analytical Observations Supporting the Above Data:
- Passenger Cars at 35.0%: The passenger car segment commands the largest share, reflecting rising urban income levels, greater access to vehicle financing, and the steady introduction of new models across price segments, sustaining high component volumes across powertrain, body, safety, and electronics categories.
- OEM Channel at 60.0%: OEM demand dominates because vehicle assembly plants require large, consistent, quality-certified component volumes delivered on precise schedules, reinforced by government policies requiring high domestic content in vehicle production.
- North India at 31.0%: North India's leadership reflects its established position as India's largest passenger car production region, supported by a dense ecosystem of Tier-1 and Tier-2 suppliers concentrated near major assembly facilities, enabling efficient just-in-time supply chain operations.
India Automotive Components Market Overview
The India automotive components market encompasses the design, manufacture, and supply of all mechanical, electrical, electronic, and structural parts used across the full range of vehicle types assembled in India, including passenger cars, commercial vehicles, two-wheelers, three-wheelers, and off-road vehicles. The market serves two primary demand channels: the OEM channel requiring factory-fitted components delivered under rigorous quality and scheduling protocols, and the replacement channel supplying the large in-use vehicle parc through a distributed network of dealers, distributors, and retail service points.
The industry ecosystem spans multiple tiers, from raw material suppliers through sub-component manufacturers at Tier-2 and Tier-3 levels to system integrators at Tier-1 level supplying modules directly to OEM assembly lines. Government manufacturing incentive frameworks are systematically encouraging domestic production across component categories, driving investment in new capacity and supporting development of advanced component capabilities including EV-specific parts.
Market Dynamics
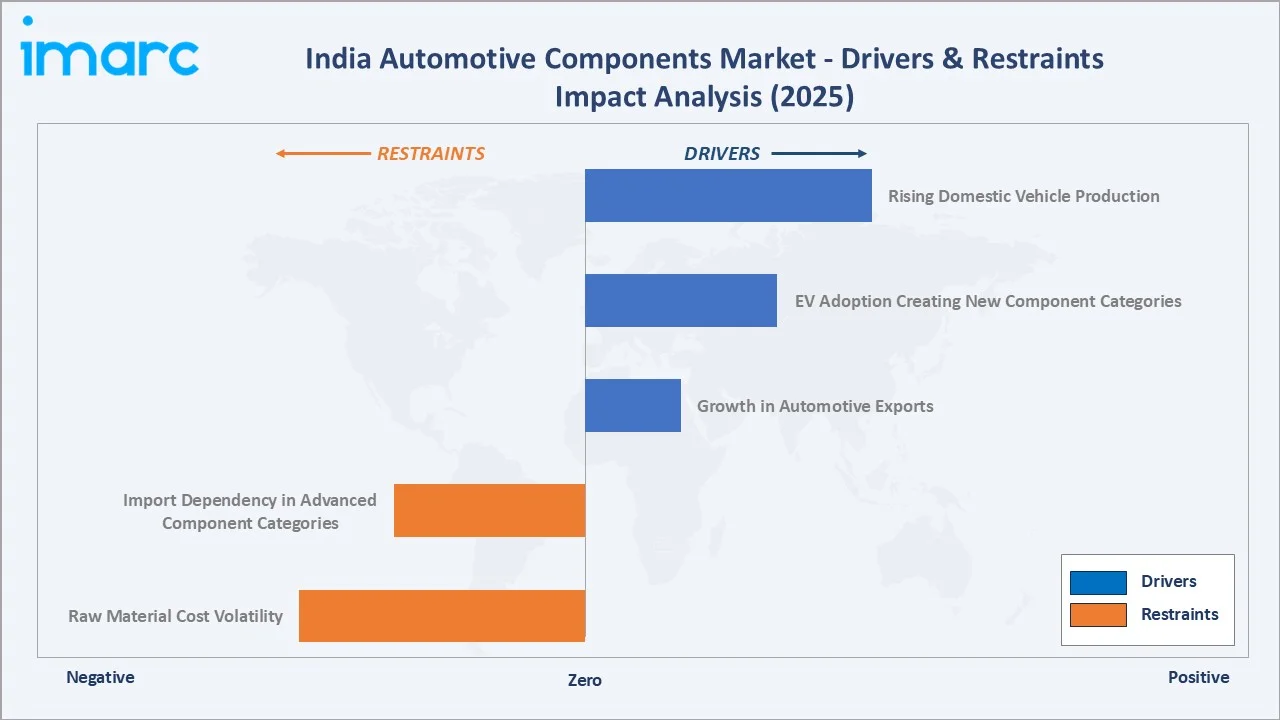
Market Drivers
- Rising Domestic Vehicle Production: In March 2026, India produced approximately 2.98 million passenger vehicles, three-wheelers, two-wheelers, and quadricycles, taking the total vehicle production in FY2026 to 34.71 million units. India's vehicle production has grown steadily across all segments, creating sustained volume-driven demand for automotive components across both OEM supply chains and the replacement aftermarket.
- EV Adoption Creating New Component Categories: In FY2026, India recorded 2.66 million EV sales, accounting for 8.62% of total automotive sales, with two- and three-wheelers contributing nearly 87% of EV volumes. The progressive shift toward electric vehicles is generating demand for battery systems, electric motors, power electronics, and related components, expanding the total addressable market for component manufacturers.
- Growth in Automotive Exports: India’s automobile exports increased by 24% in FY2026, surpassing 6.7 million units, supported by strong international demand for passenger vehicles, two-wheelers, and commercial vehicles. India's increasing competitiveness as a manufacturing hub has driven sustained growth in automotive component exports, creating additional revenue streams beyond the domestic OEM and replacement markets.
Market Restraints
- Raw Material Cost Volatility: Fluctuations in the prices of key inputs including steel, aluminum, copper, and polymer compounds can significantly compress margins for component manufacturers, particularly smaller suppliers without long-term supply arrangements.
- Import Dependency in Advanced Component Categories: India relies on imports for high-value, technology-intensive component categories including advanced electronics, precision sensors, and semiconductors, limiting domestic revenue capture in these fast-growing segments.
Market Opportunities
- Advanced Safety and Electronics Components: Regulatory mandates requiring advanced safety features in new vehicles create growing demand for sensors, cameras, radar systems, and electronic control units that are currently underprovided by domestic manufacturers.
- Export Market Development: India's improving manufacturing competitiveness and established engineering base present a growing opportunity to expand automotive component exports, with particular potential in precision components and sub-assemblies for developed markets.
Market Challenges
- Transition Risk for ICE Component Manufacturers: Manufacturers with significant exposure to internal combustion engine-specific components face the challenge of managing potential long-term demand decline as EV penetration grows, requiring proactive portfolio transition.
- Intensifying Import Competition in Premium Segments: Established global component suppliers compete aggressively in India's technology-intensive categories, making it difficult for domestic manufacturers to gain share without significant technology investment.
Emerging Market Trends
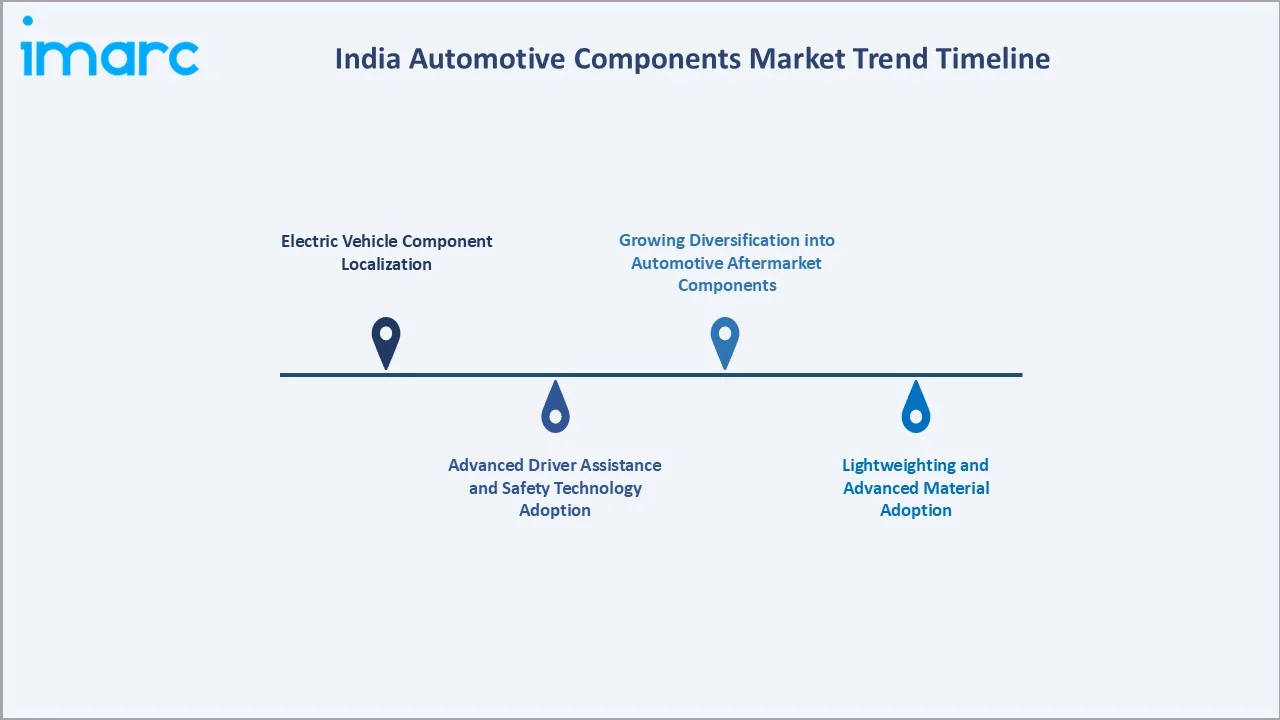
1. Electric Vehicle Component Localization
The Government launched the PM E-Drive scheme in 2024, allocating INR 10,900 crore for EV adoption and charging infrastructure. The growing adoption of electric vehicles is driving accelerating demand for domestically produced EV-specific components, including battery packs, electric motors, and power electronics. Government incentive schemes for advanced battery manufacturing are catalyzing significant investment in new production facilities, with the EV component market expected to grow substantially as vehicle electrification rates increase toward government targets.
2. Advanced Driver Assistance and Safety Technology Adoption
Regulatory requirements for advanced safety features are driving rapid growth in demand for automotive electronics, including cameras, radar sensors, and electronic control units. Global technology suppliers are expanding their India manufacturing presence, while domestic manufacturers are building capabilities in ECU production and sensor assembly, supported by government import substitution initiatives. In May 2026, Valeo was nominated by a leading Indian OEM to supply its Smart Safety 360 (VSS360) ADAS system, providing advanced driving assistance functions for commercial vehicles, marking a landmark win for domestically produced ADAS hardware.
3. Growing Diversification into Automotive Aftermarket Components
Automotive component manufacturers in India are increasingly diversifying beyond their traditional product categories into broader aftermarket portfolios, including braking, steering, belts, and vehicle maintenance products. In July 2026, NBC Bearings, a brand of National Engineering Industries Ltd., expanded its automotive aftermarket portfolio with the launch of a new range of vehicle components, including wiper blades, brake pads, belts, and steering rods. This strategy enables suppliers to capture rising replacement demand, expand customer reach, and create additional revenue streams across two-wheelers, three-wheelers, and passenger vehicles.
4. Lightweighting and Advanced Material Adoption
Stricter fuel efficiency and emissions standards are accelerating the adoption of lightweight materials including high-strength steel, aluminum alloys, and advanced engineering polymers across body, chassis, and structural component categories. Component manufacturers are investing in new material processing capabilities to meet OEM performance requirements while improving vehicle efficiency.
Industry Value Chain Analysis
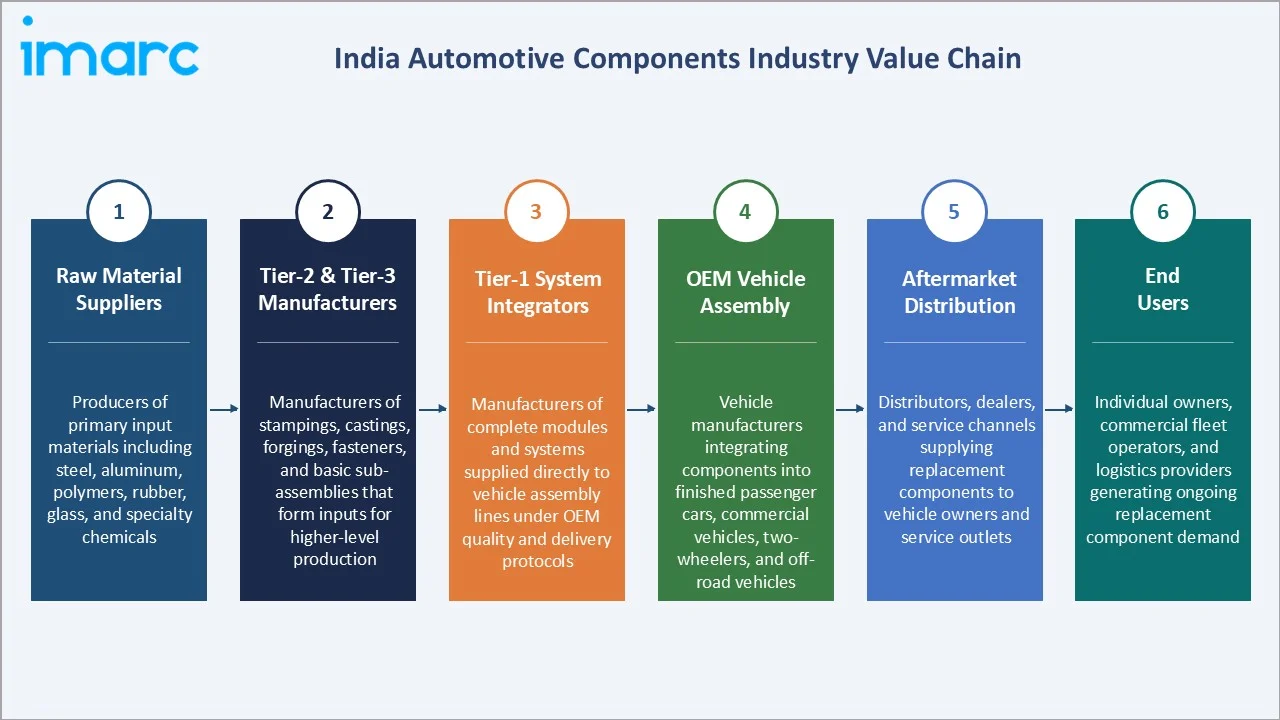
The India automotive components value chain is structured across six integrated stages from input materials through end-user vehicle operation. Each stage creates distinct value and serves as the foundation for the next, with the overall chain characterized by a large base of smaller manufacturers in the early stages transitioning toward more concentrated, technology-intensive suppliers at the system integration level closest to vehicle assembly.
|
Stage |
Key Participants |
|
Raw Material Suppliers |
Producers of primary input materials including steel, aluminum, polymers, rubber, glass, and specialty chemicals. |
|
Tier-2 & Tier-3 Manufacturers |
Manufacturers of stampings, castings, forgings, fasteners, and basic sub-assemblies that form inputs for higher-level production. |
|
Tier-1 System Integrators |
Manufacturers of complete modules and systems supplied directly to vehicle assembly lines under OEM quality and delivery protocols. |
|
OEM Vehicle Assembly |
Vehicle manufacturers integrating components into finished passenger cars, commercial vehicles, two-wheelers, and off-road vehicles. |
|
Aftermarket Distribution |
Distributors, dealers, and service channels supplying replacement components to vehicle owners and service outlets. |
|
End Users |
Individual owners, commercial fleet operators, and logistics providers generating ongoing replacement component demand. |
The Tier-1 system integration stage holds the greatest strategic significance within the value chain, as these manufacturers hold preferred vendor status with OEMs, manage the most complex manufacturing processes, and capture the highest per-unit value addition. Consolidation at this level is ongoing, driven by OEM preferences for fewer, more capable supply partners.
Technology Landscape in the India Automotive Components Industry
Electric Vehicle Powertrain Technology
Battery systems, electric motors, power electronics, and thermal management components represent the core technology categories driving the most significant investment in India's automotive component sector. Domestic manufacturers are building capabilities in battery assembly, permanent magnet motor production, and converter manufacturing, supported by government incentive schemes to accelerate local production and reduce reliance on imports.
Advanced Materials and Lightweighting
Component manufacturers are adopting high-strength steel variants, aluminum die-castings, and engineering polymer compounds to replace heavier conventional materials in body, chassis, and structural components, driven by regulatory requirements for improved fuel efficiency and emissions reduction.
Smart Manufacturing and Process Technology
Automated assembly systems, machine vision inspection, and real-time process monitoring are being adopted across the sector to improve quality consistency and meet demanding OEM defect and delivery performance standards, improving competitive positioning and enabling manufacturers to qualify for higher-tier supplier programs.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Vehicle Type |
Passenger Cars |
35.0% |
2025 |
|
Component |
Engine Parts |
28.0% |
2025 |
|
Demand Category |
OEM |
60.0% |
2025 |
|
Region |
North India |
31.0% |
2025 |

By Vehicle Type
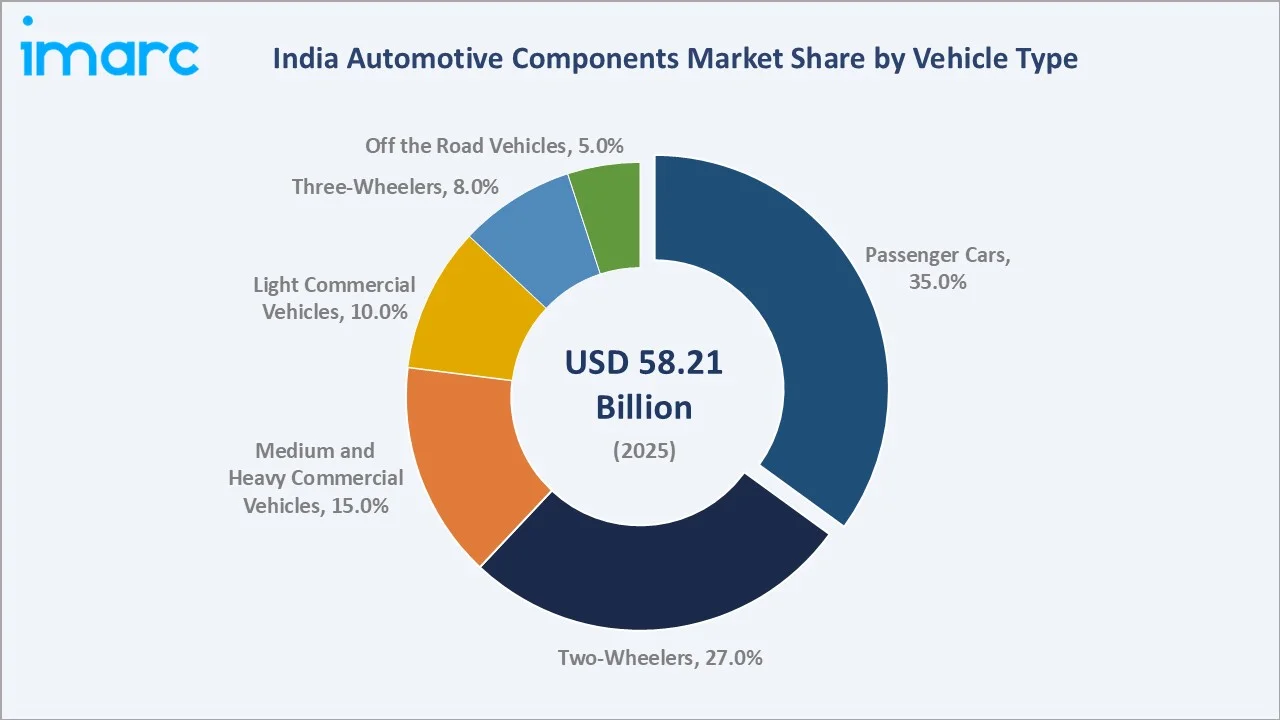
Passenger cars lead at 35.0% in 2025, supported by strong domestic consumer demand across price segments and continued OEM investment in Indian production facilities. The segment generates component demand across all major categories, including powertrain, body, safety, electronics, and interior systems.
To access detailed market analysis, Request Sample
Two-wheelers at 27.0% reflect the fundamental importance of this vehicle category to Indian mobility, with high production volumes generating large quantities of engine, body, suspension, and electrical component demand. Medium and heavy commercial vehicles at 15.0%, light commercial vehicles at 10.0%, three-wheelers at 8.0%, and off-road vehicles at 5.0% each serve distinct market needs and contribute to overall component demand diversity.
By Demand Category
OEM leads at 60.0% in 2025, driven by the consistent volume requirements of vehicle assembly operations that produce millions of vehicles annually across multiple facilities. The OEM channel is characterized by long-term supply relationships, standardized quality requirements, just-in-time delivery schedules, and pricing mechanisms that reward scale, quality certification, and supply reliability.
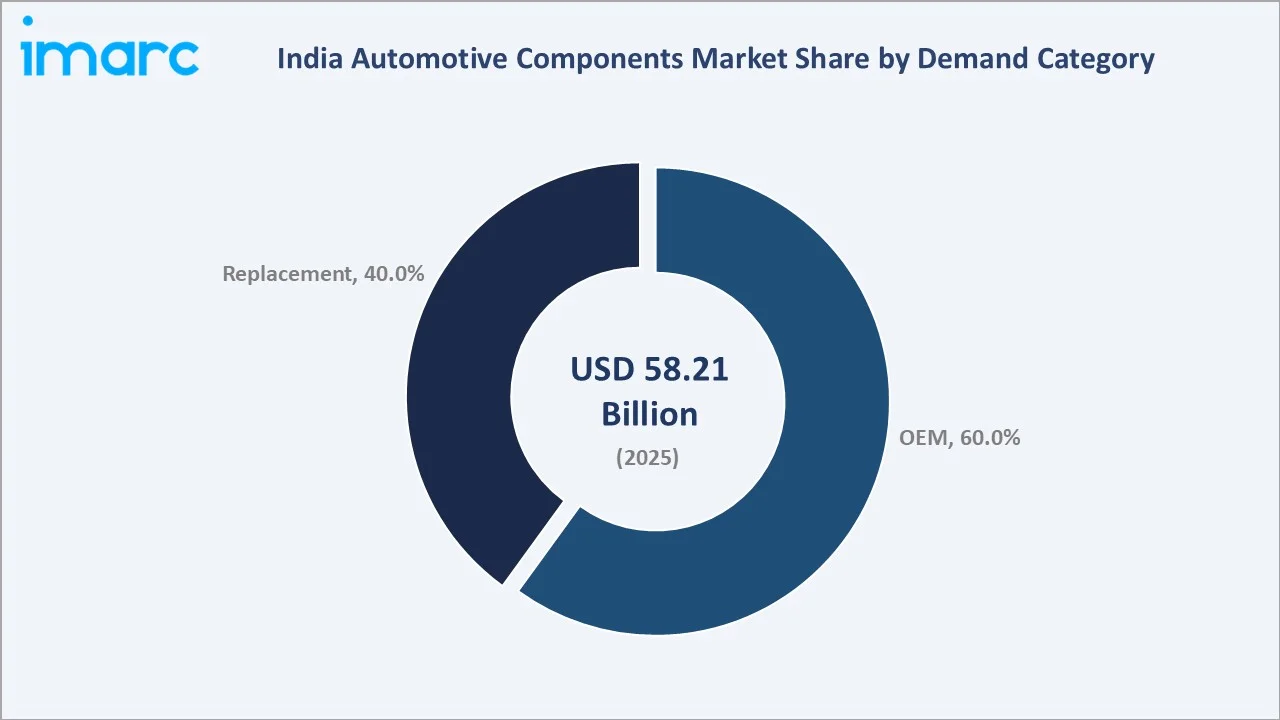
Replacement demand at 40.0% serves the large population of vehicles in operation across India, generating recurring purchasing activity across a wide range of component categories as vehicles age and require maintenance, repair, and parts replacement. The replacement channel is served through a combination of authorized dealer networks, independent distributors, retail parts outlets, and a growing e-commerce segment.
Regional Market Insights
|
Region |
Share (2025) |
Key India Automotive Components Market Drivers & Characteristics |
|
North India |
31.0% |
Reflecting the region's position as India's largest passenger car production hub, with a well-established ecosystem of component suppliers enabling efficient supply chain operations across the region. |
|
South India |
28.0% |
Reflecting a diversified automotive manufacturing base spanning passenger cars, two-wheelers, and commercial vehicles, supported by a large and capable supplier community across multiple states. |
|
West India |
25.0% |
Reflecting strong two-wheeler and commercial vehicle manufacturing activity, supported by a broad base of component manufacturers and proximity to key port infrastructure for export logistics. |
|
East India |
16.0% |
Reflecting a developing automotive manufacturing footprint, with ongoing investment in new manufacturing facilities and supplier ecosystems expected to grow the region's contribution over the forecast period. |
North India's 31.0% regional leadership reflects the concentration of passenger car manufacturing in this region, which generates the highest component demand volumes in the country and benefits from a mature supplier ecosystem that has developed around its vehicle assembly base, providing efficient and responsive supply chains.
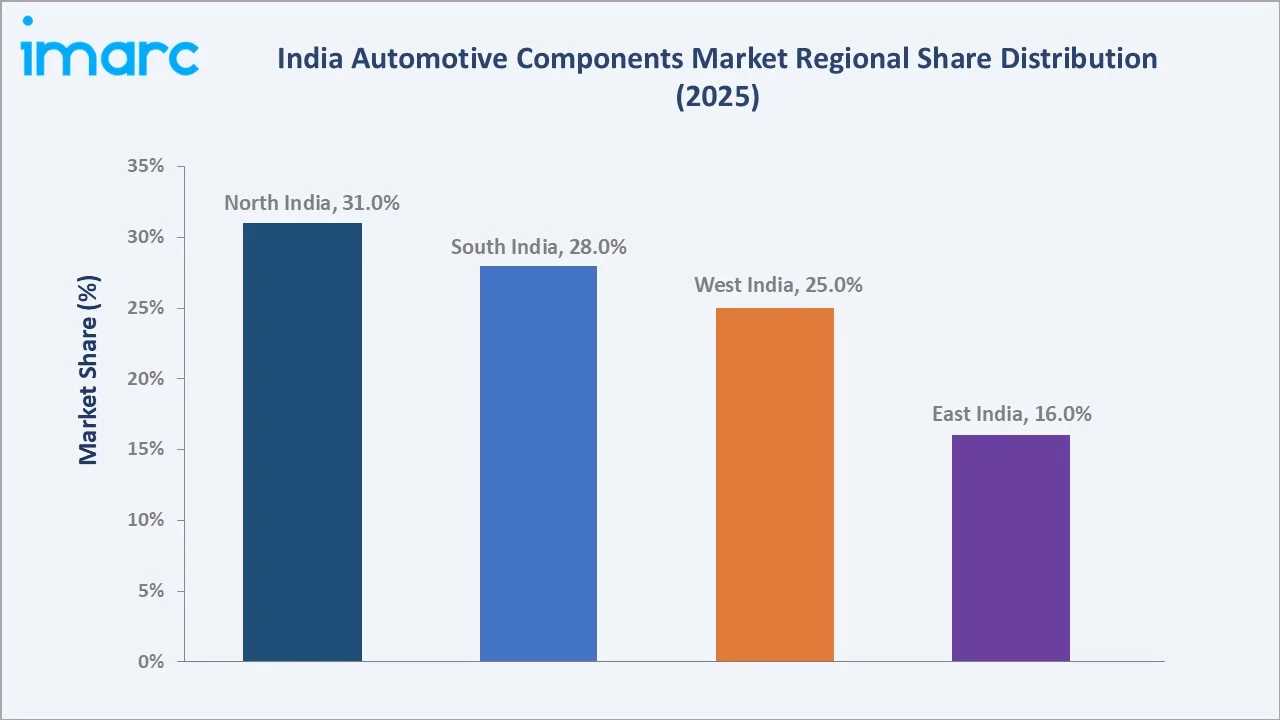
South India at 28.0% draws strength from a diverse manufacturing base across multiple states, creating broad demand across component categories. West India at 25.0% is anchored by its two-wheeler and commercial vehicle production activity and its strategic position for export-oriented manufacturing. East India at 16.0% represents a growing opportunity as new investment flows into automotive manufacturing in the region.
Competitive Landscape
The India automotive components market features a competitive landscape spanning large multinational Tier-1 suppliers alongside strong domestic manufacturers with leadership positions in specific product categories. Competition is driven by product quality, manufacturing scale, technology capability, OEM relationship depth, and cost competitiveness.
|
Company |
Key Offerings |
Market Position |
Core Strength |
|
Robert Bosch LLC |
ADAS, Air Conditioning, Brakes, Starters and Alternators, Batteries and Chargers, Steering Systems, Body Electronics |
Market Leader |
Robert Bosch GmbH plays a foundational and leading role in India's automotive components and mobility sector. |
|
Motherson Sumi Wiring India Limited |
Wiring harnesses |
Niche Player |
It serves as the dominant full-system solutions provider for original equipment manufacturers (OEMs) in the domestic wiring harness sector. |
|
Bharat Forge |
Chassis components, Engine, Transmission Components, Driveline Components |
Established Player |
Bharat Forge is India's largest exporter of auto components and a leading global manufacturer of safety-critical chassis and engine components. |
|
Uno Minda |
Automotive Lighting, Alloy Wheels, Automotive Switches, Automotive Horns, Seat Belts, Wheel Cover, Actuators |
Established Player |
Uno Minda is a leading Tier-1 manufacturer and supplier of advanced automotive systems and components, holding market leadership positions across India in core segments. |
|
EXIDE INDUSTRIES LTD. |
Four Wheeler Batteries, Three Wheeler Batteries, Two Wheeler Batteries, E-Rickshaw Batteries |
Innovator |
Exide Industries Ltd. is the largest automotive battery manufacturer in India and South Asia, powering a vast majority of the country's two-wheelers, passenger cars, commercial vehicles, and e-rickshaws. |
Companies across the competitive landscape are investing in EV component capabilities, advanced electronics, smart manufacturing, and export qualification. Market consolidation is expected to continue as OEMs favor fewer, more capable supply partners and as the technology requirements for emerging component categories create barriers that favor larger, better-resourced manufacturers.
Key Company Profiles
Robert Bosch LLC
Robert Bosch LLC is a prominent participant in the automotive components market, offering a diversified portfolio of mobility and automotive technology solutions. The company’s offerings span powertrain systems, vehicle electronics, braking technologies, sensors, software, and aftermarket components. Bosch serves major vehicle manufacturers as well as the automotive aftermarket through its manufacturing, engineering, and distribution capabilities. The company emphasizes localization, technological innovation, and product development to address evolving mobility requirements. Its operations also increasingly support electrification, connected mobility, and software-driven vehicle technologies.
- Key Offerings: ADAS, Air Conditioning, Brakes, Starters and Alternators, Batteries and Chargers, Steering Systems, Body Electronics.
- Strategic Focus: Expanding its product portfolio toward electric vehicle powertrain components and advanced electronics while maintaining its established position in conventional automotive components and growing its aftermarket and service business.
Motherson Sumi Wiring India Limited
Motherson Sumi Wiring India Limited is one of India's largest automotive wiring harness suppliers, serving major vehicle manufacturers across passenger car and commercial vehicle segments. The company operates a broad manufacturing network positioned near key OEM assembly plants to support just-in-time delivery and is expanding its capabilities to serve growing demand for high-voltage wiring systems in electric vehicles.
- Key Offerings: Wiring harnesses.
- Strategic Focus: Transitioning product mix progressively toward EV-specific wiring systems while sustaining its leadership in conventional harness supply and growing capacity to serve both domestic OEM demand and export-oriented programs.
Market Concentration Analysis
The India automotive components market is moderately fragmented at the sector level, with the top listed players collectively accounting for a significant share of organized sector revenue while a large base of smaller manufacturers serves regional OEM supply chains and the replacement market. The top five manufacturers by revenue command a combined share of approximately 15-16% of the total market, reflecting the inherent diversity of a sector spanning a wide range of component types, vehicle segments, and customer relationships.
Market concentration is higher within individual product categories, where leading suppliers often hold substantial shares of the organized domestic market. Fragmentation is most pronounced at the Tier-2 and Tier-3 levels, where thousands of smaller manufacturers supply sub-components to Tier-1 integrators and directly to OEMs for commodity component categories.
The trajectory of market concentration over the forecast period is expected to trend toward greater consolidation, driven by OEM supplier rationalization, capital and technology requirements for EV component manufacturing, and quality compliance standards that progressively raise the bar for participation in preferred supplier programs.
Investment & Growth Opportunities
Highest Growth Segments
Electric vehicle-specific component categories represent the highest-growth opportunity within the overall market, driven by government EV adoption targets and growing consumer interest in electric mobility. Advanced safety and electronics components represent the second major growth vector, supported by regulatory mandates. Organized aftermarket distribution through digital channels is also growing at above-market rates as the in-use vehicle parc expands.
Investment Themes
- EV Component Manufacturing Capability: Establishing domestic manufacturing capability in battery systems, electric motors, and power electronics positions manufacturers to capture growing demand as EV adoption increases, with early movers benefiting from preferred supplier relationships with EV manufacturers establishing their India production programs.
- Advanced Electronics and Safety Component Localization: The gap between domestic production capability and growing demand for automotive electronics, sensors, and ADAS components represents a significant opportunity for manufacturers investing in technology and quality capabilities to substitute imports across this growing market.
- Export-Oriented Precision Manufacturing: India's improving manufacturing competitiveness is generating demand from global OEMs seeking India-sourced components. Manufacturers investing in export-grade quality certifications and precision manufacturing are well positioned to capture incremental revenue as supply chain diversification strategies accelerate.
Future Market Outlook (2026-2034)
The India automotive components market is projected to grow from USD 58.21 Billion in 2025 to USD 60.53 Billion in 2026, reaching USD 82.67 Billion by 2034, exhibiting a CAGR of 3.97% during the forecast period. The market is expected to reach an intermediate milestone of approximately USD 70.73 Billion by 2030, as EV component demand becomes commercially significant and export growth begins contributing more meaningfully to overall sector revenue.
Three structural forces will define India's automotive component market through 2034. First, the progressive electrification of the vehicle fleet will reshape the composition of component demand, reduce the relative importance of conventional powertrain components while create large and growing demand for EV-specific categories. Second, the increasing technology content of vehicles across all segments, driven by safety regulations and connectivity requirements, will grow the electronics and software-related component opportunity substantially. Third, the ongoing development of India's manufacturing competitiveness and export infrastructure will support continued growth in automotive component exports, adding an incremental demand dimension that complements the domestic market and supports overall sector revenue growth through 2034.
Research Methodology
Primary Research
Primary research comprised structured interviews and consultations with automotive component manufacturing executives, vehicle OEM procurement and supply chain professionals, industry association representatives, policy experts, and aftermarket distribution channel participants. These discussions were used to validate market sizing estimates, assess competitive dynamics, identify key trends and drivers, and gather forward-looking perspectives on market evolution through the forecast period.
Secondary Research
Secondary research drew on published data from industry associations, government statistical sources, vehicle production and sales reports, company annual reports and investor presentations, trade publications, and relevant regulatory documents. Historical market data were cross-referenced across multiple sources to ensure accuracy and consistency of baseline market estimates.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling approaches incorporating historical sector growth trends, vehicle production volume projections by segment, OEM content-per-vehicle assumptions, replacement market vehicle parc expansion estimates, EV adoption rate scenarios, export growth projections, and broader macroeconomic indicators. Scenario analysis was applied to account for uncertainty in key assumptions.
India Automotive Components Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Vehicle Types Covered | Passenger Cars, Two-Wheelers, Three-Wheelers, Light Commercial Vehicles, Medium and Heavy Commercial Vehicles, Off the Road Vehicles |
| Components Covered | Engine Parts, Body and Chassis, Suspension and Brakes, Drive Transmission and Steering Parts, Electrical Parts and Equipments |
| Demand Categories Covered | OEM, Replacement |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Robert Bosch LLC, Motherson Sumi Wiring India Limited, Bharat Forge, Uno Minda, EXIDE INDUSTRIES LTD., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Frequently Asked Questions About the India Automotive Components Market Report
The India automotive components market reached USD 60.53 Billion in 2026, driven by rising domestic vehicle production, manufacturing investment, and growing automotive exports.
The market is projected to grow at a CAGR of 3.97% during 2026-2034, supported by vehicle production growth, EV component demand, advanced safety technology adoption, and expanding automotive exports.
The market is projected to reach approximately USD 70.73 Billion by 2030, driven by growing EV component production, expanding export revenues, and sustained domestic vehicle demand across all segments.
Passenger cars lead with a 35.0% share in 2025, reflecting strong domestic consumer demand, a wide model range across price segments, and sustained OEM production investment in India.
OEM leads with a 60.0% share in 2025, driven by the high-volume component requirements of vehicle assembly operations producing vehicles for domestic and export markets.
North India leads with a 31.0% share in 2025, reflecting its position as the country's largest passenger car production region supported by a well-developed Tier-1 and Tier-2 supplier ecosystem.
Key players include Robert Bosch LLC, Motherson Sumi Wiring India Limited, Bharat Forge, Uno Minda, and EXIDE INDUSTRIES LTD., among others.
The market is projected to reach USD 82.67 Billion by 2034, driven by sustained vehicle production growth, EV component scaling, expanding export revenues, and growing electronics content per vehicle from safety technology adoption.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade