
India Cable Accessories Market Size, Share, Trends and Forecast by Voltage, Installation, End User, and Region, 2026-2034
India Cable Accessories Market Size, Share, Trends & Forecast (2026-2034)
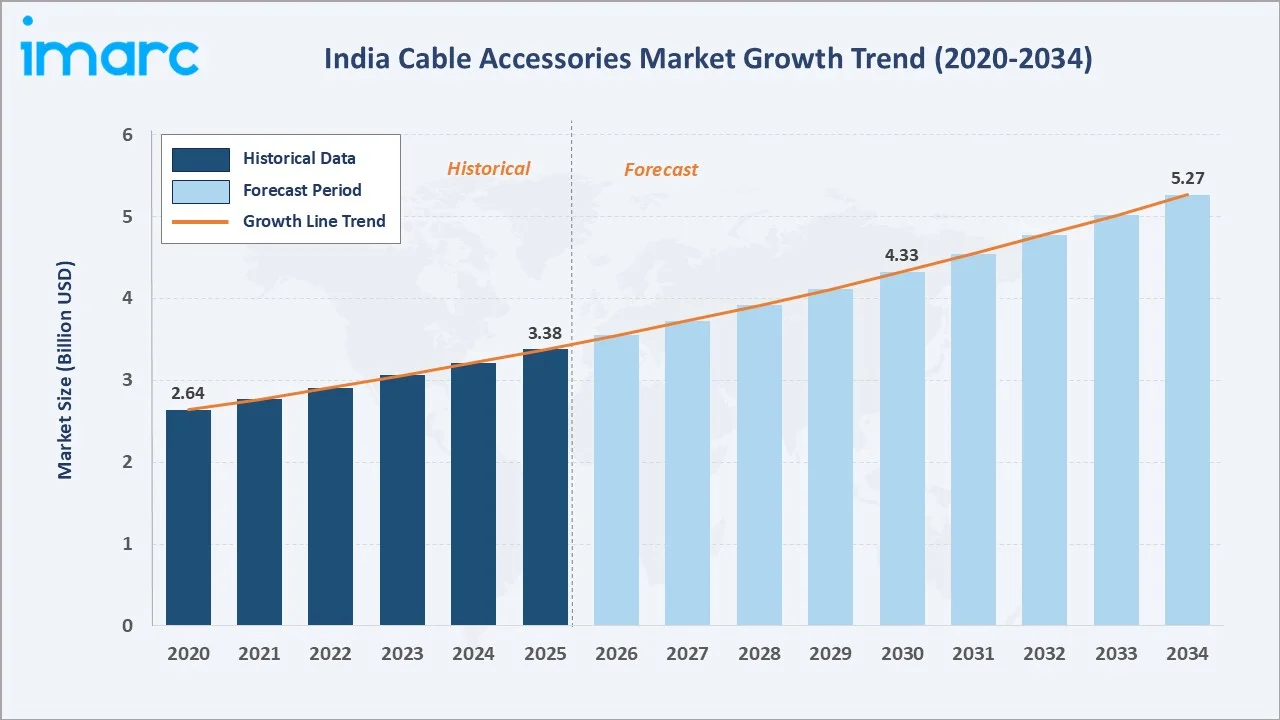
The India cable accessories market reached USD 3.38 Billion in 2025 and is projected to reach USD 5.27 Billion by 2034, growing at a CAGR of 5.04% during 2026-2034. The market is driven by rapid power grid expansion, massive renewable energy capacity addition, and urban infrastructure underground cabling programs. India’s non-fossil fuel-based installed electricity generation capacity surpassed 300 GW as of July 31, 2026, accounting for more than 60% of the country’s 500 GW target for 2030. The rapid addition of renewable generation capacity is driving the market by increasing the deployment of transmission and distribution networks required to connect solar, wind, hydro, and other clean-energy projects to the grid. Low voltage cable accessories lead at 45.8%. Overhead cable accessories lead installation at 56.9%. South India leads regionally at 34.2%.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 3.38 Billion |
|
Forecast Market Size (2034) |
USD 5.27 Billion |
|
CAGR (2026-2034) |
5.04% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Voltage |
Low Voltage Cable Accessories (45.8%, 2025) |
|
Dominant Installation |
Overhead Cable Accessories (56.9%, 2025) |
|
Leading Region |
South India (34.2%, 2025) |
The India cable accessories market has demonstrated steady growth, increasing from USD 2.64 Billion in 2020 to USD 3.38 Billion in 2025, reflecting expanding power infrastructure investment and accelerating renewable energy integration. The market is projected to reach USD 4.33 Billion by 2030 and further grow to USD 5.27 Billion by 2034, supported by India's ambitious 500 GW non-fossil fuel capacity target and growing urban underground cabling mandates.
To get more information on this market, Request Sample
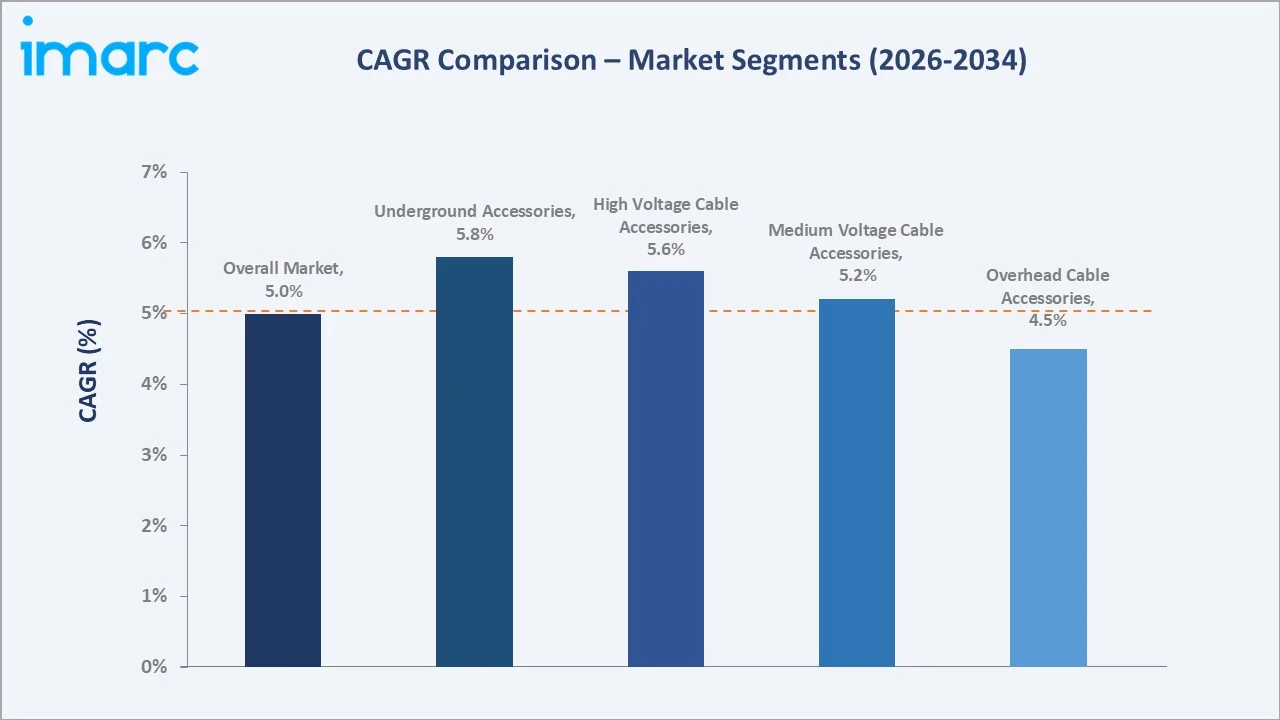
Underground accessories lead the segment CAGR at ~5.8% through expanding urban underground cabling programs and metro rail networks. High voltage cable accessories grow at ~5.6% CAGR through HVDC transmission lines and renewable energy evacuation corridors. Medium voltage cable accessories grow at ~5.2% CAGR through RDSS distribution network modernization.
Executive Summary
The India cable accessories market is witnessing robust growth, supported by the government's transformative investments in power transmission and distribution infrastructure, aggressive renewable energy capacity targets, and expanding urban electrification programs. Cable accessories, including cable joints, cable terminations, connectors, lugs, and cable glands, serve as critical safety and continuity components in electrical networks across low, medium, and high voltage systems.
Low voltage cable accessories lead at 45.8% through sheer volume in building and industrial applications. Overhead cable accessories lead at 56.9% installation through existing rural distribution network dominance. South India leads at 34.2% through its large renewable energy installed base and expanding manufacturing sector.
Key Market Insights
|
Insight |
Data |
|
Dominant Voltage |
Low Voltage Cable Accessories – 45.8% share (2025) |
|
Leading Installation |
Overhead Cable Accessories – 56.9% market share (2025) |
|
Leading Region |
South India – 34.2% share (2025) |
|
Market Opportunity |
500 GW non-fossil fuel capacity evacuation accessories; RDSS distribution network upgrade; urban underground cabling programs; HVDC transmission accessories; EV charging infrastructure accessories |
Key Analytical Observations Supporting the Above Data:
- Low Voltage Cable Accessories at 45.8%: Low voltage cable accessories, including cable glands, lugs, connectors, terminal blocks, and heat shrink joints for ≤1kV applications, dominate by share due to their pervasive application across industrial, commercial, and residential electrical systems.
- Overhead Cable Accessories at 56.9%: Overhead accessories, including overhead line connectors, suspension clamps, strain clamps, vibration dampers, and aerial bundled cable (ABC) accessories, lead the installation type due to India's extensive existing overhead rural distribution network and distribution lines.
- South India at 34.2%: South India leads due to the region's concentrated renewable energy installed base, combined with the region's dense industrial manufacturing base in Tamil Nadu and Karnataka, generating intensive low-voltage accessories demand.
India Cable Accessories Market Overview
The India cable accessories market encompasses hardware and components used to connect, terminate, protect, and route electrical cables across power transmission and distribution networks, industrial electrical systems, and building wiring infrastructure. Product categories include cable joints (straight-through joints, branch joints), cable terminations (outdoor, indoor, plug-in terminations), cable lugs and connectors, cable glands and cable cleats, overhead line fittings (suspension clamps, strain clamps, connectors), and specialty accessories for HVDC systems. The market serves power utilities including renewable energy developers, industrial manufacturers, EPC contractors, railway electrification projects, and building infrastructure programs.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
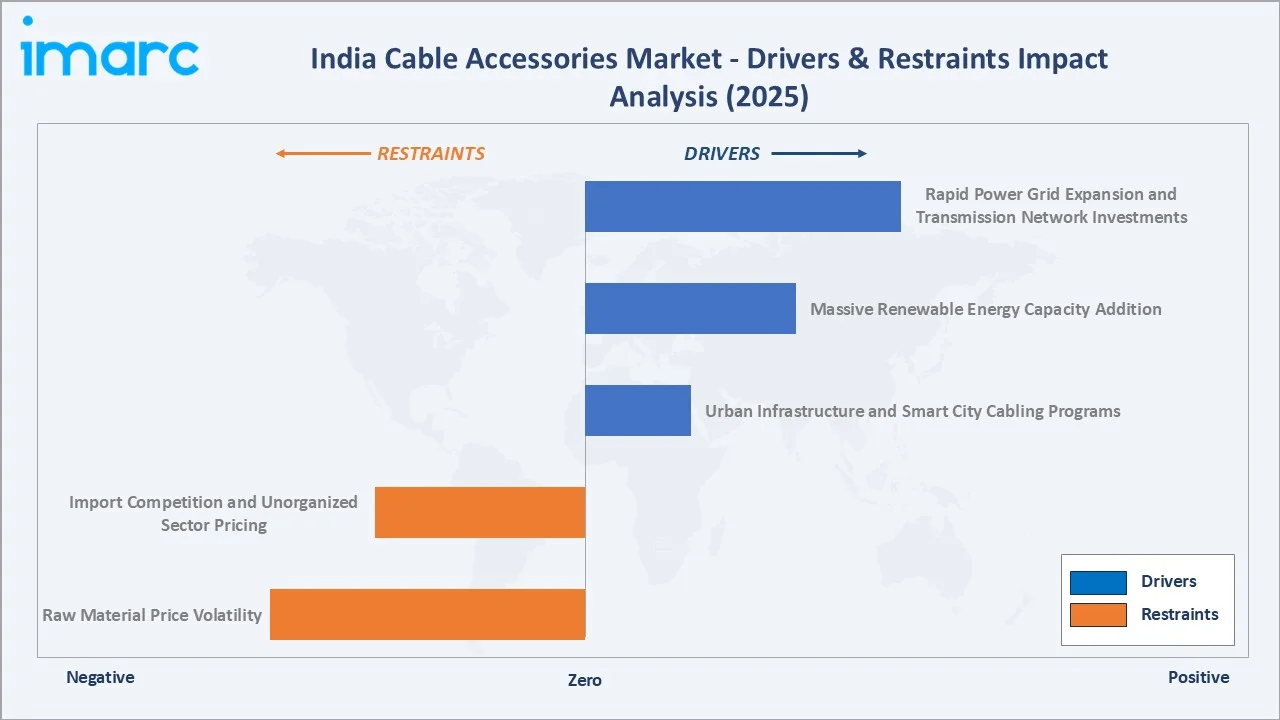
- Rapid Power Grid Expansion and Transmission Network Investments: Under the National Electricity Plan (Transmission) plan, the transmission network is expected to increase from 5.09 lakh circuit kilometers (ckm) in June 2026 to 6.48 lakh ckm by 2032, while transformation capacity is projected to rise from 1,478 GVA to 2,345 GVA. In addition, the country’s inter-regional transmission capacity is planned to expand from 120 GW in June 2026 to 168 GW by 2032, directly driving demand for high-voltage cable joints, terminations, and overhead line accessories across new transmission corridors. Each transmission line addition requires thousands of cable accessories at substation termination points and intermediate joints.
- Massive Renewable Energy Capacity Addition: India's 500 GW non-fossil energy target by 2030 is creating unprecedented demand for cable accessories at solar park collection networks, wind farm array cables, and substation integration points. Solar parks require medium-voltage cable accessories for inter-string connections and string combiner boxes, while offshore wind development creates specialized subsea cable accessories demand.
- Urban Infrastructure and Smart City Cabling Programs: The installation of more than 84,000 CCTV cameras across 100 Smart Cities under India’s Smart Cities Mission is increasing demand for reliable power and data connectivity infrastructure. The expansion of surveillance networks supports higher consumption of cable connectors, joints, glands, terminations, and other accessories required for secure and continuous operation of CCTV and smart-city systems.
Market Restraints
- Raw Material Price Volatility: Cable accessories incorporate copper conductors, XLPE insulation, silicone rubber components, and specialized polymer compound whose prices are subject to significant global commodity market volatility. Copper prices create significant manufacturing cost variability that complicates pricing for long-term project contracts. XLPE and silicone prices are sensitive to petrochemical feedstock costs that amplify margin pressure during commodity upswings.
- Import Competition and Unorganized Sector Pricing: India's cable accessories market faces competition from imports at significantly lower price points for standard low-voltage accessories. The unorganized domestic sector additionally produces non-certified accessories at discounts to organized sector pricing, winning price-sensitive procurement in rural distribution projects where technical specification enforcement is inconsistent. This pricing dynamic limits organized sector volume growth in rural and semi-urban project markets.
Market Opportunities
- HVDC Transmission Accessories for Long-Distance Renewable Energy Evacuation: India's Green Energy Corridors Phase II (INR 12,031 Crore) and HVDC transmission lines planned for evacuating renewable energy to consumption centers in North and South India create significant demand for specialized HVDC cable accessories, including HVDC cable joints, sealing ends, and transition accessories, that command premium pricing over equivalent AC accessories and require advanced manufacturing capabilities currently dominated by global suppliers.
- EV Charging Infrastructure Cable Accessories: India's growing EV charging network requires fast charging cable accessories including high-current DC cable glands, connectors, and flexible conduit systems that are technically distinct from standard AC power accessories. EV charging installation programs create distributed demand across retail, commercial, and highway locations for specialized cable accessories that organized domestic manufacturers can develop to reduce import dependence.
Market Challenges
- Technical Specification Compliance and Quality Infrastructure: High-voltage cable accessories require stringent regulatory certification and approval for use in national grid installations. The certification and testing infrastructure creates capacity bottlenecks for new product approval, with HV product certification timelines extending 12-24 months. Smaller manufacturers struggle to bear certification costs for specialized product lines serving limited project volumes.
- Skilled Installation Workforce Gap: Proper cable jointing and termination quality is critically dependent on skilled jointing technicians whose work directly impacts network reliability. India faces a shortage of certified cable jointing technicians, particularly for medium and high voltage applications, creating quality assurance challenges in distributed project execution environments. Improper joint installation is a leading cause of cable network failures in India, creating long-term reliability concerns that sophisticated utilities address through certified jointing contractor programs.
Emerging Market Trends
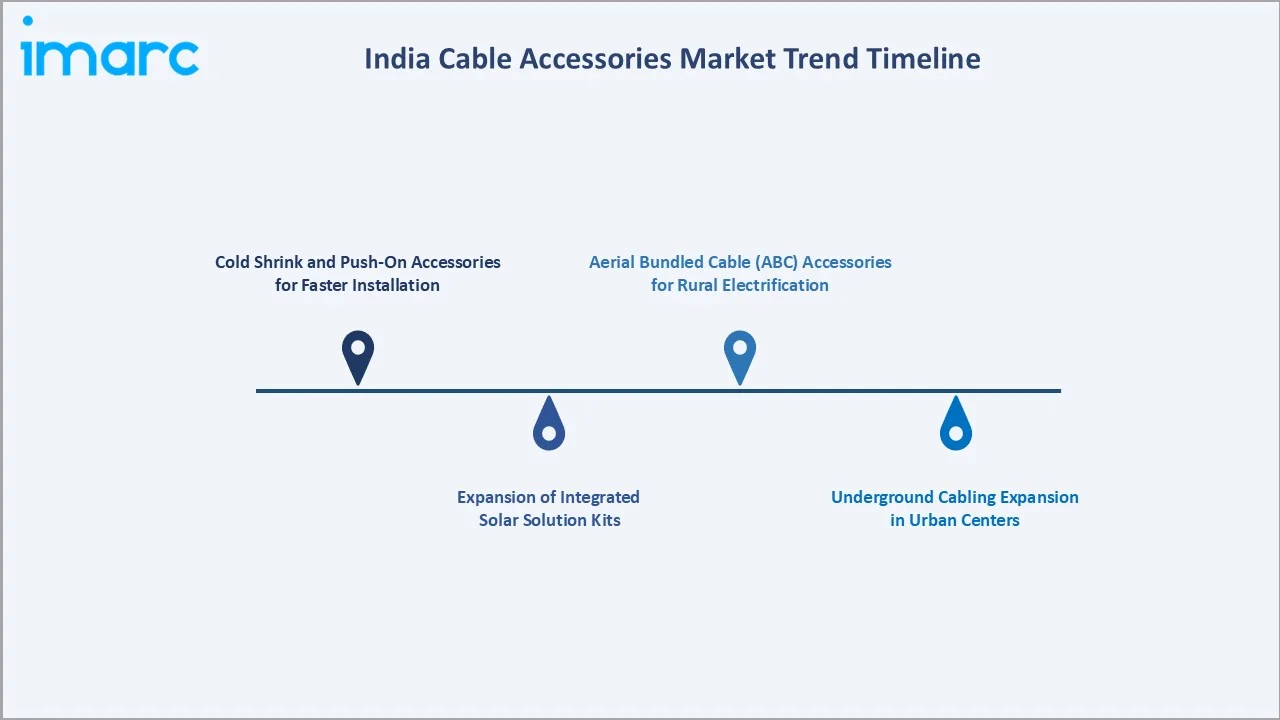
1. Cold Shrink and Push-On Accessories for Faster Installation
Cold shrink cable accessories, pre-expanded polymer tubes that self-contract around cable termination points without requiring heat sources, are gaining adoption in India's cable accessories market as utilities and contractors seek to reduce installation time, eliminate heat source safety risks, and enable jointing in wet or confined environments. Leading suppliers are expanding cold shrink product portfolios for medium voltage applications where underground cable deployment is creating high-volume demand for reliable, installation-quality-independent accessories.
2. Expansion of Integrated Solar Solution Kits
In November 2025, Polycab India Limited introduced its new Polycab Solar Kits at the Renewable Energy India (REI) Expo 2025. Designed for residential, commercial, and rural applications, the kits provide an integrated solar power solution comprising high-efficiency grid-tie inverters, solar cables, AC/DC distribution boxes, earthing kits, connectors, and lugs. The launch highlights a growing shift toward bundled, ready-to-install solar solutions that combine inverters, cables, distribution boxes, connectors, lugs, and other accessories in a single package. This trend is supporting demand for standardized cable accessories while simplifying solar adoption across residential, commercial, and rural applications.
3. Aerial Bundled Cable (ABC) Accessories for Rural Electrification
The shift from bare conductor overhead lines to aerial bundled conductor (ABC) systems under rural electrification and distribution modernization programs is driving demand for specialized ABC accessories, AB cable connectors, ABC cable clamps, piercing connectors, and ABC joints, distinct from traditional overhead line fittings. ABC adoption reduces pilferage, improves safety, and enables branch connections without line interruption, with ABC accessories becoming standard specification items in Saubhagya and RDSS rural distribution projects across India.
4. Underground Cabling Expansion in Urban Centers
State utility urban underground cabling mandates are accelerating the shift from overhead to underground distribution. Underground cable accessories for XLPE cables, including straight-through joints, T-branch joints, and heat-shrink terminations, are seeing volume growth significantly exceeding the overall market growth rate. Cold shrink and push-on accessories for underground urban networks are preferred for speed of installation and reduced skill sensitivity.
Industry Value Chain Analysis
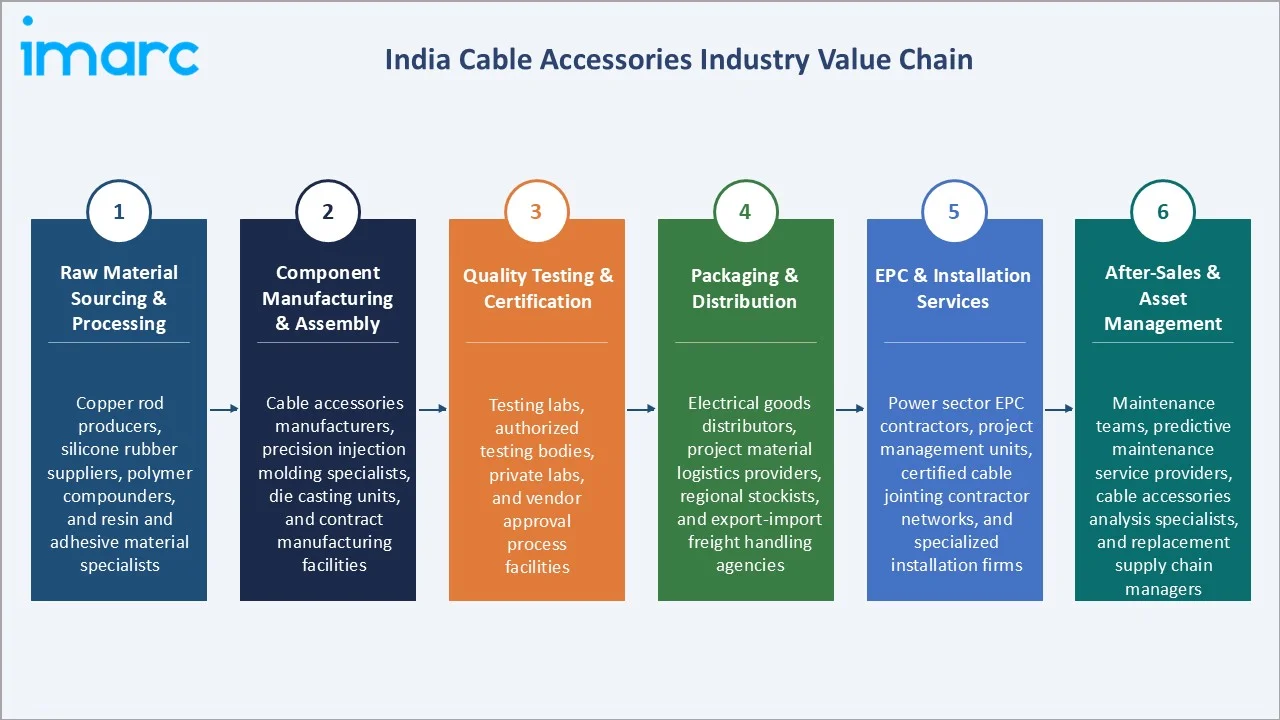
The India cable accessories market value chain integrates raw material sourcing and processing, component manufacturing and assembly, quality testing and certification, packaging and distribution, EPC and installation services, and after-sales and asset management.
|
Stage |
Key Participants |
|
Raw Material Sourcing & Processing |
Copper rod producers, silicone rubber suppliers, polymer compounders, and resin and adhesive material specialists. |
|
Component Manufacturing & Assembly |
Cable accessories manufacturers, precision injection molding specialists, die casting units, and contract manufacturing facilities. |
|
Quality Testing & Certification |
Testing labs, authorized testing bodies, private labs, and vendor approval process facilities. |
|
Packaging & Distribution |
Electrical goods distributors, project material logistics providers, regional stockists, and export-import freight handling agencies. |
|
EPC & Installation Services |
Power sector EPC contractors, project management units, certified cable jointing contractor networks, and specialized installation firms. |
|
After-Sales & Asset Management |
Maintenance teams, predictive maintenance service providers, cable accessories analysis specialists, and replacement supply chain managers. |
Quality testing and certification represent the most critical value chain stage for premium cable accessories, as certification and technical approval are mandatory for grid-connected applications and directly determine product eligibility for the highest-value transmission and distribution project procurement.
Technology Landscape in the India Cable Accessories Industry
Heat Shrink and Cold Shrink Accessories Technology
Heat shrink cable accessories, such as polymer-based tubes, molded parts, and breakout boots that contract and seal around cable insulation when heated, remain the dominant technology for cable terminations and joints across low and medium voltage applications in India. Cold shrink technology, where pre-expanded silicone rubber components self-contract around cable ends without any heat source, is gaining rapid adoption in urban underground cabling projects where safety regulations restrict open-flame tools in confined underground spaces and manholes.
Pre-Molded and Plug-In Cable Accessories Technology
Pre-molded cable accessories, factory-produced elastomeric silicone or EPDM components with integrated geometric stress control, semi-conductive screen, and outer insulation layers, deliver the highest quality consistency by eliminating field-applied stress control and sealing layers that are susceptible to installation quality variability. Plug-in separable connectors and elbow terminations for switchgear and ring main unit interfaces enable tool-free, live-line connection and disconnection for compact modular switchgear and package substation integration.
HVDC and Advanced High Voltage Accessories Technology
High voltage direct current (HVDC) cable accessories, including DC-rated cable joints, sealing ends, and transition accessories for transmission systems, represent the most technically demanding and highest-value segment of India's cable accessories market, currently predominantly supplied by global specialists at a pricing premium over equivalent AC cable accessories. India's planned HVDC transmission corridors require type-tested HVDC accessories that comply with specialized DC dielectric stress control requirements distinct from AC system designs.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Voltage |
Low Voltage Cable Accessories |
45.8% |
2025 |
|
Installation |
Overhead Cable Accessories |
56.9% |
2025 |
|
End User |
Industrial |
🔒 |
2025 |
|
Region |
South India |
34.2% |
2025 |

By Voltage
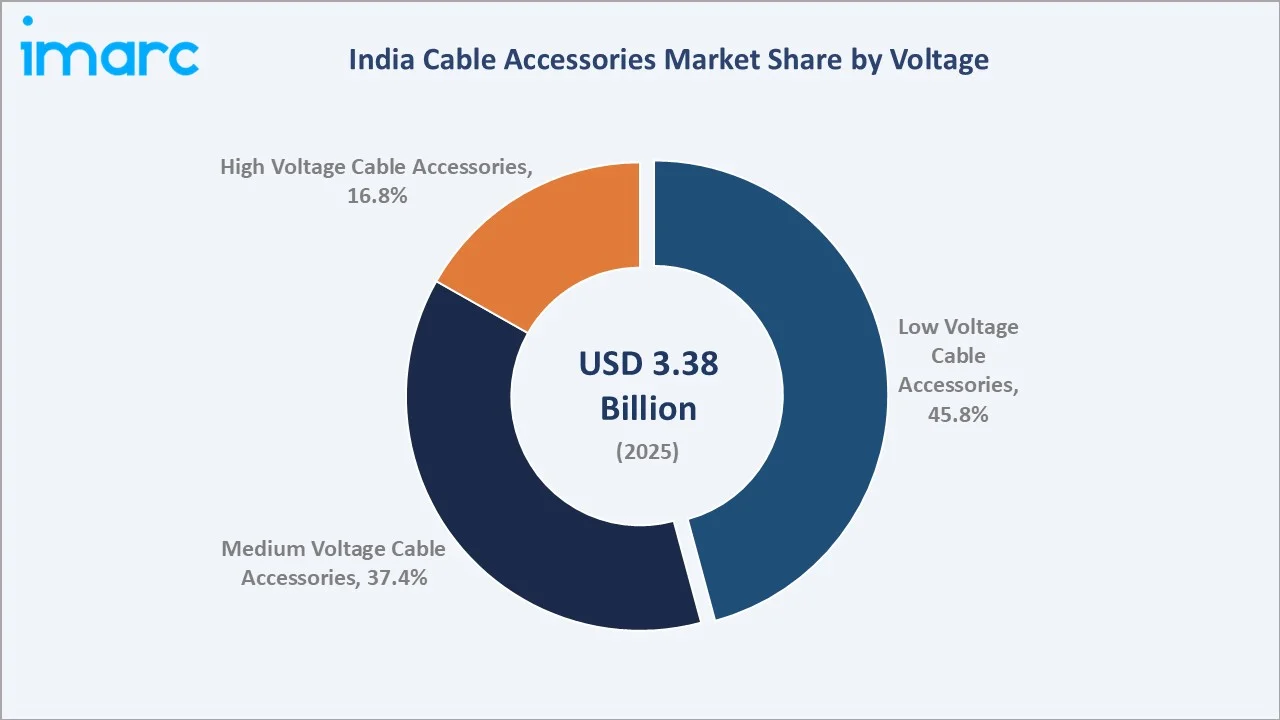
Low voltage cable accessories lead at 45.8% (2025), driven by the pervasive application of low-voltage accessories across industrial, commercial, and residential electrical systems in India's growing economy. Cable glands, lugs, connectors, terminal blocks, and heat shrink tubes serve the largest base of electrical installations and benefit from both new construction and maintenance replacement demand cycles.
To access detailed market analysis, Request Sample
Medium voltage cable accessories account for 37.4% (2025), serving distribution network applications and renewable energy collection systems, the most actively invested voltage segment under RDSS and renewable energy programs. High voltage cable accessories represent 16.8% (2025), growing fastest at ~5.6% CAGR through HVDC transmission and transmission network expansion programs.
By Installation
Overhead cable accessories lead at 56.9% (2025), reflecting India's large existing overhead distribution and transmission infrastructure, requiring consistent maintenance accessories supply and rural electrification extension. Suspension clamps, strain clamps, vibration dampers, and ABC accessories serve both new line construction and maintenance replacement demand.
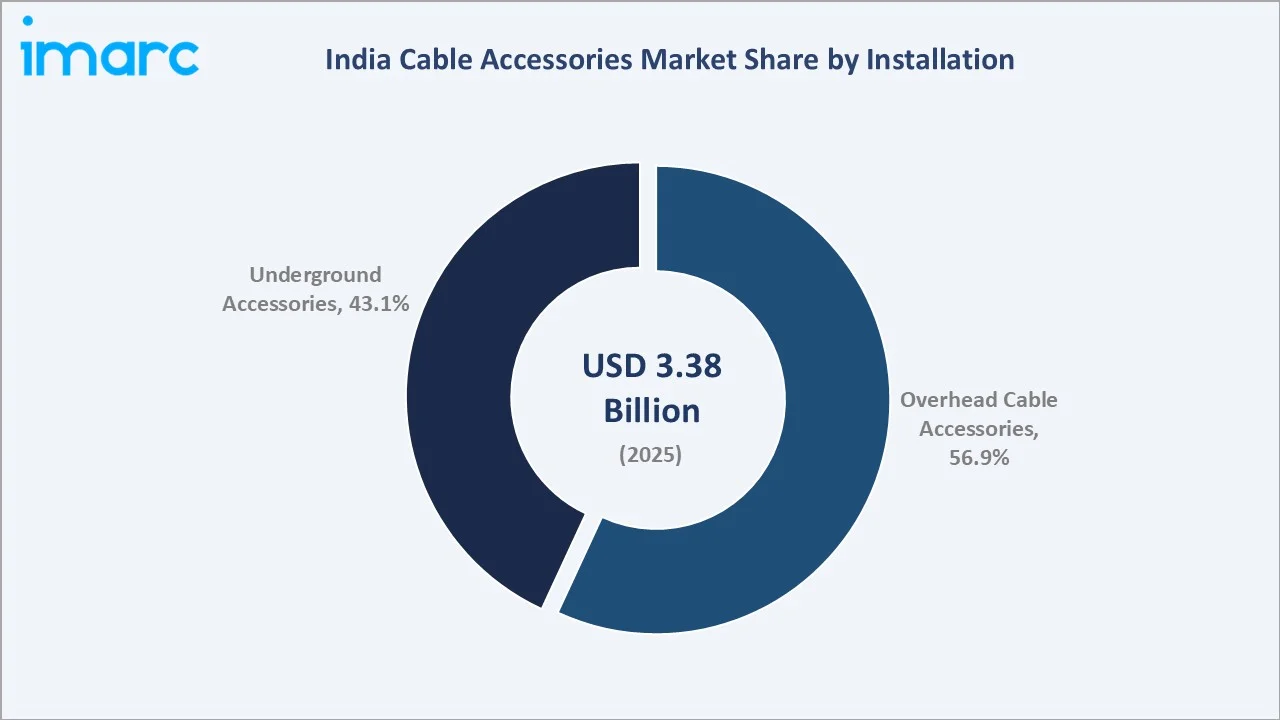
Underground accessories account for 43.1% (2025) and grow at the fastest CAGR of ~5.8%, driven by urban underground cabling mandates, RDSS distribution network upgrades replacing overhead with underground cables, and metro rail and airport infrastructure projects where overhead cables are operationally infeasible. Underground accessories include heat shrink and cold shrink cable joints, cable terminations, cable cleats, and conduit accessories.
Regional Market Insights
|
Region |
Share (2025) |
Key India Cable Accessories Market Drivers & Characteristics |
|
South India |
34.2% |
Largest market driven by Tamil Nadu and Andhra Pradesh's massive wind and solar energy installed base requiring medium-voltage collection accessories. |
|
West & Central India |
29.8% |
Strong market anchored by Rajasthan's world-scale solar parks requiring large-volume cable accessories for string connections and evacuation lines. |
|
North India |
22.4% |
Growing market driven by Delhi NCR's underground cabling and metro rail projects, Punjab and Haryana's agricultural feeder separations. |
|
East India |
13.6% |
Emerging market with West Bengal's industrial sector, Odisha's mining and power generation expansion, Jharkhand's heavy industry electrification. |
South India's 34.2% market leadership reflects the region's dual advantage of being both India's largest renewable energy producer and one of India's most industrialized regions, with manufacturing corridors in Tamil Nadu, Karnataka, and Telangana generating intensive low-voltage accessories demand. West and Central India's 29.8% is driven by Rajasthan's world-scale solar parks and Gujarat's rapidly growing renewable energy and industrial sector.
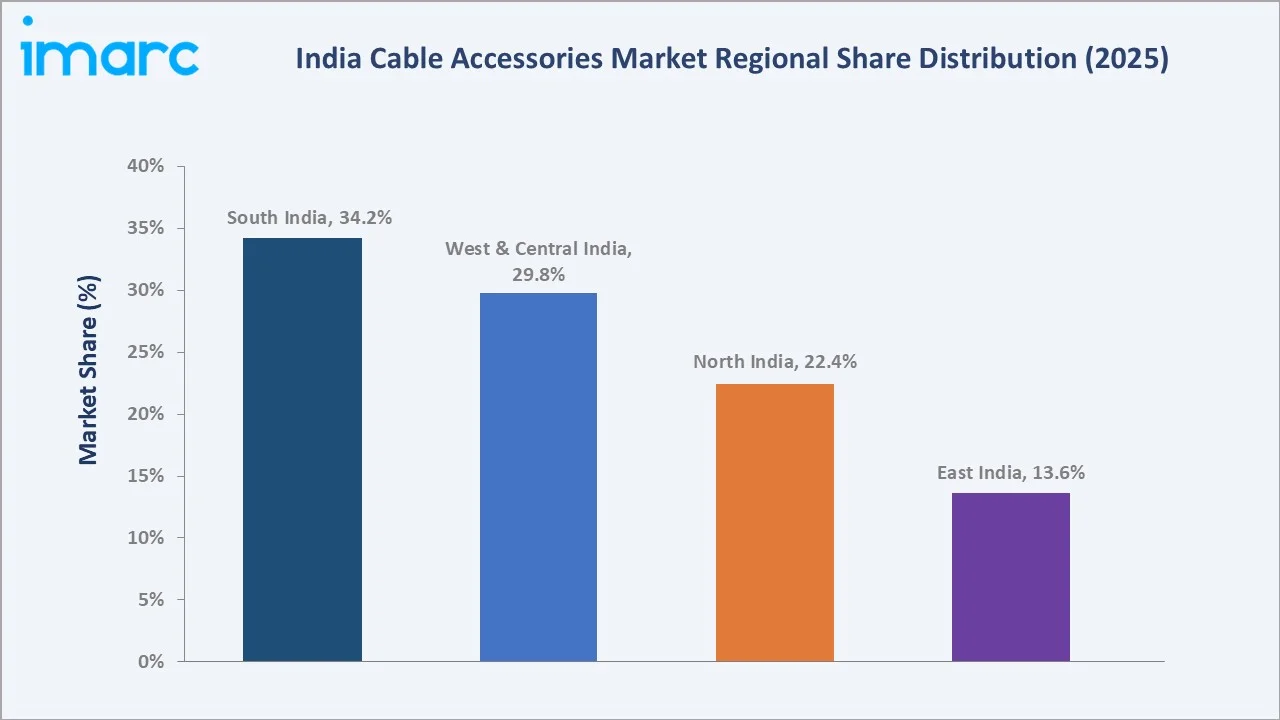
North India at 22.4% benefits from Delhi NCR's underground cabling programs, the industrial corridor, and planned Green Energy Corridors bringing Rajasthan and Ladakh renewable energy through North India. East India at 13.6% represents a growing opportunity, with Odisha and West Bengal's expanding industrial investment and planned HVDC transmission links to consume Eastern India generation creating structured cable accessories demand through the forecast period.
Competitive Landscape
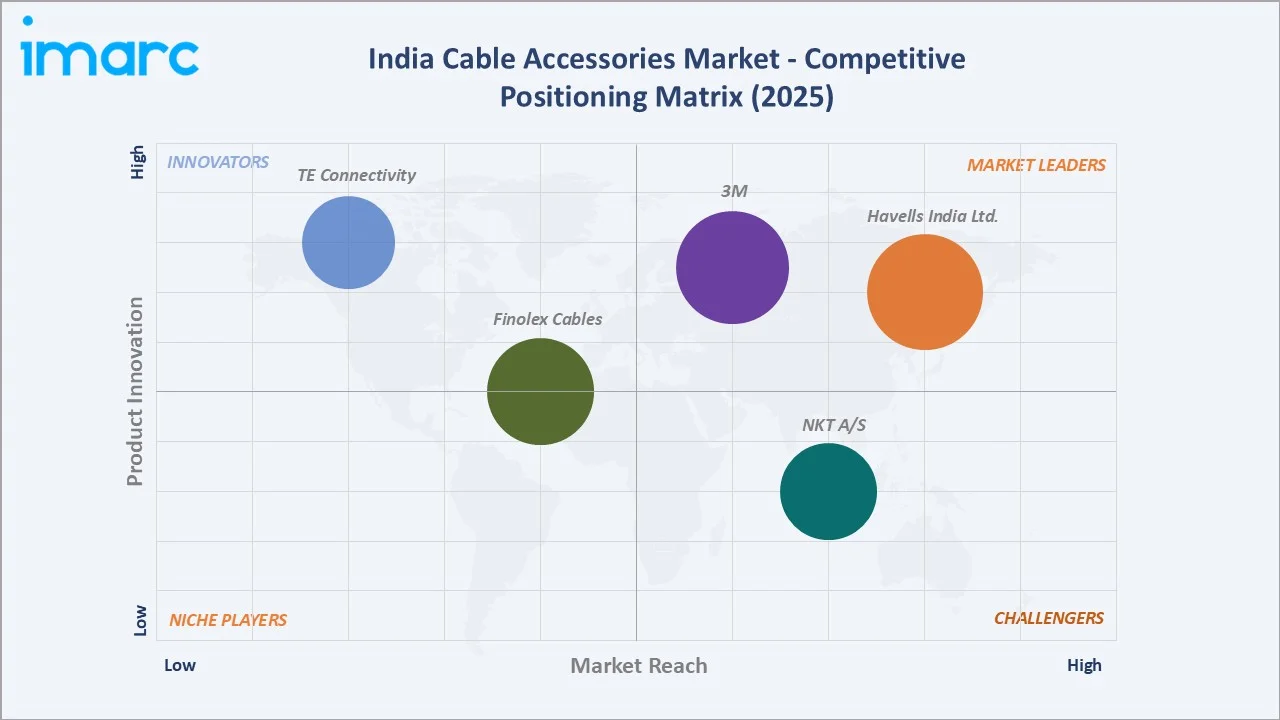
The India cable accessories market is moderately concentrated among organized manufacturers, with a large unorganized sector competing on price in standard low-voltage applications. Market participants compete on product certification credentials, voltage range coverage, installation support quality, distributor and EPC contractor network depth, and technical after-sales service capability.
|
Company |
Key Products |
Market Position |
Core Strength |
|
Havells India Ltd. |
Lifesavior Plug 16 A, 6 A 3 Pin Plugtop, 16 A 3 Pin Plugtop, 6 A 3 Pin Plugtop with Indicator, 16 A Plugtop With Indicator |
Market Leader |
Havells India Ltd. plays a major role in India's cable accessories market through extensive domestic manufacturing, high safety standards, and a vast distribution network. |
|
3M |
Power Cable Terminations, Compression Lugs, Separable Connectors, Cold Shrink Splices, Heat Shrink Splices, Grounding Connectors |
Market Leader |
3M plays a major role with a broad range of low- and medium-voltage cable accessories in India to terminate, splice, and seal power cables efficiently. |
|
Finolex Cables |
6A 2 Pin Top, 6A 3 Pin Top, 16A 3 Pin Top, Spikeguard 1.5Mtr 4*1 Universal, Angle Holder, 4.5 Inch Round Plate, 32A Surface DP Switch, 2 Pin Multiplug |
Established Player |
Finolex Cables is a leading manufacturer in India's cable industry, providing essential conduits, rigid PVC fittings, and electrical accessories that complement its core wiring and cabling portfolios. |
|
NKT A/S |
High Voltage Cable Accessories (52-550 kV), Medium Voltage Cable Accessories (12-42 kV) |
Challenger |
NKT A/S supplies high-end cable accessories up to 550 kV to support India's power transmission, distribution, and green energy transition. |
|
TE Connectivity |
Duct Seals, Joints & Splices, Power Cable Breakouts, Power Cable End Caps, Power Cable Heat Shrink Tubing, Power Cable Terminations, Power Cable Wraps |
Innovator |
TE Connectivity provides essential power cable accessories, joints, terminations, and heat shrink tubing to support India's growing energy, industrial, and infrastructure grids |
Companies are also investing in certification expansion for new product categories, cold shrink technology adoption, renewable energy-specific product development, and HVDC accessories type testing to differentiate in India's evolving cable accessories market. Progressive consolidation through product line expansion and acquisition of specialty capabilities is expected as market segments become increasingly technically demanding.
Key Company Profiles
Havells India Ltd.
Havells India Ltd. is a prominent electrical equipment and consumer electricals company with a diversified portfolio spanning cables and wires, switchgear, lighting, power distribution products, and related accessories. In the India cable accessories market, the company benefits from its broad distribution network, established brand presence, and participation across residential, commercial, industrial, and infrastructure applications.
- Key Products: Lifesavior Plug 16 A, 6 A 3 Pin Plugtop, 16 A 3 Pin Plugtop, 6 A 3 Pin Plugtop with Indicator, 16 A Plugtop With Indicator.
- Strategic Focus: Strengthening its manufacturing capabilities while targeting demand from infrastructure, renewable energy, data centers, railways, metros, telecom, and industrial projects, with an emphasis on safety, reliability, and value-added products.
3M
3M is a technology and industrial solutions company with a strong presence in India through its electrical construction and maintenance business. In the India cable accessories market, the company offers a comprehensive portfolio of power cable terminations, joints, splices, heat shrink and cold shrink solutions, separable connectors, and cable insulation products serving utility, industrial, renewable energy, and infrastructure applications.
- Key Products: Power Cable Terminations, Compression Lugs, Separable Connectors, Cold Shrink Splices, Heat Shrink Splices, Grounding Connectors.
- Strategic Focus: Focuses on technology-driven, reliable, and easy-to-install cable accessories, particularly its Cold Shrink joints and terminations for medium- and high-voltage applications.
Market Concentration Analysis
The India cable accessories market is moderately fragmented, with a mix of large multinational specialty accessories manufacturers, diversified domestic electrical equipment companies, and a significant unorganized sector producing uncertified accessories for price-sensitive segments. Organized manufacturers compete on certification credentials, product quality, technical service depth, and geographic supply network coverage.
Competition intensifies across voltage levels, with multinational brands holding a dominant share in medium and high voltage segments where certification barriers and technical complexity limit unorganized sector participation. In contrast, the low voltage segment remains contested between organized domestic producers and a large informal sector supplying uncertified accessories at price discounts. The market is expected to see progressive formalization as procurement increasingly mandates certified and third-party tested accessories, renewable energy project developers enforce quality specifications that exclude uncertified products, and RDSS scheme implementation requires compliant accessories for distribution network upgrades.
Investment & Growth Opportunities
Highest Growth Segments
Underground accessories (~5.8% CAGR through urban cabling), high voltage cable accessories (~5.6% CAGR through HVDC and transmission expansion), medium voltage renewable energy accessories, South India renewable energy project accessories market, and EV charging infrastructure cable accessories represent the highest-growth investment vectors in the India cable accessories market through 2034.
Investment Themes
- HVDC cable accessories technology development: India's planned HVDC transmission corridors require accessories currently predominantly imported at standard AC cable accessory pricing. Domestic manufacturers investing in HVDC accessories type testing and manufacturing capability can capture significant import substitution revenue while establishing strategic positioning for India's growing HVDC infrastructure pipeline, with first-mover certification advantages creating durable competitive barriers.
- Cold shrink accessories expansion for urban underground markets: RDSS urban underground cabling programs and smart city underground utility corridor mandates are creating multi-year demand growth for cold shrink cable accessories that enable faster, safer installation in urban environments. Manufacturers expanding cold shrink product portfolios from 11kV to 33kV class accessories are positioned to capture growing urban utility project demand at premium pricing over heat shrink alternatives.
Future Market Outlook (2026-2034)
The India cable accessories market is projected to grow from USD 3.38 Billion in 2025 to USD 5.27 Billion by 2034, delivering a 5.04% CAGR over the forecast period through accelerating power grid expansion, massive renewable energy capacity addition driving collection network accessories demand, RDSS-funded distribution network modernization, and progressive urban underground cabling program execution. The market's anchor value of USD 4.33 Billion in 2030 represents India's cable accessories ecosystem at organized sector formalization inflection and renewable energy-driven medium-voltage accessories mainstream growth.
Three structural forces are expected to define the growth of the India cable accessories market through 2034. First, India's energy transition will create sustained, large-scale demand for medium-voltage cable accessories in solar and wind energy collection networks, and high-voltage accessories for renewable energy evacuation transmission lines. Second, urbanization-driven infrastructure investment will sustain above-market growth rates for underground accessories categories, progressively shifting the market's installation type mix from overhead-dominated toward a balanced overhead-underground composition by 2034. Third, regulatory enforcement of quality certification requirements will progressively formalize the market by displacing uncertified unorganized sector supply, expanding organized sector addressable revenue even within moderate overall CAGR parameters, and improving pricing realization for certified manufacturers sustaining investment in quality manufacturing and technical service.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with senior executives from cable accessories manufacturers, power utility procurement managers, renewable energy EPC contractors, cable jointing specialists, and electrical trade distributors. Discussions validated market size estimates, assessed demand growth drivers across voltage and installation segments, evaluated competitive dynamics, and provided insights into regulatory developments, technology trends, and long-term growth opportunities in India's cable accessories market.
Secondary Research
Secondary research encompassed electricity statistics, company annual reports, certification databases, technical publications, electrical industry association reports, and credible energy infrastructure analyst publications. These sources supported market sizing, demand segment analysis, regional consumption data, and policy framework assessment.
Forecasting Models
Forecasting models were developed using historical market revenue data, power sector capital expenditure trajectories, renewable energy capacity addition targets, RDSS scheme disbursement schedules, and macroeconomic indicators. Both top-down and bottom-up approaches were applied and validated through primary expert consultations. Urban underground cabling program implementation timelines, enforcement trajectory, HVDC project sanction schedules, and raw material price scenarios were incorporated to generate reliable forecasts through 2034.
Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Voltages Covered | Low Voltage Cable Accessories, Medium Voltage Cable Accessories, High Voltage Cable Accessories |
| Installations Covered | Overhead Cable Accessories, Underground Accessories |
| End Users Covered | Industrial, Renewables |
| Regions Covered | North India, West and Central India, South India, East India |
| Companies Covered | Havells India Ltd., 3M, Finolex Cables, NKT A/S, TE Connectivity, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Frequently Asked Questions About the India Cable Accessories Market Report
The India cable accessories market reached USD 3.38 Billion in 2025, driven by power grid expansion, renewable energy capacity addition, and distribution network modernization. Urban underground cabling programs and metro rail electrification are further supporting near-term market growth.
The India cable accessories market grows at 5.04% CAGR during 2026-2034, reaching USD 5.27 Billion by 2034. The CAGR reflects sustained power sector investment, a 500 GW non-fossil fuel capacity target, RDSS distribution modernization, and growing urban underground cabling demand across India's major metropolitan areas.
Low voltage cable accessories lead at 45.8% (2025), driven by pervasive application across industrial, commercial, and residential electrical systems. Low-voltage accessories, including cable glands, lugs, and connectors, serve the largest volume of electrical connections in India's growing economy, generating consistent demand across new construction and replacement cycles.
Overhead cable accessories lead at 56.9% (2025), reflecting India's extensive existing overhead distribution and transmission infrastructure requiring consistent maintenance accessories supply.
South India leads at 34.2% (2025), driven by Tamil Nadu and Andhra Pradesh's large renewable energy installed base requiring cable accessories for collection networks, Karnataka's industrial manufacturing sector, and expanding urban underground cabling programs in Chennai, Bengaluru, and Hyderabad.
Leading companies include Havells India Ltd., 3M, Finolex Cables, NKT A/S, and TE Connectivity, among others.
The market is projected to reach approximately USD 4.33 Billion by 2030, representing organized sector formalization inflection and renewable energy-driven medium-voltage accessories mainstream growth. Growth will be anchored by 500 GW non-fossil fuel capacity target execution, RDSS distribution modernization, and urban underground cabling program completion.
Priority investment opportunities include HVDC cable accessories technology development for India's planned long-distance renewable energy transmission corridors, cold shrink product expansion for urban underground cabling programs, renewable energy EPC contractor specification partnerships, and organized sector expansion targeting BIS enforcement-driven market formalization.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade