India Children's Wear Market Size, Share, Trends and Forecast by Product Category, Consumer Group, Gender, Distribution Channel, and Region, 2026-2034
India Children's Wear Market Size, Share, Trends & Forecast (2026-2034)
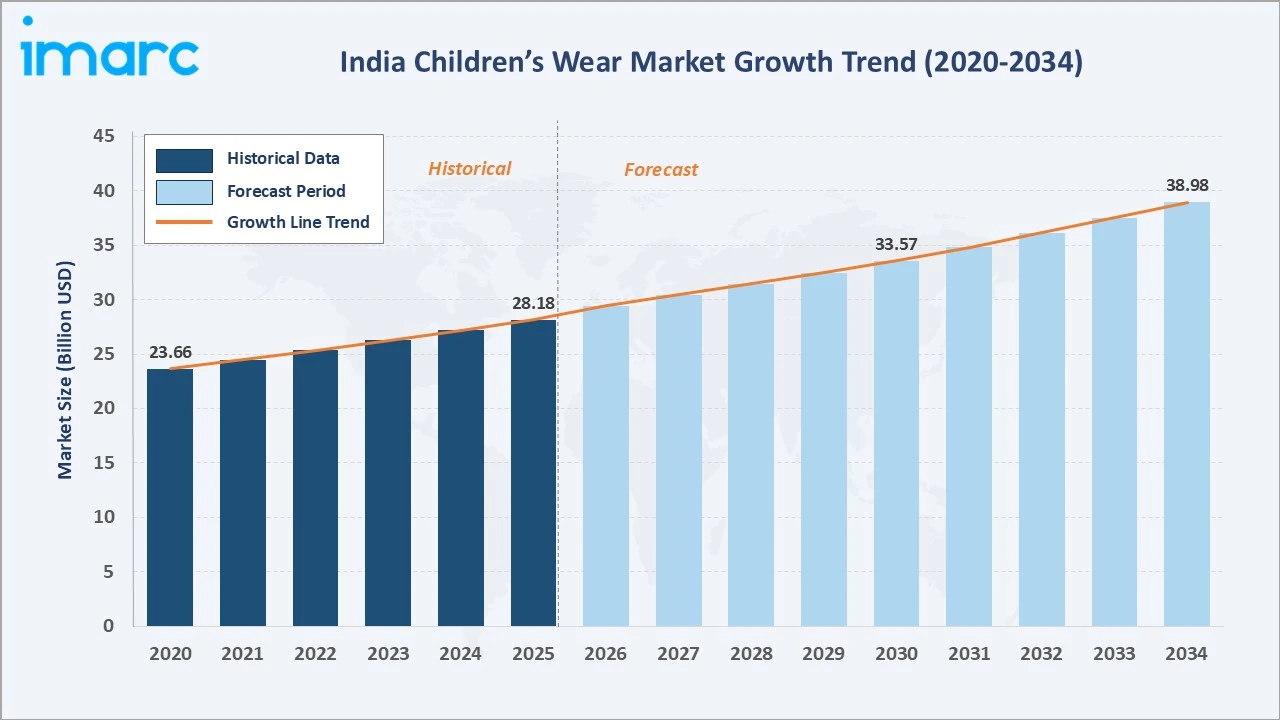
The India children's wear market grew from USD 28.18 Billion in 2025 to USD 29.46 Billion in 2026 and is projected to reach USD 38.98 Billion by 2034, registering a CAGR of 3.56% during 2026-2034. Rising disposable incomes, rapid urbanization, and growing fashion-consciousness among parents are key growth drivers. The children's wear market size in India is expanding steadily, supported by a large and growing child population.
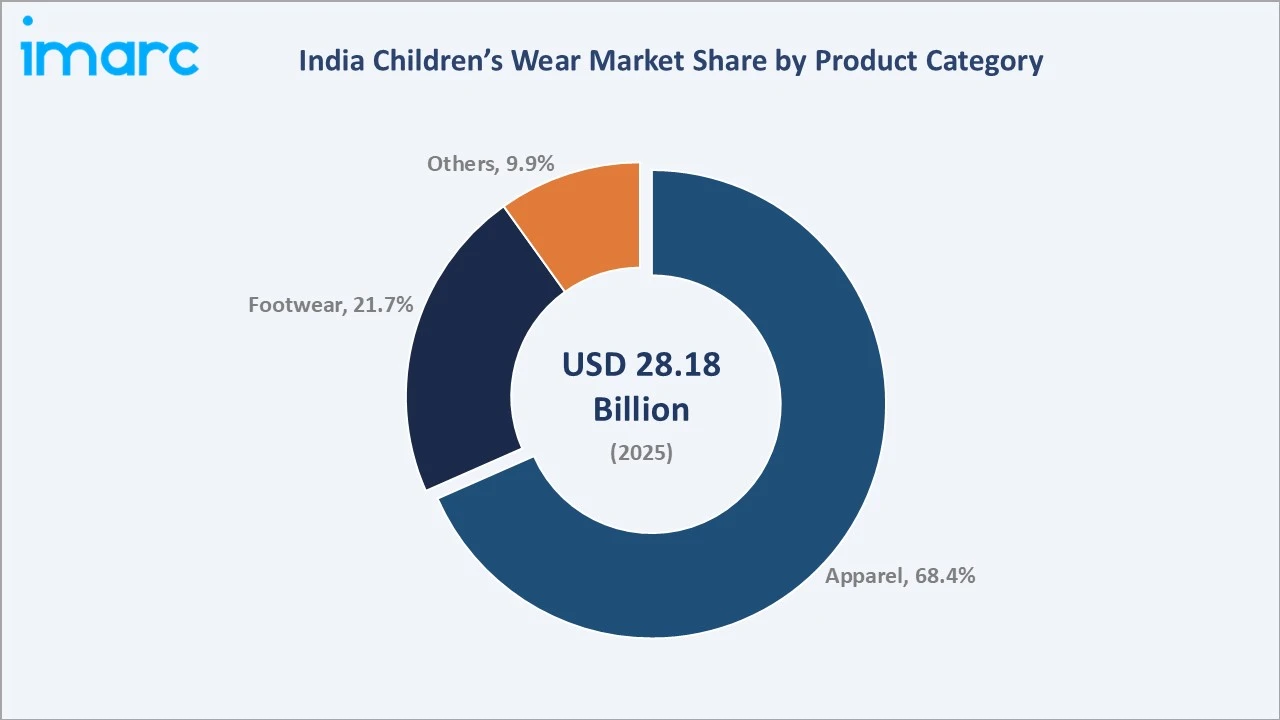
Increasing e-commerce penetration, social media influence, and premiumization of children's apparel are further accelerating growth. Children's clothing market statistics show Apparel dominating at 68.4%. Girls lead gender segments at 46.8%. West India commands the largest regional share at 31.3%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 28.18 Billion |
|
Market Size (2026) |
USD 29.46 Billion |
|
Forecast Market Size (2034) |
USD 38.98 Billion |
|
CAGR (2026-2034) |
3.56% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product Category |
Apparel (68.4%, 2025) |
|
Dominant Gender |
Girls (46.8%, 2025) |
|
Leading Region |
West India (31.3%, 2025) |
The children's wear market size in India increased from USD 23.66 Billion in 2020 to USD 28.18 Billion in 2025 and is estimated to reach USD 29.46 Billion in 2026. The market is further expected to grow to USD 33.57 Billion by 2030 and USD 38.98 Billion by 2034. India's large child population and rising parental spending power form a robust commercial foundation for the market.
To get more information on this market, Request Sample
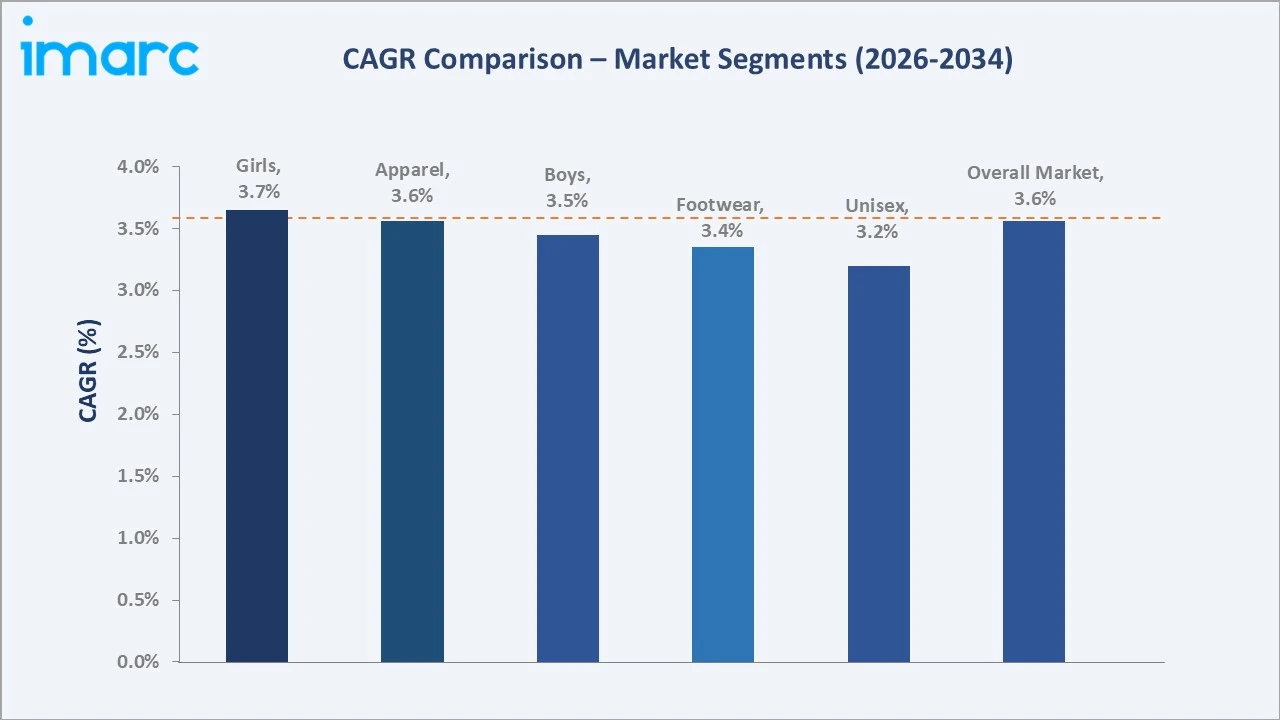
Apparel grows at the market average CAGR of 3.56%, driven by expanding fast-fashion and branded kidswear penetration. Footwear and others represent smaller but consistently growing sub-segments. Children's clothing market statistics indicate girls' wear outpaces boys' wear at ~3.65% CAGR through premiumization.
Executive Summary
The India children's wear market expanded from USD 28.18 Billion in 2025 to an estimated USD 29.46 Billion in 2026. The market's scale is underpinned by India's large and growing child population, rising parental aspirations, and deepening e-commerce penetration across Tier I and II cities. Branded and premium kidswear is increasingly replacing value-driven purchases.
The organized children's wear segment is witnessing structural expansion, supported by improving retail infrastructure, increasing brand awareness among younger parent demographics, and growing investment in children's fashion by both domestic and international players. Supply chain modernization and the rise of omnichannel distribution are enabling brands to serve a broader and more geographically diverse consumer base. Rising urbanization and improving household incomes are collectively elevating the per-child expenditure on apparel, footwear, and accessories across income segments.
The market is projected to reach USD 38.98 Billion by 2034. Apparel at 68.4% leads through mass-market demand and fast-fashion adoption. Girls at 46.8% reflects premium spending in the segment. West India at 31.3% dominates through high urban retail density and consumer purchasing power.
Key Market Insights
|
Insight |
Data |
|
Dominant Product Category |
Apparel – 68.4% share (2025) |
|
Dominant Gender |
Girls – 46.8% market share (2025) |
|
Leading Region |
West India – 31.3% share (2025) |
|
Market Opportunity |
Premium branded kidswear; sustainable children's apparel; D2C kidswear platforms; school uniforms segment; gifting and occasion wear |
Key Analytical Observations:
- Apparel at 68.4%: Apparel dominates at 68.4% due to its wide variety like school uniforms, casual wear, ethnic attire, and seasonal collections, serving everyday need across all demographic segments
- Girls at 46.8%: Girls segment leads at 46.8% driven by premium and fashion-forward buying behavior, with parents spending more on girls' branded and occasion-specific clothing compared to boys
- West India at 31.3%: West India leads at 31.3% through Mumbai's large retail ecosystem, higher per-capita incomes, and strong e-commerce penetration in Maharashtra and Gujarat
India Children's Wear Market Overview
India children's wear market is commercially positioned at a unique intersection: one of the world's largest child populations creating substantial unit-volume demand, a rising middle class driving premiumization of children's clothing, and expanding organized retail and e-commerce enabling brand penetration across geographies.
The market integrates domestic manufacturing, international brand licensing, multi-brand retail, department stores, and growing D2C e-commerce. Macroeconomic factors including rising disposable incomes, urbanization, and improved consumer awareness are supporting sustained market expansion.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
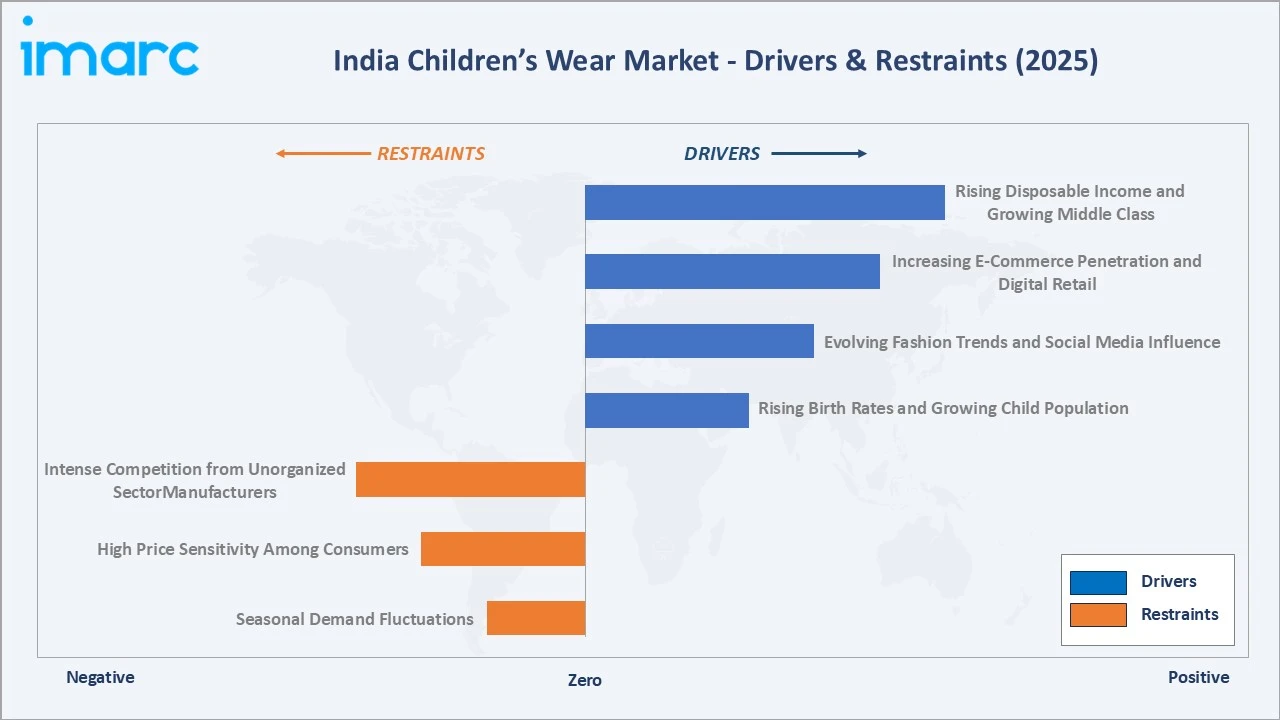
- Rising Disposable Income and Growing Middle Class: India's per capita disposable income is rising steadily, with household spending on children's apparel and footwear increasing meaningfully. As middle-class families expand their purchasing power, demand for branded, quality-assured kidswear is growing. Parents are increasingly trading up from unbranded to organized-sector children's clothing, directly expanding the children's wear market size in India across Tier I and II cities. Greater financial stability among dual-income urban households is enabling higher per-child expenditure on clothing, footwear, and accessories across all age groups. Improved purchasing capacity is also supporting premiumization, with organized retail channels reporting consistent growth in average transaction values for children's apparel categories.
- Increasing E-Commerce Penetration and Digital Retail: E-commerce platforms have democratized access to children's fashion brands across urban and semi-urban India. Online-exclusive kidswear brands, subscription boxes, and digital-first D2C channels are expanding consumer reach. Growing smartphone adoption, improved logistics, and competitive pricing enable parents to explore and purchase children's apparel from national and international brands with ease. The convenience of doorstep delivery, easy returns, and platform-driven discoverability is encouraging first-time branded purchases among consumers in Tier II and III markets. Continued expansion of digital payment infrastructure and last-mile logistics is expected to further accelerate online channel growth through the forecast period.
- Evolving Fashion Trends and Social Media Influence: Social media platforms, influencer marketing, and celebrity-endorsed kidswear collections are shaping parental purchase decisions. Demand for trendy, occasion-specific, and premium children's clothing is rising among aspirational urban consumers. International fashion trends are increasingly reflected in children's wardrobes, supporting premiumization and growth in mid-to-high price segments. Parents are showing greater brand awareness and willingness to invest in aesthetically driven, seasonally refreshed children's clothing collections. The proliferation of parenting communities, mommy bloggers, and children's lifestyle content on digital platforms is creating new and scalable marketing channels for kidswear brands.
- Rising Birth Rates and Growing Child Population: India's large child population estimated at over 350 million children below the age of 15 forms the primary demand foundation for the children's wear market. Children's clothing market statistics confirm consistent unit-volume demand supported by parents' annual repurchase cycles driven by rapid child growth. Urban birth rates and improved child nutrition standards support continued market expansion. The sustained size of India's young demographic cohort ensures a structurally large and recurring consumer base for apparel, footwear, and accessories throughout the forecast period. Government initiatives focused on child health, education enrollment, and nutritional support further reinforce consistent demand for children's clothing at a population scale.
Market Restraints
- Intense Competition from Unorganized Sector: A large portion of India's children's wear market is served by local manufacturers and unbranded players offering products at significantly lower price points. Organized brands face difficulty competing on price in Tier III and rural markets, limiting their penetration. Unorganized players' flexibility in production and pricing continues to constrain the organized sector's volume growth. The fragmented nature of domestic manufacturing allows informal players to adapt quickly to local demand patterns without the compliance and marketing overheads borne by organized brands. This structural cost advantage makes it challenging for established brands to expand their share in price-sensitive geographies without compromising margin sustainability.
- High Price Sensitivity Among Consumers: Despite rising incomes, a significant share of India's consumer base remains price-sensitive, particularly for children's clothing which is repurchased frequently due to rapid growth cycles. Parents often prioritize durability and value over brand, limiting premium positioning in mid-market segments. This restrains margin expansion and slows premiumization in value-driven markets. The frequent replacement requirement inherent to children's apparel increases the total household spend burden, making value-for-money a primary purchase criterion across a broad consumer base. Brands seeking to move consumers up the price ladder must invest heavily in perceived quality and trust-building, extending payback timelines for premium product line launches.
- Seasonal Demand Fluctuations: Children's wear demand is concentrated around back-to-school seasons, festive periods, and summer, creating significant intra-year volatility. Inventory management challenges during off-peak periods increase operational costs for retailers and brands. Seasonal concentration also limits continuous revenue visibility and requires higher marketing investment to maintain year-round consumer engagement. Brands and retailers must plan production and procurement cycles several months in advance, exposing them to demand forecasting risk and excess inventory write-offs when seasonal sell-through underperforms. Managing working capital efficiently across peak and off-peak periods remains a structural operational challenge for both large organized players and smaller regional brands.
Market Opportunities
- Sustainable and Organic Kidswear: Growing parental awareness about chemical-free, GOTS-certified, and organic cotton children's clothing is creating a premium niche. Brands offering OEKO-TEX-certified and sustainably sourced kidswear can command higher margins and build long-term brand loyalty among health-conscious parents. The increasing availability of certified organic textiles from domestic suppliers is improving cost competitiveness for sustainable kidswear brands, making the category accessible to a broader middle-income consumer segment. As environmental consciousness grows among millennial and Gen Z parents, sustainability credentials are becoming a meaningful differentiator that supports both brand positioning and pricing power.
- Tier II and III City Expansion: Rising consumer aspirations and increasing branded retail penetration in smaller cities represent significant untapped market potential. Organized kidswear brands expanding franchise retail and e-commerce delivery to Tier II and III cities can access a large and growing first-time branded buyer population. Improved road connectivity, logistics infrastructure, and digital payment adoption in smaller urban centers are reducing the barriers to organized retail expansion beyond metro markets. Brands that establish presence early in these geographies are likely to benefit from strong first-mover advantages as consumer awareness and income levels continue to rise.
Market Challenges
- Short Product Lifecycle: Children outgrow clothing rapidly, creating high repurchase frequency but also limiting per-unit revenue potential. Brands must continuously refresh collections while managing inventory efficiently to prevent markdowns, adding complexity to supply chain management. The need to maintain wide size ranges across multiple age groups further increases SKU complexity and procurement costs for organized players. Managing the balance between collection freshness, size availability, and inventory turnover requires sophisticated demand planning capabilities that smaller brands may find difficult to sustain profitably.
- Counterfeit and Grey Market Products: Counterfeit branded children's apparel undermines authorized brand revenues and creates consumer trust issues. Grey market imports at below-MRP pricing challenge the value propositions of organized players and authorized retailers across metros and online marketplaces. The proliferation of counterfeit products on digital platforms makes brand protection increasingly difficult, requiring ongoing investment in enforcement, consumer education, and authentication technologies. These challenges erode pricing discipline across the market and create reputational risk for brands whose products are most frequently counterfeited.
Emerging Market Trends
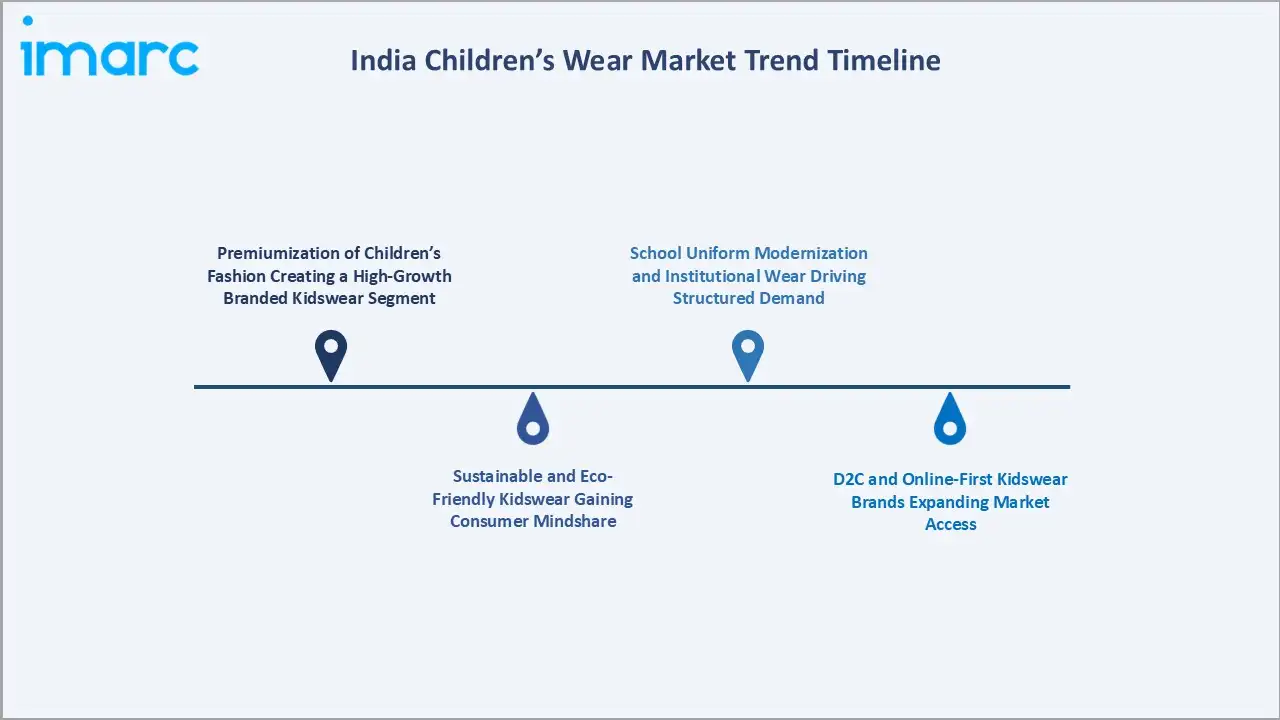
1. Premiumization of Children's Fashion Creating a High-Growth Branded Kidswear Segment
Premium and luxury children's apparel brands are gaining traction in India's urban markets. Parents with higher disposable incomes are purchasing branded occasion wear, designer ethnic wear, and international-label children's clothing for special occasions. Premiumization is driving above-market growth in the organized sector.
2. Sustainable and Eco-Friendly Kidswear Gaining Consumer Mindshare
Demand for organic, chemical-free, and sustainably produced children's clothing is rising among urban, educated parents. Brands offering GOTS-certified organic cotton, OEKO-TEX-approved fabrics, and recycled-material schoolwear are attracting premium pricing. This trend is shaping new product development and supply chain investments across the market.
3. D2C and Online-First Kidswear Brands Expanding Market Access
Digital-native D2C children's clothing brands are disrupting traditional retail by reaching consumers directly through social media, marketplaces, and branded websites. Lower overheads and data-driven inventory management enable competitive pricing. This trend is expanding the organized sector's reach into Tier II and III markets and driving category awareness.
4. School Uniform Modernization and Institutional Wear Driving Structured Demand
Modern school uniforms with performance fabrics, ergonomic designs, and branded school-specific collections are creating structured seasonal demand. Institutional tie-ups between schools and apparel brands are providing predictable bulk-order revenue streams. This segment represents a commercially stable and growing sub-category within the children's wear market.
Industry Value Chain Analysis
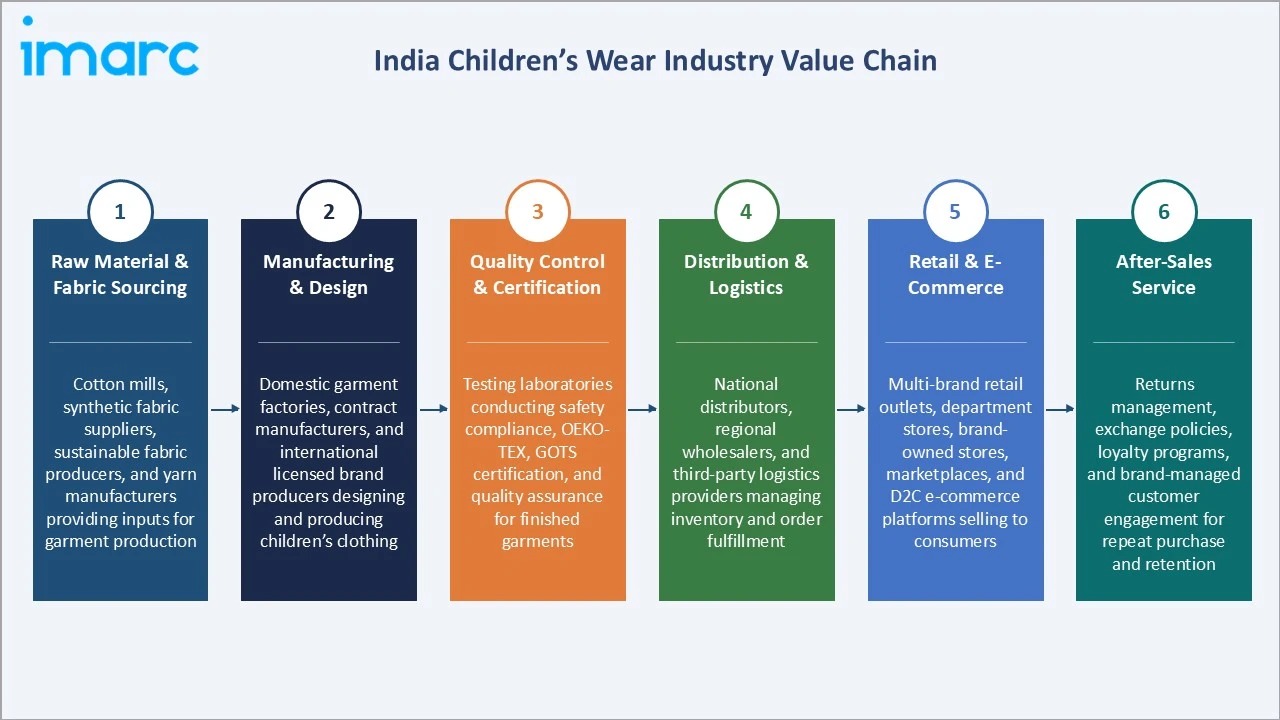
India children's wear value chain spans raw material sourcing to end consumer delivery, integrating domestic manufacturing with import channels and modern retail distribution.
|
Stage |
Key Participants |
|
Raw Material & Fabric Sourcing |
Cotton mills, synthetic fabric suppliers, sustainable fabric producers, and yarn manufacturers providing inputs for garment production |
|
Manufacturing & Design |
Domestic garment factories, contract manufacturers, and international licensed brand producers designing and producing children's clothing |
|
Quality Control & Certification |
Testing laboratories conducting safety compliance, OEKO-TEX, GOTS certification, and quality assurance for finished garments |
|
Distribution & Logistics |
National distributors, regional wholesalers, and third-party logistics providers managing inventory and order fulfillment |
|
Retail & E-Commerce |
Multi-brand retail outlets, department stores, brand-owned stores, marketplaces, and D2C e-commerce platforms selling to consumers |
|
After-Sales Service |
Returns management, exchange policies, loyalty programs, and brand-managed customer engagement for repeat purchase and retention |
E-commerce has emerged as India children's wear value chain's most commercially dynamic distribution stage, with online platforms enabling brand discovery, comparison, and purchase across geographies. Quality certification stages are increasingly critical as consumer awareness of fabric safety and chemical compliance grows.
Technology Landscape in the India Children's Wear Industry
Digital Commerce and AI-Powered Personalization
E-commerce platforms and AI-driven recommendation engines are transforming how parents discover and purchase children's clothing. Machine learning algorithms tailor product suggestions by child age, gender, and past purchase behavior. D2C brands are leveraging these tools to improve customer lifetime value and reduce acquisition costs.
Sustainable Fabric Technologies
Innovations in organic cotton processing, recycled polyester blends, and naturally-dyed fabrics are enabling brands to offer certified eco-friendly children's clothing. Advances in GOTS-certified and OEKO-TEX-approved fabric production are reducing cost barriers to sustainable kidswear, allowing broader adoption across mid-market price points.
Smart Fit and Virtual Try-On Technologies
Augmented reality-based virtual try-on tools and AI size recommendation engines are reducing return rates in online children's apparel. Size prediction algorithms using child height, weight, and age data help parents select correct sizes with confidence, improving conversion rates and customer satisfaction on digital platforms.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Category |
Apparel |
68.4% |
2025 |
|
Gender |
Girls |
46.8% |
2025 |
|
Distribution Channel |
🔒 |
🔒 |
2025 |
|
Consumer Group |
🔒 |
🔒 |
2025 |
|
Region |
West India |
31.3% |
2025 |

By Product Category
Apparel leads at 68.4% (2025). The apparel segment encompasses India's most commercially diverse and high-volume children's clothing category, spanning school uniforms, casual wear, ethnic occasion wear, sportswear, and seasonal fashion. It serves everyday demand across all demographics, age groups, and income levels.
To access detailed market analysis, Request Sample
Footwear at 21.7% is growing at ~3.35% CAGR, driven by branded school shoes, sports footwear, and seasonal sandal categories. Others at 9.9% includes accessories such as hats, bags, and belts, growing steadily alongside the core segments.
By Gender
Girls lead at 46.8% (2025). This segment is commercially distinguished by higher average selling prices, greater occasions-wear and fashion-driven purchase frequency, and above-market premiumization rates driven by parental propensity to spend more on girls' branded and fashion-oriented clothing.
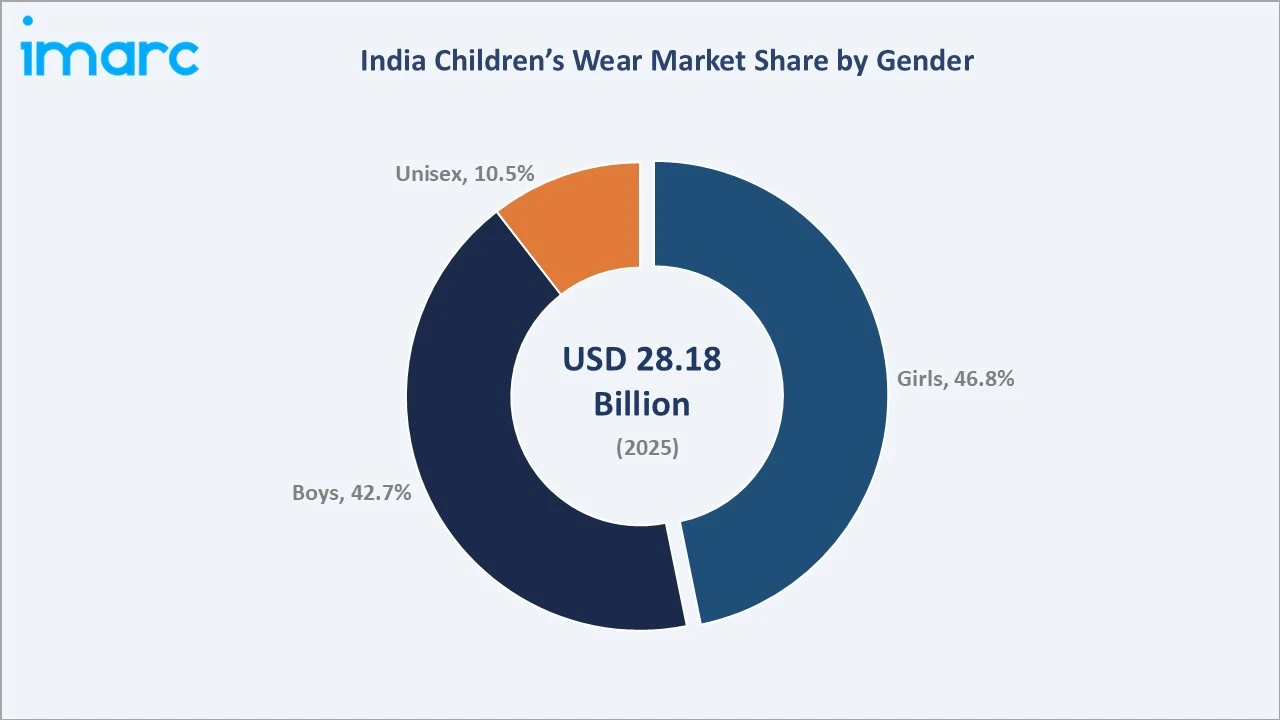
Boys at 42.7% reflects strong demand for school uniforms, casual T-shirts, and sports apparel, growing at ~3.45% CAGR. Unisex at 10.5% is growing fastest at ~3.20% CAGR through gender-neutral fashion trends, newborn and infant categories, and school-authorized unisex uniform specifications.
Regional Market Insights
|
Region |
Share (2025) |
Key India Children's Wear Market Drivers & Characteristics |
|
West India |
31.3% |
Driven by Mumbai and Pune metropolitan retail density, high per-capita income, strong organized retail penetration, and significant e-commerce adoption. |
|
South India |
25.6% |
Reflects Bengaluru, Chennai, and Hyderabad's affluent consumer base with strong demand for premium and branded children's apparel, supported by high tech-sector incomes. |
|
North India |
24.8% |
Delhi-NCR's large retail market, diverse consumer base, and cultural demand for ethnic occasion wear and school uniform categories drive substantial volume. |
|
East India |
18.3% |
Rising incomes in Kolkata and Bhubaneswar along with first-generation branded kidswear adoption are gradually supporting growth in organized-sector children's clothing. |
West India's 31.3% regional leadership reflects Maharashtra and Gujarat's combined strength in organized retail, high consumer spending, and gateway status for international children's clothing brand entry. South India's 25.6% reflects IT-sector wealth in Bengaluru and Hyderabad, creating premium kidswear demand.
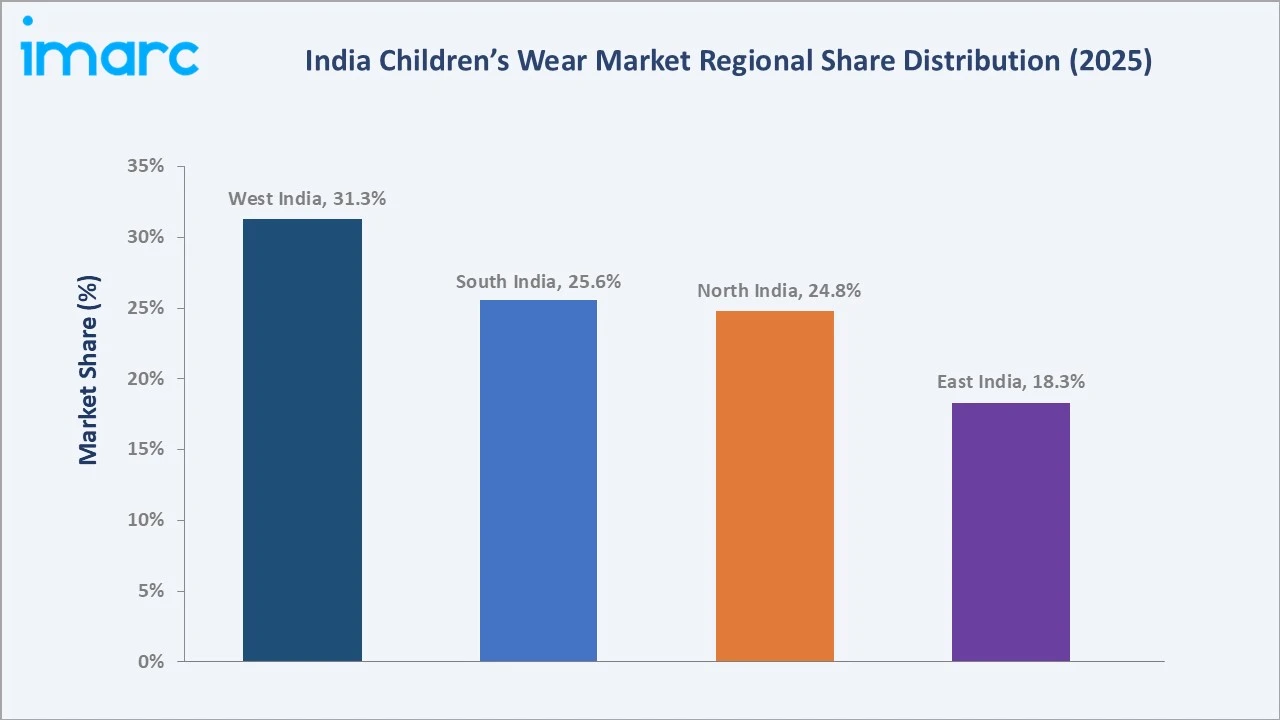
North India's 24.8% reflects Delhi-NCR's multi-brand retail depth and strong festive occasion wear demand. East India at 18.3% remains commercially underpenetrated by organized brands but is growing above the national CAGR through Kolkata's improving retail infrastructure and rising consumer brand awareness.
Competitive Landscape
India children's wear competitive landscape is highly fragmented, combining domestic mass-market producers, international fast-fashion brands, and premium licensed kidswear labels. Competition is intensifying through e-commerce channel growth, D2C brand emergence, and increasing international brand presence.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
Carter's, Inc. |
Carter's, OshKosh B'gosh, Skip Hop |
Market Leader |
Carter's, Inc. is the largest branded marketer of children's clothing in North America with a growing India presence through exclusive licensed distribution partnerships. |
|
Benetton Group S.r.l. |
United Colors of Benetton |
Strong Challenger |
Benetton Group S.r.l. operates a strong branded children's wear presence in India through its United Colors of Benetton label, offering colorful, fashion-forward kidswear across premium retail outlets. |
|
Brainbees Solutions Limited |
FirstCry |
Market Leader |
Brainbees Solutions Limited operates India's largest omnichannel baby and children's products platform, combining a high-traffic e-commerce marketplace with an expanding offline franchise network. |
|
Mothercare plc |
Mothercare |
Innovator |
Mothercare plc serves India's premium baby and children's wear segment through franchise retail, offering trusted international-brand kidswear and accessories to aspirational urban parents. |
|
H&M Hennes & Mauritz AB |
H&M Kids |
Strong Challenger |
H&M Hennes & Mauritz AB operates an extensive children's clothing range in its India stores, serving the fast-fashion mid-market with trend-forward and affordable kidswear collections. |
The competitive landscape's most significant dynamic is the coexistence of organized international brands and large domestic e-commerce platforms, with Brainbees Solutions Limited (FirstCry) commanding India's broadest children's product distribution network. E-commerce competition is intensifying through direct brand storefronts and marketplace private labels.
Key Company Profiles
Carter's, Inc.
Carter's, Inc. is the largest branded marketer of apparel exclusively for babies and young children in the United States and a growing presence in India through licensed distribution partners. The company's multi-brand portfolio and strong consumer recognition drive market leadership.
- Key Brands: Carter's, OshKosh B'gosh, Skip Hop.
- Recent Developments: On October 14, 2026, Carter’s, Inc., through its OshKosh B’gosh brand, announced a limited-edition children’s clothing collection in collaboration with fashion designer Sergio Hudson and Harlem’s Fashion Row. The collection reinterprets classic denim, overalls and heritage designs with bold colours and contemporary tailoring. Covering baby, toddler and children’s sizes, the collection is priced between $22 and $45 and is scheduled to launch on October 22, 2026, through Carter’s website and select retail stores. The collaboration expands the brand’s children’s wear offering through designer-led products.
- Strategic Focus: Deepening India retail and e-commerce distribution through licensed partnerships while maintaining premium brand positioning across newborn, toddler, and young-children age categories.
Benetton Group S.r.l.
Benetton Group S.r.l. is an Italian fashion brand with a long-established India presence across children's and adult apparel categories. Its United Colors of Benetton label is among India's most recognized international children's fashion brands, known for colorful and socially conscious design positioning.
- Key Brands: United Colors of Benetton Kids, Sisley Young.
- Recent Developments: On March 20, 2026, Benetton announced a collaboration with Cloudco Entertainment, the owner of Care Bears, to launch an exclusive children’s fashion collection for kids aged 1–6 years and juniors aged 7–14 years. The collection features T-shirts and sweatshirts incorporating Care Bears’ colourful characters and playful designs. Scheduled to be available in Benetton stores from Spring/Summer 2026, the collaboration strengthens the company’s children’s wear portfolio by combining character-based designs with everyday apparel.
- Strategic Focus: Sustaining India brand presence through premium retail positioning, social responsibility-linked marketing campaigns, and collection refreshes aligned with seasonal fashion cycles.
Brainbees Solutions Limited
Brainbees Solutions Limited operates FirstCry, India's largest integrated omnichannel platform for baby and children's products. The company combines a high-traffic online marketplace with over 900 franchise stores across India, providing unmatched product variety and geographic reach in the children's wear and accessories market.
- Key Brands: FirstCry, BabyHug, Intellibaby.
- Strategic Focus: Expanding omnichannel reach through franchise store network growth, private-label children's apparel portfolio development, and international expansion of the FirstCry platform.
Market Concentration Analysis
India children's wear market is highly fragmented at the mass-market segment, with no single organized player commanding more than 10–15% of overall market share by value. Brainbees Solutions Limited (FirstCry) leads in distribution reach rather than exclusive market share, functioning as a marketplace for multiple brands. International fast-fashion players including H&M and Inditex hold the strongest positions in the mid-premium urban segment.
Market concentration is evolving through two opposing forces: e-commerce platforms aggregating multi-brand demand at the national level and increasing organized brand share, while the unorganized sector maintains resilience in Tier III and rural markets through price competitiveness. Premium brand concentration is increasing as international brand entry grows.
Investment & Growth Opportunities
Highest Growth Segments
Among the key product and gender segments, Girls' apparel leads with a ~3.65% CAGR driven by premiumization and fashion-forward purchasing, followed by Apparel overall at ~3.56% CAGR, Boys' segment at ~3.45% CAGR, and Footwear at ~3.35% CAGR. Unisex and Others (Product) segments register ~3.20% and ~3.10% CAGRs respectively. These growth differentials highlight Girls' apparel and branded Footwear as the highest-return investment vectors through 2034.
Emerging Investment Opportunities
India's sustainable and organic children's clothing segment is emerging as the highest-differentiation growth opportunity, driven by rising parental health and environmental awareness. Brands offering GOTS-certified and chemical-free kidswear can command premium pricing and build defensible brand loyalty in the urban consumer segment.
Investment Themes
- D2C Brand Opportunity: D2C digital-first children's wear brands leveraging social media acquisition and AI personalization for above-market growth in Tier I and II cities
- Sustainable Kidswear: Sustainable and certified organic kidswear brands catering to the health-conscious urban parent segment with a demonstrated willingness to pay a premium for certification-backed quality
- Tier II/III Expansion: Omnichannel franchise retail expansion in Tier II and III cities, replicating the FirstCry model for branded children's apparel through licensed franchise networks
Future Market Outlook (2026-2034)
The India children's wear market is projected to grow from USD 28.18 Billion in 2025 to USD 29.46 Billion in 2026, reaching USD 38.98 Billion by 2034, registering a CAGR of 3.56% during 2026-2034. The anchor value of USD 33.57 Billion in 2030 reflects sustained commercial expansion through India's income growth, retail infrastructure development, and increasing branded kidswear penetration.
Three structural forces define market growth through 2034: India's expanding middle class creating the world's largest new-entry branded children's clothing consumer base; e-commerce and D2C channels democratizing access to branded kidswear across geographies; and rising parental education and brand awareness driving premiumization across all regional markets.
Research Methodology
Primary Research
Primary research comprised structured interviews with India children's wear industry stakeholders including Brand Directors, Retail Heads, e-commerce Category Managers, Manufacturing Partners, and consumer survey data from parents across North, South, East, and West India, covering urban, semi-urban, and Tier II demographics.
Secondary Research
Secondary research encompassed India textile and garment export data, Ministry of Textiles reports, company annual reports, e-commerce platform disclosures, brand investor presentations, industry association publications, and children's apparel market surveys. Over 50 secondary sources reviewed.
Forecasting Models
Market revenue forecasts were developed using a child population stratification model: India's child population by age group multiplied by annual apparel and footwear spend per child across urban and rural demographics, adjusted for income growth rates and brand penetration trajectories per segment.
India Children's Wear Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Categories Covered | Apparel, Footwear, Others |
| Consumer Groups Covered | Infant (0-12 Months), Toddler (1-3 Years), Preschool (3-5 Years), Gradeschooler (5-12 Years) |
| Gender Covered | Boys, Girls, Unisex |
| Distribution Channels Covered | Offline, Online |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Carter's, Inc., Benetton Group S.r.l., Brainbees Solutions Limited, Mothercare plc, H&M Hennes & Mauritz AB, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India children’s wear market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India children’s wear market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India children’s wear industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Children's Wear Market Report
India children's wear market size is estimated at USD 29.46 Billion in 2026, driven by rising disposable incomes, a large child population, growing brand penetration, and expanding e-commerce access across urban and semi-urban markets. The children's wear market size in India continues to expand steadily.
India children's wear market grows at 3.56% CAGR during 2026-2034, reaching USD 38.98 Billion by 2034. Growth is driven by premiumization, e-commerce expansion, D2C brand proliferation, and rising parental spending on branded children's apparel and footwear.
Apparel leads at 68.4% through its diverse sub-categories school uniforms, casual wear, ethnic occasion wear, and sportswear collectively serving everyday demand across all demographic segments and income levels across India.
Girls lead at 46.8% through higher parental premium spending on fashion and occasion wear. Children's clothing market statistics confirm girls' branded apparel commands higher average selling prices and drives above-market premiumization within the segment.
West India leads at 31.3% through Maharashtra and Gujarat's organized retail density, high consumer income, and e-commerce adoption, particularly in the Mumbai, Pune, and Ahmedabad metropolitan markets.
Leading companies include Carter's, Inc., Benetton Group S.r.l., Brainbees Solutions Limited, Mothercare plc, and H&M Hennes & Mauritz AB, among others.
India children's wear market is projected to reach approximately USD 33.57 Billion by 2030, with e-commerce representing a growing share of distribution, premium branded kidswear expanding into Tier II cities, and sustainable children's apparel gaining above-market consumer traction.
Three priority investment opportunities include D2C digital-first children's fashion brands leveraging social commerce, sustainable and certified organic kidswear premium segment, and omnichannel franchise retail expansion into Tier II and III cities. Children's clothing market statistics confirm these as structurally high-growth vectors through 2034.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade