India Connected Vehicles Market Size, Share, Trends and Forecast by Technology Type, Application, Connectivity, Vehicle Connectivity, Vehicle, and Region, 2026-2034
India Connected Vehicles Market Size, Share, Trends & Forecast (2026-2034)
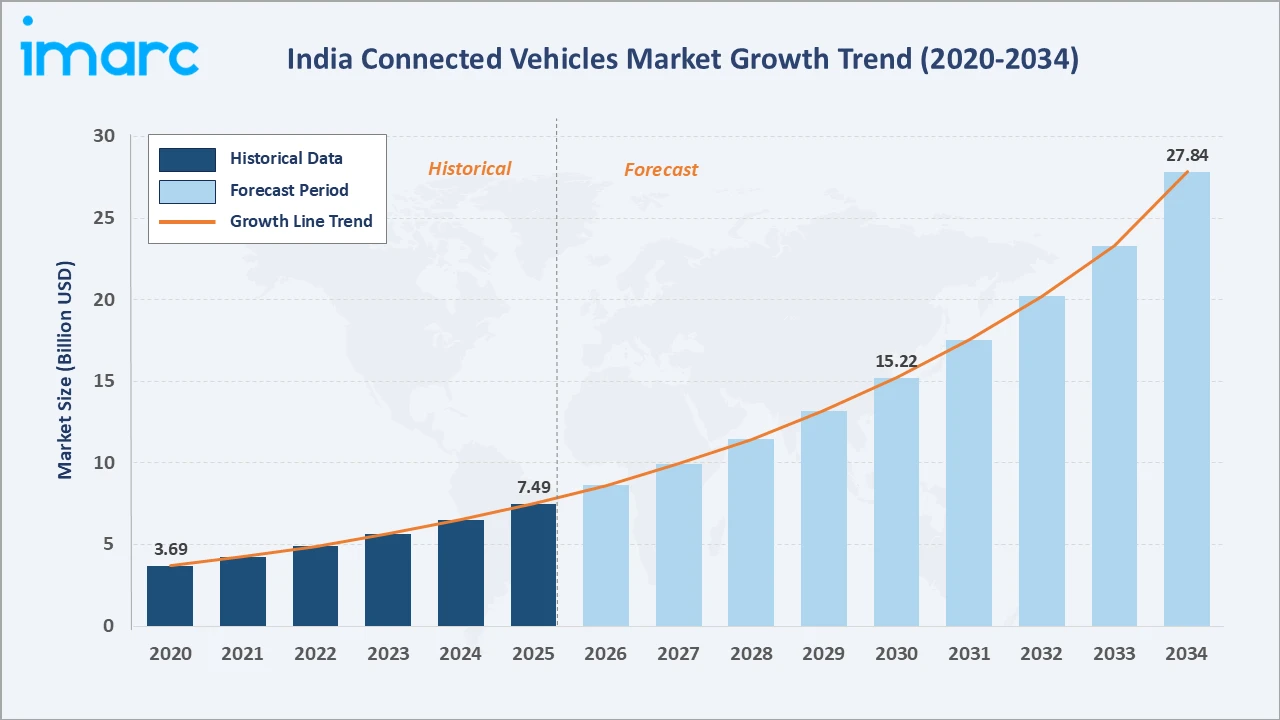
The India connected vehicles market grew from USD 7.49 Billion in 2025 to USD 8.63 Billion in 2026 and is projected to reach USD 27.84 Billion by 2034, exhibiting a CAGR of 15.24% during 2026-2034. India's automotive sector is undergoing a transformative shift, with vehicle-to-infrastructure connectivity emerging as a key enabler of safer roads and smarter mobility.
4G/LTE leads the technology type segment at 74.6%, telematics commands 42.7% of the application segment, and West India holds a 30.8% regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 7.49 Billion |
|
Market Size (2026) |
USD 8.63 Billion |
|
Forecast Market Size (2034) |
USD 27.84 Billion |
|
CAGR (2026-2034) |
15.24% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
West India (30.8%, 2025) |
|
Second Largest Region |
North India (28.7%, 2025) |
|
Leading Technology Type |
4G/LTE (74.6%, 2025) |
|
Leading Application |
Telematics (42.7%, 2025) |
The India connected vehicles market expanded from USD 3.69 Billion in 2020 to USD 7.49 Billion in 2025 and is estimated to reach USD 8.63 Billion in 2026. Anchored at USD 15.22 Billion in 2030, the forecast to USD 27.84 Billion by 2034 is supported by accelerating OEM adoption of factory-fitted connectivity modules and government-backed road safety initiatives.
To get more information on this market, Request Sample
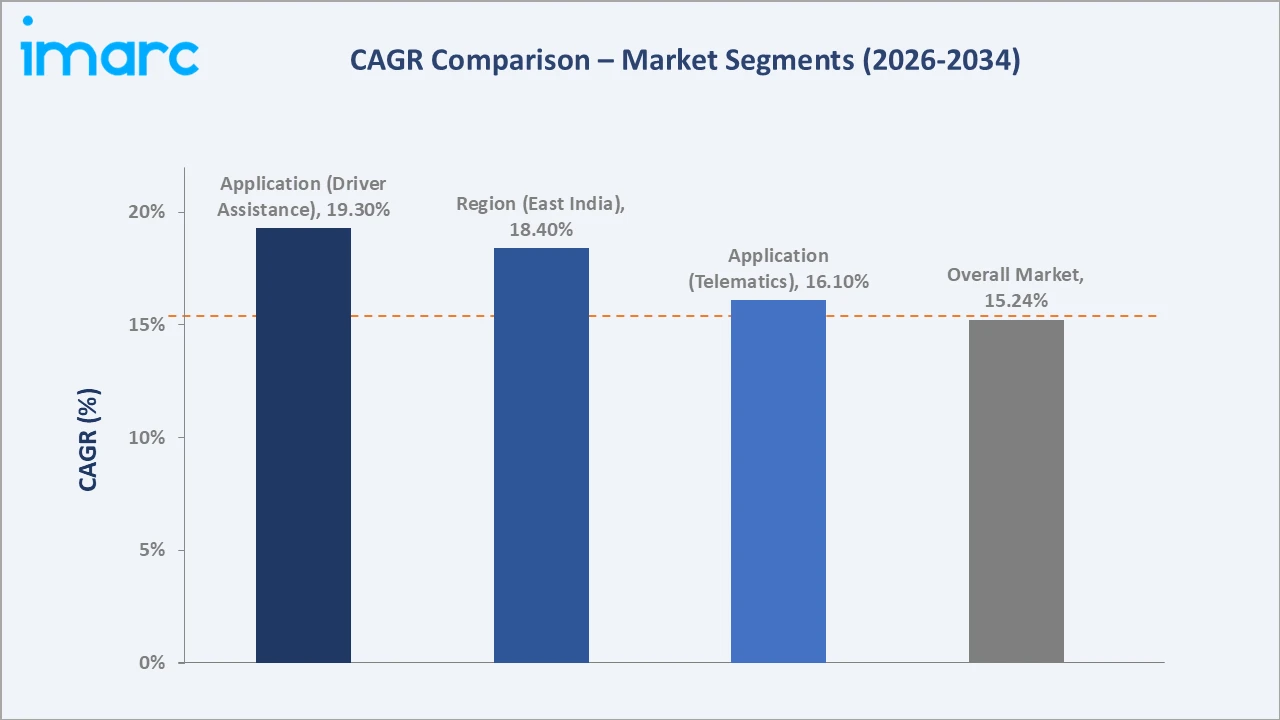
CAGR trajectories across technology type and application sub-segments, together with regional patterns, show driver assistance and East India expanding faster than the overall 15.24% market CAGR, supported by increasing regulatory focus on advanced driver assistance systems, deeper cellular infrastructure penetration, and growing fleet-based telematics adoption across commercial vehicle categories.
Executive Summary
The India connected vehicles market is on a strong growth trajectory, expanding from USD 7.49 Billion in 2025 to an estimated USD 8.63 Billion in 2026. The industry has evolved from basic GPS tracking and emergency call systems to fully integrated, multi-application connectivity platforms spanning telematics, infotainment, and driver assistance.
4G/LTE leads the technology type segment at 74.6% in 2025, reflecting the widespread availability of LTE networks and OEM preference for high-bandwidth, low-latency connectivity in new vehicle models. Telematics dominates the application segment at 42.7%, supported by commercial fleet management adoption, insurance telematics, and government vehicle tracking mandates. West India commands a 30.8% regional share, driven by high vehicle density, strong OEM presence, and a developed digital ecosystem in Maharashtra and Gujarat.
Key Market Insights
|
Insight |
Data |
|
Leading Technology Type |
4G/LTE – 74.6% share (2025) |
|
Second Largest Technology Type |
3G – 16.8% share (2025) |
|
Leading Application |
Telematics – 42.7% share (2025) |
|
Second Largest Application |
Infotainment – 31.5% share (2025) |
|
Leading Region |
West India – 30.8% share (2025) |
|
Second Largest Region |
North India – 28.7% share (2025) |
|
Top Companies |
Robert Bosch GmbH, Continental AG, Samsung Electronics Co., Ltd., Visteon Corporation |
Key Analytical Observations Supporting the Above Data:
- 4G/LTE dominance at 74.6% reflects OEM preference for high-bandwidth connectivity enabling simultaneous telematics, infotainment, and over-the-air software update capabilities within a single embedded module.
- 3G at 16.8% continues to serve cost-sensitive aftermarket connectivity applications and older vehicle cohorts where backward compatibility remains a commercial priority for fleet operators.
- Telematics leadership at 42.7% is supported by mandatory vehicle tracking regulations for commercial vehicles, growing fleet management adoption, and expanding usage-based insurance programs across the market.
- Infotainment at 31.5% reflects rising integration of connected navigation, streaming, smartphone mirroring, voice assistants, and real-time traffic services as automakers increasingly enhance in-vehicle digital experiences.
- West India at 30.8% leads regional share, anchored by concentrated OEM manufacturing clusters in Pune, Nashik, and Ahmedabad alongside a mature automotive component supplier ecosystem.
India Connected Vehicles Market Overview
Connected vehicles are automobiles equipped with internet access, on-board diagnostics, and communication modules enabling real-time data exchange between the vehicle, its passengers, infrastructure, and external networks. Core functionalities include remote diagnostics, fleet management, navigation, infotainment, emergency response, and driver assistance, spanning passenger cars, commercial vehicles, and two-wheelers.
The India connected vehicles ecosystem integrates automotive OEMs, connectivity module suppliers, telecom network operators, software platform developers, fleet management companies, regulatory bodies, and end users. Together, these stakeholders enable secure, scalable V2X communications supported by expanding cellular infrastructure, government vehicle safety mandates, and rising consumer demand for in-vehicle digital experiences.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
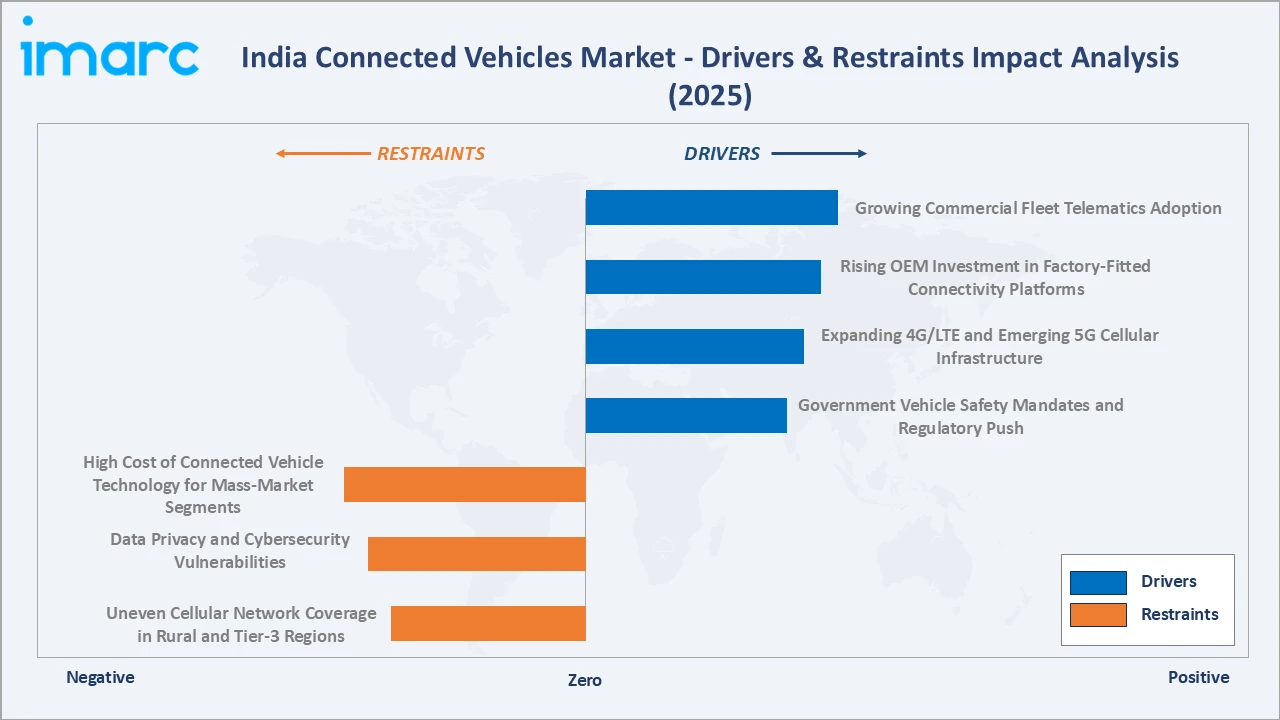
- Government Vehicle Safety Mandates and Regulatory Push: The implementation of mandatory safety features and strengthening vehicle safety regulations are encouraging automakers to adopt connected technologies that support real-time monitoring, emergency response, and enhanced driver and passenger protection.
- Expanding 4G/LTE and Emerging 5G Cellular Infrastructure: Rising 4G coverage across urban and semi-urban areas provides the network backbone for real-time vehicle connectivity applications, while emerging 5G rollouts are expected to enable ultra-low latency vehicle-to-infrastructure communications, unlocking next-generation autonomous and assisted driving capabilities.
- Rising OEM Investment in Factory-Fitted Connectivity Platforms: Leading automobile manufacturers are integrating embedded telematics, infotainment, and driver assistance modules into standard vehicle configurations. This factory-fitted approach improves unit economics and creates ongoing service revenue streams through connected subscriptions and over-the-air software updates, supporting sustained market growth.
- Growing Commercial Fleet Telematics Adoption: Commercial fleet operators are rapidly adopting GPS-linked telematics solutions to optimize routes, monitor driver behavior, manage fuel consumption, and ensure regulatory compliance. Expanding e-commerce, logistics, and last-mile delivery industries are significantly widening the addressable market for fleet connectivity services. As per IMARC Group, the India e-commerce market size was valued at USD 129.72 Billion in 2025.
Market Restraints
- High Cost of Connected Vehicle Technology for Mass-Market Segments: Embedded connectivity hardware, telematics modules, and data subscription services add meaningful incremental costs to vehicle prices, limiting adoption in price-sensitive entry-level and two-wheeler segments that represent a significant share of India's total vehicle sales.
- Data Privacy and Cybersecurity Vulnerabilities: Connected vehicles generate large volumes of location, behavioral, and diagnostic data, creating exposure to unauthorized data access, remote system intrusions, and privacy breaches. As connectivity penetration deepens, regulatory scrutiny around data protection and vehicle cybersecurity standards is expected to increase operational compliance requirements for platform providers.
- Uneven Cellular Network Coverage in Rural and Tier-3 Regions: Significant gaps in 4G/LTE availability in rural districts and hilly terrain limit the reliability of real-time vehicle connectivity in these geographies, constraining market growth in regions outside urban and semi-urban corridors.
Market Opportunities
- Rapid Expansion of Usage-Based Insurance and Telematics Services: Rising insurance company interest in telematics-based premium models presents a significant growth opportunity for connected vehicle data platform providers. Accurate driver behavior scoring, enabled by real-time telematics data, supports premium differentiation and incentivizes safer driving behaviors across personal and commercial vehicle segments.
- Proliferation of EVs Creating New Connectivity Demand: The expanding EV segment in India requires battery management monitoring, charging infrastructure locators, and remote diagnostics as baseline capabilities, making factory-fitted connectivity a necessity rather than a premium feature. Growing government EV incentive programs are expected to accelerate the convergence of electrification and connectivity.
Market Challenges
- Fragmented Aftermarket Standards and Ecosystem Interoperability: The coexistence of multiple connectivity protocols, hardware generations, and OEM-specific platforms creates integration complexity for third-party service providers seeking to build cross-brand connected vehicle services and data platforms.
- Consumer Awareness and Technology Adoption Barriers in Semi-Urban Markets: Limited consumer awareness of connected vehicle benefits, combined with low digital literacy in semi-urban and rural geographies, constrains demand generation for subscription-based connectivity services beyond basic GPS and emergency functions.
Emerging Market Trends
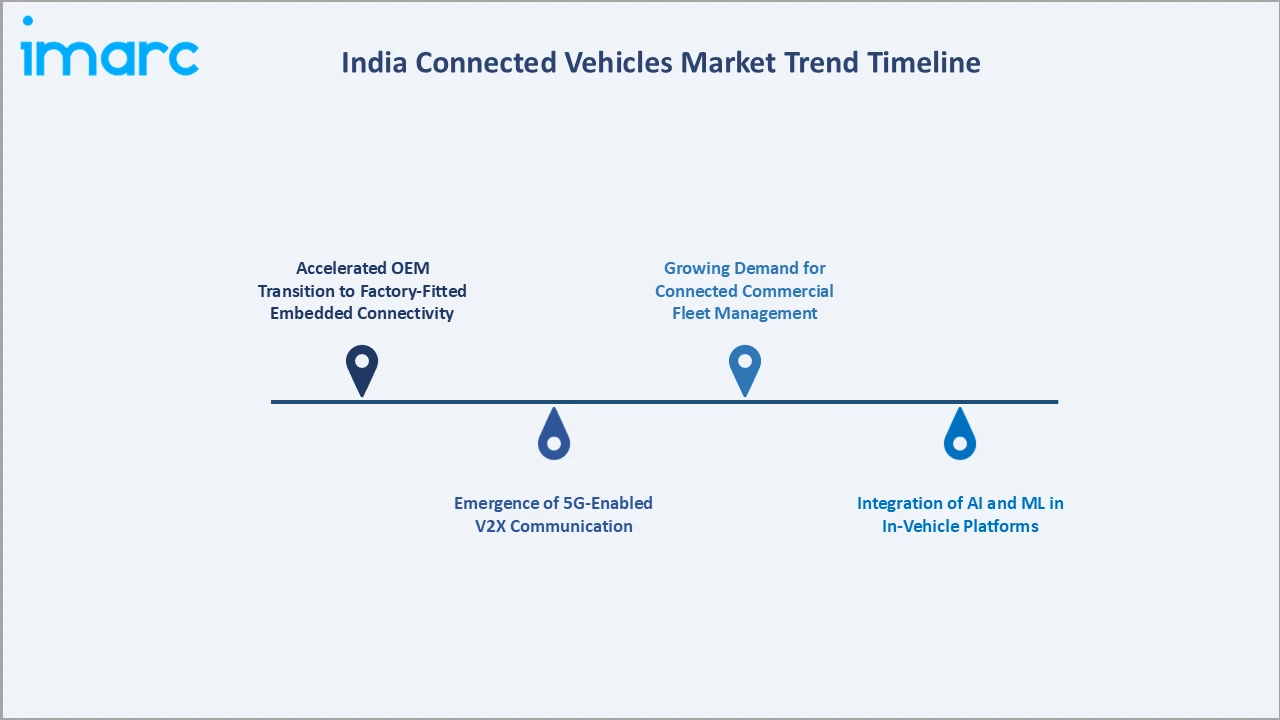
1. Accelerated OEM Transition to Factory-Fitted Embedded Connectivity
Indian and global OEMs operating in India are standardizing factory-fitted connectivity modules across mid-range and entry vehicle platforms, shifting from aftermarket add-ons to integrated eSIM-based embedded systems. This transition reduces installation costs, improves reliability, and enables seamless over-the-air software update capabilities.
2. Emergence of 5G-Enabled V2X Communication
With 5G infrastructure beginning to expand in major Indian metros, automotive OEMs and technology suppliers are initiating V2X pilot programs to test vehicle-to-infrastructure and vehicle-to-vehicle communication use cases. These pilots are expected to catalyze next-generation connected vehicle applications in safety and traffic management.
3. Integration of AI and Machine Learning (ML) in In-Vehicle Platforms
AI-powered voice assistants, predictive maintenance alerts, and personalized infotainment recommendations are being integrated into connected vehicle platforms, improving driver experience and reducing unplanned service events.
4. Growing Demand for Connected Commercial Fleet Management Solutions
Expanding e-commerce logistics, cold-chain transportation, and last-mile delivery networks are driving significant demand for real-time fleet visibility, route optimization, and driver behavior monitoring platforms. These solutions are generating recurring data subscription revenue streams for connectivity platform providers.
Industry Value Chain Analysis
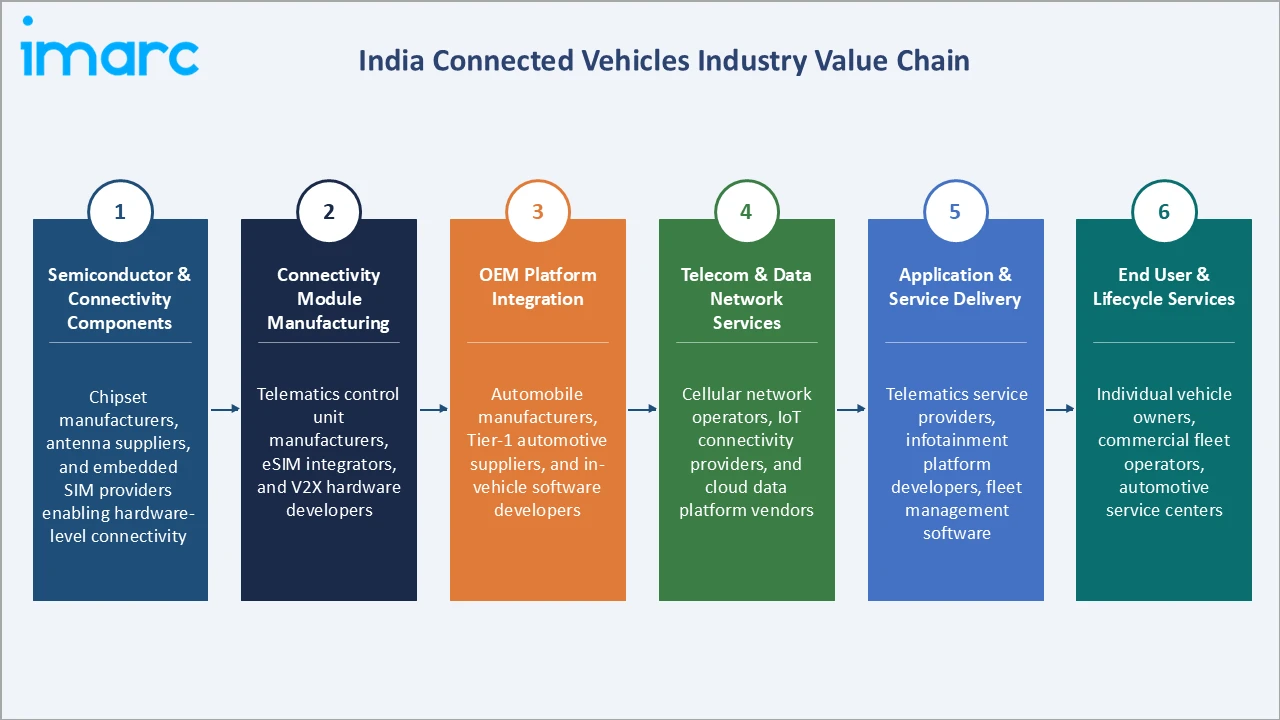
The India connected vehicles value chain spans six stages, from semiconductor and connectivity component manufacturing through end-user vehicle operation and lifecycle services. Connectivity platform integration, OEM embedding, and data service delivery capture the highest value-add, while raw material and component supply stages operate on narrower margins.
|
Stage |
Key Players / Examples |
|
Semiconductor & Connectivity Components |
Chipset manufacturers, antenna suppliers, and embedded SIM providers enabling hardware-level vehicle connectivity modules |
|
Connectivity Module Manufacturing |
Telematics control unit manufacturers, eSIM integrators, and V2X hardware developers supplying to OEM assembly lines |
|
OEM Platform Integration |
Automobile manufacturers, Tier-1 automotive suppliers, and in-vehicle software developers embedding connectivity into vehicle architectures |
|
Telecom & Data Network Services |
Cellular network operators, IoT connectivity providers, and cloud data platform vendors enabling vehicle data transmission and processing |
|
Application & Service Delivery |
Telematics service providers, infotainment platform developers, fleet management software companies, and ADAS solution vendors |
|
End User & Lifecycle Services |
Individual vehicle owners, commercial fleet operators, automotive service centers, and over-the-air update service providers |
Vertically integrated OEMs that own proprietary telematics platforms and direct end-user data relationships are positioned to capture greater value than institutions dependent on third-party connectivity module suppliers or cloud service providers.
Technology Landscape in the India Connected Vehicles Industry
4G/LTE and Emerging 5G Cellular Connectivity
LTE-based embedded connectivity modules have become the standard for factory-fitted vehicle applications in India, supporting telematics, infotainment data streaming, and remote diagnostics. Emerging 5G modules are being introduced by OEMs in premium vehicle segments, enabling ultra-low latency communication required for ADAS and V2X use cases.
Telematics and GPS-Based Fleet Management Technology
Advanced GPS-linked telematics systems provide real-time vehicle tracking, geofencing, driver behavior scoring, and fuel consumption analytics for commercial fleet operators. Growing integration with ERP and logistics management platforms is expanding telematics from standalone tracking to end-to-end fleet lifecycle management.
In-Vehicle Infotainment and Head Unit Platforms
Connected infotainment systems are evolving from proprietary OEM interfaces toward open operating system platforms that support third-party application ecosystems, voice assistants, and seamless smartphone mirroring, driving user engagement and enabling software monetization through connected subscriptions.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Technology Type |
4G/LTE |
74.6% |
2025 |
|
Application |
Telematics |
42.7% |
2025 |
|
Connectivity |
🔒 |
🔒 |
2025 |
|
Vehicle Connectivity |
🔒 |
🔒 |
2025 |
|
Vehicle |
🔒 |
🔒 |
2025 |
|
Region |
West India |
30.8% |
2025 |
By Technology Type
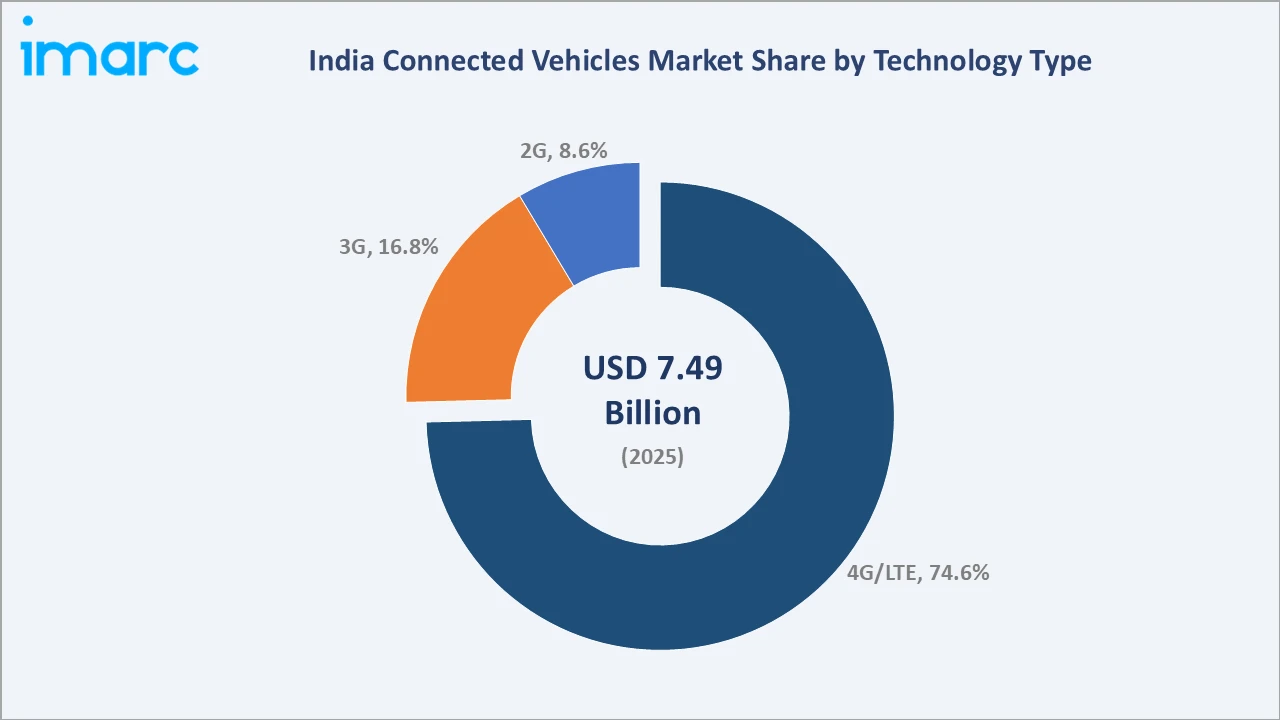
4G/LTE commands a 74.6% majority share in 2025, reflecting widespread cellular network availability and OEM preference for high-bandwidth embedded connectivity modules that support simultaneous telematics data transmission, infotainment streaming, and over-the-air software updates.
To access detailed market analysis, Request Sample
3G at 16.8% in 2025 remains relevant in aftermarket connectivity applications, cost-sensitive commercial vehicle categories, and older vehicle cohorts where backward compatibility with existing telematics infrastructure justifies legacy protocol retention.
By Application
Telematics leads the application segment at 42.7% in 2025, driven by mandatory commercial vehicle tracking regulations, growing fleet management adoption across logistics and e-commerce sectors, and expanding usage-based insurance programs that require real-time vehicle data collection and transmission.
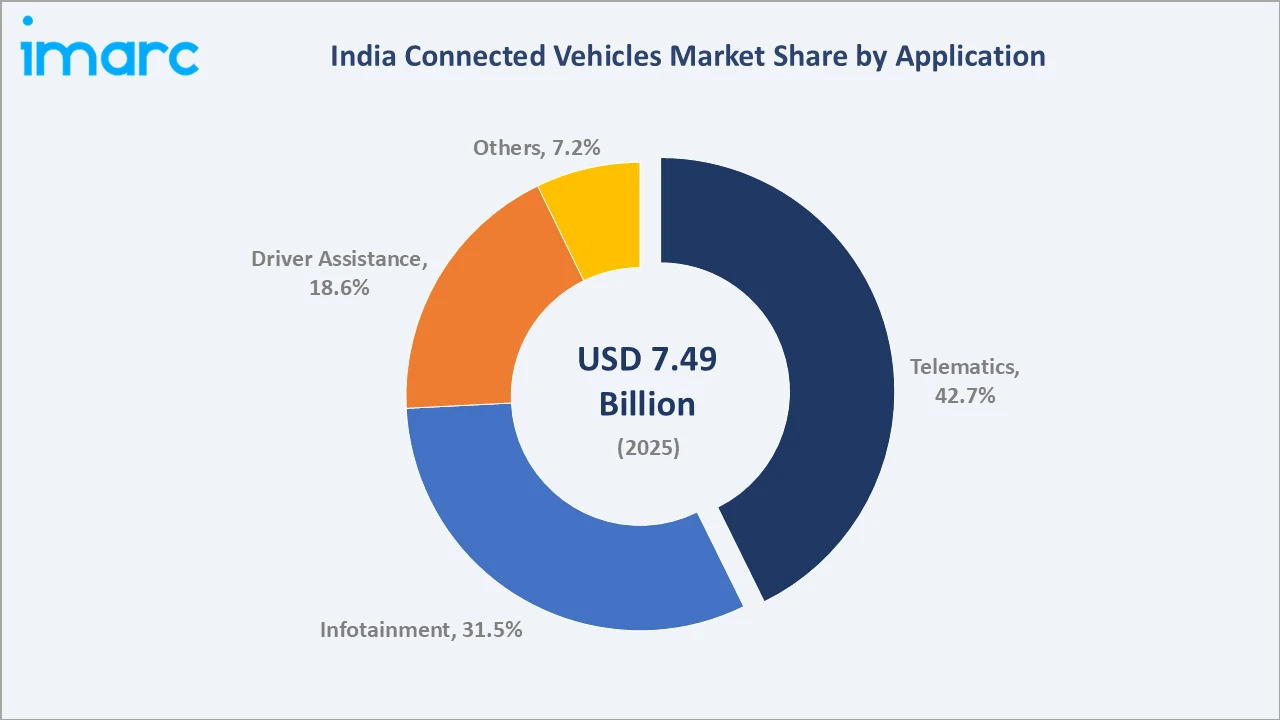
Infotainment at 31.5% in 2025 reflects rising consumer demand for integrated navigation, media streaming, and smartphone connectivity within vehicle cabins, with OEMs investing in connected head unit platforms across mid-range and premium segments.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
West India |
30.8% |
Concentrated OEM and Tier-1 supplier base, high vehicle density, mature digital infrastructure, and strong consumer purchasing power |
|
North India |
28.7% |
Large vehicle sales volumes, expanding commercial fleet networks, and growing government regulatory compliance requirements |
|
South India |
25.4% |
Strong technology and IT sector presence, high smartphone adoption, active telematics adoption in logistics, and growing OEM investment |
|
East India |
15.1% |
Expanding cellular coverage, rising vehicle registrations in tier-2 cities, and growing commercial fleet telematics demand |
West India at 30.8% in 2025 leads the regional landscape, supported by a concentrated automotive OEM and Tier-1 supplier base in Pune, Nashik, and Ahmedabad, a mature digital ecosystem, high vehicle density, and strong regulatory compliance infrastructure. The region's industrial clusters and consumer purchasing power reinforce connected vehicle adoption across both passenger and commercial vehicle categories.
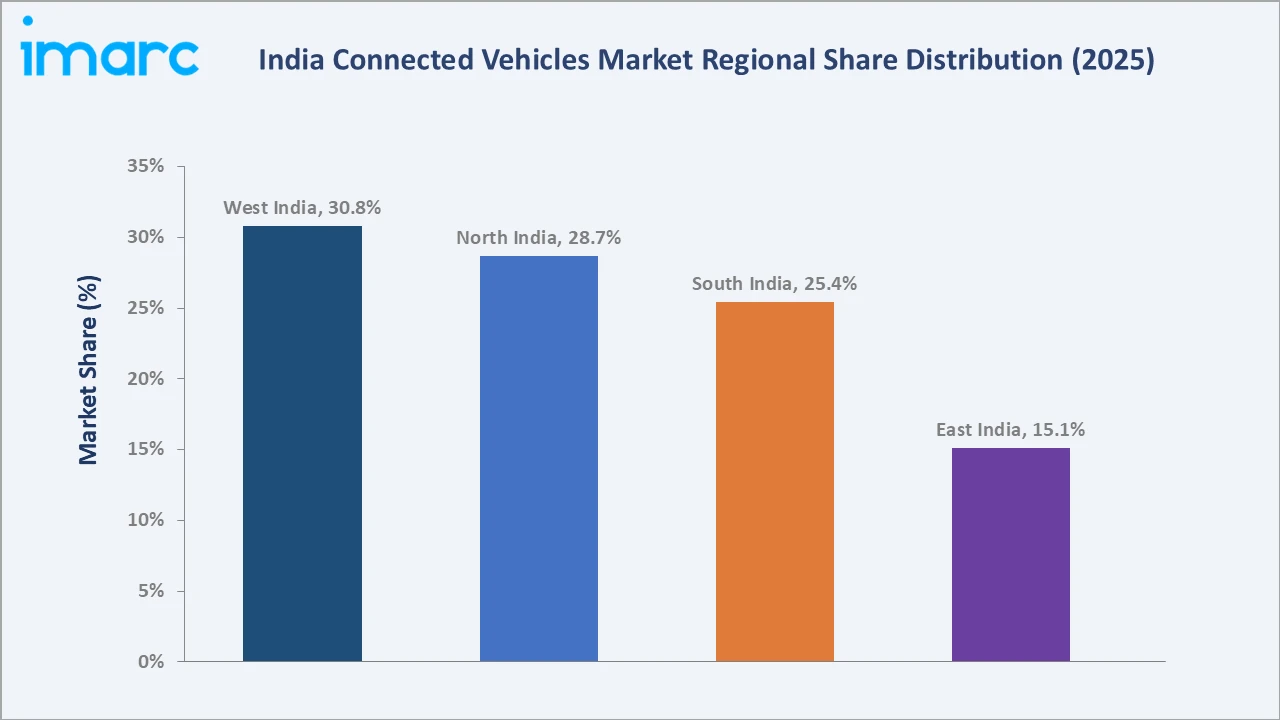
East India, while currently the smallest regional contributor at 15.1%, presents the fastest growth potential as expanding cellular infrastructure and growing vehicle sales in tier-2 cities in West Bengal, Odisha, and Assam attract OEM attention. Rising commercial vehicle fleet deployments for logistics and agriculture are creating early-stage demand for telematics services in the region.
Competitive Landscape
The India connected vehicles market is moderately concentrated, with established global automotive technology providers and domestic IT majors competing alongside specialized telematics and infotainment platform vendors. Connectivity module depth, OEM integration capability, regulatory compliance readiness, and data platform scalability form the key competitive differentiators across the industry.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
|
Robert Bosch GmbH |
Bosch Connected Mobility Solutions |
Leader |
Expanding connected vehicle platform portfolio and deepening OEM integration capabilities |
|
Continental AG |
Telematics Control Unit (TCU) |
Leader |
Growing telematics and V2X platform adoption across passenger and commercial vehicle segments |
|
Samsung Electronics Co., Ltd. |
HARMAN Ignite |
Leader |
Strengthening in-vehicle infotainment and connected services ecosystem across global OEM partnerships |
|
Visteon Corporation |
SmartCore Cockpit |
Challenger |
Growing digital cockpit and connected infotainment platform adoption among OEM partners |
Key players include Robert Bosch GmbH, Continental AG, Samsung Electronics Co., Ltd., and Visteon Corporation, among others.
Key Company Profiles
Robert Bosch GmbH
Robert Bosch GmbH is a global technology and engineering company headquartered in Gerlingen, Germany, providing connected mobility solutions, automotive sensors, telematics modules, and vehicle software to OEMs operating in India and internationally.
- Product Portfolio: Connected vehicle portfolio covering telematics control units, in-vehicle infotainment interfaces, and over-the-air update infrastructure for passenger and commercial vehicles.
- Recent Developments: Robert Bosch GmbH continues to develop its connected mobility product portfolio, investing in next-generation vehicle connectivity modules and cloud-based automotive platforms across key global and regional markets.
- Strategic Focus: Strengthening connected vehicle platform capabilities and enhancing OEM integration across passenger and commercial vehicle segments.
Continental AG
Continental AG is a Germany-based global automotive technology supplier providing telematics control units, intelligent transportation systems, and in-vehicle network components to vehicle manufacturers across India and other markets.
- Product Portfolio: Telematics control unit (TCU) and vehicle-to-cloud data management platforms.
- Recent Developments: Continental AG continues to advance its connected vehicle hardware and software capabilities, with ongoing investment in next-generation telematics and V2X communication solutions for OEM production programs.
- Strategic Focus: Driving telematics and V2X platform adoption across passenger and commercial vehicle OEM supply programs in India and international markets.
Samsung Electronics Co. Ltd.
Samsung Electronics Co. Ltd., through its wholly owned subsidiary HARMAN International, is a global technology company providing connected car solutions, infotainment systems, and digital cockpit platforms to automotive OEMs in India and globally.
- Product Portfolio: HARMAN Ignite connected services platform, digital cockpit solutions, infotainment systems, and connected vehicle software.
- Recent Developments: The firm continues to advance its connected vehicle platform capabilities, supporting OEM partners in delivering digital in-vehicle experiences and connected services across multiple vehicle programs.
- Strategic Focus: Expanding the in-vehicle infotainment and connected services ecosystem while strengthening partnerships with passenger vehicle OEMs worldwide.
Market Concentration Analysis
The India connected vehicles market is moderately concentrated, with global Tier-1 automotive technology suppliers and domestic engineering services firms collectively accounting for a significant portion of connectivity module supply and platform deployments across OEM programs. Scale, OEM integration depth, and regulatory compliance expertise create meaningful barriers to entry for smaller competitors.
Barriers to entry include high research and development investment requirements, the need for automotive-grade quality certifications, long OEM qualification cycles, and the technical complexity of integrating connectivity platforms with diverse vehicle electrical architectures. These factors favor established Tier-1 suppliers with proven OEM relationships and global scale.
Consolidation is increasing as global technology providers acquire specialized telematics and infotainment software companies to broaden platform capabilities. Strategic partnerships between OEMs, connectivity platform developers, and telecom operators are also shaping competitive positioning, with joint development agreements becoming a preferred model for platform differentiation.
Investment & Growth Opportunities
Fastest-Growing Segments
Driver assistance is expanding fastest among application categories, driven by increasing regulatory mandates for ADAS-linked safety systems and OEM investment in safety differentiation across mid-range vehicle platforms.
Emerging Markets
East India is the fastest-growing region, supported by rising vehicle registrations, expanding cellular infrastructure, and growing commercial fleet telematics demand from logistics and agriculture sectors. The region represents a significant untapped opportunity for connectivity platform providers and aftermarket telematics solution vendors able to deliver affordable, localized services.
Venture & Investment Trends
Investment activity is concentrated in connected EV platforms, AI-driven telematics analytics, and software-defined vehicle architectures. Capital is also flowing into fleet management SaaS platforms targeting India's expanding logistics and e-commerce delivery vehicle base, alongside cybersecurity solutions that address growing regulatory scrutiny of connected vehicle data protection requirements.
Future Market Outlook (2026-2034)
The India connected vehicles market is forecast to expand from USD 7.49 Billion in 2025 to USD 8.63 Billion in 2026, reaching USD 27.84 Billion by 2034, registering a CAGR of 15.24% during 2026–2034, adding approximately USD 19.21 Billion in incremental market value over the forecast period.
Four forces will shape the market through 2034: continued OEM adoption of factory-fitted embedded connectivity across all vehicle segments; expansion of 5G networks enabling V2X and advanced ADAS applications; growth of EVs creating new connectivity demand for remote battery monitoring and charging management; and deepening fleet telematics penetration across commercial vehicle operators in logistics, agriculture, and public transport.
By 2034, connected vehicles in India are expected to be defined by software-defined architectures, with OTA update capabilities and AI-powered infotainment and driver assistance features becoming standard across the mass-market vehicle segment. Continued government support for vehicle safety regulations and expanding cellular infrastructure investment are expected to further accelerate the growth of India's connected vehicles ecosystem.
Research Methodology
Primary Research
Primary research included structured interviews with automotive OEM technology executives, Tier-1 connectivity module suppliers, fleet management platform providers, and regulatory specialists, validating market sizing, segment mix, and regional demand patterns.
Secondary Research
Secondary sources included Ministry of Road Transport and Highways publications, NITI Aayog mobility reports, Telecom Regulatory Authority of India data, annual reports and investor presentations from listed automotive and technology companies, and industry association publications from SIAM and ACMA.
Forecasting Models
Market forecasts used top-down and bottom-up models combining vehicle production and sales volumes, connectivity module penetration rates, application adoption trends, and macroeconomic variables. Scenario analysis addressed regulatory developments, 5G infrastructure rollout pace, and EV adoption trajectories.
India Connected Vehicles Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Technology Types Covered | 4G/LTE, 3G, 2G |
| Applications Covered | Driver Assistance, Telematics, Infotainment, Others |
| Connectivities Covered | Integrated, Embedded, Tethered |
| Vehicle Connectivities Covered | Vehicle to Vehicle (V2V), Vehicle to Infrastructure (V2I), Vehicle to Pedestrian (V2P) |
| Vehicles Covered | Passenger Cars, Commercial Vehicle |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Robert Bosch GmbH, Continental AG, Samsung Electronics Co., Ltd., Visteon Corporation, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India connected vehicles market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India connected vehicles market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India connected vehicles industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Connected Vehicles Market Report
The India connected vehicles market is estimated at USD 8.63 Billion in 2026, supported by rising OEM adoption of factory-fitted telematics and expanding 4G/LTE network infrastructure.
The market is projected to grow at a CAGR of 15.24% from 2026-2034, reaching USD 27.84 Billion, driven by technology mandates and expanding digital mobility ecosystems.
4G/LTE leads the technology type segment at 74.6% in 2025, driven by wide network availability and OEM preference for high-bandwidth embedded connectivity modules.
Telematics commands the largest share at 42.7% in 2025, supported by commercial fleet tracking mandates, usage-based insurance programs, and growing fleet management adoption.
West India holds the largest regional share at 30.8% in 2025, driven by concentrated OEM manufacturing clusters and mature digital infrastructure in Maharashtra and Gujarat.
Key players include Robert Bosch GmbH, Continental AG, Samsung Electronics Co., Ltd., and Visteon Corporation, among others.
5G will enable ultra-low latency V2X communication, supporting advanced driver assistance and smart traffic management applications, accelerating next-generation connectivity adoption through 2034.
Expanding EV adoption is creating new demand for factory-fitted connectivity supporting battery monitoring, remote diagnostics, and charging management, making connectivity a standard EV feature.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade