
India Corrugated Boxes Market Size, Share, Trends and Forecast by Material Used, End Use, and Region, 2026-2034
India Corrugated Boxes Market Size, Share, Trends & Forecast (2026-2034)
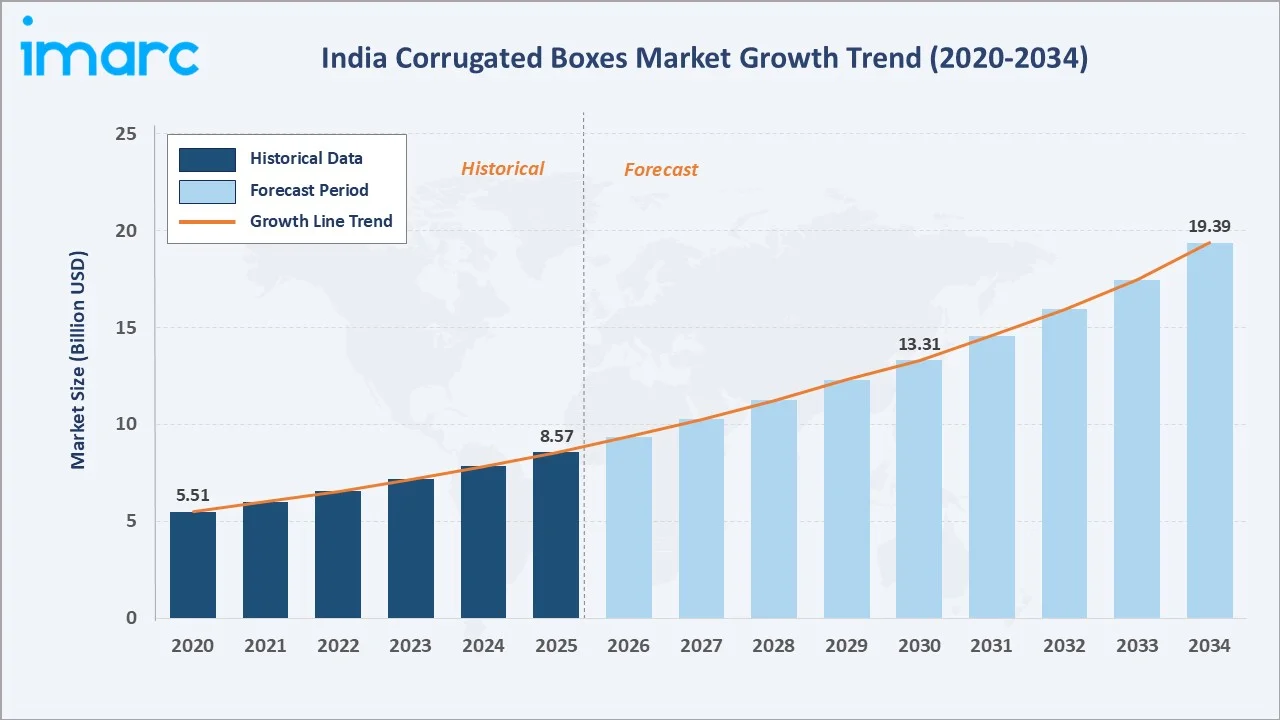
The India corrugated boxes market grew from USD 8.57 Billion in 2025 to USD 9.36 Billion in 2026 and is projected to reach USD 19.39 Billion by 2034, growing at a CAGR of 9.21% during 2026-2034. Market expansion is driven by rapid growth in organized retail, booming e-commerce penetration, and accelerating demand from India's food processing and FMCG industries. Recycled corrugates lead with a 62.7% material share in 2025, food products and beverages account for 31.8% of end-use demand, and West and Central India hold the largest regional share at 32.6%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 8.57 Billion |
|
Market Size (2026) |
USD 9.36 Billion |
|
Forecast Market Size (2034) |
USD 19.39 Billion |
|
CAGR (2026-2034) |
9.21% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Material Used |
Recycled Corrugates (62.7%, 2025) |
|
Dominant End Use |
Food Products & Beverages (31.8%, 2025) |
|
Leading Region |
West & Central India (32.6%, 2025) |
The India corrugated boxes market grew from approximately USD 5.51 Billion in 2020 to USD 8.57 Billion in 2025, reflecting robust historical growth. The market reached USD 9.36 Billion in 2026 and is estimated to cross USD 13.31 Billion by 2030 and is projected to reach USD 19.39 Billion by 2034, supported by rising packaging demand across food, FMCG, pharmaceutical, and e-commerce logistics sectors throughout India.
To get more information on this market, Request Sample
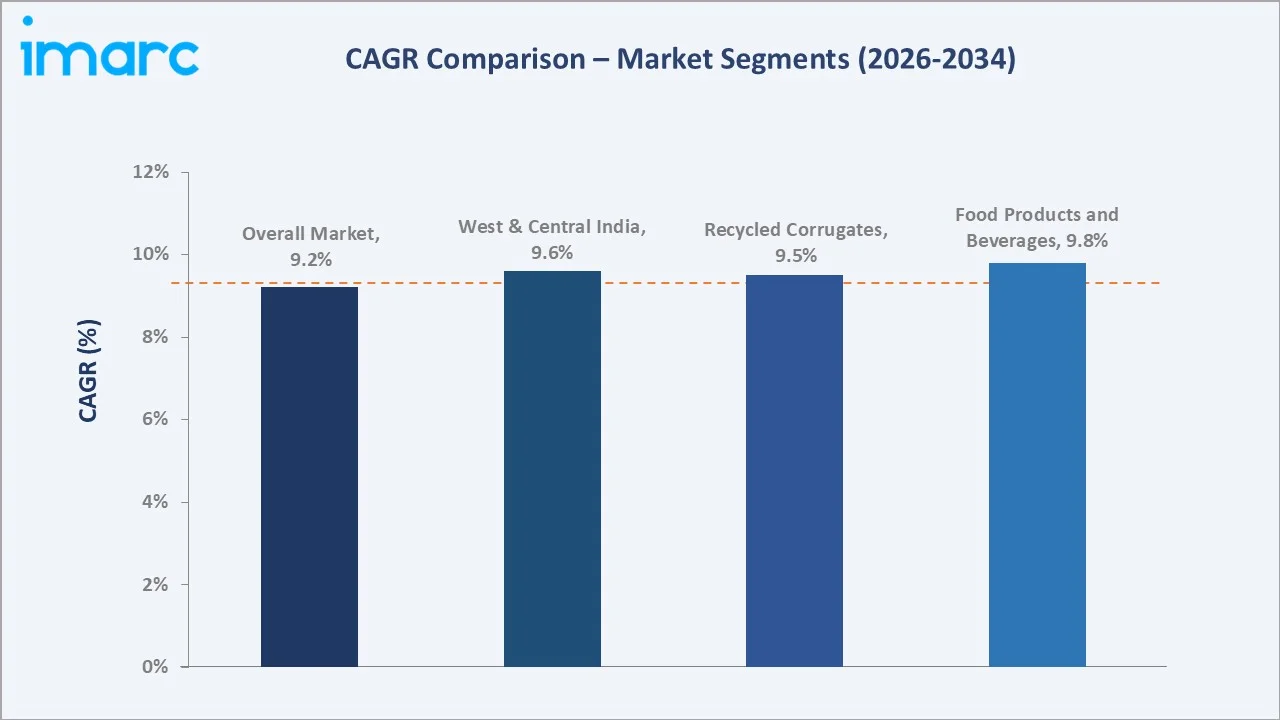
West & Central India is the fastest-growing at 9.6% CAGR, driven by expanding warehousing and logistics infrastructure and rapid FMCG distribution network growth. Food products and beverages at ~9.8% CAGR and recycled corrugates at ~9.5% CAGR represent the highest growth sub-segments through 2034.
Executive Summary
The India corrugated boxes market is experiencing sustained high-growth expansion, anchored by the country's booming e-commerce sector, accelerating organized retail penetration, and a rapidly maturing food processing industry that collectively drive demand for high-quality, cost-effective primary and secondary packaging solutions.
Recycled corrugates command a dominant 62.7% material share in 2025, driven by the lower production cost of recycled fiber-based liners, increasing availability of waste paper feedstock, and growing sustainability mandates from large brand owners and e-commerce majors requiring recycled content in their packaging specifications.
Food products and beverages account for 31.8% of end-use demand, reflecting the critical role of corrugated packaging in ambient food transport, beverage multipacks, and export-oriented processed food supply chains. West and Central India lead with a 32.6% regional share in 2025, anchored by the Maharashtra and Gujarat industrial clusters that house major food, chemical, and FMCG manufacturing capacity requiring high volumes of corrugated packaging.
Key Market Insights
|
Insight |
Data |
|
Dominant Material Used |
Recycled Corrugates (62.7%, 2025) |
|
Dominant End Use |
Food Products & Beverages (31.8%, 2025) |
|
Leading Region |
West & Central India (32.6%, 2025) |
|
Key Market Opportunity |
E-commerce logistics packaging and sustainable corrugated solutions |
Key Data-Driven Insights Shaping the India Corrugated Boxes Market Landscape:
- Recycled Corrugates at 62.7%: Recycled corrugates dominate the market, supported by the lower feedstock cost of recovered wastepaper and increasing large brand owner mandates requiring recycled-content packaging as part of extended producer responsibility and corporate sustainability commitments.
- Food Products & Beverages at 31.8%: Food products and beverages drive corrugated packaging demand, reflecting the sector's extensive reliance on corrugated secondary and transit packaging for perishable distribution, export supply chains, and retail-ready packaging formats across India's growing organized grocery sector.
- West & Central India at 32.6%: West and Central India holds a high regional market share supported by the industrial clusters housing major FMCG, chemical, and food processing manufacturing that generate sustained high-volume corrugated packaging demand.
India Corrugated Boxes Market Overview
Corrugated boxes are multi-layered paperboard packaging structures comprising one or more layers of fluted corrugated medium sandwiched between flat liner sheets, engineered to provide superior stacking strength, vibration dampening, and transit protection for packaged goods across virtually every consumer and industrial supply chain. India's corrugated box manufacturing industry serves as a critical enabling infrastructure for the country's rapidly modernizing consumer goods, agricultural, pharmaceutical, and export logistics supply chains, with demand closely correlated with GDP growth, manufacturing output, and the expansion of organized retail and e-commerce channels.
The Indian corrugated packaging ecosystem encompasses waste paper and virgin pulp aggregators, integrated paper and board mills, corrugating machinery operators, box converting facilities ranging from small regional converters to large integrated manufacturers, and distribution channels spanning direct-to-manufacturer sales and packaging distributors. Government initiatives under Make in India, PLI schemes for food processing, and rapid infrastructure development are structurally expanding the manufacturing base that generates corrugated packaging demand.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
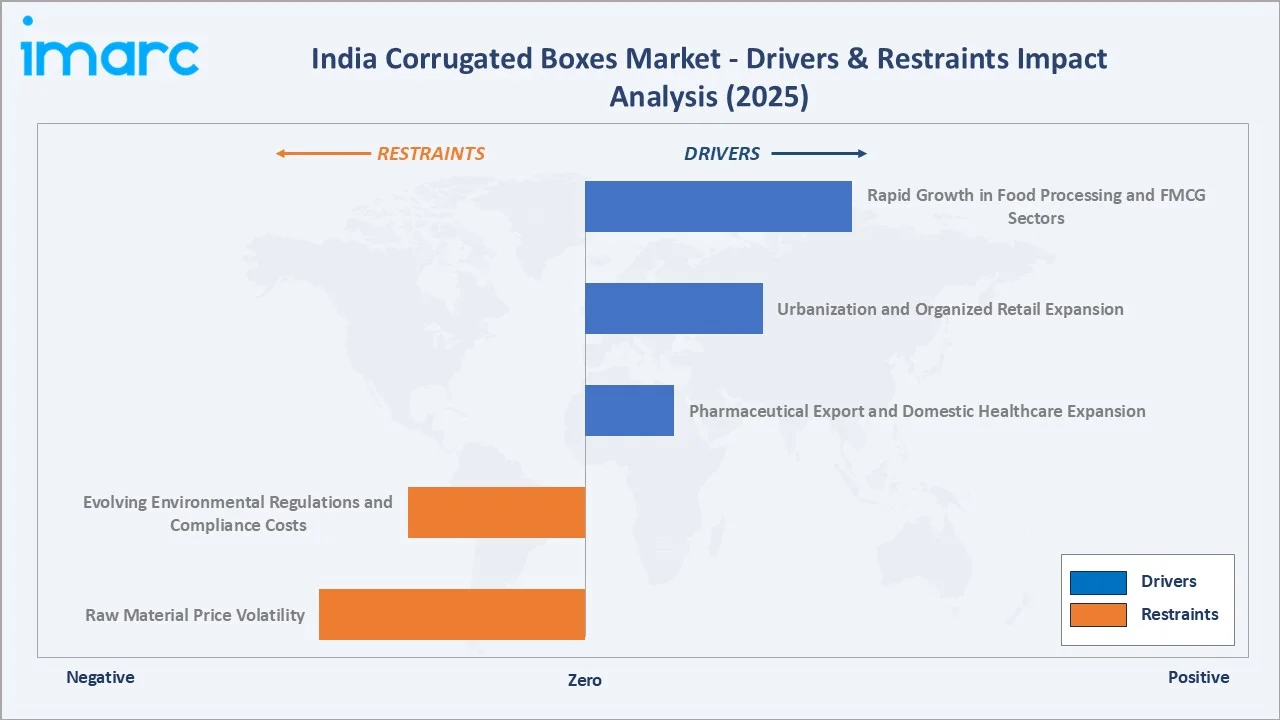
- Rapid Growth in Food Processing and FMCG Sectors: For 2024–25, the Ministry’s budget allocation for the food processing sector increased by approximately 30.19% over the previous year. India's food processing industry relies extensively on corrugated packaging for primary, secondary, and transit packaging of processed foods, beverages, dairy, and agricultural commodities. Government PLI schemes for food processing are accelerating capacity additions that directly expand corrugated demand across this largest end-use segment.
- Urbanization and Organized Retail Expansion: India’s urban population is projected to reach 40% by 2030, while urban areas are expected to contribute approximately 75% of India’s GDP. India's accelerating urbanization and the expansion of organized grocery, consumer electronics, and fashion retail chains require standardized, brand-compliant corrugated secondary packaging for efficient store replenishment and retail-ready shelf displays.
- Pharmaceutical Export and Domestic Healthcare Expansion: India’s pharmaceutical industry ranks third globally in terms of production volume and 11th in terms of market value, comprising over 3,000 pharmaceutical companies and approximately 10,500 manufacturing facilities. Rising domestic pharmaceutical manufacturing capacity and India's position as the leading generic drug exporter drive demand for pharmaceutical-grade corrugated shippers and transit packaging compliant with international regulatory standards.
Market Restraints
- Raw Material Price Volatility: Corrugated box manufacturing costs are significantly influenced by wastepaper, recycled fiber, and virgin kraft pulp prices, which are subject to global commodity market fluctuations and domestic wastepaper collection efficiency. Price volatility compresses converter margins and periodically disrupts procurement planning for large end-users operating under fixed packaging budget cycles.
- Evolving Environmental Regulations and Compliance Costs: Increasing regulatory focus on plastic packaging has heightened scrutiny of packaging materials broadly. While corrugated is largely viewed favorably as a sustainable material, evolving extended producer responsibility regulations and state-level packaging mandates create compliance complexity that can temporarily disrupt established supply chain packaging specifications.
Market Opportunities
- E-Commerce Fulfillment Packaging Expansion: E-commerce logistics packaging represents the single largest near-term incremental growth opportunity, as India's online retail sector expands into Tier-2 and Tier-3 cities requiring localized corrugated packaging supply chains capable of serving last-mile delivery networks with right-sized, lightweight packaging solutions.
- Sustainable Packaging Innovation: Sustainable corrugated innovations including high-recycled-content grades, biodegradable coatings replacing plastic lamination, and water-based inks are gaining rapid traction among large brand owners committing to science-based sustainability targets that specify corrugated packaging sustainability criteria.
Market Challenges
- Market Fragmentation and Pricing Pressure: India's corrugated box market is characterized by a large number of small and medium-scale regional converters operating alongside large integrated manufacturers. This fragmented structure creates pricing pressure, quality inconsistency, and challenges for end-users seeking consistent, standardized packaging supply across geographically distributed manufacturing operations.
- Moisture Sensitivity and Quality Consistency Challenges: Corrugated box quality is sensitive to moisture and humidity during storage and transit in India's tropical climate. Maintaining packaging integrity across long distribution chains, particularly for export shipments and agricultural products requiring refrigerated logistics, requires technical investment in moisture-resistant liner grades that increase material costs.
Emerging Market Trends
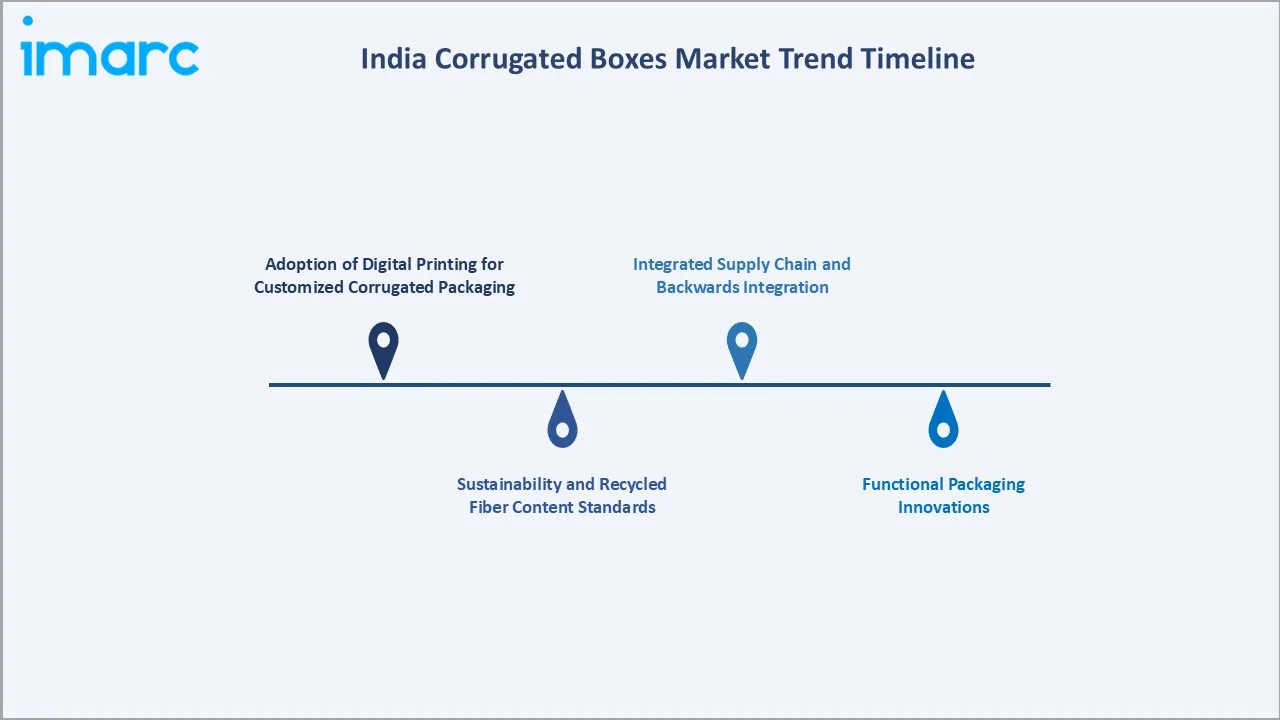
1. Adoption of Digital Printing for Customized Corrugated Packaging
The India corrugated boxes market is witnessing a shift toward digital printing solutions to meet growing demand for short-run, customized, and on-demand packaging. In October 2026, PixelJet launched its Aquablaze digital press for water-based packaging applications at Anuga FoodTech 2026 in Mumbai, targeting the growing demand for short-run and customized corrugated packaging. Designed for applications such as pizza boxes, the press uses water-based dye and pigment inks and offers greater flexibility to corrugated box manufacturers compared with conventional printing methods.
2. Sustainability and Recycled Fiber Content Standards
The brand owners operating in India are progressively mandating higher recycled fiber content in corrugated packaging specifications as part of science-based sustainability commitments. India's growing domestic wastepaper collection infrastructure and the expansion of organized recycling aggregators are improving recycled fiber availability, supporting the shift toward higher post-consumer recycled content grades without compromising box performance specifications.
3. Integrated Supply Chain and Backwards Integration
Leading corrugated box manufacturers are investing in backward integration into paper and board manufacturing to secure raw material supply, stabilize input costs, and improve margin resilience against commodity price cycles. This consolidation trend is increasing the scale and competitive advantage of India's largest corrugated packaging groups relative to smaller regional converters.
4. Functional Packaging Innovations
The development of moisture-resistant, humidity-buffering, and grease-resistant corrugated grades is expanding the addressable application scope beyond traditional dry goods packaging into fresh food, cold chain, and food service applications. Bio-based and compostable barrier coatings replacing plastic film lamination are gaining commercial traction in food and pharmaceutical packaging segments driven by brand sustainability commitments and regulatory tailwinds.
Industry Value Chain Analysis
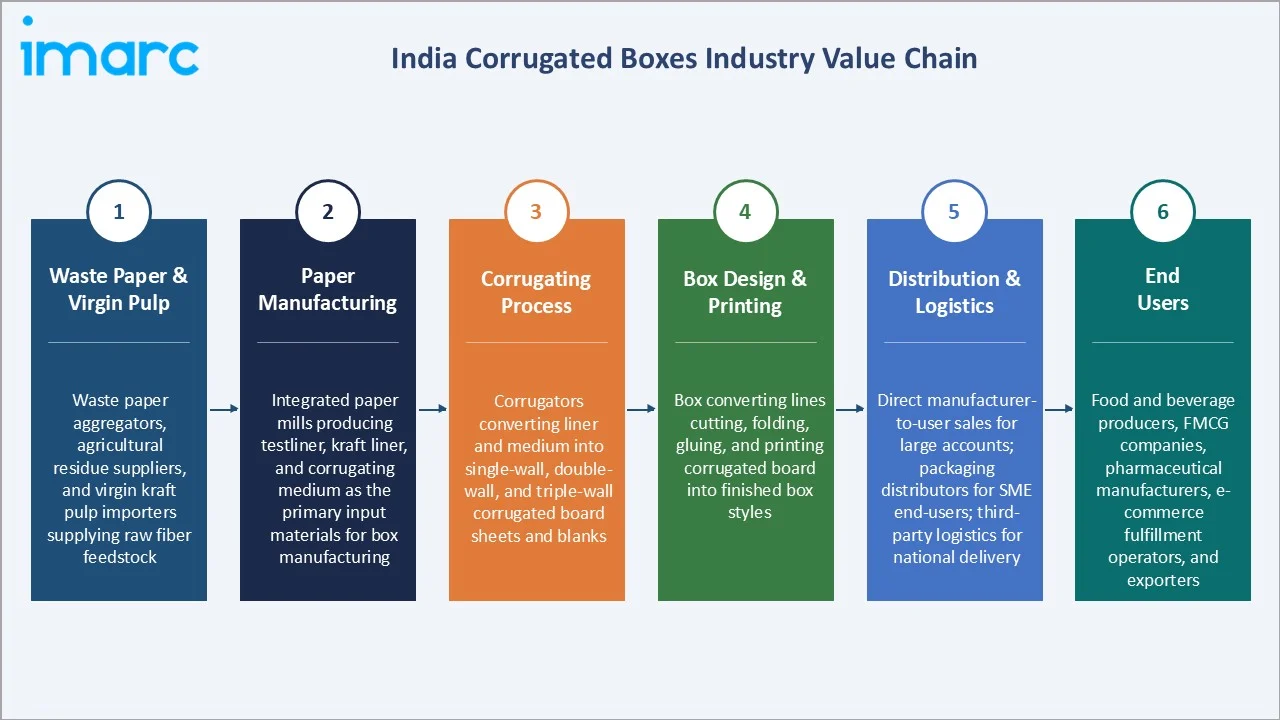
The India corrugated boxes value chain spans wastepaper and virgin pulp aggregation, paper and board manufacturing, corrugating and converting, box design and printing, and distribution to end users. The chain integrates both formal large-scale integrated players and a large informal sector of small, corrugated converters serving regional markets.
|
Stage |
Description |
|
Waste Paper & Virgin Pulp |
Waste paper aggregators, agricultural residue suppliers, and virgin kraft pulp importers supplying raw fiber feedstock. |
|
Paper Manufacturing |
Integrated paper mills producing testliner, kraft liner, and corrugating medium as the primary input materials for box manufacturing. |
|
Corrugating Process |
Corrugators converting liner and medium into single-wall, double-wall, and triple-wall corrugated board sheets and blanks. |
|
Box Design & Printing |
Box converting lines cutting, folding, gluing, and printing corrugated board into finished box styles. |
|
Distribution & Logistics |
Direct manufacturer-to-user sales for large accounts; packaging distributors for SME end-users; third-party logistics for national delivery. |
|
End Users |
Food and beverage producers, FMCG companies, pharmaceutical manufacturers, e-commerce fulfillment operators, and exporters. |
The highest value-added stages within the corrugated boxes value chain are box design and printing, where customization, print quality, structural engineering, and lead time responsiveness differentiate converters and support premium pricing. Integrated manufacturers that control both paper production and converting capture a significantly greater share of the total value chain margin, providing competitive cost advantages over pure converters dependent on open-market board procurement at spot prices.
Technology Landscape in the India Corrugated Boxes Industry
High-Speed Corrugating Lines and Automation
Modern corrugated manufacturing plants in India are deploying high-speed single-facer and double-backer corrugating lines operating at 200-300 meters per minute, significantly improving throughput per production shift and reducing per-unit manufacturing cost relative to older-generation equipment. Advanced process control systems maintain flute geometry, glue application consistency, and board warp parameters within tight tolerances critical for high-speed downstream converting operations.
Digital and Flexographic Printing Technology
Water-based flexographic printing and single-pass digital inkjet printing systems are enabling Indian corrugated manufacturers to deliver high-resolution graphics, multi-color brand packaging, and variable data printing on corrugated surfaces without the setup costs and minimum order quantities associated with traditional multi-pass printing. These technologies are particularly valuable for e-commerce and FMCG customers requiring short-run seasonal and regional packaging variants.
Sustainable Material Science Innovation
Research and commercial adoption of bio-based barrier coatings, water-resistant starch-based adhesives, and high-performance recycled fiber paper grades are enabling Indian corrugated manufacturers to deliver packaging that meets moisture resistance, food contact safety, and sustainability requirements simultaneously. These innovations are expanding the addressable application range of corrugated packaging into traditionally plastic-dominated food and fresh produce packaging categories.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
| Material Used | Recycled Corrugates | 62.7% | 2025 |
| End Use | Food Products and Beverages | 31.8% | 2025 |
| Region | West and Central India | 32.6% | 2025 |

By Material Used
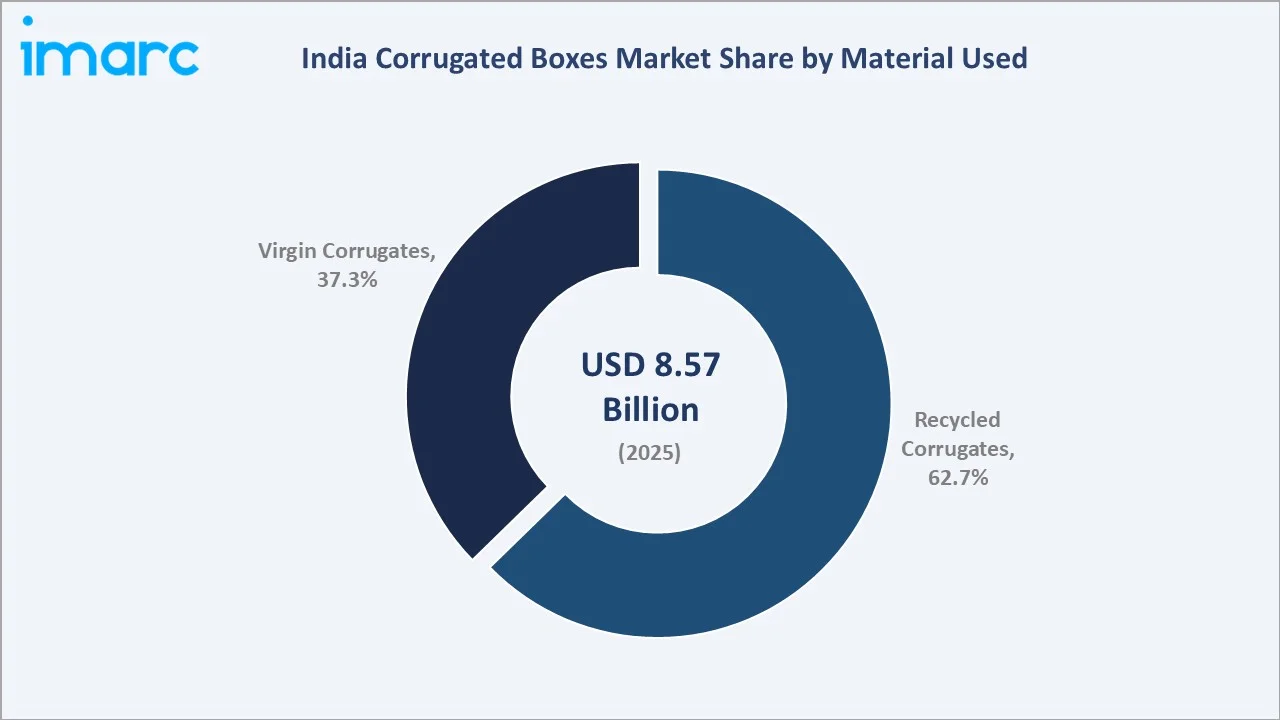
Recycled corrugates represent the dominant segment with 62.7% market share in 2025, reflecting their widespread adoption across the full spectrum of corrugated packaging applications from FMCG transit boxes to e-commerce shipping cartons and agricultural export packaging.
To access detailed market analysis, Request Sample
Virgin corrugates account for 37.3% of the market, serving applications requiring higher burst strength, superior print quality, and food contact compliance, including pharmaceutical packaging, premium consumer goods, and export-grade fresh produce and seafood packaging where box performance under challenging transit conditions is critical.
By End Use
Food products and beverages represent the largest end-use segment, accounting for 31.8% of corrugated packaging demand in India in 2025. The food processing industry's extensive reliance on corrugated secondary packaging for ambient food, dairy, beverage, and agricultural commodity distribution underpins this segment's dominant position.
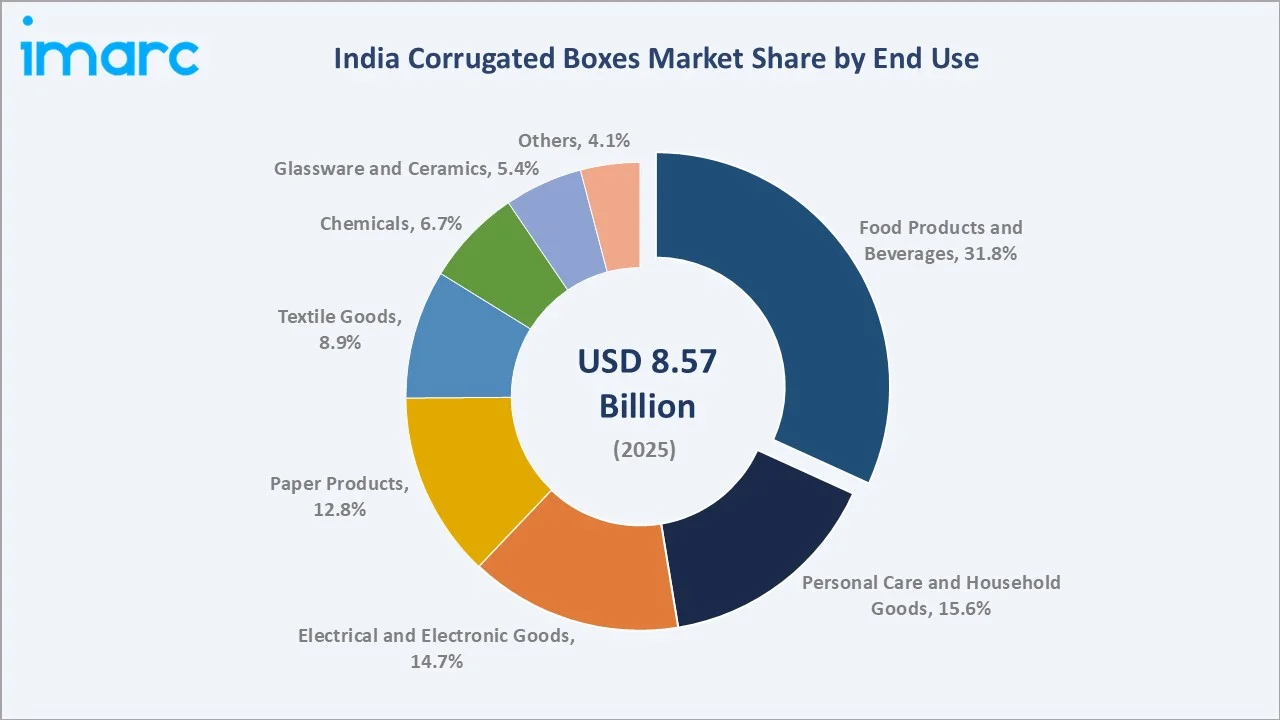
Personal care and household goods account for 15.6% of demand, driven by India's growing organized FMCG sector and the expansion of modern retail channels requiring shelf-ready corrugated secondary packaging. Electrical and electronic goods represent 14.7% of demand, reflecting India's rapidly expanding consumer electronics market and growing domestic manufacturing of appliances and electronics under the PLI scheme. Paper products account for 12.8%, followed by textile goods at 8.9%, chemicals at 6.7%, glassware and ceramics at 5.4%, and others at 4.1%, reflecting the broad cross-sectoral utility of corrugated packaging across India's diversified manufacturing economy.
Regional Market Insights
|
Region |
Share (2025) |
Key Characteristics |
|
West & Central India |
32.6% |
Major FMCG, chemical, and food processing industrial clusters and strong packaging demand from export-oriented manufacturing. |
|
North India |
29.4% |
Rapidly expanding logistics hub, agricultural packaging, and growing e-commerce fulfillment infrastructure. |
|
South India |
23.1% |
Pharmaceutical and electronics manufacturing and growing food processing and export packaging demand. |
|
East India |
14.9% |
Emerging industrial corridor, government-led manufacturing investments, and growing jute and tea export packaging requirements. |
West and Central India holds the largest regional share at 32.6% in 2025, anchored by the industrial clusters that collectively host a significant portion of India's FMCG manufacturing, chemical production, and food processing capacity. North India follows with a 29.4% share, driven by the rapidly growing warehousing and logistics ecosystem serving India's largest e-commerce market, combined with agricultural packaging demand from extensive food grain and horticultural production belts.
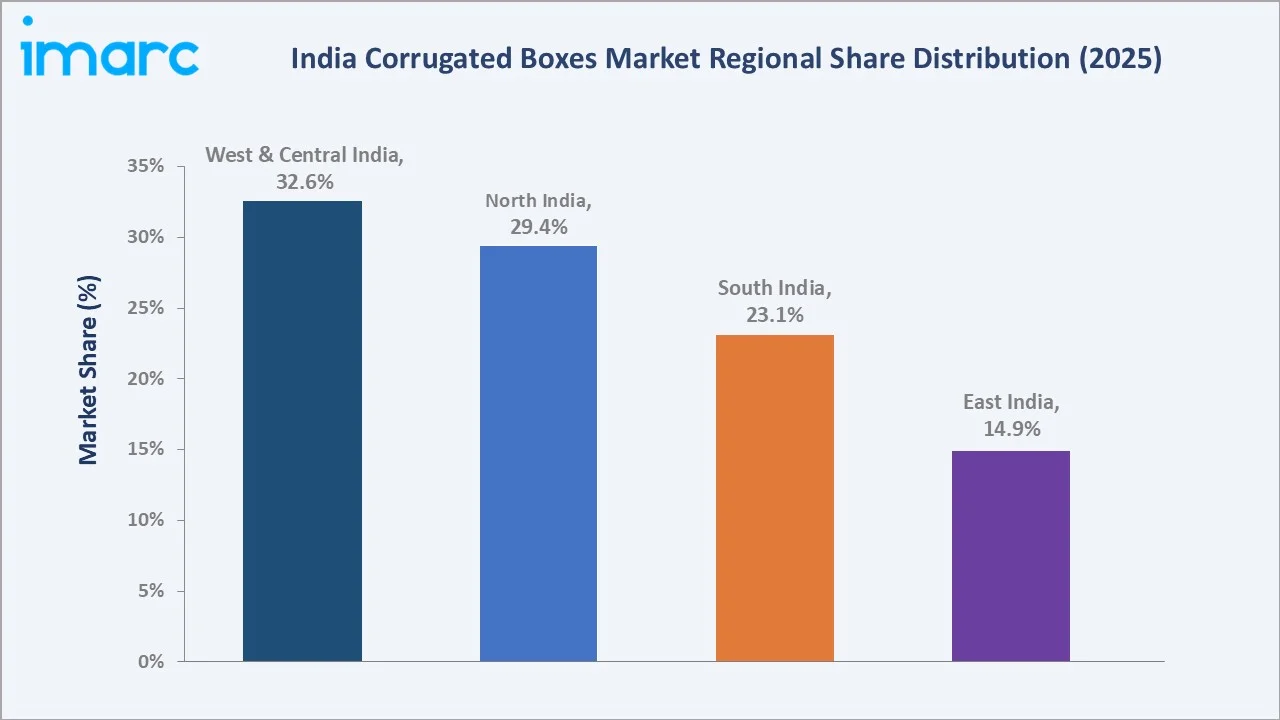
South India accounts for 23.1% of the market, with strong pharmaceutical and electronics packaging demand from industrial zones, alongside a growing food processing and seafood export sector that drives specialized moisture-resistant corrugated packaging requirements. East India holds a 14.9% share and represents an emerging growth region, with government-driven industrial development initiatives, expanding consumer goods manufacturing, and traditional tea and jute export packaging demand providing the foundation for above-average regional market growth as investment into Eastern India's industrial corridors accelerates through 2034.
Competitive Landscape
The India corrugated boxes market exhibits moderate fragmentation, with large integrated manufacturers holding significant regional share alongside a vast base of small and medium-scale regional corrugated converters. The top players compete on product quality, converting capabilities, print technology, geographic reach, and backward integration into paper and board manufacturing, which provides meaningful cost and supply chain advantages in a commodity-sensitive market.
|
Company |
Key Offerings |
Market Position |
Core Strengths |
| ITC Limited | Flexo Corrugated Boxes | Market Leader | ITC Limited plays a major role in India’s corrugated and specialized packaging industry through its Packaging and Printing Business and its upstream Paperboards and Specialty Papers Division. |
| International Paper | Corrugated Fanfold, Corrugated Cardboard Sheets, DryPack Corrugated Fish Box | Challenger | International Paper is a leader in the manufacture of renewable, fiber-based packaging, producing fully recyclable corrugated boxes. |
| Smurfit Westrock | Bespoke corrugated cardboard packaging | Established Player | Smurfit Westrock operates in India through its subsidiary, WestRock India Private Limited, contributing to the country's paper-based and corrugated packaging ecosystem. |
| JK Paper Ltd | E-Flute Corrugated Boxes, Corrugated Trays & Bin Boxes | Innovator | JK Paper Ltd. is currently one of the largest players in the corrugated boxes segment in India. |
The competitive landscape is defined by the significant advantage that integrated manufacturers hold through control of the paper-to-box value chain, which enables better margin management against raw material price volatility and faster lead times relative to pure converters dependent on board market procurement.
Key Company Profiles
ITC Limited
ITC Limited is the market leader in India's corrugated packaging segment, operating as a large-scale integrated manufacturer with direct access to ITC's paperboard production assets that supply premium virgin fiber board for its corrugated product range. The division operates technologically advanced corrugating and converting facilities serving India's largest FMCG, food, and consumer goods companies with corrugated transit packaging and retail-ready secondary packaging solutions. ITC's integrated operations spanning paper manufacturing through converting provide a structural cost and quality advantage over non-integrated competitors, reinforcing its market leadership position.
- Key Offerings: Flexo Corrugated Boxes.
- Strategic Focus: Deepening integration across the paperboard-to-box value chain, expanding sustainable corrugated product range with recycled fiber content, and growing share of premium food and FMCG packaging accounts.
International Paper
International Paper's India operations serve as a premium kraft liner and paperboard supplier supporting the Indian corrugated supply chain, with its recognized product quality standards making its output the preferred input for premium corrugated grades serving pharmaceutical, electronics, and export-oriented food packaging applications. The company's deep experience in sustainable paper manufacturing and its commitment to certified fiber sourcing align with the growing sustainability requirements of multinational brand owners operating corrugated supply chains in India.
- Key Offerings: Corrugated Fanfold, Corrugated Cardboard Sheets, DryPack Corrugated Fish Box.
- Strategic Focus: Strengthening premium segment positioning through certified sustainable fiber grades, expanding pharmaceutical and export packaging market penetration, and growing direct converter supply partnerships across India.
Market Concentration Analysis
The India corrugated boxes market demonstrates moderate fragmentation, with large integrated manufacturers holding significant positions but competing alongside a substantial base of regional small and medium-scale converters serving local markets.
The dual-tier market structure reflects both the capital-intensive nature of integrated manufacturing operations and the structural advantages that regional proximity and established local customer relationships provide to smaller converters in a market where logistics costs and lead time responsiveness are key procurement criteria.
Consolidation is gradually accelerating as integrated manufacturers invest in new capacity and regional acquisitions, while smaller converters face margin pressure from raw material cost volatility, technology investment requirements, and growing quality and sustainability specification demands from organized FMCG and e-commerce customers.
Investment & Growth Opportunities
Fastest Growing Segments
West & Central India is the fastest-growing at 9.6% CAGR. Food products and beverages at ~9.8% CAGR and recycled corrugates at ~9.5% CAGR represent the highest growth segments through 2034.
Investment Themes
- E-Commerce Fulfillment Packaging Platforms: E-commerce packaging infrastructure investment, including automated box-making systems, digital printing lines, and right-sizing technology platforms, represents the most compelling near-term investment theme, enabling manufacturers to capture premium pricing from e-commerce fulfillment operators requiring custom-specification, brand-compliant shipping packaging.
- Vertical Integration and Raw Material Security: Backward integration into paperboard and testliner manufacturing provides a durable cost advantage and margin resilience, making investment in integrated paper-to-box manufacturing operations the most strategically defensible position in India's corrugated packaging value chain for companies with sufficient capital.
- Export-Grade Agricultural and Food Packaging: Agricultural export packaging innovation for fresh produce, seafood, processed food, and horticultural products represents a high-value growth opportunity, requiring specialized moisture-resistant corrugated grades and export-certified structural designs that command premium pricing over standard domestic-grade corrugated transit packaging.
Future Market Outlook (2026-2034)
The India corrugated boxes market grew from USD 8.57 Billion in 2025 to USD 9.36 Billion in 2026 and is projected to reach USD 19.39 Billion by 2034, growing at a CAGR of 9.21% during 2026-2034. This robust growth trajectory reflects the structural alignment of India's corrugated packaging demand with the country's broad economic expansion, manufacturing sector growth, and the deepening penetration of organized retail and e-commerce channels that systematically convert unpackaged or loosely packaged goods flows into corrugated-intensive supply chains.
Three structural forces will define the India corrugated boxes market through 2034. First, the sustained expansion of India's e-commerce sector into smaller cities and the associated buildout of logistics infrastructure will create an increasingly large and geographically distributed corrugated demand base that rewards manufacturers with national supply capabilities and digital printing flexibility.
Second, the integration of sustainability requirements into corrugated packaging specifications by multinational brand owners and large domestic FMCG companies will progressively differentiate manufacturers capable of supplying certified sustainable corrugated grades, accelerating consolidation around quality-oriented integrated players. Third, India's ambition to become a leading global manufacturing hub under Make in India and PLI schemes will generate growing export-oriented packaging demand requiring premium corrugated grades that meet international buyer specifications across food, pharmaceutical, electronics, and engineering goods export supply chains.
Research Methodology
Primary Research
Primary research involved structured interviews with corrugated box manufacturers, paper mill executives, packaging procurement managers, FMCG supply chain directors, and e-commerce logistics operators across India's major industrial regions. Over 120 primary interactions informed market sizing, competitive positioning, end-use demand analysis, and regional market dynamics, including raw material supply chains and technology adoption trends.
Secondary Research
Secondary research encompassed Indian Corrugated Cases Manufacturers Association (ICCMA) publications, Confederation of Indian Industry packaging sector reports, BIS standards for corrugated packaging, company annual reports, government industrial production data from the Ministry of Commerce and Industry, and trade publications from the Indian Paper Manufacturers Association and Packaging Industry Association of India.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling approaches. Bottom-up analysis aggregated corrugated packaging demand across end-use sectors, material grades, and geographies using production output and consumption data. Top-down validation cross-referenced total market estimates against India's manufacturing GDP growth trajectories and packaging intensity benchmarks from comparable emerging markets at similar development stages.
India Corrugated Boxes Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Materials Used Covered | Recycled Corrugates, Virgin Corrugates |
| End Uses Covered | Food Products and Beverages, Paper Products, Electrical and Electronic Goods, Personal Care and Household Goods, Chemicals, Glassware and Ceramics, Textile Goods, Others |
| Regions Covered | North India, West and Central India, South India, East India |
| Companies Covered | ITC Limited, International Paper, Smurfit Westrock, JK Paper Ltd, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Frequently Asked Questions About the India Corrugated Boxes Market Report
The India corrugated boxes market reached USD 8.57 Billion in 2025, driven by strong demand from food processing, FMCG, e-commerce logistics, and pharmaceutical packaging sectors across the country.
The market is projected to grow at a CAGR of 9.21% during 2026-2034, reaching USD 19.39 Billion by 2034, driven by e-commerce expansion, organized retail growth, and food processing sector investments.
The India corrugated boxes market is forecast to reach USD 19.39 Billion by 2034, expanding from USD 9.36 Billion in 2026 as manufacturing growth, organized retail penetration, and e-commerce logistics demand accelerate nationally.
Recycled corrugates dominate with a 62.7% material share in 2025, driven by their lower production cost, improving recycled fiber availability, and growing brand owner mandates for recycled-content packaging.
Food products and beverages represent 31.8% of corrugated packaging demand in 2025, reflecting the food processing industry's extensive reliance on corrugated secondary packaging for distribution, export, and retail supply chains.
West and Central India lead with 32.6% market share in 2025, anchored by the industrial clusters hosting major FMCG, chemical, and food processing manufacturing capacity.
Key players include ITC Limited, International Paper, Smurfit Westrock, and JK Paper Ltd, among others.
Key opportunities include e-commerce right-sizing packaging solutions, sustainable recycled-content corrugated grades, agricultural and food export packaging, digital printing for short-run FMCG packaging, and pharmaceutical secondary packaging growth.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade