India FemTech Market Size, Share, Trends and Forecast by Type, Application, End Use, and Region, 2026-2034
India FemTech Market Size, Share, Trends & Forecast (2026-2034)
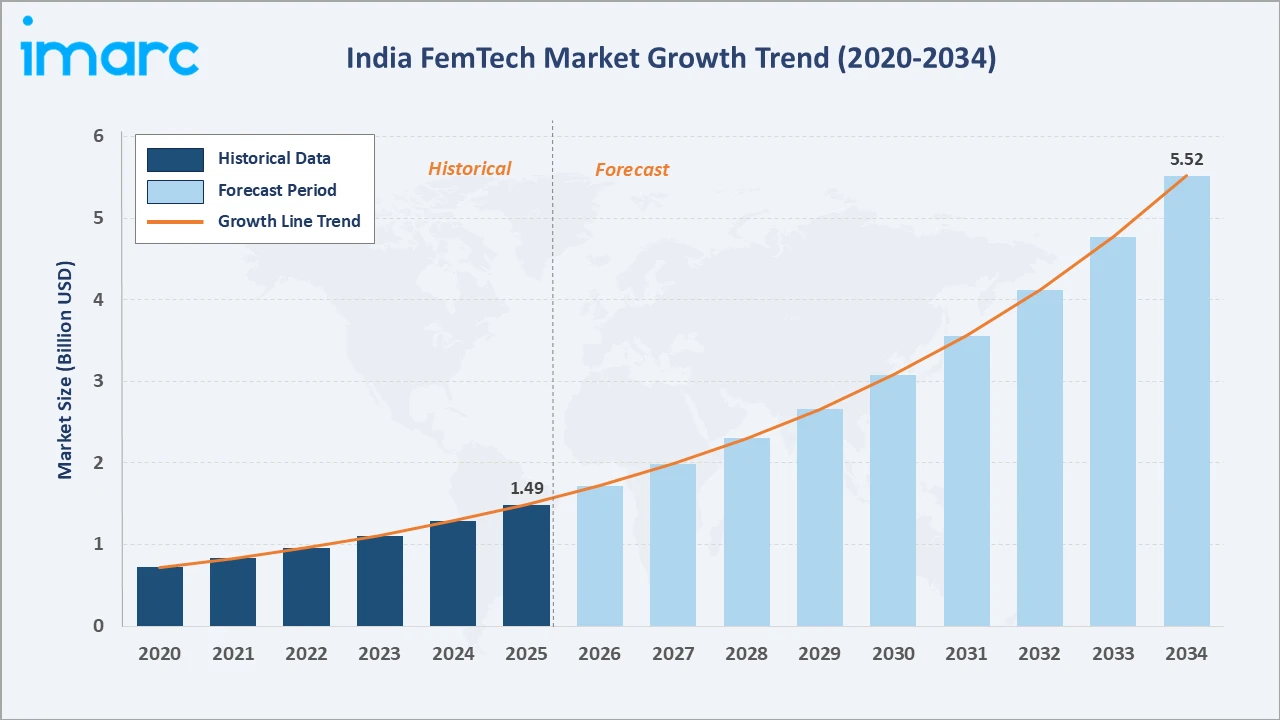
The India FemTech market grew from USD 1.49 Billion in 2025 to USD 1.72 Billion in 2026 and is projected to reach USD 5.52 Billion by 2034, exhibiting a CAGR of 15.70% during 2026-2034. Rising awareness of women's health, expanding smartphone penetration, and increasing consumer acceptance of digital health solutions are the primary forces shaping market growth.
Devices lead the type segment at 38.0%, direct to consumer dominates the end use segment at 26.0%, and North India commands 29.0% of regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 1.49 Billion |
|
Market Size (2026) |
USD 1.72 Billion |
|
Forecast Market Size (2034) |
USD 5.52 Billion |
|
CAGR (2026-2034) |
15.70% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
North India (29.0%, 2025) |
|
Second Largest Region |
South India (28.0%, 2025) |
|
Leading Type |
Devices (38.0%, 2025) |
|
Leading End Use |
Direct to Consumer (26.0%, 2025) |
The India FemTech market size increased from USD 0.72 Billion in 2020 to USD 1.49 Billion in 2025 and is estimated to reach USD 1.72 Billion in 2026. The market is further expected to grow to USD 3.08 Billion by 2030 and USD 5.52 Billion by 2034. The market is shaped by India's vast and underserved women's health landscape, a rapidly growing smartphone-enabled consumer base, and the emergence of a mature direct-to-consumer FemTech ecosystem spanning reproductive health, menstrual care, fertility management, and maternal wellness.
To get more information on this market, Request Sample
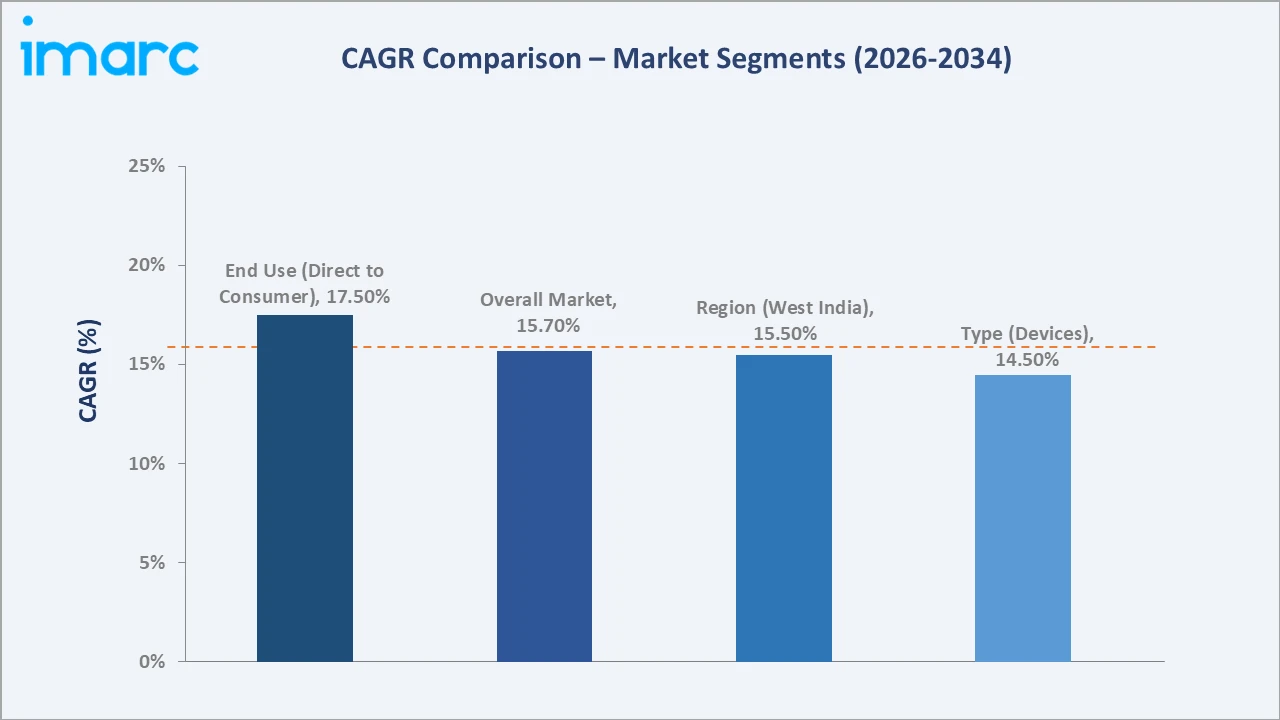
CAGR trajectories across type, end use, and regional sub-segments show software and direct to consumer expanding faster than the overall 15.70% market CAGR, driven by technology investment, rising digital health adoption, and expanding e-commerce penetration across India.
Executive Summary
The India FemTech market expanded from USD 1.49 Billion in 2025 to an estimated USD 1.72 Billion in 2026. Growth is supported by rising demand for women-centric digital health solutions, expanding direct-to-consumer platforms, and increasing healthcare awareness among women across India.
Devices command 38.0% type segment share, reflecting the growing adoption of reproductive health wearables and diagnostic devices among Indian women. Direct to consumer leads the end use segment at 26.0%, driven by rising consumer preference for purchasing personal health and wellness products online. North India leads regional share at 29.0%, supported by high population density and expanding urban healthcare infrastructure.
Key Market Insights
| Insight | Data |
|---|---|
| Leading Type | Devices – 38.0% share (2025) |
| Second Largest Type | Services – 27.0% share (2025) |
| Leading End Use | Direct to Consumer – 26.0% share (2025) |
| Second Largest End Use | Hospitals – 24.0% share (2025) |
| Leading Region | North India – 29.0% share (2025) |
| Second Largest Region | South India – 28.0% share (2025) |
| Top Companies | Flo Health Inc., Mankind Pharma Limited, Nua Woman |
Key Analytical Observations Expanding On the Data Above:
- Devices dominance at 38.0% reflects the growing integration of smart reproductive health monitoring and diagnostic devices into women's daily health routines, supported by improving device affordability and digital accessibility across India.
- Services at 27.0% is expanding as telemedicine consultations, fertility counseling, and digital gynecological care platforms gain traction among working women seeking private and convenient healthcare access.
- Direct to consumer leadership at 26.0% reflects the rapid growth of e-commerce platforms offering feminine care, contraceptive, and pregnancy-related health products directly to women across urban and semi-urban India.
- Hospitals at 24.0% is supported by the integration of FemTech diagnostic tools and women-focused health monitoring systems into hospital clinical workflows and women's health departments.
- North India at 29.0% leads regional share due to high population concentration, expanding healthcare infrastructure, and increasing consumer spending on women's health products and digital wellness platforms.
India FemTech Market Overview
FemTech refers to technology-driven products and services designed to address the specific health needs of women, encompassing reproductive health, menstrual care, fertility management, maternal health, menopause, and sexual wellness. The sector spans hardware devices, mobile health applications, software platforms, and consumer health products aimed at improving health outcomes and enhancing convenience for women at every life stage.
The India FemTech ecosystem integrates device manufacturers, software developers, healthcare providers, direct-to-consumer brands, fertility clinics, and government health programs. Rising smartphone penetration, expanding digital payment infrastructure, and improving healthcare literacy among women are key macroeconomic enablers supporting a commercially dynamic and increasingly investible FemTech market across India's diverse landscape.
Market Dynamics
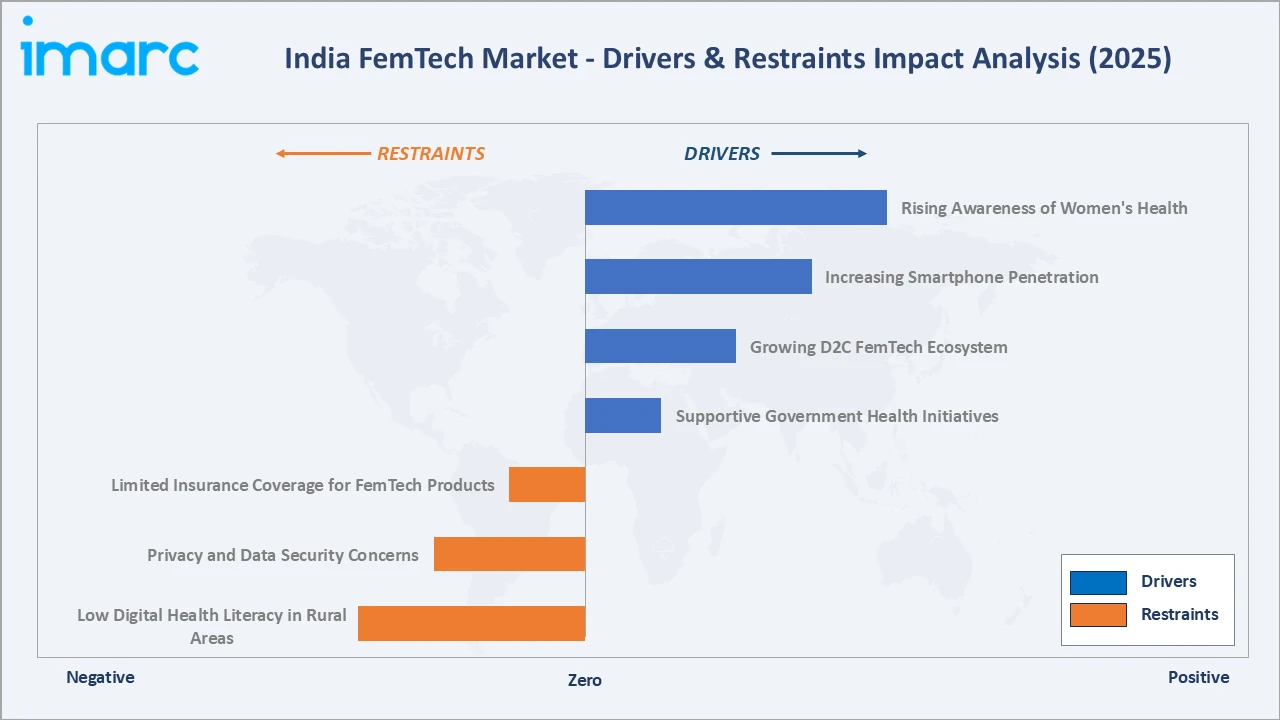
To evaluate market opportunities, Request Sample
Market Drivers
- Rising Awareness of Women's Health: Growing awareness of women's health issues, reproductive wellness, and preventive healthcare is increasing demand for FemTech products and services across India. Improved access to health information through digital platforms and educational campaigns is encouraging women to seek timely medical advice and adopt more informed healthcare practices.
- Increasing Smartphone Penetration: With smartphone users in India exceeding 740 Million in 2025, mobile-first FemTech applications for menstrual tracking, fertility monitoring, and telemedicine are reaching increasingly larger audiences, enabling scalable and affordable healthcare delivery.
- Growing D2C FemTech Ecosystem: A growing base of India-focused FemTech startups and established brands is expanding the range of products and services available to women, from sustainable menstrual care to AI-powered reproductive health tracking and online fertility consultation.
- Supportive Government Health Initiatives: Government initiatives including the National Digital Health Mission, Ayushman Bharat, and maternal health programs are supporting digital health infrastructure development, creating favorable conditions for FemTech adoption across diverse population segments.
Market Restraints
- Low Digital Health Literacy in Rural Areas: A significant share of India's rural and semi-urban female population has limited awareness of digital health tools, reducing addressable market penetration for app-based and device-driven FemTech solutions in lower-tier geographies.
- Privacy and Data Security Concerns: Women's willingness to adopt digital health platforms is constrained by concerns around the collection and storage of sensitive reproductive and health data, limiting user trust and long-term retention for FemTech applications.
- Limited Insurance Coverage for FemTech Products: The majority of FemTech products and digital health services are not covered under mainstream health insurance schemes, limiting affordability and adoption among price-sensitive consumer segments in India.
Market Opportunities
- Expansion into Tier-2 and Tier-3 Cities: Tier-2 and Tier-3 cities in India represent a largely underserved opportunity for FemTech brands, with rising disposable incomes, improving digital connectivity, and growing awareness creating an expanding addressable consumer base.
- Integration with India's Digital Health Infrastructure: Integration with India's Unified Health Interface and National Digital Health Mission frameworks enables FemTech platforms to access a structured digital health infrastructure, facilitating data interoperability and broader healthcare ecosystem participation.
Market Challenges
- Fragmented Regulatory Environment: FemTech operates across healthcare, consumer goods, medical devices, and digital health verticals, each governed by distinct regulatory frameworks in India. Navigating overlapping compliance requirements increases operational complexity for FemTech companies.
- Cultural Barriers to Women's Health Discussions: Deep-rooted social norms around discussing women's reproductive health continue to limit open consumer engagement in certain demographic segments, constraining awareness campaigns and product adoption in conservative markets.
Emerging Market Trends
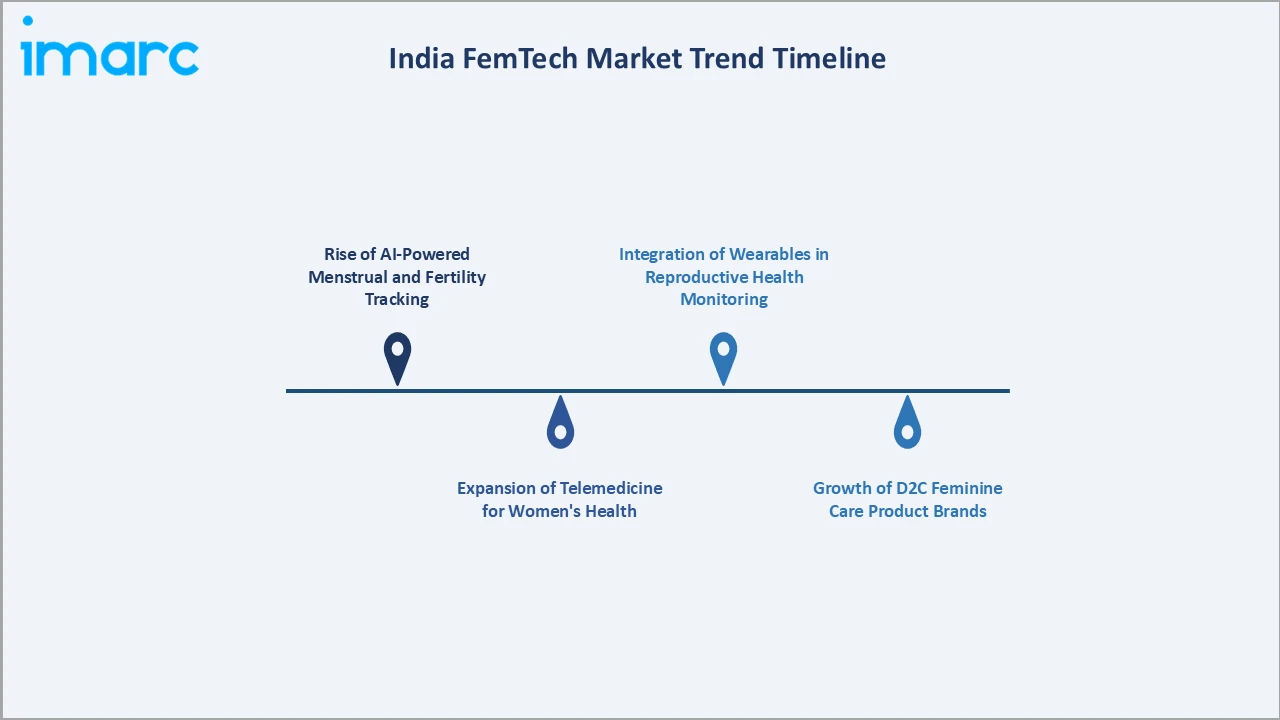
1. Rise of AI-Powered Menstrual and Fertility Tracking
AI is transforming menstrual and fertility tracking by enabling personalized cycle predictions, ovulation insights, and health anomaly detection. Growing user comfort with health data sharing and improving model accuracy are expanding AI adoption across the segment.
2. Expansion of Telemedicine for Women's Health
Telemedicine platforms offering gynecology, obstetrics, and fertility consultations have seen sustained demand growth. These platforms are reducing geographic barriers to specialized women's healthcare, particularly benefiting women in Tier-2 and Tier-3 cities with limited access to in-person specialist consultations.
3. Growth of D2C Feminine Care Product Brands
Direct-to-consumer FemTech brands are expanding their product portfolios to include eco-friendly menstrual care, intimate wellness, and reproductive health products. E-commerce and social media-driven discovery are enabling these brands to build loyal consumer communities while bypassing traditional retail distribution channels.
4. Integration of Wearables in Reproductive Health Monitoring
Wearable devices capable of tracking basal body temperature, heart rate variability, and other physiological indicators relevant to reproductive health are gaining traction among health-conscious Indian women. Improving sensor miniaturization and battery life are expanding the wearable FemTech opportunity across fertility and general wellness segments.
Industry Value Chain Analysis
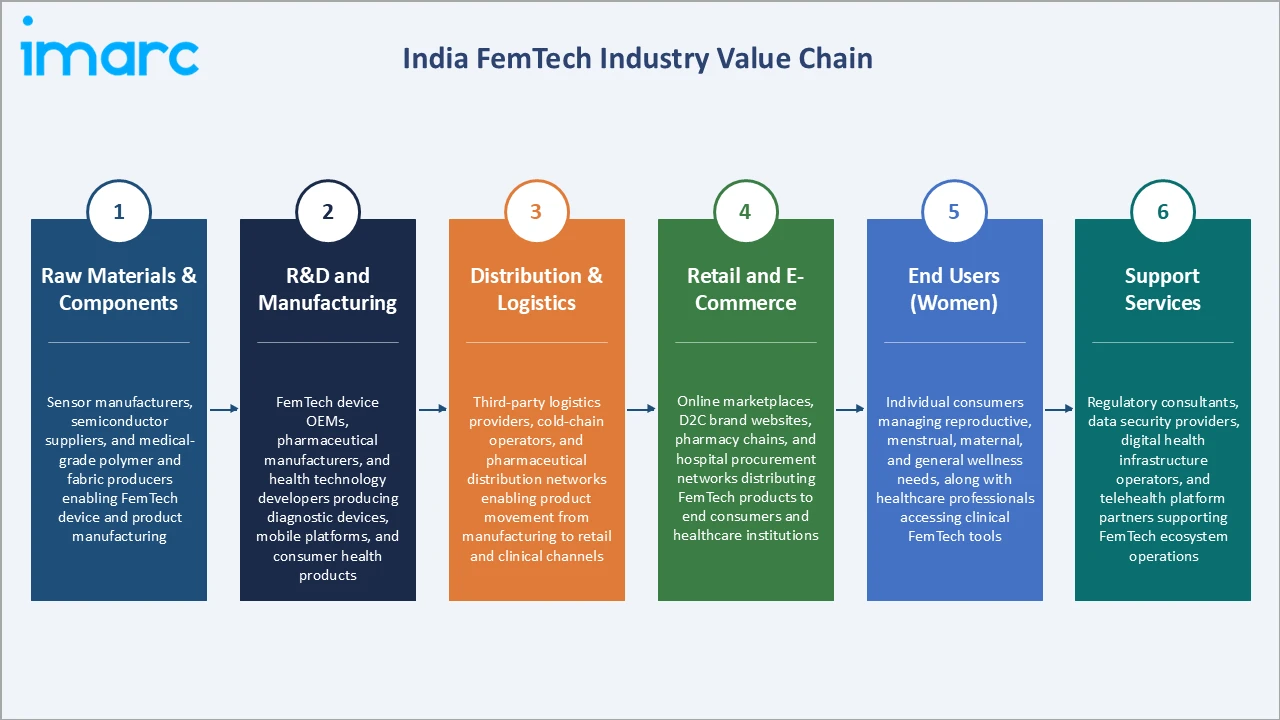
The India FemTech value chain spans six stages, from raw material and component sourcing through research and development, manufacturing, distribution, retail, and end-user delivery. Platform software, device manufacturing, and direct-to-consumer retail stages capture the highest value, while regulatory compliance and post-sale support are increasingly determining competitive position in a maturing market.
| Stage | Key Players / Examples |
|---|---|
| Raw Materials & Components | Sensor manufacturers, semiconductor suppliers, and medical-grade polymer and fabric producers enabling FemTech device and product manufacturing |
| R&D and Manufacturing | FemTech device OEMs, pharmaceutical manufacturers, and health technology developers producing diagnostic devices, mobile platforms, and consumer health products |
| Distribution & Logistics | Third-party logistics providers, cold-chain operators, and pharmaceutical distribution networks enabling product movement from manufacturing to retail and clinical channels |
| Retail and E-Commerce | Online marketplaces, D2C brand websites, pharmacy chains, and hospital procurement networks distributing FemTech products to end consumers and healthcare institutions |
| End Users (Women) | Individual consumers managing reproductive, menstrual, maternal, and general wellness needs, along with healthcare professionals accessing clinical FemTech tools |
| Support Services | Regulatory consultants, data security providers, digital health infrastructure operators, and telehealth platform partners supporting FemTech ecosystem operations |
Vertically integrated players, especially those owning proprietary diagnostic platforms, original women's health data assets, and direct consumer relationships, are positioned to capture greater value in the India FemTech market than participants reliant on third-party distribution or licensed technology infrastructure.
Technology Landscape in the India FemTech Industry
AI-Powered Health Analytics
Machine learning (ML) algorithms are enabling menstrual cycle prediction, fertility window estimation, and early anomaly detection across FemTech platforms. AI models trained on large anonymized health datasets are improving personalization and clinical relevance of digital women's health tools.
Wearable Health Monitoring
Wearable biosensors measuring basal body temperature, heart rate, and hormonal indicators are advancing reproductive health monitoring. Miniaturized sensor technology and improved wireless connectivity are enabling continuous tracking in compact, consumer-friendly form factors.
Telemedicine and Remote Care
Telehealth platforms integrating video consultation, digital prescription, and remote patient monitoring are expanding specialist women's healthcare access. These platforms are reducing consultation barriers for gynecology, fertility, and maternal health across geographic and economic divides in India.
Digital Therapeutics and Mobile Applications
Prescription and non-prescription digital therapeutics addressing menstrual disorders, PCOS management, and postpartum support are an emerging FemTech segment. Mobile applications providing evidence-based health education and behavioral coaching are complementing clinical care across the women's health continuum.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Type | Devices | 38.0% | 2025 |
| Application | Pregnancy and Nursing Care | 18.0% | 2025 |
| End Use | Direct to Consumer | 26.0% | 2025 |
| Region | North India | 29.0% | 2025 |

By Type
Devices command a 38.0% majority share in 2025, driven by the growing adoption of smart diagnostic devices, reproductive health monitors, and wearable health trackers among Indian women. The segment benefits from improving device affordability and expanding e-commerce distribution infrastructure enabling broader consumer reach.
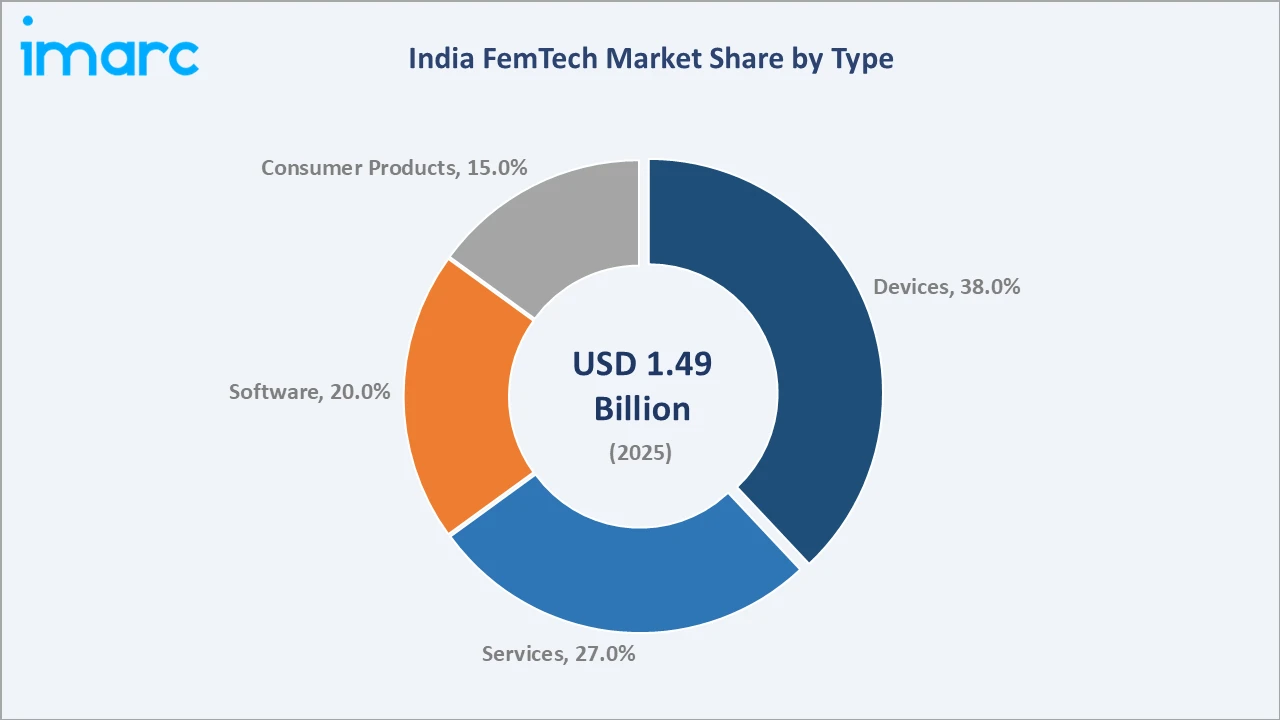
To access detailed market analysis, Request Sample
Services at 27.0% is the second-largest type segment, driven by rising demand for telehealth consultations, fertility counseling, and digital gynecological care. The segment is expanding as women increasingly prioritize convenient, private, and expert-guided healthcare experiences accessible from their smartphones.
By End Use
Direct to consumer leads the end use segment at 26.0% in 2025, reflecting the rapid growth of online purchase channels for feminine care, contraceptive, and pregnancy-related health products. Rising consumer comfort with digital health commerce and expanding D2C brand ecosystems are driving this segment's continued growth.
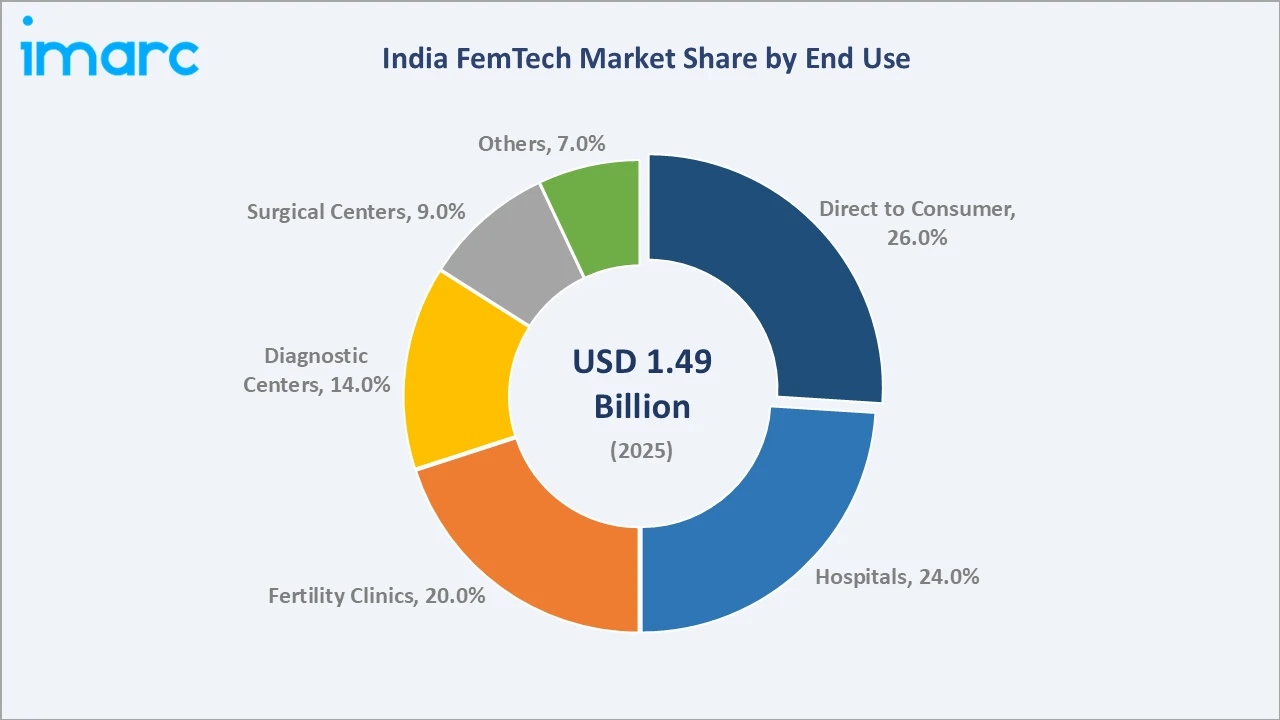
Hospitals at 24.0% represent the second-largest end use segment, supported by the integration of FemTech diagnostic tools, women's health monitoring systems, and digital health platforms into hospital clinical workflows and women's health departments across India.
Regional Market Insights
| Region | Share (2025) | Key Growth Drivers |
|---|---|---|
| North India | 29.0% | High population density and large urban centers in Delhi and Uttar Pradesh, expanding healthcare infrastructure, growing middle-class consumer spending on women's wellness, and rising digital health adoption |
| South India | 28.0% | Strong healthcare ecosystem in Bangalore, Hyderabad, and Chennai, high literacy rates among women, active FemTech startup ecosystem, and established medical infrastructure supporting digital health integration |
| West India | 25.0% | Maharashtra and Gujarat's industrial base, established healthcare infrastructure, strong D2C brand distribution network, growing fertility clinic presence in Mumbai and Pune |
| East India | 18.0% | Emerging urban development in Kolkata and Bhubaneswar, rising awareness of women's health, expanding government healthcare investment, and growing digital connectivity enabling FemTech platform adoption |
North India at 29.0% in 2025 leads the regional landscape, anchored by high population concentration in Delhi NCR and Uttar Pradesh, expanding urban healthcare infrastructure, and increasing consumer expenditure on personal health and wellness products among India's growing urban female population.
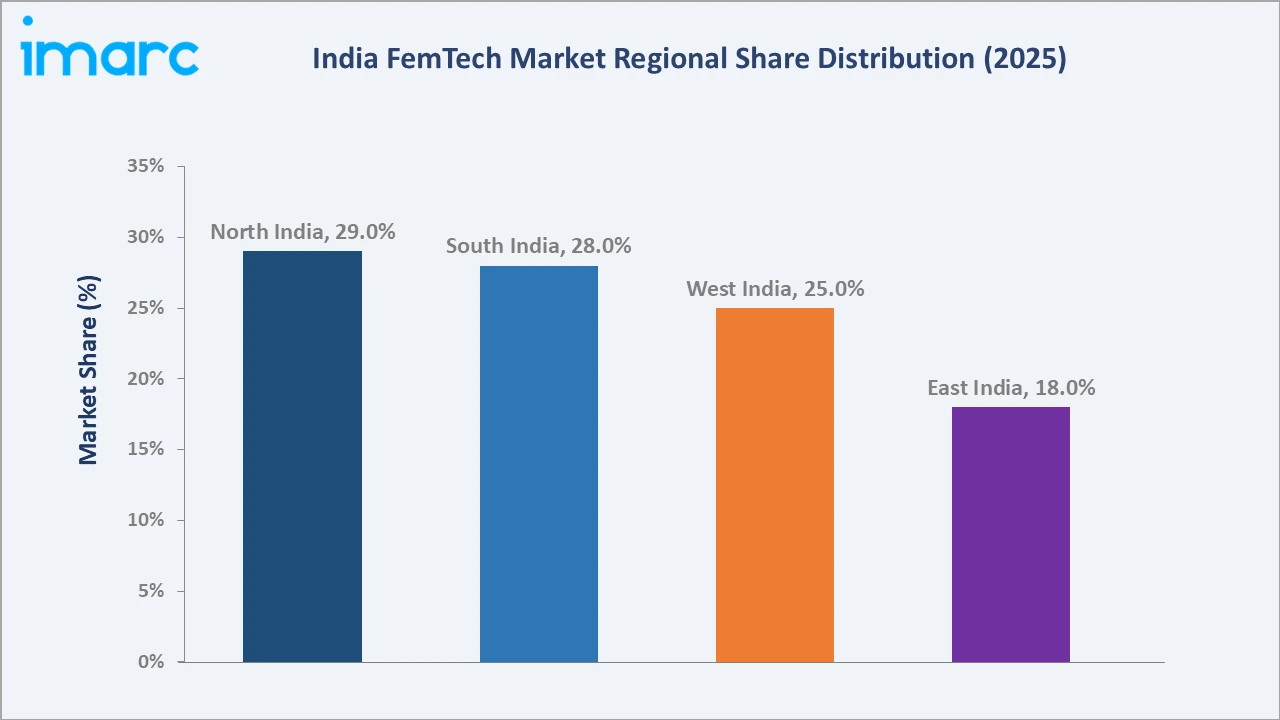
East India, while currently the smallest regional contributor at 18.0%, is expanding as urban development in Odisha, West Bengal, and Jharkhand progresses and as government investment in digital health infrastructure improves FemTech platform access and consumer awareness in the region.
Competitive Landscape
The India FemTech market features a mix of global health technology platforms, established Indian pharmaceutical and consumer health companies, and specialized FemTech startups competing on technology depth, product innovation, distribution reach, and brand trust. Platform personalization, clinical credibility, and distribution scale are the primary competitive differentiators across the market.
| Company Name | Brand / Key Product | Position | Strategic Focus |
|---|---|---|---|
| Flo Health Inc. | Flo App | Leader | Expanding AI-driven menstrual and reproductive health tracking with deepening integration across fertility, pregnancy, and wellness features for women globally |
| Mankind Pharma Limited | Prega News | Leader | Strengthening distribution and brand presence for women's diagnostic and healthcare products across pharmacy and retail channels in India |
| Nua Woman | Nua | Challenger | Growing the range of sustainable and dermatologically tested feminine care products while expanding direct-to-consumer digital commerce capabilities |
Key players include Flo Health Inc., Mankind Pharma Limited, and Nua Woman, among others.
Key Company Profiles
Flo Health Inc.
Flo Health Inc. is a global digital health company headquartered in London, United Kingdom, operating one of the world's most widely used period and ovulation tracking applications. The platform serves millions of users globally, including a large and growing user base across India, offering menstrual cycle tracking, fertility insights, and pregnancy guidance.
- Product Portfolio: AI-powered period and ovulation tracker, pregnancy monitoring tools, menopause health resources, and personalized reproductive health insights delivered through the Flo mobile application.
- Recent Developments: The company continues to expand its AI-driven health prediction capabilities and has broadened its platform to include menopause and chronic condition management features for women.
- Strategic Focus: Strengthening AI-driven personalization across the reproductive health journey and expanding platform capabilities to address a broader range of women's health conditions globally.
Mankind Pharma Limited
Mankind Pharma Limited is one of India's leading pharmaceutical companies, headquartered in New Delhi. The company's Prega News brand is among India's most recognized pregnancy detection test products, widely distributed across pharmacy and retail channels nationwide.
- Product Portfolio: Prega News pregnancy detection test kits and a range of women's diagnostic and reproductive health products available through pharmacy, retail, and online channels across India.
- Recent Developments: The company continues to expand its women's health product portfolio and strengthen distribution reach across urban and semi-urban markets in India.
- Strategic Focus: Expanding branded women's health product presence across pharmacy and digital commerce channels and growing consumer health product offerings targeting women across life stages.
Nua Woman
Nua Woman is an Indian direct-to-consumer FemTech brand headquartered in Mumbai, Maharashtra. The company offers a range of sustainable, skin-safe, and toxin-free menstrual care and intimate wellness products, distributed primarily through its own digital platform and major e-commerce marketplaces.
- Product Portfolio: Sustainable menstrual pads, panty liners, tampons, period underwear, and intimate hygiene products designed for sensitive skin and available through direct-to-consumer and e-commerce channels.
- Recent Developments: The company has expanded its product range and grown its subscriber base through personalized subscription offerings and community-driven brand engagement campaigns.
- Strategic Focus: Building a sustainable and community-driven feminine care brand through product innovation, transparent communication, and expanding direct-to-consumer digital distribution.
Market Concentration Analysis
The India FemTech market is moderately fragmented, with the top three players, comprising global health technology platforms and established Indian consumer health companies, collectively accounting for a significant but not dominant share of overall market revenue. The market's dynamic character and diverse product categories limit concentration, with strong activity from emerging D2C brands and specialized health technology startups.
Barriers to entry include the need to establish consumer trust, comply with healthcare data privacy and regulatory requirements, and develop reliable, evidence-based women's health solutions. New entrants may also face challenges in securing funding, acquiring customers, building partnerships with healthcare providers, and differentiating their offerings in an increasingly competitive market.
Consolidation is gaining momentum, with larger pharmaceutical and consumer health companies acquiring or partnering with FemTech startups to expand their women's health portfolios. Strategic investments from venture capital and private equity are also accelerating growth among mid-tier FemTech platforms, contributing to gradual market consolidation.
Investment & Growth Opportunities
Fastest-Growing Segments
Software is the fastest-growing type sub-segment, driven by rising demand for AI-powered health analytics, cycle prediction tools, and digital therapeutic applications. Direct to consumer is the fastest-growing end use segment, supported by e-commerce platform growth and expanding D2C brand ecosystems targeting India's female health consumer base.
Emerging Markets
East India represents the fastest-growing regional opportunity, with expanding urban development in Odisha, West Bengal, and Jharkhand, improving digital connectivity, and growing government investment in healthcare infrastructure creating significant untapped potential for FemTech brands and platforms.
Venture & Investment Trends
Investment activity is concentrated in AI-driven health platforms, telemedicine for women's health, and sustainable feminine care brands. Capital is also flowing into fertility technology platforms and digital maternal health solutions, supported by growing awareness of India's large and underserved women's health market opportunity.
Future Market Outlook (2026-2034)
The India FemTech market is projected to grow from USD 1.49 Billion in 2025 to USD 1.72 Billion in 2026, reaching USD 5.52 Billion by 2034, registering a CAGR of 15.70% during 2026-2034.
Four forces will shape the market through 2034: expanding adoption of AI-powered reproductive health platforms; improving economics of FemTech device manufacturing as scale increases; continued growth of India's D2C brand ecosystem; and deepening integration of FemTech solutions with India's National Digital Health Mission infrastructure.
By 2034, the India FemTech market is expected to feature a mix of globally scaled digital health platforms, established consumer health companies with strong women's health portfolios, and a cohort of technology-differentiated Indian FemTech brands serving the full spectrum of women's health needs across reproductive, maternal, and general wellness.
Research Methodology
Primary Research
Primary research included structured discussions with gynecologists, women's health specialists, FemTech platform operators, D2C brand founders, and healthcare administrators, validating market sizing, segment composition, and regional demand patterns across the India FemTech ecosystem.
Secondary Research
Secondary sources included Ministry of Health and Family Welfare publications, National Health Authority data, company annual reports, investor presentations, and public disclosures from FemTech platforms, consumer health brands, and medical device companies operating across India.
Forecasting Models
Market forecasts used top-down and bottom-up models combining population demographic analysis, smartphone and digital health penetration projections, product segment growth assumptions, and healthcare expenditure trends. Scenario analysis addressed technology adoption rates, regulatory developments, and investment activity in India's FemTech sector.
India FemTech Market Report Coverage:
|
Report Features |
Details |
|
Base Year of the Analysis |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Units |
Billion USD |
|
Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
|
Types Covered |
Devices, Services, Software, Consumer Products |
|
Applications Covered |
Pregnancy and Nursing Care, Reproductive Health and Contraception, Pelvic and Uterine Health, Sexual Health, Women Wellness, Menstrual Health, Longevity and Mental Health, General Health, Menopause Care |
|
End Uses Covered |
Fertility Clinics, Direct to Consumer, Hospitals, Surgical Centers, Diagnostic Centers, Others |
|
Regions Covered |
North India, South India, East India, West India |
| Companies Covered | Flo Health Inc., Mankind Pharma Limited, Nua Woman, etc. |
|
Customization Scope |
10% Free Customization |
| Post-Sale Analyst Support |
10-12 Weeks |
|
Delivery Format |
PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Frequently Asked Questions About the India FemTech Market Report
The India FemTech market size is estimated at USD 1.72 Billion in 2026, driven by rising women's health awareness, growing smartphone penetration, and expanding D2C digital health platforms across India.
The India FemTech market is projected to grow at a CAGR of 15.70% from 2026-2034, reaching USD 5.52 Billion, supported by digital health adoption, AI-driven platforms, and expanding healthcare infrastructure.
Devices dominate the type segment at 38.0% share in 2025, driven by growing adoption of smart reproductive health monitors, diagnostic devices, and wearable health trackers among Indian women.
Direct to consumer leads the end use segment at 26.0% share in 2025, driven by rising preference for online purchase of feminine care, contraceptive, and pregnancy-related health products.
North India commands 29.0% share in 2025, supported by high population concentration in Delhi NCR and Uttar Pradesh, expanding healthcare infrastructure, and growing urban female consumer spending.
East India is the fastest-growing region, supported by expanding urban development, improving digital connectivity, and growing government healthcare investment in Odisha, West Bengal, and Jharkhand.
Key players include Flo Health Inc., Mankind Pharma Limited, and Nua Woman, among others.
Key drivers include rising awareness of women's health, increasing smartphone penetration, growing D2C FemTech ecosystems, and supportive government digital health initiatives across India.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade