India Fibre Cement Boards and Sheets Market Size, Share, Trends and Forecast by Raw Material, Application, End Use, and Region, 2026-2034
India Fibre Cement Boards and Sheets Market Size, Share, Trends & Forecast (2026-2034)
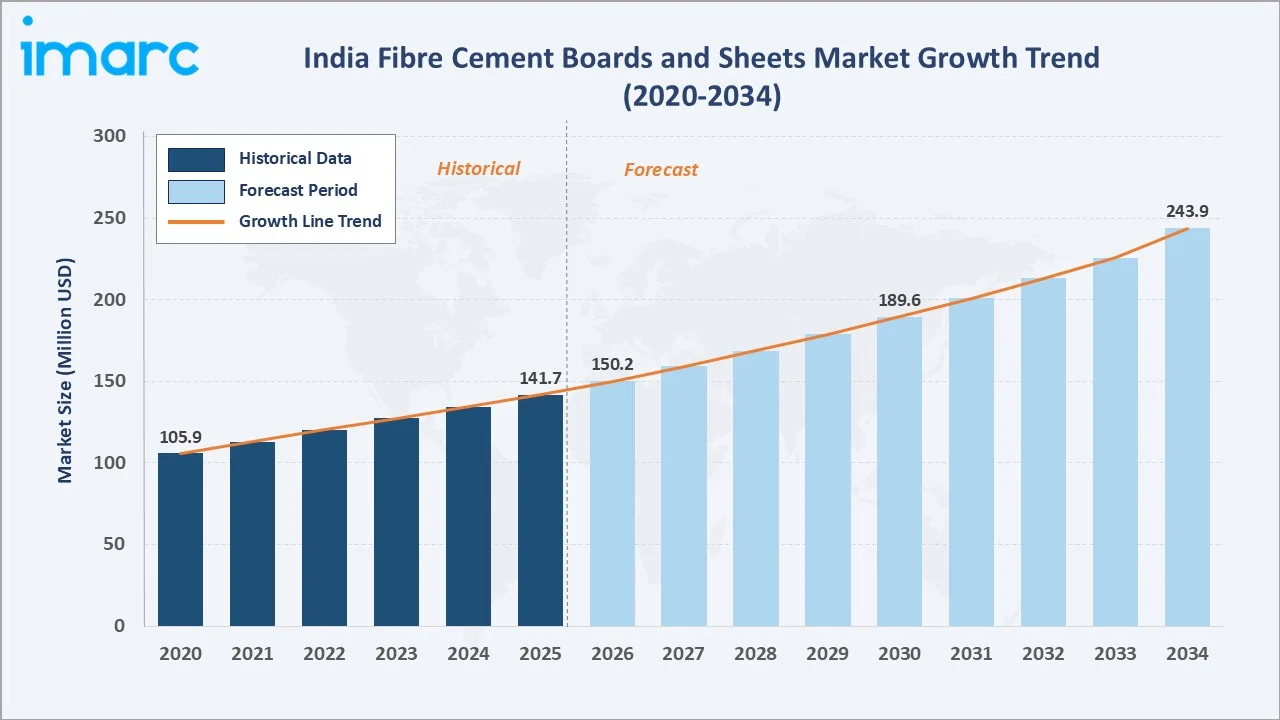
The India fibre cement boards and sheets market grew from USD 141.7 Million in 2025 to USD 150.2 Million in 2026 and is projected to reach USD 243.9 Million by 2034, growing at a CAGR of 6.00% during 2026-2034. The market is driven by rising demand for sustainable construction materials, government green building initiatives, and rapid urbanization across residential and commercial segments.
Asbestos leads with 55.8% raw material share. Roofing is the dominant application at 36.8%. North India commands 31.5% of the national market share, supported by strong infrastructure and housing construction activity.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 141.7 Million |
|
Market Size (2026) |
USD 150.2 Million |
|
Forecast Market Size (2034) |
USD 243.9 Million |
|
CAGR (2026-2034) |
6.00% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Raw Material |
Asbestos (55.8%, 2025) |
|
Dominant Application |
Roofing (36.8%, 2025) |
|
Leading Region |
North India (31.5%, 2025) |
The India fibre cement boards and sheets market size increased from USD 105.9 Million in 2020 to USD 141.7 Million in 2025 and is estimated to reach USD 150.2 Million in 2026. The market is further expected to grow to USD 189.6 Million by 2030 and USD 243.9 Million by 2034, driven by sustained construction sector growth, green building adoption, and government-backed housing programmes.
To get more information on this market, Request Sample
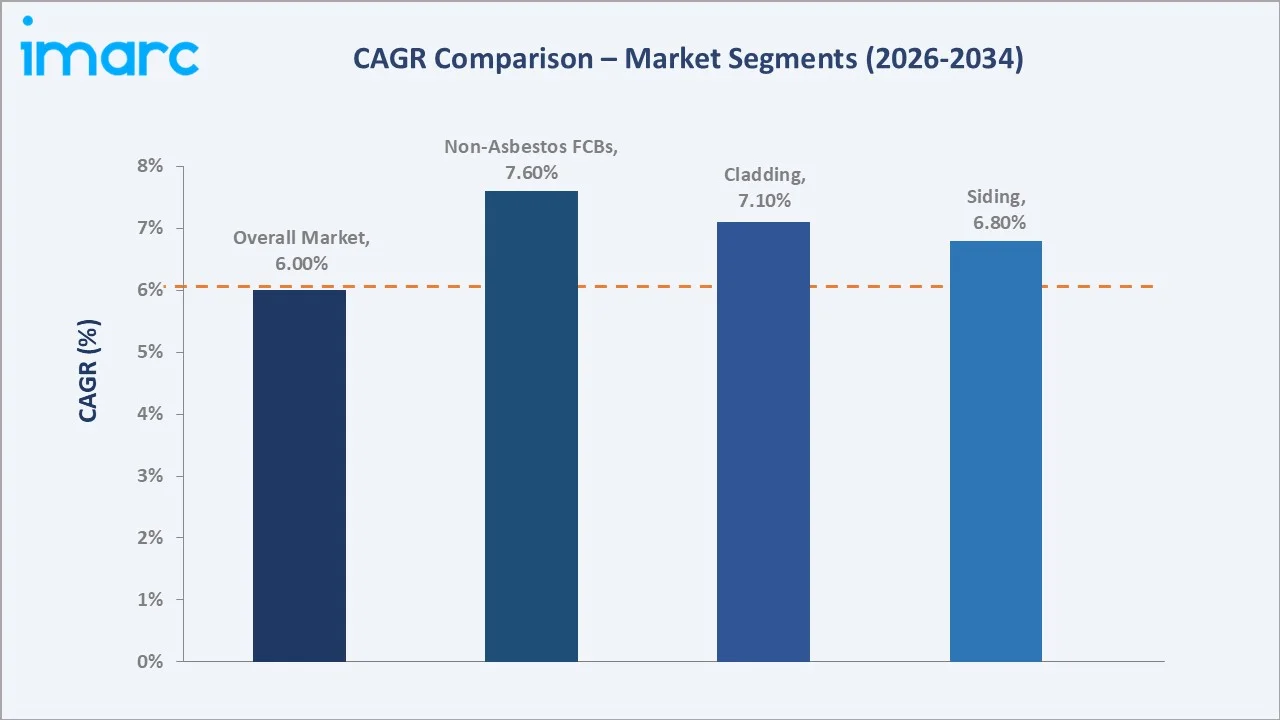
Non-asbestos FCBs grow fastest at ~7.6% CAGR as environmental regulations and LEED/GRIHA certification requirements drive substitution. Cladding segment grows at ~7.1% CAGR through rising commercial real estate and facade application adoption.
Executive Summary
The India fibre cement boards and sheets market expanded from USD 141.7 Million in 2025 to an estimated USD 150.2 Million in 2026, positioning it among India's fastest-growing construction materials categories. Market growth is underpinned by urbanization, government housing schemes, and rising adoption of fire-resistant, moisture-proof building solutions across residential, commercial, and industrial segments.
The market is projected to reach USD 243.9 Million by 2034 at a CAGR of 6.00%. Asbestos at 55.8% leads raw material share. Roofing at 36.8% is the dominant application. North India leads regionally at 31.5%, driven by dense construction activity under PMAY and Smart Cities Mission programmes.
Key Market Insights
|
Insight |
Data |
|
Dominant Raw Material |
Asbestos – 55.8% share (2025) |
|
Dominant Application |
Roofing – 36.8% market share (2025) |
|
Leading Region |
North India – 31.5% share (2025) |
|
Market Opportunity |
Non-asbestos FCB substitution; green building certifications; smart city infrastructure; prefabricated construction growth |
Key Analytical Observations Supporting the Above Data:
- Asbestos at 55.8%: Asbestos-based FCBs dominate due to their cost-effectiveness, high tensile strength, and established distribution networks across rural and semi-urban roofing markets, particularly in Tier-2 and Tier-3 geographies.
- Roofing at 36.8%: Roofing leads application demand driven by affordability, durability in diverse climate conditions, and wide adoption in low-cost housing, industrial sheds, and rural residential construction.
- North India at 31.5%: North India leads due to high construction activity across Delhi-NCR, UP, Haryana, and Rajasthan, supported by PMAY affordable housing targets and strong infrastructure investment in smart cities.
India Fibre Cement Boards and Sheets Market Overview
India fibre cement boards and sheets market is positioned at the convergence of one of the world's largest construction markets, an active government infrastructure investment agenda, and a rapidly evolving regulatory environment promoting sustainable and non-asbestos building materials. The market spans roofing, cladding, siding, moulding and trimming applications across residential and non-residential end uses.
The ecosystem integrates domestic manufacturers, raw material suppliers, organized distribution networks, and a growing base of contractors and developers adopting fibre cement products. Macroeconomic factors include urbanization, PMAY housing targets, Smart Cities Mission, and green building mandates driving sustained demand across all four Indian regions.
Market Dynamics
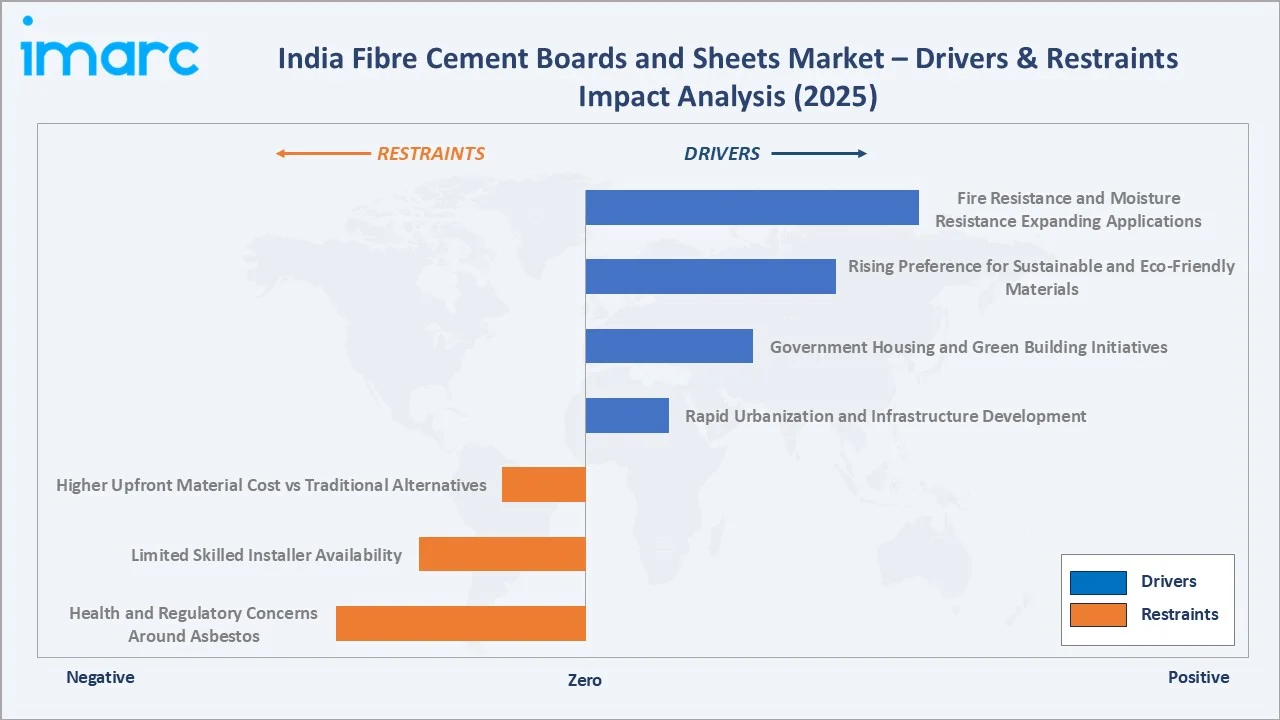
To evaluate market opportunities, Request Sample
Market Drivers
- Rapid Urbanization and Infrastructure Development: India's urbanization and large-scale infrastructure programmes are driving consistent demand for durable, fire-resistant fibre cement products across residential and commercial construction. Government capital expenditure under PMAY and Smart Cities Mission directly supports roofing and cladding material procurement, creating structured volume demand for organized FCB manufacturers across all four regions.
- Government Housing and Green Building Initiatives: PMAY, Housing for All, and state-level affordable housing programmes are expanding the addressable market for FCBs, particularly in roofing applications for economically weaker section housing. India's third-place global ranking for LEED certifications, with 370 certified projects covering 8.5 Million GSM, is driving non-asbestos FCB adoption as a sustainable substitute for traditional plywood and gypsum materials.
- Rising Preference for Sustainable and Eco-Friendly Materials: Increasing environmental awareness among developers, architects, and specifiers is shifting procurement toward non-asbestos fibre cement boards that meet LEED, IGBC, and GRIHA certification requirements. FCBs' low carbon footprint, recyclability, and compliance with BIS IS 14862 standards make them a preferred choice for green-rated residential and commercial projects across urban India.
- Fire Resistance and Moisture Resistance Expanding Applications: FCBs' inherent fire-resistant, moisture-proof, and termite-resistant properties are driving adoption in false ceilings, wall cladding, flooring, and modular kitchens across residential and hospitality applications. Rising housing sales, reaching an 11-year high in the first half of 2024 with 1,73,000 units sold, directly supports demand for interior-grade FCBs across premium and mid-range residential segments.
Market Restraints
- Higher Upfront Material Cost versus Traditional Alternatives: FCBs carry a higher per-unit cost compared to conventional plywood, gypsum, and corrugated metal sheets, limiting adoption among price-sensitive consumers in rural and semi-urban markets. This cost differential restricts organized FCB penetration in the mass residential and low-cost housing segments, where unorganized suppliers offering cheaper alternatives maintain strong market positions.
- Limited Skilled Installer Availability: A shortage of trained installers familiar with FCB installation techniques restricts product adoption in smaller cities and rural areas. Unlike conventional roofing materials, FCBs require specific tools and skills for cutting, drilling, and fastening, creating a service gap that limits market expansion beyond metropolitan and Tier-1 construction hubs.
- Health and Regulatory Concerns Around Asbestos: Growing regulatory scrutiny over asbestos-based FCBs, supported by WHO health advisories and state-level policy discussions, is creating uncertainty for manufacturers reliant on asbestos raw materials. Potential future asbestos phase-out regulations may require significant production retooling investments, increasing costs and operational risk for asbestos-based FCB producers.
Market Opportunities
- Non-Asbestos FCB Substitution and Premium Product Development: The regulatory shift away from asbestos-based products and growing specification-grade demand from green-rated projects create significant opportunity for non-asbestos FCB manufacturers to expand market share. Premium product ranges with enhanced aesthetic finishes, lightweight profiles, and smart building compatibility are emerging as high-margin growth segments.
- Prefabricated and Modular Construction Adoption: Growing adoption of prefabricated and modular construction techniques across data centres, cold storage, co-working spaces, and institutional buildings is creating new structured demand for dry, fire-resistant FCBs as interior and exterior cladding materials.
Market Challenges
- Distribution Reach in Rural and Semi-Urban Markets: Establishing organized distribution networks in Tier-3 and rural geographies remains challenging, where unorganized local suppliers and cheap metal roofing sheets dominate. FCB manufacturers require sustained investment in dealer development, contractor training, and last-mile logistics to expand market penetration.
- Raw Material Price Volatility and Supply Chain Risks: Fluctuations in cement, cellulose fibre, and synthetic fibre prices create margin pressure for FCB manufacturers, particularly for companies without backward integration into key raw materials. Global supply chain disruptions affecting cellulose fibre availability add further procurement risk.
Emerging Market Trends
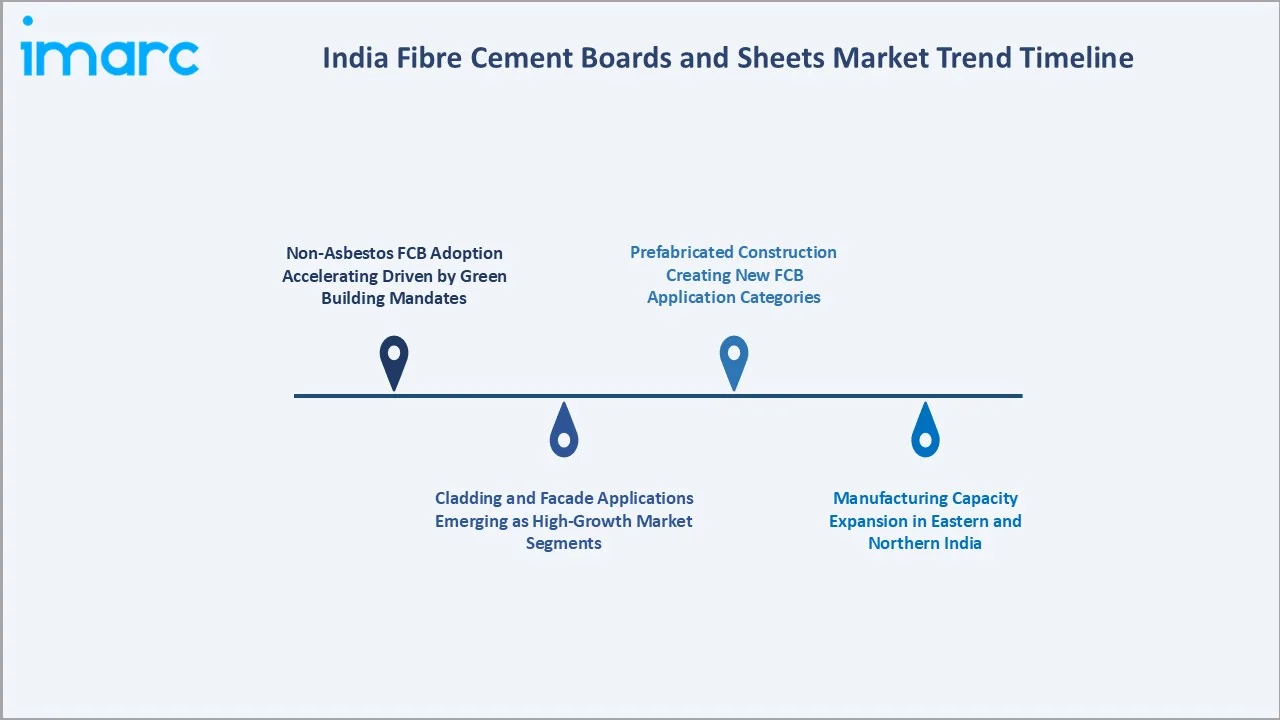
1. Non-Asbestos FCB Adoption Accelerating Driven by Green Building Mandates
Non-asbestos fibre cement boards are gaining market share as LEED, IGBC, and GRIHA certifications become standard specifications for commercial and premium residential projects. Manufacturers are expanding their non-asbestos product portfolios to address this rapidly growing specification-grade demand segment.
2. Cladding and Facade Applications Emerging as High-Growth Market Segments
Commercial real estate growth and rising consumer preference for modern exterior aesthetics are driving strong demand for FCB cladding and facade systems. Architects and developers are specifying FCB-based rainscreen cladding systems for their weather resistance, design versatility, and low maintenance requirements.
3. Manufacturing Capacity Expansion in Eastern and Northern India
Leading manufacturers are establishing new production facilities in eastern and northern India to reduce transportation costs and serve emerging construction markets. Everest Industries' MOU with the Government of Assam in February 2025 to invest USD 16.83 Million for a new FCB plant in Goalpara reflects this geographic expansion trend.
4. Prefabricated Construction Creating New FCB Application Categories
The growing adoption of prefabricated and fast-track construction techniques for EWS/LIG housing, data centres, and institutional buildings is creating new structured demand for lightweight, fire-resistant FCB panels as interior partitioning and exterior cladding materials.
Industry Value Chain Analysis
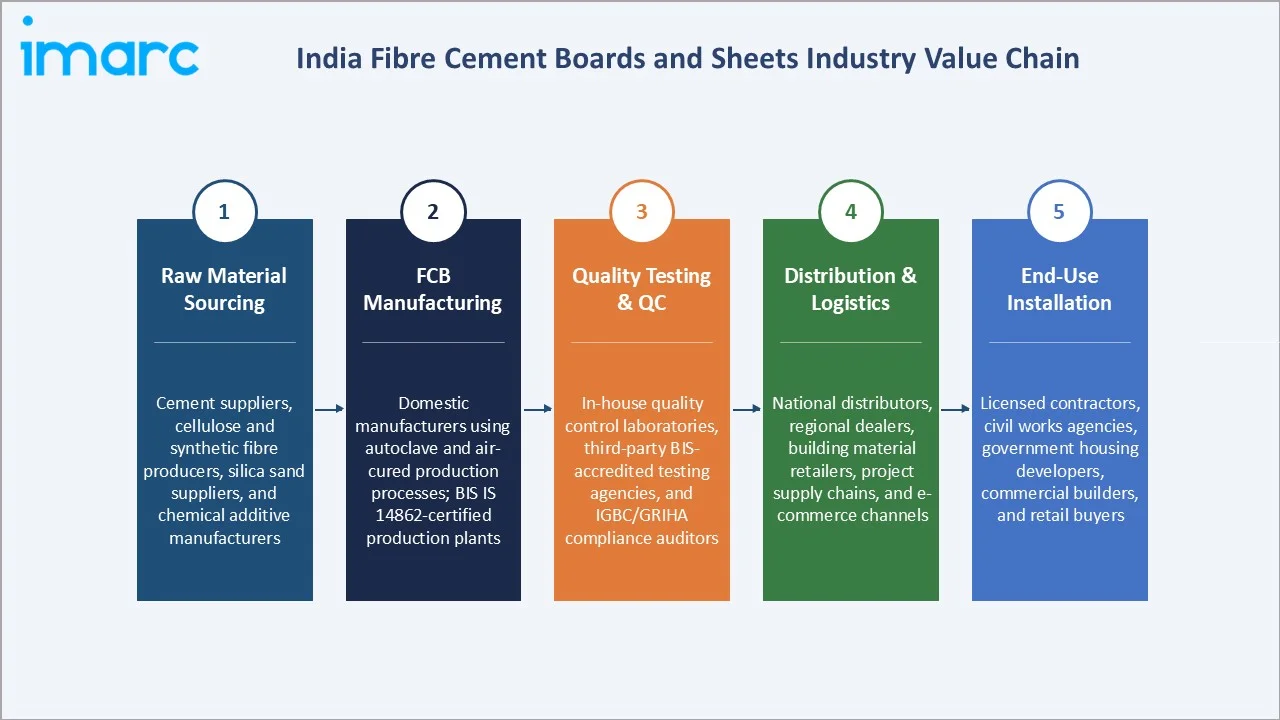
The India fibre cement boards and sheets value chain spans raw material sourcing, autoclave-based manufacturing, BIS-certified quality testing, organized distribution, and end-use installation. The value chain's structure creates competitive dynamics where vertically integrated manufacturers with captive raw material sourcing achieve superior margin profiles.
|
Stage |
Key Participants |
|
Raw Material Sourcing |
Cement suppliers, cellulose and synthetic fibre producers, silica sand suppliers, and chemical additive manufacturers |
|
FCB Manufacturing |
Domestic manufacturers using autoclave and air-cured production processes; BIS IS 14862-certified production plants |
|
Quality Testing & QC |
In-house quality control laboratories, third-party BIS-accredited testing agencies, and IGBC/GRIHA compliance auditors |
|
Distribution & Logistics |
National distributors, regional dealers, building material retailers, project supply chains, and e-commerce channels |
|
End-Use Installation |
Licensed contractors, civil works agencies, government housing developers, commercial builders, and retail buyers |
The distribution and retail stage is the most commercially consequential, where manufacturers' investment in dealer incentive programs, contractor training, and specification support directly determines market share outcomes in India's fragmented building materials landscape.
Technology Landscape in the India Fibre Cement Boards and Sheets Industry
Autoclaved Fibre Cement Manufacturing Technology
Autoclaved FCB production using cement, cellulose fibres, silica, and water under high-pressure steam curing delivers superior dimensional stability, high density, and enhanced fire resistance. This technology is the standard for premium-grade boards used in cladding, facades, and high-specification interior applications.
Air-Cured Non-Asbestos Fibre Cement Technology
Air-cured manufacturing using synthetic and cellulose fibres without asbestos enables cost-effective production of roofing sheets and standard boards at scale. This technology is driving the transition from asbestos-based products as environmental regulations and green building mandates tighten across the industry.
Digital Printing and Surface Treatment Technologies
Advanced digital printing and surface coating technologies enable manufacturers to produce FCBs with wood, stone, and textured finishes for interior cladding and facade applications. These value-added surface treatments are creating premium product categories with higher margins and stronger specification-grade demand from architects and interior designers.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Raw Material |
Asbestos |
55.8% |
2025 |
|
Application |
Roofing |
36.8% |
2025 |
|
End Use |
Non-Residential |
52.5% |
2025 |
|
Region |
North India |
31.5% |
2025 |

By Raw Material
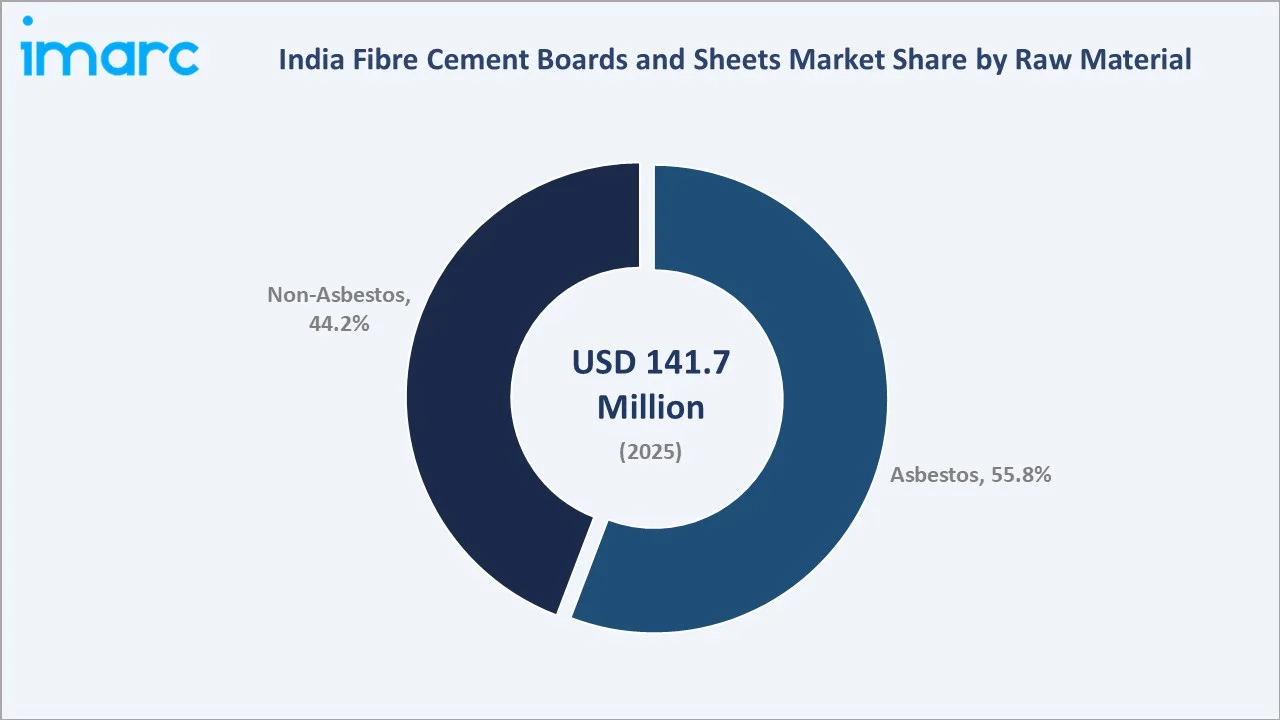
Asbestos leads at 55.8% (2025). Asbestos-based FCBs remain dominant due to their cost-effectiveness, availability of established supply chains, and strong demand from rural and semi-urban roofing markets. Their high tensile strength and weather resistance make them the preferred choice for low-cost residential roofing across Tier-3 and rural geographies.
To access detailed market analysis, Request Sample
Non-Asbestos at 44.2% is the faster-growing segment at ~7.6% CAGR, driven by green building certification requirements, regulatory pressure on asbestos, and growing specification-grade demand from commercial and premium residential construction projects adopting LEED and GRIHA-certified building materials.
By Application
Roofing leads at 36.8% (2025). Roofing is the dominant application reflecting widespread use of fibre cement corrugated sheets in residential and industrial construction across rural, semi-urban, and Tier-2 city markets. Cost-effectiveness, ease of installation, and long service life support roofing's dominant share across all regions.
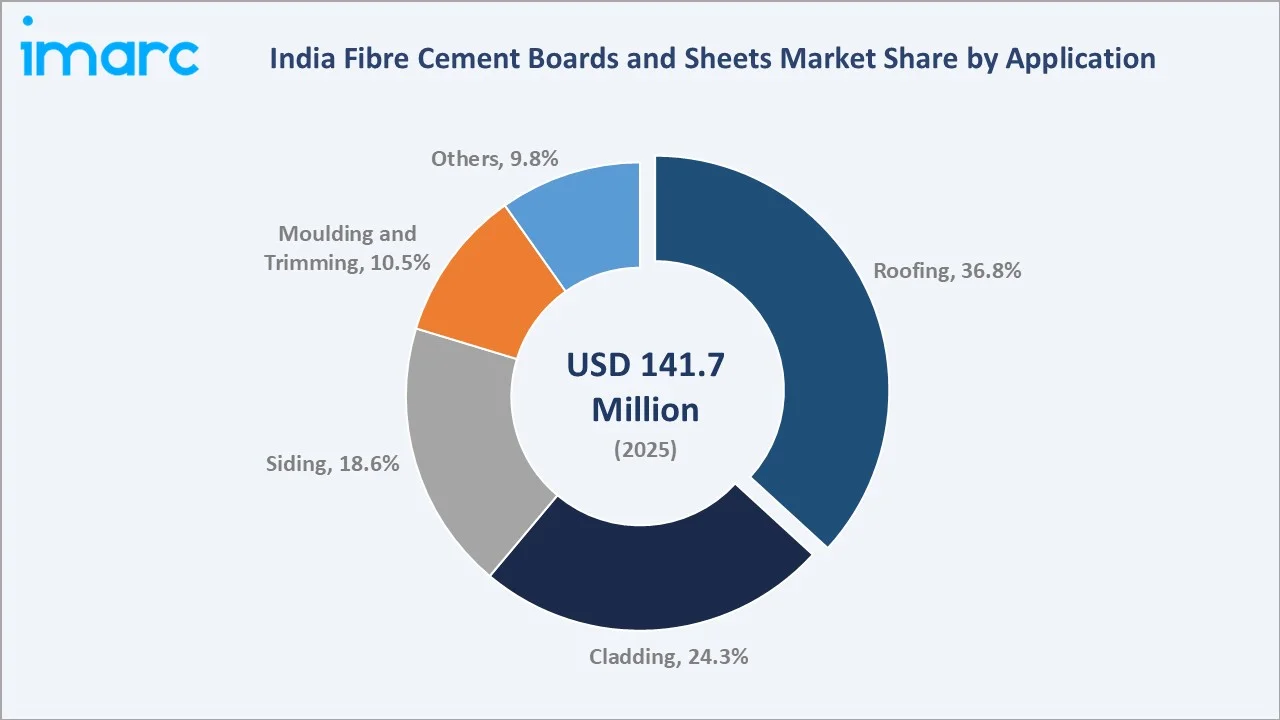
Cladding at 24.3% is growing at ~7.1% CAGR through rising commercial real estate and premium residential facade demand. Siding at 18.6%, Moulding and Trimming at 10.5%, and Others at 9.8% address a diverse range of interior and exterior applications across residential, hospitality, and institutional construction segments.
Regional Market Insights
|
Region |
Share (2025) |
Key India Fibre Cement Boards and Sheets Market Drivers & Characteristics |
|
North India |
31.5% |
Driven by dense construction activity across Delhi-NCR, UP, Haryana, and Rajasthan under PMAY affordable housing and smart city infrastructure programmes. |
|
West India |
28.4% |
Supported by Mumbai's commercial real estate pipeline, Gujarat's industrial and infrastructure development, and Maharashtra's large residential construction activity. |
|
South India |
23.2% |
Reflects strong industrial and commercial construction demand across Tamil Nadu, Karnataka, Andhra Pradesh, and Telangana, with coastal climate conditions driving roofing and cladding adoption. |
|
East India |
16.9% |
Growing construction activity in West Bengal, Odisha, and Assam, supported by new FCB manufacturing investments in the region and increasing demand for affordable roofing solutions. |
North India's 31.5% market leadership reflects Delhi-NCR's dense residential and commercial construction pipeline, UP's large-scale PMAY housing programmes, and Rajasthan's expanding smart city infrastructure investments. West India's 28.4% reflects Mumbai's commercial real estate density and Gujarat's industrial township development creating sustained FCB demand.
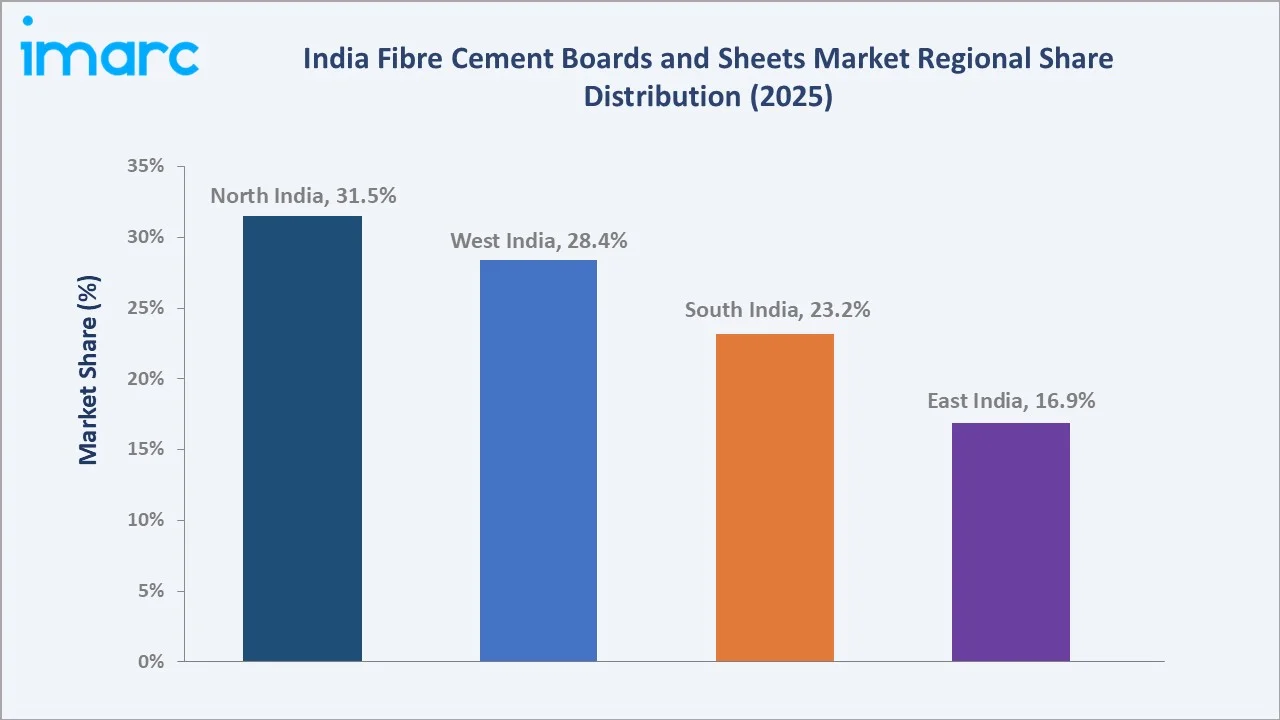
South India's 23.2% reflects Tamil Nadu and Andhra Pradesh's strong manufacturing and industrial construction base, while coastal climate conditions drive elevated roofing and cladding demand. East India's 16.9% is growing above the overall market CAGR as new manufacturing capacity investments, including Everest Industries' Assam plant, create improved supply chain economics.
Competitive Landscape
India fibre cement boards and sheets market competitive landscape is characterized by a mix of large domestic-listed manufacturers and specialized producers. Competition is intensifying through capacity expansion, non-asbestos product development, and geographic expansion into underserved regions.
|
Company |
Key Products |
Market Position |
Core Strength |
|
Visaka Industries Limited |
Cement Roofing Sheets |
Strong Challenger |
Comprehensive non-asbestos FCB portfolio with capacity expansion in West Bengal and strong South India presence; VNXT engineered boards target premium specification-grade commercial and green-certified projects, supporting above-average margin realization. |
|
Ramco Industries Limited |
Ramco Hicem |
Strong Challenger |
South India-focused manufacturer with strong dealer network and competitive pricing in the roofing segment; long-standing presence in Tamil Nadu and Andhra Pradesh provides deep regional distribution penetration and strong contractor preference programs. |
|
NCL Industries |
NCL cement boards |
Strong Challenger |
Andhra Pradesh-based manufacturer with strong regional presence and competitive roofing product range; established distributor relationships across South India and integrated cement operations provide a cost structure advantage over non-integrated FCB manufacturers. |
|
U. P. ASBESTOS LIMITED |
Asbestos Cement Sheet |
Strong Challenger |
Established North India-focused manufacturer with strong presence in asbestos-based roofing segment; deep distribution penetration in UP, Rajasthan, and Haryana through long-standing dealer networks supports volume demand capture in rural and semi-urban markets. |
Key players include Visaka Industries Limited, Ramco Industries Limited, NCL Industries, U. P. ASBESTOS LIMITED, and others.
Key Company Profiles
Visaka Industries Ltd.
Visaka Industries Ltd. is a prominent Indian building materials manufacturer specializing in non-asbestos fibre cement boards and sheets, known for its V-Boards and VNXT product range, with manufacturing presence across South India and expanding capacity in eastern India.
- Key Products: Cement Roofing Sheets
- Strategic Focus: Expanding non-asbestos FCB production capacity to capture growing specification-grade market demand from LEED and GRIHA-certified construction projects; geographic diversification into eastern India through new manufacturing investment; and building premium product portfolio targeting commercial and hospitality segments.
Ramco Industries Limited
Ramco Industries Limited is a company with interests in building materials, cotton yarn, surgical cotton, software, and power, and is one of the leading fibre cement sheet and calcium silicate board manufacturers in South Asia.
- Key Products: Ramco Hicem
- Strategic Focus: Expanding fibre cement board production capacity into central India through the new Madhya Pradesh plant to strengthen pan-India distribution reach; leveraging the established 8,000-strong partner network across South Asia to grow market share in roofing and dry construction applications; and advancing the non-asbestos Ramco Greencor and Ramco Hicem product ranges to capture growing specification-grade demand from commercial and green-certified construction projects.
Market Concentration Analysis
India fibre cement boards and sheets market is moderately concentrated among the top five players, with the key players commanding significant combined organized-market share. The market remains fragmented due to regional manufacturers and unorganized producers with strong local distribution in rural roofing segments.
Market concentration is evolving as large manufacturers accelerate capacity expansion and non-asbestos product transitions, while regulatory pressure on asbestos-based producers and the growth of green building specifications are reshaping the competitive landscape in favour of organized, BIS-certified manufacturers.
Investment & Growth Opportunities
Highest Growth Segments
Non-asbestos FCBs (~7.6% CAGR through green building mandate adoption), cladding and facade applications (~7.1% CAGR through commercial real estate growth), siding (~6.8% CAGR through premium residential demand), and East India market expansion (~8% CAGR from lower penetration base) represent the highest-growth investment vectors through 2034.
Emerging Investment Opportunities
The non-asbestos FCB market, growing at ~7.6% annually, represents the most attractive high-margin investment opportunity. Specification-grade products with LEED and GRIHA certification compatibility, premium surface finishes, and lightweight profiles are creating premium categories commanding significant price premiums over standard asbestos roofing sheets.
Investment Themes
- Non-asbestos FCB production capacity expansion targeting green building specification market: Manufacturers investing in autoclave and air-cured non-asbestos FCB production are positioned to capture above-market growth as LEED, IGBC, and GRIHA certification mandates drive specification-grade material substitution across commercial and premium residential construction.
- East India manufacturing and distribution network development for organized market share capture: Eastern India represents the most commercially underserved organized FCB market, with growing construction demand and lower organized-brand penetration creating significant first-mover advantage for manufacturers establishing regional manufacturing and dealer networks.
Future Market Outlook (2026-2034)
The India fibre cement boards and sheets market is projected to grow from USD 141.7 Million in 2025 to USD 150.2 Million in 2026, reaching USD 243.9 Million by 2034, registering a CAGR of 6.00% during 2026–2034. The market's anchor value of approximately USD 189.6 Million in 2030 reflects the structural inflection as non-asbestos products achieve majority market share and green building mandates become standard specifications.
Three structural forces define growth through 2034: India's sustained housing and infrastructure investment creating volume demand; regulatory and specification-grade shifts driving non-asbestos product adoption; and geographic market democratization through new eastern and northern region manufacturing capacity investments.
Research Methodology
Primary Research
Primary research comprised structured interviews with India fibre cement boards and sheets industry stakeholders, including product managers, sales directors, channel distributors, contractors, real estate developers, and institutional buyers across North, West, South, and East India, covering roofing, cladding, and interior application segments.
Secondary Research
Secondary research encompassed India construction sector data, BIS certification reports, company annual reports, industry association publications, green building certification data, government housing scheme progress reports, and investor presentations. Over 40 secondary sources were reviewed.
Forecasting Models
Market revenue forecasts were developed using a construction activity-linked demand model: India's residential and non-residential construction square footage pipeline multiplied by FCB application density per construction type and average ASP per segment, with green building adoption multiplier applied across non-asbestos specification segments.
India Fibre Cement Boards and Sheets Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Raw Materials Covered | Asbestos, Non-Asbestos |
| Applications Covered | Roofing, Siding, Cladding, Moulding and Trimming, Others |
| End Uses Covered | Residential, Non-Residential |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Visaka Industries Limited, Ramco Industries Limited, NCL Industries, U. P. ASBESTOS LIMITED, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India fibre cement boards and sheets market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India fibre cement boards and sheets market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India fibre cement boards and sheets industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Fibre Cement Boards and Sheets Market Report
India fibre cement boards and sheets market size is estimated at USD 150.2 Million in 2026, driven by urbanization, green building adoption, and infrastructure growth. Rising demand for sustainable, fire-resistant building materials further supports market expansion across residential and commercial segments.
India fibre cement boards and sheets market grows at 6.00% CAGR during 2026-2034, reaching USD 243.9 Million by 2034. Growth is sustained by housing construction, green building mandates, rural electrification, and the ongoing transition from asbestos to non-asbestos products.
Asbestos leads at 55.8% through established supply chains, cost-effectiveness, and strong demand from rural and semi-urban roofing markets. However, non-asbestos is the faster-growing segment driven by green building certification requirements.
Roofing leads at 36.8% through cost-effectiveness, durability across diverse climatic conditions, and widespread adoption in low-cost residential, rural housing, and industrial shed construction across all Indian regions.
North India leads at 31.5% through dense construction activity in Delhi-NCR, large-scale PMAY housing programmes in UP, and government smart city infrastructure investment across Rajasthan and Haryana creating consistent structural volume demand.
Leading companies include include Visaka Industries Limited, Ramco Industries Limited, NCL Industries, U. P. ASBESTOS LIMITED, and others.
India fibre cement boards and sheets market is projected to reach approximately USD 189.6 Million by 2030, with non-asbestos FCBs achieving majority market share, cladding and facade applications growing rapidly, and eastern India emerging as the most commercially dynamic regional growth market.
Three priority investment opportunities: non-asbestos FCB production capacity expansion targeting green building specification demand; East India manufacturing and distribution network development; and premium cladding and facade product range development targeting commercial real estate and hospitality specification segments.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade