India Hybrid Vehicles Market Size, Share, Trends and Forecast by Hybrid Vehicle Type, Vehicle Type, and Region, 2026-2034
India Hybrid Vehicles Market Size, Share, Trends & Forecast (2026-2034)
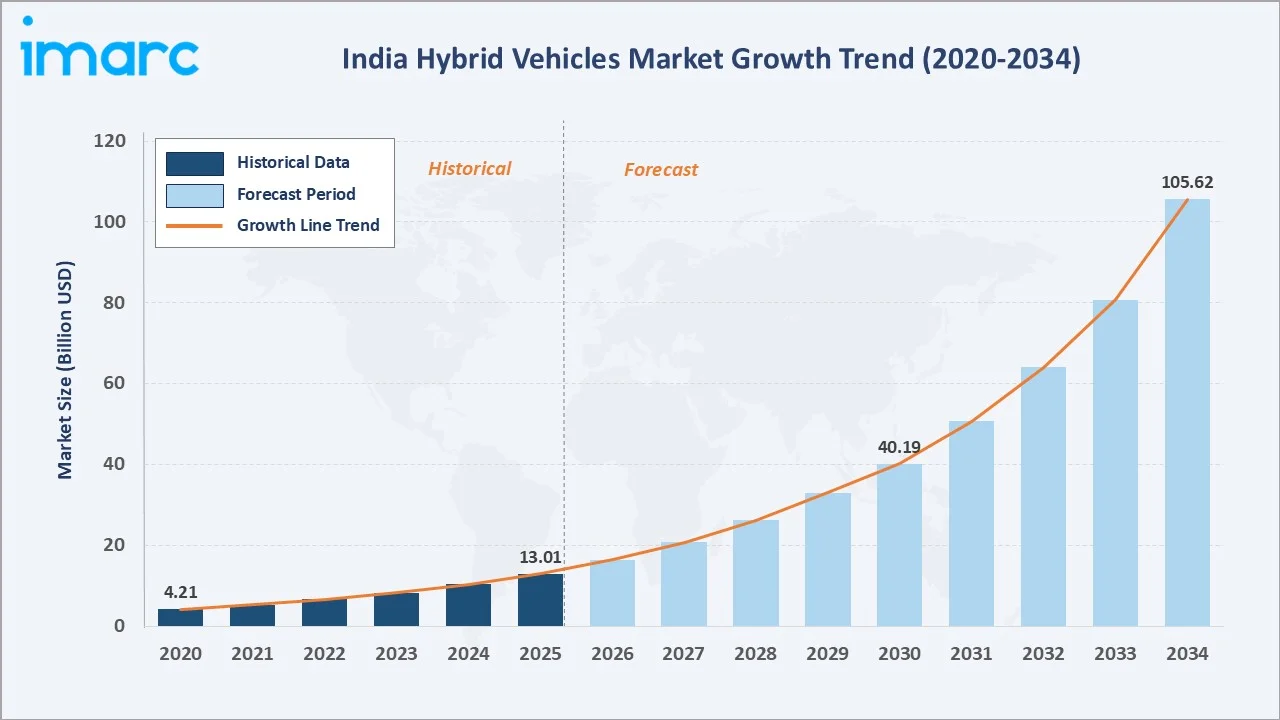
The India hybrid vehicles market grew from USD 13.01 Billion in 2025 to USD 17.39 Billion in 2026 and is projected to reach USD 105.62 Billion by 2034, exhibiting an exceptional CAGR of 25.30% during 2026-2034. During January–June 2026, India recorded 148,023 electric passenger vehicle retail sales, marking a substantial 79% year-on-year increase from 82,535 units in H1 2025. In comparison, strong hybrid vehicles registered 57,885 units, indicating that approximately 2.56 electric cars were sold for every strong hybrid vehicle during the period. This rising consumer acceptance of electrified mobility is supporting the India hybrid vehicles market, as buyers increasingly prioritize fuel efficiency, lower emissions, and alternatives to conventional internal combustion engine vehicles. Full-hybrid leads at 54.5%, passenger cars dominate at 92.5%, and North India commands the largest regional share at 32.5%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 13.01 Billion |
| Market Size (2026) | USD 17.39 Billion |
|
Forecast Market Size (2034) |
USD 105.62 Billion |
|
CAGR (2026-2034) |
25.30% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Hybrid Vehicle Type |
Full-Hybrid – 54.5% (2025) |
|
Dominant Vehicle Type |
Passenger Cars – 92.5% (2025) |
|
Leading Region |
North India – 32.5% (2025) |
The India hybrid vehicles market expanded from USD 4.21 Billion in 2020 to USD 13.01 Billion in 2025 and an estimated USD 17.39 Billion in 2026, driven by normalizing full-hybrid technology, mass-market mild-hybrid (MHEV) integration, and the mandatory CO2 reduction targets compelling all OEMs to accelerate electrification of their India model lineup. The market is projected to reach USD 40.19 Billion by 2030 and USD 105.62 Billion by 2034.
To get more information on this market, Request Sample
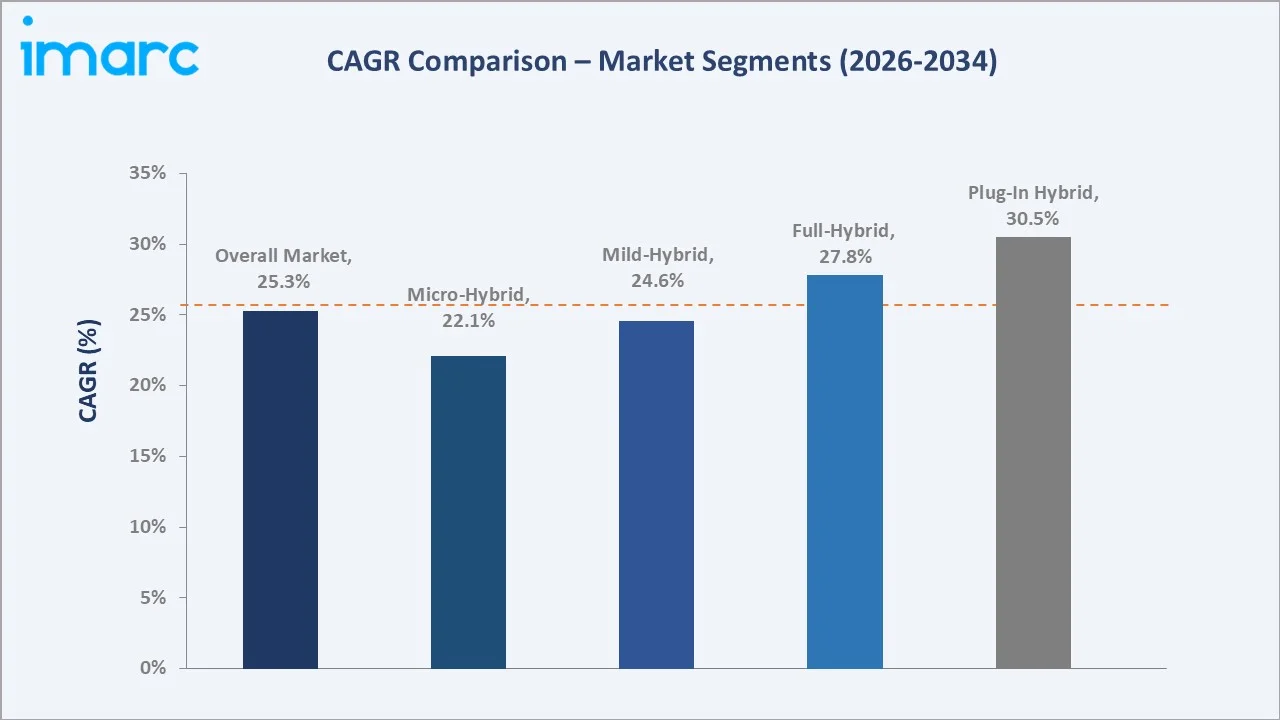
Plug-in hybrid grows fastest at ~30.50% CAGR through FAME III subsidy inclusion and urban charging infrastructure expansion. Full-hybrid grows at ~27.80% CAGR through Toyota’s volume scaling and new OEM entries. Mild-hybrid grows at ~24.60% CAGR through mass-market OEM integration across B and C segment vehicles. Micro-hybrid grows at ~22.10% CAGR through commercial vehicle and entry-level car fuel economy compliance.
Executive Summary
India hybrid vehicles market represents one of the Asia-Pacific region’s most rapidly accelerating automotive electrification transitions, where one of the largest automobile market by volume is undergoing a structural technology shift from pure internal combustion engine (ICE) vehicles toward increasingly electrified powertrains, with hybrid vehicles serving as the pragmatic technology bridge that simultaneously delivers material CO2 emission reduction and fuel economy improvement without the range anxiety, charging infrastructure dependency, and upfront cost barriers of full battery electric vehicles.
Full-hybrid’s 54.5% dominance reflects the market’s quality leadership by Toyota and Honda, whose full-hybrid systems deliver real-world fuel economy improvements versus comparable ICE vehicles that represent compelling total cost of ownership advantages. Passenger cars’ 92.5% vehicle type dominance reflects India’s hybrid market’s current concentration in the personal mobility segment. North India’s 32.5% regional leadership reflects the Delhi NCR’s large premium vehicle market, the pollution control restrictions that incentivize non-ICE vehicle ownership, and the region’s above-average household income density driving hybrid premium vehicle purchases.
Key Market Insights
|
Insight |
Data |
|
Dominant Hybrid Vehicle Type |
Full-Hybrid – 54.5% share (2025) |
|
Dominant Vehicle Type |
Passenger Cars – 92.5% share (2025) |
|
Leading Region |
North India – 32.5% share (2025) |
|
Market Opportunity |
PHEV infrastructure-linked subsidy under FAME III; hybrid taxi and app-based ride-hailing fleet adoption; hybrid commercial vehicles; indigenous hybrid battery manufacturing under PLI scheme |
Key Analytical Observations:
- Full-Hybrid at 54.5% (2025): Full-hybrid vehicles, defined by their capacity to drive on electric power alone at low speeds, recuperate kinetic energy through regenerative braking, and seamlessly blend electric motor and combustion engine power through an electronic power split device, command India’s hybrid market through technology leadership that has created a benchmark for full-hybrid performance against which all competing hybrid architectures are evaluated.
- Passenger Cars at 92.5% (2025): Passenger cars’ overwhelming dominance reflects India’s hybrid market’s current characterization as a personal mobility technology, where the fuel cost saving rationale, the premium aspirational positioning, and the urban commute use case alignment collectively make hybrid powertrains most compelling for individual car buyers making considered purchase decisions rather than commercial fleet operators prioritizing total cost of ownership across multiple assets.
- North India at 32.5% (2025): North India leads the market, supported by strong vehicle demand across major urban centers such as Delhi-NCR, Chandigarh, and Jaipur, along with rising consumer preference for fuel-efficient and lower-emission vehicles. Higher purchasing power, expanding dealership networks, and growing awareness of hybrid technologies further strengthen regional adoption.
India Hybrid Vehicles Market Overview
The India hybrid vehicles market encompasses passenger cars and commercial vehicles equipped with hybrid powertrains that combine an internal combustion engine with one or more electric motors. It includes mild hybrids, full/strong hybrids, and plug-in hybrid electric vehicles (PHEVs) across multiple vehicle categories. Macroeconomic factors include rising disposable incomes, rapid urbanization, fluctuating fuel prices, and continued growth in passenger vehicle ownership. Economic expansion, infrastructure development, stricter emission standards, and government support for cleaner mobility are also encouraging the adoption of fuel-efficient hybrid vehicles.
Market Dynamics
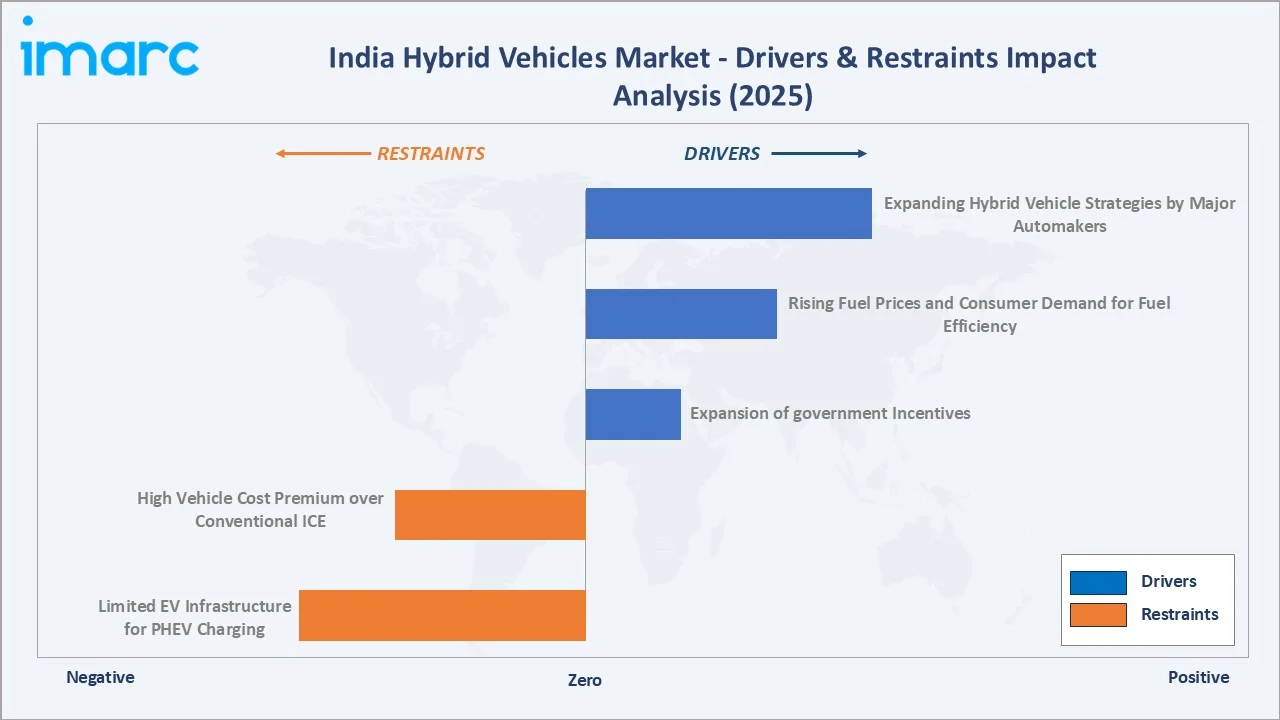
To evaluate market opportunities, Request Sample
Market Drivers
- Expanding Hybrid Vehicle Strategies by Major Automakers: Maruti Suzuki aims for hybrids to account for 25% of its powertrain mix by 2030, alongside 35% CNG and 15% EVs, while Hyundai expects hybrids to contribute around 14%, equal to its targeted EV share. These strategies indicate growing OEM commitment to hybrid technology, which is expected to broaden model availability, improve consumer access, and accelerate growth of the India hybrid vehicles market.
- Rising Fuel Prices and Consumer Demand for Fuel Efficiency: The latest fuel price revision added ₹2.61 per liter to petrol and ₹2.71 per liter to diesel, pushing petrol prices in Delhi above ₹102 per liter and diesel prices beyond ₹95 per liter. Rising fuel prices have fundamentally altered the total cost-of-ownership calculation for hybrid versus conventional ICE vehicles. For commercial operators, the fuel savings payback period compresses to 18-24 months, creating a compelling commercial case for fleet-level hybrid conversion that cab operators, including Ola, Uber, and more, have progressively acted upon.
- Expansion of government Incentives: India’s FAME (Faster Adoption and Manufacturing of Electric Vehicles) policy architecture has been the single most important government intervention supporting the hybrid market’s development alongside the electric vehicle ecosystem. FAME II’s focus on the bus segment laid the foundation for the commercial vehicle hybrid market through urban bus operator procurement.
Market Restraints
- High Vehicle Cost Premium over Conventional ICE: Hybrid vehicles generally carry a higher upfront purchase price than comparable internal combustion engine (ICE) vehicles due to the added cost of batteries, electric motors, and power electronics. This price premium can discourage cost-sensitive buyers, particularly in the mass-market segment. Limited awareness of long-term fuel savings also slows adoption, thereby hampering the growth of the market.
- Limited EV Infrastructure for PHEV Charging: The limited availability and uneven distribution of public charging stations across India restrict the convenience of owning plug-in hybrid electric vehicles (PHEVs). Charging infrastructure remains concentrated in major urban centers, creating accessibility challenges in smaller cities and along highways. This infrastructure gap reduces the practical benefits of PHEVs and can discourage consumers from adopting plug-in hybrid models.
Market Opportunities
- Commercial Fleet Hybrid Transition for Cab Aggregators and Corporate Fleets: As of July 2026, Bharat Taxi had approximately 8 lakh registered drivers and nearly 41 lakh registered customers across multiple cities in India. India’s registered commercial cab aggregator vehicles represent the hybrid market’s highest-impact fleet adoption opportunity, where individual driver-partner economics create a compelling business case for hybrid adoption that generates fuel savings versus equivalent ICE vehicles.
- Hybrid Battery Localization under Production Linked Incentive (PLI) Scheme: The Government of India’s PLI Scheme for Advanced Chemistry Cell (ACC) Battery Storage, with INR 18,100 crore allocated to develop 50 GWh of domestic battery manufacturing capacity, creates a strategic localization opportunity for hybrid vehicle battery systems that currently rely on imported NiMH and lithium-ion battery packs from Toyota’s Japanese supply chain, driving cost reduction in hybrid battery pack cost as domestic manufacturing scales and import duties on localized components reduce.
Market Challenges
- Limited Consumer Awareness of Hybrid Technologies: Many Indian consumers remain unfamiliar with the differences between mild, strong, and plug-in hybrid technologies. Limited understanding of fuel savings, operating benefits, and ownership costs can make purchase decisions difficult. This restricts hybrid adoption, particularly outside major metropolitan areas.
- Battery Replacement and Maintenance Concerns: Hybrid vehicles integrate batteries, electric motors, power electronics, and conventional engines, resulting in relatively complex powertrains. Consumer concerns regarding battery replacement costs and specialized maintenance can affect purchase confidence. Limited availability of trained technicians in smaller cities further adds to this challenge.
Emerging Market Trends
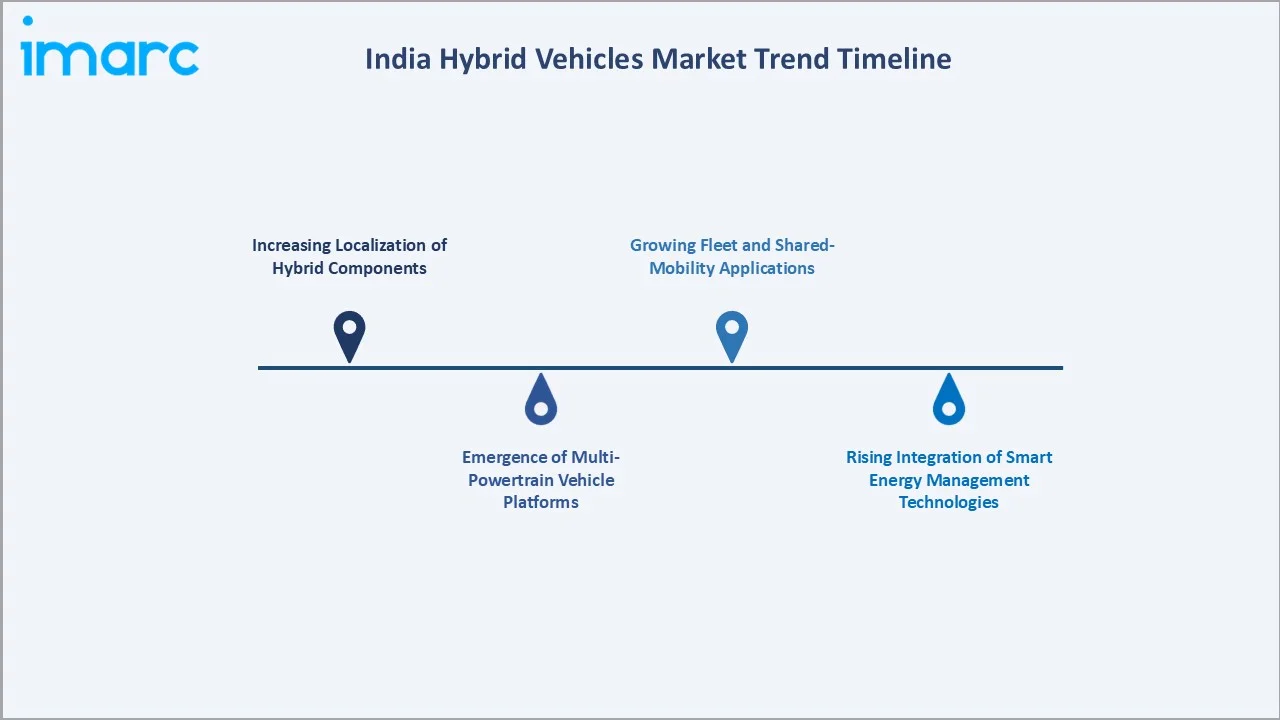
1. Increasing Localization of Hybrid Components
Automakers and suppliers are gradually focusing on local production of batteries, electric motors, power electronics, and related components. Greater localization can reduce dependence on imports and lower overall hybrid vehicle production costs. It can also strengthen supply-chain resilience and enable manufacturers to offer hybrid technology across more price segments. India's expanding automotive manufacturing ecosystem provides a strong foundation for this transition. Localization is therefore expected to improve the long-term affordability of hybrid vehicles.
2. Emergence of Multi-Powertrain Vehicle Platforms
JSW MG Motor plans to introduce two new-energy SUVs in FY27, including a battery electric vehicle (BEV) and a plug-in hybrid electric vehicle (PHEV), based on its new ADAPT platform. The flexible architecture supports multiple propulsion technologies, including BEVs, HEVs, PHEVs, and REEVs, enabling the company to develop different powertrain options on a common platform. This approach allows automakers to diversify electrified product portfolios while improving development efficiency and localization potential. The planned FY27 PHEV launch also signals rising OEM interest in plug-in hybrid technology within the India hybrid vehicles market.
3. Growing Fleet and Shared-Mobility Applications
Fleet operators, taxi services, and shared-mobility companies are increasingly evaluating fuel-efficient vehicles to reduce operating expenses. Hybrid vehicles can provide significant efficiency advantages in urban stop-and-go conditions, where regenerative braking and electric operation are most effective. High annual vehicle utilization can also help offset the higher initial purchase cost through fuel savings. Expansion of app-based mobility services is increasing the potential customer base. This creates opportunities for greater hybrid penetration in commercial passenger mobility.
4. Rising Integration of Smart Energy Management Technologies
Hybrid vehicles are increasingly incorporating intelligent energy management systems that optimize the interaction between engines, electric motors, and batteries. Advanced software can determine the most efficient power source according to speed, driving conditions, and battery charge. Regenerative braking technologies are also improving energy recovery during vehicle operation. These developments enhance fuel economy and driving performance. Continued digitalization of vehicle powertrains is expected to accelerate this trend.
Industry Value Chain Analysis
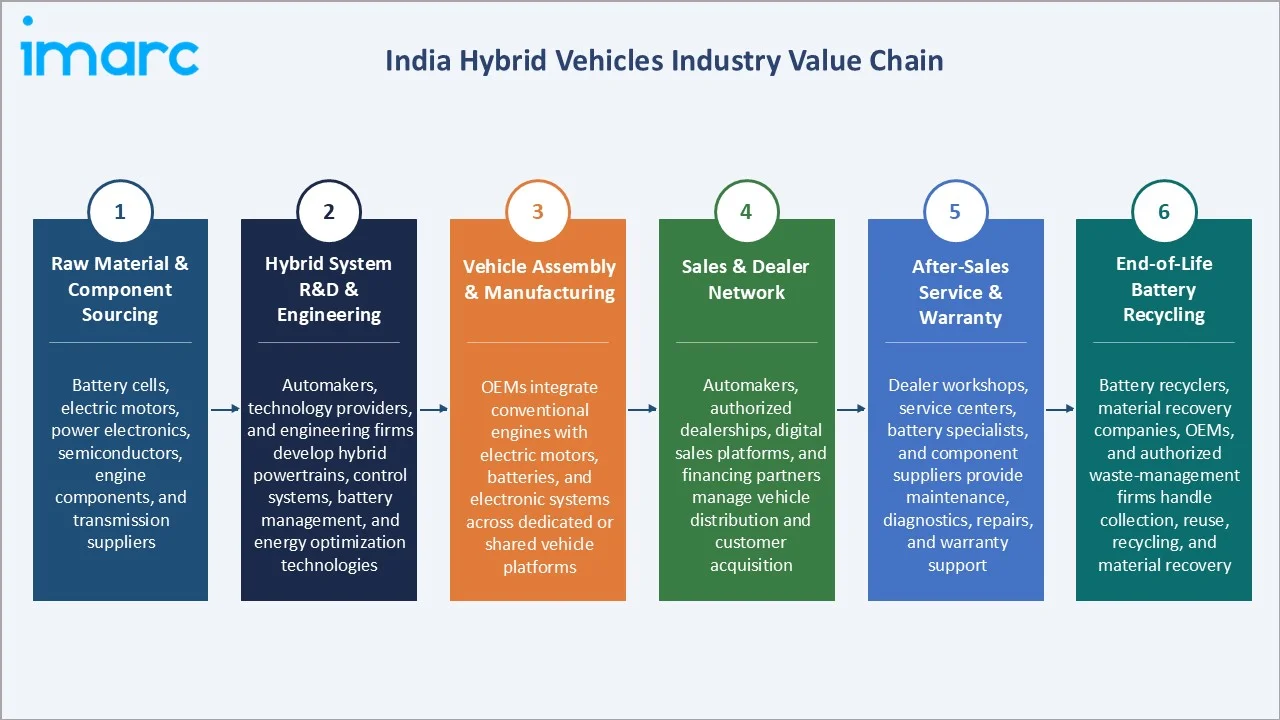
India hybrid vehicle value chain integrates raw material & component sourcing, hybrid system R&D & engineering, vehicle assembly & manufacturing, sales & dealer network, after-sales service & warranty, and end-of-life battery recycling.
|
Stage |
Key Participants |
|
Raw Material & Component Sourcing |
Battery cells, electric motors, power electronics, semiconductors, engine components, and transmission suppliers. |
|
Hybrid System R&D & Engineering |
Automakers, technology providers, and engineering firms develop hybrid powertrains, control systems, battery management, and energy optimization technologies. |
|
Vehicle Assembly & Manufacturing |
OEMs integrate conventional engines with electric motors, batteries, and electronic systems across dedicated or shared vehicle platforms. |
|
Sales & Dealer Network |
Automakers, authorized dealerships, digital sales platforms, and financing partners manage vehicle distribution and customer acquisition. |
|
After-Sales Service & Warranty |
Dealer workshops, service centers, battery specialists, and component suppliers provide maintenance, diagnostics, repairs, and warranty support. |
|
End-of-Life Battery Recycling |
Battery recyclers, material recovery companies, OEMs, and authorized waste-management firms handle collection, reuse, recycling, and material recovery. |
Hybrid system R&D & engineering is the most value-added stage, as it involves developing proprietary powertrain technologies, battery management systems, control software, and energy optimization solutions. Strong R&D capabilities directly influence vehicle efficiency, performance, reliability, and product differentiation.
Technology Landscape in the India Hybrid Vehicles Industry
Strong Hybrid Electric Vehicle (HEV) Technology
Strong hybrid systems combine an internal combustion engine with an electric motor capable of independently propelling the vehicle. The system automatically switches between electric, engine, and combined operation depending on driving conditions. Regenerative braking recovers energy to recharge the battery without external charging. This technology provides improved fuel efficiency and lower emissions, particularly in urban traffic. Strong hybrids are increasingly relevant for India's transition toward electrified mobility.
Mild Hybrid Electric Vehicle (MHEV) Technology
Mild hybrids typically use a smaller electric motor or integrated starter-generator to assist the conventional engine rather than independently power the vehicle. Key functions include engine start-stop, torque assistance, and regenerative energy recovery. The relatively simple architecture makes mild hybrids easier to integrate into conventional vehicle platforms. They provide incremental improvements in fuel economy while keeping costs below those of more sophisticated strong-hybrid systems. This technology remains suitable for cost-sensitive vehicle segments.
Plug-in Hybrid Electric Vehicle (PHEV) Technology
PHEVs combine an internal combustion engine with a rechargeable battery and electric propulsion system. Unlike conventional hybrids, their batteries can be charged through an external electricity source, enabling greater electric-only operation. Once battery charge declines, the vehicle can continue operating through its hybrid powertrain. PHEVs therefore combine electric urban mobility with the longer-distance flexibility of conventional fuel. The technology is emerging as another electrification pathway for the Indian automotive industry.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Hybrid Vehicle Type |
Full-Hybrid |
54.5% |
2025 |
|
Vehicle Type |
Passenger Cars |
92.5% |
2025 |
|
Region |
North India |
32.5% |
2025 |

By Hybrid Vehicle Type
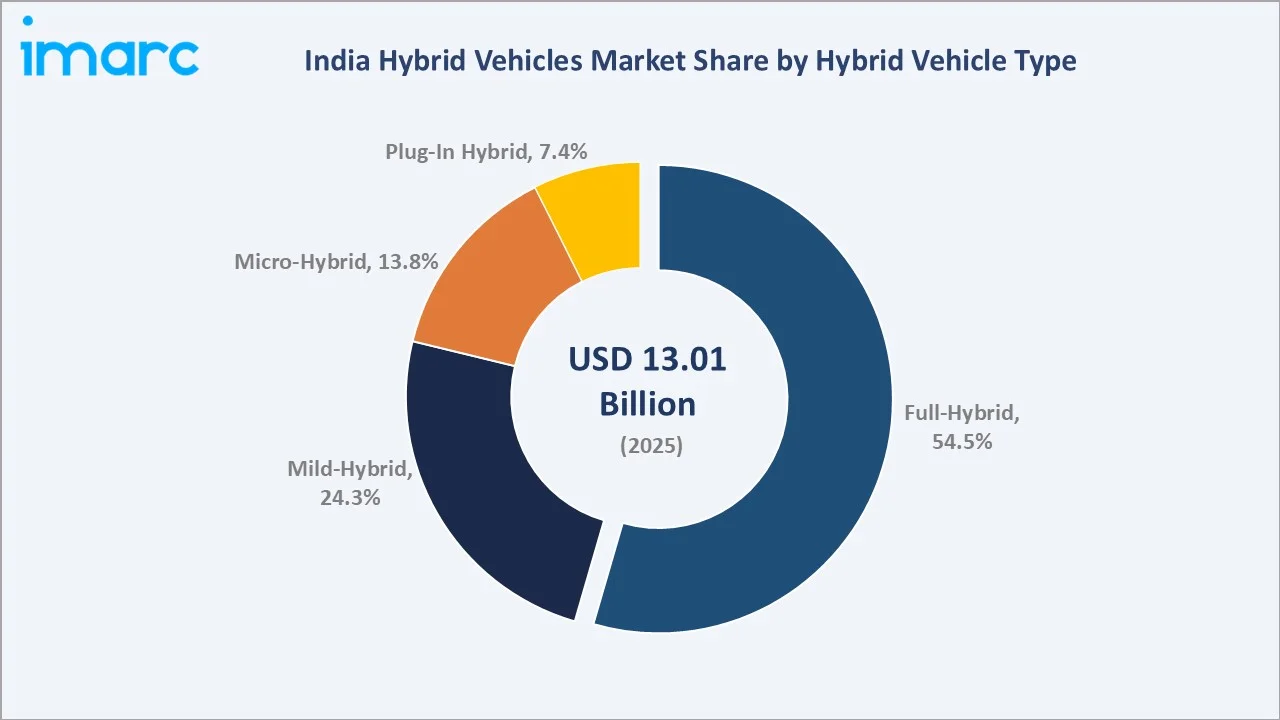
Full-hybrid leads at 54.5% (2025) through Toyota and Honda’s technology leadership and self-charging narrative effectiveness. Mild-hybrid at 24.3% serves mass-market volumes through Maruti Suzuki’s SHVS integration.
To access detailed market analysis, Request Sample
Micro-hybrid at 13.8% serves entry-level compliance and commercial applications. Plug-in hybrid at 7.4% is growing fastest at ~30.50% CAGR through FAME III subsidy and infrastructure alignment.
By Vehicle Type
Passenger cars lead at 92.5% (2025) through the personal mobility sector’s dominant hybrid adoption driven by fuel cost sensitivity and aspirational premium positioning.
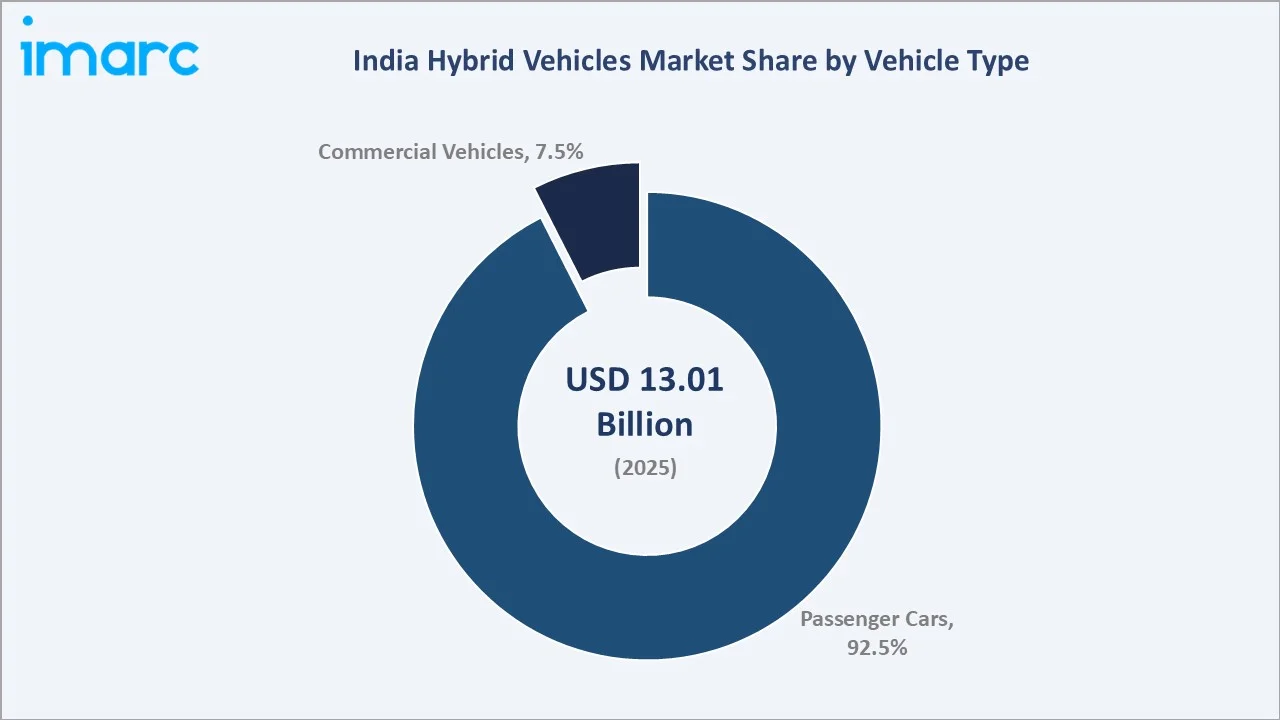
Commercial vehicles at 7.5%, growing at ~28.50% CAGR through government fleet procurement, cab aggregator conversion, and BRTS bus hybridization under FAME II and FAME III mandates.
Regional Market Insights
|
Region |
Share (2025) |
Key India Hybrid Vehicle Market Drivers & Characteristics |
|
North India |
32.5% |
Leads due to strong hybrid adoption in Uttar Pradesh, Delhi-NCR, and Haryana, supported by large urban markets, fuel-efficiency demand, and favorable state-level policies. |
|
West India |
29.4% |
Benefits from high passenger vehicle demand, strong automotive clusters in Maharashtra and Gujarat, extensive dealer networks, and rising adoption of cleaner powertrains. |
|
South India |
25.6% |
Supported by major automotive manufacturing hubs, technology-aware consumers, higher urbanization, and growing acceptance of electrified vehicles in Karnataka, Tamil Nadu, and other states. |
|
East India |
12.5% |
Growth is supported by improving road infrastructure, expanding vehicle ownership, urbanization, and gradually increasing awareness of fuel-efficient hybrid vehicles. |
North India is leading with a 32.5% share in 2025, supported by high hybrid adoption across Uttar Pradesh, Delhi-NCR, and Haryana. West India accounts for 29.4%, benefiting from large automotive markets, higher vehicle ownership, and established dealer networks in Maharashtra and Gujarat.
South India holds 25.6%, supported by strong automotive manufacturing, technology-aware consumers, and demand for fuel-efficient vehicles across Tamil Nadu and Karnataka. East India represents 12.5%, with adoption gradually increasing alongside urbanization, improving purchasing power, and expanding vehicle availability.
Competitive Landscape
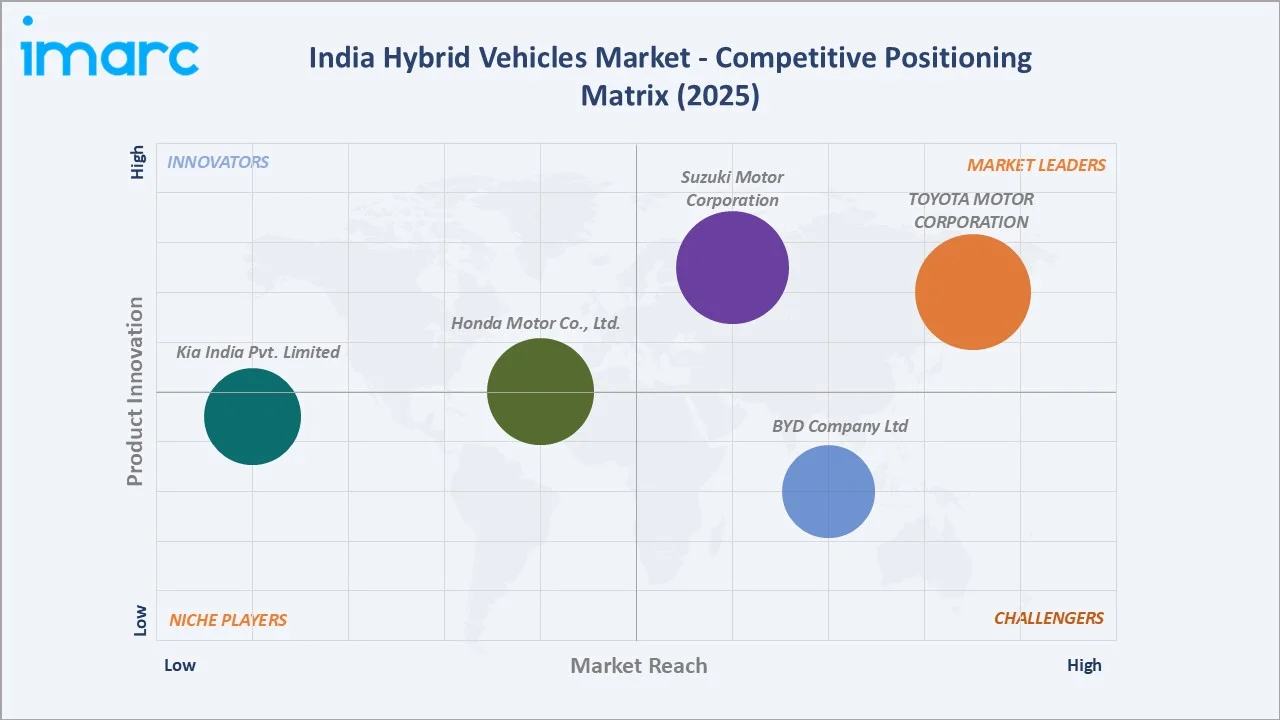
The India hybrid vehicles market is relatively concentrated, with established automakers maintaining strong positions in the mass-market strong-hybrid segment. Competition is intensifying as manufacturers expand hybrid portfolios, introduce hybrid SUVs, localize technologies, and develop multi-powertrain platforms to address growing demand for fuel-efficient vehicles.
|
Company |
Key Products |
Market Position |
Core Strength |
|
TOYOTA MOTOR CORPORATION |
Toyota Hybrid SUVs, Toyota Hybrid Cars, Toyota Plug In Hybrids (PHEVs) |
Market Leader |
Through its joint venture, Toyota Kirloskar Motor (TKM), the Toyota Motor Corporation has dominated hybrid sales in India. |
|
Suzuki Motor Corporation |
INVICTO, GRAND VITARA, ERTIGA, BREZZA, FRONX |
Market Leader |
Their strategy relies on making both mild-hybrid and strong-hybrid technologies accessible to mass-market buyers to reduce emissions and improve fuel economy. |
|
Honda Motor Co., Ltd. |
City e:HEV |
Established Player |
Honda Motor Co., Ltd. uses India as a central pillar of its global hybrid and electrification strategy, focusing on its proprietary e: HEV strong-hybrid technology. |
|
Kia India Pvt. Limited |
Sportage Hybrid, Sorento Plug-in Hybrid |
Established Player |
Actively transforming its portfolio to include strong hybrid electric vehicles (HEVs) as part of a broader multi-powertrain strategy. |
|
BYD Company Ltd |
The BYD DM-i Super Plug-In Hybrid EV |
Challenger |
BYD, with its proprietary DM-i (Dual Mode Intelligent) plug-in hybrid technology, is positioning itself as a bridge for consumers hesitant to switch directly to fully electric vehicles |
India hybrid vehicle competitive landscape is evolving from a technology leadership concentration toward a multi-OEM field where accelerating hybrid model launches will create the competitive pricing pressure that drives average full-hybrid price below the psychological threshold required for mass-market adoption by 2028-2030.
Key Company Profiles
TOYOTA MOTOR CORPORATION
TOYOTA MOTOR CORPORATION is an automotive manufacturer engaged primarily in the production and sale of motor vehicles. In India, the company operates through Toyota Kirloskar Motor and has established a significant presence in the hybrid vehicle segment through its self-charging strong hybrid technology. Toyota leverages its extensive global hybrid expertise, manufacturing capabilities, dealership network, and increasing localization to strengthen its position in India. The company follows a multi-pathway approach toward cleaner mobility, encompassing HEVs, PHEVs, BEVs, fuel-cell vehicles, and alternative-fuel technologies to address diverse mobility and infrastructure requirements.
- Key Products: Toyota Hybrid SUVs, Toyota Hybrid Cars, Toyota Plug In Hybrids (PHEVs).
- Strategic Focus: Strengthening self-charging strong hybrid electric vehicles (SHEVs) as part of its broader multi-pathway approach to carbon neutrality. The company emphasizes expanding hybrid adoption by offering improved fuel efficiency, lower emissions, and electrified driving without dependence on external charging infrastructure.
Suzuki Motor Corporation
Suzuki Motor Corporation is an automobile manufacturer engaged in the development and production of passenger vehicles, motorcycles, marine products, and mobility solutions. In India, Suzuki maintains a major automotive presence through its subsidiary, Maruti Suzuki India Limited, which manufactures and markets passenger vehicles across multiple segments. Within the India hybrid vehicle market, Suzuki supports both mild-hybrid and strong-hybrid technologies, emphasizing improved fuel efficiency, reduced emissions, regenerative braking, and electrified driving capabilities.
- Key Products: INVICTO, GRAND VITARA, ERTIGA, BREZZA, FRONX.
- Strategic Focus: Focused on a multi-pathway electrification approach in India, combining strong hybrids, mild hybrids, BEVs, CNG/CBG, and flex-fuel technologies according to local customer and energy requirements. The company plans to strengthen hybrid adoption through compact, energy-efficient powertrains, lightweight batteries, and greater localization, while expanding its SUV and MPV portfolio.
Market Concentration Analysis
The India hybrid vehicles market is moderately concentrated, with a limited number of established automotive manufacturers holding strong positions in the segment. Leading players benefit from established brands, extensive dealership networks, advanced hybrid technologies, and large-scale manufacturing capabilities. High development costs and technological complexity create significant entry barriers for new participants. Competition primarily centers on fuel efficiency, vehicle pricing, performance, localization, and product portfolio expansion. However, the competitive landscape is gradually broadening as more automakers develop hybrid and plug-in hybrid models. Increasing consumer acceptance of electrified vehicles is expected to encourage further market entry and intensify competition.
Investment & Growth Opportunities
Highest Growth Segments
Plug-in hybrid (~30.50% CAGR) represents India’s highest-growth hybrid investment opportunity through 2034, driven by FAME III’s proposed PHEV subsidy inclusion and urban charging infrastructure expansion that will progressively remove the commercial barriers preventing mass PHEV adoption in India.
Investment Themes
- Hybrid Battery Cell Manufacturing under PLI ACC Scheme: Investment in domestic advanced chemistry cell manufacturing can strengthen the supply chain for hybrid vehicle batteries while reducing dependence on imported cells. PLI-supported capacity can also improve localization, lower battery costs, and create opportunities for battery manufacturers and automotive suppliers.
- Hybrid-Specific Fleet Financing for Cab Aggregator Market: Dedicated financing and leasing solutions for hybrid vehicles can enable cab aggregators and fleet operators to overcome higher upfront acquisition costs. High vehicle utilization and fuel savings can strengthen the total cost of ownership proposition, creating opportunities for banks, NBFCs, leasing companies, and fleet-financing providers.
Future Market Outlook (2026-2034)
The India hybrid vehicles market is expected to increase from USD 13.01 Billion in 2025 to USD 17.39 Billion in 2026 and further to USD 105.62 Billion by 2034, delivering an exceptional 25.30% CAGR that positions India’s hybrid vehicle sector as one of the fastest-growing automotive technology transitions among major economies. The midpoint anchor of USD 40.19 Billion in 2030 confirms the structural acceleration implicit in a market growing at compound rates that reflect both technology adoption curve inflection and policy-driven demand pull.
First, the regulatory mandate structure governing India’s automotive sector is creating an effectively non-optional hybrid technology adoption timeline for every OEM operating in India’s passenger vehicle market. Second, the competitive dynamics within India’s hybrid vehicle OEM landscape are undergoing the most rapid transformation in the market’s history. Third, the hybrid price compression will drive the most important demand democratization event in the market’s history, expanding the addressable buyer pool from India’s current new vehicle buyers who consider hybrid vehicles to pricing that reaches the mainstream consideration threshold that India’s mass-affluent consumer segment occupies.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with hybrid business division leadership, powertrain engineering team, product planning team, electrification strategy division, automotive dealers in Delhi NCR, Mumbai, Bengaluru, and Chennai regarding hybrid vehicle sales dynamics, fleet operators and cab aggregator driver-partners on hybrid vehicle total cost of ownership experience, FAME III policy development, electrification committee, and automotive finance institutions on hybrid vehicle loan product development.
Secondary Research
Secondary research encompassed a detailed review of government publications, automotive industry reports, company annual reports, investor presentations, regulatory documents, and credible trade databases. The research also included analysis of vehicle sales trends, hybrid technology developments, policy initiatives, competitive strategies, and regional adoption patterns across India.
Forecasting Models
Forecasting models were developed using historical India hybrid vehicle sales data, FAME III subsidy scenario modeling, GST rationalization scenario modeling for strong hybrids, new model launch pipeline analysis, India passenger vehicle market growth aligned to GDP and income growth trajectory, fuel price projection scenario, hybrid battery cost reduction trajectory aligned to battery price decline forecast, and competitive pricing scenario modeling for full-hybrid democratization by 2030.
India Hybrid Vehicles Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Hybrid Vehicle Types Covered | Micro-Hybrid, Mild-Hybrid, Full-Hybrid, Plug-In Hybrid |
| Vehicle Types Covered | Passenger Cars, Commercial Vehicles |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | TOYOTA MOTOR CORPORATION, Suzuki Motor Corporation, Honda Motor Co., Ltd., Kia India Pvt. Limited, BYD Company Ltd, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India hybrid vehicles market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India hybrid vehicles market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India hybrid vehicles industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Hybrid Vehicles Market Report
India hybrid vehicles market size is estimated at USD 17.39 Billion in 2026, driven by rising fuel prices, growing demand for fuel-efficient vehicles, and increasing consumer preference for lower-emission mobility solutions. Expanding strong-hybrid model availability, supportive electrification strategies, and greater OEM investment in hybrid technologies are further supporting market growth.
The market grows at 25.30% CAGR, reaching USD 105.62 Billion by 2034, supported by expanding hybrid model portfolios, rising fuel-efficiency requirements, and increasing consumer acceptance of electrified powertrains. Greater localization of hybrid components and continued investment by major automakers are also expected to accelerate market expansion.
Full-hybrid leads at 54.5% (2025) through self-charging hybrid technology and urban efficiency leadership.
Passenger cars lead at 92.5% (2025) through the personal mobility sector’s fuel cost sensitivity and aspirational premium positioning hybrid adoption.
North India leads at 32.5% through Delhi NCR’s GRAP pollution control incentives for hybrid/EV vehicle preference, India’s largest cab aggregator fleet market where hybrid fuel savings economics are most compelling at commercial mileage, and the region’s premium vehicle market density commands the highest penetration.
Leading companies include TOYOTA MOTOR CORPORATION, Suzuki Motor Corporation, Honda Motor Co., Ltd., Kia India Pvt. Limited, and BYD Company Ltd, among others.
The market is projected to reach USD 40.19 Billion by 2030, driven by rising fuel prices, expanding strong-hybrid vehicle availability, and growing demand for fuel-efficient mobility solutions. Increasing OEM investments, greater component localization, and broader consumer acceptance of electrified powertrains are further supporting market growth.
Top investment opportunities include hybrid battery cell and module manufacturing under the PLI ACC scheme, hybrid-specific fleet financing platform, hybrid vehicle charging infrastructure for PHEVs, hybrid battery second-life energy storage, and OEM-agnostic hybrid diagnostic and service technology.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade