India Industrial PC Market Size, Share, Trends and Forecast by Type, Display Type, Sales Channel, End Use Industry and Region, 2026-2034
India Industrial PC Market Size, Share, Trends & Forecast (2026-2034)
The India industrial PC market grew from USD 184.5 Million in 2025 to USD 193.8 Million in 2026 and is projected to reach USD 263.9 Million by 2034, growing at a CAGR of 3.94% during 2026-2034. The market is driven by accelerating Industry 4.0 adoption, PLI scheme-linked electronics manufacturing expansion, and growing IIoT and edge computing deployments across automotive, pharmaceutical, and energy sectors. As of December 31, 2025, India’s Production Linked Incentive (PLI) schemes attracted more than ₹2.16 lakh crore in investments, generating incremental production and sales exceeding ₹20.41 lakh crore. These investments are supporting the India industrial PC market by accelerating domestic manufacturing, factory automation, electronics production, and digitalization across PLI-supported industries. Panel IPC leads type at 31.6%. Capacitive leads display type at 56.8%. West India leads regionally at 34.2%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 184.5 Million |
|
Market Size (2026) |
USD 193.8 Million |
|
Forecast Market Size (2034) |
USD 263.9 Million |
|
CAGR (2026-2034) |
3.94% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Panel IPC (31.6%, 2025) |
|
Dominant Display Type |
Capacitive (56.8%, 2025) |
|
Leading Region |
West India (34.2%, 2025) |
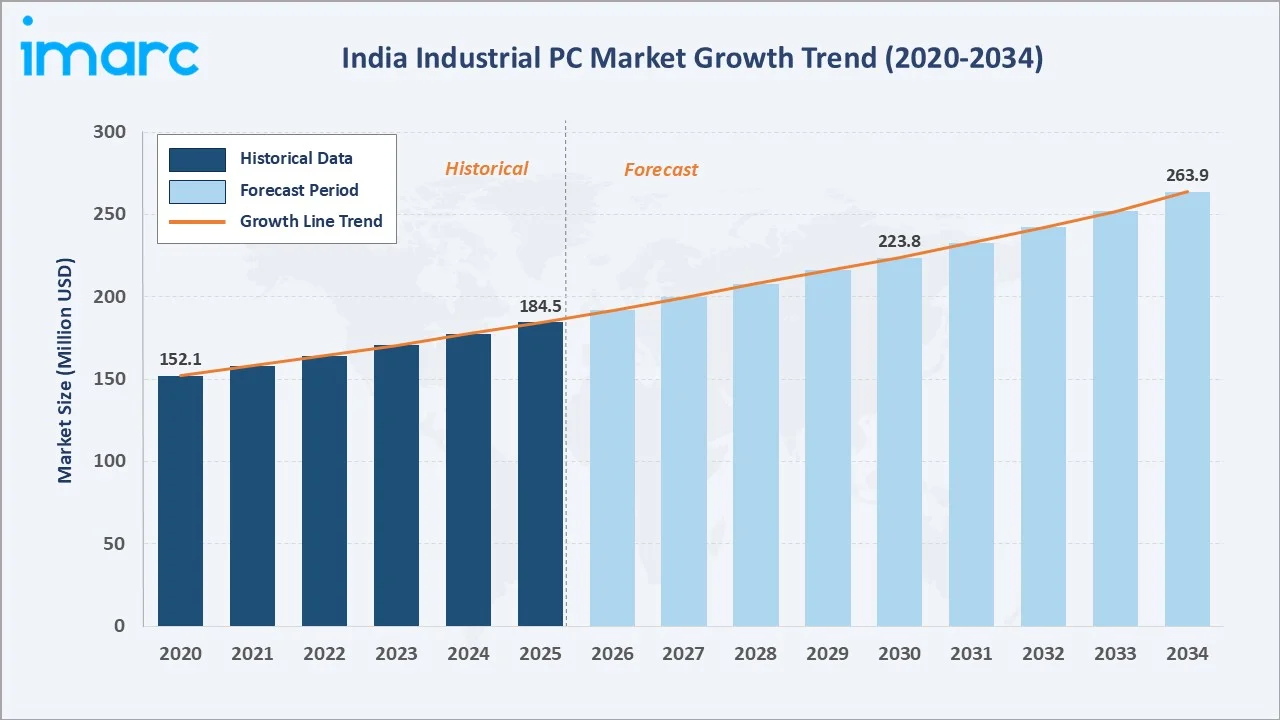
The India industrial PC market has demonstrated steady growth, increasing from USD 152.1 Million in 2020 to USD 184.5 Million in 2025 and an estimated USD 193.8 Million in 2026, reflecting consistent industrial automation investment across manufacturing, energy, and process industries. The market is projected to reach USD 223.8 Million by 2030 and further grow to USD 263.9 Million by 2034, supported by India's smart manufacturing ambitions, growing semiconductor and electronics manufacturing investments, and expanding pharmaceutical and healthcare automation requirements.
To get more information on this market, Request Sample
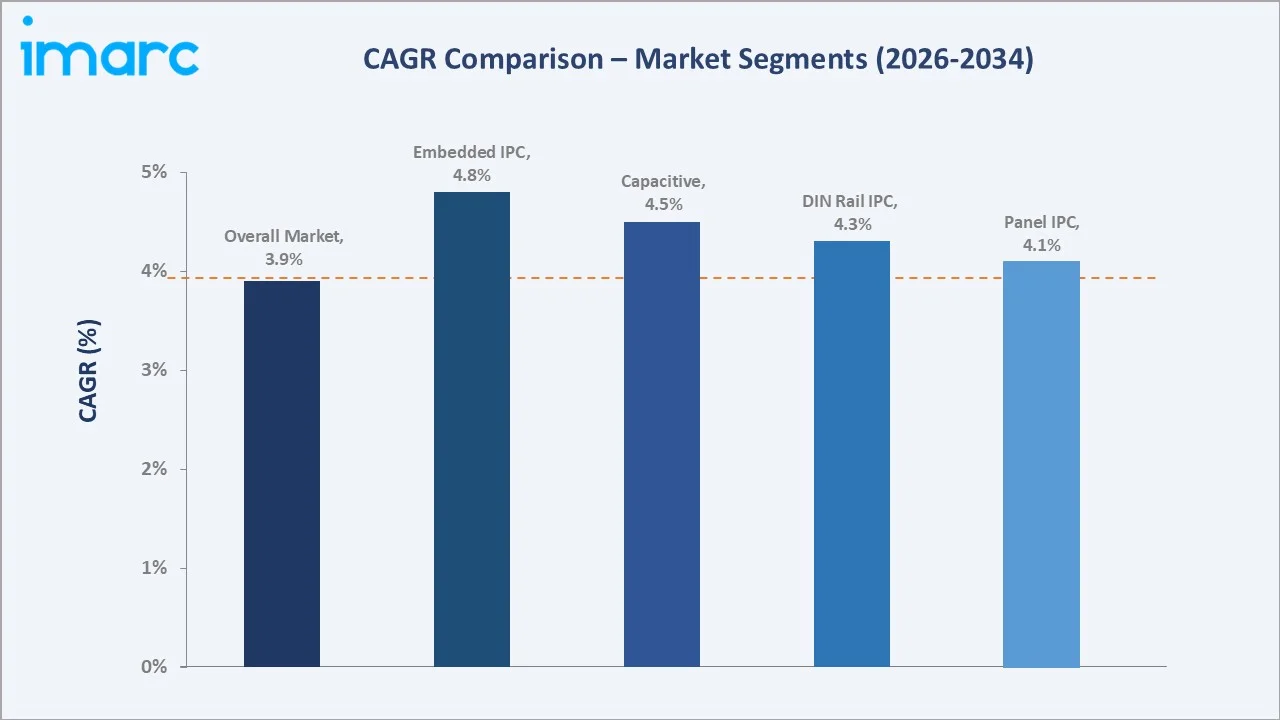
Embedded IPC leads segment CAGR at ~4.8% through growing edge AI and IIoT gateway deployments. Capacitive display grows at ~4.5% CAGR through touchscreen HMI adoption in clean-room and precision manufacturing. DIN rail IPC grows at ~4.3% CAGR through expanding industrial control panel applications in energy and utilities.
Executive Summary
The India industrial PC market is witnessing steady growth, supported by the country's accelerating Industry 4.0 adoption trajectory, PLI scheme-driven expansion of electronics and semiconductor manufacturing, and growing demand for ruggedized computing platforms across automotive, pharmaceutical, energy, and aerospace sectors.
Panel IPC leads at 31.6% through universal HMI applications. Capacitive leads display type at 56.8% through precision touch dominance. West India leads at 34.2% through its dense manufacturing and automation customer base.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Panel IPC – 31.6% share (2025) |
|
Leading Display Type |
Capacitive – 56.8% market share (2025) |
|
Leading Region |
West India – 34.2% share (2025) |
|
Market Opportunity |
PLI-linked semiconductor and electronics IPC demand; pharmaceutical GMP-compliant Panel IPC; AI-accelerated edge IPC for IIoT; defense and aerospace ruggedized IPC; EV and green energy automation |
Key Analytical Observations Supporting the Above Data:
- Panel IPC at 31.6%: Panel IPCs, integrating display, processor, I/O, and HMI into a single flat-panel unit, dominate as the most versatile and universally applicable IPC form factor for machine control, process visualization, and operator workstation applications. Panel IPCs are deployed across virtually all industrial automation applications, from CNC machine tool control to pharmaceutical batch processing and packaging line HMI.
- Capacitive Display at 56.8%: Capacitive touchscreen displays lead over resistive as they provide superior multi-touch sensitivity, higher optical clarity, greater durability for high-cycle industrial touch interactions, and compatibility with gloved operation modes. India's growing premium manufacturing sectors prefer capacitive display IPCs for their hygienic smooth-surface design and accuracy advantages, driving progressive capacitive technology adoption above resistive historical dominance in price-sensitive industrial segments.
- West India at 34.2%: West India leads through Maharashtra's concentration of pharmaceutical manufacturing, automotive industry, and chemical processing facilities that represent India's most intensive industrial automation customers.
India Industrial PC Market Overview
The India industrial PC market encompasses ruggedized computing hardware, including panel IPCs, box IPCs, embedded IPCs, rack mount IPCs, DIN rail IPCs, and related form factors, designed for deployment in industrial environments characterized by temperature extremes, vibration, dust, moisture, and EMI exposure. These systems serve as the computing intelligence in HMI workstations, SCADA servers, machine controllers, edge computing gateways, and process control systems across manufacturing, energy, pharmaceutical, automotive, aerospace, defense, and semiconductor industries.
Display types including capacitive and resistive touchscreens provide operator interaction capabilities. The market includes both imported international brands and growing domestic supply through system integrators and local assembly operations. PLI scheme support for IT hardware and electronics manufacturing is progressively incentivizing domestic IPC assembly in India, while Industry 4.0 adoption driven by the National Manufacturing Policy and smart city programs creates growing demand across multiple end-use industries.
Market Dynamics
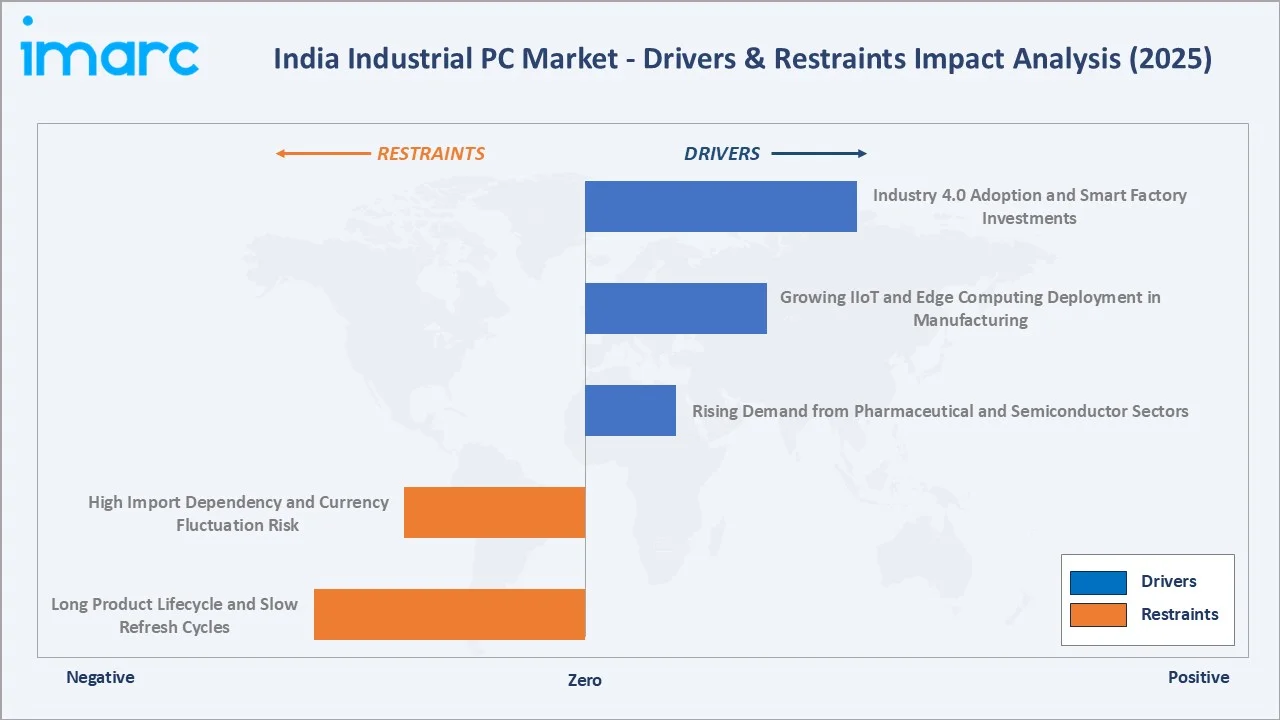
To evaluate market opportunities, Request Sample
Market Drivers
- Industry 4.0 Adoption and Smart Factory Investments: India's manufacturing sector is progressively adopting Industry 4.0 technologies, IIoT, AI, digital twin, and real-time analytics, requiring ruggedized industrial PCs as the edge intelligence layer connecting plant-floor OT equipment with enterprise IT systems. In March 2026, Siemens introduced Teamcenter Digital Reality Viewer and Digital Twin Composer in India as core components of its Industrial AI Operating System. Digital Twin Composer combines digital twin data, simulation, and real-time operational inputs, enabling manufacturers to test and optimize changes virtually before physical implementation.
- Growing IIoT and Edge Computing Deployment in Manufacturing: The integration of Industrial IoT sensors and real-time data processing at the factory edge, enabled by affordable sensor connectivity and cloud platform integration, requires robust edge computing platforms capable of running AI inference, data aggregation, and protocol conversion in harsh industrial environments. Embedded IPCs and DIN rail IPCs are increasingly deployed as edge gateways in motor panels, equipment enclosures, and plant network rooms, creating a growing installed base beyond traditional HMI workstation applications.
- Rising Demand from Pharmaceutical and Semiconductor Sectors: India’s pharmaceutical industry ranks third globally by production volume and eleventh by market value. The sector recorded an annual turnover of Rs. 4.72 lakh crore in FY25, implementing GMP-compliant digital manufacturing with compliance requirements that mandate validated, audit-trail-enabled computing in production environments. Simultaneously, India's semiconductor mission is attracting fab investments that require cleanroom automation, requiring high-reliability, low-particle-emission panel IPCs with smooth-surface capacitive displays and fanless designs.
Market Restraints
- High Import Dependency and Currency Fluctuation Risk: India imports the majority of industrial PCs, making the market highly sensitive to USD/INR and EUR/INR exchange rate movements. Rupee depreciation increases INR-denominated IPC pricing, compressing end-customer purchasing budgets and extending capital expenditure decision timelines. Import dependency also creates supply chain vulnerability to global component shortages.
- Long Product Lifecycle and Slow Refresh Cycles: Industrial PCs in installed applications typically operate for 7-15 years, reflecting industrial customers' preference for long-term stability and validated software compatibility over performance refresh. Extended product lifecycles significantly slow market replacement demand growth compared to commercial PC markets with 3-5 year refresh cycles. Installed IPC base expansion through new factory investments drives market growth more than replacement demand, making the market's growth rate closely correlated with India's capital expenditure cycle in manufacturing.
Market Opportunities
- EV and Green Energy Automation: India's rapidly expanding electric vehicle manufacturing sector and growing renewable energy infrastructure, including solar parks and wind farms, require specialized IPC platforms for battery management system testing, EV assembly line control, and energy management systems. These new industrial segments create growing IPC demand from customers who previously had minimal automation computing requirements, expanding the total addressable market.
- AI-Enabled Rugged Industrial PCs: In March 2026, Getac Technology Corporation launched an AI-ready rugged device portfolio in India, designed to operate reliably across harsh weather conditions, remote sites, and infrastructure-constrained environments. The new devices combine rugged durability with advanced AI capabilities to support field operations in sectors such as pharmaceuticals, manufacturing, automotive, and transportation, as India continues to accelerate digital transformation across Industry 4.0, EVs, aviation, and rail infrastructure. Increasing use of edge AI, predictive maintenance, real-time diagnostics, production monitoring, and digital compliance workflows is expected to expand demand for high-performance industrial computing solutions.
Market Challenges
- Software Ecosystem and OT Cybersecurity Complexity: Indian manufacturing enterprises implementing industrial PCs in connected IIoT architectures face complex OT cybersecurity challenges as plant-floor IPC networks are increasingly connected to enterprise IT systems and cloud platforms. The absence of mature OT security practices among many Indian industrial customers, combined with the complexity of patching and updating industrial PCs in 24/7 production environments without process disruption, creates significant deployment risk management challenges.
- Skilled Workforce Gap for Industrial Computing Integration: Effective industrial PC deployment requires engineers with combined OT and IT competencies that are in short supply in India. The shortage of industrial automation engineers limits the speed at which enterprises can deploy and maintain complex IPC-based automation systems, constraining market adoption velocity even when budget is available.
Emerging Market Trends
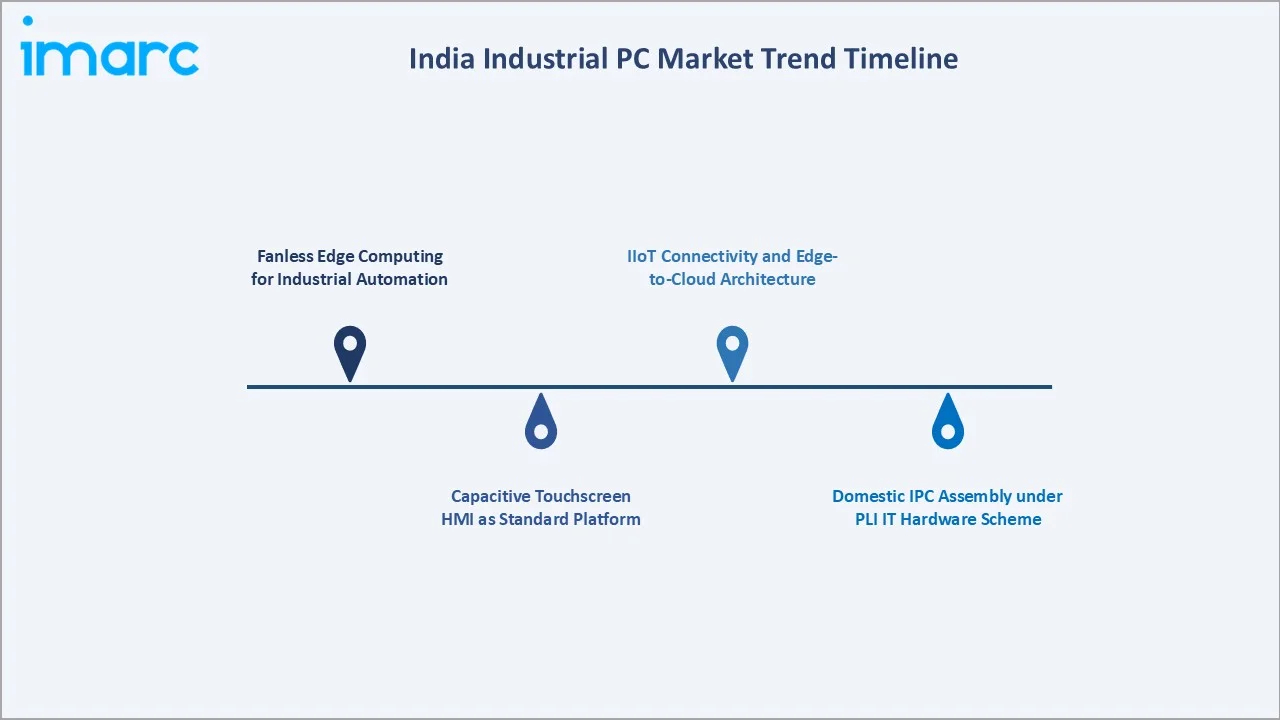
1. Fanless Edge Computing for Industrial Automation
In December 2025, CONTEC launched the BX-M4600 Series, a fanless embedded industrial PC developed for edge computing applications. Equipped with 13th Gen Intel Core i7/i5/i3 processors, the system combines performance and efficiency cores to deliver strong computing capability with optimized power consumption. Its Intel UHD Graphics 770 also supports multi-display and video-processing applications, making it suitable for industrial automation, digital signage, and visual data processing. Demand is increasing for compact, energy-efficient platforms that support real-time analytics, machine vision, multi-display processing, and Industry 4.0 applications while maintaining reliability in harsh industrial environments.
2. Capacitive Touchscreen HMI as Standard Platform
Capacitive multi-touch displays are rapidly replacing resistive touchscreens as the standard HMI interface across new industrial PC deployments, driven by superior tactile experience, higher display resolution and brightness, and compatibility with industrial gloves through configurable touch sensitivity modes. Pharmaceutical GMP environments and precision electronics assembly are particularly strong drivers of capacitive touchscreen adoption that is progressively becoming the baseline expectation for new IPC procurement.
3. IIoT Connectivity and Edge-to-Cloud Architecture
IIoT connectivity and edge-to-cloud architecture are emerging as industries increasingly connect machines, sensors, and industrial PCs for continuous data exchange. Edge computing enables real-time processing close to production equipment, while cloud platforms support centralized analytics, storage, and remote monitoring. This integration improves predictive maintenance, operational visibility, automation, and data-driven decision-making across smart manufacturing environments.
4. Domestic IPC Assembly under PLI IT Hardware Scheme
India's PLI scheme for IT hardware is beginning to create incentives for domestic industrial PC assembly operations, as qualified manufacturers can claim production-linked incentives on domestically assembled computing hardware. System integrators, IPC brands, and domestic players are exploring assembly operations in India to benefit from PLI incentives while reducing import exposure. While full domestic IPC manufacturing remains limited by component ecosystem development, assembly operations using imported boards with local integration are progressively expanding India's domestic IPC supply capability.
Industry Value Chain Analysis
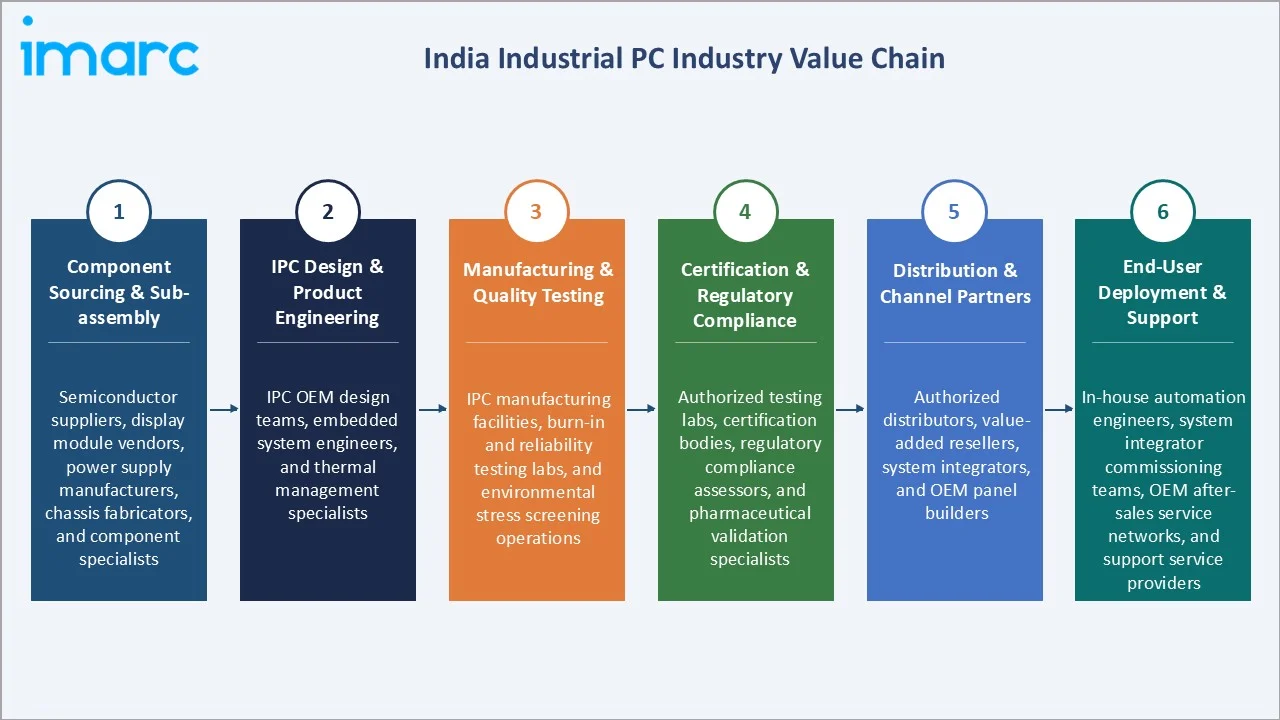
The India industrial PC market value chain integrates component sourcing and sub-assembly, IPC design and product engineering, manufacturing and quality testing, certification and regulatory compliance, distribution and channel partners, and end-user deployment and support.
|
Stage |
Key Participants |
|
Component Sourcing & Sub-assembly |
Semiconductor suppliers, display module vendors, power supply manufacturers, chassis fabricators, and component specialists. |
|
IPC Design & Product Engineering |
IPC OEM design teams, embedded system engineers, and thermal management specialists. |
|
Manufacturing & Quality Testing |
IPC manufacturing facilities, burn-in and reliability testing labs, and environmental stress screening operations. |
|
Certification & Regulatory Compliance |
Authorized testing labs, certification bodies, regulatory compliance assessors, and pharmaceutical validation specialists. |
|
Distribution & Channel Partners |
Authorized distributors, value-added resellers, system integrators, and OEM panel builders. |
|
End-User Deployment & Support |
In-house automation engineers, system integrator commissioning teams, OEM after-sales service networks, and support service providers. |
Distribution and channel partners represent the most commercially influential stage in the India industrial PC market value chain, as value-added resellers and system integrators determine product selection, application engineering support quality, and after-sales service availability for the large majority of Indian industrial customers who lack in-house IPC expertise for specification, selection, and deployment.
Technology Landscape in the India Industrial PC Industry
Panel IPC and HMI Platform Technology
Modern panel IPCs integrate Intel processors, ARM-based SoCs, or AMD processors with capacitive or resistive multi-touch displays, industrial I/O, and fanless or forced-air thermal management in sealed front-panel designs. Screen sizes range from 7-inch compact operator panels to 24-inch or larger visualization workstations. High-brightness displays for outdoor or high-ambient-light deployments and wide operating temperature variants are increasingly demanded by India's outdoor infrastructure and process automation customers.
Display Technology: Capacitive vs. Resistive
Capacitive projected capacitive (PCAP) touch technology is increasingly adopted in industrial displays, offering 10-point multi-touch, superior optical clarity through glass-laminated construction, and high durability exceeding more touch cycles. Resistive touchscreens maintain relevance in applications requiring stylus or thick-gloved input, low-cost price points, and compatibility with liquid-contaminated surfaces where capacitive touch may false-trigger. India's growing pharmaceutical and semiconductor sectors' clean-room requirements are accelerating capacitive adoption above the national average.
IPC Cybersecurity and OT Security
Industrial PC manufacturers are increasingly integrating hardware root-of-trust, secure boot capabilities, encrypted storage, and trusted platform module hardware into IPC platforms to address growing OT cybersecurity requirements. Software security features including allowlisting applications, encrypted industrial communication protocols, and network segmentation support are becoming differentiating features for IPCs deployed in connected IIoT architectures where OT-IT convergence creates new attack surfaces.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Panel IPC |
31.6% |
2025 |
|
Display Type |
Capacitive |
56.8% |
2025 |
|
Sales Channel |
🔒 |
🔒 |
2025 |
|
End Use Industry |
🔒 |
🔒 |
2025 |
|
Region |
West India |
34.2% |
2025 |

By Type
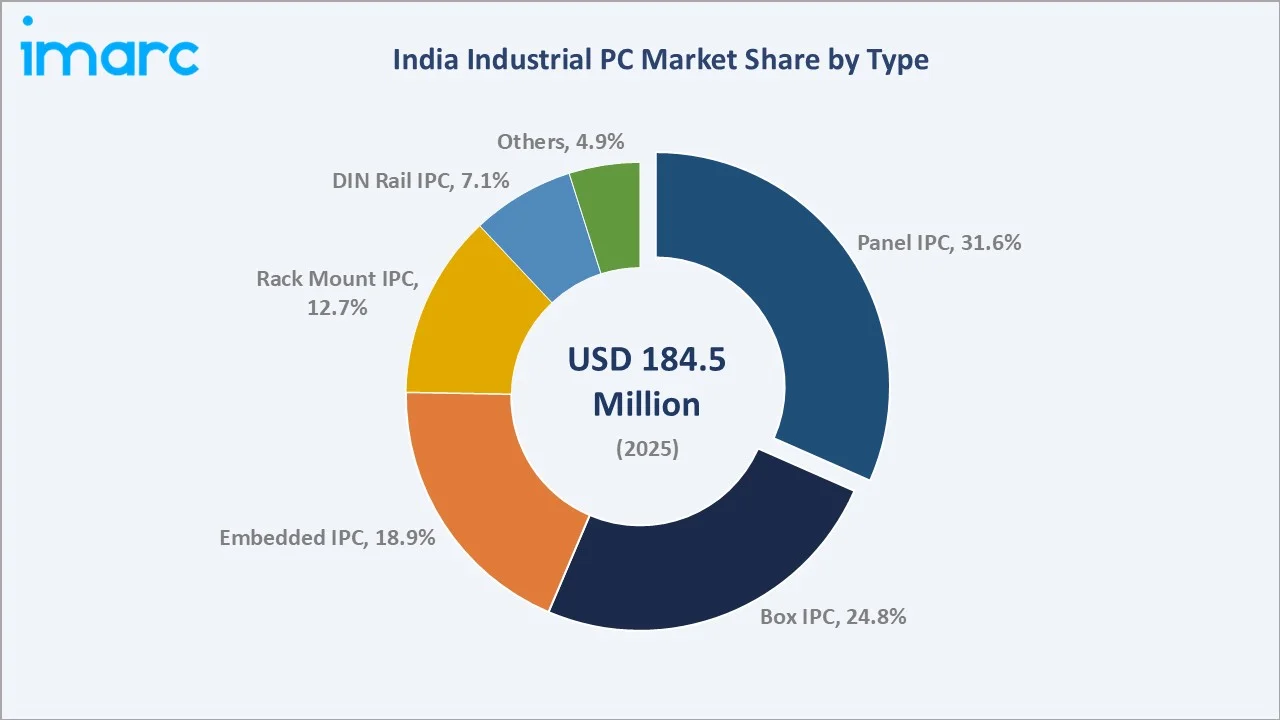
Panel IPC leads at 31.6% (2025), reflecting its universal deployment as machine HMI, operator workstation, and process visualization platform across virtually all industrial automation applications. Panel IPCs' integrated display-computer design simplifies installation and maintenance versus separate monitor-plus-computer configurations, while front-panel IP65 protection meets washdown requirements in food, beverage, and pharmaceutical manufacturing environments.
To access detailed market analysis, Request Sample
Box IPC accounts for 24.8%, serving as flexible general-purpose industrial computers for control room workstations and panel PC motherboards without integrated displays. Embedded IPC represents 18.9%, growing fastest through IIoT gateway and machine-embedded applications. Rack mount IPC holds 12.7%, DIN rail IPC 7.1%, and others 4.9%.
By Display Type
Capacitive display leads at 56.8% (2025), driven by its superior user experience, multi-touch capability, higher optical clarity, and seamless sealed-surface design ideal for hygienic pharmaceutical and food processing environments. The growing preference among new automation system designs for capacitive touchscreen HMI reflects operators' familiarity with smartphone-style touch interaction and the productivity advantages of multi-touch pinch-zoom in complex process overview displays.
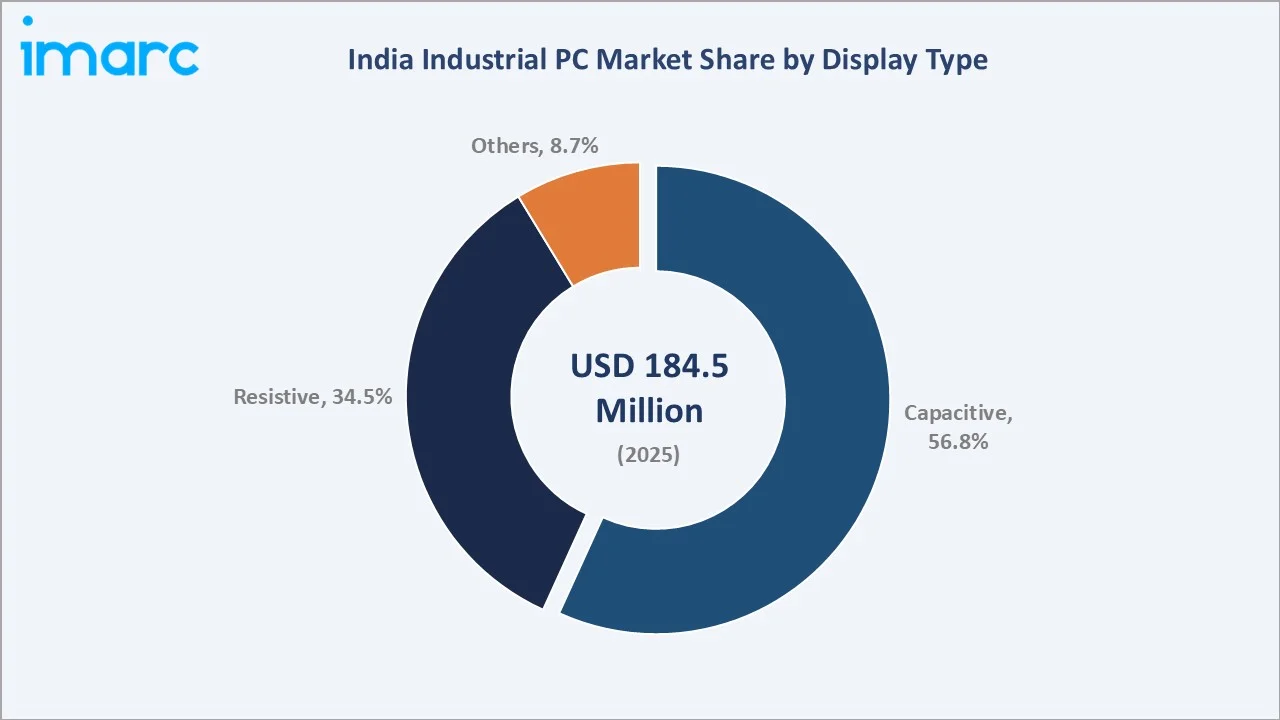
Resistive display accounts for 34.5%, maintaining significant market presence in price-sensitive applications, outdoor kiosks, and environments where thick-gloved operation is required. Others represent 8.7%, encompassing infrared, SAW, and optical touch technology for specialized industrial applications.
Regional Market Insights
|
Region |
Share (2025) |
Key India Industrial PC Market Drivers & Characteristics |
|
West India |
34.2% |
Largest market driven by Maharashtra's pharmaceutical manufacturing clusters, Pune automotive OEM and Tier-1 supplier plants, Gujarat petrochemical and chemical industry automation. |
|
South India |
29.6% |
Fast-growing region with Bengaluru and Hyderabad's semiconductor and electronics manufacturing expansion, Tamil Nadu's automotive and EV manufacturing growth, Karnataka's aerospace and defense sector. |
|
North India |
20.1% |
Growing market with Haryana and UP automotive manufacturing, Delhi NCR's general engineering and pharmaceutical sectors, and Rajasthan's energy and mining automation requirements. |
|
East India |
16.1% |
Emerging market with West Bengal and Odisha's growing industrial base, steel and heavy engineering sector automation, expanding pharmaceutical manufacturing. |
West India's 34.2% dominance reflects Maharashtra's unique combination of India's densest pharmaceutical manufacturing cluster and Pune's automotive industry, representing some of India's most automation-intensive manufacturing facilities. South India's 29.6% and strong growth trajectory reflect Bengaluru's semiconductor and defense electronics manufacturing expansion, Tamil Nadu's EV industry growth, and the region's overall technology orientation accelerating Industry 4.0 adoption.
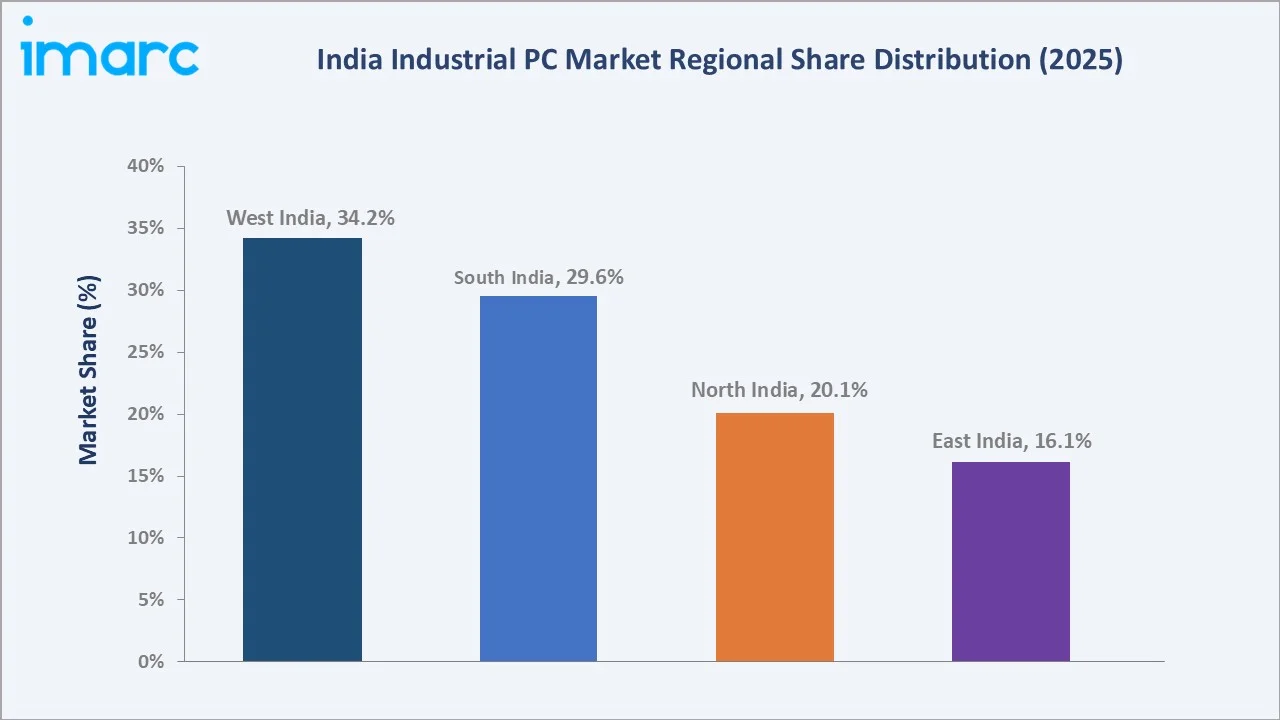
North India at 20.1% benefits from Haryana and Uttar Pradesh's automotive and general engineering manufacturing, while the Delhi NCR industrial corridor creates significant automation investment from diverse manufacturing sectors. East India at 16.1% represents a growing opportunity as West Bengal and Odisha's industrial diversification creates new automation customers, and the region's steel, heavy engineering, and pharmaceutical sectors progressively adopt industrial PC-based control and monitoring systems.
Competitive Landscape
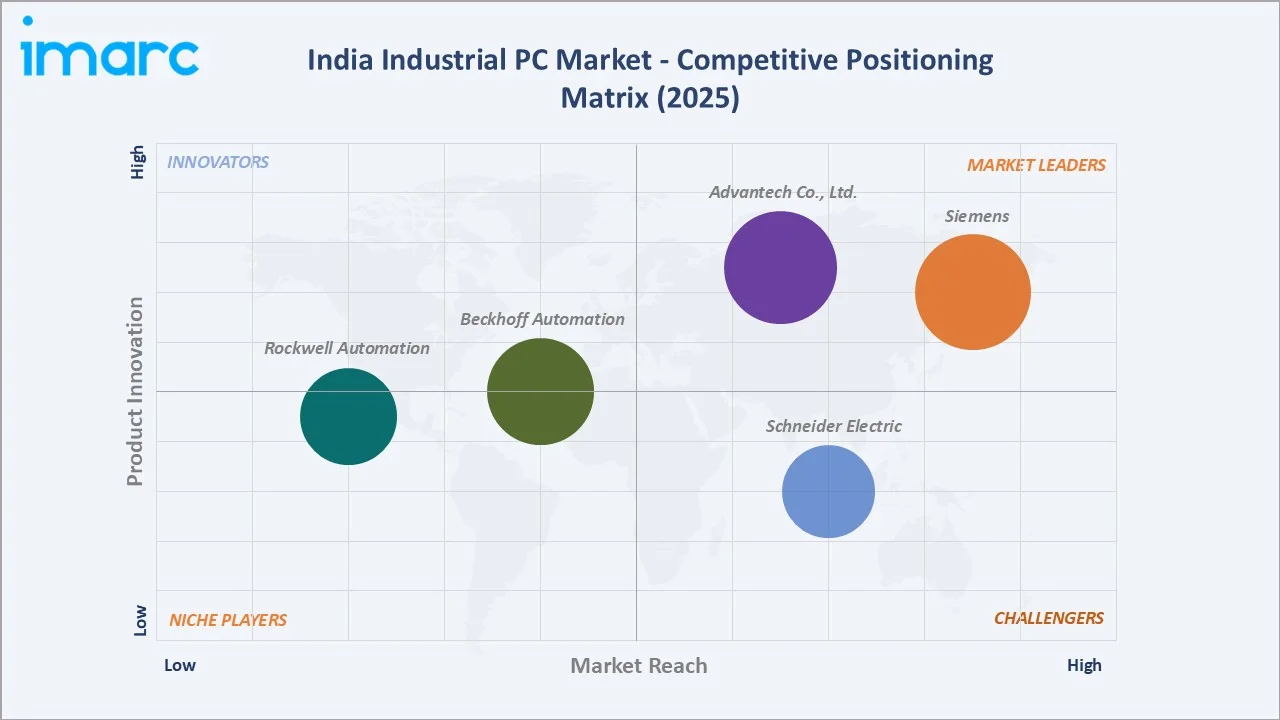
The India industrial PC market is moderately concentrated among a mix of multinational automation technology companies, specialized IPC OEMs, and regional distributors and system integrators. Market participants compete on product portfolio breadth, application engineering support depth, long-term availability commitments, certification credentials, and after-sales service network quality. AI integration capability, IIoT connectivity features, and India-specific application expertise are emerging as key competitive differentiators.
|
Company |
Key Products |
Market Position |
Core Strength |
|
Siemens |
SIMATIC Rack PC, SIMATIC Box PC, SIMATIC Panel PC |
Market Leader |
Siemens plays a major role in the Indian Industrial PC market by providing rugged, high-performance computing devices that control and connect factory machines. |
|
Advantech Co., Ltd. |
RISC Based Panel PC, Entry & Slim-Bezel Panel PC, Enhanced Panel PC, Scalable Panel PC |
Market Leader |
Advantech Co., Ltd. is the leading global provider of Industrial PCs and plays a dominant role in advancing India's industrial automation and smart technology sectors |
|
Beckhoff Automation |
Ultra-compact Industrial PCs, Fanless built-in Industrial PCs, Compact Industrial PCs, Ultra-compact Industrial PCs in IP65, 19-inch slide-in Industrial PCs |
Established Player |
Beckhoff Automation is a pioneer in PC-based automation, playing a major role in transforming how Indian industries control machines and processes |
|
Rockwell Automation |
ASEM 6300 Industrial Computers |
Established Player |
Through its Allen-Bradley brand, Rockwell provides a wide range of industrial computers. |
|
Schneider Electric |
Harmony P6, Harmony FP6 |
Challenger |
Schneider Electric's IPCs are designed to survive harsh environments while supporting critical industrial tasks |
Companies are also investing in AI-accelerated IPC platforms, IIoT connectivity features, India-specific application engineering resources, and long-term product lifecycle commitment programs to differentiate in India's competitive industrial automation market. Further consolidation through strategic partnerships between automation majors and system integrators is expected as the market matures.
Key Company Profiles
Siemens
Siemens is the leading industrial automation technology provider, offering the most comprehensive portfolio of industrial PCs through its SIMATIC IPC series. Siemens' tight integration of SIMATIC IPCs with portal engineering software ecosystems creates a complete automation architecture that resonates strongly with India's large-enterprise manufacturing customers in pharmaceutical, chemical, and automotive sectors.
- Key Products: SIMATIC Rack PC, SIMATIC Box PC, SIMATIC Panel PC.
- Strategic Focus: SIMATIC IPC integration with Siemens industrial edge for AI-powered edge computing, pharma sector compliance program, India manufacturing expansion through various facilities, expanding cybersecurity portfolio for OT-IT converged architectures.
Advantech Co., Ltd.
Advantech Co., Ltd. is one of the largest industrial computer manufacturers and operates a significant India business through its Bengaluru-based India headquarters and extensive distributor network. Advantech's IPC product portfolio is the broadest available in the India market, addressing applications from simple machine HMI to complex Edge AI inference and IIoT gateway requirements across diverse industrial verticals.
- Key Products: RISC Based Panel PC, Entry & Slim-Bezel Panel PC, Enhanced Panel PC, Scalable Panel PC.
- Strategic Focus: WISE-IoT cloud platform integration for edge-to-cloud IIoT deployments, edge AI acceleration, India pharmaceutical and semiconductor sector vertical solutions, PLI-linked domestic assembly evaluation for India market.
Market Concentration Analysis
The India industrial PC market is moderately concentrated, with the top five players Siemens, Advantech Co., Ltd., Beckhoff Automation, Rockwell Automation, and Schneider Electric, collectively estimated to account for approximately 55-65% of total India market revenue in 2025. Multinational brands command premium positioning through comprehensive product portfolios, certified compliance credentials, and strong after-sales support networks that Indian SME customers increasingly value as automation system complexity grows.
Market fragmentation persists in price-sensitive mid-market and SME segments, where Asian-origin IPC brands and India-based system integrators compete on price and localization against European automation majors. The market is expected to see progressive consolidation as PLI scheme incentives attract more organized domestic IPC assembly operations and as system integrators increasingly build preferred supplier relationships with specific IPC brands for recurring project business.
Investment & Growth Opportunities
Highest Growth Segments
Embedded IPC for IIoT edge (~4.8% CAGR), capacitive display IPC (~4.5% CAGR), DIN rail IPC for energy automation (~4.3% CAGR), South India semiconductor and EV manufacturing market expansion, and AI-accelerated IPC for quality inspection represent the highest-growth investment vectors in the India industrial PC market through 2034.
Investment Themes
- AI-accelerated Edge IPC development: Integration of AI neural processing capability into industrial PC platforms enables new high-value applications including real-time quality inspection, predictive maintenance, and autonomous process adjustment that traditional IPCs cannot perform. Platforms combining industrial-grade reliability with AI inference capability command price premiums over standard IPCs while enabling measurable ROI for industrial customers, creating a powerful adoption value proposition.
- Pharmaceutical GMP-compliant IPC specialization: India's world-scale pharmaceutical manufacturing sector represents one of the most demanding and high-value industrial PC application segments, requiring validated computing, stainless steel enclosure compatibility, and fanless hygienic designs. Vendors establishing pharma-specific IPC validation packages, GMP documentation support, and dedicated pharma application engineering resources can capture premium positioning in this high-margin segment.
Future Market Outlook (2026-2034)
The India industrial PC market is projected to grow from USD 184.5 Million in 2025 to USD 193.8 Million in 2026 and further to USD 263.9 Million by 2034, delivering a 3.94% CAGR over the forecast period through accelerating Industry 4.0 smart factory adoption, PLI scheme-linked electronics and semiconductor manufacturing expansion, growing pharmaceutical GMP-compliant digital manufacturing, and increasing IIoT edge computing deployments requiring industrial-grade computing platforms. The market's anchor value of USD 223.8 Million in 2030 represents India's industrial PC ecosystem at AI-accelerated edge IPC mainstream adoption and IIoT-connected factory architecture widespread deployment inflection.
Three structural forces are expected to define the growth of the India industrial PC market through 2034. First, India's sustained manufacturing sector expansion will create consistent new factory construction and greenfield automation investment demand that serves as the primary growth engine for industrial PCs, with each new manufacturing facility requiring IPC-based HMI, machine control, and process monitoring systems across its production infrastructure. Second, the progressive digitalization of India's existing manufacturing base through IIoT sensor integration, edge analytics deployment, and IT/OT convergence will drive incremental IPC installation in established factories as standalone machines are connected to industrial networks and existing HMI terminals are upgraded to IPC-based platforms capable of supporting IIoT data collection and local AI inference workloads. Third, the emergence of specialized high-value IPC segments will expand total addressable market value beyond commodity machine HMI replacement cycles, supporting sustained market value CAGR above India's broader manufacturing investment growth rate through 2034.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with senior executives from industrial PC manufacturers, industrial automation system integrators, end-user manufacturing enterprises, regulatory compliance specialists, and industry analysts covering India's industrial automation and electronics markets. Discussions validated market size estimates, assessed technology adoption trends, evaluated competitive dynamics, and provided insights into regulatory developments, application requirements, and long-term growth opportunities across India's industrial PC market.
Secondary Research
Secondary research encompassed company financial disclosures, PLI scheme documentation, Ministry of Heavy Industries automotive PLI reports, industrial IoT reports, electronics manufacturing statistics, and credible industrial automation industry analyst publications. These sources supported market sizing, technology trend analysis, competitive positioning assessment, and end-use industry growth forecasting across India's industrial PC market.
Forecasting Models
Forecasting models were developed using historical market revenue data, industrial capex investment trajectories, PLI scheme-approved project timelines, IIoT adoption rate projections, and macroeconomic indicators. Both top-down and bottom-up approaches were applied and validated through primary expert consultations. AI-accelerated IPC adoption rates, domestic assembly program development timelines, pharmaceutical sector digitalization pace, and semiconductor manufacturing ecosystem development trajectories were incorporated to generate reliable forecasts through 2034.
India Industrial PC Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Panel IPC, Rack Mount IPC, Box IPC, Embedded IPC, DIN Rail IPC, Others |
| Display Types Covered | Resistive, Capacitive, Others |
| Sales Channels Covered | Direct Sales, Indirect Sales |
| End Use Industries Covered | Automotive, Healthcare, Chemical, Aerospace and Defense, Semiconductor and Electronics, Energy and Power, Oil and Gas, Others |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Siemens, Advantech Co., Ltd., Beckhoff Automation, Rockwell Automation, Schneider Electric, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India industrial PC market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India industrial PC market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India industrial PC industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Industrial PC Market Report
The India industrial PC market size is estimated at USD 193.8 Million in 2026, driven by growing Industry 4.0 adoption, PLI-linked electronics manufacturing expansion, and increasing IIoT edge computing deployments. Rising demand from pharmaceutical GMP-compliant manufacturing and semiconductor sector automation is further supporting near-term market growth.
The India industrial PC market grows at 3.94% CAGR during 2026-2034, reaching USD 263.9 Million by 2034. The CAGR reflects steady industrial automation investment growth, AI-accelerated IPC adoption, pharmaceutical and semiconductor sector expansion, and growing IIoT edge computing requirements across India's manufacturing ecosystem.
Panel IPC leads at 31.6% (2025), driven by its universal deployment as a machine HMI and process visualization platform across industrial automation applications. Panel IPC's integrated display-computer design, front-panel protection, and operator familiarity make it the default choice for new automation system HMI requirements across manufacturing, pharmaceutical, and energy sectors.
Capacitive display dominates at 56.8% (2025), reflecting superior multi-touch user experience, higher optical clarity, hygienic smooth-surface design for clean-room applications, and compatibility with modern smartphone-style operator interaction. Growing adoption in pharmaceutical, semiconductor, and precision automotive manufacturing is accelerating capacitive displacement of resistive in new IPC installations.
West India leads at 34.2% (2025), anchored by Maharashtra's pharmaceutical manufacturing clusters, Pune automotive industry, Gujarat petrochemical sector, and Maharashtra's diverse food processing and engineering manufacturing base requiring extensive Panel IPC HMI deployments across industrial automation applications.
Leading companies include Siemens, Advantech Co., Ltd., Beckhoff Automation, Rockwell Automation, and Schneider Electric, among others.
The market is projected to reach approximately USD 223.8 Million by 2030, representing the ecosystem at AI-accelerated edge IPC mainstream adoption and IIoT-connected factory architecture widespread deployment. Growth will be anchored by pharmaceutical and semiconductor sector expansion, PLI-linked new manufacturing capacity, and progressive IIoT upgrade investments in existing facilities.
Priority investment opportunities include AI-accelerated edge IPC platforms enabling quality inspection and predictive maintenance at premium pricing, pharmaceutical GMP-compliant IPC specialization with validated computing packages, PLI-linked domestic IPC assembly operations reducing import exposure, and South India semiconductor and EV manufacturing sector market development.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade