
India Non-Poultry Meat Market Size, Share, Trends and Forecast by Product and States, 2026-2034
India Non-Poultry Meat Market Size, Share, Trends & Forecast (2026-2034)
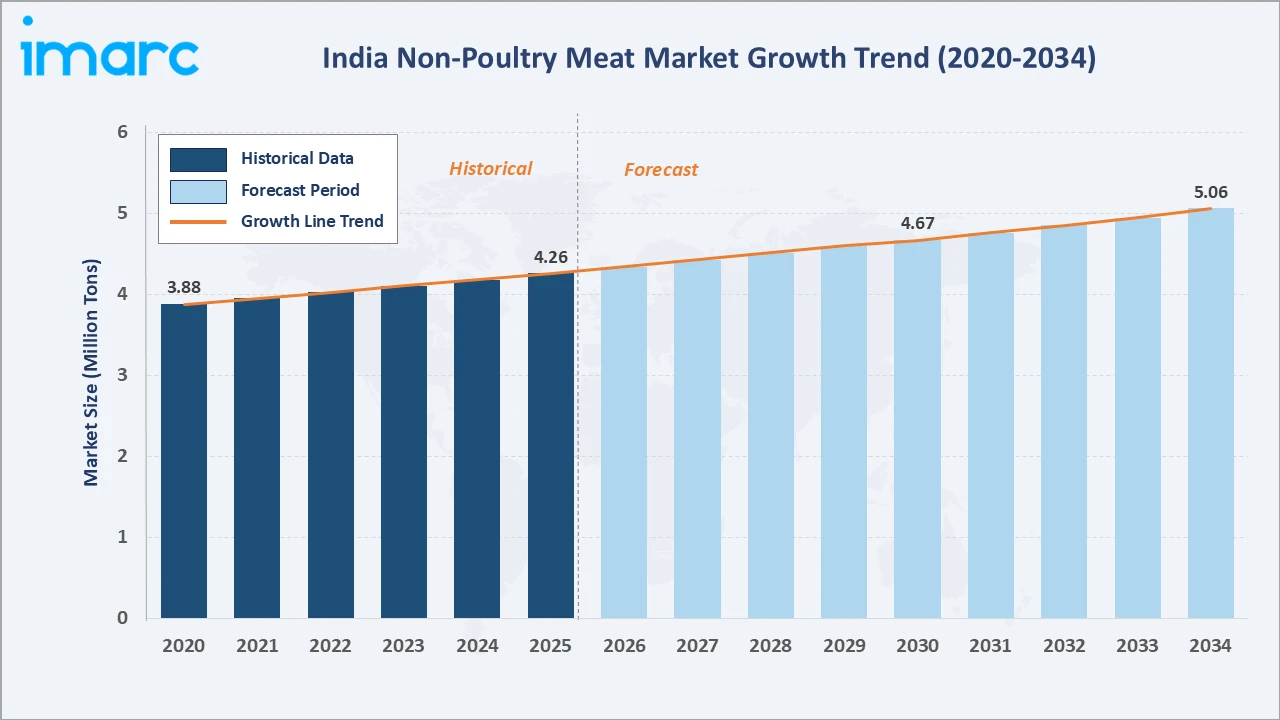
The India non-poultry meat market grew from 4.26 Million Tons in 2025 to 4.34 Million Tons in 2026 and is projected to reach 5.06 Million Tons by 2034, growing at a CAGR of 1.87% during 2026-2034. Buffalo meat exports in India rose 25.6% to $5.1 billion in 2025–26, with exports jumping another 66.6% year-on-year to nearly $1.5 billion in April–June 2026, underscoring the sector's dual role as a domestic protein source and major foreign exchange earner. Beef leads at 34.7% of total volume, while Uttar Pradesh dominates regionally at 18.6% in 2025.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
4.26 Million Tons |
|
Market Size (2026) |
4.34 Million Tons |
|
Forecast Market Size (2034) |
5.06 Million Tons |
|
CAGR (2026-2034) |
1.87% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product Type |
Beef (34.7%, 2025) |
|
Leading State |
Uttar Pradesh (18.6%, 2025) |
The India non-poultry meat market expanded from 3.88 Million Tons in 2020 to 4.26 Million Tons in 2025, and further to 4.34 Million Tons in 2026, reflecting steady demand growth driven by domestic consumption and export channels. The market is projected to reach 4.67 Million Tons by 2030 before reaching 5.06 Million Tons by 2034.
To get more information on this market, Request Sample
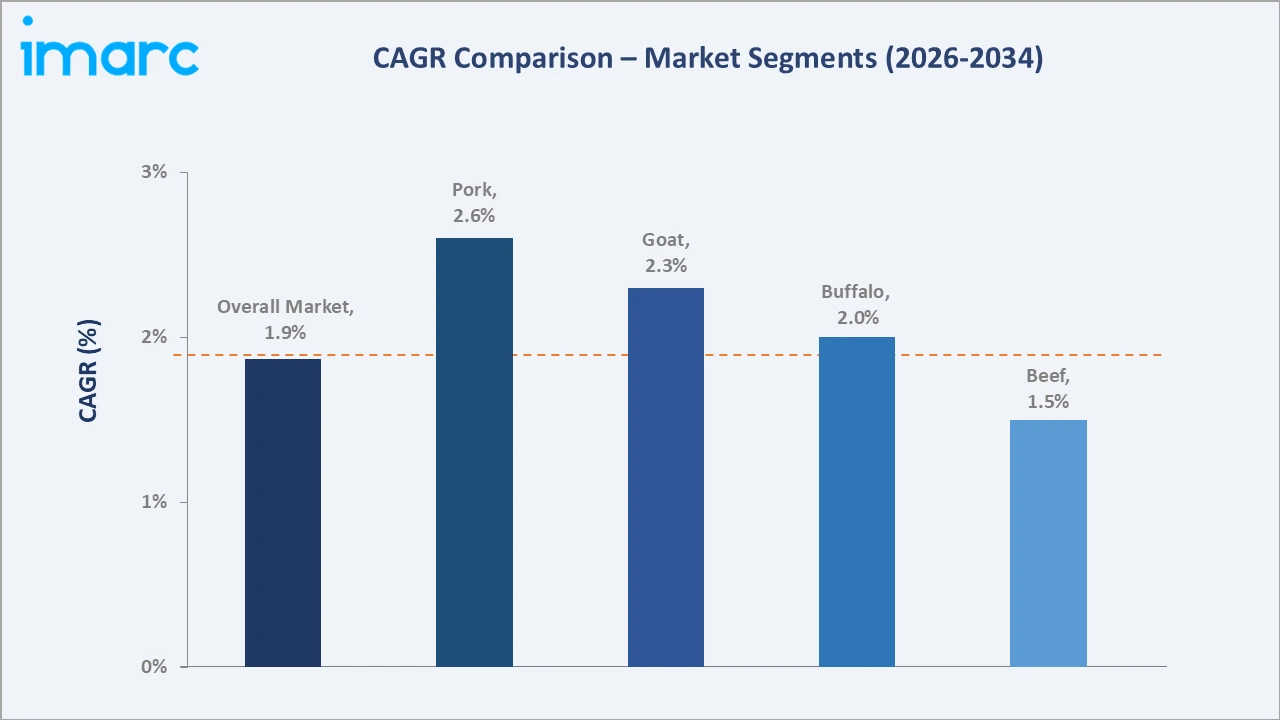
Goat meat grows at 2.3% CAGR, underpinned by premiumization and steady cultural demand across communities. Pork at 2.6% CAGR is the fastest-growing segment from a lower base. Buffalo meat at 2.0% CAGR benefits from consistent export demand.
Executive Summary
The India non-poultry meat market is on a consistent growth trajectory, driven by rising per capita protein consumption, expanding cold chain infrastructure, and growing organized retail penetration. India is one of the largest producers and exporters of buffalo meat, contributing significantly to foreign exchange earnings.
Beef leads at 34.7%, driven by large-scale export-oriented processing. Buffalo meat at 29.8% serves both domestic and export demand, with India accounting for a major share of global buffalo meat trade. Goat meat at 16.6% is the fastest-growing premium segment. Uttar Pradesh leads regionally at 18.6%, supported by the largest livestock population and established abattoir infrastructure in the country.
Key Market Insights
|
Metric |
Value |
|
Dominant Product Type |
Beef – 34.7% share (2025) |
|
Leading State |
Uttar Pradesh – 18.6% (2025) |
|
Key Market Opportunity |
Expanding organized retail, cold chain investments, and rising export demand from the Middle East and Southeast Asia create sustained growth pathways across all non-poultry meat categories. |
Key Analytical Observations Supporting the Above Data:
- Beef at 34.7%: Beef leads the market primarily due to large-scale export-oriented processing. India is among the top three global exporters of beef, with production concentrated in Uttar Pradesh, Maharashtra, and Andhra Pradesh, catering to halal-certified demand in the Middle East and Southeast Asia.
- Uttar Pradesh at 18.6%: Uttar Pradesh leads regional production, housing India's largest cattle and buffalo population. The state accounts for a significant share of both slaughter output and processed meat exports, supported by established abattoir infrastructure and proximity to key northern India markets.
India Non-Poultry Meat Market Overview
The India non-poultry meat market encompasses the production, processing, distribution, and consumption of red meats, including beef, buffalo, goat, pork, and sheep, across domestic and export channels. India's livestock population growth provides the supply base for this market. The industry ecosystem spans livestock farmers, abattoirs, cold chain operators, wholesale distributors, organized retailers, food service establishments, and international export buyers requiring halal-certified processed meat.
Macro drivers include rising disposable incomes in urban centers, demographic growth in protein-consuming age groups, and expansion of modern food retail. The market serves a diverse consumer base from rural households to premium urban food service channels, with export markets representing a structurally significant demand driver for processed buffalo and beef segments.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
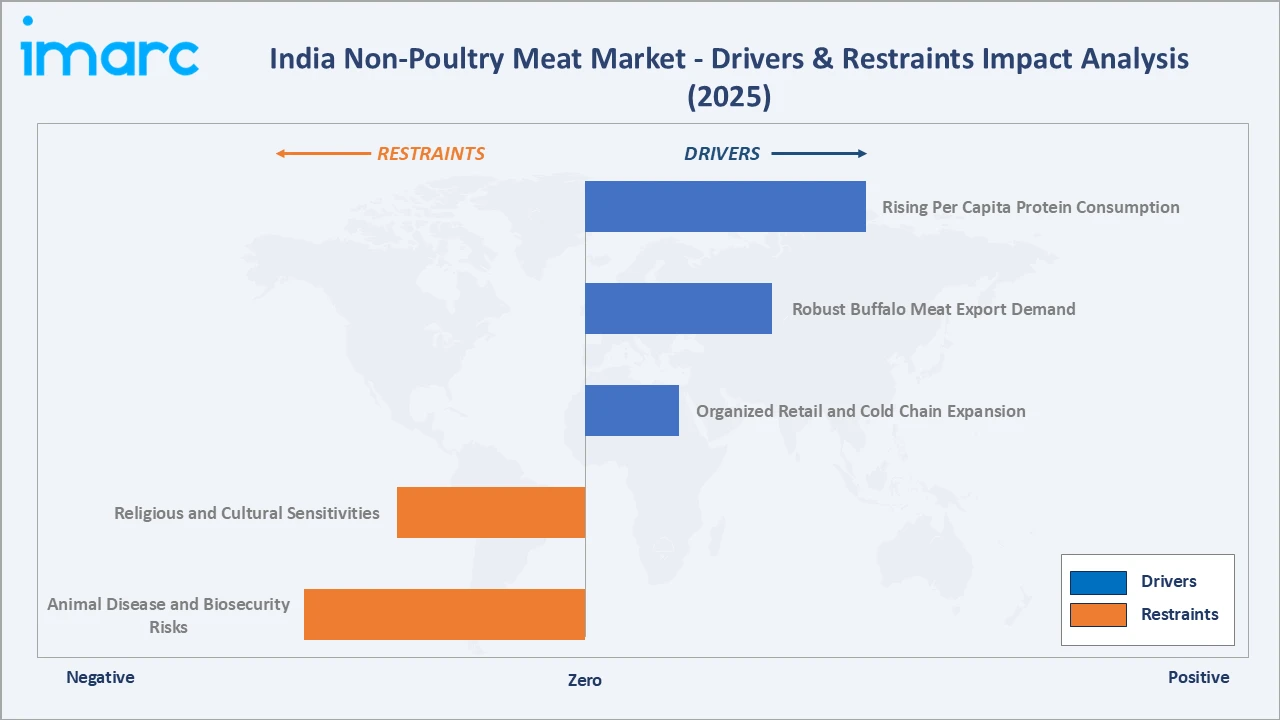
- Rising Per Capita Protein Consumption: India ranks fourth globally in meat production, with output estimated at 10.50 million tons in 2024–25, reflecting a 2.46% increase over 2023–24. Rising incomes and urbanization are structurally increasing protein consumption, supporting long-term volume growth. The urban food service sector and quick service restaurants are key demand expansion channels contributing to sustained domestic market growth.
- Robust Buffalo Meat Export Demand: India exported approximately 1.42 million tons of buffalo meat in FY2025–26, generating export revenue of around US$5.10 billion. Halal certification infrastructure, competitive farm-gate pricing, and established trade relationships with GCC and Southeast Asian buyers provide a durable export competitive position for Indian processors.
- Organized Retail and Cold Chain Expansion: Modern retail formats, organized meat chains, and e-commerce delivery platforms are growing in urban India, improving consumer access to hygienically processed and packaged non-poultry meat. Digital platforms have recorded sustained order volume growth since 2021, accelerating the formalization of urban meat consumption.
Market Restraints
- Religious and Cultural Sensitivities: Consumption of certain red meats is restricted by religious dietary norms for a significant portion of India's population. These cultural sensitivities limit the addressable consumer base for specific categories and create disparities across states.
- Animal Disease and Biosecurity Risks: Periodic outbreaks of foot-and-mouth disease, lumpy skin disease, and other livestock conditions impact cattle and buffalo populations, creating supply disruptions and temporarily affecting export volumes and buyer confidence in India's meat supply chain.
Market Opportunities
- Value-Added and Processed Meat Products: Consumer preference shifts toward ready-to-cook marinated meats, packaged cuts, and processed products. Value-added segments command price premiums over commodity meat, driving processor investment in marination, portioning, and modified atmosphere packaging technologies that improve margins and retail shelf presence.
- E-Commerce Meat Delivery Platforms: Urban meat delivery platforms are achieving double-digit monthly order growth in metropolitan areas, leveraging smartphone adoption and convenience-driven consumption patterns. Digital channels improve product traceability and pricing transparency, supporting market formalization and premium consumer access in high-density urban markets.
Market Challenges
- Fragmented Unorganized Infrastructure: A large proportion of meat supply passes through unregulated local butcheries and informal slaughter points outside quality control frameworks. Formalization requires significant capital investment in modern abattoir infrastructure, cold chain connectivity, and consistent regulatory compliance across fragmented small-scale operators.
- Feed Cost and Price Volatility: Livestock feed costs, particularly maize and soybean meals, are subject to seasonal price fluctuations that compress producer margins and create farm-gate price volatility. Retail price sensitivity in lower-income consumer segments limits the ability to pass on input cost increases, constraining profitability across the value chain.
Emerging Market Trends
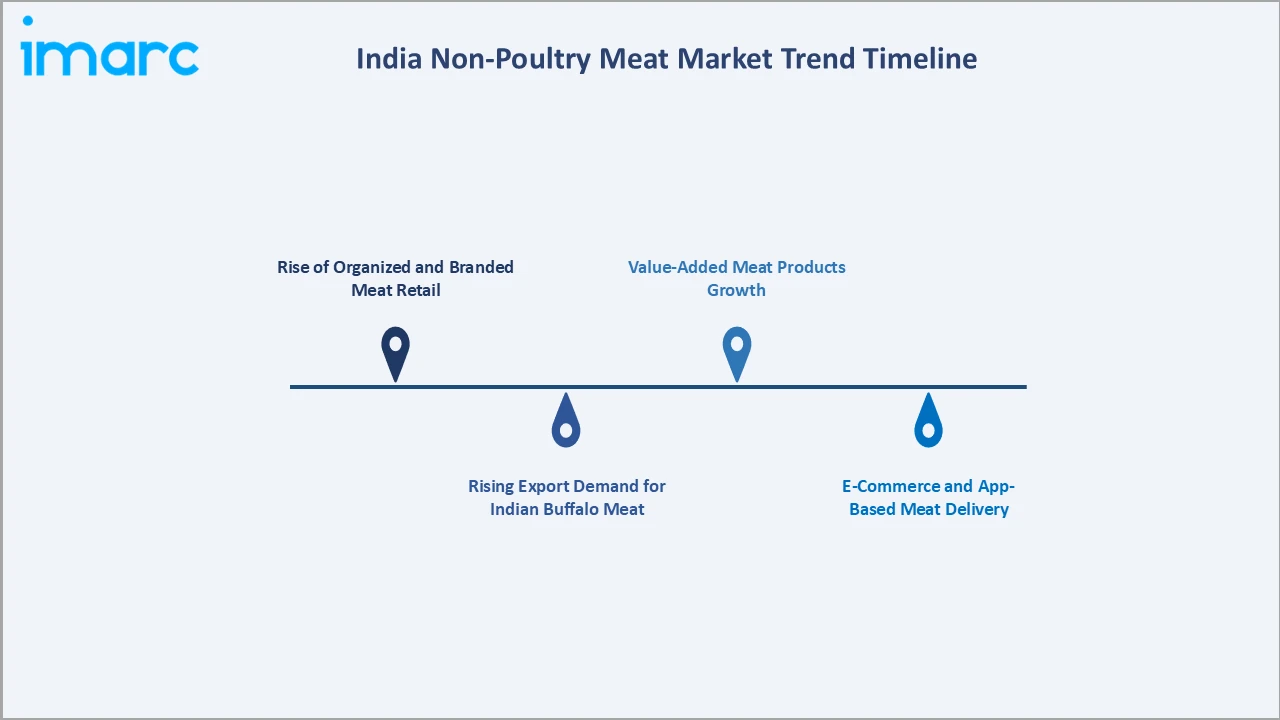
1. Rise of Organized and Branded Meat Retail
Modern organized meat retail chains and branded fresh meat counters are expanding in Tier-1 and Tier-2 cities. Organized retail penetration for fresh meat remained below 15% of total market volume in 2025, indicating large headroom. Brands emphasizing hygiene, traceability, and certified quality are gaining preference over traditional wet markets, particularly among urban consumers.
2. Rising Export Demand for Indian Buffalo Meat
India’s non-poultry meat market is witnessing growing export opportunities, particularly for buffalo meat, driven by rising demand in international markets and other Asian countries. India emerged as the largest supplier of buffalo meat to Uzbekistan, exporting around 33,900 tons in the first half of 2026. During the same period, Uzbekistan imported approximately 72,000 tons of beef in total.
3. Value-Added Meat Products Growth
Consumer demand for ready-to-cook marinated meats, minced products, kebab mixes, and packaged cuts is growing in urban India. Value-added products generate significantly higher revenue per kilogram versus commodity fresh cuts. Processor investment in marination and packaging technologies is expanding this high-margin category across modern retail and e-commerce channels.
4. E-Commerce and App-Based Meat Delivery
Online meat delivery platforms are growing rapidly in metropolitan areas, leveraging improved cold chain logistics and app-based consumer convenience. These platforms are formalizing meat consumption by improving product traceability, standardizing portion sizes, and providing consumers with hygiene-certified products at competitive price points through subscription models.
Industry Value Chain Analysis
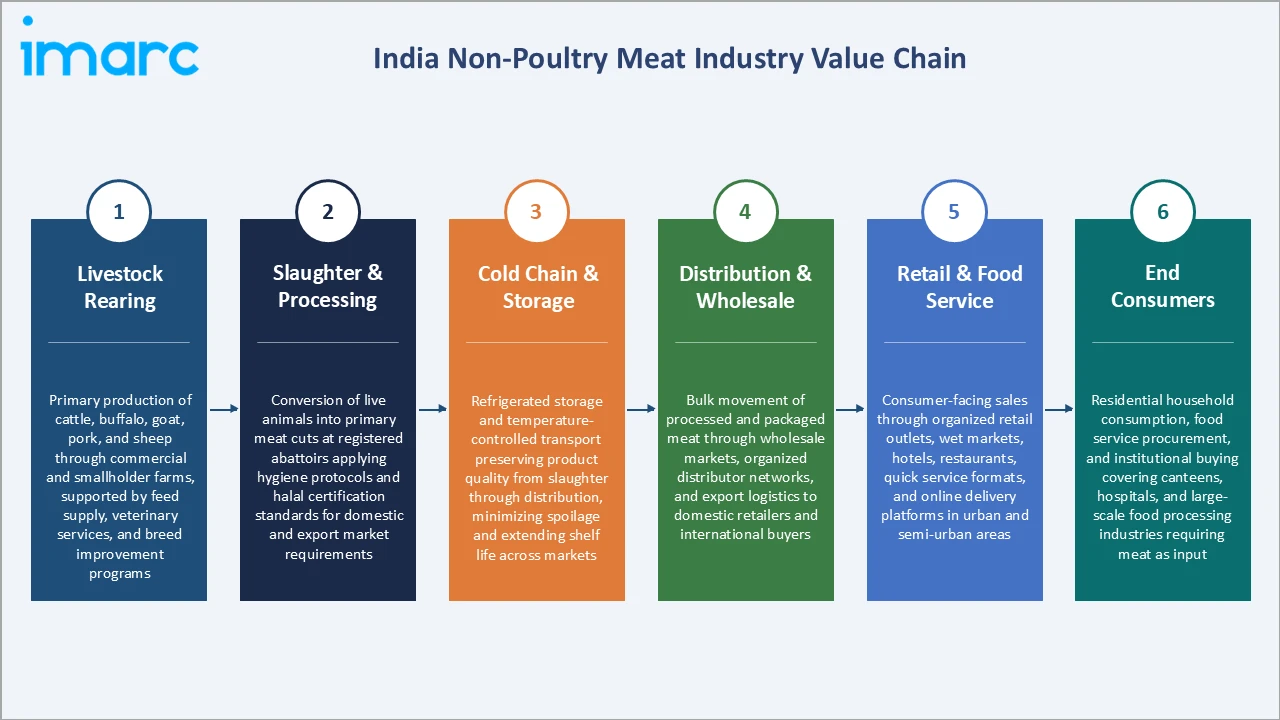
The India non-poultry meat market value chain spans six integrated stages, from primary livestock rearing through consumer delivery. Each stage adds distinct value, with the highest value addition concentrated at the slaughter and processing stage, where hygiene certification, halal compliance, and product differentiation create durable competitive advantages.
| Stage | Key Activities & Value Addition |
|---|---|
| Livestock Rearing | Primary production of cattle, buffalo, goat, pork, and sheep through commercial and smallholder farms, supported by feed supply, veterinary services, and breed improvement programs. |
| Slaughter & Processing | Conversion of live animals into primary meat cuts at registered abattoirs applying hygiene protocols and halal certification standards for domestic and export market requirements. |
| Cold Chain & Storage | Refrigerated storage and temperature-controlled transport preserving product quality from slaughter through distribution, minimizing spoilage and extending shelf life across markets. |
| Distribution & Wholesale | Bulk movement of processed and packaged meat through wholesale markets, organized distributor networks, and export logistics to domestic retailers and international buyers. |
| Retail & Food Service | Consumer-facing sales through organized retail outlets, wet markets, hotels, restaurants, quick service formats, and online delivery platforms in urban and semi-urban areas. |
| End Consumers | Residential household consumption, food service procurement, and institutional buying covering canteens, hospitals, and large-scale food processing industries requiring meat as input. |
The slaughter and processing stage holds the greatest strategic significance, as modern abattoir infrastructure, halal certification, and cold-processing technology determine product quality and export eligibility. The distribution and retail stage is progressively formalizing, with organized players and digital platforms gaining share from traditional wet market channels.
Technology Landscape in the India Non-Poultry Meat Industry
Modern Abattoir and Processing Technology
Mechanized slaughter lines, automated carcass handling systems, and integrated inspection technologies are replacing manual processing in larger abattoirs. These systems improve throughput, reduce contamination risk, and standardize product quality, enabling consistent supply for organized retail and export buyers with stringent hygiene and certification requirements.
Cold Chain and Refrigeration Technology
Advanced refrigeration systems, blast freezing units, and GPS-tracked refrigerated transport are improving cold chain coverage from abattoir through last-mile delivery. Modified atmosphere packaging extends fresh meat shelf life, improving distribution reach and reducing retail wastage, critical for organized retail viability in a warm-climate market.
Traceability and Quality Certification Systems
Blockchain-based meat traceability platforms and RFID-enabled livestock tracking are being adopted by export-oriented processors to meet international buyer requirements for origin certification. End-to-end supply chain visibility from livestock farm through consumer delivery supports premium pricing and access to quality-sensitive export markets.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Product Type | Beef | 34.7% | 2025 |
| States | Uttar Pradesh | 18.6% | 2025 |

By Product
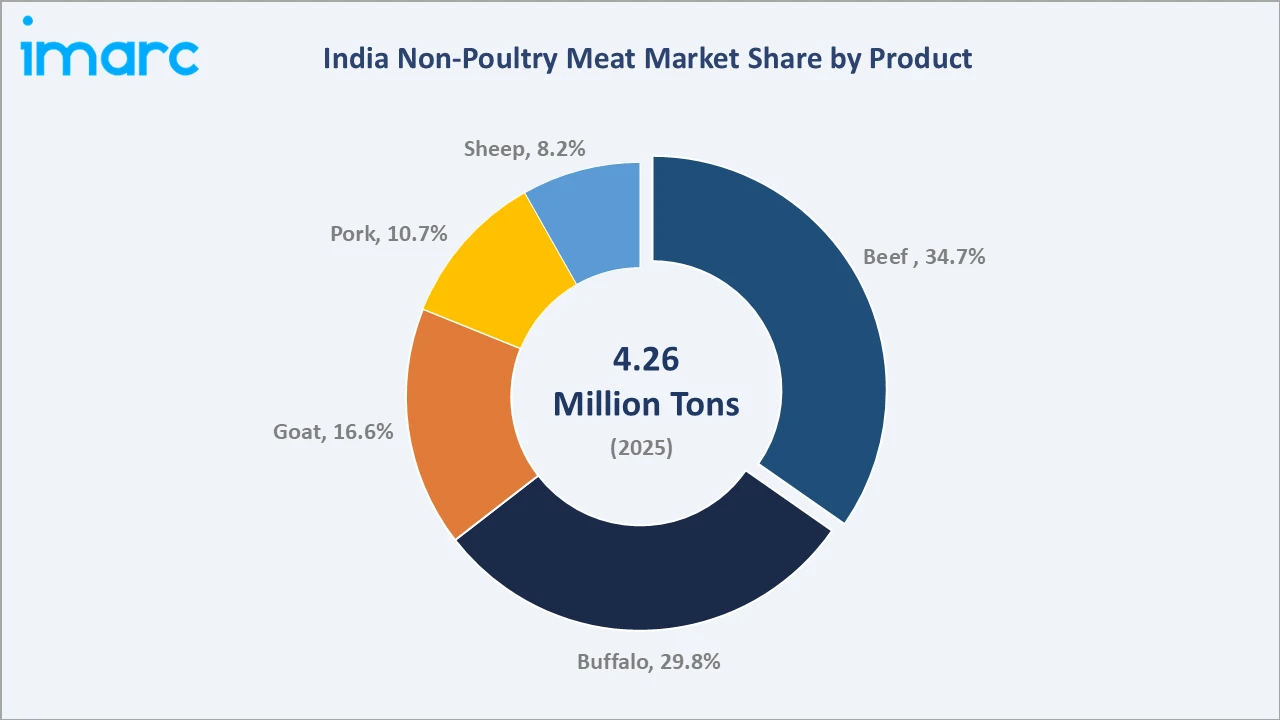
Beef leads with a 34.7% share in 2025, driven primarily by large-scale export-oriented processing operations. Export demand continues to sustain high production volumes in this segment. Buffalo meat at 29.8% serves both domestic and export channels. Domestically, it is widely consumed in northern, eastern, and western India as an affordable and protein-rich option.
To access detailed market analysis, Request Sample
Goat meat at 16.6% is experiencing the fastest per-segment volume growth, driven by its premium positioning, year-round demand, and high acceptance across all religious communities. Pork at 10.7% is concentrated in northeastern states, Goa, and Kerala, where cultural acceptance is high. Sheep at 8.2% command the highest retail price among non-poultry meats, concentrated in festival-season demand peaks.
Regional Market Insights
|
State |
Share (2025) |
Key Demand Drivers & Characteristics |
|
Uttar Pradesh |
18.6% |
Largest livestock population base; dominant buffalo meat production and processing hub, strong rural and urban domestic demand across all non-poultry meat categories. |
|
Maharashtra |
10.8% |
Large urban consumer base in metropolitan areas; active buffalo and goat meat consumption, growing organized retail and food service penetration. |
|
Telangana |
9.7% |
High per capita meat consumption, strong goat and beef demand from local cultural communities, growing food service sector activity in urban areas. |
|
West Bengal |
8.9% |
Buffalo and goat meat are dietary staples, organized retail expansion and strong food service demand supporting volume growth. |
|
Andhra Pradesh |
8.1% |
Export-oriented buffalo meat processing activity, high domestic goat and sheep meat demand, particularly during festive seasons. |
|
Bihar |
7.3% |
Growing livestock production base, buffalo and goat meat consumption driven by large rural population and rising peri-urban demand. |
|
Kerala |
6.8% |
One of the highest per capita meat-consuming states, beef and buffalo widely consumed, strong organized retail presence in urban markets. |
|
Tamil Nadu |
5.9% |
Significant domestic beef and goat meat demand; growing modern retail and food service channels expanding organized market presence. |
|
Karnataka |
5.4% |
Diversified meat consumption, sheep and goat meat demand supported by urban food service and retail growth across major cities. |
|
Rajasthan |
4.7% |
Sheep and goat meat dominate consumption, strong festive season demand, growing peri-urban markets supporting incremental volume growth. |
|
Madhya Pradesh |
3.8% |
Large livestock population, goat and buffalo meat consumption distributed across semi-urban and rural markets with growing organized sector presence. |
|
Punjab |
2.9% |
Buffalo and goat meat consumption primarily in urban and semi-urban areas, organized retail penetration growing, supporting quality-certified product demand. |
|
Gujarat |
2.4% |
Buffalo meat production active, export-linked processing activity, domestic demand concentrated in specific communities and urban food service channels. |
|
Haryana |
2.4% |
Buffalo and goat meat consumption driven by urban demand and proximity to NCR markets, established livestock base supporting local production. |
|
Orissa |
2.3% |
Growing domestic meat demand across rural and urban consumers, buffalo and goat meat are primary categories supported by local livestock production. |
Uttar Pradesh at 18.6% dominates regional contribution, anchored by India's largest cattle and buffalo herd base and well-established abattoir and export processing infrastructure. Maharashtra at 10.8% reflects strong urban consumption in Mumbai and Pune, supported by diverse community demand and growing organized meat retail channels.
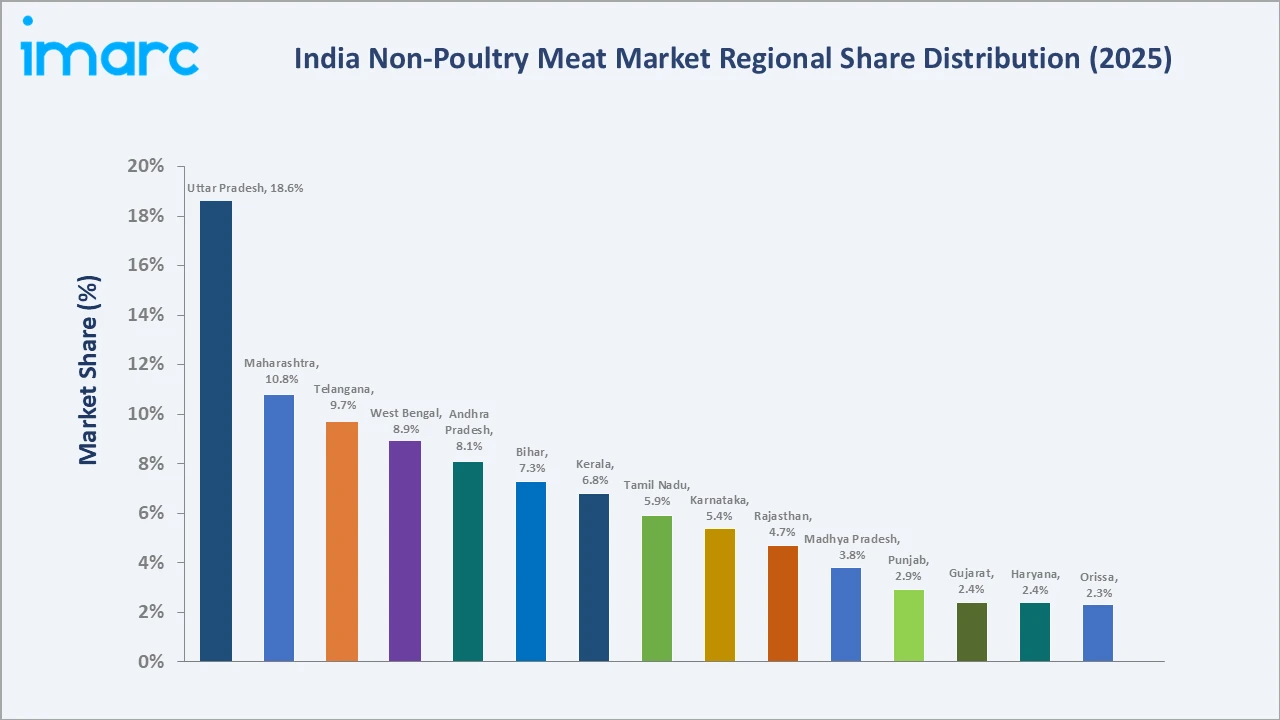
Telangana at 9.7% benefits from high per capita consumption and a vibrant food service sector, while West Bengal at 8.9% is anchored by buffalo and goat meat as daily dietary staples. Andhra Pradesh, at 8.1%, serves both domestic and export-linked buffalo processing demand. Bihar at 7.3% is supported by a large rural population and a growing livestock base.
Kerala at 6.8% has beef and buffalo forming a core part of the daily diet and strong urban retail penetration. Tamil Nadu at 5.9% and Karnataka at 5.4% show diversified demand across goat, sheep, and buffalo categories, driven by urban food service growth and organized retail expansion. Rajasthan at 4.7% is a key sheep and goat meat market with strong festive season demand peaks. Madhya Pradesh at 3.8% and Punjab at 2.9% reflect growing semi-urban and urban meat demand. Gujarat at 2.4%, Haryana at 2.4%, and Orissa at 2.3% represent emerging state-level markets where incrementally organized sector growth and rising incomes are progressively expanding consumption volumes.
Competitive Landscape
The India non-poultry meat market is highly fragmented, combining a small number of large export-oriented processors with most of the regional operators and an unorganized domestic sector.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| Al-Marzia Agro Foods | Buffalo Meat Cuts, Goat Meat Cuts | Market Leader | Al-Marzia Agro Foods is a key player and exporter in India's non-poultry meat sector, specializing in Halal-certified frozen buffalo meat and beef/mutton processing. |
| ALM Industries Ltd. | Premium Buffalo Cuts, Premium Goat Cuts | Established Player | ALM Industries Ltd. is a prominent export-oriented food processing enterprise in India specializing in the processing and export of non-poultry meats. |
| Al-Hamd Agro Food Products Pvt. Ltd. | Buffalo Meat | Challenger | Al-Hamd Agro Food Products Pvt. Ltd. is one of India's leading private exporters and processors of Halal fresh and frozen buffalo meat. |
| AOV Agro Foods Pvt. Ltd. | Goat and Lamb Products | Innovator | AOV Agro Foods Pvt. Ltd. plays a major role in India’s non-poultry meat industry through integrated slaughter, processing, and global distribution standards. |
| Mayur Piggery Farm | Raw Pork, Pork Offals | Niche Player | Mayur Piggery Farm operates as a vertically integrated commercial producer of raw and processed pork. |
The competitive landscape is bifurcated between large export-oriented processors with integrated cold chain and halal certification infrastructure, and regional domestic operators serving local demand. Export leaders benefit from economies of scale and established international buyer relationships that create durable competitive advantages difficult for smaller players to replicate.
Key Company Profiles
Al-Marzia Agro Foods
Al Marzia Agro Foods is one of the major players in India's non-poultry meat export sector, specializing in halal-certified buffalo and goat products. The company serves international markets with a focus on quality consistency and supply reliability. Its distribution network covers key import markets including GCC countries and Southeast Asia.
- Key Offerings: Buffalo Meat Cuts, Goat Meat Cuts.
- Strategic Focus: Expanding halal-certified export product range, strengthening Middle East and Southeast Asia buyer relationships, and improving supply chain efficiency and export logistics operations.
ALM Industries Ltd.
ALM Industries Ltd. is a meat processing and export company with significant operations in the buffalo meat segment. The company maintains large-scale processing infrastructure aligned with export quality requirements and serves both export markets and domestic wholesale distribution channels.
- Key Offerings: Premium Buffalo Cuts, Premium Goat Cuts.
- Strategic Focus: Maintaining export quality standards, expanding international market penetration, and strengthening domestic distribution network to capture growing urban and semi-urban demand.
Market Concentration Analysis
The India non-poultry meat market exhibits low to moderate concentration at the organized sector level. The organized processing segment is led by a small number of large export-oriented companies that collectively account for the majority of formal sector output and virtually all of India's non-poultry meat export volumes. Consolidation in the organized segment has been driven by the need for scale, cold chain investment, and halal certification infrastructure to effectively serve quality-sensitive export buyers and urban domestic organized retail channels.
The broader market, encompassing the unorganized sector, remains highly fragmented, with thousands of local butchers, small slaughter operations, and regional wholesale traders accounting for the majority of domestic consumption volumes. This fragmentation creates ongoing opportunities for organized operators to capture market share by offering hygiene assurance, consistent quality, and modern retail distribution channels that align with the growing urban consumer preference for branded and certified meat products.
Investment & Growth Opportunities
Highest Growth Segments
Goat meat at approximately 2.3% CAGR is the highest-growth segment, driven by premium positioning and consistent festival and food service demand. Pork at approximately 2.6% CAGR is growing fastest from a lower base in high-consumption states. Value-added and packaged meat products offer the highest margin expansion potential across all categories, with premiums of 30-40% over commodity cuts.
Investment Themes
- Modern Abattoir and Cold Chain Infrastructure: Investment in integrated modern abattoir complexes and refrigerated logistics addresses the critical infrastructure gap that limits organized sector growth. Such investments improve product quality, enable export eligibility, and are aligned with government food processing sector incentive programs that reduce the effective capital cost for qualified operators.
- Value-Added Meat Processing: Consumer-facing value-added categories including marinated cuts, packaged minced meat, and ready-to-cook products command 30-40% price premiums over commodity fresh cuts. Investment in processing, marination, and modified atmosphere packaging technology serves growing urban consumer demand for convenience and hygiene-certified products.
- E-Commerce and Digital Distribution: Urban meat delivery platforms represent a high-growth investment theme, with digital channels growing faster than organized retail in Tier-1 cities. Investment in cold chain-optimized last-mile logistics and consumer-facing apps enables market formalization and premium urban consumer demand capture with superior margin profiles versus commodity distribution.
Future Market Outlook (2026-2034)
The India non-poultry meat market grew from 4.26 Million Tons in 2025 to 4.34 Million Tons in 2026, reaching 5.06 Million Tons by 2034, exhibiting a CAGR of 1.87% during 2026-2034. The market is projected to reach an intermediate milestone of 4.67 Million Tons by 2030, as domestic consumption growth and organized retail expansion cumulatively drive volume gains across all segments.
Three structural forces will define India's non-poultry meat market through 2034. First, rising protein consumption driven by income growth and urbanization will provide consistent domestic demand expansion. Second, export demand from the Middle East and Southeast Asia will sustain large-scale buffalo and beef processing, supported by India's large livestock population and cost competitiveness. Third, market formalization through organized retail, cold chain investment, and e-commerce growth will progressively shift value toward branded and hygiene-certified products through 2034.
Research Methodology
Primary Research
Primary research comprised structured consultations with non-poultry meat processing company executives, livestock traders, abattoir operators, organized retail procurement managers, and export market specialists. These discussions validated market sizing estimates, regional production dynamics, competitive positioning, and regulatory influences across India's meat ecosystem.
Secondary Research
Secondary research drew on published government data, including the Ministry of Agriculture livestock census, export statistics, National Livestock Mission reports, and Food Safety and Standards Authority guidelines. Company annual reports, export certification databases, and trade publications covering India's meat and food processing sector were cross-referenced with primary findings.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling incorporating historical livestock production trends, per capita consumption growth projections, export volume trajectories, organized retail penetration models, and government policy continuity assumptions. Historical data spanning 2020 through 2025 was validated across primary and secondary sources prior to forecast model application.
Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million Tons |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Products Covered | Beef, Buffalo, Goat, Sheep, Pork |
| States Covered | Uttar Pradesh, Telangana, Maharashtra, West Bengal, Andhra Pradesh, Bihar, Kerala, Rajasthan, Tamil Nadu, Karnataka, Punjab, Orissa, Madhya Pradesh, Haryana, Gujrat |
| Companies Covered | Al-Marzia Agro Foods, ALM Industries Ltd., Al-Hamd Agro Food Products Pvt. Ltd., AOV Agro Foods Pvt. Ltd., Mayur Piggery Farm, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Frequently Asked Questions About the India Non-Poultry Meat Market Report
The India non-poultry meat market reached 4.34 Million Tons in 2026, driven by domestic protein demand, buffalo meat exports, and expanding organized retail distribution.
The market is projected to grow at a CAGR of 1.87% during 2026-2034, supported by domestic consumption growth, cold chain expansion, and sustained export demand.
The market is projected to reach 5.06 Million Tons by 2034, driven by rising protein consumption, organized retail growth, and growing export volumes from India.
Beef leads with a 34.7% share in 2025, driven by large-scale export-oriented processing and India's position as a top global beef exporter.
Uttar Pradesh leads with an 18.6% share in 2025, supported by India's largest livestock population and established meat processing and export infrastructure.
The market is projected to reach approximately 4.67 Million Tons by 2030, reflecting steady domestic demand and export volume growth across non-poultry meat segments.
Key players include Al-Marzia Agro Foods, ALM Industries Ltd., Al-Hamd Agro Food Products Pvt. Ltd., AOV Agro Foods Pvt. Ltd., and Mayur Piggery Farm, among others.
Key opportunities include modern abattoir infrastructure, cold chain investment, value-added meat processing, and e-commerce meat delivery platform development across urban India.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade