
India Payroll Outsourcing Market Size, Share, Trends and Forecast by Type, Application, End Use Industry, and Region, 2026-2034
India Payroll Outsourcing Market Size, Share, Trends & Forecast (2026-2034)
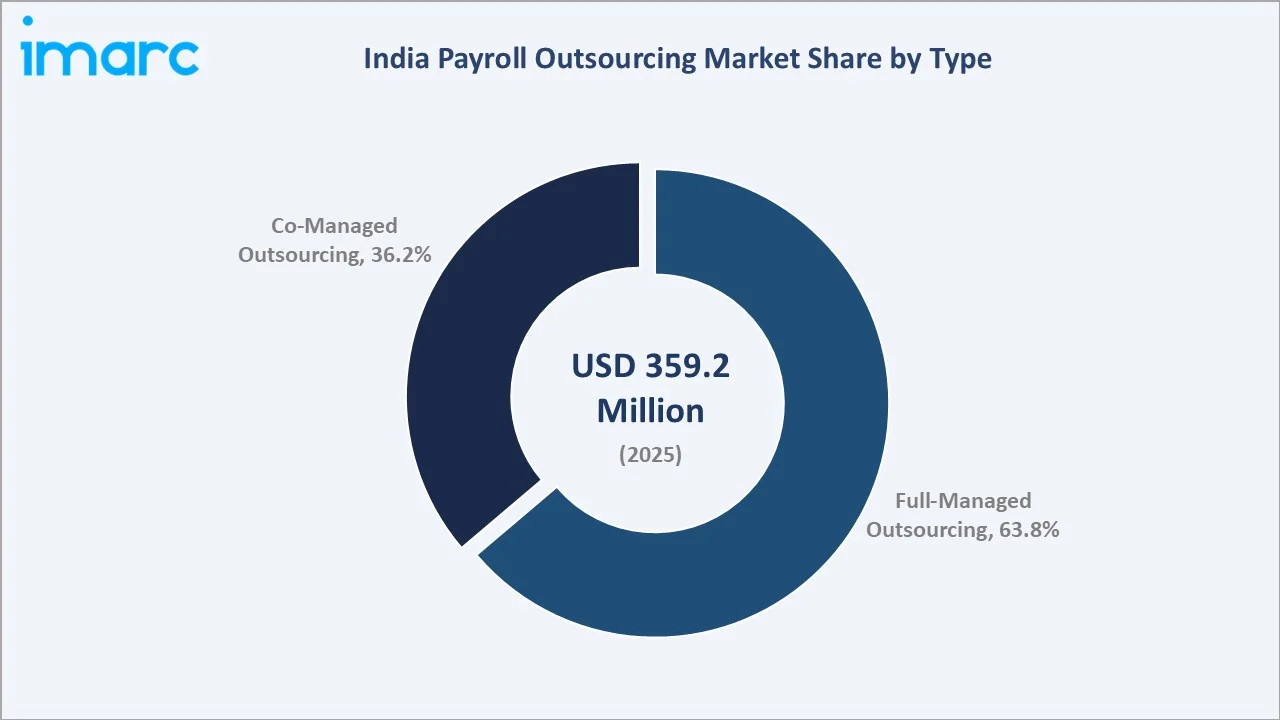
The India payroll outsourcing market grew from USD 359.2 Million in 2025 to USD 379.7 Million in 2026 and is projected to reach USD 592.1 Million by 2034, growing at a CAGR of 5.71% during 2026-2034. India's four new labor codes consolidating 29 central labor laws are creating significant compliance complexity that is driving organizations of all sizes to outsource payroll processing. Full-managed outsourcing dominates at 63.8% by type, large business leads at 47.6% by application, and West India commands the largest regional share at 31.2%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 359.2 Million |
|
Market Size (2026) |
USD 379.7 Million |
|
Forecast Market Size (2034) |
USD 592.1 Million |
|
CAGR (2026-2034) |
5.71% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Full-Managed Outsourcing (63.8%, 2025) |
|
Dominant Application |
Large Business (47.6%, 2025) |
|
Leading Region |
West India (31.2%, 2025) |
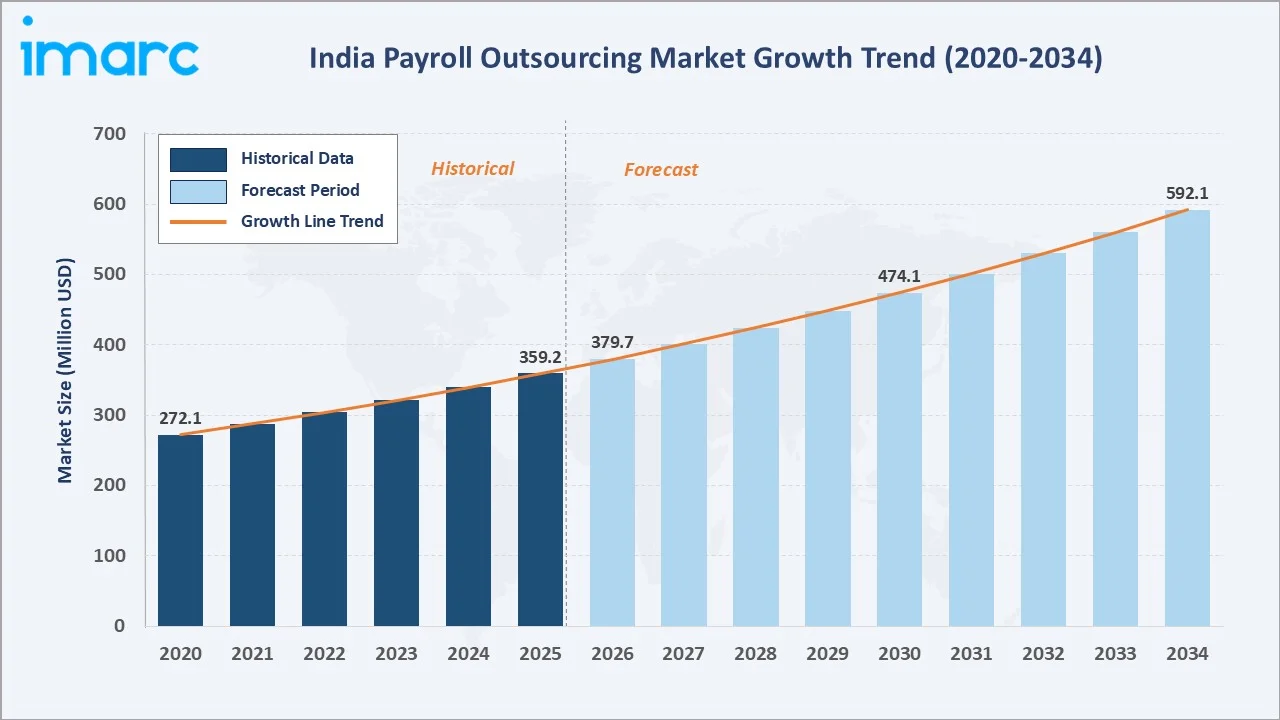
The India payroll outsourcing market grew from USD 272.1 Million in 2020 to USD 359.2 Million by 2025 and is estimated to reach USD 379.7 Million in 2026. The market is projected to reach USD 474.1 Million by 2030 and USD 592.1 Million by 2034.
To get more information on this market, Request Sample
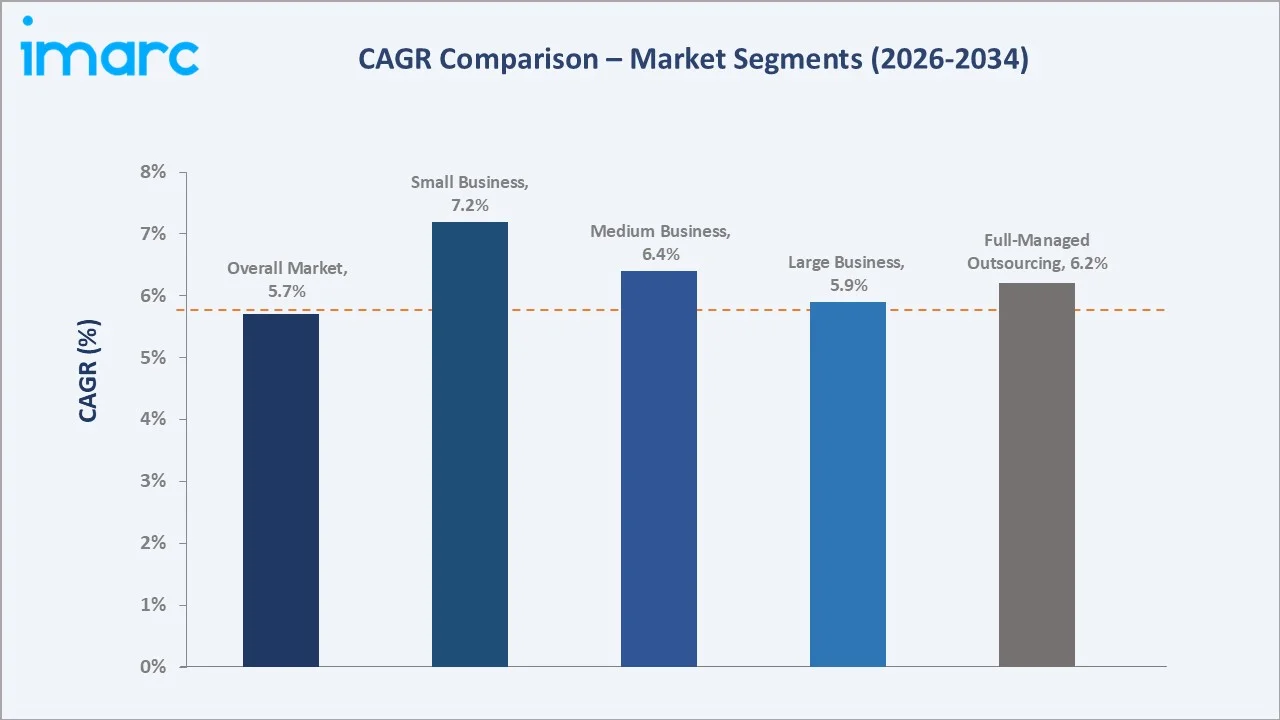
Full-managed outsourcing grows at ~6.2% CAGR as organizations seek complete payroll lifecycle management. Small business segment grows fastest at ~7.2% CAGR through MSME formalization under the labor code. Large business grows at ~5.9% CAGR through complex multi-state compliance requirements.
Executive Summary
The India payroll outsourcing market is growing steadily, driven by accelerating regulatory complexity, digital transformation of HR functions, and the formalization of India's vast unorganized workforce under GST and labor code reforms. The market is sustained by enterprise demand for compliance-managed full-service payroll, rapid MSME cloud payroll adoption, and multinational corporations centralizing India payroll through global outsourcing partnerships.
Full-managed outsourcing commands 63.8% as organizations prefer end-to-end payroll accountability with zero in-house processing. Large business leads at 47.6% through complex multi-entity, multi-state payroll requirements. West India holds 31.2%, anchored by the BFSI sector and IT and manufacturing corridors requiring sophisticated statutory compliance management.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Full-Managed Outsourcing - 63.8% share (2025) |
|
Dominant Application |
Large Business - 47.6% share (2025) |
|
Leading Region |
West India - 31.2% (2025) |
|
Key Market Opportunity |
India's MSMEs increasingly formalizing payroll under GST and labor code requirements represent an incremental market opportunity by 2030 for cloud-based payroll outsourcing providers. |
Key Analytical Observations Supporting the Above Data:
- Full-Managed Outsourcing at 63.8%: Organizations increasingly prefer full-managed outsourcing where the service provider assumes complete responsibility for payroll processing, statutory compliance, tax filings, and salary disbursement. India's complex compliance landscape makes in-house management resource-intensive, strongly favoring fully managed models.
- Large Business at 47.6%: Large enterprises generate the highest payroll outsourcing revenue per client through complex requirements spanning multi-location payroll, senior executive variable pay, and multi-country payroll for Indian MNCs. BFSI and IT sectors, the two largest organized sector employers with the most complex payroll structures, dominate large business demand.
- West India at 31.2%: Mumbai concentrates India's BFSI headquarters, manufacturing conglomerates, and media sector requiring complex payroll including variable pay and perquisite valuation.
India Payroll Outsourcing Market Overview
The India payroll outsourcing market encompasses third-party management of employee payroll processing, statutory compliance filings, salary disbursement, tax computation, and HR reporting services delivered to organizations across small, medium, and large business segments. India's payroll compliance environment is among the most complex. The implementation of four labor codes is adding further structural complexity, making specialist payroll outsourcing economically rational for organizations across all size segments.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
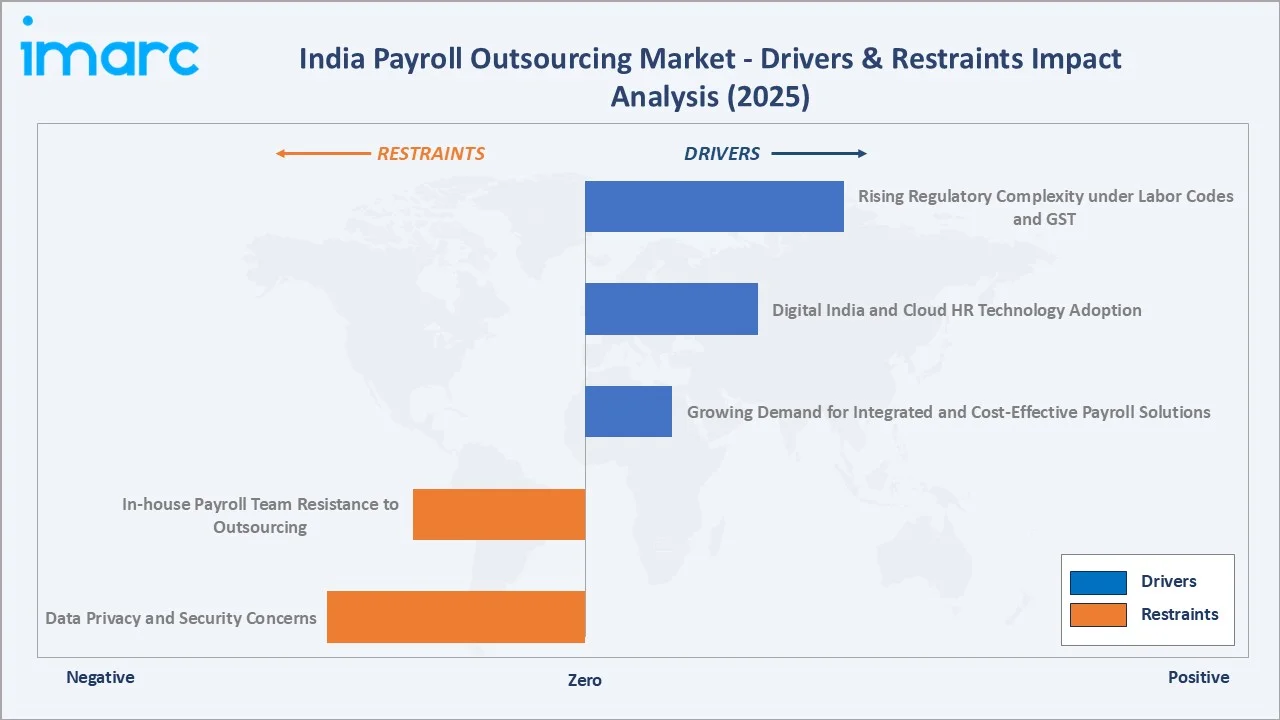
- Rising Regulatory Complexity under Labor Codes and GST: India's four new labor codes, consolidating 29 central labor laws, are materially changing PF wage definitions, leave encashment calculations, gratuity eligibility, and variable pay compliance. Organizations lacking internal regulatory tracking capabilities are increasingly turning to specialist payroll providers to ensure compliance, avoid penalties, and manage continuous statutory update cycles. EPFO's digital filing systems and ESIC's online claim settlement require technology-integrated payroll that most SMEs cannot maintain in-house.
- Digital India and Cloud HR Technology Adoption: India's cloud HR and payroll SaaS adoption growth, with platforms like Keka HR, greytHR, and PeopleStrong enabling affordable payroll outsourcing. The government's Digital India push, improving internet penetration in Tier-2 and Tier-3 cities, is expanding the addressable market for cloud-based payroll outsourcing beyond metro areas.
- Growing Demand for Integrated and Cost-Effective Payroll Solutions: The expansion of small and growing businesses in India is increasing demand for streamlined payroll and HR management solutions that reduce administrative complexity and operating costs. In August 2026, MedleyHR launched a self-service HR and payroll platform tailored to India’s small and growing businesses seeking an alternative to spreadsheets and complex enterprise solutions. The integrated platform combines payroll, attendance, leave management, employee records, performance tracking, document management, HR workflows, and employee self-service capabilities.
Market Restraints
- Data Privacy and Security Concerns: Payroll data contains India's most sensitive employee personal information such as Aadhaar, PAN, bank account numbers, salary details, and health insurance data. Regulatory implementation is raising the compliance bar for payroll outsourcing providers, creating data residency and processing consent requirements that are increasing service delivery complexity and limiting adoption among data-sensitive sectors like BFSI and healthcare.
- In-house Payroll Team Resistance to Outsourcing: Established large enterprises with dedicated in-house payroll teams of 5-20 professionals face internal resistance to outsourcing driven by concerns about job displacement, loss of data control, and service quality uncertainty. Organizational change management requirements and transition costs create inertia that slows outsourcing adoption in the large enterprise segment.
Market Opportunities
- Increasing Adoption of AI-Enabled Payroll Automation: The growing integration of AI into payroll operations is driving demand for outsourced and managed payroll services by improving process efficiency, accuracy, and scalability. In August 2026, Kredily introduced Kredily 3.0, an upgraded AI-first HRMS and payroll platform featuring KAI, an agentic AI solution that automates payroll and HR workflows through natural-language commands. The company has also expanded its offerings with the launch of AI-enabled managed payroll services.
- Payroll Analytics and Workforce Cost Intelligence: Advanced payroll outsourcing providers are offering salary benchmarking, workforce cost ratio analytics, and predictive headcount cost modeling as value-added services above basic payroll processing. These analytics services command premium pricing above base payroll fees, significantly improving revenue per client and creating competitive differentiation.
Market Challenges
- High Client Customization Requirements and Fragmented Compliance: India's states have differing professional tax slabs, Shop & Establishment Act provisions, and local levies that require payroll software customization at the state level. Service providers must maintain active compliance databases for regulatory jurisdictions simultaneously, creating significant ongoing investment requirements that disadvantage smaller payroll outsourcing operators.
- Price Sensitivity in SME Segment Limiting Revenue Growth: India's MSME segment is also the most price-sensitive. This creates a structural challenge where the fastest-growing customer segment generates the lowest revenue per employee, requiring high volume and automation-first delivery models to achieve profitability.
Emerging Market Trends
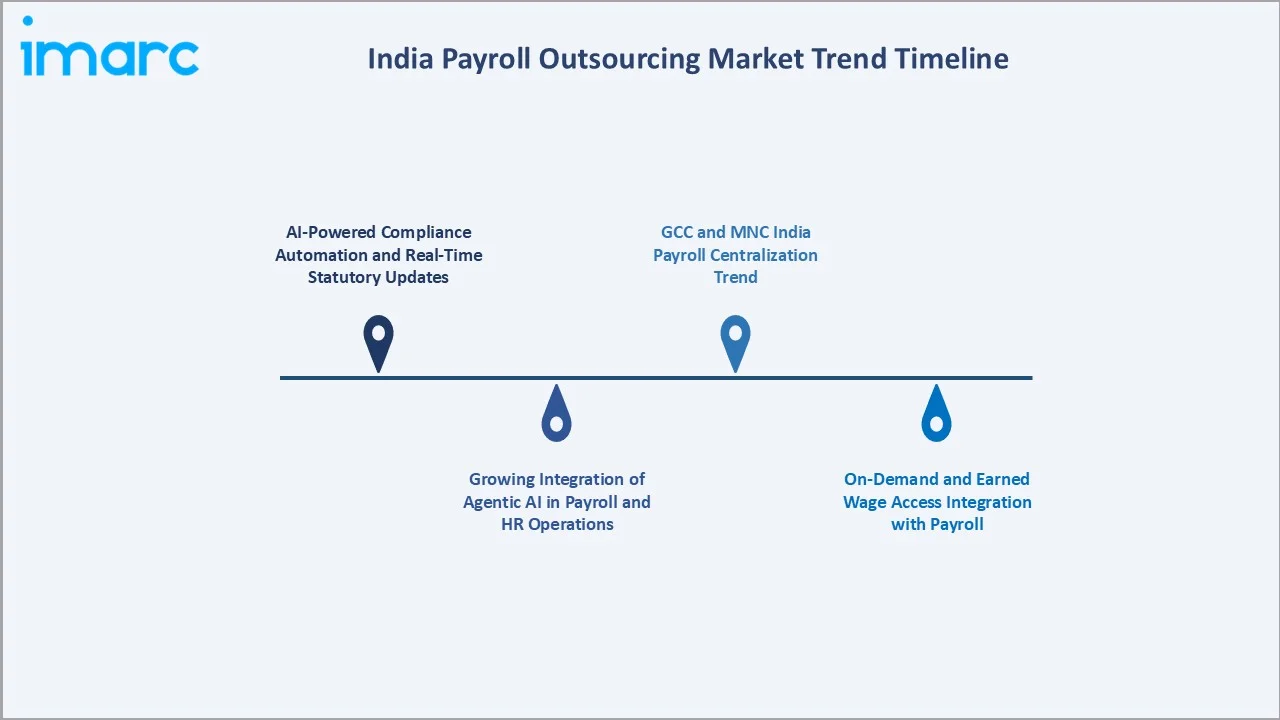
1. AI-Powered Compliance Automation and Real-Time Statutory Updates
India's payroll outsourcing platforms are deploying AI and machine learning to automate statutory compliance updates, instantly reflecting changes in PF wage definitions, TDS slabs, ESIC contribution rates, and state-level Professional Tax revisions into payroll calculations. Keka HR's AI-based compliance engine and greytHR's statutory updates both reduce manual compliance monitoring effort, enabling providers to scale SME payroll volumes without proportional compliance team growth.
2. Growing Integration of Agentic AI in Payroll and HR Operations
The India payroll outsourcing market is witnessing increased adoption of agentic AI to automate routine workflows, generate workforce insights, and simplify complex HR processes. In June 2026, greytHR launched NAVOS, an agentic AI assistant integrated directly into its HRMS platform to streamline and automate HR operations. The solution enables users to execute HR tasks, access workforce insights, and manage complex processes more efficiently through an intuitive AI-driven interface.
3. GCC and MNC India Payroll Centralization Trend
India hosts 1,700+ Global Capability Centers (GCCs), projected to reach 2,400 centers by 2030 are driving demand for enterprise-grade payroll outsourcing with global parent integration capabilities, connecting India payroll to various platforms used by MNC headquarters. Many major companies are expanding their India GCC payroll capabilities to serve this segment, offering seamless global-to-local payroll data flows with real-time India statutory compliance assurance.
4. On-Demand and Earned Wage Access Integration with Payroll
India's earned wage access (EWA) and on-demand pay trend is integrating with payroll outsourcing platforms to offer employee financial wellness benefits. Payroll outsourcing providers integrating EWA capabilities differentiate their offering, improve employee satisfaction metrics for client organizations, and create additional fintech revenue streams from the earned wage advance float.
Industry Value Chain Analysis
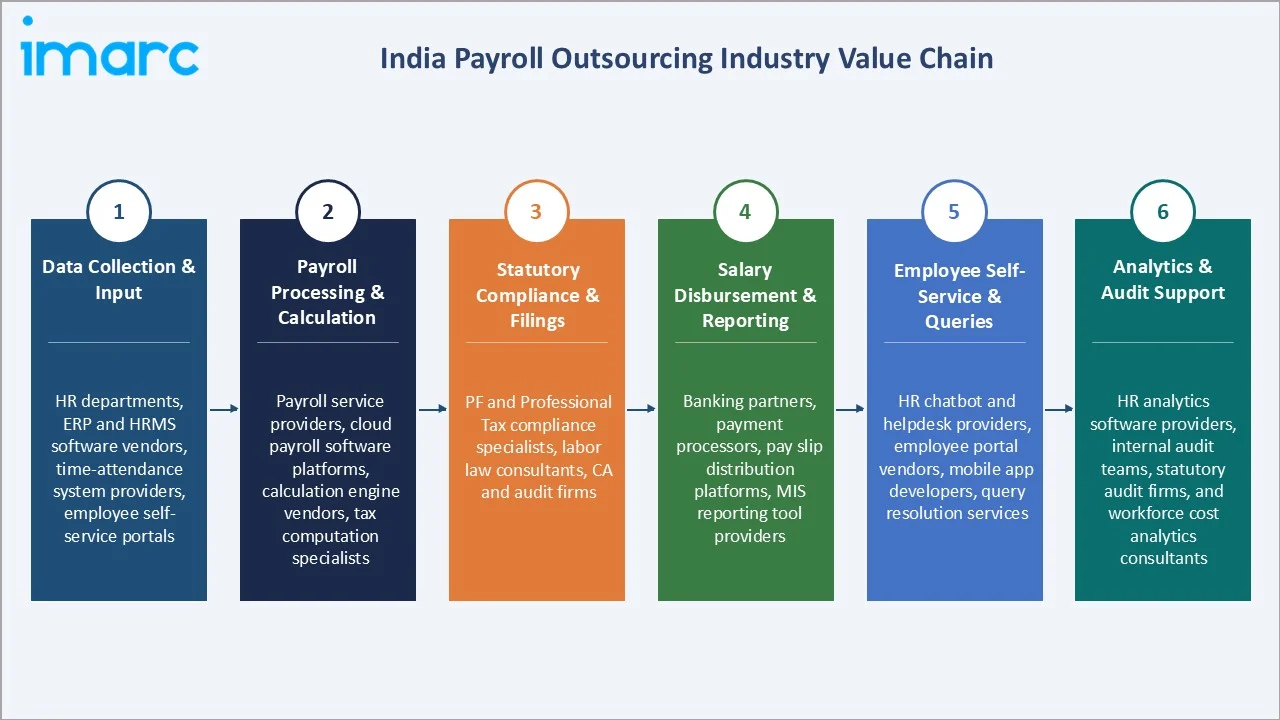
The India payroll outsourcing value chain encompasses data collection and validation, payroll processing and calculation, statutory compliance and filing, salary disbursement and reporting, employee self-service support, and analytics and audit, with specialist providers managing the entire chain on behalf of client organizations.
|
Stage |
Key Players |
|
Data Collection & Input |
HR departments, ERP and HRMS software vendors, time-attendance system providers, employee self-service portals. |
|
Payroll Processing & Calculation |
Payroll service providers, cloud payroll software platforms, calculation engine vendors, tax computation specialists. |
|
Statutory Compliance & Filings |
PF and Professional Tax compliance specialists, labor law consultants, CA and audit firms. |
|
Salary Disbursement & Reporting |
Banking partners, payment processors, pay slip distribution platforms, MIS reporting tool providers. |
|
Employee Self-Service & Queries |
HR chatbot and helpdesk providers, employee portal vendors, mobile app developers, query resolution services. |
|
Analytics & Audit Support |
HR analytics software providers, internal audit teams, statutory audit firms, and workforce cost analytics consultants. |
Statutory compliance and filing represent the highest-complexity and highest-value stage in the payroll outsourcing value chain, where specialist knowledge of EPFO, Income Tax, and state-level regulations commands premium service pricing. Providers automating this stage through real-time compliance engines achieve the highest margins and lowest error rates, creating durable competitive advantages over manual compliance processing operations.
Technology Landscape in the India Payroll Outsourcing Industry
Cloud-Native Payroll SaaS Platforms
India's payroll outsourcing market is being reshaped by cloud-native SaaS platforms offering subscription-based payroll processing with zero upfront implementation costs. These platforms deliver pre-built statutory compliance engines covering PF, professional tax, and labor welfare fund across all Indian states, enabling SMEs to outsource payroll without complex customization. Mobile-first payroll self-service portals are enabling even daily-wage and blue-collar workforce payroll management through app-based interfaces.
AI-Driven Compliance and Anomaly Detection
Advanced payroll outsourcing platforms are deploying machine learning models trained on historical payroll patterns to detect anomalies, sudden salary spikes, PF contribution mismatches, duplicate employee records, and TDS computation errors before disbursement. Natural language processing chatbots are handling most of the employee payroll queries without human intervention.
API-First Integration Architecture
Modern payroll outsourcing platforms offer open API integration with adjacent HR, ERP, and fintech systems. This API-first architecture enables embedded payroll within existing business workflows, reducing data re-entry errors and processing time. Banking-payroll integration enabling instant salary credit post-payroll approval represents the leading edge of integrated financial infrastructure for payroll delivery.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Full-Managed Outsourcing |
63.8% |
2025 |
|
Application |
Large Business |
47.6% |
2025 |
|
End Use Industry |
🔒 |
🔒 |
2025 |
|
Region |
West India |
31.2% |
2025 |

By Type
Full-managed outsourcing leads at 63.8%, as organizations delegate complete payroll responsibility, from employee data management and salary calculation to statutory filing and salary disbursement, to specialist providers. This model eliminates the need for internal payroll staff, dramatically reduces compliance risk through provider accountability, and scales seamlessly with organizational growth without proportional HR headcount addition.
To access detailed market analysis, Request Sample
Co-managed outsourcing holds 36.2% and is growing among mid-to-large enterprises that prefer to retain internal payroll oversight while outsourcing the technology processing, compliance monitoring, and reporting infrastructure. This hybrid model is particularly popular in the IT sector, where companies maintain HR generalists managing payroll strategy while specialist providers handle the regulatory and technical processing layer.
By Application
Large business dominates at 47.6%, generating the highest per-client revenue through complex multi-entity payroll spanning thousands of employees across multiple states, elaborate variable pay structures, and senior executive perquisite management. Large enterprises in BFSI, IT, manufacturing, and pharmaceuticals are the earliest and deepest adopters of fully managed payroll outsourcing, with high contract values.
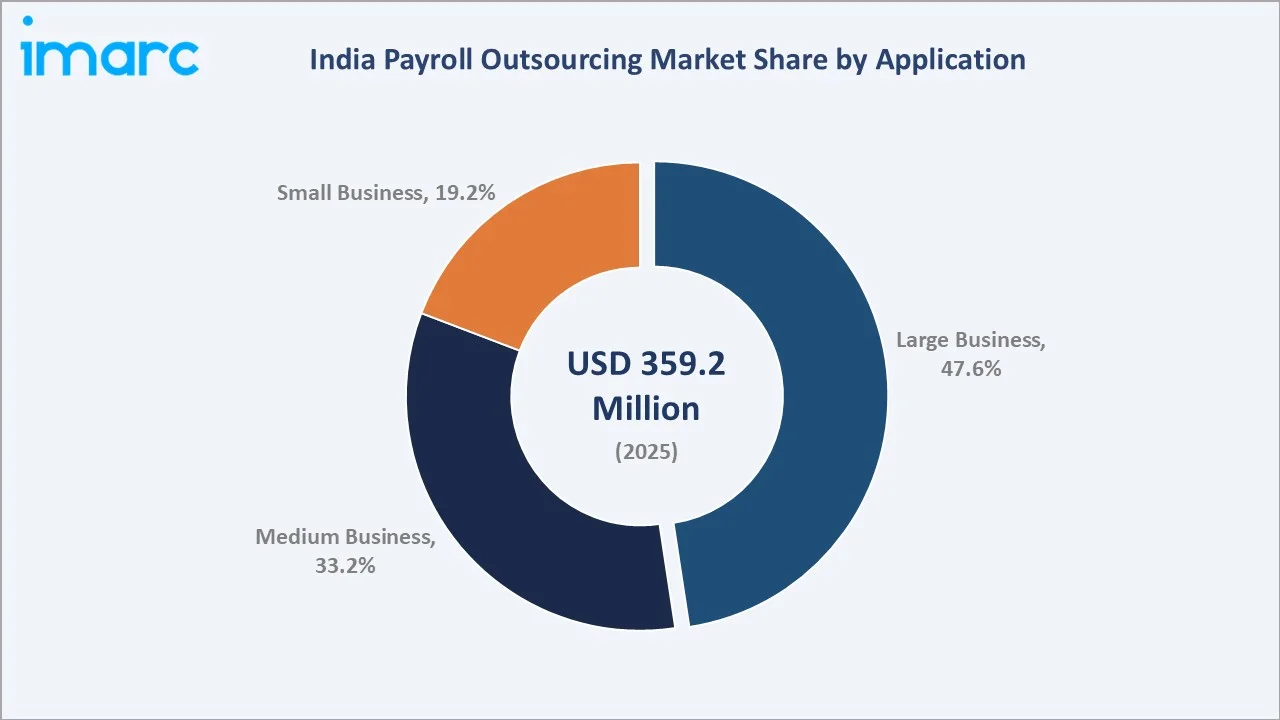
Medium business holds 33.2% and is growing at ~6.4% CAGR as 500-5,000 employee companies find full in-house payroll teams uneconomical versus specialist outsourcing. Small business at 19.2% is growing fastest at ~7.2% CAGR through cloud payroll SaaS adoption as MSME formalization under labor codes makes payroll compliance mandatory.
Regional Market Insights
|
Region |
Share (2025) |
Key India Payroll Outsourcing Market Drivers & Characteristics |
|
West India |
31.2% |
Reflecting concentration of BFSI, IT, and manufacturing corporates with complex multi-state payroll requirements, and large MSME formalization demand. |
|
South India |
29.6% |
Reflecting IT sector payroll complexity, manufacturing hubs, and growing professional services sector requiring statutory compliance-heavy payroll outsourcing. |
|
North India |
23.8% |
Reflecting large enterprise headquarters, government-linked PSU payroll outsourcing demand, and rising MSME formalization generating growing payroll compliance outsourcing needs. |
|
East India |
15.4% |
Reflecting traditional industries, emerging IT sector growth, and increasing payroll outsourcing adoption among industrial and mining sector enterprises. |
West India's 31.2% share reflects concentration of BFSI headquarters and the BSE/NSE financial ecosystem, generating complex payroll with variable pay and commission structures requiring specialist management. IT and manufacturing sectors add substantial mid-market outsourcing demand.
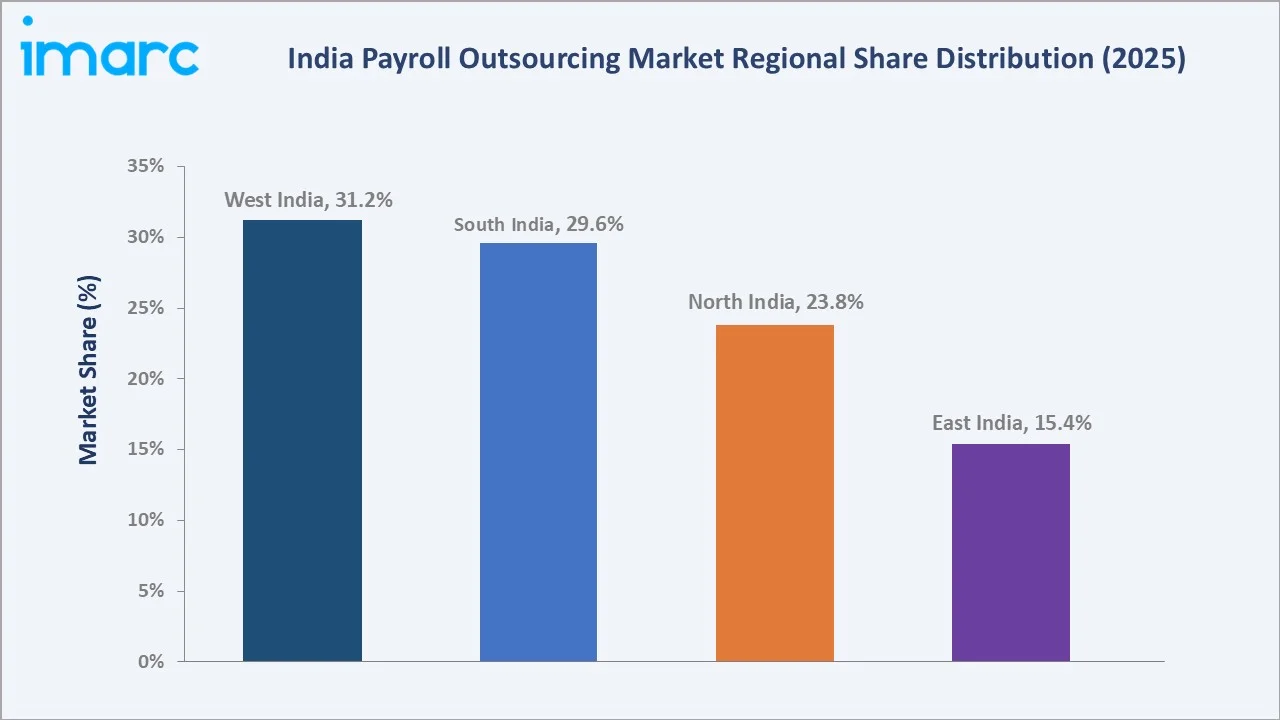
South India's 29.6% is driven by IT employees across GCCs and Indian IT majors requiring sophisticated payroll management with multi-country employee handling. North India's 23.8% reflects large enterprise concentration and rising MSME demand from the growing formal manufacturing sector. East India at 15.4% is positioned for above-average growth as labor code implementation drives formalization across the industrial sector.
Competitive Landscape
The India payroll outsourcing market features a competitive landscape spanning global enterprise payroll specialists, Indian cloud HR-payroll SaaS platforms, integrated HCM providers, and fintech-integrated payroll innovators. Market leadership is contested across compliance depth, technology platform capability, client service quality, and scalability from SME to large enterprise.
|
Company |
Key Offerings |
Market Position |
Core Strength |
|
ADP, Inc. |
ADP payroll outsourcing |
Market Leader |
ADP, Inc. acts as a leading provider of cloud-based payroll and statutory compliance outsourcing, managing wage calculations, tax filings, and employee self-service tools for businesses. |
|
Paychex Inc. |
Paychex Flex |
Established Player |
Paychex, Inc. operates an established corporate office in India that functions as a crucial global delivery and support hub for its worldwide human resources and payroll operations. |
|
Keka Technologies |
Keka Payroll and HR software |
Market Leader |
Keka Technologies serves as a modern, cloud-native HR and payroll software platform that automates core salary processing, statutory compliance, and workforce management. |
|
Ramco Systems |
Payce Payroll Software |
Established Player |
Ramco Systems serves as a major technology and managed services provider in India's payroll outsourcing landscape, offering AI-powered platforms. |
|
Adrenalin eSystems |
MAX Payroll |
Challenger |
Adrenalin eSystems plays a major role in India's payroll outsourcing and Human Capital Management (HCM) sector through its flagship MAX Payroll. |
The competitive dynamics are evolving as India-origin cloud payroll SaaS platforms challenge global providers in the SME and mid-market segments through superior local compliance, affordable pricing, and mobile-first user experiences. Global providers retain dominance in large enterprises and GCC segments through multi-country payroll capabilities and global audit trail requirements.
Key Company Profiles
ADP, Inc.
ADP, Inc. is a provider of human capital management (HCM), payroll, and workforce management solutions, serving organizations across diverse industries. In the India payroll outsourcing market, the company provides payroll processing, compliance support, HR administration, and technology-enabled workforce solutions. Its scalable service capabilities cater to both domestic businesses and multinational enterprises with complex payroll requirements.
- Key Offerings: ADP Payroll Outsourcing
- Strategic Focus: Strengthening its technology-enabled payroll outsourcing capabilities through automation, cloud-based platforms, and integrated workforce solutions. The company emphasizes payroll accuracy, regulatory compliance, data security, and scalable services to address the evolving requirements of businesses in India.
Paychex Inc.
Paychex Inc. is a provider of payroll, human capital management, and workforce-related solutions for businesses of varying sizes. Its service portfolio includes payroll processing, HR administration, workforce management, and technology-enabled solutions designed to streamline employee-related operations. In the broader payroll outsourcing landscape, the company emphasizes integrated platforms and scalable service delivery.
- Key Offerings: Paychex Flex
- Strategic Focus: Strengthening technology-enabled payroll and HR services through automation, cloud-based platforms, and integrated workforce management solutions. Its strategic approach emphasizes operational efficiency, payroll accuracy, regulatory compliance, and scalable service delivery to address evolving business requirements.
Market Concentration Analysis
The India payroll outsourcing market is moderately fragmented, with no single provider dominating more than 15-20% of total market revenue. Global providers lead in large enterprise revenue share, while India-origin cloud SaaS platforms dominate SME and mid-market client count. The top five providers collectively account for an estimated 40-50% of organized market revenue, with the remaining share distributed among regional and boutique payroll outsourcing firms serving specific industry verticals or geographies.
Market consolidation is accelerating through strategic acquisitions as HCM platforms build payroll capabilities and payroll providers add HR modules. The SME segment's rapid growth is attracting new entrants, including fintech platforms and accounting software providers integrating payroll as an add-on, potentially fragmenting the entry-level market while creating consolidation at the mid-to-enterprise tier through platform bundling and switching costs.
Investment & Growth Opportunities
Highest Growth Segments
Small business payroll outsourcing (~7.2% CAGR) through MSME formalization, medium business cloud HRMS-payroll convergence (~6.4% CAGR), GCC and MNC India payroll managed services, gig economy and contractor payroll platforms, and labor code transition advisory-led outsourcing represent the highest-return investment vectors in the India payroll outsourcing market through 2034.
Investment Themes
- Cloud Payroll SaaS for Tier-2 and Tier-3 City MSMEs: India's MSME formalization wave under GST and labor code is reaching smaller cities where no established payroll outsourcing infrastructure exists. Affordable cloud platforms with regional language support and WhatsApp-based payslip delivery can capture millions of first-time payroll outsourcing clients, generating subscription revenue at scale.
- Integrated HCM and Payroll Platform with Banking Rails: Embedding payroll within unified HCM platforms that also manage recruitment, performance, and benefits, then connecting to banking APIs for instant salary credit creates a comprehensive employee experience platform with significantly higher switching costs and revenue per client than standalone payroll services.
- Payroll Analytics and Workforce Cost Intelligence Premium Services: Building predictive workforce cost modeling, department-wise payroll efficiency benchmarking, and financial impact simulation as premium advisory services on top of base payroll processing doubles or triples revenue per enterprise client while deepening consulting relationships that drive long-term contract renewals.
Future Market Outlook (2026-2034)
The India payroll outsourcing market is projected to grow from USD 359.2 Million in 2025 to USD 379.7 Million in 2026, reaching USD 592.1 Million by 2034, exhibiting a CAGR of 5.71% during 2026-2034. The market is projected to reach an anchor value of USD 474.1 Million by 2030, representing the mid-period milestone at which labor code implementation achieves regulatory certainty, MSME payroll formalization reaches critical mass, and cloud payroll SaaS penetration among Indian enterprises.
Three structural forces will define the India payroll outsourcing market through 2034. First, India's regulatory environment is becoming permanently more complex, with labor code implementation, regulatory compliance, and EPFO's digital transformation creating ongoing compliance requirements that make specialist outsourcing strategically rational for organizations across all sizes and sectors. Second, the convergence of payroll with HCM, banking, and analytics platforms is transforming payroll outsourcing from a cost-center service into a strategic HR technology investment, enabling providers to charge premium pricing for integrated capabilities well above commodity payroll processing. Third, the formalization of India's vast MSME sector creates a decade-long structural demand expansion for affordable, technology-enabled payroll outsourcing at scale.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with payroll outsourcing service executives, HR directors of large and mid-market Indian enterprises, EPFO and regulatory consultants, CA and payroll compliance professionals, and HR technology platform product managers. These discussions validated market size estimates, outsourcing type demand patterns, application segment adoption, and technology trajectory for the 2026-2034 forecast period.
Secondary Research
Secondary research encompassed Ministry of Labor and Employment publications, EPFO annual reports, corporate registration data, HR technology reports, IMARC Group proprietary HR services and SaaS databases, annual reports of key market participants, and industry publications covering India's payroll technology and outsourcing market developments through 2025.
Forecasting Models
Forecasting models incorporated historical payroll outsourcing revenue growth correlations with organized sector employment expansion, labor code implementation timelines and MSME formalization projections, cloud SaaS adoption curves, GCC growth forecasts, and macroeconomic indicators. Both bottom-up client segment and average revenue per client modeling and top-down market sizing approaches were cross-validated for forecast consistency across all segments and regions.
India Payroll Outsourcing Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Full-Managed Outsourcing, Co-Managed Outsourcing |
| Applications Covered | Small Business, Medium Business, Large Business |
| End Use Industries Covered | BFSI, Consumer and Industrial Products, IT and Telecommunication, Public Sector, Healthcare, Others |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | ADP, Inc., Paychex Inc., Keka Technologies, Ramco Systems, Adrenalin eSystems, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India payroll outsourcing market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India payroll outsourcing market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India payroll outsourcing industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Payroll Outsourcing Market Report
The India payroll outsourcing market reached USD 379.7 Million in 2026, driven by rising labor code compliance complexity, MSME formalization under GST, cloud payroll SaaS adoption, and GCC payroll managed services demand across India's organized sector.
The India payroll outsourcing market is projected to grow at a CAGR of 5.71% during 2026-2034, driven by regulatory complexity, MSME payroll formalization, integrated HCM-payroll platform adoption, and GCC payroll managed services expansion across India's growing formal economy.
The market is projected to reach USD 474.1 Million by 2030. The mid-period milestone is driven by regulatory certainty driving enterprise adoption, the MSME formalization wave creating first-time outsourcing demand, and cloud payroll SaaS expansion.
Full-managed outsourcing leads with a 63.8% share in 2025, as organizations prefer complete payroll lifecycle delegation, covering processing, compliance, filings, and disbursement, to specialist providers who assume regulatory accountability across India's complex multi-state payroll compliance landscape.
Large business leads with a 47.6% share in 2025, through complex multi-entity, multi-state payroll requirements including variable pay, ESOP administration, and executive perquisites across BFSI, IT, manufacturing, and pharmaceutical enterprises generating the highest revenue per client.
West India leads with a 31.2% share in 2025, anchored by BFSI sector concentration, IT and manufacturing hubs, and MSME formalization demand generating India's highest combination of enterprise complexity and SME volume payroll outsourcing.
Key players include ADP, Inc., Paychex Inc., Keka Technologies, Ramco Systems, and Adrenalin eSystems, among others.
The India payroll outsourcing market is projected to reach USD 592.1 Million by 2034, driven by complete labor code implementation, widespread MSME payroll formalization, integrated HCM-payroll platform dominance, GCC payroll managed services growth, and advanced payroll analytics service premiumization.
Key opportunities include cloud payroll SaaS for Tier-2 and Tier-3 MSME markets, GCC payroll managed services, integrated HCM-payroll-banking platforms, earned wage access integration for employee financial wellness and payroll analytics premium services.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade