
India Peptide Synthesis Market Size, Share, Trends and Forecast by Product, Technology, Application, End Use, and Region, 2026-2034
India Peptide Synthesis Market Size, Share, Trends & Forecast (2026-2034)
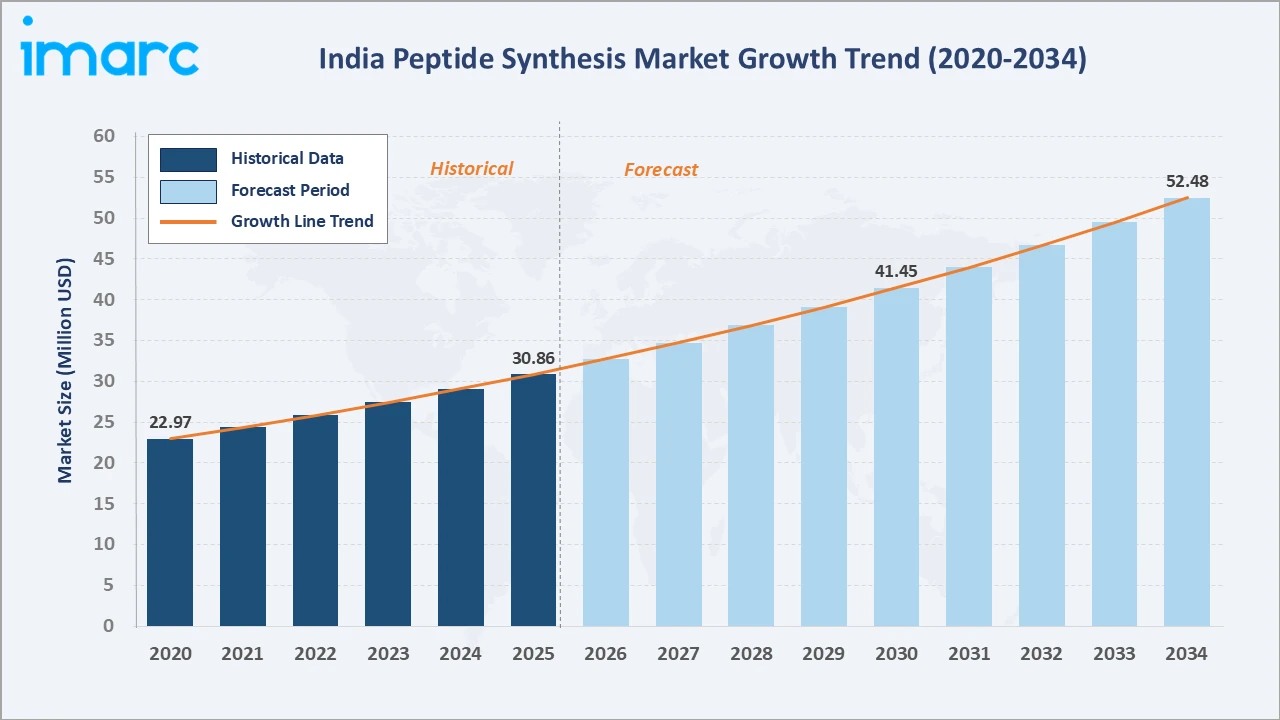
The India peptide synthesis market size reached USD 30.86 Million in 2025 and is projected to reach USD 32.74 Million in 2026, growing at a CAGR of 6.08% to attain USD 52.48 Million by 2034. India's health and wellness-driven pharmaceutical sector, rapid CRDMO expansion, and growing GLP-1 therapeutics demand are key catalysts for sustained market growth. Reagents and consumables lead the product segment at 52.8%, SPPS technology at 61.7% dominates and West India leads region at 32.8%.
Peptide synthesis in India has become a strategically important capability as domestic and multinational pharmaceutical companies seek cost-competitive manufacturing partnerships for complex therapeutic molecules. The India Peptide Synthesis Market research indicates significant capacity addition cycles underway, reflecting the country's rising role in global peptide supply chains.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 30.86 Million |
|
Market Size (2026) |
USD 32.74 Million |
|
Forecast Market Size (2034) |
USD 52.48 Million |
|
CAGR (2026-2034) |
6.08% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product |
Reagents and Consumables (52.8%, 2025) |
|
Dominant Technology |
Solid Phase Peptide Synthesis (SPPS) (61.7%, 2025) |
|
Leading Region |
West India (32.8%, 2025) |
The India peptide synthesis market has expanded from USD 22.97 Million in 2020 to USD 30.86 Million in 2025, with growth accelerating to USD 32.74 Million in 2026. The market is expected to reach USD 41.45 Million by 2030 and USD 52.48 Million by 2034, reflecting consistent demand growth across therapeutic, research, and contract manufacturing segments. India's peptide synthesis ecosystem is commercially distinguished by its dual positioning as both a domestic therapeutic demand hub and a globally competitive contract manufacturing destination serving international pharmaceutical innovators.
To get more information on this market, Request Sample
SPPS technology commands market leadership at 61.7% owing to its scalability, automation compatibility, and GMP compliance advantages for commercial-scale therapeutic peptide production. Reagents and consumables sustain the highest product share as synthesis throughput expands across both research and commercial facilities.
The India Peptide Synthesis Market market cap is projected to grow significantly over the forecast period as new capacity investments and regulatory approvals accelerate commercialization timelines.
Executive Summary
The India peptide synthesis market is poised for robust expansion, projected to grow from USD 32.74 Million in 2026 to USD 52.48 Million by 2034, registering a CAGR of 6.08%. The market's expansion is underpinned by rising demand for peptide therapeutics, CDMO capacity additions, and government policy support through PLI incentives for pharmaceutical manufacturing.
Reagents and consumables lead the product segment at 52.8%, reflecting the high consumption intensity of amino acids, resins, and coupling reagents in SPPS workflows. SPPS technology at 61.7% dominates due to its process automation potential and suitability for GMP-compliant commercial-scale peptide synthesis. West India at 32.8% leads regionally through its dense concentration of pharmaceutical and CDMO facilities across the Mumbai–Pune corridor.
Key Market Insights
| Insight | Data |
|---|---|
| Dominant Product | Reagents and Consumables – 52.8% share (2025) |
| Dominant Technology | Solid Phase Peptide Synthesis (SPPS) – 61.7% market share (2025) |
| Leading Region | West – 32.8% share (2025) |
| Market Opportunity | GLP-1 manufacturing, government incentives, contract manufacturing, academic and research institute |
Key Analytical Observations Supporting the Above Data:
- Reagents & Consumables at 52.8%: Dominance driven by continuous consumption of amino acid building blocks, Fmoc reagents, resins, and coupling agents in each synthesis cycle across all peptide synthesis facilities in India. Volume consumption scales proportionally with synthesis throughput, creating a stable recurring revenue base. Rising GLP-1 manufacturing mandates are further elevating reagent consumption intensity at commercial-scale facilities.
- SPPS at 61.7%: Solid Phase Peptide Synthesis dominates due to operational efficiency, automation compatibility, and ability to synthesize complex sequences with high purity for GMP-compliant therapeutic production. Investments in automated synthesizers are enabling cost-effective scale-up at leading Indian CDMOs. Integration with PAT (Process Analytical Technology) tools is improving real-time quality monitoring and yield optimization.
- West India at 32.8%: Regional leadership from concentration of pharmaceutical manufacturing facilities, CDMO clusters in the Mumbai–Pune corridor, and established supply chain infrastructure with port access. The region benefits from proximity to major international airports and seaports, facilitating export of peptide APIs to regulated markets. Government-designated pharmaceutical zones and SEZs in Maharashtra and Gujarat further reinforce the region's infrastructure advantage.
India Peptide Synthesis Market Overview
Peptide synthesis in India is commercially positioned at the intersection of domestic therapeutic demand growth and global CDMO opportunity. The country's established pharmaceutical manufacturing base, combined with cost-competitive synthesis capabilities, is attracting contract manufacturing mandates from global innovators developing GLP-1 agonists, oncology peptides, and cardiovascular therapeutics.
The market ecosystem integrates raw material suppliers, domestic CDMOs, research institutions, and end-use pharmaceutical companies. Government initiatives including the Production Linked Incentive scheme for pharmaceuticals and the National Biopharma Mission are creating structural tailwinds for peptide synthesis capacity expansion.
Market Dynamics
To access detailed market analysis, Request Sample
Market Drivers
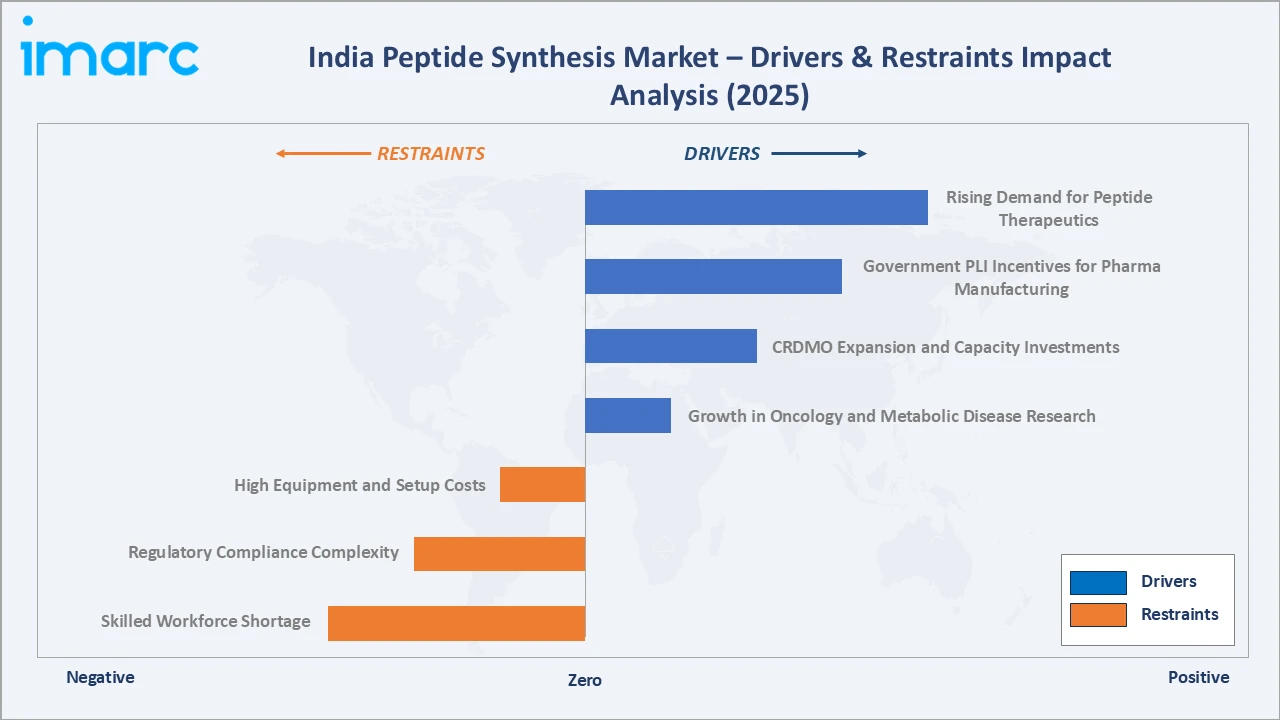
- Rising Demand for Peptide Therapeutics: Escalating global and domestic demand for GLP-1 receptor agonists for obesity and diabetes management, oncology peptides, and cardiovascular therapeutics is driving capacity expansion across Indian peptide synthesis facilities. India's cost-competitive manufacturing positions it as a preferred supplier for global innovators seeking diversified supply chains outside established markets. The growing prevalence of metabolic and endocrine disorders in India is simultaneously expanding the domestic therapeutic peptide market, creating a dual demand dynamic that incentivizes capacity investment.
- Government PLI Incentives for Pharma Manufacturing: The Production Linked Incentive scheme for pharmaceuticals allocates substantial capital subsidies for API and complex molecule manufacturing, incentivizing Indian CDMOs to invest in peptide synthesis equipment, GMP infrastructure, and workforce development. PLI scheme participants receive production-linked incentives that partially offset the high capital expenditure associated with GMP peptide synthesis infrastructure. Complementary programs through the National Biopharma Mission and Department of Biotechnology funding are supporting R&D activities at academic and private sector peptide research organizations.
- CRDMO Expansion and Capacity Investments: Leading Indian contract research, development, and manufacturing organizations are scaling dedicated peptide synthesis capacity, supported by foreign direct investment and partnerships with global pharmaceutical innovators seeking geographically diversified supply chains. New dedicated peptide synthesis buildings with automated synthesizers, HPLC purification train, and lyophilization suites are being commissioned at major CDMO campuses across Hyderabad, Pune, and Mumbai. Strategic acquisitions and joint ventures are accelerating technology transfer of advanced synthesis platforms and proprietary peptide manufacturing processes into the Indian CDMO ecosystem.
- Growth in Oncology and Metabolic Disease Research: Rising prevalence of cancer and metabolic disorders in India is accelerating academic and clinical peptide research, generating demand for synthesis reagents, equipment, and custom peptide services from pharmaceutical and biotechnology companies. CSIR, DBT, and DST-funded research programs at IITs, NIMHANS, and national laboratories are producing a pipeline of novel peptide drug candidates requiring synthesis support services. India's growing clinical trial ecosystem is also creating demand for GMP-grade research peptides for Phase I–III oncology and metabolic disease studies.
Market Restraints
- High Equipment and Setup Costs: Capital-intensive peptide synthesizers, HPLC purification systems, lyophilizers, and mass spectrometry equipment require substantial upfront investment, creating barriers for small and mid-sized organizations seeking GMP-compliant peptide synthesis capabilities. A fully equipped GMP peptide synthesis suite can require capital investment of INR 50–200 crore depending on scale, rendering it inaccessible for early-stage companies and academic spinouts. Ongoing maintenance costs, consumable expenses, and equipment upgrade cycles further elevate the total cost of ownership, limiting market participation to well-capitalized organizations.
- Regulatory Compliance Complexity: Navigating GMP guidelines under Schedule M, CDSCO drug approval requirements, and international regulatory standards creates compliance burdens that increase operational costs and extend time-to-market for therapeutic peptide products. Companies targeting US FDA, EMA, or other regulated market approvals for peptide APIs face multi-year compliance timelines involving facility inspections, analytical validation, and extensive documentation requirements. Regulatory divergence between Indian and international GMP standards historically required dual compliance investments, though harmonization efforts are gradually reducing this burden.
- Skilled Workforce Shortage: A limited pool of trained peptide chemists and process development scientists with GMP manufacturing experience constrains scale-up velocity, particularly for organizations seeking to rapidly expand capacity for global pharmaceutical clients. The specialized skill set required for GMP peptide synthesis combining organic chemistry expertise, HPLC method development, lyophilization science, and regulatory documentation is not widely available in the Indian talent market. Educational programs in peptide chemistry at Indian universities are limited, creating a structural talent supply gap that CDMOs are addressing through in-house training academies and international recruitment.
Market Opportunities
- GLP-1 Peptide API Contract Manufacturing: Surging global demand for semaglutide and other GLP-1 receptor agonists creates a substantial contract manufacturing opportunity for Indian CDMOs with established SPPS capacity and regulatory track records serving global innovators. India's CRDMO sector is well-positioned to capture a meaningful share of GLP-1 API manufacturing as innovators seek to diversify supply chains beyond incumbent European and North American contract manufacturers.
- Academic and Research Institute Services: Growing investment in peptide-based drug discovery at Indian academic institutions and biotechnology parks is creating sustained demand for custom peptide synthesis services, analytical support, and specialized consumables. Government-funded programs through the Department of Biotechnology, CSIR, and ICMR are supporting peptide drug discovery programs at national research institutes, generating recurring custom synthesis mandates. Emerging biotechnology clusters in Hyderabad, Bengaluru, and Pune are incubating peptide-focused startups that rely on contract synthesis service providers for their early-stage molecule development activities.
Market Challenges
- Intellectual Property and Technology Transfer Risks: Managing proprietary synthesis routes, process know-how, and analytical methods in contract manufacturing arrangements requires robust IP protection frameworks that remain a concern for multinational clients engaging Indian peptide CDMOs. Global innovators with next-generation peptide candidates require comprehensive IP confidentiality agreements, trade secret protections, and data integrity assurances before committing to Indian manufacturing partnerships. Strengthening IP enforcement infrastructure and building track records of secure technology management will be critical for Indian CDMOs seeking to attract mandates for breakthrough therapeutic peptide molecules.
- Cold Chain and Logistics Infrastructure: Peptide APIs require strict cold chain storage and transportation conditions; gaps in temperature-controlled logistics infrastructure across India create quality risk and increase distribution costs for peptide manufacturers. Long-distance transport of temperature-sensitive peptide materials from synthesis facilities to end-use pharmaceutical manufacturers involves multiple cold chain transfer points where temperature excursion risks exist. Investments in dedicated cold chain logistics infrastructure, real-time temperature monitoring, and regulatory-compliant packaging protocols are required to support consistent quality delivery across India's geographically dispersed pharmaceutical supply chain.
Emerging Market Trends
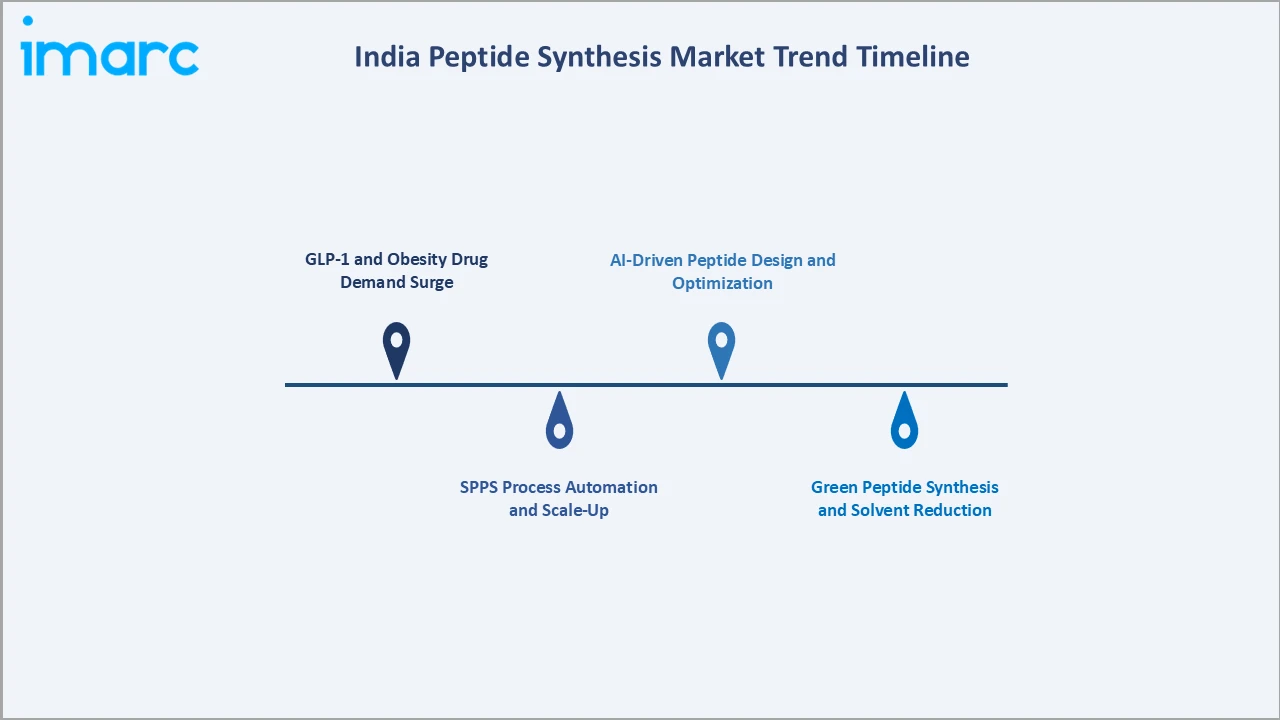
GLP-1 and Obesity Drug Demand Surge
Global demand for GLP-1 receptor agonists is driving unprecedented peptide synthesis capacity investment in India. CDMOs with established SPPS capabilities are receiving increased contract inquiries for semaglutide analogue manufacturing, positioning India as an alternative supply source.
SPPS Process Automation and Scale-Up
Automated peptide synthesizers and flow chemistry platforms are being adopted by leading Indian CDMOs to improve synthesis efficiency, reduce solvent consumption, and enable cost-competitive large-scale GMP production for global therapeutic peptide markets.
Green Peptide Synthesis and Solvent Reduction
Environmental sustainability pressures are driving adoption of green chemistry principles in peptide synthesis, including water-compatible solid supports, reduced hazardous solvent protocols, and recyclable coupling reagents across Indian synthesis facilities.
AI-Driven Peptide Design and Optimization
Artificial intelligence and machine learning tools are being integrated into peptide discovery workflows at Indian biotech firms and research institutions, accelerating hit identification, sequence optimization, and synthesis condition prediction.
Industry Value Chain Analysis
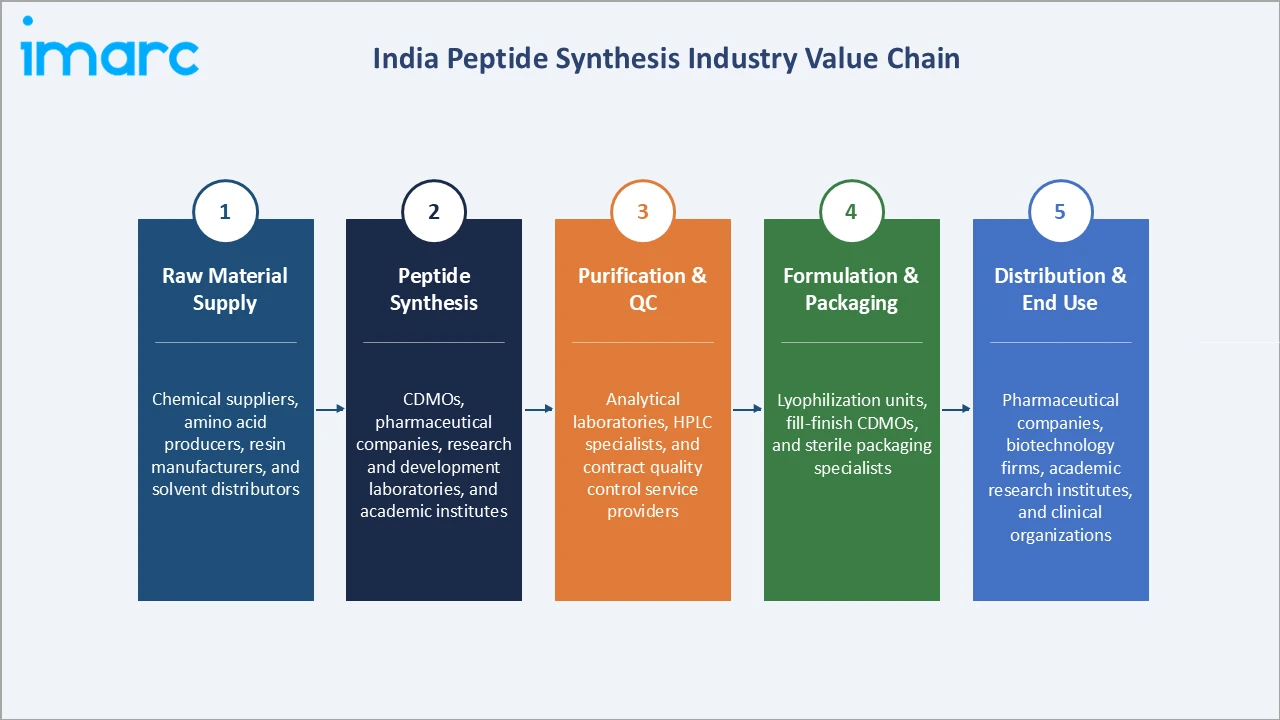
The India peptide synthesis market value chain spans raw material sourcing, synthesis and manufacturing, purification, formulation, and end-use distribution. Each stage involves specialized participants contributing distinct technical capabilities and regulatory expertise.
| Stage | Key Participants |
|---|---|
| Raw Material Supply | Chemical suppliers, amino acid producers, resin manufacturers, and solvent distributors |
| Peptide Synthesis | CDMOs, pharmaceutical companies, research and development laboratories, and academic institutes |
| Purification & QC | Analytical laboratories, HPLC specialists, and contract quality control service providers |
| Formulation & Packaging | Lyophilization units, fill-finish CDMOs, and sterile packaging specialists |
| Distribution & End Use | Pharmaceutical companies, biotechnology firms, academic research institutes, and clinical organizations |
Raw material suppliers provide amino acid building blocks, Fmoc-protected residues, resins, and coupling reagents sourced domestically and through import channels. Synthesis facilities integrate SPPS and LPPS platforms with analytical capabilities for in-process quality monitoring. Purification and quality control stages ensure peptide purity, yield optimization, and regulatory compliance before formulation and distribution to end users.
Technology Landscape in the India Peptide Synthesis Industry
Solid Phase Peptide Synthesis (SPPS)
SPPS commands 61.7% technology share through its automation compatibility, ability to produce complex peptide sequences with high purity yields, and scalability for GMP manufacturing. Fmoc-based SPPS protocols dominate commercial peptide production in India, supported by commercially available automated synthesizers and established reagent supply chains.
Liquid Phase Peptide Synthesis (LPPS)
LPPS at 21.4% is preferred for short peptide production and large-scale manufacturing of specific therapeutic APIs. Granules India's acquisition of Senn Chemicals AG brought proprietary LPPS expertise to the Indian market, expanding domestic capacity for solution-phase synthesis of cost-sensitive peptide molecules.
Hybrid Technology
Hybrid technology at 16.9% combines SPPS and LPPS advantages, enabling segment-based assembly of complex peptides with reduced synthesis steps. This approach is gaining traction for long-chain therapeutic peptides and cyclic peptides where neither SPPS nor LPPS alone offers optimal efficiency.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product |
Reagents & Consumables |
52.8% |
2025 |
|
Technology |
Solid Phase Peptide Synthesis (SPPS) |
61.7% |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
End Use |
🔒 |
🔒 |
2025 |
|
Region |
West India |
32.8% |
2025 |

By Product
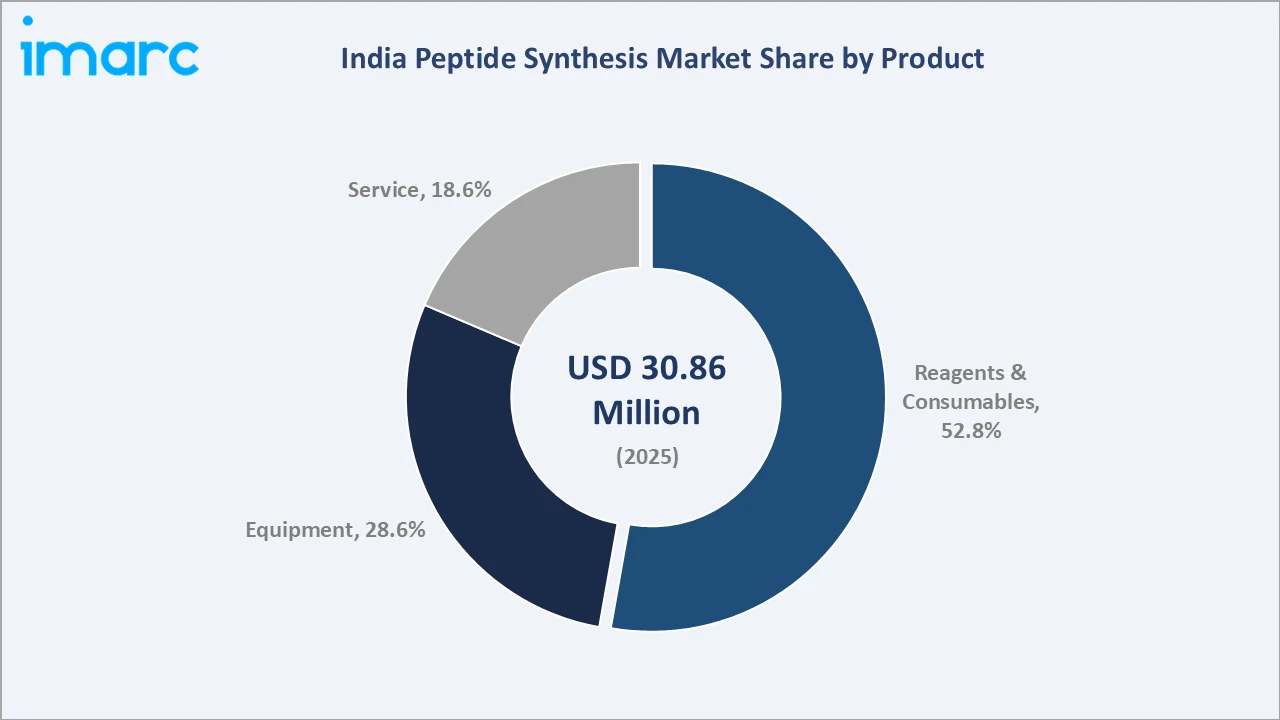
Reagents and consumables dominate product segmentation at 52.8% in 2025, driven by continuous consumption of Fmoc-amino acids, resins, coupling reagents, and cleavage cocktails across synthesis cycles.
To access detailed market analysis, Request Sample
Equipment at 28.6% includes peptide synthesizers, HPLC purification systems, and lyophilizers, which are essential capital investments for expanding synthesis capacity. Service at 18.6% covers contract synthesis, analytical services, and process development for pharmaceutical and research clients.
By Technology
SPPS leads at 61.7% due to process efficiency, automation capability, and suitability for GMP-compliant therapeutic peptide production.
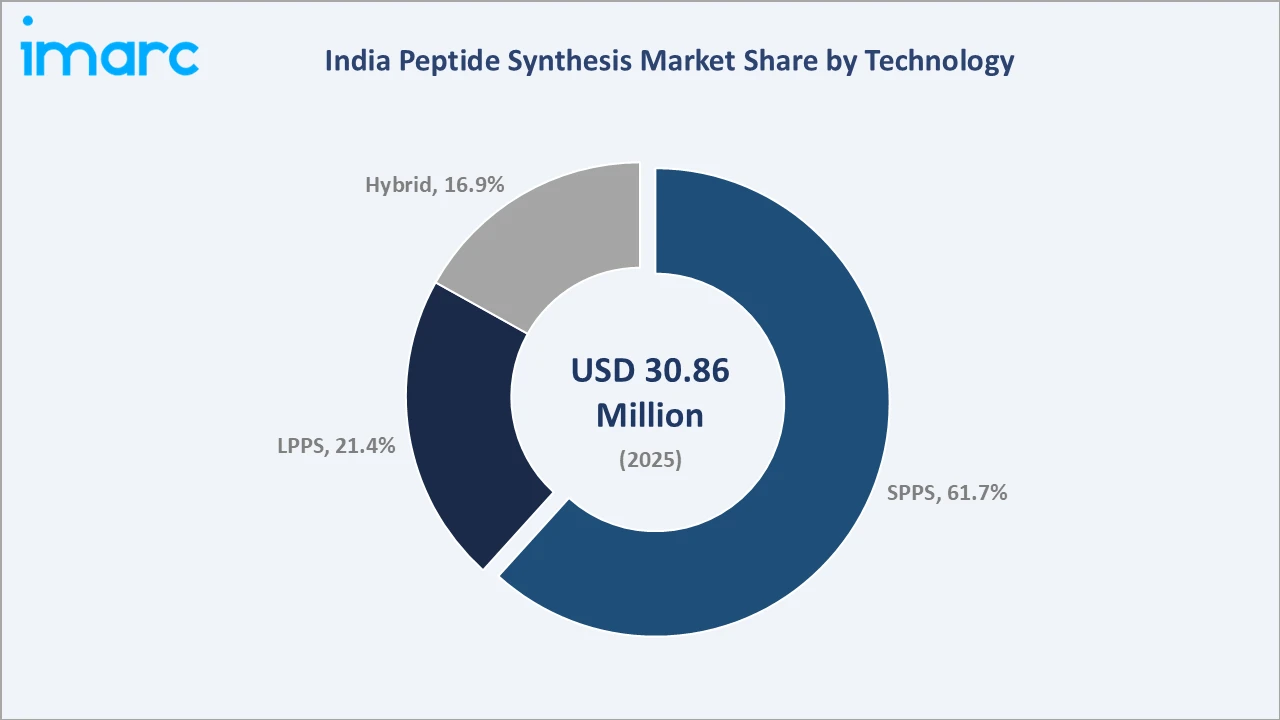
LPPS at 21.4% serves specific commercial peptide APIs where solution-phase synthesis offers cost advantages. Hybrid technology at 16.9% is growing as manufacturers develop optimized protocols for complex therapeutic molecules.
Regional Market Insights
|
Region |
Share (2025) |
Key Market Drivers |
|
West India |
32.8% |
Dense CDMO and API manufacturing clusters in Mumbai–Pune corridor; established cold-chain and regulatory infrastructure |
|
South India |
28.4% |
Biotech parks and peptide research centers in Hyderabad and Bengaluru; strong academic and startup ecosystem |
|
North India |
23.1% |
Academic research institutions, CSIR and DBT-funded peptide programs, pharma manufacturing in Delhi NCR |
|
East India |
15.7% |
Emerging pharmaceutical manufacturing base; growing research capacity supported by government investment |
West India maintains the largest regional share at 32.8% in 2025, driven by the concentration of pharmaceutical CDMOs, API manufacturers, and research facilities across the Mumbai–Pune–Ahmedabad pharmaceutical corridor.
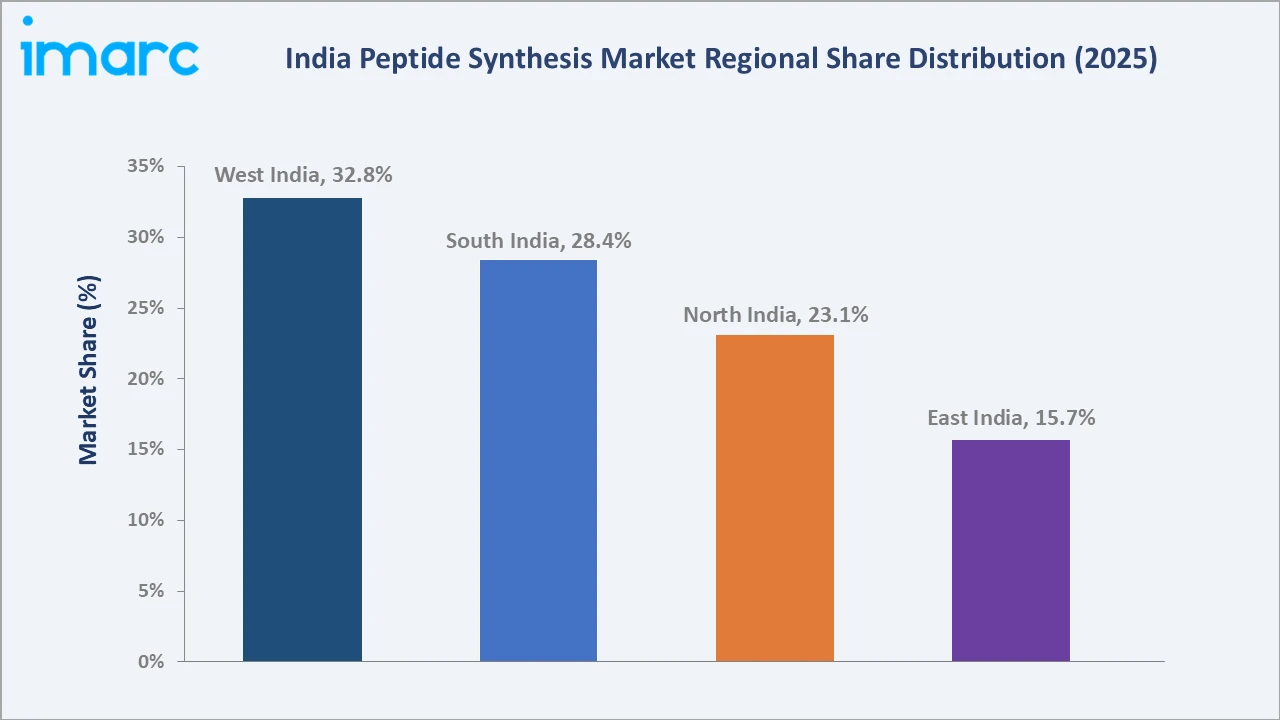
South India at 28.4% benefits from Hyderabad's pharmaceutical cluster and Bengaluru's biotechnology ecosystem, where dedicated peptide research centers and biotech startups generate sustained demand for synthesis services and equipment. North India's 23.1% share reflects academic research demand from IITs, CSIR laboratories, and pharmaceutical companies in the Delhi NCR region. East India at 15.7% represents an emerging opportunity as pharmaceutical manufacturing capacity grows under government infrastructure support programs.
Competitive Landscape
The India peptide synthesis competitive landscape features a heterogeneous mix of domestic CDMOs, multinational manufacturers with Indian operations, specialized peptide API producers, and integrated pharmaceutical companies with dedicated peptide capabilities. Competition is primarily differentiated through GMP regulatory credentials, synthesis technology platforms, therapeutic area specialization, and CRDMO service depth.
| Company | Key Services | Market Position | Core Strength |
|---|---|---|---|
| Sai Life Sciences | Peptide synthesis, CMC R&D, CRDMO services | Innovation Leader | Dedicated peptide research center in Hyderabad; expanding into peptide APIs for global pharma |
| Granules | API synthesis, LPPS and SPPS manufacturing | Market Challenger | Acquired Senn Chemicals AG gaining proprietary LPPS and SPPS expertise for global peptide markets |
| Piramal Pharma Limited | Peptide APIs, oncology CMO, CDMO services | Market Leader | Acquired Hemmo Pharmaceuticals gaining established SPPS/LPPS synthesis infrastructure |
| PolyPeptide Group | GMP peptide manufacturing, global supply | Global Specialist | GMP-compliant commercial-scale synthesis facility in Ambernath serving multinational clients |
| Biocon | Biosimilars, peptide biologics, generic APIs | Strong Challenger | Integrated biopharmaceutical platform for peptide-based biologics and biosimilars for global markets |
| Divi's Laboratories Limited | Custom synthesis, peptide APIs | Market Challenger | Large-scale production facilities and expertise in complex molecule synthesis for regulated markets |
Key players include Sai Life Sciences, Granules, Piramal Pharma Limited, PolyPeptide Group, Biocon, Divi's Laboratories Limited, and others.
Key Company Profiles
Sai Life Sciences
Sai Life Sciences is an integrated CRDMO headquartered in Hyderabad, offering discovery chemistry, process development, and GMP API manufacturing services to global pharmaceutical innovators. The company has established a dedicated peptide research center that positions it as a growing innovation leader in the Indian peptide synthesis ecosystem.
- Key Services: Integrated CRDMO services encompassing peptide API synthesis, CMC process development, and GMP manufacturing for global pharmaceutical clients across discovery through commercial-scale stages.
- Strategic Focus: Deepening GMP peptide synthesis capabilities, growing the portfolio of peptide API development mandates from global partners, and positioning as a preferred India-based CRDMO for complex therapeutic peptide molecules.
Granules
Granules are a vertically integrated pharmaceutical company manufacturing APIs, pharmaceutical formulation intermediates, and finished dosage forms for regulated global markets. The company has entered the peptide synthesis space through strategic international acquisition, gaining proprietary synthesis expertise.
- Key Services: API synthesis, solid-phase and liquid-phase peptide manufacturing, pharmaceutical formulation intermediates, and contract manufacturing for regulated markets across therapeutics categories.
- Strategic Focus: Leveraging acquired peptide synthesis expertise to build international peptide API capabilities, target GLP-1 and specialty therapeutic supply opportunities, and expand regulated market revenues from peptide molecule manufacturing.
Market Concentration Analysis
The India peptide synthesis market exhibits a moderately fragmented structure, with the top five operators accounting for approximately 35–40% of organized market revenue. Fragmentation reflects geographic dispersion of synthesis capacity, differing therapeutic area specializations, and the meaningful role of mid-sized CDMOs and academic-affiliated synthesis units competing through niche expertise in specific peptide classes.
Concentration is highest in the GLP-1 and oncology peptide segments, where GMP-certified manufacturers with established regulatory track records command a disproportionate share of high-value contract manufacturing mandates from multinational pharmaceutical innovators. Research and custom synthesis segments remain highly fragmented, with smaller specialty labs, academic spinouts, and peptide service providers competing on price, turnaround time, and technical depth for discovery-stage and small-batch synthesis requirements.
Investment & Growth Opportunities
Highest Growth Segments
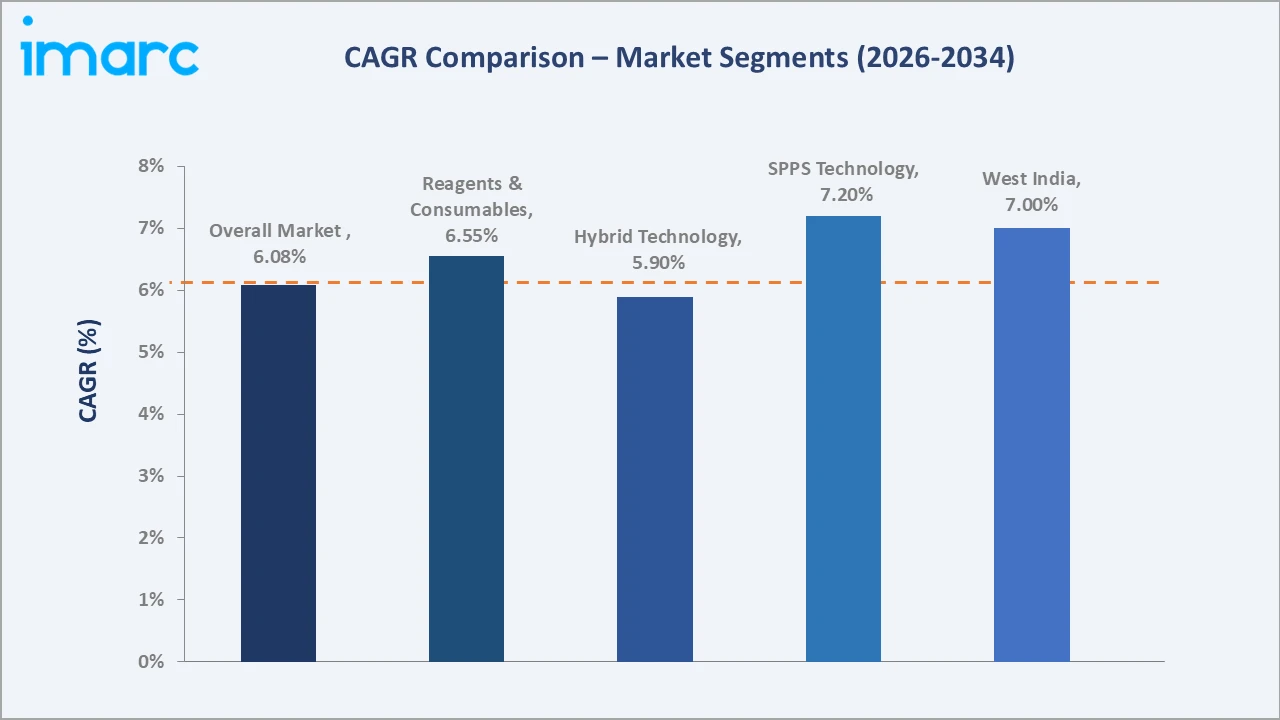
SPPS technology (~7.2% CAGR driven by demand for high-throughput peptide production), West India regional market (~7.0% CAGR supported by pharmaceutical and biotechnology manufacturing expansion), reagents and consumables (~6.55% CAGR from increasing peptide synthesis activity), and hybrid technology (~5.9% CAGR) represent key growth segments through 2034, while the overall India peptide synthesis market is projected to grow at 6.08% CAGR during 2026–2034.
Emerging Investment Opportunities
Dedicated GMP peptide synthesis campuses with integrated SPPS, LPPS, purification, and lyophilization capabilities represent greenfield investment opportunities across India's pharmaceutical manufacturing clusters. Hyderabad's genome valley and the Pune–Mumbai pharmaceutical corridor offer established infrastructure, regulatory environment, and talent ecosystems favorable for new peptide synthesis facility development.
Investment Themes
- GMP Infrastructure Expansion for Regulated Markets: Investment in US FDA and EMA-compliant peptide synthesis infrastructure enables Indian CDMOs to access premium contract manufacturing mandates from regulated market innovators, commanding significantly higher pricing than non-regulated synthesis services.
- Technology-Enabled Synthesis Optimization: Investment in continuous flow peptide synthesis platforms, AI-driven process optimization tools, and automated PAT integration creates competitive advantages enabling higher throughput, lower solvent consumption, and reduced cost-of-goods for commercial-scale GMP peptide production.
Future Market Outlook (2026-2034)
The India peptide synthesis market grew from USD 32.74 Million in 2026 and is projected to reach USD 52.48 Million by 2034, growing at a CAGR of 6.08% during the forecast period 2026-2034, driven by sustained demand for GLP-1 therapeutics, oncology peptides, and CDMO capacity expansion.
SPPS technology will continue to dominate through the forecast period, accelerated by automation adoption and cost optimization initiatives across commercial peptide synthesis facilities. West India is expected to maintain regional leadership as pharmaceutical CDMOs expand dedicated peptide synthesis infrastructure within the established Mumbai–Pune corridor.
Research Methodology
Primary Research
Primary research included structured interviews with peptide synthesis facility managers, CDMO business development executives, procurement specialists at pharmaceutical companies, and academic researchers across Indian peptide synthesis hubs in Hyderabad, Mumbai, Pune, and Bengaluru.
Secondary Research
Secondary research encompassed analysis of published academic studies, IMARC Group proprietary databases, government PLI scheme documentation, CDSCO regulatory filings, industry association reports from the Indian Pharmaceutical Alliance, and company annual reports and regulatory filings.
Data Validation
All market size estimates and segment share data were validated through cross-referencing multiple primary and secondary sources, triangulation with capacity utilization data, and expert panel review by IMARC Group's pharmaceutical research division to ensure analytical accuracy and consistency.
India Peptide Synthesis Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Products Covered |
|
| Technologies Covered | Liquid Phase Peptide Synthesis (LPPS), Solid Phase Peptide Synthesis (SPPS), Hybrid Technology |
| Applications Covered |
|
| End Uses Covered | Pharmaceutical and Biotechnology Companies, CDMOs and CROs, Academic and Research Institutes |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Sai Life Sciences, Granules, Piramal Pharma Limited, PolyPeptide Group, Biocon, Divi's Laboratories Limited, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC's industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India peptide synthesis market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India peptide synthesis market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India peptide synthesis industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Peptide Synthesis Market Report
The India peptide synthesis market size reached USD 30.86 Million in 2025 and is projected to reach USD 32.74 Million in 2026, growing at a CAGR of 6.08% to attain USD 52.48 Million by 2034.
Reagents and consumables dominate the product segment with a 52.8% share in 2025, driven by the continuous consumption of amino acids, resins, coupling reagents, and solvents across synthesis cycles at research and commercial facilities.
Solid Phase Peptide Synthesis (SPPS) leads with a 61.7% technology share in 2025, preferred for its automation compatibility, high purity yields, and suitability for GMP-compliant commercial-scale therapeutic peptide manufacturing.
West India leads regionally with a 32.8% share in 2025, driven by the dense concentration of pharmaceutical CDMOs, API manufacturers, and research facilities in the Mumbai–Pune–Ahmedabad pharmaceutical corridor.
Key growth drivers include rising global demand for GLP-1 receptor agonists, government PLI incentives for pharmaceutical manufacturing, CDMO capacity expansions, and increasing academic and clinical research in oncology and metabolic peptide therapeutics.
Key players include Sai Life Sciences, Granules, Piramal Pharma Limited, PolyPeptide Group, Biocon, Divi's Laboratories Limited, and others.
Major challenges include high capital equipment costs, regulatory compliance complexity under GMP and CDSCO frameworks, skilled workforce shortages in peptide chemistry, and cold chain infrastructure gaps for peptide API distribution.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade