
India Pizza Market Size, Share, Trends and Forecast by Type, Crust Type, Distribution Channel, and Region, 2026-2034
India Pizza Market Size, Share, Trends & Forecast (2026-2034)
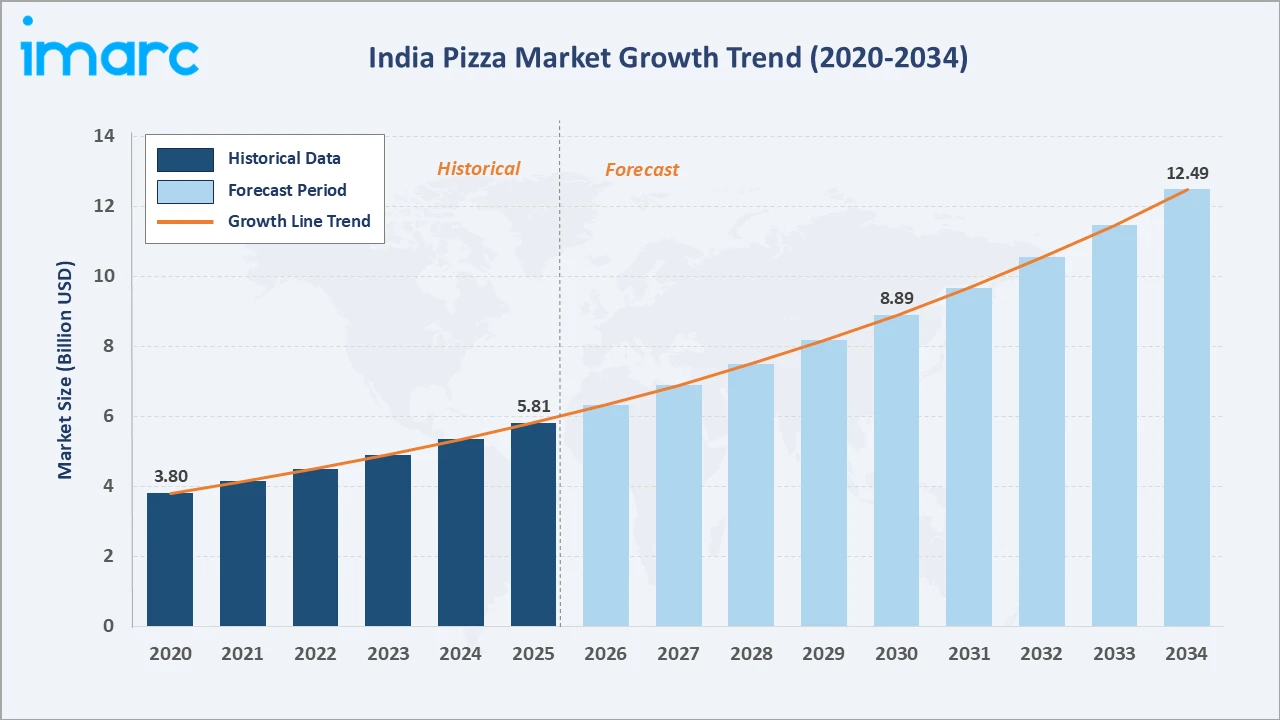
The India pizza market grew from USD 5.81 Billion in 2025 to USD 6.33 Billion in 2026 and is projected to reach USD 12.49 Billion by 2034, growing at a CAGR of 8.87% during 2026-2034. With Domino's India crossing 1,995 operational stores across 421 cities as of September 2024, the rapid expansion of organized quick-service restaurant (QSR) chains across urban and semi-urban India continues to be the primary growth enabler for the market.
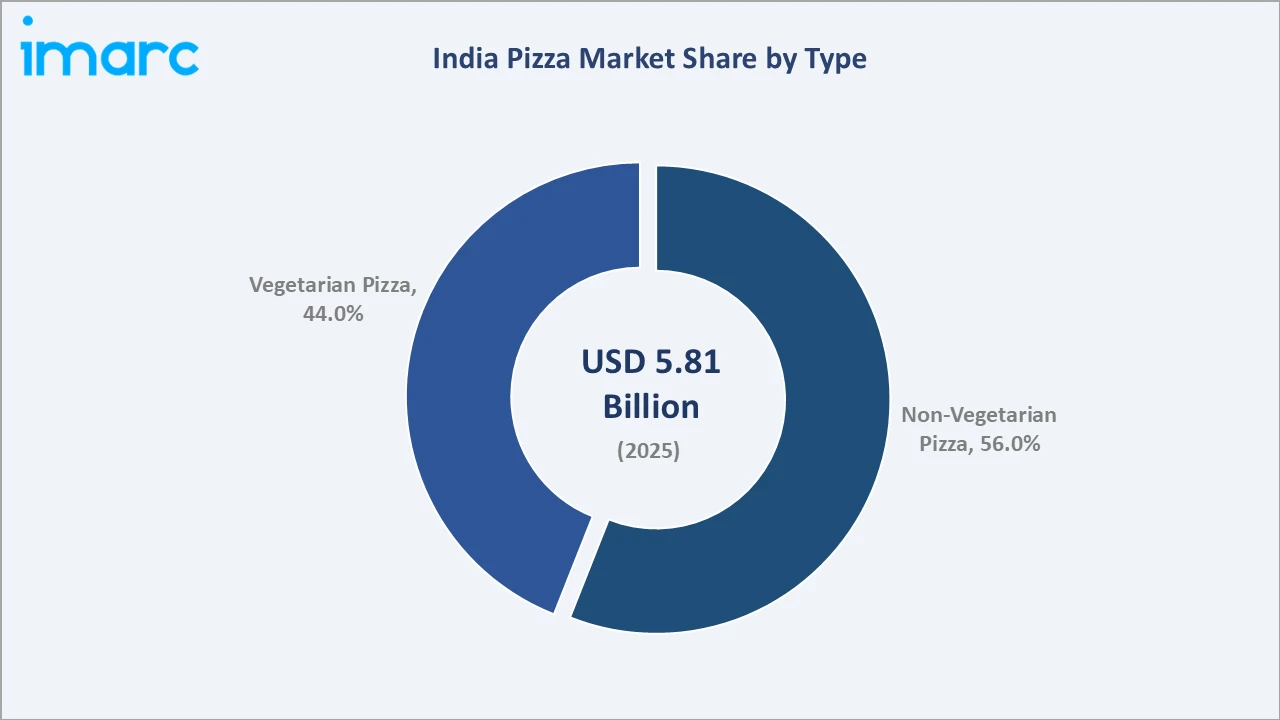
Non-vegetarian pizza leads the type segment at 56.0%, thick crust dominates the crust type segment at 48.0%, and South India commands 34.0% regional share.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 5.81 Billion |
| Market Size (2026) | USD 6.33 Billion |
| Forecast Market Size (2034) | USD 12.49 Billion |
| CAGR (2026-2034) | 8.87% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Largest Region | South India (34.0%, 2025) |
| Second Largest Region | North India (29.2%, 2025) |
| Leading Type | Non-Vegetarian Pizza (56.0%, 2025) |
| Leading Crust Type | Thick Crust (48.0%, 2025) |
The India pizza market size increased from USD 3.80 Billion in 2020 to USD 5.81 Billion in 2025 and is estimated to reach USD 6.33 Billion in 2026. The market is further expected to grow to USD 8.89 Billion by 2030 and USD 12.49 Billion by 2034, supported by accelerating cloud kitchen growth, premiumization trends, and expanding pizza consumption in tier-2 and tier-3 cities.
To get more information on this market, Request Sample
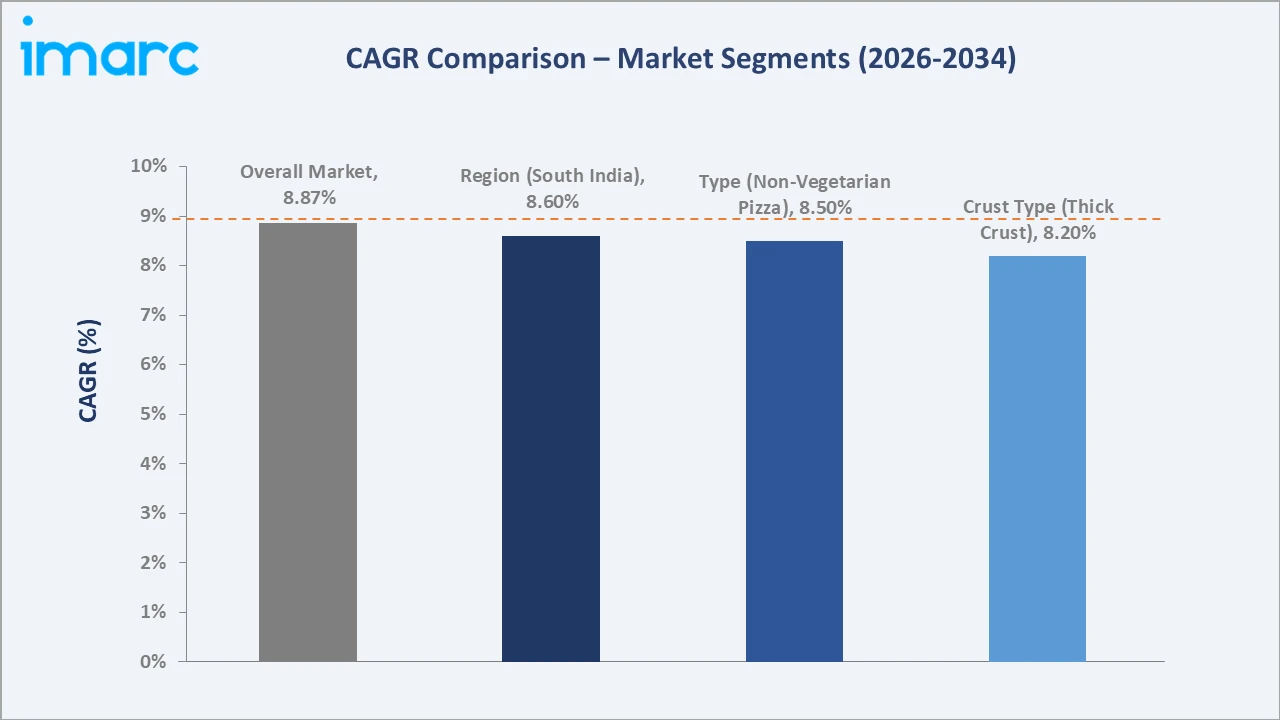
CAGR trajectories across type and crust type sub-segments, together with regional patterns, show stuffed crust and East India expanding faster than the overall 8.87% market CAGR, driven by rising consumer appetite for premium and indulgent pizza formats and expanding digital infrastructure in emerging markets.
Executive Summary
The India pizza market expanded from USD 5.81 Billion in 2025 to an estimated USD 6.33 Billion in 2026. The industry has evolved from a metro-centric food service offering to a widely distributed, delivery-first category spanning organized QSR chains, cloud kitchens, casual dining establishments, and artisanal outlets. Rising disposable incomes, a large and growing youth population, and deepening penetration of organized food service into tier-2 and tier-3 cities are the primary structural drivers sustaining growth through the forecast period.
Non-vegetarian pizza leads the type segment at 56.0% in 2025, driven by widespread availability of chicken-topped variants through organized QSR chains. Thick crust at 48.0% dominates crust type preferences owing to its broad distribution and familiar consumer appeal. South India at 34.0% leads the regional landscape, fueled by the strong presence of organized pizza chains, growing urban demand, and rising consumer preference for convenient dining options.
Key Market Insights
| Insight | Data |
|---|---|
| Leading Type | Non-Vegetarian Pizza – 56.0% share (2025) |
| Second Largest Type | Vegetarian Pizza – 44.0% share (2025) |
| Leading Crust Type | Thick Crust – 48.0% share (2025) |
| Second Largest Crust Type | Thin Crust – 31.7% share (2025) |
| Leading Region | South India – 34.0% share (2025) |
| Second Largest Region | North India – 29.2% share (2025) |
| Top Companies | Jubilant FoodWorks Limited, Rebel Foods Pvt. Ltd., Copenhagen Hospitality Private Limited, Gourmet Investments Pvt. Ltd. |
Key Analytical Observations Expanding On the Data Above:
- Non-vegetarian pizza at 56.0% dominance reflects India's growing preference for protein-rich toppings, including chicken tikka, barbeque chicken, and mutton variants, which align with evolving consumer taste profiles across metros and major urban centers.
- Vegetarian pizza at 44.0% reflects India's large vegetarian consumer base, with demand supported by diverse vegetable toppings, paneer-based variants, and menu options catering to vegetarian dietary preferences.
- Thick crust at 48.0% remains the most preferred crust style, supported by its broad distribution through organized QSR chains and its familiarity among mainstream consumers across regions.
- Thin crust share at 31.7% reflects consumer interest in lighter crust options, particularly among urban customers seeking varied textures and alternative pizza formats.
- South India at 34.0% leads the regional market, supported by a high density of organized food service outlets, strong urbanization, and a growing young consumer base driving pizza consumption in cities such as Bengaluru, Chennai, and Hyderabad.
India Pizza Market Overview
Pizza is one of the fastest-growing segments within India's broader food service industry, encompassing QSR chains, cloud kitchens, casual dining establishments, and artisanal pizza studios. The category spans a wide range of formats like thick crust, thin crust, and stuffed crust variants, served with vegetarian and non-vegetarian topping combinations catering to India's diverse regional palates.
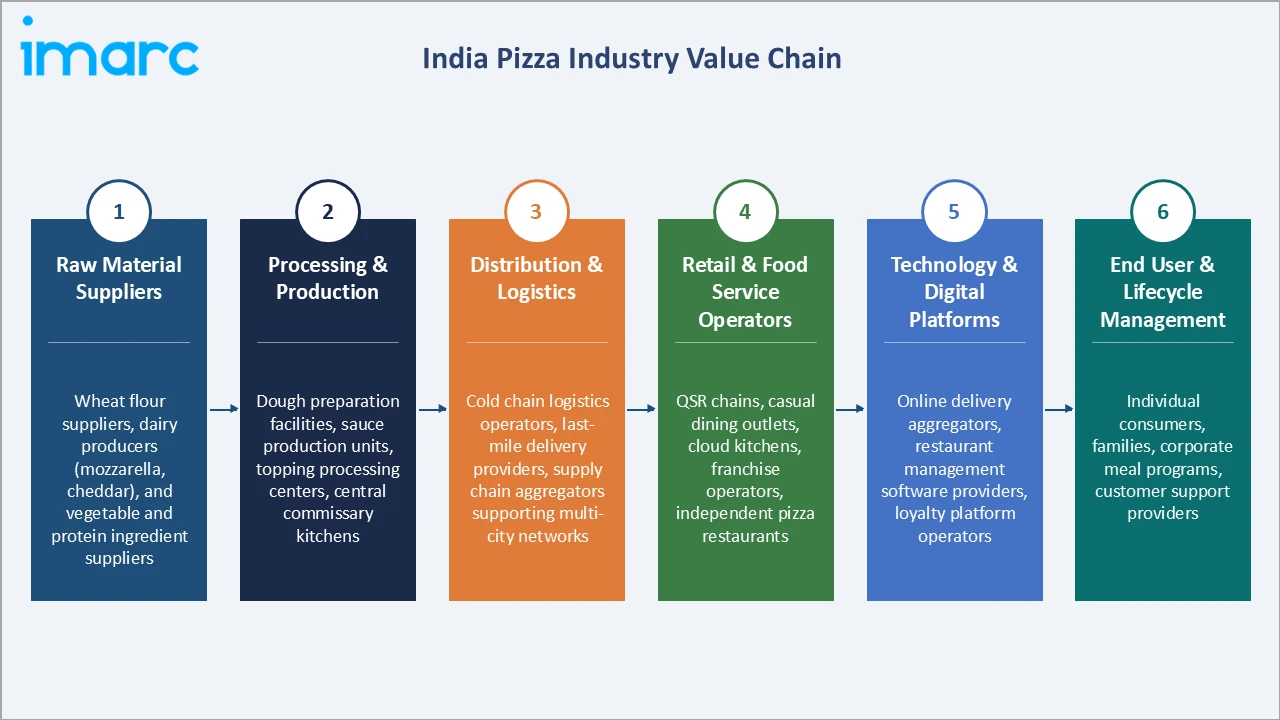
The Indian pizza ecosystem integrates organized chain operators, independent restaurants, cloud kitchen brands, delivery aggregators, ingredient and dough suppliers, cold chain logistics providers, and digital ordering platforms. Together, they form an interconnected network enabling the rapid expansion of pizza consumption across urban and semi-urban India, supported by increasing smartphone penetration and evolving consumer food preferences.
Market Dynamics
To evaluate market opportunities, Request Sample
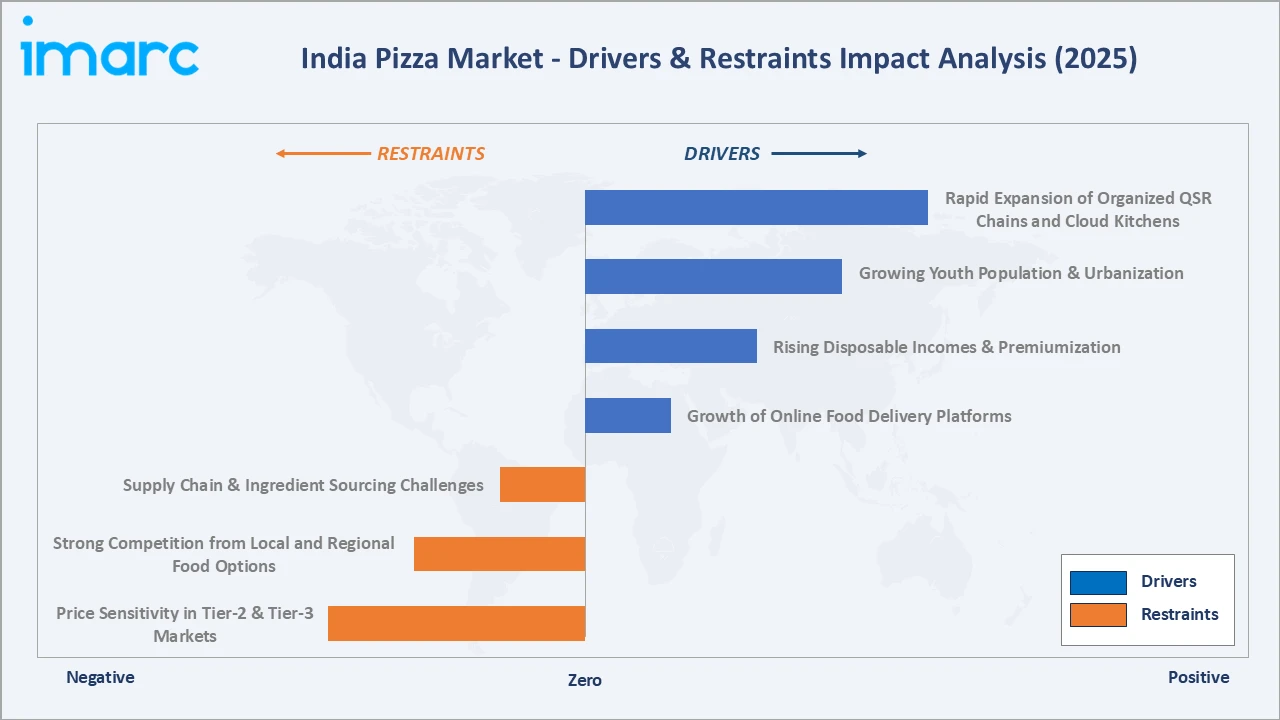
Market Drivers
- Rapid Expansion of Organized QSR Chains and Cloud Kitchens: The organized food service sector continues to expand, with branded outlets across the pizza industry in India benefiting from scalable franchise models, wider geographic reach, and growing consumer acceptance of organized dining formats. As per IMARC Group, the India cloud kitchen market was valued at USD 1.24 Billion in 2025.
- Growing Youth Population and Urbanization: India's young population and expanding urban centers support pizza consumption, as younger consumers increasingly seek international food options, convenient meals, and varied dining experiences. Rising smartphone usage, online food delivery services, and changing lifestyles further strengthen demand across metropolitan and emerging urban markets.
- Rising Disposable Incomes and Premiumization: Increasing household incomes in metro and tier-2 cities are encouraging consumers to trade up toward premium pizza offerings with specialty toppings, artisan crusts, and international flavor profiles, widening average transaction values for organized operators.
- Growth of Online Food Delivery Platforms: The rapid expansion of food delivery aggregators has significantly lowered the barrier to pizza purchase, enabling consumers in smaller cities to access organized pizza brands with the same ease as metro consumers, directly broadening the addressable pizza market in India and unlocking demand in previously underserved geographies.
Market Restraints
- Price Sensitivity in Tier-2 and Tier-3 Markets: A significant portion of India's consumer base in smaller cities and towns remains price-sensitive, limiting the penetration of premium-priced pizza offerings and constraining market growth below certain price thresholds in non-metro markets.
- Strong Competition from Local and Regional Food Options: Traditional Indian snack and food formats, including samosas, chaat, and biryani, compete directly with pizza for consumer spending in the out-of-home food segment, particularly among value-conscious consumers in smaller markets.
- Supply Chain and Ingredient Sourcing Challenges: Consistent sourcing of quality mozzarella, wheat flour, and specialty toppings across diverse geographic regions poses operational challenges for organized pizza chains, affecting cost structures and product consistency across multi-city networks.
Market Opportunities
- Expansion into Tier-2 and Tier-3 Cities: A growing middle class and rising smartphone penetration in smaller cities present significant untapped opportunities for organized pizza chains to extend their footprint beyond metro markets through franchising and delivery-first models.
- Innovation in Vegetarian and Regional Flavor Profiles: Developing regional-flavored pizza variants integrating local spices and ingredients offers brands an opportunity to tap into India's diverse culinary preferences and attract a broader, more geographically distributed consumer base.
Market Challenges
- Rising Food and Real Estate Costs: Increasing commodity prices for cheese and wheat, combined with rising commercial real estate costs in metro cities, are compressing margins for organized pizza operators and making unit economics management a key strategic priority.
- Maintaining Quality Consistency Across Formats: Ensuring uniform product quality across cloud kitchens, dine-in outlets, and delivery channels remains a persistent operational challenge as chains scale rapidly across diverse geographic markets with varying supply chain infrastructure.
Emerging Market Trends
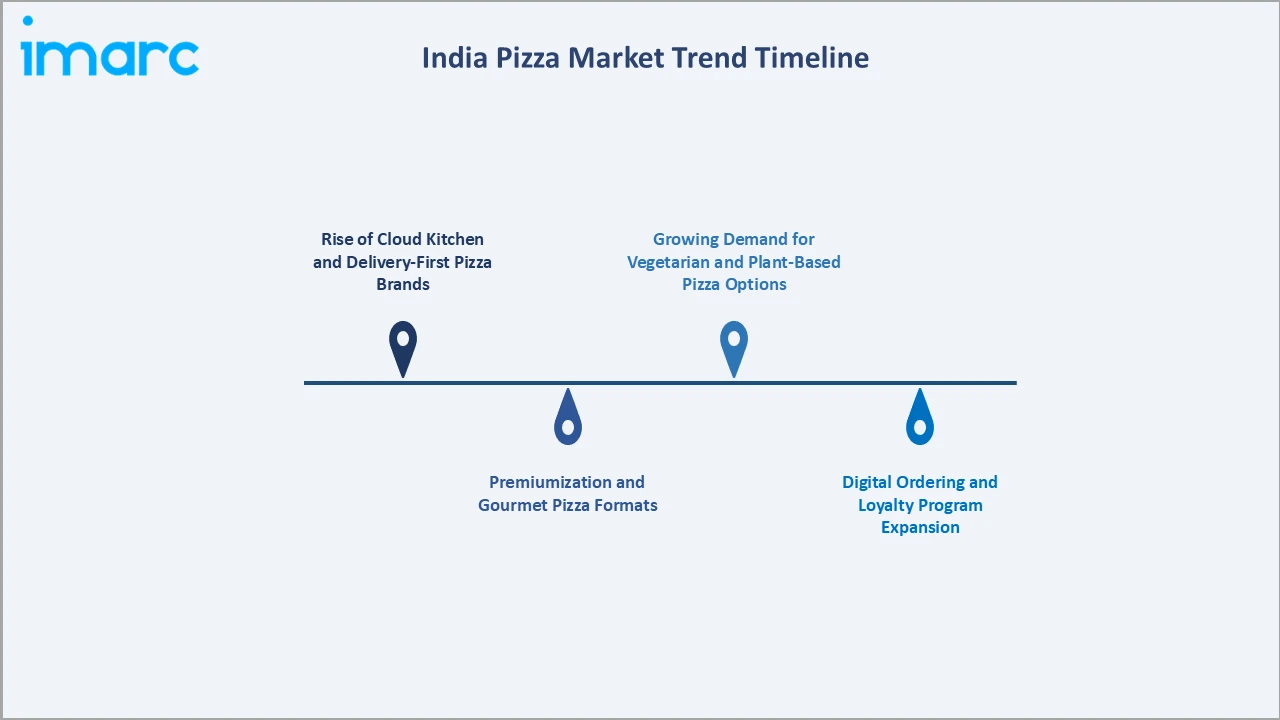
1. Rise of Cloud Kitchen and Delivery-First Pizza Brands
The expansion of cloud kitchens and online food delivery platforms is reshaping pizza consumption in India, with consumers increasingly opting for convenient home delivery and digital ordering. Brands demonstrate the potential of delivery-focused pizza operations, which benefit from lower infrastructure requirements, efficient kitchen utilization, and wider customer reach without relying on traditional dine-in outlets.
2. Premiumization and Gourmet Pizza Formats
Consumers in metros and tier-1 cities are increasingly seeking premium, artisanal, and gourmet pizza formats with specialty cheese, imported meats, and international flavor profiles. This trend is gradually reshaping the pizza market share in India, as organized chains and independent operators develop and expand premium product lines alongside entry-level offerings to serve a broader consumer spectrum.
3. Growing Demand for Vegetarian and Plant-Based Pizza Options
Health-conscious consumers and India's culturally large vegetarian population are driving demand for innovative vegetarian toppings, plant-based protein substitutes, and whole-grain crust options. Leading chains are expanding their vegetarian menus to cater to this growing segment and differentiate within an increasingly competitive pizza landscape.
4. Digital Ordering and Loyalty Program Expansion
Direct ordering applications, CRM-linked loyalty programs, and personalized digital promotions are becoming key competitive tools for pizza chains in India. Brands are investing in digital engagement platforms to reduce dependency on third-party delivery aggregators, improve margin structures on delivery orders, and deepen consumer loyalty.
Industry Value Chain Analysis
The India pizza market value chain spans six stages, from raw material and ingredient sourcing through end-user engagement and lifecycle management. Platform development, food service delivery, and digital channel integration capture the highest value-add, while supply chain efficiency and food safety compliance capabilities increasingly determine sustainable competitive position within this rapidly scaling category.
| Stage | Key Players / Examples |
|---|---|
| Raw Material Suppliers | Wheat flour suppliers, dairy producers (mozzarella, cheddar), vegetable and protein ingredient suppliers, and packaging material manufacturers |
| Processing & Production | Dough preparation facilities, sauce production units, topping processing centers, and central commissary kitchens |
| Distribution & Logistics | Cold chain logistics operators, last-mile delivery service providers, and supply chain aggregators supporting multi-city networks |
| Retail & Food Service Operators | QSR chains, casual dining outlets, cloud kitchens, franchise operators, and independent pizza restaurants |
| Technology & Digital Platforms | Online food delivery aggregators, restaurant management software providers, loyalty platform operators, and digital ordering application developers |
| End User & Lifecycle Management | Individual consumers, families, corporate meal programs, and customer support and feedback management providers |
Vertically integrated pizza operators, especially those owning proprietary supply chains, central commissary kitchens, and direct digital ordering platforms, are positioned to capture greater margin than operators reliant on third-party infrastructure across multiple stages of the value chain.
Technology Landscape in the India Pizza Industry
Cloud Kitchen Technology and AI-Driven Order Management
Pizza operators in India are increasingly leveraging cloud kitchen platforms integrated with AI-driven order management systems that optimize kitchen workflows, reduce preparation times, and balance delivery loads across geographic clusters. These platforms enable brands to scale rapidly without the capital requirements of traditional dine-in restaurant formats.
Digital Ordering and CRM Platforms
Advanced CRM and direct ordering platforms are enabling pizza brands to gather consumer data, personalize promotions, and reduce reliance on third-party delivery aggregators. Investment in proprietary apps and loyalty ecosystems is becoming a key differentiator for leading organized chains.
Supply Chain Digitization and Cold Chain Technology
Investment in supply chain digitization, including cold chain temperature monitoring, demand forecasting algorithms, and supplier integration tools, is improving ingredient freshness and reducing wastage for organized pizza operators, a capability central to the pizza industry India forecast as multi-city delivery networks continue to scale through 2034.
Automated Food Preparation Equipment
Leading chains are deploying automated dough preparation, portioning, and topping equipment to maintain product consistency at scale while managing rising labor costs across high-volume outlets. Automation is enabling standardized quality delivery across diverse franchise and cloud kitchen formats.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Type | Non-Vegetarian Pizza | 56.0% | 2025 |
| Crust Type | Thick Crust | 48.0% | 2025 |
| Distribution Channel | Quick Service Restaurants (QSR) | 62.0% | 2025 |
| Region | South India | 34.0% | 2025 |

By Type
Non-vegetarian pizza commands a 56.0% majority share in 2025, driven by strong consumer preference for chicken-topped variants including chicken tikka, barbeque chicken, and pepperoni, widely available through organized QSR chain menus. The segment benefits from menu innovation, competitive pricing at quick-service formats, and cross-regional appeal among India's urban youth population.
To access detailed market analysis, Request Sample
Vegetarian pizza at 44.0% in 2025 reflects India's large vegetarian consumer base and growing demand for paneer, corn, and mixed vegetable pizza variants. The segment is supported by expanding menu diversity at organized chains and strong performance in South India and Gujarat, where vegetarian food preferences are culturally dominant.
By Crust Type
Thick crust leads the crust type segment with 48.0% share in 2025, driven by its broad distribution across organized QSR chains and consumer preference for a filling, substantial eating experience. Its dominance reflects the outsized market presence of large-format pizza chains whose core menus are built around thick-crust offerings.
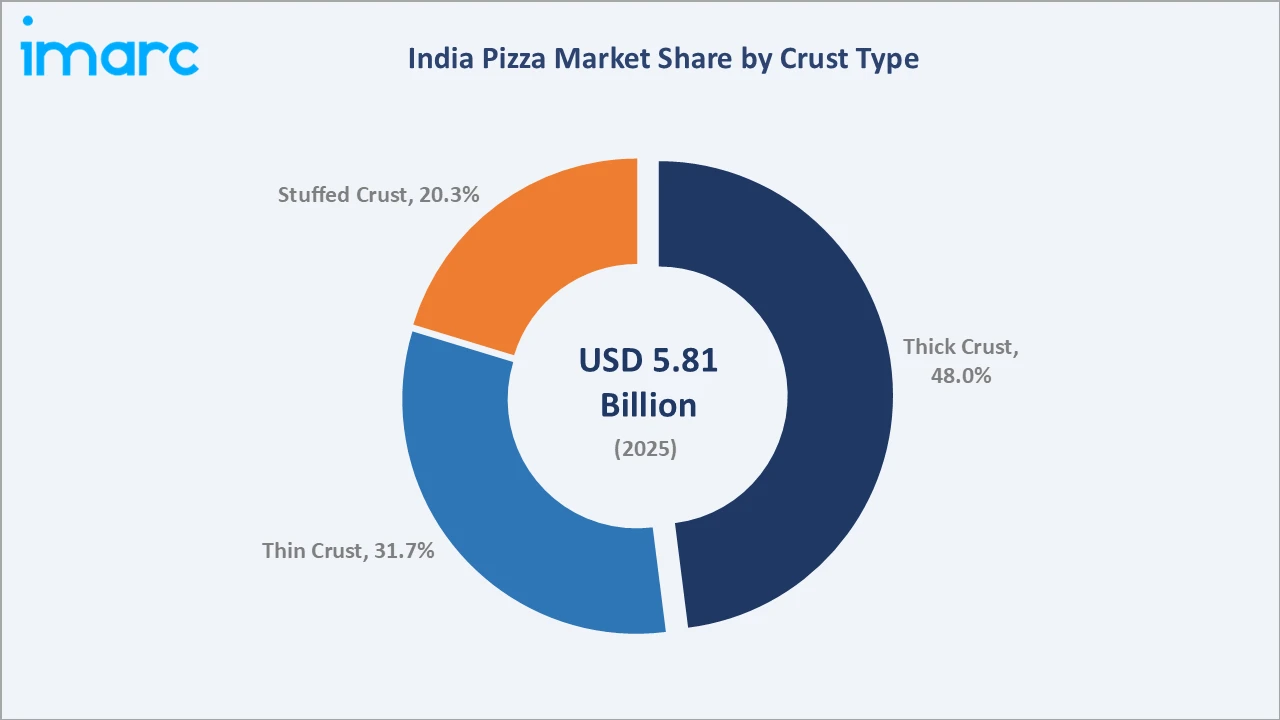
Thin crust at 31.7% is gaining traction among health-conscious consumers and those preferring lighter meal options and Italian-style pizza formats.
Regional Market Insights
| Region | Share (2025) | Key Growth Drivers |
|---|---|---|
| South India | 34.0% | High urban density, growing youth population, strong organized food service penetration, and increasing disposable incomes in major cities |
| North India | 29.2% | Large consumer base, rising QSR chain penetration, expanding delivery networks, and growing appetite for western and international food formats |
| West and Central India | 23.6% | Dense metropolitan population, strong commercial activity, increasing organized retail, and high adoption of online food delivery platforms |
| East India | 13.2% | Emerging urban markets, growing digital connectivity, rising food service investments, and expanding tier-2 city participation |
South India at 34.0% in 2025 leads the regional landscape, anchored by cities such as Bengaluru, Chennai, and Hyderabad, which host some of the highest densities of organized pizza outlets per capita in India. Strong technology sector employment, a young professional consumer base, and high digital ordering adoption support sustained regional leadership through the forecast period.
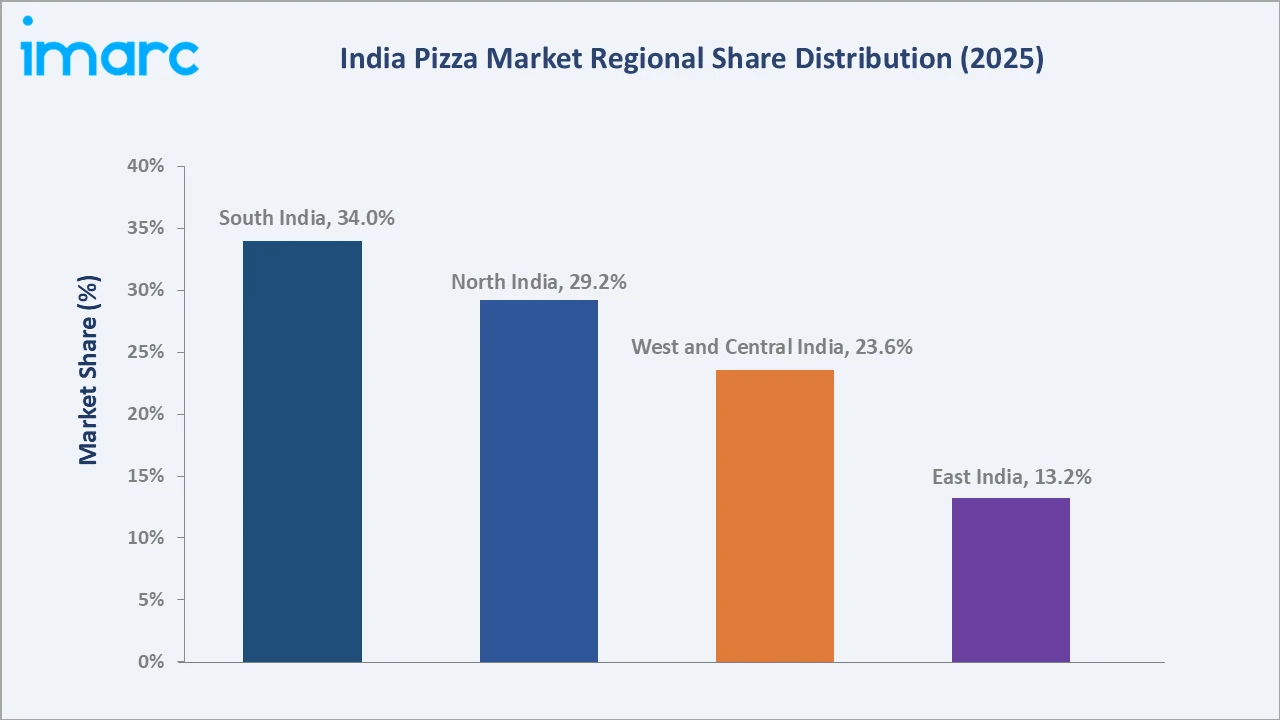
East India, while currently the smallest regional contributor at 13.2%, is expanding rapidly as regional food service operators and national chains extend pizza delivery infrastructure into underserved tier-2 and tier-3 cities in West Bengal, Odisha, and Jharkhand, supporting strong long-term regional growth potential through 2034.
Competitive Landscape
The India pizza market is moderately concentrated, with organized QSR chains and technology-enabled cloud kitchen brands leading market share while a large number of independent restaurants and regional players compete across local and regional markets. Network scale, supply chain depth, digital ordering capability, and brand recognition form the key competitive differentiators across the organized pizza industry.
| Company Name | Brand / Key Product | Position | Strategic Focus |
|---|---|---|---|
| Jubilant FoodWorks Limited | Domino's Pizza | Leader | Expanding store network across tier-2 and tier-3 cities while strengthening digital ordering and loyalty platforms |
| Rebel Foods Pvt. Ltd. | Oven Story Pizza | Challenger | Growing delivery-first pizza network through cloud kitchen model and digital platform integration |
| Copenhagen Hospitality Private Limited | La Pino'z Pizza | Challenger | Expanding organized pizza network in tier-2 and tier-3 cities through franchise model |
| Gourmet Investments Pvt. Ltd. | PizzaExpress | Challenger | Focusing on premium casual dining experience and menu differentiation to capture urban upscale consumers |
Key players include Jubilant FoodWorks Limited, Rebel Foods Pvt. Ltd., Copenhagen Hospitality Private Limited, and Gourmet Investments Pvt. Ltd., among others.
Key Company Profiles
Jubilant FoodWorks Limited
Jubilant FoodWorks Limited is an Indian food service company headquartered in Noida, Uttar Pradesh. It is the leading organized pizza chain operator in India by outlet count and revenue.
- Product Portfolio: Pizza, pasta, garlic bread, sides, desserts, and beverages under the Domino's Pizza brand across dine-in, takeaway, and delivery formats.
- Recent Developments: The company continues to invest in store network expansion, digital ordering infrastructure, and consumer engagement initiatives, with ongoing efforts to improve delivery efficiency and strengthen its loyalty program nationwide.
- Strategic Focus: Broadening its organized restaurant footprint across emerging urban markets while deepening consumer engagement through proprietary digital platforms, loyalty ecosystems, and delivery infrastructure upgrades.
Rebel Foods Pvt. Ltd.
Rebel Foods Pvt. Ltd. is an Indian cloud kitchen company that operates multiple food brands, including Oven Story Pizza, one of India's leading delivery-first pizza brands. The company runs a large network of cloud kitchens across cities in India.
- Product Portfolio: Delivery-focused pizza offerings under the Oven Story Pizza brand, featuring gourmet, premium, and value-oriented variants designed for online ordering and food delivery platforms.
- Recent Developments: Rebel Foods Pvt. Ltd. continues to strengthen its cloud kitchen operations and extend the Oven Story Pizza brand's reach through platform partnerships, direct digital channels, and ongoing product range development.
- Strategic Focus: Strengthening cloud kitchen density and delivery coverage to widen brand accessibility, while integrating deeper with digital ordering platforms to improve order volume and consumer retention.
Copenhagen Hospitality Private Limited
Copenhagen Hospitality Private Limited is the holding company behind La Pino'z Pizza. The brand is known for offering large-format, value-for-money pizzas through a franchise-driven model targeting tier-1, tier-2, and tier-3 cities across India.
- Product Portfolio: Wide range of vegetarian and non-vegetarian pizzas across multiple size formats, offered at competitive price points designed to serve value-seeking consumers across diverse urban and semi-urban markets.
- Recent Developments: The company continues to grow its franchise network and extend its organized pizza presence into new cities and geographies, supported by its value-oriented positioning and large pizza size proposition.
- Strategic Focus: Accelerating franchise-led geographic growth to bring organized pizza access to a wider base of consumers in smaller urban centers, leveraging competitive pricing and large-format value positioning as core brand differentiators.
Market Concentration Analysis
The India pizza market is moderately fragmented, with established international chains, domestic brands, and emerging cloud kitchen operators competing across dine-in, takeaway, and delivery channels.
Barriers to entry include high supply chain infrastructure costs, investment in food safety compliance systems, and competition from entrenched branded chains with well-established delivery networks and consumer loyalty ecosystems. These factors favor organized operators with proven franchise capabilities and scalable delivery infrastructure.
Consolidation is gradually increasing as cloud kitchen models lower capital requirements and enable new brand entries, while established chains continue to strengthen network coverage through franchising, platform acquisitions, and digital ecosystem investment. Strategic partnerships between organized chains and delivery aggregators are further shaping competitive positioning across the market.
Investment & Growth Opportunities
Fastest-Growing Segments
Vegetarian pizza is expanding faster as consumer awareness around health and wellness grows, supported by innovation in plant-based toppings and whole-grain crust variants. Stuffed crust is gaining significant momentum among indulgence-focused consumers.
Emerging Markets
East India represents the fastest-growing region, with expanding digital connectivity, growing food service investments, and rising participation from tier-2 cities in West Bengal, Odisha, and Jharkhand. The region represents significant untapped opportunity for organized pizza brands and cloud kitchen operators able to deliver localized, competitively priced pizza experiences.
Venture & Investment Trends
Investment activity in the India pizza market is concentrated in cloud kitchen platforms, digital ordering technology, and franchise expansion capital. Angel and venture funding is flowing into delivery-first pizza brands and technology-enabled food service models that combine operational cost efficiency with rapid scalability. Strategic investment is also directed toward supply chain technology, cold chain infrastructure, and consumer data platforms that support personalized pizza marketing.
Future Market Outlook (2026-2034)
The India pizza market is projected to grow from USD 5.81 Billion in 2025 to USD 6.33 Billion in 2026, reaching USD 12.49 Billion by 2034, registering a CAGR of 8.87% during 2026-2034.
Four forces will shape the market through 2034: continued expansion of organized QSR and cloud kitchen networks into tier-2 and tier-3 cities; premiumization of pizza menus targeting higher-income urban consumers; deepening of digital ordering, loyalty, and personalization platforms; and sustained penetration into India's rapidly urbanizing non-metro markets.
By 2034, the India pizza market is expected to reflect a more balanced mix of delivery-first and dine-in formats, with vegetarian, regional-flavored, and plant-based variants capturing a growing share of total consumption. Continued investment in supply chain infrastructure, brand differentiation, and digital consumer engagement will define long-term competitive positioning.
Research Methodology
Primary Research
Primary research included structured interviews with food service operators, franchise partners, supply chain specialists, and consumer behavior experts, validating market sizing, segment mix, and regional demand patterns across India's organized pizza industry.
Secondary Research
Secondary sources included industry association publications from the National Restaurant Association of India (NRAI), company annual reports and investor presentations, food delivery platform data, government food processing industry statistics from the Ministry of Food Processing Industries, and consumer survey data.
Forecasting Models
Market forecasts used top-down and bottom-up models combining organized outlet count growth rates, average revenue per unit trends, consumer demand surveys, delivery volume data, and macroeconomic indicators. Scenario analysis addressed premiumization pace, tier-2 expansion rates, and competitive landscape developments.
Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Types Covered | Non-Vegetarian Pizza, Vegetarian Pizza |
| Crust Types Covered | Thick Crust, Thin Crust, Stuffed Crust |
| Distribution Channels Covered | Quick Service Restaurants (QSR), Full-Service Restaurants (FSR), Others |
| Regions Covered | South India, North India, West & Central India, East India |
| Companies Covered | Jubilant FoodWorks Limited, Rebel Foods Pvt. Ltd., Copenhagen Hospitality Private Limited, Gourmet Investments Pvt. Ltd., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Frequently Asked Questions About the India Pizza Market Report
The India pizza market size is estimated at USD 6.33 Billion in 2026, driven by rising disposable incomes, rapid QSR chain expansion, and growing online food delivery adoption.
The market is projected to grow at a CAGR of 8.87% from 2026-2034, reaching USD 12.49 Billion, supported by cloud kitchen growth, premiumization, and expanding pizza penetration in tier-2 and tier-3 cities.
Non-vegetarian pizza leads the type segment at 56.0% in 2025, driven by strong consumer preference for chicken-topped variants including chicken tikka, barbeque chicken, and pepperoni across organized QSR chain menus.
Thick crust dominates with 48.0% share in 2025, reflecting its broad distribution through organized pizza chains and mainstream consumer preference for a substantial, filling eating experience.
South India commands 34.0% share in 2025, led by Bengaluru, Chennai, and Hyderabad, which host high densities of organized pizza outlets and a large, digitally connected young consumer base.
Leading players include Jubilant FoodWorks Limited, Rebel Foods Pvt. Ltd., Copenhagen Hospitality Private Limited, and Gourmet Investments Pvt. Ltd., among others.
Key drivers include rapid QSR chain expansion, a large youth population, rising disposable incomes, growing online food delivery adoption, and the proliferation of cloud kitchen brands offering delivery-first pizza at competitive price points.
Cloud kitchens are enabling new pizza brands to scale rapidly with lower capital requirements, expanding delivery-first pizza consumption in metro and tier-2 cities and increasing competition for organized dine-in pizza chains.
Premiumization is driving demand for gourmet, artisanal, and specialty pizza formats with premium ingredients, particularly among urban professionals in metro and tier-1 cities, expanding average transaction values for organized pizza operators.
Key opportunities include expansion into tier-2 and tier-3 cities, innovation in vegetarian and regional-flavored pizza variants, growth of delivery-first cloud kitchen brands, and investment in digital ordering and loyalty platform capabilities.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade