India Residential Energy Storage Market Size, Share, Trends and Forecast by Technology, Installation Type, End-User, and Region, 2026-2034
India Residential Energy Storage Market Size, Share, Trends & Forecast (2026-2034)
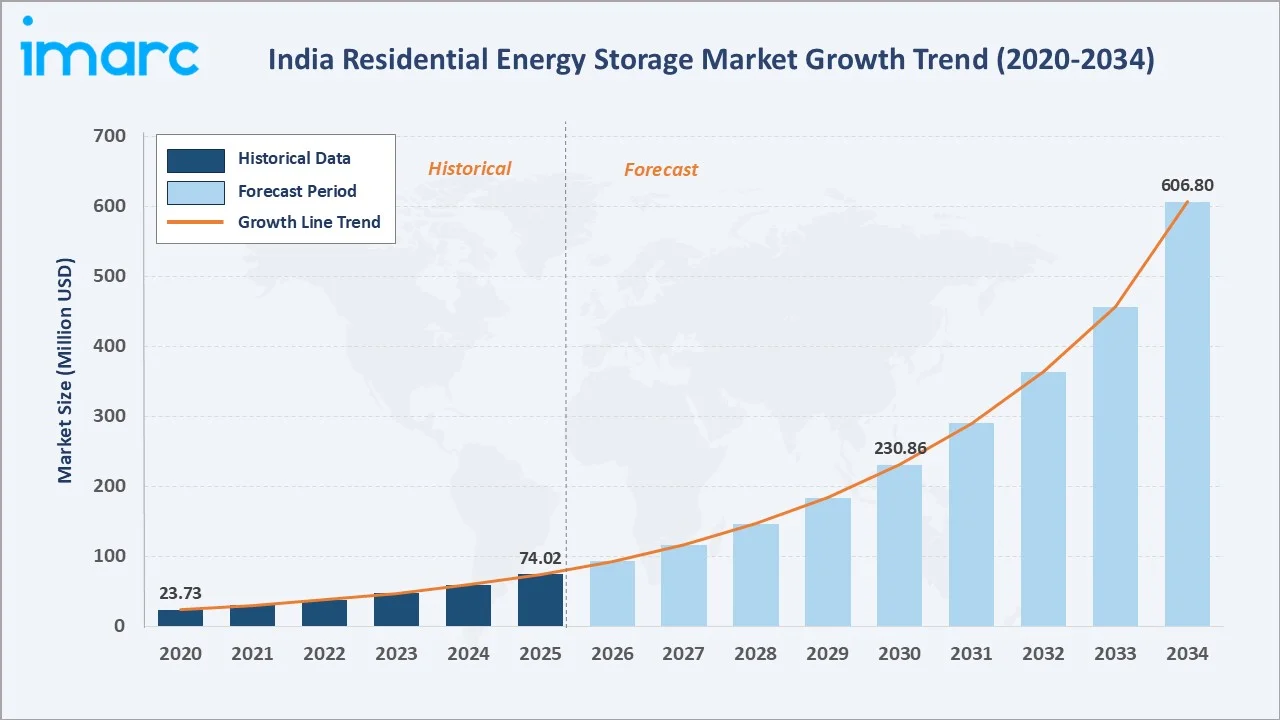
The India residential energy storage market size reached USD 74.02 Million in 2025 and is projected to reach USD 606.80 Million by 2034, exhibiting a growth rate (CAGR) of 25.54% during 2026-2034. The market is driven by rising energy demand, growing rooftop solar adoption, government incentives under PM-Surya Ghar, and advancements in lithium-ion battery technology.
Lithium-Ion Batteries dominate the technology segment at 62.5% in 2025, reflecting superior energy density and declining cell costs. Wall-Mounted systems lead installation type at 42.7%, supported by compact urban-fit design. West India leads regionally at 31.5%, anchored by Maharashtra and Gujarat's strong renewable energy policy environment and high rooftop solar penetration.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 74.02 Million |
|
Forecast Market Size (2034) |
USD 606.80 Million |
|
CAGR (2026-2034) |
25.54% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Technology |
Lithium-Ion Batteries (62.5%, 2025) |
|
Dominant Installation Type |
Wall-Mounted (42.7%, 2025) |
|
Leading Region |
West India (31.5%, 2025) |
The market expanded from an estimated USD 23.73 Million in 2020 to USD 74.02 Million in 2025, driven by post-pandemic solar adoption acceleration and rising household demand for energy independence. The market is anchored at an estimated USD 230.86 Million in 2030 and is forecast to reach USD 606.80 Million by 2034, with growth compounding as lithium-ion costs fall and policy incentives deepen.
To get more information on this market, Request Sample
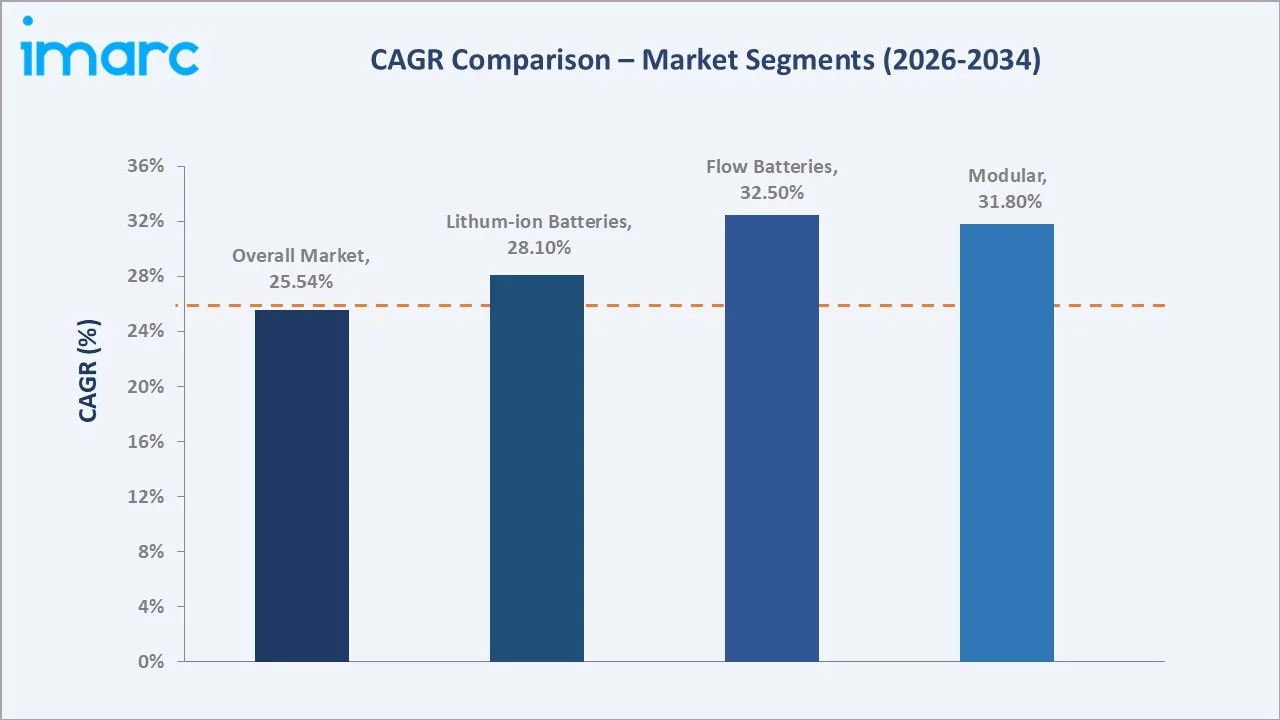
Lithium-Ion Batteries and Wall-Mounted installation systems are set to grow fastest through 2034, outpacing the overall CAGR of 25.54%. Flow Batteries and Modular installation types also record strong growth as scalable grid-interactive designs gain traction, while Lead-Acid Batteries grow more slowly as the market transitions toward advanced chemistry solutions.
Executive Summary
The India residential energy storage market reached USD 74.02 Million in 2025, representing one of Asia's fastest-growing residential storage markets, underpinned by rising solar rooftop installations, declining battery costs, and strong government policy support under the PM-Surya Ghar scheme. Energy storage in India performs a dual role of backup power and solar energy management across urban and rural households. The market is projected to reach USD 606.80 Million by 2034.
Lithium-Ion Batteries at 62.5% dominate by capturing the premium and mainstream residential segment with superior cycle life and declining costs. Wall-Mounted systems at 42.7% lead through compact urban-fit design suited to Indian apartments. West India at 31.5% leads nationally through Maharashtra and Gujarat's strong solar ecosystem and proactive state net-metering policy frameworks.
Key Market Insights
|
Insight |
Data |
|
Dominant Technology |
Lithium-Ion Batteries – 62.5% share (2025) |
|
Dominant Installation Type |
Wall-Mounted – 42.7% share (2025) |
|
Leading Region |
West India – 31.5% share (2025) |
|
Market Opportunity |
Grid-tied solar storage, V2G integration, modular plug-and-play, AI-enabled home energy management |
Key Analytical Observations Supporting the Above Data:
- Lithium-Ion Batteries at 62.5%: This segment dominates as falling cell costs and superior cycle life make lithium-ion the preferred choice for solar-paired residential storage. Government PLI schemes accelerating domestic cell manufacturing are further improving affordability and reliability, creating a self-reinforcing adoption dynamic across urban and semi-urban households.
- Wall-Mounted at 42.7%: Wall-mounted systems dominate due to space-efficient design optimised for Indian urban apartment housing. Integrated solar-plus-storage kits incorporating wall-mount batteries in the 5–15 kWh range are increasingly offered by leading manufacturers targeting the middle-income residential segment.
- West India at 31.5%: West India leads driven by Maharashtra's progressive solar net-metering policy and Gujarat's strong rooftop solar penetration among urban and semi-urban households, supported by proactive state distribution company frameworks and high consumer awareness of energy independence benefits.
India Residential Energy Storage Market Overview
The India residential energy storage market encompasses the design, manufacturing, and installation of battery storage systems for individual homes, including wall-mounted lithium-ion units, floor-standing lead-acid systems, modular expandable arrays, and sodium-based storage devices, all integrated with solar photovoltaic and grid connections across urban and rural households.
The ecosystem integrates cell and pack manufacturers, system integrators, inverter OEMs, EPC contractors, and retail distributors, all operating under BIS and IEC certification standards. Macroeconomic factors shaping the market include India's solar capacity additions under national schemes, electricity tariff levels, grid reliability standards, household income growth, and evolving net-metering regulations.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
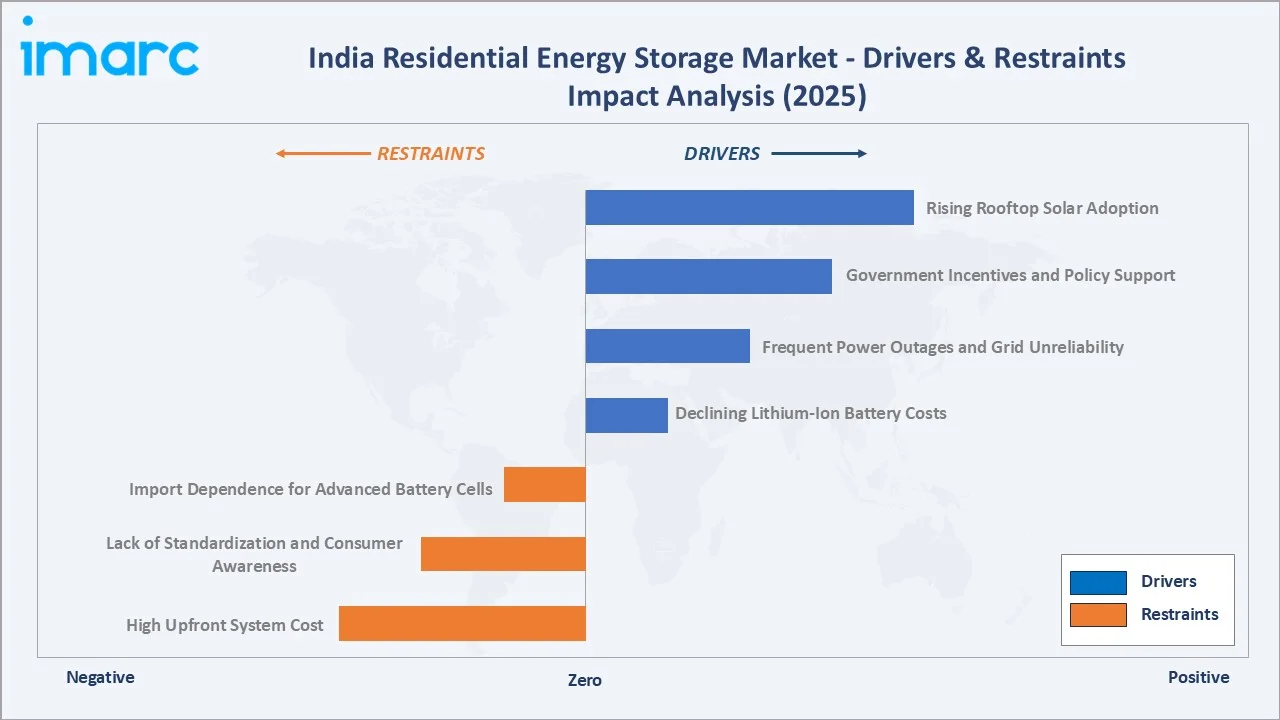
- Rising Rooftop Solar Adoption: Rapid growth in residential rooftop solar installations under the PM-Surya Ghar scheme is creating strong complementary demand for residential storage systems to store surplus solar energy. The scheme's target of one crore rooftop installations directly expands the addressable storage market by creating solar-owning households with a natural energy storage need. Leading banks and NBFCs increasingly support storage integration with rooftop solar through bundled financing.
- Government Incentives and Policy Support: Government initiatives promoting rooftop solar, battery storage, domestic cell manufacturing, and grid integration are supporting the adoption of residential energy storage systems in India. Policies, production-linked incentives for advanced battery manufacturing, and state-level net-metering frameworks are improving the economics of solar-plus-storage installations. These measures, combined with efforts to expand distributed renewable energy and reduce dependence on conventional grid power, are encouraging households to invest in energy storage solutions and supporting sustained market growth.
- Frequent Power Outages and Grid Unreliability: Persistent voltage fluctuations and load-shedding across tier-2 and tier-3 cities and rural India compel homeowners to invest in energy storage as a reliable backup solution. Unreliable grid supply in Uttar Pradesh, Bihar, Rajasthan, and parts of Maharashtra creates baseline storage demand independent of solar adoption. This backup demand provides a resilient market foundation even in states with lower solar penetration.
- Declining Lithium-Ion Battery Costs: Falling global lithium-ion cell prices, driven by Chinese manufacturing scale and domestic PLI-supported production, are substantially reducing residential system costs toward mass-market affordability. Cell prices have declined over 80% in the past decade and continue to fall, with LFP chemistry increasingly accessible to mid-income Indian households. Domestic gigafactories under development by Exide and Amara Raja are expected to further accelerate this cost reduction trajectory.
Market Restraints
- High Upfront System Cost: Despite declining cell prices, residential energy storage systems remain a significant capital expenditure for average Indian households, limiting penetration beyond upper-middle-income segments. A 10 kWh wall-mounted lithium-ion system typically costs INR 3–5 Lakh before subsidy, which remains prohibitive for a large segment of the addressable market. Accessible EMI financing and pay-as-you-save models are emerging but not yet mainstream, constraining adoption pace.
- Lack of Standardization and Consumer Awareness: Fragmented product standards, inconsistent quality benchmarks, and limited consumer education on system performance and warranty terms create purchasing hesitation. Households often struggle to evaluate competing chemistry claims, warranty duration, and cycle-life specifications, making them vulnerable to lower-quality imports at attractive price points. Greater standardization under BIS and public consumer education campaigns are needed to build systematic market trust.
- Import Dependence for Advanced Battery Cells: Domestic lithium-ion cell manufacturing remains nascent, keeping residential storage costs vulnerable to exchange rate fluctuations, import duties, and global supply chain disruptions. India currently imports the majority of lithium-ion cells from China and South Korea, exposing the market to geopolitical trade risk. Until PLI-supported gigafactories achieve meaningful production scale by 2027–2028, this structural dependence limits margin improvement for domestic system integrators.
Market Opportunities
- Integration with Electric Vehicle Charging: Growing household EV adoption is creating opportunities for combined home energy management systems that optimize solar generation, battery storage, and EV charging simultaneously. Vehicle-to-grid (V2G) technology is maturing, and early residential pilots are demonstrating the ability to use EV batteries as additional home storage. Manufacturers offering integrated solar, storage, and EV charging systems can capture premium pricing across the rapidly growing green-mobility consumer segment.
- Modular and Scalable Storage Solutions: Rising demand for plug-and-play modular systems that allow households to start with a single battery unit and expand capacity incrementally presents a significant product opportunity. Modular designs lower the entry-level system cost to INR 80,000–1.2 Lakh for a 2–3 kWh starter unit, expanding the addressable market to a much broader income segment. As energy needs and budgets grow, modular upgradeability creates long-term customer relationships and repeat revenue for manufacturers.
Market Challenges
- Regulatory Complexity: Varied state-level net-metering rules, grid interconnection standards, and subsidy disbursement timelines create market fragmentation and slow residential storage deployment across multiple jurisdictions. Installers operating across Maharashtra, Gujarat, Rajasthan, and Tamil Nadu must navigate materially different regulatory requirements, increasing compliance cost and deployment time. Harmonization of central net-metering standards would substantially reduce this friction and accelerate national market development.
- Competition from Diesel Generators: Entrenched diesel generator usage as backup power in many Indian homes and communities remains a cost-competitive alternative in areas with accessible diesel supply. A 3.5 kVA diesel generator has an upfront cost of INR 30,000–50,000, significantly below a comparable energy storage system, despite higher long-term fuel and maintenance costs. Bridging this perception gap through lifecycle cost communication and financing tools is a critical commercial challenge for storage market participants.
Emerging Market Trends
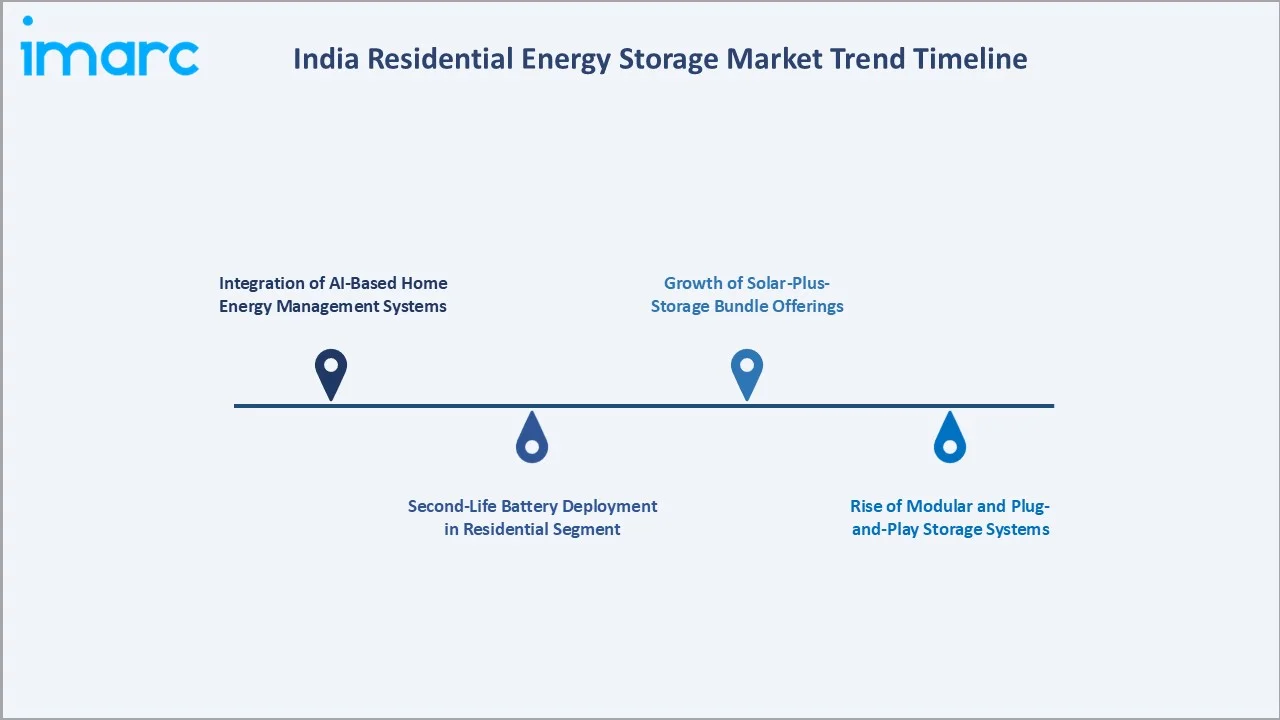
1. Integration of AI-Based Home Energy Management Systems
Manufacturers are embedding artificial intelligence and IoT connectivity into residential storage systems, enabling real-time optimization of solar generation, grid consumption, and battery dispatch. This shift toward smart energy management is reshaping product value propositions, with brands competing on software intelligence and connectivity features rather than hardware specifications alone.
2. Growth of Solar-Plus-Storage Bundle Offerings
Leading solar EPCs and battery brands are increasingly offering integrated solar-plus-storage bundles, simplifying the customer decision journey and enabling single-warranty coverage. Bundled offerings reduce installation complexity and provide a more compelling return-on-investment narrative that accelerates adoption across the urban middle-income segment.
3. Second-Life Battery Deployment in Residential Segment
Repurposing of retired electric vehicle battery packs for residential storage is an emerging cost-reduction strategy gaining early traction. Second-life LFP batteries offer 70–80% of original capacity at substantially lower cost, presenting a viable entry point for price-sensitive households as pilot programs expand among domestic battery manufacturers.
4. Rise of Modular and Plug-and-Play Storage Systems
Modular storage platforms allowing households to start with a small unit and expand capacity incrementally are gaining market acceptance. This design approach lowers entry-level cost, reduces upfront commitment, and aligns with India's diverse household income distribution, substantially expanding the addressable residential storage market.
Industry Value Chain Analysis
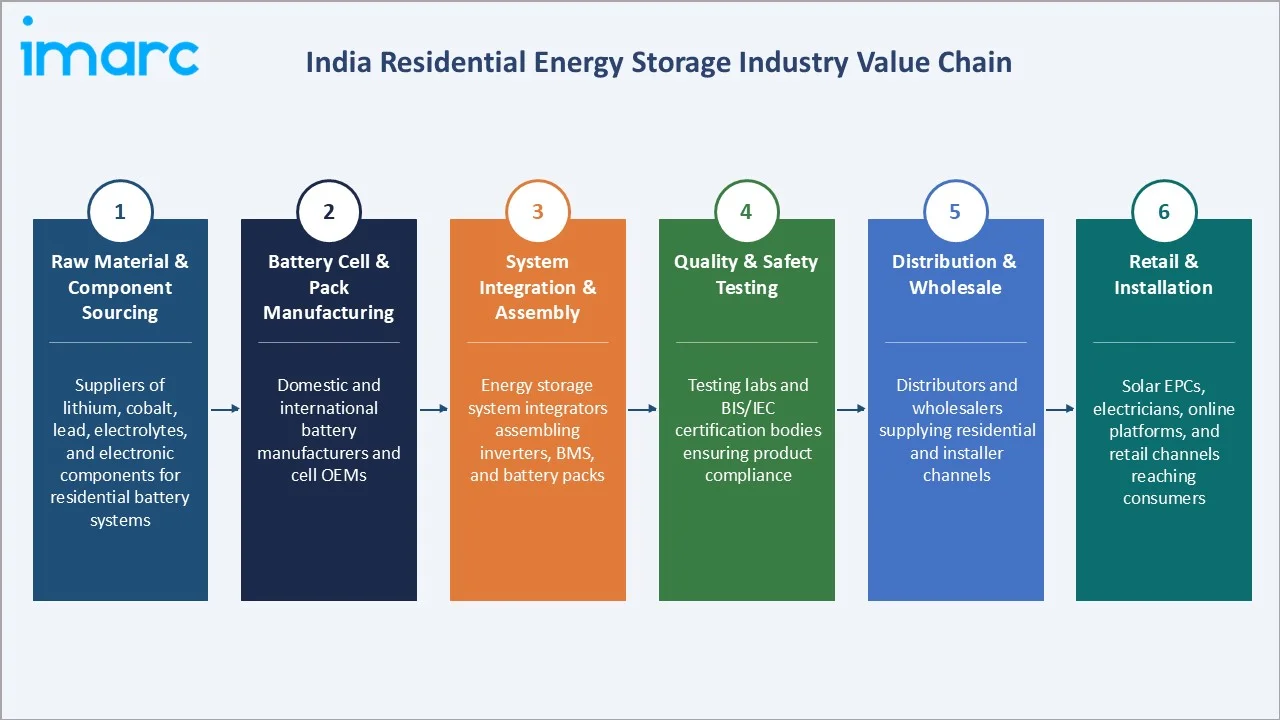
The India residential energy storage value chain spans raw material and cell sourcing, battery pack manufacturing, system integration, quality testing, distribution, and residential installation, with increasing emphasis on software and energy management capabilities at the integration and aftermarket stages.
|
Stage |
Key Participants |
|
Raw Material & Component Sourcing |
Suppliers of lithium, cobalt, lead, electrolytes, and electronic components |
|
Battery Cell & Pack Manufacturing |
Domestic and international battery manufacturers and cell OEMs |
|
System Integration & Assembly |
Energy storage system integrators assembling inverters, BMS, and battery packs |
|
Quality & Safety Testing |
Testing labs and BIS/IEC certification bodies ensuring product compliance |
|
Distribution & Wholesale |
Distributors and wholesalers supplying residential and installer channels |
|
Retail & Installation |
Solar EPCs, electricians, online platforms, and retail channels reaching consumers |
Battery cell and pack manufacturing represents the most capital-intensive and strategically critical stage, with domestic production capacity accelerated under PLI incentives. System integration and software are increasingly important value-add layers as home energy management systems differentiate premium offerings in the residential storage market.
Technology Landscape in the India Residential Energy Storage Industry
Lithium-Ion Battery Technology
Lithium iron phosphate (LFP) and NMC chemistry lithium-ion batteries are the dominant technology in India's residential storage market, prized for high cycle life exceeding 4,000 cycles, thermal stability, and compact energy density. Domestic PLI-supported cell manufacturing is progressively reducing LFP system costs toward grid parity with diesel backup alternatives for urban consumers.
Lead-Acid Battery Systems
Valve-regulated lead-acid (VRLA) and tubular lead-acid batteries retain a significant residential share, particularly in cost-sensitive rural and semi-urban applications where upfront cost is the primary purchase criterion. Their established supply chain, low initial cost, and BIS-certified domestic manufacturing maintain demand in off-grid and hybrid solar backup installations.
Flow Battery and Sodium-Based Storage
Vanadium redox flow batteries and sodium-ion storage technologies are at an early commercial stage in India's residential segment, favored for their long cycle life, safe chemistry profiles, and potential for low-cost domestic materials sourcing. Pilot installations are establishing performance benchmarks needed for broader residential adoption through the forecast period.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Technology |
Lithium-Ion Batteries |
62.5% |
2025 |
|
Installation Type |
Wall-Mounted |
42.7% |
2025 |
|
End-User |
🔒 |
🔒 |
2025 |
|
Region |
West India |
31.5% |
2025 |

By Technology
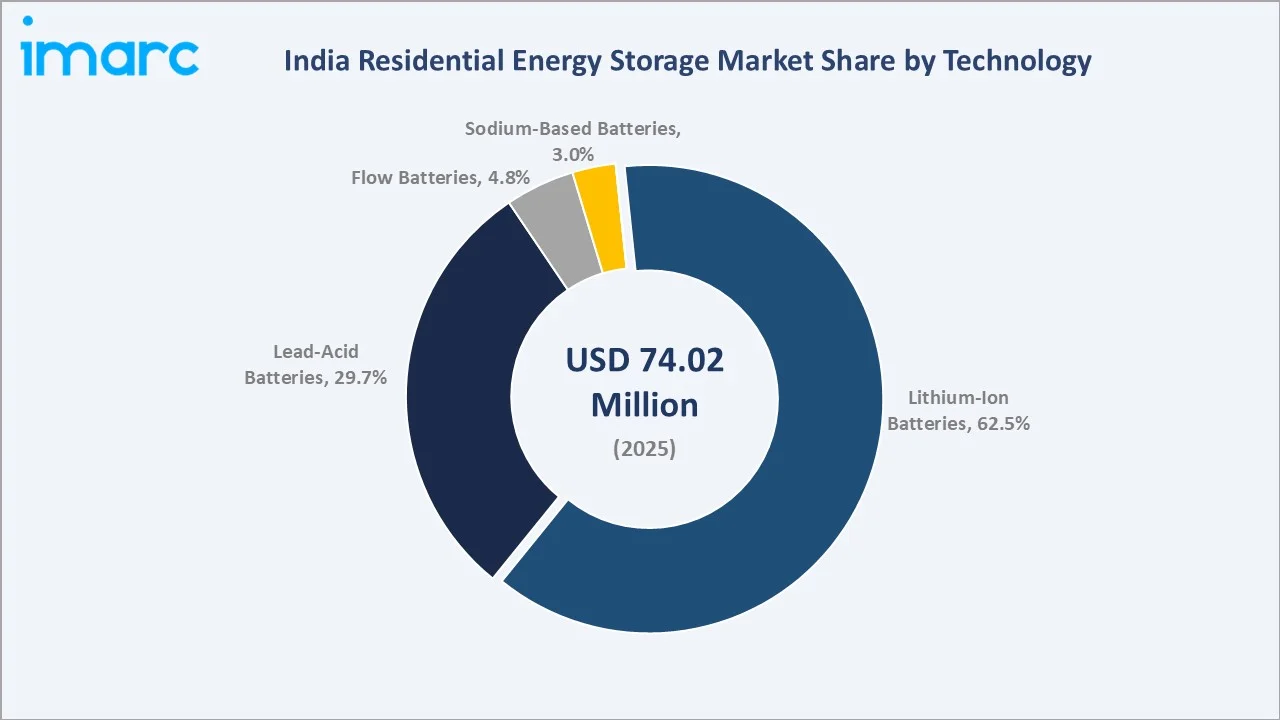
Lithium-Ion Batteries lead at 62.5% in 2025, encompassing the premium and mainstream residential storage segment. This segment's dominance reflects declining cell costs, superior cycle life, and strong brand investment by Exide Industries, Amara Raja Energy & Mobility, and Luminous Power Technologies in LFP residential product lines and solar-plus-storage bundles.
To access detailed market analysis, Request Sample
Lead-Acid Batteries follow at 29.7%, driven by established supply chains, low upfront cost, and entrenched distribution networks serving rural and off-grid residential markets. Flow Batteries hold 4.8% and Sodium-Based Batteries account for 3.0%, representing early-stage technologies gaining initial residential traction through pilot deployments.
By Installation Type
Wall-Mounted systems lead at 42.7% in 2025, supported by space-efficient design optimised for Indian urban apartments and compact residential layouts. Leading brands offer wall-mount lithium-ion units in the 5–15 kWh range designed for seamless integration with rooftop solar inverter systems at premium price points.
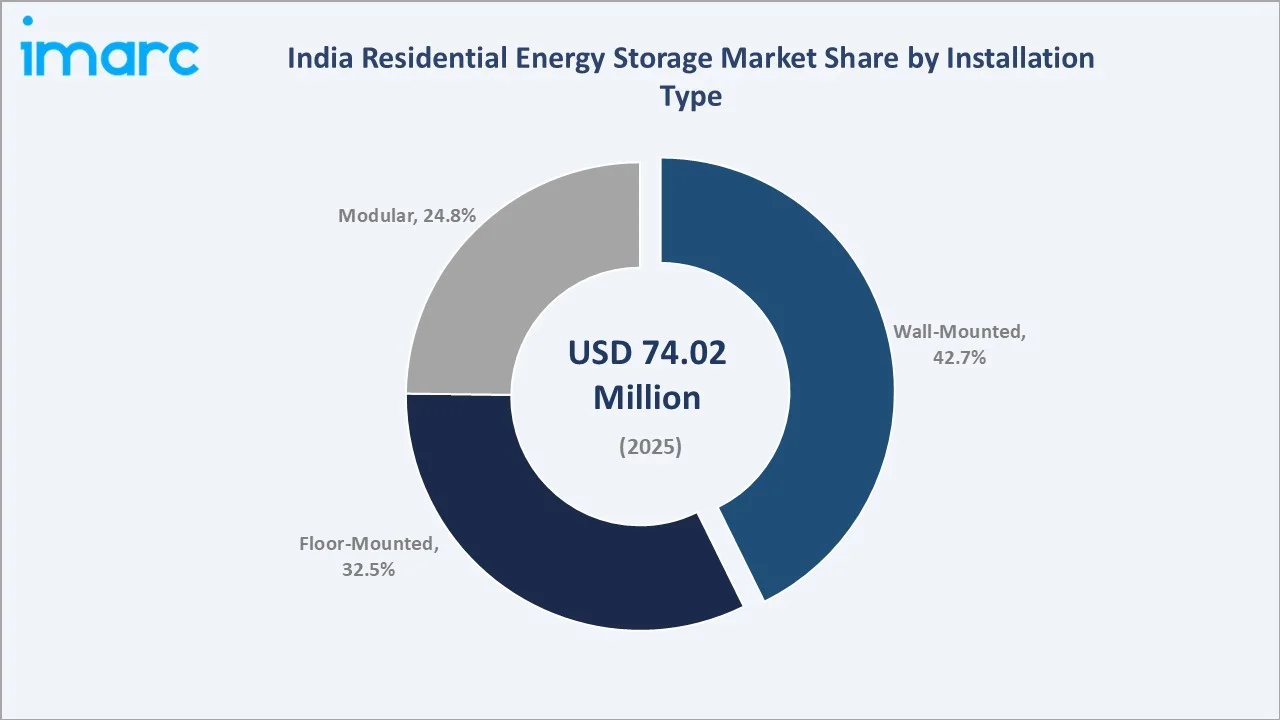
Floor-Mounted systems hold 32.5%, preferred for higher-capacity rural and semi-urban residential installations where floor space is available. Modular systems account for 24.8%, growing rapidly as scalable plug-and-play designs attract households seeking incremental capacity expansion aligned with growing solar installations.
Regional Market Insights
|
Region |
Share (2025) |
Key Characteristics |
|
West India |
31.5% |
Driven by Maharashtra and Gujarat solar policy leadership and high rooftop solar penetration among urban households |
|
North India |
28.7% |
Supported by frequent grid outages in UP, Rajasthan, and Bihar driving backup storage demand alongside rising solar adoption |
|
South India |
24.6% |
Anchored by Tamil Nadu and Karnataka renewable energy programs and growing EV adoption creating complementary storage demand |
|
East India |
15.2% |
Emerging growth region driven by rural electrification gaps, rising awareness, and state incentives for residential energy access |
West India, at 31.5%, leads through Maharashtra's progressive solar net-metering framework and Gujarat's high rooftop solar penetration among urban and semi-urban households. North India, at 28.7%, follows on frequent power outages in Uttar Pradesh, Rajasthan, and Bihar driving sustained backup storage demand.
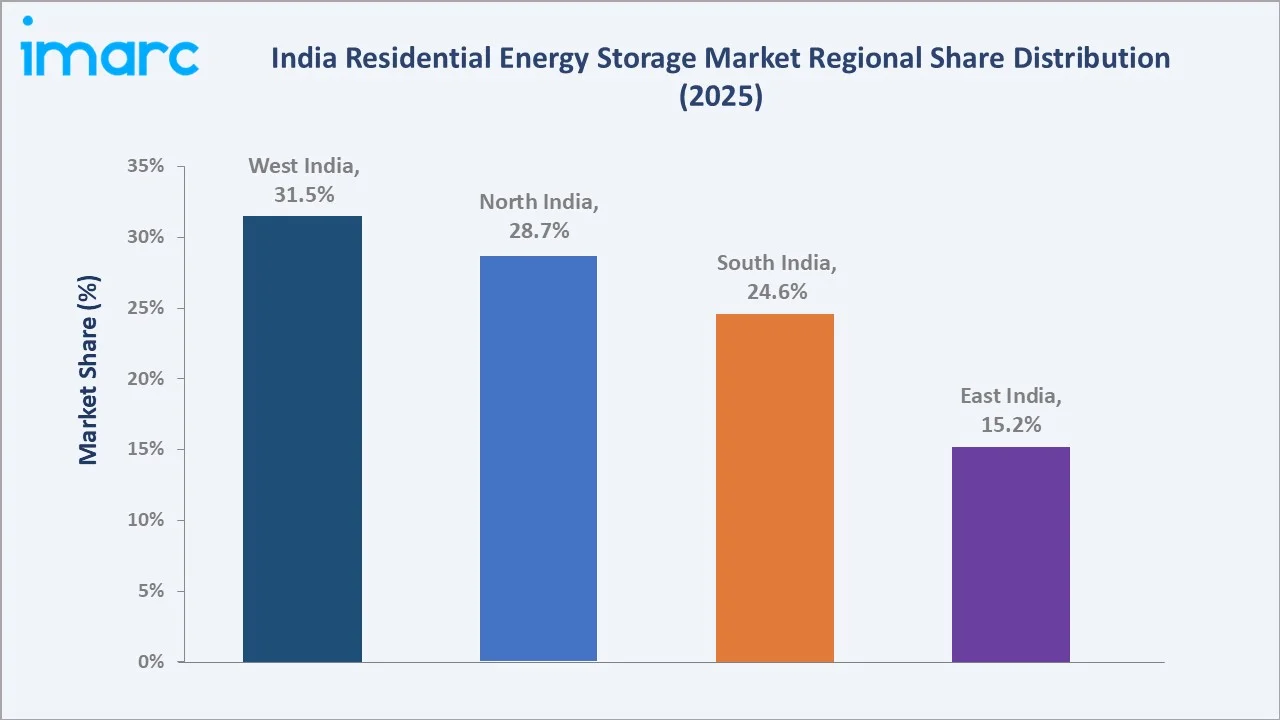
South India, at 24.6%, reflects Tamil Nadu and Karnataka's strong renewable energy programs and growing EV adoption generating complementary home-charging storage demand. East India, at 15.2%, is the emerging growth region with lowest current penetration, presenting significant long-term opportunity as rural electrification and household income growth expand the addressable storage consumer base.
Competitive Landscape
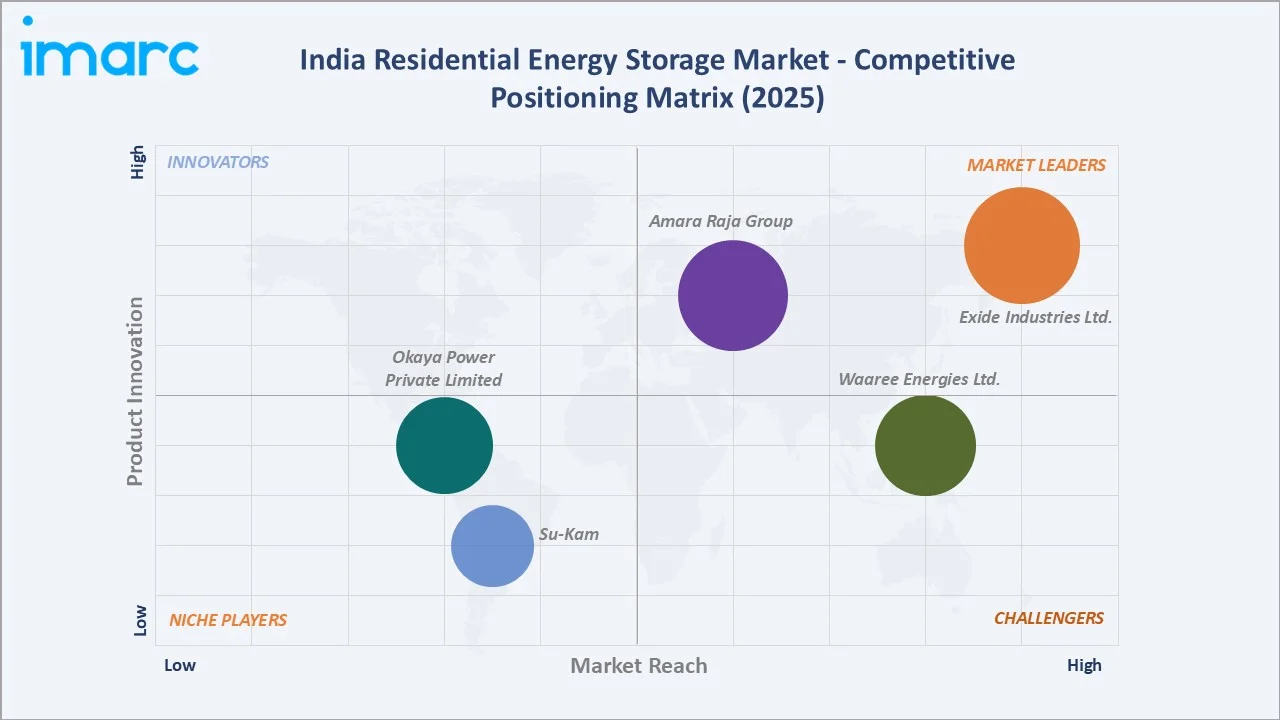
The India residential energy storage competitive landscape is highly dynamic, featuring domestic battery conglomerates transitioning from lead-acid to lithium-ion chemistry, solar-integrated storage specialists, and niche regional players. Competition centres on battery chemistry, system integration capability, price-performance ratio, installer network depth, and warranty terms.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
Exide Industries Ltd. |
Exide Solar, Exide EL VRLA, Exide Energy Solutions Li-Ion |
Market Leader |
Exide Industries leads through seven decades of battery manufacturing and pan-India BIS-certified distribution. |
|
Amara Raja Group |
Amaron Solar, Quanta VRLA, PowerStack BESS |
Market Leader |
Amara Raja combines lead-acid to lithium transition capability with a Gotion High-Tech LFP partnership. |
|
Waaree Energies Ltd. |
Waaree PowerSafe BESS, Solar+Storage kits |
Strong Challenger |
Waaree leverages India's largest solar module manufacturing position to offer integrated storage solutions. |
|
Okaya Power Private Limited |
Okaya Solar Flat Plate, Okaya Lithium batteries |
Niche Player |
Okaya anchors cost-competitive residential solar battery supply with strong North India distribution. |
|
Su-Kam |
Brainy Eco, Fusion+ Solar Inverter, Solar PCU |
Niche Player |
Su-Kam pioneered affordable solar home systems with PCU and battery combos for off-grid households. |
Key players include Exide Industries Ltd., Amara Raja Group, Waaree Energies Ltd., Okaya Power Private Limited, Su-Kam, and others.
Key Company Profiles
Exide Industries Ltd.
Exide Industries Ltd. is India's oldest and largest battery manufacturer, holding over seven decades of manufacturing expertise in lead-acid batteries and actively expanding into advanced lithium-ion solutions through its subsidiary Exide Energy Solutions Ltd., which is developing a 12 GWh greenfield LFP cell manufacturing facility supported by PLI incentives.
- Key Products: Exide Solar flat plate batteries, Exide EL VRLA batteries, Exide Energy Solutions lithium-ion residential packs.
- Strategic Focus: Exide is scaling lithium-ion cell manufacturing under the PLI scheme to reduce import dependence while capturing the growing residential solar-plus-storage market through its pan-India distribution network. The company is prioritising LFP chemistry development in partnership with SVOLT, targeting above-market growth in urban residential storage systems priced competitively against imported alternatives. Its established dealer and installer network of over 40,000 outlets provides an unmatched last-mile distribution advantage.
Amara Raja Group
Amara Raja Group, operating through its energy & mobility division, is India's second-largest battery manufacturer, known for its Amaron brand, with deep expertise in industrial lead-acid batteries and a strategic pivot toward advanced LFP chemistry through a technology partnership with China's Gotion High-Tech for gigafactory development under the national battery PLI programme.
- Key Products: Amaron Solar tubular batteries, Quanta VRLA residential batteries, PowerStack lithium-ion BESS.
- Strategic Focus: Amara Raja is accelerating its LFP residential storage product line with Gotion technology transfer, targeting the solar-paired storage segment as rooftop solar penetration deepens across West and South India. The company is investing in modular BESS formats suited to apartment-dwelling urban consumers, complementing its dominant position in the rural tubular battery market. Its manufacturing scale across Andhra Pradesh and Telangana enables cost-competitive residential pricing once domestic LFP cell production scales.
Market Concentration Analysis
The India residential energy storage market is fragmented at the system integration level but moderately concentrated at the battery manufacturing tier, with the key players jointly commanding leading shares of battery supply to residential channels. Market concentration is expected to consolidate progressively as PLI-supported domestic cell manufacturing scales and brand differentiation on software and energy management capabilities increases through the forecast period.
Investment & Growth Opportunities
Highest Growth Segments
Lithium-Ion Batteries (~28% CAGR) and Modular installation systems (~32% CAGR) represent the market's highest-growth investment vectors through 2034, outpacing the overall market CAGR of 25.54% as cost reduction accelerates mainstream adoption and scalable designs attract a broader residential consumer base across income segments.
Emerging Investment Opportunities
AI-enabled home energy management software, second-life EV battery repurposing for residential use, and solar-plus-storage bundle distribution represent the market's highest-value emerging opportunities. These segments benefit from India's rapidly expanding solar installation base and growing consumer appetite for integrated energy independence solutions.
Investment Themes
- Domestic Cell Manufacturing Capacity: Investment in PLI-supported LFP and NMC cell manufacturing offers a structural cost advantage and supply security premium as residential storage volumes scale toward USD 606.80 Million by 2034, positioning early investors favourably against import-dependent competitors.
- Tier-2 and Tier-3 City Distribution Expansion: Building installer and retail distribution networks in underserved tier-2 and tier-3 Indian cities captures the next adoption wave as system costs decline toward mass-market affordability and awareness of solar-plus-storage benefits deepens through government communication programmes.
Future Market Outlook (2026-2034)
The India residential energy storage market is projected to grow from USD 74.02 Million in 2025 to USD 606.80 Million by 2034, delivering a 25.54% CAGR over the forecast period. The market's anchor value of an estimated USD 230.86 Million in 2030 reflects a storage industry entering mainstream residential adoption as system costs cross affordability thresholds for the urban middle class across tier-1 and tier-2 cities.
Lithium-ion technology and modular installation formats are expected to achieve decisive market dominance by the end of the forecast period as PLI-driven domestic cell manufacturing substantially reduces system prices. Three structural forces will define market growth through 2034: the compounding strength of India's rooftop solar ecosystem, continued government policy support for residential storage integration, and rising household income enabling storage investment across a progressively broader demographic.
Research Methodology
Primary Research
Primary research comprised structured interviews with residential energy storage installers, battery manufacturers, solar EPC contractors, distribution channel partners, and state energy policy representatives, providing first-hand insight into demand trends, pricing dynamics, and competitive positioning across India's four regional markets.
Secondary Research
Secondary research encompassed company annual reports, MNRE solar capacity data, BIS certification records, PLI scheme disclosures, state net-metering policy documents, and industry publications, cross-verified across multiple independent sources to ensure data reliability and regional market coverage.
Forecasting Models
Market revenue forecasts were developed using a bottom-up demand model incorporating India's state-level rooftop solar capacity additions, battery system cost reduction curves derived from international benchmarks, household income distribution by segment, and policy incentive timelines under the PM-Surya Ghar programme and PLI battery scheme.
India Residential Energy Storage Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Technologies Covered | Lithium-Ion Batteries, Lead-Acid Batteries, Flow Batteries, Sodium-Based Batteries |
| Installation Types Covered | Wall-Mounted, Floor-Mounted, Modular |
| End- Users Covered | Single-Family Homes, Multi-Family Homes |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Exide Industries Ltd., Amara Raja Group, Waaree Energies Ltd., Okaya Power Private Limited, Su-Kam, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India residential energy storage market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India residential energy storage market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India residential energy storage industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Residential Energy Storage Market Report
The India residential energy storage market reached USD 74.02 Million in 2025, driven by Lithium-Ion Batteries dominating at 62.5%, Wall-Mounted systems leading at 42.7%, strong rooftop solar adoption under the PM-Surya Ghar scheme, and government incentives expanding the addressable consumer base.
The India residential energy storage market grows at a 25.54% CAGR during 2026-2034, reaching USD 606.80 Million by 2034. This growth reflects accelerating lithium-ion cost reduction, expanding rooftop solar installations, and deepening government support for residential energy independence.
Lithium-Ion Batteries lead at 62.5% in 2025, capturing the mainstream residential segment through superior cycle life and declining costs. This segment grows at an above-market CAGR driven by PLI-supported domestic manufacturing and solar-plus-storage bundling by leading brands including Exide, Amara Raja, and Luminous.
Wall-Mounted systems lead at 42.7%, preferred for space-efficient design suited to urban Indian apartments. Wall-mounted lithium-ion units in the 5–15 kWh range are the primary product format offered by leading manufacturers targeting the urban middle-income residential segment with solar-integrated storage solutions.
West India leads at 31.5% through Maharashtra and Gujarat's strong solar ecosystem, proactive net-metering policies, and high rooftop solar penetration among urban households, alongside strong secondary contribution from North India at 28.7%, which benefits from persistent grid reliability challenges.
Leading companies include Exide Industries Ltd., Amara Raja Group, Waaree Energies Ltd., Okaya Power Private Limited, Su-Kam, and others.
The India residential energy storage market is projected to reach approximately USD 230.86 Million by 2030, with lithium-ion and modular segment growth outpacing the overall market as domestic cell manufacturing scales and residential solar penetration deepens across tier-1 and tier-2 Indian cities.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade