India Sanitary Ware Market Size, Share, Trends and Forecast by Material, Type, Application, End User, and Region, 2026-2034
India Sanitary Ware Market Size, Share, Trends & Forecast (2026-2034)
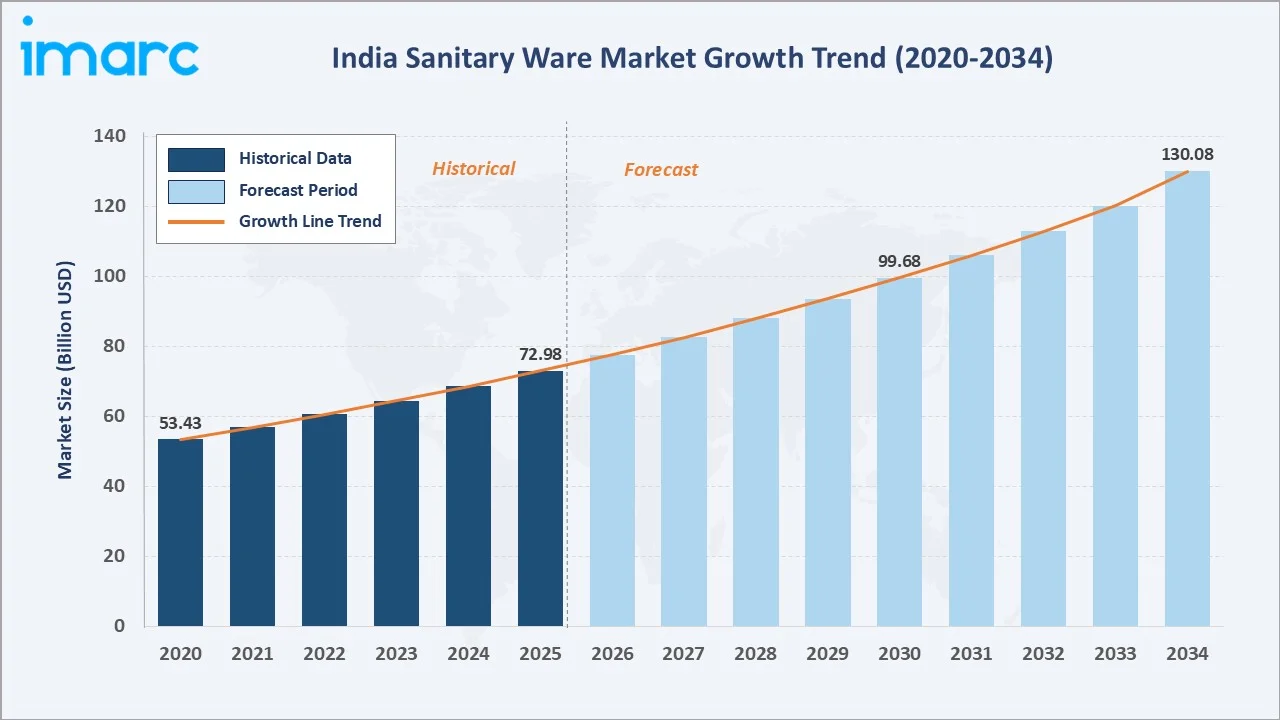
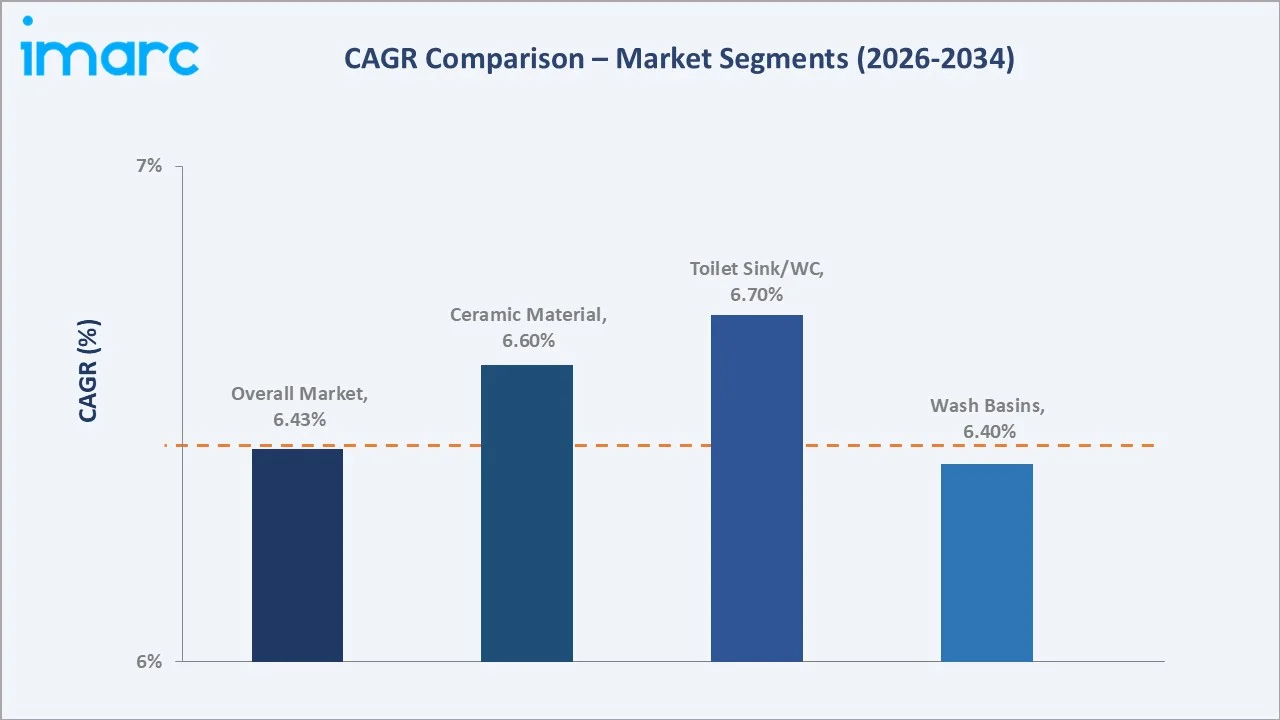
The India sanitary ware market size reached USD 72.98 Billion in 2025. The market is projected to reach USD 130.08 Billion by 2034, exhibiting a CAGR of 6.43% during 2026-2034. The sanitaryware market in India is driven by rapid urbanization, rising disposable incomes, government sanitation programs (Swachh Bharat Mission, PMAY), real estate expansion, and growing preference for premium and smart bathroom solutions. Ceramic dominates at 88.5%, Toilet Sink/Water Closet leads at 37.5%, and West India commands 32.5% regional share.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 72.98 Billion |
|
Forecast Market Size (2034) |
USD 130.08 Billion |
|
CAGR (2026-2034) |
6.43% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Material |
Ceramic (88.5%, 2025) |
|
Dominant Type |
Toilet Sink/Water Closet (37.5%, 2025) |
|
Leading Region |
West India (32.5%, 2025) |
The sanitaryware market size in India expanded from USD 53.43 Billion in 2020 to USD 72.98 Billion in 2025, anchored at USD 99.68 Billion in 2030, and forecast to reach USD 130.08 Billion by 2034. This steady trajectory reflects structural urbanization, government sanitation mandates, and growing aspirational consumption driving sustained demand across residential, commercial, and institutional segments throughout the period.
To get more information on this market, Request Sample
Ceramic material dominates at 88.5%, driven by durability, hygiene properties, and wide consumer acceptance across all price segments. The Toilet Sink/Water Closet type leads at 37.5%, reflecting essential product demand across both residential and commercial construction, significantly amplified by government toilet infrastructure programs at national scale.
Executive Summary
The India sanitary ware market reached USD 72.98 Billion in 2025, representing one of the construction sector's most consistently growing verticals, driven by structural urbanization and government-mandated sanitation improvements across urban and rural India. The market is projected to reach USD 130.08 Billion by 2034.
Ceramic at 88.5% dominates through superior durability, hygiene, aesthetic versatility, and cost-competitive manufacturing. Toilet Sink/Water Closet at 37.5% leads as the most essential and universally demanded product category. West India at 32.5% leads through Mumbai's premium real estate, Gujarat's industrial growth, and Pune's expanding residential market driven by IT-sector workforce housing demand.
Key Market Insights
|
Insight |
Data |
|
Dominant Material |
Ceramic – 88.5% share (2025) |
|
Dominant Type |
Toilet Sink/Water Closet – 37.5% market share (2025) |
|
Leading Region |
West India – 32.5% market share (2025) |
|
Market Opportunity |
Smart bathrooms, water-efficient fixtures, premium branded products, and Tier 2/3 city penetration |
Key Analytical Observations Supporting the Above Data:
- Ceramic at 88.5%: Ceramic dominates as the preferred material due to its superior durability, ease of cleaning, non-porous surface, and heat resistance. Manufacturing cost advantage over premium alternatives supports accessibility across all price segments in India's highly price-sensitive and volume-driven market environment.
- Toilet Sink/Water Closet at 37.5%: The water closet segment leads because it constitutes an essential product in every household, institutional, and commercial facility. Government mandates under Swachh Bharat Mission and PMAY have driven mass adoption across urban and rural India at historically unprecedented installation volumes.
- West India at 32.5%: The western region leads through Mumbai's premium real estate market, Gujarat's industrial and residential growth corridors, and Pune's expanding IT-sector housing demand, complemented by Maharashtra's large hotel and hospitality construction pipeline.
India Sanitary Ware Market Overview
The India sanitary ware market encompasses the design, manufacture, supply, and installation of all ceramic and non-ceramic plumbing fixtures used in residential, commercial, and institutional bathroom and kitchen settings, including water closets, wash basins, cisterns, pedestals, and related accessories across all quality and price tiers.
The ecosystem integrates raw material suppliers, domestic and international manufacturers, distributor and dealer networks, branded retail experience centers, installation contractors, and government regulatory bodies enforcing BIS product standards. Macroeconomic factors include urbanization cycles, housing construction activity, disposable income growth, hospitality industry expansion, and government sanitation investment at national and state levels.
Market Dynamics
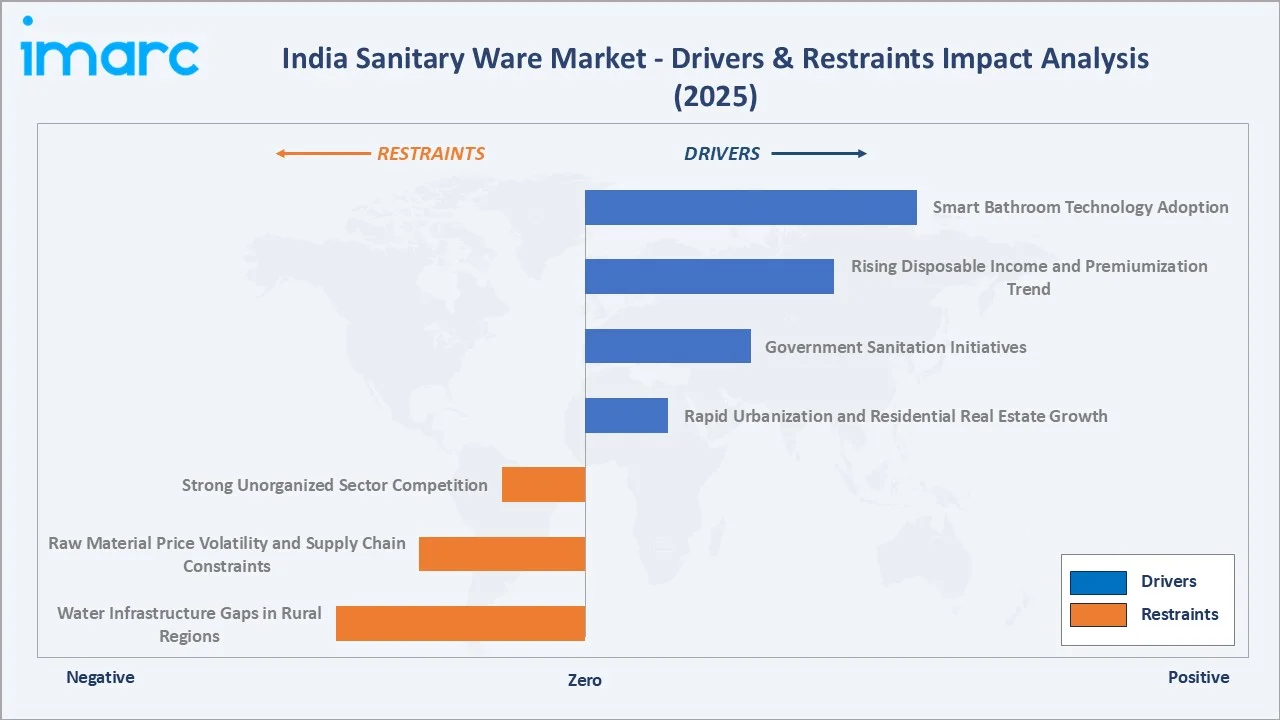
To evaluate market opportunities, Request Sample
Market Drivers
- Rapid Urbanization and Residential Real Estate Growth: India's continuing urbanization and expansion of residential construction are supporting sustained demand for sanitary ware and modern bathroom infrastructure. The development of new housing, particularly in emerging urban centers and Tier 2 and Tier 3 cities, is creating additional demand across economy, mid-range, and premium product segments. Rising homeownership and increasing spending on bathroom renovation and upgrades are also expanding the market beyond major metropolitan areas.
- Government Sanitation Initiatives: Government-led sanitation and urban infrastructure programs are contributing to demand for sanitary ware across residential, institutional, and public facilities. Initiatives such as the Swachh Bharat Mission, AMRUT 2.0, and Jal Jeevan Mission continue to support investments in sanitation, water supply, and related infrastructure. These programs are also creating opportunities for organized sanitary ware manufacturers as improving sanitation standards encourage greater adoption of durable and standardized products.
- Rising Disposable Income and Premiumization Trend: Growth in household incomes and the expansion of India's middle- and upper-income consumer base are encouraging greater spending on bathroom products. Consumers, particularly in urban areas, are increasingly seeking products with improved aesthetics, functionality, durability, and brand recognition. This shift toward premium and branded sanitary ware is creating opportunities for domestic and international manufacturers while gradually positioning bathroom products as an element of home design and lifestyle.
- Smart Bathroom Technology Adoption: Growing interest in smart-home solutions is supporting the adoption of technology-enabled bathroom products, including sensor-based faucets, touchless flushing systems, intelligent toilets, and water-monitoring solutions. Adoption is currently more prominent in premium residential properties, hotels, and other high-end applications, where consumers and businesses place greater emphasis on convenience, hygiene, water efficiency, and automation. The integration of connected technologies with sanitary ware is therefore creating new opportunities for manufacturers to differentiate their products and expand into higher-value segments.
Market Restraints
- Strong Unorganized Sector Competition: The unorganized sector manufactures lower-cost sanitaryware using conventional technologies, catering to mass-market and low-income consumer segments. This limits pricing power for organized players in volume tiers and restricts market penetration into rural and semi-urban areas where price sensitivity remains the dominant purchasing criterion. Unorganized manufacturers benefit from lower overhead costs, minimal regulatory compliance burden, and established local distributor relationships that allow them to undercut organized brands on price, particularly in markets where brand awareness remains limited.
- Raw Material Price Volatility and Supply Chain Constraints: Ceramic sanitaryware manufacturing depends on kaolin, feldspar, quartz, and silica, subject to domestic mining policy changes and pricing volatility. Import dependency for premium glazes, colorants, and specialized components from Italy and China introduces supply chain risks and margin pressure. Global commodity price fluctuations and currency exchange rate movements affect the landed cost of imported inputs, making cost planning difficult for manufacturers and creating periodic margin compression that limits capacity investment decisions by mid-sized producers.
- Water Infrastructure Gaps in Rural Regions: Inadequate water infrastructure in rural and semi-urban India limits adoption of sanitary products requiring consistent water supply. Regions with intermittent access have lower upgrade rates for modern fixtures, constraining geographic expansion potential despite government sanitation program penetration across these areas. The mismatch between toilet construction mandates under Swachh Bharat Mission and actual water availability in some rural areas creates situations where installed sanitary products remain underutilized, slowing repeat purchase cycles and reducing effective market demand in affected regions.
Market Opportunities
- Smart and Water-Efficient Fixture Innovation: Rising water conservation awareness and green building certification requirements are creating strong demand for dual-flush systems, sensor faucets, and IoT-enabled water monitors. Manufacturers offering certified water-efficient products benefit from government procurement preferences and premium consumer willingness-to-pay. The growing adoption of GRIHA and LEED green building certifications by commercial developers is creating a structured specification channel for water-saving sanitary products, enabling manufacturers with certified product portfolios to access high-value institutional procurement at scale.
- Tier 2 and Tier 3 City Market Penetration: India's fast-growing Tier 2 and Tier 3 cities represent significant untapped demand for branded sanitary ware, driven by rising disposable incomes, new residential construction, and aspirational consumption patterns among upwardly mobile urban households seeking differentiated bathroom products. E-commerce platform expansion and improved logistics infrastructure are enabling branded sanitary ware companies to reach consumers in secondary cities without the capital-intensive investment of opening physical retail stores, dramatically lowering the cost of geographic market expansion.
Market Challenges
- Intense Price Competition and Margin Compression: The coexistence of organized premium players, mid-segment brands, and a large unorganized sector creates intense price competition across the market. Cost pressure from imported Chinese sanitaryware limits margin expansion for domestic manufacturers in high-volume, price-sensitive market segments. Organized manufacturers face the dual challenge of defending mid-market share against unorganized competitors on price and simultaneously investing in premium product development to compete with global brands entering the Indian luxury segment, stretching marketing and development resources simultaneously.
- Skilled Installation Workforce Shortage: The shortage of trained plumbers and sanitaryware installation professionals, particularly for smart and premium products, creates an installation quality gap that affects consumer satisfaction and brand perception. Lack of standardized certification for installation personnel remains a market-level structural challenge. Consumer complaints arising from improper installation of premium sanitary products negatively impact brand reputation and after-sales service costs for manufacturers, diverting resources from growth investments toward warranty and service operations across dealer networks.
Emerging Market Trends
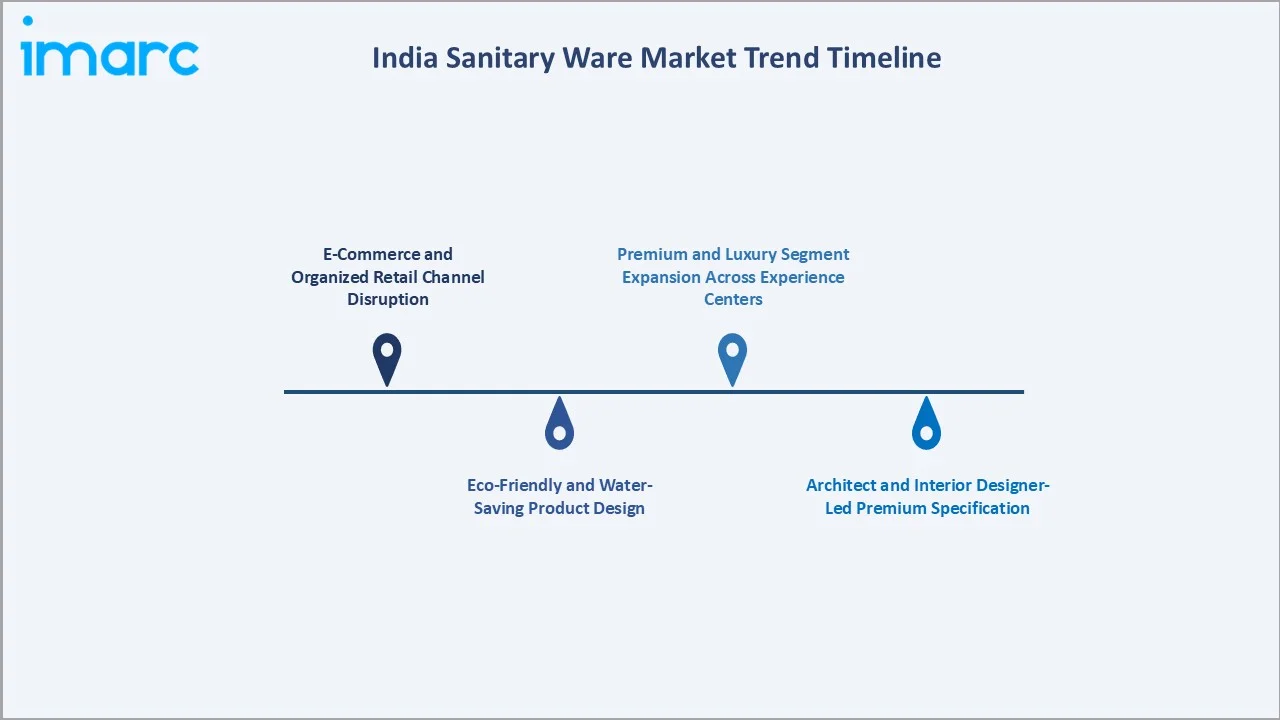
1. Premium and Luxury Segment Expansion Across Experience Centers
Leading brands including Kohler, Duravit, Jaquar, and Hansgrohe are aggressively expanding branded experience centers in Indian cities. These centers transform the consumer journey by enabling tactile product evaluation and design consultation, increasing conversion rates and average transaction values for premium products. The growing influence of interior designers in bathroom specification further accelerates adoption of premium branded lines across high-value residential projects.
2. E-Commerce and Organized Retail Channel Disruption
E-commerce platforms are reshaping sanitaryware distribution by enabling consumers in Tier 2 and Tier 3 cities to access branded products previously unavailable locally. Organized retailers and direct-to-consumer brand platforms are supplementing the traditional dealer-contractor channel, improving market reach, and increasing consumer price transparency across all sanitary ware product categories nationally.
3. Eco-Friendly and Water-Saving Product Design
Dual-flush systems, rimless toilet bowl technology, and water-efficient faucet designs are becoming standard specifications in new residential and commercial projects. This shift is driven by green building standards, sustainability-focused procurement policies, and growing water conservation awareness among urban consumers and institutional buyers procuring sanitaryware at scale.
4. Architect and Interior Designer-Led Premium Specification
The growing influence of architects and interior designers in bathroom specification is elevating premium brand adoption. Brands investing in design community engagement, product sample programs, and project support services are gaining disproportionate share in high-value residential and hospitality projects, reshaping the distribution mix toward specification-led channels.
Industry Value Chain Analysis
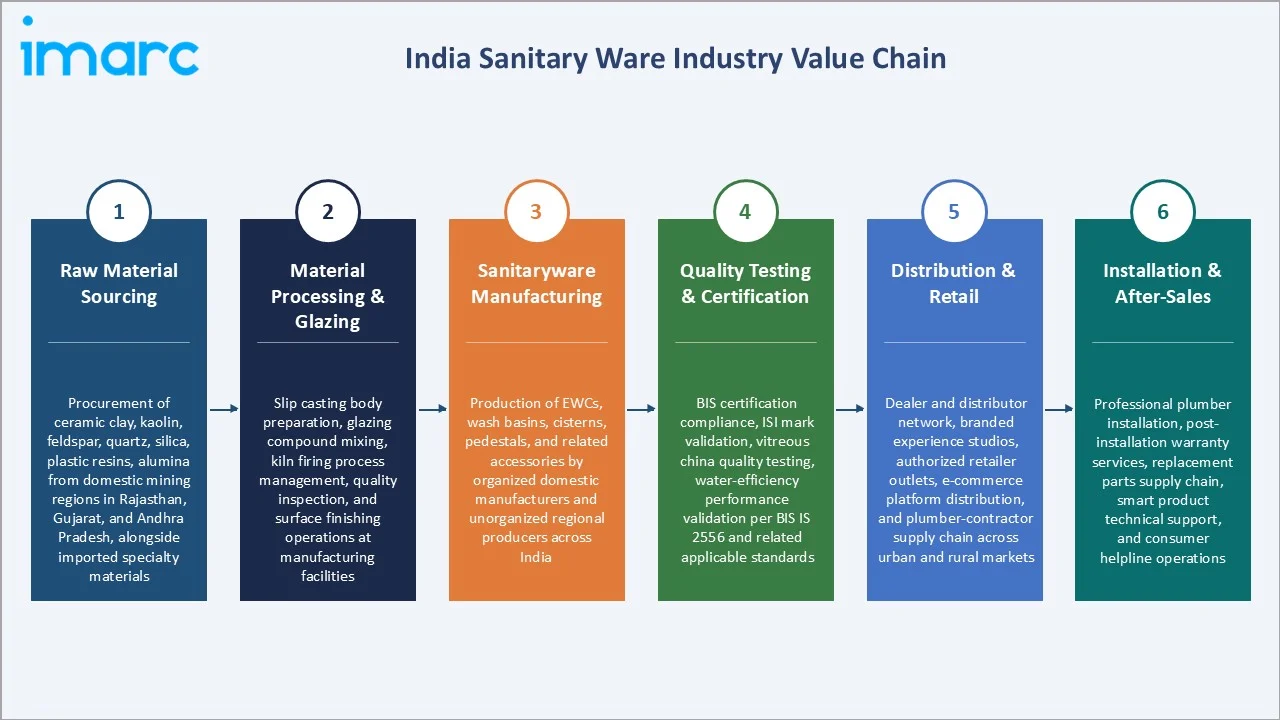
The India sanitary ware industry value chain integrates raw material mining and processing, ceramic body preparation and slip casting, kiln firing and glazing, quality testing and BIS certification, branded product distribution through dealer and retail channels, professional installation, and comprehensive after-sales service delivery.
|
Stage |
Key Participants & Activities |
|
Raw Material Sourcing |
Procurement of ceramic clay, kaolin, feldspar, quartz, silica, plastic resins, alumina from domestic mining regions in Rajasthan, Gujarat, and Andhra Pradesh, alongside imported specialty materials |
|
Material Processing & Glazing |
Slip casting body preparation, glazing compound mixing, kiln firing process management, quality inspection, and surface finishing operations at manufacturing facilities |
|
Sanitaryware Manufacturing |
Production of EWCs, wash basins, cisterns, pedestals, and related accessories by organized domestic manufacturers and unorganized regional producers across India |
|
Quality Testing & Certification |
BIS certification compliance, ISI mark validation, vitreous china quality testing, water-efficiency performance validation per BIS IS 2556 and related applicable standards |
|
Distribution & Retail |
Dealer and distributor network, branded experience studios, authorized retailer outlets, e-commerce platform distribution, and plumber-contractor supply chain across urban and rural markets |
|
Installation & After-Sales |
Professional plumber installation, post-installation warranty services, replacement parts supply chain, smart product technical support, and consumer helpline operations |
Technology Landscape in the India Sanitary Ware Industry
Vitreous China Manufacturing Technology
Vitreous china manufacturing using high-temperature kiln firing, advanced slip casting, and automated glazing lines remains the dominant production technology. Leading manufacturers including Cera, HSIL, and Parryware have invested in capacity upgrades to improve production efficiency, surface quality consistency, and dimensional accuracy across large-volume product batches.
Rimless Toilet Bowl Technology
Rimless toilet bowl designs eliminate the traditional rim to improve hygiene, reduce bacterial buildup, and enable more effective flushing with lower water consumption. This technology is gaining rapid acceptance in premium and mid-premium segments, with Cera's Senator Rimless and Kohler's advanced flush systems leading commercial adoption across organized retail channels.
Smart Sensor and IoT Bathroom Technology
Sensor-based faucets, touchless flush systems, smart shower controls, and IoT-enabled water consumption monitoring define the technology frontier of the Indian market. Smart bathroom product adoption is growing fastest in luxury residential, five-star hospitality, and premium corporate office fitout segments across India's major metropolitan centers.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Material |
Ceramic |
88.5% |
2025 |
|
Type |
Toilet Sink/Water Closet |
37.5% |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
End User |
🔒 |
🔒 |
2025 |
|
Region |
West India |
32.5% |
2025 |

By Material
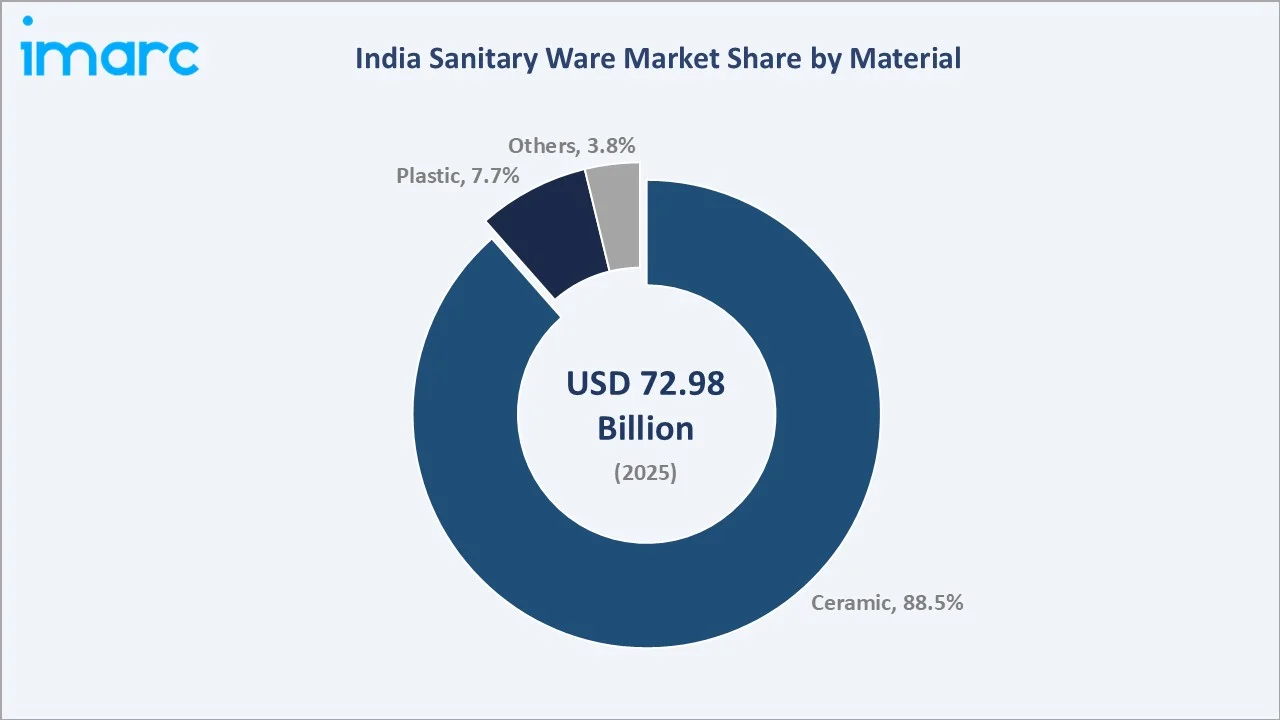
Ceramic dominates the sanitaryware market in India at 88.5% in 2025, capturing the mainstream market across all residential, commercial, and institutional segments. Ceramic's dominance reflects its superior durability, hygiene, aesthetic versatility, and cost-competitive manufacturing economics relative to plastic and specialty alternative materials.
To access detailed market analysis, Request Sample
Plastic at 7.7% serves the lower-price segment and specific product categories like cisterns and cistern components where lightweight properties offer manufacturing advantages. Others at 3.8% include stone resin, acrylic, stainless steel, and composite materials, primarily used in high-design premium applications targeting luxury residential and hospitality interior design specifications.
By Type
Toilet Sink/Water Closet leads at 37.5% in 2025, representing the most essential and universally demanded product category. WC demand is further amplified by government toilet construction mandates under Swachh Bharat Mission and PMAY housing programs driving mass installation across urban and semi-urban India at volume levels not seen in prior decades.
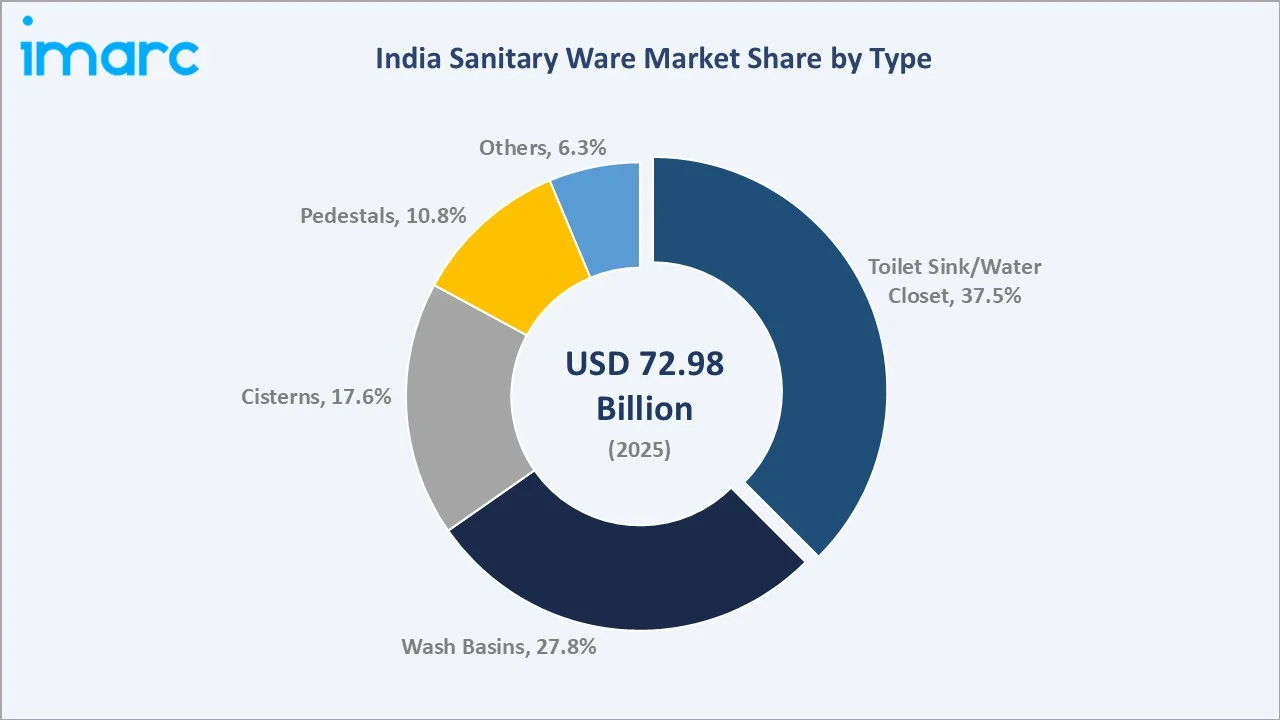
Wash Basins at 27.8% represent the second-largest type, driven by residential bathroom upgrades and commercial facility installations in offices, hotels, hospitals, and educational institutions. Cisterns at 17.6% follow, constituting an essential component of WC installations. Pedestals at 10.8% and Others at 6.3% serve specific installation format and designer specification preferences.
Regional Market Insights
|
Region |
Share (2025) |
Key Market Drivers & Characteristics |
|
West India |
32.5% |
Driven by strong real estate activity, premium demand from metropolitan markets, and significant hospitality construction across the region |
|
North India |
28.7% |
Supported by government housing schemes, rapid residential development, and large-scale national sanitation infrastructure investment programs |
|
South India |
23.6% |
Anchored by high urbanization in major technology-driven cities, rising premium adoption, and a strong domestic manufacturing base |
|
East India |
15.2% |
Emerging market with growing urban housing demand, supported by smart city programs and improving sanitation infrastructure investment |
West India, at 32.5%, leads through Mumbai's premium real estate demand, Gujarat's rapid urban and industrial expansion, and Pune's growing IT-sector residential development. North India, at 28.7%, benefits from the largest scale of government housing programs, Delhi-NCR's premium residential market, and Uttar Pradesh's massive housing construction activity extending to smaller secondary cities.
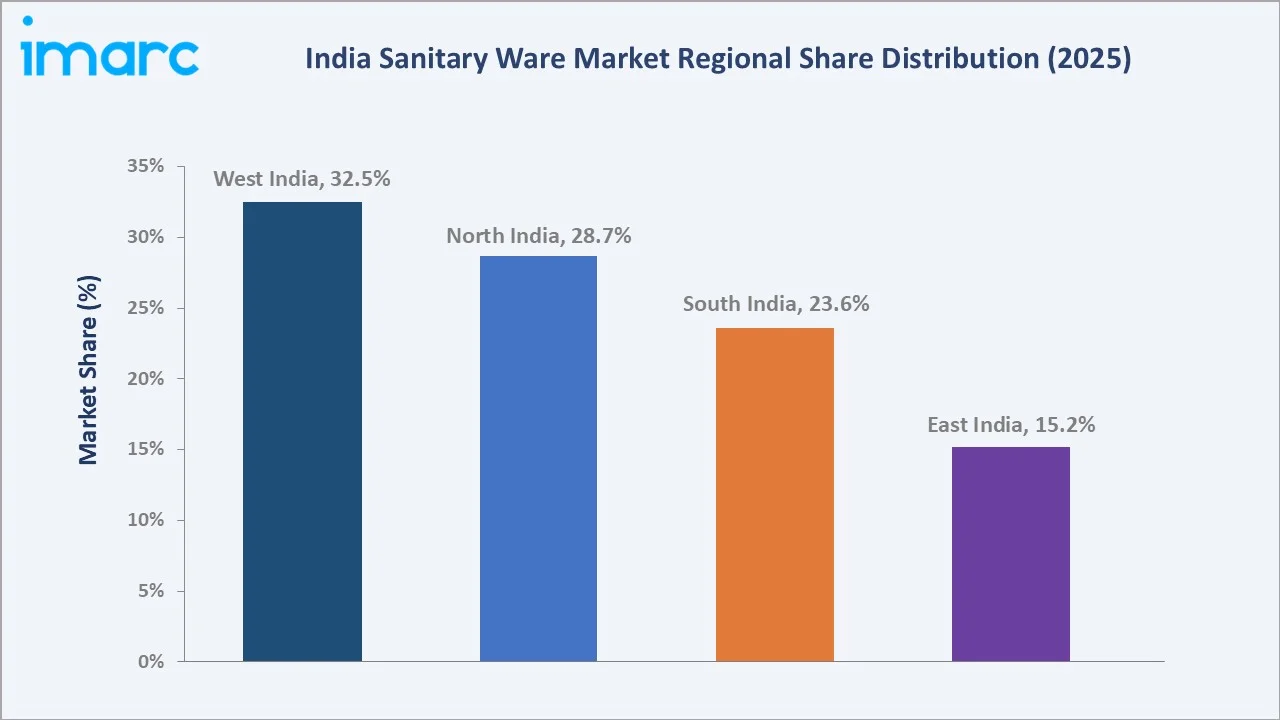
South India, at 23.6%, reflects Bengaluru's strong tech-sector-led premium housing demand, Chennai's large residential and commercial market, and Hyderabad's rapid urban expansion driving institutional and residential sanitary ware procurement. East India, at 15.2%, represents an emerging growth region anchored by Kolkata's urban renewal and smart city programs across Odisha, Bihar, and West Bengal states.
Competitive Landscape
The India sanitary ware market competitive landscape is moderately concentrated, alongside international premium brands competing across distinct price and quality tiers targeting different consumer demographics.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
Somany Impresa |
Queo Premium Toilets, Hindware Sanitaryware, Art Series EWC, Alpine Wash Basins |
Market Leader |
Operating through Hindware, largest domestic manufacturer with integrated vitreous china production; strong pan-India distribution targeting luxury segment consumers |
|
Cera |
Senator Rimless EWC, Cera Luxe Series, Cera Quartz Wash Basins, One-Piece Closets |
Market Leader |
Gujarat-based manufacturer; strong Style Studio retail network and broad mid-to-premium product range across all key product categories |
|
Jaquar Global |
Jaquar One-Piece EWC, Artize Luxury Range, Cistern Range, Wash Basin Collection |
Strong Challenger |
Vertically integrated bath solutions provider covering faucets, showers, and sanitaryware; premium Artize brand targets architect-specified luxury residential and hospitality segment |
|
Kohler Co. |
Veil Intelligent Toilet, San Raphael EWC, Caxton Pedestal Basin, Touchless Faucets |
Market Leader |
Global premium brand with India experience centers; leading position in luxury and smart bathroom segment with touchless and IoT-integrated bathroom fixture portfolio |
Key players include Somany Impresa, Cera, Jaquar Global, Kohler Co., and others.
Key Company Profiles
Cera
Cera is a Gujarat-based Indian manufacturer and one of the country's leading organized sanitary ware brands, operating its primary manufacturing facility in Mehsana with capacity scaled toward 3.5 million pieces annually, complemented by an expanding branded retail studio network across India.
- Key Products: Senator Rimless EWC, Cera Luxe Series, Cera Quartz Wash Basins, One-Piece Closets, and faucet range covering mid-market to premium consumer segments. The Senator Rimless product line addresses the growing consumer preference for improved hygiene and water efficiency in toilet design, positioned at a competitive price point relative to international premium alternatives.
- Strategic Focus: Expanding the Cera Style Studio network across Tier 1 and 2 cities to drive premiumization, developing water-saving and eco-certified product ranges for GRIHA and LEED green building compliance, and growing faucet and wellness product integration to position Cera as a complete bathroom solutions provider at competitive price points for Indian consumers.
Jaquar Global
Jaquar is a leading bath solutions manufacturer with a fully integrated portfolio covering faucets, showers, sanitaryware, water heaters, and lighting under the Jaquar and Artize brands, with manufacturing in Haryana and Rajasthan and a substantial and growing international export business.
- Key Products: Jaquar One-Piece EWC, Artize Luxury Collections, Jaquar Cisterns, Wash Basin Range, and complete integrated bathroom systems coordinating sanitaryware with faucets and shower solutions. The Artize brand represents Jaquar's premium design-led offering positioned at the ultra-luxury segment competing directly with imported European brands in architect-specified residential and hospitality projects.
- Strategic Focus: Building complete bathroom solution capabilities from sanitaryware to faucets, showers, and lighting to capture the full project value chain; expanding the Artize brand in architect-led premium projects; growing exports to Middle East and ASEAN markets; and investing in digital design tools that enable architects to specify Jaquar products seamlessly into high-value residential and hospitality projects.
Market Concentration Analysis
The India sanitary ware market is moderately concentrated at the organized sector level, with the key players collectively accounting for approximately 55–65% of organized sector revenue. The unorganized sector accounts for an estimated 35–45% of total market volume, primarily serving rural and price-sensitive urban consumer segments.
Market concentration is gradually increasing as organized players expand capacity, brand awareness, and retail infrastructure, steadily displacing unorganized competition in mid-market segments. International premium brands are capturing disproportionate value share in the growing luxury segment, with organized premium accounting for an increasing proportion of total market revenue as urbanization and income growth expand the premium consumer base.
Investment & Growth Opportunities
Highest Growth Segments
Smart bathroom segment (~9–12% CAGR), Tier 2/3 city branded product penetration (~8% CAGR), luxury/premium sanitaryware (~9% CAGR), water-efficient product lines (~8.5% CAGR), and hospitality sector fitout demand (~7.5% CAGR) represent the highest-growth investment vectors through 2034.
Emerging Investment Opportunities
Smart bathroom technology integration represents the highest per-unit value emerging opportunity, with sensor-based and IoT-enabled sanitary products generating 2–4x the per-unit revenue of standard ceramicware. Luxury real estate and five-star hospitality construction pipelines in India's major metropolitan centers provide structured and growing institutional demand.
Investment Themes
- Greenfield ceramic manufacturing capacity in growth corridors: India's long-term urbanization and PMAY housing pipeline creates a structurally growing demand pool for mid-market ceramic sanitaryware, warranting investment in efficient domestic capacity to progressively displace unorganized sector supply across volume market segments.
- Premium brand experience center network expansion: The proven impact of branded experience centers on premium sanitaryware conversion makes retail network investment a high-ROI growth strategy for organized players seeking to expand premium category revenue across Tier 1 and 2 city consumer markets in India.
Future Market Outlook (2026-2034)
The India sanitary ware market is projected to grow from USD 72.98 Billion in 2025 to USD 130.08 Billion by 2034, delivering a 6.43% CAGR. Three structural forces define growth: India's ongoing urbanization creating sustained new construction demand, government sanitation infrastructure investment expanding market access, and rising consumer aspirations driving premiumization across all product segments throughout the forecast period.
The ceramic material category will maintain dominance at above 88% share through the forecast period, while smart and specialty products gain incremental share from a growing base. Toilet Sink/Water Closet will remain the largest product category, with Wash Basins growing as bathroom renovation activity accelerates. West India and North India will continue leading regional growth, with East India representing the fastest-growing region from a lower base driven by urban infrastructure investment.
Research Methodology
Primary Research
Primary research comprised structured interviews with 45+ industry stakeholders (2025), including sanitaryware manufacturing executives, distributor and dealer channel partners, construction project procurement managers, interior designers and architects, and government sanitation program administrators, conducted across all major Indian metropolitan and regional markets.
Secondary Research
Secondary research encompassed company annual reports and investor presentations; Ministry of Housing and Urban Affairs PMAY data; Swachh Bharat Mission official progress reports; AMRUT 2.0 program documentation; BIS certification and IS 2556 standard references; Census urbanization data; IMARC Group proprietary database; and trade association reports, with over 50 secondary sources systematically reviewed.
Forecasting Models
Market revenue forecasts were developed using a bottom-up construction activity model incorporating: (i) residential and commercial construction volume by region; (ii) average sanitaryware spend per unit by construction category; (iii) renovation and replacement demand cycle estimation; (iv) premiumization and product mix shift adjustments; and (v) government program-driven demand overlay for sanitation infrastructure across India.
India Sanitary Ware Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Materials Covered | Ceramic, Plastic, Others |
| Types Covered | Toilet Sink/Water Closet, Wash Basins, Pedestals, Cisterns, Others |
| Applications Covered | Kitchen, Bathroom |
| End Users Covered | Residential, Commercial |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Somany Impresa, Cera, Jaquar Global, Kohler Co., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India sanitary ware market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India sanitary ware market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India sanitary ware industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Sanitary Ware Market Report
The India sanitary ware market reached USD 72.98 Billion in 2025, driven by ceramic material dominance at 88.5%, Toilet Sink/Water Closet leading at 37.5%, West India commanding 32.5% regional share, and structural demand from PMAY housing programs and Swachh Bharat Mission sanitation infrastructure investment at national and state levels.
The India sanitary ware market grows at a CAGR of 6.43% during 2026-2034, reaching USD 130.08 Billion by 2034, driven by urbanization, premiumization, smart bathroom technology adoption, and sustained government sanitation investment across residential and commercial construction segments throughout India.
Ceramic leads at 88.5%, capturing the mainstream market across all consumer segments through superior durability, hygiene properties, aesthetic versatility, and cost-effective manufacturing economics relative to plastic and other alternative materials used in sanitary ware production.
Toilet Sink/Water Closet leads at 37.5% through universal demand across residential, commercial, and institutional applications, amplified by government-mandated toilet construction programs under Swachh Bharat Mission, making it the most essential and highest-volume product category in the market.
West India leads at 32.5% through Mumbai's premium real estate demand, Gujarat's industrial and urban growth, and Pune's expanding IT-sector residential market, making the western region India's highest-revenue sanitary ware consumption zone across all price tiers.
Leading companies include Somany Impresa, Cera, Jaquar Global, Kohler Co., and others.
The India sanitary ware market is projected to reach approximately USD 99.68 Billion by 2030, with organized sector market share consolidation, smart bathroom adoption expanding in premium residential projects, and Tier 2/3 city market penetration by branded players driving growth across emerging geographic clusters and secondary urban markets.
Three priority investment opportunities: greenfield ceramic manufacturing capacity targeting PMAY-driven volume demand, premium brand experience center network expansion for premiumization capture in Tier 1 and 2 cities, and smart bathroom technology integration for luxury residential and hospitality segment positioning across India's rapidly evolving premium consumer market.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade