India Ship Repairing Market Size, Share, Trends and Forecast by Vessel Type, Application, End User, and Region, 2026-2034
India Ship Repairing Market Size, Share, Trends & Forecast (2026-2034)
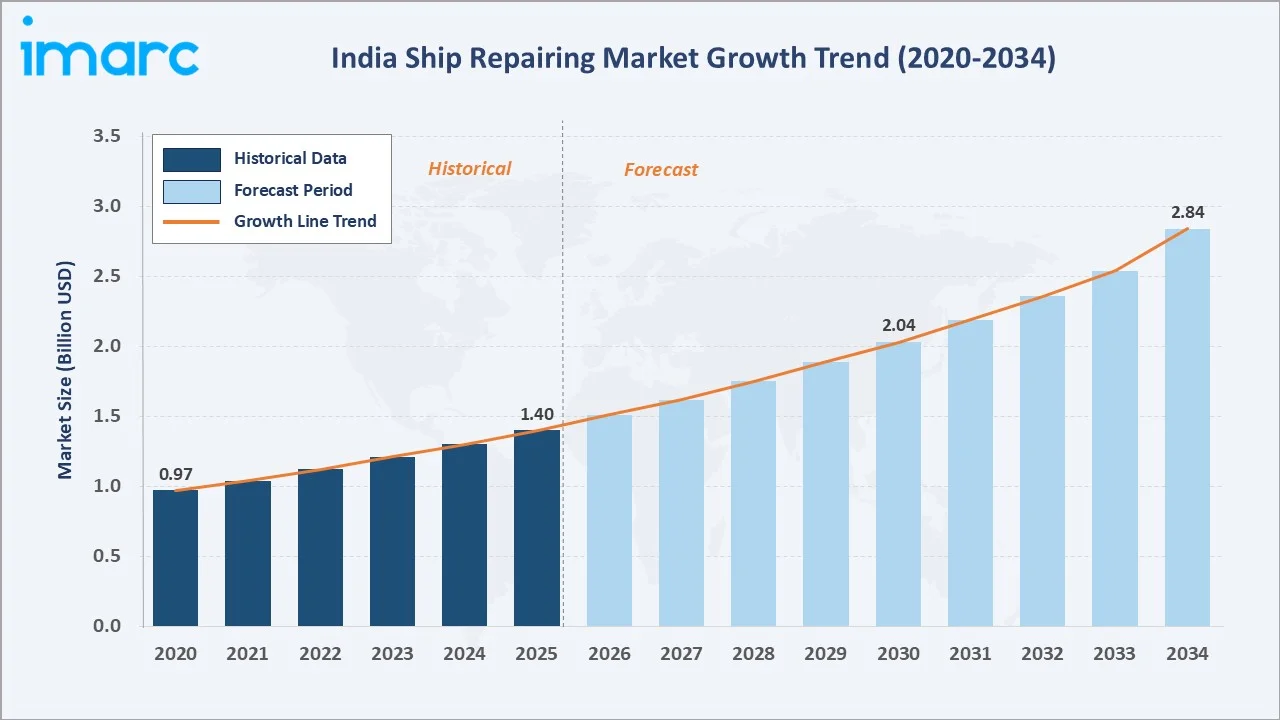
The India ship repairing market size increased from USD 1.40 Billion in 2025 to USD 1.56 Billion in 2026 and is projected to reach USD 2.84 Billion by 2034, exhibiting a CAGR of 7.73% during 2026-2034. Rising coastal and EXIM cargo movement, an aging domestic fleet, sustained naval refit demand, and a widening policy push for maritime self-reliance are the primary drivers shaping market growth.
Bulk cargo carrier leads the vessel type segment at 27.8%, general services dominate the application segment at 25.7%, and West India commands 38.5% regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 1.40 Billion |
|
Market Size (2026) |
USD 1.56 Billion |
|
Forecast Market Size (2034) |
USD 2.84 Billion |
|
CAGR (2026-2034) |
7.73% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
West India (38.5%, 2025) |
|
Second Largest Region |
South India (29.7%, 2025) |
|
Leading Vessel Type |
Bulk Cargo Carrier (27.8%, 2025) |
|
Leading Application |
General Services (25.7%, 2025) |
The India ship repairing market expanded from USD 0.97 Billion in 2020 to USD 1.40 Billion in 2025 and an estimated USD 1.56 Billion in 2026, supported by recovering coastal shipping volumes and steady dry-docking cycles. Anchored at USD 2.04 Billion in 2030, the forecast to USD 2.84 Billion by 2034 rests on new repair infrastructure, deeper private yard participation, and rising retrofit demand.
To get more information on this market, Request Sample
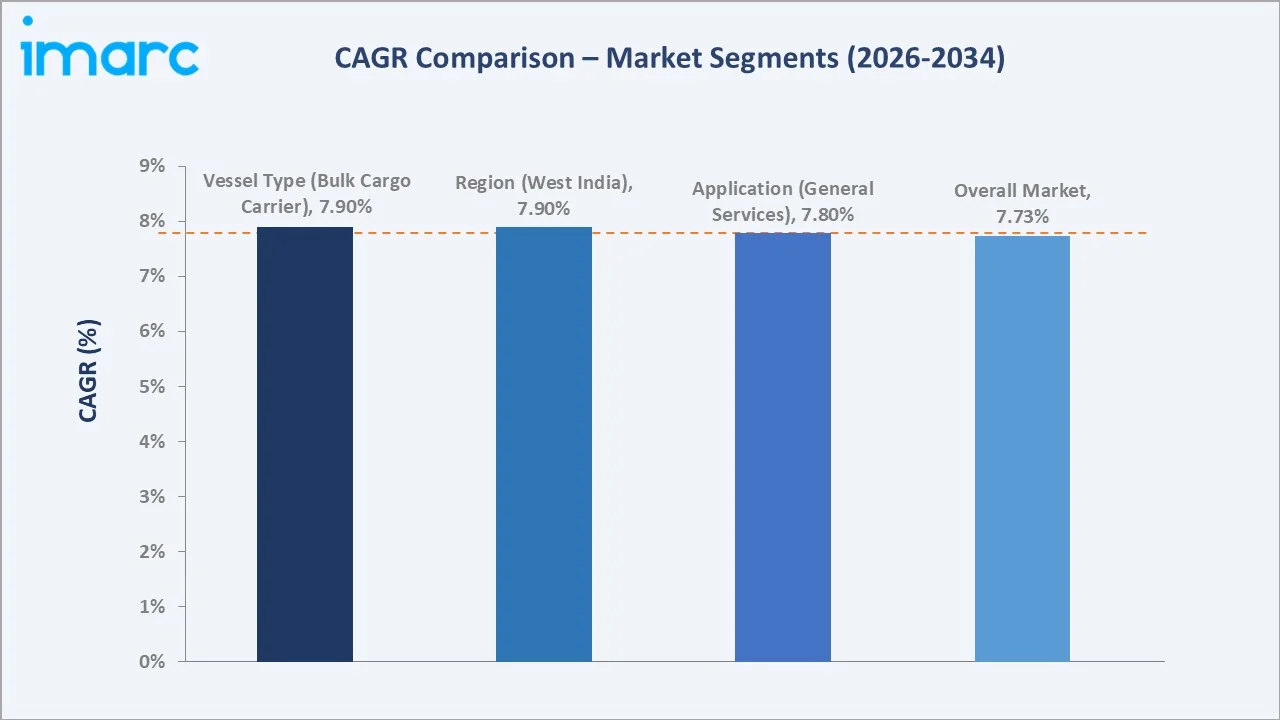
CAGR trajectories across vessel type, application, and regional sub-segments show electric works, container ships, and South India expanding faster than the overall CAGR of 7.73%, reflecting fleet modernization and onboard automation.
Executive Summary
The India ship repairing market expanded from USD 0.97 Billion in 2020 to USD 1.56 Billion in 2026, is projected to reach USD 2.84 Billion by 2034. The sector has moved from small, fragmented repair work toward organized, dock-based servicing of commercial and defense tonnage.
Bulk cargo carrier dominates the vessel type segment at 27.8% in 2025, supported by a large dry bulk trade in coal, iron ore, and fertilizers. General services lead the application segment at 25.7%, reflecting routine hull cleaning, painting, and survey-linked work across nearly every dry-docking cycle. West India commands 38.5% of the regional share, led by the density of ports, refineries, and yards across Gujarat and Maharashtra.
Key Market Insights
|
Insight |
Data |
|
Leading Vessel Type |
Bulk Cargo Carrier - 27.8% share (2025) |
|
Second Largest Vessel Type |
Container Ships - 22.5% share (2025) |
|
Leading Application |
General Services - 25.7% share (2025) |
|
Second Largest Application |
Engine Parts - 21.8% share (2025) |
|
Leading Region |
West India - 38.5% share (2025) |
|
Second Largest Region |
South India - 29.7% share (2025) |
|
Top Companies |
Cochin Shipyard Limited, Mazagon Dock Shipbuilders Limited, Larsen & Toubro Limited, Hindustan Shipyard Limited |
Key Analytical Observations Expanding On the Data Above:
- Bulk cargo carrier leadership at 27.8% is anchored by India’s extensive handling of dry bulk commodities, including coal, iron ore, and agricultural products. Regular port calls and recurring maintenance requirements support steady repair demand from this vessel class.
- Container ships share at 22.5% is supported by India’s growing containerized trade and expanding port infrastructure. High vessel utilization and frequent port calls create recurring requirements for routine maintenance, machinery servicing, and docking-related repairs.
- General services at 25.7% cover hull cleaning, blasting, painting, and staging work that recurs in almost every docking.
- Engine parts share at 21.8% is driven by main engine overhauls, auxiliary machinery refurbishment, and pump and turbocharger work. The segment carries higher value per job and rewards yards with skilled machining capability.
- West India at 38.5% dominates regional share, anchored by Gujarat and Maharashtra. Port density, refinery traffic, and established private and defense yards sustain a steady flow of repair work through the year.
India Ship Repairing Market Overview
Ship repairing refers to the maintenance, survey, refit, conversion, and life extension of commercial and defense vessels, covering hull steel renewal, machinery overhaul, electrical and automation work, coating, and docking. The market spans bulk cargo carrier, container ships, general cargo ships, crude oil tankers, chemical tankers, and others.
The Indian ecosystem links steel and equipment suppliers, dry dock and ship lift operators, service contractors, classification societies, port authorities, and fleet owners spanning shipping lines, the Indian Navy, and the Indian Coast Guard.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
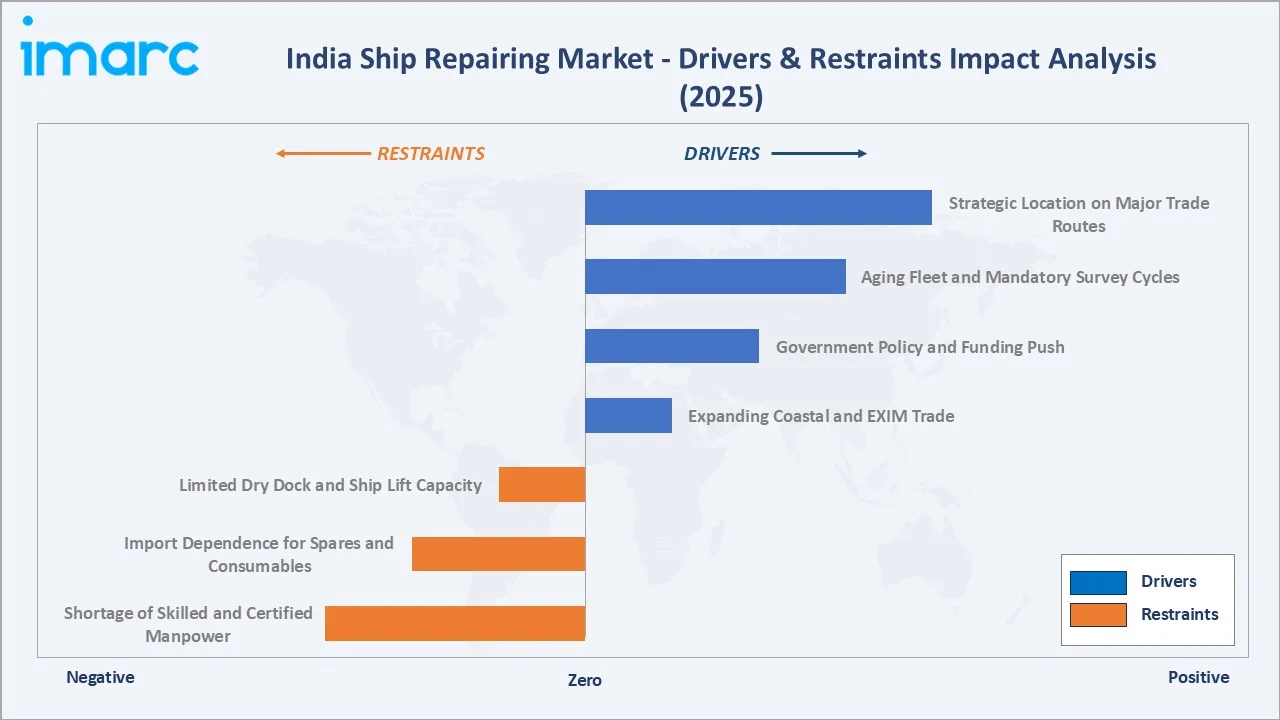
- Expanding Coastal and EXIM Trade: Rising cargo throughput at major and non-major ports is increasing vessel calls along both coasts. Higher traffic translates directly into more docking cycles, voyage repairs, and afloat maintenance work for Indian yards.
- Government Policy and Funding Push: Sustained policy support for maritime self-reliance is improving the commercial case for Indian repair yards. Maritime India Vision (MIV) 2030 targets lifting India into the top 10 shipbuilding and ship repair nations by 2030, backed by dedicated funding, a national shipbuilding mission, and cluster development.
- Aging Fleet and Mandatory Survey Cycles: A growing number of older vessels operating in and around Indian waters require periodic surveys, machinery overhauls, hull inspections, and other maintenance work. Mandatory inspection and certification schedules create recurring repair demand and support more predictable workloads for Indian shipyards.
- Strategic Location on Major Trade Routes: India’s location along major international shipping routes between Europe, the Middle East, Africa, and Asia provides Indian shipyards with access to passing commercial vessels. Proximity to key maritime corridors can encourage owners to undertake repairs and maintenance in Indian yards, particularly when competitive turnaround times and costs are available.
Market Restraints
- Limited Dry Dock and Ship Lift Capacity: Available docking slots remain scarce relative to demand, and several docks are sized for smaller tonnage. Constrained capacity forces owners of larger vessels to look overseas, limiting the work Indian yards can accept.
- Import Dependence for Spares and Consumables: Many critical spares, coatings, and specialized components are sourced from abroad. Customs clearance timelines and freight lead times inflate repair costs and stretch turnaround, weakening price competitiveness against established hubs.
- Shortage of Skilled and Certified Manpower: Ship repair depends on experienced welders, fitters, pipe workers, and marine electricians. Attrition to other sectors and uneven certification pipelines make it difficult for yards to staff peak docking seasons reliably.
Market Opportunities
- Green Retrofit and Emission Compliance Work: Tightening decarbonization and ballast water rules are creating a pipeline of scrubber fitting, energy-saving device installation, and treatment system retrofits that Indian yards can execute at competitive cost.
- Ship Repair Clusters and Ancillary Ecosystems: Developing clusters around major repair facilities can localize spares, coatings, and specialized services, cutting import dependence and materially shortening vessel turnaround for both domestic and foreign owners.
Market Challenges
- Competition from Established Regional Hubs: Yards in the Gulf, China, and Southeast Asia offer proven turnaround, deep ancillary networks, and predictable pricing. Winning repeat foreign tonnage requires Indian yards to match reliability, not only cost.
- Working Capital and Order Predictability: Repair work is short-cycle and irregular, making capacity planning difficult. Uneven order flow and delayed payments strain the working capital of smaller private yards and constrain their reinvestment in equipment.
Emerging Market Trends
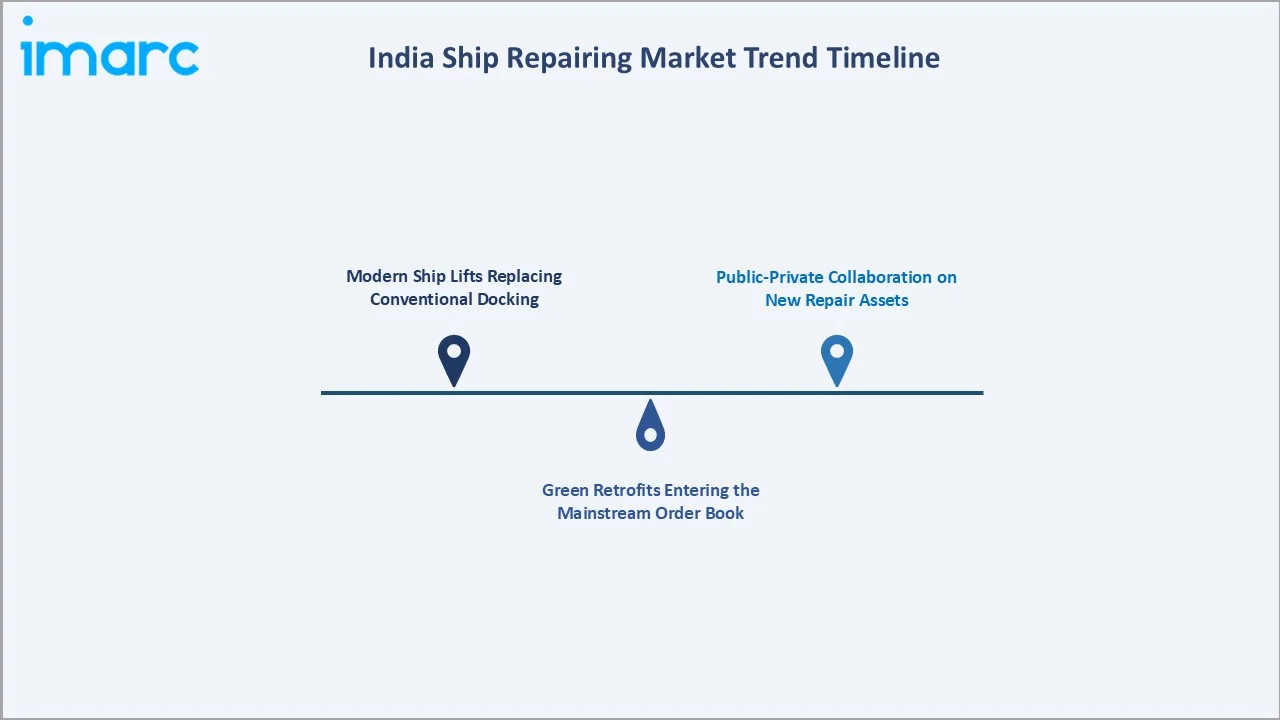
1. Modern Ship Lifts Replacing Conventional Docking
Ship lift and transfer systems are steadily displacing single-berth graving docks as the preferred format for commercial repair. These systems enable faster vessel turnaround, improve yard productivity, and allow efficient handling of vessels across different sizes.
2. Green Retrofits Entering the Mainstream Order Book
Emission reduction and ballast water compliance work is moving from occasional projects into routine docking scope. Yards are building capability in scrubber installation, energy-saving device fitting, and hull coating upgrades, raising the technical content of each job.
3. Public-Private Collaboration on New Repair Assets
Port authorities and shipyards are increasingly partnering on dedicated repair infrastructure rather than building alone. Joint development combines land, deep draft, and yard expertise, spreading the capital burden and accelerating new capacity.
Industry Value Chain Analysis
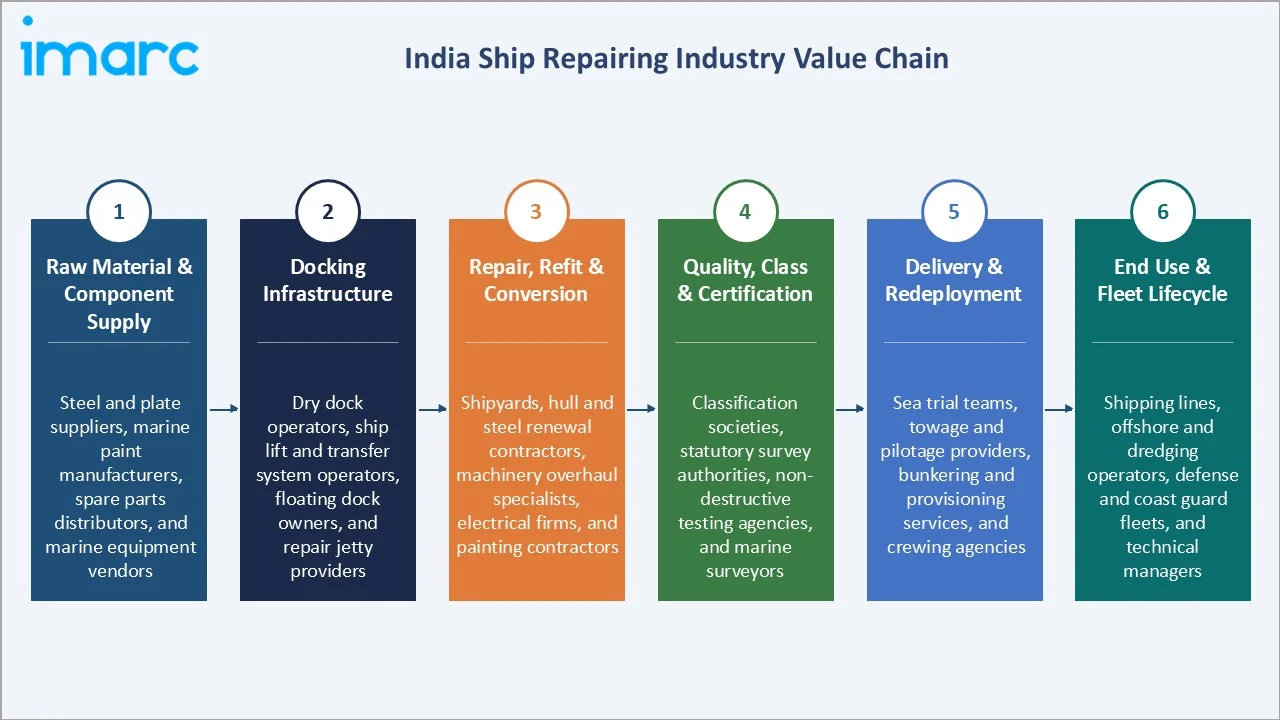
The India ship repairing value chain spans six stages, from material and component supply through end-user fleet lifecycle management. Docking infrastructure and the repair execution stage capture the highest value-add, while certification and delivery capability increasingly determine whether a yard wins repeat tonnage.
|
Stage |
Key Players / Examples |
|
Raw Material & Component Supply |
Steel and plate suppliers, marine paint and coating manufacturers, spare parts distributors, and marine equipment vendors |
|
Docking Infrastructure |
Dry dock operators, ship lift and transfer system operators, floating dock owners, and repair jetty and berth providers |
|
Repair, Refit & Conversion |
Shipyards, hull and steel renewal contractors, machinery overhaul specialists, electrical and automation firms, and painting contractors |
|
Quality, Class & Certification |
Classification societies, statutory survey authorities, non-destructive testing agencies, and independent marine surveyors |
|
Delivery & Redeployment |
Sea trial teams, towage and pilotage providers, bunkering and provisioning services, and crewing agencies |
|
End Use & Fleet Lifecycle |
Shipping lines, offshore and dredging operators, defense and coast guard fleets, and technical managers |
Vertically integrated yards that control docking assets, in-house steel and machining shops, and direct owner relationships are positioned to capture more value than contractors dependent on third-party facilities and imported inputs.
Technology Landscape in the India Ship Repairing Industry
Ship Lift Systems and Automated Docking
Ship lift and transfer platforms move vessels onto parallel hardstand positions instead of occupying a single dock for the full repair duration. Automated winch control, load monitoring, and rail transfer reduce docking risk and raise concurrent vessel handling.
Robotic Blasting, Coating, and Inspection
Robotic hull cleaning crawlers, automated grit blasting units, and remotely operated vehicles are being introduced for underwater inspection and coating work, cutting staging time and improving surface preparation.
Digital Twins, Analytics, and Yard Planning
Digital twin models, three-dimensional scanning, and yard planning software help engineers pre-fabricate steel blocks and sequence trades before arrival. Predictive analytics on machinery condition freezes repair scope earlier, improving berth utilization.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Vessel Type |
Bulk Cargo Carrier |
27.8% |
2025 |
|
Application |
General Services |
25.7% |
2025 |
|
End User |
🔒 |
🔒 |
2025 |
|
Region |
West India |
38.5% |
2025 |

By Vessel Type
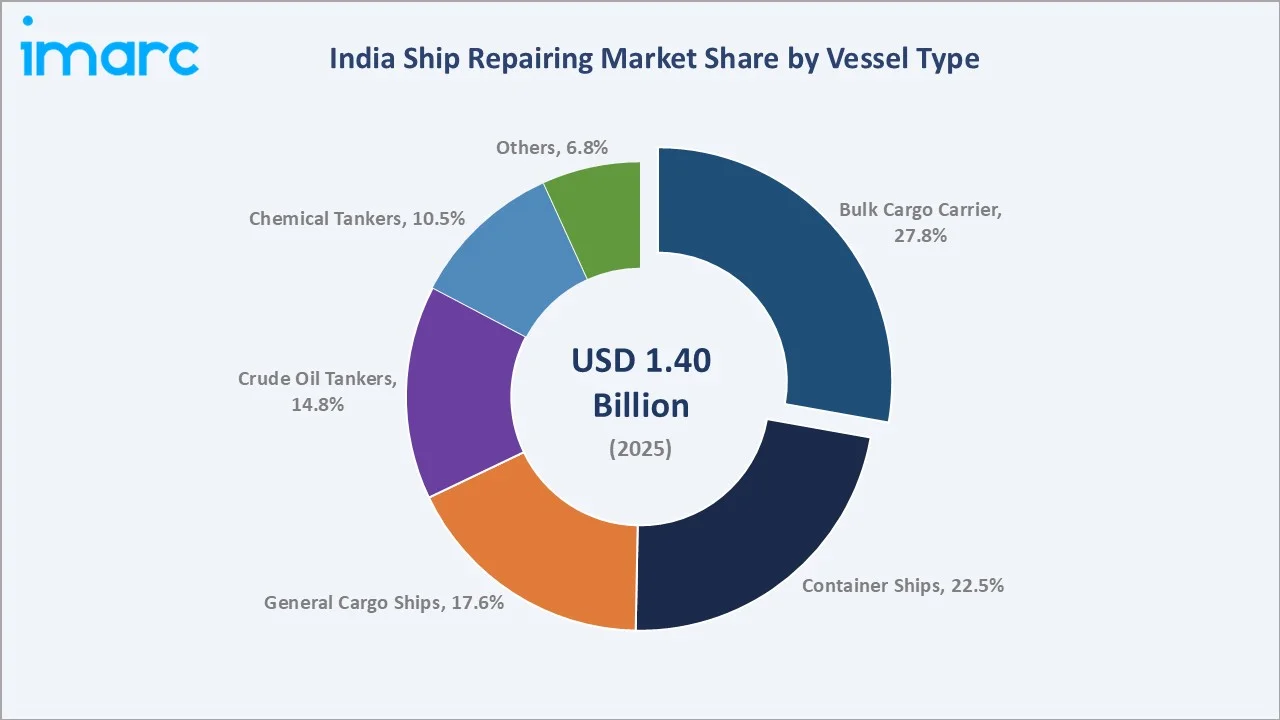
Bulk cargo carrier commands a 27.8% share in 2025, driven by India’s heavy dry bulk trade in coal, iron ore, and fertilizers. The segment benefits from predictable survey cycles, straightforward hull geometry, and steel renewal work that Indian yards are well equipped to execute at competitive cost.
To access detailed market analysis, Request Sample
Container ships at 22.5% in 2025 form the second largest vessel type segment. Rising containerized throughput, expanding feeder networks, and tighter schedule discipline are pushing operators toward repair yards located close to their trading routes, which supports steady growth for Indian facilities.
By Application
General services dominate with a 25.7% share in 2025, reflecting hull cleaning, blasting, painting, staging, and survey preparation that recur in virtually every docking. Its repeatability across vessel classes makes it the most reliable revenue line for Indian repair yards.
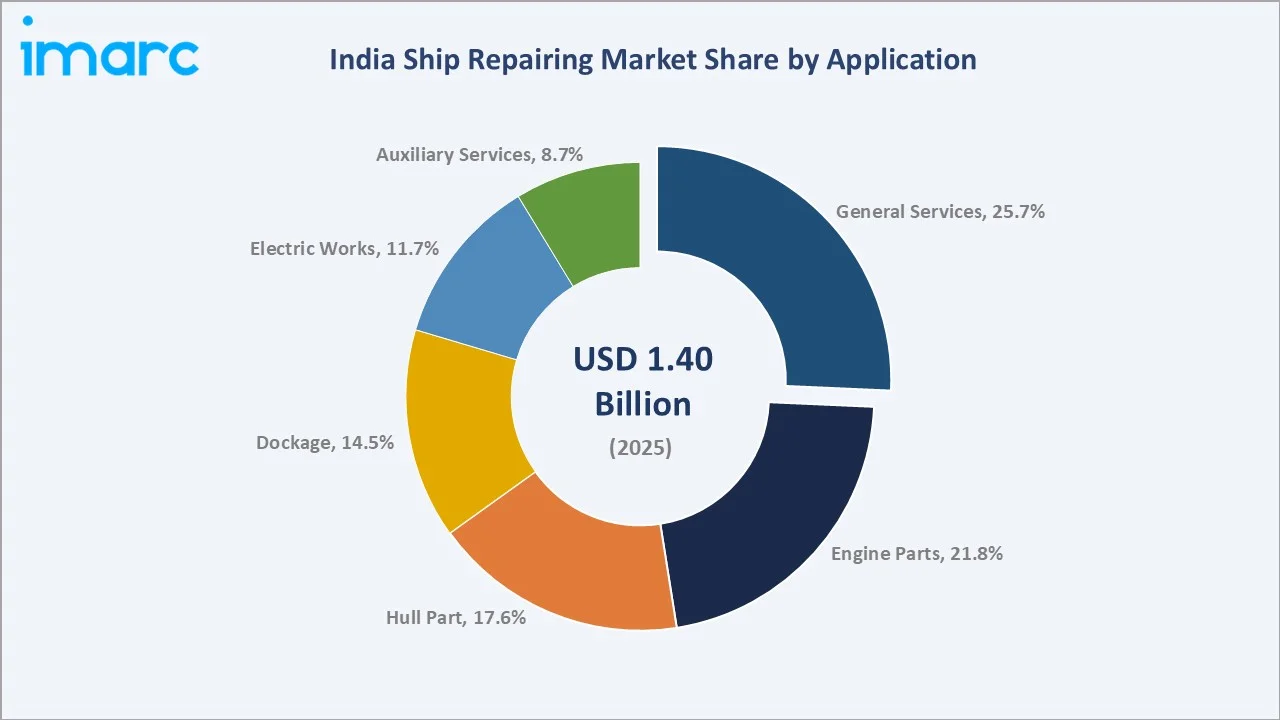
Engine parts at 21.8% in 2025 cover main engine overhauls, auxiliary machinery refurbishment, and pump, turbocharger, and shafting work. The category rewards yards with skilled machining capability and access to genuine spares, and it typically carries a higher margin than routine surface work.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
West India |
38.5% |
High port density, large refinery and tanker traffic, established shipyard base, and strong ancillary support |
|
South India |
29.7% |
Deep natural drafts, modern ship lift infrastructure, proximity to east-west trade routes, and growing private yard activity |
|
East India |
20.6% |
Large dry bulk cargo movement, defense and public sector yard presence, and expanding port capacity |
|
North India |
11.2% |
Inland waterway vessel maintenance, component supply into coastal yards, and river-based cargo operations |
West India at 38.5% in 2025 leads the regional landscape, anchored by Gujarat and Maharashtra. A dense cluster of major and non-major ports, heavy tanker and offshore traffic, and a mature engineering ancillary base sustain year-round docking demand across both commercial and defense tonnage.
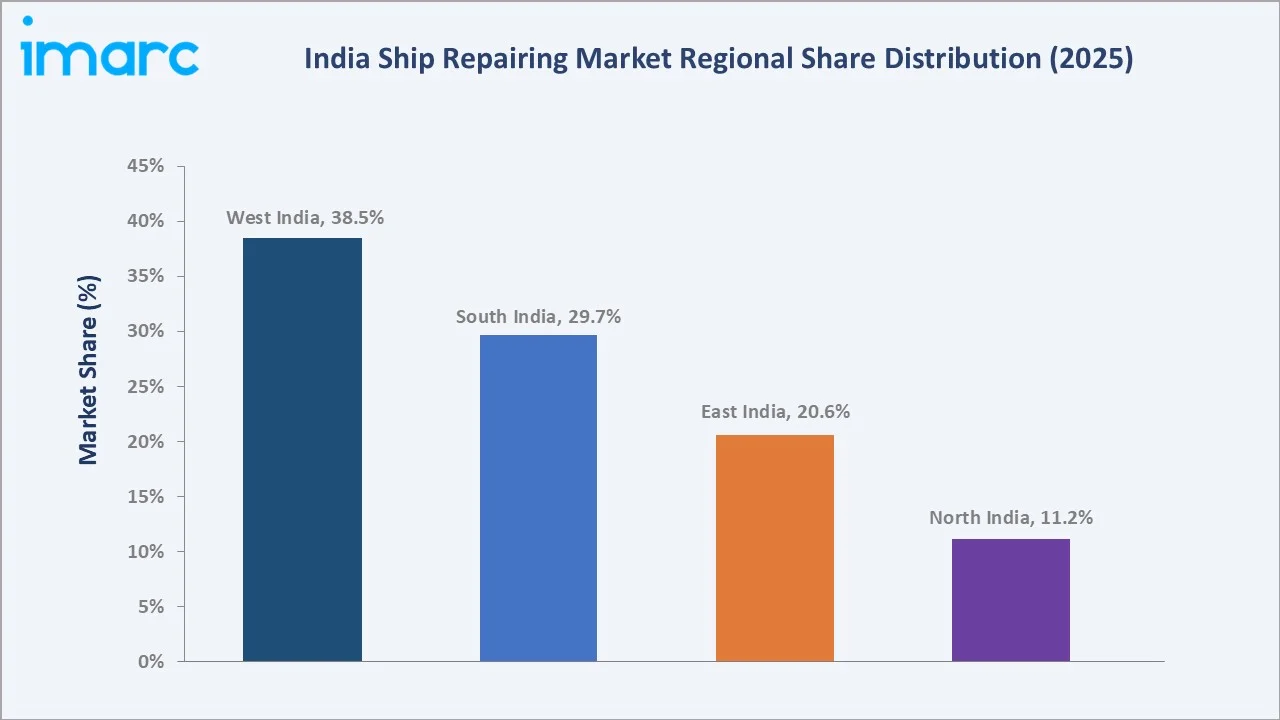
South India at 29.7% is the fastest growing region. Deep natural drafts, newly commissioned ship lift capacity, and proximity to the main east-west shipping corridor are drawing international tonnage that previously routed to overseas yards.
Competitive Landscape
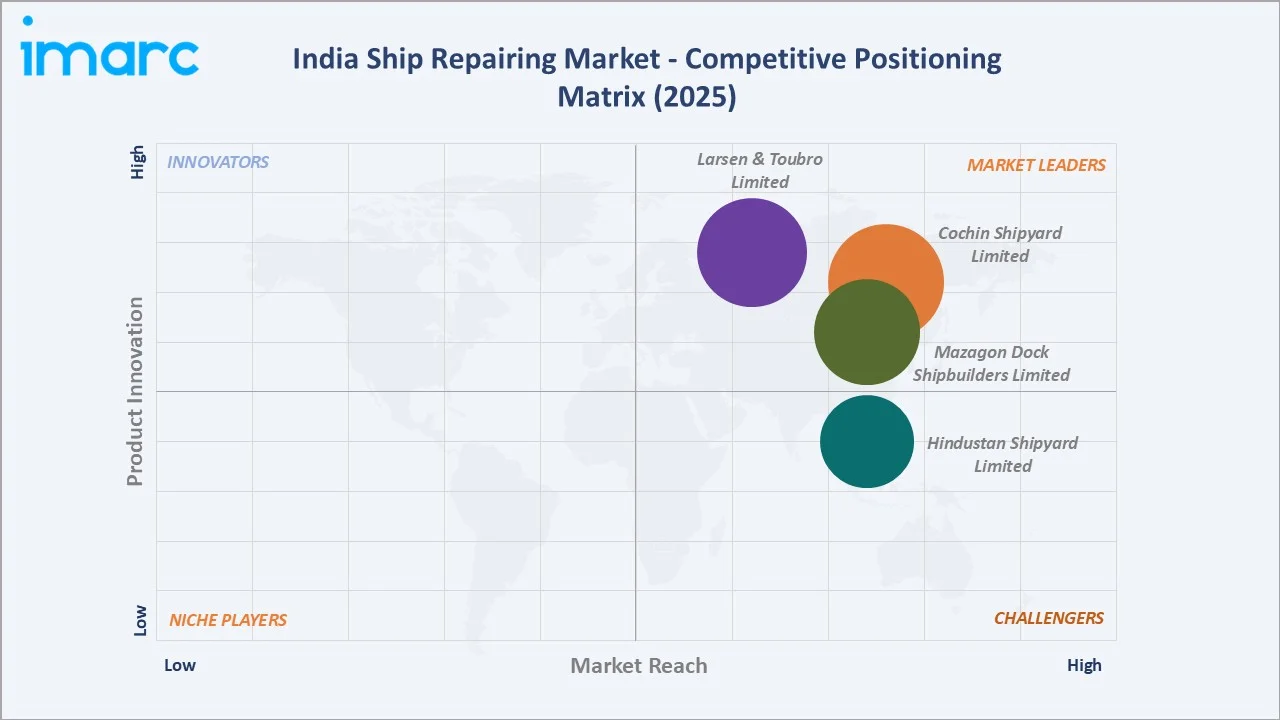
The India ship repairing market is moderately fragmented, with defense-linked public sector yards leading on capability and scale while private yards compete on turnaround and commercial flexibility. Dock availability, manpower depth, ancillary access, and classification approvals form the key moats.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
|
Cochin Shipyard Limited |
Ship Repair |
Leader |
Expanding modern repair capacity and building an integrated repair ecosystem |
|
Mazagon Dock Shipbuilders Limited |
Mazagon Dock Ship Repair and Refit |
Leader |
Deepening complex refit capability and extending regional service reach |
|
Larsen & Toubro Limited |
L&T Ship Repair Services |
Leader |
Positioning integrated yard infrastructure for higher-value repair mandates |
|
Hindustan Shipyard Limited |
HSL Ship Repair Division |
Challenger |
Strengthening dry dock utilization and specialized refit capability |
Key players include Cochin Shipyard Limited, Mazagon Dock Shipbuilders Limited, Larsen & Toubro Limited, and Hindustan Shipyard Limited, among others.
Key Company Profiles
Cochin Shipyard Limited
Cochin Shipyard Limited is a public sector shipyard headquartered in Kochi, Kerala, operating under the Ministry of Ports, Shipping and Waterways. It is among India’s largest ship repair providers, with dedicated repair units along both the western and eastern coasts.
- Product Portfolio: Ship repair, refit, conversion, and life-extension services for commercial and defense vessels, supported by dry docks and a ship lift and transfer system.
- Recent Developments: The company is expanding its ship repair capacity, upgrading dry dock infrastructure, and strengthening its repair capabilities to serve a broader range of commercial and defense vessels.
- Strategic Focus: Expanding modern repair capacity and building an integrated ancillary ecosystem around its facilities.
Mazagon Dock Shipbuilders Limited
Mazagon Dock Shipbuilders Limited is a defense public sector undertaking based in Mumbai, Maharashtra. Alongside warship and submarine construction, it undertakes repair, refit, and life-extension work for naval and commercial vessels.
- Product Portfolio: Ship and submarine repair and refit services, machinery overhaul, and life-extension programs supported by dry dock and wet basin facilities.
- Recent Developments: The company has continued to broaden its repair and refit capability and widen the range of vessels it services across defense and commercial segments.
- Strategic Focus: Deepening complex refit capability and extending regional service reach alongside its core defense programs.
Larsen & Toubro Limited
Larsen & Toubro Limited is an Indian engineering and construction group headquartered in Mumbai, with capabilities spanning shipbuilding, ship repair, defense, and heavy engineering.
- Product Portfolio: Ship repair, refit, and mid-life upgrade services covering hull and steel work, machinery overhaul, and system modernization for commercial, defense, and foreign vessels.
- Recent Developments: The company has continued to invest in its yard infrastructure and expand the scope of repair and refit work handled at its facility.
- Strategic Focus: Positioning integrated yard infrastructure for higher-value repair mandates and expanding engagement with international fleet operators.
Market Concentration Analysis
The India ship repairing market is moderately concentrated at the top. Cochin Shipyard Limited, Mazagon Dock Shipbuilders Limited, and Larsen & Toubro Limited together account for a meaningful share of organized repair activity.
Barriers to entry are structural. New participants require dry dock or ship lift assets, deep-draft waterfront, classification approvals, and a trained workforce, favoring incumbents.
Consolidation is gradually increasing as public sector yards acquire regional capacity and private yards partner with port authorities on shared infrastructure, while alliances with international specialists reshape positioning.
Investment & Growth Opportunities
Fastest-Growing Segments
Electric works expand fastest among applications, supported by rising automation, power management, and navigation complexity on board. Container ships lead vessel type growth, driven by expanding containerized trade and schedule-sensitive liner operators.
Emerging Markets
South India is the fastest growing region, anchored by deep natural drafts, new ship lift capacity, and proximity to the main east-west corridor, offering headroom for yards able to guarantee turnaround for international tonnage.
Venture & Investment Trends
Capital is flowing into ship lift systems, floating docks, and repair jetties, often through port authority and shipyard partnerships, and into ancillary clusters covering spares, coatings, and subcontracting.
Future Market Outlook (2026-2034)
The India ship repairing market is projected to grow from USD 1.40 Billion in 2025 to USD 1.56 Billion in 2026 and is forecast to reach USD 2.84 Billion by 2034 at a CAGR of 7.73%, adding roughly USD 1.44 Billion in incremental value.
Four forces will shape the market through 2034: a widening base of modern docking infrastructure; green retrofit work entering routine docking scope; deeper public-private collaboration on repair assets; and localization of spares around repair clusters.
By 2034, ship repairing in India is expected to be defined by faster turnaround, larger permissible vessel sizes, and a higher share of foreign tonnage docking at Indian yards.
Research Methodology
Primary Research
Primary research included structured interviews with shipyard executives, port authority officials, classification surveyors, fleet technical managers, and equipment suppliers, validating market sizing, regional demand, and vessel mix.
Secondary Research
Secondary sources included Ministry of Ports, Shipping and Waterways publications, Directorate General of Shipping records, port authority traffic data, Cabinet and policy announcements, and annual reports and investor presentations from listed shipyards.
Forecasting Models
Market forecasts combined top-down and bottom-up models built on vessel call volumes, docking cycle frequency, average repair value per vessel class, and capacity addition schedules. Scenario analysis addressed policy execution pace and competitive pressure from regional hubs.
India Ship Repairing Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Vessel Types Covered | General Cargo Ships, Bulk Cargo Carrier, Crude Oil Tankers, Chemical Tankers, Container Ships, Others |
| Applications Covered | General Services, Dockage, Hull Part, Engine Parts, Electric Works, Auxiliary Services |
| End Users Covered | Transport Companies, Military, Others |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Cochin Shipyard Limited, Mazagon Dock Shipbuilders Limited, Larsen & Toubro Limited, Hindustan Shipyard Limited, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India ship repairing market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India ship repairing market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India ship repairing industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Ship Repairing Market Report
The India ship repairing market size is estimated at USD 1.56 Billion in 2026, supported by rising vessel calls, mandatory survey cycles, and steady demand from commercial and defense fleets.
The market is projected to grow at a CAGR of 7.73% from 2026-2034, reaching USD 2.84 Billion, supported by new docking capacity and rising green retrofit work.
Bulk cargo carrier leads the market at 27.8% in 2025, driven by heavy dry bulk trade in coal, iron ore, and fertilizers across Indian ports.
General services dominate the market at 25.7% in 2025, covering hull cleaning, blasting, painting, staging, and survey preparation work.
West India commands 38.5% in 2025, led by high port density, refinery and tanker traffic, and an established shipyard and ancillary base across Gujarat and Maharashtra.
South India at 29.7% is the fastest growing region, supported by deep natural drafts, modern ship lift capacity, and proximity to major east-west shipping routes.
Leading players include Cochin Shipyard Limited, Mazagon Dock Shipbuilders Limited, Larsen & Toubro Limited, and Hindustan Shipyard Limited, among others.
Growth is driven by expanding coastal and EXIM trade, an aging fleet requiring mandatory surveys, sustained policy support, and India’s location on major global shipping routes.
Limited dry dock capacity, import dependence for spares, shortage of certified skilled manpower, and competition from established repair hubs in the Gulf and East Asia.
Maritime policy support, dedicated funding mechanisms, and cluster development programs are improving yard economics and encouraging investment in modern docking infrastructure.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade