India Solar Panel Recycling Market Size, Share, Trends and Forecast by Process, Type, Material, Shelf Life, and Region, 2026-2034
India Solar Panel Recycling Market Size, Share, Trends & Forecast (2026-2034)
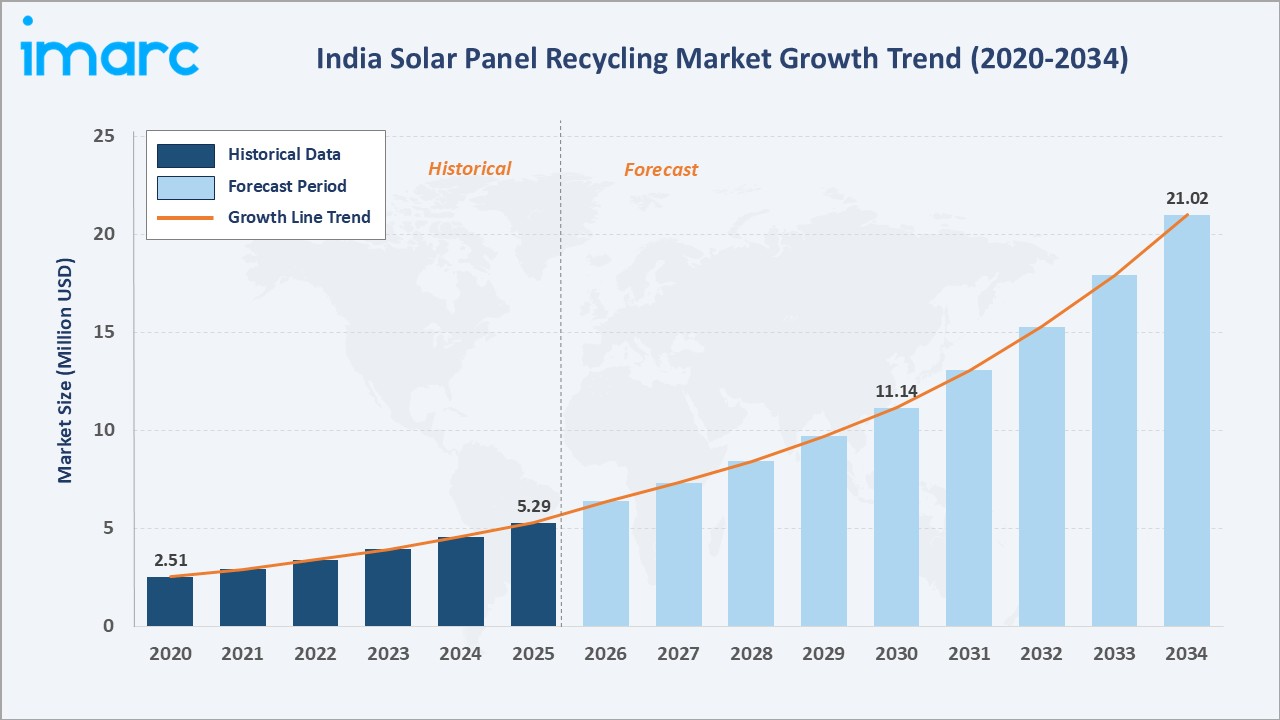
The India solar panel recycling market grew from USD 5.29 Million in 2025 to USD 6.38 Million in 2026 and is projected to reach USD 21.02 Million by 2034, exhibiting a CAGR of 16.08% during 2026-2034. Growing regulatory emphasis on extended producer responsibility (EPR), rising recovery value of silicon, silver, and aluminum, and increasing ESG commitments by solar utilities are the primary forces shaping market growth.
Mechanical leads the process segment at 43.7%, crystalline silicon dominates the type segment at 91.6%, and West India commands 31.8% of regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 5.29 Million |
|
Market Size (2026) |
USD 6.38 Million |
|
Forecast Market Size (2034) |
USD 21.02 Million |
|
CAGR (2026-2034) |
16.08% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
West India (31.8%, 2025) |
|
Second Largest Region |
South India (27.6%, 2025) |
|
Leading Process |
Mechanical (43.7%, 2025) |
|
Leading Type |
Crystalline Silicon (91.6%, 2025) |
The India solar panel recycling market size increased from USD 2.51 Million in 2020 to USD 5.29 Million in 2025 and is estimated to reach USD 6.38 Million in 2026. The market is further expected to grow to USD 11.14 Million by 2030 and USD 21.02 Million by 2034. The market is commercially unique among global recycling markets, underpinned by one of the world's fastest-growing solar installed bases, a rapidly expanding organized recycling sector driven by EPR mandates, and a growing recovery value chain for silicon, silver, and aluminum from decommissioned photovoltaic modules.
To get more information on this market, Request Sample
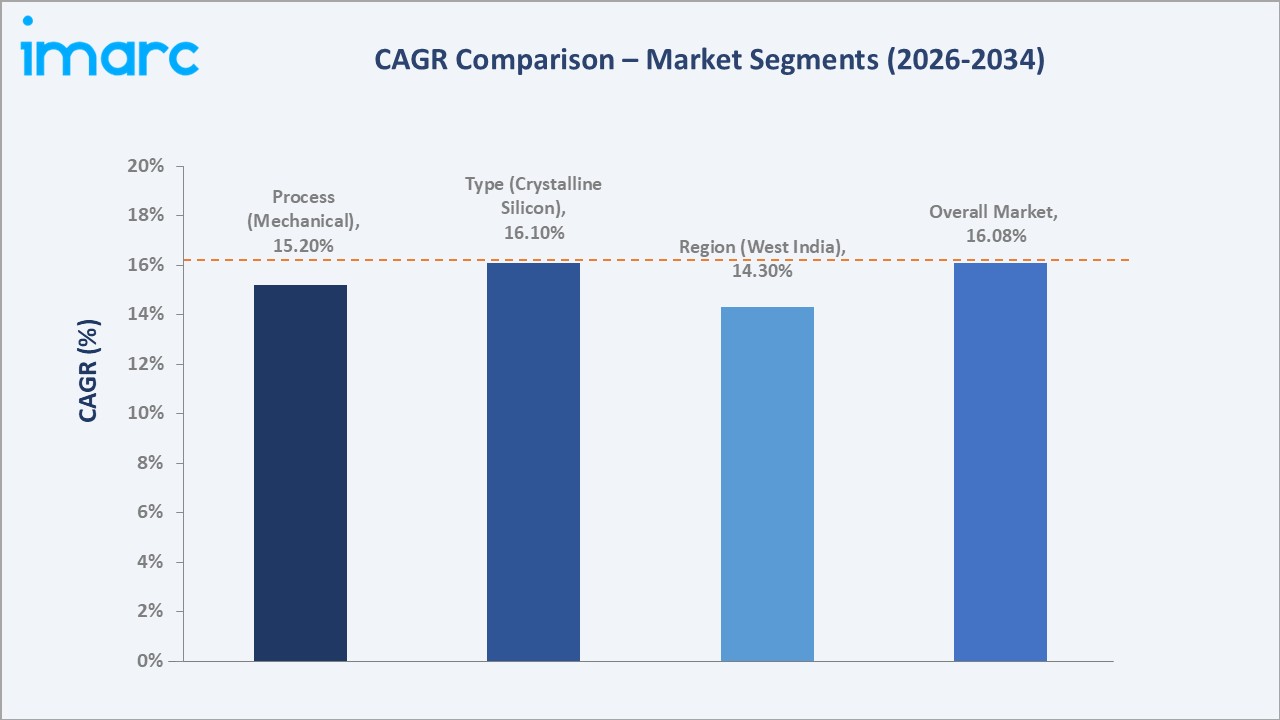
CAGR trajectories across process, type, and regional sub-segments show laser and East India expanding faster than the overall 16.08% market CAGR, driven by technology investment, expanding solar installations in eastern states, and increasing government incentives for recycling infrastructure.
Executive Summary
The India solar panel recycling market expanded from USD 5.29 Million in 2025 to an estimated USD 6.38 Million in 2026, positioning it among the world's fastest-growing panel recycling markets by growth rate. The market's scale is underpinned by India's rapidly growing solar installed base, the increasing volume of first-cycle end-of-life panels entering the recycling stream, and rising investment in organized, technology-enabled processing infrastructure.
Mechanical commands 43.7% process share, reflecting its cost-effectiveness and readiness for scale. Crystalline silicon represents 91.6% of the type segment, driven by its widespread use in solar photovoltaic installations and the substantial volume of end-of-life panels requiring recycling. West India leads regional share at 31.8%, anchored by Rajasthan and Gujarat's large-scale solar installations and proximity to industrial recycling clusters.
Key Market Insights
|
Insight |
Data |
|
Leading Process |
Mechanical – 43.7% share (2025) |
|
Second Largest Process |
Thermal – 31.8% share (2025) |
|
Leading Type |
Crystalline Silicon – 91.6% share (2025) |
|
Second Largest Type |
Thin Film – 6.3% share (2025) |
|
Leading Region |
West India – 31.8% share (2025) |
|
Second Largest Region |
South India – 27.6% share (2025) |
|
Top Companies |
First Solar, Inc., Attero Recycling Pvt. Ltd., Jakson Engineers Ltd. |
Key Analytical Observations Expanding on the Data Above:
- Mechanical dominance at 43.7% reflects its lower capital requirement and operational readiness at current market scale, making it the preferred entry point for recycling operators across India.
- Thermal share at 31.8% is growing as operators invest in higher-efficiency separation systems that improve silver and silicon recovery rates from end-of-life crystalline panels.
- Crystalline silicon leadership at 91.6% is driven by its high power conversion efficiency, established manufacturing ecosystem, and widespread adoption across utility-scale and rooftop solar installations in India.
- Thin film at 6.3% is supported by demand for lightweight and flexible photovoltaic modules in specialized applications, including installations where conventional rigid panels face structural or space constraints.
- West India at 31.8% leads regional share due to Rajasthan and Gujarat hosting large utility-scale solar parks in India, generating high volume of first-cycle end-of-life panels.
India Solar Panel Recycling Market Overview
Solar panel recycling refers to the systematic recovery of valuable and hazardous materials from decommissioned photovoltaic modules, including silicon, silver, aluminum, glass, and lead. The process prevents hazardous leachate contamination from landfilled panels while recovering high-value materials for reuse in manufacturing supply chains. Applications range from precious metal recovery for electronics to cullet glass reuse in construction and polysilicon refining for new panel manufacturing.
The Indian ecosystem integrates raw material suppliers, solar panel manufacturers, end-of-life collectors, licensed recycling facilities, material refining units, and secondary market buyers. Government bodies, technology providers, and logistics partners form the supporting layer. Together, they enable a compliant, economically viable, and increasingly scalable recycling ecosystem across India's major solar-generating states.
Market Dynamics
To evaluate market opportunities, Request Sample
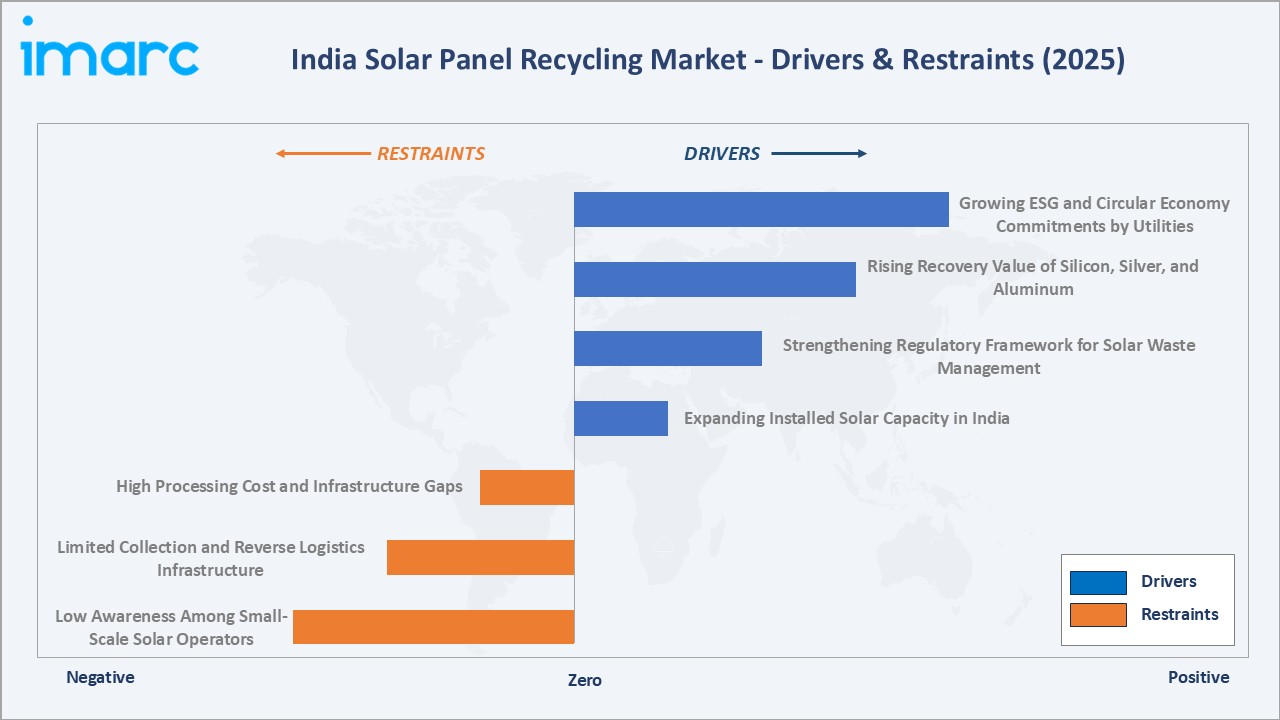
Market Drivers
- Expanding Installed Solar Capacity in India: India has set an ambitious target of 500 GW of renewable energy capacity by 2030, with solar comprising the majority of additions. This expanding installed base is generating a growing pipeline of end-of-life panels, directly enlarging the addressable recycling opportunity across all process segments.
- Strengthening Regulatory Framework for Solar Waste Management: Evolving waste management regulations and EPR requirements are encouraging solar manufacturers, project developers, and recyclers to establish structured collection, handling, and recycling systems for end-of-life photovoltaic modules, supporting responsible disposal and material recovery.
- Rising Recovery Value of Silicon, Silver, and Aluminum: Improving material separation technologies and rising commodity prices for polysilicon, silver, and aluminum are improving the unit economics of panel recycling, making it commercially viable beyond large-scale operators.
- Growing ESG and Circular Economy Commitments by Utilities: India's large solar developers and utilities are incorporating circular economy principles into their sustainability commitments, driving demand for certified end-of-life panel management solutions.
Market Restraints
- High Processing Cost and Infrastructure Gaps: Establishing compliant panel recycling facilities requires significant capital investment in specialized shredders, thermal chambers, and filtration systems, limiting market entry to well-funded operators and creating capacity gaps in smaller states.
- Limited Collection and Reverse Logistics Infrastructure: Fragmented collection networks, inadequate transportation systems, and limited access to specialized recycling facilities complicate the movement of end-of-life panels from dispersed solar installations to processing centers, constraining the growth of the solar panel recycling management market.
- Low Awareness Among Small-Scale Solar Operators: A significant share of rooftop and small commercial solar installations are managed by operators who lack awareness of end-of-life compliance requirements, limiting feedstock availability for organized recyclers.
Market Opportunities
- Development of Centralized Recycling Hubs: Establishing dedicated solar panel recycling clusters near India's major solar parks in Rajasthan, Gujarat, and Andhra Pradesh can significantly reduce logistics costs and improve feedstock aggregation efficiency.
- Export Demand for Recovered High-Purity Silicon: Recovered polysilicon and silicon wafer fragments from Indian recycling operations are increasingly attractive to global semiconductor and solar manufacturing supply chains, creating an export revenue stream that improves recycling economics.
Market Challenges
- Logistics and Reverse Supply Chain Complexity: Moving decommissioned panels, which are fragile, bulky, and potentially hazardous, from installation sites to recycling facilities across geographically dispersed locations presents significant logistical and cost challenges.
- Contamination and Quality Control in Material Recovery: Recovering high-purity materials from multi-layer panel structures without cross-contamination requires precise process control, making consistent output quality a persistent operational challenge for recyclers.
Emerging Market Trends
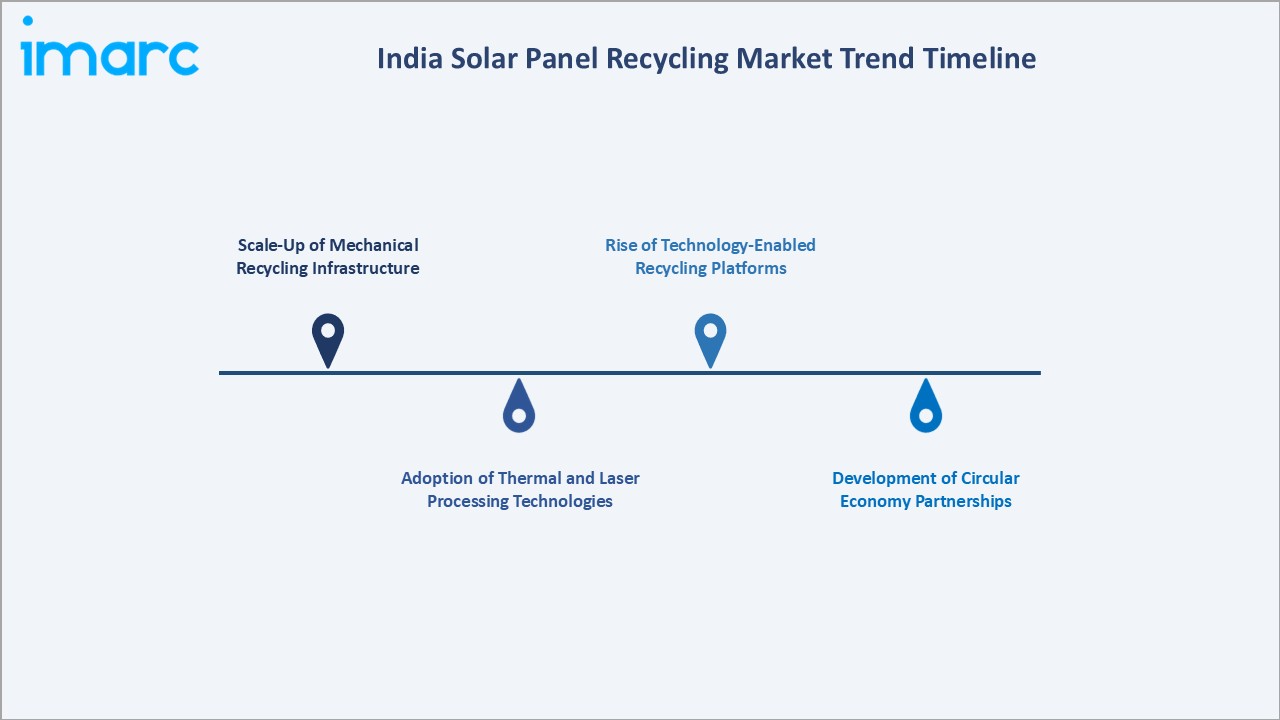
1. Scale-Up of Mechanical Recycling Infrastructure
Mechanical recycling, encompassing shredding, crushing, and sorting, remains the most commercially accessible process for Indian operators due to lower capital requirements and relatively straightforward technology integration. Capacity expansions across Rajasthan and Gujarat are increasing throughput, while automation is improving separation quality.
2. Adoption of Thermal and Laser Processing Technologies
Thermal delamination and laser-assisted separation are gaining traction for their superior material recovery rates, particularly for silver and silicon. These technologies also help improve separation precision and recover valuable components from complex photovoltaic module structures.
3. Development of Circular Economy Partnerships
Solar panel manufacturers, utilities, and recyclers are forming integrated partnerships to establish closed-loop material flows. Agreements enabling recovered silicon and silver to re-enter domestic manufacturing supply chains are emerging, supporting both cost reduction and sustainability goals for participating companies. Such collaborations are strengthening resource efficiency and creating new opportunities across the solar waste recycling market.
4. Rise of Technology-Enabled Recycling Platforms
Digital platforms linking decommissioning service providers, logistics operators, and recycling facilities are beginning to formalize the reverse supply chain. These platforms improve feedstock aggregation efficiency and provide compliance documentation, reducing friction for small-scale solar operators seeking certified end-of-life management.
Industry Value Chain Analysis
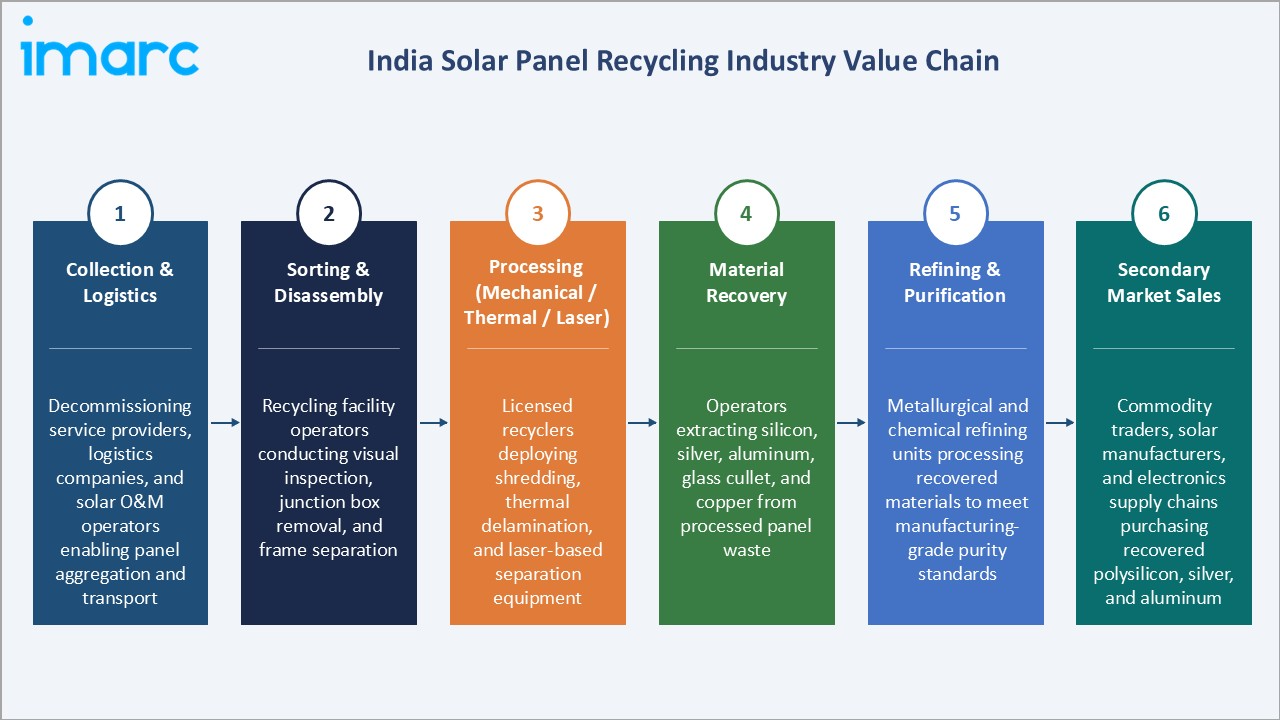
The India solar panel recycling value chain spans six stages, from collection and reverse logistics through material recovery and secondary market distribution. Processing, material recovery, and refining stages capture the highest value-add, while compliance documentation and certified end-of-life verification are increasingly determining competitive position in a regulatory-driven market.
|
Stage |
Key Players / Examples |
|
Collection & Logistics |
Decommissioning service providers, logistics companies, and solar O&M operators enabling panel aggregation and transport |
|
Sorting & Disassembly |
Recycling facility operators conducting visual inspection, junction box removal, and frame separation |
|
Processing (Mechanical / Thermal / Laser) |
Licensed recyclers deploying shredding, thermal delamination, and laser-based separation equipment |
|
Material Recovery |
Operators extracting silicon, silver, aluminum, glass cullet, and copper from processed panel waste |
|
Refining & Purification |
Metallurgical and chemical refining units processing recovered materials to meet manufacturing-grade purity standards |
|
Secondary Market Sales |
Commodity traders, solar manufacturers, and electronics supply chains purchasing recovered polysilicon, silver, and aluminum |
Vertically integrated operators controlling collection, processing, and material recovery are positioned to capture greater margin than single-stage recyclers dependent on spot feedstock and commodity buyers.
Technology Landscape in the India Solar Panel Recycling Industry
Mechanical Processing
Mechanical recycling, encompassing industrial shredding, hammer milling, and eddy-current separation, remains the predominant technology. It offers a cost-effective entry point for high-volume operations but produces mixed material fractions that require secondary processing for high-purity recovery.
Thermal Processing
Thermal delamination uses controlled heat to decompose EVA encapsulant layers, enabling clean separation of glass, silicon wafers, and metal contacts. The process achieves higher material purity than mechanical approaches and is gaining adoption among Indian operators investing in silver recovery at scale.
Laser Processing
Laser-assisted ablation selectively removes thin layers and contacts from panel surfaces without mechanical stress, enabling precise recovery of silver busbars and highly intact silicon wafers. While capital-intensive, the technology is attracting investment from technology-focused Indian recyclers targeting high-value material streams.
Automation and Process Integration
The top solar panel recycling companies in India are piloting robotic disassembly systems, automated sorting conveyors, and integrated chemical extraction units at their larger facilities. Automation improves throughput consistency, reduces labor intensity, and enhances safety management for hazardous material handling in panel processing operations.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Process |
Mechanical |
43.7% |
2025 |
|
Type |
Crystalline Silicon |
91.6% |
2025 |
|
Material |
🔒 |
🔒 |
2025 |
|
Shelf Life |
🔒 |
🔒 |
2025 |
|
Region |
West India |
31.8% |
2025 |
By Process
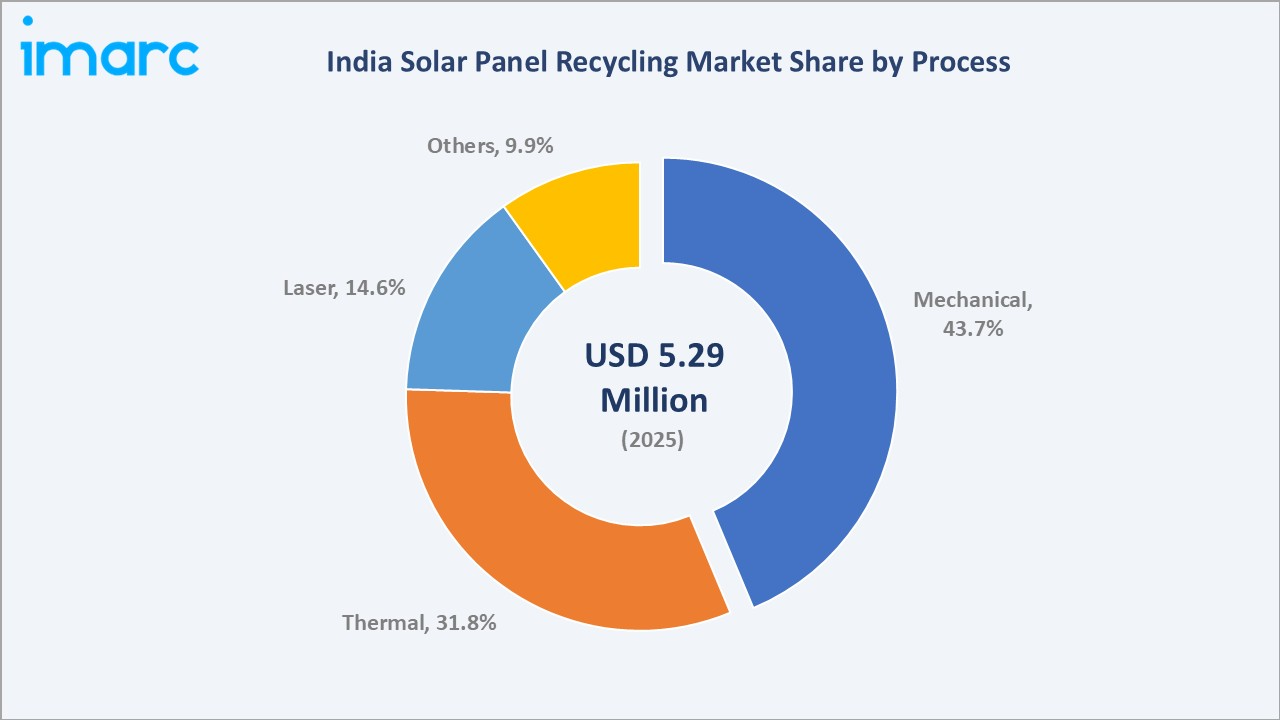
Mechanical commands a 43.7% majority share in 2025, driven by its lower capital cost, operational simplicity, and compatibility with India's current scale of end-of-life panel volumes. The segment benefits from availability of industrial shredding and sorting equipment from adjacent e-waste and metal recycling industries, supporting faster facility ramp-up across major solar states.
To access detailed market analysis, Request Sample
Thermal at 31.8% is the second-largest segment, supported by its ability to recover valuable materials, including silver and silicon, from end-of-life panels. Ongoing improvements in processing efficiency further enhance its potential for material recovery.
By Type
Crystalline silicon represents 91.6% of the type segment in 2025, directly reflecting its dominant share in India's installed solar base. Its widespread adoption across utility-scale and rooftop installations drives demand for recycling solutions as panels reach the end of their operational life.
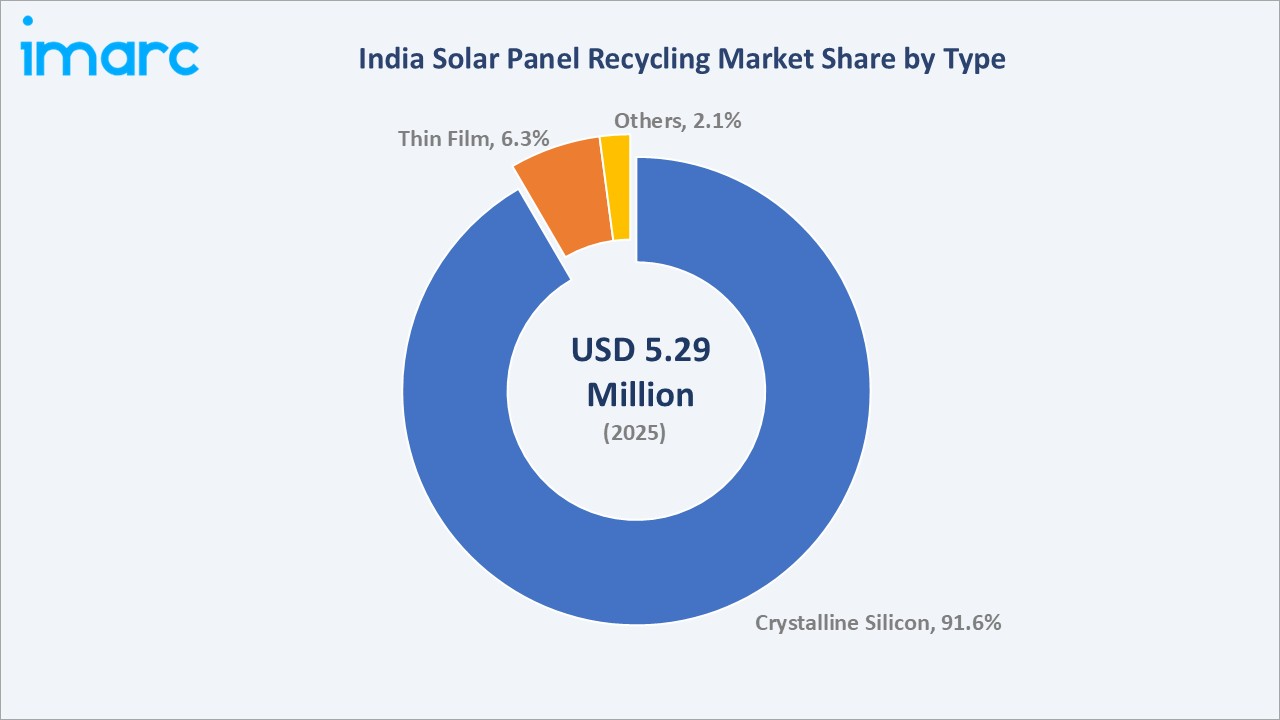
Thin film at 6.3% is a smaller but strategically important segment, supported by demand for lightweight modules and specialized photovoltaic applications requiring flexible installation options.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
West India |
31.8% |
Large utility-scale solar parks in Rajasthan and Gujarat, proximity to industrial recycling clusters, high panel decommissioning volumes, and established industrial infrastructure |
|
South India |
27.6% |
Strong solar installations in Andhra Pradesh, Telangana, and Karnataka, growing technology sector investment in recycling, and proximity to port-based material export channels |
|
North India |
24.3% |
Expanding solar capacity in Uttar Pradesh, Himachal Pradesh, and Punjab, growing government emphasis on green energy transition, and increasing panel installation maturity |
|
East India |
16.3% |
Emerging solar installations in Odisha and West Bengal, expanding industrial base, growing government infrastructure support, and rising awareness of compliant panel disposal |
West India at 31.8% in 2025 leads the regional landscape, anchored by extensive solar installations in Rajasthan and Gujarat and the growing availability of industrial infrastructure for solar panel collection and recycling.
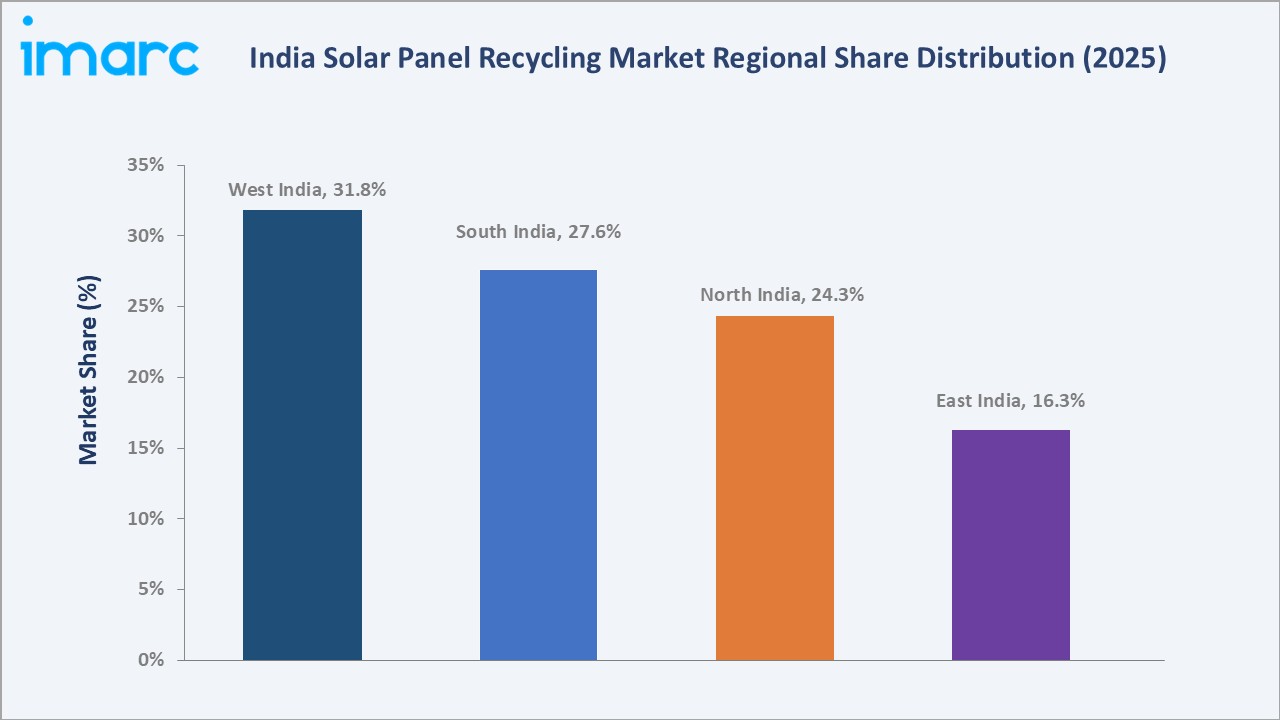
East India, while currently the smallest regional contributor at 16.3%, is expanding as solar installations in Odisha, West Bengal, and Jharkhand mature and as government industrial development initiatives improve recycling infrastructure access in the region.
Competitive Landscape
The India solar panel recycling market is fragmented, with a mix of global material technology companies, established domestic e-waste recyclers, and specialist solar recyclers competing on technology depth, material recovery efficiency, and regulatory compliance credentials. Scale, certified processing capability, and proximity to major solar installation clusters form the key competitive differentiators across the industry.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
|
First Solar, Inc. |
First Solar Recycling Service |
Leader |
Expanding end-of-life panel collection and processing capabilities through proprietary recycling infrastructure and technology investment |
|
Attero Recycling Pvt. Ltd. |
E-Waste Management |
Leader |
Growing solar panel recycling capacity alongside established e-waste operations and expanding certified processing footprint across India |
|
Jakson Engineers Ltd. |
Jakson Engineers |
Challenger |
Developing advanced solar PV module recycling capabilities through strategic technology partnerships, targeting high-value material recovery and large-scale processing capacity across India |
Key players include First Solar, Inc., Attero Recycling Pvt. Ltd., and Jakson Engineers Ltd., among others.
Key Company Profiles
First Solar, Inc.
First Solar, Inc. is a United States-based semiconductor manufacturer and solar energy company headquartered in Tempe, Arizona. The company operates an integrated panel recycling program designed to recover glass, semiconductor material, and metals from decommissioned modules.
- Product Portfolio: Thin-film photovoltaic modules and an integrated panel recycling program covering collection, transportation, and material recovery from end-of-life modules.
- Recent Developments: The company continues to advance its panel recycling infrastructure and expand its certified collection and processing capabilities across its operating markets.
- Strategic Focus: Strengthening proprietary end-of-life module recovery infrastructure and scaling certified collection logistics to support growing panel decommissioning volumes across international markets.
Attero Recycling Pvt. Ltd.
Attero Recycling Pvt. Ltd. is an Indian e-waste recycling company headquartered in Noida, Uttar Pradesh. The company operates a certified facility for processing electronic waste, including solar panels, recovering metals and materials for reuse in manufacturing supply chains.
- Product Portfolio: Integrated e-waste recycling services covering consumer electronics, industrial equipment, and solar panel end-of-life management, with certified material recovery operations across India.
- Recent Developments: The company continues to build its solar panel recycling capacity and broaden its certified processing services, supporting growing demand from Indian solar operators and regulatory compliance requirements.
- Strategic Focus: Building dedicated solar panel recycling capacity within its certified processing platform and expanding service coverage across major solar-producing states in India.
Jakson Engineers Ltd.
Jakson Engineers Ltd. is an Indian engineering company with a long-standing presence in the energy and infrastructure sectors. The company is developing solar PV module recycling capabilities in India, targeting large-scale processing of end-of-life photovoltaic panels.
- Product Portfolio: Engineering and energy sector services, with an emerging solar PV module recycling capability targeting high-value material recovery from end-of-life crystalline silicon panels.
- Recent Developments: The company is progressing its solar PV module recycling facility development, advancing technology partnerships and infrastructure activities in support of its planned processing operations in India.
- Strategic Focus: Establishing industrial-scale photovoltaic module recycling infrastructure through international technology collaboration, targeting high-yield material recovery across aluminum, glass, and semiconductor streams.
Market Concentration Analysis
The India solar panel recycling market is fragmented, with the top tier of operators, including domestic e-waste recyclers and global material technology companies, accounting for a modest share of overall processing volumes. The market's early-stage character limits concentration, with significant informal and unorganized activity still present alongside licensed operators.
Barriers to entry include capital requirements for compliant processing equipment, the need for CPCB authorization and EPR registration, technical expertise in hazardous material handling, and the logistics challenge of aggregating geographically dispersed end-of-life panels. These factors favor established e-waste recyclers and companies with existing compliance infrastructure over greenfield entrants.
Consolidation is at an early stage, with a few larger operators beginning to invest in expanded capacity ahead of anticipated regulatory mandate implementation. Strategic partnerships between solar developers and certified recyclers, and between technology providers and processing companies, are emerging as a key structure for scaling compliant recycling capacity in the near to medium term.
Investment & Growth Opportunities
Fastest-Growing Segments
Laser is expanding fastest among process sub-segments, driven by improving capital accessibility and growing awareness of its superior material recovery yields. Thin film is expected to grow at an above-average rate as thin film installations age and as the specialist handling requirements create a premium-priced service niche.
Emerging Markets
East India is the fastest-growing regional market, supported by expanding solar installations in Odisha, West Bengal, and Jharkhand, and by improving industrial infrastructure in those states. The region represents significant untapped opportunity for recyclers able to establish early-mover processing capacity ahead of regulatory mandate implementation.
Venture & Investment Trends
Investment activity is concentrated in technology-enabled recycling platforms, centralized recycling hub development near major solar parks, and precision material recovery systems for silver and polysilicon. Capital is also flowing into compliance and traceability technology platforms that address the documentation and certification requirements of EPR-compliant solar panel end-of-life management.
Future Market Outlook (2026-2034)
The India solar panel recycling market is projected to grow from USD 5.29 Million in 2025 to USD 6.38 Million in 2026, reaching USD 21.02 Million by 2034, registering a CAGR of 16.08% during 2026-2034.
Four forces will shape the market through 2034: implementation of mandatory EPR frameworks for solar panels; improving economics of silver and polysilicon recovery as separation technology matures; expansion of centralized recycling clusters near India's major solar states; and growing integration of recovered materials into domestic solar manufacturing supply chains.
By 2034, the India solar panel recycling market is expected to be characterized by a mix of technology-differentiated licensed operators, manufacturer-led take-back programs, and aggregation platforms linking dispersed small-scale installations to certified facilities. Continued solar capacity addition will sustain strong feedstock volume growth through the forecast period.
Research Methodology
Primary Research
Primary research included structured discussions with solar recycling facility operators, solar project developers, material recovery specialists, and regulatory officials, validating market sizing, segment mix, and regional demand patterns across the India solar panel recycling ecosystem.
Secondary Research
Secondary sources included MNRE publications, CPCB e-waste management data, Ministry of New and Renewable Energy reports, and public disclosures from listed solar manufacturers, utility companies, and recycling service providers operating in India.
Forecasting Models
Market forecasts used top-down and bottom-up models combining installed solar base projections, panel decommissioning rate assumptions, recycling penetration estimates, and material recovery economics. Scenario analysis addressed regulatory implementation pace, technology adoption rates, and infrastructure investment trends.
India Solar Panel Recycling Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Processes Covered | Thermal, Mechanical, Laser, Others |
| Types Covered | Crystalline Silicon, Thin Film, Others |
| Materials Covered | Metal, Glass, Aluminum, Silicon, Others |
| Shelf Lives Covered | Normal Loss, Early Loss |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | First Solar, Inc., Attero Recycling Pvt. Ltd., Jakson Engineers Ltd., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India solar panel recycling market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India solar panel recycling market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India solar panel recycling industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Solar Panel Recycling Market Report
The India solar panel recycling market size is estimated at USD 6.38 Million in 2026, driven by expanding solar installations, tightening EPR regulatory frameworks, and rising material recovery economics for silicon, silver, and aluminum from decommissioned photovoltaic panels.
The market is projected to grow at a CAGR of 16.08% from 2026 to 2034, reaching USD 21.02 Million by 2034, supported by EPR mandates and expanding organized recycling capacity.
Mechanical dominates the market at 43.7% process share in 2025, driven by its cost-effectiveness and operational readiness at current market scale.
Crystalline silicon represents 91.6% of the type segment in 2025, driven by its widespread adoption across utility-scale and rooftop solar installations in India, which generates a substantial volume of panels requiring end-of-life recycling.
West India commands 31.8% share in 2025, led by Rajasthan and Gujarat's large utility-scale solar parks generating high end-of-life panel volumes.
East India is the fastest-growing region, supported by expanding solar installations, improving industrial infrastructure, and rising government support for organized recycling.
Key players include First Solar, Inc., Attero Recycling Pvt. Ltd., and Jakson Engineers Ltd., among others.
Key drivers include India's expanding solar base, regulatory EPR frameworks, improving material recovery economics for silicon and silver, and growing ESG commitments by solar utilities.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade