
India Water Purifier Market Size, Share, Trends and Forecast by Technology Type, Distribution Channel, End User, and Region, 2026-2034
India Water Purifier Market Size, Share, Trends & Forecast (2026-2034)
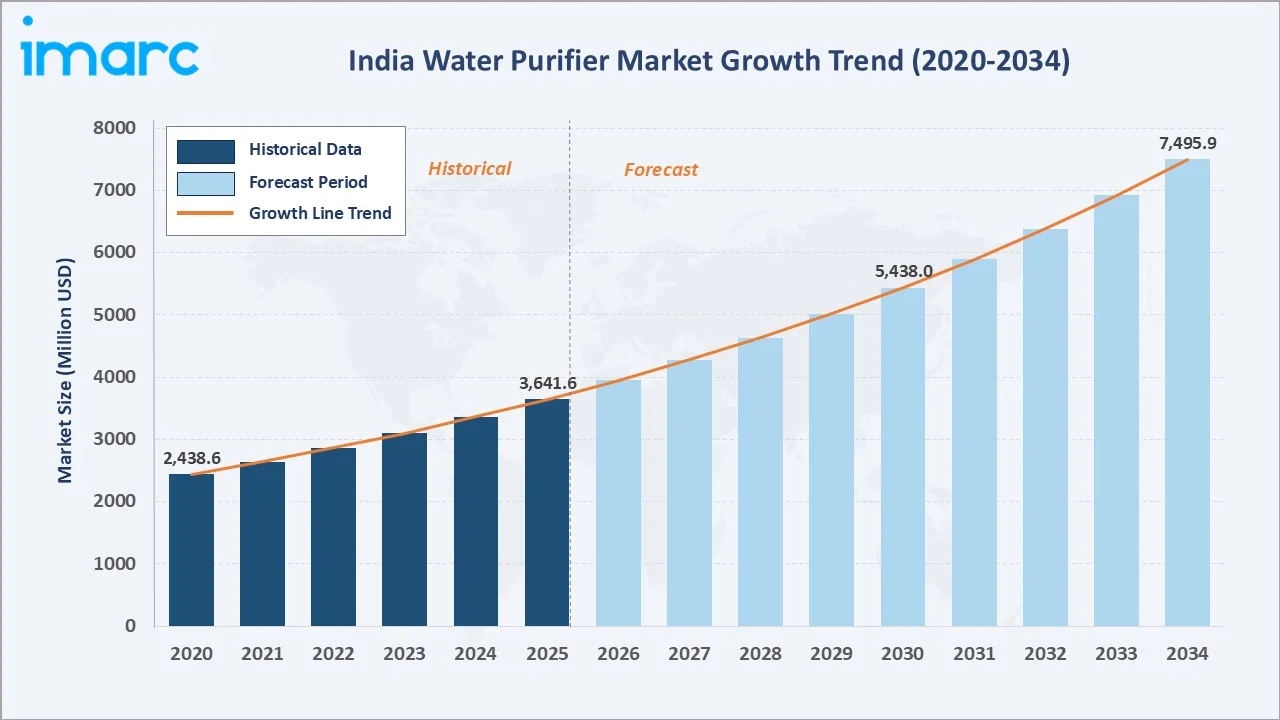
The India water purifier market grew from USD 3,641.6 Million in 2025 to USD 3,946.3 Million in 2026 and is projected to reach USD 7,495.9 Million by 2034, growing at a CAGR of 8.4% during 2026-2034. India's water purifier market is propelled by the country's severe and pervasive safe drinking water access deficit, combined with accelerating Jal Jeevan Mission piped water supply expansion creating new in-home purification demand, rapidly expanding e-commerce reaching Tier-2 and Tier-3 cities with affordable RO and UV purifiers, and growing health consciousness among India's urban middle class driving systematic upgrade from contaminated borewell dependence to purified household water. RO purifiers lead technology share at 36.0%, retail stores dominate distribution at 40.0%, and North India commands 30.0% regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 3,641.6 Million |
|
Market Size (2026) |
USD 3,946.3 Million |
|
Forecast Market Size (2034) |
USD 7,495.9 Million |
|
CAGR (2026-2034) |
8.4% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Technology Type |
RO Purifiers (36.0%, 2025) |
|
Dominant Distribution Channel |
Retail Stores (40.0%, 2025) |
|
Leading Region |
North India (30.0%, 2025) |
The India water purifier market grew from USD 2,438.6 Million in 2020 to USD 3,641.6 Million by 2025 and is estimated to reach USD 3,946.3 Million in 2026. The market is projected to reach USD 5,438.0 Million by 2030 and USD 7,495.9 Million by 2034.
To get more information on this market, Request Sample
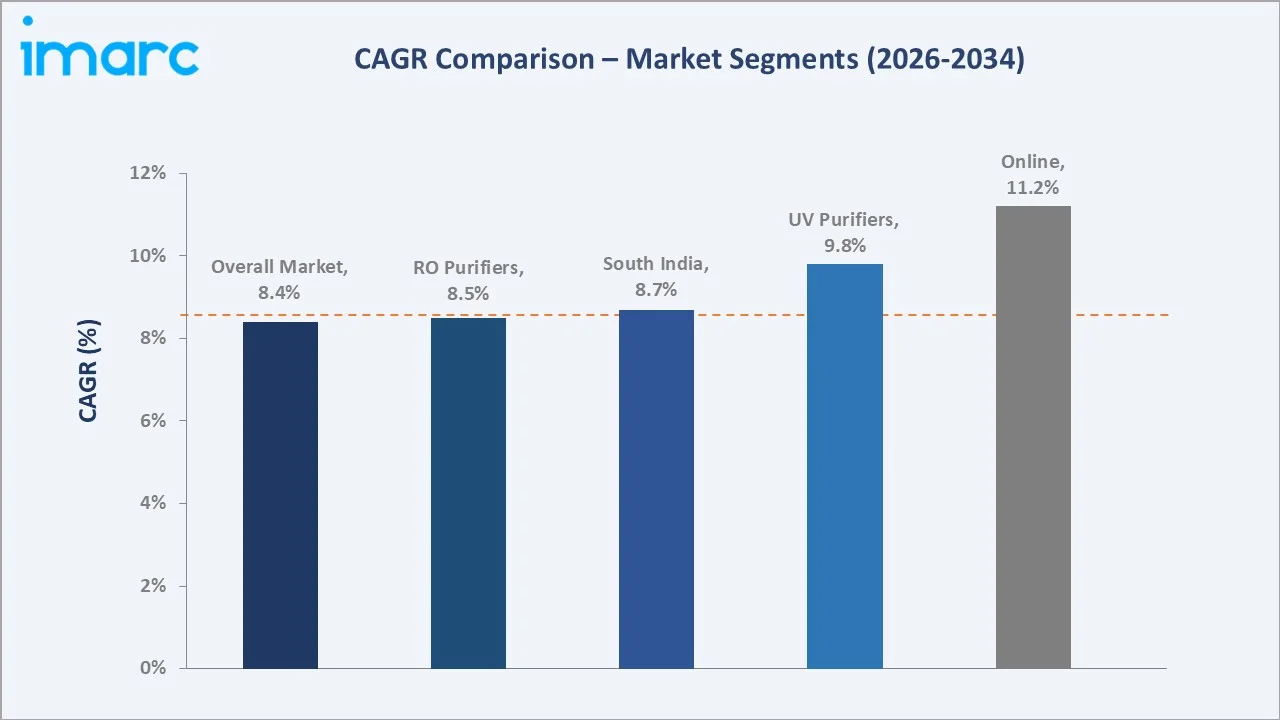
The online distribution channel grows fastest at ~11.2% CAGR through Amazon India, Flipkart, and brand e-stores, reaching price-sensitive Tier-2/3 consumers. UV purifiers expand at ~9.8% CAGR through biological contamination awareness and electricity-independent gravity UV combinations. South India leads regional growth at ~8.7% CAGR through premium smart purifier adoption and high baseline penetration driving upgrade cycles.
Executive Summary
The India water purifier market is one of the fastest-growing consumer durables categories, driven by the structural convergence of a severe national water quality crisis affecting hundreds of millions of households, rising consumer health awareness, affordable e-commerce distribution enabling first-time purifier purchase in previously inaccessible markets, and continuous product innovation spanning IoT-connected smart purifiers, mineral-enhancing water treatment systems, and subscription-based AMC service models.
RO purifiers command 36.0% of technology share through their superior TDS and heavy metal removal performance for India's highly contaminated groundwater. Retail stores lead distribution at 40.0% through organized retail and dealer networks enabling product demonstration. North India dominates at 30.0% through Delhi NCR's severe water contamination and high per-household purifier spending.
Key Market Insights
|
Insight |
Data |
|
Dominant Technology Type |
RO Purifiers - 36.0% share (2025) |
|
Dominant Distribution Channel |
Retail Stores - 40.0% share (2025) |
|
Leading Region |
North India - 30.0% (2025) |
|
Key Market Opportunity |
Rising demand for smart and IoT-enabled water purifiers, expansion into rural and Tier II/III markets, growing adoption of energy-efficient and low-water-wastage purification technologies, increasing demand for affordable subscription/rental models, and development of advanced multi-stage purification solutions for region-specific water quality issues. |
Key Analytical Observations Supporting the Above Data:
- RO Purifiers at 36.0%: Reverse osmosis purifiers dominate through their unique capability to remove dissolved solids (TDS), heavy metals (arsenic, lead, fluoride, nitrate), and biological contaminants simultaneously, addressing the comprehensive contamination profile of India's groundwater that gravity filters and UV-only systems cannot handle.
- Retail Stores at 40.0%: Retail stores lead through their combination of product demonstration capability, immediate availability for consumer purchase, and installation service coordination that digital channels cannot fully replicate for a category requiring in-home water line connection.
- North India at 30.0%: North India's market leadership reflects the region's uniquely severe water contamination profile combining high dissolved solids from overexploited groundwater aquifers, heavy metal contamination, and Delhi NCR's urban water supply crisis, where most of the piped water supplied fails quality standards.
India Water Purifier Market Overview
The India water purifier market encompasses household, institutional, and industrial water treatment appliances using physical and chemical filtration processes to remove biological contaminants (bacteria, viruses, protozoa), dissolved chemical pollutants (heavy metals, pesticides, nitrates), and physical impurities (sediment, turbidity) from drinking water. The technology spectrum spans reverse osmosis (RO) membrane systems, ultraviolet (UV) disinfection units, gravity-based activated carbon and nano-silver filter systems, sediment filtration cartridges, and water softeners for hard water treatment.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
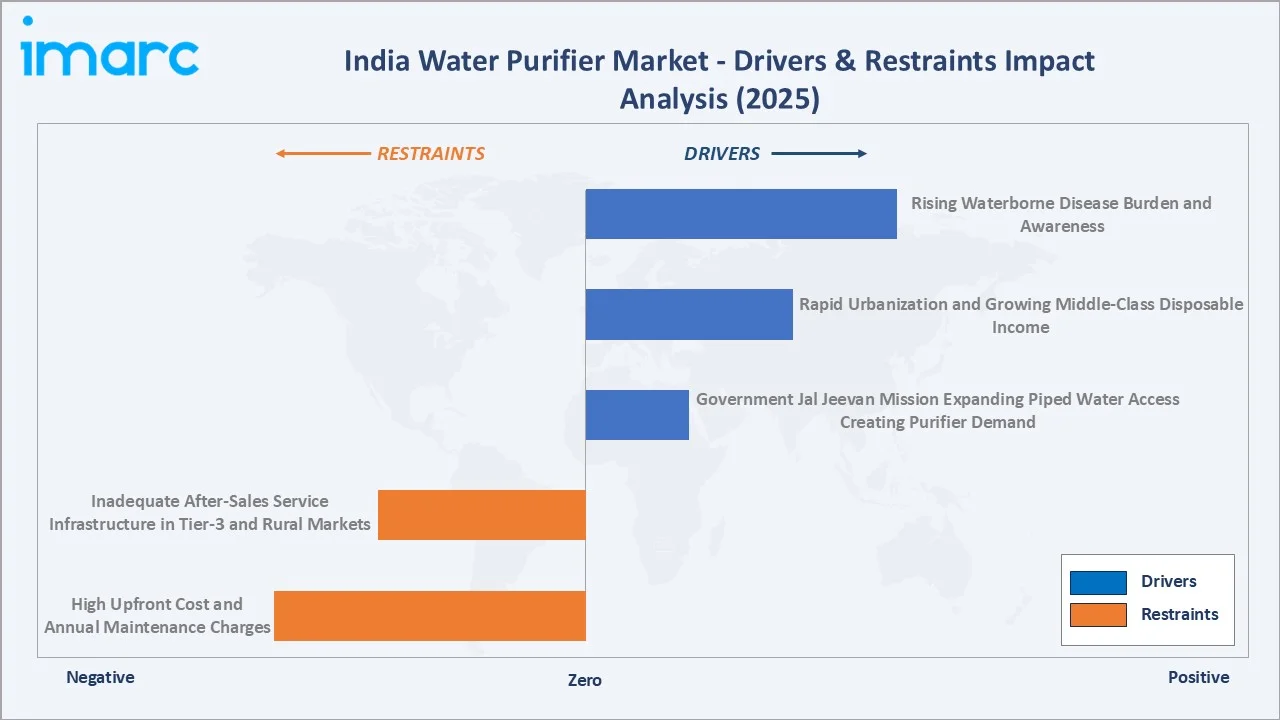
- Rising Waterborne Disease Burden and Awareness: India records approximately 37.7 Million cases of waterborne illness annually. The rising burden of waterborne diseases is increasing consumer awareness regarding the health risks associated with contaminated drinking water in India. Growing concerns over bacteria, viruses, heavy metals, and other impurities are encouraging households to adopt advanced water purification systems. Consequently, demand for RO, UV, UF, and multi-stage water purifiers is increasing across urban and rural areas.
- Rapid Urbanization and Growing Middle-Class Disposable Income: India's urban population is projected to reach 600 Million by 2031. Tier-2 and Tier-3 cities are generating first-generation water purifier adopters among rising middle-class households with high annual incomes that support RO purifier purchases. This Tier-2/3 urbanization wave is the primary volume growth driver.
- Government Jal Jeevan Mission Expanding Piped Water Access Creating Purifier Demand: As of October 22, 2025, over 81% of India’s rural households, or 15.72 crore homes, had access to safe tap water under the Jal Jeevan Mission. The Jal Jeevan Mission's piped water connection delivery to rural households creates a critical driver for water purifier demand by establishing the piped water infrastructure prerequisite for household purifier installation. Rural households receiving their first piped water connection become potential first-time purifier buyers as awareness grows that piped water from aging rural distribution infrastructure still requires in-home purification for biological contamination.
Market Restraints
- High Upfront Cost and Annual Maintenance Charges: High upfront costs of advanced water purifiers, particularly RO and multi-stage systems, limit adoption among price-sensitive households in India. Recurring expenses for filter and membrane replacement, servicing, and annual maintenance contracts further increase the total cost of ownership. These costs can discourage consumers in lower-income and rural segments from purchasing or upgrading water purifiers, thereby restraining market growth.
- Inadequate After-Sales Service Infrastructure in Tier-3 and Rural Markets: Inadequate after-sales service infrastructure in Tier-3 cities and rural areas is limiting the adoption of water purifiers in India. Limited availability of trained technicians, authorized service centers, and replacement filters often results in delayed maintenance and higher servicing costs. Since regular upkeep is essential for effective purification, weak service networks reduce consumer confidence and discourage purchases, thereby constraining market expansion in underserved regions.
Market Opportunities
- IoT-Connected Smart Water Purifiers for India's Digital Consumer: In India, approximately 85.5% of households have at least one smartphone. These smartphone users and the rapidly expanding smart home ecosystem create a large and growing addressable market for Wi-Fi-connected water purifiers with real-time filter life monitoring, water consumption tracking, TDS display, and smartphone app-based service scheduling.
- Water Purifier Subscription and Purification-as-a-Service Models: India's successful SaaS and subscription economy provides the commercial template for a water purifier subscription model (WAAS - Water as a Service) where consumers pay for purifier hardware placement, installation, filter replacement, and maintenance without upfront capital outlay.
Market Challenges
- Counterfeit and Non-Certified Water Purifier Products in Price-Sensitive Markets: India's water purifier market faces a significant counterfeit and non-compliant product problem, particularly in price-sensitive markets where local manufacturers sell non-certified RO systems without proven performance standards for bacteria removal, TDS reduction consistency, or long-term membrane quality.
- Water Waste and Environmental Concerns with RO Technology: Standard household RO purifiers reject wastewater for every 1 liter of purified output, generating significant water wastage in a water-stressed country where per-capita freshwater availability is declining. Brands are responding with tankless RO systems with 1:1 recovery ratios, brine recovery systems, and wastewater reuse recommendations for toilet flushing and floor cleaning, but consumer awareness and behavior change to reduce RO wastewater remain inadequate relative to the scale of the environmental challenge.
Emerging Market Trends
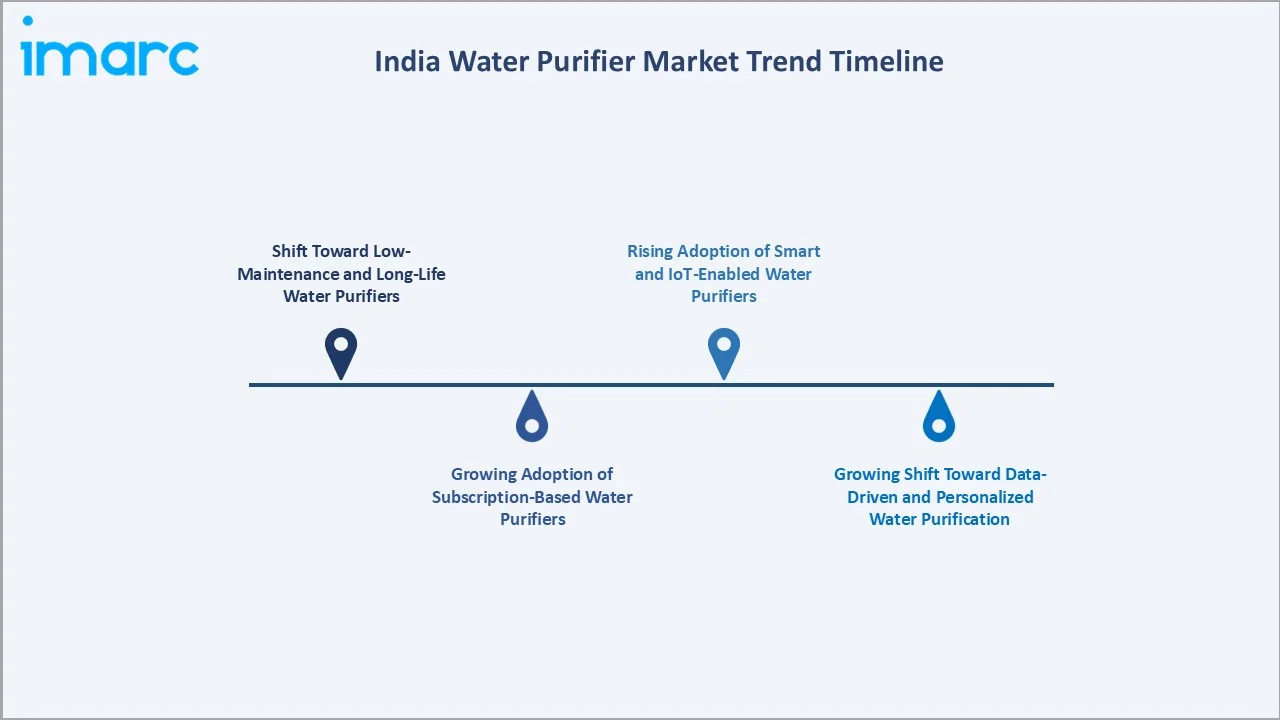
1. Shift Toward Low-Maintenance and Long-Life Water Purifiers
Manufacturers are increasingly introducing advanced RO systems with longer-lasting filters and reduced maintenance requirements, improving convenience and lowering the total cost of ownership for consumers. In August 2026, Urban Company’s sub-brand Native launched the M3 and M3 Pro premium RO water purifiers in India, featuring filters designed to last up to three years without routine servicing or replacement. The company claims the low-maintenance design could help consumers save up to INR 26,000 over nine years.
2. Growing Adoption of Subscription-Based Water Purifiers
The India water purifier market is witnessing a shift toward rental and subscription-based models, enabling consumers to access purification systems at affordable monthly costs without high upfront investment. Bundled maintenance and periodic filter replacements further reduce ownership hassles, making these models increasingly attractive to cost-conscious households. In July 2026, RentoMojo expanded its Delhi-NCR presence by introducing rentals for its own water purifiers, starting at INR 292 per month. The subscription includes free filter replacements every six months and comprehensive maintenance, helping consumers reduce ownership and servicing costs while improving access to reliable water purification solutions.
3. Rising Adoption of Smart and IoT-Enabled Water Purifiers
Manufacturers are integrating smart controls and advanced purification technologies to enhance convenience, enable predictive maintenance, and differentiate premium product offerings. In July 2026, KENT RO Systems expanded its water purifier portfolio with the launch of the KENT Sapphire IoT, an advanced RO purifier featuring smart connectivity and enhanced purification technology. The system delivers mineral-rich drinking water while allowing users to remotely monitor and manage purifier performance through IoT-enabled features.
4. Growing Shift Toward Data-Driven and Personalized Water Purification
In June 2026, Atomberg Technologies launched a free Pincode-Level Water Quality Intelligence Tool, claimed to be the first of its kind in India, enabling households to assess local water quality and select a water purifier suited to their specific purification needs. Digital water-quality intelligence tools are supporting more personalized purchasing decisions while encouraging manufacturers to develop purification systems tailored to regional contamination profiles.
Industry Value Chain Analysis
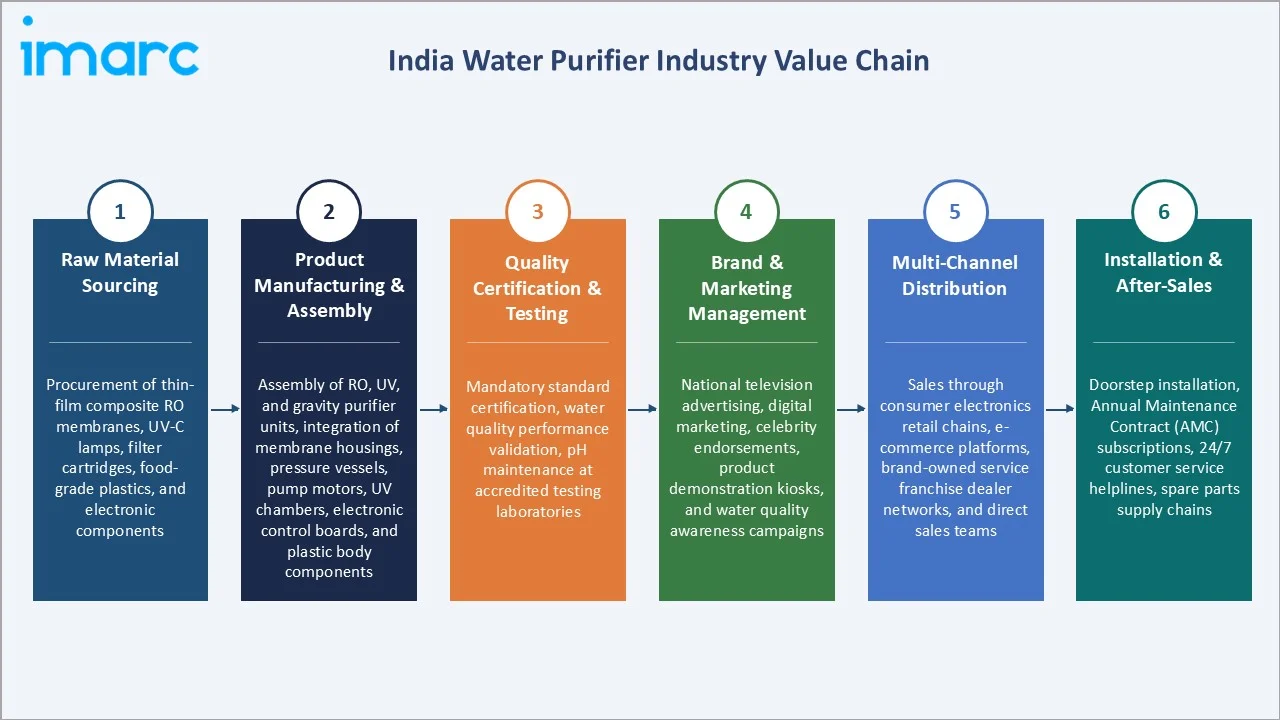
The India water purifier market value chain encompasses six stages from raw material sourcing through installation and after-sales service, with each stage representing distinct competitive advantages and market access requirements.
|
Stage |
Description |
|
Raw Material Sourcing |
Procurement of thin-film composite RO membranes, UV-C lamps, filter cartridges, food-grade plastics, and electronic components. |
|
Product Manufacturing & Assembly |
Assembly of RO, UV, and gravity purifier units, integration of membrane housings, pressure vessels, pump motors, UV chambers, electronic control boards, and plastic body components. |
|
Quality Certification & Testing |
Mandatory standard certification, water quality performance validation, pH maintenance at accredited testing laboratories. |
|
Brand & Marketing Management |
National television advertising, digital marketing, celebrity endorsements, product demonstration kiosks, and water quality awareness campaigns. |
|
Multi-Channel Distribution |
Sales through consumer electronics retail chains, e-commerce platforms, brand-owned service franchise dealer networks, and direct sales teams. |
|
Installation & After-Sales |
Doorstep installation, Annual Maintenance Contract (AMC) subscriptions, 24/7 customer service helplines, spare parts supply chains. |
Installation and after-sales service represent the highest-value competitive differentiation stage in India's water purifier market, where the quality, speed, and reliability of post-sale service determine customer retention, AMC renewal rates, and word-of-mouth referral that is the most important lead generation mechanism for India's water purifier category.
Technology Landscape in the India Water Purifier Industry
Reverse Osmosis Technology Evolution and Mineral Recovery Innovation
India's RO water purifier technology is advancing through several parallel development tracks addressing the dual consumer challenges of water quality optimization and water waste reduction. High-recovery RO systems are entering India's premium market through brands, addressing India's growing water conservation consciousness without compromising purification performance. Remineralization stages are standard features in premium RO systems, addressing the concern that RO's TDS removal also strips beneficial minerals.
UV Purification and Multi-Stage Combination Technology
UV water purification technology is evolving from single-stage bacterial disinfection toward multi-stage combination systems incorporating UV-C LED technology, ultrafiltration (UF) membrane stages for virus and colloid removal, and activated carbon post-filtration for taste and odor improvement. UV-C LED technology is enabling a new generation of flow-through UV purifiers without storage tanks for always-on purified water availability.
Digital Water Quality Monitoring and Smart Purifier Technology
Digital water quality monitoring is becoming a standard feature across India's premium purifier market, with real-time TDS meters, filter life indicators, water volume tracking, and quality parameter displays enabling consumer visibility into purifier performance that was previously inaccessible without laboratory testing. IoT connectivity is the next frontier of digital purifier technology, reaching commercial scale in India's premium consumer segment.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Technology Type |
RO Purifiers |
36.0% |
2025 |
|
Distribution Channel |
Retail Stores |
40.0% |
2025 |
|
End User |
Household |
44.0% |
2025 |
|
Region |
North India |
30.0% |
2025 |

By Technology Type
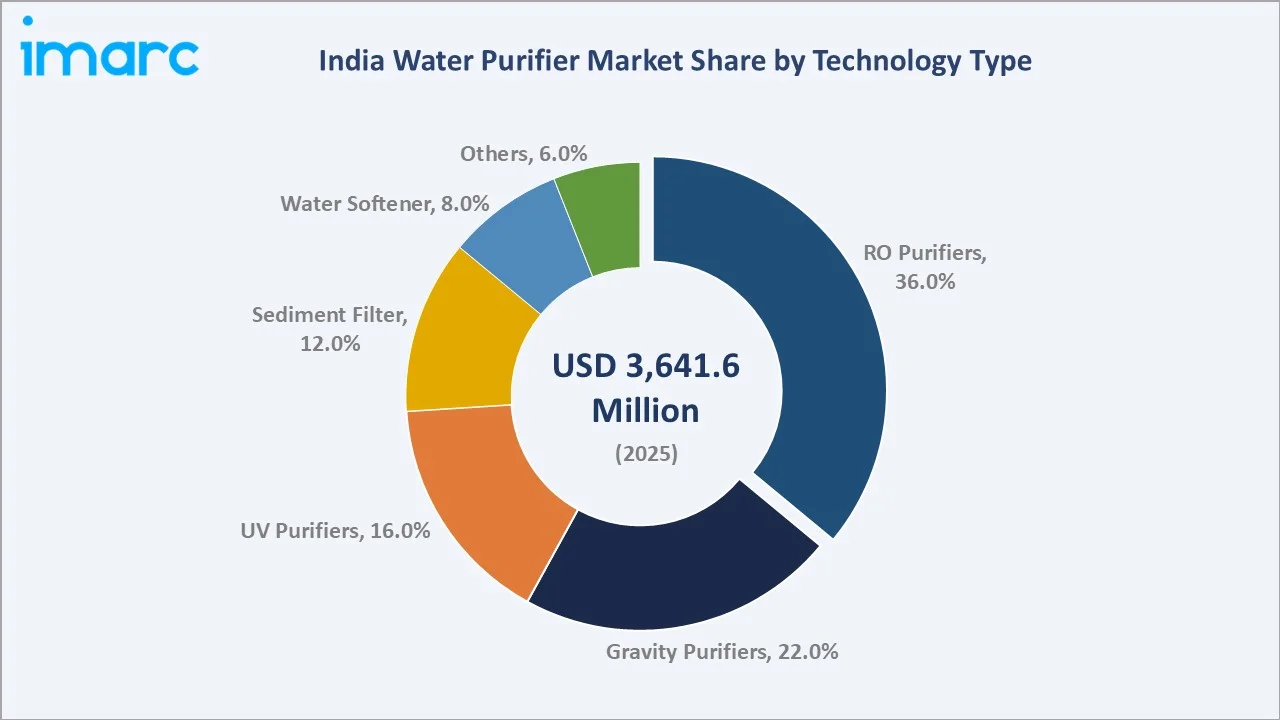
RO purifiers command 36.0% in 2025, driven by their multi-contaminant removal superiority for India's diverse and severe groundwater contamination profile. India's groundwater quality challenge creates a uniquely complex purification requirement that only membrane-based RO systems can comprehensively address.
To access detailed market analysis, Request Sample
Gravity purifiers at 22.0% serve India's large price-sensitive rural and semi-urban consumer base through zero-electricity operation. UV purifiers at 16.0% grow at ~9.8% CAGR through biological contamination awareness in low-TDS but high-bacteria water supply regions. Sediment filters at 12.0% serve pre-filtration and standalone turbidity removal needs. Water softeners at 8.0% address India's hard water regions in coastal areas. Others at 6.0% include alkaline ionizers and portable purifiers.
By Distribution Channel
Retail stores lead at 40.0%, serving consumers who prioritize product demonstration, same-day purchase, and immediate installation coordination. India's consumer electronics retail chain expansion provides organized retail infrastructure where branded water purifiers occupy dedicated category sections with working demonstration units, trained category specialists, and in-store installation booking services that replicate the direct sales model at scale.
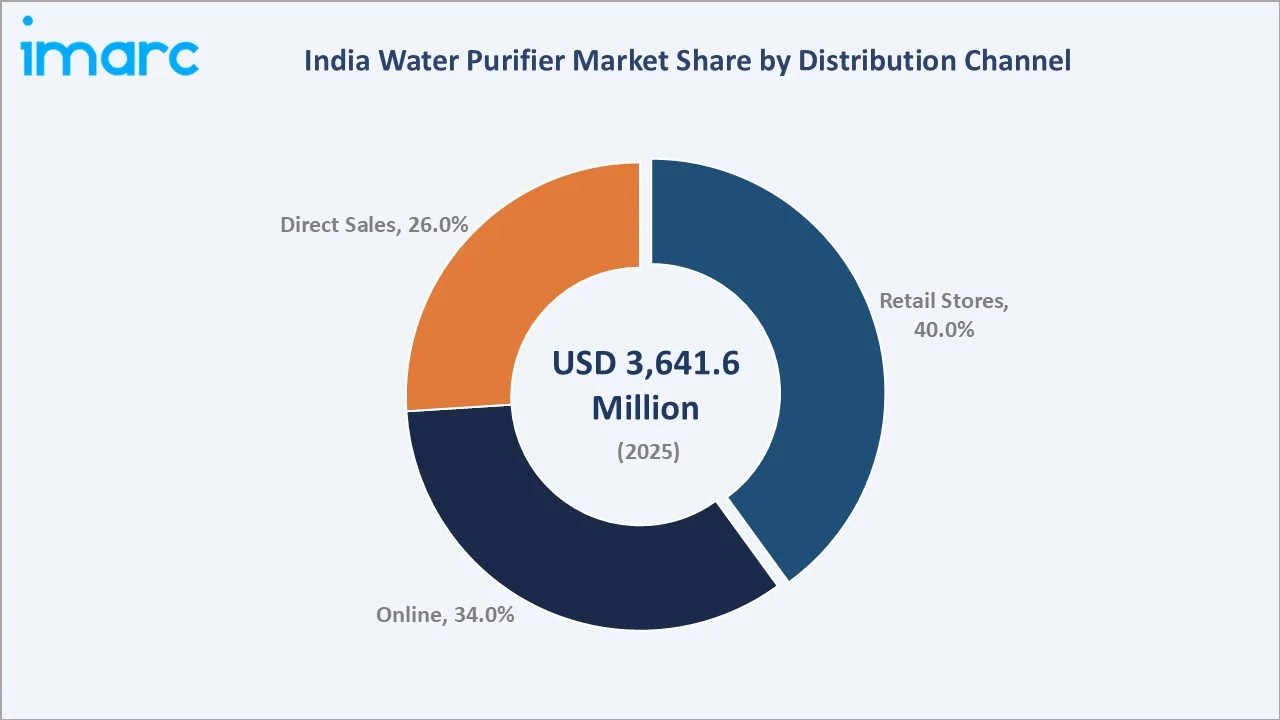
The online channel at 34.0% grows fastest at ~11.2% CAGR through Amazon India, Flipkart, and brand e-stores, enabling price-transparent comparison shopping, reaching Tier-2/3 consumers without local retail access, and EMI purchases with zero-cost financing for purifiers. Direct sales at 26.0% encompasses a direct salesperson model, dealer network direct installation, and brand-owned exclusive franchise showrooms that combine sales and service in a single consumer engagement.
Regional Market Insights
|
Region |
Share (2025) |
Key India Water Purifier Market Drivers & Characteristics |
|
North India |
30.0% |
North India leads through a combination of severe groundwater contamination challenges, high urban consumer density, and the region's historically above-average water quality concern culture driving per-household purifier adoption. |
|
South India |
27.0% |
South India's strong water purifier market reflects the region's combination of high urban consumer awareness of water quality issues, elevated per-capita incomes, particularly in tech economy populations, and the highest water purifier penetration rate among Indian regions, with urban South Indian households owning water purifiers. |
|
West and Central India |
25.0% |
West and Central India's water purifier market is anchored by high population and a well-developed organized retail purifier channel alongside a rapidly growing middle-class consumer market. |
|
East India |
18.0% |
East India represents the most significant under-penetrated growth opportunity, significantly below the national urban average. West Bengal's acute arsenic contamination crisis creates urgent public health demand for arsenic-removing purifiers that standard RO technology provides. |
North India's 30.0% market leadership reflects Delhi NCR's structural position as India's water quality crisis epicenter, where the combination of highly contaminated river source water, aging distribution infrastructure adding biological contamination, and seasonal groundwater stress creates year-round consumer urgency for reliable water purification that no other Indian region experiences at equivalent scale and income concentration.
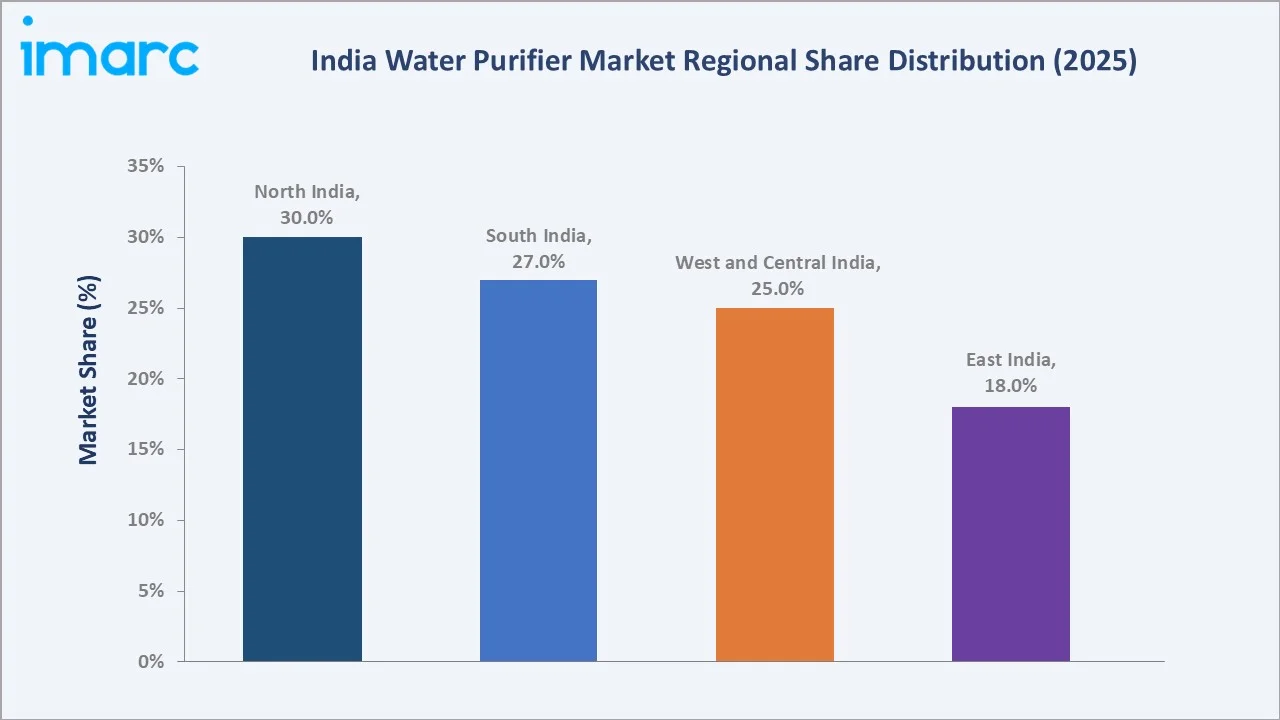
South India at 27.0% leverages the highest household penetration rate and premium upgrade cycle among established purifier users. West and Central India at 25.0% grows through organized retail and an expanding middle class. East India at 18.0% represents the highest-growth opportunity frontier through West Bengal's arsenic crisis urgency, first-generation adoption wave, and Jal Jeevan Mission infrastructure creating piped water prerequisite for rural purifier demand.
Competitive Landscape
India water purifier market features a concentrated competitive structure through brand equity accumulated over decades of advertising investment, national service network infrastructure, and certified product portfolios spanning multiple price tiers and technology types.
|
Company |
Key Products |
Market Position |
Core Strength |
|
KENT |
KENT Supreme IoT 2Y, KENT Ace IoT 2Y, KENT Supreme Plus Neo 2Y, KENT New Grand, KENT Sapphire IoT RO Water Purifier, KENT Pearl IoT RO Water Purifier |
Market Leader |
KENT is a pioneer and market leader in the Indian water purifier industry, credited with introducing and popularizing Reverse Osmosis (RO) technology to tackle varying water conditions across Indian households. |
|
A.O. Smith |
Pureit Lithos 2X RO Purifier, Pureit Revito Prime Mineral RO+MF+UV Water Purifier, Pureit Ultima Eco Mineral RO+UV+MF Water Purifier |
Market Leader |
A.O. Smith is a major premium player in the Indian water purifier market, known for introducing energy-efficient, high-recovery Reverse Osmosis (RO) systems and advanced multi-stage purification technologies. |
|
Havells India Ltd. |
Havells FAB NEO Water Purifier, Havells Aquas Neo Water Purifier, Havells Aquas Pro Water Purifier, Havells Aquas Pro 3X RO+UV Water Purifier |
Established Player |
Havells India Ltd. is a major player in the Indian water purifier market, having successfully transitioned from a traditional electrical goods manufacturer into a comprehensive consumer durable brand. |
|
Tata Sons Private Limited |
Tata Swach Viva Silver UV+UF, TATA SWACH SMART, TATA SWACH SILVER BOOST |
Established Player |
Tata Sons Private Limited spearheaded the launch of Tata Swach to provide affordable, safe drinking water to rural and low-income communities in India. |
|
Xiaomi |
Mi Smart Water Purifier (RO + UV), Mijia Smart Water Purifier N800G |
Innovator |
Xiaomi entered the Indian water purifier market by launching the Mi Smart Water Purifier (RO+UV), aiming to disrupt the home appliance sector with smart features and user maintenance. |
Competitive dynamics are shifting through the convergence of e-commerce democratizing distribution, smart purifier technology creating a premium innovation sub-market where technology differentiation rather than advertising spend determines consumer preference, and subscription models potentially restructuring the category economics from one-time hardware sales to recurring service revenue that rewards brands with superior after-sales capability over those with superior manufacturing scale.
Key Company Profiles
KENT
KENT is a prominent player in the India water purifier market, offering a diversified portfolio of RO, UV, UF, and gravity-based purification systems. The company serves residential and commercial customers through an extensive distribution and service network. KENT emphasizes advanced purification technologies, product innovation, and water-quality management to address varying consumer requirements. Its portfolio increasingly incorporates features such as mineral retention, digital monitoring, and smart connectivity. The company continues to strengthen its market presence through product launches, brand development, and expansion of its sales and after-sales capabilities.
- Key Products: KENT Supreme IoT 2Y, KENT Ace IoT 2Y, KENT Supreme Plus Neo 2Y, KENT New Grand, KENT Sapphire IoT RO Water Purifier, KENT Pearl IoT RO Water Purifier.
- Recent Developments: In July 2026, KENT RO Systems strengthened its water purification portfolio with the launch of the KENT Sapphire IoT, an advanced RO purifier featuring smart connectivity. The product combines mineral-rich water purification with IoT capabilities that allow users to conveniently monitor and manage purifier performance.
- Strategic Focus: Focuses on product innovation, advanced purification technologies, and smart connected solutions to strengthen its position in the India water purifier market. The company also emphasizes portfolio expansion, wider distribution and after-sales coverage, and solutions tailored to varying regional water-quality requirements.
A.O. Smith
A. O. Smith is an established participant in the India water purifier market, offering a range of residential water purification solutions. The company focuses on advanced RO purification technologies, water recovery, and solutions designed to address varying water-quality conditions. Its product portfolio emphasizes performance, durability, convenience, and modern design. A. O. Smith supports its market presence through distribution channels and after-sales services across India. The company continues to emphasize technology-driven product development to meet evolving consumer requirements.
- Key Products: Pureit Lithos 2X RO Purifier, Pureit Revito Prime Mineral RO+MF+UV Water Purifier, Pureit Ultima Eco Mineral RO+UV+MF Water Purifier.
- Strategic Focus: Focuses on technology-driven product innovation, advanced RO purification, and water-efficient solutions to address evolving consumer requirements in India. The company also emphasizes premium product positioning, distribution expansion, and reliable after-sales services to strengthen its presence in the water purifier market.
Market Concentration Analysis
India water purifier market exhibits moderate-to-high concentration in the organized segment, with KENT, A.O. Smith, Havells India Ltd., and Tata Sons Private Limited collectively commanding an estimated 65-75% of organized purifier market revenue. This concentration is built on decade-long brand equity investment, certification infrastructure, and service network development that create meaningful barriers for new entrants without equivalent capital commitments. However, e-commerce disruption is enabling well-funded challengers to gain market share without the traditional dealer network investment.
The unorganized market, consisting of local RO assemblers, non-certified imported systems, and regional brands, is estimated to represent 25-30% of total India water purifier unit sales, primarily concentrated in Tier-3 and rural markets where price sensitivity outweighs brand considerations. Progressive BIS enforcement and consumer awareness growth are expected to gradually shift this unorganized market share toward organized branded products through the forecast period.
Investment & Growth Opportunities
Highest Growth Segments
Online distribution (~11.2% CAGR), UV purifier technology segment (~9.8% CAGR), IoT smart water purifiers, subscription WAAS models, institutional/commercial water treatment, East India rural purifier penetration through Jal Jeevan Mission, affordable gravity purifier innovation for rural markets, and water purifier export from India's growing manufacturing base represent the highest-return investment opportunities through 2034.
Investment Themes
- Subscription Water Purification Service Platform: India's WAAS (Water as a Service) subscription model is validated by subscriber base and represents the most transformative business model innovation in the category. Investment in a full-stack subscription water purification platform could capture high recurring revenue per household from India's middle-class urban households currently owning or considering water purifiers.
- Rural Water Purification for Jal Jeevan Mission Beneficiary Households: Jal Jeevan Mission rural household connections represent an enormous first-time purifier addressable market as households receiving piped water for the first time recognize in-home purification needs. Investment in affordable gravity purifiers with arsenic and fluoride removal capability, microfinance-enabled EMI purchase programs for rural households, and government procurement partnerships for subsidized purifier distribution in contamination-affected districts could capture this historically underserved market at scale through government program alignment.
Future Market Outlook (2026-2034)
The India water purifier market is projected to grow from USD 3,641.6 Million in 2025 to USD 3,946.3 Million in 2026, reaching USD 7,495.9 Million by 2034, exhibiting a CAGR of 8.4% during 2026-2034. The market is projected to reach USD 5,438.0 Million by 2030, the mid-period milestone when subscription WAAS models are expected to represent 20-25% of organized purifier revenue, IoT-connected smart purifiers will reach 35-40% of premium segment sales, East India's market will have achieved above-national-average growth through Jal Jeevan Mission infrastructure maturation, and the organized market's share of total India purifier unit sales will have grown as BIS enforcement and consumer brand awareness reduce the unorganized market's share.
Three transformative forces will shape India's water purifier market through 2034. First, the subscription model transformation will create a more stable, predictable market revenue trajectory while significantly improving purifier penetration rates by removing the upfront capital barrier for middle-income households currently priced out of the category. Second, the geographic expansion frontier will add new purifier consumer households to the addressable India market by 2034. Third, the technology premiumization trajectory will structurally elevate India's average water purifier selling price, generating above-volume revenue CAGR that compounds with the geographic penetration expansion driving unit volume growth.
Research Methodology
Primary Research
Primary research comprised structured interviews with water purifier brand marketing managers and sales directors, organized retail category buyers, e-commerce category managers, technical committee members for water purifier standards, state officials managing Jal Jeevan Mission implementation, and independent water quality testing laboratory directors. Consumer demand validation incorporated structured surveys with urban and semi-urban India household respondents.
Secondary Research
Secondary research incorporated certification database analysis for registered water purifier products, India groundwater quality data for regional contamination mapping, water quality strategy documents, Ministry of Jal Jeevan Mission progress reports, India water purifier shipment statistics, company annual reports and investor presentations, product listing and review data analysis, and India household consumer electronics ownership survey data.
Forecasting Models
Market forecasting integrated India household income distribution trajectory projections, urban population growth forecasts, Jal Jeevan Mission rural connection completion timelines and rural purifier adoption uptake modeling, e-commerce penetration trajectory analysis by city tier, certification market share displacement of unorganized segment, technology mix evolution modeling from IoT adoption rate analysis in adjacent consumer electronics categories, and average selling price trajectory projections accounting for premiumization and subscription model revenue reporting changes.
India Water Purifier Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Technology Types Covered | Gravity Purifiers, RO Purifiers, UV Purifiers, Sediment Filter, Water Softener, Others |
| Distribution Channels Covered | Retail Stores, Direct Stores, Online |
| End Users Covered | Industrial, Commercial, Household |
| Regions Covered | North India, West and Central India, South India, East India |
| Companies Covered | KENT, A.O. Smith, Havells India Ltd., Tata Sons Private Limited, Xiaomi, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Frequently Asked Questions About the India Water Purifier Market Report
The India water purifier market reached USD 3,946.3 Million in 2026, driven by India's severe waterborne disease burden, Jal Jeevan Mission piped water expansion creating purification demand, e-commerce enabling Tier-2/3 city purifier access, and rising middle-class health consciousness.
The market is projected to grow at a CAGR of 8.4% during 2026-2034, driven by e-commerce expansion, IoT smart purifier adoption, subscription WAAS model growth, Jal Jeevan Mission rural infrastructure enabling rural adoption, and Tier-2/3 city middle-class income growth.
The market is projected to reach USD 5,438.0 Million by 2030, when subscription WAAS models' growth, smart IoT purifiers premium segment sales, East India's growth, Jal Jeevan Mission maturation, and organized brands' share growth.
RO purifiers lead with a 36.0% share in 2025, driven by their superior multi-contaminant removal capability addressing India's complex groundwater contamination profile, including dissolved solids, heavy metals (arsenic, fluoride), biological pathogens, and chemical pollutants that gravity and UV-only systems cannot comprehensively address.
Retail stores lead with a 40.0% share in 2025, through organized retail chains and dealer networks enabling product demonstration, same-day purchase, and installation coordination for a category requiring in-home water line connection that purely digital channels cannot fully replicate.
North India leads with a 30.0% share in 2025, through urban population facing severe water contamination, rapidly growing middle class, and North India's above-national-average consumer willingness to invest in premium water purification driven by visible and documented water quality crises.
Key players include KENT, A.O. Smith, Havells India Ltd., Tata Sons Private Limited, and Xiaomi, among others.
The market is projected to reach USD 7,495.9 Million by 2034, driven by subscription WAAS model transformation improving penetration among income-constrained households, geographic expansion across East India and rural Jal Jeevan Mission areas adding new consumer households, and technology premiumization.
Key investment opportunities include subscription WAAS platform development targeting new middle-income subscribers, affordable rural gravity purifier innovation for Jal Jeevan Mission beneficiary households, smart water quality monitoring data platforms combining IoT purifier sensor data with groundwater contamination mapping, and institutional commercial water treatment for India's growing hospitality, food service, and healthcare facility sectors.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade