Indonesia Cyber Insurance Market Size, Share, Trends and Forecast by Component, Insurance Type, Organization Size, End-Use Industry, and Region, 2026-2034
Indonesia Cyber Insurance Market Size, Share, Trends & Forecast (2026-2034)
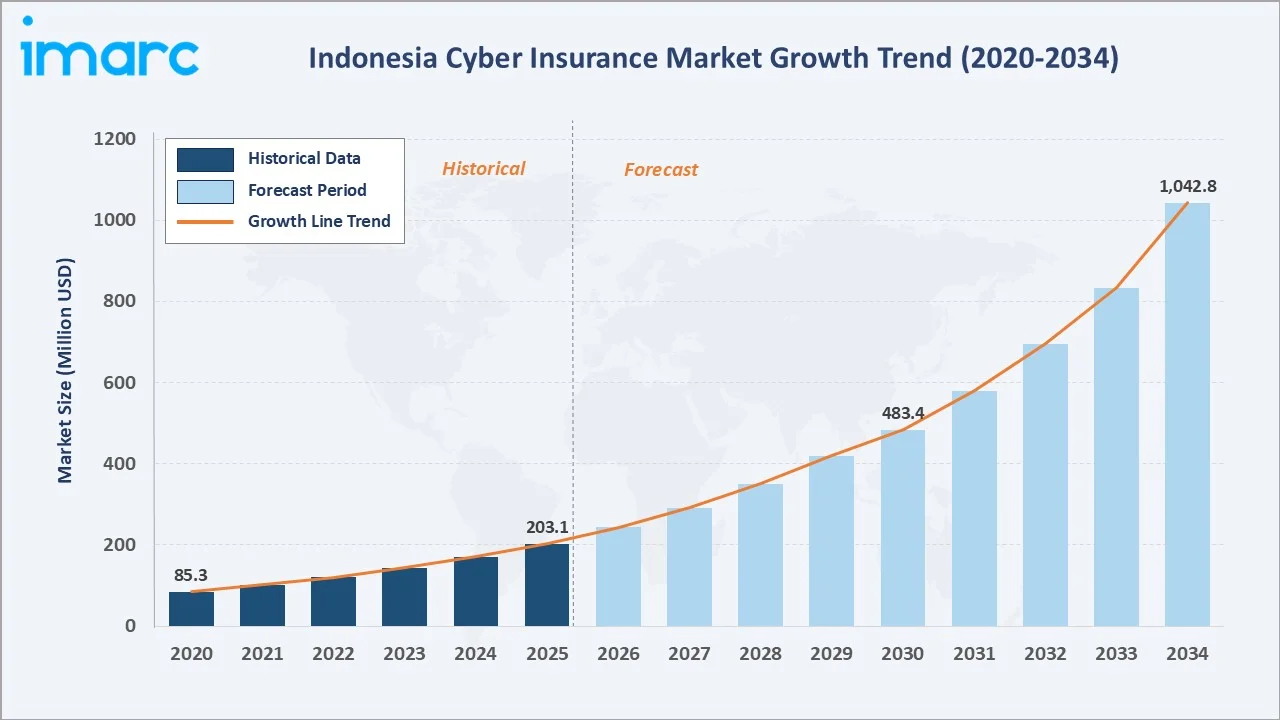
The Indonesia cyber insurance market reached USD 203.1 Million in 2025 and is projected to reach USD 1,042.8 Million by 2034, growing at a CAGR of 18.94% during 2026-2034. The market is driven by an escalating cyber threat landscape, rapid growth of Indonesia's digital economy expanding the cyber attack surface, and rising enterprise awareness of financial exposure from data breaches and ransomware events. Indonesia experienced approximately 5.5 billion cyberattacks in 2025, representing nearly a sevenfold increase compared with the 2020–2024 annual average. The sharp rise in cyber threats is increasing businesses’ exposure to data breaches, operational disruptions, and financial losses, thereby strengthening demand for cyber insurance coverage. Solution leads at 58.7% by component, stand-alone dominates at 56.4% by insurance type, and Java holds the largest regional share at 56.3%.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 203.1 Million |
|
Forecast Market Size (2034) |
USD 1,042.8 Million |
|
CAGR (2026-2034) |
18.94% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Component |
Solution (58.7%, 2025) |
|
Dominant Insurance Type |
Stand-alone (56.4%, 2025) |
|
Leading Region |
Java (56.3%, 2025) |
The Indonesia cyber insurance market has grown from USD 85.3 million in 2020 to USD 203.1 million in 2025, reflecting a period of rapid expansion driven by escalating cyber incidents and increasing regulatory requirements. The market is projected to reach USD 483.4 million by 2030 and USD 1,042.8 million by 2034, sustaining an exceptional 18.94% CAGR.
To get more information on this market, Request Sample
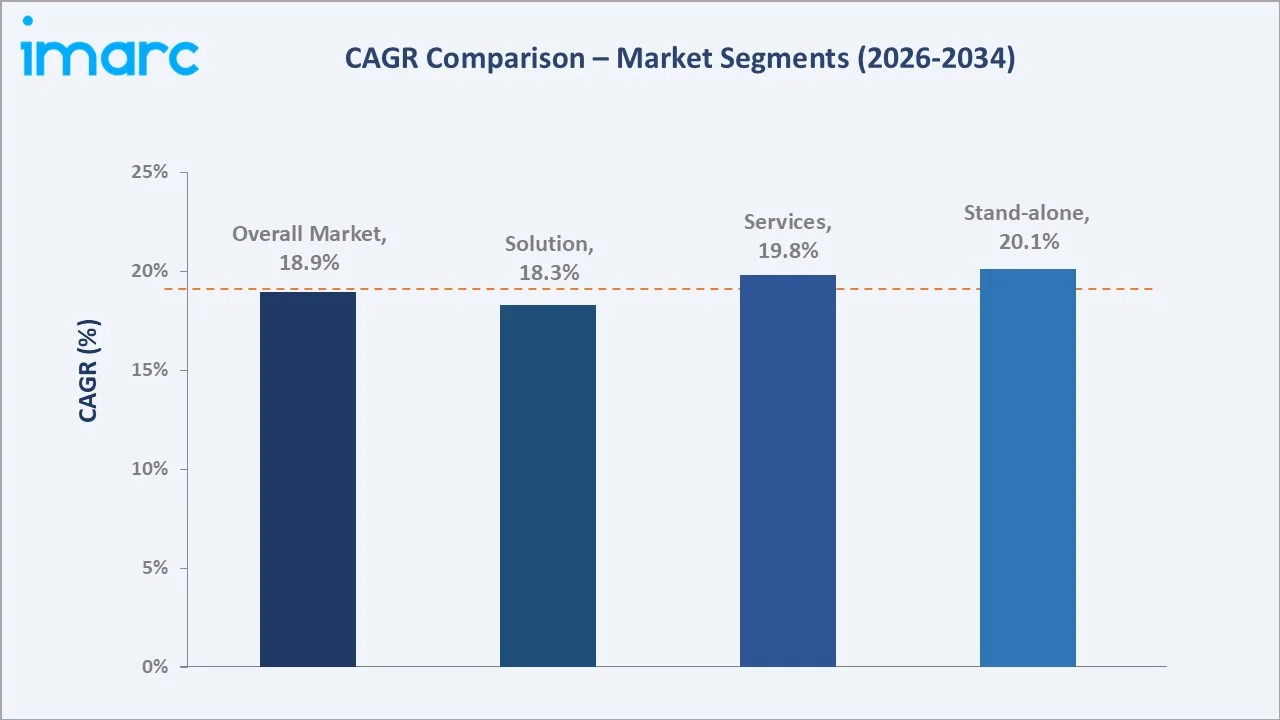
Stand-alone cyber insurance grows at ~20.1% CAGR through dedicated policy adoption. Services grow at ~19.8% CAGR through managed detection and incident response integration. Solution grows at ~18.3% CAGR through cyber risk assessment platform adoption.
Executive Summary
The Indonesia cyber insurance market is experiencing exceptional growth, emerging as Southeast Asia's most dynamic cyber risk transfer market as digital transformation accelerates across the archipelago's banking, technology, healthcare, retail, and government sectors. Indonesia's position as one of the most populous nations and one of Asia's fastest-growing digital economies creates a uniquely expansive and rapidly escalating cyber risk exposure profile. Solution at 58.7% leads through integrated cyber risk assessment and monitoring platform adoption. Stand-alone at 56.4% leads through dedicated cyber policy demand from large enterprises. Java leads regionally at 56.3%.
Key Market Insights
|
Insight |
Data |
|
Dominant Component |
Solution - 58.7% share (2025) |
|
Dominant Insurance Type |
Stand-alone - 56.4% share (2025) |
|
Leading Region |
Java - 56.3% share (2025) |
|
Market opportunities |
Rising demand for cyber risk coverage, SME-focused policies, ransomware protection, data-breach insurance, business interruption coverage, and customized solutions for digital enterprises. |
Key Analytical Observations Supporting the Above Data:
- Solution at 58.7%: Solution-based cyber insurance components lead because Indonesian enterprises are increasingly requiring integrated cyber risk assessment, continuous monitoring, threat intelligence, and security rating services as prerequisites for policy issuance.
- Stand-alone at 56.4%: Stand-alone cyber insurance policies dominate because large Indonesian enterprises in BFSI, healthcare, and IT sectors recognize that comprehensive cyber risk exposure cannot be adequately covered within packaged multi-line policies.
- Java at 56.3%: Java's dominance reflects the island's concentration of Indonesia's largest enterprises across banking, telecommunications, technology, and government sectors in Jakarta, the nation's financial capital.
Indonesia Cyber Insurance Market Overview
The Indonesia cyber insurance market encompasses financial products and services designed to protect individuals, businesses, and organizations against digital risks including data breaches, ransomware attacks, business email compromise, cloud outages, and regulatory compliance failures. Products include stand-alone cyber insurance policies covering first-party losses (data recovery, business interruption, ransomware response, crisis management) and third-party liabilities (data breach notification, regulatory fines, network security liability), and packaged cyber endorsements bundled within existing commercial insurance policies. Services encompass pre-loss cybersecurity consulting, vulnerability assessments, security awareness training, and post-loss incident response, forensics, legal support, and public relations crisis management.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
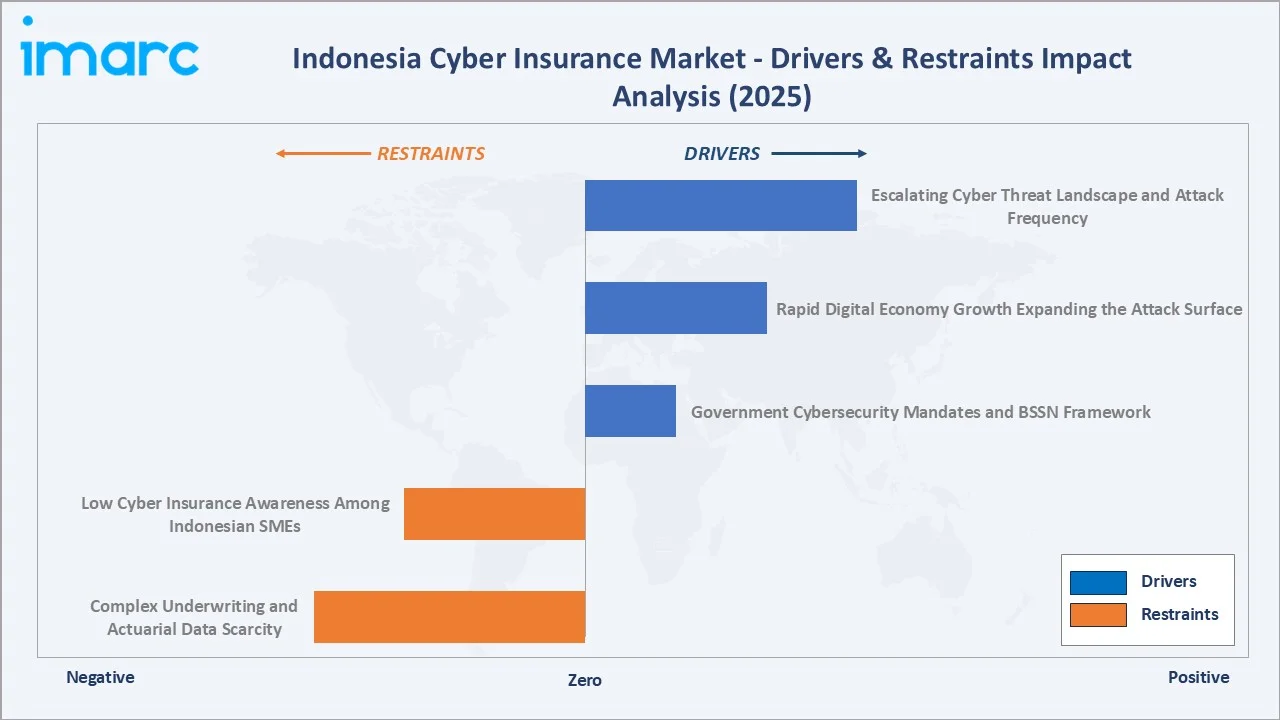
- Escalating Cyber Threat Landscape and Attack Frequency: BSSN reported approximately 5.5 billion cyberattacks in Indonesia during 2025, marking a 714% increase compared with the average annual level recorded between 2020 and 2024, with ransomware, phishing, malware, and web defacement attacks targeting the banking, government, healthcare, and retail sectors at unprecedented frequency. High-profile breaches catalyzed executive awareness of cyber financial exposure and dramatically accelerated insurance adoption.
- Rapid Digital Economy Growth Expanding the Attack Surface: According to the ProSpace Research Institute, Indonesia’s digital economy is projected to reach a value of USD 130–150 billion by the end of 2026, creating an enormous and rapidly expanding attack surface. The proliferation of FinTech platforms, e-commerce ecosystems, cloud migrations, and mobile payment systems generates concentrated digital asset exposures that incumbent physical insurance products cannot address, creating natural demand for dedicated cyber insurance solutions.
- Government Cybersecurity Mandates and BSSN Framework: BSSN's National Cyber Security Strategy is creating regulatory imperatives for enhanced cybersecurity postures across government-linked enterprises, state-owned banks, and critical infrastructure operators. These mandates are directly influencing enterprise procurement of cyber insurance as part of comprehensive cyber risk management frameworks that satisfy board-level and regulatory governance requirements.
Market Restraints
- Low Cyber Insurance Awareness Among Indonesian SMEs: Micro, small, and medium enterprises (MSMEs) play a vital role in Indonesia’s economy, accounting for more than 60% of GDP and employing approximately 97% of the country’s workforce, demonstrates very limited awareness of cyber insurance as a risk management tool. Cost sensitivity, limited cybersecurity budgets, and the perception that cyber attacks primarily affect large enterprises constrain market penetration in this substantial segment. Educating SMEs about cyber risk exposure and affordable insurance options is a critical industry challenge.
- Complex Underwriting and Actuarial Data Scarcity: Indonesian cyber insurance underwriting faces significant challenges from limited historical loss data, rapidly evolving threat vectors, and difficulty in accurately quantifying systemic cyber risk correlations. The absence of standardized cyber loss databases for the Indonesian market creates actuarial uncertainty that leads insurers to apply conservative premium pricing and coverage limitations, potentially making products cost-prohibitive for budget-constrained enterprise buyers.
Market Opportunities
- SME Cyber Insurance Product Innovation and Accessibility: Indonesia's 64 million SME ecosystem represents the largest underserved cyber insurance market in Southeast Asia. Developing standardized, affordable, and accessible cyber insurance products for SMEs through digital distribution platforms, microinsurance formats, and bank assurance partnerships with Indonesia's large commercial banking network creates a transformational market expansion opportunity that could multiply current market size within the forecast period.
- Integration with Cybersecurity Managed Service Providers: Partnerships between cyber insurers and Managed Security Service Providers (MSSPs) operating in Indonesia create bundled cyber risk management propositions that embed insurance within security service contracts. This distribution model reaches enterprise technology buyers through familiar procurement channels, improves loss prevention through continuous monitoring, and creates recurring revenue relationships that strengthen insurer-client data intelligence for improved underwriting accuracy.
Market Challenges
- Systemic Cyber Risk Accumulation and Correlated Loss Events: The increasing concentration of Indonesian enterprises on shared cloud platforms, common software dependencies, and interconnected payment networks creates potential for correlated loss events where a single cyber incident triggers simultaneous claims across multiple policyholders. Managing systemic cyber risk accumulation requires sophisticated portfolio management and reinsurance arrangements that increase operational complexity for Indonesian cyber insurance providers.
- Talent Shortage in Cyber Insurance Underwriting Expertise: Indonesia faces a significant shortage of professionals with dual expertise in cybersecurity and insurance underwriting. The specialized knowledge required to assess an organization's cyber risk posture, evaluate security controls, and price coverage appropriately limits insurer capacity to expand underwriting operations. Investment in talent development, international expertise partnerships, and AI-powered underwriting tools is required to overcome this structural bottleneck.
Emerging Market Trends
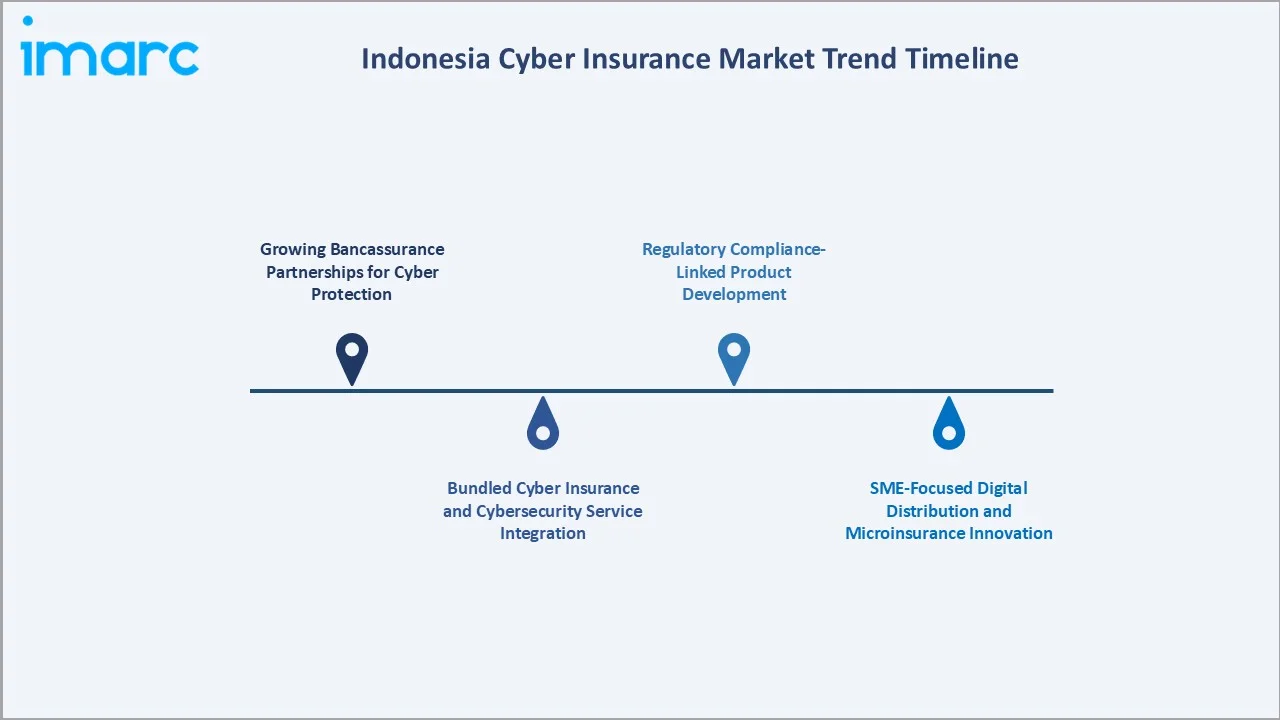
1. Growing Bancassurance Partnerships for Cyber Protection
In March 2026, Chubb Indonesia, in partnership with Bank DBS Indonesia, introduced Cyber Guard, a comprehensive cyber insurance solution to protect customers against digital fraud and cybercrime. The policy covers unauthorized card transactions, phishing- or malware-related account takeovers, and financial losses caused by social engineering scams. The launch highlights a rising trend of insurers partnering with banks to distribute cyber insurance directly to retail customers. Such collaborations can broaden market reach, simplify policy access, and embed cyber protection within everyday banking relationships.
2. Bundled Cyber Insurance and Cybersecurity Service Integration
Leading Indonesian cyber insurers are differentiating by embedding cybersecurity services within policy coverage, transforming cyber insurance from a passive financial product into an active risk management partnership. These bundled propositions include pre-loss services such as security posture assessments, employee phishing simulation training, dark web credential monitoring, and patch management advisory; and post-loss services such as 24/7 incident response retainers, forensic investigation teams, legal counsel, and crisis communications support. This value-added model improves loss ratios while increasing policyholder engagement and retention.
3. Regulatory Compliance-Linked Product Development
Regulatory enforcement is driving product innovation in compliance-linked cyber insurance, with insurers developing specific endorsements covering data breach notification costs, regulatory investigation defense, administrative fine indemnification, and data subject compensation. Evolving technology risk management guidelines for the financial services sector are creating additional compliance-linked coverage needs for Indonesian banks, insurance companies, and fintech firms that must demonstrate enterprise-wide cyber risk management governance to regulatory examiners.
4. SME-Focused Digital Distribution and Microinsurance Innovation
The emerging SME cyber insurance segment in Indonesia is being addressed through digital-first distribution innovations including online self-serve policy portals, API-integrated bancassurance channels, and e-commerce platform partnership programs. Parametric cyber insurance products that trigger automatic payments upon verified cyber incident parameters are being piloted as simple, transparent alternatives to complex claims-based policies for SME buyers who lack internal expertise to navigate traditional insurance claims processes.
Industry Value Chain Analysis
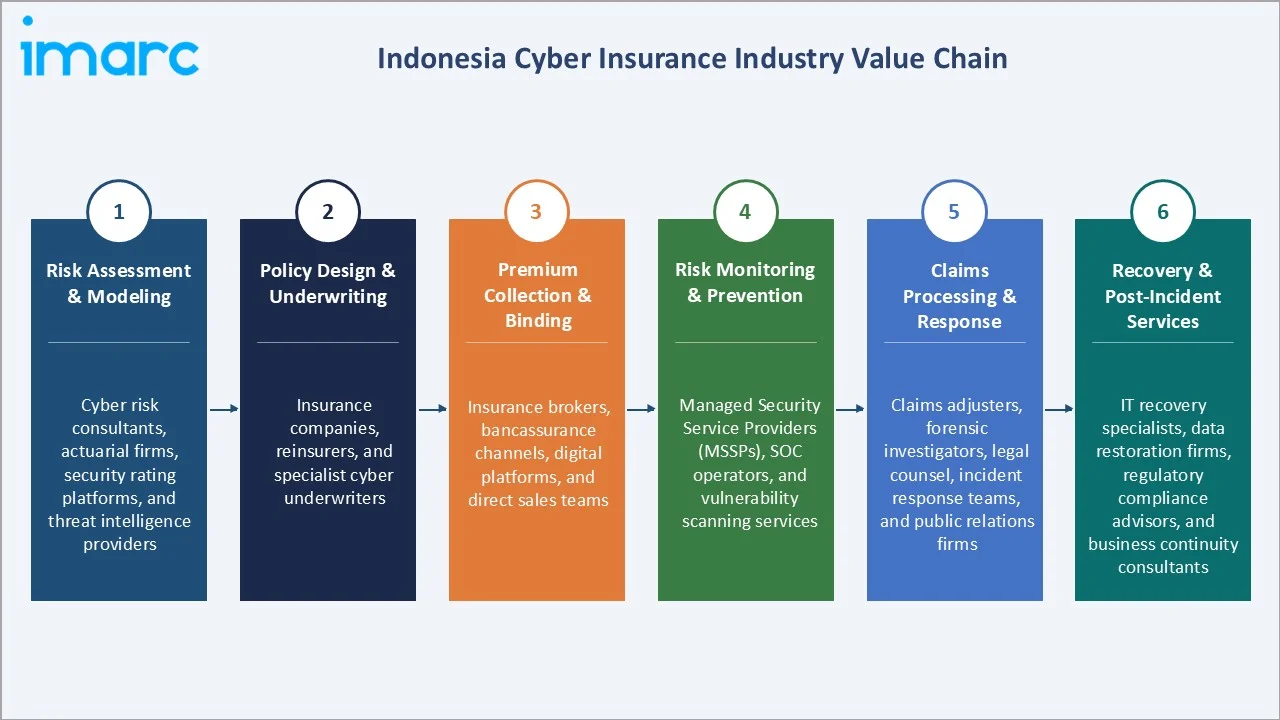
The Indonesia cyber insurance value chain integrates risk assessment and modeling, policy design and underwriting, premium collection and binding, risk monitoring and prevention, claims processing and response, and recovery and post-incident services across the cyber risk management ecosystem.
|
Stage |
Key Participants |
|
Risk Assessment & Modeling |
Cyber risk consultants, actuarial firms, security rating platforms, and threat intelligence providers. |
|
Policy Design & Underwriting |
Insurance companies, reinsurers, and specialist cyber underwriters. |
|
Premium Collection & Binding |
Insurance brokers, bancassurance channels, digital platforms, and direct sales teams. |
|
Risk Monitoring & Prevention |
Managed Security Service Providers (MSSPs), SOC operators, and vulnerability scanning services. |
|
Claims Processing & Response |
Claims adjusters, forensic investigators, legal counsel, incident response teams, and public relations firms. |
|
Recovery & Post-Incident Services |
IT recovery specialists, data restoration firms, regulatory compliance advisors, and business continuity consultants. |
Claims processing and incident response represent the most critical value stage in the Indonesia cyber insurance chain, as rapid and effective incident response directly determines policyholder recovery outcomes and insurer loss costs. Insurers that maintain pre-qualified panels of forensic investigation firms, legal counsel, and IT recovery specialists available 24/7 achieve superior claims outcomes, faster business restoration for policyholders, and improved loss ratios compared to insurers without dedicated incident response capability.
Technology Landscape in the Indonesia Cyber Insurance Industry
Cyber Risk Quantification and Security Rating Technology
Advanced cyber risk quantification platforms are becoming foundational to Indonesian cyber insurance underwriting. These platforms provide continuous outside-in assessments of organizational security posture by analyzing publicly observable security signals including certificate validity, open port exposure, software vulnerability disclosures, and data breach history. AI-driven risk scoring enables Indonesian insurers to make data-informed underwriting decisions, dynamically adjust policy pricing based on real-time security posture changes, and identify emerging risk concentrations within their insurance portfolios.
Claims Technology and Digital Incident Response
Indonesian cyber insurers are investing in digital claims management platforms that streamline the first notice of loss, forensic evidence collection, and claims resolution workflow for cyber incidents. Integration with incident response retainer panels through automated case management systems enables rapid deployment of forensic, legal, and IT recovery resources within hours of a covered cyber event. Blockchain-based evidence preservation tools are emerging as a means to maintain forensically sound records of incident timelines and response actions that support both claims validation and potential regulatory or legal proceedings.
Digital Distribution and InsurTech Platform Technology
InsurTech platforms are transforming cyber insurance distribution in Indonesia by enabling online risk assessment questionnaires, automated quote generation, and digital policy issuance for SME and small enterprise buyers. API integrations with accounting software, cloud platforms, and cybersecurity tools enable automated data collection that reduces underwriting friction and improves risk assessment accuracy. Mobile-first policy management applications allow Indonesian policyholders to submit claims, access incident response contacts, and monitor their coverage status through smartphone interfaces.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Component |
Solution |
58.7% |
2025 |
|
Insurance Type |
Stand-alone |
56.4% |
2025 |
|
Organization Size |
🔒 |
🔒 |
2025 |
|
End-Use Industry |
🔒 |
🔒 |
2025 |
|
Region |
Java |
56.3% |
2025 |

By Component
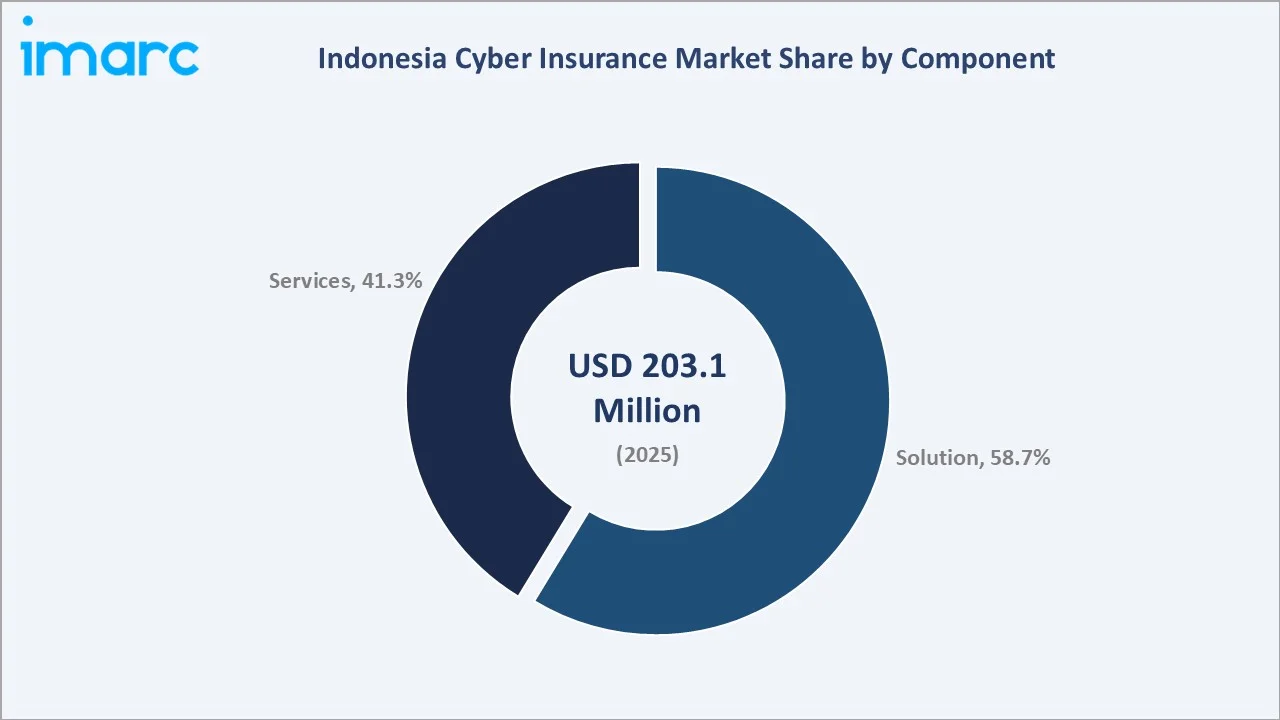
Solution leads at 58.7% (2025), driven by enterprise demand for integrated cyber risk assessment platforms, security rating services, threat intelligence tools, and risk monitoring dashboards that provide active cyber risk management value beyond financial indemnification.
To access detailed market analysis, Request Sample
Services at 41.3% reflect the growing importance of pre-loss cybersecurity consulting, employee training, vulnerability assessments, and post-loss incident response, forensics, and legal support services embedded within comprehensive cyber insurance programs. The services component is expected to grow at ~19.8% CAGR through 2034, approaching revenue parity with solutions as Indonesian policyholders recognize the value of active risk management services over purely passive financial protection.
By Insurance Type
Stand-alone policies lead at 56.4% (2025), preferred by large Indonesian enterprises in BFSI, healthcare, and technology sectors that require comprehensive dedicated cyber coverage with meaningful policy limits that packaged endorsements cannot provide.
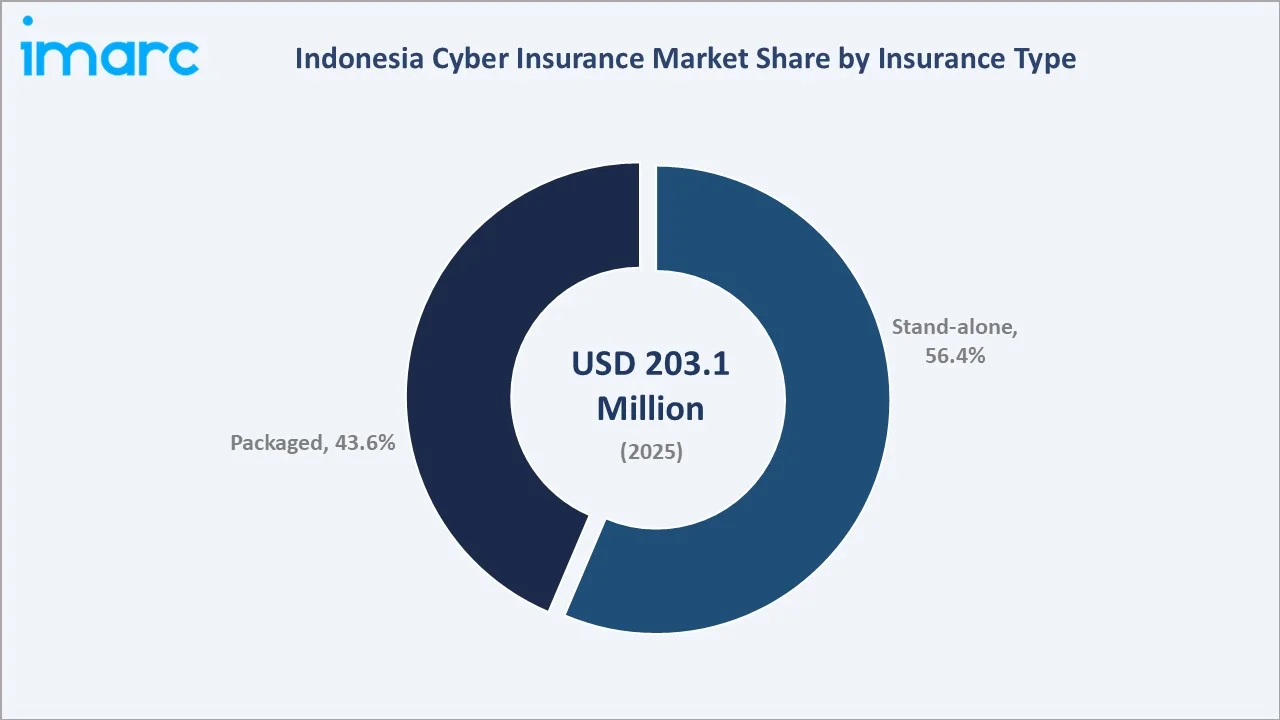
Packaged cyber insurance at 43.6% serves SMEs and mid-market enterprises that seek cyber risk protection through the convenience of existing commercial insurance relationships. As cyber risk awareness expands among SMEs and packaged policy limitations become apparent following incidents, conversion to stand-alone policies is expected to sustain stand-alone's leadership position.
Regional Market Insights
|
Region |
Share (2025) |
Key Indonesia Cyber Insurance Market Drivers & Characteristics |
|
Java |
56.3% |
Reflecting the concentration of national financial institutions, large technology enterprises, and government agencies, creating market demand. |
|
Sumatra |
18.7% |
Reflecting the presence of regional banking headquarters, palm oil and mining sector digital operations, and growing commercial enterprise penetration. |
|
Kalimantan |
10.2% |
Reflecting rising digital enterprise activity linked to the new capital city development, energy sector digital transformation, and expanding financial services infrastructure. |
|
Sulawesi |
7.4% |
Reflecting growing commercial digitalization in Makassar, expanding fintech platform penetration, and increasing enterprise awareness of cyber risks among regional banking and trading companies. |
|
Others |
7.4% |
Reflecting cyber insurance adoption in the tourism-dependent digital economy, Papua's infrastructure investment activities, and eastern Indonesian provincial enterprises with growing digital footprints. |
Java's 56.3% dominance is underpinned by Jakarta's status as Indonesia's financial capital, hosting the headquarters of all national state-owned banks, major insurance companies, technology unicorns, and multinational corporations that collectively represent Indonesia's highest concentration of insurable digital assets and regulatory compliance obligations. Sumatra's 18.7% reflects the island's large regional economy anchored by commercial centers, where banking, palm oil trading, and telecommunications enterprises increasingly recognize cyber risk exposure.
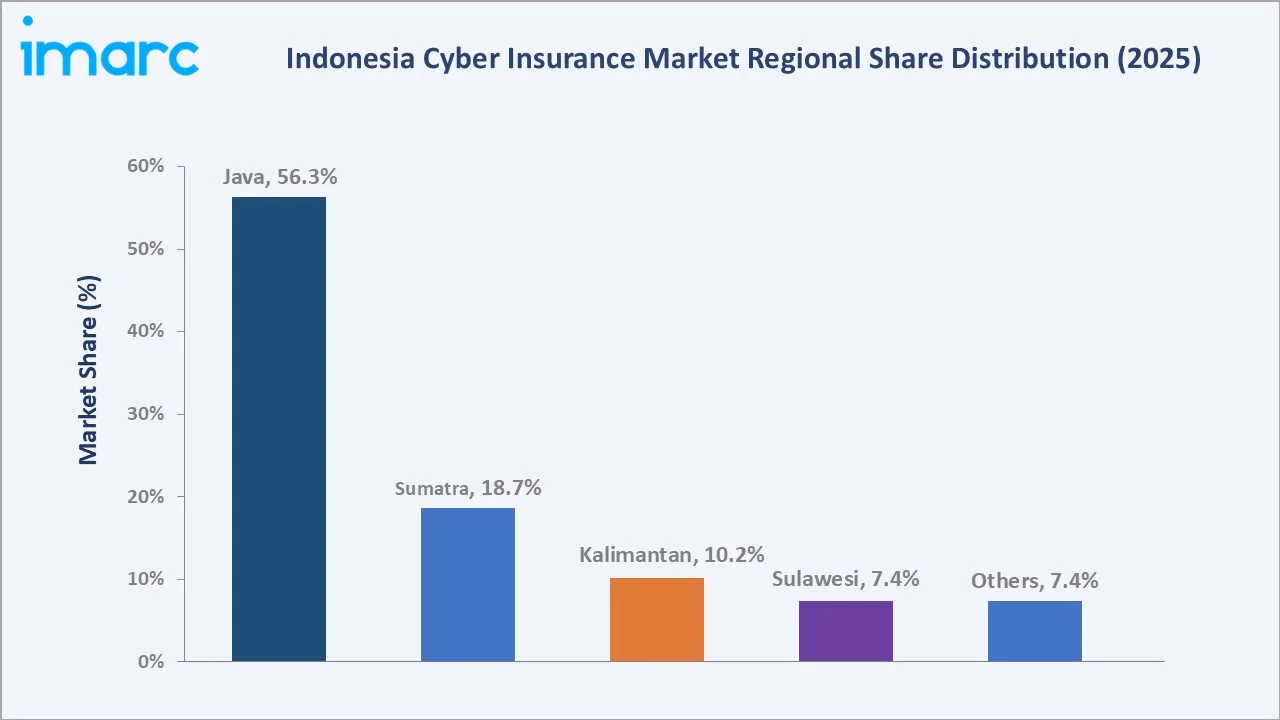
Kalimantan's 10.2% is expected to grow above the market average through 2034, driven by the development of Indonesia's new capital city, creating significant government and enterprise digital infrastructure that will require cyber risk protection. Sulawesi at 7.4% reflects Makassar's growing commercial importance and the island's expanding fintech and digital service economy. Others at 7.4% encompasses Bali's tourism and hospitality digital economy and the government-supported development activities across eastern Indonesian provinces.
Competitive Landscape
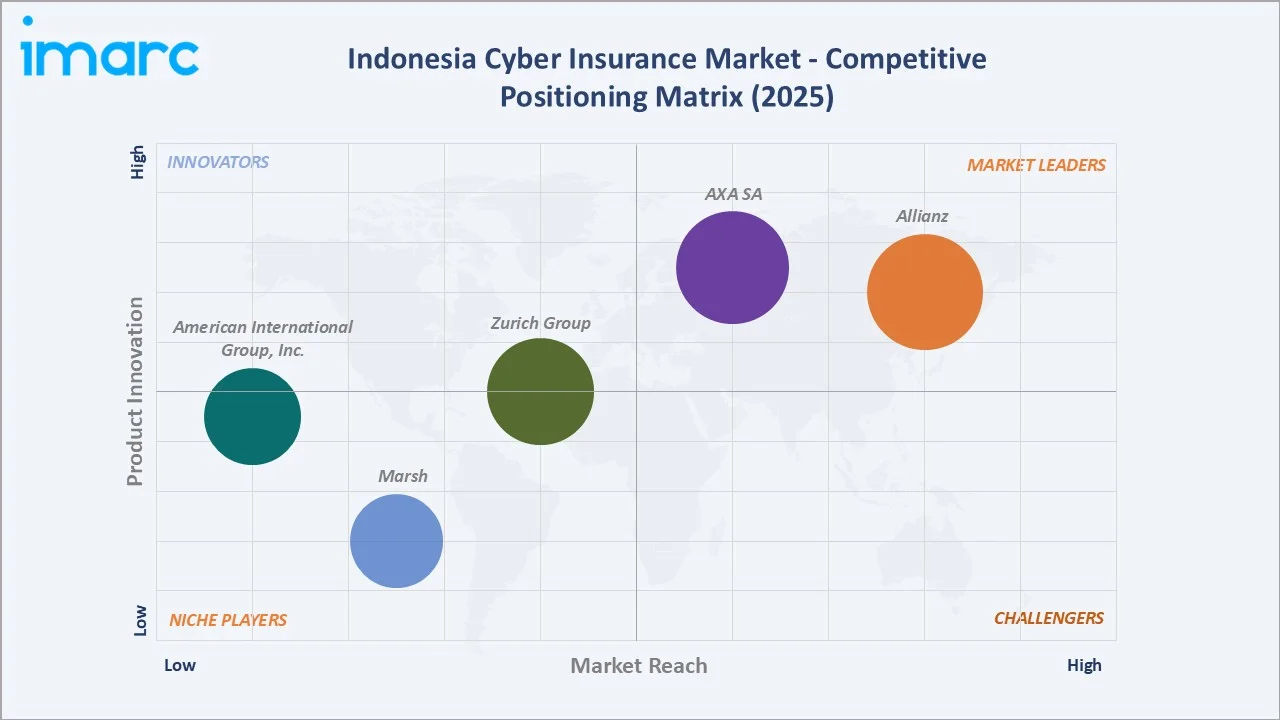
The Indonesia cyber insurance market features multinational insurance giants, regional Asian insurers, and growing Indonesian domestic players competing across enterprise, mid-market, and emerging SME segments. Market competition is driven by policy coverage breadth, incident response capabilities, cybersecurity service bundling, claims handling reputation, and pricing competitiveness.
|
Company |
Key Offerings |
Market Position |
Core Strength |
|
Allianz |
Allianz Commercial Cyber Insurance |
Market Leader |
Allianz provides localized commercial insurance solutions in Indonesia, including specialized risk transfer and digital threat protection for large and mid-sized businesses. |
|
AXA SA |
AXA XL CyberRiskConnect |
Market Leader |
AXA SA, through its commercial insurance division AXA XL, operates as a major institutional player and insurer in the rapidly evolving Indonesian cyber insurance landscape. |
|
Zurich Group |
Zurich Cyber Insurance |
Established Player |
Zurich Insurance Group operates as a key participant, contributing to local service delivery, digital expansion, and risk innovation. |
|
American International Group, Inc. |
AIG Cyber Insurance |
Established Player |
American International Group, Inc. operates in Indonesia through AIG Insurance Indonesia to provide general insurance solutions, supervised by the local financial authority. |
|
Marsh |
Cyber Protect |
Niche Player |
Marsh acts as a leading cyber risk advisor and insurance broker in Indonesia and across Asia, helping businesses secure financial protection and build digital resilience. |
Companies across the competitive landscape are investing in AI-powered underwriting tools, cybersecurity service bundling, SME digital distribution platforms, and regional market expansion capabilities. The market is expected to attract additional specialist cyber insurers and InsurTech entrants as Indonesia's premium pool growth demonstrates compelling commercial opportunity.
Key Company Profiles
Allianz
Allianz is one of the largest insurance and asset management groups and operates as a leading provider of both life and general insurance in Indonesia. In cyber insurance, Allianz Indonesia draws upon Allianz’s position as one of the largest cyber insurers globally, providing Indonesian enterprise clients with access to world-class cyber underwriting expertise, international incident response networks, and comprehensive coverage structures. Its cyber insurance products address data breach, ransomware, business interruption, regulatory defense, and cyber extortion exposures for Indonesian large enterprise and multinational company clients.
- Key Offerings: Allianz Commercial Cyber Insurance.
- Strategic Focus: Expanding Indonesian cyber insurance market share through enhanced SME product accessibility, strengthening incident response service bundling through local MSSP partnerships, and developing parametric cyber insurance products for technology sector clients seeking faster claims resolution mechanisms.
AXA SA
AXA SA is one of the largest insurance companies and one of the leading financial protection companies. AXA has made cyber insurance a strategic global growth priority, and its Indonesian operations reflect this emphasis through investments in cyber product development, digital distribution, and cybersecurity service integration. AXA's XL Insurance specialty division provides substantial cyber underwriting capacity for Indonesian large enterprise clients, while AXA's digital transformation initiatives are enabling SME-accessible cyber products through online distribution channels. AXA Indonesia's risk consulting team provides pre-insurance cybersecurity assessments and post-incident support that differentiates its cyber proposition beyond financial indemnification.
- Key Offerings: AXA XL CyberRiskConnect.
- Strategic Focus: Scaling SME cyber insurance penetration through digital platform distribution and simplified underwriting questionnaires, deepening enterprise client cyber risk advisory services, and expanding AXA's incident response network within Indonesia through local cybersecurity firm partnerships.
Market Concentration Analysis
The Indonesia cyber insurance market exhibits moderate concentration, with international insurers collectively commanding approximately 55-60% of total cyber insurance premium revenues in 2025. Domestic and regional players serve important complementary market segments. Market concentration is expected to moderate as InsurTech entrants, new specialist cyber insurance market participants, and SME-focused digital platforms expand the market's competitive landscape through 2034.
Investment & Growth Opportunities
Highest Growth Segments
SME cyber insurance digital platforms, healthcare sector cyber coverage, parametric cyber products, managed security service provider partnerships, and Kalimantan/Nusantara capital city-linked enterprise coverage represent the highest-growth investment vectors in the Indonesia cyber insurance market through 2034.
Investment Themes
- SME cyber insurance digital platform development: Building online self-serve cyber insurance platforms targeting Indonesia's SMEs creates the largest addressable market expansion opportunity. Simplified underwriting questionnaires, automated quote and bind capability, and affordable annual premiums designed for SME budgets can unlock a market segment representing multiples of current premium volume.
- MSSP-insurer partnership ecosystem development: Strategic partnerships between cyber insurers and Indonesia's growing MSSP market create bundled cyber risk management propositions that reach enterprise technology buyers through familiar security service procurement channels, improve loss prevention through continuous monitoring, and generate premium volume growth through warm referral distribution.
Future Market Outlook (2026-2034)
The Indonesia cyber insurance market is projected to grow from USD 203.1 Million in 2025 to USD 1,042.8 Million by 2034, exhibiting an exceptional CAGR of 18.94% during 2026-2034. The market is projected to reach an anchor value of USD 483.4 Million by 2030, representing the mid-period inflection point at which regulatory enforcement reaches full maturity and SME market penetration achieves commercial scale.
Three structural forces will define the Indonesia cyber insurance market through 2034. First, the escalating cyber threat environment will sustain and amplify enterprise demand for financial protection against cyber incidents. Second, the SME market penetration breakthrough expected between 2026 and 2030 will dramatically expand the addressable market. Third, regulatory evolution will progressively mandate or strongly incentivize cyber insurance adoption across critical infrastructure operators, financial service providers, and healthcare organizations.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with cyber insurance underwriters, insurance brokers, corporate risk managers, cybersecurity consulting firms, regulatory experts, and industry analysts. These discussions validated market size estimates, assessed coverage demand drivers, evaluated competitive dynamics, and provided insights into regulatory developments, underwriting challenges, and future market evolution in the Indonesia cyber insurance market.
Secondary Research
Secondary research encompassed insurance industry statistics, annual cybersecurity reports, implementation guidance, Indonesia Central Statistics Bureau digital economy data, global cyber insurance industry publications, insurer annual reports, and academic research on cyber risk quantification and insurance market development in emerging economies.
Forecasting Models
Forecasting models incorporated historical cyber insurance premium growth trends, cyber incident frequency and severity data, regulatory enforcement timeline projections, digital economy growth forecasts, and competitive market share dynamics. Both bottom-up models based on enterprise segment penetration rates and top-down macroeconomic models were applied and cross-validated to ensure forecast consistency.
Indonesia Cyber Insurance Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Components Covered | Solution, Services |
| Insurance Types Covered | Packaged, Stand-alone |
| Organization Sizes Covered | Small and Medium Enterprises, Large Enterprises |
| End-Use Industries Covered | BFSI, Healthcare, IT and Telecom, Retail, Others |
| Regions Covered | Java, Sumatra, Kalimantan, Sulawesi, Others |
| Companies Covered | Allianz, AXA SA, Zurich Group, American International Group, Inc., Marsh, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Indonesia cyber insurance market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Indonesia cyber insurance market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Indonesia cyber insurance industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Indonesia Cyber Insurance Market Report
The Indonesia cyber insurance market reached USD 203.1 Million in 2025, driven by escalating cyber threats, regulatory compliance demand, rapid digital economy growth, national cybersecurity framework mandates, and rising enterprise awareness of financial exposure from data breaches and ransomware attacks.
The Indonesia cyber insurance market is projected to grow at a CAGR of 18.94% during 2026-2034, sustained by regulatory compliance demand, escalating cyber threat frequency, digital economy expansion, and emerging SME market penetration unlocking significant new premium volumes.
The market is projected to reach approximately USD 483.4 Million by 2030, representing the mid-period inflection at which enforcement matures, SME cyber insurance achieves commercial scale, and mandatory or strongly incentivized cyber coverage requirements emerge for critical infrastructure operators.
Solution leads with a 58.7% share in 2025, driven by enterprise demand for integrated cyber risk assessment platforms, security rating tools, and threat monitoring services that provide active risk management value bundled within comprehensive cyber insurance programs.
Stand-alone cyber insurance leads with a 56.4% share in 2025, preferred by large Indonesian enterprises requiring comprehensive dedicated cyber coverage with meaningful policy limits that packaged endorsements cannot provide for banking, healthcare, and technology sector risk exposures.
Java leads with a 56.3% share in 2025, driven by its concentration of national financial institutions, technology unicorns, multinational corporations, and government agencies in Jakarta that represent Indonesia's highest density of insurable digital assets and regulatory compliance obligations.
Key players include Allianz, AXA SA, Zurich Group, American International Group, Inc., and Marsh, among others.
The Indonesia cyber insurance market is projected to reach USD 1,042.8 Million by 2034, driven by SME market penetration, regulatory mandates, escalating cyber incident frequency, and progressive adoption across all major Indonesian industry verticals, including BFSI, healthcare, IT, and retail sectors.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade