Japan Bridge Construction Market Size, Share, Trends and Forecast by Type, Material, Application, and Region, 2026-2034
Japan Bridge Construction Market Size, Share, Trends & Forecast (2026-2034)
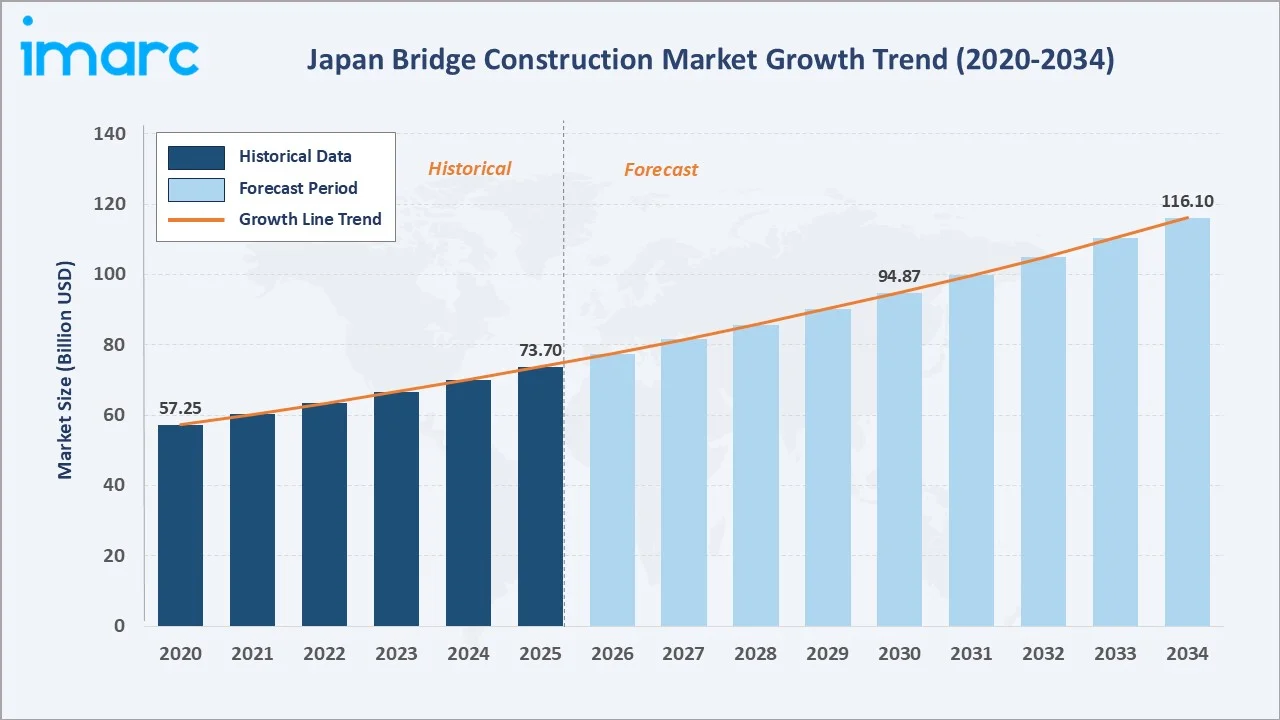
The Japan bridge construction market reached USD 73.70 Billion in 2025 and is projected to reach USD 116.10 Billion by 2034, growing at a CAGR of 5.18% during 2026-2034. The market is driven by large-scale government infrastructure investment, an aging bridge stock requiring urgent rehabilitation, and expanding rail and highway network programs. By 2040, approximately 75% of Japan’s road bridges are projected to reach or exceed their designated service life. This is driving the market by increasing demand for bridge replacement, reconstruction, rehabilitation, and structural upgrades. Concrete leads in materials at 51.6%. Road and highway dominate application at 76.4%. The Kanto region leads regionally at 28.7%.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 73.70 Billion |
|
Forecast Market Size (2034) |
USD 116.10 Billion |
|
CAGR (2026-2034) |
5.18% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Material |
Concrete (51.6%, 2025) |
|
Leading Application |
Road and Highway (76.4%, 2025) |
|
Leading Region |
Kanto Region (28.7%, 2025) |
The Japan bridge construction market has grown steadily from USD 57.25 Billion in 2020 to USD 73.70 Billion in 2025, sustained by Japan's large-scale government infrastructure spending and accelerating bridge rehabilitation demand as Japan's bridge stock ages rapidly. The market is projected to reach USD 94.87 Billion by 2030 and USD 116.10 Billion by 2034, supported by expressway expansion and post-earthquake recovery construction programs.
To get more information on this market, Request Sample
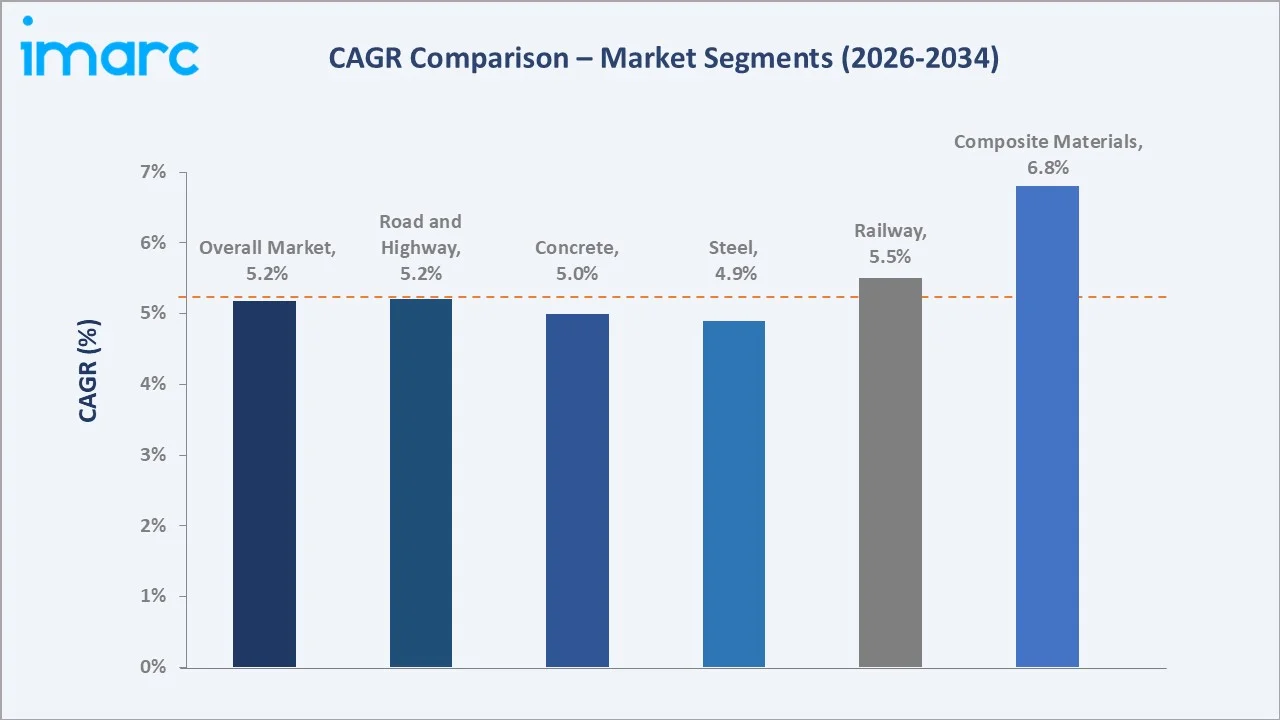
Composite materials grow at ~6.8% CAGR through carbon fiber reinforced polymer (CFRP) adoption in bridge rehabilitation and new construction. Road and highway application grows at ~5.2% CAGR through expressway new construction and aged road bridge replacement. Railway grows at ~5.5% CAGR through extension projects and urban rail bridge upgrades.
Executive Summary
The Japan bridge construction market is one of Asia's largest and most technically sophisticated infrastructure markets, driven by a unique combination of aging bridge infrastructure, seismic engineering requirements, and sustained government commitment to national resilience investment. Japan operates the most earthquake-prone major economy.
Concrete dominates material share at 51.6% through its cost-effectiveness, proven performance in Japan's humid coastal environments, and wide applicability across beam, truss, and girder bridge types on national and prefectural road networks. Road and highway applications lead at 76.4%, reflecting Japan's expanding Shinkansen and urban networks. Kanto region leads regionally at 28.7%.
Key Market Insights
|
Insight |
Data |
|
Dominant Material |
Concrete - 51.6% share (2025) |
|
Leading Application |
Road and Highway - 76.4% share (2025) |
|
Leading Region |
Kanto Region - 28.7% share (2025) |
|
Market Opportunity |
Bridge rehabilitation; seismic retrofitting; expressways; Shinkansen extensions; digitalization |
Key Analytical Observations Supporting the Above Data:
- Concrete at 51.6%: Concrete dominates Japan's bridge construction material mix due to its cost-effectiveness for standard beam and box girder bridge types, excellent durability in Japan's coastal environments with appropriate concrete protection systems, and wide availability through Japan's extensive ready-mix concrete and precast manufacturing infrastructure.
- Road and Highway at 76.4%: Road and highway application dominates through Japan's extensive national expressway network, national highways, and prefectural and municipal road bridge replacement programs driven by aging infrastructure.
- Kanto Region at 28.7%: The Kanto region leads through the Tokyo metropolitan area's massive infrastructure investment in expressway expansion, urban rail bridge rehabilitation, and its concentration of major bridge construction companies, structural engineering firms, and government project management authorities managing the nation's largest infrastructure portfolios.
Japan Bridge Construction Market Overview
The Japan bridge construction market encompasses the planning, design, procurement, construction, and rehabilitation of bridge infrastructure across three material categories, concrete, steel, and composite materials, and two primary application areas: road and highway, and railway. Bridge types include beam bridges, truss bridges, arch bridges, suspension bridges, and cable-stayed bridges. Key clients include national government agencies, prefectural and municipal governments, railway operators, Tokyo Metro, Osaka Metro, and private infrastructure concession holders. Japan's seismically active geography means all bridge designs must comply with rigorous earthquake-resistant design standards, driving sophisticated engineering solutions and premium construction costs.
Market Dynamics
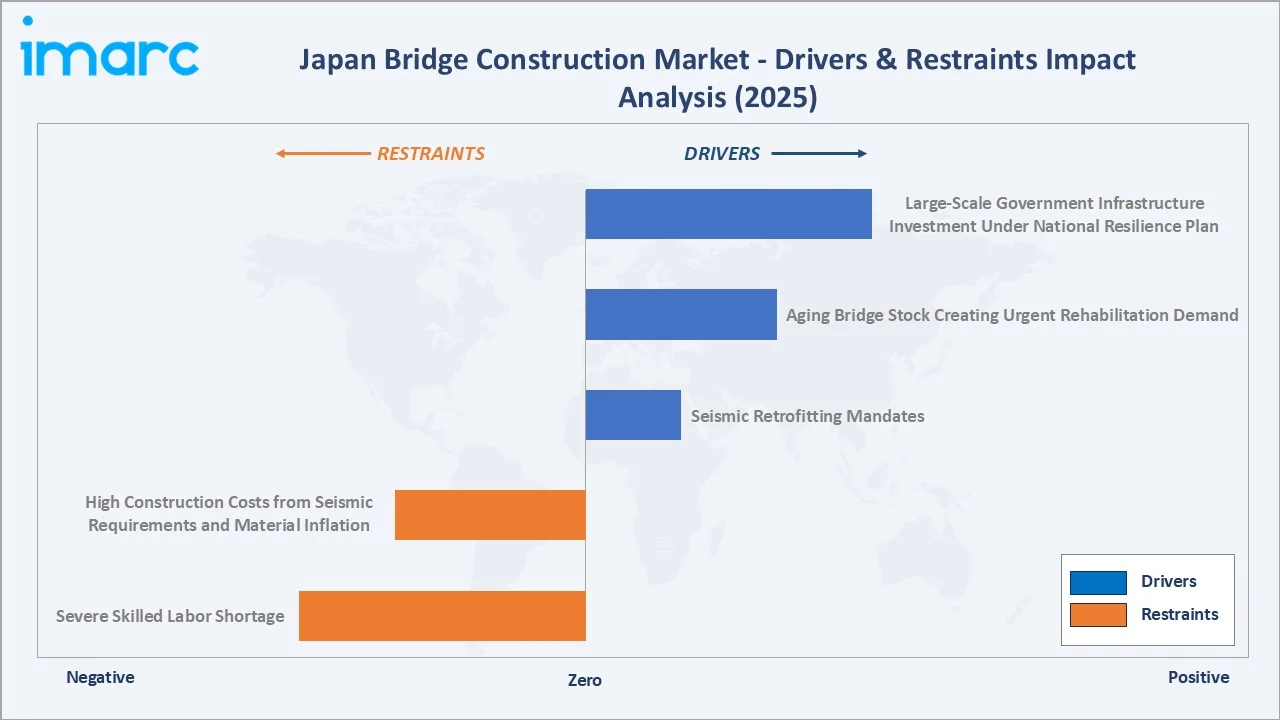
To evaluate market opportunities, Request Sample
Market Drivers
- Large-Scale Government Infrastructure Investment Under National Resilience Plan: The Japan government approved a five-year national resilience program worth over USD 130 billion (around JPY 20 trillion) for FY2026-FY2030. This sustained, policy-mandated government investment commitment creates a highly visible and stable project pipeline for bridge construction companies, supporting multi-year contract backlogs and equipment investment decisions.
- Aging Bridge Stock Creating Urgent Rehabilitation Demand: By 2040, approximately 75% of Japan’s road bridges are expected to reach the end of their designated service life. This aging crisis creates an enormous and structurally unavoidable wave of bridge repair, rehabilitation, and replacement investment that will sustain market growth regardless of economic cycles.
- Seismic Retrofitting Mandates: Japan’s stringent seismic safety requirements are driving investment in the reinforcement, rehabilitation, and reconstruction of aging bridges to improve earthquake resilience. These mandates encourage the adoption of advanced structural strengthening techniques, seismic isolation systems, and durable construction materials, thereby supporting sustained growth in the Japan bridge construction market.
Market Restraints
- Severe Skilled Labor Shortage: Japan's construction industry faces an acute and worsening skilled labor shortage as the aging workforce retires and younger generations show limited interest in construction sector employment. This labor constraint creates project execution bottlenecks, schedule delays, and cost escalation across the bridge construction market.
- High Construction Costs from Seismic Requirements and Material Inflation: Japan's mandatory seismic design standards for bridge structures add high costs to bridge construction compared to non-seismic markets. Post-COVID global material price inflation, affecting steel, cement, and specialized construction materials, has further elevated project costs and created budget overruns on pre-awarded contracts, challenging project viability for local government bridge owners with fixed maintenance budgets.
Market Opportunities
- BIM/CIM Digital Engineering and Smart Bridge Management: The growing adoption of BIM/CIM presents opportunities to improve bridge planning, design, construction, and lifecycle management through integrated digital data. Combined with IoT sensors and structural health monitoring, these technologies enable predictive maintenance and early detection of structural issues. This can reduce lifecycle costs, improve safety, and create opportunities for engineering, software, and smart infrastructure solution providers.
- Composite Materials and Advanced Repair Technologies: Carbon fiber reinforced polymer (CFRP) sheets, CFRP cables, fiber reinforced polymer (FRP) bridge deck panels, and ultra-high-performance concrete (UHPC) represent advanced materials technologies with growing adoption in Japan's bridge market. These materials enable lighter, stronger bridge structures with superior corrosion resistance and reduced maintenance requirements. CFRP cable replacement for aging suspension and cable-stayed bridge main cables, and CFRP jacketing for bridge pier seismic strengthening, represent particularly high-growth application areas within the composite materials segment.
Market Challenges
- Construction Cost Escalation and Budget Constraints for Local Governments: While national government bridge programs benefit from substantial budget commitments under the National Resilience Plan, prefectural and municipal governments managing the majority of Japan's local road bridge stock face severe fiscal constraints. This fiscal capacity gap means that bridge deterioration is progressing faster than repair rates in some local government jurisdictions.
- Procurement Innovation Requirements for Complex Rehabilitation Projects: Traditional Japanese public construction procurement, based on lowest-price tendering with detailed specifications, creates challenges for innovative bridge rehabilitation projects requiring specialized techniques, proprietary materials, or advanced engineering solutions. The bridge construction industry requires expanded adoption of performance-based specifications, design-build procurement, and lifecycle cost-based evaluation to enable the most technically appropriate and economically optimal rehabilitation solutions for Japan's aging bridge stock.
Emerging Market Trends
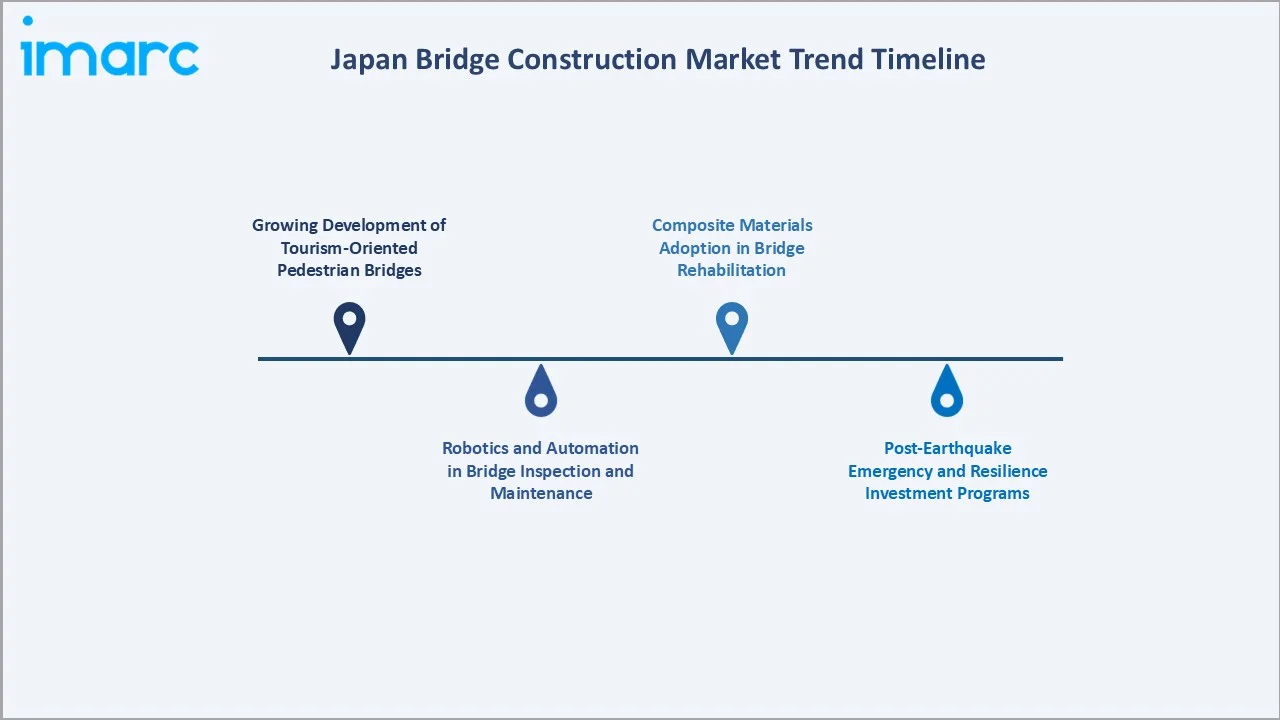
1. Growing Development of Tourism-Oriented Pedestrian Bridges
In August 2026, Japan introduced a 220-meter pedestrian suspension bridge, Skybridge, at the Biwako Valley resort in Otsu, Shiga Prefecture. Situated around 1,100 meters above sea level, the bridge provides panoramic views of Lake Biwa and the surrounding mountains. It began a pre-opening phase on August 22, ahead of its official opening on September 14. The launch highlights increasing investment in landmark pedestrian infrastructure that combines mobility with tourism and recreational experiences. Such projects are creating opportunities for specialized bridge design, lightweight structural systems, and scenic infrastructure development in Japan.
2. Robotics and Automation in Bridge Inspection and Maintenance
The chronic skilled labor shortage is accelerating adoption of robotics, drone inspection, and AI-powered structural analysis in Japan's bridge inspection and maintenance sector. Drone-based bridge inspection has been approved as an alternative to conventional close-up inspection from platforms or rope access, with drone inspection deployed on difficult-to-access bridge structures in mountainous and coastal locations. Robotic bridge painting and surface preparation systems, AI-powered defect detection from drone and camera imagery, and automated bridge monitoring sensor networks are emerging as critical technologies for managing Japan's vast bridge stock with reduced human inspector dependency.
3. Composite Materials Adoption in Bridge Rehabilitation
CFRP (Carbon Fiber Reinforced Polymer) materials are gaining significant traction in Japan's bridge rehabilitation market through two primary applications: pier seismic strengthening using CFRP jacketing to enhance ductility and confinement, and cable replacement using CFRP main cables with superior corrosion resistance and fatigue life compared to conventional high-strength steel wire cables. Japan's coastal bridge environment makes corrosion-resistant CFRP particularly valuable for extending bridge service life and reducing maintenance costs, creating sustained growth momentum for the Composite Materials segment.
4. Post-Earthquake Emergency and Resilience Investment Programs
Increasing emphasis on rapid infrastructure recovery after earthquakes is driving investment in bridge strengthening, replacement, and emergency repair projects across Japan. Government-backed resilience programs are also encouraging the use of seismic-resistant designs, advanced materials, and structural monitoring systems. This trend is creating sustained opportunities for bridge contractors, engineering firms, and infrastructure technology providers.
Industry Value Chain Analysis
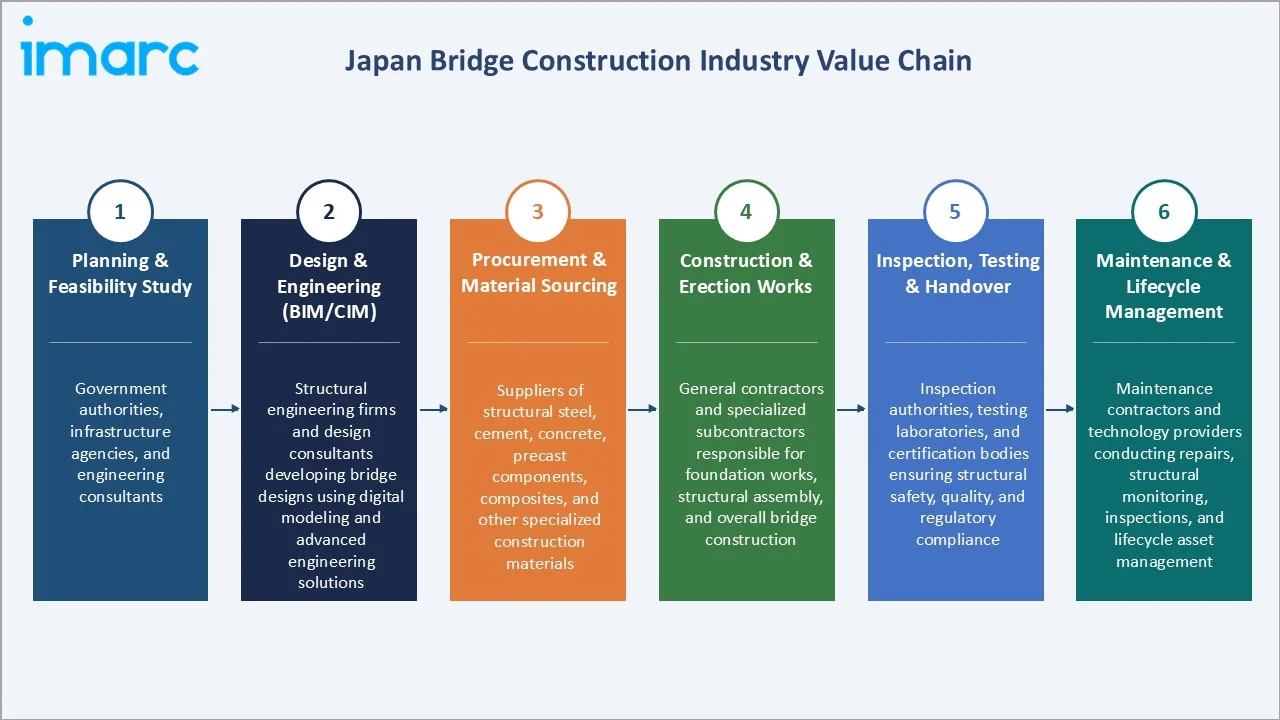
The Japan bridge construction market value chain integrates project planning and feasibility studies, engineering design and BIM/CIM modeling, material procurement and manufacturing, construction and erection works, inspection, testing and project handover, and lifecycle maintenance and management.
|
Stage |
Key Participants |
|
Planning & Feasibility Study |
Government authorities, infrastructure agencies, and engineering consultants. |
|
Design & Engineering (BIM/CIM) |
Structural engineering firms and design consultants developing bridge designs using digital modeling and advanced engineering solutions. |
|
Procurement & Material Sourcing |
Suppliers of structural steel, cement, concrete, precast components, composites, and other specialized construction materials. |
|
Construction & Erection Works |
General contractors and specialized subcontractors responsible for foundation works, structural assembly, and overall bridge construction. |
|
Inspection, Testing & Handover |
Inspection authorities, testing laboratories, and certification bodies ensuring structural safety, quality, and regulatory compliance. |
|
Maintenance & Lifecycle Management |
Maintenance contractors and technology providers conducting repairs, structural monitoring, inspections, and lifecycle asset management. |
Construction and erection work represent the highest-value and most technically demanding stage, requiring significant specialized equipment including crawler cranes, straddle carriers, and incremental launching machinery for steel and concrete bridge construction. Maintenance and lifecycle management is becoming increasingly strategic as Japan's bridge aging crisis creates growing annual maintenance contract streams for contractors with digital inspection and structural health monitoring capabilities.
Technology Landscape in the Japan Bridge Construction Industry
BIM/CIM and Digital Construction Technology
Building/construction information modeling (BIM/CIM) has become the defining digital technology transformation in Japan's bridge construction industry. 3D bridge models created in BIM/CIM platforms enable comprehensive design review, construction simulation, quantity takeoff automation, and lifetime maintenance data management. Leading contractors have invested significantly in BIM/CIM software deployment, staff training, and proprietary digital construction workflow development.
Seismic Engineering Technology and Isolation Systems
Japan's bridge seismic engineering technology represents the global benchmark for earthquake-resistant design and retrofitting. Lead rubber bearing (LRB) seismic isolation systems, friction pendulum isolators, viscous damper arrays, and steel damper devices are routinely specified for new bridge construction and retrofitting of pre-1995 structures. Earthquakes accelerated the adoption of seismic performance evaluation tools, including non-linear dynamic analysis software and shake table validation, driving technology investment across Japan's bridge engineering sector, with structural health monitoring sensor networks being integrated into new bridge designs for real-time earthquake response monitoring.
Advanced Materials and Prefabrication Technology
Ultra-high performance concrete (UHPC) is gaining adoption in Japan's bridge deck overlay, connection detail, and thin precast panel applications for bridge rehabilitation. Carbon fiber reinforced polymer (CFRP) composites are used in pier seismic strengthening, deck panels, and experimental main cable applications. Advanced prefabrication and off-site manufacturing are reducing on-site construction time, improving quality consistency, and addressing the skilled labor shortage by transferring complex work to controlled factory environments.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
🔒 |
🔒 |
2025 |
|
Material |
Concrete |
51.6% |
2025 |
|
Application |
Road and Highway |
76.4% |
2025 |
|
Region |
Kanto Region |
28.7% |
2025 |

By Material
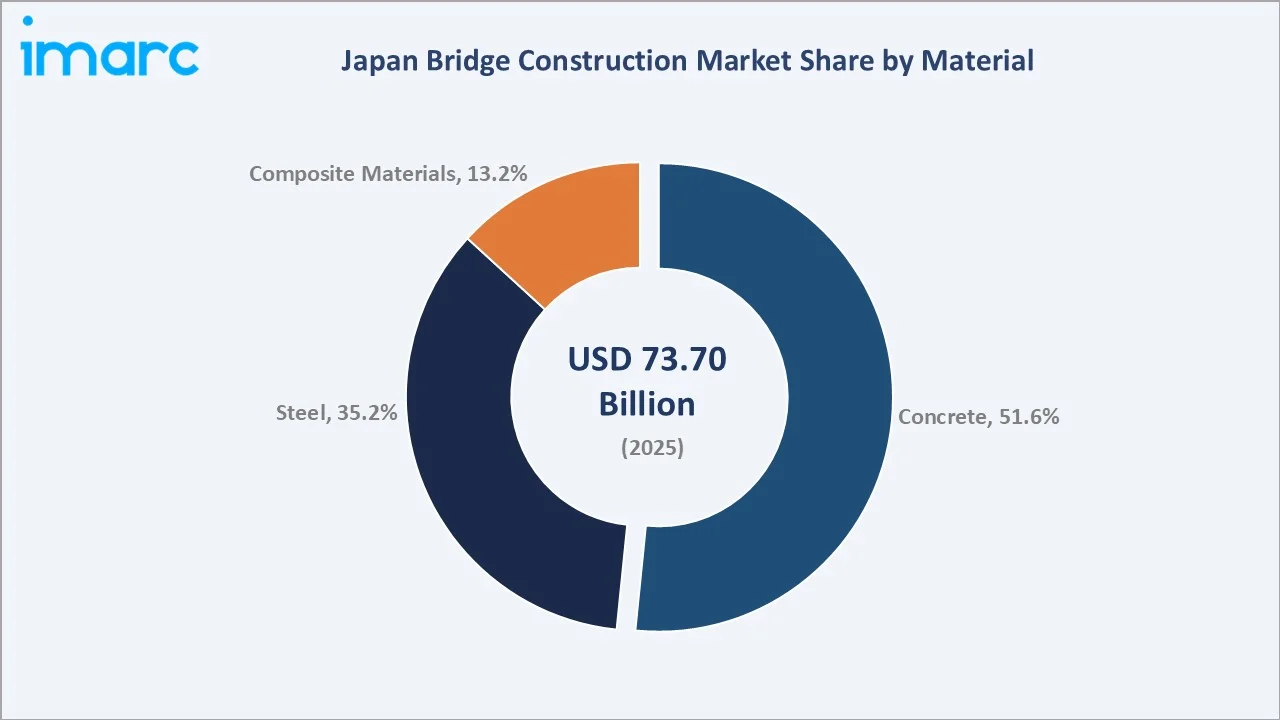
Concrete dominates at 51.6% (2025), reflecting its cost-effectiveness, proven durability, and widespread applicability across beam bridge, box girder, and slab bridge types that form the majority of Japan's national and prefectural road bridge stock. Concrete grows at ~5.0% CAGR through sustained road bridge replacement and rehabilitation programs, with prestressed concrete and ultra-high-performance concrete variants driving premiumization in the segment.
To access detailed market analysis, Request Sample
Steel at 35.2% reflects its indispensable role in long-span bridges, seismically engineered structures, high-speed rail bridge infrastructure, and major expressway interchange structures requiring high load capacity and structural ductility. Composite Materials at 13.2% is growing fastest at ~6.8% CAGR through CFRP seismic strengthening, FRP deck panels, and advanced material adoption in bridge rehabilitation applications targeting corrosion resistance and weight reduction.
By Application
Road and highway application leads at 76.4% (2025), encompassing managed national highway bridges, expressway bridge new construction and rehabilitation, and prefectural and municipal road bridge programs.
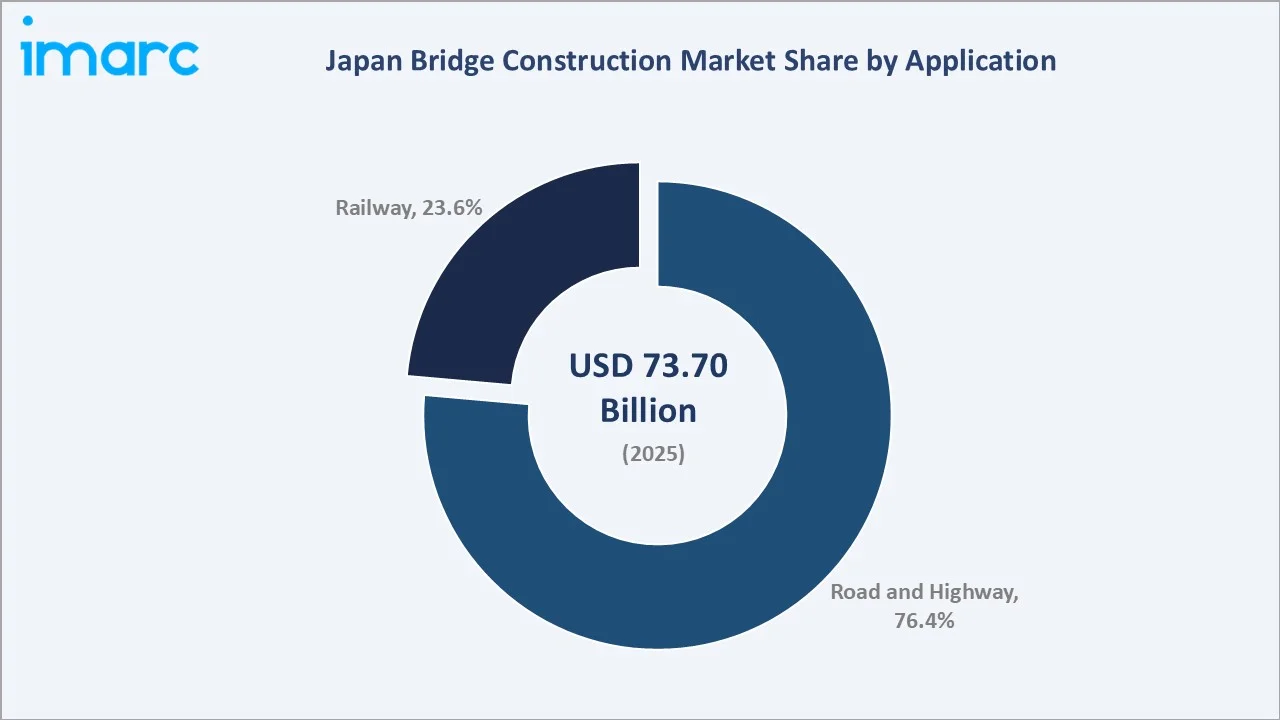
Railway bridge construction at 23.6% reflects the construction of Shinkansen extension projects alongside urban rail bridge rehabilitation programs in Tokyo and Osaka metropolitan areas. Railway grows at ~5.5% CAGR through 2034, supported by the government's commitment to complete the Shinkansen network and major urban rail capacity expansion projects.
Regional Market Insights
|
Region |
Share (2025) |
Key Japan Bridge Construction Market Drivers & Characteristics |
|
Kanto Region |
28.7% |
Reflecting the Tokyo metropolitan area's massive infrastructure investment in Metropolitan Expressway rehabilitation and the concentration of major bridge engineering firms. |
|
Kansai/Kinki Region |
17.5% |
Reflecting the Osaka-Kobe-Kyoto metropolitan corridor's expressway bridge rehabilitation, Osaka Bay area infrastructure development, Shinkansen and urban rail bridge programs. |
|
Central/Chubu Region |
15.8% |
Reflecting major expressway new construction including Shin-Tomei Expressway extensions, Chuo Expressway rehabilitation, Hokuriku Shinkansen bridge construction through mountainous terrain. |
|
Kyushu-Okinawa Region |
10.6% |
Reflecting bridge construction for Kyushu Shinkansen upgrades, Nagasaki Shinkansen new infrastructure, and Okinawa's island connectivity bridge maintenance programs. |
|
Tohoku Region |
8.9% |
Reflecting continued earthquake and tsunami reconstruction bridge programs and ongoing highway network reinforcement. |
|
Chugoku Region |
7.6% |
Reflecting Hiroshima-Yamaguchi expressway bridge programs and the iconic Seto Inland Sea bridge maintenance requirements on the Setouchi Highway. |
|
Hokkaido Region |
6.2% |
Reflecting bridge construction and rehabilitation for the Hokkaido Shinkansen expansion, and Hokkaido expressway network bridge maintenance. |
|
Shikoku Region |
4.7% |
Reflecting maintenance of the iconic Seto-Ohashi Bridge, alongside prefectural road bridge rehabilitation on Japan's smallest main island. |
The Kanto region's 28.7% dominance reflects Tokyo's position as Japan's primary infrastructure investment concentration, with the Metropolitan Expressway Company's multi-decade renewal program and massive urban rail bridge rehabilitation programs sustaining the region's market leadership. The Kansai/Kinki region's 17.5% share is supported by Osaka's infrastructure preparation for Expo 2025 legacy and ongoing Bay Area development.
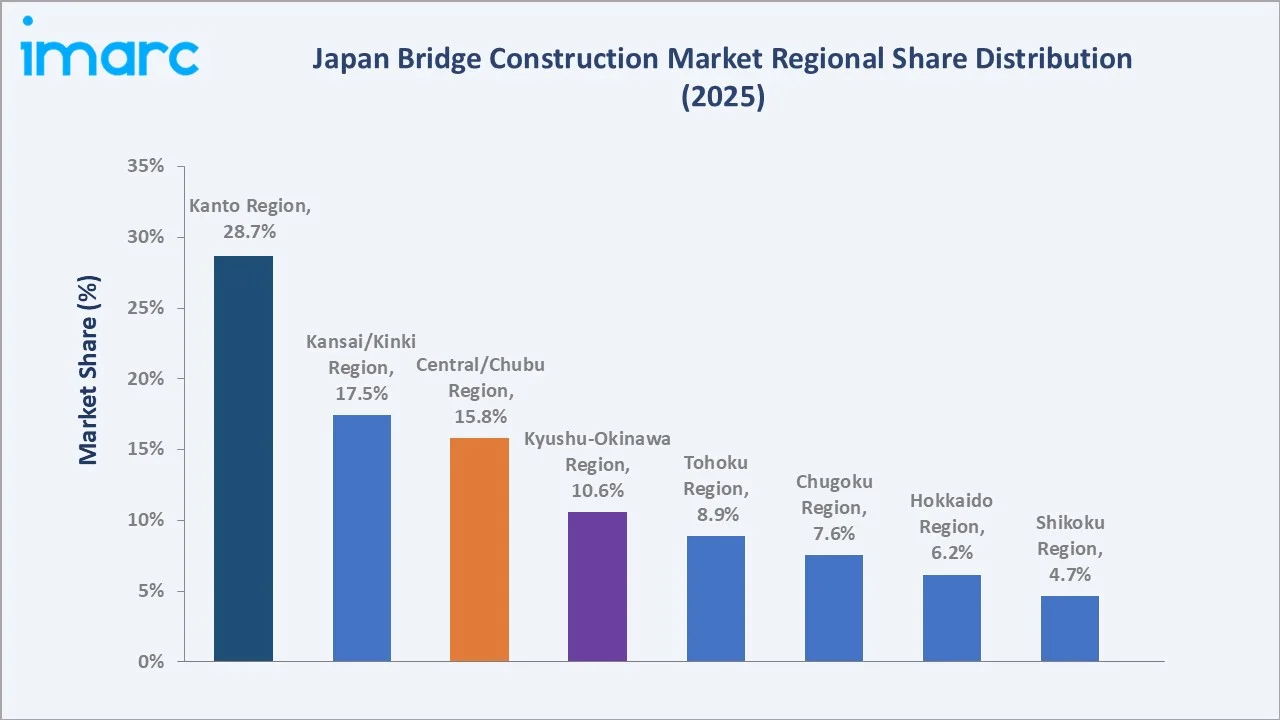
The Central/Chubu region's 15.8% reflects the expressway bridge construction and rehabilitation programs alongside the Hokuriku Shinkansen's demanding mountain crossing bridge structures. Kyushu-Okinawa's 10.6% reflects Nagasaki Shinkansen bridge infrastructure and Okinawa's unique island connectivity maintenance requirements. The Tohoku, Chugoku, Hokkaido, and Shikoku regions collectively represent 27.4% of total market share, with seismic retrofitting, aging expressway rehabilitation, and Shinkansen expansion sustaining construction activity across all outer regions through 2034.
Competitive Landscape
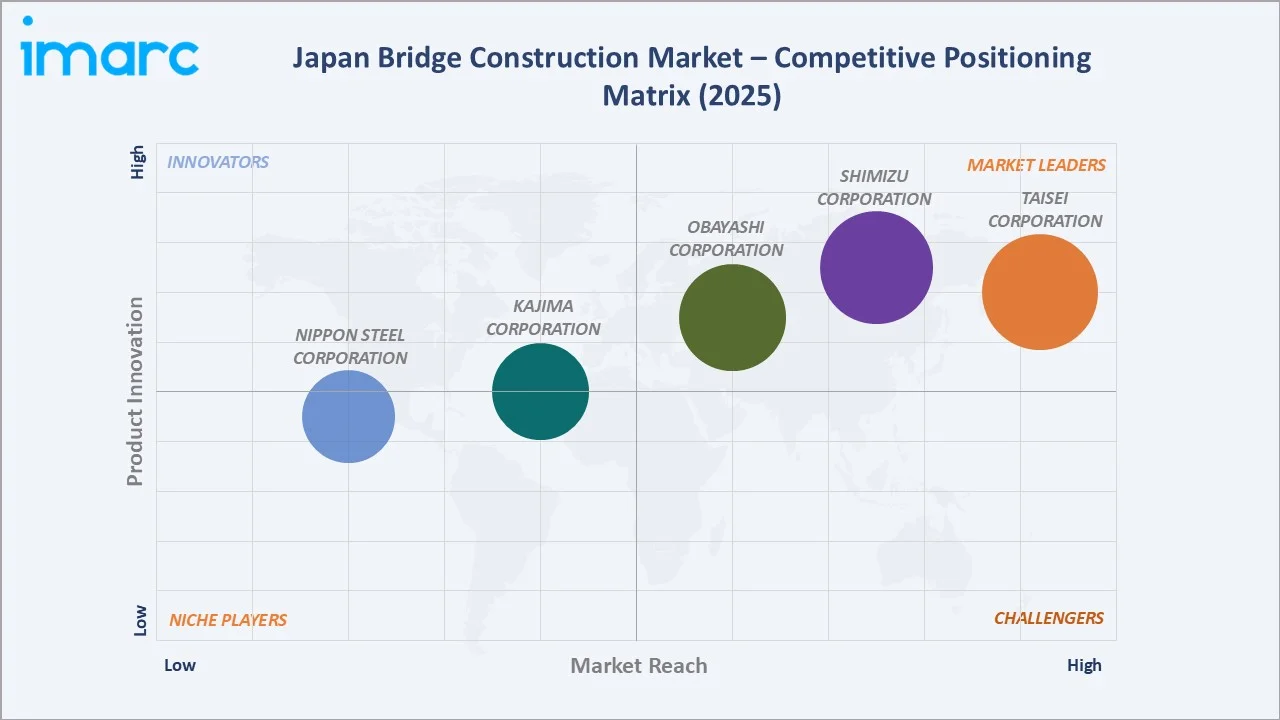
Japan bridge construction market is characterized by a well-structured competitive landscape of large general contractors with specialized bridge engineering divisions, supplemented by steel bridge fabrication specialists and engineering companies. Competition centers on technical capability alongside public tendering performance, track record on major bridges, and the breadth of self-performing construction capability.
|
Company |
Key Projects |
Market Position |
Core Strength |
|
TAISEI CORPORATION |
Hatatekura Bridge Reconstruction, Metropolitan Inter City Expressway (Ken-O-Do), Tonegawa Bridge, Tohoku Expressway Michinoku Bridge Deck Replacement Project |
Market Leader |
Taisei Corporation is one of Japan's five "super general contractors" and plays a major role in constructing complex infrastructure, including large-scale bridges, highways, and tunnels, both domestically and internationally. |
|
SHIMIZU CORPORATION |
Kuno River Bridge, National Highway No.42 Susami-Kushimoto Road Azumamegawa No.1 Bridge, Tohoku Expressway Natsukawa Bridge Deck Replacement Project |
Market Leader |
Shimizu Corporation acts as a leading general contractor in Japan, designing, building, and renovating critical public infrastructure, including specialized bridge construction and renewal projects. |
|
OBAYASHI CORPORATION |
Shin-Matsudo Bridge Substructure, Tokai-Kanjo Expressway Niwada Viaduct, HIGASHI-MEIHAN EXPWY Yatomi Viaduct |
Market Leader |
Obayashi Corporation is a major Japanese construction contractor that builds and rehabilitates complex bridge infrastructure both domestically and internationally. |
|
KAJIMA CORPORATION |
Tsubasa Bridge, Rainbowbridge |
Established Player |
Kajima Corporation constructs major bridges, viaducts, and highway infrastructure across Japan and internationally. |
|
NIPPON STEEL CORPORATION |
Panel Bridge, Duplex stainless steel footbridge, Bridge using square piping, Water pipe bridge |
Established Player |
Nippon Steel Corporation provides specialized high-performance steel materials, modular components, and engineering solutions for global bridge construction. |
The competitive landscape is shaped by government public works procurement through open competitive tendering, design-build (DB), and early contractor involvement (ECI) procurement methods for complex rehabilitation projects. Technical scoring criteria are becoming critical competitive differentiators alongside price competition in public bridge tendering.
Key Company Profiles
TAISEI CORPORATION
TAISEI CORPORATION is one of Japan's major general contractors and a leader in bridge construction through its Civil Engineering Division, which handles major expressway, urban, and railway bridge projects across Japan and internationally. Taisei has pioneered seismic isolation technology adoption in Japanese bridge construction and is an early leader in BIM/CIM digital engineering for bridge infrastructure. The company maintains a strong track record on complex expressway bridge rehabilitation projects and urban expressway construction in the Kanto Region, including significant Metropolitan Expressway renewal program contracts.
- Key Projects: Hatatekura Bridge Reconstruction, Metropolitan Inter City Expressway (Ken-O-Do), Tonegawa Bridge, Tohoku Expressway Michinoku Bridge Deck Replacement Project.
- Strategic Focus: Advancing BIM/CIM adoption across all civil infrastructure projects, developing proprietary construction automation and robotics for bridge erection, expanding innovative ECI and design-build project delivery capability; strengthening seismic engineering excellence.
SHIMIZU CORPORATION
SHIMIZU CORPORATION, one of Japan's oldest and most prestigious general contractors, operates a highly capable civil engineering division with world-class bridge construction expertise spanning steel, concrete, and composite bridge types. Shimizu's railway bridge engineering capability is particularly strong, having delivered major Shinkansen bridge infrastructure on multiple high-speed rail extension projects. The company integrates advanced seismic engineering, BIM/CIM digital modeling, and construction robotics research into its bridge project delivery, and has developed proprietary automated bridge inspection systems using drone and AI technologies.
- Key Projects: Kuno River Bridge, National Highway No.42 Susami-Kushimoto Road Azumamegawa No.1 Bridge, Tohoku Expressway Natsukawa Bridge Deck Replacement Project.
- Strategic Focus: Expanding extension bridge construction capability, advancing construction automation to address labor shortage, developing AI-powered bridge inspection technology, growing infrastructure overseas to supplement Japan domestic market through global bridge construction expertise.
Market Concentration Analysis
Japan bridge construction market is moderately concentrated at the contractor level, with the top five general contractors collectively competing for the largest public infrastructure projects through competitive tendering. Specialized steel bridge contractors collectively account for a significant share of steel bridge construction and fabrication. The prestressed concrete specialist segment is served by specialist contractors with deep technical expertise in Japan's dominant concrete bridge construction methodology. Expressway bridge projects and managed national highway bridge programs collectively represent the market's highest-value procurement segments, while prefectural and municipal bridge programs create a more fragmented competitive environment with strong regional contractor participation.
Investment & Growth Opportunities
Highest Growth Segments
Composite materials bridge rehabilitation (~6.8% CAGR est.), railway bridge construction (~5.5% CAGR est.), BIM/CIM digital engineering platform development, seismic retrofitting program execution, and smart bridge sensor network installation and maintenance represent Japan's highest-priority bridge construction investment vectors through 2034.
Investment Themes
- Bridge Rehabilitation Technology and Lifecycle Management: Japan's aging bridge stock crisis creates a structurally unavoidable and growing rehabilitation investment requirement. Companies developing proprietary rehabilitation technologies that extend bridge service life at lower cost than full replacement are positioned to capture disproportionate value from this demand wave. Lifecycle management capability combining digital inspection, SHM, and predictive maintenance creates recurring revenue streams beyond one-time construction contracts.
- Construction Automation and Robotics for Labor-Shortage Resilience: Japan's severe and worsening construction skilled labor shortage makes automation and robotics investment a strategic necessity for bridge construction companies seeking to maintain project delivery capacity. Companies leading robotics-assisted bridge construction can sustain output volumes despite workforce decline, differentiate on construction quality and schedule reliability, and capture growing contract volumes as labor-intensive competitors face capacity constraints.
Future Market Outlook (2026-2034)
The Japan bridge construction market is projected to grow from USD 73.70 Billion in 2025 to USD 116.10 Billion by 2034, delivering a 5.18% CAGR over the forecast period through sustained government infrastructure investment, escalating bridge rehabilitation demand, seismic retrofitting program acceleration, Shinkansen network completion, and composite material technology adoption. The market's anchor value of USD 94.87 Billion in 2030 represents the structural inflection at which Japan's bridge aging rehabilitation crisis reaches peak investment intensity as the 50-year service life threshold is breached by a rapidly growing proportion of the national bridge stock.
Three structural forces are expected to define the Japan bridge construction market through 2034. First, the aging bridge crisis will escalate from a significant market driver in 2025 to the dominant demand force through 2034. Second, Japan's earthquake-driven seismic engineering requirements will continuously elevate bridge construction technical complexity and value. Third, digital technology transformation will reshape competitive dynamics and create new service revenue streams for market leaders.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with senior executives from major bridge construction contractors, structural engineering consulting firms, government infrastructure managers, steel and concrete material suppliers, inspection technology companies, and industry analysts specializing in Japan's civil infrastructure sector. Discussions validated market size estimates, assessed material and application segment dynamics, evaluated competitive positioning, and gathered qualitative insights on aging bridge rehabilitation demand, seismic policy developments, and BIM/CIM digital engineering adoption rates across Japan's bridge industry.
Secondary Research
Secondary research encompassed road and bridge statistics, Japan Road Association publications, Japan technical reports, prefectural infrastructure master plans, construction company annual reports and financial disclosures, press releases on major bridge project awards, seismic engineering research publications, and reputed market intelligence publications. These resources analyzed market trends, technology adoption, competitive positioning, and regional market dynamics across Japan's bridge construction industry.
Forecasting Models
Forecasting models were developed using historical market revenue data (2020-2025), bridge aging statistics and rehabilitation investment projections, expressway development program timelines, Shinkansen extension construction schedules, seismic retrofitting program investment requirements, and macroeconomic public works budget indicators. The analysis incorporated both top-down and bottom-up approaches, validated through primary research cross-referencing, to generate reliable market forecasts through 2034.
Japan Bridge Construction Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Beam Bridge, Truss Bridge, Arch Bridge, Suspension Bridge, Cable-stayed Bridge, Others |
| Materials Covered | Steel, Concrete, Composite Materials |
| Applications Covered | Road and Highway, Railway |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | TAISEI CORPORATION, SHIMIZU CORPORATION, OBAYASHI CORPORATION, KAJIMA CORPORATION, NIPPON STEEL CORPORATION, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan bridge construction market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan bridge construction market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan bridge construction industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Bridge Construction Market Report
The Japan bridge construction market reached USD 73.70 Billion in 2025, driven by large-scale government infrastructure investment, aging bridge rehabilitation demand, seismic retrofitting programs, and Shinkansen network expansion projects.
The market is projected to grow at a CAGR of 5.18% during 2026-2034, reaching USD 116.10 Billion by 2034, driven by the aging bridge rehabilitation wave, seismic retrofitting mandates, expressway programs, Shinkansen extension construction, and composite material adoption in bridge rehabilitation.
Concrete leads at 51.6% (2025) through its cost-effectiveness across the majority of Japan's road bridge stock, wide applicability in beam and box girder bridge types, and proven durability.
Road and highway leads at 76.4% (2025) through expressway new construction and rehabilitation programs and the massive aging road bridge stock requiring repair and replacement.
The Kanto region leads at 28.7% (2025) through Tokyo metropolitan area infrastructure programs including Metropolitan Expressway renewal, Tokyo Outer Ring Road, and urban rail bridge rehabilitation, combined with the concentration of major bridge construction company headquarters and national program management.
Leading companies include TAISEI CORPORATION, SHIMIZU CORPORATION, OBAYASHI CORPORATION, KAJIMA CORPORATION, and NIPPON STEEL CORPORATION, among others.
The market is projected to reach approximately USD 94.87 Billion by 2030, reflecting the peak intensity of the aging bridge rehabilitation wave, accelerated seismic retrofitting programs, Hokkaido Shinkansen extension bridge construction, and BIM/CIM digital engineering mainstream adoption across major bridge projects.
Priority investment opportunities include bridge rehabilitation technology development, construction automation and robotics addressing the labor shortage, BIM/CIM digital engineering platform development, structural health monitoring sensor network deployment, Shinkansen extension bridge engineering capability, and composite material innovation for corrosion-resistant bridge solutions in Japan's challenging coastal environment.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade