Japan Electric Bus Market Size, Share, Trends and Forecast by Propulsion Type, Battery Type, Length, Range, Battery Capacity, and Region, 2026-2034
Japan Electric Bus Market Size, Share, Trends & Forecast (2026-2034)
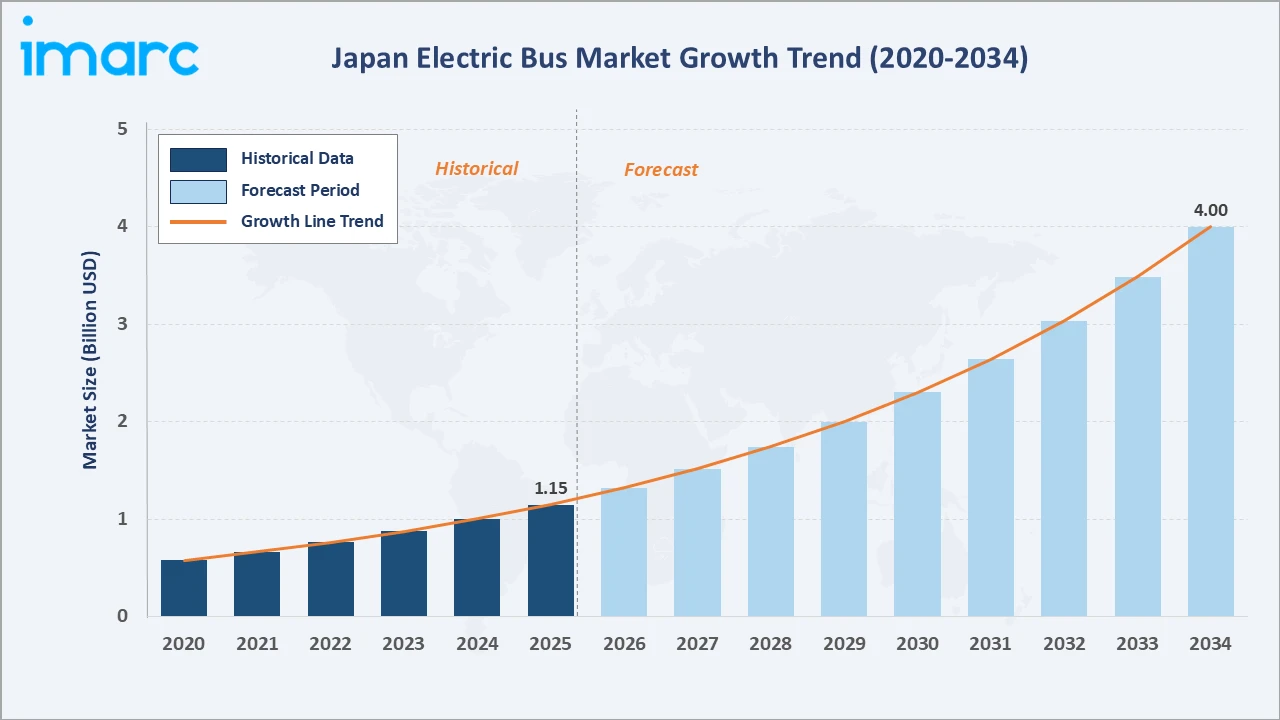
The Japan electric bus market grew from USD 1.15 Billion in 2025 to USD 1.32 Billion in 2026 and is projected to reach USD 4.00 Billion by 2034, growing at a CAGR of 14.84% during 2026-2034. According to the Automobile Inspection & Registration Information Association, the number of electric buses increased from 101 units at the end of March 2020 to 580 units by the end of March 2024, accelerating the growth of the market. Battery electric vehicles (BEVs) dominate with a 90.0% share; lithium-ion battery leads the battery type at 95.0%, while the Kanto region leads at 35.0% of national fleet deployments in 2025, driven by Tokyo's metropolitan transit electrification commitment.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 1.15 Billion |
|
Market Size (2026) |
USD 1.32 Billion |
|
Market Forecast (2034) |
USD 4.00 Billion |
|
CAGR (2026-2034) |
14.84% |
|
Historical Period |
2020-2025 |
|
Base Year |
2025 |
|
Forecast Period |
2026-2034 |
|
Largest Propulsion Type |
Battery Electric Vehicle (BEV) (90.0%) |
|
Dominant Battery Type |
Lithium-ion Battery (95.0%) |
|
Largest Region |
Kanto Region (35.0%) |
The Japan electric bus market grew from USD 0.58 Billion in 2020 to USD 1.15 Billion in 2025 and to USD 1.32 Billion in 2026, reflecting robust pre-commercial fleet rollouts and policy-backed procurement programs. By 2030, the market is projected to reach USD 2.30 Billion, before accelerating to USD 4.00 Billion by 2034.
To get more information on this market, Request Sample
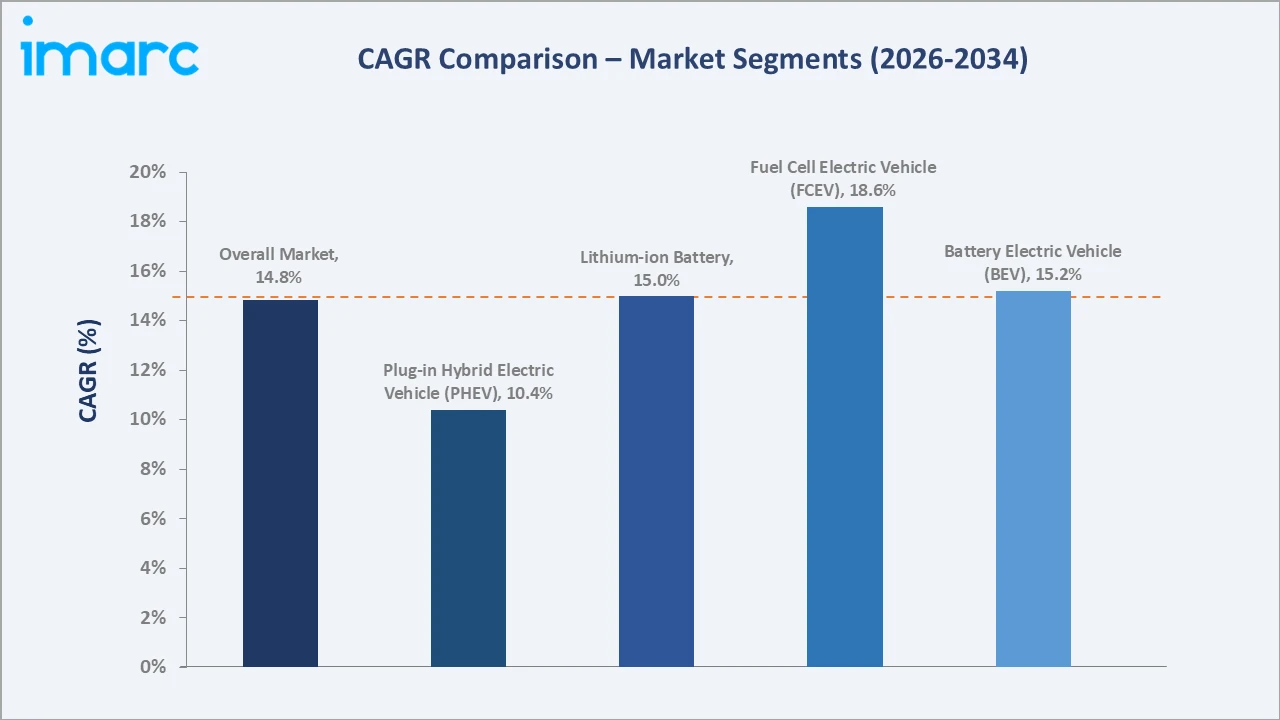
Fuel cell electric vehicles (FCEVs) represent the fastest-growing propulsion at an estimated 18.6% CAGR during 2026-2034, supported by Japan's national hydrogen strategy and investments in refueling infrastructure. Battery electric vehicles (BEVs) are growing at a 15.2% CAGR, and lithium-ion batteries are growing at a 15.0% CAGR.
Executive Summary
The Japan electric bus market is on a high-growth trajectory, anchored by the country's binding 2050 carbon neutrality commitment and its medium-term 2035 target to electrify all new commercial vehicles. Battery cost reductions are improving fleet economics across urban transit operators. Fuel cell electric vehicle (FCEV) adoption is gaining momentum, particularly for intercity and high-capacity routes where battery charging infrastructure remains constrained.
Battery electric vehicles (BEVs) hold a commanding 90.0% share of all electric bus deployments in 2025, underpinned by their operational maturity, established charging infrastructure, and superior range performance. Lithium-ion batteries account for 95.0% of all bus battery systems, reflecting their cost-performance advantage over alternative chemistries. The Kanto region leads at 35.0% of national fleet deployments, driven by Tokyo Metropolitan Government procurement programs and high-frequency urban bus routes.
Key Market Insights
|
Insight |
Data |
|
Dominant Propulsion Type |
Battery Electric Vehicle (BEV) (90.0%) |
|
Dominant Battery Type |
Lithium-ion Battery (95.0%) |
|
Leading Region |
Kanto Region (35.0%) |
|
Key Market Opportunity |
Fleet electrification mandates and hydrogen bus scale-up for intercity routes |
Key Analytical Observations Supporting the Above Data:
- Battery Electric Vehicle (BEV) at 90.0%: Battery electric buses maintain dominance due to declining lithium-ion costs, mature charging ecosystems across urban Japan, and operational ranges.
- Lithium-ion Battery at 95.0%: Lithium-ion batteries account for nearly all bus battery systems due to their proven energy density, fast-charging capability, and improving cycle life.
- Kanto Region at 35.0%: The Kanto region leads due to Tokyo's large urban bus network, government procurement programs, and concentration of charging infrastructure investments across metropolitan commuter routes.
Japan Electric Bus Market Overview
The Japan electric bus market encompasses the design, manufacturing, procurement, deployment, and operation of zero-emission buses powered by electric drivetrains, including battery electric, fuel cell electric, and plug-in hybrid configurations. The market spans urban transit systems, intercity coach services, airport shuttle operations, and school transport networks. Key macroeconomic enablers include Japan's 2050 carbon neutrality mandate, Tokyo's aim to deploy at least 300 zero-emission buses by 2030, and subsidy frameworks that reduce operator acquisition costs. The ecosystem integrates battery suppliers, charging infrastructure providers, fleet operators, and municipal transit authorities in an increasingly coordinated technology deployment chain.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
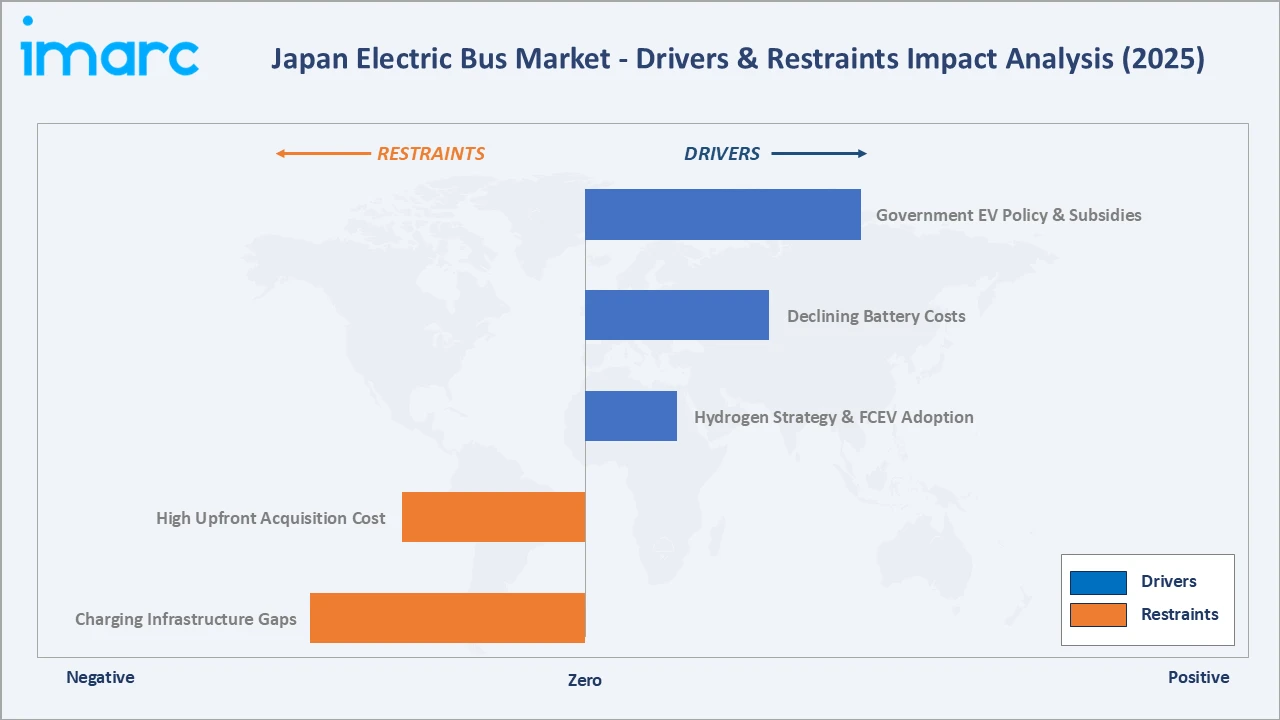
- Government EV Policy & Subsidies: Under the Zero Emission Tokyo Strategy, Tokyo aims to deploy at least 300 zero-emission buses by 2030, and Japan's 2050 carbon neutrality target are compelling transit operators to accelerate fleet replacement. National and municipal subsidy programs are directly improving fleet economics for transit authorities.
- Declining Battery Costs: Lithium-ion battery pack prices have declined over the past decade, making BEV bus total cost of ownership competitive with diesel alternatives across medium and long fleet operational cycles.
- Hydrogen Strategy & FCEV Adoption: Japan's mobility strategy set targets for deploying 200,000 fuel cell vehicles (FCVs) by 2025 and 800,000 by 2030, alongside plans to establish 320 hydrogen fueling stations by 2025 and 900 by 2030. This infrastructure expansion can indirectly benefit the Japan electric bus market by improving access to hydrogen technologies and strengthening policy support for zero-emission public transportation, including fuel cell electric buses.
Market Restraints
- High Upfront Acquisition Cost: The upfront acquisition cost of an electric bus remains substantially higher than equivalent diesel models, creating budgetary constraints for smaller municipal transit operators, particularly those serving lower-density suburban and rural routes with limited subsidy access.
- Charging Infrastructure Gaps: Charging infrastructure gaps persist in less densely populated regions, limiting electric bus deployment to urban corridors and leaving suburban and rural transit networks dependent on conventional powertrains.
Market Opportunities
- Expansion of Zero-Emission Public Transportation: Japan's commitment to reducing carbon emissions is creating opportunities for electric bus manufacturers to supply zero-emission vehicles to public transportation operators. The replacement of conventional diesel buses with battery-electric buses is expected to support market expansion, particularly in urban areas with high passenger traffic.
- Development of Hydrogen Fuel Cell Electric Buses: Japan's investments in hydrogen mobility and refueling infrastructure are creating opportunities for fuel cell electric buses, particularly for long-distance routes and high-utilization public transport services. In October 2026, Toyota launched the second-generation Sora hydrogen fuel-cell bus in Japan, co-developed with Isuzu. Built on Isuzu’s flat-floor electric bus platform, the model features Toyota’s fuel-cell stack, repositioned at the front of the roof to optimize component layout.
Market Challenges
- Grid Capacity Constraints: Grid capacity constraints in high-density urban depot locations require significant electrical infrastructure upgrades, adding to total electrification costs for transit operators managing large fleets.
- Battery End-of-Life Management and Recycling Infrastructure: Battery end-of-life management and recycling infrastructure remain nascent, creating operational complexity and long-term cost uncertainty for fleet operators managing large volumes of decommissioned battery packs across multi-year fleet replacement programs.
Emerging Market Trends
1. Adoption of Ultra-Fast Pantograph Charging Technology
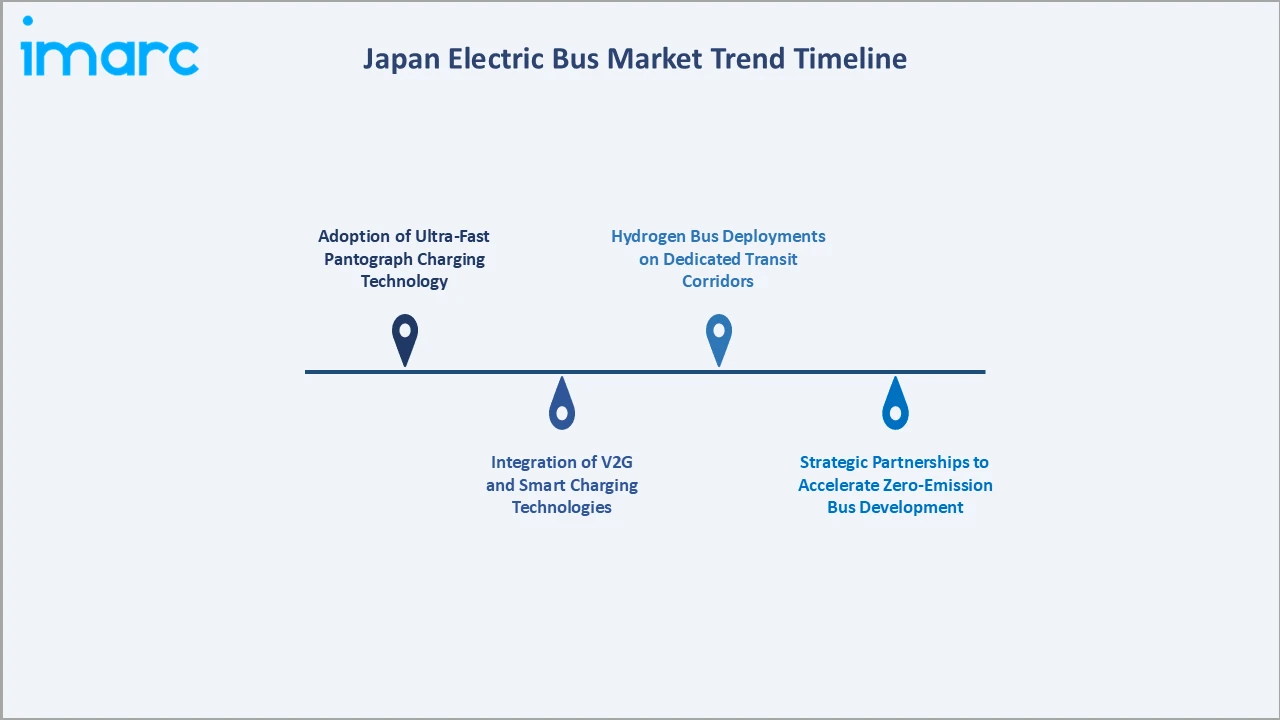
In October 2026, Rinko Bus, Toshiba, and Drive Electro Technology launched a demonstration project in Kawasaki, Japan, featuring a retrofitted electric bus with a pantograph charging system that enables recharging in approximately 10 minutes. The bus is scheduled to enter passenger service on local routes in December 2026. This technology can reduce charging downtime, improve fleet utilization, and support the electrification of public transportation routes.
2. Integration of V2G and Smart Charging Technologies
Vehicle-to-grid (V2G) technology is gaining commercial traction in Japan's electric bus fleets, enabling bus battery packs to support grid stabilization during peak demand periods. Demand-responsive smart charging platforms deployed at urban bus depots are demonstrating measurable reductions in peak energy procurement costs, improving overall fleet operational economics.
3. Hydrogen Bus Deployments on Dedicated Transit Corridors
Hydrogen fuel cell buses are being introduced on select high-frequency intercity and airport shuttle corridors where extended range and rapid refueling capability provide operational advantages over battery-only alternatives. Japan's growing network of hydrogen refueling stations is progressively extending the viable operating range of FCEV transit fleets.
4. Strategic Partnerships to Accelerate Zero-Emission Bus Development
By combining bus manufacturing expertise with technology capabilities, the partnership aims to strengthen the development and commercialization of zero-emission buses for domestic and international markets. Mitsubishi Fuso and Foxconn plan to establish Fuso Bus, an equally owned joint venture, on November 2, 2026, subject to the completion of the transaction. The company will develop, manufacture, sell, and service conventional and zero-emission buses for domestic and international markets.
Industry Value Chain Analysis
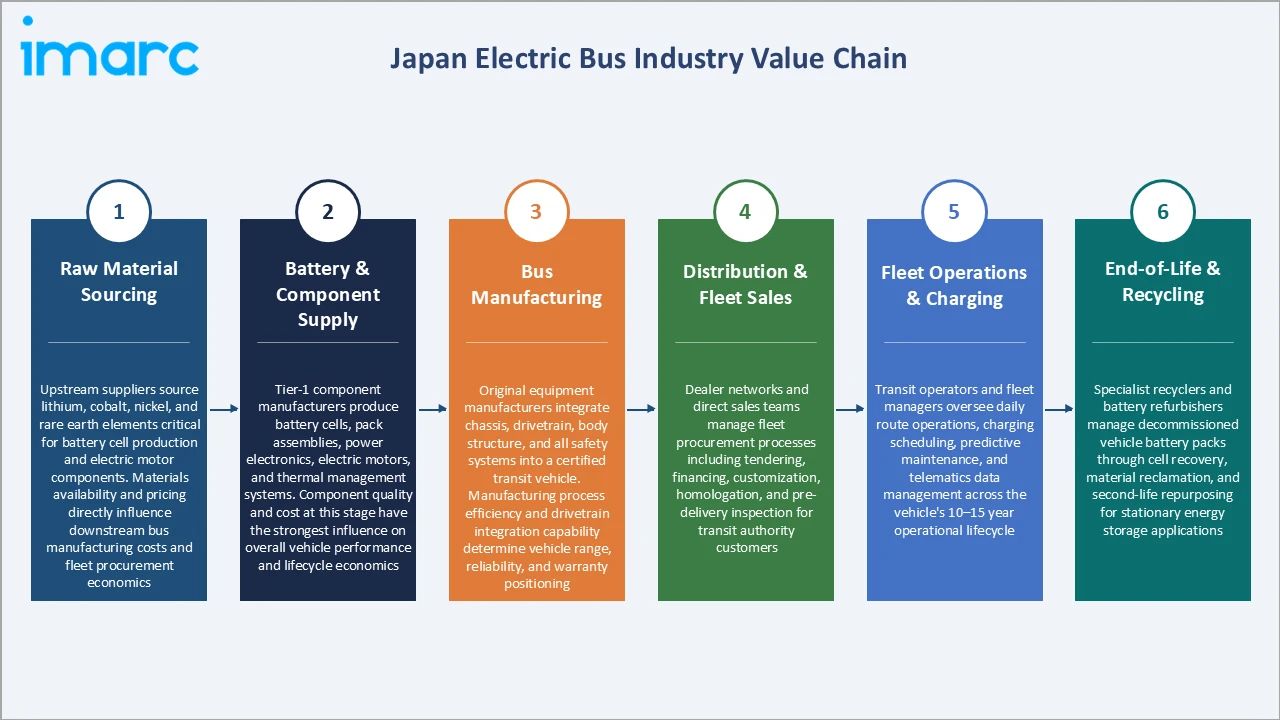
The Japan electric bus market value chain spans six integrated stages from raw material sourcing through end-of-life management. Each stage represents a distinct tier of economic activity, with value addition increasing progressively from upstream commodity extraction to downstream fleet operations and service delivery.
|
Stage |
Key Participants & Description |
|
Raw Material Sourcing |
Upstream suppliers source lithium, cobalt, nickel, and rare earth elements critical for battery cell production and electric motor components. Materials availability and pricing directly influence downstream bus manufacturing costs and fleet procurement economics. |
|
Battery & Component Supply |
Tier-1 component manufacturers produce battery cells, pack assemblies, power electronics, electric motors, and thermal management systems. Component quality and cost at this stage have the strongest influence on overall vehicle performance and lifecycle economics. |
|
Bus Manufacturing |
Original equipment manufacturers integrate chassis, drivetrain, body structure, and all safety systems into a certified transit vehicle. Manufacturing process efficiency and drivetrain integration capability determine vehicle range, reliability, and warranty positioning. |
|
Distribution & Fleet Sales |
Dealer networks and direct sales teams manage fleet procurement processes including tendering, financing, customization, homologation, and pre-delivery inspection for transit authority customers. |
|
Fleet Operations & Charging |
Transit operators and fleet managers oversee daily route operations, charging scheduling, predictive maintenance, and telematics data management across the vehicle's 10–15 year operational lifecycle. |
|
End-of-Life & Recycling |
Specialist recyclers and battery refurbishers manage decommissioned vehicle battery packs through cell recovery, material reclamation, and second-life repurposing for stationary energy storage applications. |
The fleet operations & charging stage generates the highest cumulative value across the electric bus lifecycle. Transit operators capture recurring revenue streams spanning energy procurement, scheduled maintenance, software subscription services, and telematics platform subscriptions over the vehicle's full operational period.
Technology Landscape in the Japan Electric Bus Industry
Battery Technology Innovation
Advancements in battery technology improve energy density, charging speed, battery life, and overall vehicle performance. The development of high-capacity batteries and ultra-fast charging systems can reduce downtime and extend driving range. These innovations also help lower operating costs and accelerate the adoption of electric buses among public transportation operators.
Smart Connectivity & Fleet Management
The integration of IoT, telematics, and AI-powered fleet management systems enables real-time vehicle monitoring, route optimization, and predictive maintenance. These technologies help operators optimize battery usage, reduce downtime, and improve operational efficiency. Additionally, smart charging management can minimize energy costs and support the efficient deployment of electric bus fleets.
Charging Infrastructure & Automation
Innovations such as pantograph charging and smart depot charging systems can reduce charging time, minimize operational downtime, and improve fleet utilization. These developments are encouraging public transportation operators to adopt electric buses by enhancing operational efficiency and simplifying fleet electrification.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Propulsion Type | Battery Electric Vehicle (BEV) | 90.0% | 2025 |
| Battery Type | Lithium-ion Battery | 95.0% | 2025 |
| Length | 🔒 | 🔒 | 2025 |
| Range | 🔒 | 🔒 | 2025 |
| Battery Capacity | 🔒 | 🔒 | 2025 |
| Region | Kanto Region | 35.0% | 2025 |

By Propulsion Type
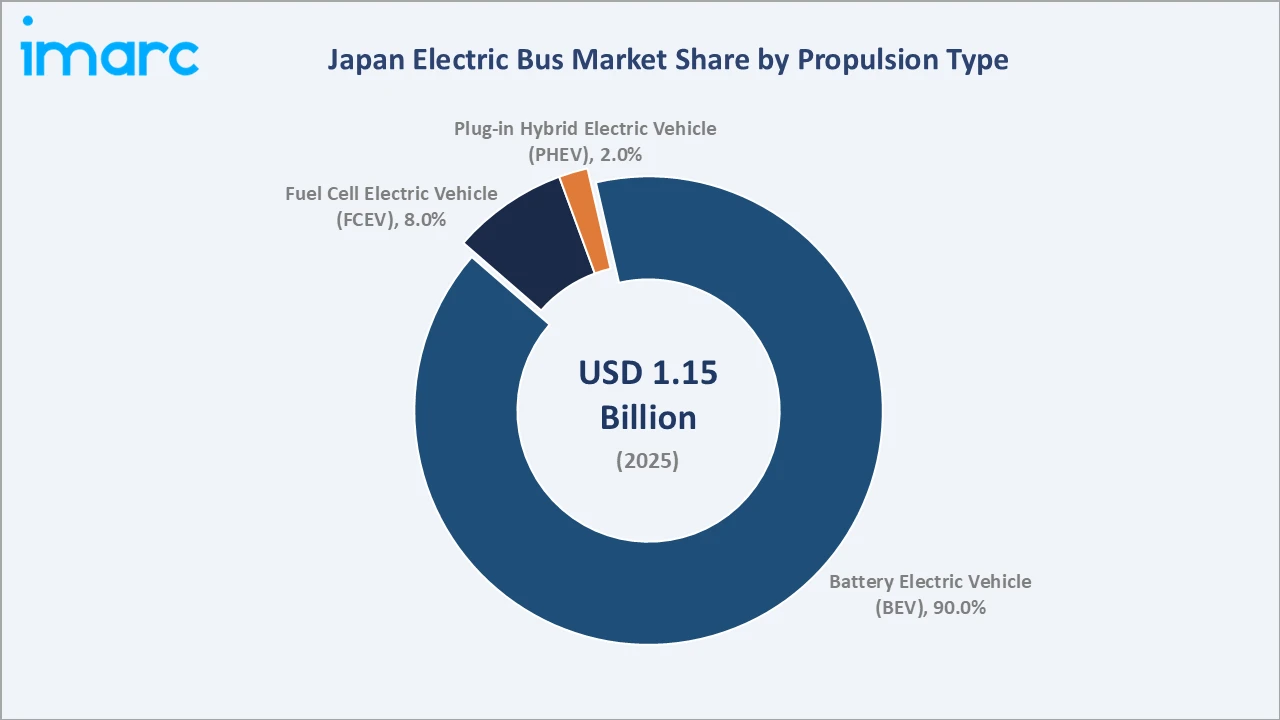
Battery electric vehicles (BEVs) command a dominant 90.0% share in 2025, reflecting their operational maturity, established charging infrastructure, and competitive total cost of ownership. Declining battery costs and expanding rapid-charging networks continue to reinforce BEV dominance through the forecast period.
To access detailed market analysis, Request Sample
Fuel cell electric vehicles (FCEVs) hold an 8.0% share in 2025 and represent the fastest-growing sub-segment at an estimated 18.6% CAGR during 2026-2034. FCEV buses are gaining traction on intercity and airport shuttle corridors where their 500+ km range and rapid refueling capability offer operational advantages. Plug-in hybrid electric vehicles (PHEVs) account for 2.0% in 2025, primarily serving transit operators in areas with constrained charging infrastructure.
By Battery Type
Lithium-ion batteries account for 95.0% in 2025, reflecting their superior energy density, proven safety record, and continuously improving cycle life. LFP and NMC variants dominate bus applications, with LFP gaining share for depot-charged urban routes due to its enhanced thermal stability and lower cost.
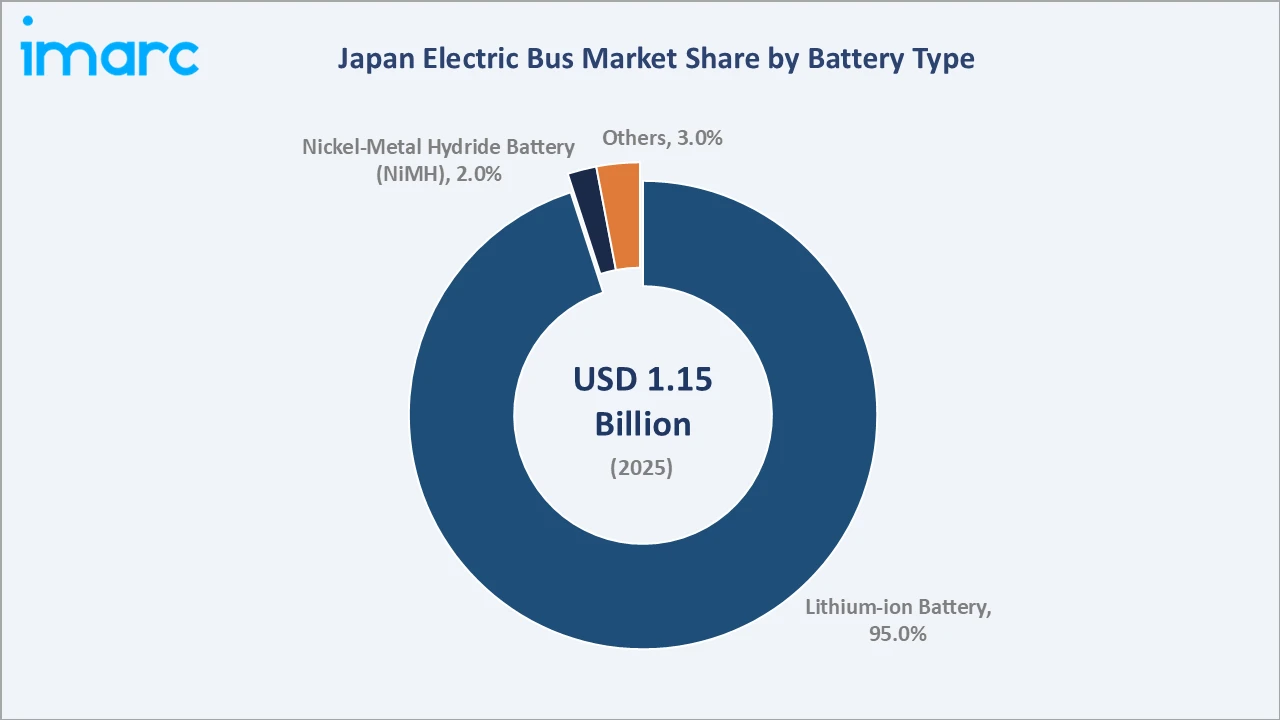
Nickel-metal hydride (NiMH) batteries retain a 2.0% share in 2025, primarily in legacy hybrid-electric bus systems still operating on older platforms. Their market share is expected to decline progressively as fleet replacement programs introduce lithium-ion-equipped replacements. Others, including emerging solid-state and sodium-ion chemistries, account for the remaining 3.0%, with commercial deployment anticipated in the early 2030s.
Regional Market Insights
|
Region |
Share (2025) |
Key Japan Electric Bus Market Drivers & Characteristics |
|
Kanto Region |
35.0% |
Highest concentration of urban transit fleet operations; large metropolitan bus networks drive BEV procurement. |
|
Kansai/Kinki Region |
20.0% |
Major commercial and tourism hubs support transit electrification; intercity BEV route expansion is underway. |
|
Central/Chubu Region |
18.0% |
Industrial corridor transit networks and airport shuttle electrification are key demand drivers. |
|
Kyushu-Okinawa |
8.0% |
Tourism-driven transit electrification and island grid decarbonization create unique fleet deployment dynamics. |
|
Tohoku Region |
7.0% |
Post-reconstruction transit modernization programs and renewable energy integration support EV bus deployment. |
|
Chugoku Region |
5.0% |
Moderate fleet scale with growing electrification investment in key urban transit corridors. |
|
Hokkaido Region |
4.0% |
Cold-weather battery performance challenges addressed through thermal management advancements. |
|
Shikoku Region |
3.0% |
Smallest market; limited fleet scale but growing municipal interest in green transit solutions. |
Kanto region leads with a 35.0% share in 2025, anchored by the country's largest metropolitan bus network and a strong municipal commitment to zero-emission fleet procurement. Kansai/Kinki region accounts for 20.0% of the national market, supported by active transit electrification programs across its major cities. Central/Chubu region holds an 18.0% share, driven by an extensive urban transit network and airport shuttle electrification requirements linking major international aviation hubs. Kyushu-Okinawa region accounts for 8.0%, where island-based renewable energy ecosystems and distinct grid decarbonization objectives create unique incentives for electric bus fleet adoption.
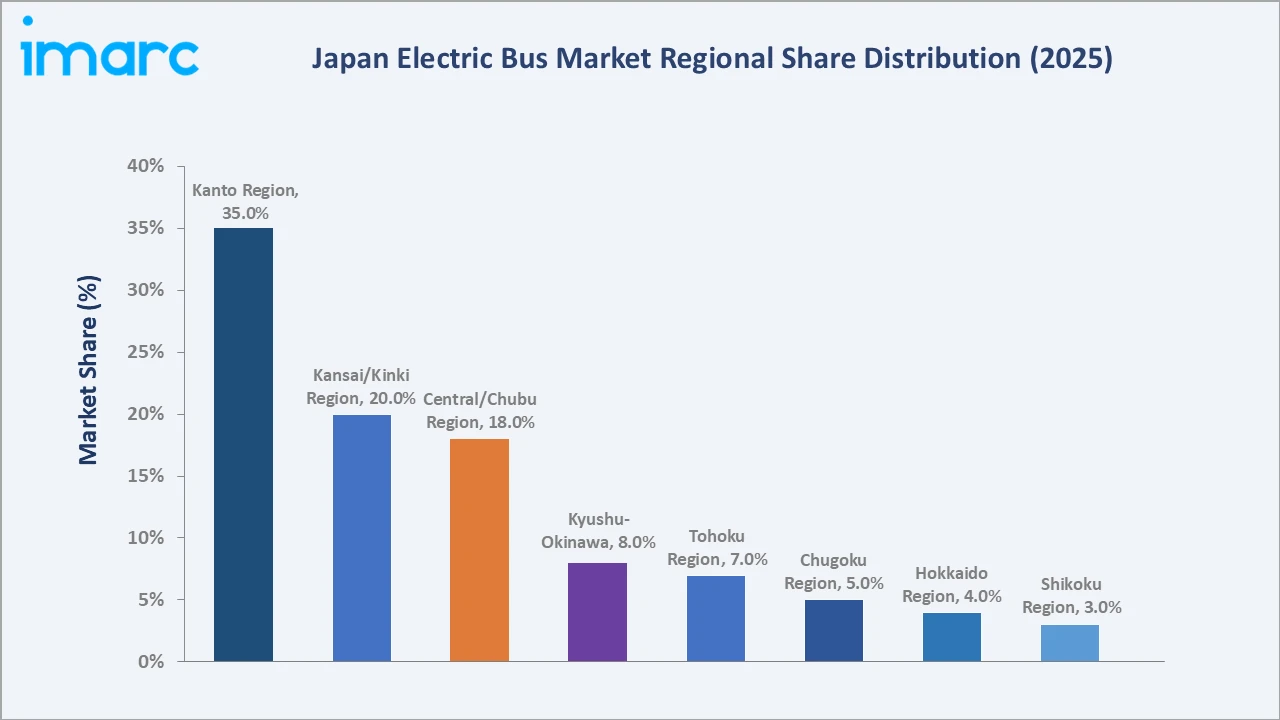
Tohoku region represents 7.0% of the market, supported by post-disaster reconstruction transit modernization programs and strong integration of renewable energy generation with electric bus charging operations. Chugoku region holds a 5.0% share, reflecting a moderate fleet scale with focused electrification investment in key urban transit corridors. Hokkaido region accounts for 4.0% of the market. Shikoku region represents the smallest market segment at 3.0%, constrained by limited urban fleet scale and lower transit passenger volumes.
Competitive Landscape
The Japan electric bus market features a moderately concentrated competitive structure, with global BEV bus manufacturers and domestic industrial conglomerates competing alongside emerging technology specialists.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| BYD Company Ltd. | BYD K9, BYD C9 | Market Leader | BYD electric buses operate across multiple Japanese regions and cities, supporting local public transit and disaster-relief infrastructure. |
| ARCHION Corporation | HINO Poncho Z EV light-duty electric bus | Market Leader | Through Hino Motors, Ltd., ARCHION shapes the Japanese electric and low-emission bus market primarily via compact community and zero-emission transit solutions. |
| ISUZU MOTORS LIMITED | ERGA EV | Innovator | Isuzu Motors Limited plays a leading role by pioneering mass-produced flat-floor battery-electric and hydrogen fuel-cell route buses. |
| TOYOTA MOTOR CORPORATION | Sora | Established Player | Toyota Motor Corporation plays a leading role in Japan's electric bus market by focusing heavily on hydrogen fuel-cell electric vehicles (FCEVs) and strategic industrial partnerships. |
| Hyundai Motor Company | ELEC CITY | Challenger | Hyundai Motor Company entered the Japanese electric bus market by supplying its zero-emission Elec City model to support local decarbonization and public transit goals. |
Competitive intensity is increasing as battery cost parity narrows the performance gap between market entrants and incumbents. Strategic partnerships between bus OEMs, battery suppliers, and charging infrastructure providers are becoming key competitive differentiators in the fleet procurement cycle.
Key Company Profiles
BYD Company Ltd.
BYD Company Ltd. is a leading manufacturer of zero-emission commercial vehicles and offers a comprehensive electric bus portfolio spanning urban route buses, intercity coaches, and airport shuttle platforms. Its vertically integrated production model supports competitive fleet pricing and enables continuous performance iteration across propulsion and battery systems.
- Key Offerings: BYD K9, BYD C9.
- Strategic Focus: Expanding market presence through fleet-competitive pricing, localized after-sales service partnerships, continuous battery range improvement, and deployment of next-generation energy management systems across transit operator fleets.
ISUZU MOTORS LIMITED
ISUZU MOTORS LIMITED is a prominent commercial vehicle manufacturer with an established presence in the bus and truck segments. This company is developing electric bus solutions centered on full-size and mid-size route bus applications for urban and suburban transit operators transitioning from diesel fleets.
- Key Offerings: ERGA EV.
- Key Developments: In May 2024, Isuzu Motors Limited launched the ERGA EV, Japan’s first fully flat-floor battery-electric route bus, designed to support zero-emission public transportation and advance the country’s transition toward carbon neutrality.
- Strategic Focus: Focused on scaling electric bus production capacity, expanding its EV-qualified dealer and service network, and developing next-generation platforms with extended range and fast-charging capability aligned with the fleet replacement cycle.
Market Concentration Analysis
The Japan electric bus market exhibits moderate concentration at the manufacturer level, with a small group of established OEMs collectively accounting for the majority of annual fleet procurement volumes. The top manufacturers benefit from long-standing transit operator relationships, local service infrastructure, and production scale that new entrants find difficult to replicate in the near term.
The broader electric bus ecosystem, encompassing battery suppliers, charging infrastructure providers, and technology integrators, is significantly more fragmented, with a diverse range of domestic and international players competing across specific technology and service niches. Consolidation through strategic partnerships and joint ventures is expected to increase over the forecast period as the market matures.
Investment & Growth Opportunities
Highest Growth Segments
Fuel cell electric vehicles (FCEVs) represent the highest-growth sub-segment at an estimated 18.6% CAGR during 2026-2034, driven by Japan's hydrogen strategy and growing intercity route deployments. Investment in FCEV bus platforms and hydrogen refueling infrastructure offers significant upside as range and refueling advantages become commercially decisive for high-utilization transit routes.
Investment Themes
- Charging Infrastructure Deployment: Rapid expansion of depot and terminal charging infrastructure across Japan's urban transit networks represents an estimated multi-billion-dollar investment opportunity, with transit operators allocating capital at an accelerating pace through 2030 fleet electrification programs.
- Solid-State Battery Development: Japan's leading automotive companies are investing in solid-state battery technology for transit bus applications, targeting energy densities above 400 Wh/kg and commercial readiness by the early 2030s, offering transformative range and safety improvements.
Future Market Outlook (2026-2034)
The Japan electric bus market grew from USD 1.15 Billion in 2025 to USD 1.32 Billion in 2026, reaching a projected USD 4.00 Billion by 2034, at a CAGR of 14.84% during 2026-2034. The market's growth trajectory is underpinned by binding government policy commitments, accelerating fleet replacement cycles, and rapid battery cost improvements compressing the total cost of ownership gap with diesel alternatives.
Three structural forces will define Japan's electric bus market through 2034. First, government-mandated zero-emission procurement targets will systematically replace aging diesel fleets with BEV and FCEV alternatives, driving sustained volume growth across all regional transit networks. Second, solid-state battery commercialization by the early 2030s will dramatically improve range, safety, and charging performance, expanding the addressable fleet replacement market. Third, Japan's hydrogen infrastructure scale-up will enable FCEV buses to capture a growing share of intercity and high-capacity transit routes, diversifying the market's propulsion technology mix.
Research Methodology
Primary Research
Primary research comprised structured consultations with electric bus manufacturers, transit authority procurement officials, fleet operators, battery technology suppliers, and charging infrastructure providers. Inputs were validated against fleet deployment data, procurement tender records, and operator performance reports to ensure analytical accuracy.
Secondary Research
Secondary research drew on published government policy documents, Japan Ministry of Land, Infrastructure, Transport and Tourism fleet data, METI energy and hydrogen strategy publications, transit authority annual reports, battery industry association data, and international electric vehicle market databases.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling approaches, incorporating historical fleet replacement rates, government subsidy program timelines, battery cost decline curves, charging infrastructure rollout schedules, and regional transit operator electrification commitments.
Japan Electric Bus Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Propulsion Types Covered | Battery Electric Vehicle (BEV), Fuel Cell Electric Vehicle (FCEV), Plug-In Hybrid Electric Vehicle (PHEV) |
| Battery Types Covered | Lithium-Ion Battery, Nickel-Metal Hydride Battery (Nimh), Others |
| Lengths Covered | Less Than 9 Meters, 9-14 Meters, Above 14 Meters |
| Ranges Covered | Less Than 200 Miles, More Than 200 Miles |
| Battery Capacities Covered | Up To 400 kWh, Above 400 Kwh |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | BYD Company Ltd., ARCHION Corporation, ISUZU MOTORS LIMITED, TOYOTA MOTOR CORPORATION, Hyundai Motor Company, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan electric bus market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan electric bus market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan electric bus industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Electric Bus Market Report
The Japan electric bus market reached USD 1.32 Billion in 2026, driven by government EV mandates, fleet electrification programs, and declining battery costs.
The market is projected to grow at a CAGR of 14.84% during 2026-2034, supported by policy mandates, battery cost improvements, and expanding charging infrastructure.
The market is projected to reach approximately USD 2.30 Billion by 2030, driven by fleet replacement cycles and growing hydrogen bus deployments on intercity routes.
BEV (Battery Electric Vehicle) leads with a 90.0% share in 2025, supported by mature charging infrastructure, declining battery costs, and proven operational range.
Lithium-ion batteries dominate with a 95.0% share in 2025, reflecting superior energy density, fast-charging capability, and improving cycle life.
Kanto region leads with a 35.0% share in 2025, driven by Tokyo's large urban bus network and the metropolitan government's zero-emission fleet procurement commitment.
Key players include BYD Company Ltd., ARCHION Corporation, ISUZU MOTORS LIMITED, TOYOTA MOTOR CORPORATION, and Hyundai Motor Company, among others.
The market is projected to reach USD 4.00 Billion by 2034, driven by full-fleet electrification mandates, solid-state battery commercialization, and FCEV scale-up.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade