
Japan Hair Dryer Market Size, Share, Trends and Forecast by Type, Application, Distribution Channel, and Region, 2026-2034
Japan Hair Dryer Market Size, Share, Trends & Forecast (2026-2034)
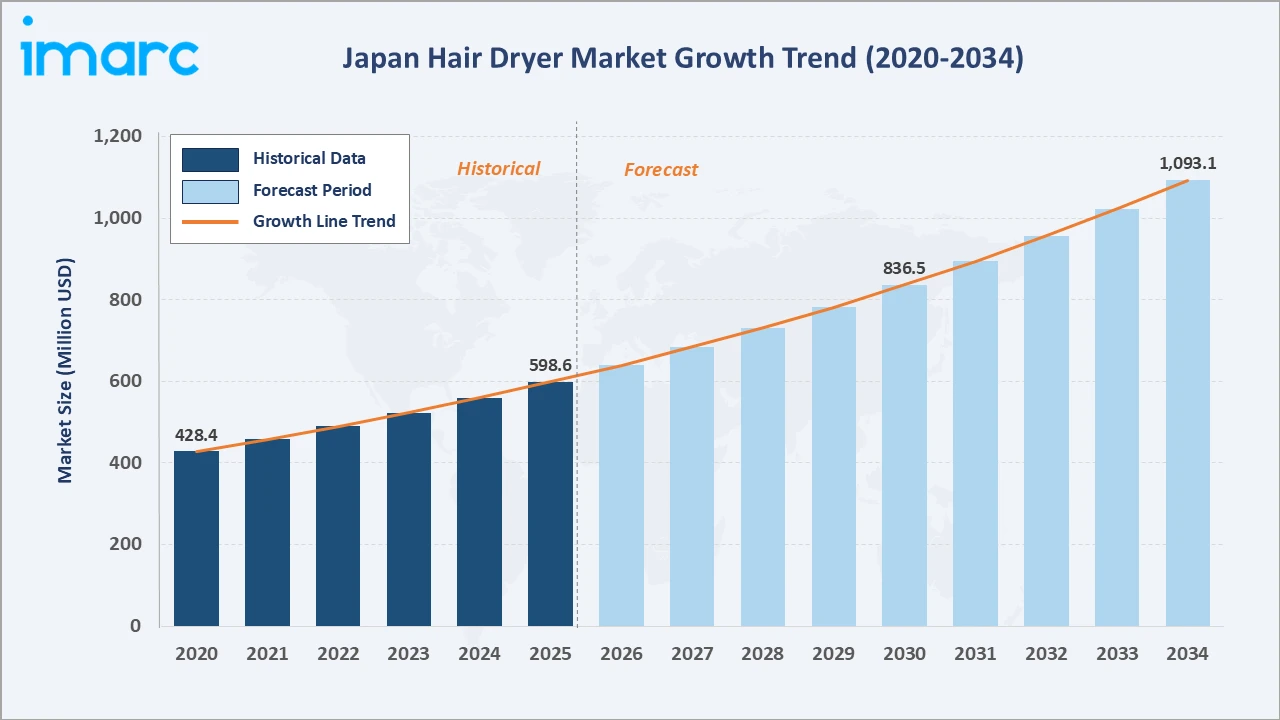
The Japan hair dryer market grew from USD 598.6 Million in 2025 to USD 640.0 Million in 2026 and is projected to reach USD 1,093.1 Million by 2034, growing at a CAGR of 6.92% during 2026-2034. Rising consumer demand for premium, technologically advanced personal care appliances, increasing urbanization, and the growing salon-grade home-care trend drive the market.
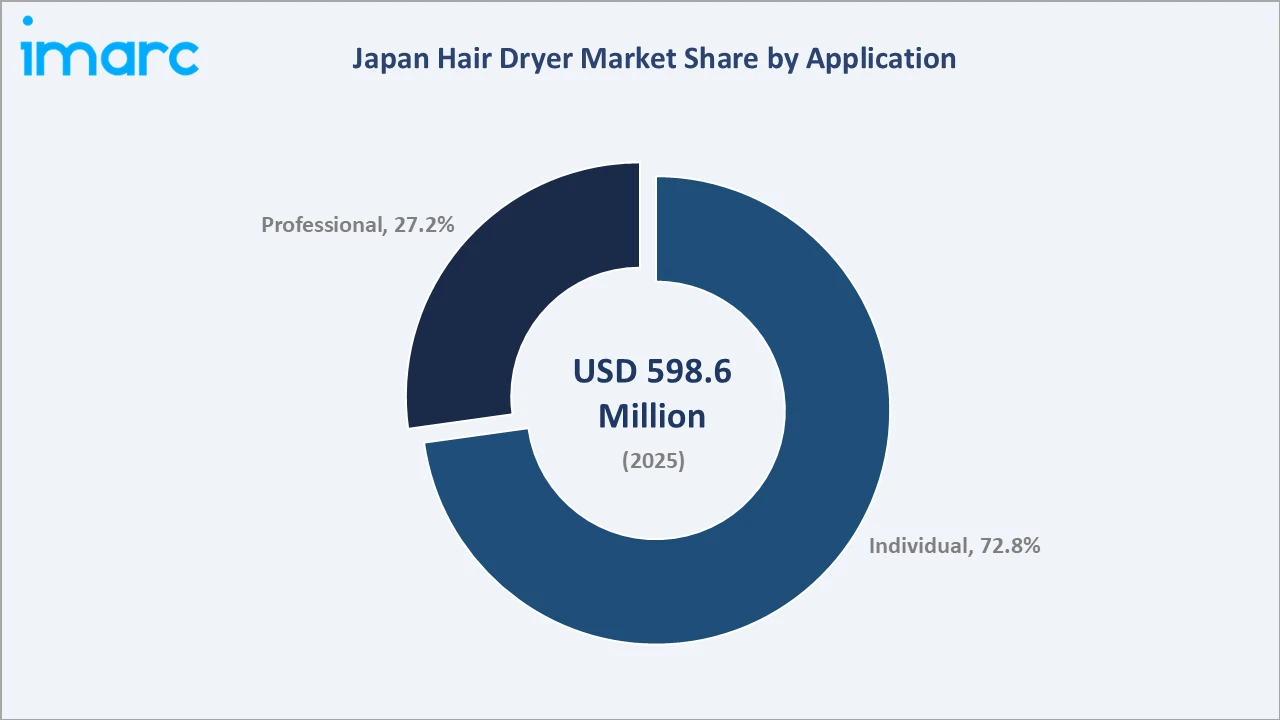
Individual consumers command 72.8% share, while offline channels lead at 64.7%. Kanto Region dominates with 35.8% of the national market.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 598.6 Million |
|
Market Size (2026) |
USD 640.0 Million |
|
Forecast Market Size (2034) |
USD 1,093.1 Million |
|
CAGR (2026-2034) |
6.92% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Application |
Individual (72.8%, 2025) |
|
Dominant Distribution Channel |
Offline (64.7%, 2025) |
|
Leading Region |
Kanto Region (35.8%, 2025) |
The Japan hair dryer market size increased from USD 428.4 Million in 2020 to USD 598.6 Million in 2025 and is estimated to reach USD 640.0 Million in 2026. The market is further expected to grow to USD 836.5 Million by 2030 and USD 1,093.1 Million by 2034.
To get more information on this market, Request Sample
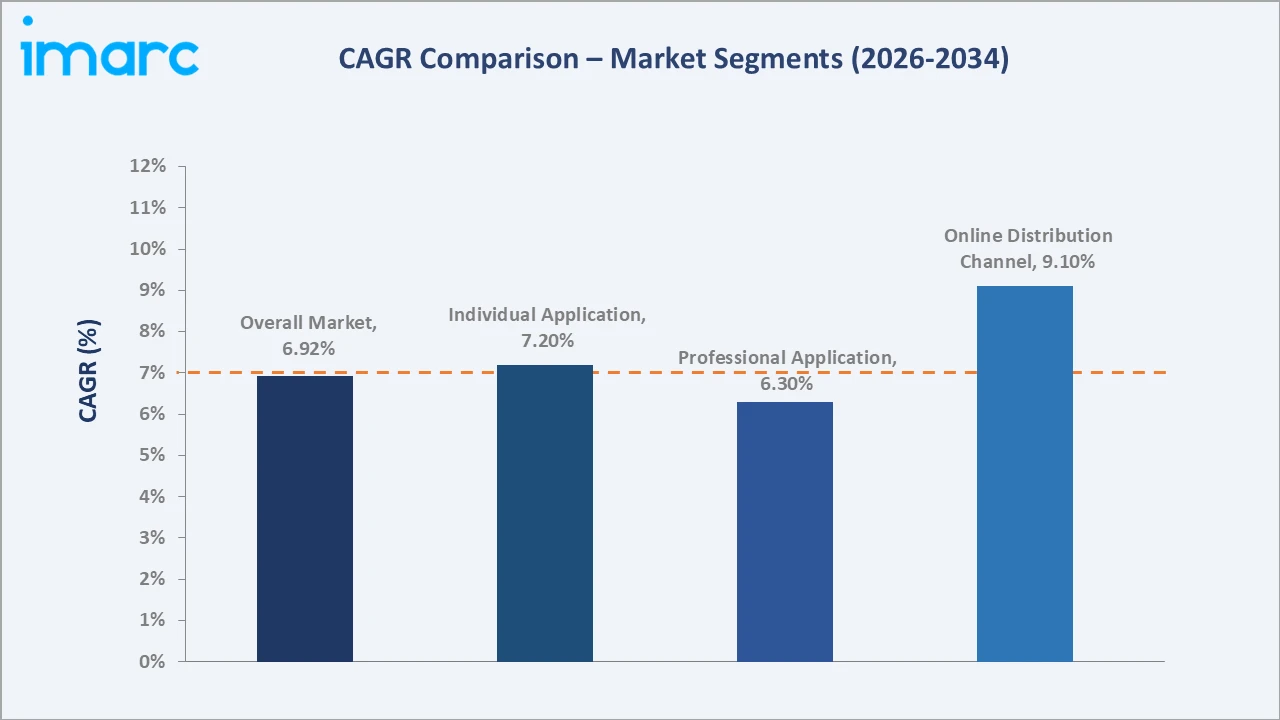
The individual application segment leads at approximately 7.2% CAGR, driven by Japan's high per-capita spending on personal grooming and rising demand for salon-quality results at home. The professional segment at 27.2% grows at approximately 6.3% CAGR, supported by Japan's flourishing salon and beauty services industry across major urban centers.
Executive Summary
The Japan hair dryer market expanded from USD 598.6 Million in 2025 to an estimated USD 640.0 Million in 2026, positioning it among Asia's most commercially mature personal care appliance segments. The market's growth is underpinned by Japan's technologically sophisticated consumer base, high per-capita grooming expenditure, and robust retail infrastructure spanning both offline specialty stores and rapidly growing e-commerce channels across all eight regional markets. The market is projected to reach USD 1,093.1 Million by 2034 at 6.92% CAGR.
Individual consumers at 72.8% represent the primary demand driver, while professional salons at 27.2% continue to expand through Japan's dense urban beauty services network. Kanto Region leads with 35.8% share, reflecting Tokyo's role as Japan's dominant retail and consumer hub. Offline channels at 64.7% retain leadership through established specialty electronics retailers, while online channels at 35.3% are the fastest-growing distribution segment driven by Japan's strong digital commerce infrastructure and DTC brand penetration.
Key Market Insights
| Insight | Data |
|---|---|
| Dominant Application | Individual – 72.8% share (2025) |
| Dominant Distribution | Offline – 64.7% market share (2025) |
| Leading Region | Kanto Region – 35.8% share (2025) |
| Fastest Growing Segment | Online Distribution Channel (~9.1% CAGR, 2026-2034) |
| Key Market Opportunity | Premium AI-powered dryer expansion; online DTC brand launches; professional salon channel growth in secondary regional markets |
Key Analytical Observations Supporting the Above Data:
- Individual at 72.8%: The individual segment dominates due to Japan's high consumer spending on personal grooming, growing at-home salon-grade care trend, and broad availability of premium consumer hair dryers from leading domestic and international brands across all price tiers.
- Offline at 64.7%: Physical retail channels lead through Japan's established electronics specialty store network, consumer preference for in-store product testing before purchase, and the presence of large-format appliance retailers concentrated in Kanto and Kansai regions.
- Online at 35.3% and growing at ~9.1% CAGR: E-commerce channels are the fastest-growing distribution segment, driven by Japan's robust digital retail infrastructure, mobile commerce adoption, and increasing DTC brand presence on major e-commerce platforms.
- Kanto at 35.8%: Kanto Region dominates due to Tokyo's position as Japan's largest consumer market, highest retail density, and greatest concentration of premium electronics retail outlets and professional beauty salon networks nationally.
Japan Hair Dryer Market Overview
The Japan hair dryer market is commercially positioned at a unique intersection: Asia's most technologically advanced consumer electronics market, a deep-rooted personal care and beauty culture with high per-capita grooming spend, and a rapidly evolving professional salon services sector creating structured B2B demand. The market's commercial structure features strong domestic brand presence alongside growing international premium brand penetration across key urban retail centers.
Japan's hair dryer ecosystem integrates domestic manufacturers, international brand importers, multi-channel retail networks, e-commerce platforms, and professional salon distribution channels. Macroeconomic factors including aging population-driven premium health and beauty spending, urbanization concentration in Tokyo and Osaka, and continuous technology investment by domestic electronics manufacturers are shaping the market's competitive dynamics and product innovation trajectory.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
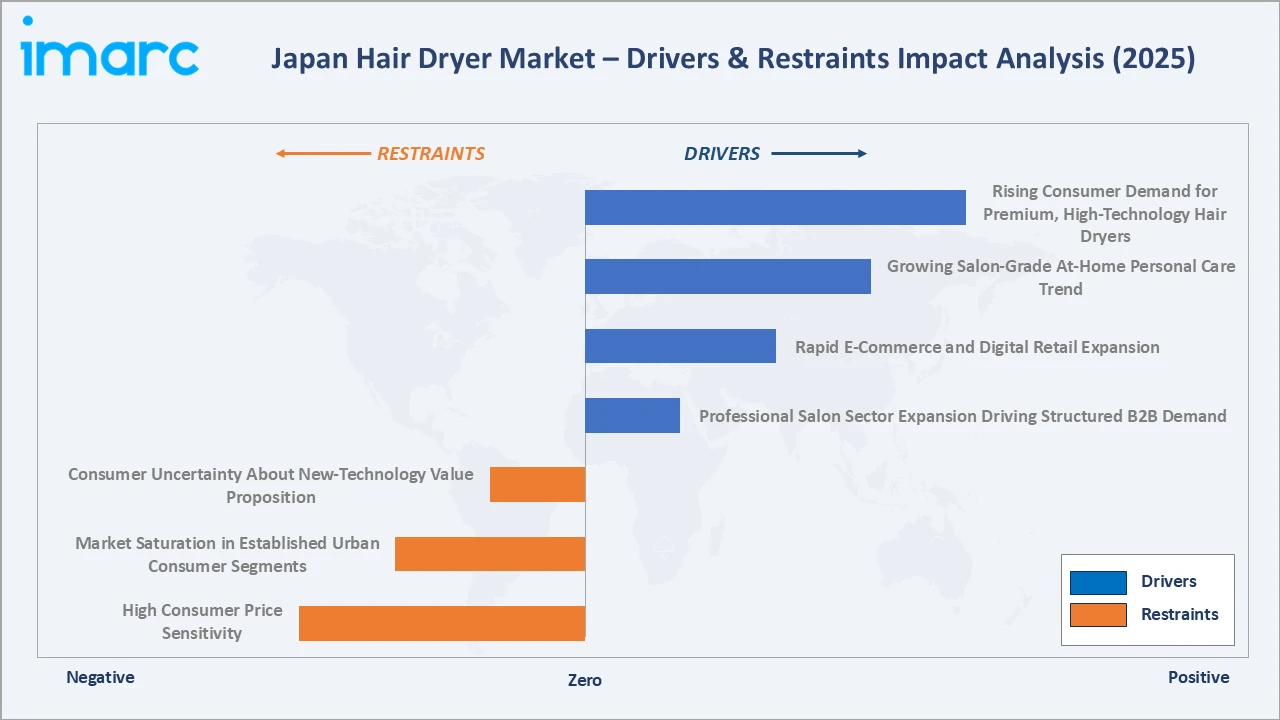
- Rising Consumer Demand for Premium, High-Technology Hair Dryers: Japan's consumers increasingly demand ionic, infrared, and AI temperature-controlled dryers that reduce heat damage and optimize drying time. Premium product adoption is accelerating as consumers prioritize hair health alongside performance, driving manufacturers to invest in advanced technology integration across consumer product lines. The premiumization trend is expanding the high-value market tier, supporting above-average revenue growth per unit sold and elevating average selling prices across both individual and professional application segments through the forecast period.
- Growing Salon-Grade At-Home Personal Care Trend: Japan's consumers increasingly seek professional-level hair care results at home, driving demand for consumer-grade salon performance dryers. This structural consumer shift toward premium at-home grooming appliances is expanding the individual application segment's addressable market. Beauty content media, influencer endorsements, and Japan's strong consumer engagement with premium personal care routines are further reinforcing this trend, encouraging higher per-unit spending and more frequent product upgrades among individual consumers.
- Rapid E-Commerce and Digital Retail Expansion: Japan's e-commerce infrastructure is accelerating hair dryer market reach across urban and rural consumer segments, with the online channel growing at approximately 9.1% CAGR through 2034. Online platforms enable brand discovery, competitive pricing transparency, and consumer review-driven purchase decisions. The expansion of DTC e-commerce channels is enabling premium and emerging brands to reach Japan's tech-savvy consumer base efficiently, reducing distribution costs and supporting above-market brand margin capture through direct consumer engagement strategies.
- Professional Salon Sector Expansion Driving Structured B2B Demand: Japan's expanding urban professional salon network creates structured demand for high-performance commercial hair dryers offering rapid drying, reduced noise, and extended durability. The professional segment's approximately 6.3% CAGR through 2034 represents a commercially attractive high-value B2B channel with above-average product replacement frequency. Growing consumer spending on professional beauty services across Japan's major urban centers is directly supporting the professional salon sector's demand for premium commercial-grade hair dryer products and accessories.
Market Restraints
- High Consumer Price Sensitivity: The entry-level consumer segment remains constrained by price sensitivity, limiting volume growth in lower price tier hair dryer categories. This creates structural growth limits for volume-focused market participants and compresses margins across commodity segments. Intense price competition from low-cost import brands further limits the ability of established manufacturers to maintain pricing power in the entry-level tier, challenging profitability and volume growth targets for value-segment product lines.
- Market Saturation in Established Urban Consumer Segments: Mature urban consumer markets exhibit near-complete penetration of hair dryer ownership, constraining primary demand growth and increasing dependence on replacement cycle and premiumization as the primary volume driver. Extended product durability driven by improved component quality further limits annual replacement-driven sales volume in Japan's most commercially mature urban consumer markets, requiring manufacturers to rely more heavily on technology-driven upgrade motivations rather than first-time purchase demand.
- Consumer Uncertainty About New-Technology Value Proposition: Consumer hesitation in validating the practical benefits of new hair care technologies creates adoption barriers for premium-priced advanced models and slows market diffusion of innovation. Generic consumer skepticism about technology premiums, particularly for AI-powered and smart connectivity features, limits rapid diffusion of high-value product tiers. Brands must invest significantly in consumer education, demonstration experiences, and influencer-led content marketing to overcome skepticism and drive premium tier adoption at the pace required to sustain high-CAGR growth projections.
Market Opportunities
- Expansion of Online Direct-to-Consumer Hair Dryer Brands: The rapidly growing online channel presents a significant opportunity for DTC brands to reach consumers directly, reduce distribution costs, and build brand communities. Premium digital-native brands targeting Japan's tech-savvy consumer base represent a commercially attractive expansion pathway. Investment in platform marketing, live commerce, and influencer-driven digital campaigns enables new entrants to establish brand awareness and consumer loyalty cost-effectively, accelerating market penetration without requiring large-scale physical retail presence.
- Emerging Regional Market Development Outside Kanto: Regions outside Kanto, including Kansai at 19.4%, Central/Chubu at 16.8%, and Kyushu-Okinawa at 10.6%, offer above-average growth potential as retail infrastructure expands and consumer purchasing power in secondary urban centers continues increasing. Targeted regional retail partnerships, localized marketing strategies, and e-commerce channel investment in under-penetrated secondary and tertiary markets represent significant opportunities for market share expansion by both domestic and international brand participants.
- Sustainable and Eco-Friendly Hair Dryer Product Development: Japan's environmentally conscious consumer base is creating demand for energy-efficient, eco-friendly models using sustainable materials and reduced-plastic packaging. Government energy efficiency incentives and expanding circular economy purchasing motivations are further accelerating adoption of eco-friendly product lines across retail channels. Brands that invest in credible sustainability certifications, recyclable product design, and transparent environmental impact reporting can access Japan's growing premium eco-conscious consumer segment and command above-average price points for sustainable innovations.
Market Challenges
- Rapid Technological Change Increasing R&D Investment Requirements: Accelerating technology cycles in hair care appliances require continuous R&D investment to maintain competitive product portfolios and satisfy Japan's demanding technology-forward consumer expectations. Manufacturers face increasing pressure to integrate new features while managing product development costs and maintaining premium margin positioning. Short product lifecycle windows driven by rapid innovation create inventory management challenges and require sophisticated demand forecasting capabilities, adding operational complexity and cost to sustained participation in Japan's premium hair dryer market.
- Intensifying Competition from Domestic and International Brands: Japan's hair dryer market faces increasing competitive intensity as established domestic brands and international premium entrants compete across price and technology tiers simultaneously. Managing brand positioning while sustaining margin structure across a fragmented competitive landscape with multiple well-resourced participants remains a persistent strategic challenge. New market entrants leveraging digital-native DTC strategies and aggressive pricing are further intensifying competitive dynamics, particularly in the mid-premium segment where both domestic and international brands compete most directly.
Emerging Market Trends
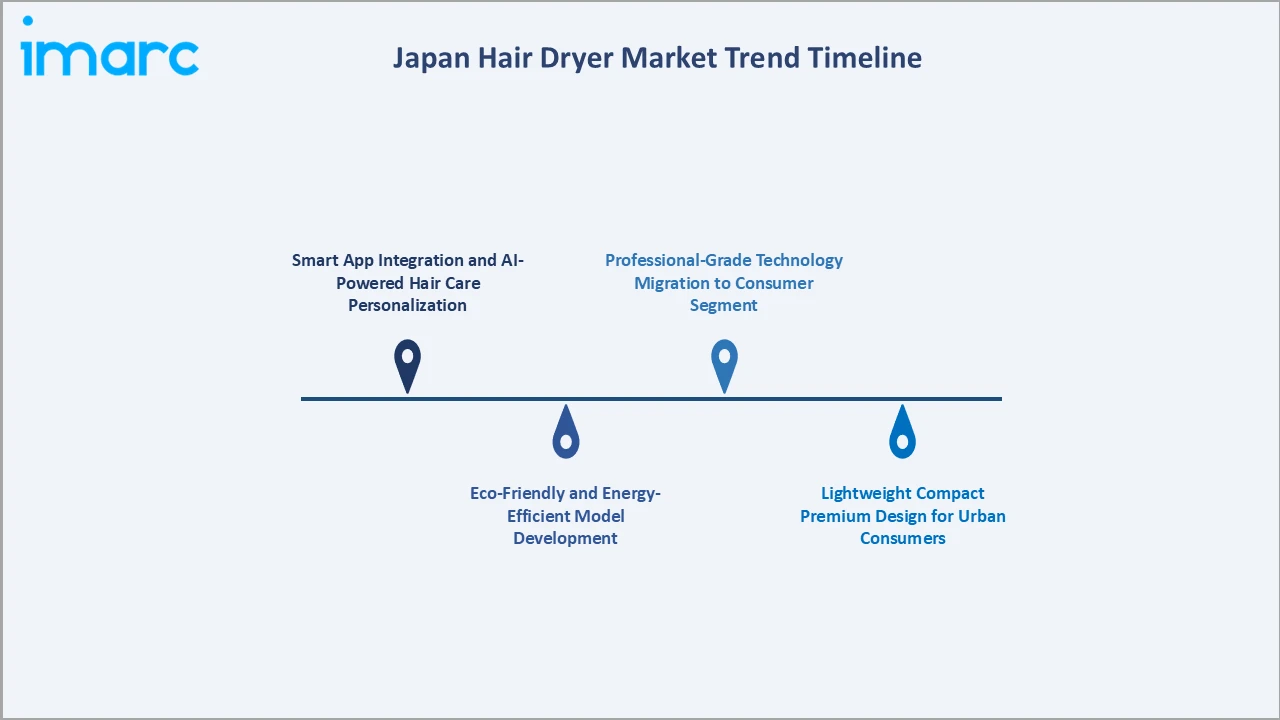
1. Smart App Integration and AI-Powered Hair Care Personalization
Smart hair dryers connecting to mobile apps for personalized drying routines are gaining traction in Japan's technology-forward consumer market. AI temperature control systems that automatically adjust heat output based on real-time hair moisture and thickness measurements are emerging as a key premium product differentiator, minimizing heat damage while optimizing drying efficiency and expanding premium consumer adoption.
2. Eco-Friendly and Energy-Efficient Model Development
Japan's environmentally conscious consumers are driving growing demand for energy-efficient models using sustainable, recycled, or biodegradable materials. Government energy efficiency incentives and Japan's strong circular economy culture are accelerating adoption of eco-friendly hair dryer product lines across both offline specialty retail and online DTC channels.
3. Lightweight Compact Premium Design for Urban Consumers
Japan's urban consumers, particularly in high-density Kanto and Kansai markets, increasingly demand lightweight, compact, and aesthetically premium hair dryers that combine portable convenience with professional-level drying performance and advanced technology specifications.
4. Professional-Grade Technology Migration to Consumer Segment
Technologies originally developed for professional salon use, including nanoe moisture technology and ceramic tourmaline heating components, are migrating to premium consumer product lines. This technology trickle-down effect is expanding the premium tier's addressable market and supporting above-average price point adoption among individual consumers.
Industry Value Chain Analysis
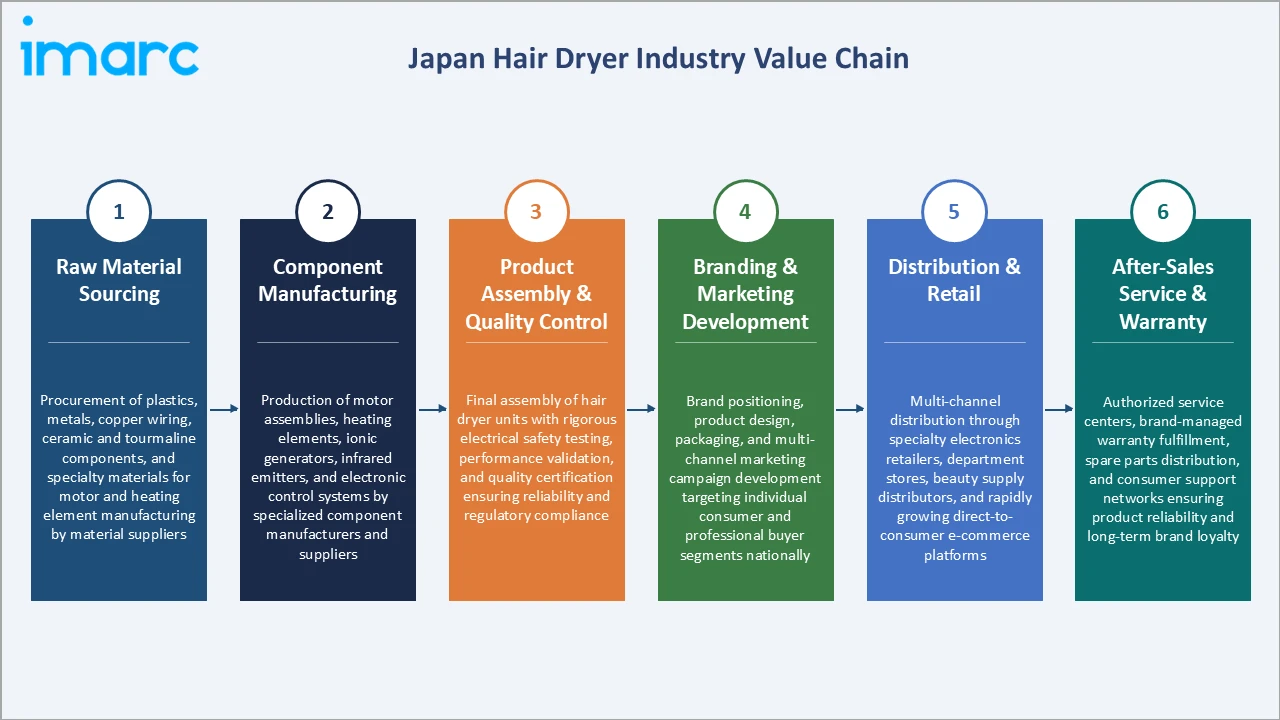
Japan's hair dryer value chain represents one of the most integrated consumer electronics supply chains in Asia-Pacific, combining sophisticated component manufacturing, advanced quality control processes, multi-channel distribution infrastructure, and well-developed after-sales service networks supporting both consumer and professional appliance segments.
| Stage | Description |
|---|---|
| Raw Material Sourcing | Procurement of plastics, metals, copper wiring, ceramic and tourmaline components, and specialty materials for motor and heating element manufacturing by material suppliers |
| Component Manufacturing | Production of motor assemblies, heating elements, ionic generators, infrared emitters, and electronic control systems by specialized component manufacturers and suppliers |
| Product Assembly & Quality Control | Final assembly of hair dryer units with rigorous electrical safety testing, performance validation, and quality certification ensuring reliability and regulatory compliance |
| Branding & Marketing Development | Brand positioning, product design, packaging, and multi-channel marketing campaign development targeting individual consumer and professional buyer segments nationally |
| Distribution & Retail | Multi-channel distribution through specialty electronics retailers, department stores, beauty supply distributors, and rapidly growing direct-to-consumer e-commerce platforms |
| After-Sales Service & Warranty | Authorized service centers, brand-managed warranty fulfillment, spare parts distribution, and consumer support networks ensuring product reliability and long-term brand loyalty |
The product assembly and quality control stage represents Japan's hair dryer value chain's most commercially value-added stage, where manufacturers invest approximately 18–25% of product cost in rigorous testing, safety certification, and performance validation. This investment supports Japan's premium product reputation and sustains consumer confidence in both domestic retail and export markets across the Asia-Pacific region.
Technology Landscape in the Japan Hair Dryer Industry
Ionic and Nanoe Technology
Ionic technology that generates negative ions to neutralize static, reduce frizz, and enhance hair shine is the dominant technology platform across Japan's consumer and professional hair dryer segments. Nanoe moisture-infusion technology, which releases nano-sized water particles to condition hair during drying, represents a premium innovation tier commanding significant consumer price premiums in Japan's advanced personal care market.
AI-Powered Temperature Control and Infrared Heat Technology
AI temperature control systems that automatically adjust heat settings based on hair moisture and thickness measurements are an emerging premium technology tier reshaping the high-value consumer segment. Combined with infrared heat technology that heats hair from the inside rather than the surface, these innovations minimize heat damage while optimizing drying efficiency, driving above-average adoption across Japan's premium segments.
Ceramic and Tourmaline Component Technology
Ceramic and tourmaline-coated heating elements emit far-infrared heat and generate additional ionic activity, reducing static and enhancing shine during the drying process. These materials are widely adopted across mid-premium to premium hair dryer categories in Japan, supported by strong consumer awareness of their hair health benefits through professional salon recommendations and beauty content media channels.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Type | 🔒 | 🔒 | 2025 |
| Application | Individual | 72.8% | 2025 |
| Distribution Channel | Offline | 64.7% | 2025 |
| Region | Kanto Region | 35.8% | 2025 |

By Application
Individual leads at 72.8% (2025). The individual segment encompasses Japan's most commercially diverse hair dryer demand spectrum, from affordable consumer models to premium salon-grade personal care appliances, covering everyday home use, travel, and at-home professional-quality styling across Japan's most commercially mature personal care appliance category.
To access detailed market analysis, Request Sample
Professional at 27.2% grows through Japan's expanding urban salon network, growing demand for high-performance commercial dryers offering rapid throughput drying, reduced operational noise, and extended product lifespan.
By Distribution Channel
Offline leads at 64.7% (2025). The offline channel encompasses Japan's established multi-format physical retail network, including major electronics specialty retailers, department store appliance floors, and beauty supply distributors.
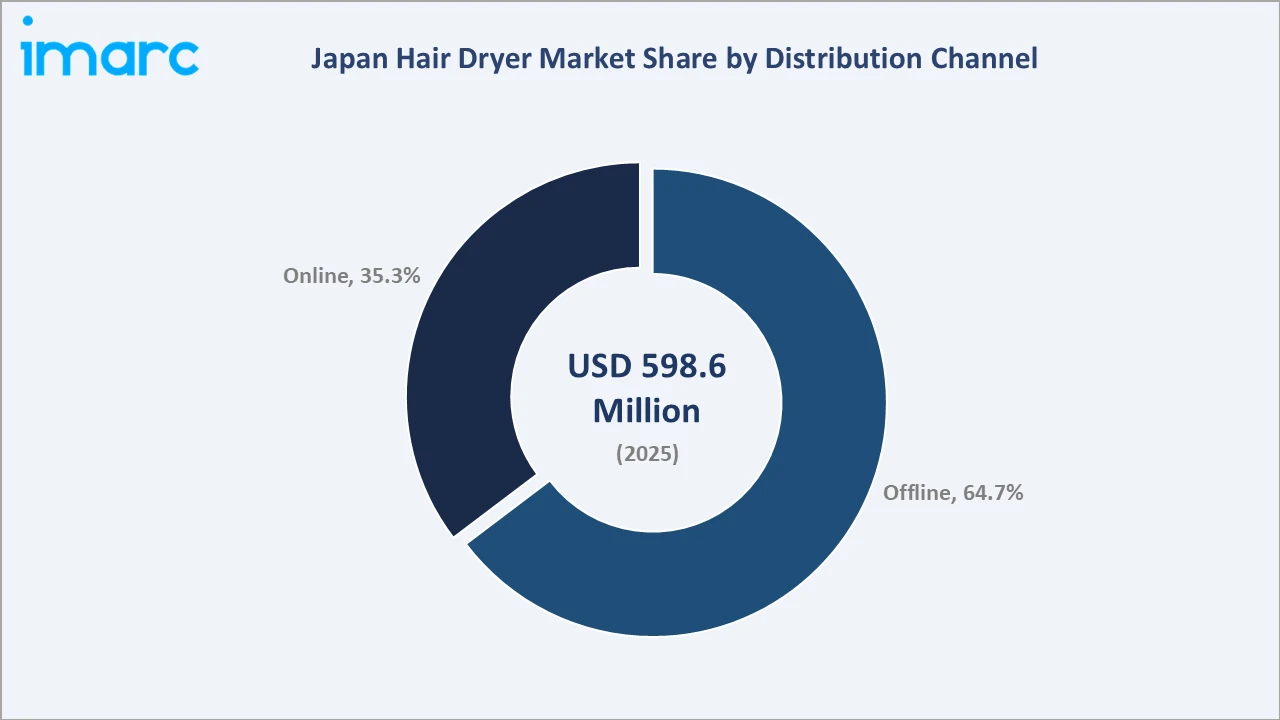
Online at 35.3% is the fastest-growing channel, supported by Japan's advanced e-commerce infrastructure, high smartphone penetration, growing consumer comfort with high-value online appliance purchases, and expanding DTC brand presence across all regional markets.
Regional Market Insights
| Region | Market Share (2025) | Key Characteristics |
|---|---|---|
| Kanto Region | 35.8% | Largest consumer market; highest retail density; dense electronics retail and salon network |
| Kansai/Kinki Region | 19.4% | Strong Osaka-Kyoto consumer base; established beauty culture; premium retail presence |
| Central/Chubu Region | 16.8% | Manufacturing and commercial hub; growing premium consumer spending segment |
| Kyushu-Okinawa Region | 10.6% | Expanding urban retail infrastructure; growing online channel penetration |
| Tohoku Region | 6.8% | Growing e-commerce adoption; expanding consumer spending across urban centers |
| Chugoku Region | 5.2% | Moderate market; specialty retail presence concentrated in Hiroshima area |
| Hokkaido Region | 3.1% | Seasonal consumer pattern; niche premium segment demand in Sapporo |
| Shikoku Region | 2.3% | Smallest regional market; online channel gaining relative importance vs. offline |
Kanto Region leads at 35.8% (2025), driven by Tokyo's position as Japan's largest and most commercially sophisticated consumer market. Kansai/Kinki Region at 19.4% is supported by Osaka's major retail hub status and Kyoto's established beauty culture, driving structured demand across both individual and professional hair dryer segments, with strong offline retail channel.
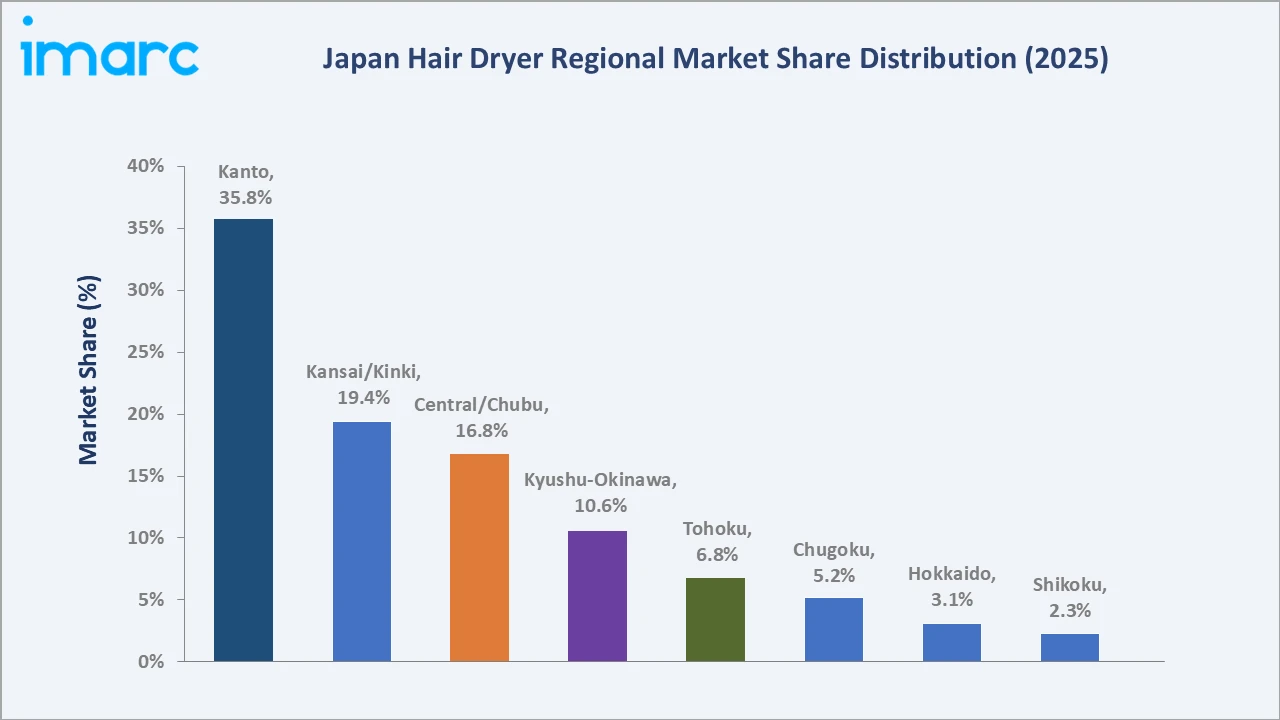
Central/Chubu Region at 16.8% benefits from Nagoya's role as a major commercial center, with a growing premium consumer segment and expanding e-commerce adoption. Kyushu-Okinawa at 10.6%, Tohoku at 6.8%, Chugoku at 5.2%, Hokkaido at 3.1%, and Shikoku at 2.3% collectively represent Japan's secondary markets, where online channel expansion is expected to drive above-average growth relative to mature Kanto through 2034.
Competitive Landscape
The Japan hair dryer market features a moderately concentrated competitive structure, dominated by well-established domestic electronics conglomerates and global premium brands.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| Panasonic Holdings Corporation | NanoCare, Ionity | Market Leader | Deep domestic brand equity; advanced nanoe moisture technology |
| Dyson | Supersonic series | Premium Challenger | Disruptive motor technology; strong premium brand positioning |
| Sharp Corporation | IB-WX903, IB-P802, IB-P602, IB-P80M, IB-P300 | Established Player | Proprietary Plasmacluster ion technology; broad domestic distribution |
| Tescom Co., Ltd. | Tribalance Ion, Moisture Ion, Protect Ion, Negative ion, Standard hair dryer | Niche Specialist | Strong professional salon channel relationships; competitive pricing |
| Maxell Izumi Co., Ltd. | Ionized air hair dryers | Niche Specialist | Compact design expertise; travel and professional niche focus |
Key players include Panasonic Holdings Corporation, Dyson, Sharp Corporation, Tescom Co., Ltd., Maxell Izumi Co., Ltd., and others.
Key Company Profiles
Panasonic Holdings Corporation
Panasonic Holdings Corporation is a globally diversified consumer electronics and industrial solutions manufacturer headquartered in Kadoma, Osaka, Japan. The company is a leading participant in Japan's personal care appliance market, leveraging deep domestic brand equity, extensive retail relationships, and continuous technology innovation to maintain market leadership across consumer and professional hair dryer segments nationally.
- Key Offerings: NanoCare, Ionity
- Key Developments: In August 2026, Panasonic unveiled its premium nanocare Hair Dryer (EH-NB70) at Kuala Lumpur Fashion Week 2026, in collaboration with Malaysian designer Min Luna. The hair dryer incorporates nanoe MOISTURE+ technology to enhance scalp hydration, regulate excess sebum, and help reduce dandruff and itchiness.
- Strategic Focus: Technology leadership through proprietary moisture and ionic innovations; multi-channel distribution optimization across offline and growing online channels; expansion of premium product tier targeting Japan's health-conscious and technology-forward consumer segments. The company continues investing in next-generation AI and IoT product platforms to sustain competitive differentiation.
Sharp Corporation
Sharp Corporation is a Japanese multinational consumer electronics and information technology company with a broad personal care appliance portfolio. The company leverages its proprietary Plasmacluster ion technology as a key competitive differentiator in Japan's premium hair dryer segment, targeting health-conscious consumers seeking scalp and hair conditioning benefits alongside drying performance.
- Key Offerings: IB-WX903, IB-P802, IB-P602, IB-P80M, IB-P300
- Strategic Focus: Proprietary technology differentiation through the Plasmacluster ion platform; domestic retail channel strength leveraging established relationships with major electronics retailers; targeting health-conscious consumer segments with scalp and hair wellness benefit messaging. Sharp's strategic focus includes extending Plasmacluster technology benefits into new product form factors and price tiers to broaden its addressable market beyond the premium segment, while investing in digital marketing to reach younger Japan consumer demographics.
Market Concentration Analysis
Japan's hair dryer market exhibits a moderately concentrated competitive structure, where a small number of established manufacturers and premium brand entrants collectively command the majority of market revenue. The concentration pattern reflects the commercial advantages of brand equity, technology differentiation, and established multi-channel retail relationships that sustain competitive barriers in Japan's mature personal care appliance market against new entrant disruption.
Competitive intensity is shaped by the coexistence of domestic manufacturers leveraging deep retail relationships and technology heritage alongside international premium brands targeting Japan's aspirational and technology-forward consumer segments. Market structure is evolving toward greater premiumization and technology differentiation as the basis for competitive positioning, rather than price-led volume competition, creating a structurally favorable revenue environment for high-value segment participants through 2034.
Investment & Growth Opportunities
Highest Growth Segments
Individual application segment (~7.2% CAGR through premium at-home care demand), online distribution channel (~9.1% CAGR through e-commerce expansion), and professional salon segment (~6.3% CAGR through urban salon network growth) represent Japan's highest-CAGR investment opportunities across 2026–2034.
Emerging Investment Opportunities
Japan's rapidly growing online DTC hair dryer market, growing at approximately 9.1% CAGR, represents the market's highest-growth distribution investment opportunity. DTC e-commerce brand platforms require authentication, product curation, and digital marketing capability above primary offline retail channel investment, but deliver above-average consumer LTV, brand loyalty, and direct pricing power that traditional offline distribution channels do not offer to emerging premium brand participants.
Investment Themes
- Online DTC channel and platform investment in Japan's fastest-growing hair dryer distribution segment, creating above-offline margin capture and direct brand equity through Japan's advanced digital commerce infrastructure and high mobile commerce adoption.
- Premium AI-powered and smart connectivity hair dryer product development investment targeting Japan's technology-forward consumer segment, establishing sustainable competitive differentiation that commodity competitors cannot replicate rapidly.
Future Market Outlook (2026-2034)
Japan's hair dryer market is expected to grow to USD 640.0 Million in 2026 and is projected to reach USD 1,093.1 Million by 2034. The market's growth trajectory is supported by structural drivers including Japan's aging population-driven premium health and beauty spending, continued technology innovation by domestic and international manufacturers, and accelerating transition toward premium, technologically advanced personal care appliances.
Technology disruptions including AI-powered hair health analysis, IoT-connected styling ecosystems, and sustainable eco-material product development will reshape competitive positioning through 2034. The online channel's expansion at approximately 9.1% CAGR will progressively redistribute distribution economics, favoring digitally-capable brands with strong DTC capabilities and data-driven consumer engagement strategies.
Research Methodology
Primary Research
Primary research involves structured interviews with industry stakeholders including hair dryer manufacturers, retail channel partners, professional salon operators, and distribution industry participants across Japan. These qualitative insights validate quantitative market estimates and capture emerging competitive and consumer trends not fully reflected in secondary data sources or published industry statistics.
Secondary Research
Secondary research encompasses analysis of publicly available industry reports, company filings, government trade statistics, and reputable market research publications. Japan's Ministry of Economy, Trade and Industry (METI) data, Japan Electronics and Information Technology Industries Association (JEITA) statistics, and major retail audit data sources inform baseline market sizing and segment distribution estimates.
Market Estimation and Forecasting
Market estimation combines bottom-up analysis of segment-level demand drivers with top-down macroeconomic trend integration. Forecasting models incorporate Japan-specific consumer spending growth trajectories, technology adoption rates, distribution channel evolution patterns, and competitive intensity scenarios to produce the 6.92% CAGR projection across the 2026–2034 forecast period.
Japan Hair Dryer Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Corded, Cordless |
| Applications Covered | Individual, Professional |
| Distribution Channels Covered | Online, Offline |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Panasonic Holdings Corporation, Dyson, Sharp Corporation, Tescom Co., Ltd., Maxell Izumi Co., Ltd., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan hair dryer market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan hair dryer market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan hair dryer industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Hair Dryer Market Report
The Japan hair dryer market reached USD 598.6 Million in 2025 and is expected to grow to USD 640.0 Million in 2026, reflecting a CAGR of 6.92%.
The Japan hair dryer market is projected to reach USD 1,093.1 Million by 2034, growing at a CAGR of 6.92% during the 2026-2034 forecast period.
The Japan hair dryer market is expected to grow at a CAGR of 6.92% during 2026-2034, driven by premium consumer demand, e-commerce expansion, and technology innovation.
The Individual segment leads with 72.8% market share in 2025, driven by Japan's high consumer grooming expenditure and growing at-home salon care trend.
Offline channels dominate at 64.7% in 2025, though Online is the fastest-growing channel at approximately 9.1% CAGR, supported by Japan's advanced e-commerce infrastructure.
Kanto Region leads with 35.8% market share in 2025, reflecting Tokyo's dominance as Japan's primary consumer electronics retail and professional beauty services hub.
Key drivers include premium consumer demand for ionic and AI-powered dryers, the at-home salon care trend, e-commerce expansion, and professional salon sector growth.
Key companies include Panasonic Holdings Corporation, Dyson, Sharp Corporation, Tescom Co., Ltd., Maxell Izumi Co., Ltd., and others.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade