Japan Hydrogen Energy Storage Market Size, Share, Trends and Forecast by Storage Form, Technology, Application, End User, and Region, 2026-2034
Japan Hydrogen Energy Storage Market Size, Share, Trends & Forecast (2026-2034)
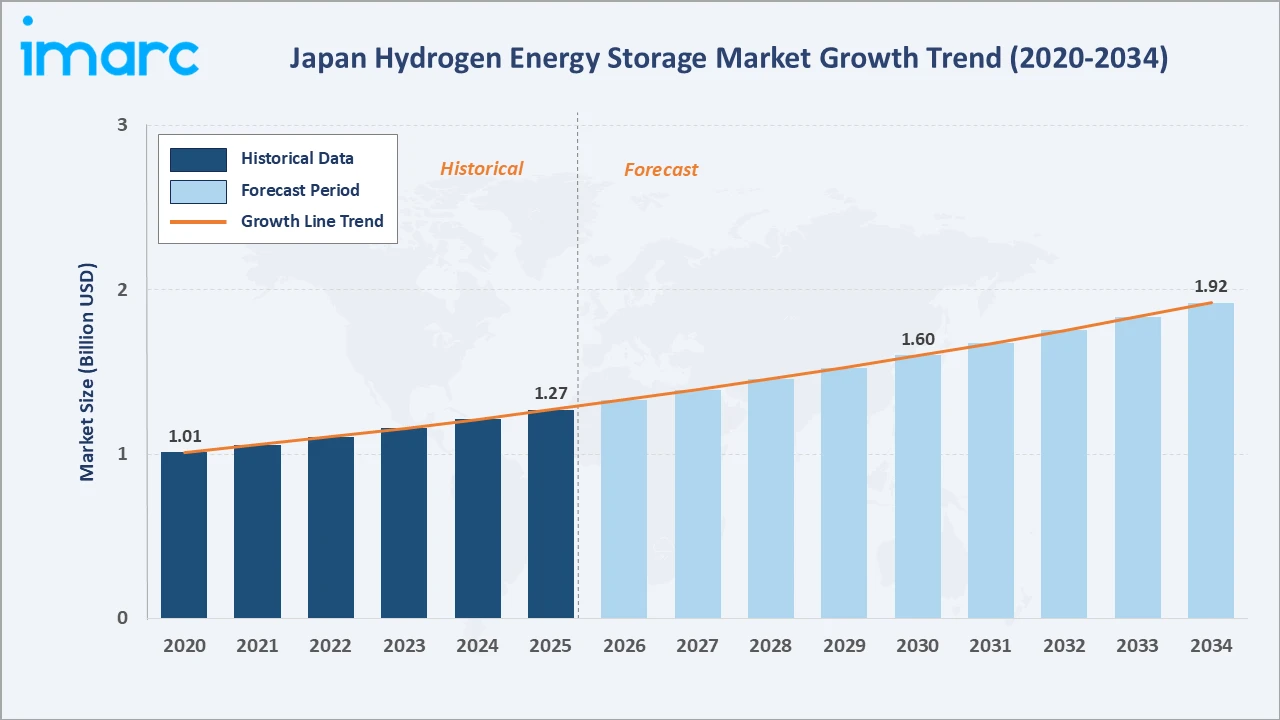
The Japan hydrogen energy storage market grew from USD 1.27 Billion in 2025 to USD 1.33 Billion in 2026 and is projected to reach USD 1.92 Billion by 2034, growing at a CAGR of 4.66% during 2026-2034. Japan's revised Basic Hydrogen Strategy targets 3 million tons of annual hydrogen consumption by 2030 and about 20 million tons per year by 2050, directly stimulating storage infrastructure investment across compression, liquefaction, and material-based technology segments. Gas leads storage form with a 65.0% share in 2025. Compression technology commands 60.0% of the technology segment. The Kanto region holds the largest regional share at 30.0% in 2025.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 1.27 Billion |
|
Market Size (2026) |
USD 1.33 Billion |
|
Forecast Market Size (2034) |
USD 1.92 Billion |
|
CAGR (2026-2034) |
4.66% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Storage Form |
Gas (65.0%, 2025) |
|
Dominant Technology |
Compression (60.0%, 2025) |
|
Leading Region |
Kanto Region (30.0%, 2025) |
The Japan hydrogen energy storage market grew from USD 1.01 Billion in 2020 to USD 1.27 Billion in 2025, and further to USD 1.33 Billion in 2026, reflecting sustained policy investment and growing industrial hydrogen adoption. The market is projected to reach USD 1.60 Billion by 2030 before reaching USD 1.92 Billion by 2034.
To get more information on this market, Request Sample
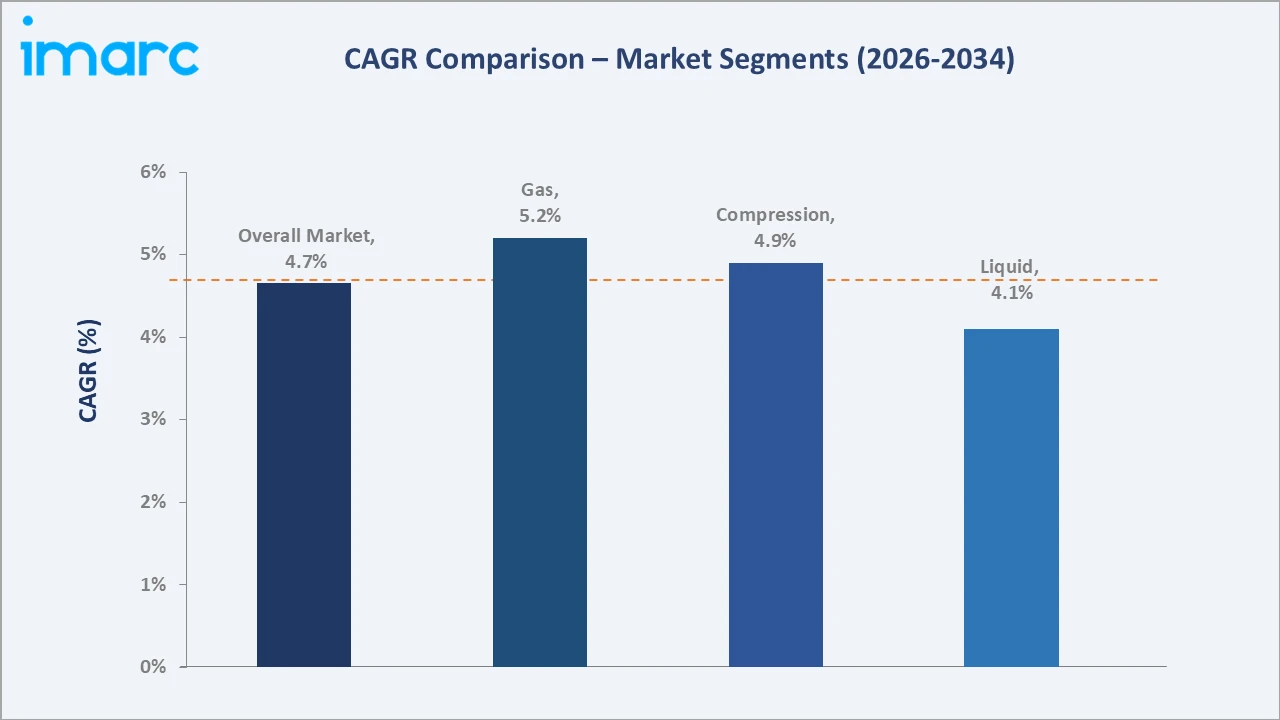
Gas storage form is projected to grow at approximately 5.2% CAGR, driven by fuel cell vehicle expansion and industrial applications. Compression technology leads at 4.9% CAGR, reflecting mature infrastructure and broad commercial applicability.
Executive Summary
The Japan hydrogen energy storage market is advancing steadily, supported by the government's long-term hydrogen energy roadmap, growing industrial and mobility decarbonization requirements, and expanding domestic storage infrastructure investment. The market has grown consistently since 2020, driven by policy commitments, public-private partnerships, and technology scale-up across compression, liquefaction, and emerging material-based storage platforms.
Gas leads with 65.0% of the storage form segment, reflecting the dominance of high-pressure gaseous hydrogen in vehicle refueling and industrial supply applications. Compression technology holds 60.0% of the technology segment, supported by proven high-pressure infrastructure. The Kanto region commands 30.0% of the market, anchored by Tokyo's industrial hydrogen demand and the highest concentration of fuel cell vehicle adoption in Japan.
Key Market Insights
|
Insight |
Data |
|
Dominant Storage Form |
Gas – 65.0% share (2025) |
|
Dominant Technology |
Compression – 60.0% share (2025) |
|
Leading Region |
Kanto Region – 30.0% (2025) |
|
Key Market Opportunity |
Japan's 3 million ton annual hydrogen target by 2030 and scaling fuel cell vehicle adoption are creating sustained long-term demand for advanced storage infrastructure across all segments. |
Key Analytical Observations Supporting the Above Data:
- Gas at 65.0%: Gaseous hydrogen at high pressure dominates because it is the most commercially mature and cost-effective format for vehicle refueling and industrial gas supply, with an established supply chain and minimal energy conversion loss versus liquefaction.
- Compression at 60.0%: Compression technology leads because it uses proven mechanical compression equipment, offers lower capital cost relative to liquefaction, and applies broadly across transportation and industrial uses, making it the preferred choice for Japan's hydrogen refueling network.
- Kanto Region at 30.0%: The Kanto region leads as it encompasses the Tokyo metropolitan area, Japan's largest industrial hub with the highest concentration of hydrogen refueling stations, fuel cell vehicle registrations, and stationary fuel cell systems among all Japanese regions.
Japan Hydrogen Energy Storage Market Overview
The Japan hydrogen energy storage market encompasses all systems, equipment, and infrastructure used to store hydrogen gas in compressed, liquid, or material-based forms for subsequent distribution to industrial, mobility, and energy applications. Core participants include hydrogen producers, compression and liquefaction equipment manufacturers, pressure vessel producers, cryogenic engineering firms, hydrogen refueling station developers, and industrial gas distributors.
The market serves fuel cell vehicle operators, stationary power facilities, steel and chemical manufacturers, and large-scale energy storage projects supporting renewable energy integration. Japan's hydrogen ecosystem benefits from strong government policy alignment, active public-private investment partnerships, and a mature industrial base capable of delivering advanced hydrogen storage components and integrated system solutions.
Market Dynamics
To evaluate market opportunities, Request Sample
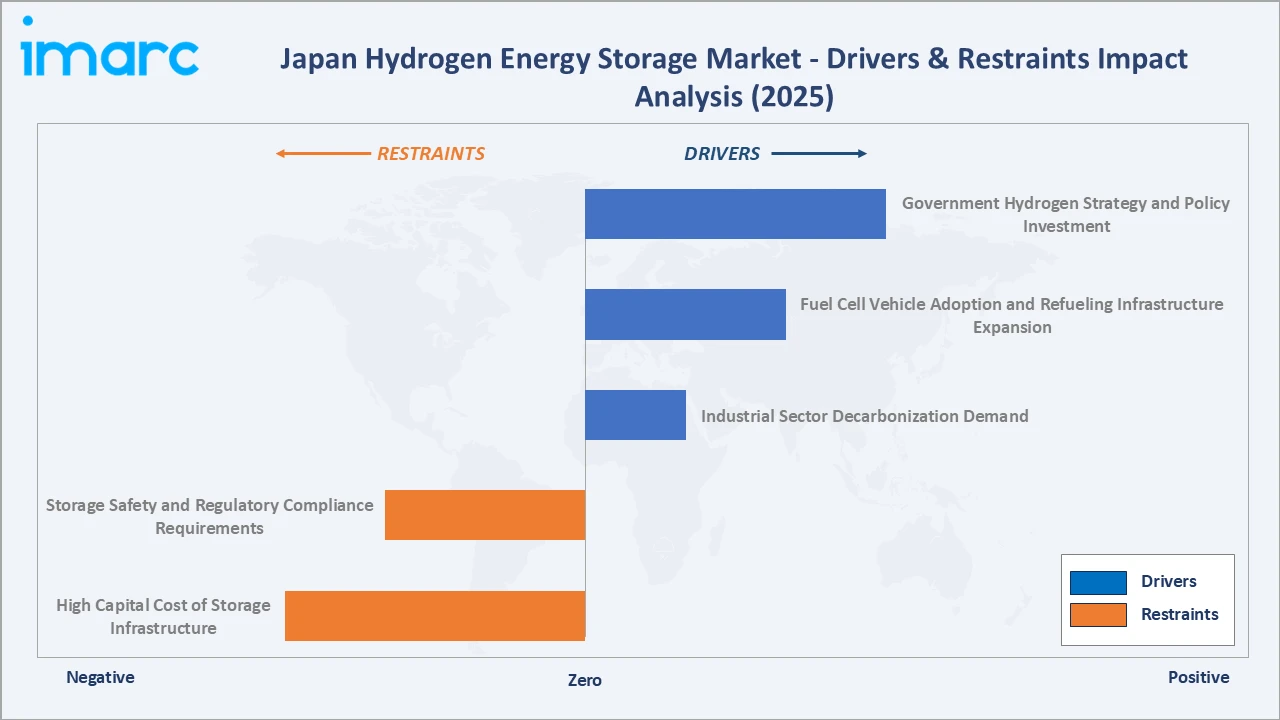
Market Drivers
- Government Hydrogen Strategy and Policy Investment: Japan's revised Basic Hydrogen Strategy sets a target of 3 million tons of annual hydrogen consumption by 2030 and 20 million tons by 2050, with public investment commitments to develop the hydrogen supply chain, including storage, transport, and distribution infrastructure.
- Fuel Cell Vehicle Adoption and Refueling Infrastructure Expansion: Japan's fuel cell vehicle fleet is expanding across passenger and commercial vehicle segments, directly driving demand for high-pressure compressed hydrogen storage at refueling stations. The government's target of 1,000 hydrogen refueling stations by 2030 underpins sustained storage capacity expansion across urban and highway corridors nationwide.
- Industrial Sector Decarbonization Demand: Japan's steel, chemical, and petrochemical industries are pursuing hydrogen co-firing and feedstock substitution to meet national carbon neutrality targets by 2050. These large-volume industrial users require reliable, large-scale hydrogen storage infrastructure to integrate hydrogen supply reliably into continuous manufacturing processes.
Market Restraints
- High Capital Cost of Storage Infrastructure: Hydrogen storage systems, particularly high-pressure compression and cryogenic liquefaction installations, require significant upfront capital investment that increases project development costs and extends payback periods, constraining the pace of expansion for smaller commercial operators.
- Storage Safety and Regulatory Compliance Requirements: Hydrogen's physical properties require stringent safety standards for storage vessel design, installation, and operation, adding complexity and cost compared to conventional fuel alternatives and creating technical and regulatory barriers that can slow deployment of new storage installations.
Market Opportunities
- International Hydrogen Import Supply Chain Development: Japan is pursuing international hydrogen supply agreements with Australia, the Middle East, and Southeast Asia to supplement domestic production. This creates significant demand for large-scale liquid hydrogen terminal and cryogenic storage infrastructure at major port facilities.
- Advanced Material-Based Storage Commercialization: Metal hydrides and advanced sorbent material storage technologies are advancing toward commercial viability, offering higher volumetric storage density and improved safety profiles, creating new market segments within the broader hydrogen storage landscape that command premium pricing.
Market Challenges
- Hydrogen Storage Efficiency and Energy Loss Management: Compression and liquefaction processes consume significant energy relative to stored hydrogen content, reducing overall efficiency when storage and release cycles are included. Managing these efficiency losses is a persistent technical challenge for system developers and operators.
- Limited Standardization of Storage Equipment: The hydrogen storage market lacks fully harmonized international standards for vessel design, testing, and certification, creating challenges for manufacturers serving multiple markets and increasing compliance costs for operators deploying diverse storage systems.
Emerging Market Trends
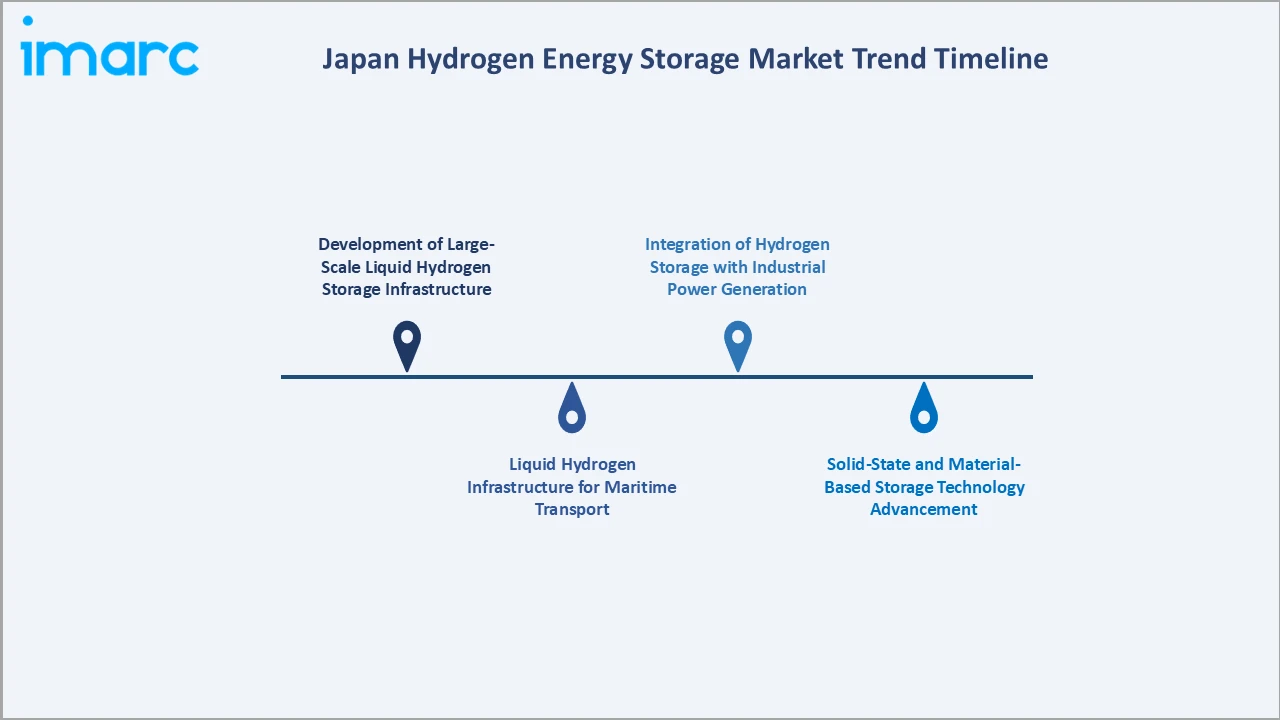
1. Development of Large-Scale Liquid Hydrogen Storage Infrastructure
Japan is witnessing increased investment in large-scale hydrogen liquefaction facilities to strengthen its hydrogen storage and supply chain capabilities. In October 2026, Kawasaki Heavy Industries began constructing a 50-tonne-per-day hydrogen liquefaction facility in Kawasaki, Japan, under NEDO’s Green Innovation Fund program. Scheduled for completion by 2028, the plant will support large-scale liquid hydrogen supply chain demonstrations from 2030.
2. Liquid Hydrogen Infrastructure for Maritime Transport
Japan is investing in large-scale liquid hydrogen terminal, storage, and maritime transport infrastructure to support international hydrogen imports. Demonstration projects led by industry consortia are validating cryogenic liquid hydrogen handling at commercial scale, establishing standards and capabilities for future commercial international supply chain operations.
3. Integration of Hydrogen Storage with Industrial Power Generation
Japan is increasingly exploring hydrogen-based energy systems to support industrial electricity needs and improve energy sustainability. In July 2026, TANAKA began operating a 500-kW pure hydrogen fuel cell facility at its Shonan site in Japan. The facility will test hydrogen-based power generation in real industrial conditions and could supply around 34% of the electricity consumed by its nearby manufacturing plant, supporting the practical adoption of hydrogen energy in industry.
4. Solid-State and Material-Based Storage Technology Advancement
Research in metal hydride and advanced porous material hydrogen storage is accelerating across Japanese research institutions. These technologies offer higher volumetric storage density at reduced pressure, which could lower safety requirements and infrastructure costs for storage in built environments and compact mobility applications.
Industry Value Chain Analysis
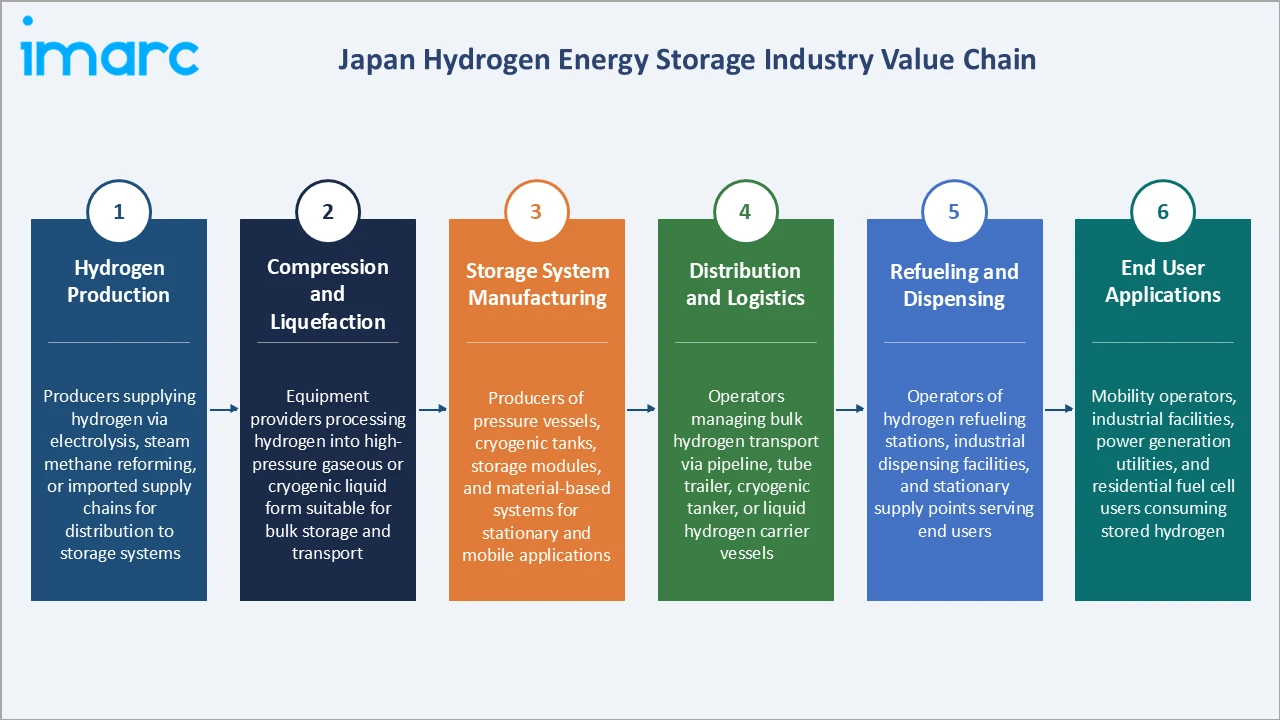
The Japan hydrogen energy storage value chain extends from hydrogen production through storage system manufacturing and end-user delivery, with value concentration at the storage system engineering and integration stage where technical expertise and safety certification create durable competitive advantages.
|
Stage |
Key Participants |
|
Hydrogen Production |
Producers supplying hydrogen via electrolysis, steam methane reforming, or imported supply chains for distribution to storage systems. |
|
Compression and Liquefaction |
Equipment providers processing hydrogen into high-pressure gaseous or cryogenic liquid form suitable for bulk storage and transport. |
|
Storage System Manufacturing |
Producers of pressure vessels, cryogenic tanks, storage modules, and material-based systems for stationary and mobile applications. |
|
Distribution and Logistics |
Operators managing bulk hydrogen transport via pipeline, tube trailer, cryogenic tanker, or liquid hydrogen carrier vessels. |
|
Refueling and Dispensing |
Operators of hydrogen refueling stations, industrial dispensing facilities, and stationary supply points serving end users. |
|
End User Applications |
Mobility operators, industrial facilities, power generation utilities, and residential fuel cell users consuming stored hydrogen. |
Storage system manufacturing holds the highest value-added position in the hydrogen storage value chain, as vessel design, material science expertise, and safety testing capabilities create technical barriers. Distribution and logistics are emerging as a high-investment segment as Japan scales its hydrogen import and domestic distribution infrastructure through 2034.
Technology Landscape in the Japan Hydrogen Energy Storage Industry
High-Pressure Compression Technology
High-pressure compression remains Japan's primary hydrogen storage technology, with vessels operating at 350 bar for buses and commercial vehicles and 700 bar for passenger cars. Advanced carbon fiber reinforced polymer (CFRP) composite vessels deliver high strength-to-weight ratios, enabling vehicle-grade storage with minimal mass penalty. Compression efficiency improvements are progressively reducing energy consumption per unit of stored hydrogen.
Cryogenic Liquid Hydrogen Technology
Liquid hydrogen storage at –253°C enables high volumetric energy density suitable for large-scale stationary storage and maritime transport. Japan is developing cryogenic storage terminals for hydrogen import facilities, with advanced insulation technology reducing boil-off losses. Liquid hydrogen is the primary format for international hydrogen trade given its superior volumetric energy density compared to compressed gas.
Material-Based Hydrogen Storage
Metal hydride and advanced sorbent material research is accelerating in Japan, targeting higher volumetric storage density at reduced pressure. These systems are in advanced R&D with pilot demonstrations underway, offering potential for compact, ambient-pressure storage in residential fuel cells and energy-constrained applications where high-pressure systems are less practical.
Underground and Large-Scale Stationary Storage
Underground hydrogen storage in geological formations and large-scale tank farms is being evaluated for seasonal energy storage and emergency buffer applications. These concepts are at the feasibility stage, with technical challenges related to hydrogen purity, geological suitability, and recovery efficiency under active investigation by research consortia.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Storage Form | Gas | 65.0% | 2025 |
| Technology | Compression | 60.0% | 2025 |
| Application | 🔒 | 🔒 | 2025 |
| End User | 🔒 | 🔒 | 2025 |
| Region | Kanto Region | 30.0% | 2025 |

By Storage Form
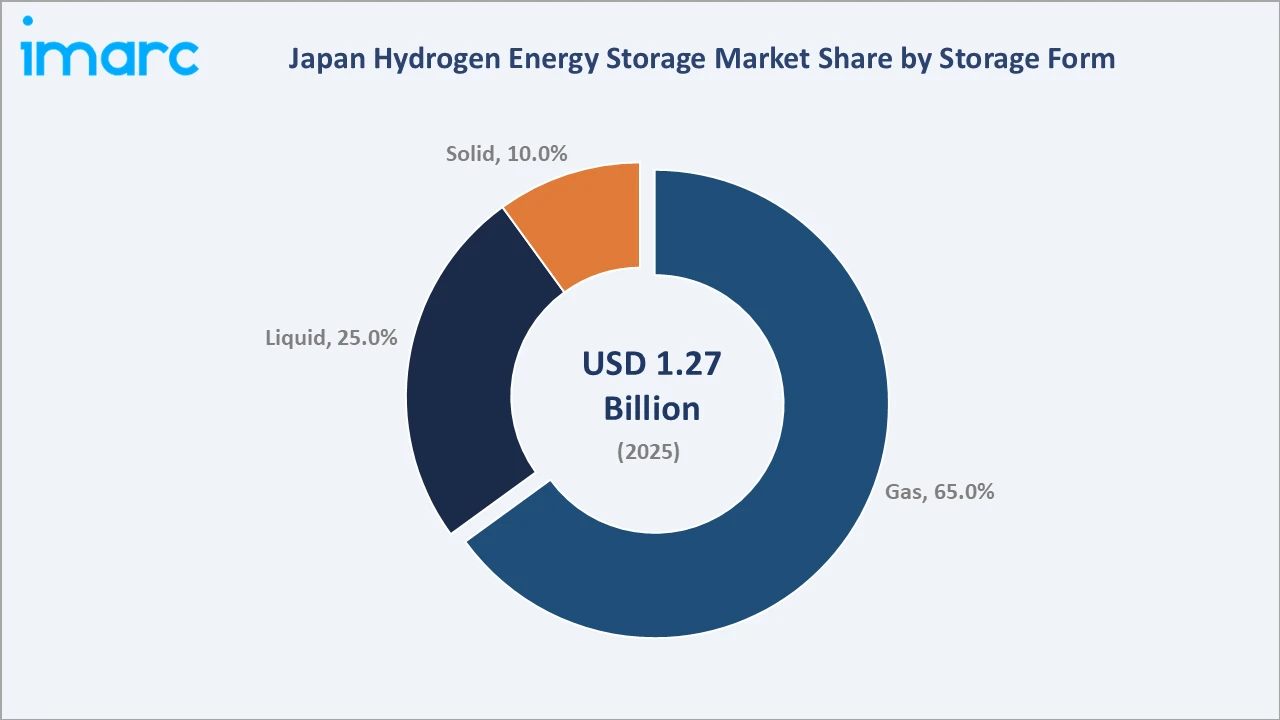
Gas leads with a 65.0% share in 2025, reflecting its dominant position in vehicle fueling and industrial supply through established high-pressure compressed gas infrastructure. Liquid at 25.0%, is growing as large-scale industrial and maritime transport applications demand higher volumetric density.
To access detailed market analysis, Request Sample
Solid at 10.0% represents emerging material-based technologies at the pilot and early commercialization stage with significant growth potential through 2034.
By Technology
Compression technology commands 60.0% of the Japan hydrogen energy storage market in 2025, underpinned by widespread deployment across fuel cell vehicle refueling stations, industrial gas supply, and distributed stationary power applications.
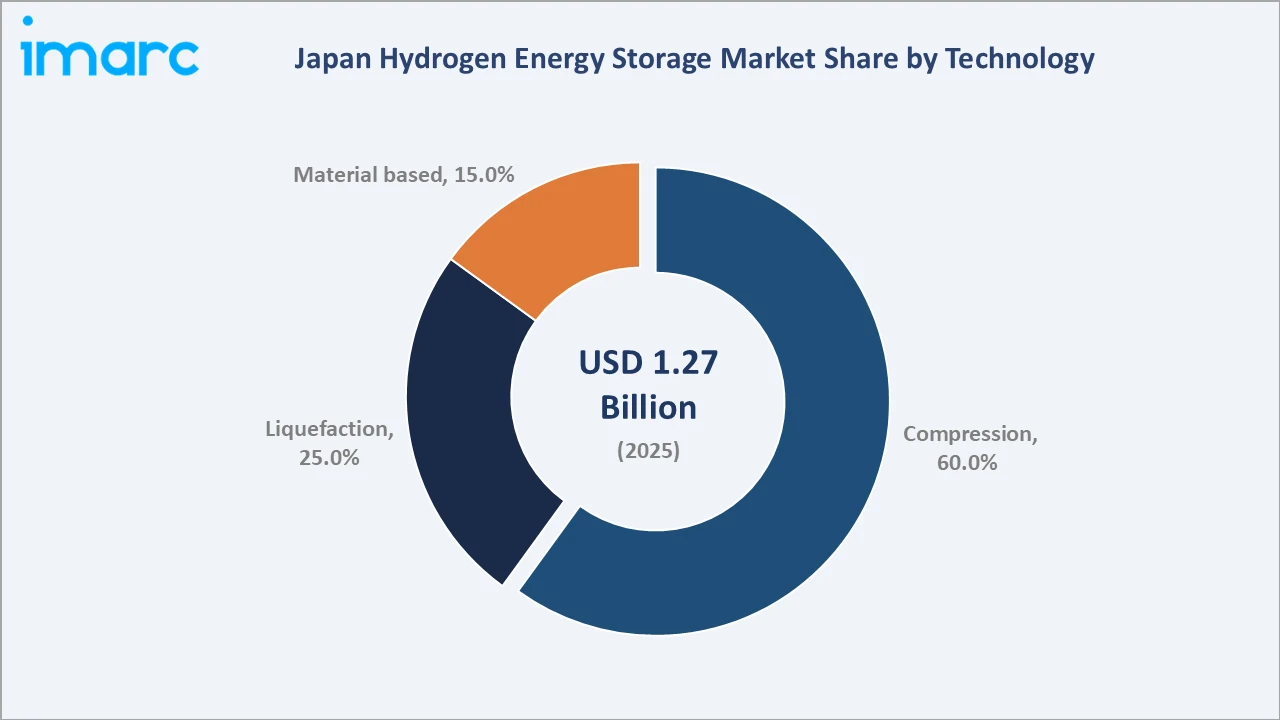
Liquefaction technology at 25.0% serves large-scale industrial users, maritime applications, and international supply chain terminals. Material-based technology at 15.0% reflects increasing R&D investment and early-stage commercialization for compact, high-density storage applications.
Regional Market Insights
|
Region |
Share (2025) |
Key Drivers & Characteristics |
|
Kanto Region |
30.0% |
High concentration of industrial users, fuel cell vehicle adoption, and hydrogen station density across the Tokyo metropolitan area, generating the largest hydrogen storage demand in Japan. |
|
Kansai/Kinki Region |
20.0% |
Strong industrial manufacturing and chemicals base driving hydrogen demand, alongside growing fuel cell vehicle infrastructure across the Osaka-Kobe industrial corridor. |
|
Central/Chubu Region |
17.0% |
Automotive manufacturing concentration creates hydrogen demand for industrial and mobility applications, with expanding storage infrastructure tied to regional decarbonization programs. |
|
Kyushu-Okinawa Region |
10.0% |
Emerging strategic hydrogen import gateway with port infrastructure development and growing industrial hydrogen demand from steel and chemicals sector operations. |
|
Tohoku Region |
7.0% |
Growing hydrogen adoption aligned with regional renewable energy development and energy transition initiatives integrating hydrogen storage into grid balancing applications. |
|
Chugoku Region |
6.0% |
Industrial manufacturing base generating consistent hydrogen demand, with regional infrastructure development underway to expand storage and distribution capacity. |
|
Hokkaido Region |
6.0% |
Abundant renewable energy resources supporting power-to-hydrogen projects and developing hydrogen storage infrastructure for regional grid balancing and export applications. |
|
Shikoku Region |
4.0% |
Smaller industrial hydrogen base with growing interest in hydrogen energy as part of regional energy diversification and clean energy transition strategies. |
The Kanto region commands 30.0% as Japan's industrial and commercial epicenter, with the highest density of hydrogen infrastructure across fuel cell vehicles, stationary systems, and industrial supply chains. The Kansai/Kinki region at 20.0% draws strength from its manufacturing and chemical industry hydrogen demand across the Osaka-Kobe industrial belt.
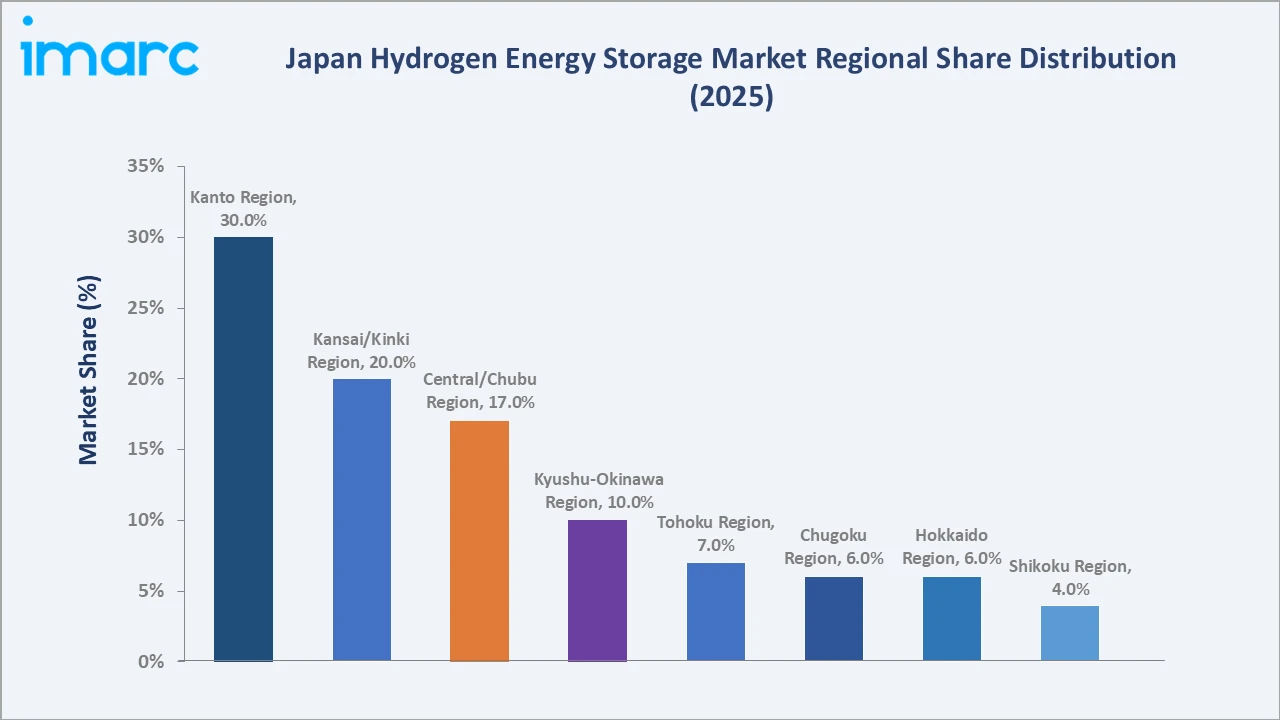
Central/Chubu region, at 17.0%, is driven by automotive manufacturing and its increasing adoption of hydrogen in production processes. Kyushu-Okinawa region, at 10.0%, is establishing itself rapidly as a hydrogen import gateway. Tohoku region at 7.0%, the Chugoku region at 6.0%, the Hokkaido region at 6.0%, and the Shikoku region at 4.0% are developing hydrogen infrastructure aligned with regional renewable energy and industrial decarbonization priorities through 2034.
Competitive Landscape
The Japan hydrogen energy storage market is led by established industrial conglomerates with integrated hydrogen capabilities spanning production, storage technology manufacturing, and distribution infrastructure.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| TOYOTA MOTOR CORPORATION | Tri-Gen System | Market Leader | Toyota Motor Corporation plays a central, multifaceted role in Japan's hydrogen energy infrastructure and storage ecosystem, bridging vehicle technology, industrial manufacturing, and large-scale supply chains. |
| Kawasaki Heavy Industries, Ltd. | Hydrogen Liquefaction System | Market Leader | Kawasaki Heavy Industries, Ltd. is a primary technology leader in Japan's hydrogen energy strategy, acting as the key builder of the country's cryogenic liquefaction, large-scale storage, and maritime transport infrastructure. |
| Iwatani Corporation | Iwatani Advanced Hydrogen Technology Center | Established Player | Iwatani Corporation acts as the foundational supplier and key infrastructure leader in Japan's hydrogen economy. |
| MITSUBISHI HEAVY INDUSTRIES, LTD. | Advanced Clean Energy Storage hub | Innovator | Mitsubishi Heavy Industries, Ltd. plays a central role in Japan's hydrogen economy and energy storage infrastructure by developing end-to-end capabilities spanning production, storage, transport, and power-generation utilization. |
| The Japan Steel Works, LTD. | Metal Hydride Tanks | Challenger | The Japan Steel Works, LTD. plays a major role in Japan's hydrogen energy storage and infrastructure sector by manufacturing high-pressure vessels, metal hydride storage systems, and specialized alloy materials. |
A diverse set of automotive, industrial gas, power generation, and engineering companies compete across different value chain segments, reflecting the cross-sector nature of hydrogen energy applications in Japan.
Key Company Profiles
TOYOTA MOTOR CORPORATION
TOYOTA MOTOR CORPORATION is a diversified Japanese automotive and technology conglomerate with extensive involvement in hydrogen energy across mobility fuel cell systems, stationary power, and hydrogen supply chain development. The company operates a broad hydrogen ecosystem serving both private and commercial segments with advanced hydrogen storage and fuel cell solutions.
- Key Offerings: Tri-Gen System.
- Strategic Focus: Expanding hydrogen adoption through fuel cell vehicle development, hydrogen engine technology, and supply chain partnerships targeting commercial vehicle fleet decarbonization and advancing storage density.
Kawasaki Heavy Industries, Ltd.
Kawasaki Heavy Industries, Ltd. is a diversified Japanese industrial conglomerate with a foundational role in Japan's liquid hydrogen supply chain, including marine transport and industrial storage. The company serves large-scale industrial and energy infrastructure customers with integrated hydrogen production, liquefaction, and storage solutions.
- Key Offerings: Hydrogen Liquefaction System.
- Strategic Focus: Developing integrated liquid hydrogen infrastructure spanning production, liquefaction, maritime transport, and onshore storage, targeting large-scale industrial hydrogen supply chain development across the Asia-Pacific region.
Market Concentration Analysis
The Japan hydrogen energy storage market reflects a concentrated competitive structure at the industrial gas and storage system manufacturing level, where large integrated players with established technology, safety certifications, and infrastructure assets hold significant advantages over smaller or newer market entrants. Market leadership is reinforced by long-term supply agreements, specialized engineering capabilities, and high capital and regulatory barriers associated with hydrogen storage infrastructure deployment.
The broader hydrogen storage ecosystem, including material-based storage technology developers and regional hydrogen refueling operators, is more fragmented, with numerous smaller participants serving specialized applications or specific geographic markets. This secondary layer of market participants is expected to consolidate progressively as hydrogen demand scales and the economic case for larger operations strengthens through 2034.
Investment & Growth Opportunities
Fastest Growing Segments
Material-based storage at 15.0% in 2025 represents the highest-potential segment for incremental share gain, driven by government R&D funding and private investment.
Investment Themes
- Large-Scale Liquid Hydrogen Storage Infrastructure: Japan's hydrogen import strategy requires significant investment in port-side cryogenic terminals and large-volume liquid hydrogen storage facilities. Public-private partnerships targeting import terminal development create long-duration infrastructure investment opportunities with stable revenue supported by government hydrogen supply program commitments.
- Next-Generation Storage Technology Commercialization: Increasing public R&D funding for advanced material-based and high-density hydrogen storage technologies creates early-stage investment opportunities in material science, vessel engineering, and integrated storage system development targeting compact mobility and stationary applications.
Future Market Outlook (2026-2034)
The Japan hydrogen energy storage market grew from USD 1.27 Billion in 2025 to USD 1.33 Billion in 2026 and is projected to reach USD 1.92 Billion by 2034, exhibiting a CAGR of 4.66% during 2026-2034. The market is expected to reach approximately USD 1.60 Billion by 2030 as national hydrogen infrastructure programs reach meaningful scale and fuel cell vehicle deployment generates broad-based hydrogen storage demand across multiple Japanese regions.
Three structural forces will define Japan's hydrogen energy storage market through 2034. First, sustained government policy investment will provide a demand foundation across compression, liquefaction, and material-based segments. Second, Japan's international hydrogen import strategy will drive significant cryogenic storage infrastructure investment at port and industrial facilities. Third, progressive maturation of material-based storage will create new higher-density storage segments complementing compressed gas and liquid hydrogen infrastructure, sustaining the market's growth trajectory through 2034.
Research Methodology
Primary Research
Primary research comprised structured consultations with hydrogen infrastructure developers, storage technology manufacturers, government energy agency officials, fuel cell vehicle industry associations, industrial gas distributors, and hydrogen refueling station operators. These discussions validated market sizing, confirmed technology segment shares, assessed regulatory drivers, and provided insights into competitive dynamics and investment trends.
Secondary Research
Secondary research drew on project databases, Ministry of Economy, Trade and Industry (METI) hydrogen roadmap publications, industry association reports, company annual reports and investor presentations, and academic publications on hydrogen storage technology development. Historical data spanning 2020 through 2025 was cross-validated across primary and secondary sources.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling approaches incorporating historical sector growth rates, government hydrogen infrastructure investment projections, fuel cell vehicle adoption models, industrial hydrogen demand growth aligned with decarbonization commitments, technology maturation timelines, and macroeconomic indicators including energy policy continuity and manufacturing sector output trends.
Japan Hydrogen Energy Storage Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Storage Forms Covered | Solid, Liquid, Gas |
| Technologies Covered | Compression, Liquefaction, Material Based |
| Applications Covered | Stationary Power, Transportation |
| End Users Covered | Utilities, Industrial, Commercial |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | TOYOTA MOTOR CORPORATION, Kawasaki Heavy Industries, Ltd., Iwatani Corporation, MITSUBISHI HEAVY INDUSTRIES, LTD., The Japan Steel Works, LTD., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan hydrogen energy storage market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan hydrogen energy storage market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan hydrogen energy storage industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Hydrogen Energy Storage Market Report
The Japan hydrogen energy storage market reached USD 1.33 Billion in 2026, driven by government hydrogen strategy implementation, fuel cell vehicle expansion, and growing industrial hydrogen demand.
The market is projected to grow at a CAGR of 4.66% during 2026-2034, supported by Japan's hydrogen infrastructure investment, fuel cell vehicle scaling, and expanding industrial and energy storage applications.
The market is projected to reach approximately USD 1.60 Billion by 2030, driven by expanding hydrogen refueling infrastructure, fuel cell vehicle adoption, and scaling of international hydrogen import terminal storage capacity.
Gas leads with a 65.0% share in 2025, reflecting its dominant role in fuel cell vehicle refueling and industrial hydrogen supply through high-pressure compressed gas infrastructure.
Compression technology leads with a 60.0% share in 2025, supported by its maturity, broad commercial applicability, and widespread deployment across Japan's hydrogen refueling and industrial supply infrastructure.
The Kanto region leads with a 30.0% share in 2025, anchored by Tokyo metropolitan industrial demand, the highest fuel cell vehicle density, and the greatest hydrogen refueling station concentration in Japan.
Leading companies include TOYOTA MOTOR CORPORATION, Kawasaki Heavy Industries, Ltd., Iwatani Corporation, MITSUBISHI HEAVY INDUSTRIES, LTD., and The Japan Steel Works, LTD., among others.
The market is projected to reach USD 1.92 Billion by 2034, supported by sustained government hydrogen investment, industrial decarbonization demand, and progressive technology maturation across storage segments.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade