
Japan Smart Ticketing Market Size, Share, Trends and Forecast by Product, Component, System, Application, and Region, 2026-2034
Japan Smart Ticketing Market Size, Share, Trends & Forecast (2026-2034)
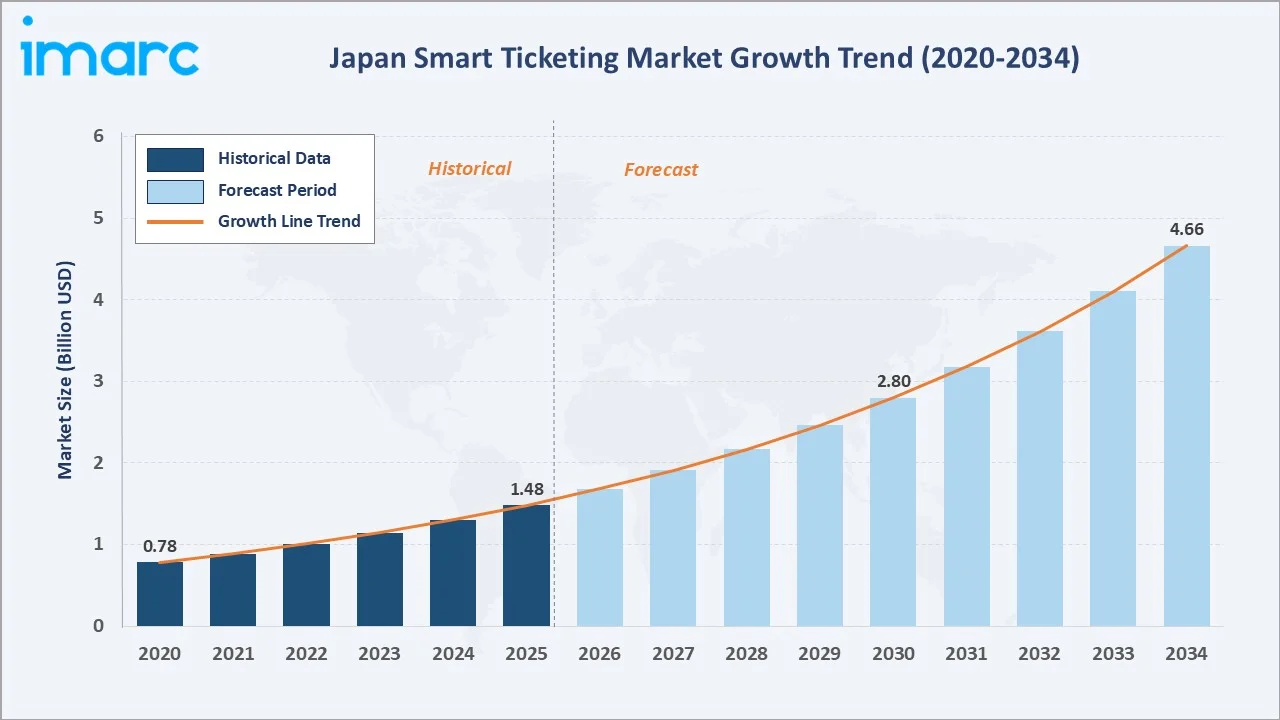
The Japan smart ticketing market was valued at USD 1.48 Billion in 2025 and is projected to reach USD 4.66 Billion by 2034, exhibiting a CAGR of 13.59% during 2026-2034. Expanding smart city investments, government-backed digitization mandates, and widening IC card and NFC adoption across rail, bus, and event networks are the primary drivers shaping market growth.
E-ticket leads the product segment at 34.8%, software dominates the component segment at 56.3%, and Kanto Region commands 32.6% regional share.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 1.48 Billion |
|
Forecast Market Size (2034) |
USD 4.66 Billion |
|
CAGR (2026-2034) |
13.59% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Kanto Region (32.6%, 2025) |
|
Second Largest Region |
Kansai/Kinki Region (18.7%, 2025) |
|
Leading Product |
E-Ticket (34.8%, 2025) |
|
Leading Component |
Software (56.3%, 2025) |
The Japan smart ticketing market expanded from USD 0.78 Billion in 2020 to USD 1.48 Billion in 2025, supported by digital transit integration programs and government smart city commitments. Anchored at USD 2.80 Billion in 2030, the forecast to USD 4.66 Billion by 2034 is sustained by accelerating NFC and QR-based ticketing deployments, expanding multimodal transport integration, and rising demand for connected venue management solutions across stadiums, concert halls, and tourist attractions.
To get more information on this market, Request Sample
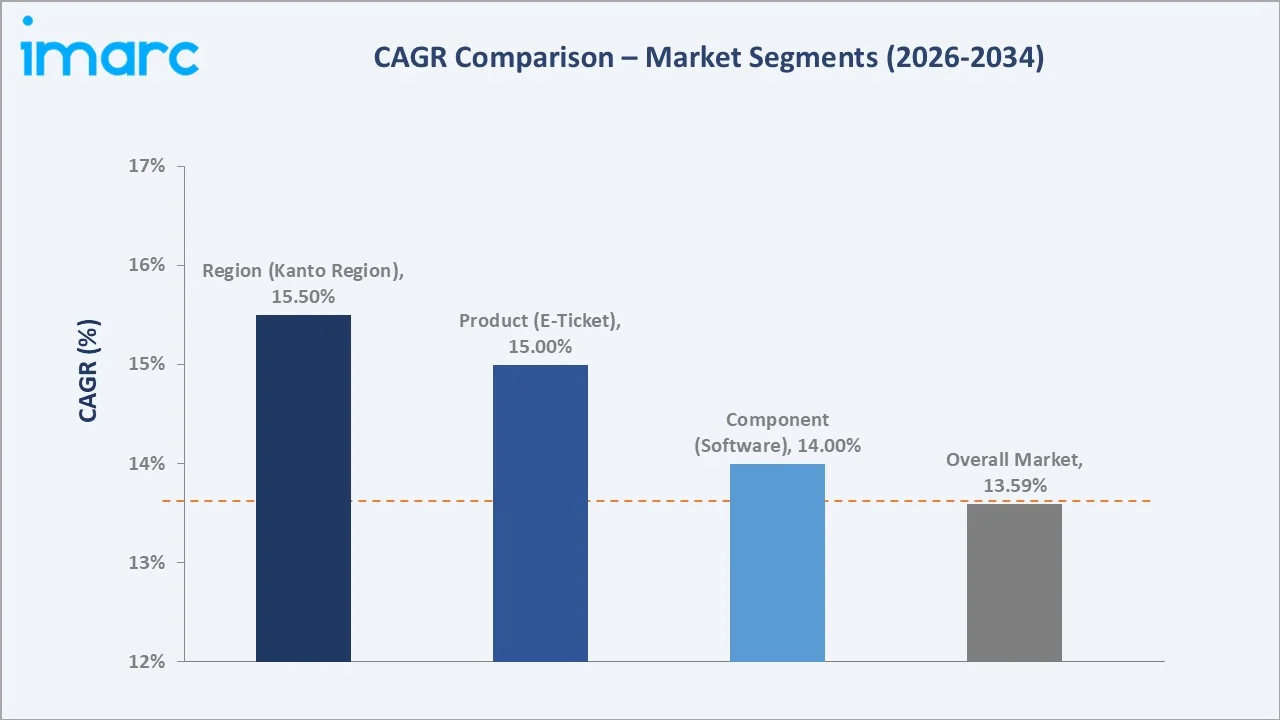
CAGR trajectories across product and component sub-segments show e-ticket and software expanding faster than the overall 13.59% market CAGR, driven by mobile-first adoption, cloud-based backend deployments, and increasing demand for seamless, contactless, and integrated ticketing experiences.
Executive Summary
The Japan smart ticketing market is on a consistent growth trajectory, expanding from USD 0.78 Billion in 2020 to USD 4.66 Billion by 2034. The market has transitioned from IC card-dominant systems to fully integrated multimodal digital ticketing ecosystems spanning transit, events, and tourism. Sustained government investment in smart city infrastructure, high smartphone penetration, and Japan's globally recognized transit efficiency are collectively accelerating this evolution.
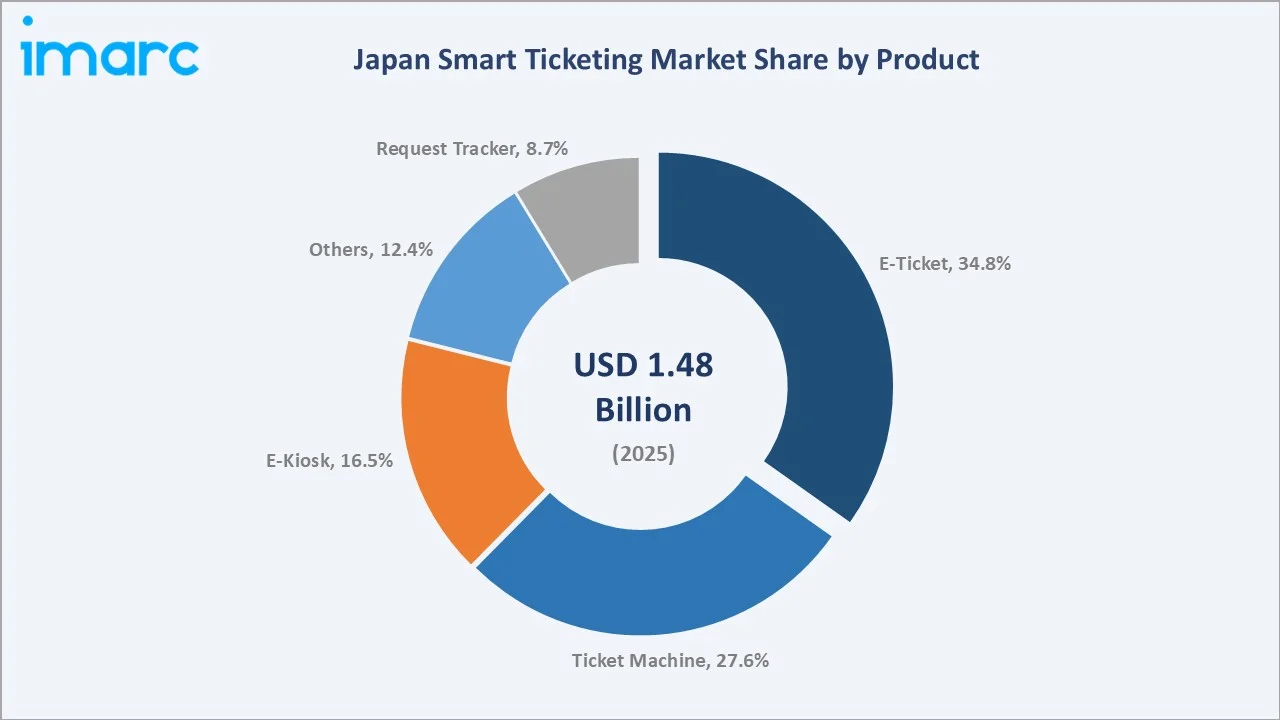
E-ticket commands 34.8% product share in 2025, supported by seamless smartphone-based issuance, real-time seat availability tracking, and integration with travel apps. Software dominates the component segment at 56.3%, driven by cloud-based platform migration, AI-enabled demand forecasting, and interoperable backend connectivity across operators. Kanto Region leads with 32.6% regional share, anchored by Greater Tokyo's dense transit network, high commuter volumes, and advanced IC card infrastructure.
Key Market Insights
|
Insight |
Data |
|
Leading Product |
E-Ticket - 34.8% share (2025) |
|
Second Largest Product |
Ticket Machine - 27.6% share (2025) |
|
Leading Component |
Software - 56.3% share (2025) |
|
Second Largest Component |
Hardware - 43.7% share (2025) |
|
Leading Region |
Kanto Region - 32.6% share (2025) |
|
Second Largest Region |
Kansai/Kinki Region – 18.7% share (2025) |
|
Top Companies |
Sony Group Corporation, NEC Corporation, Hitachi, Ltd., Fujitsu Limited, Panasonic Holdings Corporation |
Key Analytical Observations Expanding On the Data Above:
- E-ticket leadership at 34.8% is supported by broad smartphone penetration across Japan, instant barcode-based entry systems at transit hubs and venues, and integration with popular travel platforms, enabling seamless booking and real-time gate access across millions of daily commuters.
- Ticket machine share at 27.6% remains significant, anchored by Japan's strong physical interface culture, dense deployment at train stations and unmanned rural stops, accessibility for elderly users, and backup capability during digital system downtimes.
- Software dominance at 56.3% reflects the market's shift toward cloud-hosted ticketing platforms, AI-powered capacity management, and real-time integration with transit authority systems for seamless passenger data processing and revenue management.
- Hardware share at 43.7% is sustained by the continued deployment of ticket validators, automated ticket machines, gates, readers, and other physical infrastructure across Japan's extensive rail and public transportation networks.
- Kanto Region at 32.6% is anchored by Greater Tokyo's world-class rail network, robust IC card penetration, and concentration of major venue and event ticketing operators including those servicing Tokyo Dome and JR East.
Japan Smart Ticketing Market Overview
Smart ticketing refers to the deployment of electronic systems for the issuance, validation, and management of transit passes, event tickets, and access credentials using technologies, such as IC cards, NFC, QR codes, barcodes, and mobile application platforms. The market spans e-tickets, ticket machines, e-kiosks, request trackers, and other digital entry management products deployed across rail networks, airports, stadiums, concert venues, amusement parks, and urban transit corridors.
The Japanese ecosystem integrates hardware manufacturers, embedded software developers, transit operators, venue management firms, payment network providers, government regulatory bodies, and system integrators. Together, they deliver digitally connected, high-throughput ticketing infrastructure that serves over 20 million daily transit riders across the country's interconnected rail and bus systems.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
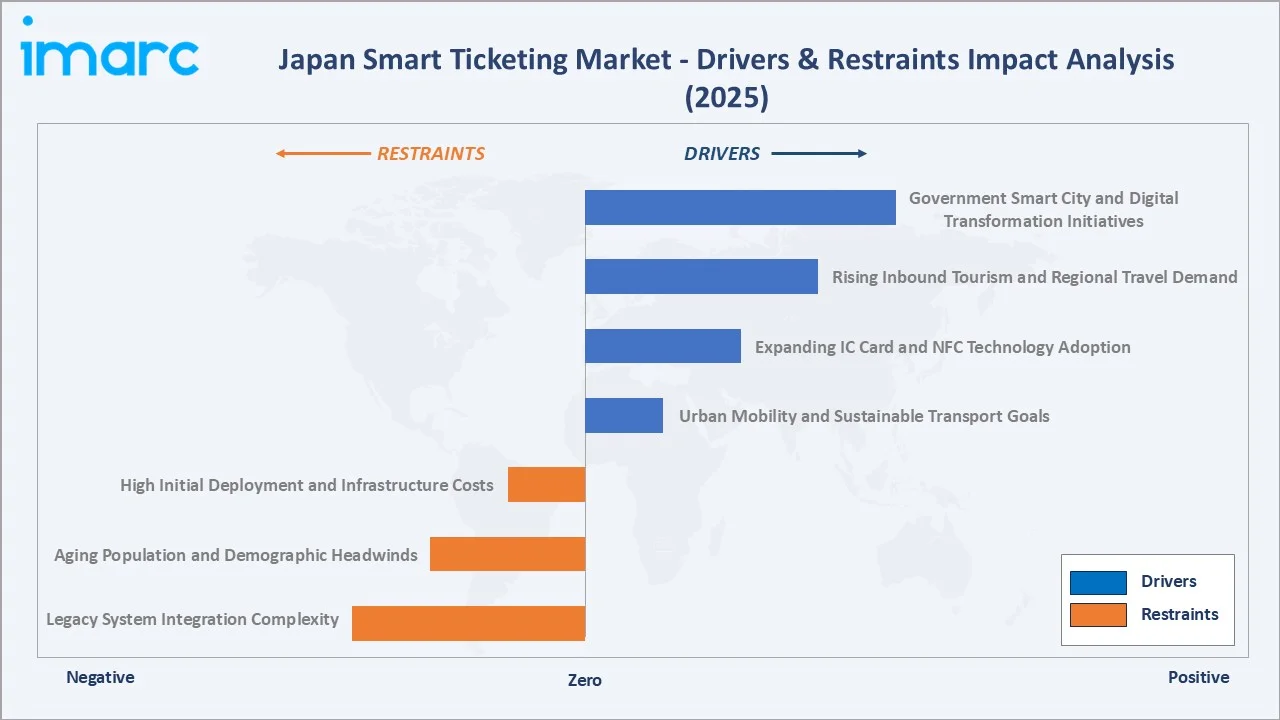
- Government Smart City and Digital Transformation Initiatives: Ongoing government smart city programs are expanding this infrastructure into tourism corridors, rural transit, and event venues, driving consistent demand for smart ticketing upgrades.
- Rising Inbound Tourism and Regional Travel Demand: In 2025, Japan welcomed a record 42.7 Million international tourists, representing an increase of over 15.8% from the previous peak of 36.9 Million in 2024. The rise in digital travel, the expansion of tourism to regional prefectures, and the growing need for multilingual, multimodal ticketing experiences are pushing transit operators to deploy advanced smart ticketing systems accessible across smartphones and global payment networks.
- Expanding IC Card and NFC Technology Adoption: Near-universal IC card acceptance across Japan's transit system, combined with rapid growth of QR and NFC-enabled smartphone ticketing, is reducing dependency on paper and magnetic strip tickets. This shift lowers operational costs and enables real-time passenger flow management, revenue optimization, and fraud reduction for operators.
- Urban Mobility and Sustainable Transport Goals: Japan's dense urban commuter base and its government's commitment to carbon-neutral transport by 2050 are jointly driving investment in integrated digital mobility platforms that include smart ticketing as a core enabling layer, connecting rail, bus, cycling, and ride-share services under unified contactless interfaces.
Market Restraints
- High Initial Deployment and Infrastructure Costs: Procurement, installation, and maintenance of enterprise-grade smart ticketing infrastructure, including gate validators, backend servers, and platform software, require substantial upfront capital, which limits adoption pace among smaller regional transit operators and independent venue managers without public subsidy access.
- Aging Population and Demographic Headwinds: Japan's population decline and aging demographic present structural challenges for long-term market volume expansion, as older users exhibit lower willingness to migrate from familiar paper or IC card formats to mobile-first ticketing applications, requiring additional investment in user interface design and assisted onboarding programs.
- Legacy System Integration Complexity: Japan's transit and venue sectors operate under complex vendor relationships and legacy system contracts. Migrating existing hardware-software stacks to modern smart ticketing platforms requires extensive interoperability testing, multi-stakeholder coordination, and prolonged procurement cycles that slow overall market expansion timelines.
Market Opportunities
- Venue and Event Ticketing Expansion: Stadiums, concert halls, amusement parks, and cultural facilities represent high-growth deployment targets for smart ticketing, driven by rising event attendance, demand for contactless entry, and interest in integrated fan experience platforms combining ticketing, food ordering, and loyalty programs.
- Tourism and Regional Transit Digitization: Japan's network of national parks, UNESCO heritage sites, and regional tourist corridors present untapped opportunities for smart ticketing deployments supporting multilingual visitor management, real-time capacity control, and digital pass issuance for domestic and international travelers.
Market Challenges
- Data Privacy and Cybersecurity Risks: Smart ticketing platforms aggregate large volumes of passenger behavior and location data, raising ongoing concerns around unauthorized access, data retention practices, and compliance with applicable data protection requirements. Operators must continuously strengthen cybersecurity measures and privacy governance frameworks.
- Multi-Format Ticketing Interoperability: Simultaneous management of IC card, QR code, NFC, barcode, and mobile app-based ticketing channels across fragmented operator networks increases technical complexity, requires multi-format validation hardware, and demands ongoing platform maintenance and compatibility testing across diverse device ecosystems.
Emerging Market Trends
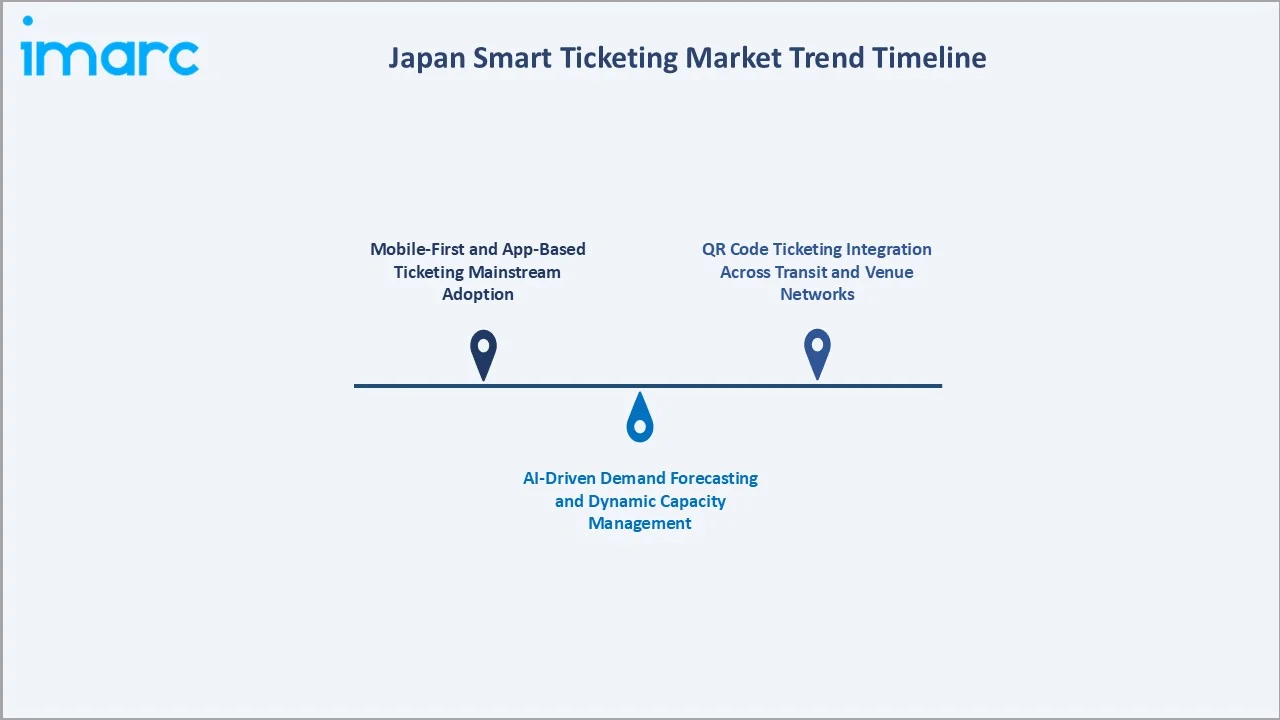
1. Mobile-First and App-Based Ticketing Mainstream Adoption
Transit operators and venue managers are rapidly deploying native mobile applications that issue, store, and validate tickets directly on smartphones, eliminating physical media. This shift is supported by growing consumer preference for convenient, contactless access and real-time ticket management across transportation and entertainment services.
2. QR Code Ticketing Integration Across Transit and Venue Networks
QR-based ticketing is gaining rapid traction across Japan's regional rail lines, tourist facilities, and event venues as a low-cost, hardware-light alternative to IC card infrastructure. This approach enables flexible ticket validation, simplifies system integration, and supports convenient access across diverse transportation and entertainment environments.
3. AI-Driven Demand Forecasting and Dynamic Capacity Management
Platform providers are embedding machine learning (ML) models into smart ticketing backends to enable real-time passenger volume forecasting, dynamic gate control, and surge-based pricing for event and leisure segments. These systems integrate ridership history, weather data, and event calendars to predict demand spikes and automate resource allocation, improving both passenger experience and operational efficiency.
Industry Value Chain Analysis
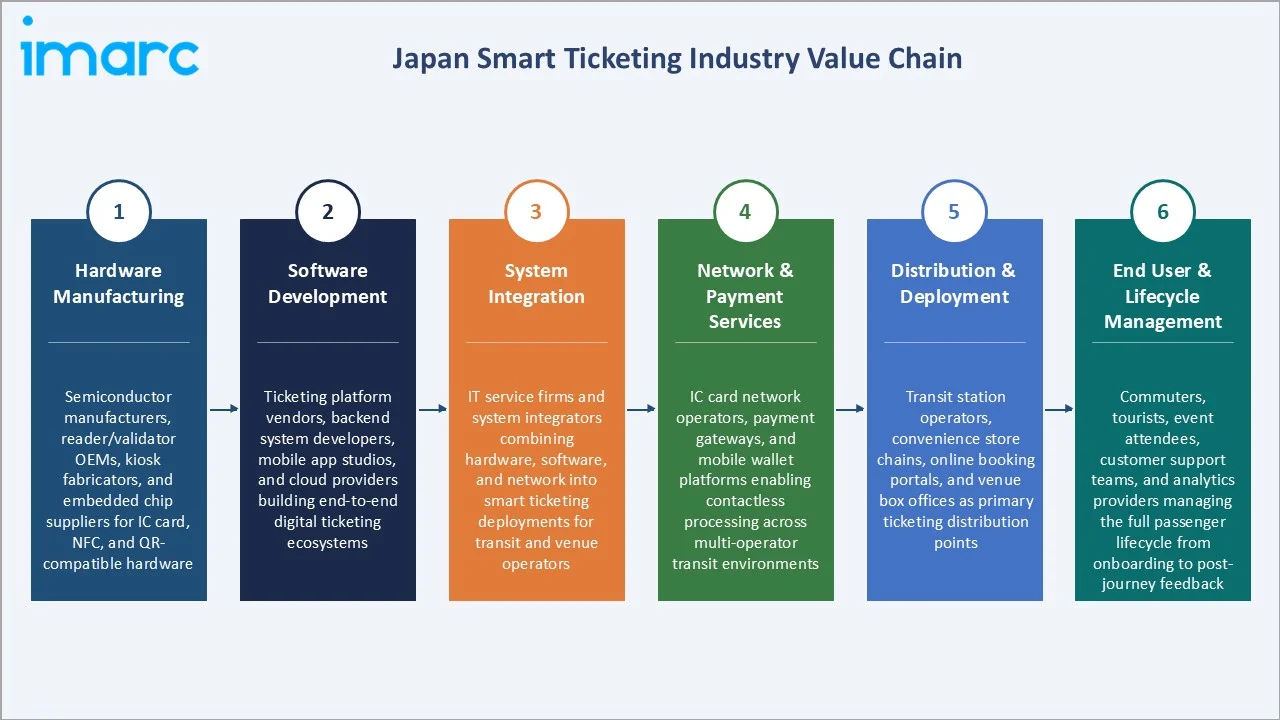
The Japan smart ticketing value chain spans six stages from hardware manufacturing through end-user lifecycle management. Software development, system integration, and network and payment services capture the highest value-add, while hardware manufacturing and distribution remain critical volume contributors. Vertically integrated players with proprietary platform software, IC card network access, and direct operator relationships are positioned to capture greater value than vendors dependent on third-party integration layers.
|
Stage |
Key Players / Examples |
|
Hardware Manufacturing |
Semiconductor manufacturers, reader and validator OEMs, kiosk fabricators, and embedded chip suppliers enabling IC card, NFC, and QR-compatible hardware |
|
Software Development |
Ticketing platform vendors, backend system developers, mobile app studios, and cloud infrastructure providers building end-to-end digital ticketing ecosystems |
|
System Integration |
IT service firms and system integrators combining hardware, software, and network components into functional smart ticketing deployments for transit and venue operators |
|
Network & Payment Services |
IC card network operators, payment gateway providers, and mobile wallet platforms enabling contactless transaction processing across multi-operator transit environments |
|
Distribution & Deployment |
Transit station operators, convenience store chains, online booking portals, and venue box offices serving as primary ticketing distribution and issuance points |
|
End User & Lifecycle Management |
Commuters, tourists, event attendees, customer support teams, and data analytics providers managing the full passenger lifecycle from onboarding to post-journey feedback |
Operators with strong government relationships and the ability to deliver end-to-end deployments, from hardware procurement through software licensing and ongoing maintenance, are increasingly preferred for major transit authority and venue contracts, reinforcing consolidation among large system integrators.
Technology Landscape in the Japan Smart Ticketing Industry
IC Card and NFC Technology Infrastructure
IC card and NFC technologies remain fundamental to smart ticketing infrastructure in Japan, enabling fast, contactless fare collection and ticket validation across rail, bus, and other transit networks. Their established acceptance and interoperability support convenient passenger access while enabling operators to manage transactions efficiently.
Cloud-Based Platform Architecture and API Integration
Modern smart ticketing deployments in Japan are migrating from on-premise server infrastructure to cloud-hosted, API-driven platforms that support real-time inventory management, dynamic pricing, multi-operator data sharing, and centralized analytics. Cloud migration enables faster product iteration, lower infrastructure costs, and seamless integration with third-party travel platforms, loyalty systems, and government passenger data registries.
AI, ML, and Predictive Analytics
AI and ML models are increasingly embedded in smart ticketing backends to support demand forecasting, anomaly detection, fraud prevention, and personalized travel recommendations. These systems process structured data from gate validators, mobile apps, and payment networks to build real-time demand models, enabling operators to optimize staffing, gate configurations, and pricing dynamically across peak and off-peak travel periods.
Biometric Authentication and Contactless Access Systems
Facial recognition and biometric authentication technologies are being piloted by major airports and large venue managers as a supplement to or replacement for IC card and QR-based entry. These systems reduce gate congestion and enhance security by linking biometric profiles to digital ticket records, enabling frictionless access without any physical device presentation.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product |
E-Ticket |
34.8% |
2025 |
|
Component |
Software |
56.3% |
2025 |
|
System |
🔒 |
🔒 |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
Region |
Kanto Region |
32.6% |
2025 |

By Product
E-ticket commands 34.8% share in 2025, driven by smartphone adoption, instant issuance through travel apps, QR and barcode gate compatibility across Tokyo's rail network, and growing acceptance at stadiums and event venues. The segment benefits from zero physical material costs, real-time delivery, and seamless integration with loyalty and travel reward platforms.
To access detailed market analysis, Request Sample
Ticket machine holds 27.6% share in 2025, sustained by Japan's high station density, accessibility requirements for elderly and foreign tourists, cash payment compatibility at unmanned rural stops, and the deep cultural familiarity with machine-based fare payment built over decades of IC card infrastructure.
By Component
Software dominates at 56.3% in 2025, reflecting the market's shift toward cloud-hosted ticketing platforms, real-time backend analytics, and mobile app ecosystems. Revenue concentration in software is driven by recurring licensing and subscription models, lower marginal delivery costs, and the growing complexity of multi-operator integration requirements that favor platform-led vendors over pure hardware suppliers.
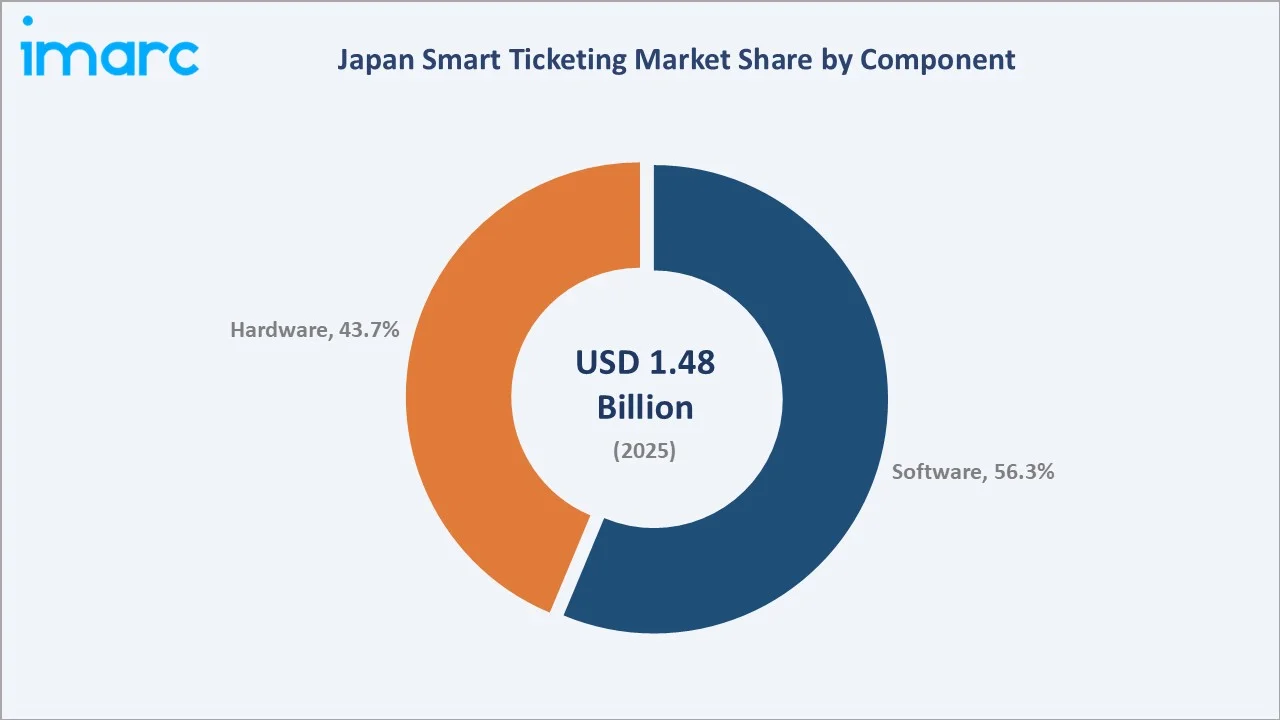
Hardware at 43.7% covers gate validators, IC card readers, kiosk terminals, and onboard vehicle validators. Despite software's dominance in value terms, hardware retains critical volume in large-scale transit and venue deployments, where physical infrastructure upgrades are required alongside software migrations.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
Kanto Region |
32.6% |
Dense urban rail network, high commuter volumes, strong IC card penetration, and concentration of major venue and tourism ticketing operators in Greater Tokyo |
|
Kansai/Kinki Region |
18.7% |
Large inbound tourism base, major venue clusters in Osaka and Kyoto, active transit digitization programs, and strong domestic business travel corridors |
|
Central/Chubu Region |
14.6% |
Manufacturing hub commuter demand, Shinkansen corridor connectivity, growing event ticketing infrastructure, and expanding regional transit smart card deployments |
|
Kyushu-Okinawa Region |
9.8% |
Fast-growing tourism infrastructure, island connectivity digitization, rising event venue investments, and government-led regional smart city pilot programs |
|
Tohoku Region |
8.2% |
Government-subsidized rural transit digitization and growing agritourism and heritage site ticketing deployments |
|
Chugoku Region |
6.7% |
Industrial corridor commuter demand, Hiroshima tourism growth, municipal transit upgrade programs, and cross-regional IC card interoperability initiatives |
|
Hokkaido Region |
5.6% |
Ski resort and nature tourism ticketing demand, Sapporo urban transit upgrades, and government rural mobility digitization funding under local revitalization plans |
|
Shikoku Region |
3.8% |
Emerging rural transit digitization, growing pilgrimage and heritage tourism, and smart ticketing pilot programs supported by prefectural government mobility grants |
Kanto Region at 32.6% in 2025 leads the market, anchored by the world's busiest rail networks centered on Tokyo, Yokohama, and surrounding commuter corridors. High IC card saturation, dense gate validator infrastructure, and the concentration of event venues, airports, and tourism hubs drive sustained demand for ticketing system upgrades and software integrations across the region.
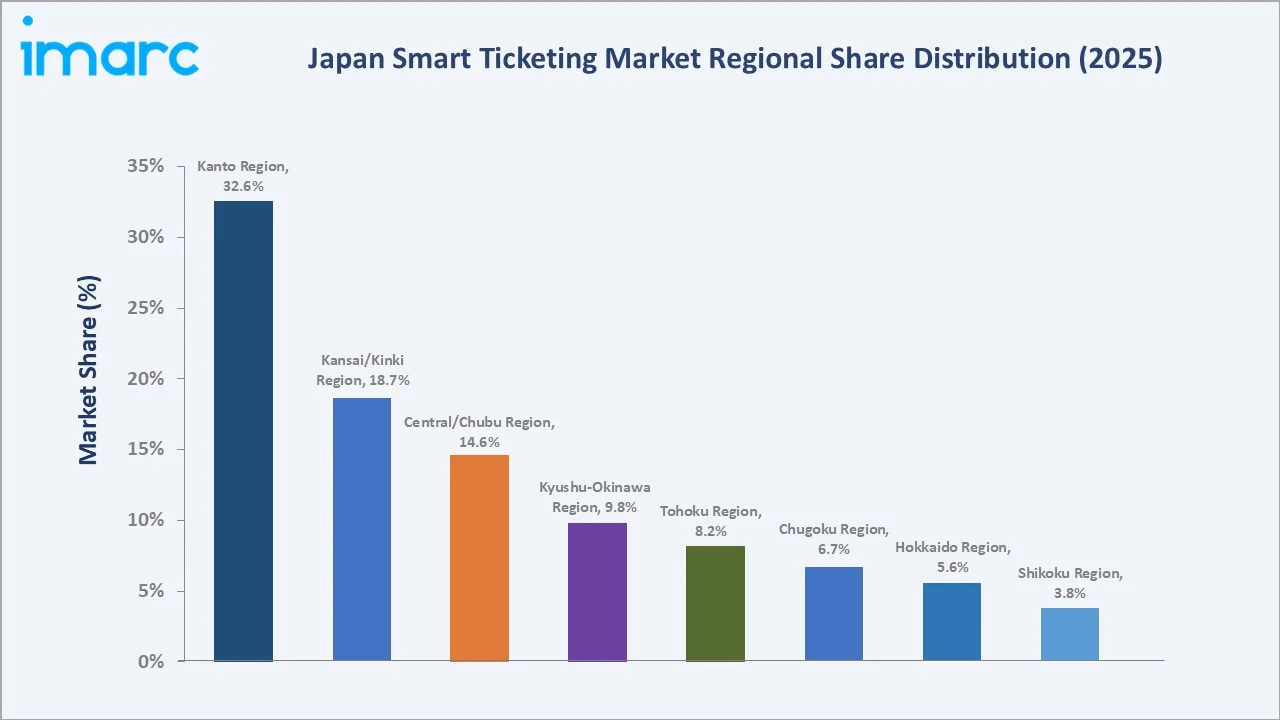
Kansai/Kinki Region at 18.7% represents Japan's second-largest smart ticketing market. The region's extensive urban rail network, strong tourism activity, and high adoption of digital and contactless payment solutions support its market position.
Competitive Landscape
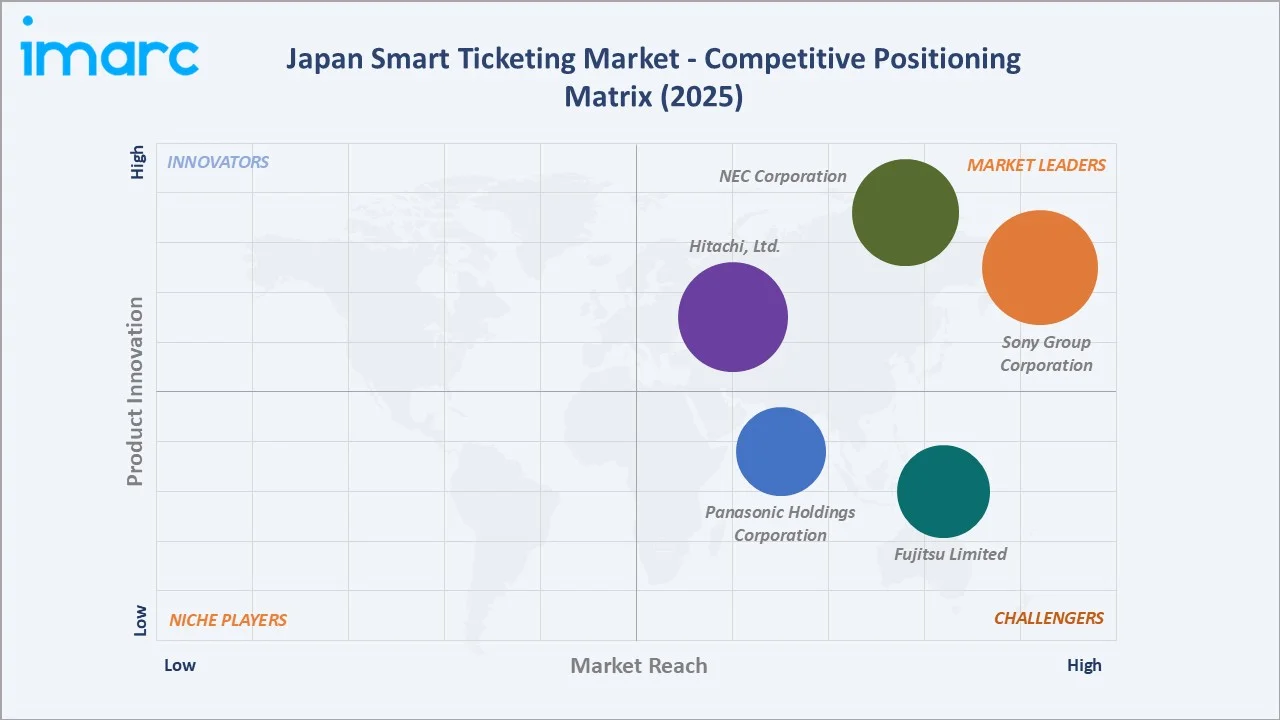
The Japan smart ticketing market is moderately concentrated, with established technology conglomerates and transit system specialists leading market share. Brand differentiation, platform interoperability, and government contract access form the key competitive moats in this regulated, infrastructure-driven market.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
|
Sony Group Corporation |
FeliCa Contactless IC Card System |
Leader |
Contactless IC chip technology development and global smart card platform licensing |
|
NEC Corporation |
NEC Automated Fare Collection (AFC) Solutions |
Leader |
End-to-end transit and venue automated fare collection system integration and managed service delivery |
|
Hitachi, Ltd. |
Digital Ticketing System |
Leader |
Large-scale gate validator and multimodal transit platform deployment for urban rail operators |
|
Fujitsu Limited |
Fujitsu Digital Ticketing Service (Uvance) |
Challenger |
Cloud-native digital ticketing platform and smart city integration services for transit and venue operators |
|
Panasonic Holdings Corporation |
Panasonic Connect Walk-Through Facial Recognition Ticket Gate |
Challenger |
Biometric walk-through gate systems and contactless venue access control for transit and large-scale events |
Key players include Sony Group Corporation, NEC Corporation, Hitachi, Ltd., Fujitsu Limited, and Panasonic Holdings Corporation, among others.
Key Company Profiles
Sony Group Corporation
Sony Group Corporation is a Japanese multinational conglomerate engaged in electronics, entertainment, semiconductor, and financial services businesses. The firm is publicly listed on the Tokyo Stock Exchange and operates globally through a network of subsidiaries and affiliates.
- Product Portfolio: FeliCa Contactless IC Card System, including IC chips, reader/writer modules, mobile FeliCa for smartphone-based NFC transit access, and software development kits supporting transit, e-money, access control, and identification applications.
- Recent Developments: The company continues to enhance its contactless ticketing technologies, strengthen mobile and NFC-based solutions, and expand interoperability across transit and payment applications.
- Strategic Focus: Expanding FeliCa licensing into international transit markets, advancing mobile NFC integration with global smartphone platforms, and supporting the development of next-generation contactless security standards for high-throughput transit environments.
NEC Corporation
NEC Corporation is a Japanese multinational information technology and electronics company that provides integrated solutions across communications infrastructure, enterprise systems, and public safety. In the smart ticketing domain, the firm delivers automated fare collection systems, transit gate infrastructure, and cloud-based ticketing platforms to public transit operators in Japan and internationally.
- Product Portfolio: NEC Automated Fare Collection (AFC) Solutions comprising fare gate validators, ticket vending machines, central clearing servers, cloud-hosted account-based ticketing platforms, and QR and IC card-compatible multi-operator transit systems.
- Recent Developments: The company is advancing automated fare collection and digital ticketing capabilities, with greater emphasis on cloud-based platforms, QR ticketing, and integrated solutions for modern transit networks.
- Strategic Focus: Expanding cloud-native AFC platform deployments for transit operators, advancing account-based ticketing and QR-based fare collection to reduce hardware dependency, and growing system integration and managed service contracts across Japan and international transit markets.
Hitachi, Ltd.
Hitachi, Ltd. is a Japanese multinational conglomerate operating across infrastructure, construction, digital systems, and social innovation businesses. Through its rail systems division, Hitachi supplies digital ticketing systems, automated fare collection infrastructure, and integrated transit management platforms to railway and metro operators.
- Product Portfolio: Digital Ticketing System covering fare gate validators, IC card processing hardware, station management software, onboard vehicle validators, and integrated operations control systems for urban, regional, and mainline rail networks.
- Recent Developments: The company continues to develop digital rail and ticketing solutions, focusing on system integration, real-time data capabilities, and connected infrastructure to improve passenger and operator experiences.
- Strategic Focus: Advancing integrated digital ticketing deployments for transit operators and developing IoT-connected gate systems for real-time passenger flow analytics.
Market Concentration Analysis
The Japan smart ticketing market is moderately concentrated, with the top three companies, Sony Group Corporation, NEC Corporation, and Hitachi, Ltd., accounting for a substantial portion of annual system deployments, IC card infrastructure revenues, and transit authority contract volumes.
Barriers to entry are high. They include the technical complexity of multi-operator transit system integration, long-cycle government procurement processes, deep infrastructure investment requirements, and established vendor relationships between major transit authorities and incumbent technology providers. These dynamics favor well-capitalized incumbents with proven large-scale deployment track records and sustained R&D investment capability.
Consolidation is progressing gradually as smaller system integrators and regional hardware vendors form strategic partnerships with platform software providers to offer end-to-end solutions. Simultaneously, international ticketing technology companies are seeking market entry through joint ventures and pilot deployments targeting event venues and tourist facilities, where procurement processes are shorter and technical requirements differ from transit authority contracts.
Investment & Growth Opportunities
Fastest-Growing Segments
E-ticket is the fastest-growing product segment, expanding on the strength of smartphone-native ticket issuance, QR gate compatibility, and zero-inventory distribution economics. Software is the highest-growth component category, driven by cloud platform migrations, SaaS licensing models, and the rising complexity of multimodal integration requirements that favor platform vendors over hardware-only suppliers.
Emerging Markets
Kanto Region leads all regions on forecast CAGR through 2034, driven by continued investment in Greater Tokyo's transit infrastructure, expanding NFC and QR-based ticketing deployments, and high concentrations of venue and tourism operators commissioning system upgrades.
Venture & Investment Trends
Capital is flowing into cloud-native smart ticketing platform vendors, biometric access integration specialists, and MaaS platform developers targeting Japan's transit and event management sectors. Investment activity is also supporting platform modernization, interoperability, and the expansion of integrated digital mobility services.
Future Market Outlook (2026-2034)
The Japan smart ticketing market is forecast to expand from USD 1.48 Billion in 2025 to USD 4.66 Billion by 2034, growing at a CAGR of 13.59% and adding approximately USD 3.18 Billion in incremental annual market value over the forecast period.
Four forces will shape the market through 2034: government investment in digital mobility infrastructure; the shift toward mobile and cloud-based ticketing; greater adoption of AI, biometrics, and real-time data; and rising inbound tourism.
By 2034, the Japan smart ticketing market is expected to be defined by fully integrated multimodal digital ecosystems, where commuters, tourists, and event attendees access rail, bus, aviation, venue entry, and loyalty rewards through unified digital credentials on smartphones or biometric profiles, with IC card hardware retained primarily as a legacy accessibility option for elderly users and international visitors unfamiliar with Japan's transit platforms.
Research Methodology
Primary Research
Primary research included structured interviews with transit authority technology officers, venue management platform providers, IC card network operators, government smart city program managers, and system integrators, validating market sizing, regional demand distribution, segment share estimates, and competitive positioning insights.
Secondary Research
Secondary sources included Japan's Ministry of Land, Infrastructure, Transport and Tourism publications, Ministry of Internal Affairs and Communications digital infrastructure reports, Cabinet Office smart city initiative documentation, annual reports and investor presentations from listed companies, patent databases, and trade association publications from relevant transit and electronics industry bodies.
Forecasting Models
Market forecasts were developed using top-down and bottom-up modeling approaches combining transit ridership volumes, hardware deployment counts, software licensing revenue data, venue ticketing transaction volumes, and macroeconomic indicators. Scenario analysis incorporated regulatory change timelines, technology adoption pace variables, tourism inflow projections, and government digitization spending estimates.
Japan Smart Ticketing Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Products Covered | Ticket Machine, E-Ticket, E-Kiosk, Request Tracker, Others |
| Components Covered | Software, Hardware |
| Systems Covered | Open Payment System, Smart Card, Near-Field Communication |
| Applications Covered | Sports and Entertainment, Transportation, Others |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Sony Group Corporation, NEC Corporation, Hitachi, Ltd., Fujitsu Limited, Panasonic Holdings Corporation, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan smart ticketing market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan smart ticketing market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan smart ticketing industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Smart Ticketing Market Report
The Japan smart ticketing market was valued at USD 1.48 Billion in 2025, driven by widespread IC card adoption, government smart city programs, and growing NFC and QR-based transit deployments.
The market is projected to grow at a CAGR of 13.59% from 2026-2034, reaching USD 4.66 Billion, supported by mobile-first adoption, multimodal platform integration, and inbound tourism growth.
E-ticket leads with 34.8% share in 2025, driven by smartphone penetration, QR gate compatibility, and integration with major travel and booking apps across Japan's transit network.
Software dominates at 56.3% in 2025, fueled by cloud platform migration, SaaS licensing growth, and increasing demand for real-time backend analytics across transit and venue operators.
Kanto Region commands 32.6% in 2025, anchored by Greater Tokyo's world-class rail network, high commuter volumes, and deep IC card and NFC infrastructure density.
Leading players include Sony Group Corporation, NEC Corporation, Hitachi, Ltd., Fujitsu Limited, and Panasonic Holdings Corporation, among others.
IC card infrastructure is expanding into mobile NFC and QR code formats, while cloud-native platforms, AI-powered demand forecasting, and biometric access integration are reshaping the technology landscape.
Government smart city mandates, digital mobility subsidies, and regional revitalization funding are key market catalysts, driving adoption across both urban transit authorities and underserved rural and regional networks.
Key challenges include high initial infrastructure costs, legacy system integration complexity, data privacy compliance requirements, and the need to balance digital adoption with accessibility for aging users.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade