
Japan Textile Recycling Market Size, Share, Trends and Forecast by Product Type, Textile Waste, Distribution Channel, End User, and Region, 2026-2034
Japan Textile Recycling Market Size, Share, Trends & Forecast (2026-2034)
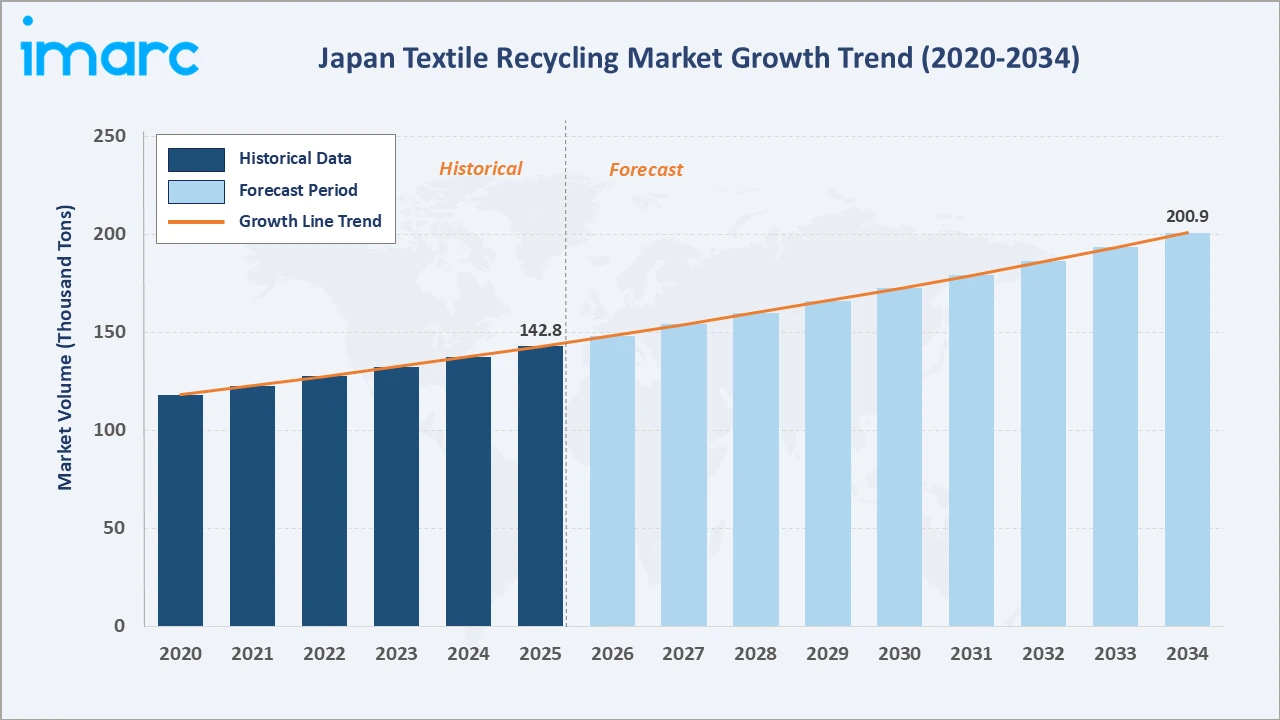
The Japan textile recycling market grew from 142.8 Thousand Tons in 2025 to 148.4 Thousand Tons in 2026 and is projected to reach 200.9 Thousand Tons by 2034, growing at a CAGR of 3.86% during 2026-2034. Corporate sustainability goals, government circular economy policies, and chemical recycling advances are driving growth. In April 2026, AXENS, IFPEN and JEPLAN announced a successful industrial test recycling post-consumer, polyester-rich textile waste.
Brand take-back programs, second-hand fashion, and fiber-to-fiber partnerships continue to expand collected and recycled volumes. Polyester and polyester fiber recycling dominates at 38.9%. The online channel leads distribution at 54.3%. The Kanto Region commands 36.7% of national market share.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Volume (2025) | 142.8 Thousand Tons |
| Market Volume (2026) | 148.4 Thousand Tons |
| Forecast Market Volume (2034) | 200.9 Thousand Tons |
| CAGR (2026-2034) | 3.86% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Dominant Product Type | Polyester and Polyester Fiber Recycling (38.9%, 2025) |
| Dominant Distribution Channel | Online Channel (54.3%, 2025) |
| Leading Region | Kanto Region (36.7%, 2025) |
The Japan textile recycling market volume increased from 118.2 Thousand Tons in 2020 to 142.8 Thousand Tons in 2025 and is estimated to reach 148.4 Thousand Tons in 2026. The market is further expected to grow to 172.6 Thousand Tons by 2030 and 200.9 Thousand Tons by 2034.
To get more information on this market, Request Sample
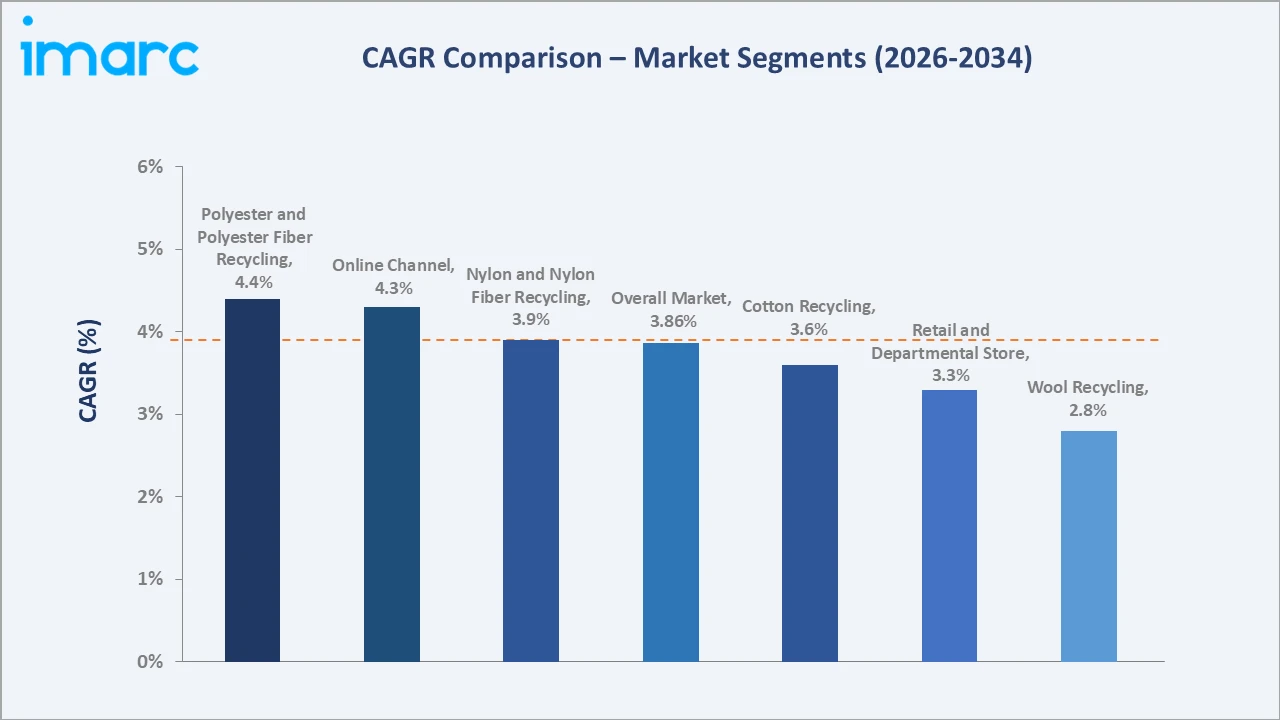
Polyester and polyester fiber recycling is expected to grow fastest at ~4.4% CAGR, supported by chemical recycling and fiber-to-fiber partnerships. The online channel follows at ~4.3% CAGR as resale platforms and online take-back services expand.
Executive Summary
The Japan textile recycling market expanded from 142.8 Thousand Tons in 2025 to an estimated 148.4 Thousand Tons in 2026. Japan discards a large volume of clothing each year, and most still ends up incinerated or in landfills.
Government circular economy targets, apparel brand take-back programs, and new chemical recycling technologies are raising recycling rates. The market is projected to reach 200.9 Thousand Tons by 2034. Polyester and polyester fiber recycling at 38.9% leads product types. The online channel at 54.3% leads distribution. The Kanto Region leads at 36.7%.
Key Market Insights
| Insight | Data |
|---|---|
| Dominant Product Type | Polyester and Polyester Fiber Recycling - 38.9% share (2025) |
| Dominant Distribution Channel | Online Channel - 54.3% market share (2025) |
| Leading Region | Kanto Region - 36.7% share (2025) |
| Market Opportunity | Chemical recycling of polyester; automated sorting; brand take-back programs; recycled fiber for apparel and industrial uses |
Key Analytical Observations Supporting the Above Data:
- Polyester and Polyester Fiber Recycling at 38.9%: Polyester leads because it is the most widely used fiber in apparel and home textiles, and both mechanical and chemical recycling technologies for polyester are well developed in Japan.
- Online Channel at 54.3%: The online channel leads because resale platforms, online take-back services, and e-commerce sales of recycled products make participation convenient for consumers.
- Kanto Region at 36.7%: The Kanto Region leads due to Tokyo’s large population, high apparel consumption, and concentration of brands, retailers, and recycling companies.
Japan Textile Recycling Market Overview
Textile recycling covers the collection, sorting, and processing of used clothing, home textiles, and industrial textile waste into new fibers, yarns, and products. It includes mechanical recycling, which shreds textiles into fibers, and chemical recycling, which breaks fibers down to raw materials.
Recycled materials are used in apparel, home textiles, and industrial products. Reuse and resale are also important parts of textile circularity. Repair and rental services help extend clothing life. These services reduce waste generation over time. Consumers increasingly value durability and longevity. Brands offer repair services to support this trend.
The industry ecosystem links waste generators, collectors and sorters, recyclers, fiber and yarn producers, regulators, and end users. Macroeconomic factors include apparel consumption, waste disposal costs, raw material prices, and circular economy policies, all of which shape demand. Japan’s high apparel consumption creates a large potential feedstock for recycling.
Incineration remains the dominant disposal route, leaving significant room for growth. Rising waste disposal costs also encourage recycling. Corporate reporting requirements are also driving change. Disclosure frameworks encourage companies to report textile waste data. Investors increasingly consider circularity in their decisions. ESG ratings increasingly reflect textile waste management.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
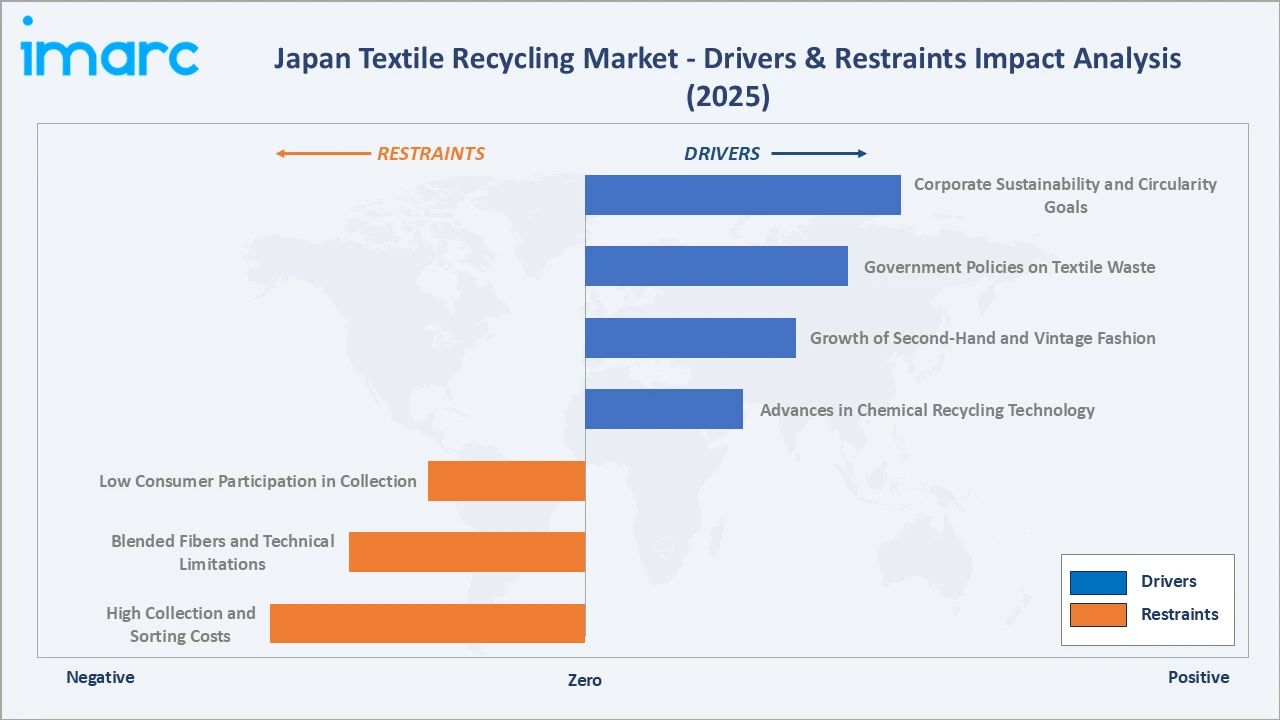
- Corporate Sustainability and Circularity Goals: Japanese apparel brands, retailers, and fiber makers are setting recycled content and waste reduction targets, increasing demand for recycled fibers. Many companies have committed to using recycled or sustainable materials across a large share of their product ranges by 2030.
- Government Policies on Textile Waste: National circular economy and resource circulation strategies encourage textile collection, reuse, and fiber-to-fiber recycling. Government agencies are studying ways to increase textile collection rates and reduce incineration of used clothing.
- Growth of Second-Hand and Vintage Fashion: Rising popularity of resale and vintage clothing supports collection and reuse, feeding recycling streams for unwearable items. Japan has a large and well-established second-hand market, and resale platforms are expanding rapidly. Items that cannot be resold are increasingly directed to recycling rather than disposal.
- Advances in Chemical Recycling Technology: New depolymerization processes produce recycled polyester equivalent to virgin quality, enabling true textile-to-textile recycling. These technologies can remove dyes and impurities, allowing colored and mixed polyester waste to be recycled into high-quality fibers.
Market Restraints
- High Collection and Sorting Costs: Collecting, transporting, and sorting mixed textile waste is labor-intensive and costly. Limited sorting infrastructure in rural areas further raises costs for recyclers.
- Blended Fibers and Technical Limitations: Blended fabrics, dyes, and finishes are difficult to separate and recycle into high-quality fibers.
- Low Consumer Participation in Collection: Many consumers still discard clothing with household waste rather than using collection programs. Awareness of recycling options remains limited in some age groups and regions. Convenient collection points and incentives are needed to increase participation. Public awareness campaigns are helping change disposal habits.
Market Opportunities
- Automated Sorting Technology: Near-infrared and AI-based sorting can improve efficiency and fiber purity. Automation also reduces labor costs and improves throughput. Several pilot sorting facilities are being developed in Japan. These facilities aim to supply sorted feedstock to chemical recyclers. Sorted feedstock commands higher prices and supports recycler economics.
- Industrial and Automotive Applications: Recycled fibers can be used in insulation, nonwovens, and automotive interiors. These applications provide stable demand for lower-grade recycled fibers. Automotive makers are increasing recycled content in interior materials. Construction and packaging applications also offer growth potential. Industrial uses absorb fibers unsuitable for apparel.
Market Challenges
- Price Competition with Virgin Fibers: Recycled fibers often cost more than virgin polyester. Scale-up and technology improvements are expected to narrow this gap. Rising virgin material costs could also improve competitiveness. Carbon pricing may further favor recycled materials. Government support for green materials also helps close the cost gap.
- Traceability and Certification: Brands require verified recycled content and supply chain transparency. Digital product passports and traceability platforms are emerging to meet this need. Certification schemes help brands make credible recycling claims. Transparency builds consumer trust in recycled products. Third-party verification is becoming standard for recycled claims.
Emerging Market Trends
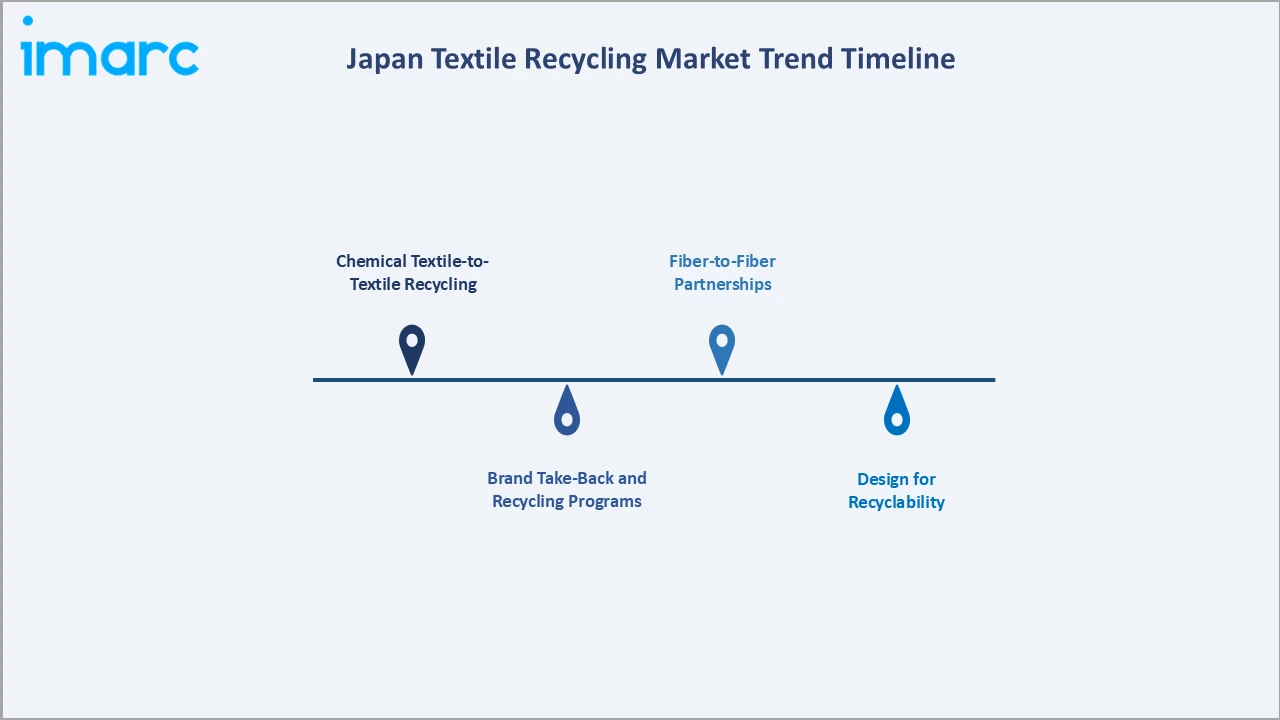
1. Chemical Textile-to-Textile Recycling
Chemical recycling is moving from pilot to industrial scale. The Rewind PET trial at JEPLAN’s Kitakyushu plant demonstrated the process at a 1,000-tonne-per-year scale.
2. Brand Take-Back and Recycling Programs
Apparel brands are expanding in-store and online collection programs to recover used garments for reuse and recycling. Discounts and loyalty points encourage consumers to return used clothing. Collection volumes are rising as programs become more widely known. Brands also use collected garments for reuse and donation.
3. Fiber-to-Fiber Partnerships
Recyclers, fiber makers, and global brands are forming partnerships to scale recycled polyester production. These partnerships combine technology, feedstock, and market access. International partnerships help Japanese technologies reach global markets. Licensing of recycling technology creates new revenue streams. Japanese firms are leaders in polyester chemical recycling technology.
Their expertise attracts global partners and investors. Overseas plants using Japanese technology are being planned. Technology exports strengthen Japan’s role in global textile circularity. Exports of recycling know-how are expected to grow.
4. Design for Recyclability
Manufacturers are developing mono-material fabrics that are easier to recycle, such as all-polyester stretch textiles. Design for recyclability is increasingly part of brand sustainability strategies. Mono-material designs reduce sorting and processing costs. Material innovation supports long-term recycling goals. Brands increasingly specify recyclable materials in product design guidelines.
Industry Value Chain Analysis
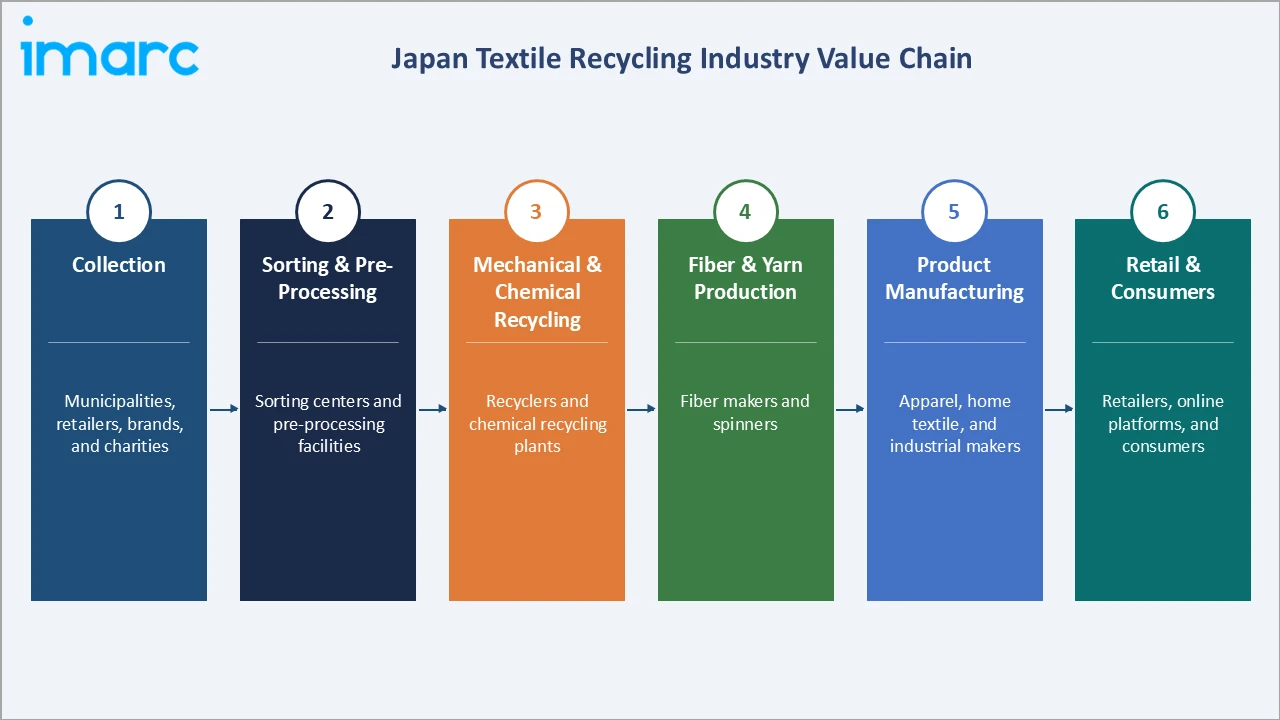
The Japan textile recycling value chain spans collection, sorting and pre-processing, mechanical and chemical recycling, fiber and yarn production, product manufacturing, and retail and consumers. Value is shifting toward advanced recycling and recycled fiber production. Collection and sorting remain the foundation for reliable feedstock supply.
Product manufacturing and retail determine final demand for recycled materials.
| Stage | Key Participants |
|---|---|
| Collection | Municipalities, retailers, brands, and charity organizations |
| Sorting & Pre-Processing | Sorting centers and pre-processing facilities |
| Mechanical & Chemical Recycling | Recyclers and chemical recycling plants |
| Fiber & Yarn Production | Fiber makers and spinners |
| Product Manufacturing | Apparel, home textile, and industrial manufacturers |
| Retail & Consumers | Retailers, online platforms, and consumers |
Sorting and pre-processing is the most consequential stage of the chain. Accurate separation by fiber type and color determines the quality and value of recycled output. Investments in sorting technology are therefore critical for the industry. Pre-processing steps such as removing zippers and buttons also affect yield.
Efficient logistics reduce transport costs and emissions. Regional hubs could improve collection economics. Reverse logistics through retail networks is also being explored. Delivery companies can collect used clothing during regular routes. This model could significantly expand convenient collection options.
Technology Landscape in the Japan Textile Recycling Industry
Mechanical Recycling
Mechanical processes shred and card textiles into fibers for yarn, nonwovens, and insulation. Mechanical recycling is energy-efficient but often reduces fiber length and quality.
Chemical Depolymerization
Chemical processes break polyester into monomers such as BHET, which are purified and repolymerized into new polyester. These processes produce recycled materials comparable to virgin polyester. Energy efficiency and catalyst recovery are key areas of innovation. Larger plants are expected to improve economics. Feedstock security is critical for plant utilization.
Partnerships with brands help secure stable feedstock. Imported textile waste may also supplement domestic supply. Feedstock quality and consistency remain top priorities.
Automated Sorting and Fiber Identification
Near-infrared sensors and AI systems identify fiber composition and color to improve sorting speed and accuracy. Automated systems help process larger volumes of mixed textile waste. Data from sorting systems supports better planning for recyclers. Sorting accuracy directly affects recycled fiber value. Investments in sorting automation are increasing.
Accurate sorting enables higher-value recycling applications. Color sorting is particularly important for polyester recycling. White and light-colored fabrics are easier to process. Dye removal technologies are expanding the range of recyclable colors.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Product Type | Polyester and Polyester Fiber Recycling | 38.9% | 2025 |
| Textile Waste | 🔒 | 🔒 | 2025 |
| Distribution Channel | Online Channel | 54.3% | 2025 |
| End User | 🔒 | 🔒 | 2025 |
| Region | Kanto Region | 36.7% | 2025 |

By Product Type
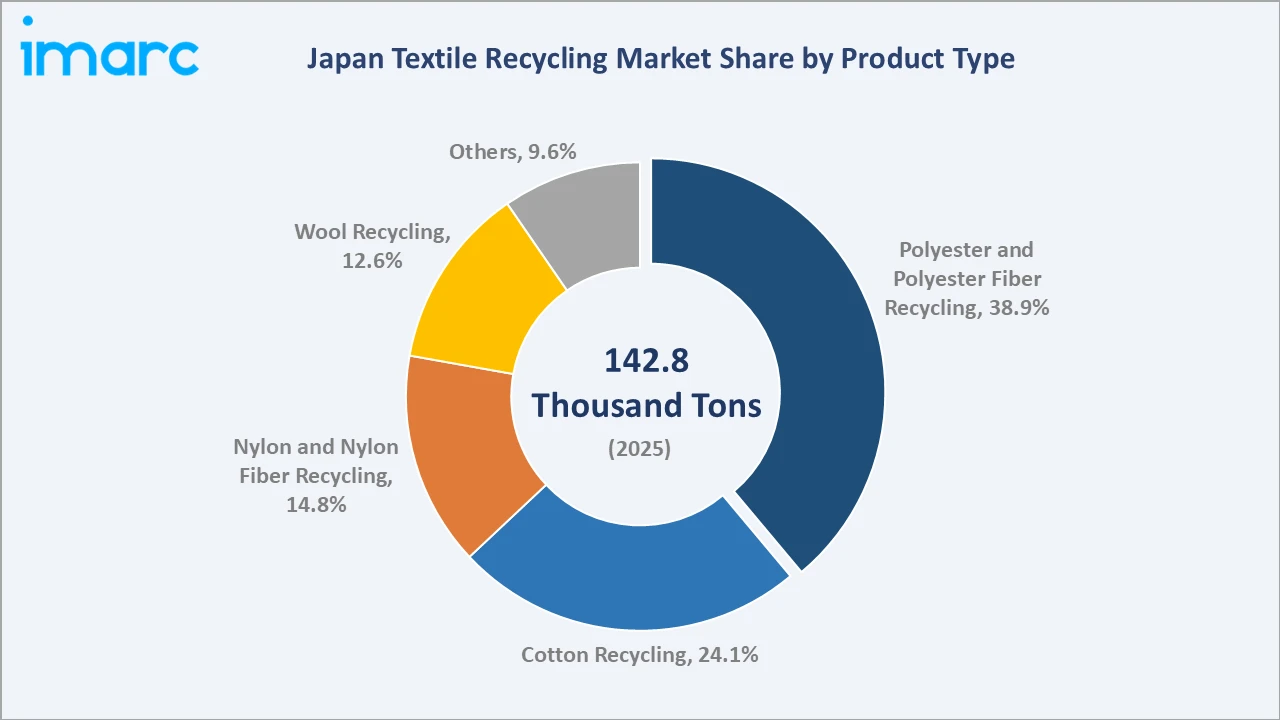
Polyester and polyester fiber recycling leads at 38.9% (2025). Polyester is widely used in apparel and has established recycling technologies. Chemical recycling capacity is expanding for polyester textiles.
To access detailed market analysis, Request Sample
Cotton recycling at 24.1% grows at ~3.6% CAGR, nylon and nylon fiber recycling at 14.8% at ~3.9%, wool recycling at 12.6% at ~2.8%, and others at 9.6% at ~3.2%. Cotton recycling is supported by brands using recycled cotton blends. Wool recycling benefits from traditional reclaiming expertise.
Nylon recycling is supported by fishing nets and industrial waste streams. Others include acrylic, rayon, and mixed fibers. These materials are often recycled into nonwovens and industrial products.
By Distribution Channel
The online channel leads at 54.3% (2025). Online resale and take-back services make participation easy. Online platforms also sell products made from recycled materials.
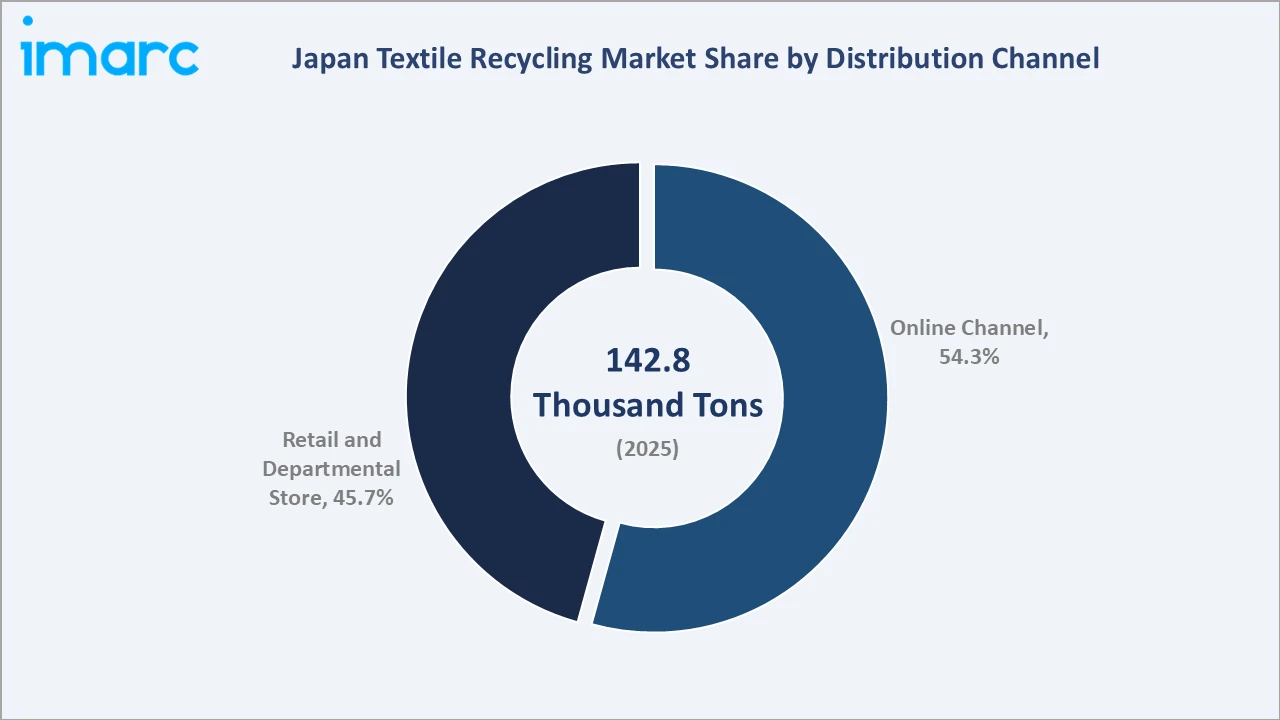
Retail and departmental stores at 45.7% grow at ~3.3% CAGR, supported by in-store collection boxes and brand programs. Department stores host seasonal collection campaigns to engage shoppers. In-store programs also strengthen customer loyalty. Retail collection boxes make returning clothes convenient.
Regional Market Insights
| Region | Share (2025) | Key Japan Textile Recycling Market Drivers & Characteristics |
|---|---|---|
| Kanto Region | 36.7% | Large population, high apparel consumption, and brand headquarters. |
| Kansai/Kinki Region | 19.8% | Osaka textile trading base and strong retail networks. |
| Central/Chubu Region | 16.4% | Textile and fiber manufacturing clusters. |
| Kyushu-Okinawa Region | 9.6% | Chemical recycling plant in Kitakyushu. |
| Tohoku Region | 6.9% | Regional collection programs and sorting. |
| Chugoku Region | 5.8% | Textile production in Okayama and Hiroshima. |
| Hokkaido Region | 3.0% | Municipal collection in Sapporo. |
| Shikoku Region | 1.8% | Towel and textile production in Ehime. |
The Kanto Region's 36.7% market leadership reflects Tokyo's large population, high apparel consumption, and concentration of brands and recyclers. Large retailers in Tokyo run extensive collection programs. The region also hosts many fashion brands and resale companies. High participation in brand programs supports collection volumes.
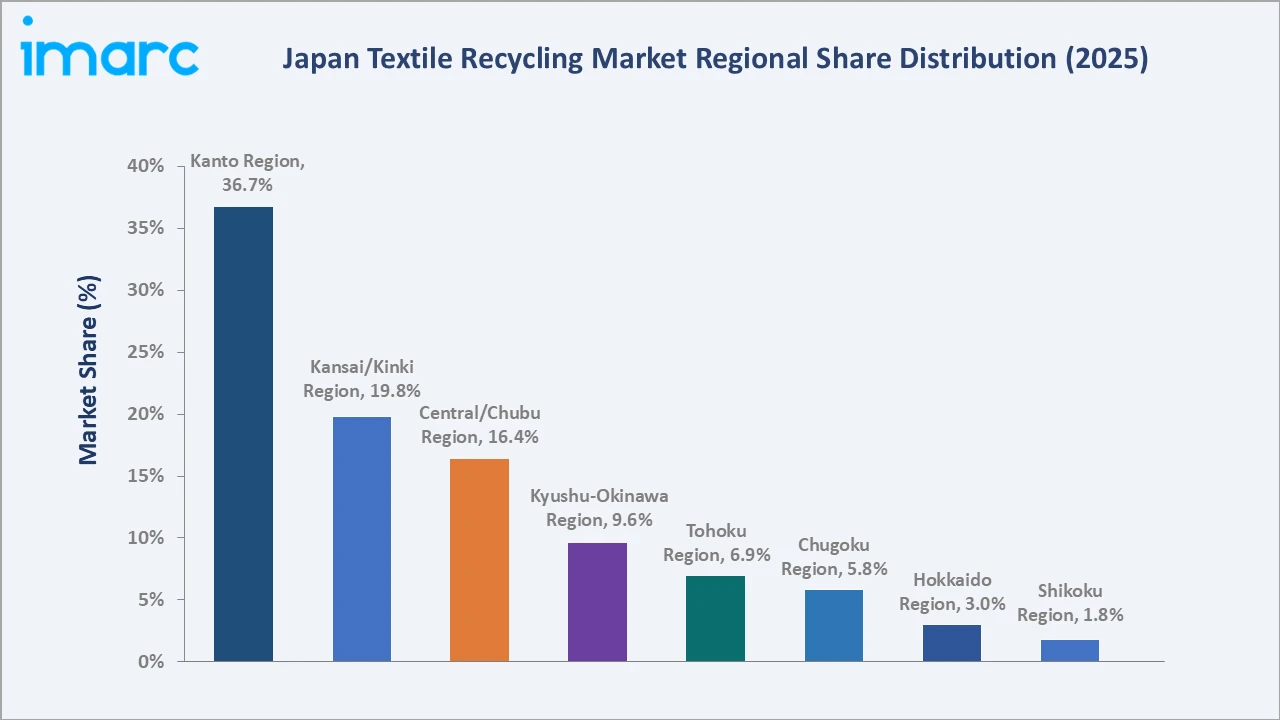
Many residents have convenient access to collection points. Dense urban infrastructure keeps collection costs low. The Kansai/Kinki Region's 19.8% reflects Osaka's textile trading base and strong retail networks.
The Central/Chubu Region's 16.4% reflects textile manufacturing clusters, while Kyushu-Okinawa's 9.6% benefits from chemical recycling in Kitakyushu. Tohoku at 6.9%, Chugoku at 5.8%, Hokkaido at 3.0%, and Shikoku at 1.8% are smaller but growing. Regional collection programs are expanding across these areas.
Municipal programs and local recyclers support collection in smaller cities. Kyushu also hosts advanced recycling facilities that attract feedstock nationally. Rural areas rely more on municipal and charity collection. Mobile collection services help reach remote communities. Collection costs remain higher in rural areas. Shared regional facilities could improve efficiency.
Public funding from national and prefectural governments may support these regional hubs and shared sorting facilities in future.
Competitive Landscape
The Japan textile recycling market includes chemical recyclers, fiber manufacturers, apparel retailers with take-back programs, and textile companies. Competition centers on recycling technology, fiber quality, collection networks, and brand partnerships. Retailers with large customer bases play an important role in collection.
Fiber manufacturers compete on quality and reliability of recycled materials. Collaboration is common even among competitors. Shared infrastructure can reduce costs for the whole industry. Industry associations coordinate standards and best practices. Shared data improves understanding of textile waste flows. Better data supports policy and investment decisions.
Government surveys on textile waste are becoming more detailed. These surveys help track progress toward national circular economy and recycling targets.
| Company | Key Brands | Market Position | Core Strength |
|---|---|---|---|
| Jeplan, Inc. | BRING | Market Leader | Chemical recycling of polyester textiles. |
| Teijin Limited | Teijin Frontier, ECOPET | Market Leader | Polyester chemical recycling and fibers. |
| Toray Industries, Inc. | Ecouse | Strong Challenger | Recycled fibers and garment recycling systems. |
| Fast Retailing Co., Ltd. | RE.UNIQLO | Strong Challenger | Large-scale garment take-back program. |
| Kurabo Industries Ltd. | L∞PLUS | Innovator | Cotton and fabric waste recycling. |
| Toyobo Co., Ltd. | Recycled Fibers | Niche Player | Recycled polyester for industrial use. |
| Unitika Ltd. | Recycled Polyester and Nylon | Niche Player | Recycled fibers and nonwovens. |
The most important competitive dynamic is scaling chemical textile-to-textile recycling. Companies with proprietary technology and strong brand partnerships are best placed to lead. Fiber makers are also developing recycled materials for industrial customers. Smaller recyclers focus on niche materials and local collection. Startups are developing new sorting and recycling technologies.
Key Company Profiles
Jeplan, Inc.
Jeplan, Inc. develops and operates chemical recycling technologies for packaging and textiles, with chemical recycling plants in Kawasaki and Kitakyushu.
- Key Brands: BRING, BRING Material.
- Recent Developments: In April 2026, JEPLAN and Syre announced a strategic partnership to accelerate commercialization of textile-to-textile polyester recycling.
- Strategic Focus: Scaling the Rewind PET process with AXENS and IFPEN for industrial chemical recycling of textile polyester.
Teijin Limited
Teijin Limited is a Japanese materials company whose fiber unit, Teijin Frontier, develops polyester fibers and chemical recycling technologies.
- Key Brands: Teijin Frontier, ECOPET.
- Recent Developments: In April 2026, Teijin Frontier developed a new stretch polyester yarn enabling 100% polyester textiles that are more readily recyclable.
- Strategic Focus: Licensing polyester chemical recycling technology through RePEaT Co., Ltd., a joint venture with JGC and ITOCHU.
Fast Retailing Co., Ltd.
Fast Retailing Co., Ltd. is the parent company of UNIQLO and GU and operates the RE.UNIQLO garment collection and recycling initiative.
- Key Brands: UNIQLO, GU, RE.UNIQLO.
- Recent Developments: In June 2026, UNIQLO launched a RE.UNIQLO garment collection pilot with recycling platform FeimaYi at four stores in China.
- Strategic Focus: Expanding product-to-product recycling, including recycled down jackets using an automated down-separation system developed by Toray Industries.
Market Concentration Analysis
The Japan textile recycling market is fragmented, with many collectors and small recyclers, while chemical recycling is concentrated among a few technology leaders.
Market concentration is increasing in chemical recycling as large companies form partnerships and scale up plants, while collection remains widely distributed. Partnerships between brands and recyclers are reshaping the landscape. International companies are also entering Japan through partnerships. Government support encourages new investment in recycling.
Market entry often requires local partners and feedstock agreements. Japan’s technology leadership attracts international interest. Joint ventures help foreign firms access Japanese expertise. Such collaborations accelerate the commercialization of new technologies.
Investment & Growth Opportunities
Highest Growth Segments
Polyester and polyester fiber recycling (~4.4% CAGR through chemical recycling), the online channel (~4.3% CAGR through resale platforms), the Central/Chubu Region (~4.0% CAGR through manufacturing clusters), and nylon recycling (~3.9% CAGR through industrial uses) represent the highest-growth investment areas through 2034.
Emerging Investment Opportunities
Automated sorting facilities and chemical recycling plants are among the most promising opportunities, improving fiber quality and recycling rates.
Investment Themes
- Chemical recycling: Produces virgin-quality recycled polyester.
- Collection networks: Brand and municipal programs increase feedstock.
Future Market Outlook (2026-2034)
The Japan textile recycling market is projected to grow from 142.8 Thousand Tons in 2025 to 148.4 Thousand Tons in 2026, reaching 200.9 Thousand Tons by 2034, registering a CAGR of 3.86% during 2026-2034.
The anchor value of 172.6 Thousand Tons in 2030 marks a point at which chemical recycling should operate at commercial scale. By then, fiber-to-fiber recycling should be more widely adopted by brands. Collection rates are expected to rise with policy support.
Three structural forces define Japan textile recycling market growth through 2034 sustainability commitments; policy support; and recycling technology advances. Together, these forces support steady growth across products and regions. Partnerships across the value chain will remain central to scaling recycling. Consumer participation will be essential for long-term success.
Policy clarity will help investors plan new projects. Clear targets would accelerate investment in collection and recycling. Policy discussions on textile targets are ongoing. Industry stakeholders are actively contributing to these discussions.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry stakeholders, including recyclers, fiber manufacturers, apparel brands, collectors, and municipal officials across Japan.
Secondary Research
Secondary research covered company press releases, government statistics, environmental reports, and industry publications. Over 50 credible secondary sources were reviewed, compared, and cross-checked for accuracy and consistency across datasets.
Forecasting Models
Market volume forecasts were developed using a supply-based model: textile waste generation by product type, channel, and region multiplied by collection and recycling rates, with segment results aggregated to total market volume. Assumptions were validated through detailed discussions with experienced industry experts, recyclers, and apparel brands across Japan.
Japan Textile Recycling Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Thousand Tons |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | Cotton Recycling, Wool Recycling, Polyester and Polyester Fiber Recycling, Nylon and Nylon Fiber Recycling, Others |
| Textile Wastes Covered | Pre-consumer Textile, Post-consumer Textile |
| Distribution Channels Covered | Online Channel, Retail and Departmental Store |
| End Users Covered | Apparel, Industrial, Home Furnishings, Non-woven, Others |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Jeplan, Inc., Teijin Limited, Toray Industries, Inc., Fast Retailing Co., Ltd., Kurabo Industries Ltd., Toyobo Co., Ltd., Unitika Ltd., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan textile recycling market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan textile recycling market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan textile recycling industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Textile Recycling Market Report
The market volume is estimated at 148.4 Thousand Tons in 2026, supported by corporate sustainability goals, government circular economy policies, expanding brand take-back programs, and new chemical recycling capacity for polyester textiles.
The market grows at 3.86% CAGR during 2026-2034, reaching 200.9 Thousand Tons by 2034. Steady growth reflects rising collection rates, scale-up of fiber-to-fiber recycling, and increasing use of recycled fibers by apparel, home textile, and industrial manufacturers.
Polyester and polyester fiber recycling leads at 38.9%. Polyester is the most widely used fiber in Japanese apparel and home textiles, and both mechanical and chemical recycling technologies for it are well established, enabling high-quality recycled fiber production.
The online channel leads at 54.3%, driven by resale and take-back platforms and e-commerce sales of recycled products.
The Kanto Region leads at 36.7%, driven by Tokyo’s large population, high apparel consumption, and concentration of brands, retailers, and recyclers.
Leading companies include Jeplan, Inc., Teijin Limited, Toray Industries, Inc., Fast Retailing Co., Ltd., Kurabo Industries Ltd., Toyobo Co., Ltd., and Unitika Ltd., among others.
The market is projected to reach approximately 172.6 Thousand Tons by 2030. By then, chemical textile-to-textile recycling is expected to operate at commercial scale, and fiber-to-fiber recycling should be more widely adopted by apparel brands across Japan.
Key trends include chemical textile-to-textile recycling moving to industrial scale, expansion of brand take-back programs, fiber-to-fiber partnerships between recyclers and global brands, and design for recyclability through mono-material fabrics.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade