Japan Wellness Tourism Market Size, Share, Trends and Forecast by Travelers Type, Service Type, Location, and Region, 2026-2034
Japan Wellness Tourism Market Size, Share, Trends & Forecast (2026-2034)
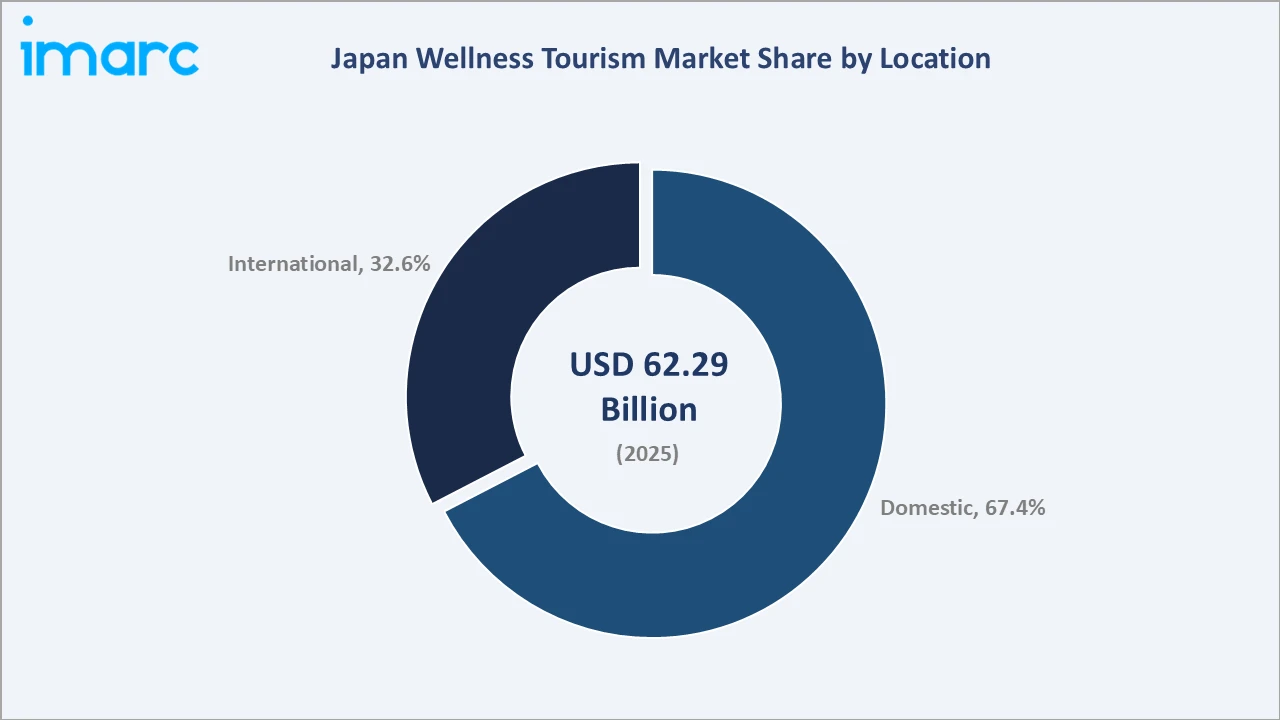
The Japan wellness tourism market grew from USD 62.29 Billion in 2025 to USD 65.50 Billion in 2026 and is projected to reach USD 97.89 Billion by 2034, growing at a CAGR of 5.15% during 2026-2034. The market is driven by rising global interest in traditional Japanese therapeutic practices including onsen thermalism, shiatsu massage, and shinrin-yoku forest bathing. Domestic tourism dominates at 67.4%. Kanto Region leads regionally at 35.8%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 62.29 Billion |
|
Market Size (2026) |
USD 65.50 Billion |
|
Forecast Market Size (2034) |
USD 97.89 Billion |
|
CAGR (2026-2034) |
5.15% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Location |
Domestic (67.4%, 2025) |
|
Dominant Travelers Type |
Primary (62.7%, 2025) |
|
Leading Region |
Kanto Region (35.8%, 2025) |
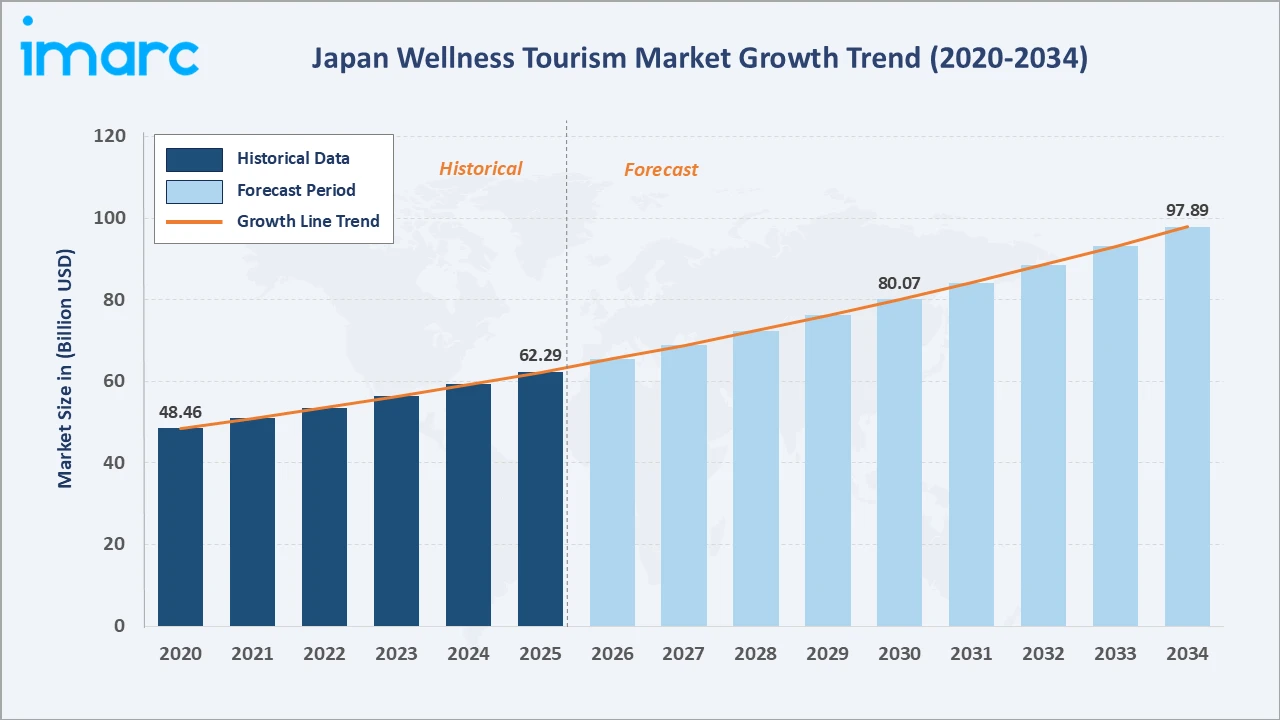
The Japan wellness tourism market size increased from USD 48.46 Billion in 2020 to USD 62.29 Billion in 2025 and is estimated to reach USD 65.50 Billion in 2026. The market is further expected to grow to USD 80.07 Billion by 2030 and USD 97.89 Billion by 2034. Japan wellness tourism is commercially unique among global wellness markets, combining one of Asia’s deepest traditional therapeutic infrastructures with rising international traveler demand and a structurally stable aging domestic consumer base.
To get more information on this market, Request Sample
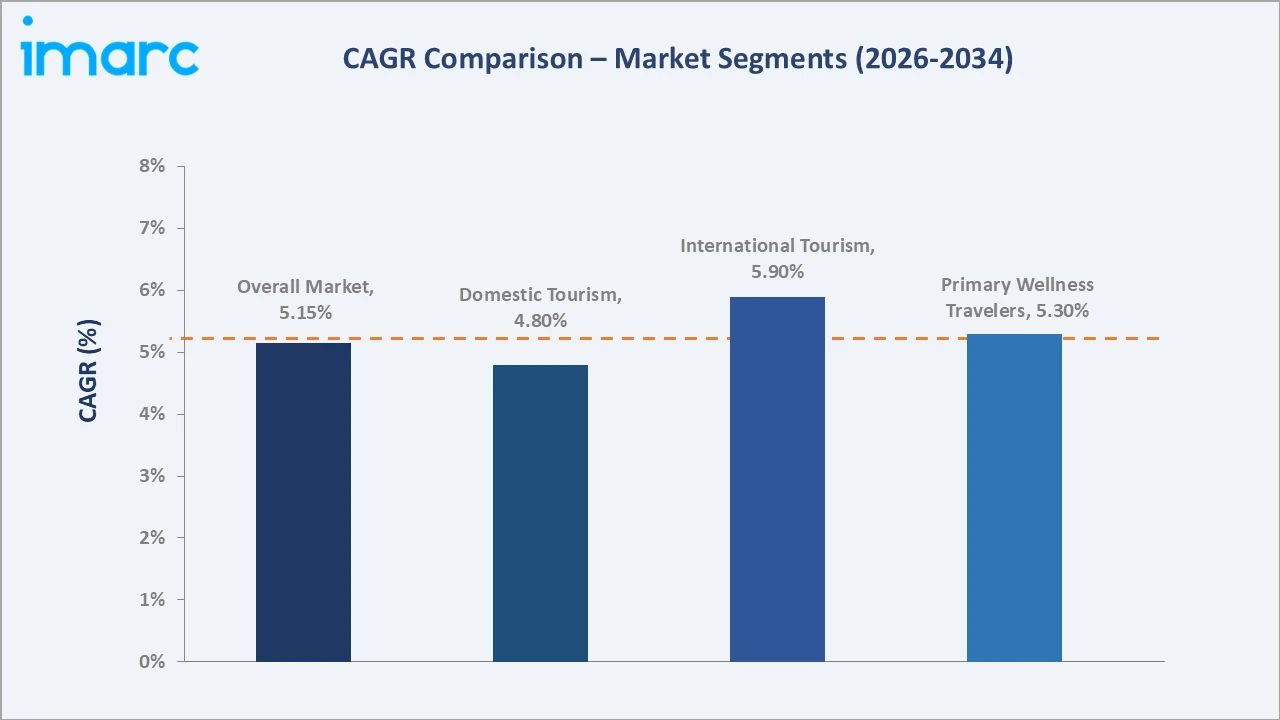
International wellness tourism grows fastest at ~5.90% CAGR through rising global awareness of Japan’s authentic therapeutic offerings. Primary wellness travelers expand at ~5.30% CAGR driven by dedicated health-seeking tourists, while secondary travelers grow at ~4.85% CAGR through wellness-integrated general tourism packages.
Executive Summary
The Japan wellness tourism market expanded from USD 62.29 Billion in 2025 to an estimated USD 65.50 Billion in 2026, positioning Japan as Asia’s leading wellness destination. The market is underpinned by traditional therapeutic offerings including over 27,000 registered onsen facilities, centuries-old shiatsu therapy traditions, and globally recognized shinrin-yoku forest bathing practices.
These structural assets create a wellness tourism proposition unmatched globally. The market is projected to reach USD 97.89 Billion by 2034 at 5.15% CAGR. Domestic tourism leads at 67.4%. Primary wellness travelers dominate at 62.7%. The Kanto Region commands 35.8% of national market share.
Key Market Insights
|
Insight |
Data |
|
Dominant Location |
Domestic – 67.4% share (2025) |
|
Dominant Travelers Type |
Primary – 62.7% market share (2025) |
|
Leading Region |
Kanto Region – 35.8% share (2025) |
|
Market Opportunity |
International wellness retreat packages; corporate wellness tourism; digital-detox retreats; onsen spa resort expansion |
Key Analytical Observations Supporting the Above Data:
- Domestic at 67.4%: The domestic segment dominates due to Japan’s deeply embedded cultural tradition of wellness travel.
- Primary Travelers at 62.7%: Primary wellness travelers lead as dedicated health seekers plan Japan trips specifically for therapeutic purposes, demonstrating higher per-trip spending and supporting premium wellness resort revenue across all regions.
- Kanto Region at 35.8%: The Kanto Region leads through Tokyo’s premium wellness facility concentration, Hakone’s renowned onsen resort cluster, and superior international transport connectivity driving both domestic and inbound wellness tourism demand.
Japan Wellness Tourism Market Overview
Japan wellness tourism market occupies a globally unique position, combining ancient therapeutic traditions with modern wellness science across an exceptionally diverse natural landscape. The market integrates traditional ryokan culture, modern spa resorts, nature-immersive retreat programs, and a growing medical wellness tourism segment serving Japan’s aging domestic population.
Japan’s wellness ecosystem encompasses onsen thermalism, forest therapy, traditional medicine (kampo), mindfulness meditation, and yoga retreats distributed across distinct regional wellness clusters. JNTO promotion and regional wellness tourism route development strengthen Japan’s competitive position as Asia’s premier wellness destination.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
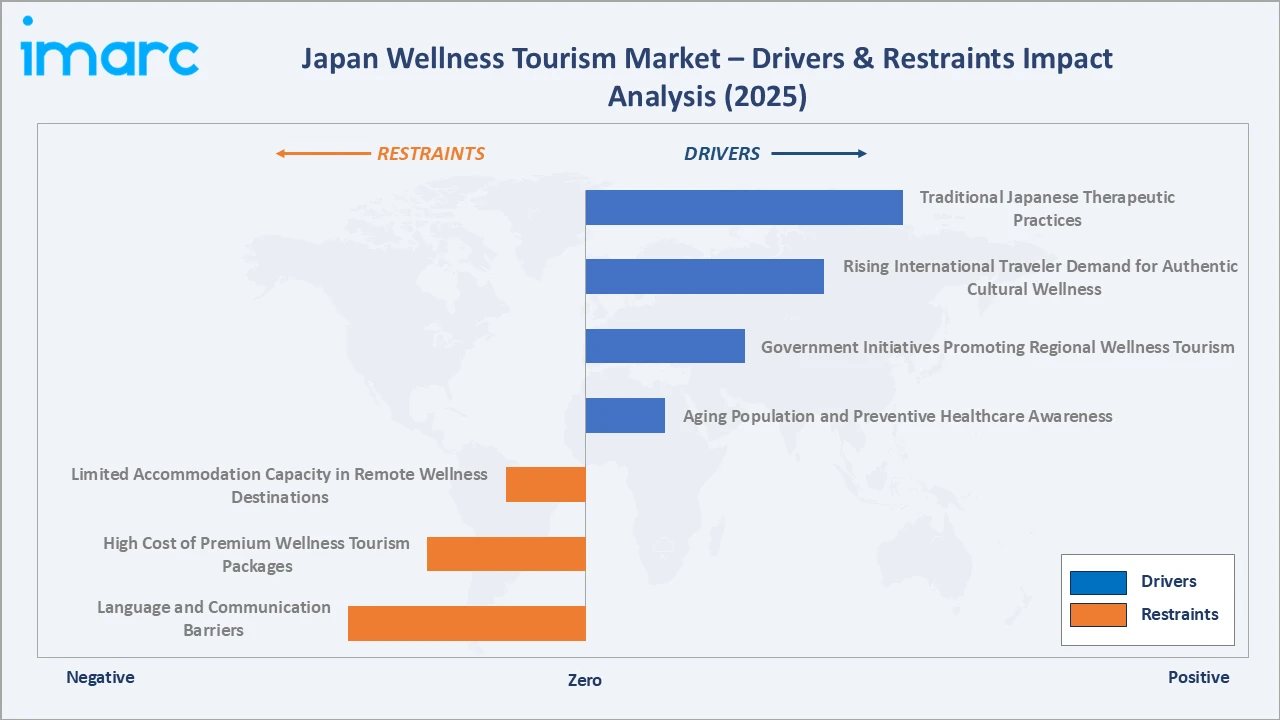
- Traditional Japanese Therapeutic Practices: Japan’s traditional practices create a globally distinctive wellness tourism product. Onsen thermalism, shiatsu massage, shinrin-yoku forest bathing, and kampo herbal medicine are integrated into modern wellness programs. Japan’s approximately 27,000 registered onsen facilities represent unmatched wellness tourism infrastructure that no competitor destination can replicate, creating a durable structural market advantage. Government-certified shinrin-yoku therapy bases, now exceeding 65 across the country, further validate Japan’s therapeutic wellness credentials at an institutional level, attracting health-focused international travelers and domestic wellness repeat visitors seeking evidence-based therapeutic experiences.
- Rising International Traveler Demand for Authentic Cultural Wellness: International travelers increasingly seek authentic cultural wellness beyond conventional spa tourism. Japan’s fusion of spiritual wellness (Zen meditation, temple stays), physical therapy (onsen, shiatsu), and nature immersion (shinrin-yoku) provides a multi-dimensional experience unavailable elsewhere. Rising wellness tourism spending from South Korean, Chinese, Australian, and European travelers is creating diverse international demand streams across Japan’s regional wellness destinations, reducing dependence on single-source market segments and improving resilience.
- Government Initiatives Promoting Regional Wellness Tourism: Japan’s Ministry of Land, Infrastructure, Transport and Tourism and JNTO actively promote wellness tourism through the “Stay Longer” campaign, regional wellness route development, and subsidized infrastructure grants. These programs increase accommodation capacity, extend tourist stays, and redistribute wellness tourism revenue to economically underdeveloped rural onsen regions. Prefectural governments in Akita, Aomori, and Yamagata have developed dedicated wellness tourism promotion budgets targeting domestic visitors, while national digital tourism platforms are improving international booking accessibility for regionally distributed wellness destinations beyond established gateway cities.
- Aging Population and Preventive Healthcare Awareness: Japan’s aging population, with over 29% of citizens aged 65 or above, generates substantial domestic wellness tourism demand for preventive healthcare-oriented travel. Older Japanese consumers actively seek onsen therapy, wellness spa programs, and medical wellness retreats, creating a structurally stable domestic demand base independent of inbound tourism fluctuations. The growth of kampo-integrated wellness retreat programs tailored for senior travelers, offered by ryokan operators in partnership with licensed traditional medicine practitioners, is expanding Japan’s domestic wellness tourism addressable market and generating above-average per-stay revenue from health-motivated senior guests.
Market Restraints
- Limited Accommodation Capacity in Remote Wellness Destinations: Remote wellness destinations, particularly heritage onsen towns such as Kinosaki, Nyuto Onsen, and Nozawa Onsen, face accommodation capacity constraints limiting visitor volume during peak seasons. Many traditional ryokan operate at small scale, creating supply-demand imbalances. Capacity expansion faces challenges from regulatory restrictions on new construction in historically sensitive zones. The shortage of trained ryokan hospitality staff across rural destinations further constrains operational capacity expansion, as traditional ryokan hospitality requires specialized cultural service skills with a multi-year training pipeline that limits rapid workforce scaling to meet rising visitor demand.
- High Cost of Premium Wellness Tourism Packages: Premium Japanese wellness tourism packages, particularly luxury ryokan experiences combining kaiseki dining, private onsen access, and therapeutic treatments, restrict market accessibility. Per-night rates at leading wellness properties can exceed USD 500–1,000, limiting demand to high-income domestic and international travelers. Currency exchange rate volatility further affects affordability for international travelers from markets with weakening currencies against the Japanese yen, periodically suppressing inbound wellness tourism demand from price-sensitive Southeast Asian markets despite strong underlying interest in Japan wellness experiences at accessible price points.
- Language and Communication Barriers: Language barriers at traditional ryokan, rural onsen facilities, and small wellness retreat operators remain a significant challenge for non-Japanese-speaking international travelers. Limited English-language booking systems, menu translations, and staff communication at regional destinations reduce commercial capture of inbound wellness demand, particularly from Western markets. Digital translation technology adoption rates remain low among small-scale ryokan operators in rural regions, where investment in international digital booking infrastructure competes with pressing property maintenance and service quality priorities, limiting near-term international accessibility improvement without targeted government support programs.
Market Opportunities
- International Wellness Retreat Package Development: Growing international awareness of Japan’s wellness credentials creates opportunity for packaged multi-destination wellness itineraries combining onsen thermalism, forest therapy, and cultural wellness immersion. Premium international travel agencies and destination management companies are developing Japan-specific wellness programs targeting high-spending Western and Southeast Asian travelers. The convergence of Japan’s certified forest therapy infrastructure, recognized onsen therapeutic benefits, and unique cultural wellness assets into commercially structured international packages represents a commercially underdeveloped opportunity, particularly for partnerships between Japanese wellness operators and global wellness travel platforms with established international client acquisition networks.
- Corporate Wellness Tourism Expansion: Japan’s rising corporate wellness culture is driving demand for executive wellness retreat programs, corporate mindfulness training in temple environments, and incentive travel packages. This segment offers higher per-participant revenue, off-peak demand smoothing, and organizational purchase cycles that reduce individual booking seasonality dependence. Corporate wellness retreat programs at Kyoto temple complexes and Hakone onsen resorts targeting Japanese and multinational company executive teams represent an emerging revenue stream with documented willingness to pay premium pricing, supporting above-market-average revenue per occupied room and multi-day stay patterns that improve regional wellness destination revenue density.
Market Challenges
- Seasonal Demand Concentration: Japan wellness tourism faces pronounced seasonal demand concentration during cherry blossom and autumn foliage seasons, generating extreme accommodation demand peaks while winter and summer shoulder periods see significant demand reduction at many regional wellness destinations. This seasonality creates operational inefficiency and revenue volatility for wellness operators. Small-scale ryokan operators particularly struggle to maintain full-year financial viability under extreme seasonal demand fluctuations, as fixed operational costs including traditional property maintenance and year-round staffing commitments cannot be reduced proportionally to off-peak revenue declines, creating structural profitability challenges that constrain investment capacity for property improvement and international marketing development.
- Infrastructure Gaps in Regional Destinations: Regional wellness destinations outside major metropolitan areas face infrastructure gaps in international transport connectivity, English-language tourism support, and digital payment systems. These access frictions limit commercial development of Japan’s regionally distributed wellness tourism assets beyond established gateway destinations. Last-mile transport connectivity between regional rail stations and remote onsen destination ryokan clusters remains inadequate for international travelers unfamiliar with Japanese rural transport logistics, creating a practical accessibility barrier that suppresses commercial conversion of wellness destination interest into confirmed bookings and completed visits despite rising international awareness and stated wellness travel intent.
Emerging Market Trends
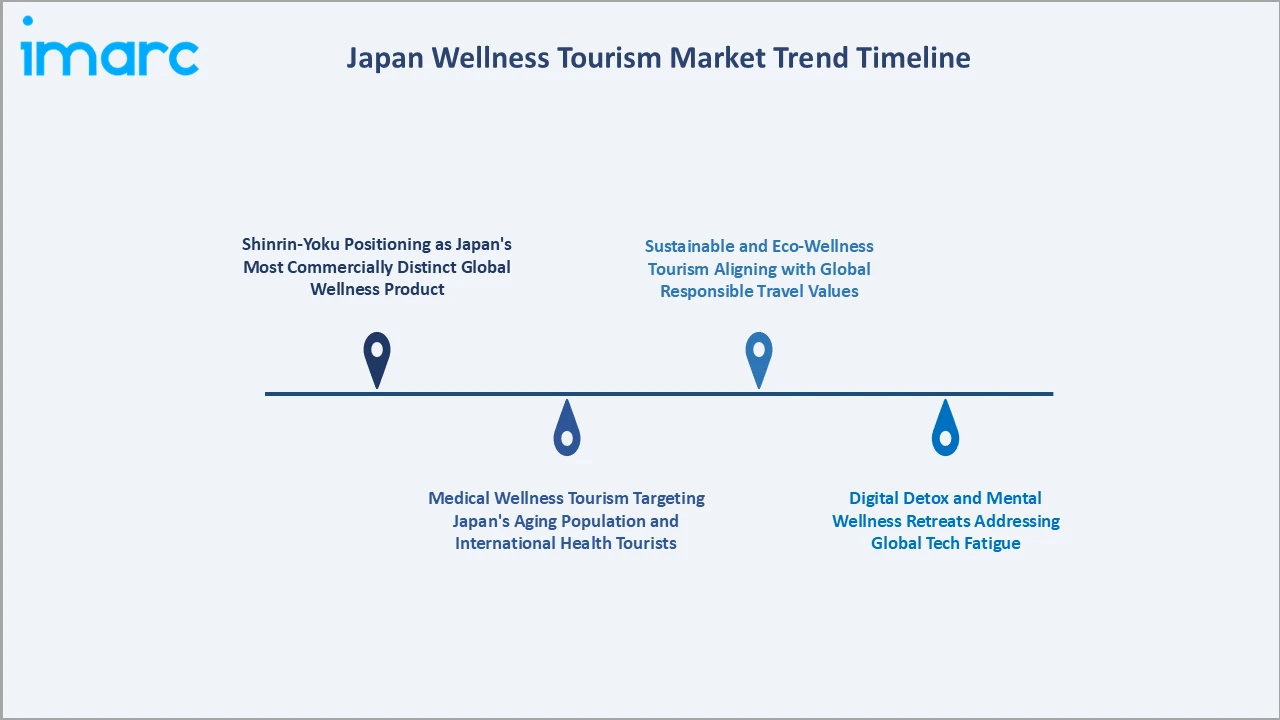
1. Shinrin-Yoku Positioning as Japan’s Most Commercially Distinct Global Wellness Product
Shinrin-yoku’s scientific validation through government-funded research has created a globally recognized therapeutic practice commercialized as a premium wellness tourism product. Major resorts integrate certified forest therapy guides, dedicated forest therapy trails, and nature-immersive programs, positioning Japan’s 67% forest coverage as commercially exploitable wellness infrastructure.
2. Medical Wellness Tourism Targeting Japan’s Aging Population and International Health Tourists
Medical wellness tourism combining traditional Japanese medicine (kampo) with modern preventive health diagnostics is emerging as Japan’s highest-growth niche. Onsen-adjacent medical facilities and preventive health screening programs target Japan’s senior population and health-conscious international travelers, creating a commercially distinct and premium-revenue segment.
3. Digital Detox and Mental Wellness Retreats Addressing Global Tech Fatigue
Technology professionals and urban knowledge workers globally are generating demand for structured digital detox wellness retreats at temple complexes, rural ryokan, and mountain retreat centers. Japan’s Zen Buddhist monastery stays, remote mountain wellness retreats, and traditional craft immersion programs position Japan uniquely for the premium mental wellness tourism segment.
4. Sustainable and Eco-Wellness Tourism Aligning with Global Responsible Travel Values
Sustainable wellness tourism demand from environmentally conscious international travelers is driving investment in eco-certified ryokan, organic local food wellness programs, and carbon-minimal nature therapy retreat operations. Japan’s existing regulatory framework for onsen water quality and natural landscape preservation provides a credible sustainability positioning platform.
Industry Value Chain Analysis
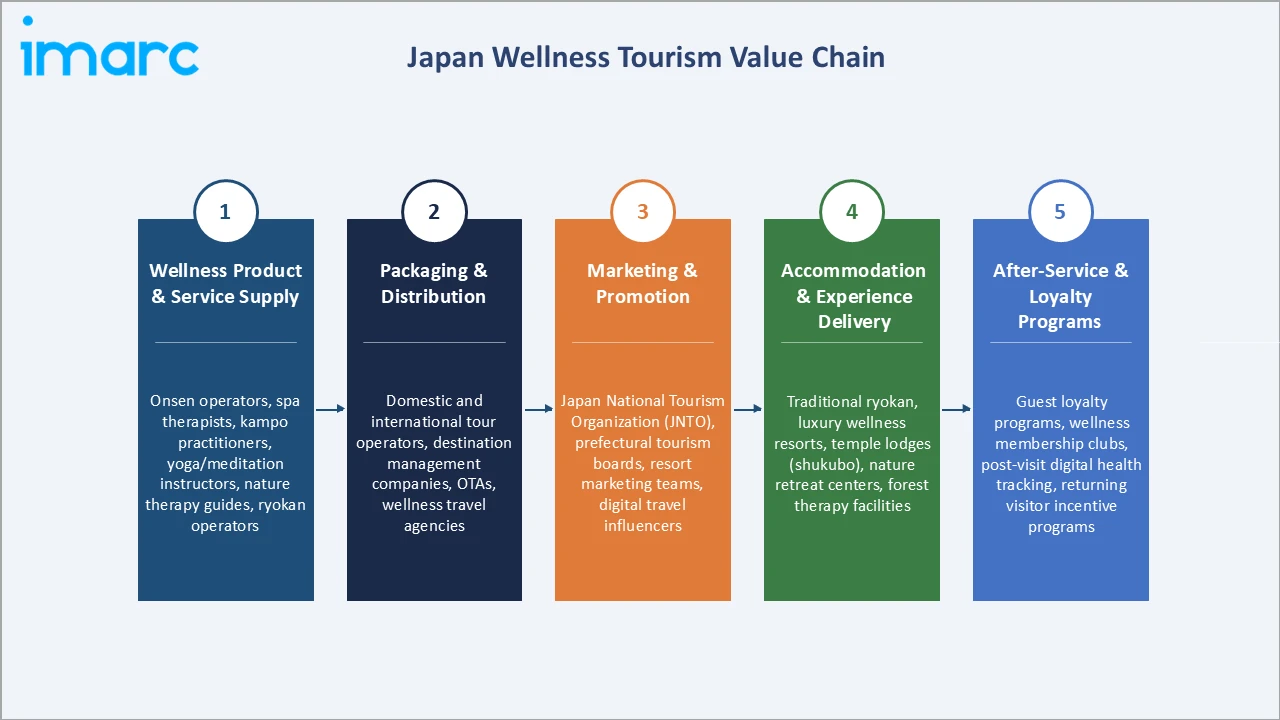
| Stage | Key Participants |
|---|---|
| Wellness Product & Service Supply | Onsen operators, spa therapists, kampo practitioners, yoga/meditation instructors, nature therapy guides, ryokan operators |
| Packaging & Distribution | Domestic and international tour operators, destination management companies, OTAs, wellness travel agencies |
| Marketing & Promotion | Japan National Tourism Organization (JNTO), prefectural tourism boards, resort marketing teams, digital travel influencers |
| Accommodation & Experience Delivery | Traditional ryokan, luxury wellness resorts, temple lodges (shukubo), nature retreat centers, forest therapy facilities |
| After-Service & Loyalty Programs | Guest loyalty programs, wellness membership clubs, post-visit digital health tracking, returning visitor incentive programs |
Japan’s wellness tourism value chain is distinguished by the exceptional depth of its traditional therapeutic service supply layer, where centuries-old onsen operators, licensed shiatsu therapists, and certified forest therapy guides create an authentic wellness product foundation that international competitors cannot replicate through facility investment alone.
Technology Landscape in the Japan Wellness Tourism Industry
Digital Health Integration in Wellness Tourism
Digital health monitoring technology integration into wellness tourism programs is enabling personalized wellness itinerary development. Onsen resort operators are deploying wearable health data analysis to customize thermal therapy protocols, while AI-powered wellness recommendation engines match therapeutic programs with individual guest health objectives.
Online Travel Agency (OTA) and Wellness Platform Technology
Wellness-specific booking platforms and OTA wellness category development are increasing Japan wellness tourism’s accessibility for international travelers. Global wellness travel platforms enable direct discovery of Japan’s regional wellness accommodations, expanding market reach beyond Japanese-language booking channels.
Immersive Technology for Cultural Wellness Experience Delivery
Virtual reality temple meditation experiences, augmented reality guided forest therapy trail navigation, and multilingual AI translation services at traditional ryokan are reducing international traveler access barriers. These technologies extend Japan’s wellness tourism commercial reach into non-Japanese-speaking markets while preserving authentic therapeutic experience quality.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Location | Domestic | 67.4% | 2025 |
| Travelers Type | Primary | 62.7% | 2025 |
| Service Type | 🔒 | 🔒 | 2025 |
| Region | Kanto Region | 35.8% | 2025 |

By Location
Domestic wellness tourism leads at 67.4% (2025), reflecting Japan’s deeply embedded cultural tradition of wellness travel as both therapeutic practice and seasonal lifestyle activity. The domestic segment’s commercial foundation rests on Japan’s extraordinary concentration of accessible onsen facilities across all 47 prefectures.
To access detailed market analysis, Request Sample
International wellness tourism at 32.6% is growing at ~5.90% CAGR through rising global awareness of Japan’s wellness credentials. International travelers demonstrate significantly higher per-trip spending, making this segment commercially disproportionate to its volume share in supporting premium wellness resort and ryokan revenue.
By Travelers Type
Primary wellness travelers lead at 62.7% (2025). These travelers plan Japan trips specifically for wellness purposes, selecting destinations, accommodations, and itineraries based on therapeutic program quality and authentic cultural wellness access, generating above-average per-trip revenue for premium wellness operators.
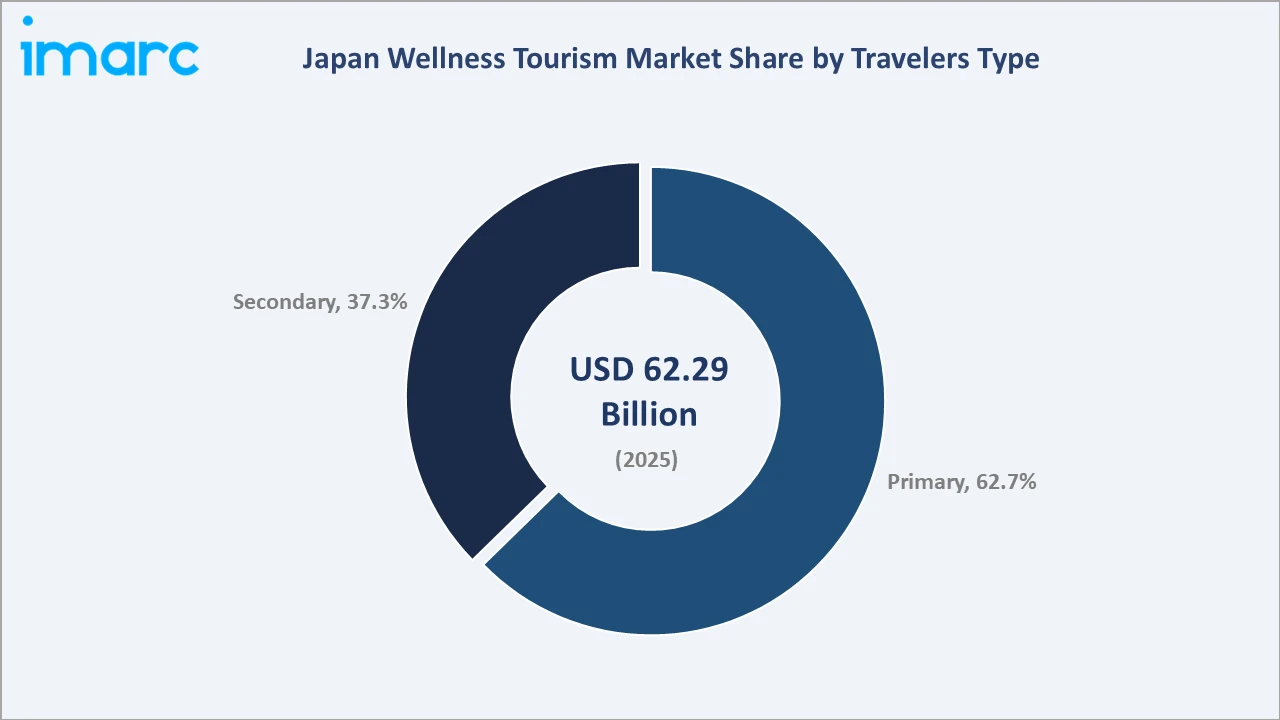
Secondary wellness travelers at 37.3% incorporate wellness activities as complementary elements of broader Japan tourism itineraries. This segment represents significant commercial opportunity as wellness program add-on sales at conventional accommodations, with hotel spa revenue and onsen day-trip packages capturing secondary wellness demand.
Regional Market Insights
|
Region |
Share (2025) |
Key Japan Wellness Tourism Market Drivers & Characteristics |
|
Kanto Region |
35.8% |
Driven by Tokyo’s premium wellness facilities, Hakone’s onsen resorts, and superior transport connectivity. |
|
Kansai/Kinki Region |
21.6% |
Led by Kyoto’s cultural wellness heritage (temple retreats, traditional ryokan) and Osaka’s hospitality infrastructure. |
|
Central/Chubu Region |
13.7% |
Benefits from Nagano’s mountain wellness retreats, alpine forest therapy trails, and scenic onsen destinations near the Japan Alps. |
|
Kyushu-Okinawa Region |
9.8% |
Combines Beppu’s globally recognized onsen cluster with Okinawa’s tropical wellness and longevity tourism appeal. |
|
Tohoku Region |
7.2% |
Growing through government-supported regional wellness development and authentic onsen heritage destination promotion. |
|
Chugoku Region |
5.1% |
Supported by nature-immersive retreat experiences and regional wellness tourism development initiatives. |
|
Hokkaido Region |
4.2% |
Known for nature wellness, winter thermal spa, agricultural wellness, and Ainu cultural wellness tourism experiences. |
|
Shikoku Region |
2.6% |
Emerging wellness destination anchored by the 88-temple pilgrimage circuit combining spiritual wellness with active tourism. |
The Kanto Region’s 35.8% market leadership reflects Tokyo’s concentration of premium urban wellness facilities, Hakone’s internationally recognized onsen resort cluster, and the region’s superior transport connectivity enabling both day-trip and multi-night wellness stays. International arrivals to Tokyo serve as the primary gateway for inbound wellness tourism.
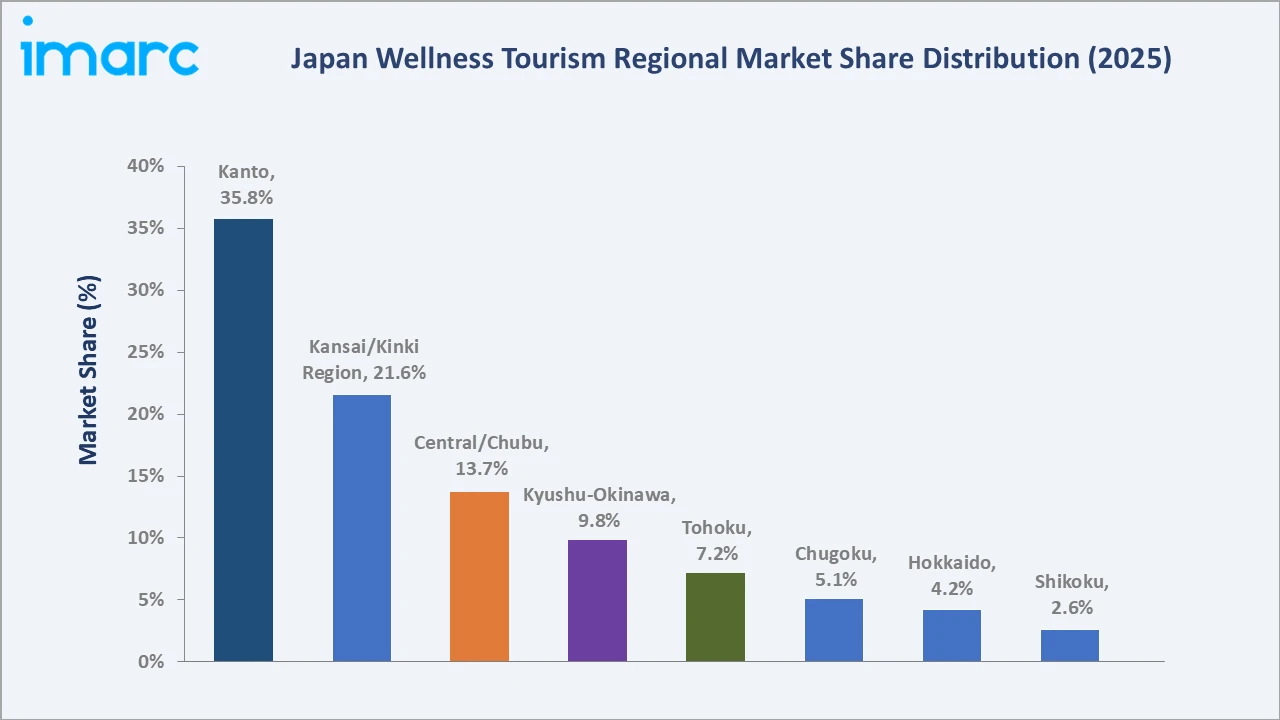
The Kansai/Kinki Region’s 21.6% reflects Kyoto’s global recognition as Japan’s cultural heritage center, supporting premium wellness tourism built around temple meditation retreats, traditional ryokan, and Arashiyama forest therapy. Kyushu-Okinawa’s 9.8% combines Beppu’s world-famous hot spring cluster with Okinawa’s tropical longevity tourism appeal.
Competitive Landscape
Japan wellness tourism market’s competitive landscape features coexistence of traditional Japanese hospitality operators and international luxury hospitality brands competing for premium wellness tourism market share.
| Company | Key Brands | Market Position | Core Strength |
|---|---|---|---|
| Hoshino Resorts Inc. | HOSHINOYA, KAI, RISONARE, OMO, BEB | Market Leader | Pioneered the transformation of traditional Japanese ryokan culture into internationally accessible luxury wellness hospitality. |
| Hyatt Corporation | Park Hyatt, Grand Hyatt, Hyatt Regency | Strong Challenger | Operates wellness-positioned luxury properties in Tokyo, Kyoto, and Osaka, integrating Japanese therapeutic elements into its global spa programs. |
| Marriott International, Inc. | The Ritz-Carlton, Westin, Sheraton, W Hotels | Strong Challenger | Maintains significant Japan presence with wellness-focused programs integrating shiatsu, yuzu botanical treatments, and meditation across major properties. |
| InterContinental Hotels Group | InterContinental, ANA Crowne Plaza | Strong Challenger | Commands broad Japan coverage through its ANA partnership, serving both wellness-focused business and leisure travelers across major destinations. |
| Aman Group S.a.r.l. | Aman Tokyo, Amanemu | Innovator | Operates Amanemu in Ise-Shima, Japan’s premier luxury onsen wellness resort, featuring traditional Japanese thermal bathing and curative hot spring programs. |
| Banyan Group | Banyan Tree | Challenger | Expanding Japan wellness resort portfolio leveraging its established Asian wellness hospitality brand and holistic spa therapy expertise. |
Key players include Hoshino Resorts Inc., Hyatt Corporation, Marriott International, Inc., InterContinental Hotels Group, Aman Group S.a.r.l., Banyan Group, and others.
Key Company Profiles
Hoshino Resorts Inc.
Hoshino Resorts Inc. is Japan’s leading multi-brand resort operator and wellness tourism market leader, operating over 60 properties across five brand families targeting distinct wellness traveler segments from ultra-luxury to budget-conscious domestic travelers.
- Key Brands: HOSHINOYA (ultra-luxury), KAI (onsen ryokan), RISONARE (resort), OMO (urban hotel), BEB (casual stay).
- Recent Developments: In April 2025, Hoshino Resorts announced expansion of its KAI onsen ryokan brand with new properties in Kusatsu and Kinosaki, Japan’s most celebrated onsen towns, targeting both domestic and international wellness travelers seeking authentic traditional Japanese hot spring experiences.
- Strategic Focus: Maintaining domestic wellness resort market leadership while expanding international brand recognition through HOSHINOYA global properties and a planned New York onsen retreat, positioning Japanese wellness hospitality standards internationally. Hoshino Resorts is investing in multilingual digital booking platform development to improve international traveler conversion rates for its regional wellness properties.
Hyatt Corporation
Hyatt Corporation operates luxury wellness-positioned properties in Japan through its Park Hyatt, Grand Hyatt, and Alila brands, with flagship properties in Tokyo, Kyoto, and Osaka serving both corporate and leisure wellness travelers seeking premium Japanese experiences.
- Key Brands: Park Hyatt, Grand Hyatt, Alila, Hyatt Regency.
- Recent Developments: In October 2024, Hyatt Regency Hakone Resort and Spa launched the “YON-KA Phyto Sleep Ritual” at its Spa IZUMI, integrating French phytotherapy with Japanese onsen therapy to create a differentiated wellness program targeting international travelers seeking premium cultural wellness experiences.
- Strategic Focus: Expanding wellness program offerings at Japan properties through premium spa partnerships, treatment development, and wellness-integrated accommodation packages targeting global high-income wellness travelers.
Market Concentration Analysis
Japan wellness tourism market is moderately concentrated, with traditional domestic operators including Hoshino Resorts, Inc. and family-operated ryokan chains commanding significant regional positions, while international luxury brands maintain meaningful premium market share through globally recognized wellness hospitality brands.
Market concentration varies significantly by segment. Traditional onsen ryokan accommodation shows high regional concentration among heritage operators in established onsen towns, while urban wellness spa facilities show lower concentration through competition between hotel spa operators, standalone wellness centers, and integrated wellness retail chains.
Investment & Growth Opportunities
Highest Growth Segments
International tourism leads growth at 5.9% CAGR through the forecast period, followed by primary travelers at 5.3% and secondary travelers at 4.85%. The overall market is projected to grow at 5.15% CAGR, while domestic tourism records a comparatively lower growth rate of 4.8%. This outlook highlights stronger expansion in international wellness tourism, supported by rising global interest in India's wellness offerings, while primary travelers contribute to growth through dedicated wellness-focused trips.
Emerging Investment Opportunities
Japan’s medical wellness tourism segment, combining preventive health diagnostics, kampo herbal medicine treatment, and onsen hydrotherapy at licensed medical wellness facilities, represents the highest-growth commercial opportunity. International medical wellness travelers from China, South Korea, and Southeast Asia create above-average per-visit revenue exceeding conventional wellness tourism.
Investment Themes
- Regional Wellness Infrastructure Investment in Underserved Rural Onsen Destinations: Japan’s rural onsen towns represent significantly underserved wellness destinations with authentic product credentials but inadequate international booking accessibility, accommodation capacity, and multilingual service capability.
- Premium International Wellness Package Development Targeting Asia-Pacific and Western Markets: Japan’s wellness tourism opportunity from premium international packaged wellness experiences remains commercially underdeveloped relative to destination reputation.
Future Market Outlook (2026-2034)
The Japan wellness tourism market is projected to grow from USD 62.29 Billion in 2025 to USD 65.50 Billion in 2026, reaching USD 97.89 Billion by 2034, registering a CAGR of 5.15% during 2026-2034. The milestone value of USD 80.07 Billion in 2030 reflects Japan’s structural wellness tourism growth supported by aging population demand.
Three structural forces define Japan wellness tourism growth through 2034: Japan’s aging domestic population creating stable preventive wellness travel demand; rising global recognition of Japan’s traditional therapeutic practices attracting premium international wellness travelers; and government-supported regional wellness tourism development redistributing growth beyond the Kanto and Kansai clusters.
Research Methodology
Primary Research
Primary research comprised structured interviews with Japan wellness tourism industry stakeholders including resort directors, wellness program managers, regional tourism board officials, onsen facility operators, traditional medicine practitioners, and consumer survey data from domestic and international Japan wellness tourists across multiple regions.
Secondary Research
Secondary research encompassed Japan Tourism Agency statistical data, JNTO inbound tourism reports, wellness resort operator annual reports, Japan medical wellness tourism industry publications, prefectural tourism promotional data, and OTA booking trend analysis. Over 50 secondary sources reviewed for comprehensive market coverage.
Forecasting Models
Market revenue forecasts were developed using a regional accommodation capacity model: Japan’s wellness accommodation inventory by region multiplied by average occupancy rates, average daily rate per segment, and wellness program attachment rates, creating total market revenue through segment and regional aggregation.
Japan Wellness Tourism Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Travelers Type Covered | Primary, Secondary |
| Service Types Covered | Transport, Lodging, Food and Beverage, Shopping, Activities and Excursion, Others |
| Locations Covered | Domestic, International |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Hoshino Resorts Inc., Hyatt Corporation, Marriott International, Inc., InterContinental Hotels Group, Aman Group S.a.r.l., Banyan Group, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan wellness tourism market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan wellness tourism market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan wellness tourism industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Wellness Tourism Market Report
Japan wellness tourism market size is estimated at USD 65.50 Billion in 2026, driven by Japan’s globally distinctive traditional therapeutic practices, government wellness tourism promotion, rising international wellness traveler demand, and Japan’s large aging domestic population seeking preventive healthcare-oriented wellness travel.
Japan wellness tourism market grows at 5.15% CAGR during 2026-2034, reaching USD 97.89 Billion by 2034. Growth is sustained by international wellness traveler demand expansion, aging population healthcare demand, government regional wellness tourism development, and rising global recognition of Japanese therapeutic practices.
Domestic wellness tourism leads at 67.4% through Japan’s deeply embedded cultural tradition of wellness travel, with over 27,000 registered onsen facilities providing nationally distributed wellness tourism infrastructure supporting year-round domestic wellness demand across all 47 prefectures.
Primary wellness travelers lead at 62.7% through Japan’s globally distinctive wellness destination appeal attracting dedicated wellness seekers who specifically plan Japan trips for therapeutic purposes, generating above-average per-trip revenue for premium wellness operators and resort destinations.
Kanto Region leads at 35.8% through Tokyo’s premium wellness facility concentration, Hakone’s internationally recognized onsen resort cluster, and the region’s superior international transport connectivity driving both domestic and inbound wellness tourism demand as Japan’s primary gateway region.
Leading companies include Hoshino Resorts Inc., Hyatt Corporation, Marriott International, Inc., InterContinental Hotels Group, Aman Group S.a.r.l., Banyan Group, and others.
Japan wellness tourism market is projected to reach approximately USD 80.07 Billion by 2030, with medical wellness tourism growing as Japan’s healthcare tourism infrastructure develops, international wellness traveler arrivals expanding, and government regional wellness destination development programs unlocking underdeveloped prefectural markets.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade