Mexico Automotive Plastics Market Size, Share, Trends and Forecast by Vehicle Type, Material, Application, and Region, 2026-2034
Mexico Automotive Plastics Market Size, Share, Trends & Forecast (2026-2034)
The Mexico automotive plastics market grew from USD 544.5 Million in 2025 to USD 560.0 Million in 2026 and is projected to reach USD 709.7 Million by 2034, growing at a CAGR of 2.84% during 2026-2034. Mexico is a major global automotive manufacturing hub, ranking fifth in light vehicle production and exports in 2024, supported by 37 manufacturing plants across 12 states. This strong OEM manufacturing base is driving demand for automotive plastics used in lightweight interiors, exteriors, under-the-hood components, and other vehicle parts, thereby supporting market growth. Conventional and traditional vehicles dominate at 87.6%, interior furnishings lead application at 31.7%, and Northern Mexico commands 46.3% regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 544.5 Million |
|
Market Size (2026) |
USD 560.0 Million |
|
Forecast Market Size (2034) |
USD 709.7 Million |
|
CAGR (2026-2034) |
2.84% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Vehicle Type |
Conventional & Traditional Vehicles (87.6%, 2025) |
|
Dominant Application |
Interior Furnishings (31.7%, 2025) |
|
Leading Region |
Northern Mexico (46.3%, 2025) |
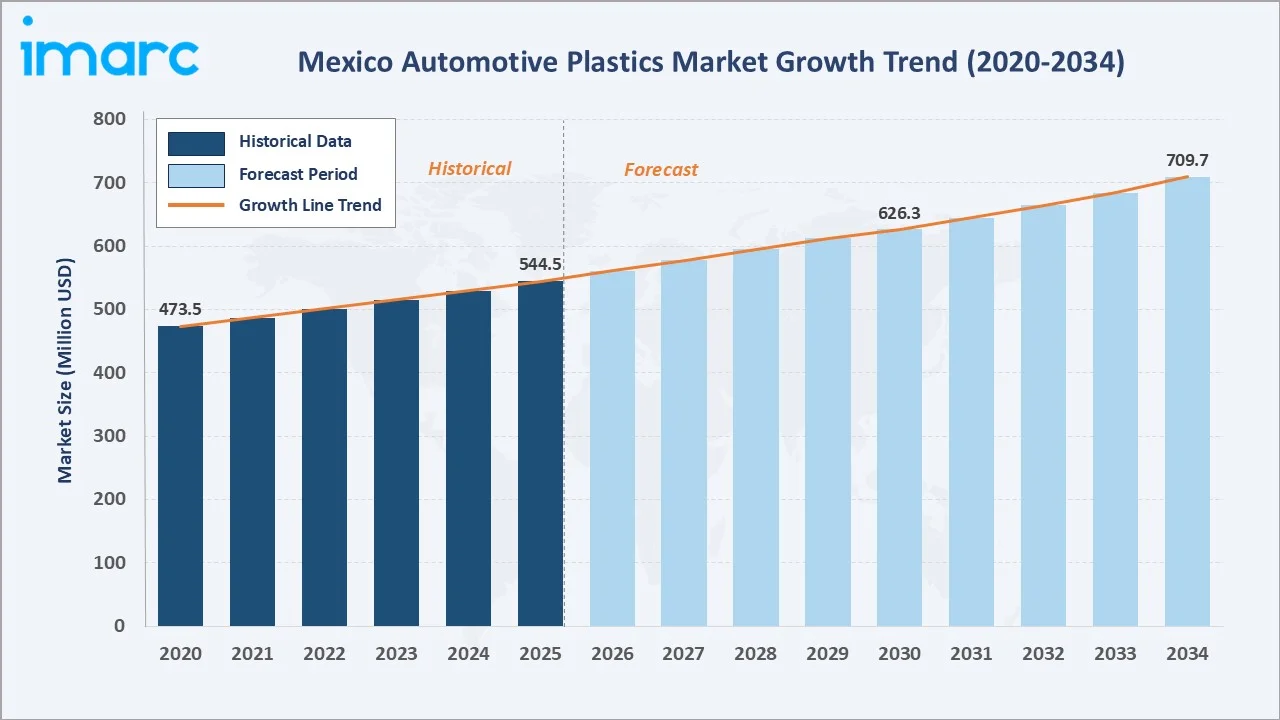
The Mexico automotive plastics market grew from USD 473.5 Million in 2020 to USD 544.5 Million by 2025 and is estimated to reach USD 560.0 Million in 2026. The market is projected to reach USD 626.3 Million by 2030 and USD 709.7 Million by 2034.
To get more information on this market, Request Sample
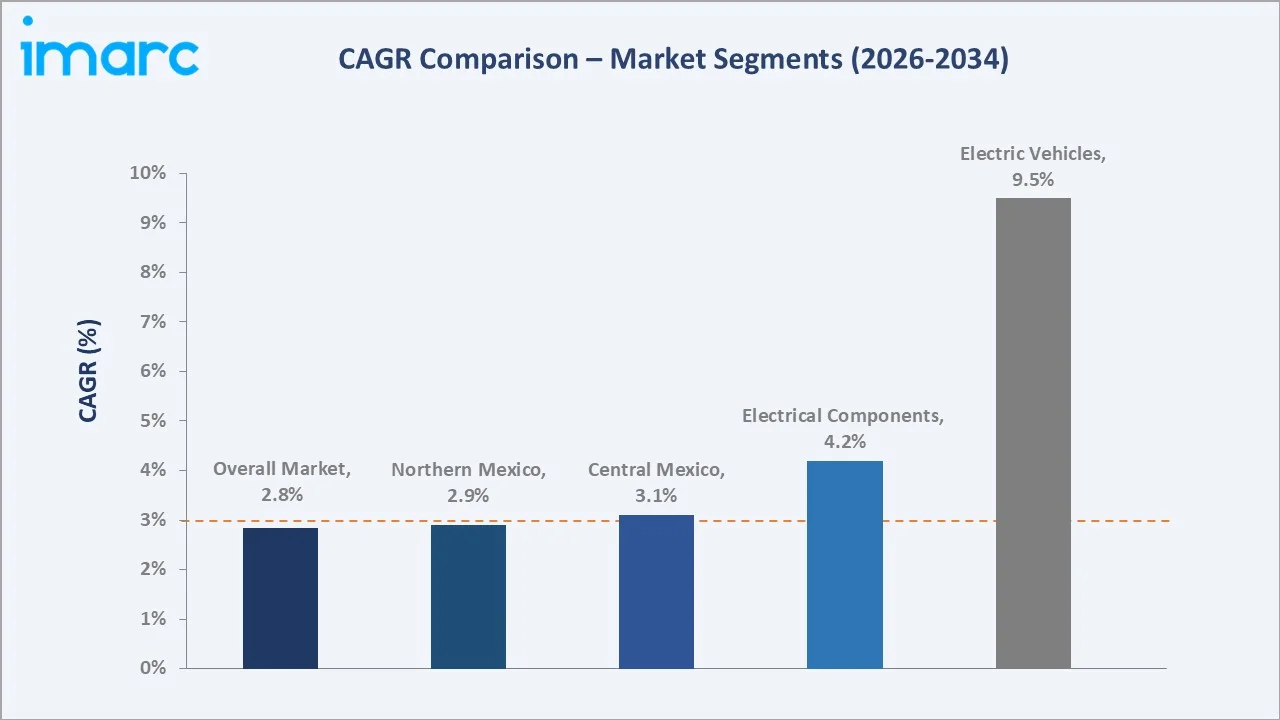
The electric vehicles segment grows fastest at ~9.5% CAGR as Mexico's EV manufacturing footprint expands through gigafactory development and OEM EV platform localization programs. Electrical components application grows at ~4.2% CAGR through EV high-voltage connector and power electronics housing demand. Central Mexico leads regional growth at ~3.1% CAGR through OEM platform additions.
Executive Summary
The Mexico automotive plastics market is a mature, steadily growing industrial segment of Mexico's automotive industry supply chain, driven by sustained OEM production volume growth, lightweighting innovation substituting engineering plastics for metal across vehicle platforms, and growing EV-grade specialty plastic demand from Mexico's emerging EV manufacturing ecosystem. Conventional and traditional vehicles dominate at 87.6% through Mexico's established ICE vehicle production leadership, with EV platforms growing at ~9.5% CAGR as the fastest-expanding segment. Interior furnishings lead applications at 31.7% through instrument panel, door panel, and seating component plastic intensity. Northern Mexico commands 46.3% through the automotive cluster's combined OEM assembly and Tier-1 supplier concentration.
Key Market Insights
|
Insight |
Data |
|
Dominant Vehicle Type |
Conventional & Traditional Vehicles - 87.6% share (2025) |
|
Dominant Application |
Interior Furnishings - 31.7% share (2025) |
|
Leading Region |
Northern Mexico - 46.3% (2025) |
|
Key Market Opportunity |
Rising electric vehicle production, increasing adoption of lightweight plastic components, growing demand for recycled and bio-based plastics, vehicle localization, and expanding automotive manufacturing capacity. |
Key Analytical Observations Supporting the Above Data:
- Conventional and Traditional Vehicles at 87.6%: Conventional internal combustion engine (ICE) vehicles dominate Mexico's automotive plastics market through their commanding share of Mexico's vehicle production, with pickup trucks and passenger cars accounting for the majority of Mexico's vehicle output for domestic sale and North American export.
- Interior Furnishings at 31.7%: Interior furnishings, encompassing instrument panels, door panels, center consoles, headliners, seat backs, pillar trims, and floor coverings, represent the largest and most visible automotive plastics application through the combination of design complexity, material variety, and high plastic content per vehicle.
- Northern Mexico at 46.3%: Northern Mexico's dominant market share reflects the region's unmatched concentration of vehicle assembly volume and supporting Tier-1 plastic parts supplier industrial parks. Northern Mexico's auto parts companies include the largest concentration of plastic injection molding, blow molding, and thermoforming operations in Mexico, creating a self-reinforcing supply chain ecosystem where polymer resin suppliers, compound processors, parts molders, and OEM assembly plants operate within integrated industrial park environments under just-in-time delivery protocols.
Mexico Automotive Plastics Market Overview
The Mexico automotive plastics market encompasses all thermoplastic and thermoset polymer materials and compounds processed into components for passenger cars, light commercial vehicles, trucks, and buses assembled in Mexico. The polymer material scope spans commodity resins (polypropylene PP, polyethylene PE, ABS) representing most of automotive plastic volume, engineering resins (polyamide PA, polycarbonate PC, POM, PBT), and specialty high-performance polymers (PEEK, PPA, PPS, PPSU).
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
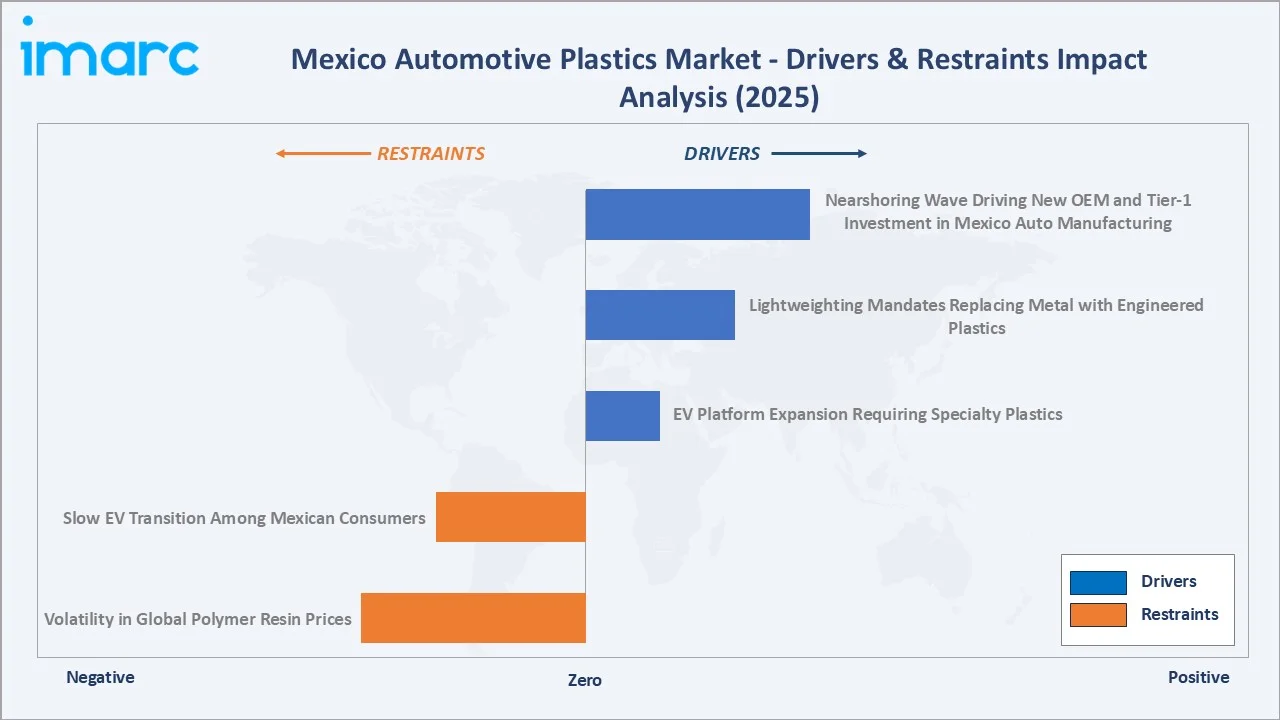
- Nearshoring Wave Driving New OEM and Tier-1 Investment in Mexico Auto Manufacturing: The structural shift of manufacturing investment from Asia to North America is generating a sustained wave of automotive facility investment in Mexico that is directly expanding automotive plastic demand.
- Lightweighting Mandates Replacing Metal with Engineered Plastics: North American OEM fuel efficiency and emissions standards are compelling OEM engineers to substitute engineering plastics and thermoplastic composites for metal components across vehicle platforms to reduce vehicle mass. Mexico-assembled vehicles are incorporating increasing plastic content per vehicle through injection-molded structural brackets replacing stamped steel, polyamide air intake manifolds replacing aluminum castings, and composite door inners replacing sheet metal, driving above-unit-growth rates for engineering plastic compound demand in Mexico.
- EV Platform Expansion Requiring Specialty Plastics: Mexico’s electrified vehicle sales reached 16,374 units in March 2026, representing a 33.9% increase compared with March 2025. Electric vehicle platforms require fundamentally different and higher-performance plastic materials compared to ICE vehicles, battery cell module housings and pack enclosures requiring high flame retardancy, dimensional stability, and thermal conductivity, high-voltage connector systems requiring tracking resistance, power electronics housings requiring continuous-use temperatures above 150°C, and EV charging port components requiring UV, weathering, and chemical resistance.
Market Restraints
- Volatility in Global Polymer Resin Prices: Fluctuating prices of key polymer resins are increasing raw material costs and creating procurement uncertainty for automotive plastics manufacturers in Mexico. Dependence on global petrochemical supply chains exposes producers to crude oil price movements, supply disruptions, and currency fluctuations. These uncertainties can squeeze profit margins and make long-term production planning more challenging, thereby hampering market growth.
- Slow EV Transition Among Mexican Consumers: The relatively gradual adoption of electric vehicles among Mexican consumers limits the near-term demand for specialized lightweight plastics used in EV battery systems, thermal management, interiors, and structural components. Factors such as higher upfront vehicle costs and developing charging infrastructure can slow EV penetration, thereby restricting new growth opportunities for automotive plastics suppliers.
Market Opportunities
- Lightweight Thermoplastic Composites for Structural Automotive Applications: In 2024, Mexico ranked as the world’s fifth-largest producer and exporter of light vehicles, with automotive exports valued at approximately USD 104.8 billion. Mexico's growing vehicle lightweighting program creates opportunity for continuous, and long-fiber reinforced thermoplastic composites to replace metal stampings and cast aluminum components in structural automotive applications, including floor pan inserts, seat structures, battery tray crossmembers, and front-end carrier modules.
- Bio-Based and Recycled Content Plastics for OEM Sustainability Mandates: European OEMs assembling vehicles in Mexico are subject to parent company sustainability commitments requiring increasing recycled and bio-based material content in new vehicle platforms. Mexico's proximity to US post-consumer plastic recycling infrastructure and chemical recycling program creates supply chain pathways for certified recycled-content automotive plastic compounds that command premium pricing from sustainability-committed OEM customers.
Market Challenges
- Security and Logistics Infrastructure Constraints in Northern Mexico Supply Chains: Northern Mexico's automotive plastics supply chain operates within a regional security environment characterized by organized crime-related transportation risks that add cost, insurance, and logistics complexity to material movements between resin production, compound manufacturing, parts molding, and OEM assembly facilities.
- Technical Workforce Availability for Advanced Automotive Plastics Processing: Mexico's automotive plastics manufacturing sector is increasingly constrained by the availability of trained engineers and technicians capable of operating advanced polymer compound extrusion, precision injection molding for engineering resins, and thermoplastic composite manufacturing processes.
Emerging Market Trends
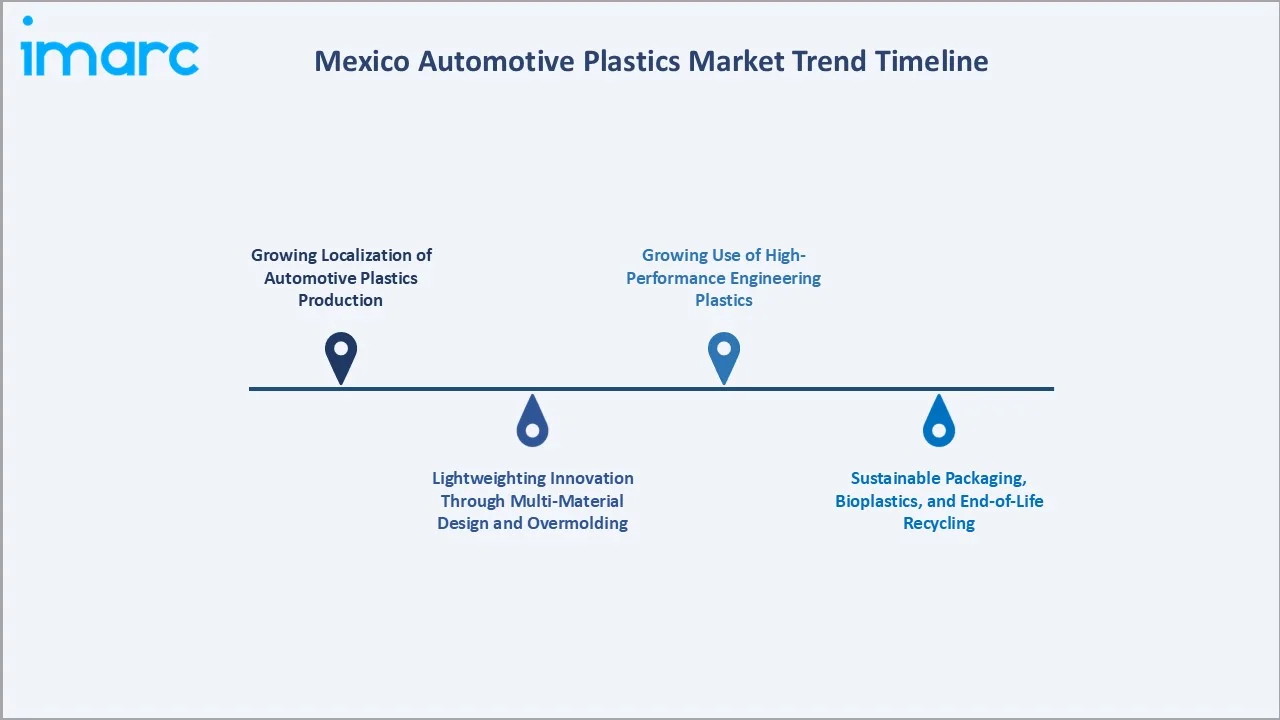
1. Growing Localization of Automotive Plastics Production
Automotive plastics manufacturers are increasingly establishing local production and compounding facilities in Mexico to serve major automakers more efficiently. In August 2025, Nanjing Julong Science & Technology commenced operations at its first overseas engineering plastics compounding plant in Ramos Arizpe, Coahuila, Mexico. Backed by a USD 10 million investment, the facility produces customized engineering plastics for automotive and other applications, strengthening localized supply capabilities for North American customers. This trend is strengthening domestic supply chains, reducing logistics dependence, and supporting demand for customized engineering plastics for vehicle applications.
2. Lightweighting Innovation Through Multi-Material Design and Overmolding
Mexico's automotive plastic design engineering community is advancing beyond single-material plastic substitution toward sophisticated multi-material design approaches, combining thermoplastic injection molding with continuous fiber reinforcement inserts, metal-plastic hybrid structures using plastic ribs overmolded onto thin metal stamping substrates, and thermoplastic foam core sandwich structures for weight-optimized door panels and trunk lids. These advanced manufacturing approaches enable additional weight savings beyond simple material substitution but require significant tooling investment and manufacturing process expertise that is concentrating among Mexico's most technically advanced Tier-1 plastic parts suppliers in the supplier clusters.
3. Growing Use of High-Performance Engineering Plastics
Demand for engineering plastics is increasing as vehicles incorporate more sophisticated electronic, safety, and thermal-management systems. High-performance polymers offer advantages such as heat resistance, chemical resistance, dimensional stability, and mechanical strength. Their use is expanding in demanding under-the-hood, electrical, structural, and powertrain applications.
4. Sustainable Packaging, Bioplastics, and End-of-Life Recycling
Sustainability initiatives are encouraging Mexico’s automotive industry to increase the use of recycled, recyclable, and bio-based plastics across vehicle components and associated packaging. Automakers and suppliers are exploring circular material systems that recover plastics from end-of-life vehicles and production waste. Growing emphasis on reducing virgin plastic consumption and carbon footprints is supporting innovation in bioplastics and closed-loop recycling. This trend is creating opportunities for sustainable material suppliers and advanced recycling technologies.
Industry Value Chain Analysis
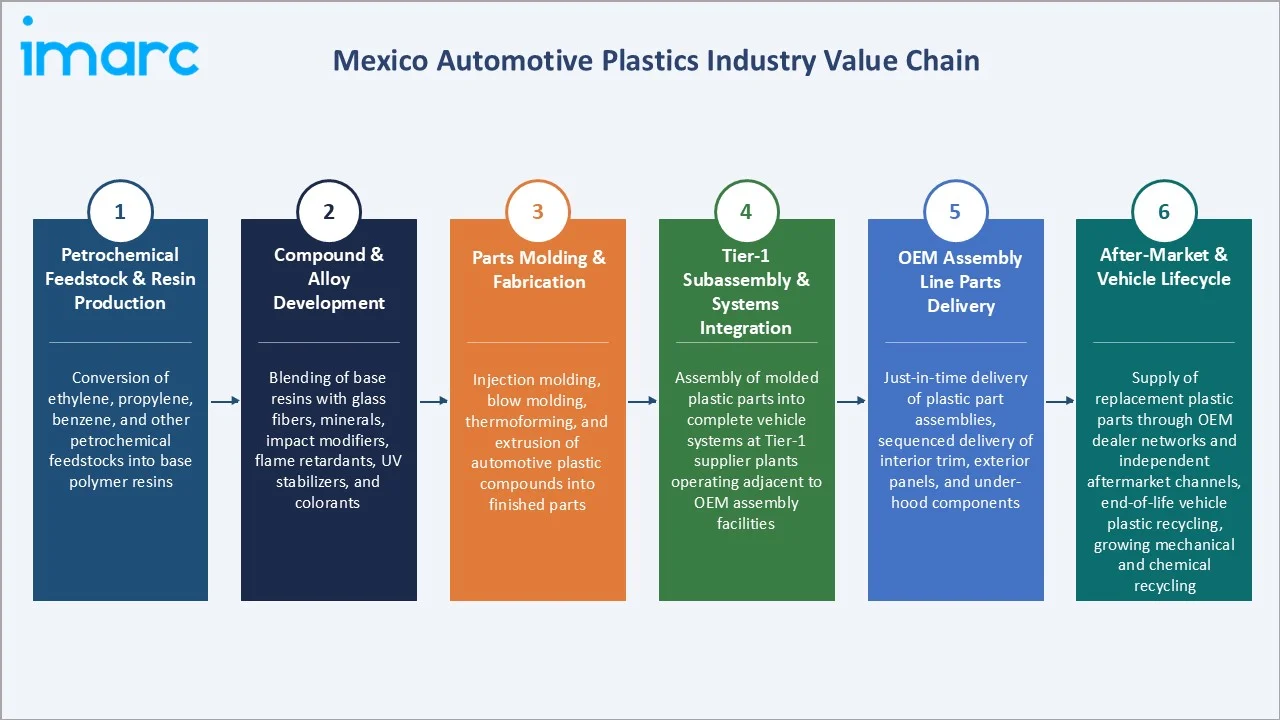
Mexico's automotive plastics value chain spans six stages from petrochemical feedstock through end-of-life vehicle recycling, with each stage representing distinct competitive positioning and value creation requirements within Mexico's automotive supply chain ecosystem.
|
Stage |
Description |
|
Petrochemical Feedstock & Resin Production |
Conversion of ethylene, propylene, benzene, and other petrochemical feedstocks into base polymer resins. |
|
Compound & Alloy Development |
Blending of base resins with glass fibers, minerals, impact modifiers, flame retardants, UV stabilizers, and colorants. |
|
Parts Molding & Fabrication |
Injection molding, blow molding, thermoforming, and extrusion of automotive plastic compounds into finished parts. |
|
Tier-1 Subassembly & Systems Integration |
Assembly of molded plastic parts into complete vehicle systems at Tier-1 supplier plants operating adjacent to OEM assembly facilities. |
|
OEM Assembly Line Parts Delivery |
Just-in-time delivery of plastic part assemblies, sequenced delivery of interior trim, exterior panels, and under-hood components. |
|
After-Market & Vehicle Lifecycle |
Supply of replacement plastic parts through OEM dealer networks and independent aftermarket channels, end-of-life vehicle plastic recycling, growing mechanical and chemical recycling. |
The Tier-1 subassembly and systems integration stage represents the highest value-creation point in Mexico's automotive plastics value chain, where injection-molded plastic parts are assembled into complete vehicle systems, instrument panel assemblies, door module systems, front-end module carriers, battery pack structures, that are delivered directly to OEM assembly line stations under sequenced just-in-time protocols.
Technology Landscape in the Mexico Automotive Plastics Industry
Engineering Resin Innovation for Under-Hood and Structural Applications
Mexico's automotive plastics technology landscape is advancing through two parallel engineering resin development tracks. For under-hood thermal management applications polyamide compound development focuses on PA6T/66 and PPA (polyphthalamide) grades that maintain structural performance at higher continuous-use temperatures than conventional PA66, enabling plastic-for-metal substitution in components previously requiring aluminum casting.
EV-Grade High-Performance Polymer Development
The transition to EV platforms in Mexico's automotive manufacturing creates demand for a distinct portfolio of high-performance polymers beyond traditional automotive material sets. Polyphenylene sulfide (PPS) is emerging as Mexico's EV battery management system housing standard, with Celanese and Solvay competing for EV program specifications at Mexico Tier-1 suppliers. Polyphenylsulfone (PPSU) from Solvay enables thin-wall battery cell separators and bus bar insulators at temperatures above 200°C with superior chemical resistance to battery electrolyte exposure.
Digital Manufacturing and Process Technology Advancement
Mexico's automotive plastics parts manufacturing sector is adopting Industry 4.0 digital manufacturing technologies, including real-time injection molding process monitoring, digital twin simulation of plastic flow and cooling for mold development, and AI-powered quality inspection systems using computer vision for surface defect detection in Class-A plastic exterior trim parts. These digital manufacturing investments are concentrated at Mexico's most sophisticated Tier-1 plastic parts suppliers who are implementing Industry 4.0 capability as a requirement for winning increasingly technical EV platform programs from OEM customers who are demanding digital manufacturing data transparency as part of their supplier qualification processes.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Vehicle Type |
Conventional and Traditional Vehicles |
87.6% |
2025 |
|
Material |
🔒 |
🔒 |
2025 |
|
Application |
Interior Furnishings |
31.7% |
2025 |
|
Region |
Northern Mexico |
46.3% |
2025 |

By Vehicle Type
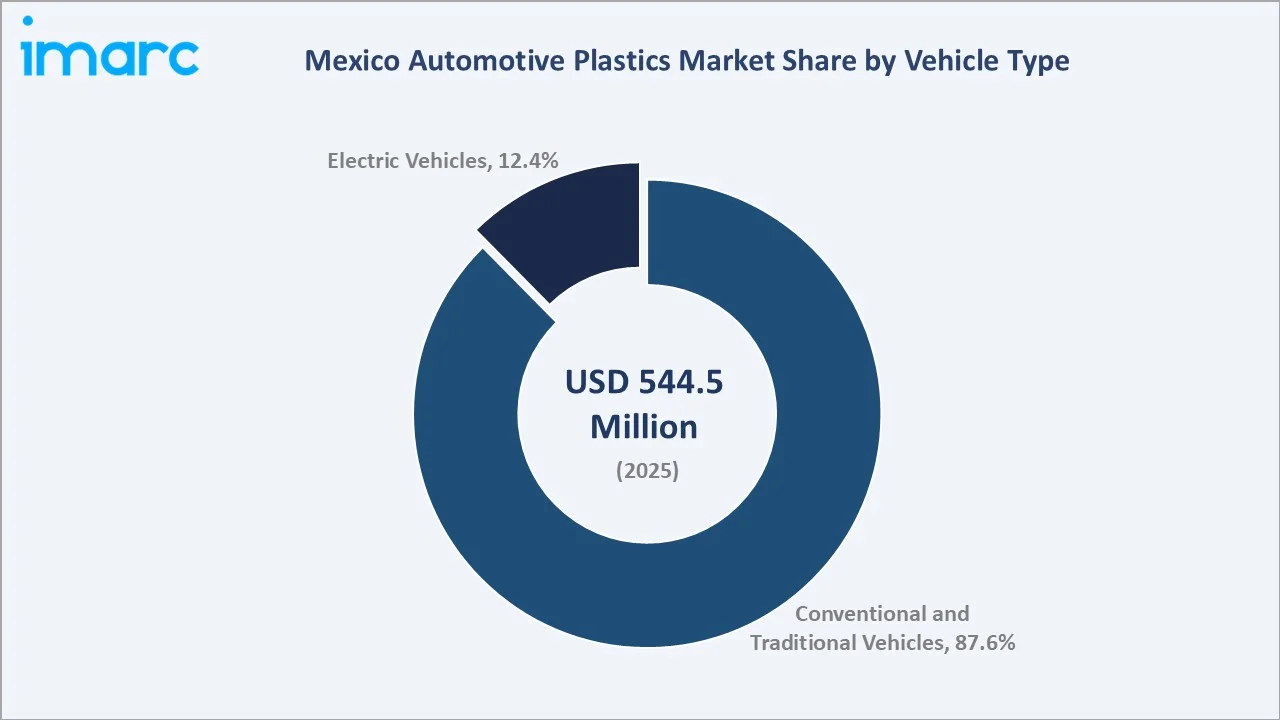
Conventional and traditional vehicles command 87.6% in 2025, reflecting Mexico's production profile dominated by ICE passenger cars and light trucks. Mexico's OEM vehicle production mix generates diverse automotive plastic demand across interior, exterior, under-hood, and powertrain applications.
To access detailed market analysis, Request Sample
Electric vehicles at 12.4% represent the fastest-growing segment at ~9.5% CAGR, currently dominated by imported CBU EVs assembled outside Mexico but including growing Mexico-produced EV content.
By Application
Interior furnishings leads at 31.7% through the plastic content intensity of Mexico's assembled vehicle interior modules, instrument panels, door panels, center consoles, headliners, and pillar trims. Mexico's Tier-1 interior module suppliers operate large injection molding complexes adjacent to OEM plants, consuming the highest single-application volumes of automotive PP, ABS, and PC/ABS in Mexico.
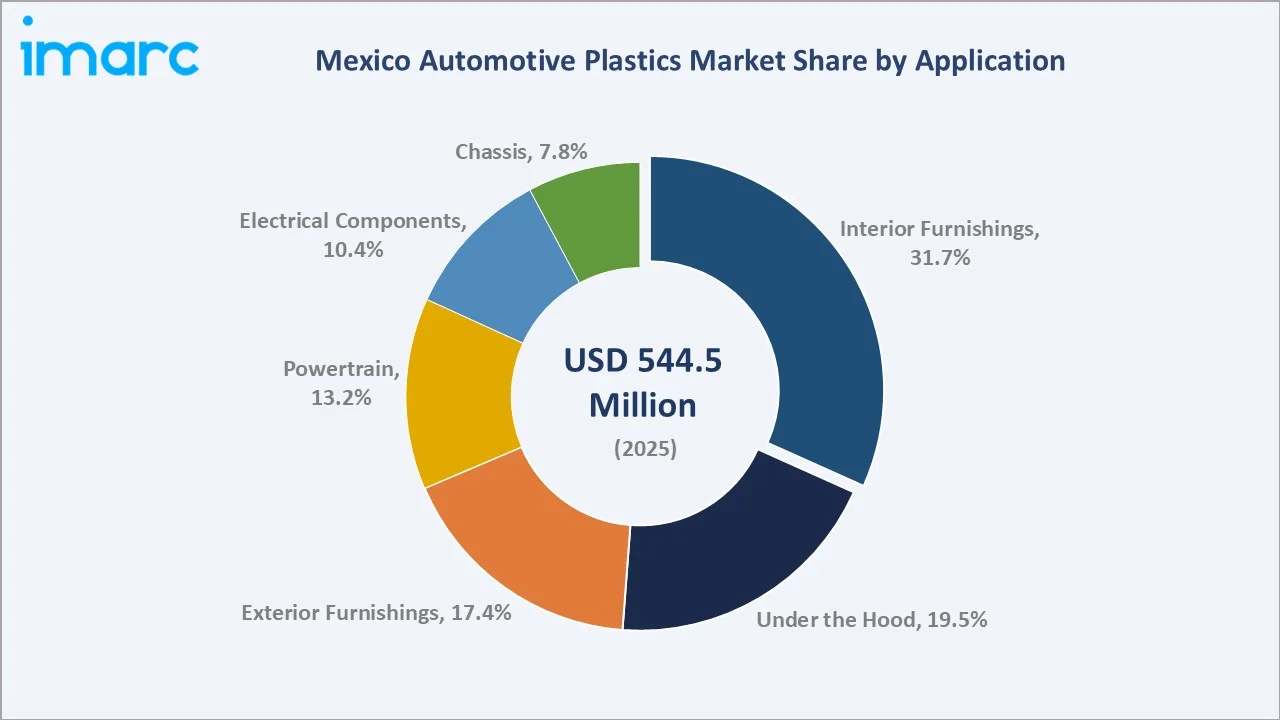
Under the hood at 19.5% encompasses air intake manifolds, thermostat housings, coolant reservoirs, engine covers, and battery trays manufactured from PA66, PA6, and PP compounds. Exterior furnishings at 17.4% include bumper fascias (PP/TPO), fender liners (HDPE), and mirror housing (ASA/ABS). Powertrain at 13.2% covers transmission components (PA, POM), fuel system (PA12, HDPE), and driveline components. Electrical components at 10.4% encompass connector housing (PA, PBT), wire conduits (PA12), and sensor housing (PPS, PA). Chassis at 7.8% includes suspension component covers and structural reinforcement applications.
Regional Market Insights
|
Region |
Share (2025) |
Key Mexico Automotive Plastics Market Drivers & Characteristics |
|
Northern Mexico |
46.3% |
Northern Mexico commands the Mexico automotive plastics market through the region's concentration of Mexico's largest and most technologically advanced vehicle assembly plants and Tier-1 supplier industrial parks. |
|
Central Mexico |
33.1% |
Central Mexico's growing EV manufacturing footprint is driving early-stage battery enclosure and thermal management plastic demand. |
|
Southern Mexico |
12.8% |
Southern Mexico's automotive plastics market, while the smallest regional segment, is growing through expanding auto parts manufacturing activity, and industrial zones serving automotive import and export logistics. |
|
Others |
7.8% |
Large electronics manufacturing clusters generate adjacent automotive electronics plastic demand through shared injection molding infrastructure, while industrial zones are attracting EV component supplier investment that will drive specialty plastic demand for power electronics housings, connector systems, and EV thermal management components. |
Northern Mexico's 46.3% market dominance is structurally secured by the region's combination of Mexico's highest automotive production density, most developed Tier-1 plastic parts supplier ecosystem, and greatest nearshoring investment pipeline.
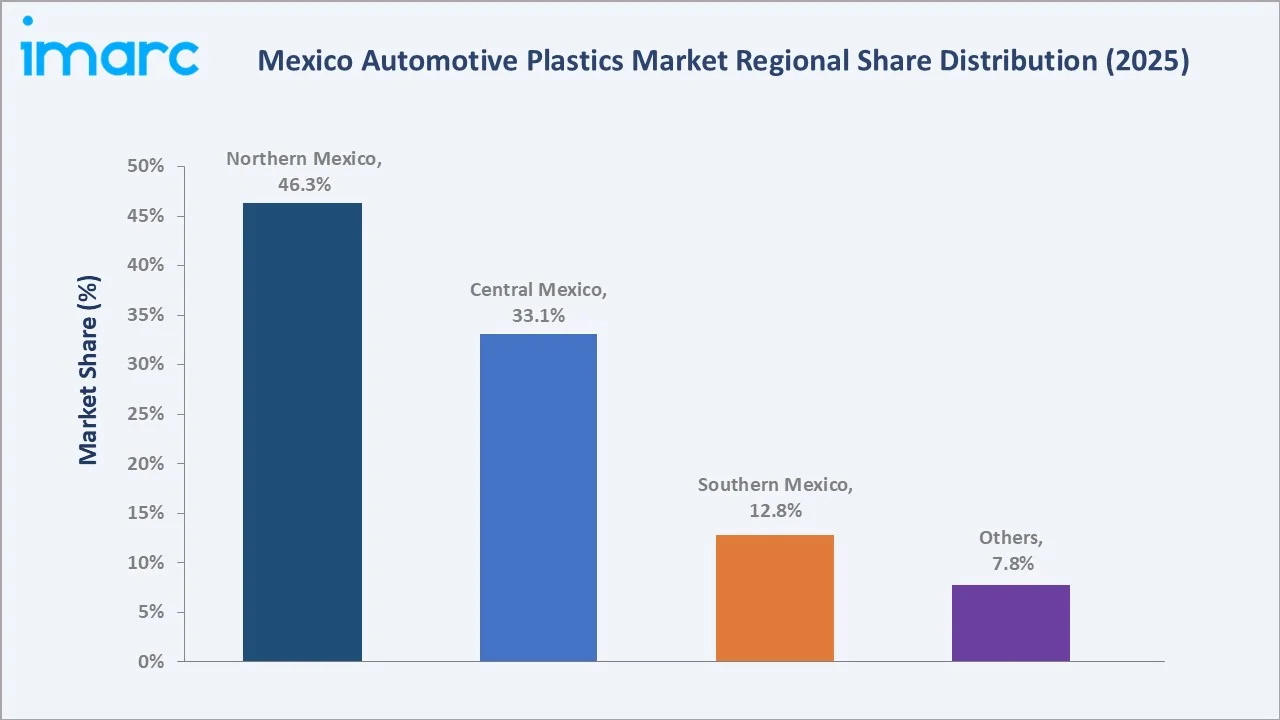
Central Mexico at 33.1% is growing through continued model introductions, quality premium and EV program development, and a growing automotive manufacturing cluster. Southern Mexico at 12.8% is expanding through southern industrial park development and port logistics plastic imports. The Others region at 7.8% includes an emerging EV component supplier cluster and electronics-adjacent automotive plastic manufacturing base.
Competitive Landscape
Mexico automotive plastics market features a technology leader tier of global specialty chemical companies supplying premium engineering compounds, an established volume supplier tier providing mainstream automotive polymer grades, an innovator tier focused on high-performance EV-grade materials, and a domestic producer tier providing commodity resin supply with regional content advantages.
|
Company |
Key Products |
Market Position |
Core Strength |
|
BASF |
Ultradur, Ultramid, Cellasto |
Market Leader |
BASF plays a critical role in the Mexico automotive plastics market, serving as a primary Tier-2 and Tier-3 chemical supplier to Mexico's massive automotive manufacturing hub. |
|
Celanese Corporation |
Zytel PA |
Market Leader |
Celanese Corporation supplies high-performance engineered thermoplastics, technical support, and localized compounding to drive lightweighting, safety, and electrification in Mexico’s automotive sector. |
|
Envalior |
Durethan |
Established Player |
Envalior plays a critical role in the Mexico automotive plastics market as a leading supplier of high-performance engineering materials. |
|
LyondellBasell Industries Holdings B.V. |
Sequel, Hifax, Softell |
Established Player |
LyondellBasell Industries Holdings B.V. is a dominant tier-supplier and leading producer of polypropylene (PP) compounds and advanced polymer solutions for the Mexican automotive plastics sector. |
Competitive dynamics in Mexico's automotive plastics market are shaped by OEM platform material specification approval processes that create qualification timelines for new polymer materials before volume production use.
Key Company Profiles
BASF
BASF is a global chemical company with an established presence in Mexico, supplying advanced material solutions to the automotive industry. In the Mexico automotive plastics market, the company offers engineering plastics, polyurethane systems, and performance materials for interior, exterior, structural, and under-the-hood applications. Its solutions support vehicle lightweighting, durability, safety, and improved performance. BASF also emphasizes material innovation and sustainable solutions to address evolving requirements among automotive OEMs and component suppliers.
- Key Products: Ultradur, Ultramid, Cellasto.
- Strategic Focus: Expanding advanced engineering plastics and performance materials in Mexico to support vehicle lightweighting, electrification, durability, and safety. The company also emphasizes sustainable material innovation, recycled content, and customized polymer solutions to address evolving automotive OEM requirements.
Celanese Corporation
Celanese Corporation is a global specialty materials and chemical company serving automotive manufacturers and component suppliers across major markets, including Mexico. In the Mexico automotive plastics market, the company provides engineered materials and high-performance polymers for interior, exterior, electrical, and under-the-hood applications. Its material portfolio supports vehicle lightweighting, durability, thermal management, and electrification requirements. The company leverages material science expertise and application development capabilities to address evolving automotive performance and sustainability needs.
- Key Products: Zytel PA.
- Strategic Focus: Expanding advanced engineered materials and high-performance polymers for lightweighting, electrification, and demanding automotive applications in Mexico. The company emphasizes material innovation, customized solutions, and sustainable polymer technologies to meet evolving OEM and component supplier requirements.
Market Concentration Analysis
Mexico automotive plastics market exhibits a clear two-tier concentration structure. In the premium engineering resin segment serving under-hood, structural, and EV applications, these companies collectively hold an estimated 45-55% of engineering compound revenues through their OEM platform specification positions established over decades of technical engagement with Mexico-based OEM engineering teams. In the volume polyolefin segment for bumper, interior substrate, and exterior applications, competitor polyolefin companies share a market dominated by PP and TPO pricing competition and regional content qualification rather than technical differentiation. Domestic producers contribute regionally important qualifying raw material supply but limited value-added compound market share.
Investment & Growth Opportunities
Highest Growth Segments
Electric vehicles plastic applications (~9.5% CAGR), electrical components (~ 4.2% CAGR), high-performance EV-grade specialty compounds, thermoplastic composite structural lightweighting, qualifying domestic compound manufacturing, Mexico supply chain development, and bio-based and recycled content automotive material development represent the highest-return investment opportunities in Mexico's automotive plastics market through 2034.
Investment Themes
- EV-Grade Specialty Compound Manufacturing in Mexico: Mexico's growing EV manufacturing footprint will generate substantial demand for EV-grade PPS, PPA, PPSU, and flame-retardant PA compounds currently imported from European or Asian chemical plants without qualifying regional content.
- Thermoplastic Composite Processing for EV Structural Lightweighting: Mexico's automotive lightweighting mandate creates demand for Tier-1 suppliers capable of manufacturing structural thermoplastic composite parts, battery tray crossmembers, floor pan inserts, door inners, and seat structures, using continuous fiber composite materials processed through compression molding and one-shot forming operations.
Future Market Outlook (2026-2034)
The Mexico automotive plastics market is projected to grow from USD 544.5 Million in 2025 to USD 560.0 Million in 2026, reaching USD 709.7 Million by 2034, exhibiting a CAGR of 2.84% during 2026-2034. The market is projected to reach USD 626.3 Million by 2030, the mid-period milestone when Mexico's nearshoring investment wave will have translated into peak concurrent new vehicle platform production ramp-ups. This EV production share growth will structurally shift Mexico's automotive plastic material portfolio from predominantly commodity PP and ABS toward a higher-value engineering compound mix including PPS, PPA, and flame-retardant PA66 grades required for EV battery and power electronics applications.
Three transformative forces will define Mexico's automotive plastics market through 2034. First, the nearshoring investment consolidation will generate a step-change increase in Mexico's annual vehicle production capacity and associated automotive plastic demand that exceeds the market's historical steady-state growth trajectory. Second, the EV platform material transition will progressively improve Mexico's automotive plastic market average selling price through the higher unit value of PPS, PPA, and flame-retardant specialty compounds versus equivalent-weight commodity PP and ABS. Third, the regional content compliance evolution will drive sustained supply chain localization investment in Mexico compound manufacturing, resin production, and recycled material processing that expands Mexico's domestic automotive plastic production base and reduces import dependency from Asian and European sources.
Research Methodology
Primary Research
Primary research comprised structured interviews with engineering polymer technical sales managers, materials engineers at Mexico-based Tier-1 automotive plastic parts suppliers, OEM purchasing and engineering managers responsible for Mexico platform material specifications, and compound processing operations managers at Mexico injection molding facilities. Supply chain mapping validation confirmed polymer flow from resin producers through compound processors to OEM assembly plants.
Secondary Research
Secondary research incorporated Mexico vehicle production statistics, industrial production indices for plastic product manufacturing, SE automotive sector investment announcement database, automotive rules of origin compliance documentation, OEM supplier portals and Tier-1 approved material lists for Mexico platform programs, company annual technical reports, and polymer pricing and supply-demand analysis for PP, PA66, PC, and ABS in North American markets.
Forecasting Models
Forecasting models integrated Mexico OEM vehicle production volume projections, per-vehicle plastic content growth modeling from lightweighting program engineering documentation, EV production share trajectory analysis from OEM investment announcement timelines, regional content compliance impact modeling on domestic material sourcing, polymer resin price trajectory projections from commodity chemical forecasts, and nearshoring investment announcement phasing analysis to estimate production ramp timing effects on automotive plastic demand.
Mexico Automotive Plastics Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Vehicle Types Covered | Conventional and Traditional Vehicles, Electric Vehicles |
| Materials Covered | Polyethylene (PE), Polypropylene (PP), Polyvinyl Chloride (PVC), Acrylonitrile Butadiene Styrene (ABS), Polyurethane (PU), Polymethyl Methacrylate (PMMA), Polycarbonate (PC), Polyamide, Others |
| Applications Covered | Powertrain, Electrical Components, Interior Furnishings, Exterior Furnishings, Under the Hood, Chassis |
| Regions Covered |
Northern Mexico, Central Mexico, Southern Mexico, Others |
| Companies Covered | BASF, Celanese Corporation, Envalior, LyondellBasell Industries Holdings B.V., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Mexico automotive plastics market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Mexico automotive plastics market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Mexico automotive plastics industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Mexico Automotive Plastics Market Report
The Mexico automotive plastics market reached USD 560.0 Million in 2026, driven by Mexico's vehicle production, nearshoring investment expanding OEM capacity, regional content compliance boosting local material sourcing, and lightweighting engineering plastic substitution for metal components across vehicle platforms.
The market is projected to grow at a CAGR of 2.84% during 2026-2034, with the EV segment growing at ~9.5% CAGR as the fastest component, driven by nearshoring-driven vehicle production expansion, EV platform localization requiring specialty plastic compounds, lightweighting initiatives, and compliance driving domestic material sourcing investment.
The market is projected to reach USD 626.3 Million by 2030, when EV manufacturing investments are expected to have ramped production, EV vehicle share of Mexico production rises, and regional content enforcement drives systematic domestic automotive compound supply chain development.
Conventional and traditional vehicles lead with an 87.6% share in 2025, reflecting Mexico's ICE vehicle production, dominated by pickup trucks and passenger cars, each incorporating plastic content across all vehicle systems.
Interior furnishings leads with a 31.7% share in 2025, encompassing instrument panels, door panels, center consoles, and headliners manufactured from PP substrates, ABS and PC/ABS Class-A surfaces, POM clips, and TPO skin materials by Mexico Tier-1 interior module suppliers adjacent to OEM assembly plants.
Northern Mexico leads with a 46.3% share in 2025, through the automotive cluster housing auto parts companies, including Mexico's largest concentration of injection molding and engineering compound processing operations serving just-in-time OEM assembly plant supply chains.
Key players include BASF, Celanese Corporation, Envalior, and LyondellBasell Industries Holdings B.V., among others.
The market is projected to reach USD 709.7 Million by 2034, driven by nearshoring production ramp completion, EV platform material portfolio premiumization increasing average compound value per vehicle, domestic compound manufacturing investment, thermoplastic composite structural lightweighting adoption, and recycled content automotive plastic supply chain development.
Key investment opportunities include EV-grade specialty compound manufacturing in Mexico for regional content qualification, thermoplastic composite processing capacity for EV structural lightweighting applications, recycled automotive plastic supply chain development to meet European OEM recycled content mandates, and domestic resin production expansion qualifying for regional value content treatment.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade