Mexico Biodegradable Food Service Disposables Market Size, Share, Trends and Forecast by Raw Material Type, Product Type, Distribution Channel, and Region, 2026-2034
Mexico Biodegradable Food Service Disposables Market Size, Share, Trends & Forecast (2026-2034)
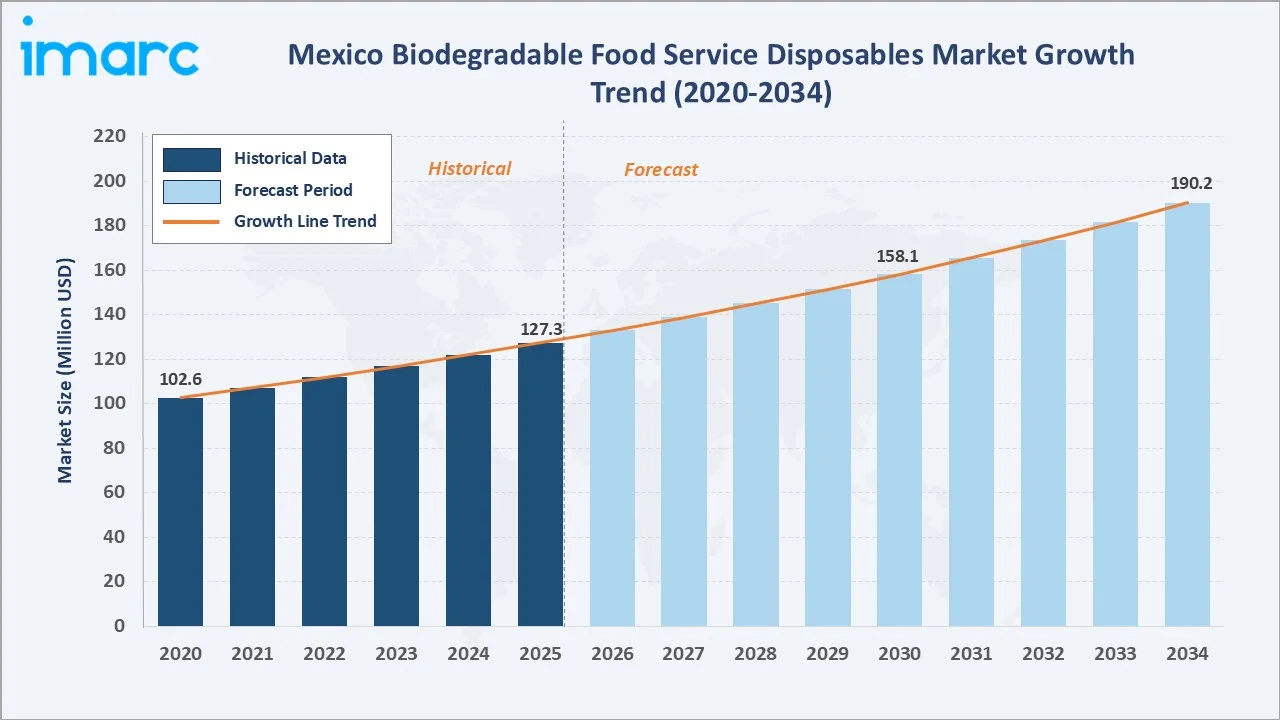
The Mexico biodegradable food service disposables market grew from USD 127.3 Million in 2025 to USD 133.0 Million in 2026 and is projected to reach USD 190.2 Million by 2034, growing at a CAGR of 4.42% during 2026-2034. Tightening rules on single-use plastics are the primary driver shaping market growth, reinforced by the General Circular Economy Law, published on January 19, 2026, which formally introduced extended producer responsibility for manufacturers and importers.
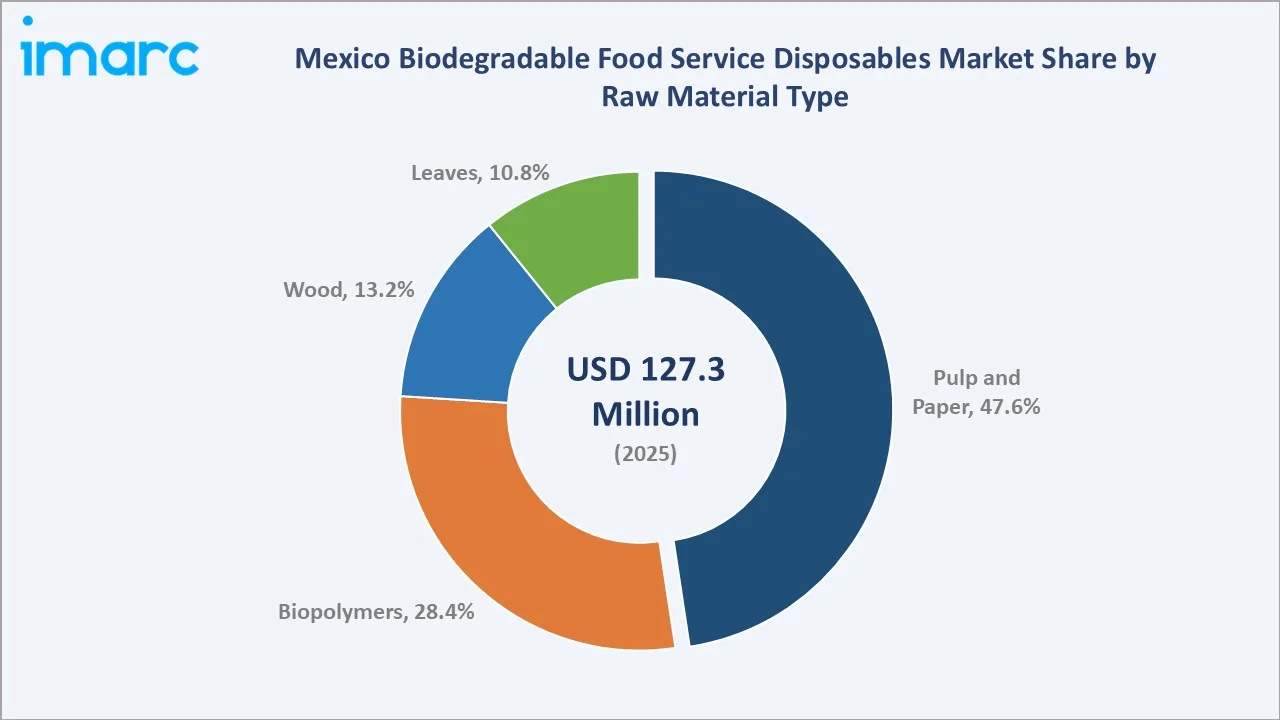
Pulp and paper lead the raw material type segment at 47.6%, cups dominate the product type segment at 32.8%, and Central Mexico commands 44.5% regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 127.3 Million |
|
Market Size (2026) |
USD 133.0 Million |
|
Forecast Market Size (2034) |
USD 190.2 Million |
|
CAGR (2026-2034) |
4.42% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Central Mexico (44.5%, 2025) |
|
Second Largest Region |
Northern Mexico (29.8%, 2025) |
|
Leading Raw Material Type |
Pulp and Paper (47.6%, 2025) |
|
Leading Product Type |
Cups (32.8%, 2025) |
The Mexico biodegradable food service disposables market size increased from USD 102.6 Million in 2020 to USD 127.3 Million in 2025 and is estimated to reach USD 133.0 Million in 2026. The market is further expected to grow to USD 158.1 Million by 2030 and USD 190.2 Million by 2034. Growth is supported by local restrictions on plastic and foam disposables, rising takeaway consumption, wider use of fiber-based packaging, and improving price competitiveness of compostable formats.
To get more information on this market, Request Sample
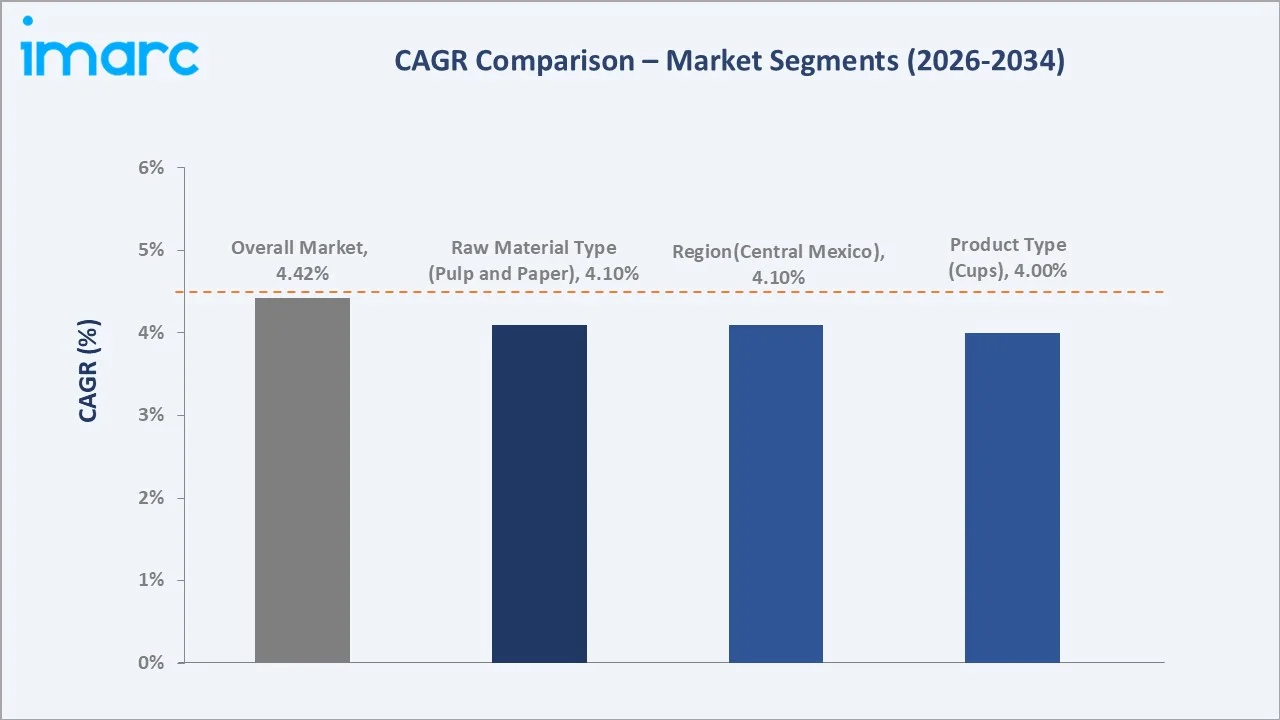
CAGR trajectories across raw material type and product type sub-segments, together with regional patterns, show Southern Mexico, biopolymers, and clamshells and containers expanding faster than the overall 4.42% market CAGR, driven by tourism-led foodservice demand, growing delivery activity, and steady innovation in plant-based resins.
Executive Summary
The Mexico biodegradable food service disposables market expanded from USD 127.3 Million in 2025 to an estimated USD 133.0 Million in 2026. The industry has moved from niche eco-friendly tableware toward mainstream compostable cups, containers, plates, and cutleries. Local plastic bans, corporate sustainability goals, and shifting consumer preferences are encouraging operators to replace foam and conventional plastic disposables.
Pulp and paper dominate the raw material type segment at 47.6% in 2025, driven by its renewable nature, established availability, and suitability for producing compostable food service products. Cups lead the product type segment with 32.8% share, fueled by their widespread use across takeaway beverages, quick-service restaurants, cafés, and food delivery applications. Central Mexico commands 44.5% of regional share, led by strict local rules on disposables and a dense restaurant network.
Key Market Insights
|
Insight |
Data |
|
Leading Raw Material Type |
Pulp and Paper - 47.6% share (2025) |
|
Second Largest Raw Material Type |
Biopolymers - 28.4% share (2025) |
|
Leading Product Type |
Cups - 32.8% share (2025) |
|
Second Largest Product Type |
Clamshells and Containers - 26.4% share (2025) |
|
Leading Region |
Central Mexico - 44.5% share (2025) |
|
Second Largest Region |
Northern Mexico - 29.8% share (2025) |
|
Top Companies |
Huhtamaki Oyj, Novolex Holdings, LLC, Dart Container Corporation, Renovapack S.A. de C.V. |
Key Analytical Observations Expanding On the Data Above:
- Pulp and paper dominance at 47.6% is supported by the wide availability of paper cups, bowls, and molded fiber plates that closely match the performance of conventional disposables at competitive prices.
- Biopolymers share at 28.4% reflects growing use of PLA-lined cups, compostable cutleries, and plant-based resins, including locally developed avocado seed bioplastics.
- Cups leadership at 32.8% is driven by high-frequency coffee, juice, and soft drink consumption across cafés, convenience stores, and quick service restaurants.
- Clamshells and containers share at 26.4% benefits from rising takeaway and delivery orders that need grease-resistant and heat-tolerant packaging.
- Central Mexico at 44.5% leads regional share, anchored by the Mexico City metropolitan area, where dense food service activity, established distribution networks, and strong demand from restaurants, cafés, and takeaway operators support consumption of biodegradable disposables.
Mexico Biodegradable Food Service Disposables Market Overview
Biodegradable food service disposables are single-use cups, plates, bowls, containers, and cutleries made from renewable materials, such as paper, sugarcane bagasse, wood, palm leaves, and plant-based polymers. These products break down under composting conditions, offering a lower-impact alternative to foam and conventional plastic tableware.
The Mexican ecosystem brings together raw material suppliers, manufacturers and converters, importers and distributors, regulators, certification bodies, foodservice operators, and composting service providers. Together, they support the shift toward compliant, compostable packaging across restaurants, hotels, institutions, and events.
Market Dynamics
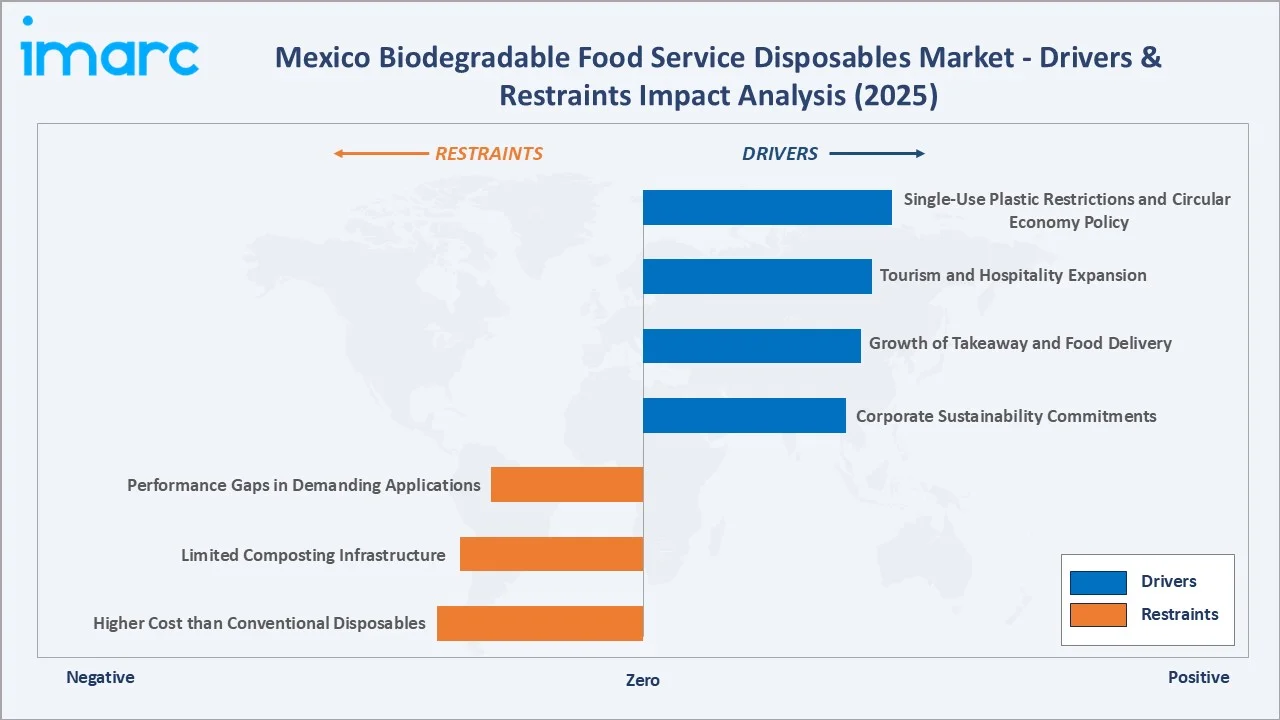
To evaluate market opportunities, Request Sample
Market Drivers
- Single-Use Plastic Restrictions and Circular Economy Policy: Mexico City's ban on plastic cutlery, cups, and food containers, along with similar state-level measures and the new national circular economy framework, is pushing foodservice operators toward compostable alternatives.
- Tourism and Hospitality Expansion: Growing visitor traffic is lifting demand for disposable tableware across hotels, resorts, cruise ports, and beach destinations that increasingly prefer eco-friendly packaging. According to the Ministry of Tourism (SECTUR), Mexico received a record 98.2 Million international visitors in 2025.
- Growth of Takeaway and Food Delivery: App-based delivery and grab-and-go formats are raising consumption of containers, cups, and cutleries, with brands favoring packaging that supports their sustainability messaging.
- Corporate Sustainability Commitments: Restaurant chains, coffee shops, and hotel groups are setting packaging targets that prioritize fiber-based and compostable options, creating steady, large-volume demand for certified products.
Market Restraints
- Higher Cost than Conventional Disposables: Compostable cups, containers, and cutleries typically cost more than foam and plastic equivalents, which slows adoption among small vendors and price-sensitive operators.
- Limited Composting Infrastructure: Few industrial composting facilities and weak separate collection mean many compostable items still end up in landfills, reducing their environmental value and weakening buyer confidence.
- Performance Gaps in Demanding Applications: Some fiber and bioplastic products still struggle with hot liquids, oily foods, and long holding times, prompting operators to keep conventional options for certain menu items.
Market Opportunities
- Locally Sourced Agro-Waste Materials: Mexico's large agricultural base, including sugarcane bagasse, wheat straw, and avocado seeds, offers low-cost feedstock for domestic production of fiber and bioplastic disposables. This can support localized supply chains, reduce reliance on imported raw materials, and encourage value addition from agricultural residues.
- Large Events and Tourism Hubs: Major sporting events, festivals, and resort destinations create openings for suppliers offering high-volume, certified compostable packaging programs. Growing sustainability requirements at hospitality and event venues can further encourage the adoption of environmentally preferable food service disposables.
Market Challenges
- Uneven Enforcement Across States: Differences in regulatory scope and enforcement between states create inconsistent demand signals and complicate national distribution strategies. Suppliers may therefore need to adapt product offerings and compliance strategies to meet varying local requirements.
- Mislabeling and Greenwashing Concerns: Products marketed as biodegradable without recognized certification can confuse buyers and erode trust in genuinely compostable offerings. Greater emphasis on transparent labeling and credible certification can help distinguish compliant products from unsupported environmental claims.
Emerging Market Trends
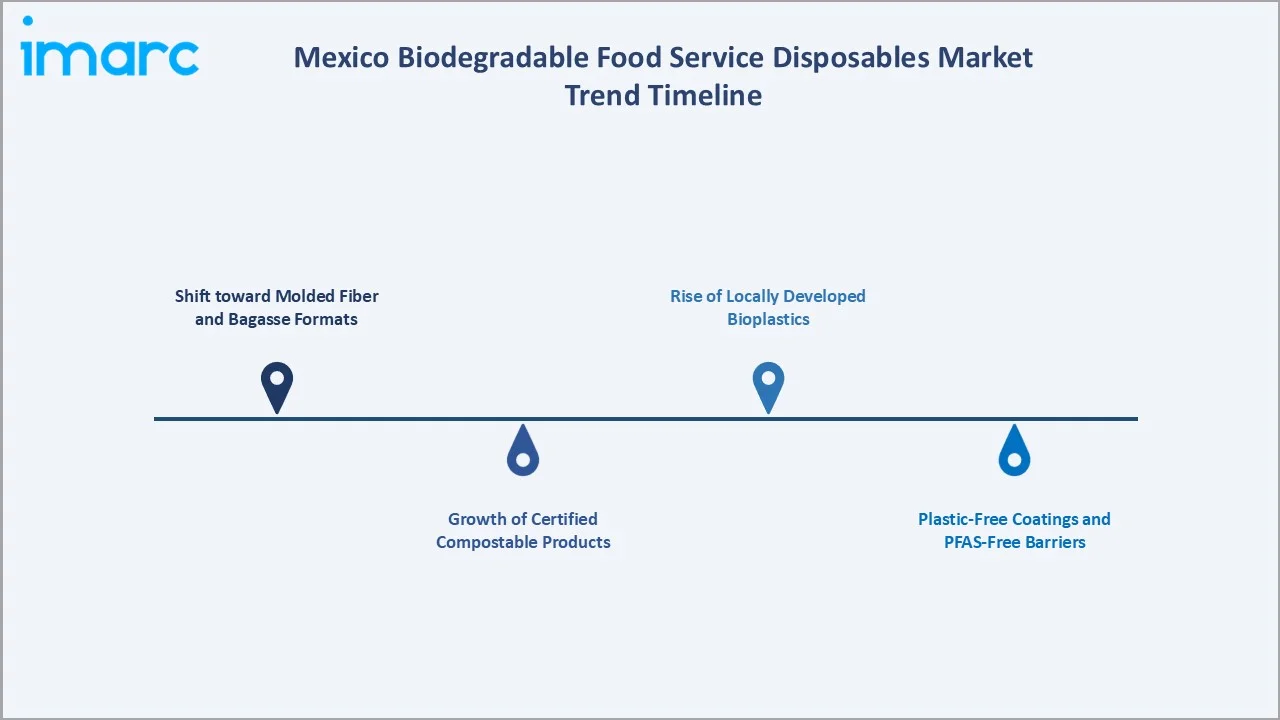
1. Shift toward Molded Fiber and Bagasse Formats
Operators are replacing foam clamshells and plates with molded fiber and sugarcane bagasse products that offer better heat and grease resistance. Suppliers are widening size ranges and adding matching lids to support complete packaging programs.
2. Growth of Certified Compostable Products
Certification is becoming a key purchasing criterion as authorities tighten the definition of compostable products. According to Mexico City's Ministry of Environment (SEDEMA), 135 companies had secured authorization to commercialize compostable bags and products in the city as of 2024, encouraging suppliers to invest in testing and labeling.
3. Rise of Locally Developed Bioplastics
Mexican innovators are converting agricultural residues, such as avocado seeds, into biopolymer resins for cutleries and straws. These materials reduce reliance on imported resins and appeal to brands seeking local, circular sourcing.
4. Plastic-Free Coatings and PFAS-Free Barriers
Manufacturers are developing water-based and plant-based coatings for cups and containers to improve compostability and avoid fluorinated chemicals, responding to rising buyer concern over food contact safety.
Industry Value Chain Analysis
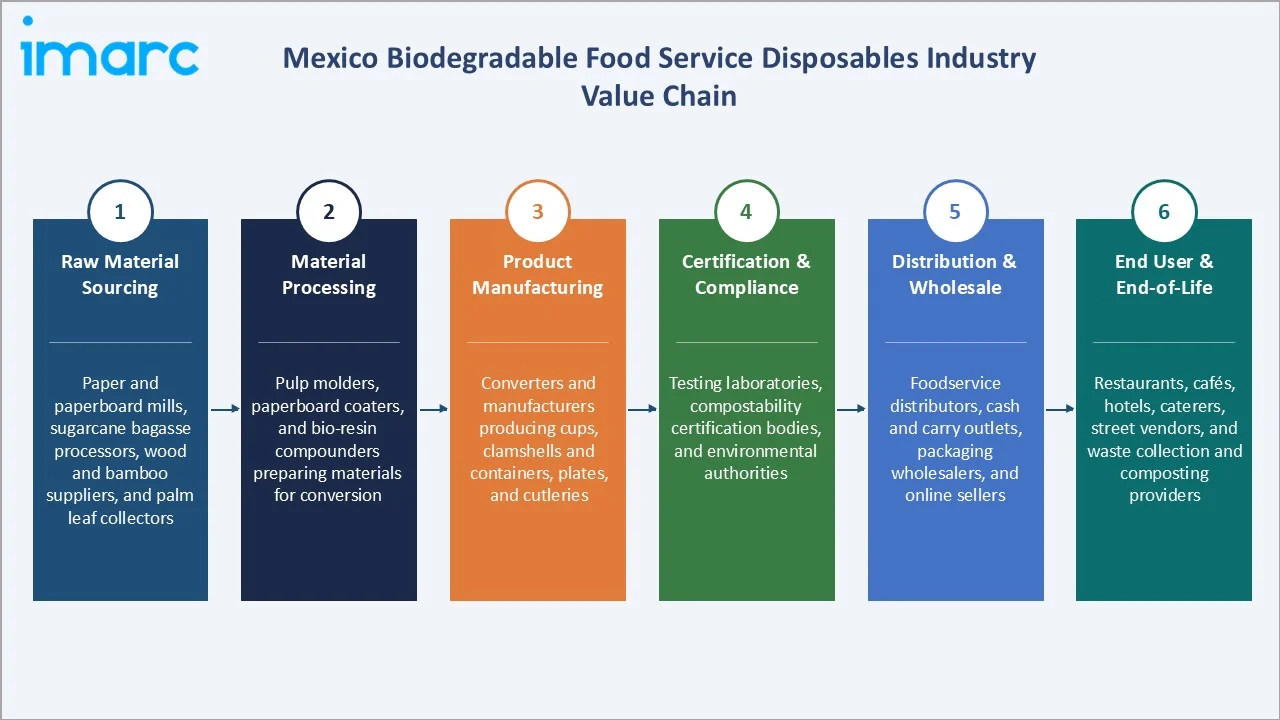
The Mexico biodegradable food service disposables value chain spans six stages, from raw material sourcing through end-user consumption and end-of-life management. Material processing and product manufacturing capture the highest value-add, while certification and compliance capabilities increasingly determine competitive position in this closely regulated category.
|
Stage |
Key Players / Examples |
|
Raw Material Sourcing |
Paper and paperboard mills, sugarcane bagasse processors, wood and bamboo suppliers, and palm leaf collectors |
|
Material Processing |
Pulp molders, paperboard coaters, and bio-resin compounders preparing materials for conversion |
|
Product Manufacturing |
Converters and manufacturers producing cups, clamshells and containers, plates, and cutleries |
|
Certification & Compliance |
Testing laboratories, compostability certification bodies, and environmental authorities |
|
Distribution & Wholesale |
Foodservice distributors, cash and carry outlets, packaging wholesalers, and online sellers |
|
End User & End-of-Life |
Restaurants, cafés, hotels, caterers, street vendors, and waste collection and composting providers |
Vertically integrated manufacturers, especially those controlling material processing and holding recognized certifications, are positioned to capture greater value than import-dependent traders. This advantage is further reinforced by tighter quality control, lower procurement risks, and greater flexibility in meeting evolving customer and regulatory requirements.
Technology Landscape in the Mexico Biodegradable Food Service Disposables Industry
Molded Fiber and Thermoforming Technology
Advanced wet-press and thermoforming lines are improving the strength, smoothness, and dimensional accuracy of molded fiber clamshells, plates, and bowls, helping them compete with foam on both appearance and function.
Bio-Based Coatings and Barrier Innovation
Water-based dispersions and plant-derived linings are replacing conventional polyethylene coatings in cups and containers, improving compostability while maintaining resistance to liquids, grease, and heat.
Biopolymer Resin Development
Producers are refining PLA blends and agro-waste-based resins to raise heat tolerance and durability, allowing compostable cutleries and lids to perform reliably with hot foods and beverages.
Automation and Digital Printing
Automated forming, stacking, and inspection systems are lowering unit costs, while digital printing enables short-run branded cups and containers for cafés and restaurant chains.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Raw Material Type |
Pulp and Paper |
47.6% |
2025 |
|
Product Type |
Cups |
32.8% |
2025 |
|
Distribution Channel |
🔒 |
🔒 |
2025 |
|
Region |
Central Mexico |
44.5% |
2025 |

By Raw Material Type
Pulp and paper command a 47.6% share in 2025, driven by the broad availability of paper cups, paperboard containers, and molded fiber tableware. The segment benefits from established converting capacity, familiar performance, and strong acceptance among quick service restaurants and cafés.
To access detailed market analysis, Request Sample
Biopolymers at 28.4% in 2025 cover PLA-based and agro-waste-based materials used in cutleries, lids, and cup linings, and are gaining ground as resin performance improves.
By Product Type
Cups lead with a 32.8% share in 2025, reflecting high daily consumption of hot and cold beverages across coffee chains, convenience stores, and juice outlets.
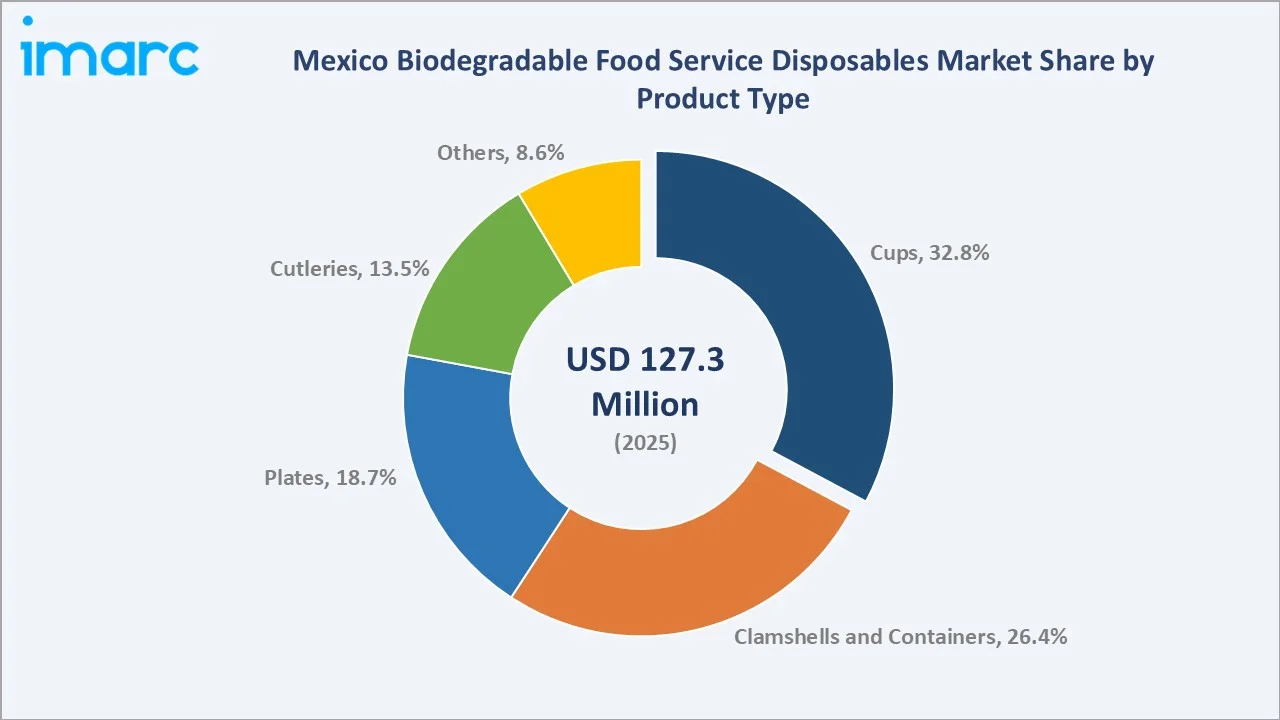
Clamshells and containers at 26.4% are expanding with takeaway and delivery demand. This segment benefits from growing demand for convenient, portion-ready packaging across restaurants, food delivery platforms, and takeaway outlets.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
Central Mexico |
44.5% |
Dense urban population, strict local rules on single-use plastics, and a large concentration of restaurants and cafés |
|
Northern Mexico |
29.8% |
Strong industrial and commercial activity, large retail and foodservice chains, and rising corporate sustainability adoption |
|
Southern Mexico |
16.2% |
Expanding tourism and hospitality sector, growing resort activity, and environmental protection priorities in coastal areas |
|
Others |
9.5% |
Gradual adoption among regional foodservice operators, widening distributor reach, and rising consumer awareness |
Central Mexico at 44.5% in 2025 leads the regional landscape, anchored by Mexico City's early and comprehensive restrictions on plastic disposables and a dense base of restaurants, cafés, and street food vendors. Strong distributor networks and high consumer awareness support sustained regional leadership.
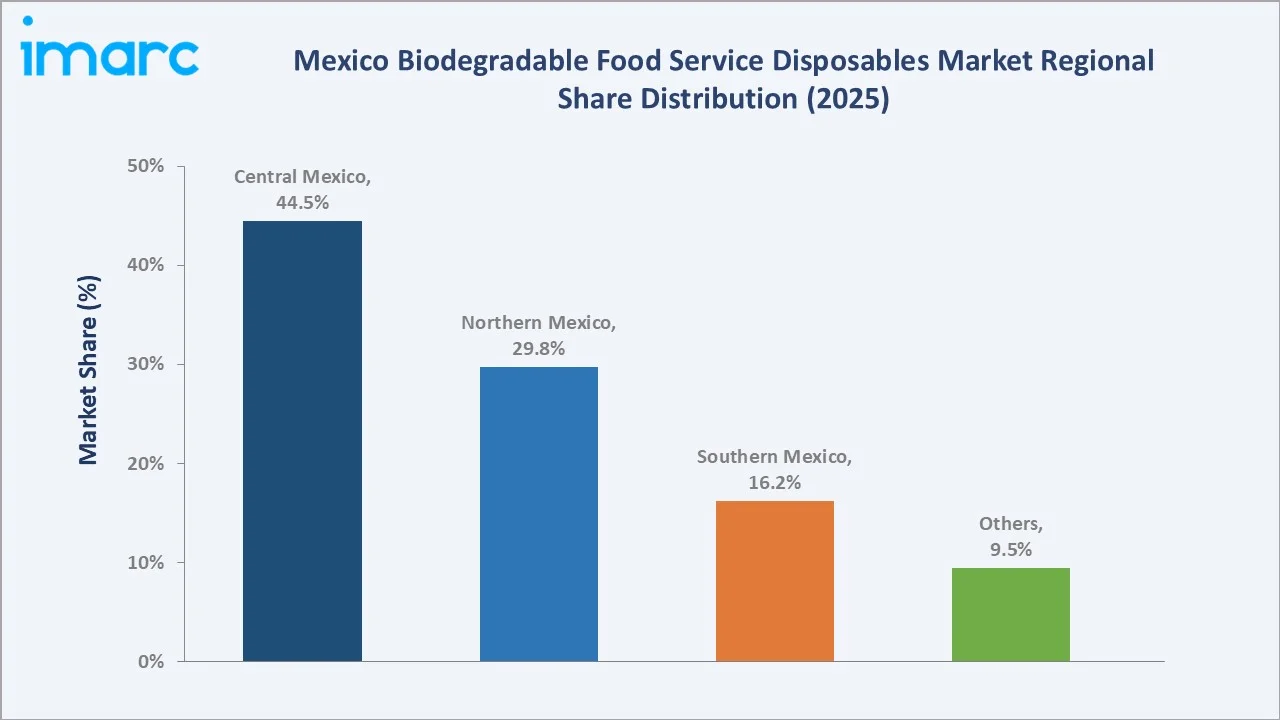
Southern Mexico, at 16.2% in 2025, is the fastest growing region as resorts, hotels, and beach destinations adopt compostable packaging to protect sensitive coastal ecosystems and meet the expectations of international visitors, supporting long-term regional growth through 2034.
Competitive Landscape
The Mexico biodegradable food service disposables market is moderately fragmented, with global packaging groups leading in scale and portfolio breadth, while domestic manufacturers and specialist suppliers compete on price, local availability, and innovative materials. Certification, product performance, and distribution reach form the key competitive differentiators.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
|
Huhtamaki Oyj |
Chinet |
Leader |
Expanding fiber-based foodservice packaging and strengthening sustainable product offerings |
|
Novolex Holdings, LLC |
Eco-Products / EarthChoice |
Leader |
Broadening sustainable packaging portfolio and strengthening manufacturing and distribution reach |
|
Dart Container Corporation |
Dart / SOLO |
Leader |
Growing compostable product lines alongside its established foodservice portfolio |
|
Renovapack S.A. de C.V. |
Renovapack |
Challenger |
Growing certified compostable offerings and customized packaging services |
Key players include Huhtamaki Oyj, Novolex Holdings, LLC, Dart Container Corporation, and Renovapack S.A. de C.V., among others.
Key Company Profiles
Huhtamaki Oyj
Huhtamaki Oyj is a Finland-headquartered global packaging company whose North America segment has production in the United States and Mexico, serving foodservice operators and retail customers.
- Product Portfolio: Paper cups and lids, food containers, and Chinet molded fiber plates and bowls.
- Recent Developments: The company continues to expand its fiber-based foodservice offerings and invest in more sustainable packaging solutions for its customers.
- Strategic Focus: Strengthening its fiber-based foodservice portfolio while advancing sustainable packaging innovation.
Novolex Holdings, LLC
Novolex Holdings, LLC is a Charlotte, North Carolina-headquartered food and specialty packaging manufacturer. The company offers a broad portfolio of sustainable packaging solutions serving food service, retail, and other end-use industries.
- Product Portfolio: Compostable and renewable cups, containers, plates, and cutleries under brands, such as Eco-Products and EarthChoice.
- Recent Developments: The company continues to integrate its expanded packaging portfolio and broaden its range of compostable and renewable foodservice products.
- Strategic Focus: Widening its sustainable foodservice packaging range while building production and distribution capabilities across Mexico.
Dart Container Corporation
Dart Container Corporation is a privately held, United States-based foodservice packaging manufacturer with manufacturing operations in Mexico.
- Product Portfolio: Cups, containers, and dinnerware under the Dart and SOLO brands, including molded fiber plates, bowls, hinged trays, and portion containers.
- Recent Developments: The firm continues to strengthen its molded fiber and paper-based product lines to support customers seeking more sustainable foodservice packaging.
- Strategic Focus: Advancing compostable and fiber-based offerings to complement its established foodservice product range.
Market Concentration Analysis
The Mexico biodegradable food service disposables market is moderately fragmented. Global packaging groups hold a meaningful share of organized supply, while a large number of domestic manufacturers, importers, and distributors serve small restaurants and street food vendors.
Barriers to entry include certification costs, investment in molding and coating equipment, and the need for broad distribution. These factors favor established manufacturers with proven quality and strong relationships with foodservice chains.
Consolidation is gradually increasing as larger packaging companies acquire complementary portfolios and regional players. Partnerships between material innovators, converters, and distributors are further shaping competitive positioning.
Investment & Growth Opportunities
Fastest-Growing Segments
Biopolymers are expanding fastest among raw material types, driven by improved resin performance and demand for compostable cutleries and lids. Clamshells and containers are the fastest-growing product type, supported by rising takeaway and delivery activity.
Emerging Markets
Southern Mexico is the fastest growing region, supported by expanding tourism, new hospitality projects, and stronger environmental priorities in coastal destinations. The region offers untapped opportunity for suppliers with reliable regional distribution.
Venture & Investment Trends
Investment activity is concentrated in molded fiber capacity, bio-based coatings, and agro-waste-derived resins. Capital is also flowing into domestic production to reduce reliance on imports and meet certification requirements.
Future Market Outlook (2026-2034)
The Mexico biodegradable food service disposables market is projected to grow from USD 127.3 Million in 2025 to USD 133.0 Million in 2026, reaching USD 190.2 Million by 2034, registering a CAGR of 4.42% during 2026-2034. The market's anchor value of USD 158.1 Million in 2030 marks a midpoint at which compostable formats move further into the mainstream.
Four forces will shape the market through 2034: implementation of extended producer responsibility; wider enforcement of plastic restrictions across states; improvements in fiber and bioplastic performance; and development of composting infrastructure.
By 2034, biodegradable food service disposables in Mexico are expected to be defined by broader adoption across food service applications, improved material performance, stronger regulatory alignment, and greater availability of composting and waste management infrastructure.
Research Methodology
Primary Research
Primary research included structured interviews with packaging manufacturers, distributors, foodservice procurement managers, and sustainability specialists, validating market sizing, segment mix, and regional demand patterns.
Secondary Research
Secondary sources included publications from SEMARNAT, SEDEMA, INEGI, and SECTUR, state environmental regulations, and annual reports, press releases, and product literature from listed and private packaging companies.
Forecasting Models
Market forecasts used top-down and bottom-up models combining foodservice activity, product consumption patterns, regulatory timelines, and macroeconomic variables. Scenario analysis addressed enforcement pace, raw material costs, and technology adoption.
Mexico Biodegradable Food Service Disposables Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Raw Material Types Covered | Pulp and Paper, Biopolymers, Leaves, Wood |
| Product Types Covered | Cups, Clamshells and Containers, Plates, Cutleries, Others |
| Distribution Channels Covered |
|
| Regions Covered | Northern Mexico, Central Mexico, Southern Mexico, Others |
| Companies Covered | Huhtamaki Oyj, Novolex Holdings, LLC, Dart Container Corporation, Renovapack S.A. de C.V., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Mexico biodegradable food service disposables market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Mexico biodegradable food service disposables market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Mexico biodegradable food service disposables industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Mexico Biodegradable Food Service Disposables Market Report
The Mexico biodegradable food service disposables market size is estimated at USD 133.0 Million in 2026, supported by restrictions on single-use plastics and rising demand for compostable packaging.
The market is projected to grow at a CAGR of 4.42% from 2026-2034, reaching USD 190.2 Million, supported by stronger regulation and wider adoption across foodservice.
Pulp and paper represent the largest raw material type, accounting for 47.6% of the market in 2025, driven by the wide availability and familiar performance of paper cups and molded fiber tableware.
Cups are the largest product type, accounting for 32.8% of the market in 2025, reflecting high daily consumption of hot and cold beverages across cafés and quick service restaurants.
Central Mexico commands 44.5% share in 2025, led by strict local rules on plastic disposables and a dense concentration of restaurants and food vendors.
Leading players include Huhtamaki Oyj, Novolex Holdings, LLC, Dart Container Corporation, and Renovapack S.A. de C.V., among others.
Local plastic bans and the national circular economy framework are pushing operators toward certified compostable packaging, while extended producer responsibility raises accountability for manufacturers.
Higher product costs, limited composting infrastructure, and uneven enforcement across states remain key challenges, slowing adoption among small and price-sensitive foodservice operators.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade