Mexico Electroplating Market Size, Share, Trends and Forecast by Type, Metal Type, End Use Industry, and Region, 2026-2034
Mexico Electroplating Market Size, Share, Trends & Forecast (2026-2034)
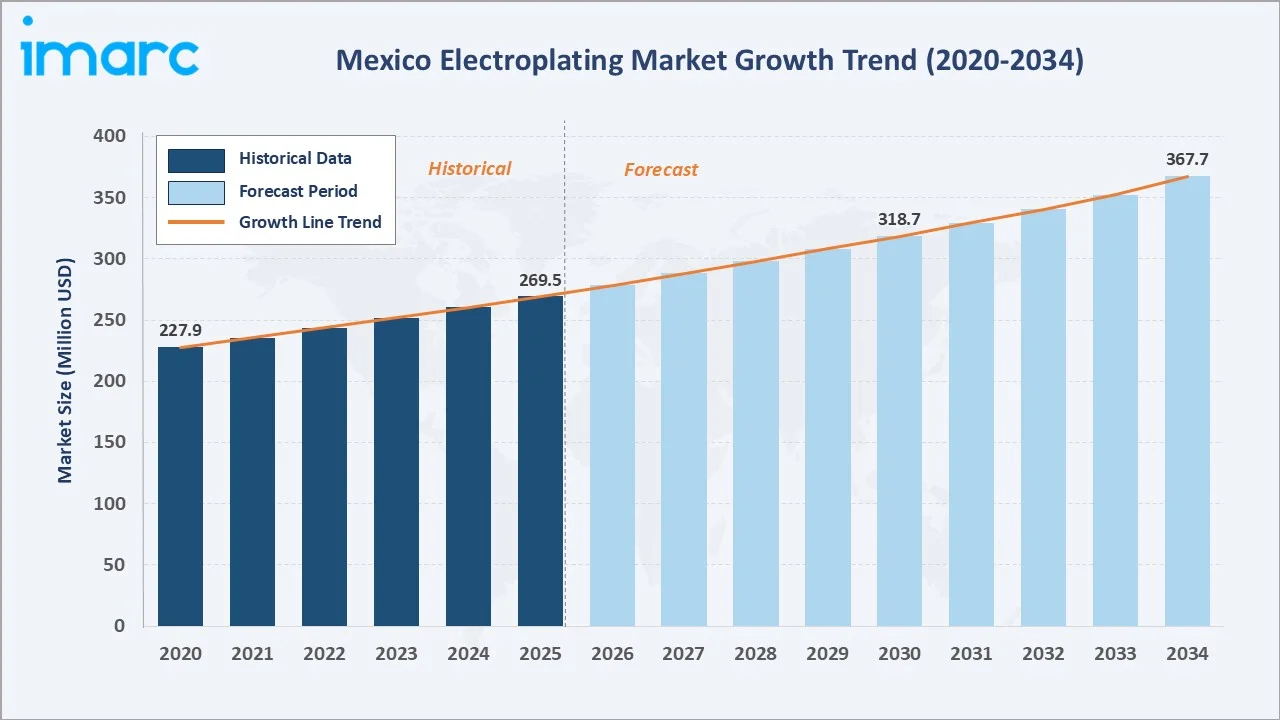
The Mexico electroplating market was valued at USD 269.5 Million in 2025 and is projected to reach USD 367.7 Million by 2034, exhibiting a CAGR of 3.41% during 2026-2034. Expanding automotive nearshoring and rising demand for corrosion-resistant industrial finishes are the primary drivers shaping the market growth.
Rack plating leads the type segment at 36.8%, automotive dominates the end-use industry segment at 41.6%, and Northern Mexico commands 43.5% regional share.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 269.5 Million |
|
Forecast Market Size (2034) |
USD 367.7 Million |
|
CAGR (2026-2034) |
3.41% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Northern Mexico (43.5%, 2025) |
|
Second Largest Region |
Central Mexico (36.7%, 2025) |
|
Leading Type |
Rack Plating (36.8%, 2025) |
|
Leading End-Use Industry |
Automotive (41.6%, 2025) |
The Mexico electroplating market expanded from USD 227.9 Million in 2020 to USD 269.5 Million in 2025, driven by steady industrial output, growing automotive component production, and gradual recovery in manufacturing investment. Anchored at USD 318.7 Million in 2030, the forecast to USD 367.7 Million by 2034 is supported by accelerating nearshoring-led capacity additions and diversification into electronics and aerospace finishing applications.
To get more information on this market, Request Sample
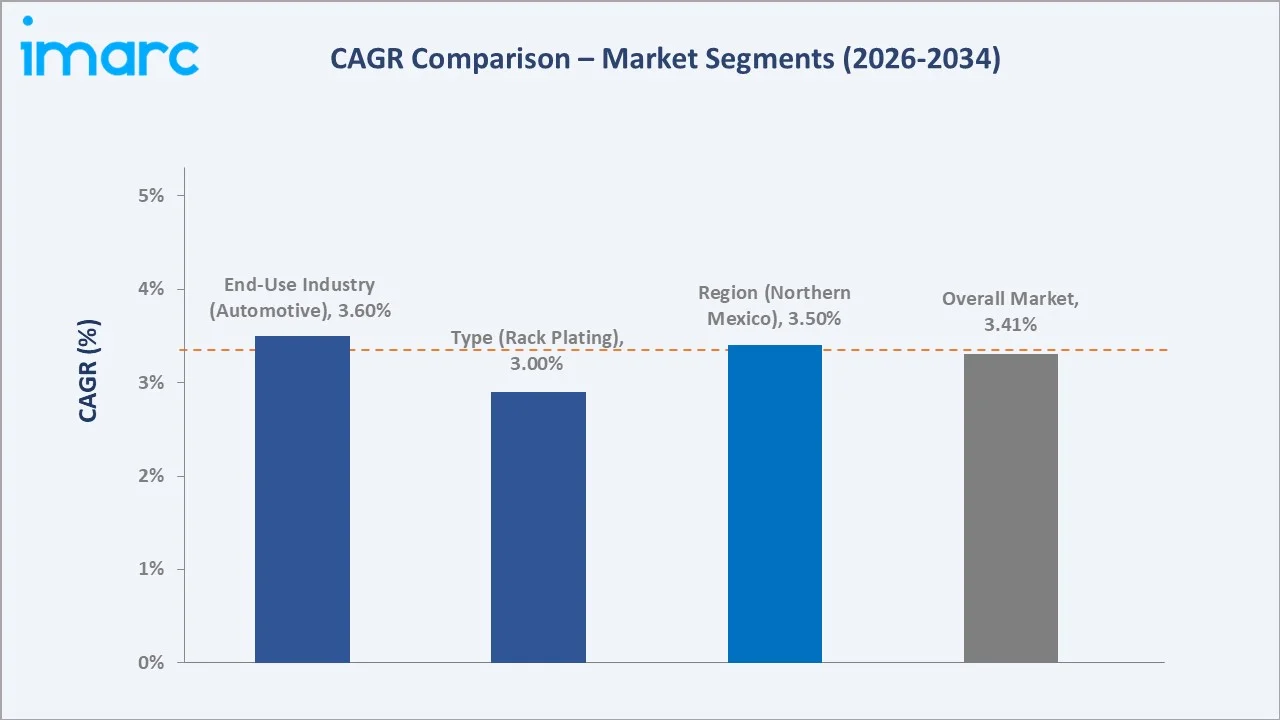
CAGR trajectories across type and end-use industry sub-segments show electrical and electronics and Southern Mexico expanding faster than the overall 3.41% market CAGR, driven by semiconductor-adjacent manufacturing growth, aerospace cluster expansion, and rising nearshoring investment beyond the traditional northern industrial corridor.
Executive Summary
The Mexico electroplating market is on a steady growth trajectory from USD 227.9 Million in 2020 to USD 367.7 Million by 2034. The industry has evolved from manual, small-batch finishing toward automated, quality-certified plating lines serving automotive, electronics, and aerospace manufacturers.
Rack plating leads the type segment at 36.8% in 2025, supported by precision finishing requirements for automotive and electronics components. Automotive dominates the end-use industry segment at 41.6%, reinforced by strong demand for corrosion-resistant and durable finishes in vehicle components. Northern Mexico commands 43.5% of regional share, led by dense automotive and electronics manufacturing clusters along the United States border.
Key Market Insights
|
Insight |
Data |
|
Leading Type |
Rack Plating - 36.8% share (2025) |
|
Second Largest Type |
Barrel Plating - 28.7% share (2025) |
|
Leading End-Use Industry |
Automotive - 41.6% share (2025) |
|
Second Largest End-Use Industry |
Electrical and Electronics - 20.3% share (2025) |
|
Leading Region |
Northern Mexico - 43.5% share (2025) |
|
Second Largest Region |
Central Mexico - 36.7% share (2025) |
|
Top Companies |
MKS Inc., Element Solutions Inc., C. Uyemura & Co., Ltd., Surventis, JCU Corporation |
Key Analytical Observations Expanding On the Data Above:
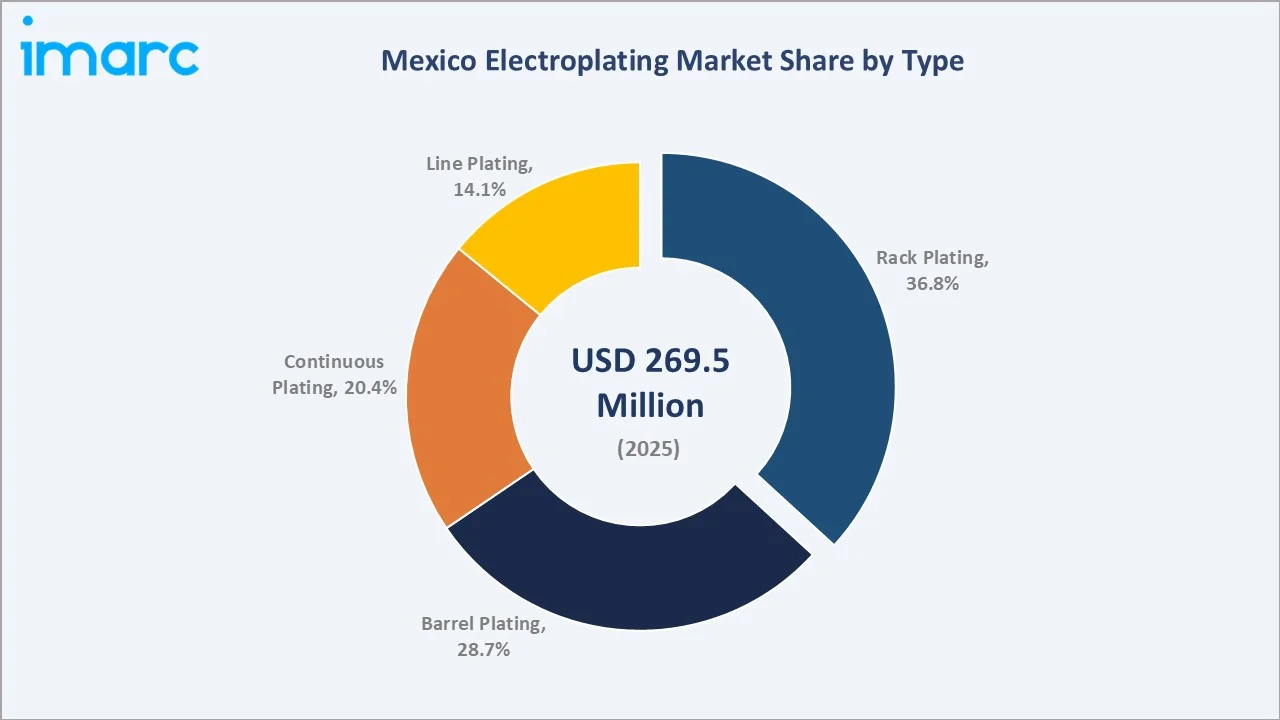
- Rack plating leadership at 36.8% reflects preference for high-quality, uniform coverage on automotive body hardware, electronic connectors, and precision industrial components requiring tight thickness tolerances.
- Barrel plating at 28.7% serves high-volume small-part finishing, such as fasteners, brackets, and hardware, valued for its cost efficiency across large production batches.
- Automotive leadership at 41.6% is anchored by Mexico's position as a top vehicle-producing nation, with plants across Northern Mexico and Central Mexico requiring corrosion-resistant plated components for chassis, trim, and under-hood parts.
- Electrical and Electronics share at 20.3% is supported by rising demand for plated connectors, terminals, housings, and other components requiring reliable conductivity, corrosion resistance, and consistent surface finishes.
- Northern Mexico at 43.5% dominates regional share, anchored by Chihuahua, Nuevo Leon, and Baja California, supported by dense automotive and electronics manufacturing clusters along the United States border.
Mexico Electroplating Market Overview
Electroplating is a surface-finishing process that deposits a thin metallic layer, such as nickel, chromium, zinc, or copper, onto a substrate through an electrochemical reaction, enhancing corrosion resistance, wear resistance, conductivity, and appearance.
The Mexican ecosystem integrates chemical and metal substrate suppliers, plating equipment providers, job-shop and captive plating operators, environmental regulators, and downstream OEM manufacturers. Proximity to the United States, established free trade agreements, and a deep tier-1 and tier-2 automotive supplier base position Mexico as a growing hub for surface finishing within North American supply chains.
Market Dynamics
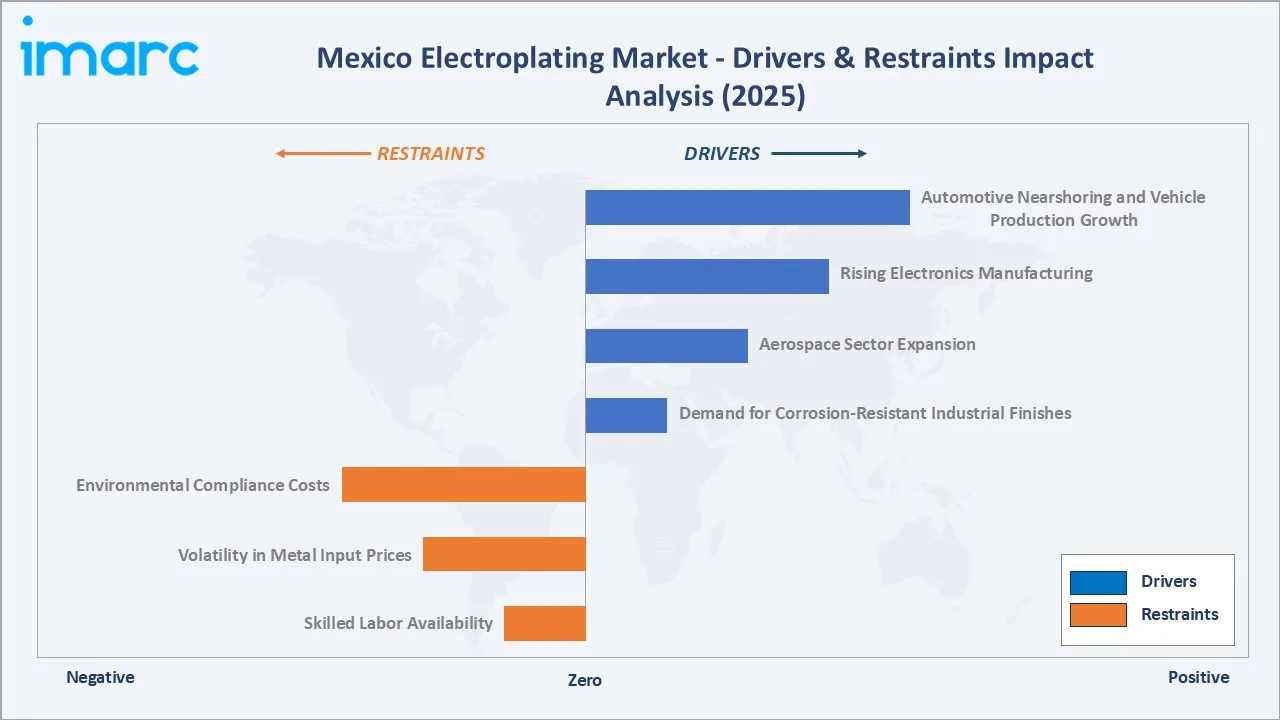
To evaluate market opportunities, Request Sample
Market Drivers
- Automotive Nearshoring and Vehicle Production Growth: Sustained relocation of automotive assembly and component manufacturing to Mexico is expanding demand for plated parts across chassis, trim, and powertrain applications.
- Rising Electronics Manufacturing: Expanding production of electronic components and consumer devices is increasing demand for copper, nickel, and precious-metal plating for conductivity and durability. In Mexico, electrical and electronic equipment reached USD 107 Billion in 2024, underscoring the scale of downstream demand for plated components.
- Aerospace Sector Expansion: Growing aerospace component manufacturing in Queretaro, Chihuahua, and Baja California is lifting demand for precision plating meeting strict aerospace-grade specifications.
- Demand for Corrosion-Resistant Industrial Finishes: Expanding industrial machinery production is driving adoption of zinc, nickel, and chrome plating for extended component life in humid, corrosive operating environments.
Market Restraints
- Environmental Compliance Costs: Wastewater treatment, hazardous chemical handling, and emissions-control requirements are raising operating costs for plating facilities, particularly smaller job shops with limited capital for upgrades.
- Volatility in Metal Input Prices: Fluctuating nickel, chromium, and copper prices create margin pressure for platers operating on fixed-price contracts with automotive and industrial customers.
- Skilled Labor Availability: Shortages of trained plating technicians and quality-control personnel in fast-growing industrial corridors can constrain capacity expansion for platers scaling operations.
Market Opportunities
- Trivalent Chromium and Eco-Friendly Chemistries: Transitioning from hexavalent to trivalent chromium and cyanide-free processes lets platers differentiate on sustainability while meeting tightening environmental standards.
- Electronics and Semiconductor-Adjacent Plating: Growing semiconductor packaging investment in Jalisco and Chihuahua creates opportunities for specialized precious-metal and copper plating services.
Market Challenges
- Offshore and Import Competition: Competitively priced plated components imported from Asia continue to pressure domestic platers on cost, particularly for standardized parts.
- Wastewater and Hazardous Waste Management: Meeting evolving discharge and disposal standards requires ongoing capital investment, creating complexity for facilities without dedicated compliance teams.
Emerging Market Trends
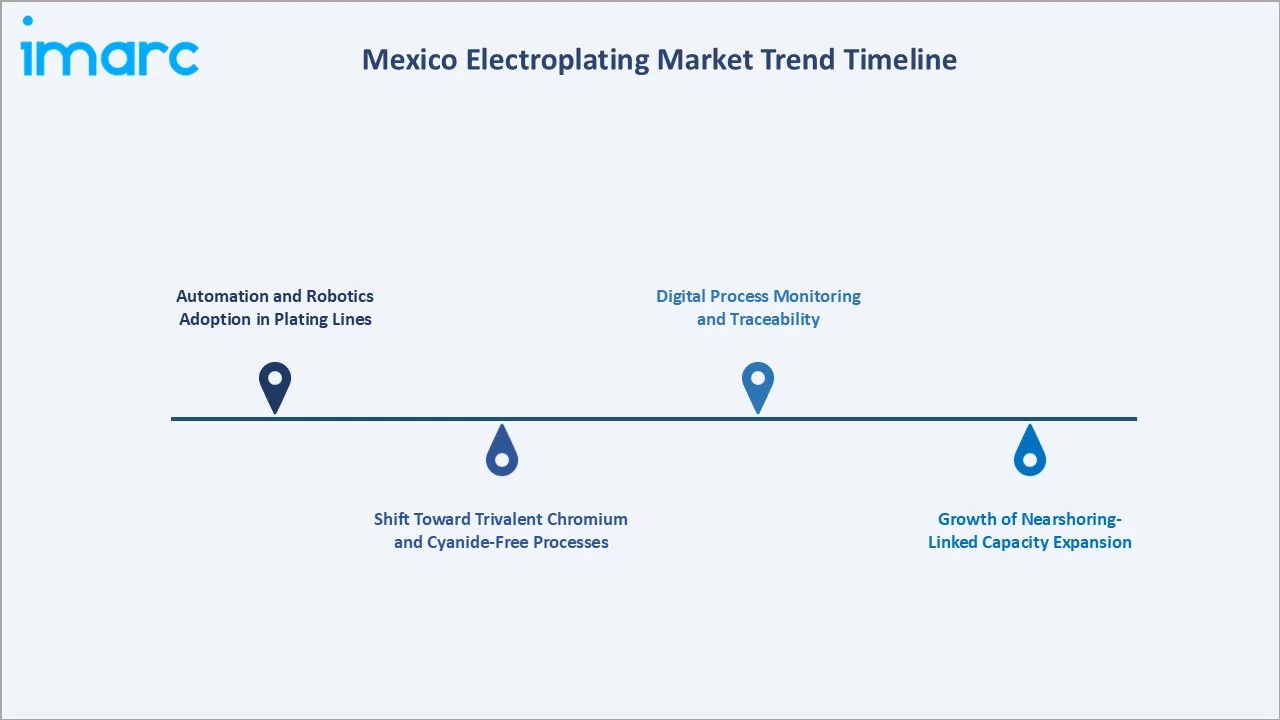
1. Automation and Robotics Adoption in Plating Lines
Mexican plating operators are increasingly automating material handling, rectifier control, and quality inspection to improve throughput and consistency. Automation is also improving process control by enabling real-time monitoring of plating parameters, reducing manual intervention, and supporting more consistent coating quality across production runs.
2. Shift Toward Trivalent Chromium and Cyanide-Free Processes
Operators are transitioning from hexavalent chromium and cyanide-based chemistries toward trivalent and cyanide-free alternatives that reduce regulatory exposure and worker safety risk while maintaining coating performance.
3. Growth of Nearshoring-Linked Capacity Expansion
New plating capacity is being added near automotive and electronics manufacturing clusters in Northern Mexico and Central Mexico, as OEMs seek finishing suppliers co-located with assembly operations to reduce logistics time.
4. Digital Process Monitoring and Traceability
Adoption of sensor-based bath monitoring and digital quality records is expanding, driven by automotive and aerospace customer requirements for full component traceability and process documentation.
Industry Value Chain Analysis
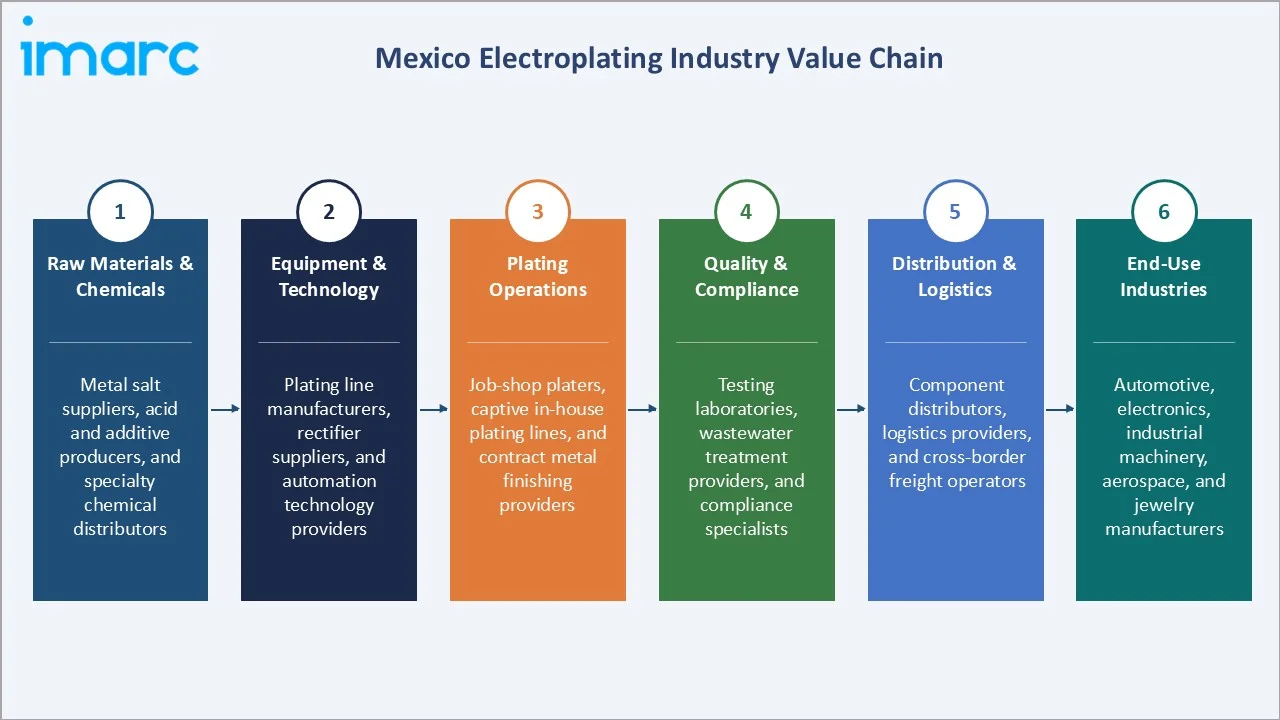
The Mexico electroplating value chain spans six stages from raw material and chemical supply through end-use industry consumption. Equipment technology and plating operations capture the highest value-add, while quality compliance increasingly determines competitive position in this regulated category.
|
Stage |
Key Players / Examples |
|
Raw Materials & Chemicals |
Metal salt suppliers, acid and additive producers, and specialty chemical distributors supporting plating bath formulation |
|
Equipment & Technology |
Plating line manufacturers, rectifier suppliers, and automation technology providers enabling process control |
|
Plating Operations |
Job-shop platers, captive in-house plating lines, and contract metal finishing providers |
|
Quality & Compliance |
Testing laboratories, wastewater treatment providers, and environmental compliance specialists |
|
Distribution & Logistics |
Component distributors, logistics providers, and cross-border freight and warehousing operators |
|
End-Use Industries |
Automotive, electronics, industrial machinery, aerospace, and jewelry manufacturers |
Vertically integrated operators, particularly those combining in-house chemical formulation with automated plating lines, are positioned to capture greater value than job shops reliant on third-party inputs and manual processes.
Technology Landscape in the Mexico Electroplating Industry
Automated Plating Line Systems
Modern Mexican plating facilities are deploying programmable logic controller-based line automation that manages rectifier current, bath chemistry, and part transfer with minimal manual intervention, improving coating consistency.
Trivalent and Non-Cyanide Chemistries
Chemical suppliers are introducing trivalent chromium, non-cyanide copper, and cyanide-free zinc systems that reduce hazardous waste generation while meeting automotive and aerospace specifications for corrosion resistance and adhesion.
Digital Process Monitoring
Sensor-based bath analysis and digital record-keeping systems enable real-time monitoring of plating thickness, temperature, and chemical concentration, supporting the traceability requirements of automotive and aerospace quality systems.
Wastewater Treatment and Recovery
Investment in closed-loop rinse water recovery and metal recovery systems is expanding as platers respond to tightening discharge standards, reducing environmental impact and raw material costs.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Rack Plating |
36.8% |
2025 |
|
Metal Type |
🔒 |
🔒 |
2025 |
|
End-Use Industry |
Automotive |
41.6% |
2025 |
|
Region |
Northern Mexico |
43.5% |
2025 |

By Type
Rack plating commands a 36.8% share in 2025, driven by its suitability for precision finishing on automotive fasteners, electronic connectors, and decorative components requiring uniform coating thickness. The segment benefits from strong quality control and compatibility with complex part geometries.
To access detailed market analysis, Request Sample
Barrel plating follows at 28.7% in 2025, serving high-volume small-part finishing such as fasteners, washers, and clips.
By End-Use Industry
Automotive leads the end-use industry segment with a 41.6% share in 2025, reflecting Mexico's position as a major vehicle and auto-parts manufacturing hub requiring plated components for chassis, trim, and under-hood applications.
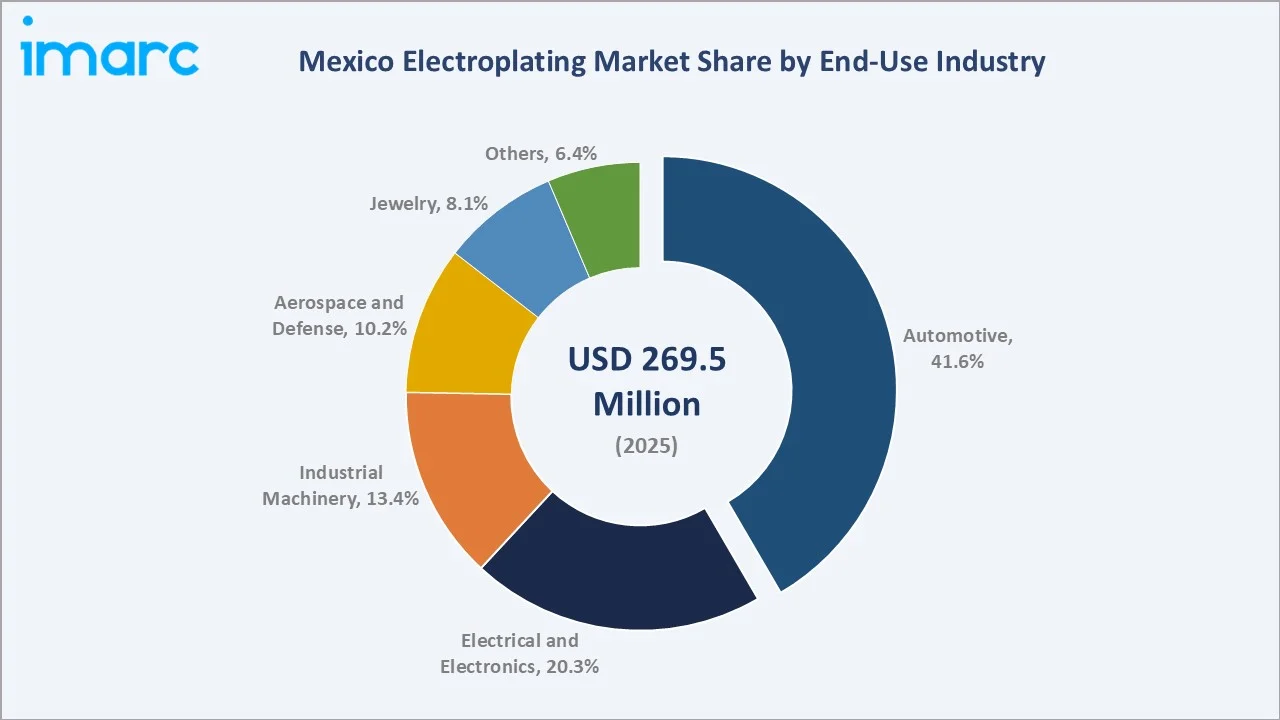
Electrical and electronics follow at 20.3%, supported by growing connector and printed circuit board finishing demand.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
Northern Mexico |
43.5% |
Strong automotive and electronics manufacturing base, proximity to the United States border, and established industrial infrastructure supporting large-scale plating operations |
|
Central Mexico |
36.7% |
Established automotive assembly plants, growing industrial machinery production, and expanding logistics connectivity to domestic and export markets |
|
Southern Mexico |
12.8% |
Emerging nearshoring investment, new industrial park development, and government incentives supporting manufacturing diversification |
|
Others |
7.0% |
Smaller-scale regional manufacturing activity and localized plating service demand across dispersed industrial zones |
Northern Mexico at 43.5% in 2025 leads the regional landscape, anchored by Chihuahua, Nuevo Leon, Baja California, and Coahuila. Dense automotive and electronics manufacturing clusters, proximity to the United States border, and mature industrial infrastructure support sustained leadership across both automotive and electronics-focused plating operations.
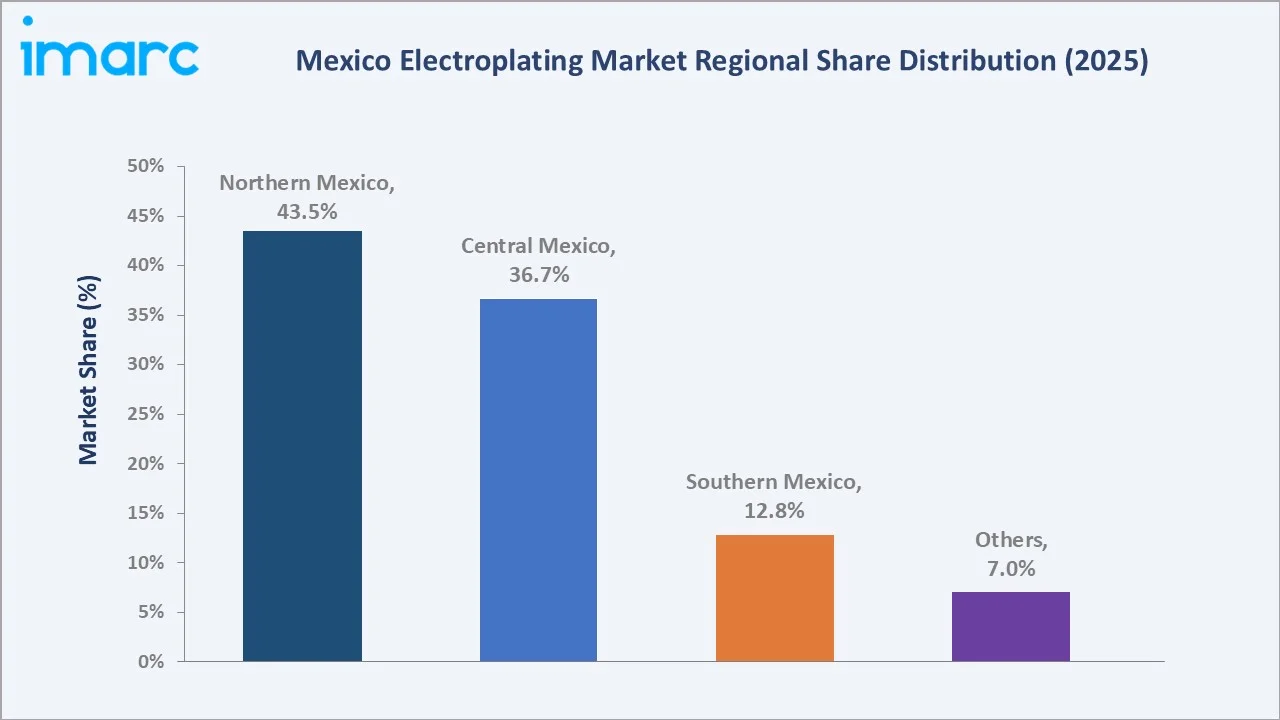
Southern Mexico at 12.8% is the fastest growing region. Expanding nearshoring investment, new industrial park development, and government incentives targeting manufacturing diversification are accelerating regional capacity additions through 2034.
Competitive Landscape
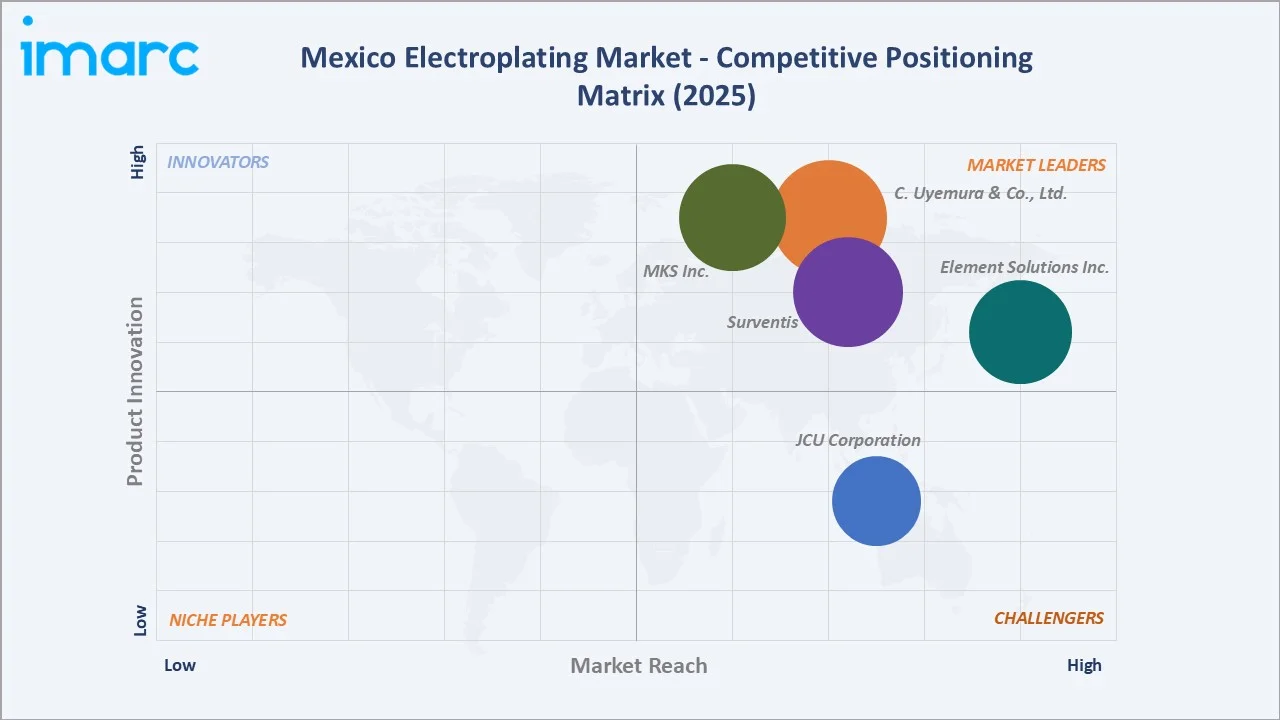
The Mexico electroplating market is moderately fragmented, with established global chemical and technology suppliers competing alongside regional and local plating service providers. Technology depth, chemical portfolio breadth, and proximity to automotive and electronics manufacturing clusters form the key competitive differentiators.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
|
MKS Inc. |
Atotech Electrolytic Plating |
Leader |
Technology-driven electroplating solutions with global manufacturing footprint |
|
Element Solutions Inc. |
MacDermid Enthone |
Leader |
Specialty chemistry provider expanding metal finishing partnerships in Mexico |
|
C. Uyemura & Co., Ltd. |
Uyemura Advanced Plating Chemistries |
Leader |
Precision plating chemistry for electronics and automotive components |
|
Surventis |
Chemetall Surface Treatment Solutions |
Leader |
Global surface treatment portfolio supporting automotive and industrial finishing |
|
JCU Corporation |
JCU Surface Treatment Chemical Products |
Challenger |
Specialty chemical provider focused on precision electronics finishing |
Key players include MKS Inc., Element Solutions Inc., C. Uyemura & Co., Ltd., Surventis, and JCU Corporation, among others.
Key Company Profiles
MKS Inc.
MKS Inc. is a global provider of foundational technologies for semiconductor manufacturing, electronics, and industrial applications. Its Atotech business supplies electroplating chemistry, equipment, and software for surface finishing applications worldwide.
- Product Portfolio: Plating chemistries and equipment covering copper, nickel, chromium, and specialty finishing systems, supporting printed circuit boards, semiconductor packaging, and general metal finishing applications.
- Recent Developments: The company continues to expand its surface finishing solutions through new chemistry, equipment, and process technologies designed to improve plating performance, production efficiency, and sustainability across electronics and industrial applications.
- Strategic Focus: Strengthening its integrated chemistry-and-equipment offering to support automotive and electronics finishing applications across global manufacturing markets.
Element Solutions Inc.
Element Solutions Inc. is a United States-based specialty chemicals company serving the electroplating and metal finishing industry, supplying plating chemistries for automotive, industrial, and decorative finishing applications globally.
- Product Portfolio: A broad range of nickel, chromium, zinc, and copper plating chemistries, along with pretreatment and specialty finishing systems for automotive, industrial, and general metal finishing customers.
- Recent Developments: The company continues to expand its metal finishing portfolio and strengthen customer partnerships across key manufacturing regions.
- Strategic Focus: Growing its specialty chemistry offerings to support automotive and industrial metal finishing customers worldwide.
C. Uyemura & Co., Ltd.
C. Uyemura & Co., Ltd. is a Japan-based surface finishing chemicals and machinery company serving electronics, automotive, and industrial customers worldwide.
- Product Portfolio: Plating chemicals and machinery for printed wiring boards, electronic components, and industrial applications, including electroless plating and precious-metal plating systems.
- Recent Developments: The company continues to expand its surface finishing technology footprint across global markets, supporting electronics and automotive customers.
- Strategic Focus: Expanding precision plating chemistry offerings for electronics and automotive components, leveraging long-standing expertise in surface finishing.
Market Concentration Analysis
The Mexico electroplating market is moderately fragmented, with global specialty chemical suppliers competing alongside numerous regional plating providers. Top players collectively hold a meaningful, though not dominant, share of supply, while plating operations remain highly distributed across job shops and captive facilities.
Barriers to entry include the capital intensity of automated plating lines, environmental permitting requirements, and technical expertise needed to meet automotive and aerospace quality certifications, favoring established suppliers and well-capitalized operators.
Consolidation is gradually increasing as larger chemical suppliers pursue partnerships and investments in regional plating operators to strengthen technical capabilities across Mexico's growing industrial corridors.
Investment & Growth Opportunities
Fastest-Growing Segments
Electrical and electronics expand fastest among end-use industries, driven by growing semiconductor packaging and connector manufacturing investment. Continuous plating is the fastest-growing type segment, supported by wire and strip finishing demand.
Emerging Markets
Southern Mexico is the fastest growing region, anchored by new industrial park development and government incentives. Rising manufacturing activity and expanding automotive and electronics investments are supporting greater demand for electroplating services across the region.
Venture & Investment Trends
Investment is concentrated in automated plating line technology, wastewater treatment and recovery systems, and eco-friendly chemistry development, alongside partnerships between global chemical suppliers and regional plating operators seeking expanded technical capabilities.
Future Market Outlook (2026-2034)
The Mexico electroplating market is forecast to expand from USD 269.5 Million in 2025 to USD 367.7 Million by 2034 at a CAGR of 3.41%, adding roughly USD 98.2 Million in incremental market value over the forecast period.
Three forces will shape the market through 2034: continued automotive and electronics nearshoring investment; gradual adoption of trivalent chromium and lower-emission plating chemistries; and expanding aerospace component manufacturing across established industrial clusters.
By 2034, the market is expected to be defined by higher automation, tighter environmental compliance, and closer integration with automotive, electronics, and aerospace OEM supply chains, as manufacturers favor regionally located, quality-certified finishing partners.
Research Methodology
Primary Research
Primary research included structured discussions with plating facility operators, component manufacturers, chemical suppliers, and industry association representatives, validating market sizing, segment mix, and regional demand patterns.
Secondary Research
Secondary sources included Mexico's Secretaria de Economia investment data, Instituto Nacional de Estadistica y Geografia manufacturing statistics, Federacion Mexicana de la Industria Aeroespacial trade data, and disclosures from major plating suppliers.
Forecasting Models
Market forecasts used top-down and bottom-up models combining automotive and electronics production volumes, plating capacity trends, and regional investment data. Scenario analysis addressed nearshoring pace, regulatory change, and input price volatility.
Mexico Electroplating Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Barrel Plating, Rack Plating, Continuous Plating, Line Plating |
| Metal Types Covered | Gold, Zinc, Platinum, Copper, Nickel, Chromium, Others |
| End Use Industries Covered | Automotive, Electrical and Electronics, Aerospace and Defense, Jewelry, Industrial Machinery, Others |
| Regions Covered | Northern Mexico, Central Mexico, Southern Mexico, Others |
| Companies Covered | MKS Inc., Element Solutions Inc., C. Uyemura & Co., Ltd., Surventis, JCU Corporation, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Mexico electroplating market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Mexico electroplating market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Mexico electroplating industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Mexico Electroplating Market Report
The Mexico electroplating market was valued at USD 269.5 Million in 2025, driven by automotive nearshoring, growing electronics manufacturing, and rising demand for corrosion-resistant industrial finishes.
The market is projected to grow at a CAGR of 3.41% from 2026-2034, reaching USD 367.7 Million, supported by expanding automotive, electronics, and aerospace component manufacturing.
Rack plating leads at 36.8% in 2025, driven by precision finishing requirements for automotive fasteners, electronic connectors, and decorative components requiring uniform coating thickness.
Automotive dominates at 41.6% in 2025, reflecting Mexico's position as a major vehicle and auto-parts manufacturing hub requiring plated components for chassis, trim, and under-hood applications.
Northern Mexico commands 43.5% in 2025, led by dense automotive and electronics manufacturing clusters near the United States border in Chihuahua, Nuevo Leon, and Baja California.
Leading players include MKS Inc., Element Solutions Inc., C. Uyemura & Co., Ltd., Surventis, and JCU Corporation, among others.
Tightening wastewater treatment and hazardous chemical handling requirements are raising compliance costs, prompting operators to adopt trivalent chromium and other lower-emission plating chemistries.
Key trends include automation and robotics adoption, trivalent chromium transition, nearshoring-linked capacity expansion, and growing digital process monitoring for automotive and aerospace traceability requirements.
Automated plating line systems, digital process monitoring, and trivalent chromium chemistries are enabling platers to improve consistency, meet environmental standards, and satisfy OEM traceability requirements.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade