
Mexico Orthopedic Devices Market Size, Share, Trends and Forecast by Product Type, End User, and Region, 2026-2034
Mexico Orthopedic Devices Market Size, Share, Trends & Forecast (2026-2034)
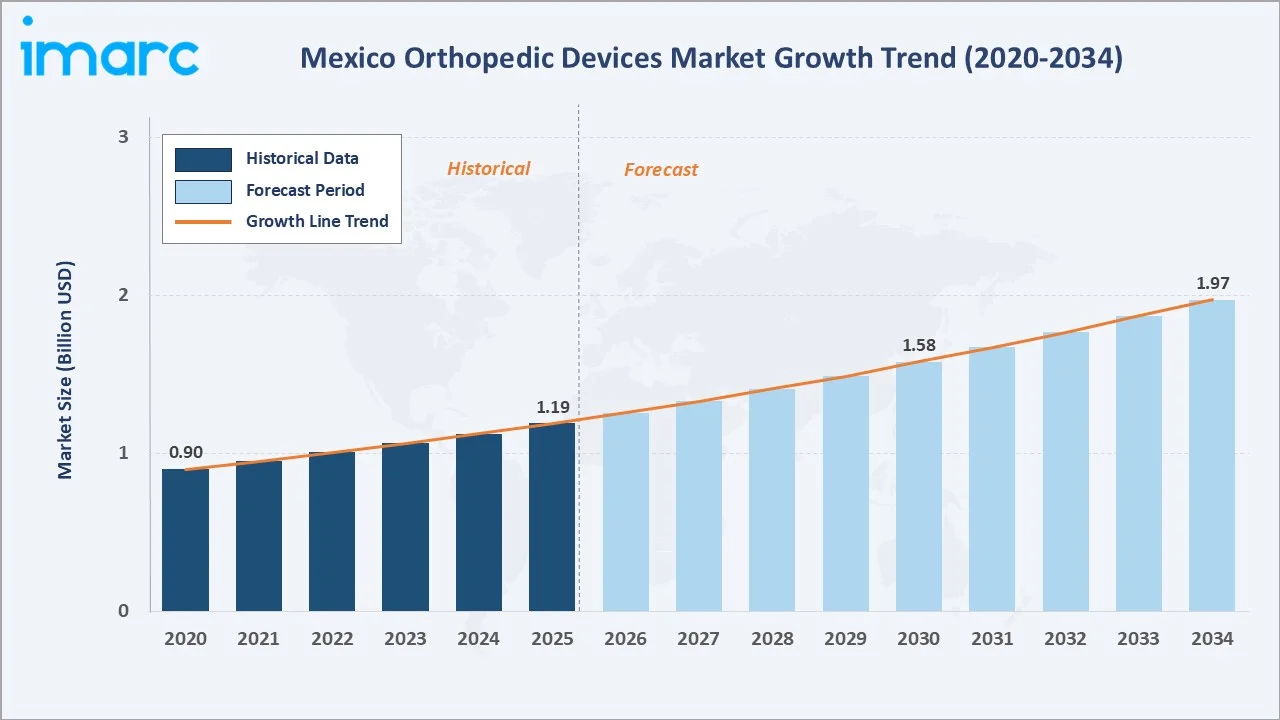
The Mexico orthopedic devices market grew from USD 1.19 Billion in 2025 to USD 1.26 Billion in 2026 and is projected to reach USD 1.97 Billion by 2034, growing at a CAGR of 5.76% during 2026-2034. Mexico's orthopedic devices market is driven by the country's aging population generating rising osteoarthritis and joint disease burden, universal healthcare coverage expansion funding orthopedic implant access for previously uninsured populations, Mexico's emergence as a leading medical tourism destination for cost-competitive joint replacement procedures, and robotic-assisted surgery technology adoption at premier private hospitals. Joint replacement and orthopedic implants lead at 43.8%, hospitals dominate end users at 76.4%, and Central Mexico commands a 44.8% regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 1.19 Billion |
|
Market Size (2026) |
USD 1.26 Billion |
|
Forecast Market Size (2034) |
USD 1.97 Billion |
|
CAGR (2026-2034) |
5.76% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product Type |
Joint Replacement/Orthopedic Implants (43.8%, 2025) |
|
Dominant End User |
Hospitals (76.4%, 2025) |
|
Leading Region |
Central Mexico (44.8%, 2025) |
The Mexico orthopedic devices market grew from USD 0.90 Billion in 2020 to USD 1.19 Billion by 2025 and is estimated to reach USD 1.26 Billion in 2026. The market is projected to reach USD 1.58 Billion by 2030 and USD 1.97 Billion by 2034.
To get more information on this market, Request Sample
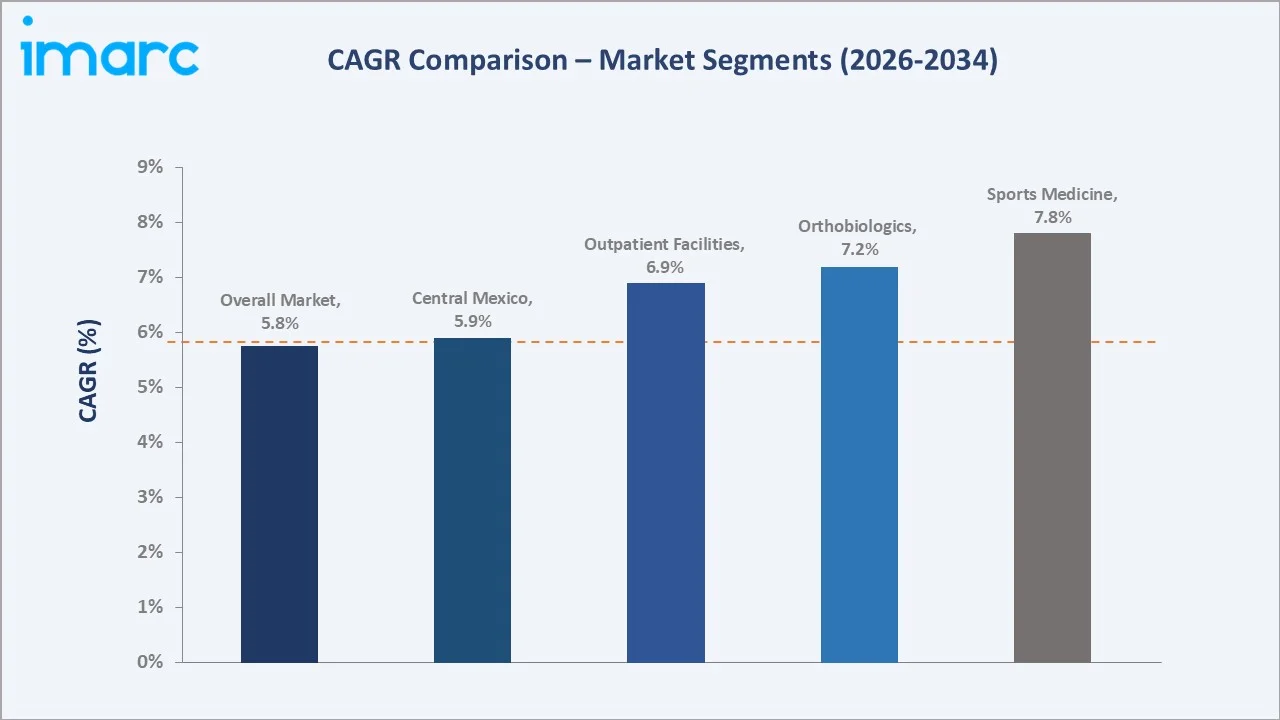
Sports medicine is the fastest-growing segment at ~7.8% CAGR through rising sports injury incidence among Mexico's active youth population and expanding arthroscopic surgical capability. Orthobiologics grow at ~7.2% CAGR through PRP, bone graft, and stem cell biologic procedure adoption in joint preservation. Outpatient facilities expanded at ~6.9% CAGR through ambulatory surgical center development enabling outpatient joint replacement procedures.
Executive Summary
The Mexico orthopedic devices market is a high-growth segment of Mexico's medical device industry, driven by a powerful combination of demographic-driven procedure volume growth, healthcare coverage expansion, medical tourism development, and surgical technology advancement. Joint replacement and orthopedic implants command 43.8% through Mexico's rising knee and hip osteoarthritis prevalence and aging population demographics. Hospitals lead end users at 76.4% through concentrated orthopedic surgical capability. Central Mexico dominates at 44.8% through unmatched concentration of orthopedic surgical expertise and premium hospital infrastructure.
Key Market Insights
|
Insight |
Data |
|
Dominant Product Type |
Joint Replacement/Orthopedic Implants - 43.8% share (2025) |
|
Dominant End User |
Hospitals - 76.4% share (2025) |
|
Leading Region |
Central Mexico - 44.8% (2025) |
|
Key Market Opportunity |
Rising demand for minimally invasive orthopedic procedures, advanced joint replacement implants, personalized and 3D-printed devices, robotic-assisted surgery, and expanding orthopedic care for the aging population |
Key analytical observations supporting the Above Data:
- Joint Replacement and Orthopedic Implants at 43.8%: Joint replacement and orthopedic implants, encompassing total knee arthroplasty (TKA), total hip arthroplasty (THA), unicompartmental knee replacement, and shoulder arthroplasty, command Mexico's orthopedic market through the high-value nature of implant systems, the large and growing patient population requiring joint replacement from age-related osteoarthritis, and Mexico's public health system prioritizing joint replacement procedures for its beneficiaries suffering from musculoskeletal disease.
- Hospitals at 76.4%: Hospitals represent the dominant end user for Mexico orthopedic devices through the surgical facility, sterile field, anesthesia, imaging, and post-operative care requirements of orthopedic implant procedures that necessitate full hospital infrastructure.
- Central Mexico at 44.8%: Central Mexico's market dominance reflects its position as Mexico's orthopedic surgical center of excellence, with major hospitals appearing on international medical tourism referral networks serving US patients, generating premium-priced orthopedic procedure volumes that elevate the region's average device ASP above the national orthopedic market average.
Mexico Orthopedic Devices Market Overview
The Mexico orthopedic devices market encompasses implants, instruments, and biologics used in surgical treatment of musculoskeletal conditions across joint reconstruction (knee, hip, shoulder, ankle), fracture fixation and trauma management, spine surgery, sports medicine arthroscopy, and orthobiologic therapies for cartilage and bone repair. Device procurement in public hospitals occurs through national tender processes where regulatory bodies issue annual orthopedic implant framework agreements, while private hospital procurement occurs through manufacturer direct sales and authorized distributor relationships.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
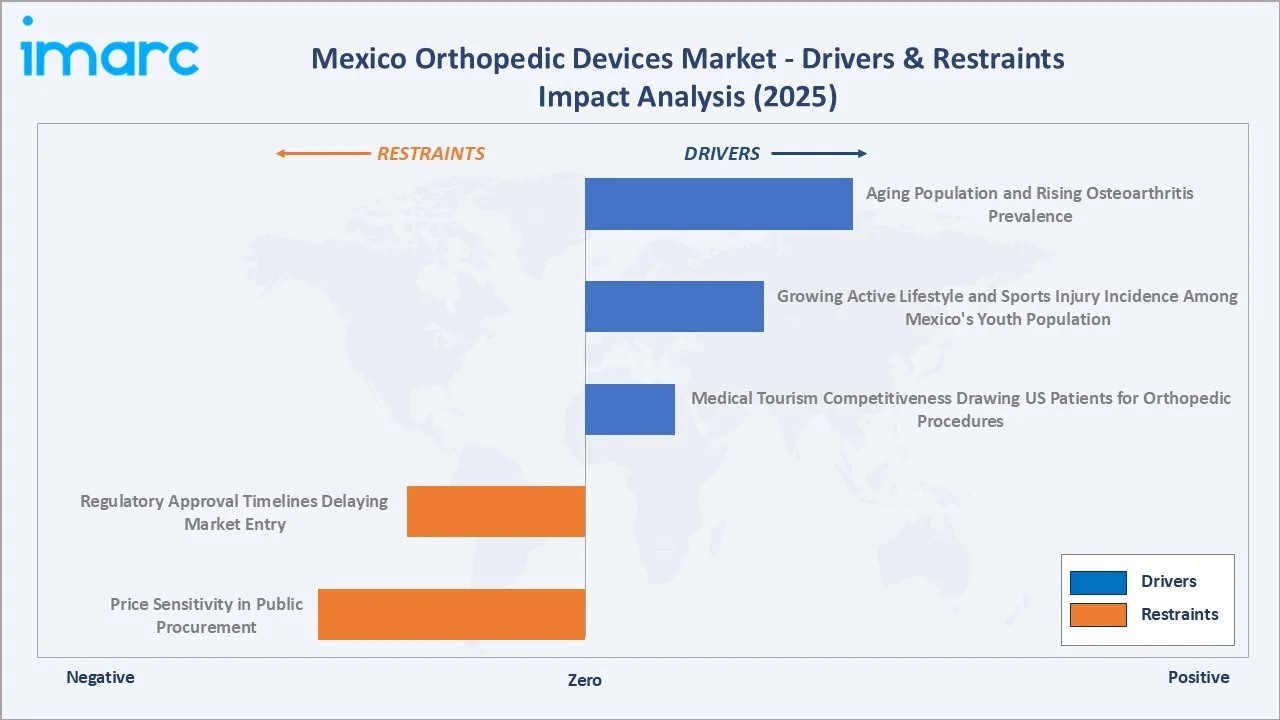
- Aging Population and Rising Osteoarthritis Prevalence: Mexico is experiencing rapid demographic aging, with the median age projected to increase from around 30.5 years currently to 43 years by 2050. Mexico's demographic transition is generating a structural increase in the patient population requiring joint replacement for end-stage osteoarthritis. Mexico's combined obesity prevalence and aging demographics create an above-average osteoarthritis burden for a middle-income country, with most of the Mexicans affected by knee osteoarthritis requiring orthopedic intervention.
- Growing Active Lifestyle and Sports Injury Incidence Among Mexico's Youth Population: Mexico's youth population of 41.0% under 25 is increasingly engaged in organized sports, generating significant anterior cruciate ligament (ACL) tears, meniscal injuries, rotator cuff tears, and ankle ligament injuries requiring sports medicine arthroscopic surgical treatment. Mexico's dedicated sports medicine and arthroscopic surgeons are performing a growing volume of arthroscopic reconstructions where major players compete for procedure-specific device selection.
- Medical Tourism Competitiveness Drawing US Patients for Orthopedic Procedures: Mexico's cost advantage for orthopedic procedures is attracting a growing volume of US patients without insurance coverage or with high-deductible plans to Mexico's premium private hospitals, particularly at border city facilities and at internationally accredited hospitals. Medical tourism orthopedic procedures generate premium device selection, creating a premium procedure channel that elevates Mexico's overall orthopedic device ASP.
Market Restraints
- Regulatory Approval Timelines Delaying Market Entry: Lengthy regulatory approval processes can delay the introduction of advanced orthopedic devices in Mexico. Requirements related to product registration, clinical documentation, safety, and quality compliance can increase costs and time-to-market for manufacturers. Such delays may restrict timely patient access to innovative implants and surgical technologies, thereby slowing market expansion.
- Price Sensitivity in Public Procurement: Strong emphasis on cost containment in Mexico’s public healthcare procurement can limit the adoption of premium orthopedic devices and advanced implants. Hospitals may prioritize lower-cost products when operating under constrained healthcare budgets, creating pricing pressure on manufacturers. This can reduce margins and slow the penetration of innovative orthopedic technologies in the public healthcare sector.
Market Opportunities
- Robotic-Assisted Orthopedic Surgery Expansion in Mexico Private Hospitals: Mexico's robotic orthopedic surgery market is at an early adoption stage, representing significant expansion potential as procedure volume data from pioneer Mexico robotic surgery programs demonstrate outcome advantages, convincing additional hospitals to invest in robotic platforms. Each robotic system installation creates a captive implant ecosystem where the system manufacturer captures implant revenue with minimal competition.
- Ambulatory Surgical Center Development Enabling Outpatient Joint Replacement: Mexico's healthcare system transformation toward ambulatory surgical centers (ASCs), driven by private insurance payer pressure to reduce hospital costs and advances in perioperative pain management enabling same-day discharge joint replacement, is creating a new outpatient orthopedic device channel.
Market Challenges
- Counterfeit and Substandard Orthopedic Implant Risk in Secondary Market Channels: Mexico's orthopedic device market faces meaningful counterfeit and substandard implant risks, particularly in trauma fixation devices (intramedullary nails, bone plates, screws) where price-competitive generic products of uncertain manufacturing quality circulate through informal distribution channels serving budget-constrained public and private hospitals.
- Surgeon Training Capacity Limitations for Advanced Orthopedic Techniques: Mexico's orthopedic surgical workforce development faces significant constraints. Training gaps are particularly acute in subspecialty areas including robotic joint replacement, minimally invasive spine surgery, and complex revision arthroplasty, limiting procedure volume growth to the subspecialty-trained surgeon capacity available in major urban centers while leaving rural and secondary city populations without access to advanced orthopedic procedures.
Emerging Market Trends
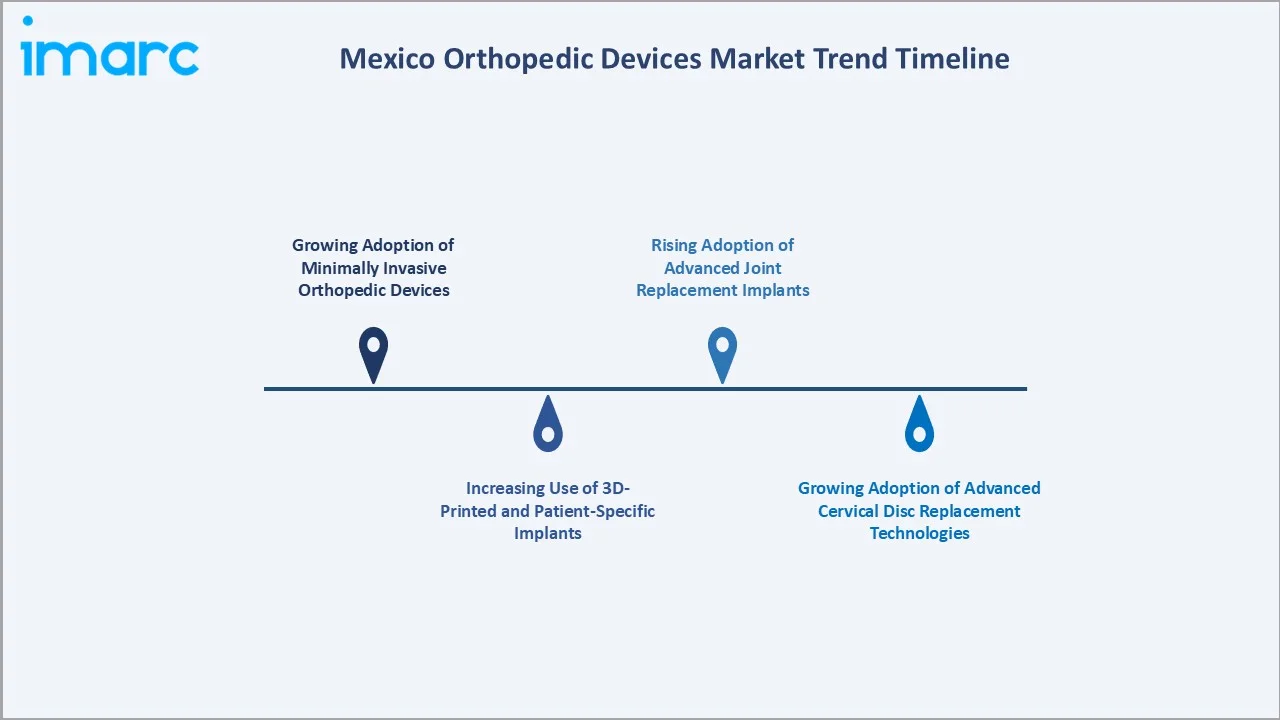
1. Growing Adoption of Minimally Invasive Orthopedic Devices
Mexico’s orthopedic devices market is witnessing increasing adoption of advanced implants designed to simplify surgical procedures and reduce invasiveness. Stand-alone cervical fusion solutions can support smaller incisions, streamlined procedures, and faster recovery, driving demand for next-generation orthopedic technologies. In August 2025, CG MedTech launched its UniSpace Stand-Alone C Cage in Mexico, expanding its orthopedic implant portfolio. The cervical fusion device eliminates the need for additional plates, simplifying surgery while supporting smaller incisions and faster patient recovery.
2. Increasing Use of 3D-Printed and Patient-Specific Implants
3D printing is gaining relevance in orthopedic care by enabling implants and surgical components tailored to individual patient anatomy. Patient-specific solutions can improve implant fit, surgical planning, and procedural precision, particularly in complex orthopedic cases. Continued advancements in additive manufacturing are expected to expand customized orthopedic applications in Mexico.
3. Rising Adoption of Advanced Joint Replacement Implants
The growing burden of age-related musculoskeletal conditions is increasing demand for advanced hip, knee, and other joint replacement devices. Manufacturers are introducing implants with improved materials, durability, and anatomical compatibility. Increasing patient expectations for mobility and quality of life are further supporting the adoption of next-generation joint reconstruction solutions.
4. Growing Adoption of Advanced Cervical Disc Replacement Technologies
Mexico is witnessing increasing adoption of next-generation cervical disc replacement solutions designed to preserve physiological motion and improve spinal treatment outcomes. Innovations such as viscoelastic prostheses and additively manufactured titanium components are supporting the shift toward advanced, motion-preserving alternatives to conventional spinal fusion. In March 2024, NGMedical GmbH completed the first implantation of its MOVE-C cervical artificial disc in Mexico. The advanced prosthesis combines simplified implantation with multidirectional physiological motion and features additively manufactured titanium endplates, expanding access to innovative spinal technologies in the country.
Industry Value Chain Analysis
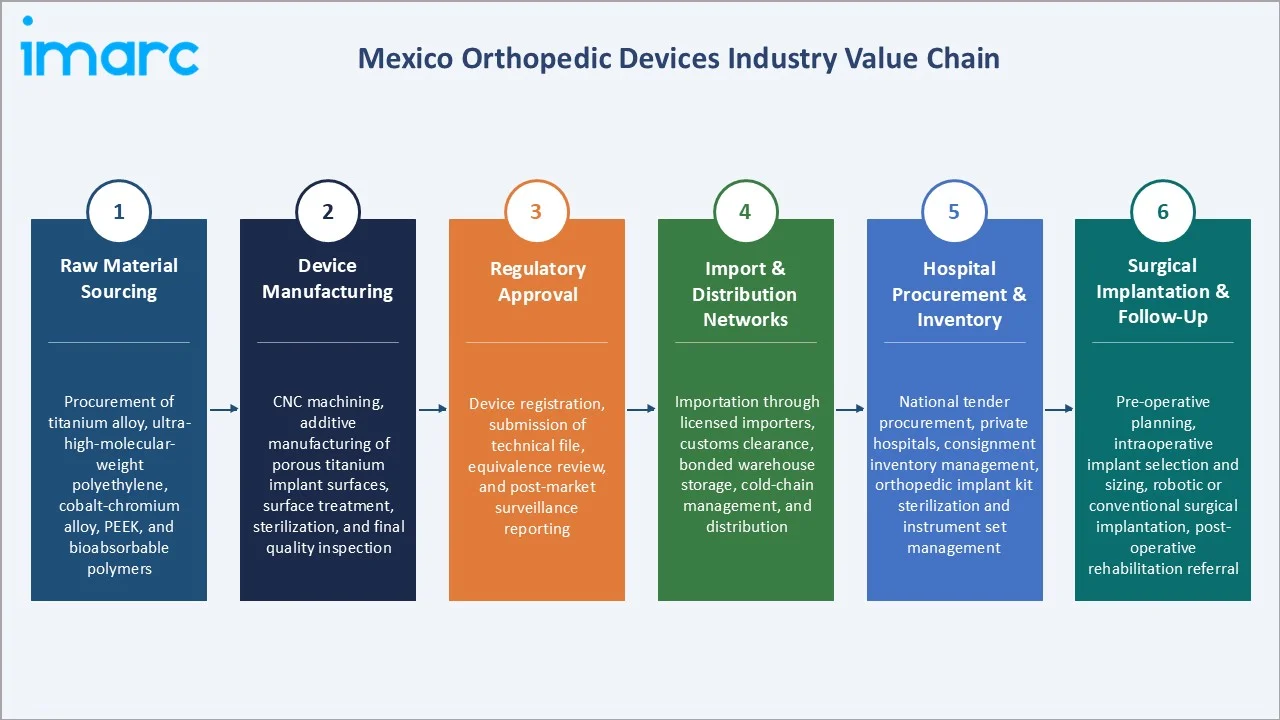
Mexico orthopedic devices value chain spans six stages from raw material sourcing through surgical implantation and follow-up, with regulatory approval and hospital procurement representing the most critical gatekeeping stages determining market access and competitive positioning.
|
Stage |
Description |
|
Raw Material Sourcing |
Procurement of titanium alloy, ultra-high-molecular-weight polyethylene, cobalt-chromium alloy, PEEK, and bioabsorbable polymers. |
|
Device Manufacturing |
CNC machining, additive manufacturing of porous titanium implant surfaces, surface treatment, sterilization, and final quality inspection. |
|
Regulatory Approval |
Device registration, submission of technical file, equivalence review, and post-market surveillance reporting. |
|
Import & Distribution Networks |
Importation through licensed importers, customs clearance, bonded warehouse storage, cold-chain management, and distribution. |
|
Hospital Procurement & Inventory |
National tender procurement, private hospitals, consignment inventory management, orthopedic implant kit sterilization and instrument set management. |
|
Surgical Implantation & Follow-Up |
Pre-operative planning, intraoperative implant selection and sizing, robotic or conventional surgical implantation, post-operative rehabilitation referral. |
Hospital procurement and inventory management represent a critical value chain bottleneck in Mexico's orthopedic device market, where tender framework agreements effectively determine device manufacturer market access to the hospital end user segment for contract periods.
Technology Landscape in the Mexico Orthopedic Devices Industry
Robotic-Assisted Orthopedic Surgery Technology
Robotic-assisted systems are increasingly being integrated into orthopedic procedures to improve surgical precision, planning, and implant positioning. These technologies combine advanced imaging, navigation, and robotic guidance to support surgeons during complex procedures, particularly joint replacements. They can enhance procedural consistency while reducing the risk of alignment errors. Growing adoption of digital surgery is supporting the development of more personalized and efficient orthopedic care.
Advanced Implant Materials and Surface Technologies
Orthopedic device manufacturers are increasingly using advanced materials such as titanium alloys, ceramics, and high-performance polymers to improve implant strength, durability, and biocompatibility. Specialized coatings and surface modifications are being developed to enhance bone integration and implant stability. Additive manufacturing is also enabling porous and patient-specific implant structures. These innovations support improved clinical performance and longer implant lifespans.
Digital Surgery Planning and Patient-Specific Instrumentation
Orthopedic procedures are increasingly incorporating digital imaging and 3D planning tools to improve preoperative decision-making and surgical precision. Patient-specific instruments can be designed using individual anatomical data to guide implant positioning and alignment during surgery. These technologies help streamline procedures, improve accuracy, and support more personalized treatment approaches. Their adoption is also advancing data-driven and digitally integrated orthopedic care.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Type |
Joint Replacement/Orthopedic Implants |
43.8% |
2025 |
|
End User |
Hospitals |
76.4% |
2025 |
|
Region |
Central Mexico |
44.8% |
2025 |

By Product Type
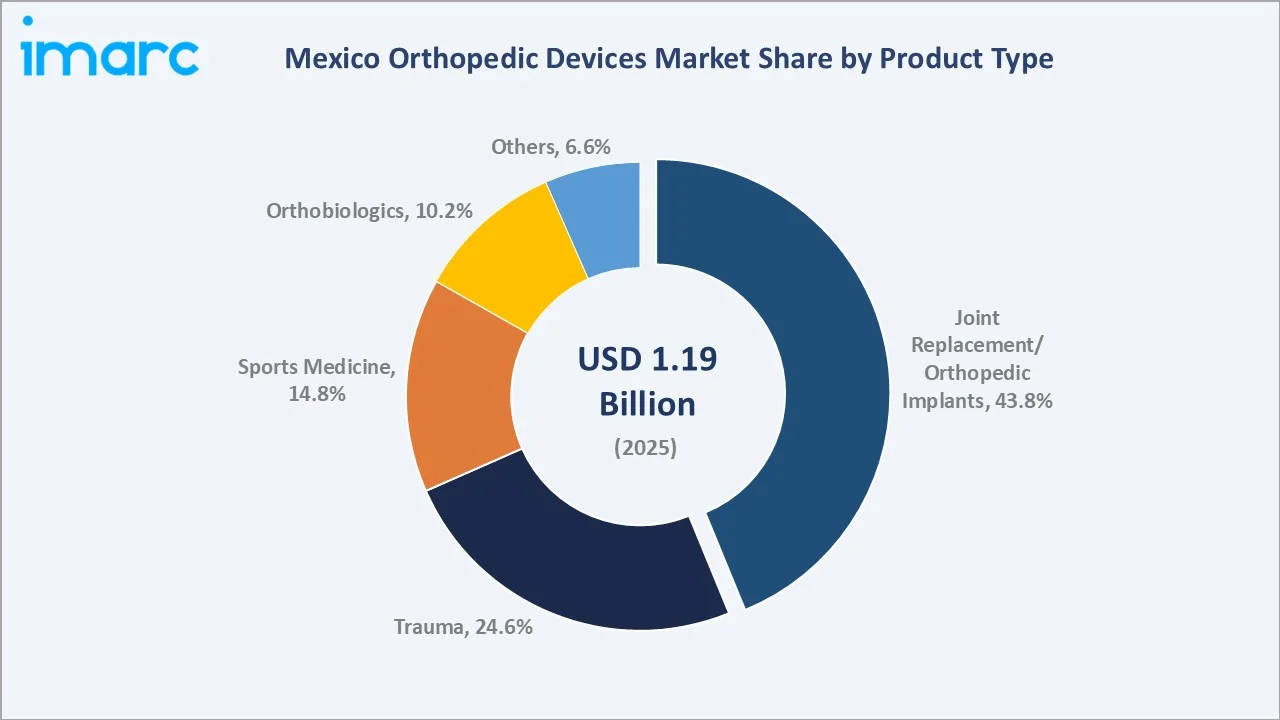
Joint replacement and orthopedic implants command 43.8% in 2025, driven by Mexico's large and growing osteoarthritis patient population, prioritization of joint replacement procedures in specialty hospital networks, and the high device ASP per procedure that concentrates market revenue in this category versus higher-volume but lower-value trauma fixation.
To access detailed market analysis, Request Sample
Trauma at 24.6% encompasses intramedullary nails, bone plates and screws, and external fixation systems for fracture management, the highest volume orthopedic procedure category in Mexico through road traffic accidents, occupational injuries, and falls in the elderly. Sports medicine at 14.8% is growing fastest at ~7.8% CAGR through ACL reconstruction, meniscal repair, and arthroscopic shoulder surgery. Orthobiologics at 10.2% grows at ~7.2% CAGR through PRP, bone graft substitute, and biologic augmentation adoption. Others at 6.6% include extremity implants and soft tissue repair.
By End User
Hospitals dominate at 76.4% through the surgical facility requirements of orthopedic implant procedures and Mexico's concentrated orthopedic surgical capacity at public and private hospital complexes. Private hospital groups represent Mexico's premium device consumption channel where robotics, premium implant brands, and biologics are adopted before diffusing to mid-tier private and public hospital settings.
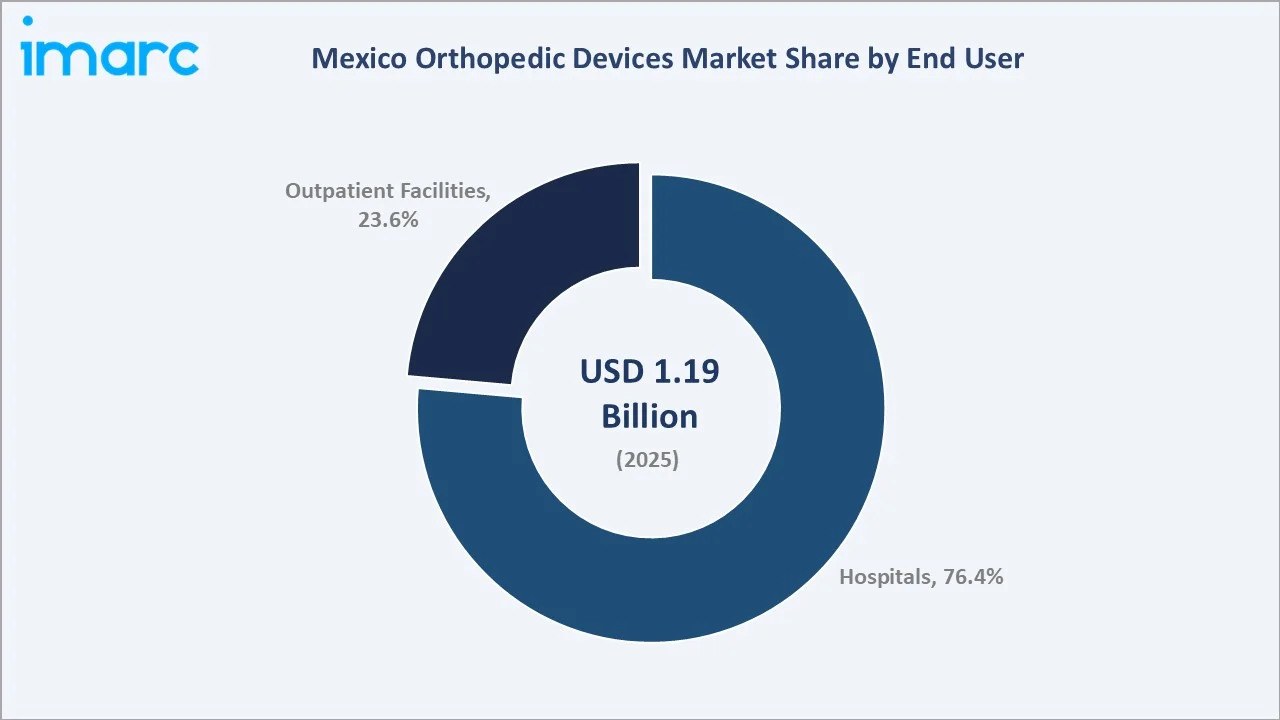
Outpatient facilities at 23.6% represent a growing segment at ~6.9% CAGR through ambulatory surgical center development for arthroscopic sports medicine procedures, injection-based orthobiologic treatments, and early-stage outpatient partial knee replacement programs in private orthopedic ASCs.
Regional Market Insights
|
Region |
Share (2025) |
Key Mexico Orthopedic Devices Market Drivers & Characteristics |
|
Central Mexico |
44.8% |
Central Mexico commands a leading share through the concentration of Mexico's most sophisticated private hospital infrastructure, largest public hospital complexes, and highest density of board-certified orthopedic surgeons. |
|
Northern Mexico |
30.5% |
Northern Mexico's orthopedic devices market reflects the region's combination of Mexico's largest manufacturing workforce population, whose physically demanding industrial and maquiladora jobs generate above-average musculoskeletal injury and joint disease rates, and the most developed private healthcare infrastructure outside Mexico City. |
|
Southern Mexico |
15.2% |
Southern Mexico's orthopedic devices market, while the smallest regional segment in absolute value, serves the region's large and underserved orthopedic care demand. |
|
Others |
9.5% |
The Others region collectively represents Mexico's fastest-developing secondary orthopedic device markets. The growing private hospital sectors serve a large urban middle-class population. |
Central Mexico's 44.8% dominance reflects a unique concentration of Mexico's most experienced orthopedic surgical subspecialists, providing the clinical expertise concentration that attracts both the most complex patient cases and the most innovative device introductions to Mexico's capital region first.
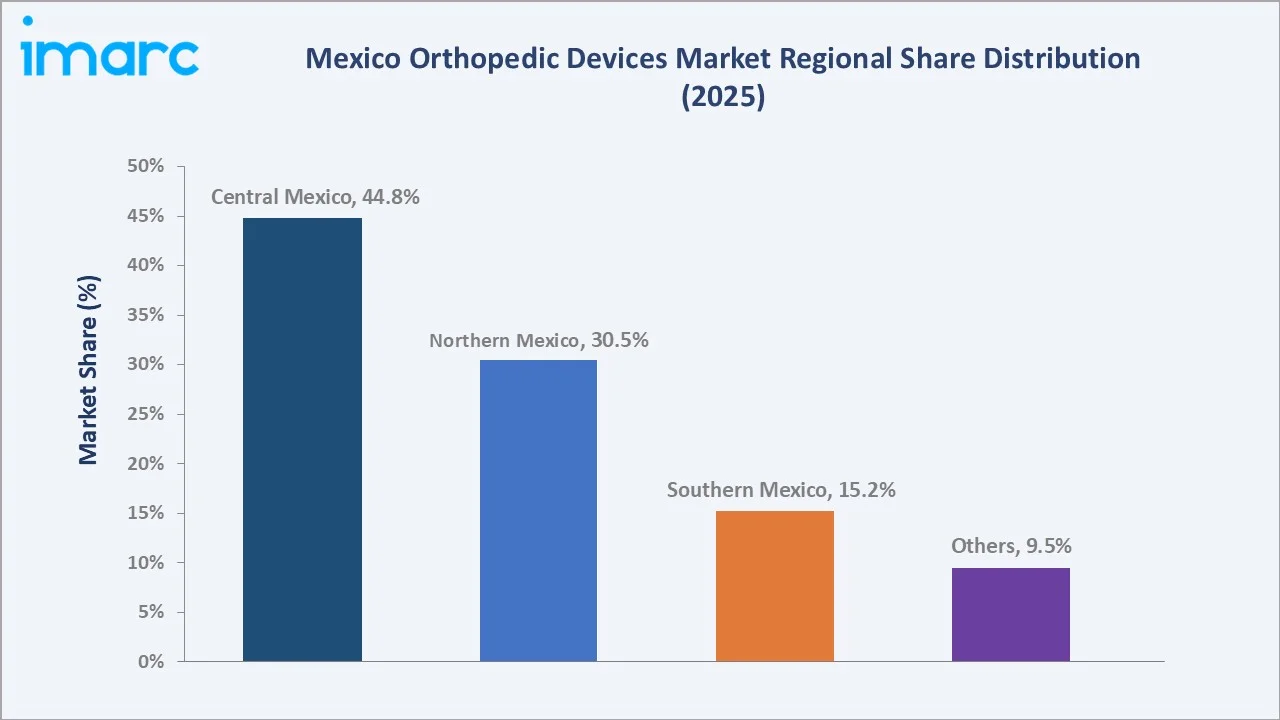
Northern Mexico at 30.5% is growing through premium hospital sector expansion and cross-border medical tourism. Southern Mexico at 15.2% remains primarily served by regional trauma and basic joint replacement programs, with emerging medical tourism developments. The Others region at 9.5% includes a distinctive cross-border orthopedic medical tourism market and a developing private orthopedic hospital sector.
Competitive Landscape
Mexico orthopedic devices market features a concentrated multinational leader tier commanding an estimated 65-75% of organized market revenue through established registrations, tender positions, and private hospital commercial presence, alongside a growing innovator tier in specialty subsegments and a developing domestic distributor and manufacturer tier.
|
Company |
Key Products |
Market Position |
Core Strength |
|
Stryker |
Mako Robotic Systems, Triathlon Knee, Accolade II, T2 Ankle Arthrodesis Nail, T2 Tibia |
Market Leader |
Stryker Corporation holds a prominent, dual-faceted role in Mexico’s orthopedic and medical device sectors. The country serves as both a critical manufacturing powerhouse for its global supply chain and a rapidly growing commercial market for advanced surgical technologies. |
|
Zimmer Biomet |
Persona Knee, Taperloc Hip, ROSA Knee with OptimiZe |
Market Leader |
Zimmer Biomet is a leading competitor in Mexico’s orthopedic and minimally invasive spine device markets, known for securing strong public-sector relationships and distributing specialized reconstructive technologies. |
|
Johnson & Johnson |
ACTIS Total Hip Solutions, Advanced Nailing System, ANTEGRA Plate System, ARCH Fixation System |
Market Leader |
Johnson & Johnson supplies and manufactures advanced orthopedic devices in Mexico through its MedTech division and its orthopedic brand, DePuy Synthes. |
|
Smith+Nephew |
LEGION Total Knee System, R3 Acetabular System, Nanos, CORI Surgical System |
Established Player |
Smith+Nephew operates as a major global provider of orthopedic reconstruction, trauma, and sports medicine devices supplied to the Mexican healthcare market through regulatory approval. |
|
Medtronic |
Mazor Robotic guidance system, O-Arm |
Established Player |
Medtronic plays a leading and highly influential role in Mexico's orthopedic devices market, acting as both a dominant commercial supplier and a major manufacturing driver. |
Competitive dynamics in Mexico's orthopedic market are shaped by three primary battlegrounds: tender pricing competitions determining public hospital market access for conventional implant systems; private hospital robotic system placements creating premium implant franchise positions with trained surgeon ecosystems; and subspecialty surgeon education programs building procedure-specific device loyalty in sports medicine and spine surgery segments that fall outside the public tender framework and are influenced primarily by surgeon preference and manufacturer training investment.
Key Company Profiles
Stryker
Stryker is a global medical technology company with a broad portfolio of orthopedic products and surgical solutions. In the Mexico orthopedic devices market, the company serves healthcare providers through joint replacement implants, trauma and extremities solutions, spinal technologies, surgical equipment, and related technologies. Its portfolio supports orthopedic reconstruction, surgical precision, and improved patient outcomes. The company leverages product innovation, clinical expertise, and distribution capabilities to address evolving orthopedic care requirements.
- Key Products: Mako Robotic Systems, Triathlon Knee, Accolade II, T2 Ankle Arthrodesis Nail, T2 Tibia.
- Strategic Focus: Strengthening its orthopedic portfolio in Mexico through advanced implants, digital surgery solutions, and technology-enabled procedures. The company emphasizes product innovation, minimally invasive approaches, and improved surgical efficiency to address evolving healthcare provider and patient needs.
Zimmer Biomet
Zimmer Biomet is a global medical technology company specializing in orthopedic reconstruction and musculoskeletal healthcare solutions. In the Mexico orthopedic devices market, the company offers joint replacement implants, sports medicine products, trauma solutions, and digital surgical technologies. Its portfolio supports hip, knee, and other orthopedic procedures across diverse patient needs. The company leverages clinical expertise, product innovation, and technology-enabled solutions to support improved surgical efficiency and patient outcomes.
- Key Products: Persona Knee, Taperloc Hip, ROSA Knee with OptimiZe.
- Strategic Focus: Strengthening its orthopedic portfolio in Mexico through advanced joint reconstruction, personalized implants, and digital surgical technologies. The company emphasizes innovation, data-driven solutions, and improved procedural efficiency to address evolving orthopedic care needs and enhance patient outcomes.
Market Concentration Analysis
The Mexico orthopedic devices market exhibits high concentration among multinational medical device companies, with Stryker, Zimmer Biomet, Johnson & Johnson, Smith+Nephew, and Medtronic collectively estimated to command 65-75% of organized market revenue through their registered device portfolios, established government tender positions, and private hospital commercial presence built over decades of Mexico market investment. This concentration is reinforced by the registration timeline that creates meaningful market entry barriers for new competitors and the surgeon education investment required to convert orthopedic surgeons from established implant preferences to new product systems.
Investment & Growth Opportunities
Highest Growth Segments
Sports medicine (~7.8% CAGR), orthobiologics (~7.2% CAGR), outpatient facilities end user segment (~6.9% CAGR), robotic-assisted joint replacement premium tier, cervical disc arthroplasty, total ankle replacement, and medical tourism orthopedic program development represent the highest-return investment opportunities in Mexico's orthopedic devices market through 2034.
Investment Themes
- Robotic Orthopedic System Capital Placement in Mexico Private Hospitals: Mexico's private hospital market is at the early adoption stage for robotic-assisted orthopedic surgery, with robotic systems installed against a long-term addressable market of private hospitals capable of supporting robotic orthopedic programs by procedure volume and physician expertise. Investment in robotic system placement at Mexico private hospitals creates durable implant franchise positions that generate premium implant revenue streams from each robotic system placement.
- Medical Tourism Infrastructure and US Patient Referral Network Development: Mexico's orthopedic medical tourism market is growing but lacks standardized quality benchmarking, US-language patient coordination services, and structured insurance billing infrastructure for US self-insured employer plans. Investment in accreditation support programs for Mexico's private orthopedic hospitals, English-language patient coordination platforms, and US insurance carrier Mexico orthopedic benefit program development would accelerate medical tourism patient volume from the US to Mexico's premium orthopedic centers and elevate device ASP through US-patient premium procedure selection.
Future Market Outlook (2026-2034)
The Mexico orthopedic devices market is projected to grow from USD 1.19 Billion in 2025 to USD 1.26 Billion in 2026, reaching USD 1.97 Billion by 2034, exhibiting a CAGR of 5.76% during 2026-2034. The market is projected to reach USD 1.58 Billion by 2030, the mid-period milestone when Mexico's robotic orthopedic surgery market is expected to have installed systems operating at major private hospitals, generating a premium robotic implant procedure revenue contribution that elevates Mexico's average joint replacement device ASP above current conventional-technique pricing.
Three transformative forces will define Mexico's orthopedic devices market through 2034. First, the robotic surgery ecosystem expansion will generate above-market CAGR in the premium private hospital segment that offsets more moderate growth in the public procurement channel. Second, the sports medicine and biologics convergence will create a high-growth specialty segment where emerging biologics-focused companies compete for Mexico orthopedic procedure share beyond joint replacement's historically dominant market weight. Third, the medical tourism maturation will attract growing US patient volumes for orthopedic procedures that generate premium device economics and elevate Mexico's orthopedic market revenue intensity per procedure toward international benchmark levels.
Research Methodology
Primary Research
Primary research comprised structured interviews with orthopedic surgeons at specialty hospitals and Mexico City private hospitals, medical device registration specialists, hospital purchasing directors at hospital groups, orthopedic device company Mexico country managers, authorized distributor executives, and Mexico medical tourism facilitators serving US patient populations. Clinical volume validation incorporated annual procedure statistics and member survey data.
Secondary Research
Secondary research incorporated medical device registration database analysis, orthopedic device tender award records, epidemiological data on musculoskeletal disease burden in Mexico, demographic projections and aging population modeling, company annual reports and Mexico commercial disclosures, accreditation database for Mexico hospitals, and medical tourism volume estimates for Mexico orthopedic procedures.
Forecasting Models
Market forecasting integrated Mexico demographic aging trajectory projections, orthopedic procedure volume growth models linked to population expansion and obesity-driven osteoarthritis prevalence rates, beneficiary coverage expansion impact on public hospital procedure budgets, medical tourism patient volume trajectory analysis, robotic surgery adoption curve modeling from comparable Latin American market experiences, and device evolution analysis accounting for robotic premium uplift and procurement price normalization pressures.
Mexico Orthopedic Devices Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered |
|
| End Users Covered | Hospitals, Outpatient Facilities |
| Regions Covered | Northern Mexico, Central Mexico, Southern Mexico, Others |
| Companies Covered | Stryker, Zimmer Biomet, Johnson & Johnson, Smith+Nephew, Medtronic, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC's industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Mexico orthopedic devices market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Mexico orthopedic devices market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Mexico orthopedic devices industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Mexico Orthopedic Devices Market Report
The Mexico orthopedic devices market reached USD 1.26 Billion in 2026, driven by Mexico's aging population and rising osteoarthritis prevalence, universal coverage expansion, growing sports medicine procedure volume, and robotic-assisted joint replacement adoption at premier private hospitals.
The market is projected to grow at a CAGR of 5.76% during 2026-2034, with sports medicine (~7.8% CAGR) and orthobiologics (~7.2% CAGR) as the fastest-growing segments, driven by demographic aging, coverage expansion, robotic surgery premium adoption, medical tourism procedure volume growth, and outpatient facility development.
The market is projected to reach USD 1.58 Billion by 2030, when Mexico's robotic orthopedic surgery installed base is expected to reach high systems and medical tourism partnerships create structured US patient referral channels for Mexico premium orthopedic centers.
Joint replacement and orthopedic implants lead with a 43.8% share in 2025, driven by Mexico's large osteoarthritis patient population, joint replacement procedure volume, high device ASP per procedure, and growing robotic-assisted joint replacement adoption in premier Mexico private hospitals.
Hospitals lead with a 76.4% share in 2025, through concentrated orthopedic surgical capability at specialty hospital complexes, private hospital groups, and the surgical facility requirements of orthopedic implant procedures requiring specialized operating theaters, imaging, and post-operative care infrastructure.
Central Mexico leads with a 44.8% share in 2025, through Mexico City's concentration of Mexico's board-certified orthopedic surgeons, national medical center complex, premium private hospitals with robotic surgery programs, and medical tourism procedure inflows from US patients.
Key players include Stryker, Zimmer Biomet, Johnson & Johnson, Smith+Nephew, and Medtronic, among others.
The market is projected to reach USD 1.97 Billion by 2034, driven by robotic surgery ecosystem maturation generating premium implant ASP elevation, sports medicine and biologics convergence driving high-growth specialty segment development, medical tourism maturation attracting US patient volumes, and demographic aging generating sustained joint replacement procedure volume growth.
Key investment opportunities include robotic orthopedic system capital placement programs in Mexico private hospitals, orthobiologics registration for biologic-enhanced orthopedic procedures, medical tourism infrastructure development for structured US patient referral partnerships, ambulatory surgical center orthopedic program development, and total ankle and shoulder replacement subspecialty program building in Mexico's growing active aging patient market.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade