Mexico Pre-Engineered Buildings Market Size, Share, Trends and Forecast by Product, End User, and Region, 2026-2034
Mexico Pre-Engineered Buildings Market Size, Share, Trends & Forecast (2026-2034)
The Mexico pre-engineered buildings market grew from USD 278.3 Million in 2025 to USD 300.2 Million in 2026 and is projected to reach USD 560.3 Million by 2034, growing at a CAGR of 7.84% during 2026-2034. The market is driven by expanding industrialization and rising demand for fast, cost-efficient construction.
Growing warehousing, logistics, and manufacturing investments are further supporting market growth. Steel structure dominates at 56.8%. Industrial sector leads end users at 43.7%. Northern Mexico commands 45.8% of the national market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 278.3 Million |
|
Market Size (2026) |
USD 300.2 Million |
|
Forecast Market Size (2034) |
USD 560.3 Million |
|
CAGR (2026-2034) |
7.84% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product |
Steel Structure (56.8%, 2025) |
|
Dominant End User |
Industrial Sector (43.7%, 2025) |
|
Leading Region |
Northern Mexico (45.8%, 2025) |
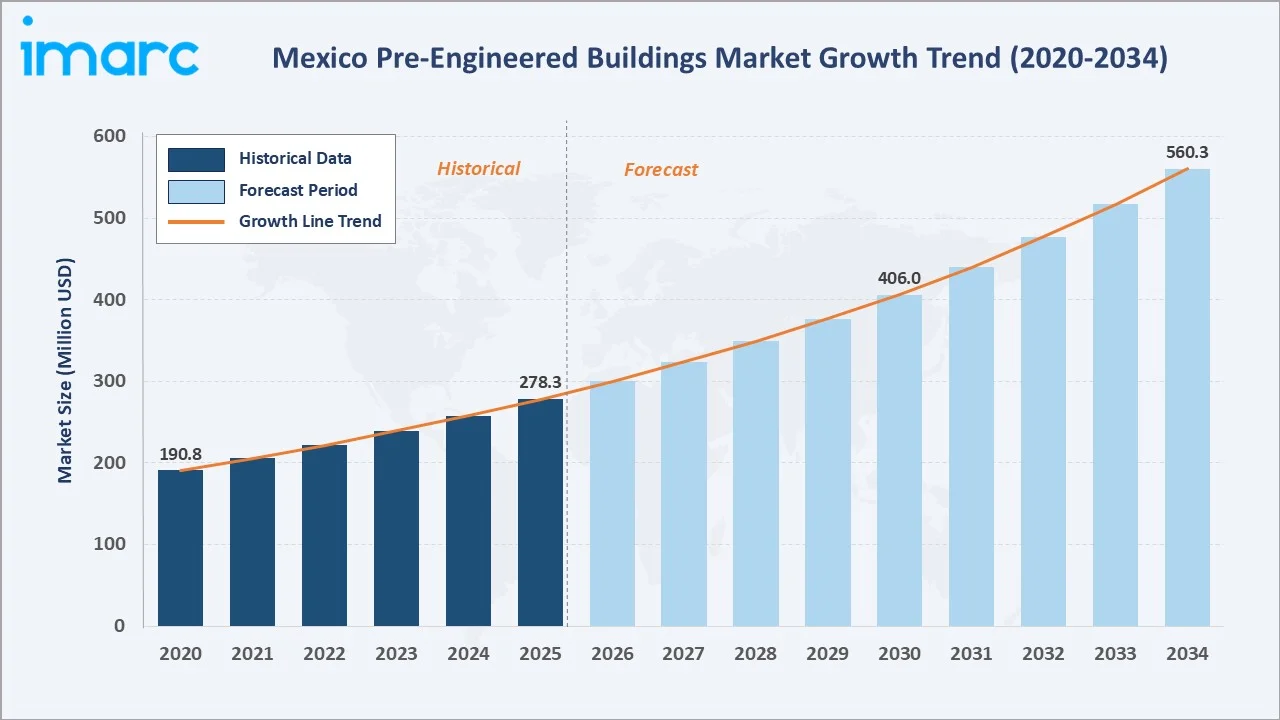
The Mexico pre-engineered buildings market size increased from USD 190.8 Million in 2020 to USD 278.3 Million in 2025 and is estimated to reach USD 300.2 Million in 2026. The market is further expected to grow to USD 406.0 Million by 2030 and USD 560.3 Million by 2034.
To get more information on this market, Request Sample
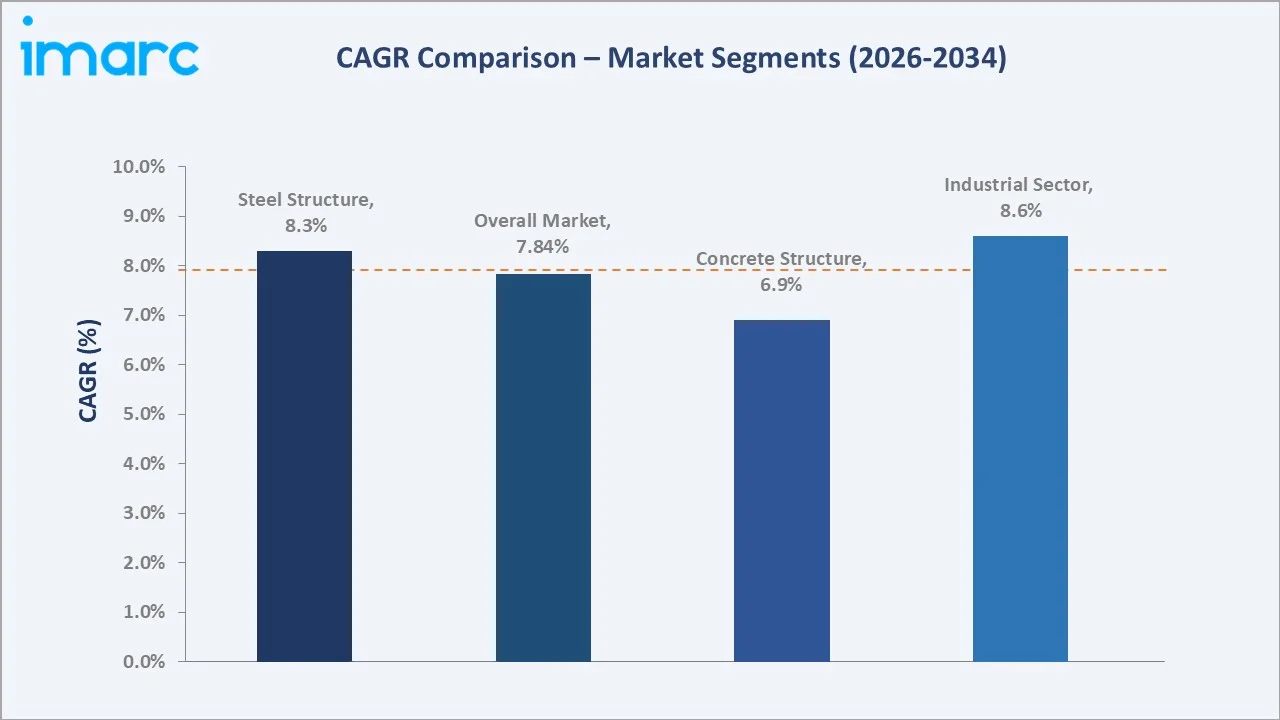
The industrial sector grows fastest at ~8.6% CAGR, supported by new manufacturing plants and logistics parks. Steel structures expand at ~8.3% CAGR owing to clear-span capability, faster erection, and recyclability, while concrete structures grow at ~6.9% CAGR through precast adoption in infrastructure projects.
Executive Summary
The Mexico pre-engineered buildings market expanded from USD 278.3 Million in 2025 to an estimated USD 300.2 Million in 2026, supported by sustained industrial, logistics, and commercial construction activity. Pre-engineered buildings are increasingly preferred for their shorter build cycles, design flexibility, and lower lifecycle costs.
The market is projected to reach USD 560.3 Million by 2034. Steel structure at 56.8% leads through its strength, speed, and scalability. Industrial sector at 43.7% reflects strong manufacturing and warehousing investment. Northern Mexico leads regionally at 45.8%.
Key Market Insights
|
Insight |
Data |
|
Dominant Product |
Steel Structure - 56.8% share (2025) |
|
Dominant End User |
Industrial Sector - 43.7% market share (2025) |
|
Leading Region |
Northern Mexico - 45.8% share (2025) |
|
Market Opportunity |
Industrial park and logistics hub development; e-commerce warehousing and cold storage; energy-efficient insulated building envelopes; modular expansion of existing facilities |
Key Analytical Observations Supporting the Above Data:
- Steel Structure at 56.8%: The steel structure segment dominates due to its high strength-to-weight ratio, large clear spans, faster erection, and ease of future expansion. Its suitability for factories, warehouses, and distribution centers makes it the preferred choice across Mexico's industrial corridors.
- Industrial Sector at 43.7%: The industrial sector dominates owing to continuous investments in manufacturing plants, logistics hubs, and industrial parks. Expanding automotive, electronics, and consumer goods production is generating strong demand for quick-to-build, large-span facilities.
- Northern Mexico at 45.8%: Northern Mexico dominates regionally due to its proximity to the United States border, dense manufacturing base, and large concentration of industrial parks in states such as Nuevo León, Coahuila, Chihuahua, and Baja California.
Mexico Pre-Engineered Buildings Market Overview
Pre-engineered buildings are factory-designed structural systems comprising primary frames, secondary members, and roof and wall cladding that are fabricated off-site and assembled on location. Their standardized engineering enables faster project delivery, predictable costs, and reduced material waste compared with conventional construction.
The market ecosystem integrates raw material suppliers, PEB manufacturers, design and engineering firms, builders, erectors, and end users. Macroeconomic factors include industrial investment, urbanization, logistics expansion, infrastructure spending, and a growing focus on energy-efficient and sustainable construction practices.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
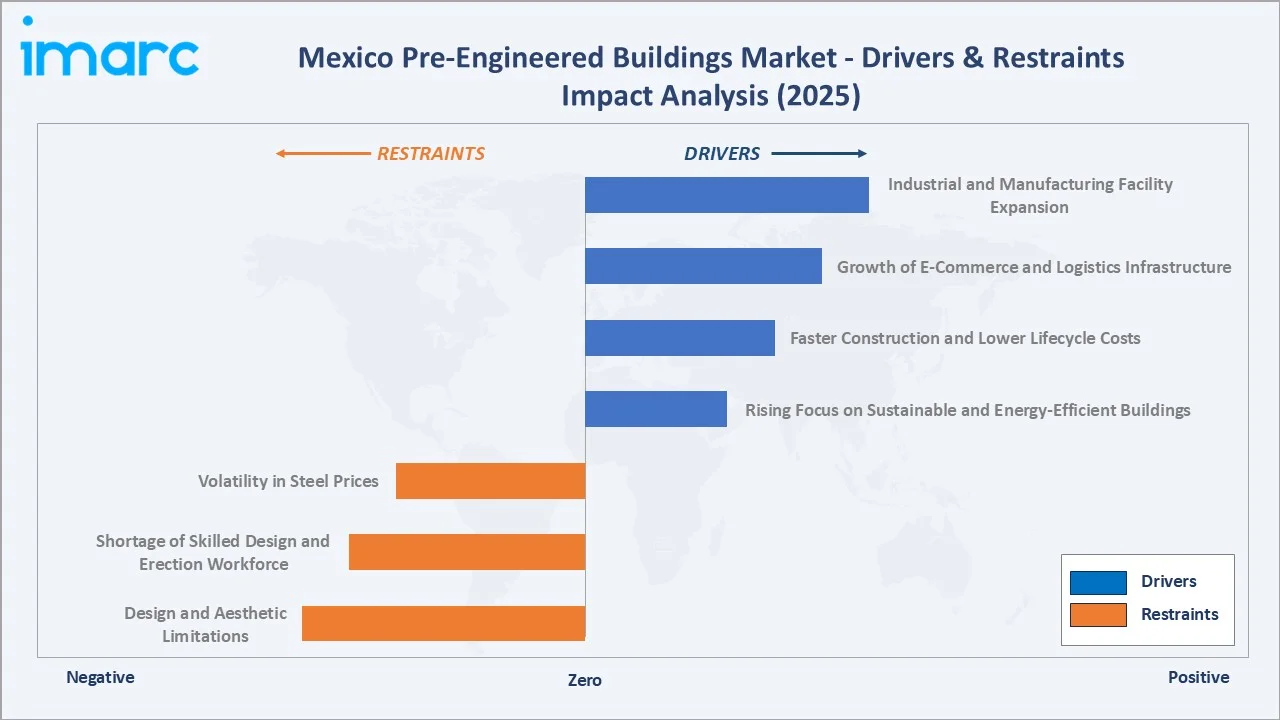
- Industrial and Manufacturing Facility Expansion: Expanding manufacturing activity is increasing demand for large, column-free facilities that can be built quickly. Pre-engineered buildings allow companies to shorten project timelines, control costs, and scale capacity in phases, making them a preferred solution for new plants and industrial parks.
- Growth of E-Commerce and Logistics Infrastructure: The rapid growth of e-commerce and organized retail is driving demand for warehouses, distribution centers, and cold storage facilities. Pre-engineered buildings offer wide clear spans, high eave heights, and flexible layouts that support modern storage systems, automation, and efficient material handling.
- Faster Construction and Lower Lifecycle Costs: Pre-engineered buildings reduce construction time because components are fabricated off-site and bolted together on location. Lower labor requirements, reduced material wastage, and minimal maintenance needs lower total project and lifecycle costs, encouraging owners to shift away from conventional construction.
- Rising Focus on Sustainable and Energy-Efficient Buildings: Growing environmental awareness is encouraging the use of recyclable steel, insulated panels, cool roofs, and daylighting systems. Pre-engineered buildings generate less construction waste and easily integrate solar panels and efficient envelopes, supporting green building goals and lower operating costs.
Market Restraints
- Volatility in Steel Prices: Fluctuating steel prices directly affect the cost of primary frames, secondary members, and cladding. Sudden price increases can disrupt project budgets, delay procurement decisions, and compress manufacturer margins, making cost planning difficult for both suppliers and building owners.
- Shortage of Skilled Design and Erection Workforce: Pre-engineered buildings require specialized expertise in structural design, detailing, and precise erection. A limited pool of trained engineers and certified erection crews can lead to project delays, quality issues, and higher installation costs, particularly in less industrialized regions.
- Design and Aesthetic Limitations: Pre-engineered buildings are often perceived as less adaptable for complex architectural designs, multi-story structures, and premium commercial projects. This perception, along with concerns about thermal and acoustic performance in some applications, limits adoption in certain residential and high-end commercial segments.
Market Opportunities
- Development of Industrial Parks and Logistics Hubs: New industrial parks and logistics hubs present a strong opportunity for pre-engineered building suppliers. Developers increasingly prefer standardized, expandable building shells that can be delivered quickly to tenants, creating recurring demand for design-build and turnkey solutions.
- Adoption of Insulated Metal Panels and Green Solutions: Rising demand for energy-efficient building envelopes is creating opportunities for insulated metal panels, solar-ready roofs, and low-carbon steel. Suppliers offering certified green building packages can differentiate their offerings and capture demand from companies pursuing sustainability commitments.
Market Challenges
- Intense Price Competition: The market faces intense price competition from local fabricators, regional manufacturers, and imported building systems. Aggressive pricing pressures margins and can lead to compromises in material quality and engineering standards, making it difficult for established players to maintain profitability.
- Compliance with Seismic and Wind Design Requirements: Buildings must be engineered to withstand seismic activity, strong winds, and extreme weather across different regions. Meeting diverse structural codes increases design complexity, engineering effort, and material costs, requiring manufacturers to invest in advanced design tools and technical expertise.
Emerging Market Trends
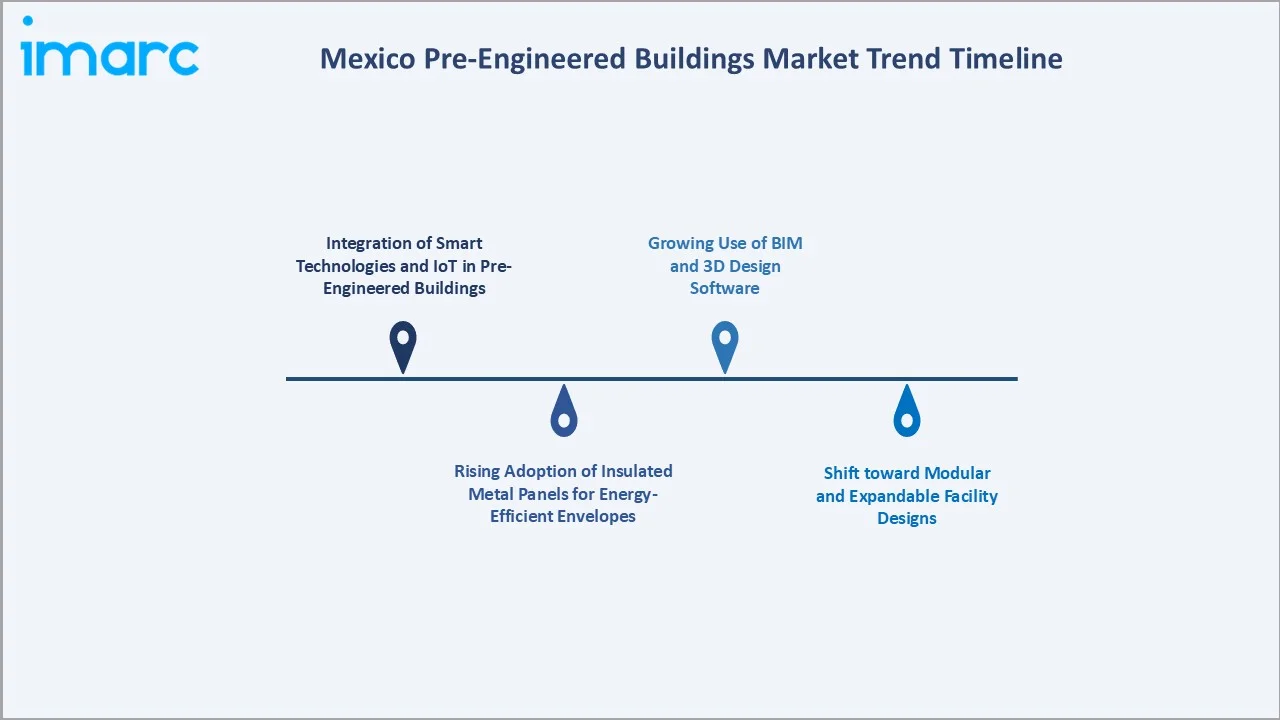
1. Integration of Smart Technologies and IoT in Pre-Engineered Buildings
Smart technologies and IoT solutions are increasingly integrated into pre-engineered buildings. Automation, energy management systems, and real-time monitoring devices help owners identify issues early, optimize energy use, and reduce maintenance costs, transforming PEBs from basic shells into intelligent, high-performance assets.
2. Rising Adoption of Insulated Metal Panels for Energy-Efficient Envelopes
Insulated metal panels are gaining traction as owners seek better thermal performance, faster enclosure, and lower operating costs. These panels combine cladding and insulation in one component, improving temperature control in warehouses, cold storage, and food processing facilities while reducing installation time.
3. Growing Use of BIM and 3D Design Software
Building information modeling and 3D design software are improving accuracy across design, detailing, and fabrication. Digital models help coordinate structural, electrical, and mechanical systems, reduce clashes and rework, and enable faster approvals, supporting more complex and customized pre-engineered building projects.
4. Shift toward Modular and Expandable Facility Designs
Companies are increasingly specifying modular and expandable designs that allow additional bays or mezzanines to be added with minimal disruption. This approach supports phased investments, aligns capacity with demand growth, and makes pre-engineered buildings attractive for operators with evolving space needs.
Industry Value Chain Analysis
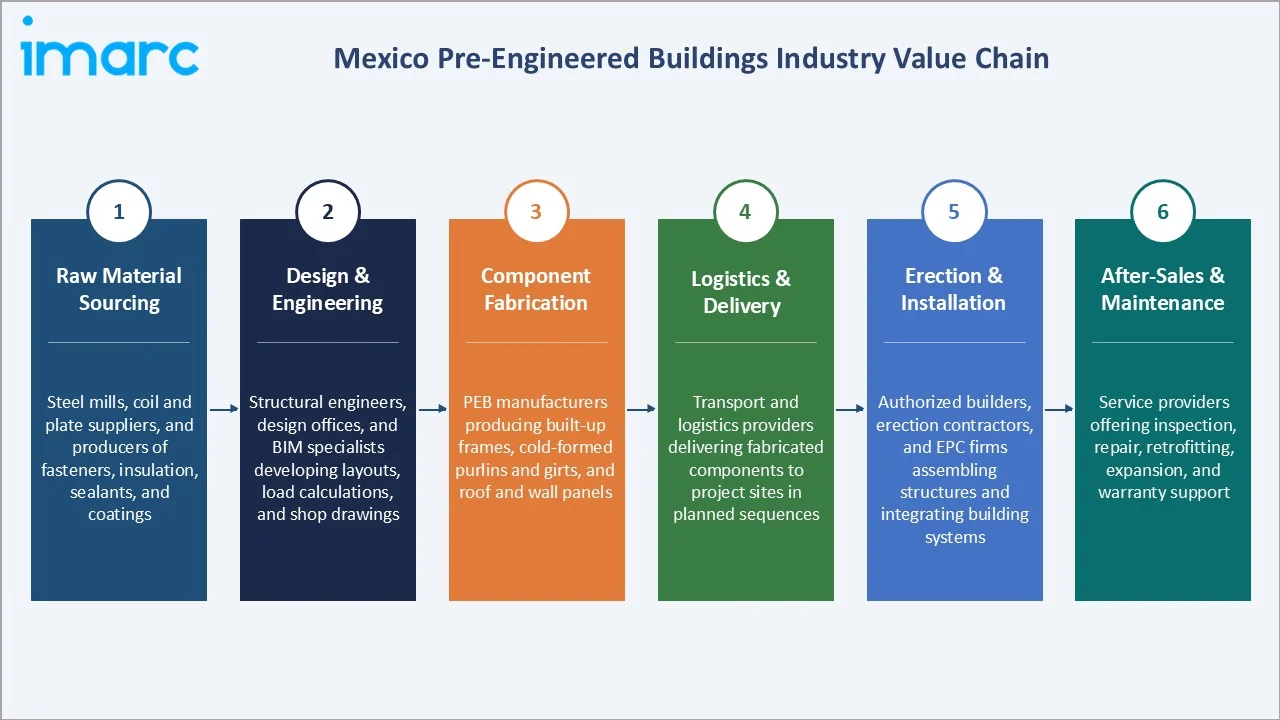
The pre-engineered buildings value chain spans raw material sourcing through design, fabrication, delivery, erection, and after-sales support. Value is increasingly created in engineering and project management, where customized design, accurate detailing, and on-time delivery differentiate suppliers in a competitive market.
|
Stage |
Key Participants |
|
Raw Material Sourcing |
Steel mills, coil and plate suppliers, and producers of fasteners, insulation, sealants, and coatings |
|
Design & Engineering |
Structural engineers, design offices, and BIM specialists developing layouts, load calculations, and shop drawings |
|
Component Fabrication |
PEB manufacturers producing built-up frames, cold-formed purlins and girts, and roof and wall panels |
|
Logistics & Delivery |
Transport and logistics providers delivering fabricated components to project sites in planned sequences |
|
Erection & Installation |
Authorized builders, erection contractors, and EPC firms assembling structures and integrating building systems |
|
After-Sales & Maintenance |
Service providers offering inspection, repair, retrofitting, expansion, and warranty support |
The design and fabrication stages are the most value-intensive in the chain, as engineering precision determines material efficiency, structural performance, and erection speed. Manufacturers combining in-house design capabilities with automated fabrication lines are better positioned to offer competitive pricing and shorter lead times.
Technology Landscape in the Mexico Pre-Engineered Buildings Industry
Building Information Modeling and 3D Design
BIM and 3D design tools enable engineers to create detailed digital prototypes of pre-engineered buildings, covering framing, cladding, and building services. These tools improve accuracy, reduce design errors, support clash detection, and generate fabrication-ready drawings, shortening project timelines and enhancing stakeholder coordination.
Automated Fabrication and Advanced Coatings
Automated welding, CNC cutting, and roll-forming lines improve the precision and consistency of structural components while increasing production throughput. Advanced galvanized and pre-painted coatings extend the service life of steel members and panels, protecting buildings against corrosion in humid, coastal, and industrial environments.
Smart Building and Energy Management Systems
Smart building technologies, including IoT sensors, automated lighting, and energy management systems, are increasingly integrated into pre-engineered buildings. These systems enable real-time monitoring of energy consumption, structural health, and indoor conditions, helping owners lower operating costs and improve safety and sustainability performance.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product |
Steel Structure |
56.8% |
2025 |
|
End User |
Industrial Sector |
43.7% |
2025 |
|
Region |
Northern Mexico |
45.8% |
2025 |

By Product
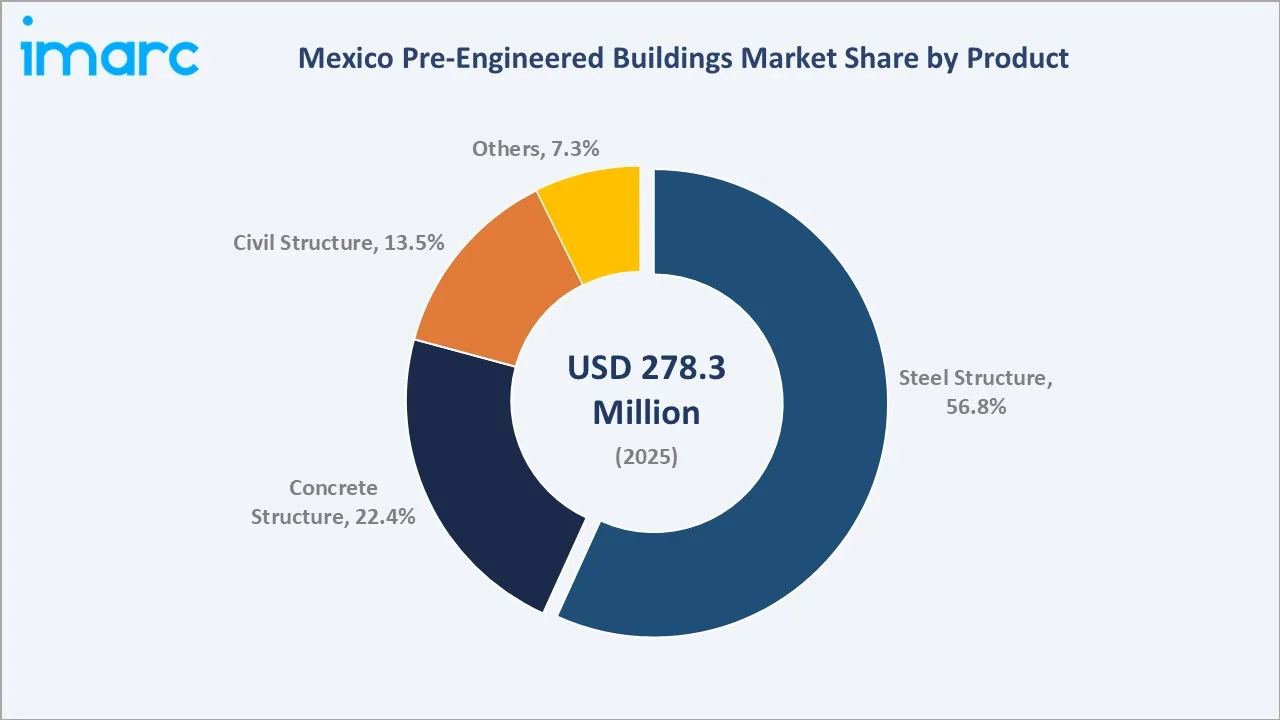
Steel structure leads at 56.8% (2025). The segment benefits from a high strength-to-weight ratio, large clear spans, and fast erection, making it the preferred solution for factories, warehouses, logistics centers, and commercial facilities across Mexico's industrial corridors.
To access detailed market analysis, Request Sample
Concrete structure at 22.4% grows at ~6.9% CAGR through precast adoption in infrastructure and institutional projects. Civil structure holds 13.5%, supported by public works and utility facilities, while others account for 7.3%, covering hybrid and specialized building systems.
By End User
Industrial sector leads at 43.7% (2025). The segment is driven by investments in manufacturing plants, industrial parks, and logistics facilities, where large-span, quickly erected buildings help companies accelerate operations and scale capacity in line with production requirements.
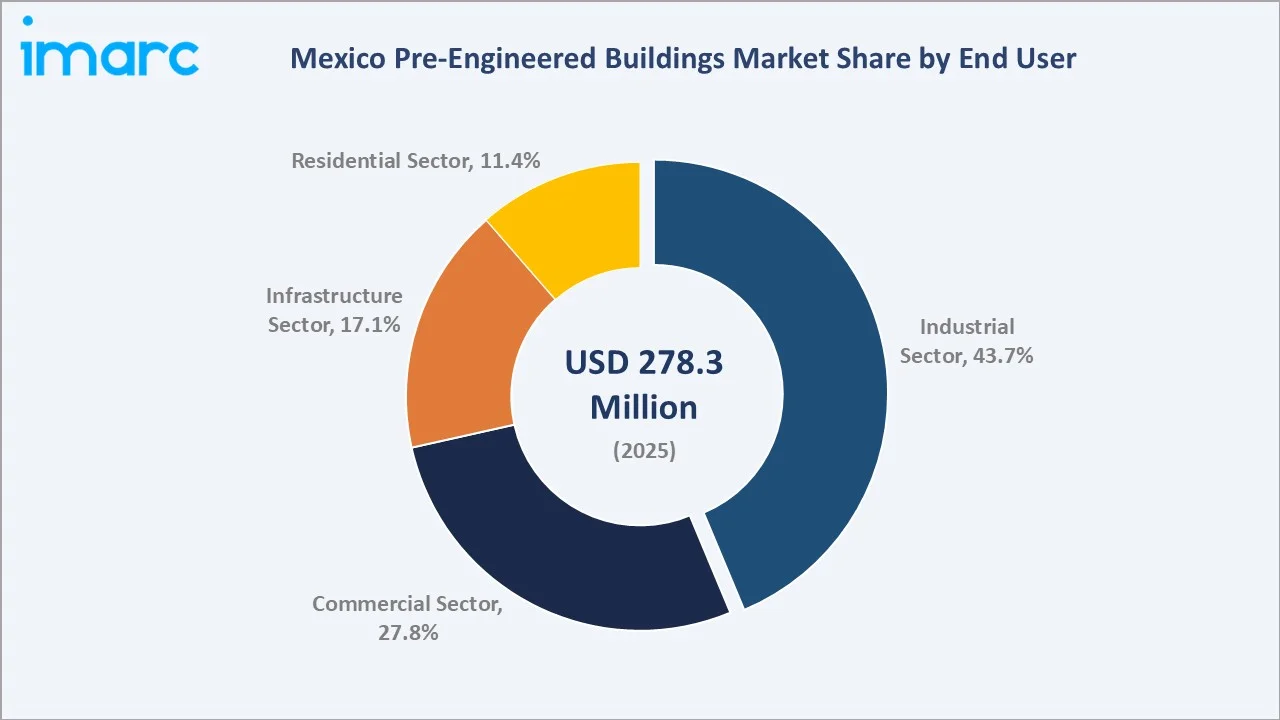
Commercial sector at 27.8% is growing at ~7.5% CAGR through retail stores, showrooms, and office facilities. Infrastructure sector at 17.1% is supported by transport and utility projects, while residential sector at 11.4% gains traction through affordable and rapid housing solutions.
Regional Market Insights
|
Region |
Share (2025) |
Key Mexico Pre-Engineered Buildings Market Drivers & Characteristics |
|
Northern Mexico |
45.8% |
Driven by border proximity, export-oriented manufacturing, and dense industrial parks in Nuevo León, Coahuila, and Chihuahua. |
|
Central Mexico |
31.6% |
Supported by automotive and aerospace clusters in the Bajío region and strong logistics demand around Mexico City. |
|
Southern Mexico |
13.7% |
Growing through public infrastructure projects, tourism-related commercial construction, and emerging industrial corridors. |
|
Others |
8.9% |
Includes remaining regions where agro-industrial, mining, and port-related facilities support gradual demand growth. |
Northern Mexico's 45.8% market leadership reflects its proximity to the United States, concentration of export-oriented manufacturing, and rapid growth of industrial parks. Central Mexico's 31.6% reflects the Bajío automotive and aerospace clusters and strong warehousing demand around the Mexico City metropolitan area.
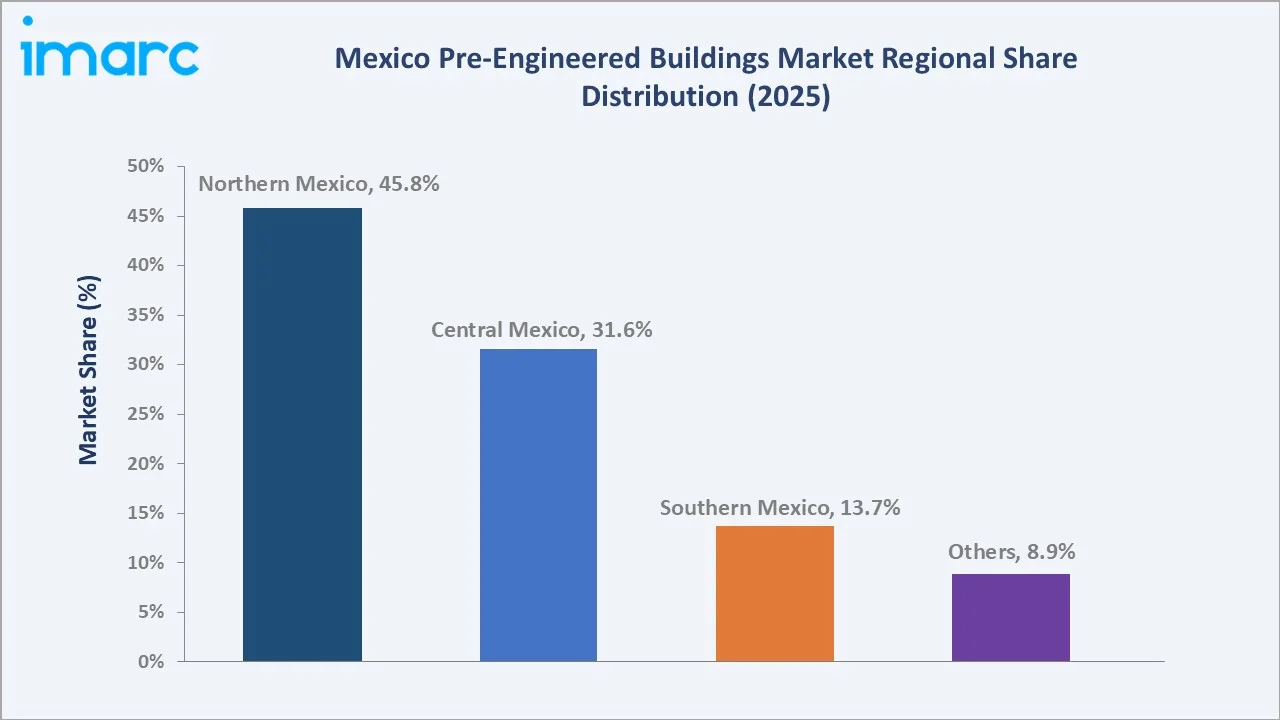
Southern Mexico's 13.7% is supported by public infrastructure development, tourism-related commercial projects, and emerging industrial corridors. Others at 8.9% cover remaining regions where agro-industrial processing, mining, and port-related facilities create steady demand for cost-effective, quickly erected buildings.
Competitive Landscape
The Mexico pre-engineered buildings market is moderately fragmented, comprising integrated steel producers, international metal building manufacturers, and regional fabricators. Competition centers on engineering capability, delivery speed, pricing, and after-sales support, and is intensifying as industrial expansion attracts new suppliers.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
Ternium |
Ternium, Ternium Metallic Buildings |
Market Leader |
Operates a Metallic Buildings plant in Ciénega de Flores, Nuevo León, manufacturing complete steel structures for distribution centers, stores, warehouses, and hangars. |
|
Nucor Corporation |
Nucor Building Systems, American Buildings |
Market Leader |
One of North America's largest manufacturers of pre-engineered metal building systems through four independent building brands. |
|
BlueScope Steel Limited |
Butler Manufacturing, Varco Pruden Buildings, BlueScope Conventional Steel |
Strong Challenger |
Pioneer of the metal building industry, offering engineered building solutions backed by an extensive builder network. |
|
Cornerstone Building Brands, Inc. |
Fortify Building Solutions, MBCI, Metal Sales |
Strong Challenger |
Leading North American manufacturer of exterior building products, with metal building systems operations in Monterrey. |
Competition is increasingly shaped by the ability to offer turnkey solutions combining design, fabrication, and erection. Global manufacturers leverage engineering expertise and builder networks, while local fabricators compete on price and proximity, pushing all participants to improve delivery speed, customization, and value-added services.
Key Company Profiles
Ternium
Ternium is a leading steel producer in Latin America with an extensive industrial presence in Mexico, supplying flat and long steel products and complete metallic building solutions for industrial and commercial construction.
- Key Brands: Ternium, Ternium Metallic Buildings, among others.
- Strategic Focus: Strengthening its integrated steel supply in Mexico and replacing imports to better serve construction and industrial customers.
Nucor Corporation
Nucor Corporation is North America's largest steel manufacturer and recycler. Through Nucor Buildings Group, it is one of the region's largest producers of pre-engineered metal building systems, supported by a wide network of authorized builders.
- Key Brands: Nucor Building Systems, American Buildings, Kirby Building Systems, CBC Steel Buildings.
- Recent Developments: In 2026, Nucor Corporation announced a US$59 million investment to expand production capabilities at its Vulcraft Indiana manufacturing facility in St. Joe, Indiana. The expansion will add capabilities to manufacture steel grating products and is expected to create 20 new full-time jobs. The investment strengthens Nucor’s downstream fabricated construction products operations. The company also noted that its Indiana operations include an insulated metal panel facility adjacent to the Nucor Building Systems Indiana campus, supporting its broader portfolio of structural steel and metal building systems used in non-residential construction.
- Strategic Focus: Offering single-source steel building solutions backed by integrated steel supply and an extensive authorized builder network.
BlueScope Steel Limited
BlueScope Steel Limited is an international steel solutions company operating in North America through BlueScope Buildings North America, a leading manufacturer of engineered building solutions whose brands pioneered the metal building industry.
- Key Brands: Butler Manufacturing, Varco Pruden Buildings, BlueScope Conventional Steel.
- Recent Developments: In August 2026, BlueScope achieved the first “metal on strip” at its new Metal Coating Line 7 (MCL7) facility in Western Sydney, marking the transition from construction to production. The facility will add up to 240,000 tonnes of metal-coating capacity, supporting products such as COLORBOND and TRUECORE steel.
- Strategic Focus: Combining engineered and conventional steel solutions to serve industrial, commercial, and multi-site construction projects.
Market Concentration Analysis
The Mexico pre-engineered buildings market is moderately fragmented. Integrated steel producers and international metal building manufacturers hold a significant share of large industrial and logistics projects, while numerous regional fabricators serve small and mid-sized projects through competitive pricing and local presence.
Market concentration is evolving through two opposing forces: consolidation among leading manufacturers through acquisitions and capacity expansion, and the entry of new local and international suppliers attracted by industrial demand, which continues to intensify competition in mid-sized project segments.
Investment & Growth Opportunities
Highest Growth Segments
Industrial sector (~8.6% CAGR through manufacturing and logistics investments), steel structures (~8.3% CAGR through clear-span and fast-erection advantages), infrastructure sector (~7.6% CAGR), and commercial sector (~7.5% CAGR) represent the highest-growth investment vectors in the Mexico pre-engineered buildings market through 2034.
Emerging Investment Opportunities
Energy-efficient building envelopes, insulated metal panels, and solar-ready roofing systems represent emerging investment areas. Growing sustainability commitments among manufacturers and logistics operators are increasing demand for green-certified pre-engineered buildings, creating opportunities for suppliers offering integrated, low-carbon building solutions.
Investment Themes
- Capacity expansion near industrial corridors: Establishing fabrication plants and service centers close to Northern and Central Mexico's industrial parks can reduce logistics costs, shorten lead times, and help suppliers capture recurring demand from manufacturers and logistics developers.
- Turnkey design-build and digital engineering capabilities: Investing in BIM-enabled design, automated fabrication, and integrated erection services allows suppliers to deliver projects faster, differentiate from low-cost fabricators, and secure long-term relationships with industrial park developers and multinational clients.
Future Market Outlook (2026-2034)
The Mexico pre-engineered buildings market is projected to grow from USD 278.3 Million in 2025 to USD 300.2 Million in 2026, reaching USD 560.3 Million by 2034, registering a CAGR of 7.84% during 2026-2034. The market is expected to reach USD 406.0 Million by 2030.
Three structural forces define market growth through 2034: continued industrial and logistics investment, rising preference for fast and cost-efficient construction methods, and increasing adoption of energy-efficient and sustainable building solutions across industrial, commercial, and infrastructure applications.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry stakeholders, including PEB manufacturers, structural engineers, EPC contractors, authorized builders, industrial park developers, steel suppliers, and end users across the industrial, commercial, infrastructure, and residential sectors in Northern, Central, and Southern Mexico.
Secondary Research
Secondary research encompassed company annual reports, investor presentations, government construction and industrial statistics, trade data, industry association publications, regulatory documents, and press releases. Over 50 secondary sources were reviewed to validate market size, segment shares, and competitive insights.
Forecasting Models
Market revenue forecasts were developed using a combination of bottom-up and top-down approaches, analyzing construction activity, industrial investment, installed floor area, and average project value by segment. Forecasts were validated against historical trends and expert inputs.
Mexico Pre-Engineered Buildings Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Products Covered | Concrete Structure, Steel Structure, Civil Structure, Others |
| End Users Covered | Industrial Sector, Commercial Sector, Infrastructure Sector, Residential Sector |
| Regions Covered | Northern Mexico, Central Mexico, Southern Mexico, Others |
| Companies Covered | Ternium, Nucor Corporation, BlueScope Steel Limited, Cornerstone Building Brands, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Mexico pre-engineered buildings market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Mexico pre-engineered buildings market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Mexico pre-engineered buildings industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Mexico Pre-Engineered Buildings Market Report
Mexico pre-engineered buildings market size is estimated at USD 300.2 Million in 2026, driven by expanding industrial and logistics construction and rising demand for fast, cost-efficient building solutions. The market reached USD 278.3 Million in 2025.
The Mexico pre-engineered buildings market grows at 7.84% CAGR during 2026-2034, reaching USD 560.3 Million by 2034. Growth is sustained by industrial expansion, e-commerce warehousing demand, and increasing adoption of sustainable construction practices.
Steel structure leads at 56.8% due to its high strength-to-weight ratio, large clear spans, faster erection, and ease of expansion for industrial and commercial facilities.
Industrial sector leads at 43.7%, driven by investments in manufacturing plants, industrial parks, and logistics facilities requiring quickly erected, large-span buildings.
Northern Mexico leads at 45.8% owing to its proximity to the United States, strong manufacturing base, and high concentration of industrial parks.
Leading companies include Ternium, Nucor Corporation, BlueScope Steel Limited, and Cornerstone Building Brands, Inc., among others.
The Mexico pre-engineered buildings market is projected to reach approximately USD 406.0 Million by 2030, supported by continued industrial park development, warehouse construction, and growing adoption of energy-efficient building envelopes.
Key investment opportunities include fabrication capacity near industrial corridors, turnkey design-build and BIM-enabled engineering services, and energy-efficient building solutions such as insulated metal panels and solar-ready roofing systems.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade