Mexico Security as a Service Market Size, Share, Trends and Forecast by Component, Organization Size, Application, Vertical, and Region, 2026-2034
Mexico Security as a Service Market Size, Share, Trends & Forecast (2026-2034)
The Mexico security as a service market was valued at USD 318.1 Million in 2025 and is projected to reach USD 893.5 Million by 2034, exhibiting a CAGR of 11.80% during 2026-2034. Rising cyberattack frequency, accelerating nearshoring-led industrial expansion, and heightened security demand ahead of the 2026 FIFA World Cup are the primary drivers shaping the market growth.
Solution leads the component segment at 71.8%, large enterprises dominate the organization size segment at 67.5%, and Central Mexico commands 46.7% regional share.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 318.1 Million |
|
Forecast Market Size (2034) |
USD 893.5 Million |
|
CAGR (2026-2034) |
11.80% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Central Mexico (46.7%, 2025) |
|
Second Largest Region |
Northern Mexico (31.6%, 2025) |
|
Leading Component |
Solution (71.8%, 2025) |
|
Leading Organization Size |
Large Enterprises (67.5%, 2025) |
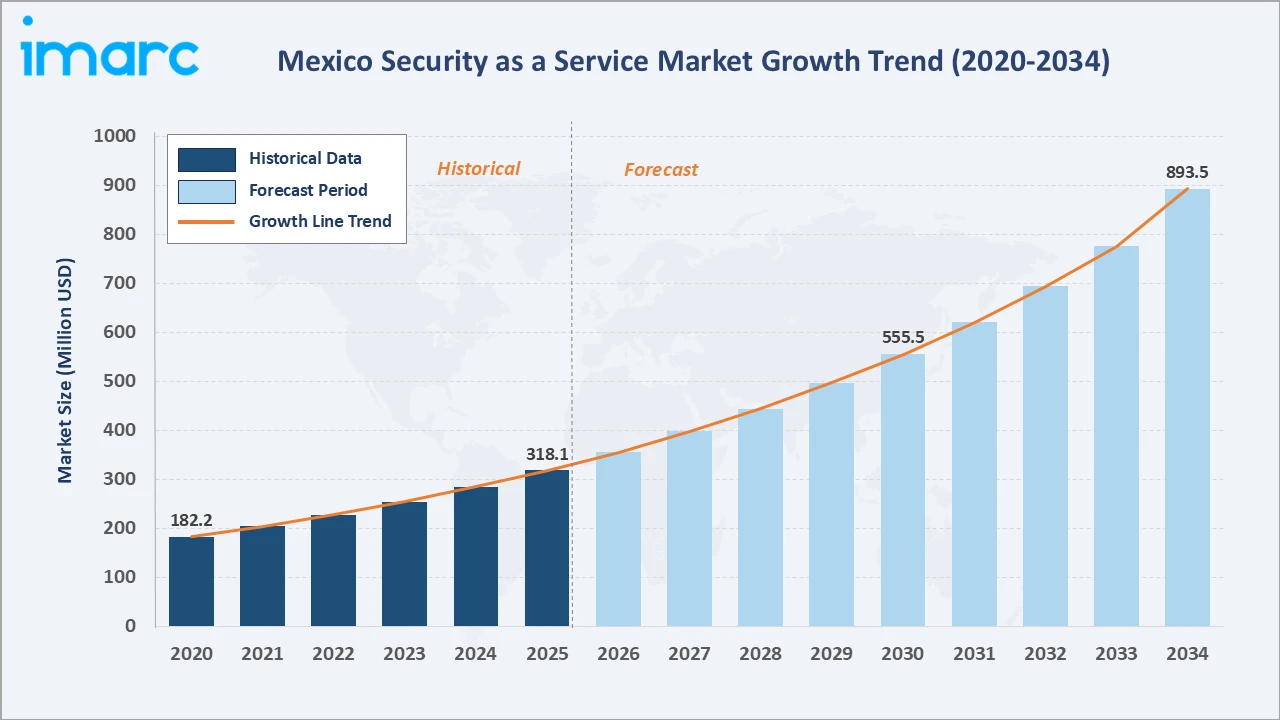
The Mexico security as a service market expanded from USD 182.2 Million in 2020 to USD 318.1 Million in 2025, driven by widening enterprise digitalization, growing regulatory pressure, and rapid cloud migration across the banking, manufacturing, and government sectors. Anchored at USD 555.5 Million in 2030, the forecast to USD 893.5 Million by 2034 is supported by accelerating adoption of managed detection and response, expanding small and medium-sized enterprise participation, and a maturing national cybersecurity policy environment.
To get more information on this market, Request Sample
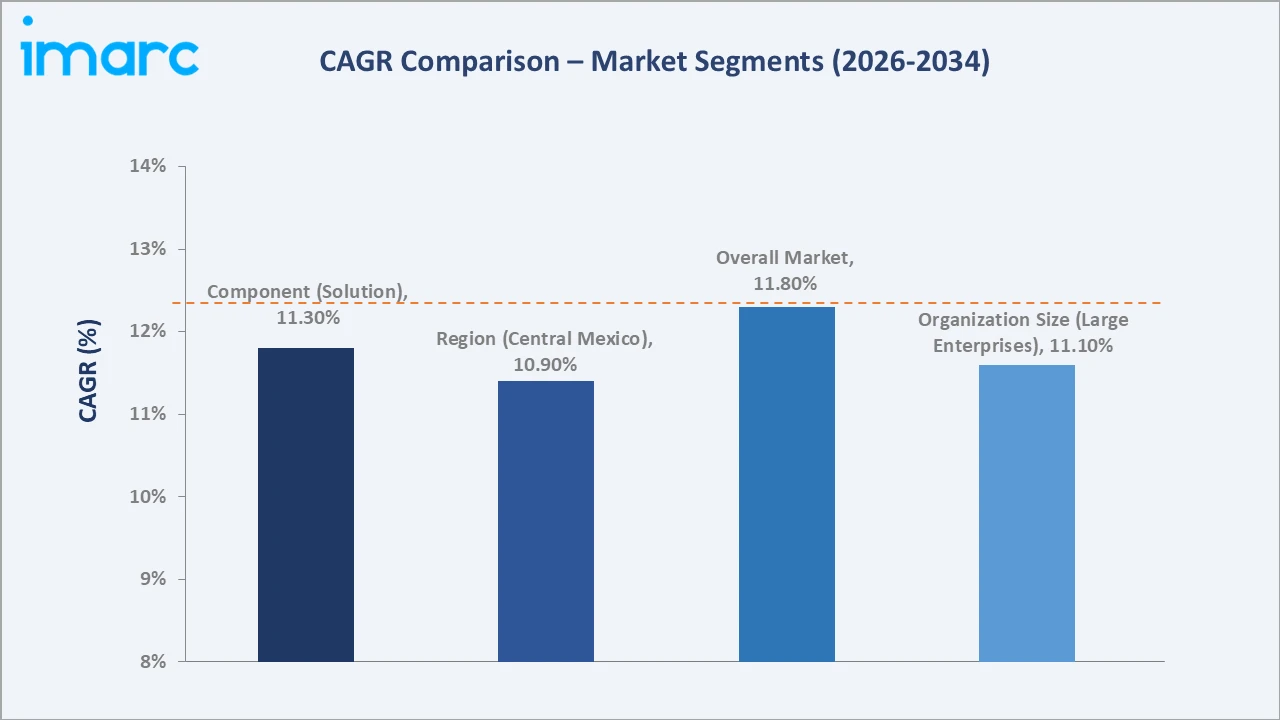
CAGR trajectories across component, organization size, and regional sub-segments show services and small and medium-sized enterprises expanding faster than the overall 11.80% market CAGR, driven by growing outsourcing of security operations, budget-conscious adoption models, and rising digital exposure among smaller organizations.
Executive Summary
The Mexico security as a service market is on a steady growth trajectory, expanding from USD 182.2 Million in 2020 to USD 893.5 Million by 2034. The industry has moved from on-premises, capital-intensive deployments toward subscription-based, cloud-delivered security models spanning identity management, threat detection, encryption, and managed monitoring services. Rising digital exposure, tightening regulatory pressure, and constrained in-house security talent are pushing organizations of every size toward outsourced protection.
Solution dominates the component segment at 71.8% in 2025, supported by growing enterprise investment in cloud-native firewalls, encryption, and identity and access management platforms. Large enterprises lead the organization size segment at 67.5%, reflecting greater budget capacity and regulatory obligations. Central Mexico commands 46.7% of the regional share, anchored by Mexico City's dense concentration of corporate headquarters and data infrastructure.
Key Market Insights
|
Insight |
Data |
|
Leading Component |
Solution - 71.8% share (2025) |
|
Second Largest Component |
Services - 28.2% share (2025) |
|
Leading Organization Size |
Large Enterprises - 67.5% share (2025) |
|
Second Largest Organization Size |
Small and Medium-sized Enterprises - 32.5% share (2025) |
|
Leading Region |
Central Mexico - 46.7% share (2025) |
|
Second Largest Region |
Northern Mexico - 31.6% share (2025) |
|
Top Companies |
IBM, Microsoft, Cisco Systems, Inc., Fortinet, Inc., Palo Alto Networks, Check Point Software Technologies Ltd. |
Key Analytical Observations Supporting the Above Data:
- Solution dominance at 71.8% is supported by rising enterprise demand for cloud-native firewalls, endpoint protection, encryption, and identity and access management platforms deployed as subscription-based offerings.
- Services share at 28.2% is expanding as organizations increasingly outsource monitoring, incident response, and consulting to managed security service providers amid persistent talent shortages.
- Large enterprises leadership at 67.5% reflects deeper budget capacity, complex multi-site infrastructure, and stronger regulatory obligations across the banking, manufacturing, and government sectors.
- Small and medium-sized enterprises share at 32.5% is expanding as subscription pricing lowers the barrier to entry, while growing adoption of cloud-based security solutions enables smaller organizations to access advanced protection without substantial upfront infrastructure investments.
- Central Mexico at 46.7% dominates regional share, anchored by Mexico City, Puebla, and the State of Mexico, supported by dense corporate concentration and data center presence.
Mexico Security as a Service Market Overview
Security as a service refers to the outsourced, cloud-delivered provision of cybersecurity capabilities, including identity and access management, encryption, data loss prevention, intrusion detection and prevention, endpoint protection, and security information and event management, offered through subscription-based models rather than on-premises infrastructure. The market spans solution offerings and complementary services such as consulting, integration, and managed monitoring.
The Mexican ecosystem integrates technology vendors, managed security service providers, cloud infrastructure operators, telecom carriers, systems integrators, regulatory authorities, and end-use enterprises across banking, manufacturing, retail, and government sectors. Together, they enable organizations to access enterprise-grade protection without heavy upfront capital investment, within an evolving national cybersecurity policy framework.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
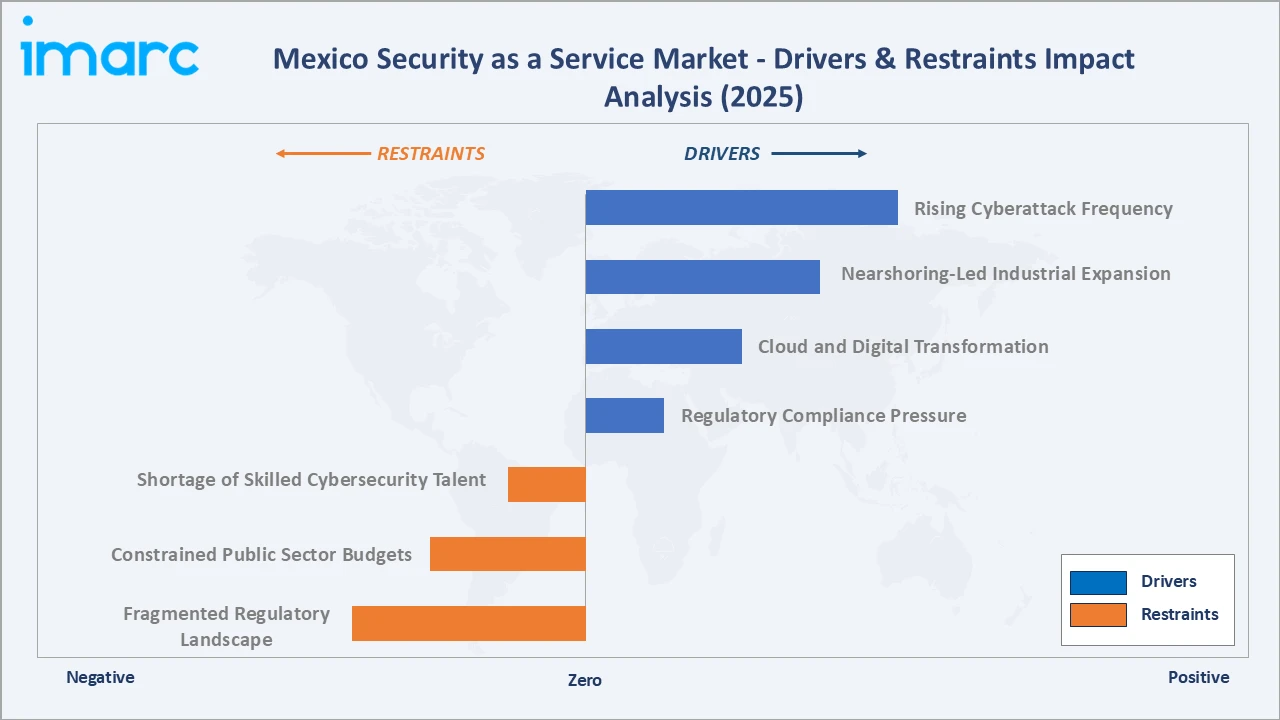
- Rising Cyberattack Frequency: Mexico's growing exposure to ransomware, phishing, and identity-based intrusions is compelling enterprises across banking, manufacturing, and government to adopt continuously updated, cloud-delivered defenses rather than static on-premises tools. In 2024, Mexico represented approximately 55% of cyberattacks in Latin America, which included ransomware, phishing, and extortion attacks, leading to an economic loss of more than USD 40 Million.
- Nearshoring-Led Industrial Expansion: The relocation of manufacturing capacity closer to the United States is bringing new factories, connected supply chains, and data centers into the threat landscape, widening demand for scalable managed security coverage.
- Cloud and Digital Transformation: Continued migration of core business applications to public and hybrid cloud environments is increasing enterprise reliance on cloud-native security tooling embedded directly into subscription-based delivery models.
- Regulatory Compliance Pressure: Tightening data protection and incident-reporting expectations are raising compliance costs, encouraging organizations to adopt managed security services that provide continuous monitoring, reporting, and compliance support.
Market Restraints
- Shortage of Skilled Cybersecurity Talent: A persistent shortage of qualified security professionals is limiting the pace at which organizations, particularly smaller ones, can build in-house monitoring capabilities, reinforcing dependence on external providers while constraining overall market absorption.
- Constrained Public Sector Budgets: Austerity measures affecting government technology spending are limiting modernization of legacy systems, leaving several public institutions exposed and slowing broader adoption of managed security contracts.
- Fragmented Regulatory Landscape: The absence of a single, comprehensive national cybersecurity law creates inconsistent compliance expectations across states and sectors, complicating standardized service delivery for multi-region operators.
Market Opportunities
- Managed Detection and Response for SMEs: Subscription-priced, cloud-delivered offerings are opening a large underserved base of small and medium-sized enterprises that previously lacked budget for dedicated security infrastructure.
- World Cup-Driven Infrastructure Modernization: Preparations for the 2026 FIFA World Cup are accelerating investment in surveillance, biometric access, and network security across host cities, creating long-term modernization opportunities beyond the tournament itself.
Market Challenges
- Persistent Identity and Multi-Cloud Security Gaps: Weak visibility over human and non-human identities across multi-cloud environments continues to expose organizations to credential-based attacks despite growing security investment.
- Balancing Cost and Coverage: Price-sensitive small and medium-sized enterprises often struggle to justify comprehensive service tiers, leading to partial coverage that leaves gaps in overall protection.
Emerging Market Trends
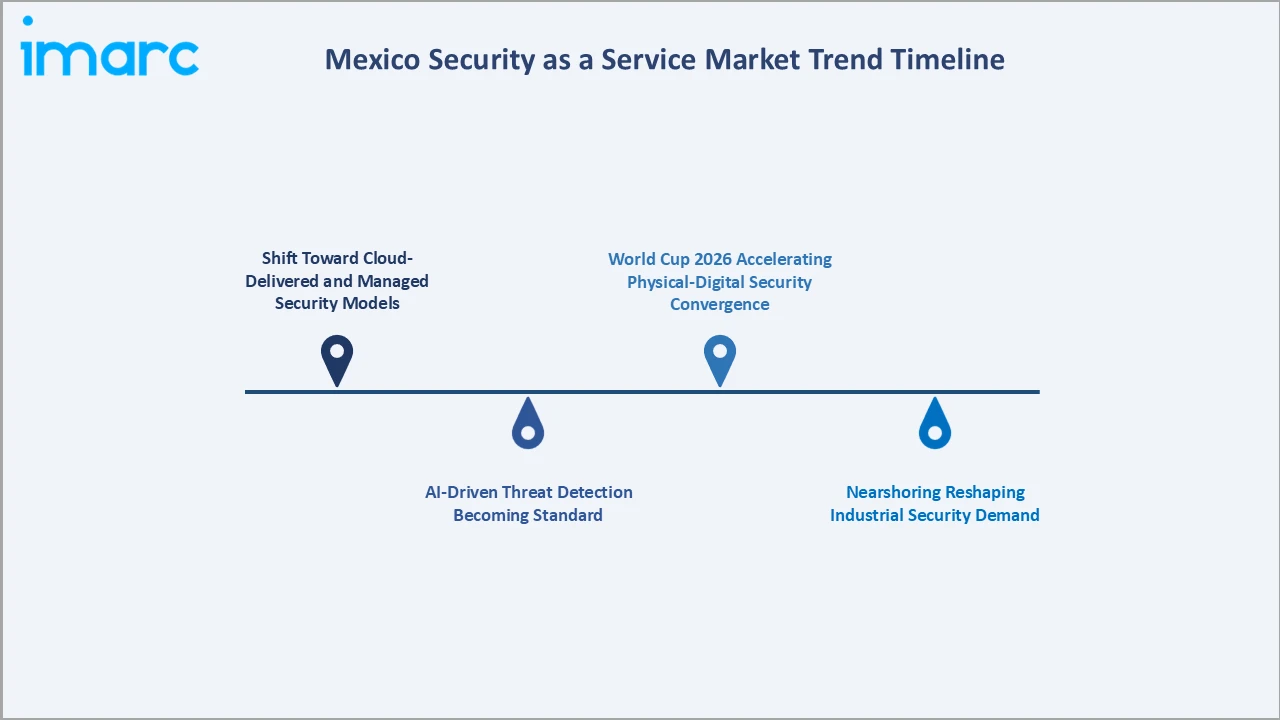
1. Shift Toward Cloud-Delivered and Managed Security Models
Organizations are steadily moving away from on-premises hardware toward subscription-priced, cloud-native security platforms that bundle detection, response, and compliance reporting into a single managed offering, easing pressure on constrained internal teams.
2. AI-Driven Threat Detection Becoming Standard
Machine learning (ML)-based anomaly detection and automated response tooling are increasingly embedded into mainstream security platforms, enabling faster identification of ransomware and identity-based intrusions across enterprise environments.
3. Nearshoring Reshaping Industrial Security Demand
Manufacturing relocation toward Mexico is expanding the operational technology attack surface, increasing demand for network monitoring, endpoint protection, and managed security services across newly established industrial facilities.
4. World Cup 2026 Accelerating Physical-Digital Security Convergence
Host cities are integrating AI-enabled video surveillance, biometric access control, and network security under unified security-as-a-service contracts, a model expected to persist well beyond the tournament.
Industry Value Chain Analysis
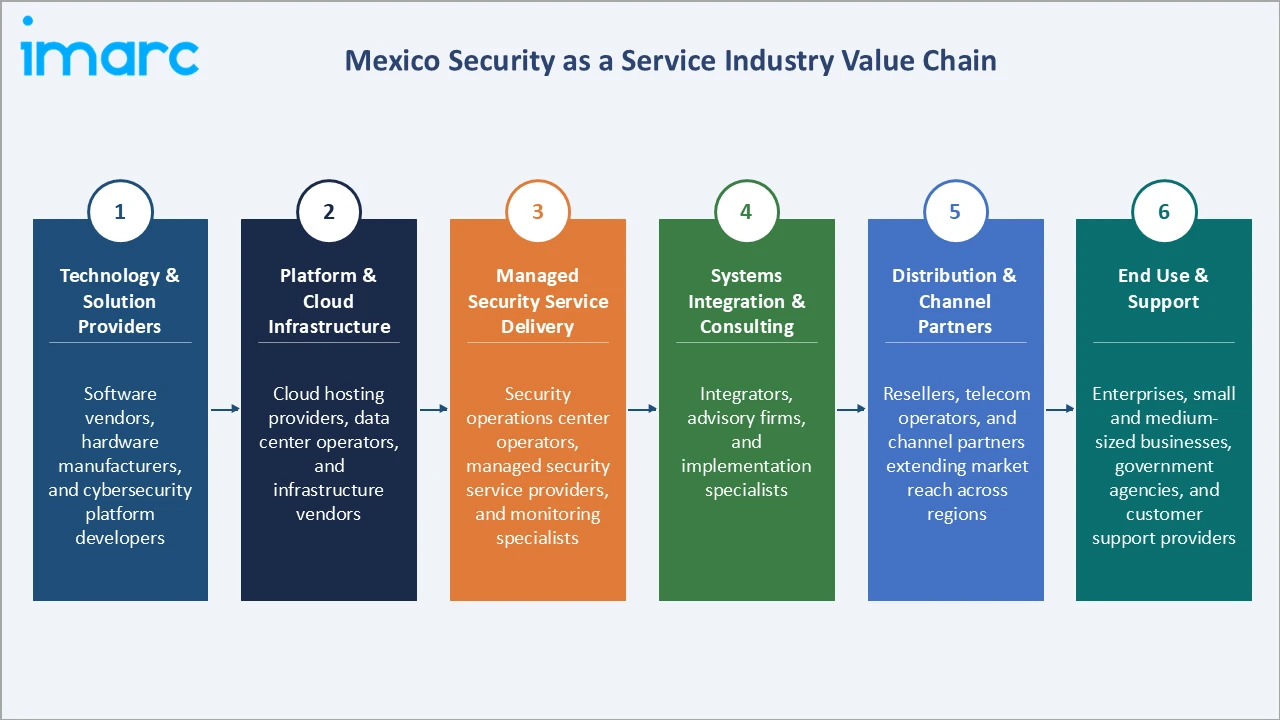
The Mexico security as a service value chain spans six stages from technology and platform supply through end-user engagement and lifecycle support. Platform development and managed delivery capture the highest value-add, while integration and distribution capabilities increasingly determine sustainable competitive position in this fast-evolving category.
|
Stage |
Key Players / Examples |
|
Technology & Solution Providers |
Software vendors, hardware manufacturers, and cybersecurity platform developers supplying core detection and protection technologies |
|
Platform & Cloud Infrastructure |
Cloud hosting providers, data center operators, and infrastructure vendors enabling scalable service delivery |
|
Managed Security Service Delivery |
Security operations center operators, managed security service providers, and monitoring specialists |
|
Systems Integration & Consulting |
Integrators, advisory firms, and implementation specialists supporting deployment and compliance |
|
Distribution & Channel Partners |
Resellers, telecom operators, and channel partners extending market reach across regions |
|
End Use & Support |
Enterprises, small and medium-sized businesses, government agencies, and ongoing customer support providers |
Vertically integrated providers, particularly those combining proprietary detection technology with direct managed-service delivery, are positioned to capture greater value than partners reliant on third-party platforms.
Technology Landscape in the Mexico Security as a Service Industry
AI and ML-Based Detection
Security platforms are increasingly deploying ML models to identify anomalous behavior, flag credential misuse, and automate initial incident triage, reducing response times across enterprise and managed environments.
Cloud-Native Security Architectures
Native integration of security tooling into public and hybrid cloud environments is replacing perimeter-based, on-premises defenses, enabling continuous monitoring across distributed infrastructure and remote workforces.
Zero-Trust and Identity-Centric Models
Growing adoption of zero-trust frameworks is shifting enterprise focus toward continuous identity verification and least-privilege access, addressing the identity and multi-cloud visibility gaps that have historically enabled credential-based intrusions.
Automation and Orchestration
Security orchestration, automation, and response tooling is streamlining incident handling across managed security operations centers, allowing providers to scale coverage across a growing base of subscription clients without proportional headcount increases.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Component |
Solution |
71.8% |
2025 |
|
Organization Size |
Large Enterprises |
67.5% |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
Vertical |
🔒 |
🔒 |
2025 |
|
Region |
Central Mexico |
46.7% |
2025 |
By Component
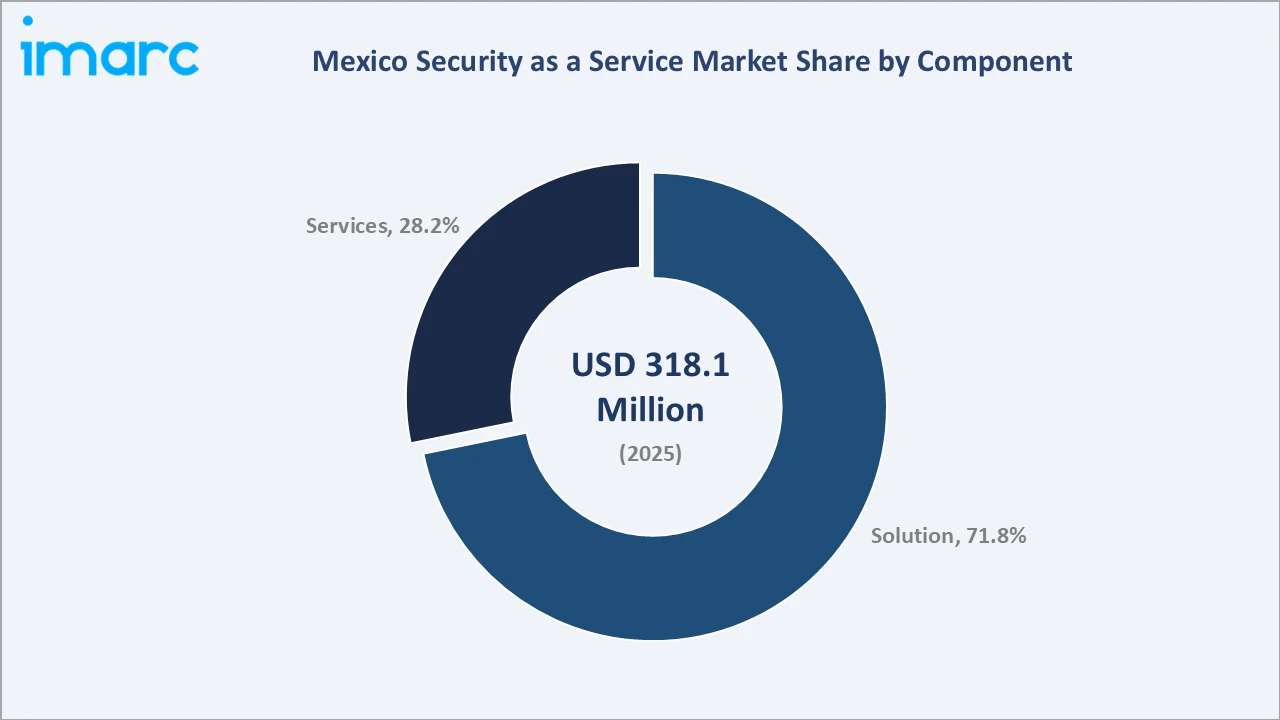
Solution commands a 71.8% majority share in 2025, driven by enterprise demand for cloud-native firewalls, encryption, endpoint protection, and identity and access management platforms delivered on a subscription basis. The segment benefits from lower deployment complexity, predictable subscription revenue, and rapid feature iteration across vendor platforms.
To access detailed market analysis, Request Sample
Services at 28.2% in 2025 cover consulting, integration, and managed monitoring offerings that support organizations lacking in-house security expertise. The segment remains vital for small and medium-sized enterprises seeking full-service protection without dedicated internal teams.
By Organization Size
Large enterprises dominate with 67.5% share in 2025, reflecting greater budget capacity, complex multi-site infrastructure, and stricter regulatory obligations across banking, manufacturing, and government sectors. The segment remains the default early adopter of comprehensive, multi-layered security service contracts.
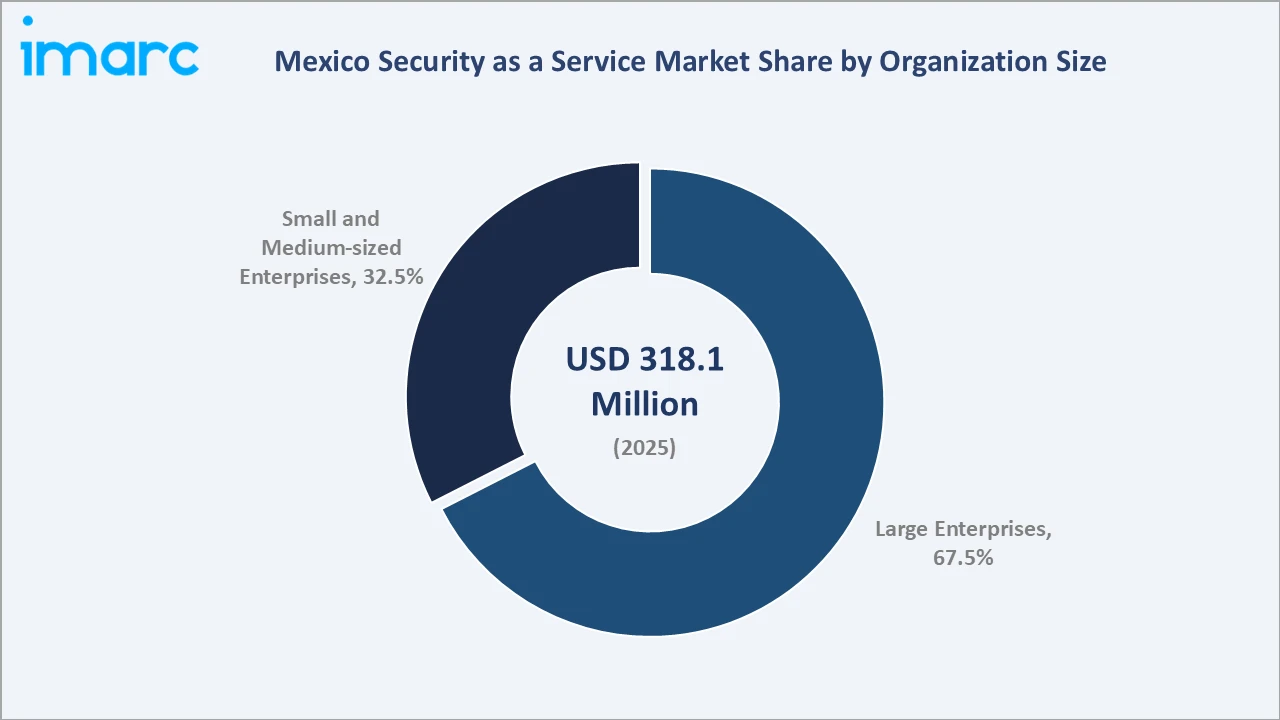
Small and medium-sized enterprises at 32.5% are expanding through affordable, subscription-priced offerings that lower the barrier to enterprise-grade protection. Rising awareness of ransomware exposure is accelerating adoption among smaller, resource-constrained businesses.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
Central Mexico |
46.7% |
Dense corporate headquarters concentration, strong data center presence, deep digital infrastructure, and high enterprise security spending |
|
Northern Mexico |
31.6% |
Nearshoring-driven manufacturing expansion, cross-border trade with the United States, and growing industrial cybersecurity requirements |
|
Southern Mexico |
14.1% |
Expanding digital adoption, emerging industrial investment, and rising government modernization initiatives |
|
Others |
7.6% |
Gradual digital infrastructure development and increasing awareness of cybersecurity risk across smaller regional markets |
Central Mexico at 46.7% in 2025 leads the regional landscape, anchored by Mexico City, Puebla, and the State of Mexico. The dense concentration of corporate headquarters, financial institutions, and data infrastructure supports sustained leadership across both solution and services segments.
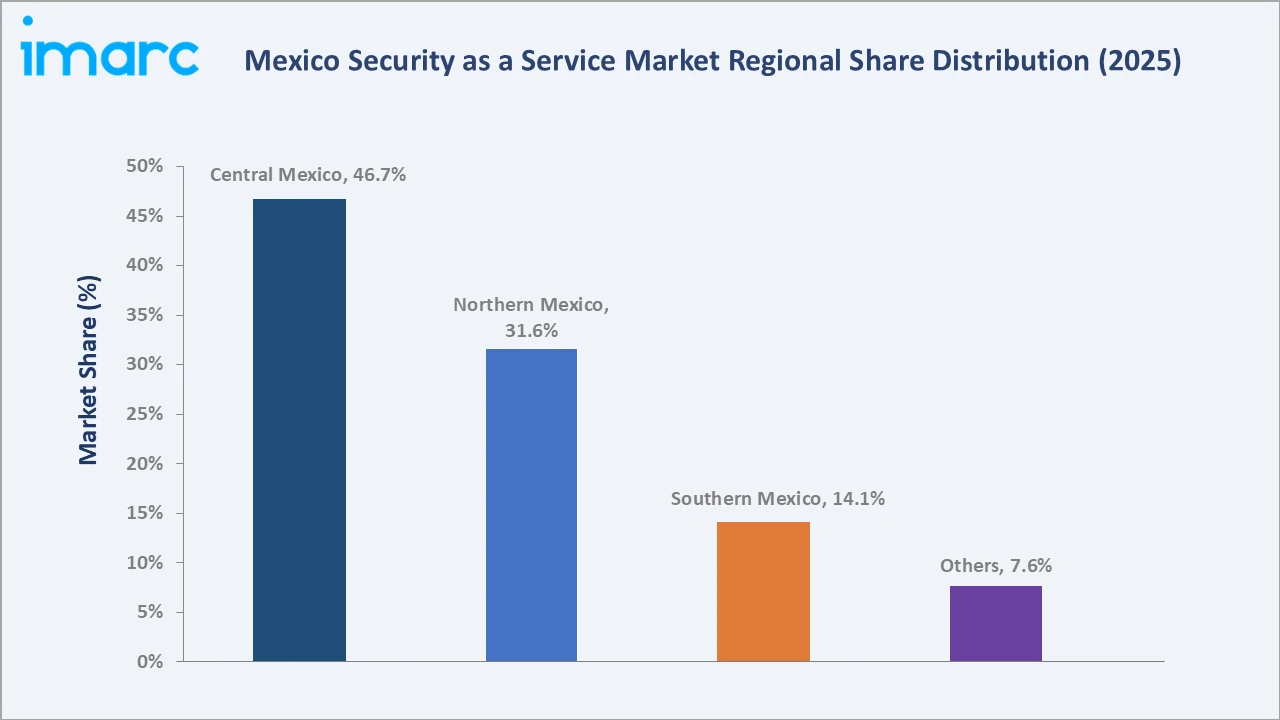
Southern Mexico, at 14.1%, is the fastest growing region. Expanding digital adoption, emerging industrial investment, and rising government modernization initiatives are accelerating regional expansion through 2034.
Competitive Landscape
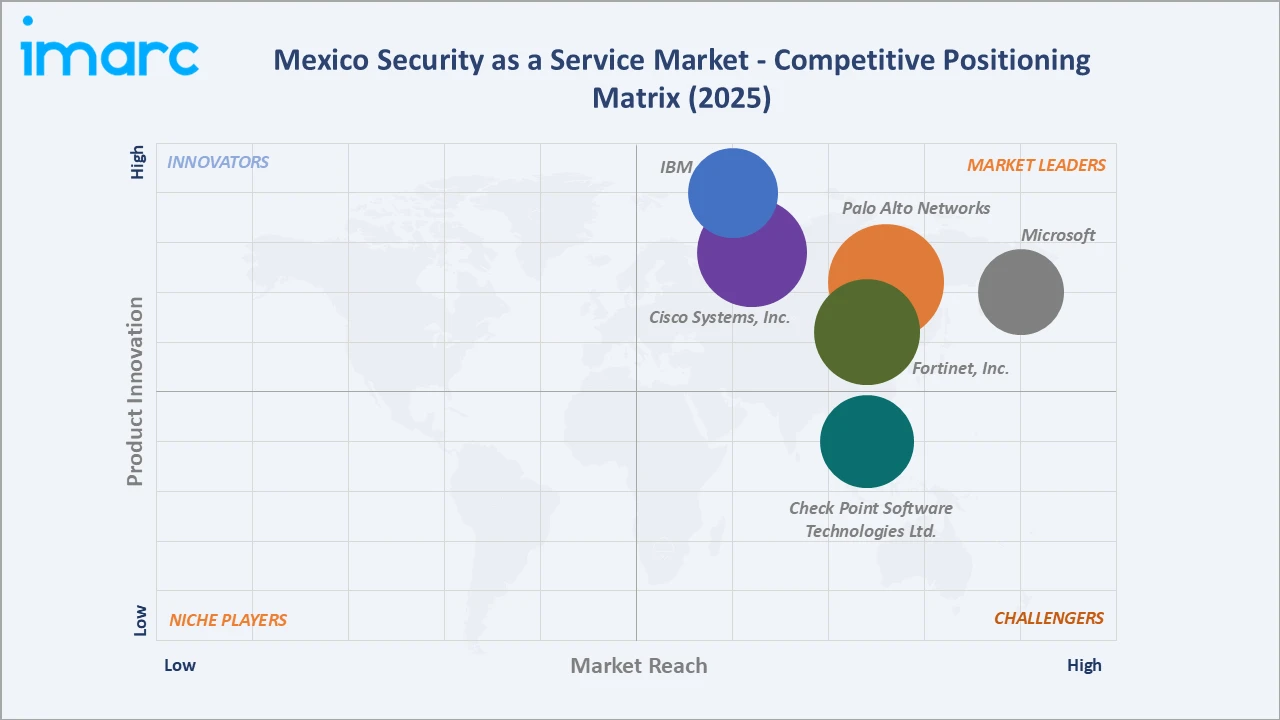
The Mexico security as a service market is moderately fragmented, with established global technology vendors leading platform depth and brand recognition while regional providers compete on localized delivery and managed service relationships. Technology breadth, cloud platform integration, and local support capability form the key competitive differentiators.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
|
IBM |
IBM Security |
Leader |
Broadening cloud-native security and AI-driven threat detection capabilities for enterprise clients |
|
Microsoft |
Microsoft Defender |
Leader |
Expanding integrated cloud security offerings across enterprise and government accounts |
|
Cisco Systems, Inc. |
Cisco Secure Access |
Leader |
Strengthening network security and unified threat visibility across hybrid environments |
|
Fortinet, Inc. |
FortiGate |
Leader |
Scaling platform-based security delivery across enterprise and mid-market segments |
|
Palo Alto Networks |
Cortex Cloud |
Leader |
Advancing cloud-native and AI-integrated security platforms for regional enterprises |
|
Check Point Software Technologies Ltd. |
Check Point Infinity Platform |
Challenger |
Growing managed threat prevention offerings across regulated industries |
Key players include IBM, Microsoft, Cisco Systems, Inc., Fortinet, Inc., Palo Alto Networks, and Check Point Software Technologies Ltd., among others.
Key Company Profiles
IBM
IBM is a global technology and consulting company headquartered in Armonk, New York, United States, with an established presence in Mexico's enterprise technology and security landscape. The company offers a broad portfolio of cybersecurity solutions spanning threat detection, identity management, and managed security services for large enterprises and government clients.
- Product Portfolio: IBM Security offering threat detection, security information and event management, identity governance, and managed detection and response for enterprise clients.
- Recent Developments: The firm continues to expand its cybersecurity portfolio through enhancements to cloud security, threat detection, identity management, and AI-enabled security capabilities, supporting the evolving security needs of enterprise and public sector organizations.
- Strategic Focus: Broadening cloud-native security and AI-driven threat detection capabilities to support large enterprise and public sector clients across Mexico.
Microsoft
Microsoft is a global technology company headquartered in Redmond, Washington, United States, with an established cloud and security footprint in Mexico. The company delivers integrated security capabilities embedded within its cloud platform, serving enterprise, government, and mid-market clients.
- Product Portfolio: Microsoft Defender offering endpoint protection, cloud security posture management, and unified security operations for enterprise clients.
- Recent Developments: The company continues to expand its unified security operations platform, integrating threat detection, identity protection, and cloud security capabilities across its enterprise product suite.
- Strategic Focus: Expanding integrated, cloud-native security offerings across enterprise and government accounts as digital transformation accelerates nationally.
Cisco Systems, Inc.
Cisco Systems, Inc. is a global networking and cybersecurity company headquartered in San Jose, California, United States, with an established enterprise and telecom customer base across Mexico. The company delivers network security and secure access offerings to enterprise clients.
- Product Portfolio: Cisco Secure Access offering cloud-delivered security service edge capabilities, including zero trust network access and secure web gateway functions.
- Recent Developments: The firm continues to expand its security service edge and zero trust portfolio, integrating new capabilities to support hybrid work and secure access requirements.
- Strategic Focus: Strengthening unified threat visibility and network security integration across hybrid enterprise environments in Mexico.
Market Concentration Analysis
The Mexico security as a service market is moderately concentrated, with a handful of global technology vendors accounting for a significant share of enterprise deployments through established platform ecosystems and channel partnerships.
Barriers to entry include the scale required to maintain continuously updated threat intelligence, the need for cloud-native platform infrastructure, and the difficulty of building trusted, localized delivery capability. These factors favor well-capitalized incumbents with established global research and development functions.
Consolidation is accelerating as larger vendors acquire specialized point solutions to broaden platform breadth, while regional managed security service providers pursue partnerships with global technology vendors to extend their service catalogs across Mexico's enterprise and public sector clients.
Investment & Growth Opportunities
Fastest-Growing Segments
Services grow fastest among components, driven by growing enterprise reliance on managed monitoring and consulting amid persistent talent shortages. Small and medium-sized enterprises represent the fastest-expanding organization size segment as subscription pricing lowers adoption barriers.
Emerging Markets
Southern Mexico is the fastest expanding region, anchored by rising digital adoption and emerging industrial investment. The market represents significant untapped opportunity for providers able to deliver cost-effective, regionally supported service offerings.
Venture & Investment Trends
Investment is concentrated in cloud-native security platforms, managed detection and response providers, and identity-centric security tooling. Capital is also flowing into regional managed security service providers positioned to serve Mexico's growing base of small and medium-sized enterprise clients.
Future Market Outlook (2026-2034)
The Mexico security as a service market is forecast to expand from USD 318.1 Million in 2025 to USD 893.5 Million by 2034 at a CAGR of 11.80%, adding roughly USD 575.4 Million in incremental market value over the forecast period.
Three forces will shape the market through 2034: continued migration toward cloud-native, subscription-priced security delivery; deeper integration of AI into threat detection and response; and sustained enterprise exposure to ransomware and identity-based attacks that reinforce demand for continuously updated protection.
By 2034, the market is expected to be defined by consolidated, platform-based security delivery, with small and medium-sized enterprises accounting for a meaningfully higher share of overall adoption. Regulatory maturation, nearshoring-driven industrial expansion, and growing digital payments infrastructure are expected to further accelerate the evolution of Mexico's security as a service ecosystem.
Research Methodology
Primary Research
Primary research included structured interviews with security platform executives, managed service providers, systems integrators, and enterprise security leaders, validating market sizing, segment mix, and regional demand patterns.
Secondary Research
Secondary sources included national cybersecurity policy publications, telecommunications regulatory filings, threat-intelligence vendor reports, and annual reports, press releases, and investor presentations from listed technology vendors.
Forecasting Models
Market forecasts used top-down and bottom-up models combining enterprise technology spending patterns, cloud adoption rates, segment mix evolution, and macroeconomic variables. Scenario analysis addressed regulatory development, talent availability, and cloud infrastructure expansion.
Mexico Security as a Service Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Components Covered | Solution, Services |
| Organization Sizes Covered | Small and Medium-sized Enterprises, Large Enterprises |
| Applications Covered | Network Security, Endpoint Security, Application Security, Cloud Security, Others |
| Verticals Covered | BFSI, Government and Defense, Retail and E-Commerce, Healthcare and Life Sciences, IT and Telecom, Energy and Utilities, Manufacturing, Others |
| Regions Covered | Northern Mexico, Central Mexico, Southern Mexico, Others |
| Companies Covered | IBM, Microsoft, Cisco Systems, Inc., Fortinet, Inc., Palo Alto Networks, Check Point Software Technologies Ltd., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Mexico security as a service market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Mexico security as a service market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Mexico security as a service industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Mexico Security as a Service Market Report
The Mexico security as a service market was valued at USD 318.1 Million in 2025, driven by rising cyberattack frequency, cloud adoption, and growing enterprise outsourcing of security operations.
The market is projected to grow at a CAGR of 11.80% from 2026-2034, reaching USD 893.5 Million, supported by nearshoring-driven demand and expanding small and medium-sized enterprise adoption.
Solution leads at 71.8% in 2025, driven by strong demand for cloud-native firewalls, encryption, and identity and access management platforms delivered through subscription-based models.
Large enterprises dominate at 67.5% in 2025, reflecting greater budget capacity, complex multi-site infrastructure, and stronger regulatory obligations across the banking, manufacturing, and government sectors.
Central Mexico commands 46.7% in 2025, led by dense corporate concentration in Mexico City and strong data center infrastructure across the surrounding metropolitan region.
Leading players include IBM, Microsoft, Cisco Systems, Inc., Fortinet, Inc., Palo Alto Networks, and Check Point Software Technologies Ltd., among others.
Nearshoring-driven manufacturing expansion is bringing new factories and connected supply chains into the threat landscape, widening demand for scalable, managed security coverage across Northern Mexico.
Advances in AI-driven threat detection, cloud-native architectures, and zero-trust frameworks are enabling providers to offer faster, more automated protection across enterprise and mid-market clients.
A persistent shortage of skilled cybersecurity professionals and constrained public sector technology budgets are limiting the pace of broader market adoption across smaller organizations.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade