Mexico Seeds Market Size, Share, Trends and Forecast by Type, Seed Type, Traits, Availability, Seed Treatment, and Region, 2026-2034
Mexico Seeds Market Size, Share, Trends & Forecast (2026-2034)
The Mexico seeds market grew from USD 557.9 Million in 2025 to USD 566.6 Million in 2026 and is projected to reach USD 645.8 Million by 2034, growing at a CAGR of 1.56% during 2026-2034. The market is driven by growing adoption of hybrid seed varieties, government agricultural support programs, and the expansion of commercial farming and export-oriented horticulture. Conventional seeds lead at 72.8% by type, herbicide-tolerant traits dominate at 51.6% by traits, and Central Mexico commands the largest regional share at 42.8% in 2025.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 557.9 Million |
|
Market Size (2026) |
USD 566.6 Million |
|
Forecast Market Size (2034) |
USD 645.8 Million |
|
CAGR (2026-2034) |
1.56% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Conventional Seeds (72.8%, 2025) |
|
Dominant Traits |
Herbicide-Tolerant (51.6%, 2025) |
|
Leading Region |
Central Mexico (42.8%, 2025) |
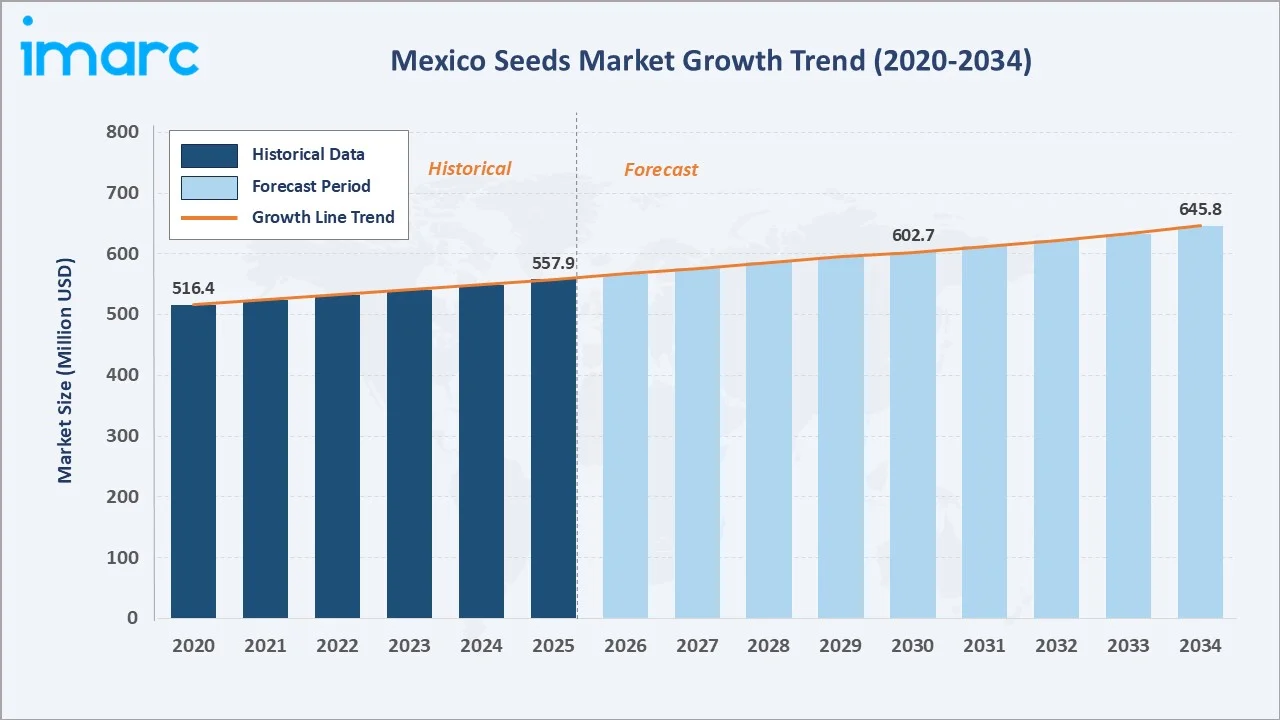
The Mexico seeds market grew from USD 516.4 Million in 2020 to USD 557.9 Million in 2025, and further to USD 566.6 Million in 2026, reflecting steady demand from hybrid seed adoption, commercial vegetable and grain production expansion, and government agricultural development programs. The market is projected to reach USD 602.7 Million by 2030 before reaching USD 645.8 Million by 2034.
To get more information on this market, Request Sample
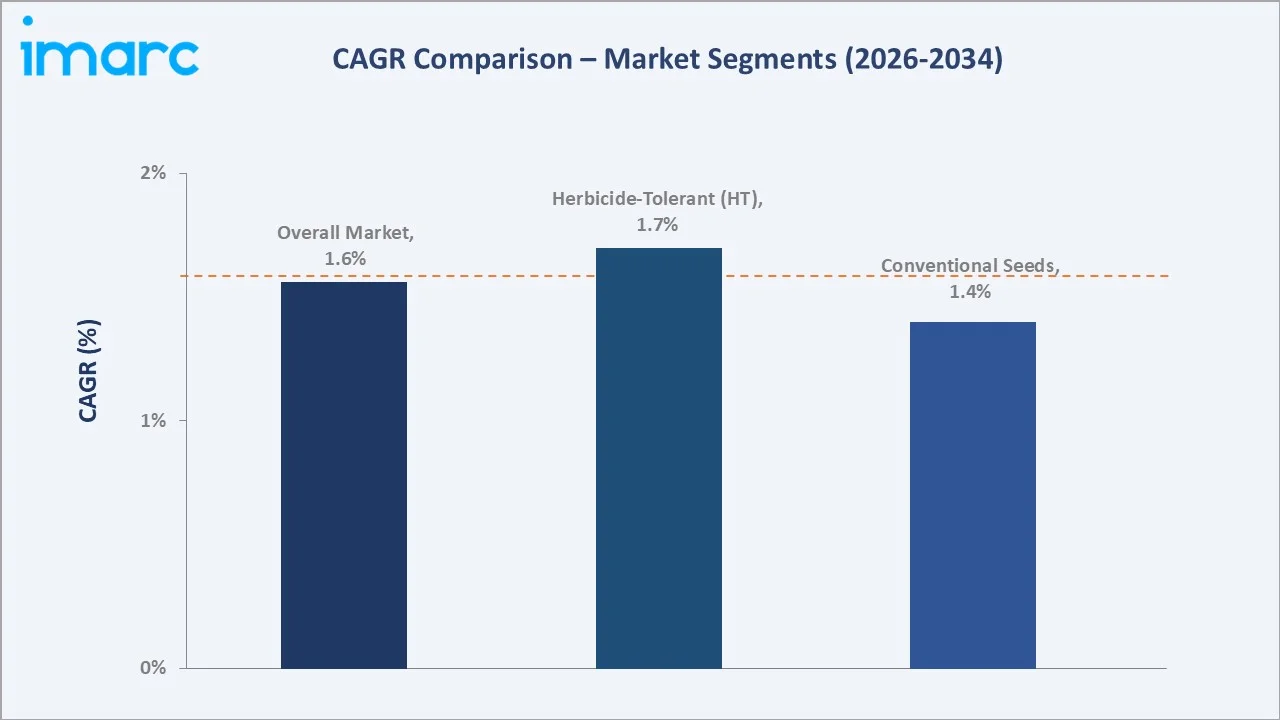
Conventional seeds are growing at 1.4% CAGR as native variety protection policies and hybrid non-GMO alternatives gain adoption across corn-growing regions. Herbicide-tolerant traits at 1.7% CAGR reflect sustained farmer preference for weed management solutions compatible with Mexico regulatory environment. The moderate overall CAGR of 1.56% reflects the regulatory complexity introduced by the GM corn ban decree, balanced by sustained growth in non-GMO hybrid seed adoption and vegetable seed demand.
Executive Summary
The Mexico seeds market is driven by expanding agricultural acreage, rising demand for higher crop yields, and the adoption of improved seed varieties. Growing cultivation of crops such as corn, vegetables, cotton, and fruits is increasing demand for quality seeds. Additionally, greater use of hybrid, disease-resistant, and drought-tolerant seeds is supporting market growth amid changing climatic conditions.
Conventional seeds at 72.8% dominate, reflecting both the regulatory preference for non-GMO varieties and the large base of smallholder corn farmers who rely on open-pollinated and conventional hybrid seed varieties for subsistence and commercial production. Herbicide-tolerant traits at 51.6% represent the largest trait category, serving commercial farmers managing weed pressure across irrigated and rainfed cultivation systems. Central Mexico leads regionally at 42.8%, driven by the Bajio agricultural heartland that is Mexico most productive commercial farming zone for corn, sorghum, wheat, and vegetables.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Conventional Seeds - 72.8% share (2025) |
|
Dominant Traits |
Herbicide-Tolerant (HT) - 51.6% share (2025) |
|
Leading Region |
Central Mexico - 42.8% (2025) |
|
Key Market Opportunity |
Non-GMO high-yielding hybrid corn and vegetable seed development to fill the market space created by the GM corn ban decree and growing export-oriented horticulture demand. |
Key Analytical Observations Supporting the Above Data:
- Conventional Seeds at 72.8%: Conventional seeds dominate because Mexico has consistently prioritized the protection of its native corn diversity and because the large base of smallholder corn farmers relies on open-pollinated and conventional hybrid varieties that are accessible, affordable, and culturally integrated into traditional agricultural systems.
- Herbicide-Tolerant Traits at 51.6%: Herbicide-tolerant traits lead because weed management is the primary agronomic challenge for Mexican farmers across both rainfed and irrigated cultivation systems, and HT varieties enable cost-effective broadleaf and grass weed control through compatible herbicide applications.
- Central Mexico at 42.8%: Central Mexico commands most of the national market because the Bajio region is Mexico most productive and commercially sophisticated agricultural zone, with high adoption rates of hybrid and improved seed varieties, strong distribution infrastructure, and proximity to the national agricultural technology support services that facilitate commercial seed adoption at scale.
Mexico Seeds Market Overview
The Mexico seeds market encompasses the production, distribution, and sale of all commercial seed categories including field crop seeds (corn, sorghum, wheat, soybeans, cotton), vegetable seeds (tomato, bell pepper, cucumber, onion, squash), forage seeds, and specialty crop seeds. Mexico is the center of origin and diversity for corn, with recognized native races representing irreplaceable genetic diversity that has shaped the country's distinctive regulatory approach to genetically modified crop cultivation. The market serves a dual demand base: a large smallholder sector growing corn for subsistence and local markets using open-pollinated and conventional hybrid varieties, and a commercial farming sector growing grain, oilseed, vegetable, and export horticulture crops using high-performance hybrid seed varieties.
Market Dynamics
To evaluate market opportunities, Request Sample
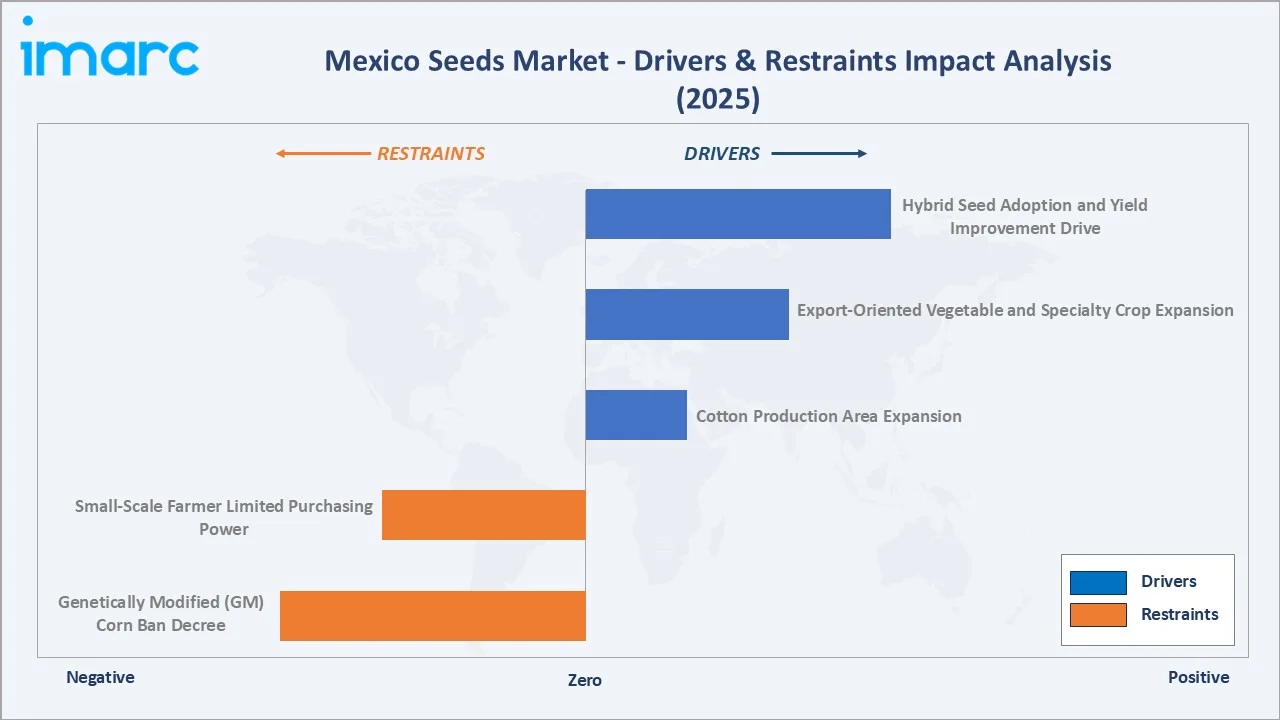
Market Drivers
- Hybrid Seed Adoption and Yield Improvement Drive: Mexico has been one of the largest markets for hybrid seeds since the early 2000s and has been consistently increasing hybrid seed usage across corn, sorghum, vegetables, and specialty crops. Hybrid corn and vegetable seeds are increasingly preferred by commercial farmers due to higher yield potential, better adaptability to local climatic conditions, and greater disease resistance. The shift from traditional open-pollinated seeds to hybrid varieties improves overall farm productivity while reducing losses caused by pests and climate variability, positively impacting the commercial seed market even as GM seed restrictions limit the broader biotechnology segment.
- Export-Oriented Vegetable and Specialty Crop Expansion: Mexico’s total vegetable exports reached 9,109,626 tons in 2024. Mexico is a major global exporter of fresh vegetables, tomatoes, avocados, and berries, with the export horticulture sector representing one of the highest-value segments of Mexico agriculture. This sector generates significant demand for premium vegetable seed varieties from international seed companies, with quality, disease resistance, and export market compatibility driving seed selection rather than price sensitivity.
- Cotton Production Area Expansion: In Mexico, post projects cotton production for MY 2026/27 at 0.87 million 480-lb bales, representing a 32% increase. Greater planted acreage encourages farmers to adopt improved, high-yielding and disease-resistant seed varieties to enhance productivity. The expansion also creates opportunities for seed suppliers to introduce advanced varieties suited to Mexico’s diverse growing conditions.
Market Restraints
- Genetically Modified (GM) Corn Ban Decree: In March 2025, President Claudia Sheinbaum signed a decree formally banning the planting of genetically modified corn throughout Mexico, formalizing constitutional reforms to Articles 4 and 27 aimed at conserving and protecting native corn varieties. This removes a category of commercial seed products from the market and introduces ongoing trade tension with corn suppliers.
- Small-Scale Farmer Limited Purchasing Power: The majority of Mexico corn farmers operate at subsistence or near-subsistence scale with limited purchasing power for premium commercial seed products. Price sensitivity among small-scale farmers constrains market penetration of commercial hybrid seed varieties in regions where traditional farmer-saved open-pollinated seed remains the default choice, particularly in southern Mexico indigenous agricultural communities.
Market Opportunities
- Vegetable Seed Premium Market Growth: Mexico large and growing export vegetable sector demands premium quality vegetable seed varieties with specific traits for disease resistance, shelf life, export market appearance, and productivity under controlled agriculture conditions. The expansion of greenhouse horticulture is particularly driving demand for premium tomato, pepper, cucumber, and other vegetable seed products.
- Native Corn Variety Improvement and Commercialization: Government policies protecting native corn varieties create an opportunity for seed programs focused on improving the productivity and consistency of native landraces while maintaining their genetic integrity, positioning improved native varieties as commercially viable alternatives for smallholder farmers committed to traditional corn cultivation within Mexico bioculturally significant corn diversity framework.
Market Challenges
- Trade Tensions and Import Corn Disruption: Trade tensions and import corn disruptions are creating uncertainty around the availability and cost of imported corn seed varieties and agricultural inputs. Changes in trade policies, tariffs, or cross-border restrictions may increase procurement costs for seed companies and farmers. Supply-chain disruptions can also delay seed deliveries and encourage greater reliance on locally produced alternatives.
- Climate Change and Drought Risk in Key Agricultural Zones: Northern Mexico large-scale irrigated agriculture depends heavily on reliable water availability, and progressive drought conditions affecting the key river systems are creating production risk that reduces farmers' willingness to invest in premium seed varieties when water availability for crop completion cannot be assured.
Emerging Market Trends
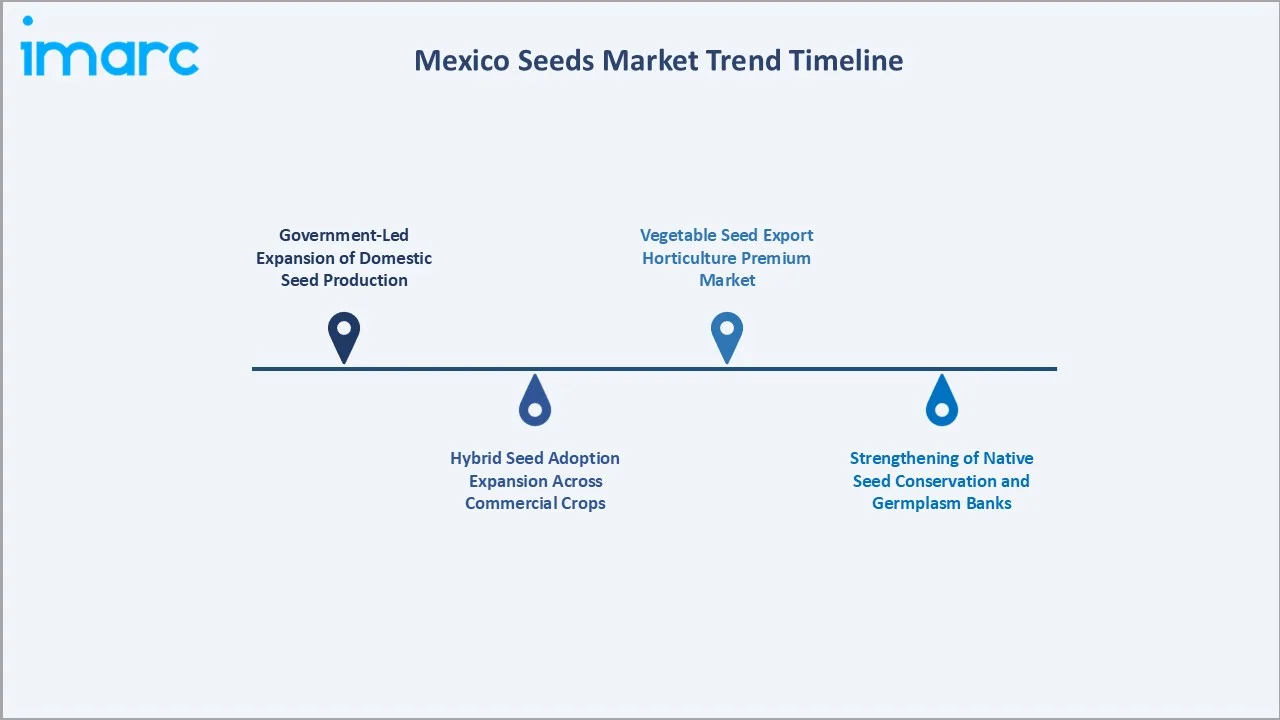
1. Government-Led Expansion of Domestic Seed Production
Increased availability of affordable, certified seeds is expected to support small and medium-sized farmers while encouraging greater adoption of quality seed varieties. In April 2025, Mexico launched PROSEBIEN, a state-owned company in Zacatecas, to expand affordable certified seed production for crops such as beans and rice. The initiative supports small and medium-sized farmers, aims to improve yields, and aligns with Plan México’s goal of food self-sufficiency by 2030 while reducing dependence on imported seeds. This launch highlights a growing focus on strengthening domestic seed production and reducing dependence on imported seeds.
2. Hybrid Seed Adoption Expansion Across Commercial Crops
Hybrid seed adoption continues to expand across Mexico commercial agriculture, driven by the inherent characteristics of high vigor, resistance to biotic and abiotic stresses, high yield potential, and uniform maturity that hybrid varieties provide versus open-pollinated alternatives. Cucumber, pumpkin, and squash show particularly strong hybrid adoption, driven by the quality consistency that hybrid seed provides for export market specification compliance. As more farmers transition from traditional to hybrid seed varieties, advanced planting equipment adoption is reinforcing commercial seed uptake by enabling farmers to maximize investment returns from premium hybrid seeds.
3. Vegetable Seed Export Horticulture Premium Market
Mexico expanding role as a global fresh produce exporter is creating sustained demand for premium vegetable seed varieties from international specialty seed companies. The greenhouse and protected cultivation sectors generate particularly strong demand for high-performance tomato, pepper, and cucumber hybrid seed varieties with specific trait profiles for export market appearance, pathogen resistance, and shelf life. This premium vegetable seed segment commands significantly higher prices per kilogram than field crop seed and is growing faster than the overall market as export horticulture investment continues.
4. Strengthening of Native Seed Conservation and Germplasm Banks
In September 2025, President Claudia Sheinbaum announced plans to strengthen germplasm and seed banks to preserve Mexico’s native corn varieties, which are regarded as an important part of the country’s cultural heritage. The initiative follows a constitutional reform restricting the cultivation of genetically modified corn, with the aim of protecting native varieties from genetic contamination and potential loss. This trend is likely to encourage demand for seed conservation, storage, and genetic resource management while supporting the protection of indigenous corn varieties.
Industry Value Chain Analysis
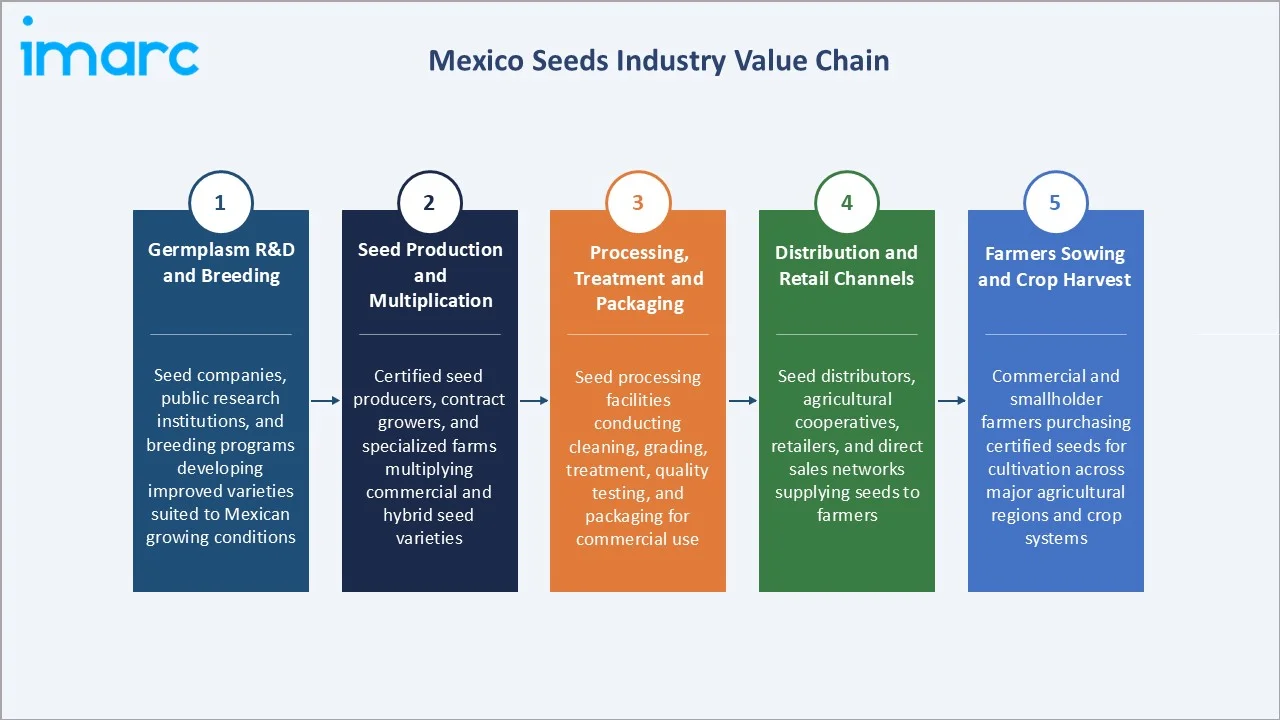
The Mexico seeds value chain spans five integrated stages from germplasm research through end-use farming. The seed production and multiplication stage captures the highest commercial value in the chain for field crop seeds, while the germplasm R&D and breeding stage provides the foundational intellectual property value that enables differentiated seed product development and commercial positioning across all crop categories.
|
Stage |
Key Participants |
|
Germplasm R&D and Breeding |
Seed companies, public research institutions, and breeding programs developing improved varieties suited to Mexican growing conditions. |
|
Seed Production and Multiplication |
Certified seed producers, contract growers, and specialized farms multiplying commercial and hybrid seed varieties. |
|
Processing, Treatment and Packaging |
Seed processing facilities conducting cleaning, grading, treatment, quality testing, and packaging for commercial use. |
|
Distribution and Retail Channels |
Seed distributors, agricultural cooperatives, retailers, and direct sales networks supplying seeds to farmers. |
|
Farmers Sowing and Crop Harvest |
Commercial and smallholder farmers purchasing certified seeds for cultivation across major agricultural regions and crop systems. |
The germplasm R&D and breeding stage is the highest value-added stage in the Mexico seeds value chain. Companies with proprietary breeding programs and extensive germplasm libraries command premium pricing and preferred agronomist recommendation across commercial farming regions, as the genetic performance advantage of superior hybrid varieties is directly measurable in farm income and provides sustainable commercial differentiation.
Technology Landscape in the Mexico Seeds Industry
Seed Treatment Technology and Biological Protection
Seed treatment technology, applying fungicide, insecticide, nematicide, and biological protection agents to seed surfaces before planting, is a growing value-added service layer in Mexico commercial seed market that improves seedling establishment, reduces early-season pest and disease pressure, and allows farmers to reduce in-crop agrochemical applications.
Vegetable Seed Trait Innovation for Export Markets
Export market vegetable seed technology is advancing rapidly, with major international vegetable seed companies developing varieties with improved pathogen resistance, post-harvest quality, and standardized appearance for retail and food service market specifications. The expansion of indoor and protected cultivation environments in Mexico largest vegetable-growing regions enables deployment of high-performance hybrid vegetable varieties optimized for controlled environment production, driving innovation in seed performance traits relevant to protected cultivation systems.
Digital Agronomy and Precision Seed Management
Leading seed companies operating in Mexico are integrating digital agronomy platforms, satellite field monitoring, and data-driven planting recommendation services with their seed product portfolios. These digital tools improve farmer variety selection accuracy, optimize planting dates and densities for local conditions, and provide early warning for pest and disease pressure that affects seed germination and crop establishment.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Conventional Seeds |
72.8% |
2025 |
|
Seed Type |
🔒 |
🔒 |
2025 |
|
Traits |
Herbicide-Tolerant (HT) |
51.6% |
2025 |
|
Availability |
🔒 |
🔒 |
2025 |
|
Seed Treatment |
🔒 |
🔒 |
2025 |
|
Region |
Central Mexico |
42.8% |
2025 |

By Type
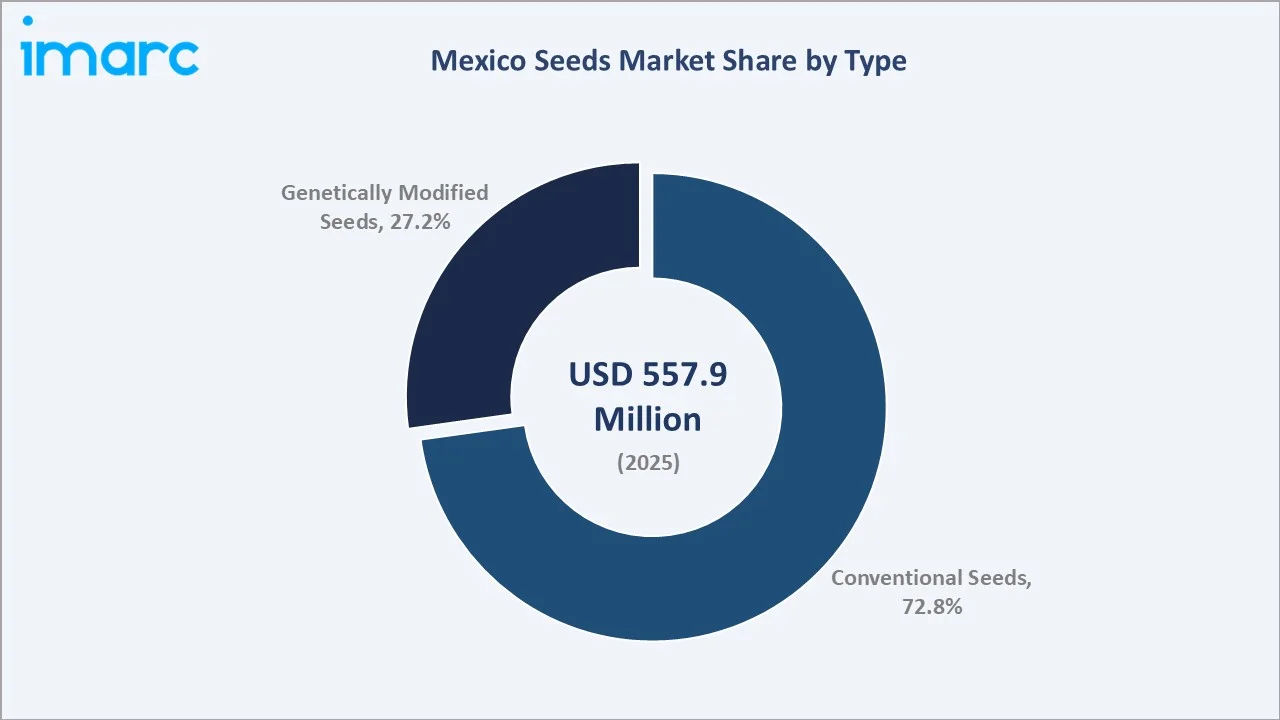
Conventional seeds lead at 72.8% in 2025, reflecting the combination of a large smallholder corn farming base that relies on open-pollinated and conventional hybrid varieties, and the cultural and policy commitment to protecting Mexico native corn diversity.
To access detailed market analysis, Request Sample
Genetically modified seeds at 27.2% serve non-corn crop categories including soybeans, cotton, and canola where GM cultivation remains permitted, as well as the import-oriented corn supply chain for animal feed and industrial uses.
By Traits
Herbicide-tolerant (HT) traits lead at 51.6% in 2025, reflecting the primary agronomic challenge of weed management that faces Mexican commercial farmers across corn, sorghum, cotton, and vegetable cultivation systems. Herbicide-tolerant varieties enable more flexible and cost-effective weed management approaches, reducing labor costs for hand weeding and enabling precision herbicide application that minimizes crop damage while controlling competitive weed species.
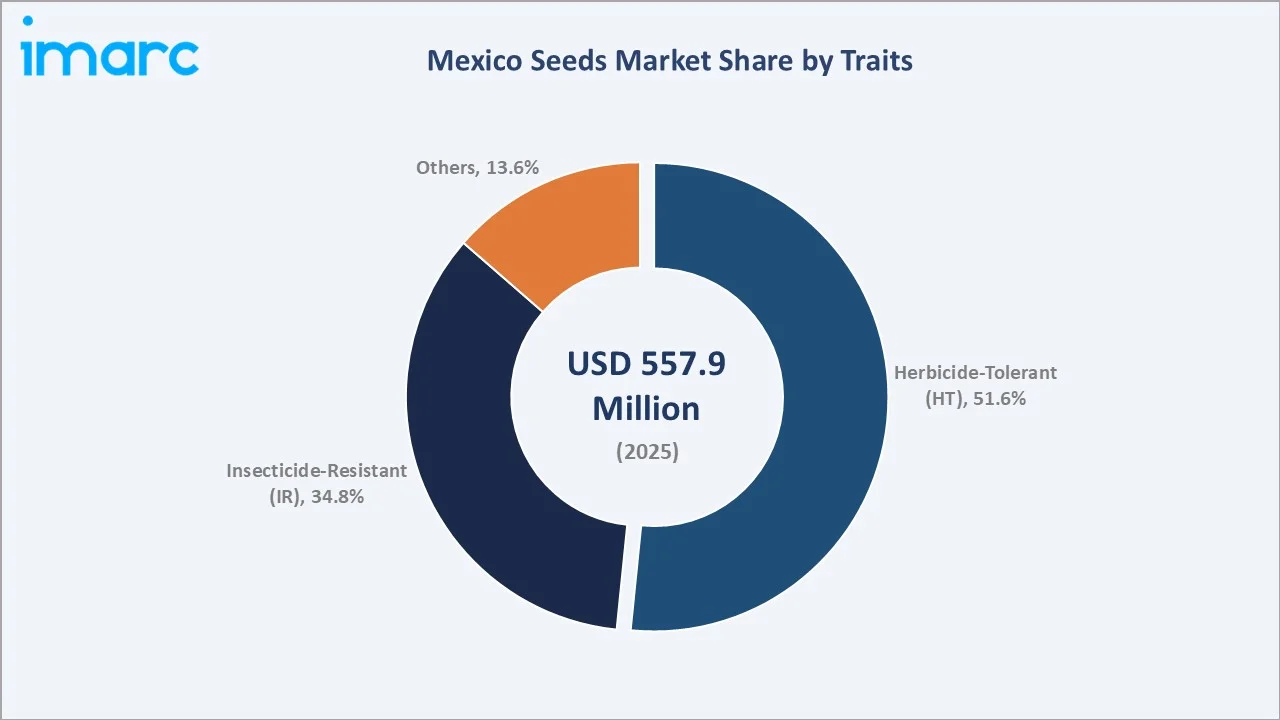
Insecticide-resistant (IR) traits at 34.8% serve commercial farmers facing significant insect pest pressure, particularly from stem borers, fall armyworm, and other Lepidopteran pests that cause substantial yield losses in corn, cotton, and sorghum. Others at 13.6% include drought-tolerant, disease-resistant, and stacked trait varieties across multiple crop categories.
Regional Market Insights
|
Region |
Share (2025) |
Key Mexico Seeds Market Drivers & Characteristics |
|
Central Mexico |
42.8% |
Strong agricultural activity and diverse crop cultivation support significant demand for certified and improved seed varieties. |
|
Northern Mexico |
33.6% |
Irrigated farming, commercial agriculture, and higher adoption of hybrid seeds contribute to regional seed demand. |
|
Southern Mexico |
18.5% |
Smallholder farming and cultivation of traditional crops drive demand for affordable and locally adapted seeds. |
|
Others |
5.1% |
Emerging agricultural areas and specialized crop production contribute to the remaining market demand. |
The Central Mexico region held the largest share of the Mexico seeds market in 2025, accounting for 42.8%, supported by extensive agricultural activity and diverse crop cultivation. Northern Mexico followed with a 33.6% share, driven by commercial farming and the use of improved seed varieties.
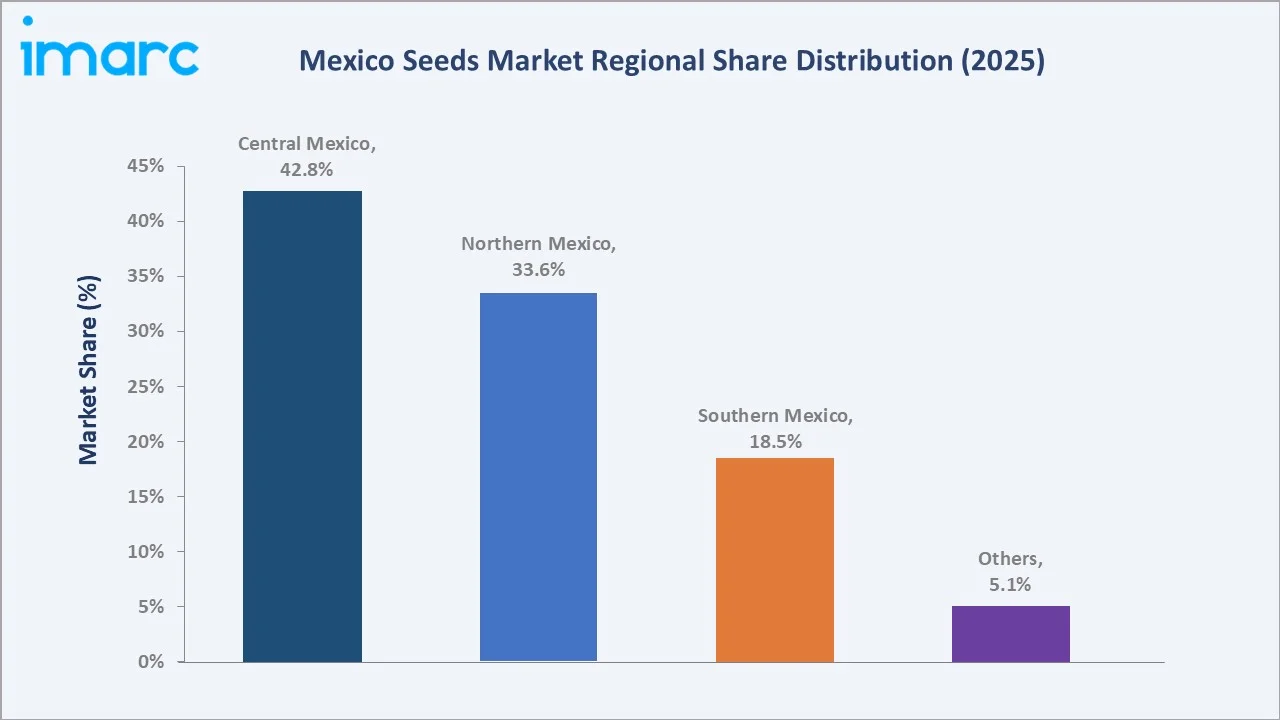
Southern Mexico represented 18.5%, with demand supported largely by smallholder farming and traditional crop production. The other regions accounted for the remaining 5.1% of the market.
Competitive Landscape
The Mexico seeds market is moderately consolidated. The market is characterized by strong competition between global agrochemical and seed conglomerates alongside specialized vegetable seed companies, international research institutions, and domestic seed producers.
| Company | Key Products | Market Position | Core Strength |
|---|---|---|---|
| Bayer AG | Asgrow, DEKALB, De Ruiter, Deltapine | Market Leader | Bayer AG shapes Mexico’s agricultural and seed sector by introducing advanced short-stature hybrid seeds, digital farming tools, and sustainable regenerative practices to combat climate challenges. |
| Corteva | Pioneer seeds, Brevant seeds | Market Leader | Corteva supplies advanced hybrid and conventional crop seeds, genetics, and seed-applied technologies to support Mexican agriculture. |
| BASF | Credenz Soybean Seed | Established Player | BASF plays a major role in Mexico’s seed and agricultural market, primarily focusing on high-value vegetable seeds, genomic research partnerships, and advanced seed treatments. |
| Sakata Seed Corporation | Astral, Katana, Log, Mandarin Delite, Musketeer, Safari, Sergeant, Shawnee | Established Player | Sakata Seed Corporation plays a major role in Mexico’s seed and agriculture industry through its local subsidiary, Grupo Sakata Seed de Mexico. |
| Rijk Zwaan Zaadteelt en Zaadhandel B.V. | Aubergine seeds, Beetroot seeds, Broccoli, Cabbage, Cauliflower and Kohlrabi seeds, Celery seeds | Challenger | Rijk Zwaan Zaadteelt en Zaadhandel B.V. functions as a major international vegetable breeding and seed company that holds a prominent market position in the Mexican vegetable seed sector. |
Companies that can deliver yield-competitive conventional hybrid corn varieties will be positioned to capture significant market share in the transition period as commercial farmers seek non-GMO alternatives with comparable productivity to previously available transgenic hybrids.
Key Company Profiles
Bayer AG
Bayer AG is a global life sciences company with operations across agriculture, healthcare, and related fields. In Mexico, the company serves the agricultural sector through its crop science portfolio, including seeds, crop protection products, and digital farming solutions. Its seed activities focus on developing and supplying improved varieties designed to support crop productivity and adaptation to local growing conditions. The company works with farmers and agricultural partners across Mexico to provide integrated crop-management solutions.
- Key Products: Asgrow, DEKALB, De Ruiter, Deltapine.
- Strategic Focus: Expanding its agricultural seed portfolio in Mexico by developing high-performance, locally adapted seed varieties. Its strategy emphasizes innovation, crop productivity, resilience to environmental stresses, and integrated solutions that support farmers across different cultivation systems.
Corteva
Corteva is a global agricultural company providing seed, crop protection, and digital agriculture solutions to farmers. In Mexico, the company offers a broad portfolio of commercial and hybrid seeds for major crops, supported by local agronomic expertise. Its seed business focuses on improving crop productivity, quality, and resilience under diverse Mexican growing conditions. Corteva also works with farmers and agricultural partners to promote modern seed technologies and sustainable farming practices.
- Key Products: Pioneer seeds, Brevant seeds.
- Strategic Focus: Focuses on strengthening its seed portfolio in Mexico through advanced breeding, hybrid seed development, and locally adapted varieties. Its strategy emphasizes improving crop productivity, resilience to environmental stresses, and farmer access to innovative seed technologies.
Market Concentration Analysis
The Mexico seeds market is moderately consolidated, with the top five companies, Bayer AG, Corteva, BASF, Sakata Seed Corporation, and Rijk Zwaan Zaadteelt en Zaadhandel B.V., together accounting for approximately 55.59% of total market share. This concentration level reflects the capital-intensive nature of commercial seed R&D, the intellectual property protection on proprietary hybrid varieties, and the agronomic service capabilities that multinational companies bring to farmer relationships that smaller domestic competitors cannot easily replicate.
The vegetable seed sub-segment is somewhat more fragmented than the field crop seed segment, with a larger number of specialist vegetable seed companies competing alongside the multinational seed conglomerates for share in Mexico premium export vegetable market. Competition in this segment is driven by variety performance, disease resistance package, and technical agronomy support rather than price alone.
Investment & Growth Opportunities
Highest Growth Segments
Vegetable seed for export horticulture represents the highest-value growth opportunity, commanding premium per-kilogram prices with growth driven by Mexico expanding its fresh produce export sector. Non-GMO high-yielding conventional hybrid corn represents the largest volume growth opportunity. Seed treatment technology represents a growing value-added opportunity to increase revenue per seed unit sold across all crop categories without regulatory constraint on treatment chemistry.
Investment Themes
- Non-GMO Conventional Hybrid Corn R&D: Investment in accelerated conventional breeding programs using genomic selection and marker-assisted selection to develop corn hybrids with stress tolerance, disease resistance, and yield performance competitive with previously available transgenic varieties. This represents the single most important strategic investment for field crop seed companies seeking to maintain commercial corn seed market share in the post-ban environment.
- Vegetable Seed Innovation for Protected Cultivation: Investment in specialty vegetable seed varieties designed for Mexico greenhouse and protected cultivation export production systems, where variety performance for export market specifications commands premium pricing and creates durable customer relationships with large commercial growers.
Future Market Outlook (2026-2034)
The Mexico seeds market stood at USD 557.9 Million in 2025 and is projected to grow from USD 566.6 Million in 2026 to USD 645.8 Million by 2034, exhibiting a CAGR of 1.56% during the forecast period. The market is expected to reach an intermediate milestone of approximately USD 602.7 Million by 2030, as non-GMO conventional hybrid corn adoption expands among commercial farmers, and the export vegetable seed sector continues its above-market growth trajectory supported by Mexico growing fresh produce export capacity.
Three structural forces will define the Mexico seeds market through 2034. First, the constitutional enshrinement of the GMO corn ban in March 2025 creates a permanent structural constraint on the biotechnology-dependent growth pathway that characterized the Mexico commercial seed market in preceding decades, necessitating a sector-wide R&D reorientation toward high-performance conventional hybrid breeding. Second, Mexico expanding role as a global fresh produce exporter will sustain above-market growth in premium vegetable seed demand through 2034, particularly in the protected cultivation segment where variety innovation drives disproportionate value creation. Third, the progressive adoption of precision agriculture, digital agronomy platforms, and seed treatment technologies across Mexico commercial farming sector.
Research Methodology
Primary Research
Primary research comprised structured consultations with seed company agronomists and commercial directors, farming cooperative representatives, researchers, agrodealer and distributor network managers, commercial corn and vegetable farmers in Central and Northern Mexico, and seed certification officials. These discussions validated market sizing, assessed the commercial impact of the GM corn ban decree, identified hybrid adoption trends, and provided competitive intelligence on market share dynamics and product strategy across major seed categories.
Secondary Research
Secondary research drew on IMARC Group market data, agricultural census and production statistics, seed certification records, company annual reports and research publications, Mexico seed market analysis, agricultural trade dispute documentation, and company investor relations materials. Historical market data spanning 2020 through 2025 was cross-validated across multiple sources.
Forecasting Models
Market forecasts incorporated historical revenue growth trend analysis, crop area and seed penetration rate modeling for corn, vegetable, and field crops, regulatory impact assessment for the GM corn ban on commercial seed demand, non-GMO hybrid adoption rate projections, vegetable seed demand modeling based on Mexico export horticulture growth scenarios, government agricultural program investment projections, and macroeconomic indicators including Mexico agricultural GDP growth and rural income trends through 2034.
Mexico Seeds Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Genetically Modified Seeds, Conventional Seeds |
| Seed Types Covered |
|
| Traits Covered | Herbicide-Tolerant (HT), Insecticide-Resistant (IR), Others |
| Availabilities Covered | Commercial Seeds, Saved Seeds |
| Seed Treatments Covered | Treated, Untreated |
| Regions Covered | Northern Mexico, Central Mexico, Southern Mexico, Others |
| Companies Covered | Bayer AG, Corteva, BASF, Sakata Seed Corporation, Rijk Zwaan Zaadteelt en Zaadhandel B.V., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Mexico seeds market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Mexico seeds market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Mexico seeds industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Mexico Seeds Market Report
The Mexico seeds market reached USD 566.6 Million in 2026, driven by hybrid seed adoption in commercial farming, vegetable seed demand from the export horticulture sector, and government agricultural support programs.
The market is projected to grow at a CAGR of 1.56% during 2026-2034, reflecting moderate growth constrained and balanced by growing vegetable seed demand, non-GMO hybrid adoption, and commercial farming sector expansion in Central and Northern Mexico.
The market is projected to reach approximately USD 602.7 Million by 2030, driven by progressive non-GMO hybrid corn adoption, continued export vegetable seed market growth, cotton area expansion to reduce import dependence, and seed treatment technology adoption improving commercial seed investment returns.
Conventional seeds lead with a 72.8% share in 2025, reflecting the cultural and policy commitment to native corn diversity protection and the large smallholder farming base using open-pollinated and conventional varieties.
Herbicide-tolerant traits lead with a 51.6% share in 2025, reflecting the primary importance of weed management as an agronomic challenge for Mexican commercial farmers, with HT varieties enabling cost-effective broadleaf and grass weed control across corn, cotton, and soybean cultivation systems.
Central Mexico leads with a 42.8% share in 2025, reflecting the Bajio region's position as Mexico most commercially sophisticated agricultural zone, with high hybrid seed adoption, strong distribution infrastructure, and diverse commercial crop production including corn, sorghum, wheat, and export vegetables.
Key players include Bayer AG, Corteva, BASF, Sakata Seed Corporation, and Rijk Zwaan Zaadteelt en Zaadhandel B.V., among others.
The market is projected to reach USD 645.8 Million by 2034, driven by non-GMO conventional hybrid corn growth following the GM ban, premium vegetable seed expansion, seed treatment technology adoption, and progressive commercial farming sector growth in the Bajio and Northern Mexico agricultural zones.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade