
Mexico Weight Management Market Size, Share, Trends and Forecast by Diet, Service, Equipment, and Region, 2026-2034
Mexico Weight Management Market Size, Share, Trends & Forecast (2026-2034)
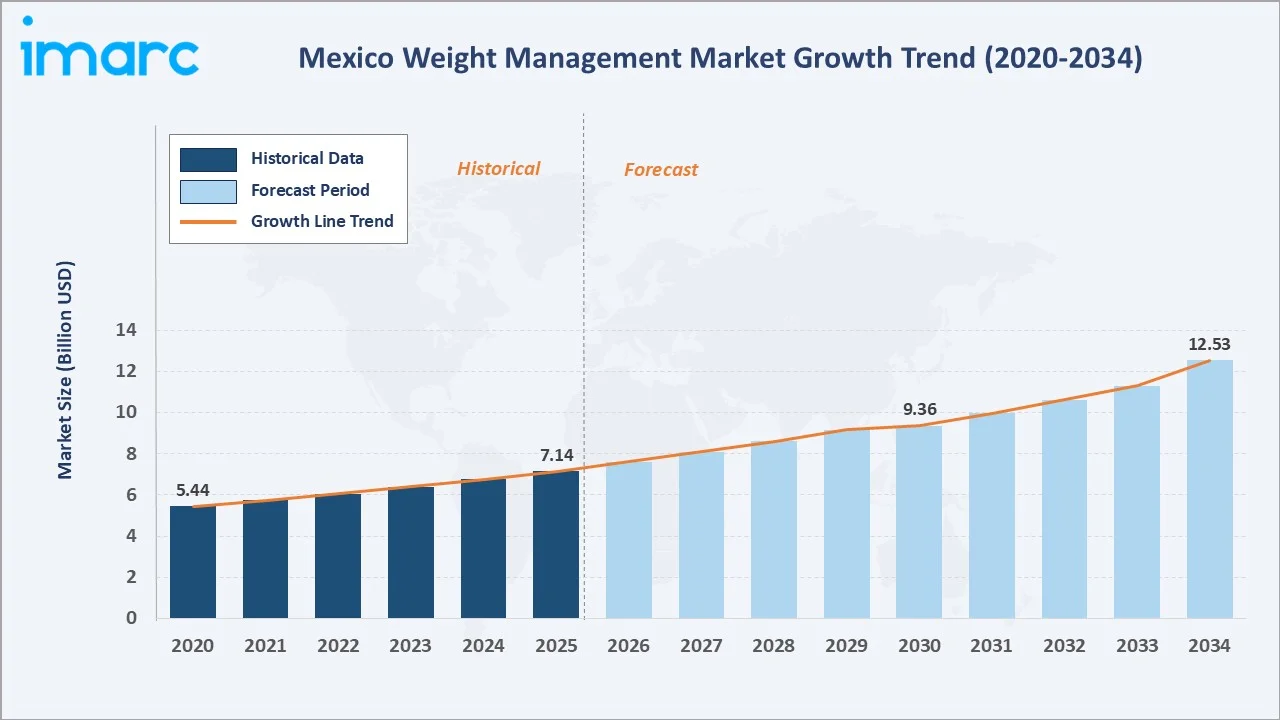
The Mexico weight management market grew from USD 7.14 Billion in 2025 to USD 7.54 Billion in 2026 and is projected to reach USD 12.53 Billion by 2034, growing at a CAGR of 5.57% during 2026-2034. Mexico’s high burden of obesity and diabetes is driving demand for weight management solutions. With obesity affecting 35.7% of adult women and 27.0% of adult men, alongside diabetes prevalence exceeding 11% among adults, growing health concerns are encouraging greater adoption of weight-loss programs, dietary products, fitness services, and other weight management solutions. Functional food leads diet category share at 35.2%, health clubs dominate service share at 40.8%, and Central Mexico commands 45.1% regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 7.14 Billion |
|
Market Size (2026) |
USD 7.54 Billion |
|
Forecast Market Size (2034) |
USD 12.53 Billion |
|
CAGR (2026-2034) |
5.57% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Diet |
Functional Food (35.2%, 2025) |
|
Dominant Service |
Health Clubs (40.8%, 2025) |
|
Leading Region |
Central Mexico (45.1%, 2025) |
The Mexico weight management market grew from USD 5.44 Billion in 2020 to USD 7.14 Billion by 2025 and is estimated to reach USD 7.54 Billion in 2026. The market is projected to reach USD 9.36 Billion by 2030 and USD 12.53 Billion by 2034.
To get more information on this market, Request Sample
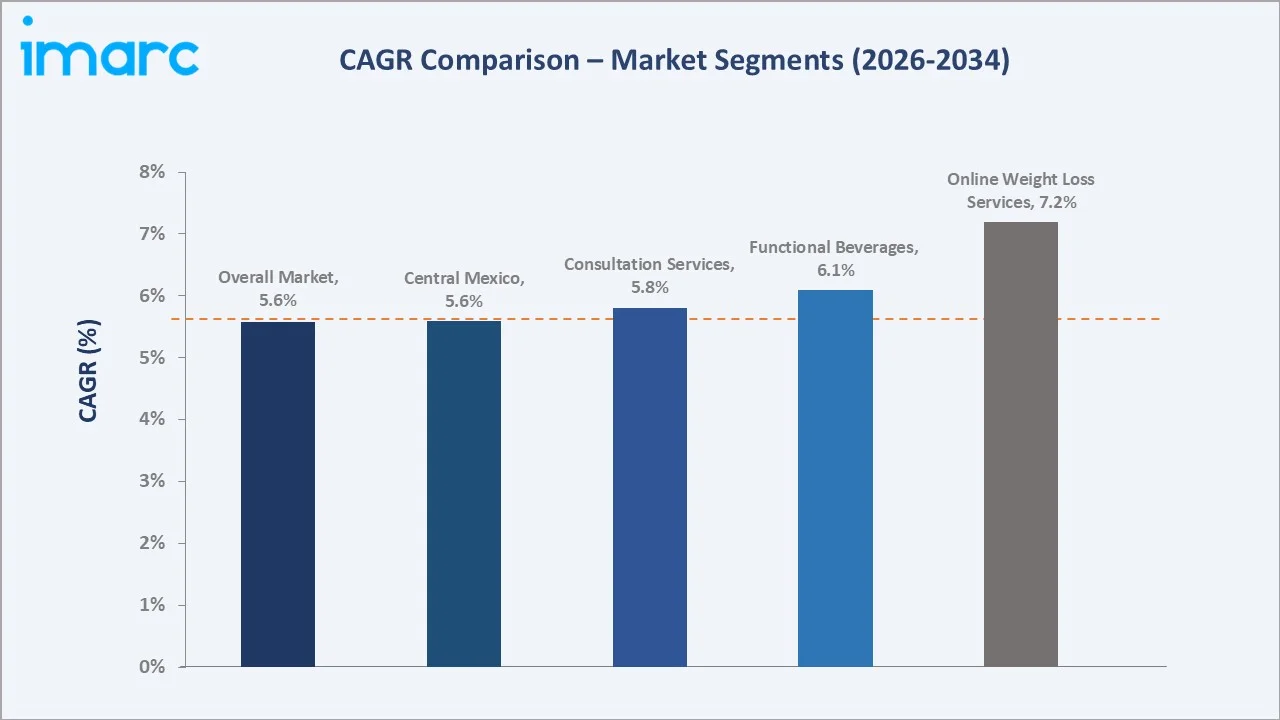
Online weight loss services are the fastest-growing segment at ~7.2% CAGR through AI-personalized nutrition platforms, telehealth dietitian consultations, and subscription digital fitness programs. Functional beverages grow at ~6.1% CAGR through protein-enriched water and functional RTD beverage adoption. Consultation services expand at ~5.8% CAGR through GLP-1 prescription growth and telehealth nutrition counseling scaling.
Executive Summary
The Mexico weight management market is a large and structurally growing consumer health industry, driven by the convergence of Mexico's severe and worsening obesity epidemic, rising middle-class health consciousness generating premium wellness spending, and transformative product and technology innovations including GLP-1 medications, AI-powered nutrition apps, and clean-label functional foods. Functional food commands a 35.2% diet share through fortified food, meal replacement, and high-protein product ranges. Health clubs lead service at 40.8% through Smart Fit's mass-market gym membership expansion. Central Mexico dominates at 45.1% through Mexico City's urban consumer concentration.
Key Market Insights
|
Insight |
Data |
|
Dominant Diet |
Functional Food - 35.2% share (2025) |
|
Dominant Service |
Health Clubs - 40.8% share (2025) |
|
Leading Region |
Central Mexico - 45.1% (2025) |
|
Key Market Opportunity |
Rising demand for personalized nutrition, digital weight-loss programs, GLP-1-based obesity treatments, functional and low-calorie foods, fitness services, and preventive healthcare solutions. |
Key Analytical Observations Supporting the Above Data:
- Functional Food at 35.2%: Functional foods, encompassing high-protein fortified foods, meal replacements, fiber-enriched products, and foods marketed with specific weight management health claims, lead Mexico's diet segment through their integration into everyday shopping occasions at supermarkets and pharmacy chains, product positioning that avoids the regulatory burden of dietary supplement claims, and strong consumer familiarity with fortified food products through decades of branded product marketing.
- Health Clubs at 40.8%: Health clubs dominate Mexico's weight management service segment through their dual role as fitness facilities and weight management behavior change environments, providing structured exercise programming, certified personal trainers with nutrition counseling capabilities, group fitness classes with proven weight management efficacy, and social community accountability that drives long-term member retention.
- Central Mexico at 45.1%: Central Mexico's commanding market share reflects the region's structural advantages as Mexico's most urbanized, highest-income, and most health-conscious consumer market. Mexico City's metropolitan population hosts Mexico's largest concentration of health club locations, specialty nutrition retailers, private nutritionist and bariatric physician practices, premium functional food retail space, and digital health app adopters.
Mexico Weight Management Market Overview
The Mexico weight management market encompasses the full ecosystem of products and services supporting weight reduction, weight maintenance, and metabolic health management for Mexico's consumer population. The diet segment covers functional foods (meal replacements, protein bars, high-fiber cereals, fortified products), dietary supplements (weight loss supplements, protein powders, fat burners, fiber supplements), and functional beverages (protein shakes, meal replacement drinks, slimming teas, functional waters). The service segment covers health clubs and gyms, professional consultation services (nutritionists, dietitians, bariatric physicians, endocrinologists), and online weight loss platforms (app-based tracking, telehealth nutrition, subscription digital coaching programs).
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
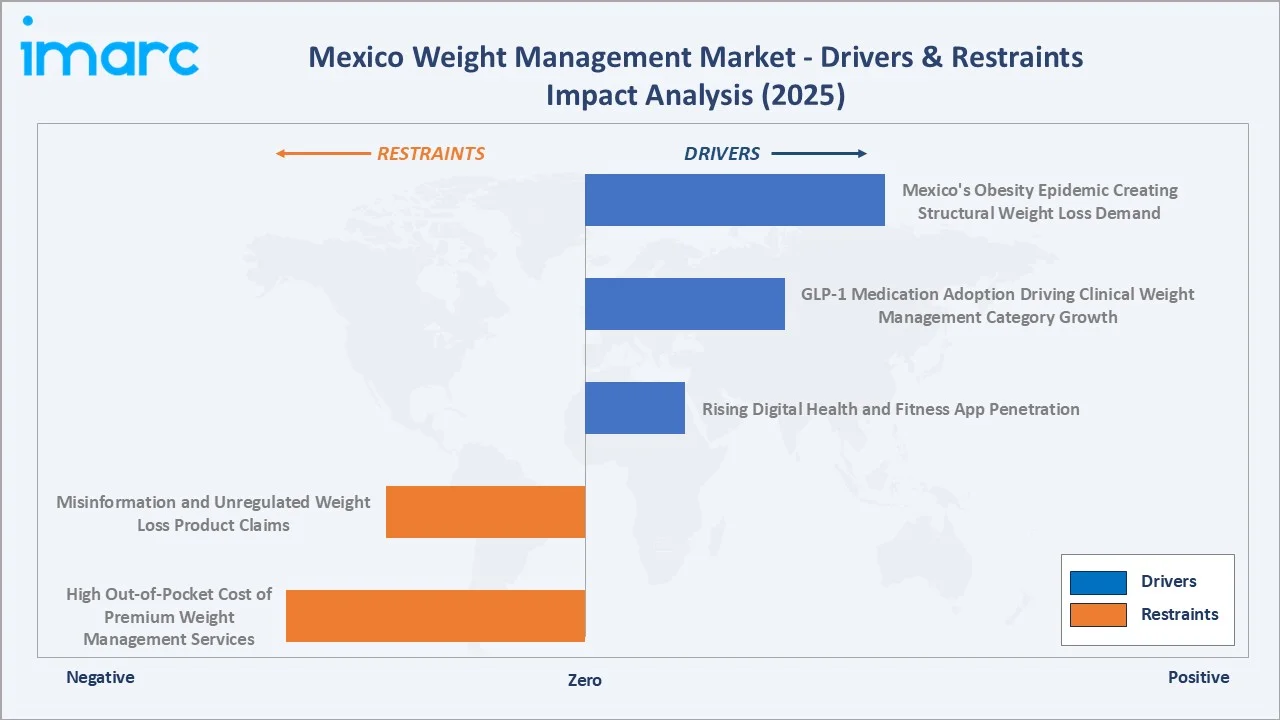
- Mexico's Obesity Epidemic Creating Structural Weight Loss Demand: Mexico faces a high burden of diet-related NCDs, with obesity affecting 35.7% of adult women and 27.0% of men, creating one of the most structurally compelled weight management product and service demand environments. Mexico's federal public health campaigns, weight control clinic programs, and nutritional education initiatives are generating sustained consumer awareness of overweight health risks that translates into commercial weight management product trial and purchase behavior.
- GLP-1 Medication Adoption Driving Clinical Weight Management Category Growth: In January 2026, Hanmi Pharmaceutical signed an exclusive distribution agreement with Mexico-based Laboratorios Sanfer for its GLP-1 obesity therapy, efpeglenatide, and its Dapalon portfolio of diabetes treatments. These medications are generating a fundamental shift in Mexico's clinical weight management market by creating the first pharmaceutical category with compelling clinical evidence of body weight reduction outcomes.
- Rising Digital Health and Fitness App Penetration: By late 2025, Mexico had approximately 110 million internet users, accounting for 83.5% of the country’s total population, driving rapid growth in app-based weight management platforms. Mexico-developed apps are capturing growing monthly active user bases for calorie tracking, macro monitoring, AI meal planning, and telehealth nutritionist consultation.
Market Restraints
- High Out-of-Pocket Cost of Premium Weight Management Services: High out-of-pocket costs for premium weight management services are limiting market accessibility, particularly among low- and middle-income consumers in Mexico. Personalized nutrition programs, specialized fitness services, and advanced obesity treatments can involve substantial recurring expenses. Limited affordability discourages long-term participation and reduces adoption beyond higher-income population groups, thereby restraining overall market growth.
- Misinformation and Unregulated Weight Loss Product Claims: Misinformation and unregulated weight-loss product claims create confusion regarding product safety and effectiveness. Misleading advertising and exaggerated results can reduce consumer trust and expose individuals to ineffective or potentially unsafe products. This uncertainty can discourage adoption of legitimate, clinically supported weight management solutions, thereby constraining market growth.
Market Opportunities
- Telehealth Nutrition and GLP-1 Management Platforms: The convergence of GLP-1 medication adoption and telehealth digital health platform growth is creating a high-value hybrid service category: telehealth-based obesity management clinics providing GLP-1 prescriptions, nutrition counseling, progress monitoring, and lifestyle coaching through digital platforms accessible from patients' smartphones. Mexico-based health startups are pioneering this model, while international telehealth providers are entering the Mexican market targeting GLP-1 management as a subscription service opportunity.
- Workplace Wellness and Corporate Weight Management Programs: Mexico's large formal sector employment base represents a major untapped corporate wellness market for employer-sponsored weight management programs. Progressive Mexican and multinational employers are implementing corporate wellness programs that include nutrition counseling, gym membership subsidies, and healthy food provision in workplace cafeterias.
Market Challenges
- Socioeconomic Inequality Limiting Premium Weight Management Program Access: Mexico's highly unequal income distribution means the highest-obesity-prevalence consumer segments (lower-income, less educated, rural populations) are precisely those with the least financial access to effective commercial weight management interventions. This creates a structural mismatch between where Mexico's obesity problem is most acute and where commercial weight management market revenues can be generated, limiting total addressable market expansion and requiring government program subsidy or very low-cost product innovation to serve the most vulnerable obese population segments commercially.
- Supply Chain and Regulatory Complexity for International Weight Management Product Entry: International weight management brands entering Mexico face a complex regulatory process, including dietary supplement notification (requiring detailed formulation disclosure and safety substantiation), functional food health claim authorization (requiring clinical evidence submission), and pharmaceutical registration for weight loss medications, which creates market entry timelines and significant regulatory compliance costs.
Emerging Market Trends
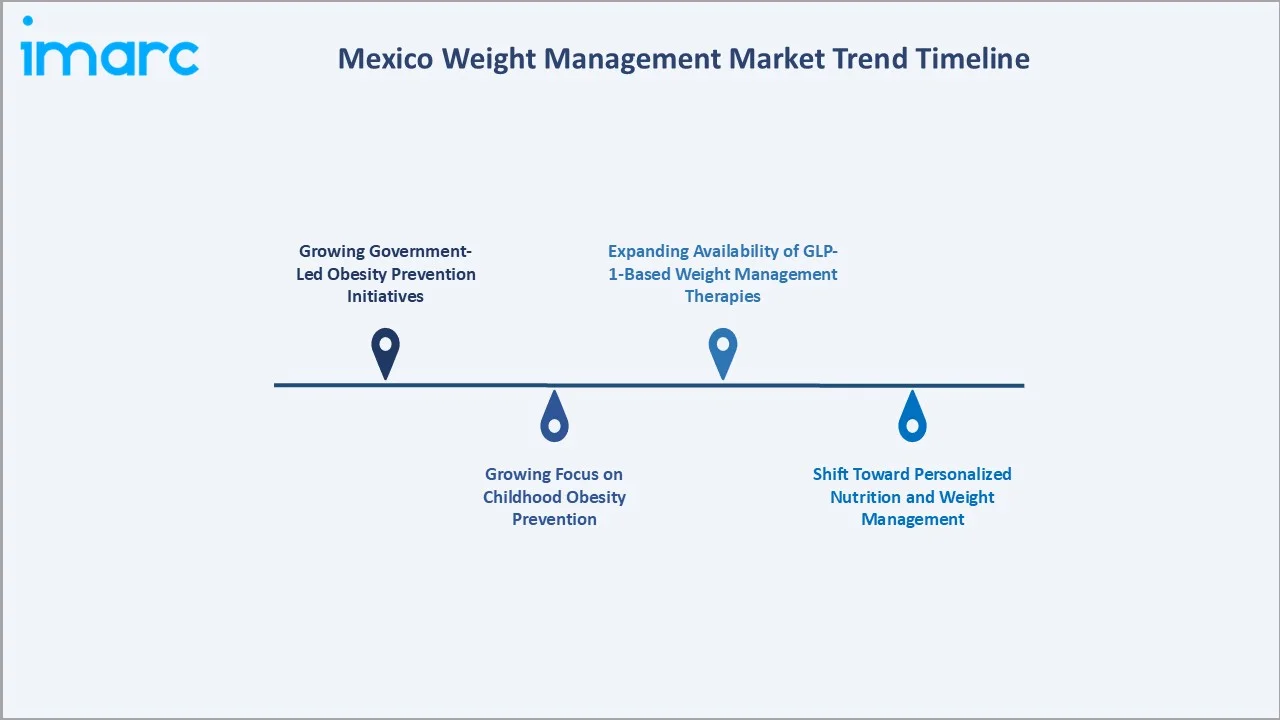
1. Growing Government-Led Obesity Prevention Initiatives
Mexico is increasingly adopting coordinated public health strategies that combine nutrition education, food regulation, fiscal measures, and scientific research to address obesity. In March 2026, Mexico’s Ministry of Health introduced the Overweight and Obesity Deceleration Strategy to curb rising obesity through prevention, regulation, research, and coordinated action. The strategy combines nutrition education, healthier food environments, fiscal policies, scientific research, and multisector collaboration through 2030 to improve public health and reduce obesity-related health risks. This trend is supporting greater awareness and preventive weight management, creating opportunities for evidence-based nutrition, wellness, and weight management solutions.
2. Growing Focus on Childhood Obesity Prevention
Rising childhood obesity in Mexico is encouraging the adoption of innovative nutrition education and awareness initiatives targeting healthier eating habits from an early age. In June 2025, Save the Children Mexico launched a health bracelet featuring beads representing different food groups to encourage healthier eating habits among children, amid concerns that nearly one in five Mexican children aged 5–11 is affected by obesity. Programs such as food-group-based educational tools are strengthening preventive weight management efforts and supporting demand for child-focused nutrition and wellness solutions.
3. Expanding Availability of GLP-1-Based Weight Management Therapies
Pharmaceutical partnerships are increasing the commercialization and accessibility of GLP-1-based obesity treatments in Mexico. In May 2024, Biocon Limited signed a semi-exclusive distribution and supply agreement with Mexico-based Medix to commercialize its vertically integrated Liraglutide (gSaxenda), a therapy used for chronic weight management. Agreements such as Biocon–Medix highlight growing industry focus on pharmacological weight management, expanding treatment options and supporting the development of Mexico’s obesity care market.
4. Shift Toward Personalized Nutrition and Weight Management
Consumers are increasingly seeking weight management programs tailored to their dietary habits, health profiles, lifestyles, and individual goals. Personalized meal plans, nutrition counseling, fitness programs, and technology-enabled monitoring are gaining relevance. This shift is encouraging providers to move beyond standardized weight-loss programs toward individualized solutions.
Industry Value Chain Analysis
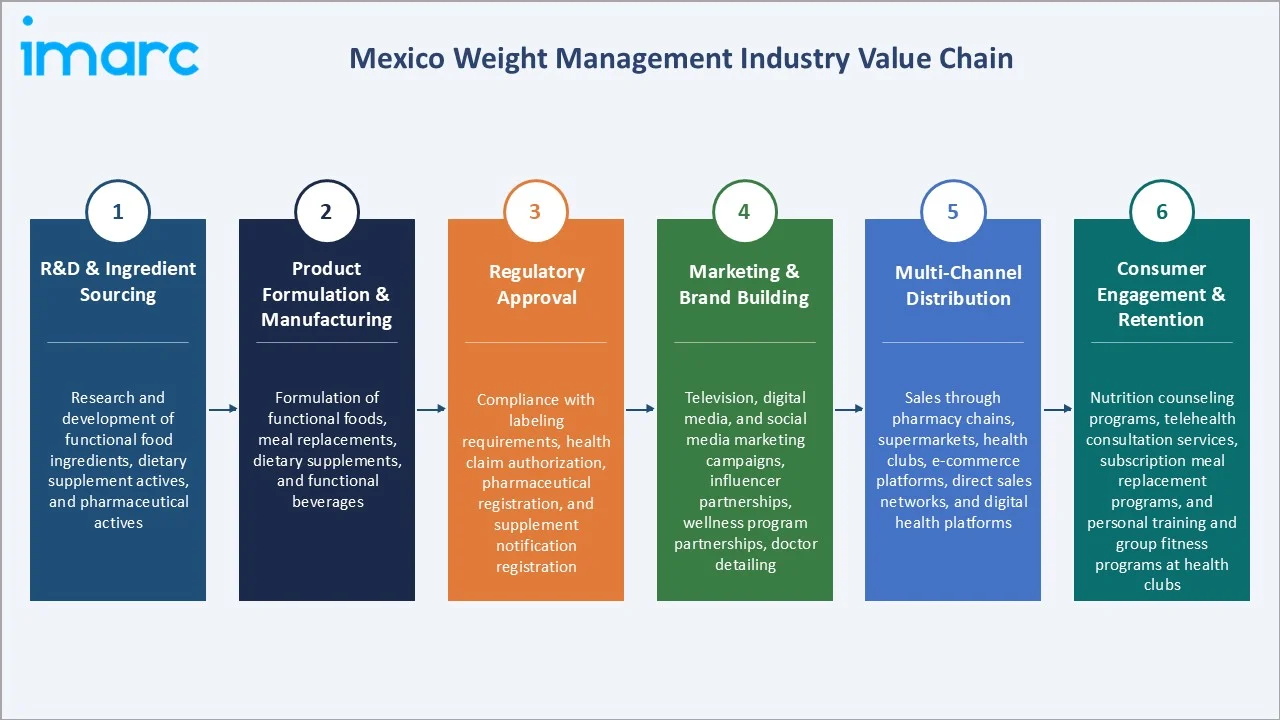
The Mexico weight management market value chain encompasses six stages from research and ingredient sourcing through consumer engagement and retention, with each stage representing distinct competitive advantages in this highly fragmented consumer health market.
|
Stage |
Description |
|
R&D & Ingredient Sourcing |
Research and development of functional food ingredients, dietary supplement actives, and pharmaceutical actives. |
|
Product Formulation & Manufacturing |
Formulation of functional foods, meal replacements, dietary supplements, and functional beverages. |
|
Regulatory Approval |
Compliance with labeling requirements, health claim authorization, pharmaceutical registration, and supplement notification registration. |
|
Marketing & Brand Building |
Television, digital media, and social media marketing campaigns, influencer partnerships, wellness program partnerships, doctor detailing. |
|
Multi-Channel Distribution |
Sales through pharmacy chains, supermarkets, health clubs, e-commerce platforms, direct sales networks, and digital health platforms. |
|
Consumer Engagement & Retention |
Nutrition counseling programs, telehealth consultation services, subscription meal replacement programs, and personal training and group fitness programs at health clubs. |
Consumer engagement and retention represent the highest value-creation stage in Mexico's weight management market, where program adherence rates directly determine health outcome delivery and commercial lifetime value. Mexico's weight management companies generating the highest per-customer revenue and lowest churn rates demonstrate that behavioral engagement and social community models outperform purely product-centric approaches in sustaining weight management consumer relationships.
Technology Landscape in the Mexico Weight Management Industry
Digital Health and AI-Powered Weight Management Platforms
Mexico's digital weight management technology ecosystem is developing rapidly, driven by the country's internet users, growing 4G/5G mobile connectivity, and increasing consumer comfort with digital health service consumption. AI-powered nutrition platforms, integrating large food composition databases localized to Mexican traditional foods (tortillas, beans, chiles, tamales, pozole), camera-based food recognition for meal logging, and machine learning algorithms for personalized calorie and macro recommendations, are improving the accuracy and consumer ease of calorie tracking for Mexican users.
GLP-1 and Pharmaceutical Weight Management Technology
GLP-1 and pharmaceutical weight management are transformative technology breakthroughs in weight management, delivering body weight reduction in clinical trials versus traditional diet and exercise programs. Mexico's GLP-1 market is growing through endocrinologist and cardiologist prescription networks, expanding toward general practitioner prescriptions as clinical guidelines evolve, and reaching direct-to-consumer through telehealth platforms providing online GLP-1 prescriptions. Pipeline GLP-1 and dual agonist medications represent the next technology wave that will further accelerate Mexico's pharmaceutical weight management market growth and create associated dietary supplement and functional food demand for GLP-1-complementary nutrition protocols.
Wearable Technology and Metabolic Health Monitoring
Fitness wearables are generating real-time physical activity tracking, heart rate monitoring, and sleep quality data that is increasingly integrated with weight management app platforms to provide comprehensive lifestyle behavioral insights for Mexican consumers managing weight. Continuous glucose monitor (CGM) technology is expanding beyond diabetic monitoring toward metabolic health optimization for non-diabetic overweight consumers seeking personalized glycemic response insights to guide dietary decision-making. Mexico's growing middle-class investment in health-tracking wearables is creating a data-rich consumer base for AI-powered weight management platforms that can personalize recommendations based on objective biometric data rather than self-reported dietary recall, improving program efficacy and consumer engagement.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Diet |
Functional Food |
35.2% |
2025 |
|
Service |
Health Clubs |
40.8% |
2025 |
|
Equipment |
Fitness Equipment |
37.4% |
2025 |
|
Region |
Central Mexico |
45.1% |
2025 |

By Diet
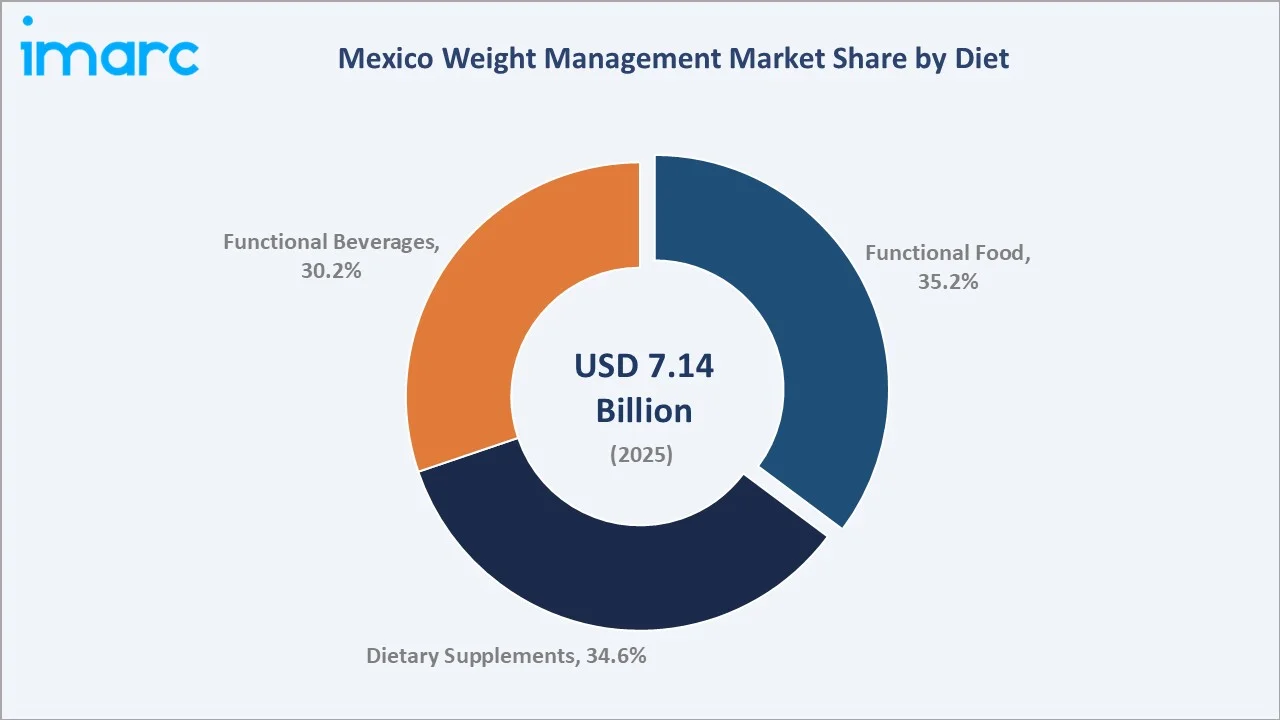
Functional food commands 35.2% in 2025, driven by its seamless integration into everyday shopping and consumption occasions, regulatory compliance advantages of clean-label formulations, and strong Mexican consumer familiarity with fortified product formats through brand heritage.
To access detailed market analysis, Request Sample
Dietary supplements at 34.6% represent a near-equal share through protein powders, weight loss supplements, fat burners, fiber supplements, and herbal weight management products distributed through pharmacies, gyms, specialty nutrition retailers, and direct sales networks. Functional beverages at 30.2% are the fastest-growing diet sub-segment through protein-enhanced water, functional RTD beverages, and slimming teas growing through convenience store channel distribution.
By Service
Health clubs lead at 40.8% in 2025, anchored by mass-market gym networks and premium operators, targeting upper-income segments. Mexico's health club industry underwent a structural transformation through a low-cost model that democratized gym membership and significantly expanded the total addressable service market for fitness-based weight management.
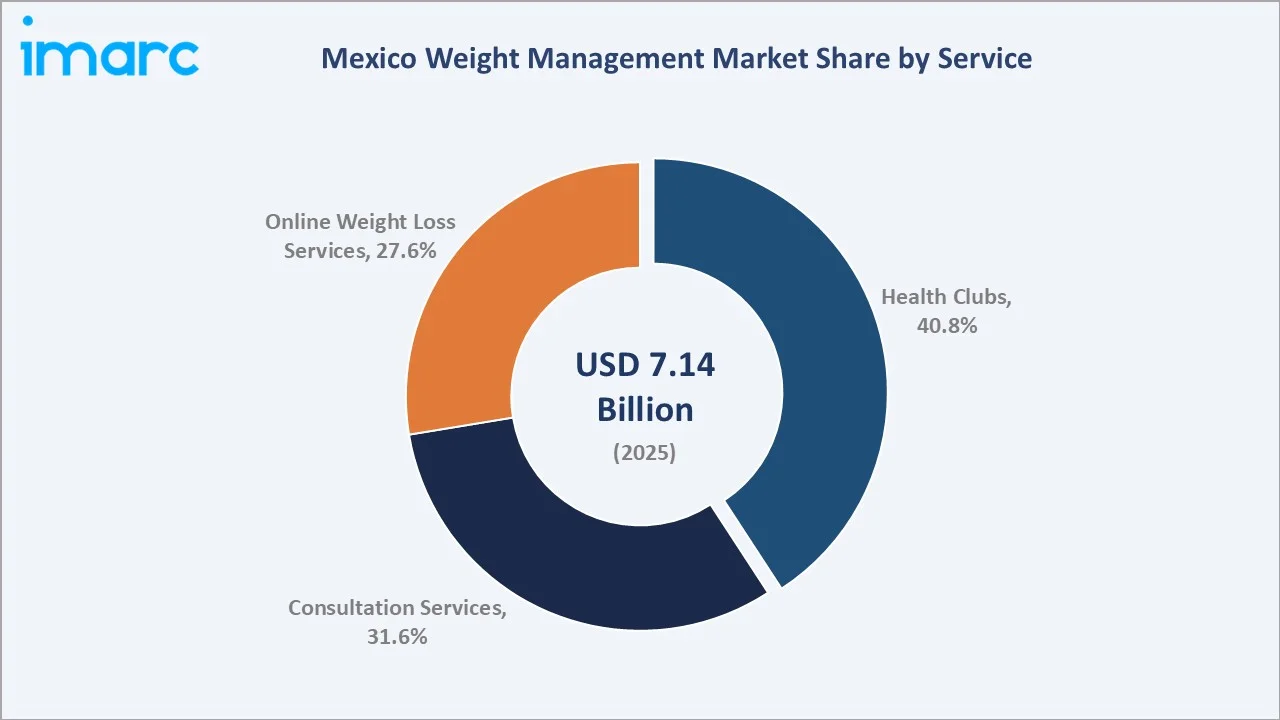
Consultation services at 31.6% encompass nutritionist and dietitian consultations, bariatric physician programs, endocrinologist GLP-1 prescription management, and nutrition counseling clinics, growing through GLP-1 medication adoption driving specialist physician consultation demand and expanding telehealth platform access to nutrition counseling. Online weight loss services at 27.6% are the fastest-growing service category at ~7.2% CAGR through digital app subscriptions, AI nutrition coaching, and telehealth weight management platform adoption.
Regional Market Insights
|
Region |
Share (2025) |
Key Mexico Weight Management Market Drivers & Characteristics |
|
Central Mexico |
45.1% |
Central Mexico commands Mexico's weight management market through its concentration of consumers in the highest-income and most health-conscious demographic segments. Mexico City's metropolitan population hosts Mexico's largest concentration of health clubs, specialty nutrition retailers, premium functional food retailers, and private bariatric and nutritionist consultation centers. |
|
Northern Mexico |
28.4% |
Northern Mexico reflects the region's higher household incomes from manufacturing sector employment, significant cross-border US cultural influence on health and fitness consumption patterns, and the largest per-capita health club membership rates in Mexico. |
|
Southern Mexico |
16.7% |
Southern Mexico represents Mexico's most under-penetrated weight management market, reflecting lower average household incomes, more limited health club infrastructure, lower digital health platform adoption, and greater reliance on traditional herbal remedies and popular pharmacy-purchased dietary supplements over premium branded weight management programs. |
|
Others |
9.8% |
The others region reflects emerging but nascent weight management market development. Growing e-commerce penetration is enabling consumers in smaller cities and semi-urban areas to access branded functional foods, dietary supplements, and online fitness programs. |
Central Mexico's 45.1% dominance reflects Mexico City's unique position as the country's economic, cultural, and health service infrastructure hub, concentrating Mexico's highest-income consumer segments, most developed specialty retail and health club footprint, greatest digital health adoption, and largest private healthcare provider network.
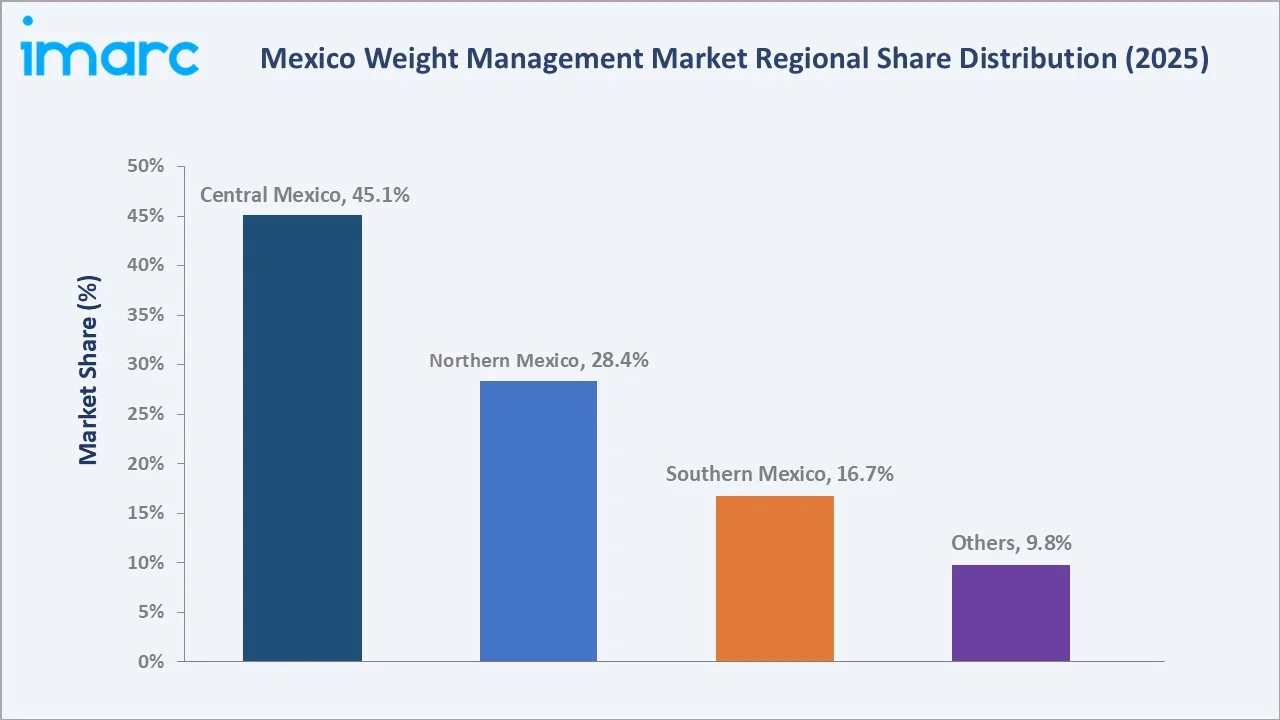
Northern Mexico's 28.4% share through Monterrey and border city affluent consumer clusters represents Mexico's second-most developed weight management market with above-average per-capita spending. Southern Mexico at 16.7% is growing through premium market development and e-commerce-enabled product access in historically underserved states. The Others segment at 9.8% represents emerging market development through digital platform reach into Tier-3 cities and semi-urban areas.
Competitive Landscape
The Mexico weight management market features a multi-tier competitive structure spanning global multinationals, US-heritage weight loss program brands, mass-market fitness infrastructure, premium specialty retailers, and digital challenger platforms, creating a highly diverse competitive landscape from herbal supplement sachets to GLP-1 pharmaceutical programs.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
Nestlé |
Optifast |
Market Leader |
Nestlé plays a major role in Mexico’s health and nutrition landscape by shifting its portfolio toward localized weight management, functional foods, and science-backed nutritional support. |
|
Herbalife International, Inc. |
Herbalife |
Market Leader |
Herbalife International, Inc. plays a major role in Mexico's weight management and nutritional supplements sector through its direct-selling business model, meal-replacement products, and community-based distribution networks. |
|
Novo Nordisk A/S |
Ozempic (semaglutide), Wegovy (semaglutide) |
Market Leader |
Novo Nordisk A/S plays a leading role in Mexico's weight management landscape by introducing advanced GLP-1 receptor agonist therapies to combat the country's high prevalence of overweight and obesity. |
|
Eli Lilly and Company |
Zepbound |
Established Player |
Eli Lilly and Company is expanding access to modern GLP-1/GIP receptor agonist therapies in Mexico to address the obesity and overweight rate. |
|
Hanmi Pharm.Co.,Ltd. |
Efpeglenatide |
Challenger |
Hanmi Pharmaceutical supplies its domestically developed GLP-1 obesity treatment, efpeglenatide, and its diabetes portfolio to Mexico through an exclusive partnership with Laboratorios Sanfer. |
Competitive dynamics are being reshaped by three simultaneous forces: GLP-1 medications' clinical disruption of traditional diet program efficacy positioning, democratization of health club access generating structural shifts in service segment revenue distribution, and digital platform scaling enabling direct-to-consumer weight management program access that bypasses traditional retail and clinic distribution models.
Key Company Profiles
Nestlé
Nestlé is a global food and beverage company with a well-established presence in Mexico, offering a diversified portfolio across nutrition, health, and wellness categories. Within the Mexico weight management market, the company participates through products that support balanced nutrition, portion control, and healthier dietary choices. Its extensive distribution network, strong brand recognition, and continued focus on nutritional innovation strengthen its market presence. The company also emphasizes product reformulation and evolving consumer preferences for convenient, health-oriented food and beverage solutions.
- Key Brands: Optifast.
- Strategic Focus: Expanding health-oriented nutrition offerings, product reformulation, and convenient solutions that support balanced diets and weight management. The company also emphasizes nutritional innovation, consumer education, and broad distribution to address evolving health and wellness preferences.
Herbalife International, Inc.
Herbalife International, Inc. is a global nutrition and wellness company with an established presence in Mexico. In the Mexico weight management market, the company offers meal-replacement shakes, protein products, dietary supplements, and other nutrition solutions supporting weight-control goals. Its business model combines personalized distributor support with a broad portfolio of wellness products. Strong brand recognition and an extensive distribution network support its position in the country's weight management sector.
- Key Brands: Herbalife
- Strategic Focus: Strengthening its weight management and nutrition portfolio in Mexico through personalized nutrition solutions, meal-replacement products, and wellness offerings. The company emphasizes product innovation, distributor-led consumer engagement, and broader accessibility to address growing demand for convenient weight management solutions.
Market Concentration Analysis
The Mexico weight management market exhibits moderate fragmentation across its two primary segments. In the diet segment, multinational consumer goods companies and direct sales specialists collectively hold an estimated 40-50% of organized diet segment revenues, with the remainder distributed across dozens of domestic and international supplement brands, functional food companies, and pharmacy private labels. In the service segment, membership volume dominance creates a single-operator market share concentration, while the consultation and online services segments remain highly fragmented among thousands of independent nutritionists, small telehealth platforms, and international digital program operators.
GLP-1 pharmaceutical products are creating a rapid concentration of clinical weight management segment revenues, potentially reshaping competitive dynamics in adjacent diet and service segments as pharmaceutical-grade weight loss efficacy resets consumer expectations and competitive positioning requirements for commercial weight management programs.
Investment & Growth Opportunities
Highest Growth Segments
Online weight loss services (~7.2% CAGR), GLP-1 pharmaceutical weight management, functional beverages (~6.1% CAGR), Tier-2 and Tier-3 city health club expansion, telehealth nutrition platform development, corporate wellness program penetration, and regulatory-compliant clean-label functional food product innovation represent the highest-return investment opportunities in Mexico's weight management market through 2034.
Investment Themes
- Integrated GLP-1 + Nutrition + Digital Coaching Platform: The Mexican market lacks a fully integrated service platform combining GLP-1 prescription management, specialized nutrition protocols for GLP-1 patients (high-protein muscle preservation diets), behavioral coaching for habit formation during rapid weight loss, and digital progress monitoring. An integrated platform addressing all four GLP-1 patient journey dimensions would command premium subscription pricing while delivering superior patient adherence and weight maintenance outcomes versus medication-alone approaches.
- Low-Cost Functional Food for Mexico's Mass Market: Mexico's highest-obesity-prevalence consumer segments are simultaneously the lowest-income and most underserved by existing premium weight management products. Investment in high-protein functional food innovation at accessible price points, distributed, leveraging regulatory-compliant clean-label formulations, would address the structural gap between where Mexico's obesity problem is most acute and where effective weight management products are currently available and affordable.
Future Market Outlook (2026-2034)
The Mexico weight management market is projected to grow from USD 7.14 Billion in 2025 to USD 7.54 Billion in 2026, reaching USD 12.53 Billion by 2034, exhibiting a CAGR of 5.57% during 2026-2034. The market is projected to reach USD 9.36 Billion by 2030, the mid-period milestone when GLP-1 medications are expected to achieve mainstream prescription adoption beyond specialist physician networks, transforming Mexico's clinical weight management market from a niche private-pay specialist service into a mainstream chronic obesity treatment accessible to a broader income spectrum.
Three transformative forces will shape the Mexico weight management market through 2034. First, the pharmaceutical transformation of obesity treatment will structurally elevate Mexico's clinical weight management service market above its current scale while creating associated demand for nutrition counseling, protein supplementation, and behavioral support services that complement pharmacotherapy. Second, digital health convergence will drive the online weight loss services segment's above-market growth through 2034. Third, the Tier-2 and Tier-3 city market development will extend the Mexico weight management market's geographic revenue concentration beyond the current Central Mexico dominance toward a more balanced national market structure that captures the full scale of Mexico's structurally large obesity management opportunity.
Research Methodology
Primary Research
Primary research comprised structured interviews with Mexico weight management brand marketing managers, regulatory affairs specialists, nutrition program directors, private bariatric physicians and endocrinologists prescribing GLP-1 medications, health club operators, registered dietitians practicing, specialty nutrition retail managers, and digital health platform founders. Consumer demand pattern validation incorporated consumer surveys with weight management product and service users.
Secondary Research
Secondary research incorporated obesity prevalence data, product registry and compliance enforcement reports, food labeling behavior change studies, nutrition program statistics, company annual reports, Mexico retail sales scanner data for functional food and dietary supplement categories, and Mexico digital health app download and revenue tracking data.
Forecasting Models
Market forecasting incorporated Mexico adult population obesity prevalence trajectory projections, per-capita health and wellness spending growth correlations with GDP per capita and coefficient evolution, GLP-1 prescription growth trajectory modeling based on pharmaceutical registry and dispensing data, health club membership penetration rate projections, digital health platform user and revenue trajectory modeling, and competitive landscape pricing and market share dynamics analysis.
Mexico Weight Management Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Diets Covered | Functional Beverages, Functional Food, Dietary Supplements |
| Services Covered | Health Clubs, Consultation Services, Online Weight Loss Services |
| Equipments Covered |
|
| Regions Covered | Northern Mexico, Central Mexico, Southern Mexico, Others |
| Companies Covered | Nestlé, Herbalife International, Inc., Novo Nordisk A/S, Eli Lilly and Company, Hanmi Pharm.Co.,Ltd., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Mexico weight management market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Mexico weight management market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Mexico weight management industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Mexico Weight Management Market Report
The Mexico weight management market reached USD 7.54 Billion in 2026, driven by Mexico's obesity epidemic, accelerating GLP-1 medication adoption, Smart Fit health club democratization, functional food label compliance driving clean-label product demand, and digital health platform penetration among Mexico's internet users.
The market is projected to grow at a CAGR of 5.57% during 2026-2034, driven by GLP-1 pharmaceutical weight management market expansion, online weight loss services digital platform growth, functional beverage innovation, Tier-2 city health club expansion, and telehealth nutrition counseling scaling.
The market is projected to reach USD 9.36 Billion by 2030, coinciding with mainstream GLP-1 prescription adoption beyond specialist physicians, biosimilar semaglutide cost reduction improving access, integrated telehealth GLP-1 management platforms, and Tier-2 city weight management market development accelerating.
Functional food leads with a 35.2% share in 2025, driven by warning label compliance advantages of clean-label formulations, seamless integration into everyday shopping occasions, and strong consumer familiarity with fortified food brand heritage in Mexico.
Health clubs lead with a 40.8% share in 2025, anchored by a low-cost health club network, democratizing gym access for Mexico's middle-income consumer and significantly expanding the organized weight management service market.
Central Mexico leads with a 45.1% share in 2025, through Mexico City's metropolitan consumer concentration, highest-income and health-conscious demographics, most developed health club and specialty nutrition retail footprint, and greatest digital health platform adoption, generating the largest online weight management subscription volumes in Mexico.
Key players include Nestlé, Herbalife International, Inc., Novo Nordisk A/S, Eli Lilly and Company, and Hanmi Pharm.Co.,Ltd., among others.
The market is projected to reach USD 12.53 Billion by 2034, driven by GLP-1 medication mainstream adoption, potentially including formulary inclusion, digital health platform convergence creating integrated metabolic health ecosystems, Tier-2 and Tier-3 city market development, and next-generation dual and triple agonist medications delivering weight reduction outcomes.
Key investment opportunities include integrated GLP-1 + nutrition + digital coaching platforms targeting Mexico's rapidly growing semaglutide patient population, low-cost functional food innovation for Mexico's mass market at accessible price points, Tier-2 city health club and nutrition service expansion, and corporate wellness program penetration among Mexico's formal sector workers.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade