
PET Packaging Market Size, Share, Trends and Forecast by Packaging Type, Form, Pack Type, Filling Technology, End-User, and Region, 2026-2034
PET Packaging Market Size, Share, Trends & Forecast (2026-2034)
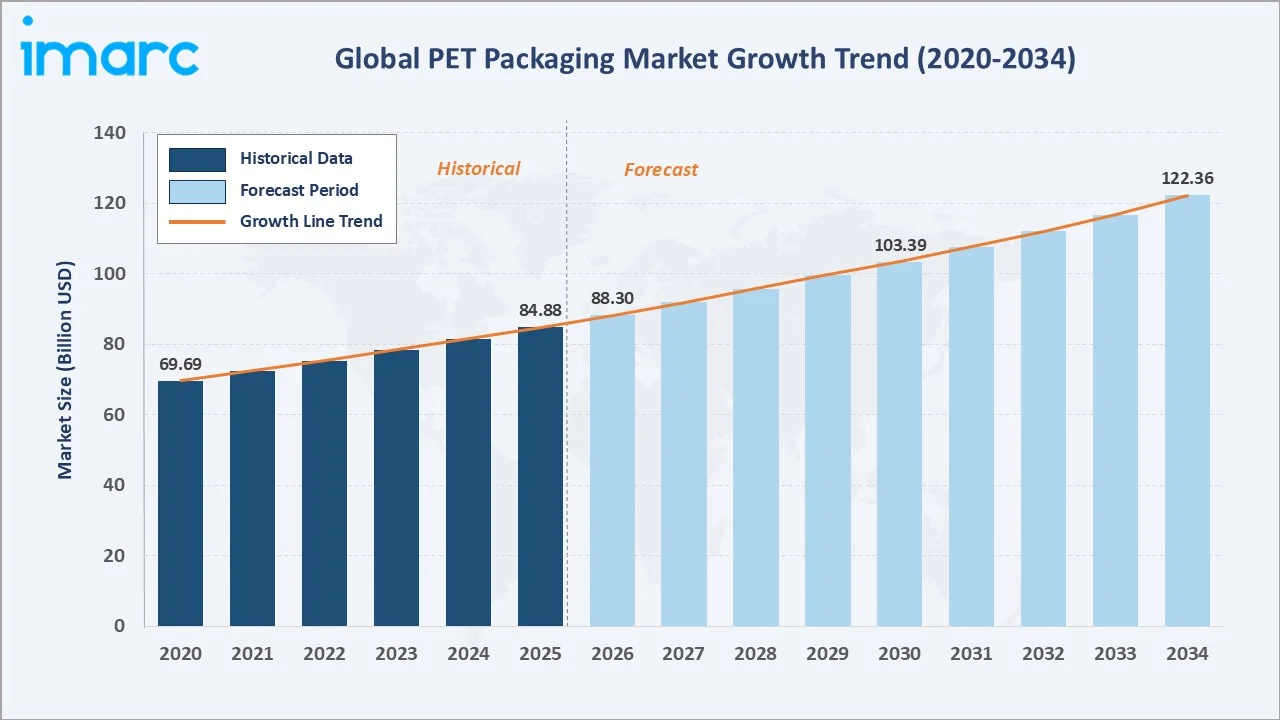
The global PET packaging market grew from USD 84.88 Billion in 2025 to USD 88.30 Billion in 2026 and is projected to reach USD 122.36 Billion by 2034, growing at a CAGR of 4.02% during 2026-2034. The market is driven by the growing global beverage industry, rising pharmaceutical packaging requirements, rapid urbanization, expanding consumer goods consumption, increasing rPET adoption, and continuous innovation in barrier coating. According to Euromonitor, nearly 7,000 new non-alcoholic beverages and 6,300 alcoholic beverage products were introduced globally in 2024. This expanding product portfolio is driving demand for PET packaging due to its lightweight, durable, cost-effective, and highly customizable properties. Bottles and jars lead at 23.3% by pack type, rigid packaging commands 76.5% by packaging type, and North America holds the largest regional share at 38.7%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 84.88 Billion |
|
Market Size (2026) |
USD 88.30 Billion |
|
Forecast Market Size (2034) |
USD 122.36 Billion |
|
CAGR (2026-2034) |
4.02% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Pack Type |
Bottles and Jars (23.3%, 2025) |
|
Dominant Packaging Type |
Rigid Packaging (76.5%, 2025) |
|
Leading Region |
North America (38.7%, 2025) |
The global PET packaging market size increased from USD 69.69 Billion in 2020 to USD 84.88 Billion in 2025 and is estimated to reach USD 88.30 Billion in 2026, representing consistent expansion across all major geographic regions and end-use sectors. The market is projected to reach USD 103.39 Billion by 2030 and USD 122.36 Billion by 2034.
To get more information on this market, Request Sample
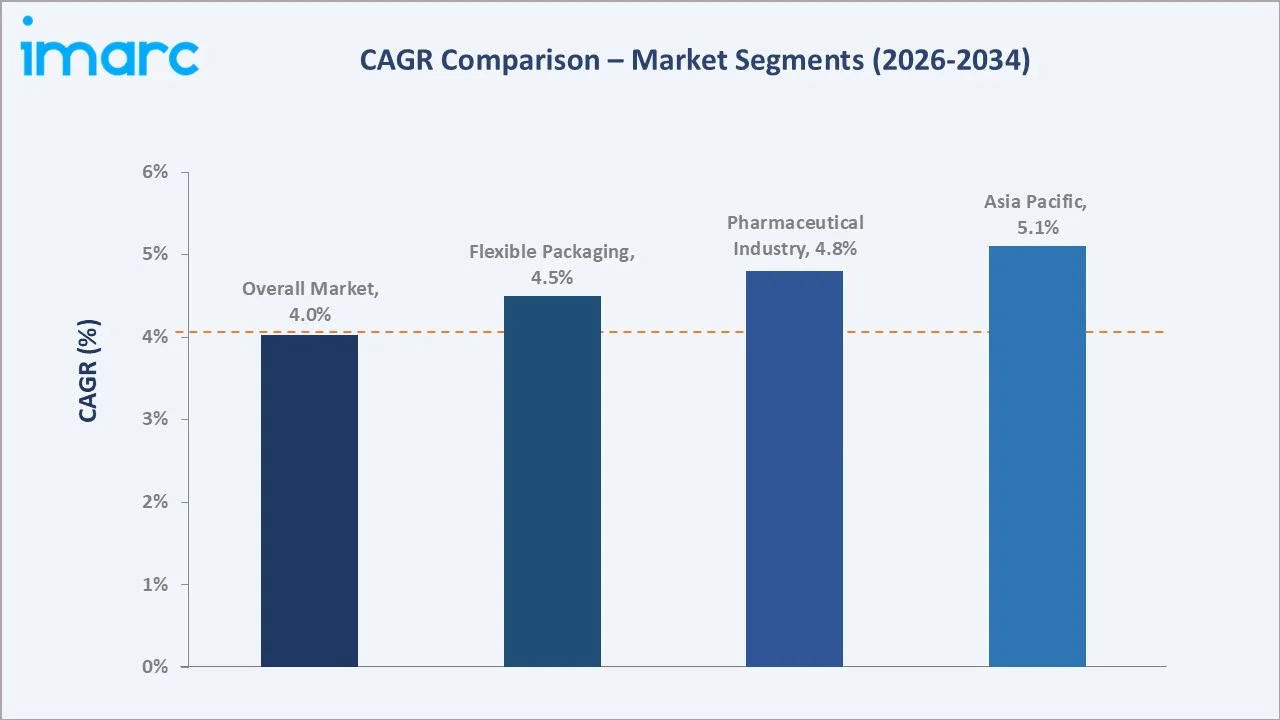
Asia Pacific grows at ~5.1% CAGR through urbanization and beverage market expansion. Pharmaceutical packaging grows at ~4.8% CAGR through global healthcare investment. Flexible PET packaging grows at ~4.5% CAGR through food and specialty applications.
Executive Summary
The global PET packaging market is one of the most structurally significant segments of the global packaging industry, serving as the foundation material for billions of consumer product units across various countries through its unique combination of clarity, safety, barrier performance, lightweighting capability, and recyclability. PET's dominance in the global beverage packaging market is structural and durable: the material's ability to contain carbonation at low wall thickness, its visual clarity enabling consumer product presentation, and its established global collection and mechanical recycling infrastructure make PET the material of choice for carbonated soft drinks, bottled water, juice, and growing categories including functional beverages and dairy products.
The PET packaging industry trends analysis confirms that sustainability transformation is the defining force reshaping product development, procurement decisions, and capital investment across all major PET packaging manufacturers. Bottles and jars lead at 23.3% by pack type through beverage and food application dominance. Rigid packaging leads at 76.5% by type through structural PET bottle and container primacy. North America leads regionally at 38.7%.
Key Market Insights
|
Insight |
Data |
|
Dominant Pack Type |
Bottles and Jars - 23.3% share (2025) |
|
Dominant Packaging Type |
Rigid Packaging - 76.5% share (2025) |
|
Leading Region |
North America - 38.7% (2025) |
|
Key Market Opportunities |
Rising demand for recyclable, lightweight, bio-based, and high-recycled-content packaging solutions across food, beverage, personal care, and pharmaceutical applications. |
Key Analytical Observations Supporting the Above Data:
- Bottles and Jars at 23.3%: PET bottles and jars command the largest pack type share through the global PET beverage packaging market's scale, encompassing bottled water, carbonated soft drinks, juice, dairy, and functional beverages. PET bottle design innovation, including extreme lightweighting, integrated handles for large format containers, and barrier-enhanced multi-layer preforms for oxygen-sensitive beverages, sustains PET's competitive position against alternative materials.
- Rigid Packaging at 76.5%: Rigid PET packaging's market dominance reflects the structural superiority of solid-wall PET containers for carbonation retention, stacking strength for retail shelf presentation, puncture and contamination resistance for food safety applications, and tamper evidence through visible integrity that flexible alternatives cannot deliver at comparable cost.
- North America at 38.7%: North America's market leadership reflects the region's high per-capita packaged beverage consumption, advanced pharmaceutical packaging procurement, extensive PET manufacturing infrastructure, and the world's most sophisticated rPET collection and reprocessing ecosystem.
PET Packaging Market Overview
The global PET packaging market encompasses all packaging products manufactured from polyethylene terephthalate (PET) thermoplastic polymer, spanning rigid packaging formats (bottles, jars, thermoformed trays, blister packs, and containers), flexible packaging formats (films, bags, pouches, and laminates), and functional components (lids, caps, closures, and preforms). PET's unique polymer properties underpin its dominant position across the global packaging industry. The PET packaging industry serves five primary end-use sectors: beverages (comprising the PET beverage packaging market for water, CSD, juice, dairy, beer, and functional drinks), food (condiments, edible oils, convenience meals, dry goods), pharmaceutical (prescription and OTC medication containers), household goods (cleaning products, personal care), and other industrial applications.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
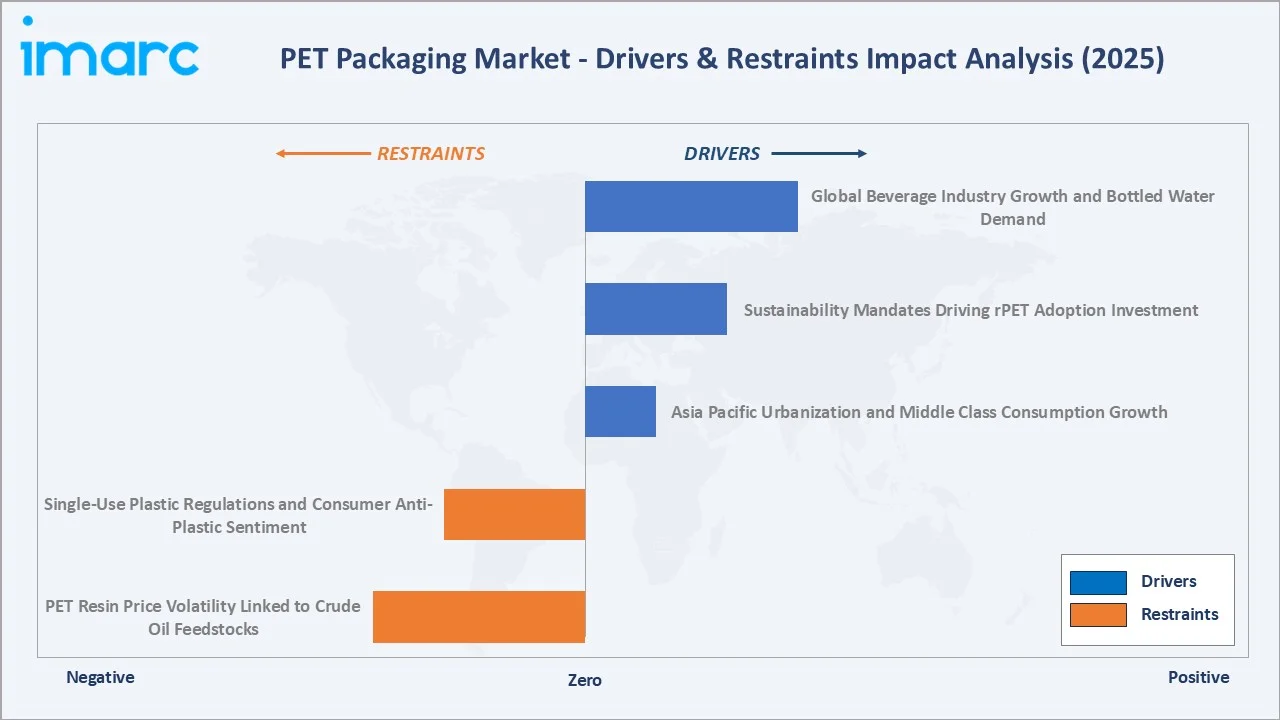
- Global Beverage Industry Growth and Bottled Water Demand: The global packaged beverages market is experiencing sustained volumetric growth through bottled water's expansion in developing markets where safe tap water access remains inconsistent, carbonated soft drink consumption in emerging economies, and the growth of functional beverages, ready-to-drink teas, sports drinks, and premium juice categories that require PET's clarity and barrier properties. In the United States, bottled water containers account for approximately 55% of all PET plastic items collected through curbside recycling programs is the primary driver of absolute PET packaging volume expansion.
- Sustainability Mandates Driving rPET Adoption Investment: The EU incorporating 25% recycled content in PET beverage bottles by 2025 and 30% by 2030, combined with voluntary brand commitments, is driving billions in capital investment in PET recycling capacity expansion globally. This rPET demand pull is generating its own market growth dynamic as brands pay premiums for certified rPET that sustains packaging industry revenue growth beyond volume.
- Asia Pacific Urbanization and Middle Class Consumption Growth: Asia is home to 54% of the world’s urban population, representing more than 2.2 billion people. By 2050, the region’s urban population is projected to increase by 50%, adding approximately 1.2 billion urban residents. Asia Pacific's continuing urbanization is driving PET bottle demand growth at rates substantially above the global market average. The transition from unpackaged water to bottled water as urban populations enter modern consumption patterns creates a great one-time demand increase that compounds annually as existing consumers increase category engagement frequency.
Market Restraints
- Single-Use Plastic Regulations and Consumer Anti-Plastic Sentiment: Progressive single-use plastic restrictions are creating market uncertainty for PET packaging brands and manufacturers, even though PET's recyclability differentiates it favorably from non-recyclable plastics targeted by most regulatory frameworks. Consumer sentiment against plastic packaging creates brand risk that motivates some FMCG companies to switch from PET to alternative materials in certain categories, particularly personal care and household products.
- PET Resin Price Volatility Linked to Crude Oil Feedstocks: PET resin production from paraxylene and MEG petrochemical feedstocks creates direct pricing linkage to crude oil market volatility that can significantly compress converter margins during feedstock price spikes. Resin price volatility makes long-term contract pricing difficult for PET packaging manufacturers and creates operational uncertainty that impedes capital investment planning.
Market Opportunities
- Expansion of Recyclable PET Packaging in Beauty and Personal Care: In September 2026, Indorama Ventures and REBHAN FPS have partnered to develop sustainable PET packaging for beauty and personal care products, combining premium aesthetics with improved recyclability and environmentally conscious materials. The collaboration highlights an opportunity to expand recyclable PET packaging solutions for premium cosmetics and personal care products, as brands increasingly seek packaging that combines sustainability, functionality, and luxury appeal.
- Hot-Fill and Aseptic PET Technology for Premium Beverage Growth: Hot-fill and aseptic PET filling technologies are expanding PET's beverage application range into premium juice, tea, coffee, isotonic sports drinks, and dairy products that require either heat treatment or sterile cold-fill packaging without refrigeration. Advanced crystallized PET (CPET) enables hot-fill resistance for juices and teas while maintaining label aesthetics. Aseptic PET filling with hydrogen peroxide or UV sterilization enables ambient temperature dairy and juice distribution in developing markets where cold chain reliability is limited, opening massive new PET bottle demand in Asia and Africa.
Market Challenges
- Collection Infrastructure Gaps Limiting Effective PET Recycling: Despite PET's established recyclability, significant collection infrastructure gaps in developing markets and underperforming collection systems in some developed economies result in substantial PET bottle leakage to landfill and the environment. Without improvements in waste collection, sorting technology, and recycling economics across Asia, Africa, and Latin America, the sustainability narrative of PET packaging is undermined by plastic pollution data that drives regulatory pressure and consumer skepticism.
- Material Substitution Competition from Alternative Packaging: PET faces growing material substitution pressure from aluminum cans (resurgence in beverage applications driven by recycling narrative), paper-based packaging for some dry food applications, and glass premium repositioning in categories where glass heritage positioning commands market premiums. While PET's total cost of ownership advantage over glass and its recycling rate advantage over aluminum cans in most markets support its competitive position, category-specific substitution dynamics require continuous PET industry innovation and communication investment.
Emerging Market Trends
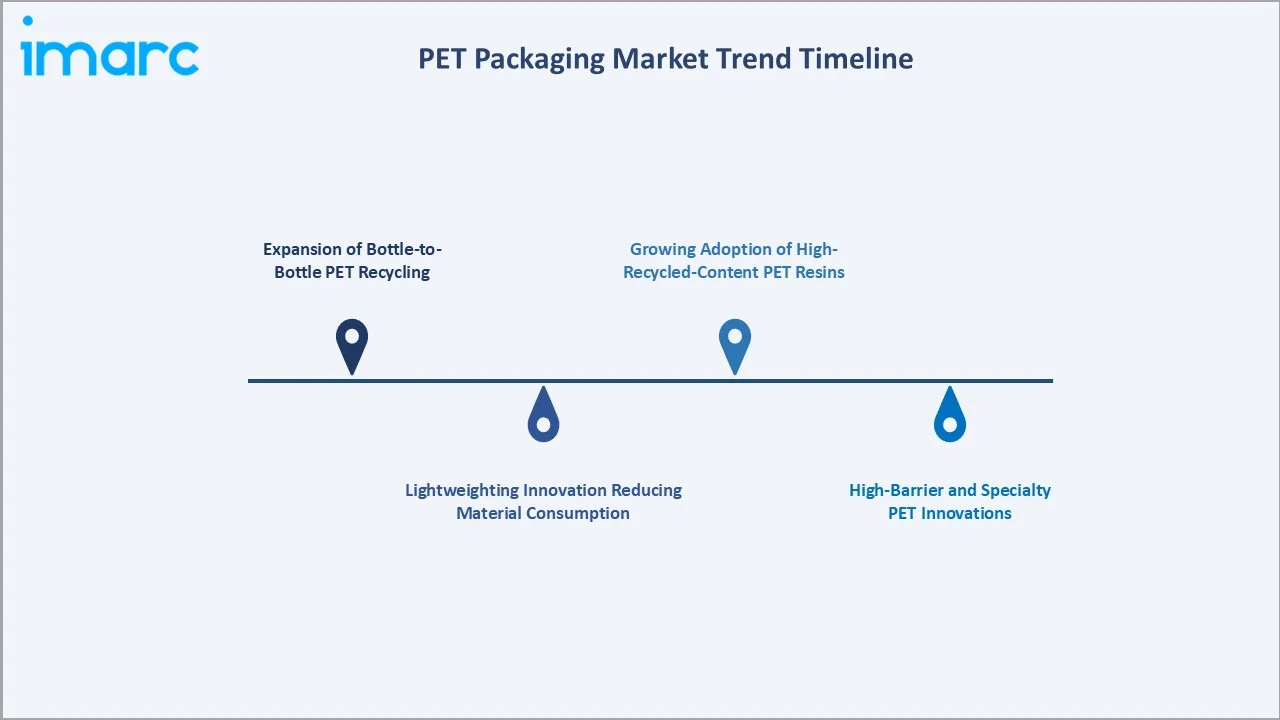
1. Expansion of Bottle-to-Bottle PET Recycling
Growing investment in food-grade PET recycling facilities is emerging as a key trend, enabling packaging manufacturers to increase recycled PET use, strengthen circularity, and meet rising sustainability requirements. In January 2026, Chemco Group launched a food-grade PET recycling facility in Gujarat, India, backed by an investment of nearly INR 125 crore (USD 13.7 million), strengthening its large-scale bottle-to-bottle recycling capabilities and supporting India’s circular plastics economy.
2. Lightweighting Innovation Reducing Material Consumption
Continuous lightweighting of PET bottles remains a major PET packaging industry trend and a primary lever for both cost reduction and environmental footprint improvement. Lightweighting reduces PET resin consumption per unit, decreases transportation carbon footprint, and lowers per-bottle material cost. Carbonated beverage bottles face greater lightweighting constraints due to pressure resistance requirements but continue to advance through optimized geometry and base design.
3. Growing Adoption of High-Recycled-Content PET Resins
Packaging manufacturers are increasingly adopting advanced PET resins that enable higher recycled content without compromising product quality or processing efficiency, supporting the transition toward more circular packaging solutions. In July 2026, Plastipak Packaging introduced pakPET Single Pellet Solution, a sustainable PET resin that enables manufacturers to incorporate higher recycled content while maintaining packaging quality, consistency, and production efficiency.
4. High-Barrier and Specialty PET Innovations
Advanced barrier coating technologies applied to PET bottles are expanding the material's application range into oxygen-sensitive beverages and food products that previously required glass or aluminum. Diamond-like carbon (DLC) internal coatings for beer PET bottles, multilayer PET-PEN (polyethylene naphthalate) copreforms for premium juice and wine applications, and active oxygen-scavenging PET for sensitive beverage applications are extending PET packaging's technical capabilities into high-value categories. These specialty PET innovations command significant premium pricing while expanding the total addressable market for PET packaging beyond its established beverage and food applications.
Industry Value Chain Analysis
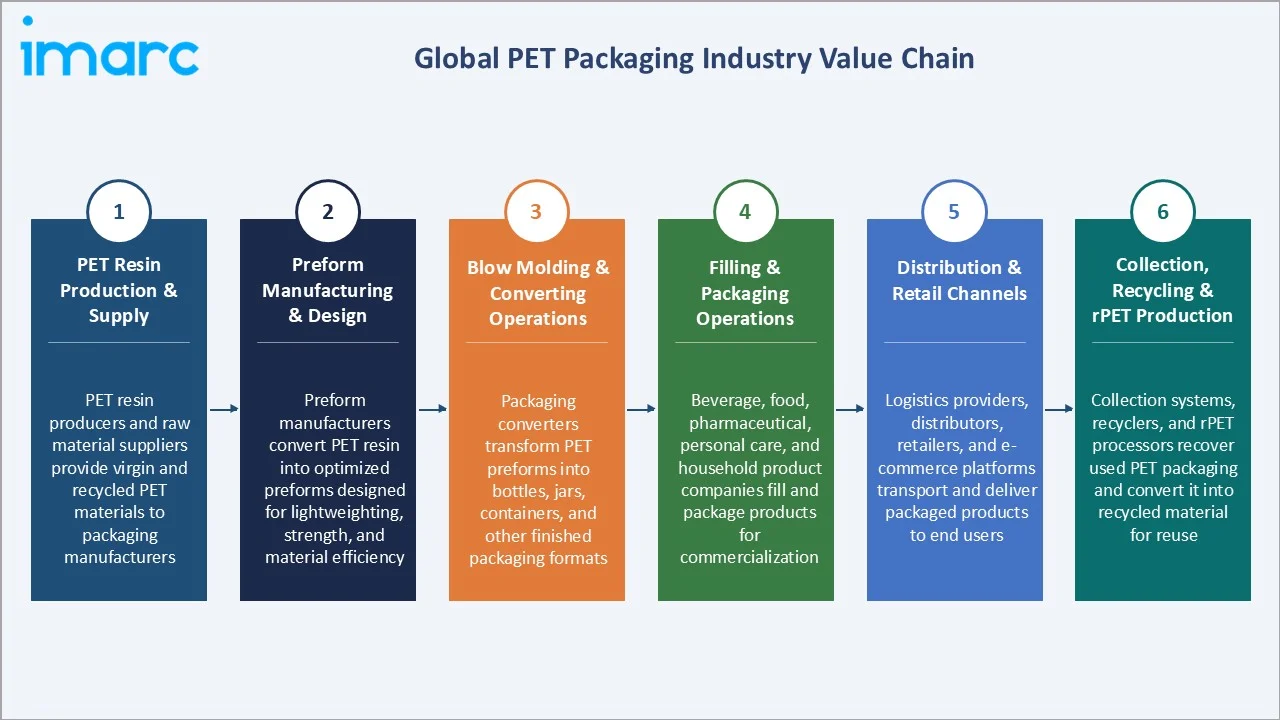
The PET packaging market industry value chain integrates PET resin production and supply, preform manufacturing and design, blow molding and converting operations, filling and packaging operations, distribution and retail channels, and post-consumer collection, recycling, and rPET production to close the circular economy loop.
|
Stage |
Key Participants |
|
PET Resin Production & Supply |
PET resin producers and raw material suppliers provide virgin and recycled PET materials to packaging manufacturers. |
|
Preform Manufacturing & Design |
Preform manufacturers convert PET resin into optimized preforms designed for lightweighting, strength, and material efficiency. |
|
Blow Molding & Converting Operations |
Packaging converters transform PET preforms into bottles, jars, containers, and other finished packaging formats. |
|
Filling & Packaging Operations |
Beverage, food, pharmaceutical, personal care, and household product companies fill and package products for commercialization. |
|
Distribution & Retail Channels |
Logistics providers, distributors, retailers, and e-commerce platforms transport and deliver packaged products to end users. |
|
Collection, Recycling & rPET Production |
Collection systems, recyclers, and rPET processors recover used PET packaging and convert it into recycled material for reuse. |
The collection, recycling, and rPET production stage is emerging as the most strategically important and investment-intensive stage in the global PET packaging value chain, as sustainability regulations and brand commitments create binding demand for certified rPET that is progressively exceeding the supply capacity of existing mechanical recycling infrastructure. PET packaging companies that vertically integrate into recycling create competitive advantages through rPET supply security that standalone converters cannot match in the rapidly tightening rPET supply market.
Technology Landscape in the PET Packaging Industry
Stretch Blow Molding Technology and Preform Innovation
Stretch blow molding (SBM) technology has advanced significantly through servo-driven mold clamping systems, integrated preform heating optimization algorithms, and robotic automation that enable higher output speeds, tighter wall thickness control, and faster format changeovers. Preform design optimization software applying finite element analysis to material distribution modeling enables lightweighting to minimum material consumption while maintaining required structural and barrier performance.
Chemical Recycling Technology for PET
Chemical recycling technologies are transforming the sustainability economics of PET packaging by enabling the recovery of PET polymer from post-consumer waste streams that cannot be mechanically recycled. These technologies collectively expand the effective recycling rate beyond mechanical recycling alone, substantially improving PET's circular economy credentials.
Multi-Layer and Barrier Coating Technology
Advanced barrier coating technologies are expanding PET's application range into categories previously requiring glass or aluminum for product quality preservation. For the PET beverage packaging market, these barrier technologies enable PET beer bottles with adequate shelf life for retail distribution, PET wine bottles for quality wines, and PET containers for oxygen-sensitive juice and nutritional beverages where PET previously performed inadequately.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Packaging Type |
Rigid Packaging |
76.5% |
2025 |
|
Form |
Amorphous PET |
🔒 |
2025 |
|
Pack Type |
Bottles and Jars |
23.3% |
2025 |
|
Filling Technology |
Cold Fill |
🔒 |
2025 |
|
End-User |
Beverages Industry |
56.6% |
2025 |
|
Region |
North America |
38.7% |
2025 |

By Pack Type
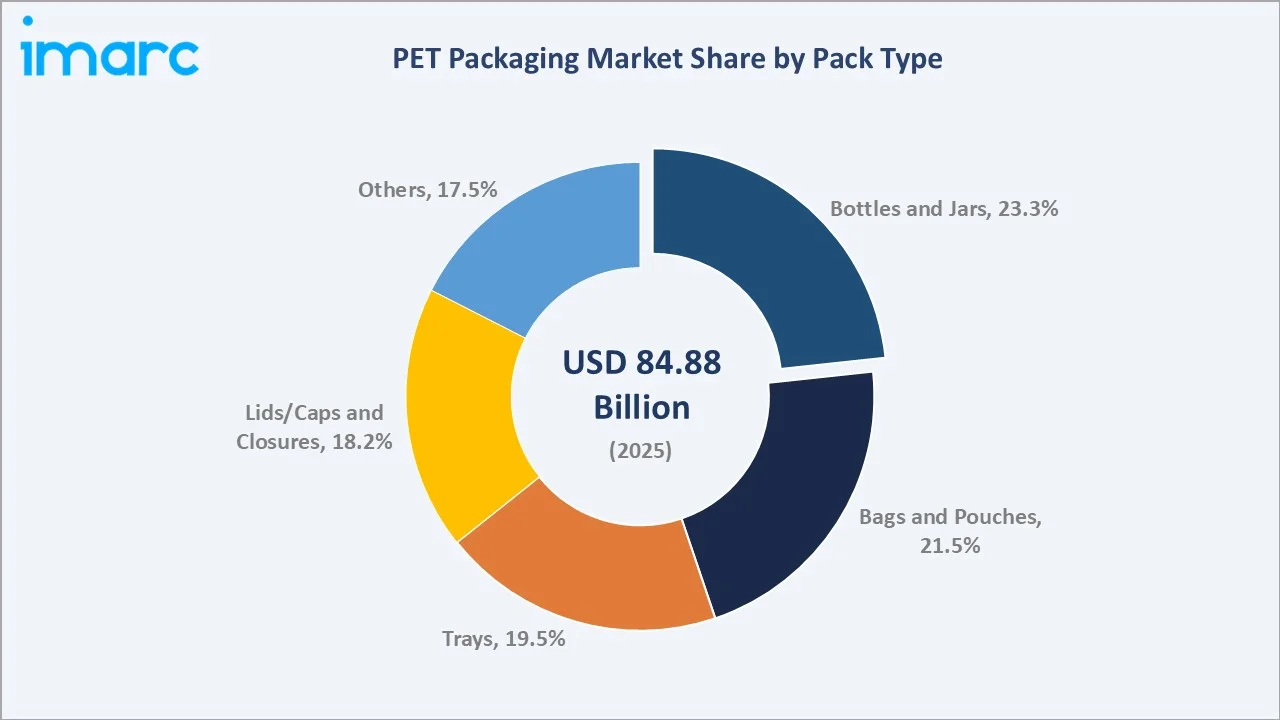
Bottles and jars lead at 23.3% (2025), through the global PET beverage packaging market's scale encompassing water, CSD, juice, dairy, beer, and functional beverages that collectively represent the largest single application for PET packaging worldwide.
To access detailed market analysis, Request Sample
Bags and pouches at 21.5% serve flexible PET film applications in food, personal care, and industrial packaging. Trays at 19.5% serve thermoformed food packaging for ready meals, fresh produce, and confectionery. Lids/caps and closures at 18.2% provide tamper evidence and resealing functionality for PET containers across all end-use categories. Others at 17.5% include films, sheets, and specialty formats for industrial and technical applications.
By Packaging Type
Rigid packaging leads at 76.5% (2025), through PET's structural dominance in bottled beverages, food jars, pharmaceutical containers, and household product bottles where solid-wall construction provides carbonation retention, tamper evidence, stacking strength, and product integrity assurance that flexible alternatives cannot replicate.
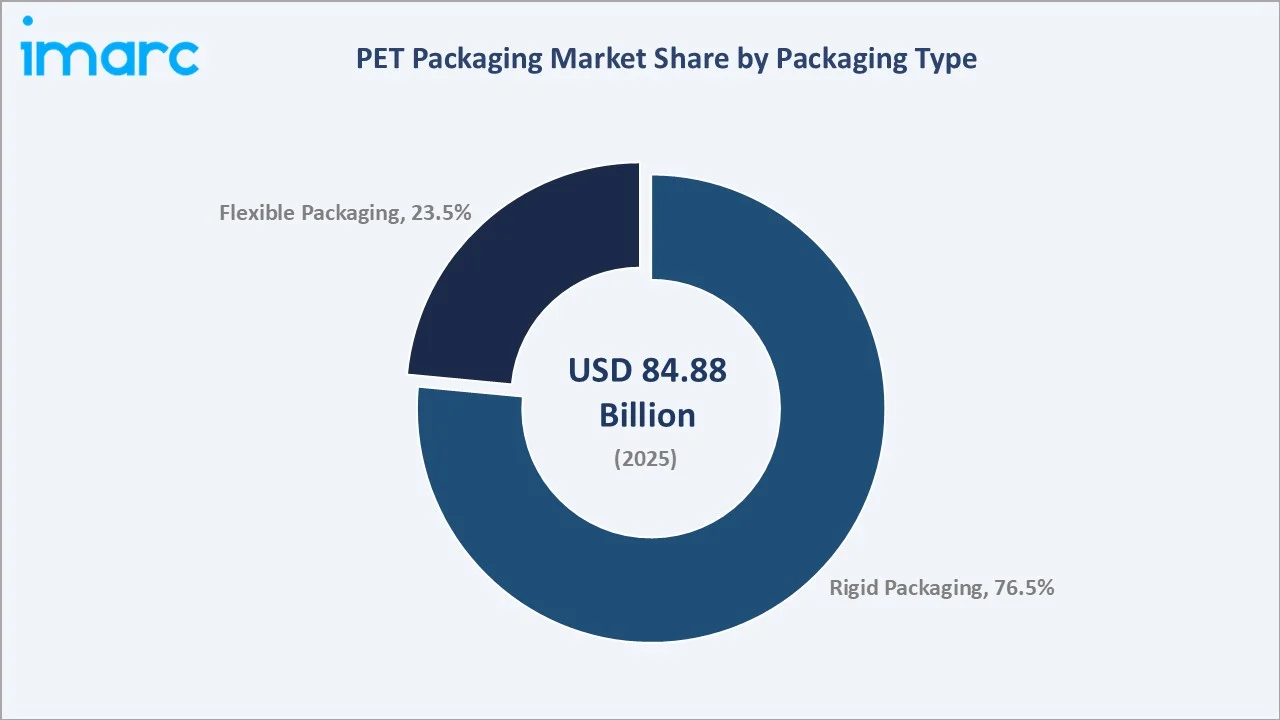
Flexible packaging at 23.5% serves a growing range of food, personal care, and industrial applications where PET film's clarity, barrier properties, and heat-sealability provide performance advantages over alternative flexible materials. Flexible PET packaging's ~4.5% CAGR reflects above-market growth through food flexible packaging conversion from polyethylene and nylon in applications where PET delivers superior barrier and aesthetics.
Regional Market Insights
|
Region |
Share (2025) |
Key PET Packaging Market Drivers & Characteristics |
|
North America |
38.7% |
Reflecting the US and Canada's high per-capita packaged beverage consumption, advanced pharmaceutical PET packaging procurement, established rPET collection and recycling infrastructure, and the largest domestic PET packaging manufacturing base. |
|
Asia Pacific |
25.5% |
Reflecting China, India, Indonesia, and Southeast Asia's rapid urbanization driving bottled water and CSD demand, fast-growing pharmaceutical sectors, and significant PET bottle manufacturing capacity serving both domestic markets and global export. |
|
Europe |
19.5% |
Reflecting stringent EU sustainability regulations, combined with mature beverage and food PET applications in Germany, France, Italy, and the UK. |
|
Latin America |
9.5% |
Reflecting Brazil, Mexico, Colombia, and Argentina's growing beverage PET markets, rapid urbanization expanding packaged goods consumption, and growing pharmaceutical PET adoption as healthcare access improves across the region. |
|
Middle East & Africa |
6.8% |
Reflecting GCC bottled water demand from extreme climate conditions and limited freshwater access, rapid African urbanization driving packaged beverage consumption growth, and growing pharmaceutical packaging localization investment in Saudi Arabia and South Africa. |
North America's 38.7% market leadership reflects the US PET packaging market's extraordinary scale, driven by the highest per-capita packaged beverage consumption, advanced pharmaceutical packaging standards requiring premium PET containers, and the established infrastructure that collectively produces the majority of US PET containers. Asia Pacific's 25.5% share understates its future trajectory: the region is growing at ~5.1% CAGR as billions of urban consumers in China, India, and Southeast Asia increase packaged beverage and food consumption.
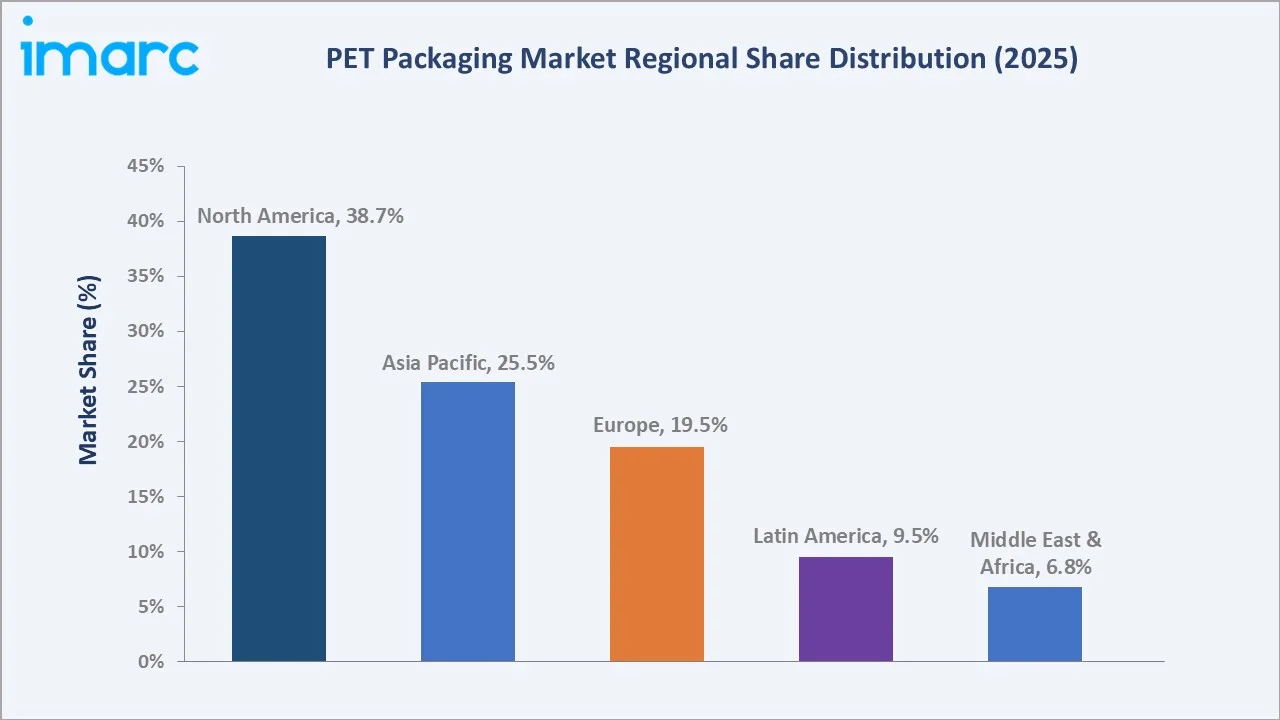
Europe's 19.5% reflects the EU's advanced regulatory environment that is simultaneously creating compliance investment demand (rPET infrastructure, design-for-recyclability engineering) and potential market disruption (alternative material switching in some categories) that creates mixed dynamics for PET market growth.
Latin America's 9.5% reflects a market combining mature PET beverage infrastructure in Brazil and Mexico with high-growth potential in Andean and Central American markets. The Middle East and Africa's 6.8% are among the fastest-growing PET markets in absolute growth percentage terms, driven by the GCC's per-capita world-leading bottled water consumption and Africa's rapid demographic and urbanization expansion.
Competitive Landscape
The global PET packaging market is moderately concentrated, with multinational packaging companies commanding significant global market shares alongside regional specialists serving specific geographic markets and application categories. Competition is driven by production scale efficiency, rPET supply chain integration, technical service capability, sustainability certification, and geographic customer proximity.
|
Company |
Key Products |
Market Position |
Core Strength |
|
Amcor plc |
DairySeal Round Bottle, Slim Ribbed Round Bottle, Slim Straight Round Bottle |
Market Leader |
Amcor plc is a leader in rigid plastic container and PET (polyethylene terephthalate) bottle manufacturing, providing lightweight, shatterproof, and fully recyclable packaging solutions. |
|
Huhtamaki |
Push Tab blister lid |
Market Leader |
Huhtamaki created an industry-first mono-material PET blister lid for pharmaceuticals and healthcare. |
|
ALPLA |
ALPLA reusable PET bottles |
Established Player |
ALPLA plays a leading global role in PET (polyethylene terephthalate) packaging by driving innovations in lightweight design, circular recycling, and alternative format development. |
|
Plastipak Holdings, Inc. |
pakPET Single Pellet Solution, SprayPET Revolution |
Established Player |
Plastipak Holdings, Inc. is a leader in the design, manufacture, and recycling of rigid plastic containers and polyethylene terephthalate (PET) preforms. |
|
Silgan Holdings Inc. |
00013 0.5oz 33-400 PET Jar – Wide-Mouth Round, 00044 0.5oz 33-400 Special PET Jar – Wide-Mouth Round, 01069 30cc 28-400 PET Wide-Mouth Tablet |
Challenger |
Silgan Plastics, operating under Silgan Holdings Inc., acts as a leading manufacturer of custom-designed rigid plastic containers and bottles, including polyethylene terephthalate (PET) packaging, for essential consumer goods. |
Companies across the competitive landscape are investing in rPET processing capability, chemical recycling partnerships, lightweighting innovation, and sustainable design-for-recyclability engineering. The global PET packaging market is expected to see continued consolidation among multinational converters while regional specialists maintain competitive positions through customer proximity and market specialization.
Key Company Profiles
Amcor plc
Amcor plc is the world's largest global packaging company with high revenues. Amcor's PET packaging operations encompass rigid PET container manufacturing for beverage, food, pharmaceutical, and personal care applications across North America, Europe, Latin America, and Asia Pacific, alongside flexible PET film-based packaging for food, medical, and specialty applications. Amcor's rPET integration strategy encompasses preferred supplier relationships with certified rPET reprocessors, participation in advanced recycling partnerships, and proactive engagement with brand customers on packaging design for recyclability optimization.
- Key Products: DairySeal Round Bottle, Slim Ribbed Round Bottle, Slim Straight Round Bottle.
- Strategic Focus: Advancing Amcor's rPET supply chain integration through strategic recycling partnerships that ensure certified recycled content availability for brand customer sustainability commitments, developing chemical recycling-derived rPET products that expand recycled content options beyond mechanically recycled material quality constraints, and growing Amcor's Asia Pacific rigid PET operations to serve the region's rapidly expanding beverage and pharmaceutical markets.
Huhtamaki
Huhtamaki is a global food packaging specialist. Huhtamaki PET packaging operations focus on thermoformed food trays, cups, lids, and food service containers serving QSR chains, food retailers, fresh produce packers, and food processors globally. The company's geographic diversification across Europe, North America, Asia Pacific, and emerging markets provides resilience against regional regulatory variation and enables service to multinational food service and retail customers with standardized global packaging requirements. Huhtamaki’s sustainability commitments focus on designing all packaging to be recyclable and incorporating recycled content across its packaging portfolio.
- Key Products: Push Tab blister lid.
- Strategic Focus: Developing design-for-recyclability innovations in food tray constructions that enable certified recyclability in existing PET collection and recycling systems, and growing Asia Pacific food packaging operations to serve the rapidly expanding modern retail and food service sectors in China, India, and Southeast Asia.
Market Concentration Analysis
The global PET packaging market exhibits moderate concentration, with Amcor, Huhtamaki, and ALPLA collectively commanding significant North American and European market share, while Asia Pacific and emerging market segments are served by a more fragmented mix of regional PET manufacturers and international converters. Market concentration is expected to increase modestly through 2034 as sustainability compliance requirements and rPET supply chain integration capability create competitive advantages for larger, capital-invested manufacturers over smaller independents.
Investment & Growth Opportunities
Highest Growth Segments
Asia Pacific PET beverage market (~5.1% CAGR), pharmaceutical PET packaging conversion (~4.8% CAGR), flexible PET film applications (~4.5% CAGR), rPET and chemical recycling technology, barrier PET innovations for premium beverages, and hot-fill and aseptic PET for emerging market dairy and juice represent the highest-growth investment vectors in the global PET packaging market through 2034.
Investment Themes
- Chemical recycling capacity investment for rPET supply security: Chemical recycling technology for PET enables the production of virgin-quality rPET from post-consumer PET waste that mechanical recycling cannot process, addressing the rPET supply shortage created by mandatory content regulations and brand commitments. Investing in chemical recycling partnerships or proprietary technology positions PET packaging manufacturers for the premium rPET supply that commands growing price premiums in the rapidly tightening certified rPET market.
- Asia Pacific PET manufacturing capacity expansion: The fastest absolute growth in PET packaging demand is occurring in Asia Pacific's beverage and pharmaceutical markets. Establishing or expanding PET manufacturing capacity, preform, blow molding, or thermoforming in Vietnam, Indonesia, India, and Bangladesh positions converters for the decade-long growth wave of packaged goods consumption expansion in these high-population, rapidly urbanizing markets.
Future Market Outlook (2026-2034)
The global PET packaging market is projected to grow from USD 84.88 Billion in 2025 to USD 88.30 Billion in 2026, reaching USD 122.36 Billion by 2034, exhibiting a CAGR of 4.02% during 2026-2034. The market is projected to reach an anchor value of USD 103.39 Billion by 2030, representing the mid-period milestone at which EU mandatory rPET content requirements reach compliance deadlines, Asia Pacific beverage market growth sustains above-global-average expansion, and chemical recycling begins achieving commercial-scale rPET production.
Three structural forces will define the global PET packaging market through 2034. First, the global beverage industry's continued volumetric expansion will sustain underlying PET packaging volume growth that compounds at above-GDP rates in most regions. Second, the mandatory sustainability transformation of PET packaging will generate significant additional market value creation beyond volume growth as brands pay premium pricing for certified rPET content and invest in packaging redesign for improved recyclability. Third, the pharmaceutical sector's progressive adoption of PET as the preferred container material for oral solid dosage medications, nutraceuticals, and laboratory supplies will expand PET packaging's market beyond its traditional beverage and food strongholds into a high-value, specification-driven segment that grows independently of general consumer goods market cycles.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with PET packaging manufacturer executives, PET resin producers, rPET processors, major brand packaging procurement managers, industry association representatives, regional PET industry bodies, and sustainability consultants specializing in the circular plastics economy. These discussions validated market size estimates, assessed segment demand dynamics, evaluated competitive positioning, and provided insights into regulatory developments and future market evolution.
Secondary Research
Secondary research encompassed annual PET recycling reports, PET market analysis, PET resin and packaging trade data, FDA food contact material database, packaging regulations, major company annual reports, industry publications covering global packaging market developments, and sustainability frameworks.
Forecasting Models
Forecasting models incorporated historical PET packaging market revenue trends, global beverage volume growth projections, pharmaceutical sector PET adoption rates, rPET supply capacity expansion schedules, Asia Pacific urbanization and middle-class growth projections, regulatory compliance timeline impact analysis, and macroeconomic indicators including consumer spending growth across major markets.
PET Packaging Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Packaging Types Covered | Rigid Packaging, Flexible Packaging |
| Forms Covered | Amorphous PET, Crystalline PET |
| Pack Types Covered | Bottles and Jars, Bags and Pouches, Trays, Lids/Caps and Closures, Others |
| Filling Technologies Covered | Hot Fill, Cold Fill, Aseptic Fill, Others |
| End Users Covered |
|
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Companies Covered | Amcor plc, Huhtamaki, ALPLA, Plastipak Holdings, Inc., Silgan Holdings Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the PET packaging market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the global PET packaging market.
- The study maps the leading, as well as the fastest-growing, regional markets.
- Porter's five forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the PET packaging industry and its attractiveness.
- The competitive landscape allows stakeholders to understand their competitive environment and provides insight into the current positions of key players in the market.
Frequently Asked Questions About the PET Packaging Market Report
The global PET packaging market reached USD 88.30 Billion in 2026, driven by beverage industry growth in bottled water and CSD applications, rising pharmaceutical PET packaging conversion from glass, Asia Pacific urbanization expanding consumer goods consumption, rPET adoption driven by sustainability mandates, and continuous barrier and lightweighting technology innovation.
The global PET packaging market is projected to grow at a CAGR of 4.02% during 2026-2034, sustained by beverage market volume growth, pharmaceutical PET conversion, Asia Pacific consumption expansion, sustainability-driven rPET premiumization, and technology innovation extending PET's application range into premium beverage and specialty food categories.
The market is projected to reach approximately USD 103.39 Billion by 2030, representing the mid-period milestone at which EU mandatory rPET content requirements reach compliance deadlines, Asia Pacific continues above-average growth, and chemical recycling achieves commercial-scale rPET production, expanding sustainable packaging supply.
Bottles and jars lead with a 23.3% share in 2025, through the PET beverage packaging market's scale encompassing bottled water, CSD, juice, dairy, and functional beverages that collectively represent the largest PET application, alongside food jar applications in condiments, edible oils, and food processing.
Rigid packaging leads with a 76.5% share in 2025, through PET's structural dominance in beverage bottles, food jars, pharmaceutical containers, and household product packaging where solid-wall construction provides carbonation retention, tamper evidence, stacking strength, and product integrity that flexible alternatives cannot deliver at comparable cost.
North America leads with a 38.7% share in 2025, driven by the highest per-capita packaged beverage consumption globally, advanced pharmaceutical PET packaging requirements, established rPET collection and recycling infrastructure, and the world's largest concentration of PET packaging manufacturing capacity.
Key players include Amcor plc, Huhtamaki, ALPLA, Plastipak Holdings, Inc., and Silgan Holdings Inc., among others.
The global PET packaging market is projected to reach USD 122.36 Billion by 2034, driven by sustained beverage industry growth, expanded pharmaceutical PET adoption, mature rPET circular economy development, Asia Pacific and emerging market consumption growth, and specialty barrier PET innovations expanding addressable applications.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade